Philippines Retail Market Size, Share, Trends and Forecast by Product, Distribution Channel, and Region, 2026-2034
Philippines Retail Market Size, Share, Trends & Forecast (2026-2034)
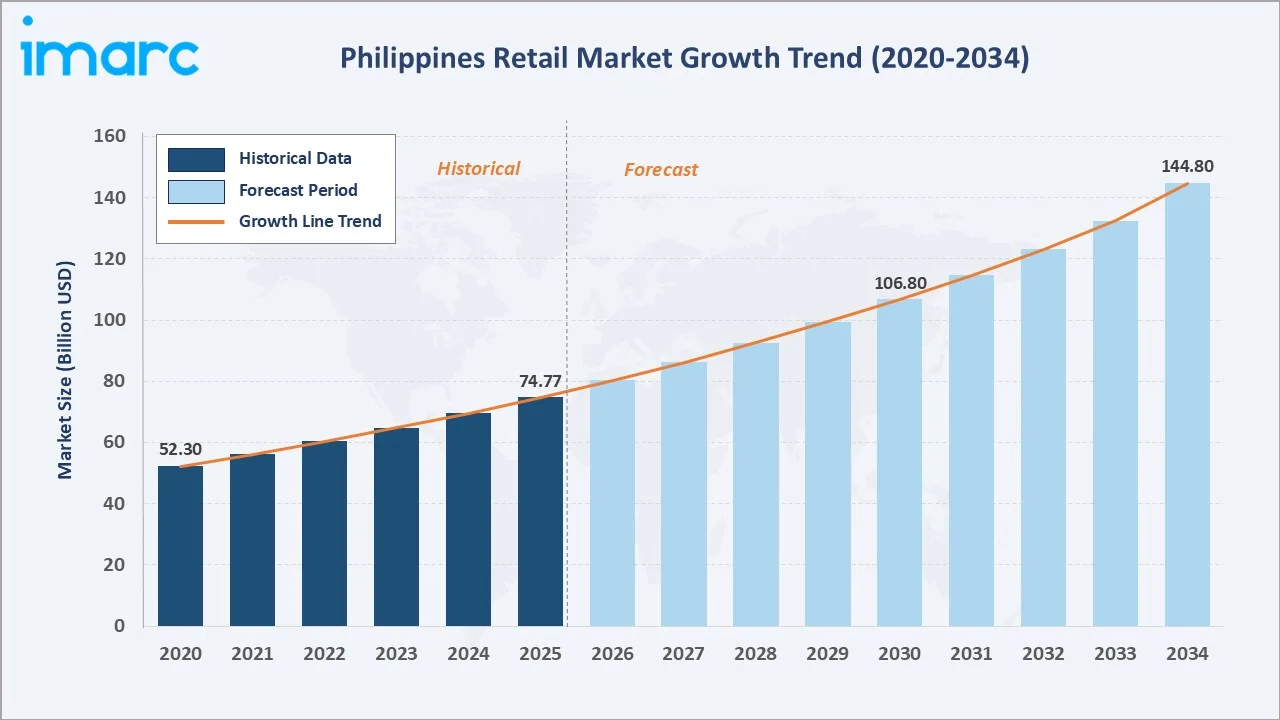
The Philippines retail market grew from USD 74.8 Billion in 2025 to USD 81.8 Billion in 2026 and is projected to reach USD 144.8 Billion by 2034, growing at a CAGR of 7.39% during 2026-2034. The market is driven by rising consumer spending, rapid urbanization, and a growing middle class. The Philippines' population exceeded 114 million in 2024, with urban consumers increasingly adopting modern retail formats and digital commerce. Strong OFW remittances, expanding digital payment infrastructure, and government retail liberalization are accelerating market growth. Supermarkets and Hypermarkets dominate at 36.8%. Food and Beverages leads product share at 43.7%. Luzon commands 58.6% of the market.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 74.8 Billion |
| Market Size (2026) | USD 81.8 Billion |
|
Forecast Market Size (2034) |
USD 144.8 Billion |
|
CAGR (2026-2034) |
7.39% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Product |
Food and Beverages (43.7%, 2025) |
|
Dominant Distribution Channel |
Supermarkets and Hypermarkets (36.8%, 2025) |
|
Leading Region |
Luzon (58.6%, 2025) |
The Philippines retail market expanded from USD 52.3 Billion in 2020 to USD 74.8 Billion in 2025 and an estimated USD 81.8 Billion in 2026, anchored at USD 106.8 Billion in 2030, and forecast to reach USD 144.8 Billion by 2034. The COVID-19 pandemic in 2020 accelerated the shift to e-commerce and digital retail formats. Post-pandemic recovery was driven by rising consumer confidence, OFW remittance inflows, and the government's retail trade liberalization agenda.
To get more information on this market, Request Sample
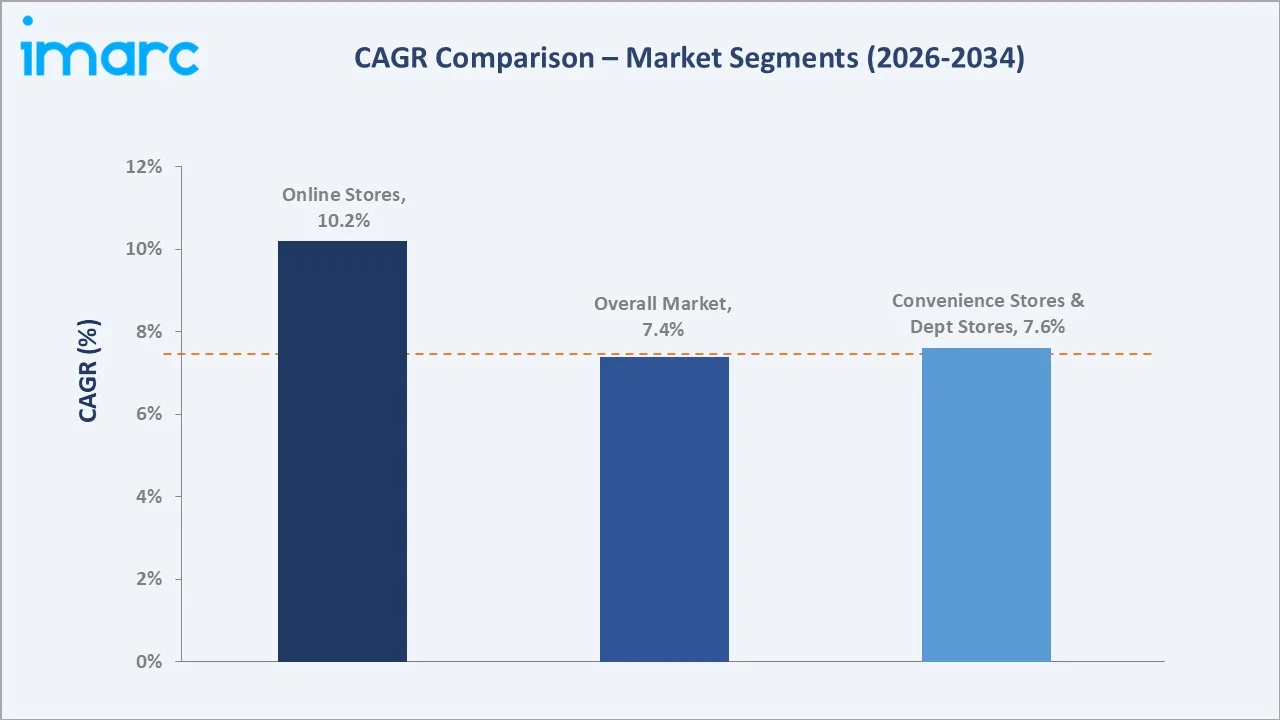
Online retail stores grow fastest at ~10.2% CAGR as smartphone penetration and digital wallet adoption expand across urban and peri-urban areas. Food and Beverages lead product categories through essential consumption demand and expanding modern grocery formats.
Executive Summary
The Philippines retail market, which increased from USD 74.8 Billion in 2025 to an estimated USD 81.8 Billion in 2026, representing one of Southeast Asia's most dynamic consumer markets. The market encompasses modern trade formats, traditional sari-sari stores, e-commerce platforms, and specialty retail channels serving a population of over 114 million people with diverse income levels and consumption needs.
Supermarkets and Hypermarkets at 36.8% dominate through convenience and one-stop shopping appeal. Food and Beverages at 43.7% leads through essential daily consumption demand. Luzon at 58.6% commands through Metro Manila's concentration of purchasing power, corporate employment, and advanced retail infrastructure.
Key Market Insights
|
Insight |
Data |
|
Dominant Product |
Food and Beverages – 43.7% share (2025) |
|
Dominant Distribution Channel |
Supermarkets and Hypermarkets – 36.8% market share (2025) |
|
Leading Region |
Luzon – 58.6% market share (2025) |
|
Market Opportunity |
E-commerce expansion; digital payment integration; rural retail modernization; health & wellness products; omnichannel retail strategies |
Key Analytical Observations Supporting the Above Data:
- Food and Beverages at 43.7%: Food and beverages dominate due to essential daily consumption patterns, expanding modern grocery formats, and strong FMCG brand penetration. The segment benefits from growing demand for packaged and processed foods among urban consumers.
- Supermarkets and Hypermarkets at 36.8%: These formats dominate because they offer one-stop shopping, air-conditioned environments, and wider product assortment. Growing middle-class preference for modern trade over traditional wet markets supports their leading position.
- Luzon at 58.6%: Luzon leads due to Metro Manila's high population density, concentration of corporate headquarters, and advanced retail infrastructure. The region benefits from higher per-capita income levels and superior logistics connectivity.
Philippines Retail Market Overview
The Philippines retail market encompasses all organized and unorganized retail formats serving consumer needs across food, apparel, electronics, personal care, and lifestyle categories. The market includes modern trade formats such as supermarkets, hypermarkets, convenience stores, department stores, specialty stores, online platforms, and the traditional sari-sari store network.
Macroeconomic factors include strong GDP growth, expanding youth demographics, rising urban population, and substantial OFW remittance flows that sustain household purchasing power. In addition, digital payment adoption, improving logistics infrastructure, and government retail trade liberalization are accelerating modern retail development across all Philippine regions.
Market Dynamics
To evaluate market opportunities, Request Sample
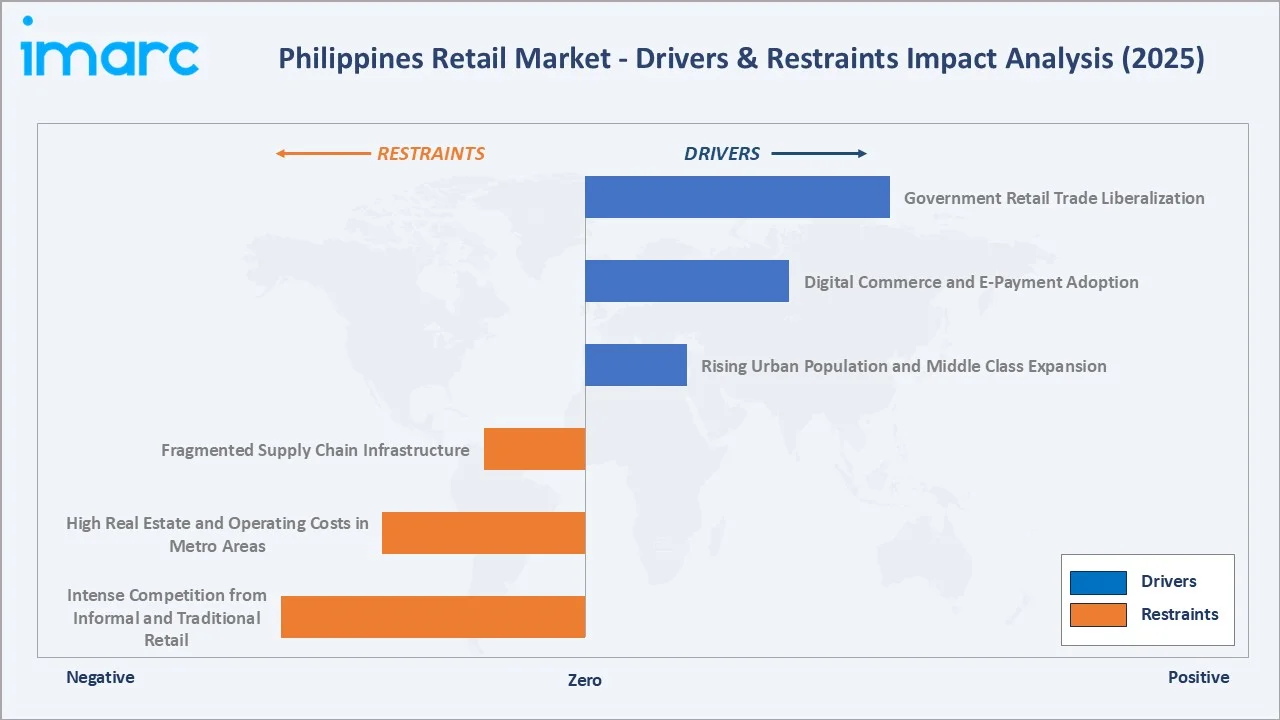
Market Drivers
- Rising Urban Population and Middle Class Expansion: Rapid urbanization is increasing the consumer base for modern retail formats. Metro Manila and emerging urban centers are driving demand for organized retail, premium products, and convenience-oriented shopping experiences. Growing middle-class income levels are expanding discretionary spending across apparel, electronics, and lifestyle categories, supporting sustained retail market growth.
- Digital Commerce and E-Payment Adoption: The rapid expansion of e-commerce platforms such as Shopee and Lazada, supported by GCash and Maya digital wallets, is transforming the retail landscape. In 2024, Bangko Sentral ng Pilipinas reported that digital payment transactions exceeded 50% of total retail volume. This shift is enabling smaller retailers to access broader markets and enabling consumers to purchase across wider product ranges conveniently.
- Government Retail Trade Liberalization: Republic Act 11595 lowered the minimum paid-up capital requirements for foreign retail enterprises, attracting international retailers and investment into the Philippine market. This is increasing competition, improving product availability, and upgrading retail infrastructure. Greater foreign participation is introducing modern retail management practices and technology adoption across the country.
- OFW Remittances Supporting Consumer Spending: The Philippines received over USD 38 billion in OFW remittances in 2024, representing one of the highest globally relative to GDP. These remittances directly fuel household retail consumption by supporting purchases of food, personal care products, electronics, and household appliances. OFW recipient households exhibit higher retail spending propensity, sustaining demand even during economic slowdowns.
Market Restraints
- Fragmented Supply Chain Infrastructure: The archipelago geography of the Philippines creates significant logistics challenges in supply chain management, particularly for inter-island product distribution. High transportation costs, cold chain deficiencies, and inadequate warehousing in provincial areas increase retail operating costs and limit product availability in non-urban markets. These inefficiencies reduce retailer margins and constrain geographic expansion.
- High Real Estate and Operating Costs in Metro Areas: Premium retail space rental rates in Metro Manila and major commercial districts significantly increase the cost of establishing and maintaining modern retail outlets. Rising utility costs and staff wages further compress retail margins. These structural cost pressures are particularly challenging for small and medium retail operators competing against large organized retail chains.
- Intense Competition from Informal and Traditional Retail: The Philippines' estimated 1.1 million sari-sari stores and traditional wet markets maintain strong competitive positions through deep community presence, flexible credit arrangements, and localized product assortments. These informal retail channels command significant share in provincial and lower-income urban markets, limiting modern trade penetration rates and compressing growth opportunities.
Market Opportunities
- E-Commerce Expansion to Provincial Markets: Increasing smartphone penetration and improving broadband connectivity in provincial areas are creating significant untapped e-commerce opportunities. Online platforms can reach consumers previously inaccessible to modern trade formats, expanding the addressable retail market. Investments in last-mile delivery infrastructure and digital financial inclusion are accelerating this provincial e-commerce opportunity.
- Health, Wellness, and Premium Product Segments: Growing middle-class health consciousness is driving demand for organic foods, nutritional supplements, premium personal care, and wellness products. Retailers investing in health and wellness product assortments are positioned to capture above-average margin categories with strong growth trajectories, supported by a population increasingly willing to pay premiums for quality products.
Market Challenges
- Infrastructure and Logistics Constraints in Island Regions: Serving the Visayas and Mindanao regions efficiently requires navigating complex inter-island logistics with higher freight costs and longer delivery lead times. These constraints limit the ability of modern retail chains to expand nationally and make it challenging to maintain competitive pricing across all geographic markets simultaneously.
- Natural Disaster Vulnerability Affecting Retail Operations: The Philippines faces recurring exposure to typhoons, earthquakes, and flooding events that disrupt retail supply chains, damage store infrastructure, and reduce consumer spending in affected regions. Retailers must invest significantly in business continuity measures and insurance coverage, increasing operational costs and creating periodic revenue disruptions across the country.
Emerging Market Trends
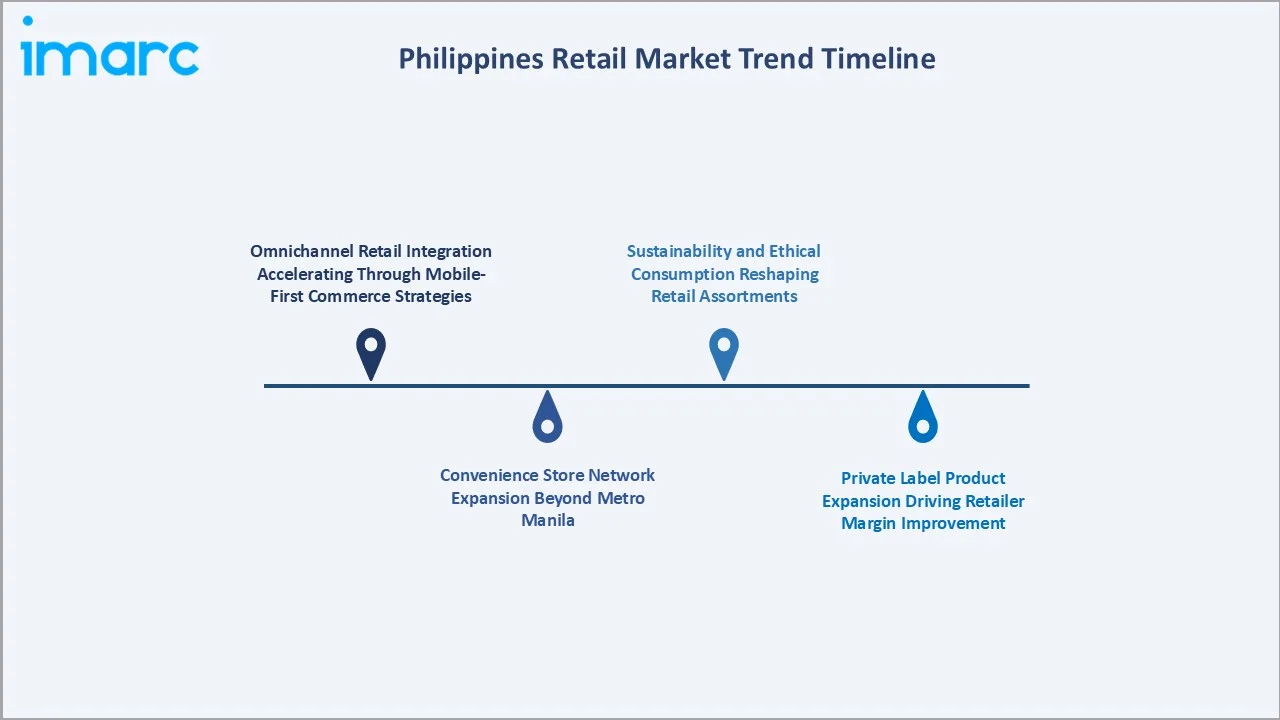
1. Omnichannel Retail Integration Accelerating Through Mobile-First Commerce Strategies
Philippine retailers are rapidly integrating physical and digital channels to create seamless omnichannel shopping experiences. SM Retail and Robinsons Retail are investing in mobile applications, click-and-collect services, and digital loyalty programs. This integration enhances customer retention and enables data-driven personalization across all touchpoints. Growing smartphone adoption across all income segments is making mobile commerce the primary retail engagement channel.
2. Convenience Store Network Expansion Beyond Metro Manila
7-Eleven, Ministop, and emerging local convenience formats are aggressively expanding into secondary cities and municipalities. Convenience stores are evolving beyond snacks and beverages to offer financial services, bill payment, and ready-to-eat meals, increasing their relevance and foot traffic. This geographic expansion is creating new retail access points in underserved communities and challenging traditional sari-sari store dominance in provincial areas.
3. Private Label Product Expansion Driving Retailer Margin Improvement
Leading Philippine retailers including SM and Robinsons are expanding private label product ranges across grocery, personal care, and household categories. Private label products offer 15-25% higher margins compared to branded equivalents while providing competitive price alternatives for value-conscious consumers. This trend is reshaping supplier-retailer power dynamics and creating stronger retailer brand identity among Filipino shoppers.
4. Sustainability and Ethical Consumption Reshaping Retail Assortments
Growing environmental awareness among Filipino consumers, particularly younger urban demographics, is influencing product sourcing and packaging decisions. Retailers are expanding sustainably sourced product ranges, reducing single-use plastics in packaging, and communicating environmental credentials more prominently. This shift is creating new product development opportunities and influencing supplier selection criteria across major retail chains nationwide.
Industry Value Chain Analysis
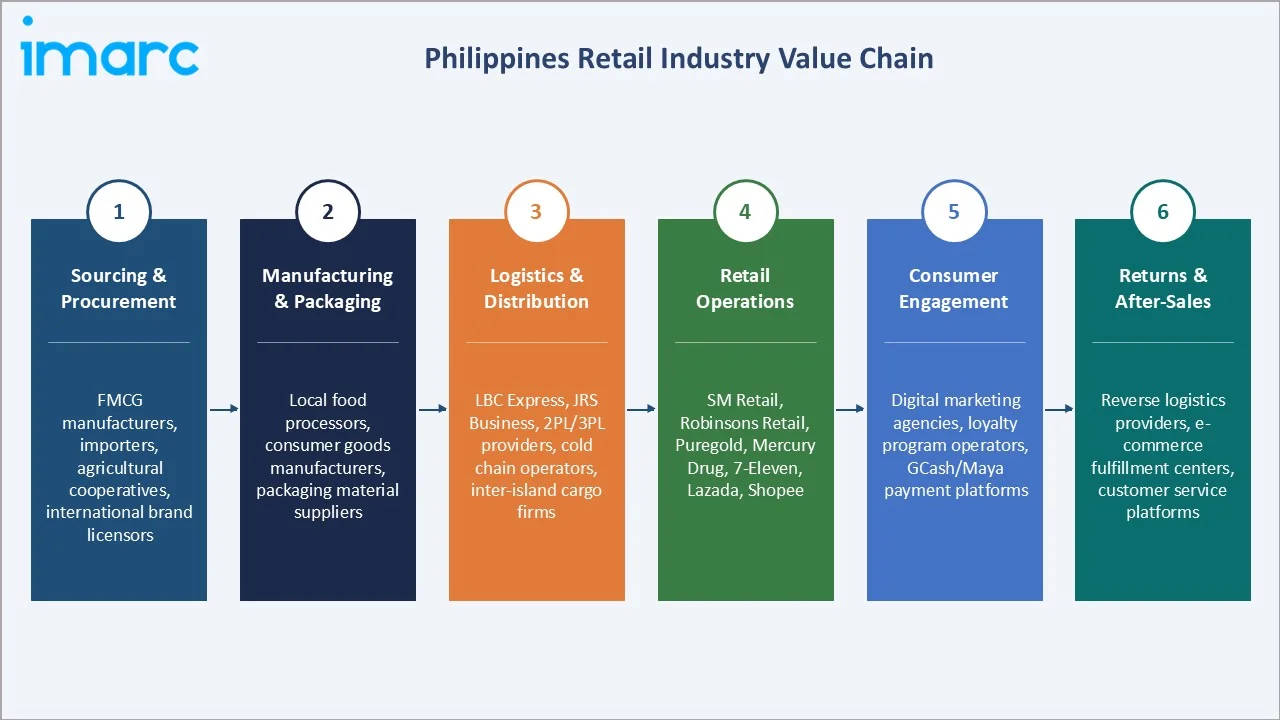
The Philippines retail value chain integrates raw material and product sourcing, manufacturing and packaging, logistics and distribution, retail operations, consumer engagement, and returns management. Each stage involves distinct industry participants and value-addition activities that collectively determine retail market efficiency and competitiveness across the archipelago.
|
Stage |
Key Participants |
|
Sourcing & Procurement |
FMCG manufacturers, importers, agricultural cooperatives, international brand licensors |
|
Manufacturing & Packaging |
Local food processors, consumer goods manufacturers, packaging material suppliers |
|
Logistics & Distribution |
LBC Express, JRS Business, 2PL/3PL providers, cold chain operators, inter-island cargo firms |
|
Retail Operations |
SM Retail, Robinsons Retail, Puregold, Mercury Drug, 7-Eleven, Lazada, Shopee |
|
Consumer Engagement |
Digital marketing agencies, loyalty program operators, GCash/Maya payment platforms |
|
Returns & After-Sales |
Reverse logistics providers, e-commerce fulfillment centers, customer service platforms |
The retail operations stage represents the market's highest commercial differentiation point, where brand presence, store experience, and product curation directly determine consumer loyalty and market share. Logistics infrastructure quality is the most critical constraint for national retail expansion across the Philippine archipelago.
Technology Landscape in the Philippines Retail Industry
E-Commerce Platforms and Mobile Commerce Technology
E-commerce platforms including Shopee, Lazada, and emerging local players are deploying AI-powered recommendation engines, social commerce features, and live-streaming capabilities that are transforming Philippine retail. Mobile-first design, integrated digital wallets, and rapid payment settlement systems are making online shopping accessible across income segments and geographic locations throughout the Philippines.
Digital Payment and Financial Technology Integration
GCash and Maya digital wallets have achieved significant penetration among Filipino consumers, enabling seamless retail payment experiences across both online and physical store formats. QR code payment systems, buy-now-pay-later financing, and mobile banking integration are expanding retail purchasing power among previously underbanked consumer segments, driving incremental retail spending volumes across the country.
Retail Analytics and Inventory Management Systems
Modern Philippine retailers are investing in cloud-based inventory management, demand forecasting, and customer analytics platforms that improve stock availability and reduce wastage. Real-time sales data integration across multiple store formats enables faster supply chain response and more accurate product assortment decisions, improving both customer satisfaction and retailer profitability across all formats.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Product |
Food and Beverages |
43.7% |
2025 |
|
Distribution Channel |
Supermarkets and Hypermarkets |
36.8% |
2025 |
|
Region |
Luzon |
58.6% |
2025 |

By Product
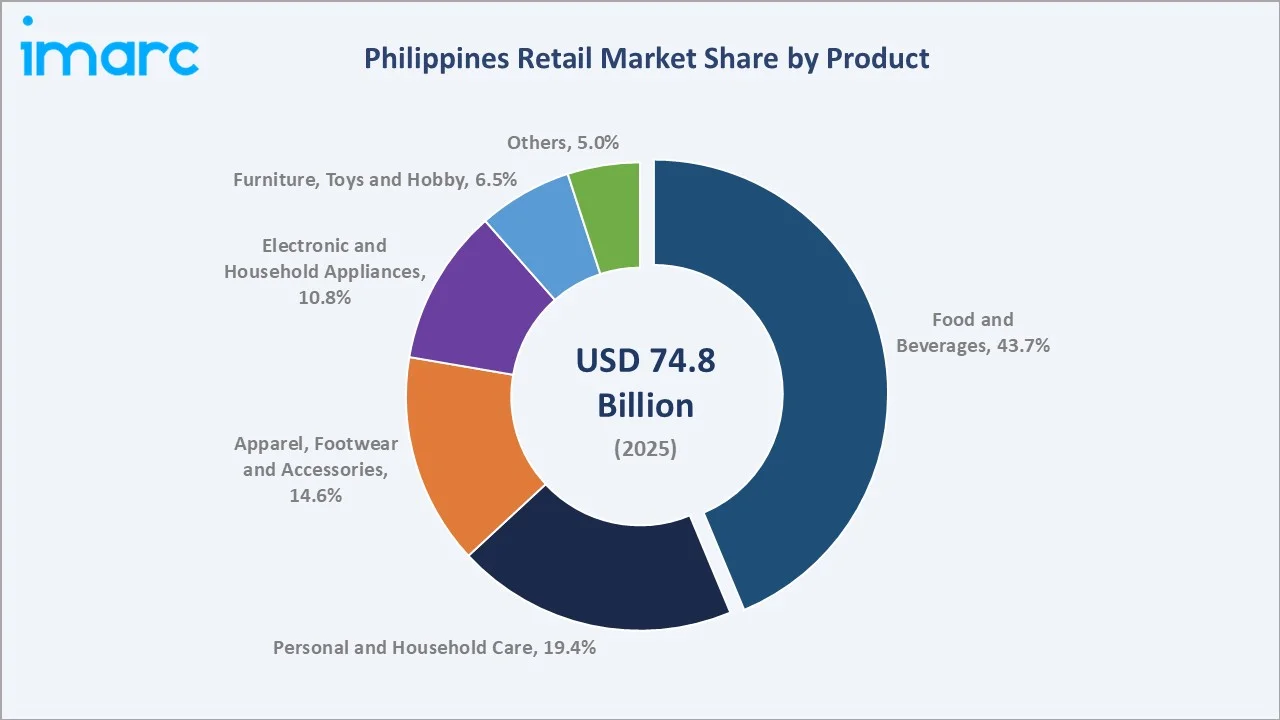
Food and Beverages leads at 43.7% (2025). The food and beverages segment encompasses packaged foods, fresh produce, beverages, dairy products, confectionery, and staple groceries sold across supermarkets, convenience stores, wet markets, and online platforms. Food and Beverages' ~8.1% CAGR reflects rising urban household incomes, premiumization of packaged food categories, and the expanding modern grocery store footprint across provincial Philippine cities.
To access detailed market analysis, Request Sample
Personal and Household Care at 19.4% grows at ~7.8% CAGR driven by rising beauty consciousness, Korean beauty trend adoption, and expanding health and wellness product ranges across modern retail formats. Apparel, Footwear and Accessories at 14.6% grows at ~7.2% CAGR through fast-fashion brand expansion and growing online fashion commerce. Electronic and Household Appliances at 10.8% grows at ~7.5% CAGR through rising household appliance penetration and consumer electronics demand. Furniture, Toys and Hobby at 6.5% grows at ~6.8% CAGR. Others at 5.0% grows at ~6.5% CAGR.
By Distribution Channel
Supermarkets and Hypermarkets lead at 36.8% (2025). The supermarkets and hypermarkets segment encompasses large-format modern retail stores offering comprehensive grocery, fresh food, household goods, and general merchandise assortments under one roof. Supermarkets and Hypermarkets' ~6.8% CAGR reflects sustained consumer preference for one-stop shopping, organized retail loyalty programs, and private label product proliferation across urban and peri-urban markets.
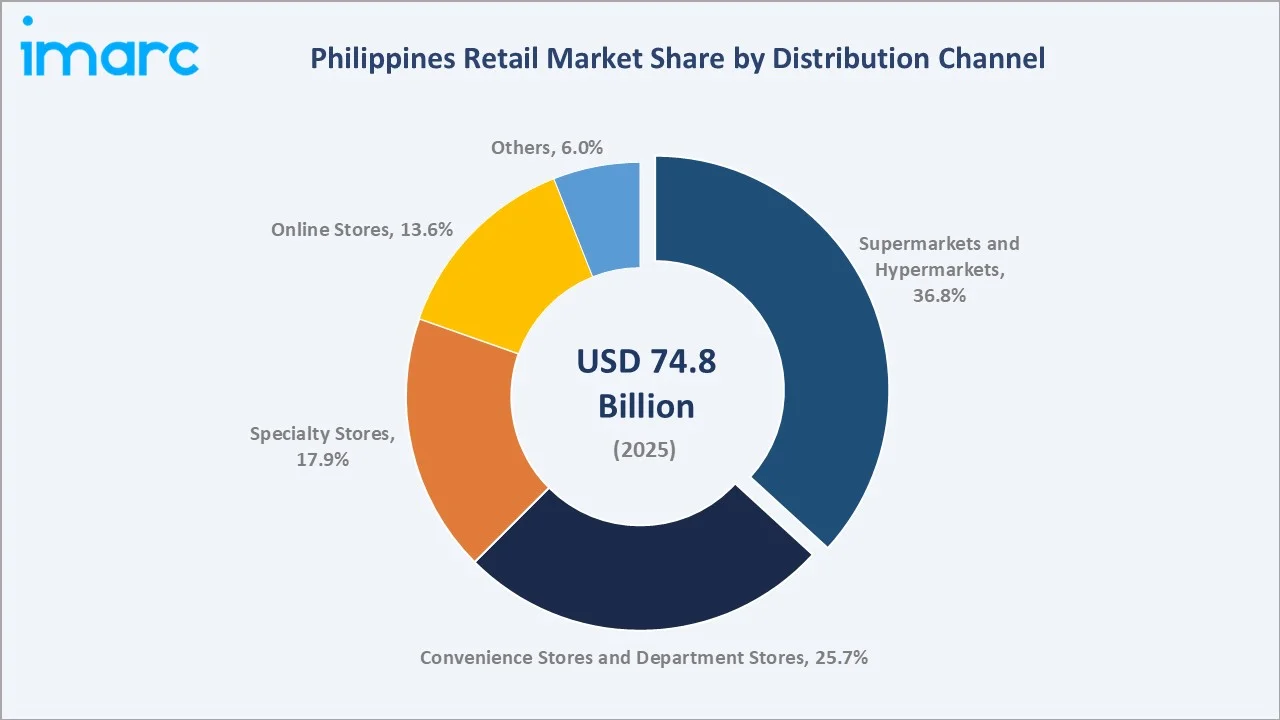
Convenience Stores and Department Stores at 25.7% grow at ~7.6% CAGR through aggressive network expansion beyond Metro Manila into secondary cities and evolving service formats including financial services and ready-to-eat meals. Specialty Stores at 17.9% grow at ~7.1% CAGR driven by premiumization and brand-dedicated retail experience demand. Online Stores at 13.6% grow fastest at ~10.2% CAGR through Shopee and Lazada platform investment, digital payment adoption, and improving last-mile delivery infrastructure. Others at 6.0% grow at ~6.2% CAGR.
Regional Market Insights
|
Region |
Share (2025) |
Key Philippines Retail Market Drivers & Characteristics |
|
Luzon |
58.6% |
Driven by Metro Manila's high population density, concentration of corporate employment, advanced retail infrastructure, and higher per-capita consumer spending. |
|
Visayas |
22.4% |
Supported by Cebu City's growing commercial hub status, expanding tourism-linked retail consumption, and rising urban household income in major Visayan cities. |
|
Mindanao |
19.0% |
Driven by agricultural income, improving peace and security environment, government infrastructure investments, and expanding retail network in Davao, Cagayan de Oro, and Zamboanga. |
Luzon's 58.6% market leadership is anchored by Metro Manila's dual position as both the Philippines' commercial capital and its highest per-capita income region. Visayas' 22.4% reflects Cebu City's emergence as a major retail hub and tourism-driven consumption growth across the central island group.
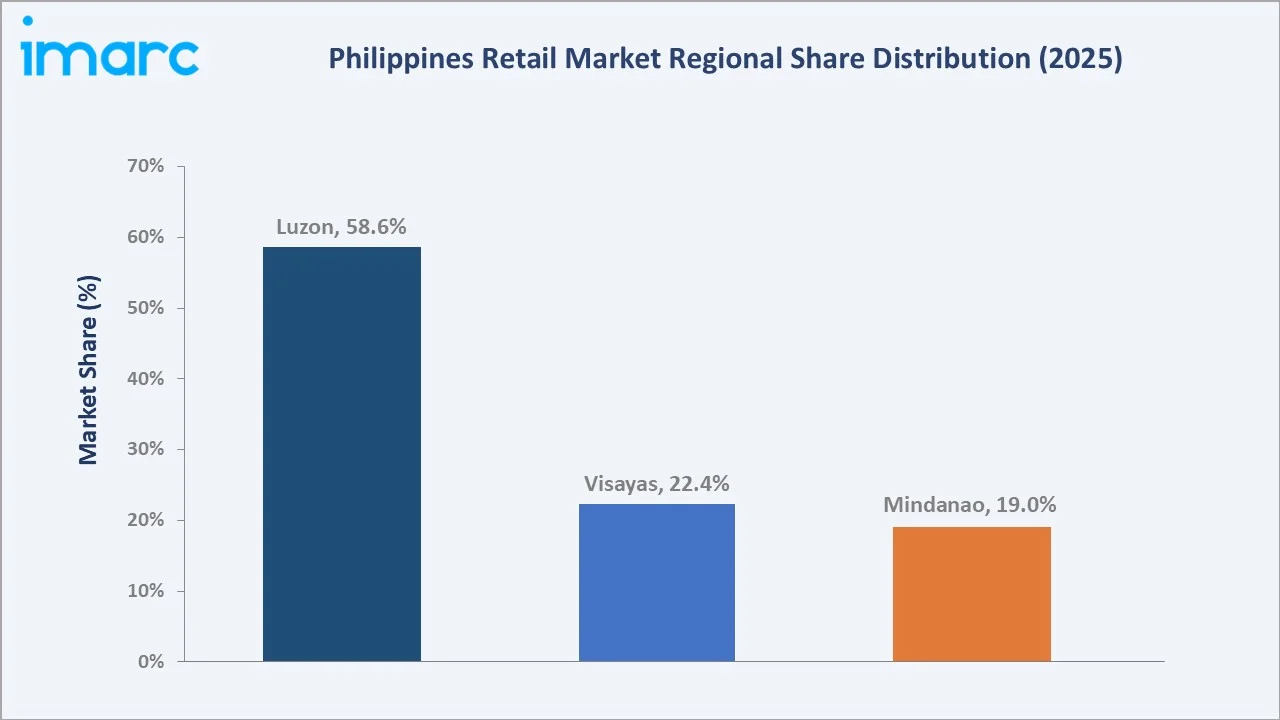
Mindanao's 19.0% encompasses the Davao-Cagayan de Oro urban corridor's expanding modern retail presence alongside agricultural income-driven rural consumption. The region represents the Philippines' most commercially dynamic growth opportunity as security improvements accelerate investment in retail infrastructure development.
Competitive Landscape
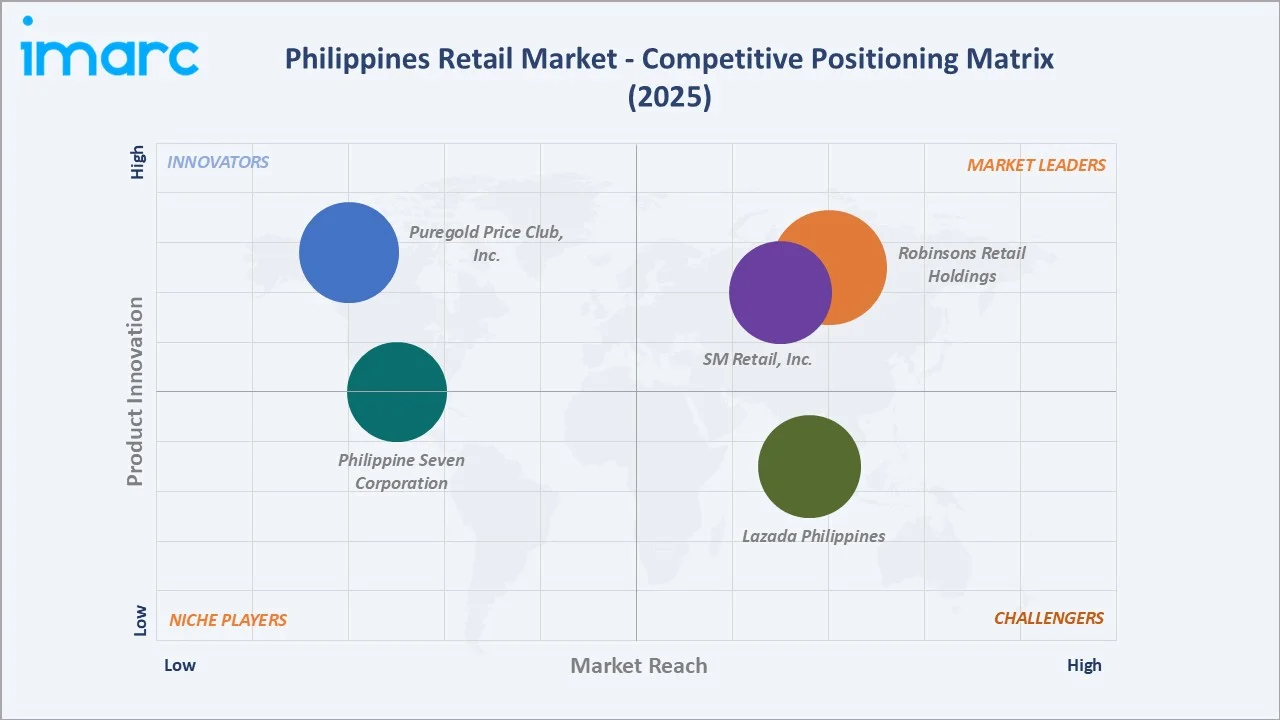
The Philippines retail market competitive landscape encompasses distinct tiers: large integrated retail conglomerates, pharmacy and health retail chains, convenience store operators, department store chains, and fast-growing e-commerce platforms that are reshaping traditional retail market share dynamics across all product categories.
|
Company Name |
Key Products |
Market Position |
Core Strength |
|
SM Retail, Inc. |
SM Supermarket, SM Hypermarket, SaveMore, WalterMart |
Market Leader |
SM Retail dominates Philippines retail through its integrated mall-anchored supermarket and hypermarket network spanning 70+ provinces nationwide. |
|
Robinsons Retail Holdings |
Robinsons Supermarket, Handyman, True Value |
Market Leader |
Robinsons Retail operates a diversified multi-format retail portfolio covering grocery, hardware, and specialty retail across the Philippines. |
|
Puregold Price Club, Inc. |
Puregold, S&R |
Established Player |
Puregold focuses on value-oriented grocery retail and membership warehouse shopping, serving price-conscious middle-income Filipino households. |
|
Philippine Seven Corporation |
Convenience food, beverages, financial services |
Market Leader |
Philippine Seven operates the Philippines' largest convenience store network, offering 24/7 access to food, beverages, and financial services nationwide. |
|
Lazada Philippines |
E-commerce marketplace, |
Established Player |
Lazada operates as a leading e-commerce marketplace platform connecting millions of Filipino buyers with domestic and international sellers. |
The SM and Robinsons conglomerates' mall-anchored retail strategies create integrated shopping ecosystems that are difficult for pure-play competitors to replicate. E-commerce platforms Shopee and Lazada are disrupting traditional retail share through aggressive price promotions, seller subsidies, and logistics network investment.
Key Company Profiles
SM Retail, Inc.
SM Retail, Inc. is the Philippines' largest retail company, operating multiple grocery, hypermarket, and specialty retail formats anchored across the SM mall network. The company leverages its unmatched retail real estate footprint and loyal SM Advantage Card membership base to maintain sustained market leadership.
- Key Products: SM Supermarket, SM Hypermarket, SaveMore, WalterMart, and specialty retail formats.
- Recent Developments: In April 2026, SM Retail announced plans to open approximately 300 new stores across the Philippines during 2026, with the expansion focused primarily on provincial areas outside major urban centers. The company said the strategy is aimed at capturing rising consumer demand in underserved markets while offering products at competitive prices. SM Retail President Jonathan Ng emphasized that the company is refining its merchandise mix and pricing to better match changing consumer needs. The expansion is expected to strengthen SM Retail’s nationwide presence across its food and non-food retail formats.
- Strategic Focus: Focuses on mall-integrated retail expansion, private label product development, digital loyalty program enhancement, and geographic network expansion into secondary Philippine cities.
Robinsons Retail Holdings, Inc.
Robinsons Retail Holdings is a leading multi-format retail conglomerate operating supermarkets, department stores, hardware retail, and specialty formats across the Philippines. The company benefits from its parent Gokongwei Group's extensive property and infrastructure assets and strategic retail format diversification.
- Key Products: Robinsons Supermarket, Shopwise, Handyman, True Value, Robinsons Department Store.
- Strategic Focus: Centered on multi-format retail integration, digital commerce acceleration, private label expansion, and strategic market entry into provincial Philippine retail markets.
Puregold Price Club, Inc.
Puregold Price Club is a leading value-oriented grocery and membership warehouse retailer serving price-sensitive Filipino households and resellers. The company's low-price positioning and S&R warehouse club format create complementary retail offerings across income segments nationwide.
- Key Products: Puregold grocery stores, S&R Membership Shopping, PureGo app digital commerce.
- Strategic Focus: Focused on value-oriented grocery retail expansion, sari-sari store reseller channel development, membership warehouse club growth, and digital retail integration for price-conscious Filipino households.
Market Concentration Analysis
The Philippines retail market is moderately concentrated at the modern trade tier, with SM Retail, Robinsons Retail, and Puregold collectively controlling approximately 45-50% of organized grocery retail. Considering the total retail market including traditional sari-sari stores and informal channels, concentration is significantly lower. E-commerce platforms Shopee and Lazada are rapidly gaining share, competing for online retail leadership.
Investment & Growth Opportunities
Highest Growth Segments
Online Stores (~10.2% CAGR), health and wellness retail (~9.5% CAGR), convenience store expansion beyond Metro Manila (~8.8% CAGR), premium food and specialty grocery (~8.2% CAGR), and omnichannel technology investment (~12% CAGR from small base) represent the highest-growth Philippines retail investment vectors through 2034.
Emerging Investment Opportunities
Provincial retail infrastructure development represents the largest near-term Philippines retail opportunity. Modern trade penetration in Visayas and Mindanao secondary cities remains significantly below Metro Manila levels, creating opportunities for organized retail chains and e-commerce platforms investing in logistics and store network expansion in underserved markets.
Investment Themes
- E-commerce and digital payment infrastructure investment for provincial market penetration: Digital retail platforms investing in improved provincial logistics coverage, GCash-integrated payment systems, and local language commerce interfaces are positioned to capture the rapidly expanding provincial e-commerce opportunity as smartphone penetration accelerates across all income segments.
- Private label product development for margin improvement and brand differentiation: Retailers investing in quality private label product ranges across grocery, personal care, and household categories can achieve 15-25% higher gross margins while offering consumers competitive price alternatives to branded products, creating sustainable competitive advantages in margin-compressed Philippine retail.
Future Market Outlook (2026-2034)
The Philippines retail market is projected to grow from USD 74.8 Billion in 2025 to USD 81.8 Billion in 2026, reaching USD 144.8 Billion by 2034, at a CAGR of 7.39% over the forecast period. The market's anchor value of USD 106.8 Billion in 2030 represents an inflection point where e-commerce will have achieved mainstream adoption, provincial retail modernization will have expanded the organized retail addressable market, and digital payment infrastructure will have largely eliminated cash transaction barriers.
Three structural forces define Philippines retail market growth through 2034 with exceptional confidence. Demographic momentum from a young, growing population with rising income levels creates consumer spending expansion that is structural and multi-decade. Digital infrastructure investment by both government and private sector is systematically expanding e-commerce reach across previously underserved geographic markets. Foreign retail investment, accelerated by the liberalized trade environment, is introducing capital, retail technology, and modern management practices improving overall market efficiency.
Research Methodology
Primary Research
Primary research comprised structured interviews with 45+ industry stakeholders (2025) including retail CEOs, e-commerce directors, supply chain managers, consumer goods brand managers, and regional retail market specialists across Luzon, Visayas, and Mindanao. Over 30 in-depth interviews were conducted.
Secondary Research
Secondary research encompassed Philippines Statistics Authority retail data, Bangko Sentral ng Pilipinas financial inclusion reports, DTI retail industry publications, company annual reports, e-commerce association data, and consumer behavior research. Over 55 secondary sources were systematically reviewed.
Forecasting Models
Market revenue forecasts were developed using a segment bottom-up model incorporating: (i) product category component; (ii) distribution channel component; (iii) regional component. Forecasts were cross-validated using top-down macroeconomic indicators.
Philippines Retail Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Product Types Covered | Food and Beverages, Personal and Household Care, Apparel, Footwear and Accessories, Furniture, Toys and Hobby, Electronic and Household Appliances, Others |
| Distribution Channels Covered | Supermarkets and Hypermarkets, Convenience Stores and Department Stores, Specialty Stores, Online Stores, Others |
| Regions Covered | Luzon, Visayas, Mindanao |
| Companies Covered | SM Retail, Inc., Robinsons Retail Holdings, Puregold Price Club, Inc., Philippine Seven Corporation, Lazada Philippines, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Philippines retail market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Philippines retail market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Philippines retail industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Philippines Retail Market Report
The Philippines retail market size is estimated at USD 81.8 Billion in 2026. The market is driven by rising urban consumer spending, OFW remittance inflows, expanding e-commerce adoption, and government retail liberalization policies attracting foreign retail investment and modernizing the Philippine retail landscape across all regions.
The market grows at 7.39% CAGR during 2026-2034, reaching USD 144.8 Billion by 2034. Online stores grow fastest at ~10.2% CAGR through accelerating e-commerce adoption and digital payment integration across the Philippines, supported by Shopee and Lazada's aggressive logistics network investment.
Food and Beverages lead at 43.7% through essential daily consumption demand, expanding modern grocery formats, and strong FMCG brand penetration among Filipino households across all income segments and geographic regions.
Supermarkets and Hypermarkets lead at 36.8% through consumer preference for one-stop modern shopping formats, air-conditioned environments, and comprehensive product assortments serving urban and peri-urban Philippine markets throughout the country.
Luzon leads at 58.6% through Metro Manila's concentration of population, corporate employment, higher per-capita income, and advanced retail infrastructure relative to other Philippine regions including Visayas and Mindanao.
Leading companies include SM Retail, Inc., Robinsons Retail Holdings, Puregold Price Club, Inc., Philippine Seven Corporation and Lazada Philippines, among several other organized and specialty retail operators.
The market is projected to reach approximately USD 106.8 Billion by 2030, with e-commerce achieving mainstream adoption in provincial markets, omnichannel retail reaching maturity among leading retailers, and foreign retail investment reshaping competitive dynamics in organized retail formats across the Philippines.
E-commerce growth is driven by high smartphone penetration, GCash and Maya digital wallet adoption, aggressive Shopee and Lazada logistics investment, improving last-mile delivery infrastructure, and sustained consumer behavioral shifts toward online shopping that originated during the COVID-19 pandemic and have persisted into structural e-commerce adoption.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade