Philippines Seeds Market Size, Share, Trends and Forecast by Type, Seed Type, Traits, Availability, Seed Treatment, and Region, 2026-2034
Philippines Seeds Market Size, Share, Trends & Forecast (2026-2034)
The Philippines seeds market grew from USD 209.5 Million in 2025 to USD 212.1 Million in 2026 and is projected to reach USD 235.2 Million by 2034, growing at a CAGR of 1.23% during 2026-2034. The market is driven by rising food demand, government-led seed enhancement programs, and growing adoption of high-yielding and hybrid seed varieties across the country's rice, corn, and vegetable sectors. Conventional seeds dominate at 65.0%, commercial seeds lead availability at 75.0%, and Luzon commands 45.0% of the national seed market.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 209.5 Million |
|
Market Size (2026) |
USD 212.1 Million |
|
Forecast Market Size (2034) |
USD 235.2 Million |
|
CAGR (2026-2034) |
1.23% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Type |
Conventional Seeds (65.0%, 2025) |
|
Dominant Availability |
Commercial Seeds (75.0%, 2025) |
|
Leading Region |
Luzon (45.0%, 2025) |
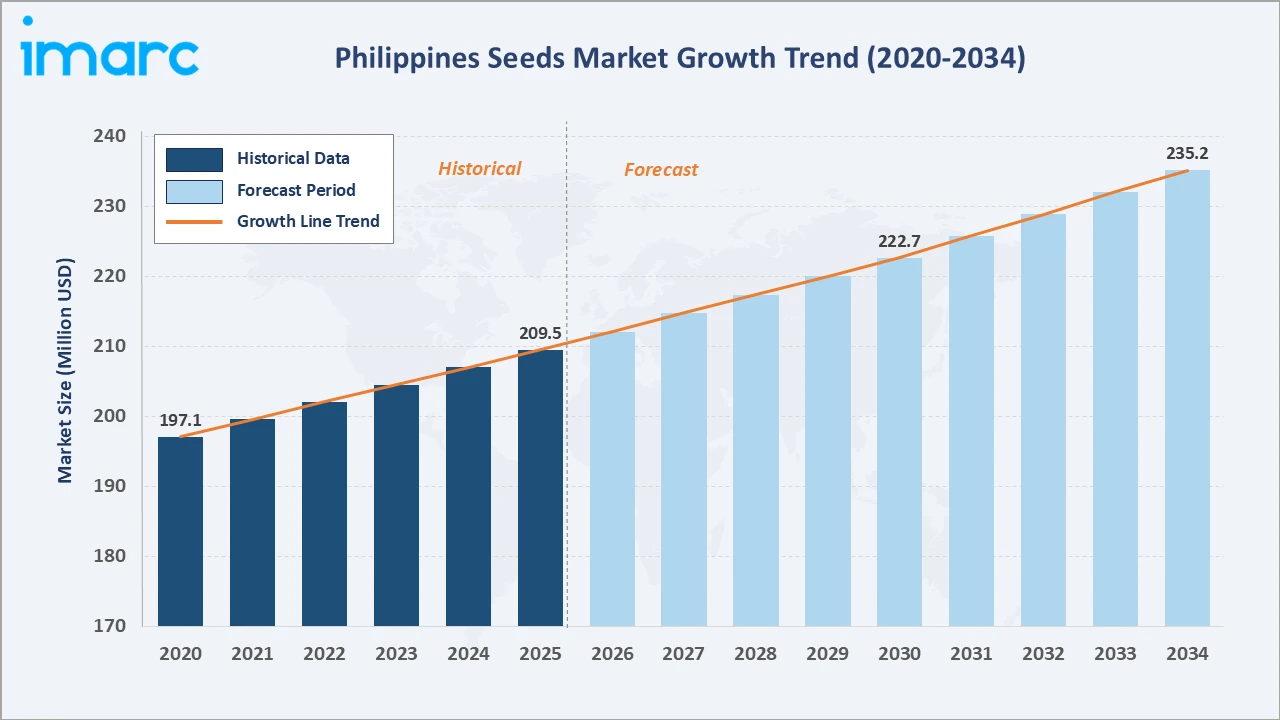
The Philippines seeds market size increased from USD 197.1 Million in 2020 to USD 209.5 Million in 2025 and is estimated to reach USD 212.1 Million in 2026. The market is further expected to grow to USD 222.7 Million by 2030 and USD 235.2 Million by 2034.
To get more information on this market, Request Sample
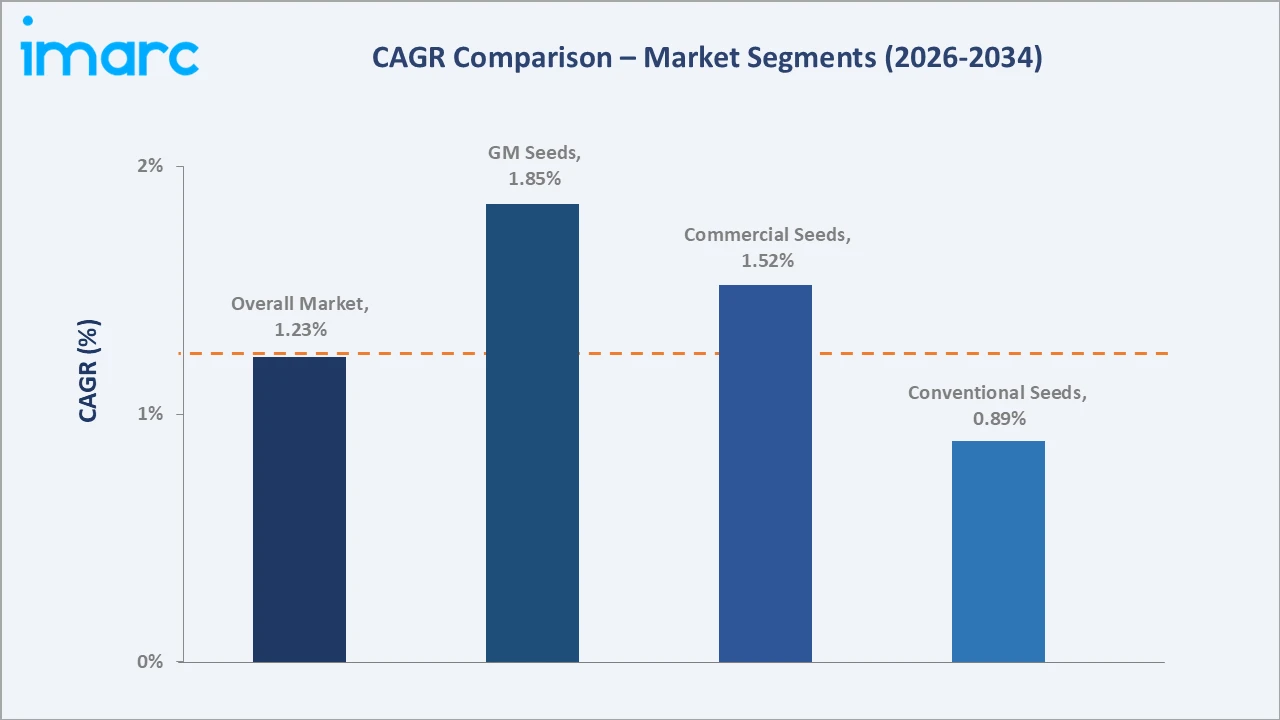
GM seeds grow fastest at 1.85% CAGR through expanding BT corn adoption and regulatory approvals for new biotech traits in Mindanao's commercial corn belt. Commercial seeds grow at 1.52% CAGR through expanding certified seed distribution networks and government-supported certification programs across all three island groups.
Executive Summary
The Philippines seeds market expanded from USD 209.5 Million in 2025 to an estimated USD 212.1 Million in 2026, positioning it as Southeast Asia's fastest-growing agricultural input market segment by volume. The market's growth is driven by a combination of government-backed seed production initiatives, rising hybrid seed adoption, and an expanding commercial farming sector. Conventional seeds hold a dominant 65.0% market share in 2025, reflecting the strong reliance on open-pollinated varieties, particularly among smallholder rice and vegetable farmers.
The commercial seeds segment accounts for 75.0% of the market, highlighting a shift toward certified, high-quality seed procurement. Luzon leads regionally with 45.0% market share, supported by dense agricultural zones and proximity to major seed distribution networks. The market is projected to reach USD 235.2 Million by 2034, growing at a CAGR of 1.23%.
Key Market Insights
|
Insight |
Data |
|
Dominant Type |
Conventional Seeds – 65.0% share (2025) |
|
Dominant Availability |
Commercial Seeds – 75.0% market share (2025) |
|
Leading Region |
Luzon – 45.0% share (2025) |
|
Key Opportunity |
Hybrid rice seed expansion; vegetable seed technology; precision seed coating in commercial farming zones |
Key Analytical Observations Supporting the Above Data:
- Conventional Seeds at 65.0%: Conventional seeds dominate the Philippines market due to their affordability and adaptability to local agro-climatic conditions. Smallholder farmers prefer open-pollinated varieties for rice, corn, and vegetables as they allow seed saving and replanting, reducing input costs.
- Commercial Seeds at 75.0%: The commercial seeds segment leads due to increasing farmer awareness of certified quality benefits, higher germination rates, and improved yields. Government programs providing certified seeds to farmer cooperatives and the growing presence of private agri-input retailers have significantly boosted commercial seed adoption across all major crop types.
- Luzon at 45.0%: Luzon dominates the regional market due to its concentration of rice and corn production zones, higher urbanization, and the presence of major seed distribution centers. The region's well-developed agricultural infrastructure, combined with proximity to government seed production farms and research institutions, supports its market leadership.
Philippines Seeds Market Overview
The Philippines seeds market is structured around two primary crop systems: rice as the dominant staple food crop and corn as the principal cash and feed crop, together representing the bulk of commercial seed demand. The country's archipelagic geography creates distinct seed demand profiles across Luzon, Visayas, and Mindanao, shaped by varying agro-climatic conditions, crop preferences, and farming scale.
The seeds ecosystem integrates public sector seed production through PhilRice and PhilMaize, private multinational seed companies, domestic seed producers, and smallholder farmer networks. The National Plant Genetic Resources Laboratory maintains over 20,000 seed samples supporting crop diversity and climate resilience. The market is commercially positioned at the intersection of traditional smallholder farming and a growing commercial agribusiness sector.
Market Dynamics
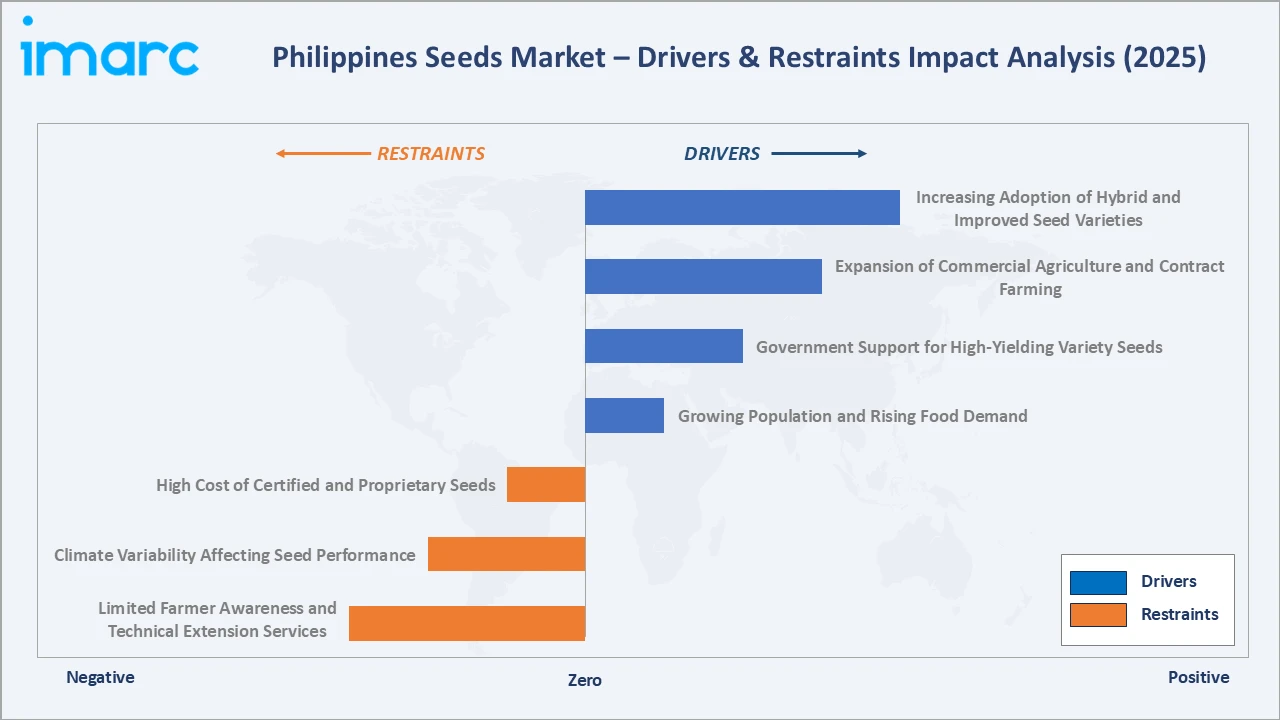
To evaluate market opportunities, Request Sample
Market Drivers
- Growing Population and Rising Food Demand: The Philippines' population exceeding 115 million in 2025 is creating consistent upward pressure on agricultural output, directly stimulating demand for high-yielding and improved seed varieties. Per capita food consumption growth is accelerating demand for rice, corn, and vegetable seeds. The government's food security agenda mandates increased domestic crop production, reinforcing seed market expansion at scale.
- Government Support for High-Yielding Variety Seeds: Government programs distributing certified inbred rice seeds, hybrid corn seeds, and vegetable seeds to farmers across municipalities significantly boost market volumes. In June 2025, certified inbred rice seeds were distributed across municipalities in Antique province ahead of the wet planting season. Subsidized seed programs through the Department of Agriculture reduce adoption barriers and accelerate the transition from farm-saved seeds to certified commercial varieties.
- Expansion of Commercial Agriculture and Contract Farming: Growing contract farming arrangements between agribusinesses, food processors, and smallholder farmers are driving demand for uniform, certified seed varieties. Commercial vegetable and corn farming expansions in Luzon and Mindanao require consistent, high-performance seed inputs. Integration of seed supply within agro-industrial value chains is increasing the share of commercially procured seeds across major crop types.
- Increasing Adoption of Hybrid and Improved Seed Varieties: Rising awareness among farmers of the yield advantages of hybrid rice, hybrid corn, and improved vegetable varieties is expanding market volumes beyond subsistence levels. Growing farmer access to credit for purchasing certified seeds, combined with extension service outreach, is further accelerating adoption of improved seed technologies.
Market Restraints
- High Cost of Certified and Proprietary Seeds: The higher price of certified commercial and hybrid seeds compared to farm-saved seeds remains a significant barrier for smallholder farmers with limited financial resources. Cost constraints reduce adoption rates among resource-poor farmers, particularly in remote and less-developed agricultural areas. Price sensitivity limits penetration of premium hybrid varieties in price-conscious market segments.
- Climate Variability Affecting Seed Performance: Increased frequency and intensity of climatic events such as typhoons, droughts, and flooding create unpredictable growing conditions that reduce the performance reliability of certified seed varieties. Climate-related crop failures discourage investment in high-cost seeds and undermine farmer confidence in commercial seed options. Adapting seed portfolios to evolving climate conditions requires ongoing R&D investment that extends market readiness timelines.
- Limited Farmer Awareness and Technical Extension Services: Gaps in agricultural extension services, particularly in remote island communities, restrict the effective dissemination of information on new seed varieties and best management practices. Low awareness of variety-specific agronomic requirements reduces effective use and yield performance of improved seeds. Insufficient post-sale technical support limits farmer satisfaction and repeat purchase rates for commercial seed products.
Market Opportunities
- Digital Agriculture and Precision Farming Integration: Integrating digital tools such as mobile advisory apps, GPS mapping, and IoT-based crop monitoring with precision seed selection creates opportunities for tailored seed recommendations. Digital seed advisory platforms connecting farmers to certified seed suppliers are emerging as a growth channel in Philippines' rapidly digitizing agricultural sector.
- Organic and Non-GMO Seed Market Expansion: Growing consumer demand for organically produced food and non-GMO crops is creating a nascent but expanding market for open-pollinated, heirloom, and certified organic seed varieties. Niche vegetable and specialty crop seed markets are developing premium-priced product segments with higher value-added potential for domestic seed companies.
Market Challenges
- Dependence on Imported Seed Germplasm: A significant portion of hybrid and improved seed germplasm used in the Philippines is sourced from international breeding programs, creating supply chain vulnerabilities and technology dependency. Import dependence limits the country's ability to develop locally adapted varieties tailored to specific Philippine agro-climatic zones.
- Supply Chain Fragmentation in Remote Agricultural Areas: Delivering certified seeds to geographically dispersed island communities involves complex logistics that increase distribution costs and delivery delays. Fragmented last-mile distribution networks in the Visayas and remote Mindanao regions limit seed market penetration and create quality assurance challenges.
Emerging Market Trends
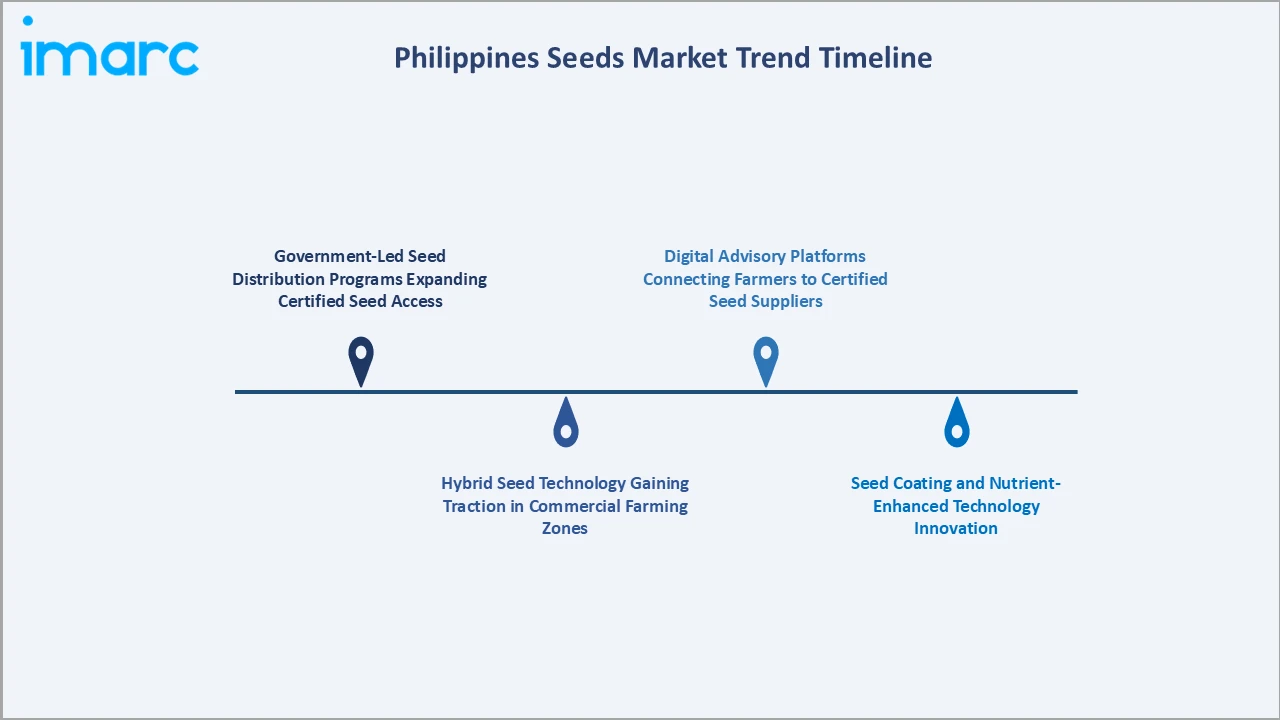
1. Government-Led Seed Distribution Programs Expanding Certified Seed Access
The Philippine government's intensified seed subsidy and distribution programs are accelerating the transition from farm-saved to certified commercial seeds. The National Seed Industry Council coordinates certified variety releases, driving farmer adoption of improved rice and corn seed varieties across all regions.
2. Hybrid Seed Technology Gaining Traction in Commercial Farming Zones
Hybrid rice and corn seed adoption is growing in commercially oriented farming zones, particularly in Luzon and Mindanao's corn belt. Hybrid varieties offering 15–25% yield gains over conventional varieties are incentivizing commercial farmers to upgrade seed inputs, despite higher procurement costs.
3. Seed Coating and Nutrient-Enhanced Technology Innovation
Seed coating technologies that improve germination rates, early seedling vigor, and resistance to soil-borne pathogens are gaining commercial traction.
4. Digital Advisory Platforms Connecting Farmers to Certified Seed Suppliers
Emerging agricultural mobile platforms are enabling smallholder farmers to access certified seed procurement, variety recommendations, and extension advisory services digitally. Government investment in digital farming infrastructure and growing smartphone penetration among Filipino farmers are accelerating digital seed market channel development.
Industry Value Chain Analysis
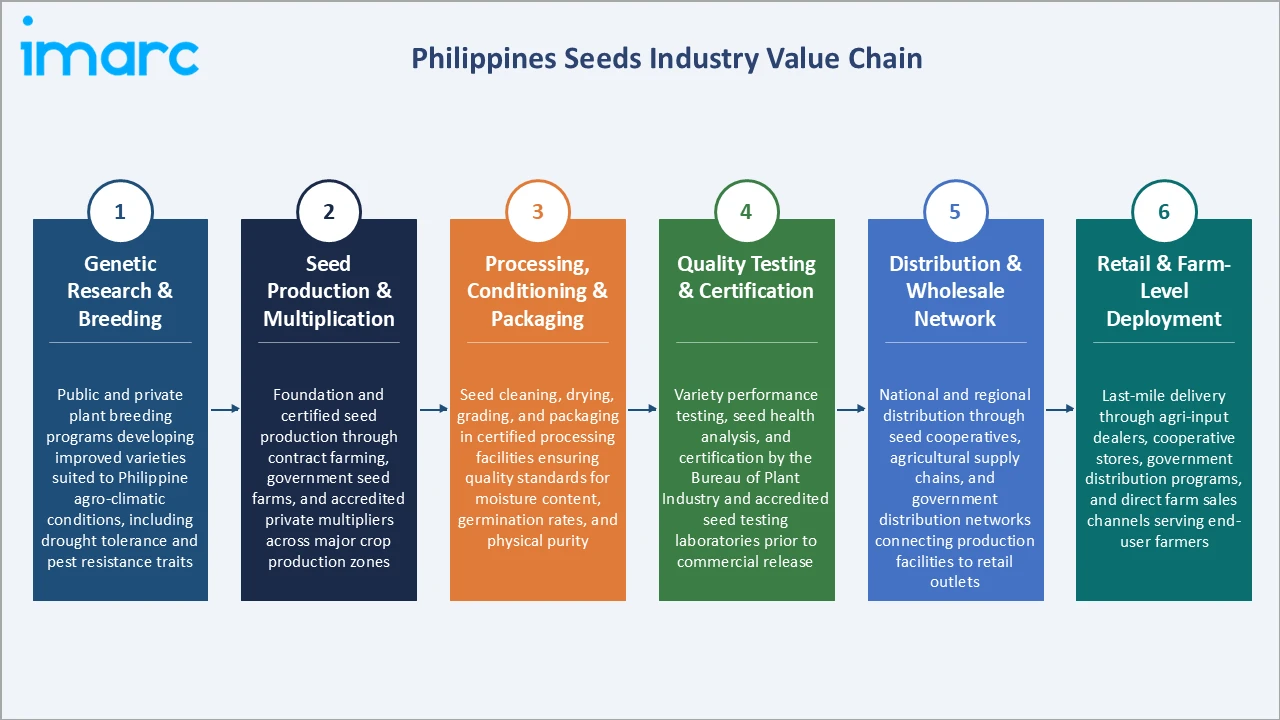
Philippines seeds value chain integrates public and private plant breeding institutions, government-accredited seed multipliers, certified testing laboratories, and commercial distribution networks. The value chain's commercial structure creates the Philippines' unique seed market dynamic, where domestic conventional and hybrid varieties compete alongside imported GM seed technologies across radically different price points.
| Stage | Key Participants |
|---|---|
| Genetic Research & Breeding | Public and private plant breeding programs developing improved varieties suited to Philippine agro-climatic conditions, including drought tolerance and pest resistance traits. |
| Seed Production & Multiplication | Foundation and certified seed production through contract farming, government seed farms, and accredited private multipliers across major crop production zones. |
| Processing, Conditioning & Packaging | Seed cleaning, drying, grading, and packaging in certified processing facilities ensuring quality standards for moisture content, germination rates, and physical purity. |
| Quality Testing & Certification | Variety performance testing, seed health analysis, and certification by the Bureau of Plant Industry and accredited seed testing laboratories prior to commercial release. |
| Distribution & Wholesale Network | National and regional distribution through seed cooperatives, agricultural supply chains, and government distribution networks connecting production facilities to retail outlets. |
| Retail & Farm-Level Deployment | Last-mile delivery through agri-input dealers, cooperative stores, government distribution programs, and direct farm sales channels serving end-user farmers. |
Seed production and multiplication is the Philippines seeds value chain's most commercially consequential stage, integrating government-accredited multipliers, private seed companies, and farmer-cooperative production networks serving the country's rice, corn, and vegetable seed markets. Quality testing and certification through the Bureau of Plant Industry ensures commercially marketed seeds meet minimum germination standards and physical purity thresholds, directly shaping the certified commercial seed market's commercial integrity and farmer trust.
Technology Landscape in the Philippines Seeds Industry
Molecular Breeding and Marker-Assisted Selection
Advanced genomic tools enabling faster development of improved varieties with targeted traits — including submergence tolerance, blast resistance, and drought tolerance — are reducing breeding cycle times. Philippine government-backed rice breeding programs at PhilRice are utilizing marker-assisted backcross breeding for faster trait introgression.
Seed Coating and Bio-Stimulant Technologies
Polymer-based seed coatings incorporating nutrients, biological agents, and fungicides are improving germination uniformity and early seedling establishment. Nutri Shield+ and similar next-generation coating products are expanding the treated seed market in the Philippines, particularly for vegetable and corn seeds.
Precision Agriculture and Variety Matching Platforms
Digital soil mapping, climate data integration, and machine learning-powered variety recommendation systems are enabling more precise seed selection aligned with specific field conditions. Precision agri tools are gaining traction among larger commercial farms, where optimized seed-agronomic management combinations deliver measurable yield improvements.
Gene Editing and Climate-Resilient Variety Development
Emerging gene editing technologies such as CRISPR-Cas9 are opening pathways for developing locally adapted, climate-resilient varieties with improved nutritional profiles. Regulatory frameworks for gene-edited crops are under development in the Philippines, with potential to accelerate the commercial availability of precision-bred seed products.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Type | Conventional Seeds | 65.0% | 2025 |
| Seed Type | 🔒 | 🔒 | 2025 |
| Traits | 🔒 | 🔒 | 2025 |
| Availability | Commercial Seeds | 76.4% | 2025 |
| Seed Treatment | 🔒 | 🔒 | 2025 |
| Region | Luzon | 45.0% | 2025 |

By Type
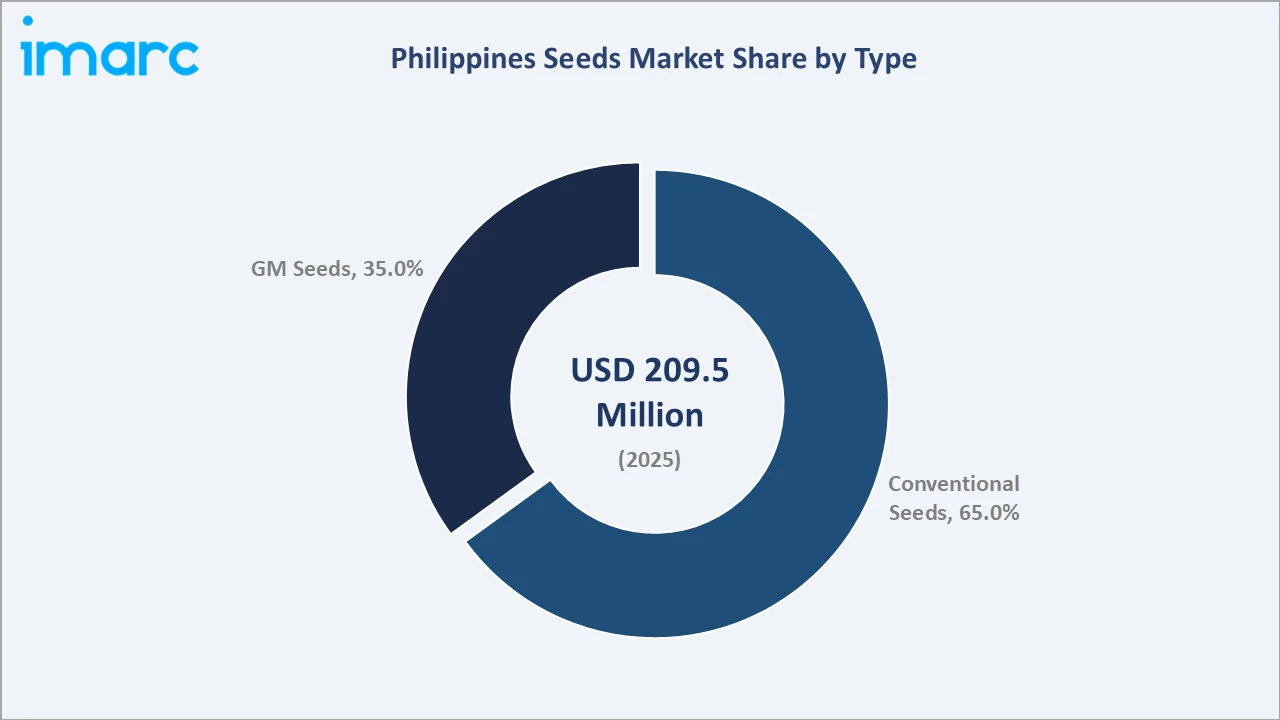
Conventional seeds hold a dominant 65.0% share of the market in 2025, owing to their wide use in rice and vegetable cultivation by smallholder farmers. Genetically modified seeds account for the remaining 35.0%, primarily driven by BT corn and herbicide-tolerant varieties in commercial corn farming zones.
To access detailed market analysis, Request Sample
Conventional seeds are supported by government seed subsidy programs and farmers' cultural preference for seed-saving. GM seed adoption is growing in commercial corn sectors in Mindanao and Luzon, where productivity imperatives outweigh higher seed costs.
By Availability
Commercial seeds account for 75.0% of the Philippines ' seed market in 2025. This dominant share reflects increasing farmer access to certified seed varieties through government programs, private agri-dealers, and cooperative networks. Saved seeds retain a 25.0% share, primarily among rice-growing smallholders in Luzon and Visayas.
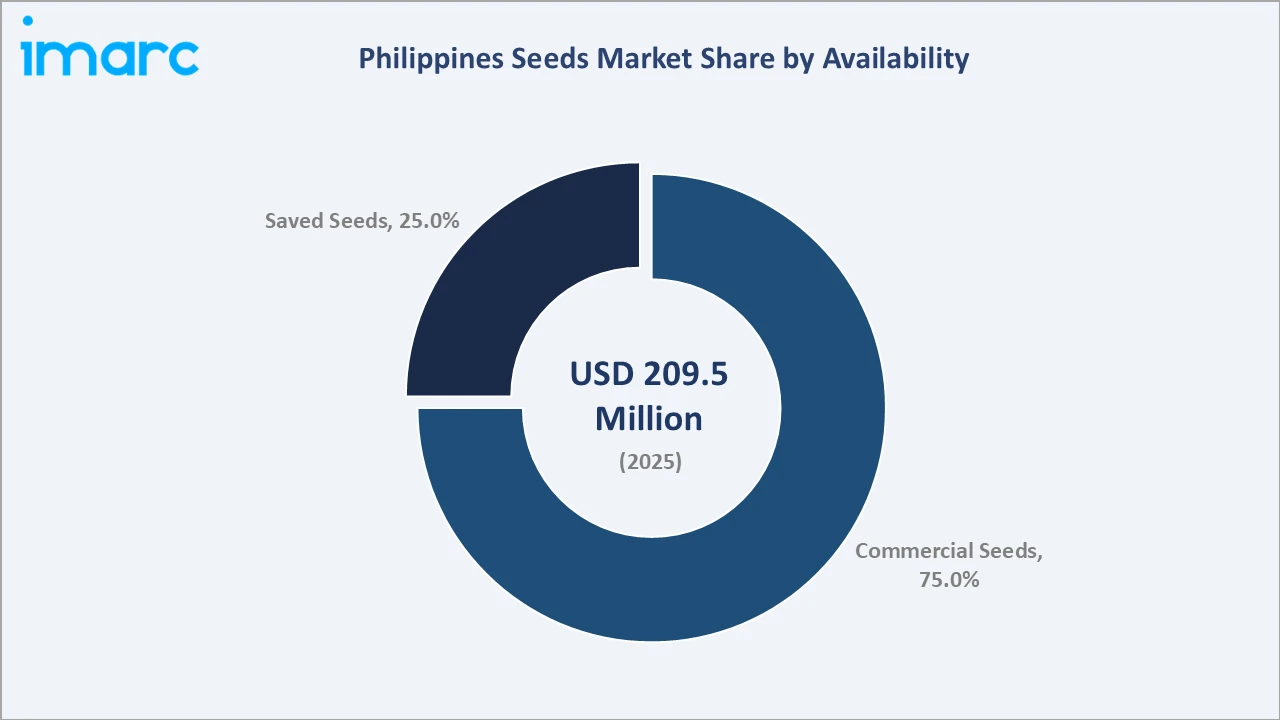
The commercial seeds segment is driven by expanding certification programs and retail network development. Saved seeds are expected to decline gradually as certified seed access improves. Policy initiatives mandating certified seed use in government-supported farming programs are accelerating the shift from saved to commercial seeds.
Regional Market Insights
| Region | Share (2025) | Key Philippines Seeds Market Drivers & Characteristics |
|---|---|---|
| Luzon | 45.0% | Driven by dense rice and corn production zones, proximity to seed distribution centers, strong commercial farming sector, and well-developed agri-input retail networks. |
| Visayas | 20.0% | Predominantly smallholder rice and vegetable farming; growing certified seed adoption; expanding commercial vegetable zones; limited last-mile distribution infrastructure. |
| Mindanao | 35.0% | Major commercial corn belt; high BT corn and hybrid seed adoption; large-scale agribusiness operations; expanding seed distribution supporting above-average regional growth. |
Luzon leads the Philippines seeds market with a 45.0% share in 2025, supported by the highest concentration of rice production zones, commercial vegetable farming belts, and seed distribution infrastructure. Mindanao holds a 35.0% share, anchored by the country's dominant commercial corn production belt where BT and hybrid corn seed adoption rates are highest.
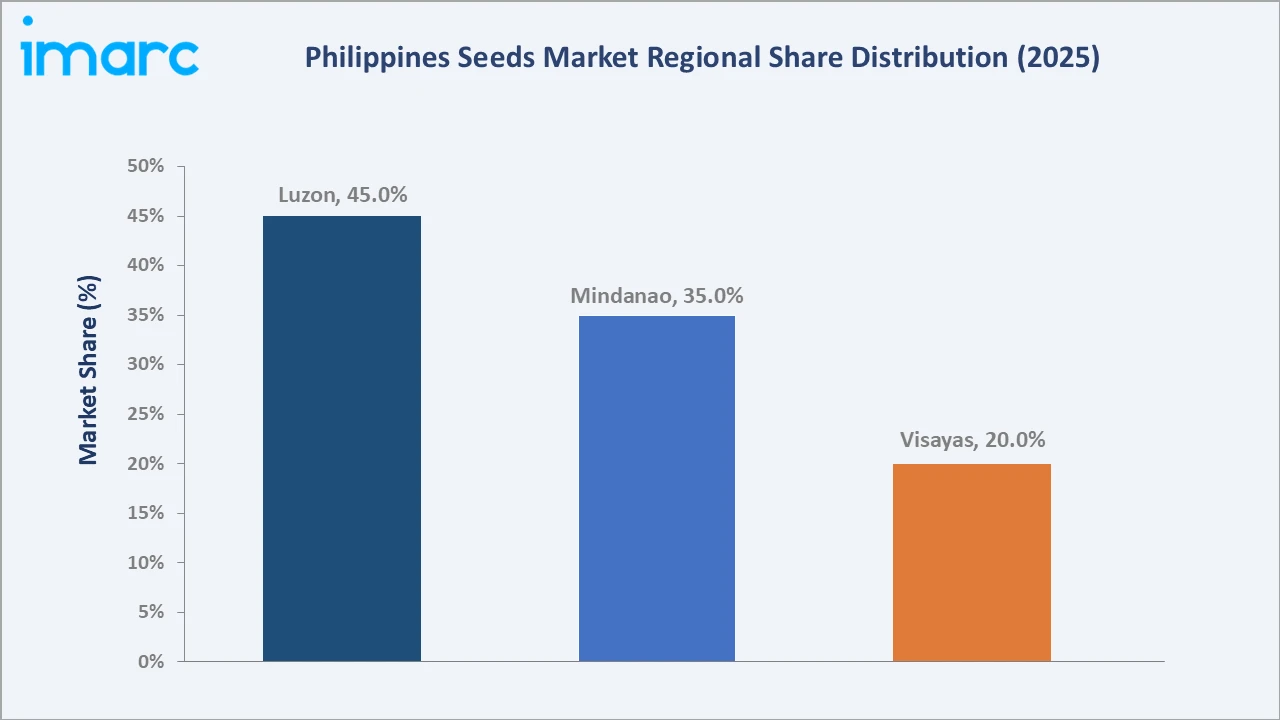
Large-scale agribusiness operations and integrated contract farming arrangements with food and feed processors drive significant commercial seed procurement volumes in the region. The Visayas region accounts for 20.0% of the market, primarily serving smallholder rice and vegetable farmers.
Competitive Landscape
The Philippines seeds market is moderately concentrated, with a mix of multinational seed corporations, regional agribusiness companies, and domestic seed producers competing across crop segments and geographies.
| Company | Key Offerings | Market Position | Core Strength |
|---|---|---|---|
| East-West Seed | Fruit and Vegetable seeds | Market Leader | Deep smallholder farmer reach; Philippines-origin brand strength; innovation in seed treatment |
| Corteva | Pioneer brand hybrid corn | Innovator | Pioneer brand equity; large commercial farm customer base; precision agri integration |
| SL-Agritech | Hybrid rice seeds | Challenger | Domestic rice genetics expertise; strong DA-PhilRice collaboration; competitive pricing |
| Ramgo Seeds International | Vegetable seeds, Cereal, Fruit seeds | Emerging Player | Domestic market knowledge; broad vegetable seed portfolio; affordability positioning |
Key players include East-West Seed, Corteva, SL-Agritech, Ramgo Seeds International, and others.
Key Company Profiles
East-West Seed
East-West Seed is a Philippines-founded multinational vegetable seed company. The company maintains strong market leadership in the vegetable seed segment, with a product portfolio exceeding 400 varieties covering tomatoes, bitter gourd, eggplant, pepper, and leafy vegetables. The company's deep farmer outreach network and extension service capabilities support its position as the country's leading vegetable seed supplier.
- Key Offerings: Fruit and vegetable seeds
- Key Developments: In July 2025, East-West Seed Philippines launched Nutri Shield+, a next-generation seed coating technology incorporating micronutrient fortification and bioprotective agents to enhance early seedling vigor and protect against early-stage pathogens.
- Strategic Focus: The company's strategic focus centers on expanding its treated seed portfolio, strengthening digital farmer engagement platforms, and increasing market penetration in Mindanao and Visayas through targeted extension service programs. Continued investment in locally adapted variety development and farmer capacity building programs supports its long-term market leadership. The company is also expanding its seed coating technology pipeline to address climate-related seedling establishment challenges.
Ramgo Seeds International
Ramgo International Corporation is one of the Philippines’ oldest and most established domestic seed companies. The company offers a broad portfolio of hybrid seeds and open-pollinated varieties (OPVs) for both major and minor lowland and highland crops, distributed through farm dealers, crop financiers, supermarkets, hardware stores, and department stores nationwide. Ramgo’s long-standing domestic distribution network and farmer trust position it as one of the most recognized Philippine-origin seed brands in the smallholder and urban gardening market.
- Key Offerings: Vegetable seeds, Cereal, Fruit seeds
- Strategic Focus: Ramgo’s strategic focus centers on strengthening its domestic distribution depth across the smallholder farmer and urban gardening segments, expanding its hybrid seed portfolio for high-value vegetables and fruit crops, and growing its contract seed production business for international markets. The company is prioritizing product accessibility and affordability as a core competitive position against multinational seed companies, leveraging its five-decade brand equity and multi-channel retail presence to deepen penetration in underserved provincial and rural agricultural markets.
Market Concentration Analysis
The Philippines seeds market exhibits a moderately concentrated structure, with the top-tier participants holding significant shares across their respective crop and product segments. The market reflects a competitive interplay between established multinational seed corporations with advanced breeding technologies and domestic companies leveraging local market knowledge and farmer relationships. Overall market concentration is balanced between competitive pressure in the commercial hybrid segments and fragmented dynamics in the conventional and saved seed segments.
Market concentration is expected to evolve incrementally through 2034 as technology-differentiated product offerings, digital channel development, and certified seed adoption programs reshape competitive positioning. The commercial seed segment shows higher concentration driven by certified variety approval requirements and distribution network investments. In contrast, the vegetable seed segment maintains lower concentration with diverse domestic and international suppliers competing across price and variety dimensions.
Investment & Growth Opportunities
Highest Growth Segments
Genetically modified (GM) seeds represent the fastest-growing segment in the Philippines seeds market, projected to expand at a 1.85% CAGR during 2026–2034, followed by commercial seeds at 1.52% CAGR. Among regional markets, Visayas leads growth at 1.42% CAGR, followed by Mindanao at 1.31% CAGR and Luzon at 1.15% CAGR. Conventional seeds are expected to grow at 0.89% CAGR, while saved seeds record the slowest growth at 0.48% CAGR.
Emerging Investment Opportunities
The Philippines hybrid rice seed segment, with penetration rates significantly below regional peers despite government yield-enhancement mandates, represents the highest-potential emerging investment opportunity in the Philippines seeds market. Hybrid rice adoption investment combines germplasm development, farmer education, and commercial distribution network building — creating an investable, scalable business model aligned with national food security priorities and projected to deliver above-market growth through 2034.
Investment Themes
- Hybrid Rice Seed Commercialization in Luzon's Commercial Rice Belt: Investment in locally adapted hybrid rice germplasm development and commercial distribution targeting yield-conscious commercial rice farmers in Luzon and Visayas represents the single largest under-penetrated growth opportunity in the Philippines seeds market, with hybrid rice penetration well below Vietnam and Indonesia benchmarks.
- Vegetable Seed Technology for High-Value Crop Expansion: The growing domestic and export demand for high-value vegetables creates a premium market for advanced vegetable seed varieties with improved disease resistance, extended shelf life, and nutritional profiles. Investment in protected cultivation seed varieties and controlled-environment agricultural seed systems targeting the country's expanding commercial vegetable sector are commercially validated emerging opportunities.
Future Market Outlook (2026-2034)
The Philippines seeds market grew from USD 212.1 Million in 2026 and is expected to grow steadily at a 1.23% CAGR through 2034, reaching USD 235.2 Million, supported by structural agricultural modernization, government seed investment programs, and expanding commercial farming. Growth will be led by the commercial seeds segment and GM seed adoption in corn production zones.
Technology disruptions including gene editing, digital variety recommendation platforms, and precision seed treatment are expected to incrementally reshape competitive dynamics and drive premium product market expansion through the forecast period. The transition from subsistence farming to commercial-scale operations will accelerate certified seed adoption and support above-trend growth in hybrid and treated seed segments.
Research Methodology
This report was developed using a rigorous multi-step research methodology combining primary and secondary data collection, expert consultation, and quantitative forecasting models.
Primary Research
Structured interviews and surveys with seed company executives, agricultural extension officers, farm cooperatives, and input retailers across Luzon, Visayas, and Mindanao providing ground-level market intelligence.
Secondary Research
Comprehensive review of government agricultural statistics from the Philippine Statistics Authority, Bureau of Plant Industry data, PhilRice and PhilMaize publications, industry association reports, and peer-reviewed agricultural journals.
Bottom-Up Market Sizing
Market size estimates derived from product-level seed volumes and per-unit values across crop types, validated through producer revenue analysis and distribution channel value assessments.
Forecasting Model
CAGR-based forward projections incorporating macroeconomic variables, crop production growth trends, technology adoption curves, policy impact assessments, and competitive landscape evolution to generate segment-level forecasts through 2034.
Philippines Seeds Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Genetically Modified Seeds, Conventional Seeds |
| Seed Types Covered |
|
| Traits Covered | Herbicide-Tolerant (HT), Insecticide-Resistant (IR), Others |
| Availabilities Covered | Commercial Seeds, Saved Seeds |
| Seed Treatments Covered | Treated, Untreated |
| Regions Covered | Luzon, Visayas, Mindanao |
| Companies Covered | East-West Seed, Corteva, SL-Agritech, Ramgo Seeds International, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Philippines seeds market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Philippines seeds market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Philippines seeds industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Philippines Seeds Market Report
The Philippines seeds market was valued at USD 212.1 Million in 2026, having grown from USD 197.1 Million in 2020 at a steady historical growth rate.
The market is projected to grow at a CAGR of 1.23% during 2026-2034, reaching USD 235.2 Million by 2034.
Conventional seeds dominate with a 65.0% market share in 2025, driven by smallholder rice and vegetable farmers using open-pollinated and seed-saving varieties.
Genetically modified seeds account for 35.0% of the market in 2025, primarily BT corn and herbicide-tolerant varieties in commercial corn production zones.
Commercial seeds lead with a 75.0% market share in 2025, reflecting increased certified seed adoption through government programs and private retail networks.
Luzon leads the national market with a 45.0% share in 2025, supported by dense rice and vegetable production zones and strong seed distribution infrastructure.
Key drivers include growing population and food demand, government seed distribution programs, expanding commercial agriculture, and increasing hybrid seed adoption.
Key players include East-West Seed, Corteva, SL-Agritech, Ramgo Seeds International, and others.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade