
Plant Genotyping Equipment Market Size, Share, Trends and Forecast by Equipment, Application, End Use, and Region, 2026-2034
Plant Genotyping Equipment Market Size, Share, Trends & Forecast (2026-2034)
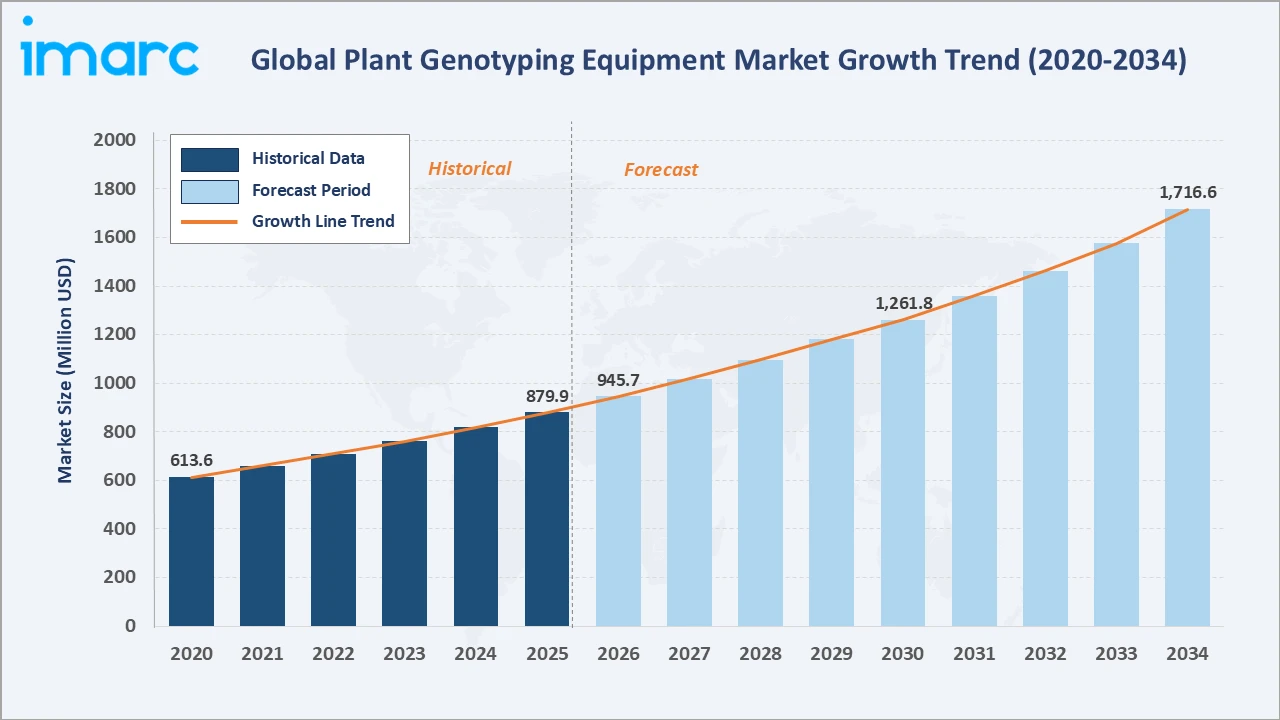
The plant genotyping equipment market grew from USD 879.9 Million in 2025 to USD 945.7 Million in 2026 and is projected to reach USD 1,716.6 Million by 2034, growing at a CAGR of 7.48% during 2026-2034. According to the Food and Agriculture Organization (FAO), global crop production must increase by 70% by 2050 to feed a projected population of 9.1 billion, making accelerated plant breeding through genomic tools a critical agricultural priority, directly driving sustained demand for high-throughput genotyping equipment across commercial seed companies, national agricultural research systems, and academic plant science programs. SNP genotyping equipment leads at 36.8%, breeding commands the largest application share at 41.7%, and Europe holds the leading regional position at 34.2%.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 879.9 Million |
|
Market Size (2026) |
USD 945.7 Million |
|
Forecast Market Size (2034) |
USD 1,716.6 Million |
|
CAGR (2026-2034) |
7.48% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Equipment |
SNP Genotyping Equipment (36.8%, 2025) |
|
Dominant Application |
Breeding (41.7%, 2025) |
|
Leading Region |
Europe (34.2%, 2025) |
The plant genotyping equipment market grew from USD 613.6 Million in 2020 to USD 879.9 Million by 2025 and is estimated to reach USD 945.7 Million in 2026. The market is projected to reach USD 1,261.8 Million by 2030 and USD 1,716.6 Million by 2034.
To get more information on this market, Request Sample
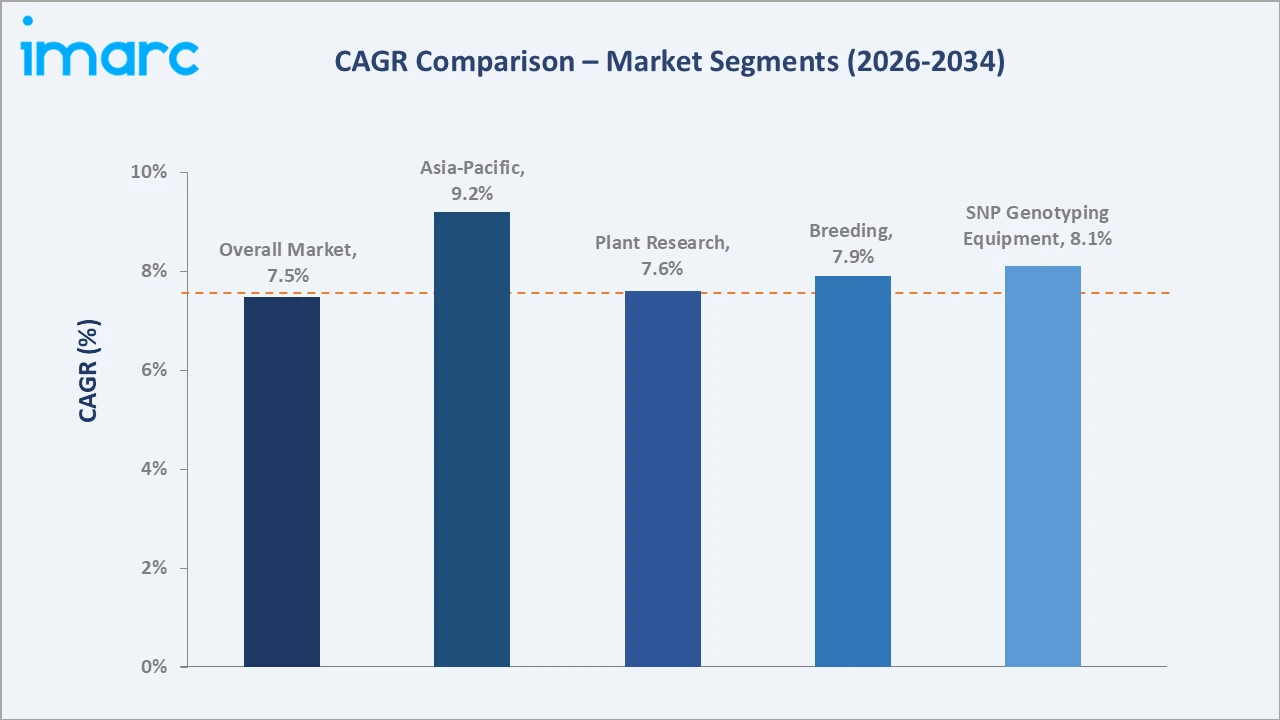
SNP genotyping equipment grows at ~8.1% CAGR through rising adoption of high-density SNP arrays in genomic selection programs. Breeding application expands at ~7.9% CAGR through molecular marker-assisted selection. Asia-Pacific grows fastest at ~9.2% CAGR through national genomics investment programs in China, India, and Australia.
Executive Summary
The plant genotyping equipment market is experiencing robust and sustained growth, underpinned by the global agricultural sector's urgent need to develop higher-yielding, disease-resistant, and climate-resilient crop varieties at accelerated timelines through precision molecular breeding technologies. The market is driven by the adoption of genomic selection in commercial breeding programs, declining costs of next-generation sequencing, and expanding government investment in crop biotechnology.
SNP genotyping equipment dominates at 36.8% through its critical role in population-scale marker-assisted selection. Breeding leads application demand at 41.7% as the primary end-use driving equipment procurement. Europe holds 34.2% market share through its advanced plant variety protection framework and deeply integrated genomic selection across commercial breeding programs.
Key Market Insights
|
Insight |
Data |
|
Dominant Equipment |
SNP Genotyping Equipment - 36.8% share (2025) |
|
Dominant Application |
Breeding - 41.7% share (2025) |
|
Leading Region |
Europe - 34.2% (2025) |
|
Key Market Opportunity |
Climate change necessitating rapid development of drought- and heat-tolerant crop varieties represents an incremental genotyping equipment demand opportunity through accelerated genomic selection programs by 2030 |
Key Analytical Observations Supporting the Above Data:
- SNP Genotyping Equipment at 36.8%: Single nucleotide polymorphism (SNP) genotyping platforms are the cornerstone of modern genomic selection in plant breeding, enabling simultaneous analysis of genetic markers.
- Breeding at 41.7%: Commercial plant breeding is the primary demand driver for genotyping equipment, as seed companies integrate genomic selection across wheat, maize, rice, soybean, and specialty crops to reduce breeding cycle times from 8-12 years to 3-5 years. Genomic estimated breeding values (GEBVs) require dense SNP genotyping of large training populations, generating consistent high-volume equipment demand from leading agricultural biotechnology companies.
- Europe at 34.2%: Europe's leadership reflects the Netherlands' and Germany's position as global plant breeding hubs combined with the EU funding for agricultural research and strict plant variety protection regulations requiring molecular characterization for registration.
Plant Genotyping Equipment Market Overview
The plant genotyping equipment market encompasses instruments, platforms, and automated systems used to analyze the genetic makeup of plant organisms for breeding, research, product development, and quality assessment applications. Key equipment categories include SNP genotyping arrays and instruments, real-time PCR systems, capillary electrophoresis DNA analyzers, automated liquid handling platforms, and next-generation sequencing instruments adapted for plant genomics applications. The market serves a diverse user base including commercial seed and biotechnology companies, academic and government research institutions, and contract genomics service providers. Declining sequencing costs have fundamentally democratized access to genomic tools, expanding the addressable market from large seed multinationals to mid-size regional breeding programs, public sector research institutions, and developing country national agricultural research systems.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
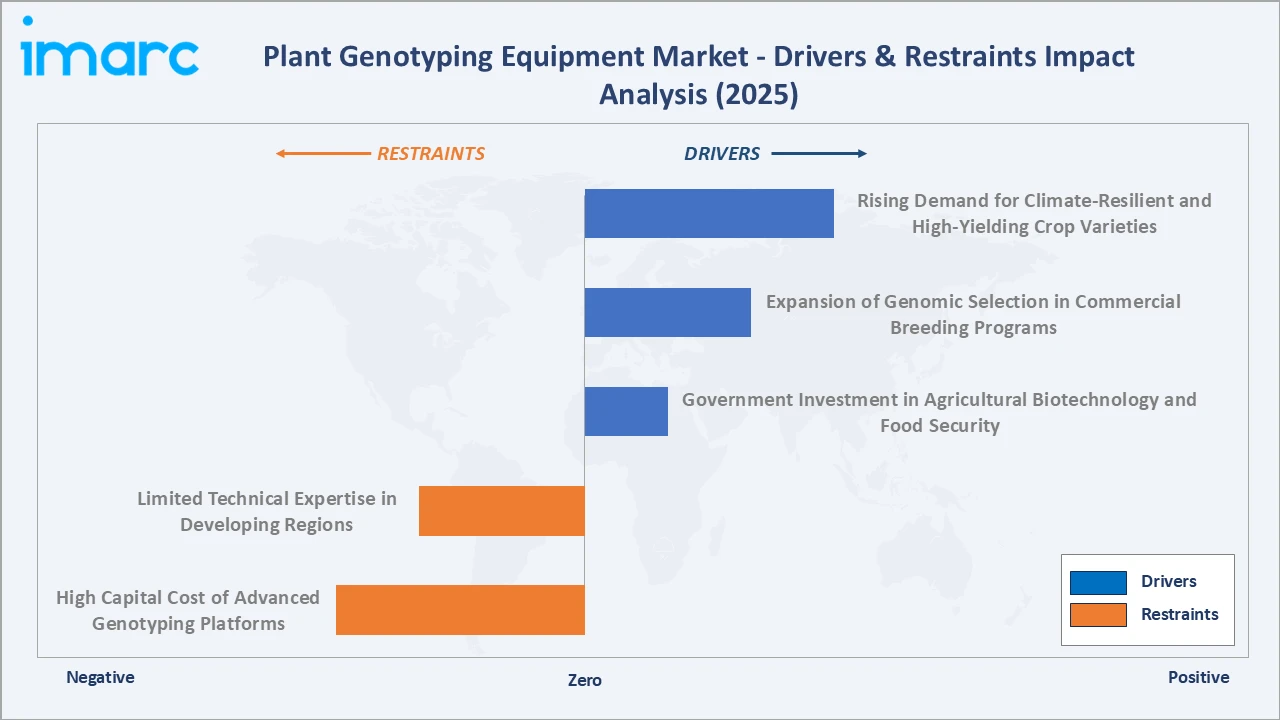
- Rising Demand for Climate-Resilient and High-Yielding Crop Varieties: With global food demand projected to increase 70% by 2050 and climate change threatening yield stability in major agricultural regions, commercial seed companies and national breeding programs are intensifying investment in genomic selection to accelerate the development of stress-tolerant, high-yielding crop varieties.
- Expansion of Genomic Selection in Commercial Breeding Programs: Major seed companies have fully integrated genomic selection across their elite breeding programs for corn, soybeans, wheat, and canola. Public-sector programs at CGIAR centers and national agricultural research systems are similarly adopting genomic selection for rice, cassava, and sorghum improvement, collectively expanding the installed base of high-throughput genotyping platforms.
- Government Investment in Agricultural Biotechnology and Food Security: National governments and multilateral organizations are significantly increasing investment in agricultural genomics as a strategic food security tool. The CGIAR Research Programs receive USD 900 Million in annual funding, with significant allocations to genomics-enabled breeding. In November 2025, the USDA’s National Institute of Food and Agriculture (NIFA) allocated $4.4 million to 10 research projects focused on minimizing the risks associated with both intentional and accidental food contamination, driving equipment procurement at US land-grant universities and agricultural research stations.
Market Restraints
- High Capital Cost of Advanced Genotyping Platforms: Enterprise-grade SNP genotyping systems represent capital expenditures, placing them beyond the budgetary reach of mid-tier breeding companies and resource-limited national agricultural research programs in developing countries. Annual maintenance contracts, adding 15-20% of the instrument purchase price, further elevate the total cost of ownership, constraining equipment penetration in price-sensitive market segments.
- Limited Technical Expertise in Developing Regions: Effective operation of advanced genotyping platforms requires specialized expertise in molecular biology, genomics, and bioinformatics that remains concentrated in high-income country research institutions and large commercial breeding programs. The shortage of trained personnel across Sub-Saharan Africa, South Asia, and Southeast Asia, regions with high agricultural development needs, limits the adoption of sophisticated genotyping equipment even when capital funding is available.
Market Opportunities
- Integration of Artificial Intelligence with Genotyping Platforms: AI-powered genomic prediction models are dramatically improving the accuracy of genomic estimated breeding values from genotyping data, increasing the value proposition of genotyping investments for breeding programs. Companies integrating AI-based trait prediction software with genotyping hardware, creating integrated genotyping-plus-prediction workflows, can command premium pricing and create switching cost advantages versus pure equipment providers.
- Emerging Market Expansion through Genotyping-as-a-Service Models: Contract genomics service providers offering genotyping-as-a-service are expanding access to plant genotyping capabilities in markets where capital equipment investment is not feasible. This service model, where breeding programs send plant tissue samples to centralized service labs for genotyping, is expanding the total addressable market by serving smaller regional seed companies and national research programs without the capital and operational infrastructure for in-house genotyping.
Market Challenges
- Data Management Complexity and Bioinformatics Infrastructure Requirements: High-throughput plant genotyping generates terabytes of genomic data per breeding cycle that requires substantial bioinformatics infrastructure, specialized analytical software, and expert data scientists to process, quality-control, and translate into actionable breeding decisions. Many breeding programs investing in genotyping equipment face high secondary costs in data management infrastructure and personnel that are not fully anticipated at the equipment procurement decision stage.
- Regulatory Complexity for Genetically Improved Plant Varieties: Varying international regulatory frameworks for plant variety registration, including molecular characterization requirements and national plant variety protection laws, create compliance complexity for genotyping service providers and equipment users operating across multiple regulatory jurisdictions, particularly in emerging markets with evolving biotechnology regulatory frameworks.
Emerging Market Trends
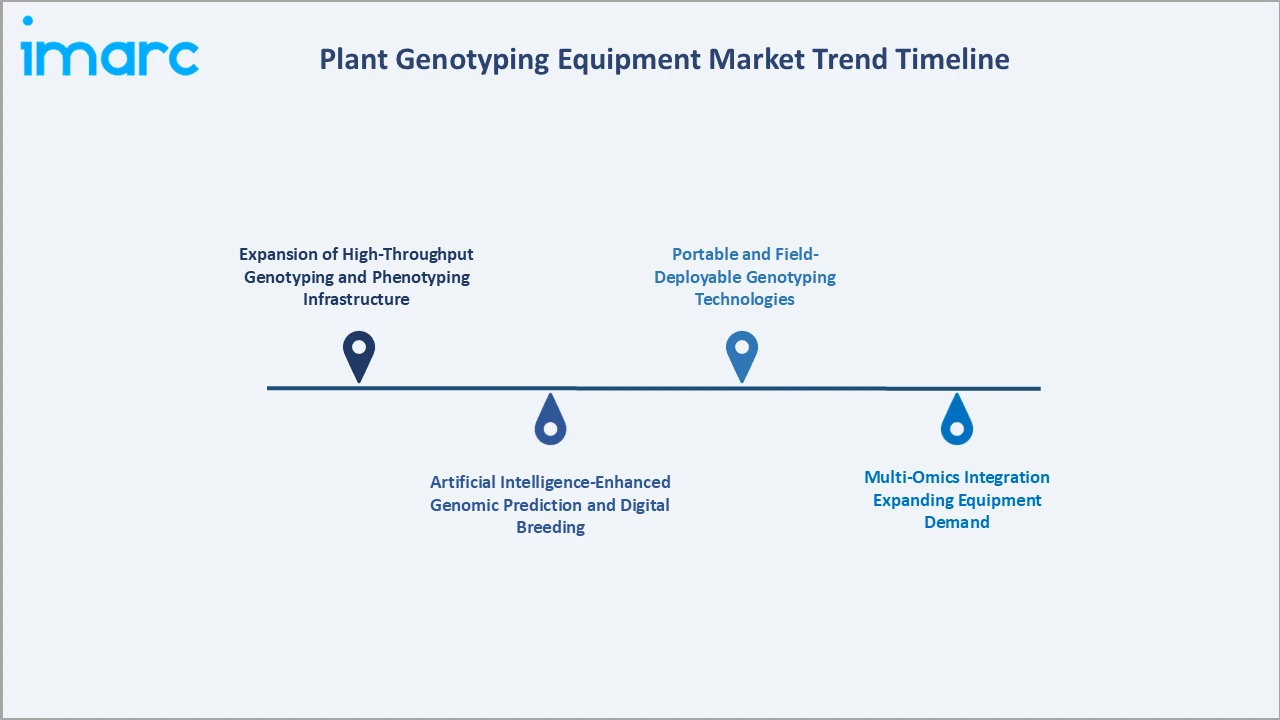
1. Expansion of High-Throughput Genotyping and Phenotyping Infrastructure
In September 2026, Dr. Jitendra Singh inaugurated the SPROUT facility at BRIC-NIPGR, New Delhi, to accelerate the development of climate-resilient crops. The controlled-environment facility enables high-throughput phenotyping and precision stress testing, supporting faster gene discovery, trait validation, and crop improvement, with a major focus on chickpea. The launch of the SPROUT facility reflects increasing investment in advanced genomic and precision phenotyping infrastructure to accelerate gene discovery, trait validation, and climate-resilient crop breeding.
2. Artificial Intelligence-Enhanced Genomic Prediction and Digital Breeding
Machine learning models trained on large-scale genotyping datasets are significantly improving genomic estimated breeding value (GEBV) prediction accuracy, increasing the economic return on genotyping investment for breeding programs. Companies, including specialized agricultural AI startups, are integrating AI prediction engines with genotyping data pipelines, creating digital breeding platforms where genotyping data flows directly into AI models generating breeding recommendations. This convergence shifts the value perception of genotyping equipment from a laboratory instrument to a critical data generation node in an AI-powered breeding decision system.
3. Portable and Field-Deployable Genotyping Technologies
The plant genotyping equipment market is witnessing a shift toward compact, portable systems that enable rapid genetic analysis directly in fields and breeding stations. These technologies reduce dependence on centralized laboratories and shorten sample-to-result timelines. Advances in portable sequencing, PCR, and point-of-use molecular diagnostics are enabling real-time identification of desirable traits, pathogens, and genetic variations, supporting faster precision breeding and crop improvement decisions.
4. Multi-Omics Integration Expanding Equipment Demand
Advanced plant breeding programs are increasingly integrating genotypic data with phenotypic, transcriptomic, metabolomic, and epigenomic data in multi-omics analyses that require diverse analytical equipment operating in coordinated workflows. This multi-omics convergence is expanding procurement beyond traditional genotyping equipment to include mass spectrometers, spectroscopy systems, and imaging platforms that collectively generate the data needed for holistic genomic-to-phenotype prediction. Equipment manufacturers developing integrated multi-omics workflow solutions are capturing higher-value contracts from elite breeding programs.
Industry Value Chain Analysis
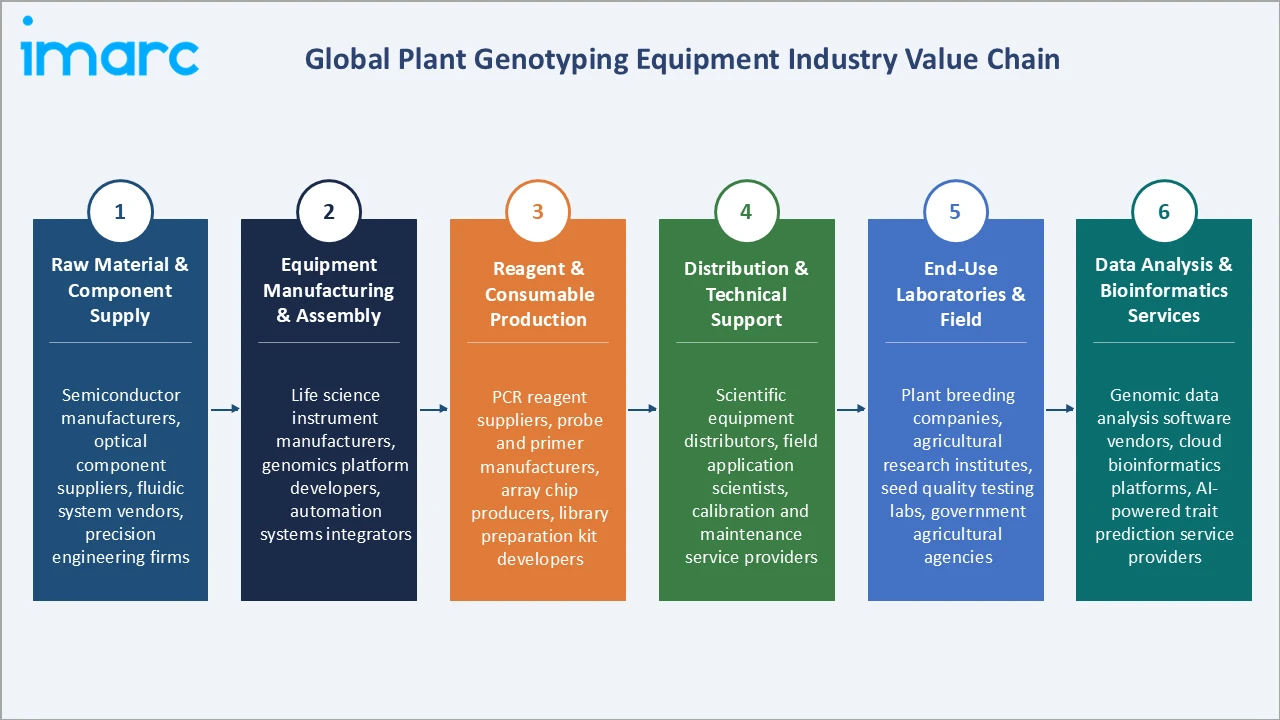
The plant genotyping equipment value chain spans raw material and component supply, instrument manufacturing, reagent and consumable production, distribution and technical support, end-use laboratory and field deployment, and data analysis and bioinformatics services.
|
Stage |
Key Players |
|
Raw Material & Component Supply |
Semiconductor manufacturers, optical component suppliers, fluidic system vendors, precision engineering firms. |
|
Equipment Manufacturing & Assembly |
Life science instrument manufacturers, genomics platform developers, automation systems integrators. |
|
Reagent & Consumable Production |
PCR reagent suppliers, probe and primer manufacturers, array chip producers, library preparation kit developers. |
|
Distribution & Technical Support |
Scientific equipment distributors, field application scientists, calibration and maintenance service providers. |
|
End-Use Laboratories & Field |
Plant breeding companies, agricultural research institutes, seed quality testing labs, government agricultural agencies. |
|
Data Analysis & Bioinformatics Services |
Genomic data analysis software vendors, cloud bioinformatics platforms, AI-powered trait prediction service providers. |
Reagent and consumable production represent a critical recurring revenue stage in the plant genotyping value chain, where equipment manufacturers generate 40-60% of installed base revenue through consumable reagent kits, SNP arrays, flow cells, and sample preparation materials with high switching costs and margin profiles. The data analysis stage is gaining increasing strategic importance as bioinformatics software and AI-powered genomic prediction services create subscription-based revenue streams that extend equipment supplier relationships throughout the breeding season.
Technology Landscape in the Plant Genotyping Equipment Industry
Next-Generation Sequencing (NGS) Technology
NGS technology has become the dominant high-throughput genotyping infrastructure in commercial plant breeding programs. Short-read sequencing enables simultaneous sequencing of millions of DNA fragments per run, enabling genotyping-by-sequencing approaches that generate genome-wide marker data without requiring pre-designed SNP arrays. The introduction of an on-instrument analysis pipeline has significantly reduced genotyping data processing time from weeks to hours, making real-time breeding cycle integration more feasible for commercial programs.
KASP and PCR Technologies
Kompetitive Allele Specific PCR (KASP) assay technology has become the standard approach for targeted SNP genotyping in plant breeding programs requiring cost-effective validation of specific marker-trait associations. KASP assays operate on standard real-time PCR instruments, making them accessible to programs with existing real-time PCR infrastructure, and require minimal sample preparation, enabling high-throughput targeted genotyping. The combination of KASP's affordability and the ubiquity of real-time PCR instruments has made targeted SNP genotyping accessible to breeding programs across all resource levels.
Long-Read Sequencing and Structural Variant Detection
Long-read nanopore sequencing and HiFi long-read technology are enabling the resolution of complex genomic regions, repeat-rich sequences, polyploid genomes, and structural variants that are inaccessible to short-read NGS approaches. In plant genomics, long-read sequencing is enabling de novo assembly of complex polyploid crop genomes (wheat, potato, oat), structural variant genotyping, and real-time field diagnostics, creating new equipment demand categories beyond traditional SNP-focused genotyping applications.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Equipment |
SNP Genotyping Equipment |
36.8% |
2025 |
|
Application |
Breeding |
41.7% |
2025 |
|
End Use |
Laboratory |
🔒 |
2025 |
|
Region |
Europe |
34.2% |
2025 |

By Equipment
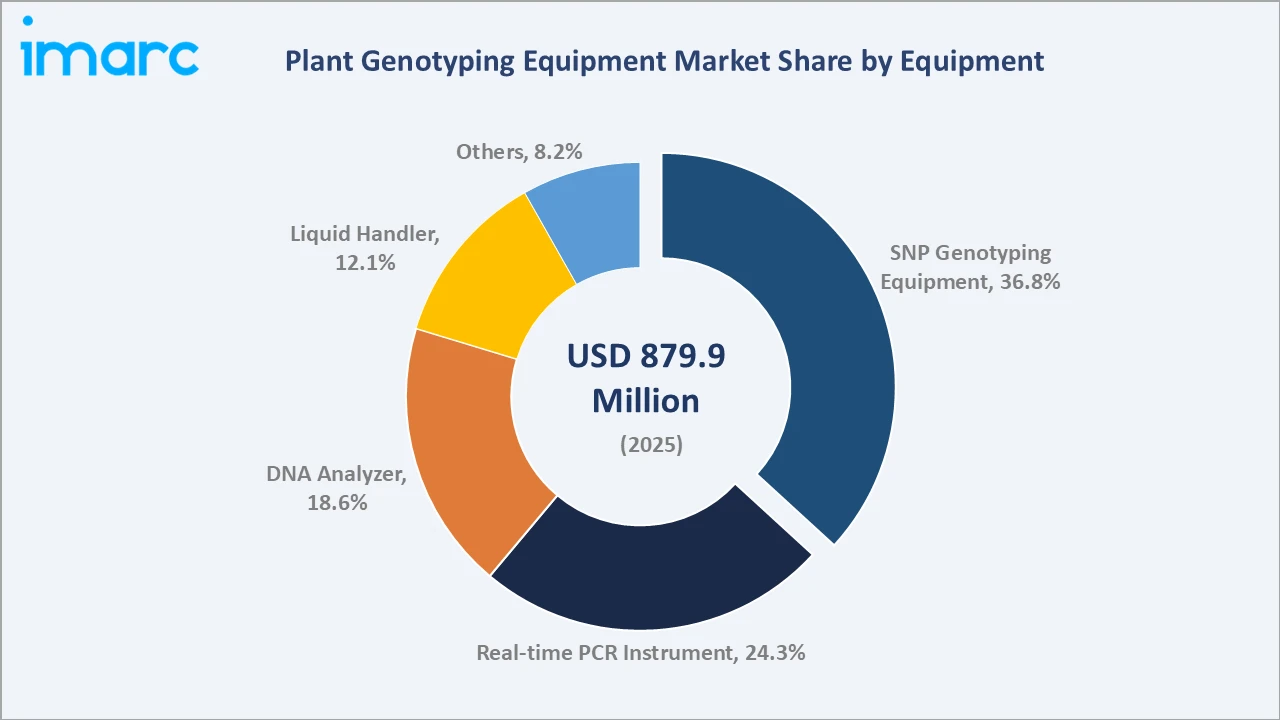
SNP genotyping equipment commands 36.8%, driven by the widespread adoption of BeadArray technology and microarray platforms in commercial genomic selection programs for major crop species. High-density SNP arrays enable genome-wide association studies (GWAS) and genomic selection with statistical power sufficient to capture complex trait architecture across diverse breeding populations.
To access detailed market analysis, Request Sample
Real-time PCR Instruments at 24.3% serve as the core equipment for targeted marker-assisted selection using KASP assays across breeding programs at all resource levels. DNA analyzers at 18.6%, primarily capillary electrophoresis instruments, provide SSR microsatellite marker genotyping, variety fingerprinting, and GMO event detection. Liquid handlers at 12.1% enable automated high-throughput sample preparation workflows essential for commercial-scale genotyping operations.
By Application
Breeding dominates at 41.7% in 2025, as commercial seed companies and public breeding programs deploy genomic selection across their complete breeding pipelines for major crop species. The integration of genotyping data into genomic estimated breeding value (GEBV) calculations has transformed plant breeding from phenotype-dependent to genotype-guided, requiring continuous high-throughput genotyping of training populations, selection candidates, and progeny testing populations.
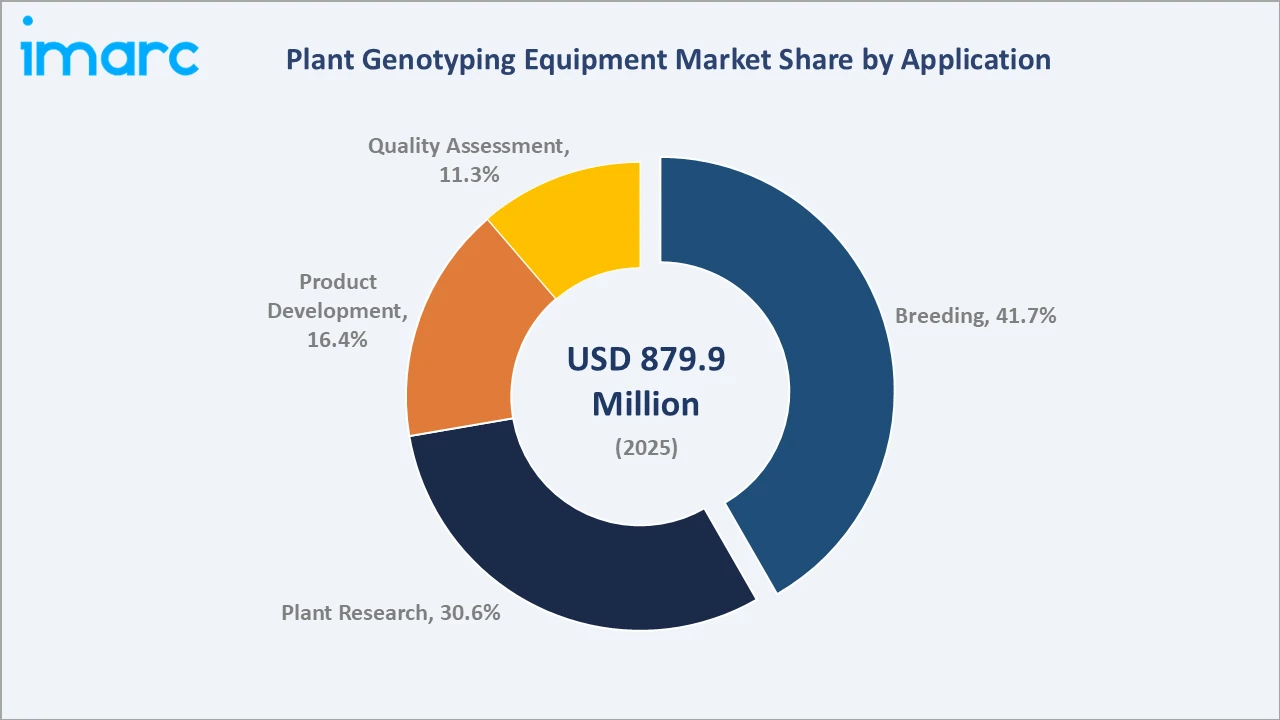
Plant research at 30.6% encompasses genomic studies at academic and government research institutions, including gene discovery, quantitative trait loci (QTL) mapping, and pan-genome analysis, that generate fundamental knowledge enabling commercial breeding program adoption. Product development at 16.4% covers molecular characterization for variety registration and plant variety protection applications. Quality assessment at 11.3% addresses seed purity testing, GMO detection, and varietal identity confirmation in the global seed trade.
Regional Market Insights
|
Region |
Share (2025) |
Key Plant Genotyping Equipment Market Drivers & Characteristics |
|
Europe |
34.2% |
Reflecting the advanced plant breeding industry, strong EU agricultural biotechnology research funding, and deep integration of genomic selection in European commercial seed programs. |
|
North America |
28.6% |
Reflecting the United States' leadership in agricultural biotechnology, large-scale genomic selection programs, and funded crop improvement research initiatives driving high-throughput genotyping demand. |
|
Asia-Pacific |
24.7% |
Reflecting China's massive national crop genomics programs, Japan's precision agriculture biotechnology investments, India's rising agricultural research capacity, and Australia's advanced wheat and barley breeding programs. |
|
Latin America |
7.1% |
Reflecting Brazil's soybean and sugarcane genomic selection programs, Argentina's advanced agricultural biotechnology sector, and growing adoption of genotyping in staple crop improvement programs. |
|
Middle East & Africa |
5.4% |
Reflecting emerging adoption of plant genotyping technologies in the advanced agricultural biotechnology sector and growing demand for drought-tolerant crop development in water-stressed agricultural systems. |
Europe's 34.2% market share reflects the continent's unique combination of advanced commercial plant breeding leadership, strong plant variety protection regulatory frameworks requiring molecular characterization, and substantial EU research funding supporting agricultural genomics.
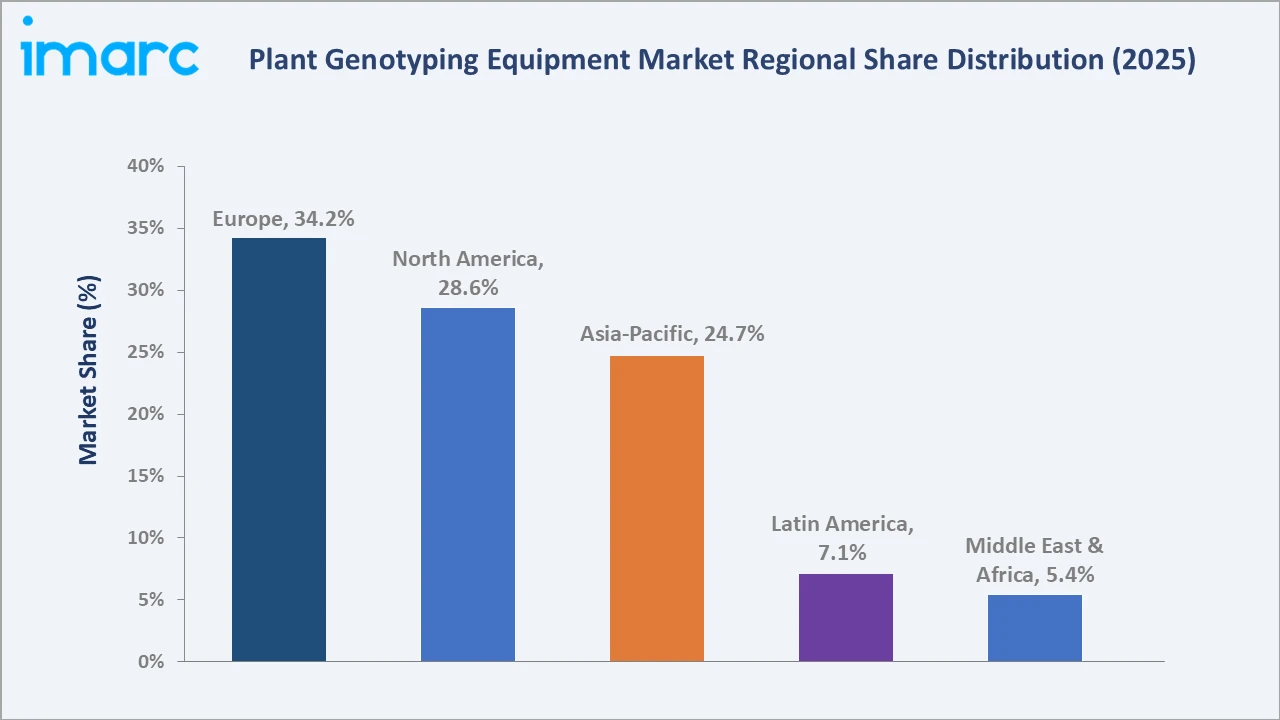
North America's 28.6% reflects the United States' leadership in agricultural biotechnology. Asia-Pacific's 24.7%, growing at the fastest regional CAGR of ~9.2%, is driven by China's ambitious National Programs for crop genome research and India's expanding agricultural biotechnology investment. Latin America's 7.1% centers on genomics programs for tropical crop improvement in Brazil. The Middle East and Africa at 5.4% represent the highest growth potential region as climate stress intensifies demand for drought-tolerant variety development.
Competitive Landscape
The plant genotyping equipment market features a concentrated competitive landscape led by large-scale life science instrument manufacturers alongside specialized genomics service providers and technology innovators. Market leadership is determined by genotyping throughput capabilities, cost per data point, crop species validation portfolio, reagent ecosystem depth, and technical application support for plant-specific genotyping workflows.
|
Company |
Key Products |
Market Position |
Core Strength |
|
Illumina, Inc. |
iScan System ordering, Infinium XT iSelect-96 Kit |
Market Leader |
Illumina, Inc. provides high-throughput microarray and next-generation sequencing (NGS) technologies that empower agricultural researchers and breeders. |
|
Thermo Fisher Scientific Inc. |
Ion PGM Sequencer |
Market Leader |
Thermo Fisher Scientific Inc. provides core instruments, software, and assay solutions that drive plant genotyping and agricultural biotechnology. |
|
LGC Limited |
Amp-Seq One kits, Flex-Seq, NxSeq kits & single cell beads, KASP genotyping panels |
Established Player |
LGC Limited, through its genetics division LGC Biosearch Technologies, is a global leader in providing end-to-end plant genotyping equipment, chemistries, and automated platforms. |
|
Daicel Corporation |
myBaits Custom Hybridization Capture Kits |
Established Player |
Daicel Corporation plays a critical role in the plant genotyping and agrigenomics market primarily through its specialized division, Daicel Arbor Biosciences. |
|
NimaGen |
EasySeq Library Prep by Reverse |
Niche Player |
Their EasySeq kits offer flexible, scalable processing for agricultural sciences, helping labs analyze plant traits and markers efficiently. |
The competitive landscape is being reshaped by the cost competition between array-based SNP genotyping and sequencing-based approaches, competing on sequencing cost reduction while array providers protect their established positions in validated commercial programs.
Key Company Profiles
Illumina, Inc.
Illumina, Inc. is a genomics technology company offering next-generation sequencing (NGS) and microarray-based solutions for plant genotyping and agrigenomics. Its technologies support SNP screening, genetic variation analysis, trait identification, and genotyping-by-sequencing across diverse crop species. The company’s solutions are widely applicable in marker-assisted breeding, genomic selection, and the development of crops with improved yield, disease resistance, and environmental resilience.
- Key Products: iScan System ordering, Infinium XT iSelect-96 Kit.
- Strategic Focus: Advancing high-throughput sequencing and array-based genotyping solutions to support large-scale plant genomic analysis and precision breeding. Its strategy emphasizes improving genomic data accuracy, scalability, and workflow efficiency to facilitate marker-assisted selection, trait discovery, and development of improved crop varieties.
Thermo Fisher Scientific Inc.
Thermo Fisher Scientific Inc. is a prominent provider of genomics and molecular biology solutions supporting plant genotyping and agricultural research. The company offers technologies for SNP genotyping, sequencing, PCR-based analysis, and genetic variation assessment across a wide range of crop species. Its solutions support applications such as marker-assisted breeding, trait discovery, genetic diversity analysis, and the development of high-yielding and climate-resilient crop varieties.
- Key Products: Ion PGM Sequencer.
- Strategic Focus: Expanding high-throughput, scalable, and automated plant genotyping solutions to improve the efficiency of crop genomic analysis. The company emphasizes advanced SNP genotyping, sequencing, and integrated workflows to support precision breeding, trait selection, and accelerated crop improvement programs.
Market Concentration Analysis
The plant genotyping equipment market is moderately concentrated, with the top 3 players collectively accounting for an estimated 45-55% of total market revenue through their broad equipment portfolios, extensive validated reagent ecosystems, and deep commercial breeding program customer relationships. The remaining market share is distributed among specialized providers creating a tiered competitive structure differentiated by technology approach, geographic focus, and customer segment.
The market's technological evolution, driven by the cost-reduction trajectory of NGS and the emergence of portable sequencing, is creating structural pressure on the established array-based genotyping equipment segment, potentially reshaping competitive dynamics as sequencing-based approaches capture an increasing share of the market. Companies with diversified portfolios spanning both array and sequencing technologies are better positioned to navigate this transition than single-technology providers.
Investment & Growth Opportunities
Highest Growth Segments
Asia-Pacific genotyping equipment adoption (~9.2% CAGR), SNP genotyping equipment for genomic selection (~8.1% CAGR), breeding application demand (~7.9% CAGR), portable and field-deployable genotyping platforms, AI-integrated genomic prediction systems, and genotyping-as-a-service for emerging market programs represent the highest-return investment vectors in the plant genotyping equipment market through 2034.
Investment Themes
- AI-Integrated Genotyping-to-Prediction Platforms: Integrating machine learning genomic prediction engines with genotyping hardware and data pipelines creates a value proposition substantially above standalone equipment, enabling providers to capture subscription-based recurring revenue from AI-powered breeding decision tools. Companies developing integrated genotyping platforms with embedded AI trait predictions are commanding premium pricing and generating lower customer churn than commodity equipment providers.
- Validated Genotyping Solutions for Specialty and Minor Crops: The majority of commercial SNP arrays and validated KASP assay panels are developed for major crops (maize, wheat, soybean, rice). Developing validated genotyping solutions for specialty crops, vegetables, fruits, cotton, pulse legumes, where genomic selection is in early adoption, represents significant incremental revenue opportunities with limited current competition from established platforms.
Future Market Outlook (2026-2034)
The plant genotyping equipment market is projected to grow from USD 879.9 Million in 2025 to USD 945.7 Million in 2026, reaching USD 1,716.6 Million by 2034, exhibiting a CAGR of 7.48% during 2026-2034. The market is projected to reach an anchor value of USD 1,261.8 Million by 2030, representing the mid-period milestone at which genomic selection becomes near-universal in Tier-1 commercial breeding programs globally, field-deployable genotyping achieves commercial scale in developing markets, and AI-integrated genomic prediction platforms begin transforming equipment procurement decisions from pure throughput specifications toward data integration capabilities.
Three structural forces will define the plant genotyping equipment market through 2034. First, the global agricultural imperative to develop climate-resilient crop varieties at unprecedented speed creates durable secular demand for genotyping equipment across both commercial breeding programs and public-sector agricultural research institutions. Second, the continued cost reduction trajectory of DNA sequencing will democratize access to genome-scale genotyping data, expanding the total addressable market from large commercial programs to regional seed companies, developing country research programs, and specialty crop breeding operations previously unable to justify genotyping infrastructure investment. Third, the integration of AI, cloud computing, and multi-omics data platforms with genotyping workflows is creating new value layers above hardware, enabling equipment providers to build comprehensive digital breeding ecosystems.
Research Methodology
Primary Research
Primary research comprised in-depth interviews with commercial plant breeding program directors, agricultural genomics laboratory managers, seed company R&D vice presidents, plant geneticists, agricultural biotechnology regulatory consultants, and equipment procurement specialists. These discussions validated market size estimates, equipment adoption trends, application priorities, and technology trajectories for the 2026-2034 forecast period.
Secondary Research
Secondary research encompassed crop production statistics, company annual reports, plant variety protection office registration data, IMARC Group proprietary agricultural biotechnology databases, peer-reviewed plant genomics literature, annual reports of key market participants, and industry publications covering agricultural genomics and life science equipment market developments through 2025.
Forecasting Models
Forecasting models incorporated historical equipment adoption correlations with agricultural R&D investment, genomic selection adoption rates across crop species and geographic markets, DNA sequencing cost trajectories, government agricultural biotechnology program funding projections, and macroeconomic indicators. Both bottom-up equipment unit and average selling price modeling and top-down total market revenue approaches were cross-validated for forecast consistency across all segments and regions.
Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Equipments Covered | SNP Genotyping Equipment, Real-time PCR Instrument, DNA Analyzer, Liquid Handler, Others |
| Applications Covered | Plant Research, Breeding, Product Development, Quality Assessment |
| End Uses Covered | Greenhouse, Field, Laboratory |
| Regions Covered | Asia Pacific, Europe, North America, Latin America, Middle East and Africa |
| Countries Covered | United States, Canada, Germany, France, United Kingdom, Italy, Spain, Russia, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Mexico |
| Companies Covered | Illumina, Inc., Thermo Fisher Scientific Inc., LGC Limited, Daicel Corporation, NimaGen, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the plant genotyping equipment market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the global plant genotyping equipment market.
- The study maps the leading, as well as the fastest-growing, regional markets. It further enables stakeholders to identify the key country-level markets within each region.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the plant genotyping equipment industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Plant Genotyping Equipment Market Report
The plant genotyping equipment market reached USD 945.7 Million in 2026, driven by commercial genomic selection adoption, declining sequencing costs, government agricultural biotechnology investment, and expanding demand for climate-resilient crop variety development through molecular breeding.
The plant genotyping equipment market is projected to grow at a CAGR of 7.48% during 2026-2034, driven by genomic selection expansion in commercial breeding, Asia-Pacific agricultural genomics investment, field-deployable genotyping technology adoption, and AI-integrated breeding platform development.
The market is projected to reach USD 1,261.8 Million by 2030, representing the mid-period milestone when genomic selection becomes near-universal in Tier-1 commercial programs, field-deployable genotyping achieves scale in developing markets, and AI prediction platforms reshape equipment procurement decisions.
SNP genotyping equipment leads with a 36.8% share in 2025, driven by adoption of microarray platforms for high-density genomic selection programs in major crop species including wheat, maize, soybean, and rice.
Breeding leads with a 41.7% share in 2025, as commercial seed companies and public breeding programs integrate genomic selection across elite breeding pipelines, requiring continuous high-throughput genotyping of training populations and selection candidates across crop species.
Europe leads with a 34.2% share in 2025, anchored by the advanced commercial plant breeding industry, EU agricultural research funding, and strict plant variety protection regulations requiring molecular characterization for variety registration.
Key players include Illumina, Inc., Thermo Fisher Scientific Inc., LGC Limited, Daicel Corporation, and NimaGen, among others.
The plant genotyping equipment market is projected to reach USD 1,716.6 Million by 2034, driven by universal genomic selection adoption, developing market expansion through portable genotyping, AI-integrated breeding platform growth, and climate-change-driven acceleration of crop improvement programs globally.
Key opportunities include AI-integrated genotyping-to-prediction platforms commanding premium pricing, field-deployable genotyping for developing-market agricultural programs, validated genotyping solutions for specialty and minor crops, and genotyping-as-a-service models expanding access to resource-limited breeding programs.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade