
India Customer Journey Analytics Market Size, Share, Trends and Forecast by Component, Touchpoint, Deployment, Organization Size, Application, Industry Vertical, and Region, 2026-2034
India Customer Journey Analytics Market Size, Share, Trends & Forecast (2026-2034)
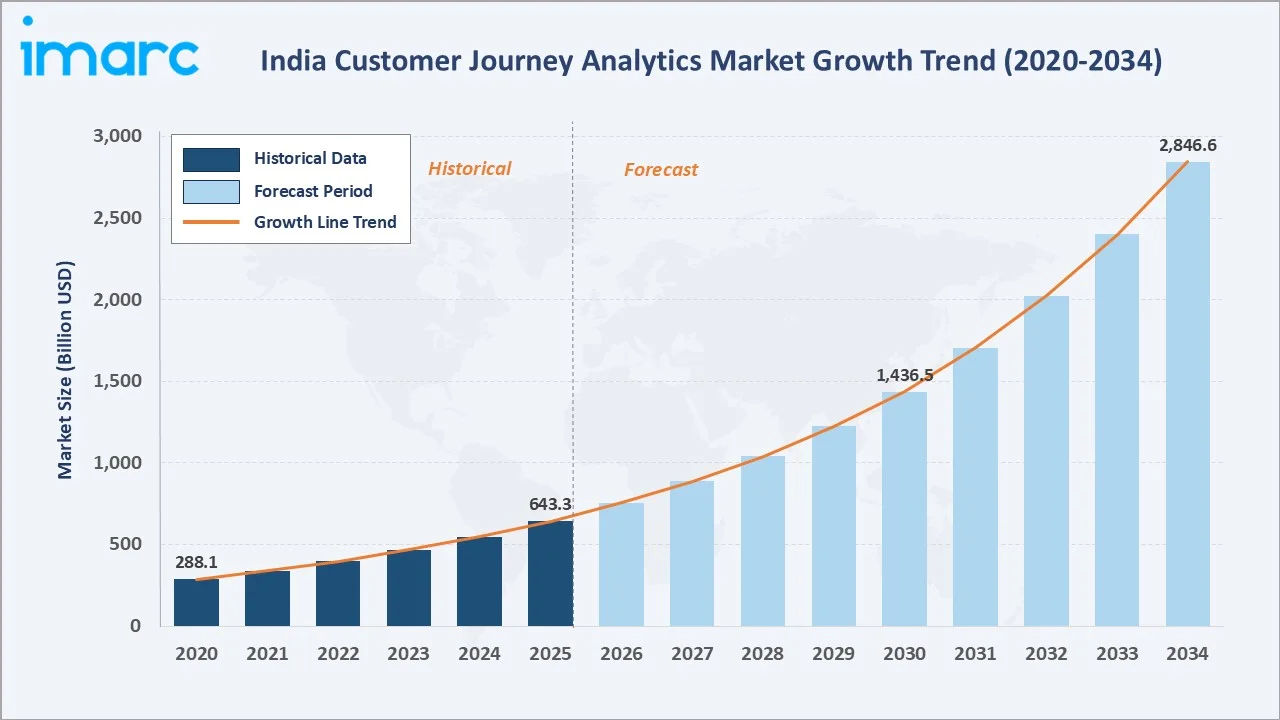
The India customer journey analytics market was valued at USD 643.3 Million in 2025, USD 755.5 Million in 2026, and is projected to reach USD 2,846.6 Million by 2034, growing at a CAGR of 17.43% during 2026-2034. Growth is powered by enterprise-wide digital transformation, AI-driven personalisation demand, and India's rapidly scaling e-commerce and BFSI sectors.
The Solution component leads at 64.8% of the market in 2025, while cloud-based deployment commands 68.7% of total deployments. South India holds the largest regional share at 34.9%, underpinned by Bengaluru and Hyderabad's technology-intensive enterprise ecosystems driving advanced CX analytics adoption across BFSI, IT, and retail verticals.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 643.3 Million |
|
Market Size (2026) |
USD 755.5 Million |
|
Forecast Market Size (2034) |
USD 2,846.6 Million |
|
CAGR (2026-2034) |
17.43% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Component |
Solution (64.8%, 2025) |
|
Dominant Deployment |
Cloud-based (68.7%, 2025) |
|
Leading Region |
South India (34.9%, 2025) |
The market grew from USD 288.1 Million in 2020 to USD 643.3 Million in 2025 and is estimated at USD 755.5 Million in 2026, projected to reach USD 1,436.5 Million by 2030 and USD 2,846.6 Million by 2034. India's CJA market is positioned at a structural inflection, combining a large digitising enterprise base with accelerating AI-led analytics adoption across BFSI, retail, telecom, and healthcare verticals.
To get more information on this market, Request Sample
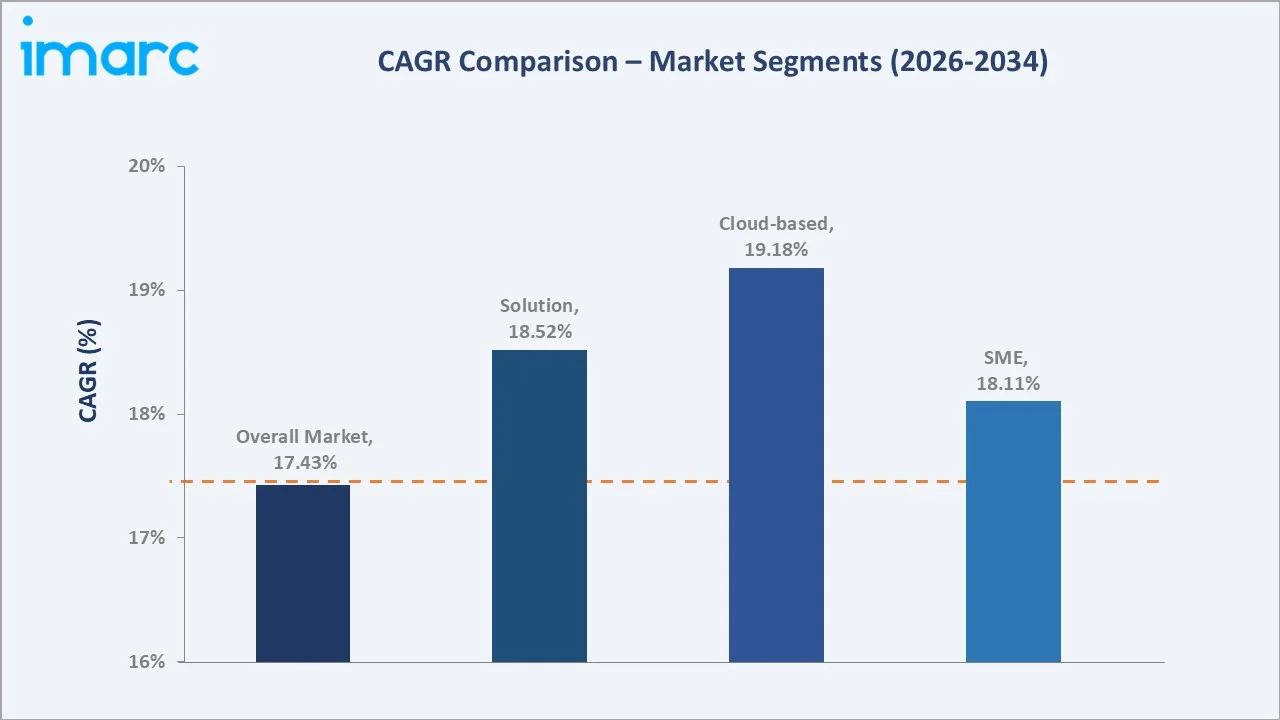
Cloud-based deployment grows fastest at ~19.18% CAGR, driven by SaaS-first enterprise digital transformation and API-led integration with CRM platforms. The Solution segment at ~18.52% CAGR leads component growth as AI-powered analytics engines expand from large enterprises to mid-market organisations across India's technology corridors.
Executive Summary
The India customer journey analytics market expanded from USD 643.3 Million in 2025 to USD 755.5 Million in 2026, among Asia-Pacific's fastest-growing analytics markets. Growth is driven by India's large digitising enterprise base, proliferating digital touchpoints across mobile, web, and social, and rising corporate investment in CX differentiation. The market is projected to reach USD 2,846.6 Million by 2034 at a CAGR of 17.43%. Solution components lead at 64.8%; cloud-based deployment at 68.7%; South India leads regionally at 34.9%.
Key Market Insights
|
Insight |
Data |
|
Dominant Component |
Solution – 64.8% share (2025) |
|
Dominant Deployment |
Cloud-based – 68.7% market share (2025) |
|
Leading Region |
South India – 34.9% share (2025) |
|
Market Opportunity |
AI-native analytics; BFSI hyper-personalisation; SME cloud CJA adoption; real-time omnichannel orchestration |
Key Analytical Observations Supporting the Above Data:
- Solution Component at 64.8%: Analytics software platforms — including journey mapping tools, customer data platforms, and AI-driven behavioural engines — dominate due to enterprises' demand for end-to-end CX visibility.
- Cloud-based Deployment at 68.7%: Cloud-based CJA deployment leads driven by API integration ease with existing CRM, ERP, and marketing automation stacks, zero-capex entry for mid-market enterprises, and real-time scalability across seasonal demand spikes.
- South India at 34.9%: South India leads through Bengaluru's concentration of global IT companies, enterprise software buyers, and analytics talent, supplemented by Hyderabad's pharmaceutical and BFSI CX investment and Chennai's manufacturing and retail analytics demand.
India Customer Journey Analytics Market Overview
India's customer journey analytics market sits at a unique convergence: one of the world's largest and most rapidly digitising enterprise bases, a decisive corporate shift toward customer-centric operating models, and an AI capability wave democratising advanced journey analytics tools from Fortune 500 companies to mid-market Indian enterprises across BFSI, retail, telecom, and healthcare.
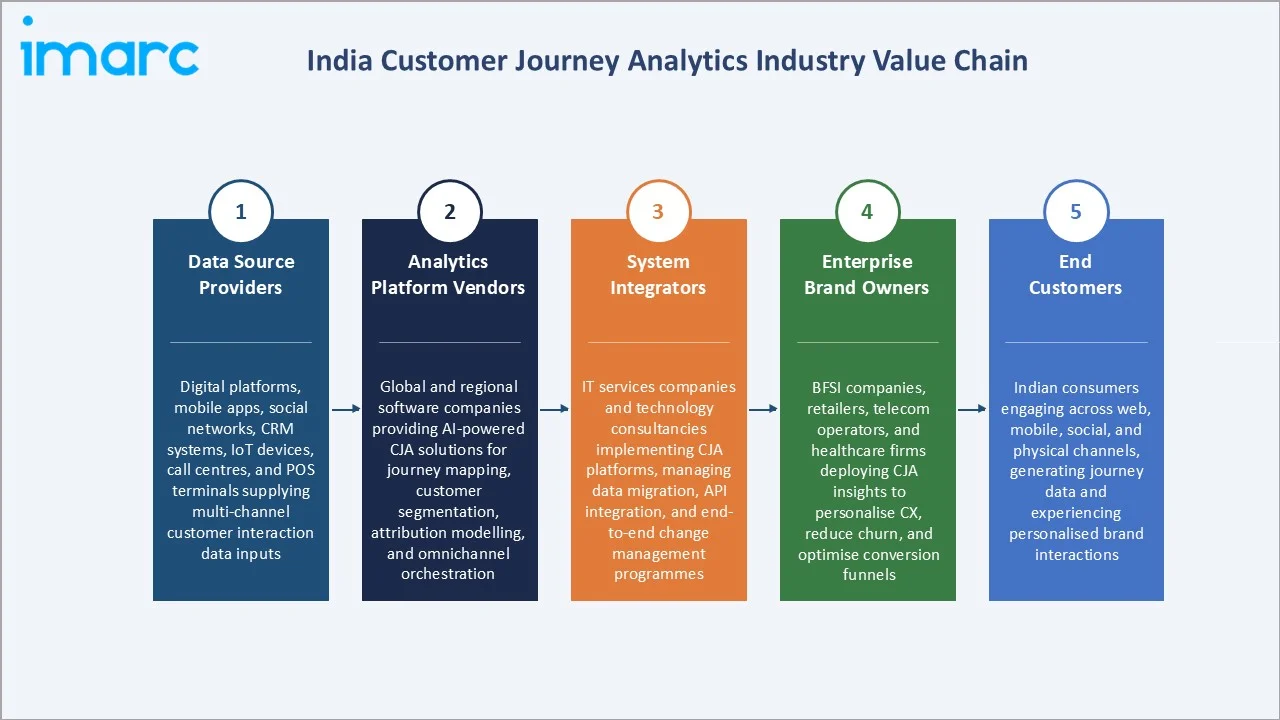
The market ecosystem spans data source providers, analytics platform vendors, system integrators, and enterprise brand owners. India's GDP growth at 6–7% annually and smartphone penetration is increasing, collectively generating multi-channel data volumes that make CJA platforms commercially indispensable for enterprises competing on CX quality across digital-first consumer segments.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
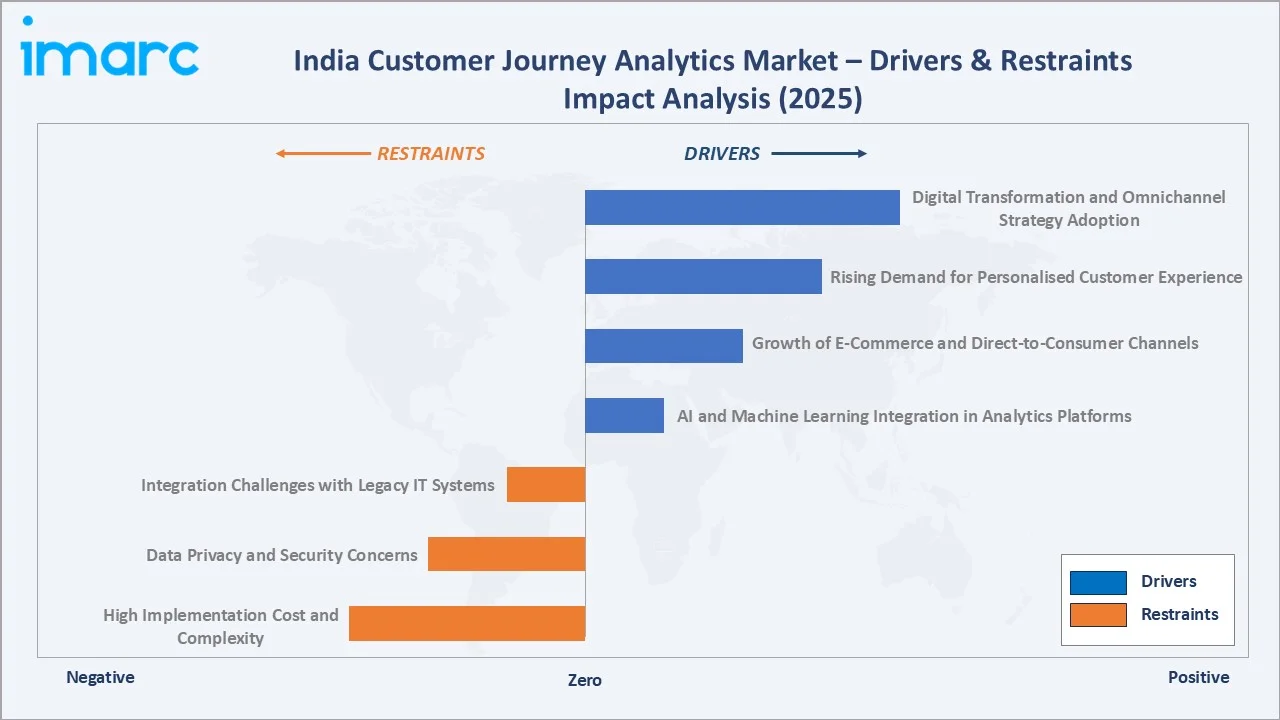
- Digital Transformation and Omnichannel Strategy Adoption: Indian enterprises are undergoing large-scale digital transformation, deploying mobile apps, AI chatbots, web portals, and social commerce channels simultaneously. Managing customer journeys across these touchpoints requires dedicated analytics platforms capable of unifying cross-channel data in real time.
- Rising Demand for Personalised Customer Experience: India's consumers expect personalised engagement across digital and physical touchpoints, with Indian consumers switch brands following impersonal experiences. Banks, telecom operators, and e-retailers are investing in CJA tools that enable real-time next-best-action recommendations and personalised journey orchestration. This consumer-driven requirement creates pull-through enterprise demand for advanced analytics solutions capable of processing millions of customer interaction signals per second at commercially viable cost, accelerating platform adoption across segments.
- Growth of E-Commerce and Direct-to-Consumer Channels: Increasing India's e-commerce market generates vast volumes of multi-touchpoint customer interaction data requiring sophisticated analytics to optimise conversion, retention, and lifetime value. Meesho, Nykaa, Flipkart, and Amazon India are deploying enterprise-grade CJA platforms to reduce cart abandonment and personalise post-purchase journeys at scale.
- AI and Machine Learning Integration in Analytics Platforms: The integration of generative AI, NLP, and predictive ML algorithms into CJA platforms dramatically expanding analytical capabilities — enabling sentiment analysis, churn prediction, and real-time journey path optimisation at enterprise scale. Indian IT companies including Infosys, TCS, and Wipro are embedding AI-native CJA modules into client solutions, creating domestic implementation expertise at scale.
Market Restraints
- High Implementation Cost and Complexity: Enterprise-grade CJA platforms require significant upfront investment in software licensing, data infrastructure modernisation, and skilled analytics talent, creating adoption barriers for SMEs and mid-market companies in non-metro India. Cost and complexity also delay return on investment realisation, extending budget cycles and limiting expansion of the addressable market beyond large enterprises in the near-to-medium term of India's CJA growth trajectory.
- Data Privacy and Security Concerns: India's Digital Personal Data Protection Act (DPDPA) 2023 imposes stringent data localisation and consent requirements, complicating cross-channel data aggregation central to CJA functionality. Enterprises face compliance uncertainty around multi-party data sharing particularly in financial services. Compliance architecture costs and consent management complexity are slowing CJA deployments in regulated BFSI and healthcare segments, creating structural restraint on the pace of full-platform adoption across India's most commercially significant CJA verticals through 2026–2028.
- Integration Challenges with Legacy IT Systems: A significant proportion of Indian enterprises operate on legacy ERP, core banking, and CRM systems with limited API connectivity. Integrating modern CJA platforms with these systems requires costly middleware development, data migration programmes, and change management investments, extending project timelines by 6–12 months on average. This integration complexity restrains CJA adoption among traditional enterprises that represent a substantial portion of India's corporate base, limiting the pace of market penetration.
Market Opportunities
- SME and Mid-Market Cloud CJA Adoption: India's 63 million MSME sector, increasingly digitising through government initiatives like PM-WANI and ONDC, represents a largely untapped addressable market for affordable cloud-based CJA solutions. Vendor pricing innovation is beginning to bring CJA into the SME segment, creating a structurally large incremental demand pool that accelerates market growth beyond large enterprise budgets, particularly in tier-2 and tier-3 city digital commerce.
- BFSI Hyper-Personalisation and Churn Prevention: India's BFSI sector, with 700 million+ bank accounts and growing digital payment adoption, represents CJA's highest-value vertical opportunity. Advanced journey analytics enabling real-time churn prediction, personalised cross-sell recommendation, and omnichannel servicing can deliver 15–25% improvement in customer retention for banks and insurers. This ROI clarity is driving dedicated BFSI CJA budgets, creating a high-growth vertical with significant incremental spend potential through 2034.
Market Challenges
- Shortage of Skilled CX Analytics Talent: Demand for CJA specialists — combining data engineering, behavioural analytics, and CX design expertise — significantly outpaces supply in India. NASSCOM estimates a shortfall of 200,000 advanced analytics professionals by 2026. This talent gap delays deployment timelines, elevates implementation costs, and constrains enterprise ability to extract full platform value, limiting the pace of market maturation and competitive differentiation for early CJA platform adopters across verticals.
- Data Fragmentation Across Customer Touchpoints: Indian enterprises operate across highly fragmented customer interaction channels creating inconsistent data structures that complicate unified journey mapping. Without standardised customer identifiers across channels, CJA platforms cannot deliver complete journey views, reducing analytical value and ROI realisation, and limiting adoption momentum among multi-channel enterprises seeking comprehensive CX visibility.
Emerging Market Trends
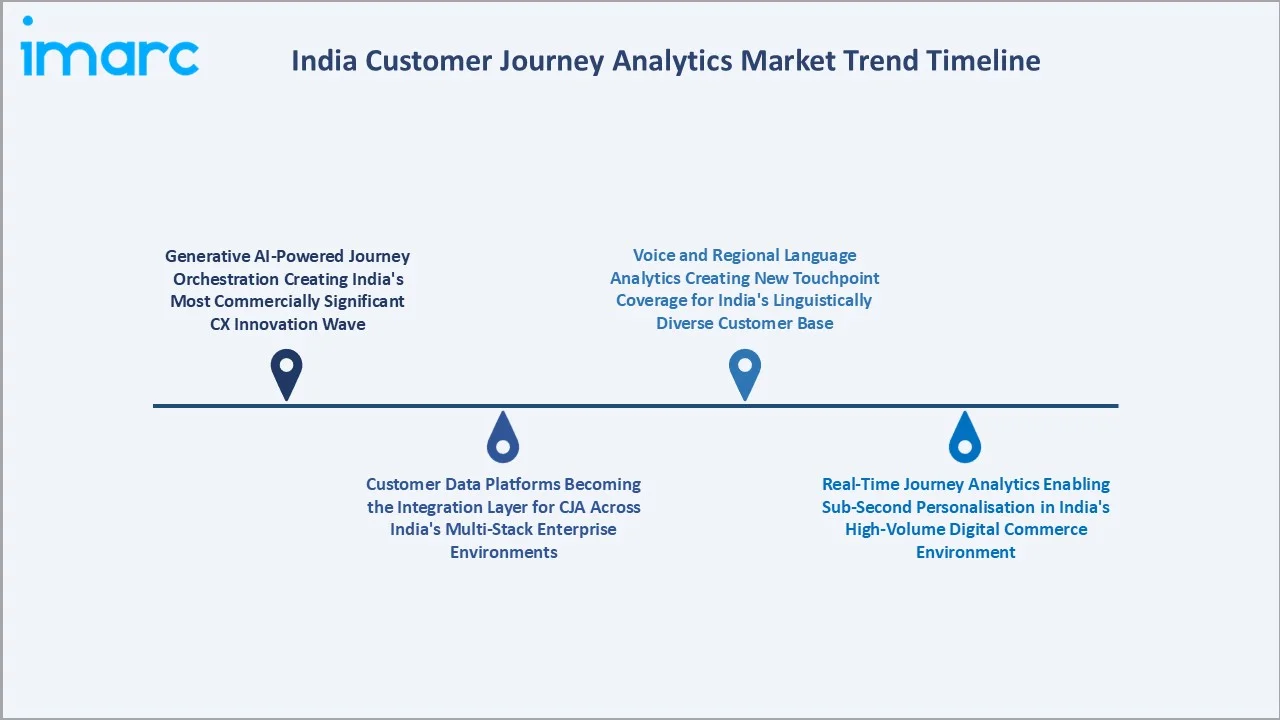
1. Generative AI-Powered Journey Orchestration Creating India's Most Commercially Significant CX Innovation Wave
Generative AI is enabling real-time, hyper-personalised journey orchestration at enterprise scale, with Adobe GenStudio, Salesforce Einstein, and SAP Joule deploying India-specific GenAI features in 2024–2025. Capabilities include dynamic content generation, predictive journey branching, and autonomous A/B testing, reducing CX team workload while improving conversion rates across digital channels.
2. Customer Data Platforms Becoming the Integration Layer for CJA Across India's Multi-Stack Enterprise Environments
CDPs are emerging as the unifying data layer enabling CJA platforms to aggregate customer signals across disparate CRM, ERP, marketing automation, and call centre systems. Segment, Bloomreach, and Adobe Real-Time CDP are gaining rapid adoption in India's e-commerce and BFSI sectors, creating a growing base of enterprise CDP infrastructure that expands the addressable market for layered CJA analytics.
3. Voice and Regional Language Analytics Creating New Touchpoint Coverage for India's Linguistically Diverse Customer Base
NLP-powered analytics capable of processing Hindi, Tamil, Telugu, and Bengali customer interactions are expanding CJA coverage beyond English-dominant digital channels to voice, regional apps, and IVR systems. This regional language capability is particularly valuable for BFSI and telecom operators serving rural and semi-urban customer segments, materially expanding CJA's addressable market.
4. Real-Time Journey Analytics Enabling Sub-Second Personalisation in India's High-Volume Digital Commerce Environment
Real-time streaming analytics architectures using Apache Kafka and cloud-native data pipelines are enabling millisecond-level customer journey response times, critical for preventing cart abandonment and optimising financial product cross-sell at India's transaction volumes of 100+ million digital payments per day, creating demonstrable business value that accelerates enterprise CJA investment decisions.
Industry Value Chain Analysis
India's customer journey analytics value chain spans multi-channel data source providers through enterprise customer engagement, with each stage presenting distinct value creation opportunities, integration requirements, and strategic growth potential for market participants through 2034.
|
Stage |
Key Participants |
| Data Source Providers | Digital platforms, mobile apps, social networks, CRM systems, IoT devices, call centres, and POS terminals supplying multi-channel customer interaction data inputs |
| Analytics Platform Vendors | Global and regional software companies providing AI-powered CJA solutions for journey mapping, customer segmentation, attribution modelling, and omnichannel orchestration |
| System Integrators | IT services companies and technology consultancies implementing CJA platforms, managing data migration, API integration, and end-to-end change management programmes |
| Enterprise Brand Owners | BFSI companies, retailers, telecom operators, and healthcare firms deploying CJA insights to personalise CX, reduce churn, and optimise conversion funnels |
| End Customers | Indian consumers engaging across web, mobile, social, and physical channels, generating journey data and experiencing personalised brand interactions |
System integrators constitute a critical value chain layer in India, as enterprises typically require 12–24 months of integration, customisation, and change management support to operationalise enterprise CJA at scale. The India SI ecosystem's depth of CJA implementation expertise is a key enabler of platform vendor market penetration and a competitive moat for partners with certified analytics deployment capabilities.
Technology Landscape in the India Customer Journey Analytics Industry
AI and Machine Learning Analytics Engines
AI-native analytics engines combining NLP, predictive ML, and graph-based journey modelling are the fastest-evolving technology layer in India's CJA market. Vendors including Adobe, Salesforce, and SAP are competing on AI model accuracy, real-time inference speed, and India-specific language support, driving rapid capability escalation and product differentiation across enterprise customer segments.
Cloud-Native and API-First Platform Architecture
Modern CJA platforms are architected on cloud-native, microservices-based foundations with REST API and pre-built connector libraries enabling rapid integration with leading CRM, CDP, and marketing automation systems. This architecture reduces enterprise time-to-value from 18 months to 6–9 months, accelerating ROI realisation and expanding the addressable market to mid-market organisations.
Real-Time Data Streaming and Event-Driven Analytics
Apache Kafka, AWS Kinesis, and Azure Event Hubs-based streaming architectures enable enterprise CJA platforms to process millions of customer events per second, enabling real-time personalisation and sub-second journey intervention at India's large digital transaction volumes. This infrastructure maturity is bringing real-time CJA capabilities previously available only to hyperscalers within reach of mid-to-large Indian enterprises in retail, BFSI, and telecom sectors.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
| Component | Solution |
64.8% |
2025 |
| Touchpoint |
🔒 |
🔒 |
2025 |
| Deployment | Cloud-based | 68.7% | 2025 |
| Organization Size | 🔒 | 🔒 | 2025 |
| Application | 🔒 | 🔒 | 2025 |
| Industry Vertical | 🔒 | 🔒 | 2025 |
|
Region |
South India |
34.9% |
2025 |

By Component
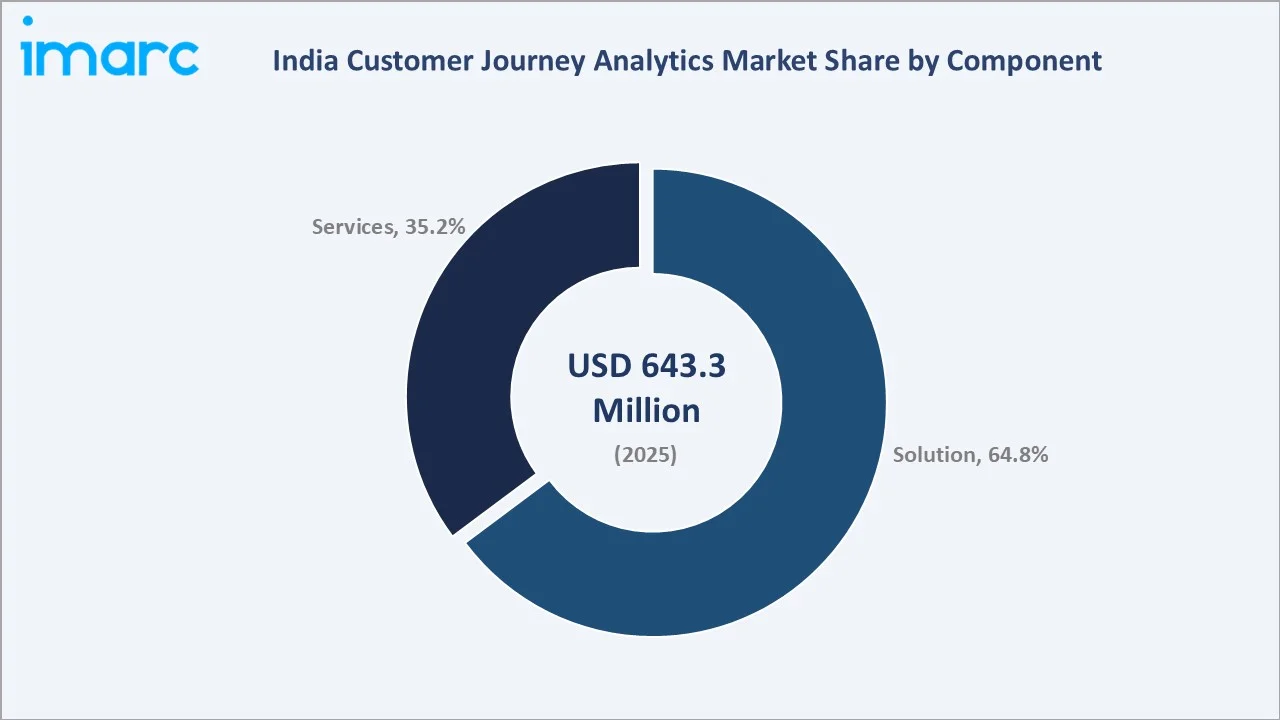
The Solution component led the India CJA market at 64.8% in 2025, driven by enterprise demand for end-to-end analytics software platforms integrating journey mapping, segmentation, attribution modelling, and real-time orchestration in a single deployable environment across BFSI, retail, telecom, and healthcare verticals.
To access detailed market analysis, Request Sample
Services account for 35.2% of the 2025 market, comprising implementation, integration, managed analytics, and training services delivered by system integrators and platform vendors.
By Deployment
Cloud-based CJA deployment commanded 68.7% in 2025, driven by SaaS delivery economics, rapid API integration with existing CRM and CDP stacks, and India's MEITY cloud-first enterprise policy. Hyperscaler data centre expansion in Mumbai, Pune, Hyderabad, and Chennai has reduced latency concerns, further accelerating cloud CJA adoption across all enterprise tiers and verticals.
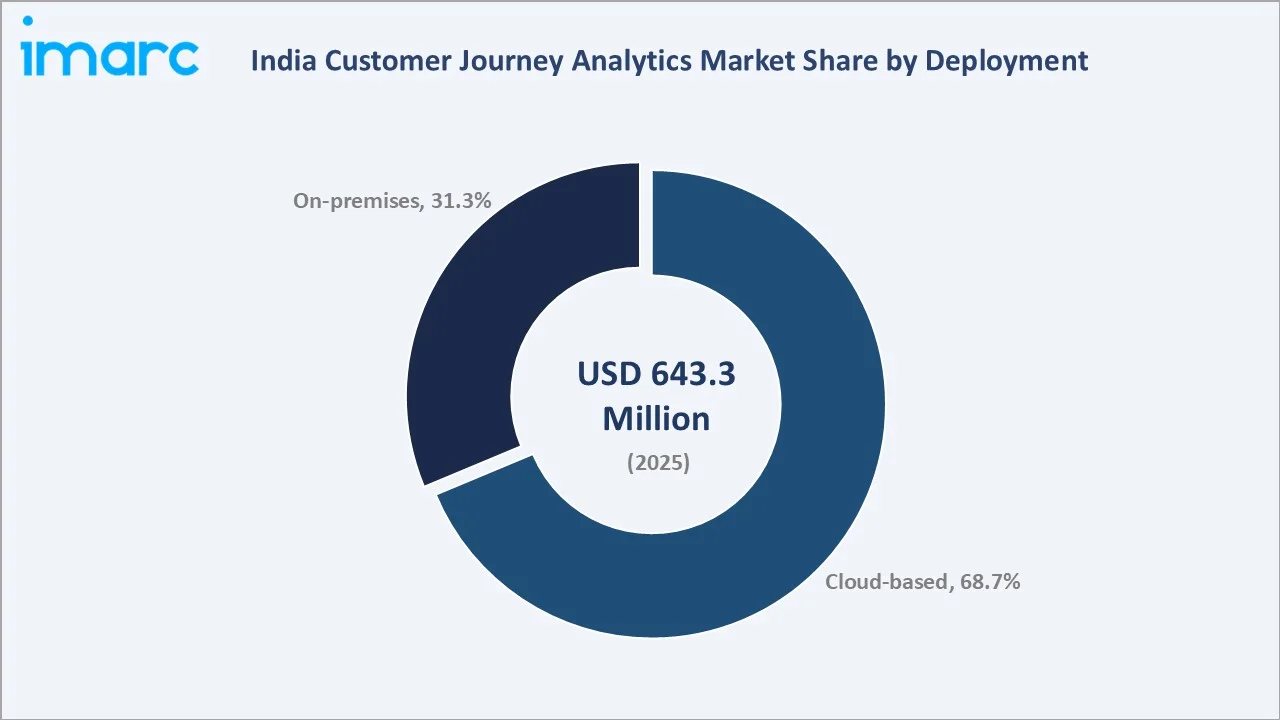
On-premises deployment retains 31.3% share, concentrated in regulated BFSI, government, and defence-adjacent sectors requiring data localisation and air-gapped security environments. The report covers the following segments:
Regional Market Insights
|
Region |
Share (2025) |
Key CJA Market Drivers & Characteristics |
| South India |
34.9% |
Driven by Bengaluru and Hyderabad IT ecosystems; large enterprise CJA deployments across BFSI, tech, and pharmaceutical verticals; highest per-company analytics spend. |
| West & Central India |
29.7% |
Mumbai BFSI cluster and Pune's manufacturing and retail sectors fuel demand; strong enterprise digitalisation driving cross-channel CX analytics investment. |
| North India |
23.8% |
NCR-based e-commerce, FMCG, and telecom companies represent dominant buyers; government digital services initiatives expanding public sector CJA interest. |
| East & Northeast India |
11.6% |
Emerging CJA market with Kolkata BFSI and retail leading adoption; growing e-commerce penetration in Northeast is creating new analytics demand footprint. |
South India's 34.9% leadership reflects Bengaluru's globally significant technology ecosystem creating both supply-side platform expertise and demand-side enterprise CJA procurement. West and Central India's 29.7% share is anchored by Mumbai's BFSI sector, India's largest single vertical spender on CX analytics.
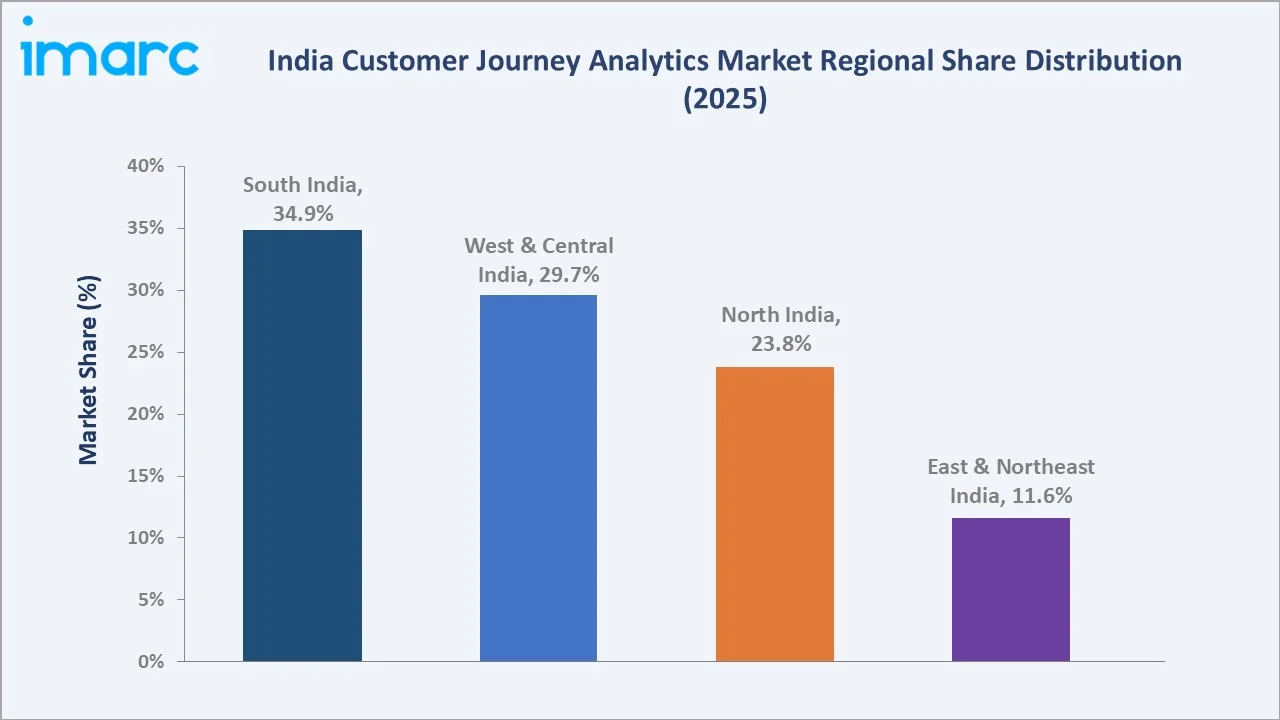
North India's 23.8% reflects NCR's large e-commerce, FMCG, and telecom buyer base. East and Northeast India, at 11.6%, represents the fastest-growing region from a low base, driven by rapid e-commerce penetration and state government digital service rollouts generating new requirements for customer journey analytics and optimisation.
Competitive Landscape
India's customer journey analytics competitive landscape is dominated by global technology leaders operating large India businesses through direct sales, system integrator partnerships, and cloud-delivered SaaS models.
| Company | Key Offerings | Market Position | Core Strength |
|---|---|---|---|
| Adobe | Adobe Experience Cloud: Real-Time CDP, Customer Journey Analytics, Journey Optimizer | Market Leader | Deepest end-to-end CX analytics suite; AI-powered with Firefly & Sensei GenAI; strong India R&D centre in Bengaluru |
| Salesforce, Inc. | Salesforce Data Cloud, Marketing Cloud Intelligence, Einstein Copilot | Market Leader | Largest enterprise CRM ecosystem integration; Einstein GPT-powered journey insights; dominant India enterprise CRM base |
| SAP SE | SAP Customer Data Cloud, SAP Marketing Cloud journey analytics | Strong Challenger | Deep ERP-to-CX analytics integration; Joule AI assistant; strong BFSI and manufacturing vertical penetration in India |
| Microsoft | Microsoft Customer Insights (Dynamics 365), Azure Synapse Analytics, Copilot CX | Strong Challenger | Azure-native integration advantage; Microsoft 365 data leverage; Copilot AI driving rapid enterprise CJA adoption |
| NiCE | NiCE CXone, NiCE CXone Mpower, Enlighten AI | Challenger | Contact centre and voice journey analytics specialisation; strong BFSI compliance analytics; growing India telecom presence |
| Oracle | Oracle CX Analytics, Oracle Unity CDP, Oracle Fusion Marketing journey intelligence | Challenger | Oracle Database integration advantage; ERP-native CX analytics; strong India mid-large enterprise installed base |
Key players include Adobe, Salesforce, Inc., SAP SE, Microsoft, NiCE, Oracle, and others.
Key Company Profiles
Adobe
Adobe is the global leader in digital experience and customer journey analytics, headquartered in San Jose, California. Adobe Experience Cloud serves India's largest e-commerce, BFSI, and media enterprises from its Bengaluru R&D and sales headquarters.
- Key Products: Adobe Real-Time Customer Data Platform for unified customer profiles across touchpoints; Adobe Customer Journey Analytics for cross-channel attribution and journey visualisation; Adobe Journey Optimizer for real-time omnichannel journey orchestration. All products integrate natively with Adobe Experience Manager and third-party CRM and CDP platforms through pre-built connectors and open APIs.
- Strategic Focus: Deepening AI-first CJA capability through Firefly and Sensei GenAI integration across the Experience Cloud suite, targeting India's rapidly scaling e-commerce and BFSI verticals with vertical-specific journey analytics templates and pre-configured BFSI compliance data models.
Salesforce, Inc.
Salesforce is the world's leading CRM platform provider. Its Salesforce Data Cloud and Marketing Cloud Intelligence solutions are deployed by India's largest BFSI, retail, and telecom enterprises for customer journey analytics, behavioural segmentation, and AI-powered CX orchestration.
- Key Products: Salesforce Data Cloud for real-time customer data unification and identity resolution across CRM, commerce, and marketing channels; Marketing Cloud Intelligence for cross-channel attribution and journey analytics; Einstein Copilot for AI-powered next-best-action recommendations. Salesforce's MuleSoft integration platform enables API-led connectivity with legacy banking, ERP, and call centre systems across India.
- Strategic Focus: Accelerating Data Cloud and AgentForce adoption among India's top 500 enterprises through a dedicated India Customer Success team and DPDPA-compliant hyperforce infrastructure. Salesforce is investing in Hindi and regional language NLP for Einstein Copilot to address India's vernacular commerce opportunity and expanding Trailhead developer training programs.
Market Concentration Analysis
India's customer journey analytics market is moderately concentrated, with the top three players accounting for an estimated 48–55% of organised market revenues in 2025. These leaders compete on AI capability, ecosystem integration depth, and India-specific compliance features rather than price, sustaining premium positioning against mid-tier and regional challengers.
Concentration is evolving through AI-driven platform convergence as CRM, analytics, and CDP categories merge into integrated CX suites. This consolidation favours full-suite players over point solution vendors, accelerating market share concentration among the top five vendors while creating a structural challenge for specialised single-capability CJA providers in India's enterprise mid-market through 2030.
Investment & Growth Opportunities
Highest Growth Segments
Cloud-based CJA deployment (~19.18% CAGR), Solution component (~18.52% CAGR), and the SME market segment (~18.11% CAGR) are India's fastest-growing CJA segments through 2034. BFSI vertical CJA investment is growing from a large 2025 base, as Indian private banks and insurance companies prioritise personalisation-driven retention and cross-sell analytics programmes.
Emerging Investment Opportunities
India-specific AI model development for regional language journey analytics represents the highest-value greenfield opportunity, enabling CJA platforms to extend beyond English-dominant enterprise buyers to the 600+ million vernacular internet users. Composable CJA architectures using MACH (Microservices, API-first, Cloud-native, Headless) principles are enabling cost-effective deployment for mid-market enterprises.
Investment Themes
- AI-Native CJA Platform Development: Investing in India-first AI journey analytics platforms incorporating regional language NLP, DPDPA-compliant data architectures, and SME-accessible pricing models, targeting the 63 million MSME segment currently underserved by enterprise-grade global CJA vendors as the market's largest structural growth opportunity through 2034.
- BFSI-Vertical CJA Specialisation: Dedicated BFSI customer journey analytics solutions combining regulatory compliance data management, churn prediction modelling, and omnichannel banking journey orchestration represent a high-ROI investment vertical — Indian banks achieve 15–25% retention improvement through CJA-optimised servicing, creating clear enterprise value justification for accelerated platform investment and expansion.
Future Market Outlook (2026-2034)
The India customer journey analytics market is projected to grow from USD 643.3 Million in 2025 to USD 755.5 Million in 2026, reaching USD 1,436.5 Million by 2030 and USD 2,846.6 Million by 2034 at a CAGR of 17.43%. The USD 1,436.5 Million milestone in 2030 marks a structural inflection where AI-native CJA transitions from large-enterprise deployment to broad mid-market adoption, and real-time personalisation at scale becomes the baseline competitive standard for India's enterprise CX function.
Three forces define CJA market growth through 2034: India's enterprise AI adoption wave, among Asia-Pacific's most rapid technology capability shifts in a large economy; structural proliferation of digital customer touchpoints generating data volumes that mandate analytics investment; and competitive CX differentiation imperative in India's intensely competitive BFSI, retail, and telecom sectors driving recurring analytics spend.
Research Methodology
Primary Research
Primary research comprised structured interviews with CJA industry stakeholders, including enterprise CX heads, analytics platform vendor sales leadership, and system integrator practice heads across BFSI, retail, telecom, and healthcare verticals, supplemented by enterprise technology buyer surveys across South, West, North, and East India covering platform selection criteria and CJA investment priorities.
Secondary Research
Secondary research encompassed enterprise analytics platform vendor annual reports, MCA company filings, NASSCOM analytics market reports, RBI digital banking statistics, platform vendor press releases, and trade publications. Over 55 secondary sources were reviewed and cross-validated against primary findings to ensure data accuracy.
Forecasting Models
Market forecasts were developed using a bottom-up model: India's enterprise technology addressable market by vertical multiplied by CJA platform penetration rates per segment, calibrated against digital transformation investment timelines and platform vendor India revenue growth trajectories through 2034.
India Customer Journey Analytics Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report | Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Components Covered | Solution, Services |
| Touchpoints Covered | Web, Social Media, Mobile, Email, Branch and Store, Call Center, Others |
| Deployments Covered | On-premises, Cloud-based |
| Organization Sizes Covered | Large Enterprises, Small and Medium-sized Enterprises |
| Applications Covered | Customer Segmentation and Targeting, Customer Behavioral Analysis, Customer Churn Analysis, Brand Management, Campaign Management, Product Management, Others |
| Industry Verticals Covered | BFSI, IT and Telecommunications, Retail and E-Commerce, Healthcare, Media and Entertainment, Travel and Hospitality, Others |
| Regions Covered | North India, West and Central India, South India, East and Northeast India |
| Companies Covered | Adobe, Salesforce, Inc., SAP SE, Microsoft, NiCE, Oracle, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the India customer journey analytics market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the India customer journey analytics market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the India customer journey analytics industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the India Customer Journey Analytics Market Report
The India customer journey analytics market size is estimated at USD 755.5 Million in 2026, growing from USD 643.3 Million in 2025, driven by enterprise digital transformation, AI-powered personalisation demand, and rapid omnichannel adoption across BFSI, retail, telecom, and e-commerce verticals in India.
The India customer journey analytics market grows at 17.43% CAGR during 2026-2034, reaching USD 2,846.6 Million by 2034. Growth is sustained by AI-native platform capability advancement, proliferating digital customer touchpoints, and intensifying competitive CX differentiation demand across India's high-growth enterprise verticals.
Solution component leads at 64.8% due to enterprise demand for end-to-end analytics software platforms integrating journey mapping, segmentation, attribution modelling, and real-time orchestration. AI-native solution capabilities from Adobe, Salesforce, and SAP are driving continued solution dominance through the forecast period.
Cloud-based deployment leads at 68.7% through SaaS economics, API-led CRM integration ease, and India's MEITY cloud-first policy support. Hyperscaler data centre expansion in India has addressed data residency concerns for BFSI, accelerating cloud CJA deployment even in regulated industries through DPDPA-compliant cloud architectures.
South India leads at 34.9% through Bengaluru and Hyderabad's concentrated technology enterprise base comprising India operations of all major global CJA platform vendors and high-propensity enterprise buyers across BFSI, IT services, and pharmaceutical verticals with above-average analytics investment maturity and digital CX commitment.
Leading companies include Adobe, Salesforce, Inc., SAP SE, Microsoft, NiCE, Oracle, and others.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade