UAE Buy Now Pay Later Market Size, Share, Trends and Forecast by Channel, Enterprise Size, End Use, and Region, 2026-2034
UAE Buy Now Pay Later Market Size, Share, Trends & Forecast (2026-2034)
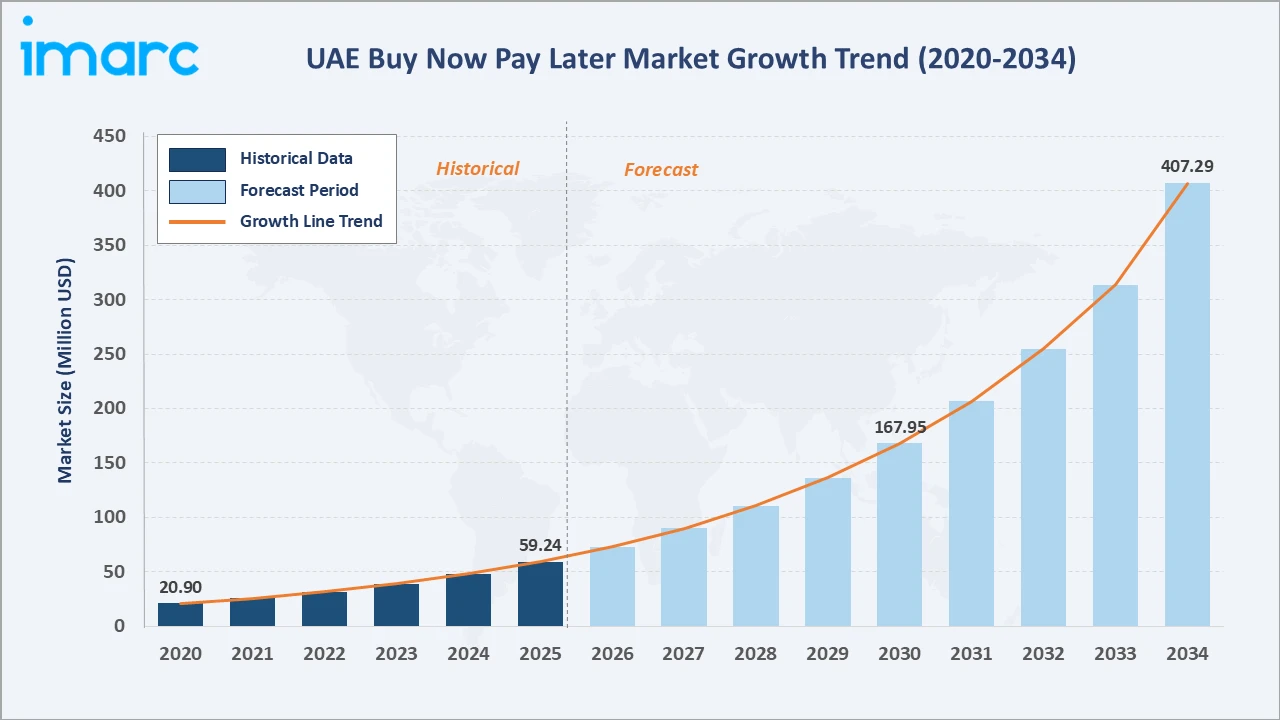
The UAE Buy Now Pay Later (BNPL) market grew from USD 59.24 Million in 2025 to USD 72.97 Million in 2026 and is projected to reach USD 407.29 Million by 2034, growing at a CAGR of 23.17% during 2026-2034. The market is driven by rising e-commerce penetration, a digitally savvy youth population, and growing fintech-bank collaborations across the UAE.
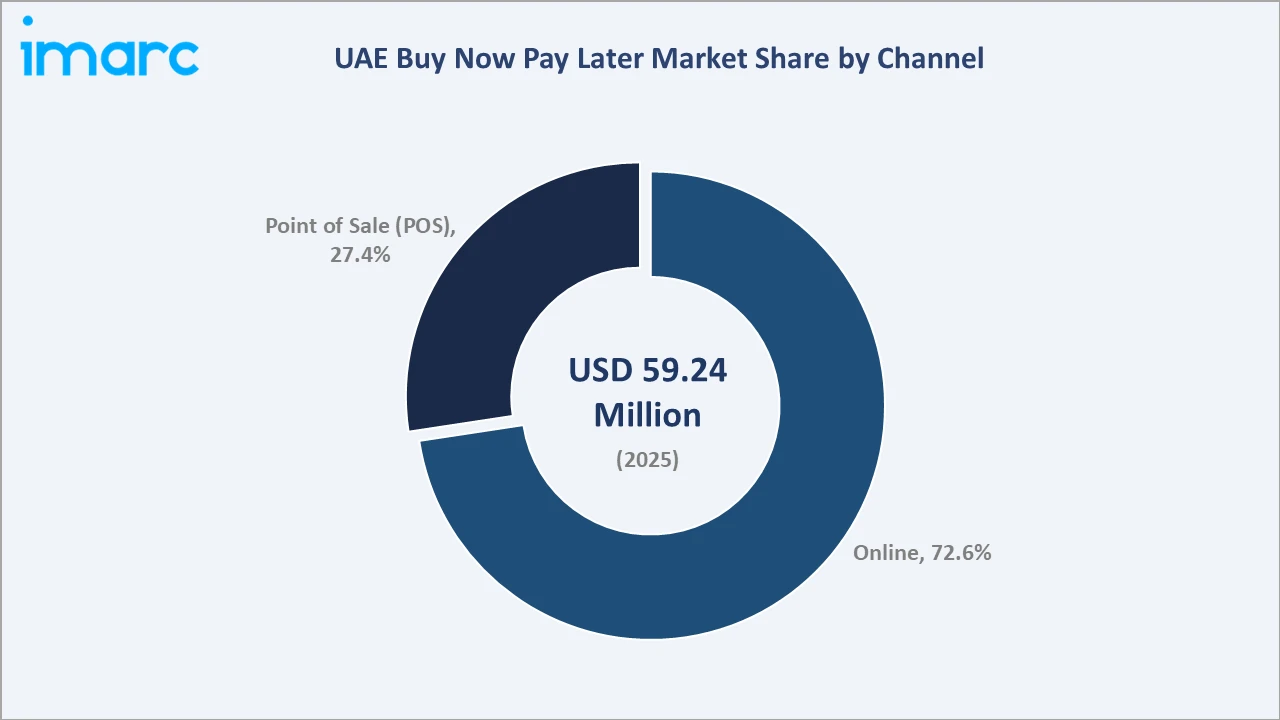
The buy now pay later UAE market is growing as consumers increasingly adopt flexible payment options for online and in-store purchases. Online BNPL leads with 72.6% channel share. Large enterprises dominate at 61.8%. Dubai commands 48.6% of the regional market share in 2025.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 59.24 Million |
|
Market Size (2026) |
USD 72.97 Million |
|
Forecast Market Size (2034) |
USD 407.29 Million |
|
CAGR (2026-2034) |
23.17% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Channel |
Online (72.6%, 2025) |
|
Dominant Enterprise Size |
Large Enterprises (61.8%, 2025) |
|
Leading Region |
Dubai (48.6%, 2025) |
The UAE BNPL market expanded from USD 20.90 Million in 2020 to USD 59.24 Million in 2025. The market is estimated to reach USD 72.97 Million in 2026, USD 167.95 Million by 2030, and USD 407.29 Million by 2034.
To get more information on this market, Request Sample
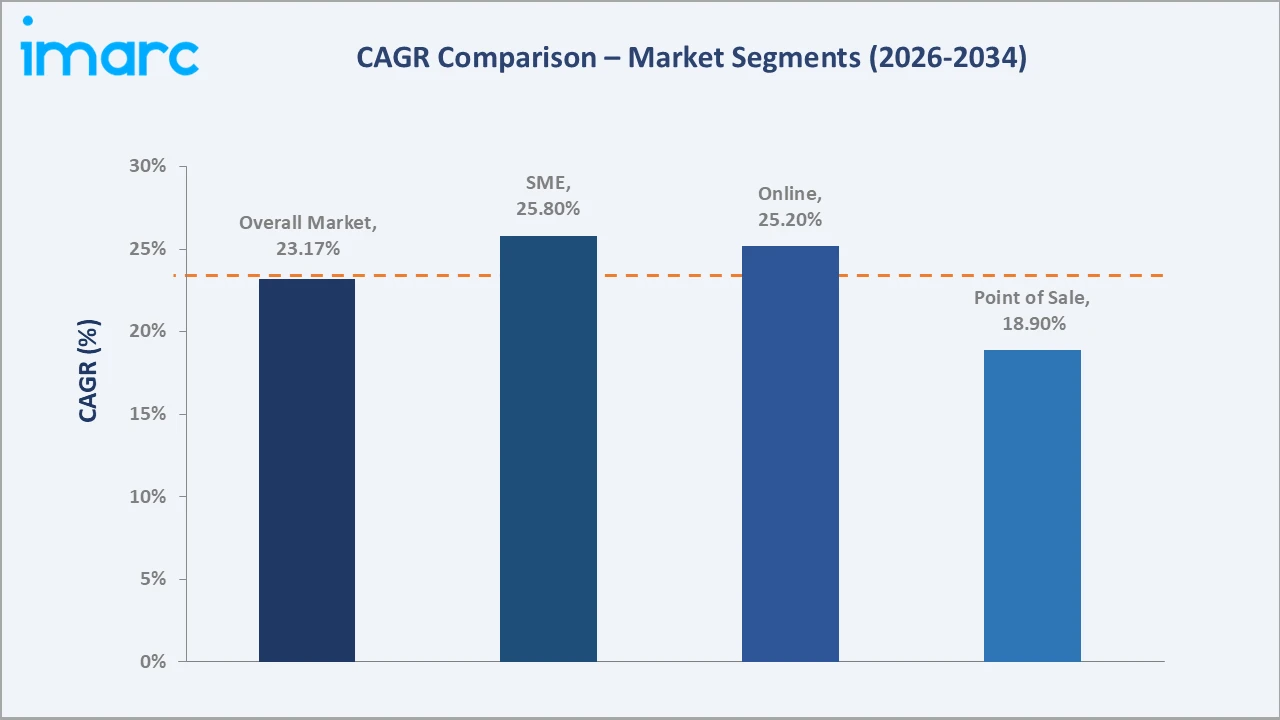
Online BNPL grows at approximately 25.2% CAGR, outpacing POS at approximately 18.9%. SMEs grow fastest at approximately 25.8% CAGR, reflecting rapid fintech adoption. Dubai leads regionally at 22.5% CAGR through its digital commerce ecosystem.
Executive Summary
The UAE BNPL market grew from USD 59.24 Million in 2025 to USD 72.97 Million in 2026 and is projected to reach USD 407.29 Million by 2034 at a CAGR of 23.17%. Rising digital commerce, regulatory clarity from the Central Bank of UAE (CBUAE), and Sharia-compliant payment structures underpin rapid expansion.
Online channels dominate at 72.6%, driven by e-commerce integration. Large enterprises command 61.8%, while SMEs grow fastest. Dubai leads with 48.6% regional share, supported by its advanced fintech infrastructure and high smartphone penetration.
Key Market Insights
|
Insight |
Data |
|
Dominant Channel |
Online – 72.6% share (2025) |
|
Dominant Enterprise Size |
Large Enterprises – 61.8% market share (2025) |
|
Leading Region |
Dubai – 48.6% share (2025) |
|
Market Opportunity |
Sharia-compliant BNPL; SME financing; healthcare and education verticals; cross-border e-commerce integration |
Key Analytical Observations:
- Online at 72.6%: E-commerce growth and seamless checkout integration drive online BNPL dominance, with platforms like Amazon.ae and Noon enabling split-payment options across fashion, electronics, and lifestyle categories.
- Large Enterprises at 61.8%: Established merchants with high transaction volumes benefit most from BNPL, leveraging lower cart abandonment and increased average order values through integrated payment solutions.
- Dubai at 48.6%: Dubai's advanced digital infrastructure, high expat population, and e-commerce density create the strongest BNPL adoption environment in the UAE, supported by a progressive fintech ecosystem.
UAE Buy Now Pay Later Market Overview
The UAE BNPL market represents one of the Middle East's fastest-growing fintech segments. Its growth is underpinned by a young, digitally connected population, high smartphone penetration exceeding 97%, and a government-driven push toward a cashless economy.
The UAE's regulatory environment, shaped by CBUAE oversight, provides a structured framework that fosters consumer confidence. Sharia-compliant, interest-free installment models align with regional Islamic finance principles, expanding addressable market reach across all consumer demographics.
Market Dynamics
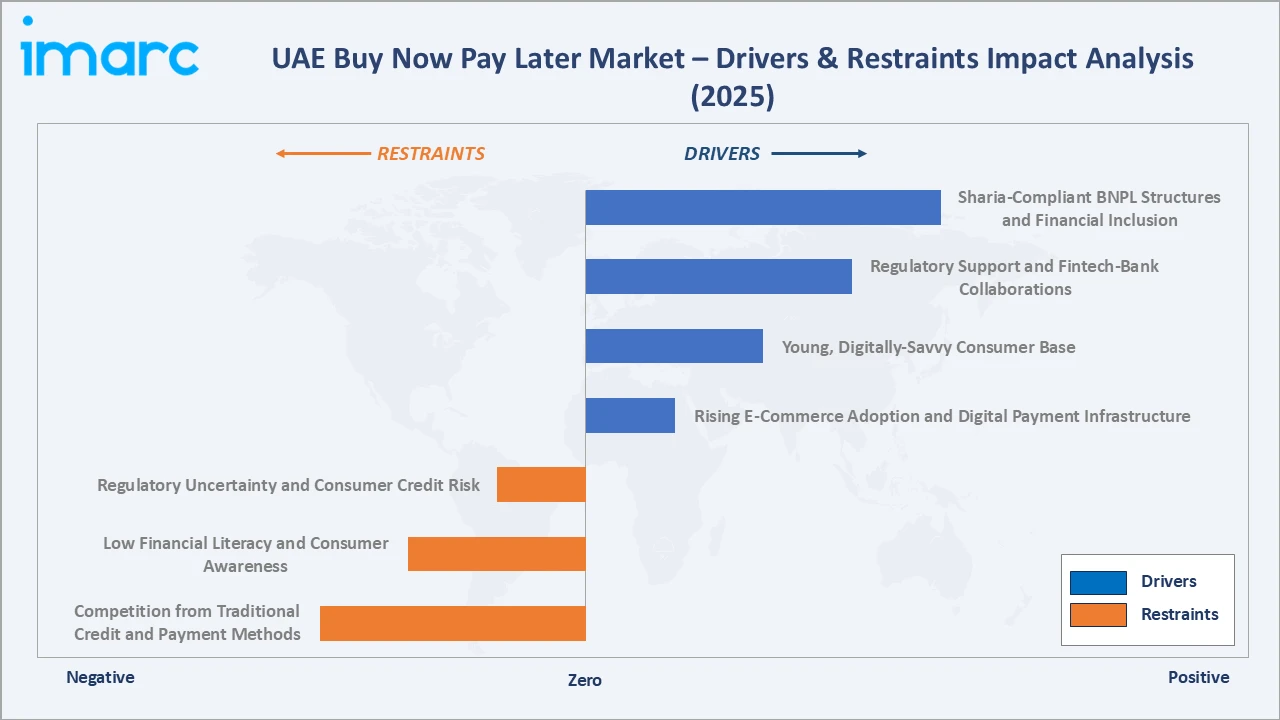
To evaluate market opportunities, Request Sample
Market Drivers
- Rising E-Commerce Adoption and Digital Payment Infrastructure: Seamless BNPL integration at checkout reduces cart abandonment by up to 30%, directly expanding consumer spending capacity and driving market adoption across retail verticals. The rapid expansion of digital payment gateways and super-app ecosystems creates additional embedded finance touchpoints for BNPL services throughout the UAE. This digital-first commercial landscape continues to accelerate consumer habituation toward split-payment models, reinforcing BNPL as a mainstream checkout option across all product categories.
- Young, Digitally-Savvy Consumer Base: Over 60% of UAE's population is under 35 years. This demographic actively embraces alternative finance, preferring interest-free installments over credit cards, with Gen Z and Millennial shoppers driving primary BNPL adoption and accelerating overall market penetration. This demographic's comfort with digital-only financial services reduces the need for physical branch infrastructure, lowering BNPL providers' operational costs and enabling rapid scalability across the UAE. Rising awareness among this cohort of the benefits of deferred payment structures further sustains long-term demand for BNPL products beyond traditional retail categories.
- Regulatory Support and Fintech-Bank Collaborations: CBUAE's oversight framework provides licensed BNPL operations clarity. Strategic partnerships between fintech providers and licensed banks, such as Tabby's collaboration with Meem Bank, expand credibility, reach, and underwriting capabilities significantly. These regulatory-backed collaborations also enhance consumer trust in BNPL platforms by associating them with established financial institutions, reducing adoption barriers across all age groups and income segments. Government-aligned digital finance initiatives, including UAE Vision 2031 and the National Digital Economy Strategy, further create a supportive macro environment for sustained BNPL market expansion.
- Sharia-Compliant BNPL Structures and Financial Inclusion: Interest-free BNPL models align with Islamic finance principles, making them accessible to a broader consumer base across the UAE. This drives financial inclusion, particularly for consumers who avoid conventional credit products due to religious considerations. Murabaha-structured BNPL products, endorsed by recognized Sharia supervisory boards, provide providers with a credible, religiously sanctioned value proposition that resonates across the UAE's diverse Muslim majority and expatriate population. As Islamic finance awareness grows regionally, Sharia-compliant BNPL is increasingly positioned as the preferred alternative to conventional credit, unlocking a structurally differentiated and loyal consumer segment.
Market Restraints
- Regulatory Uncertainty and Consumer Credit Risk: Evolving BNPL regulations create operational compliance challenges for providers. Rising consumer debt and over-extension risks, particularly among younger demographics, may prompt stricter credit controls that dampen market growth and reduce provider profitability. Inconsistent cross-emirate regulatory requirements also increase compliance complexity for BNPL providers operating simultaneously in Dubai, Abu Dhabi, and Sharjah, adding to operational overhead and legal costs. Potential mandatory credit bureau reporting obligations for BNPL transactions could further restrict the speed of approvals and reduce the frictionless experience that is central to the BNPL value proposition.
- Low Financial Literacy and Consumer Awareness: A segment of UAE consumers, particularly older demographics and lower-income expatriates, remains unfamiliar with BNPL mechanisms. Misconceptions about fees and eligibility limit broader adoption, requiring significant consumer education investment by providers. Limited awareness of late payment penalties and the cumulative impact of multiple active BNPL plans can result in consumer financial distress, generating negative press coverage that erodes market confidence and deters new user acquisition. Overcoming these literacy gaps requires sustained and costly multi-language consumer education campaigns, increasing providers' customer acquisition costs and extending the timeline to profitability in underserved market segments.
- Competition from Traditional Credit and Payment Methods: Established credit card reward programs, bank installment plans, and digital wallets present strong alternatives. High card penetration among UAE residents reduces the urgency of BNPL adoption, limiting market expansion in certain consumer segments. Major UAE banks offering zero-interest installment plans on existing credit cards with additional loyalty rewards create a compelling substitute product that requires minimal behavioral change from consumers already embedded in banking ecosystems. International payment providers expanding digital wallet and BNPL-equivalent services in the UAE further intensify competitive pressure, compressing merchant fee margins and reducing pricing power for standalone BNPL platforms.
Market Opportunities
- Expansion into Healthcare, Travel, and Education Verticals: BNPL penetration beyond retail into high-value verticals elective healthcare, international travel, and education fees represents substantial untapped revenue. These sectors offer larger transaction sizes and recurring consumer need, supporting sustained provider growth. Healthcare BNPL adoption is particularly nascent in the UAE, with less than 10% of eligible elective procedures currently financed through installment payment plans, creating a significant first-mover opportunity for BNPL providers willing to build vertical-specific partnerships. Education-focused BNPL solutions aligned with UAE government tuition-fee structures and international school payment calendars present a recurring, predictable revenue stream with low credit risk, ideal for building sustainable BNPL portfolio quality.
- SME Merchant Onboarding and B2B BNPL Solutions: The UAE's 350,000-plus SMEs represent an underserved merchant segment. B2B BNPL tools enabling SMEs to offer flexible payment options to their own customers create a dual growth opportunity for providers, expanding both merchant networks and transaction volumes. White-label BNPL infrastructure targeted at UAE banks and large retailers seeking to launch proprietary installment products offers providers a scalable, lower-risk revenue model with significantly lower customer acquisition costs than consumer-facing platforms. Dedicated SME onboarding programmes with simplified API integration, transparent merchant fee structures, and localized Arabic-language support can dramatically accelerate small business adoption and deepen provider presence across the UAE's fragmented SME retail landscape.
Market Challenges
- Credit Bureau Data Gaps and Risk Underwriting: Limited credit history for a large portion of UAE expatriates complicates risk assessment. BNPL providers must develop proprietary scoring models, increasing operational costs and the risk of non-performing loan portfolios in a competitive market. Frequent workforce turnover and shorter average UAE residency periods for expatriates mean that traditional credit bureau data is often incomplete or outdated, reducing the reliability of conventional underwriting models and elevating default risk. Investing in alternative data infrastructure encompassing transaction history, telecom payment records, and e-commerce behavior requires substantial upfront capital and ongoing data science resources, creating a significant barrier for smaller or newer BNPL market entrants.
- High Customer Acquisition Costs in a Competitive Landscape: Intense competition among regional and global BNPL providers drives up marketing and merchant subsidy costs. Achieving sustainable unit economics while scaling user acquisition remains a critical challenge for new and existing market participants. Elevated merchant discount rates offered as acquisition incentives compress provider margins during the critical growth phase, requiring substantial external capital to fund operations before reaching transaction volume thresholds that unlock profitability at scale. Consumer switching costs in BNPL remain inherently low due to the absence of loyalty lock-in mechanisms, meaning providers must invest continuously in user engagement, rewards, and exclusive merchant partnerships to maintain an active consumer base and reduce churn.
Emerging Market Trends
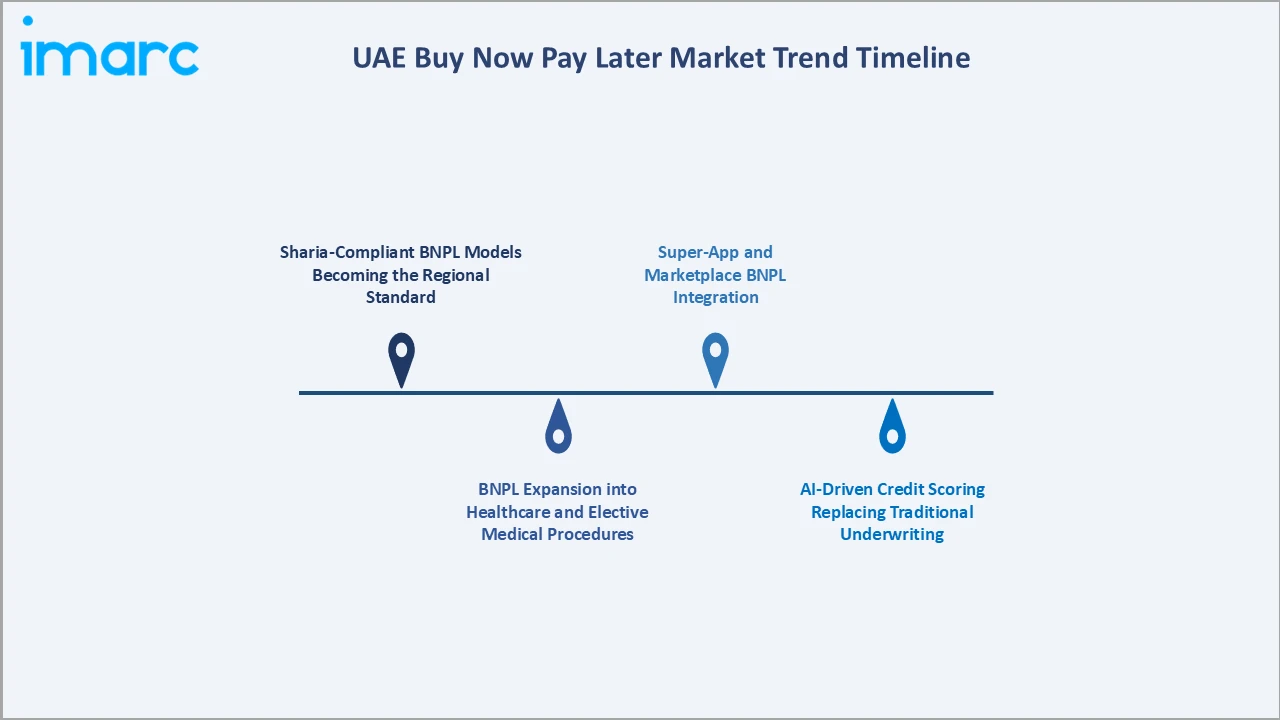
1. Sharia-Compliant BNPL Models Becoming the Regional Standard
Islamic finance principles are reshaping BNPL product design across the UAE. Providers offering Murabaha-structured installment products align with both regulatory expectations and consumer preferences, unlocking a significantly larger addressable consumer base.
2. BNPL Expansion into Healthcare and Elective Medical Procedures
UAE healthcare providers and elective surgery clinics increasingly partner with BNPL platforms to offer affordable payment plans. This trend reduces payment barriers for high-value medical services, creating a new and rapidly growing BNPL revenue vertical.
3. AI-Driven Credit Scoring Replacing Traditional Underwriting
Leading UAE BNPL providers are deploying machine learning models that analyze alternative data transaction history, utility payments, e-commerce behavior to score consumers without formal credit records, improving approval rates while maintaining portfolio quality.
4. Super-App and Marketplace BNPL Integration
Integration of BNPL within UAE super-apps, food delivery platforms, and marketplace ecosystems creates embedded finance touchpoints. Amazon.ae and Noon's BNPL partnerships exemplify this trend, making split payments available at millions of transaction points.
Industry Value Chain Analysis
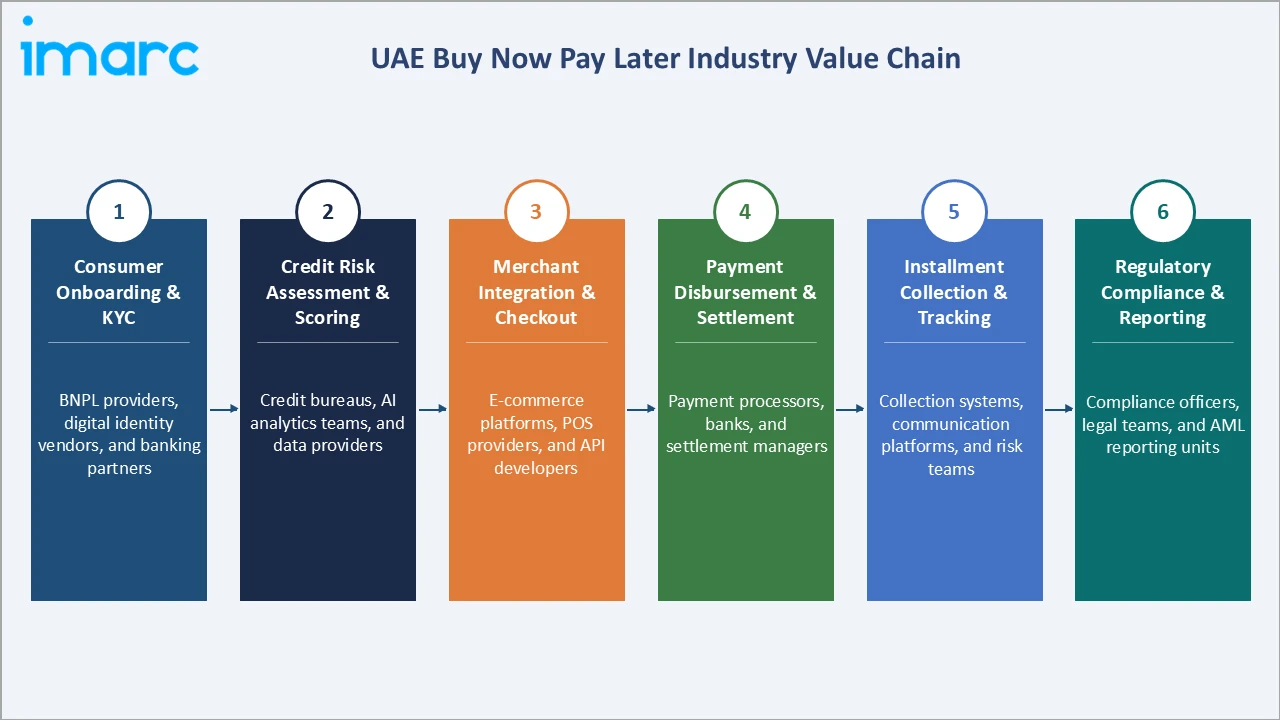
The UAE BNPL value chain integrates digital consumer onboarding, AI-driven credit assessment, merchant integration, and regulatory compliance layers.
|
Stage |
Key Participants |
|
Consumer Onboarding & KYC |
BNPL providers, digital identity vendors, and banking partners |
|
Credit Risk Assessment & Scoring |
Credit bureaus, AI analytics teams, and data providers |
|
Merchant Integration & Checkout |
E-commerce platforms, POS providers, and API developers |
|
Payment Disbursement & Settlement |
Payment processors, banks, and settlement managers |
|
Installment Collection & Tracking |
Collection systems, communication platforms, and risk teams |
|
Regulatory Compliance & Reporting |
Compliance officers, legal teams, and AML reporting units |
Each stage creates value by reducing friction for both consumers and merchants in the payment process.
Technology Landscape in the UAE BNPL Industry
AI-Powered Credit Decisioning and Risk Management
AI and machine learning are central to UAE BNPL operations. Real-time credit decisioning engines process thousands of data signals within seconds, enabling instant approval or decline decisions. These systems continuously learn from repayment behavior to improve accuracy and reduce default rates.
API-First Merchant Integration and Embedded Finance
UAE BNPL providers deploy open API frameworks enabling seamless integration with e-commerce platforms, POS systems, and mobile wallets. Embedded finance APIs allow any merchant to offer BNPL at checkout within hours, accelerating merchant network expansion across all retail categories.
Blockchain and Digital Identity Verification
Blockchain-based identity verification and digital KYC technologies reduce onboarding time from days to minutes. UAE's national digital identity infrastructure (UAE Pass) is increasingly integrated with BNPL onboarding flows, reducing fraud risk while enhancing consumer convenience and trust.
Market Segmentation Analysis
The report covers the following market segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Channel | Online | 72.6% | 2025 |
| Enterprise Size | Large Enterprises | 61.8% | 2025 |
| End Use | 🔒 | 🔒 | 2025 |
| Region | Dubai | 48.6% | 2025 |

By Channel
Online leads at 72.6% (2025). The online segment encompasses UAE's rapidly expanding e-commerce ecosystem, where BNPL is deeply integrated at digital checkout points across fashion, electronics, travel, and lifestyle platforms.
To access detailed market analysis, Request Sample
Point of Sale (POS) at 27.4% is growing as UAE retailers particularly luxury and electronics segments deploy in-store BNPL terminals. POS BNPL expansion is supported by NFC-enabled payment infrastructure across Dubai and Abu Dhabi's premium retail corridors.
By Enterprise Size
Large Enterprises lead at 61.8% (2025). Major retailers, hospitality groups, and e-commerce platforms leverage BNPL to increase average order values and improve customer retention metrics within their established merchant infrastructure.
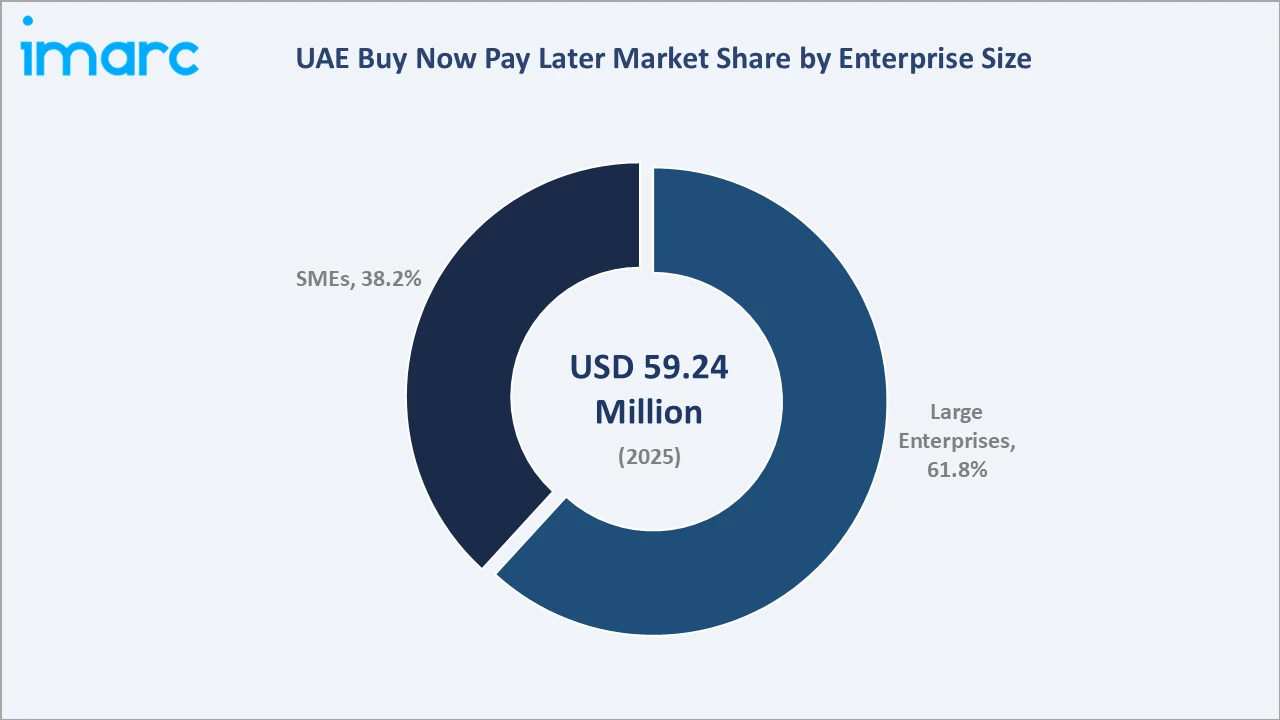
SMEs at 38.2% are growing fastest (approximately 25.8% CAGR) as accessible BNPL APIs enable smaller merchants to compete with large retailers on payment flexibility. Fintech platforms specifically targeting SME onboarding are accelerating this segment's adoption velocity.
Regional Market Insights
|
Region |
Share (2025) |
Key Characteristics |
|
Dubai |
48.6% |
Largest e-commerce hub; high fintech density; premium retail BNPL adoption. |
|
Abu Dhabi |
31.4% |
Government-backed digital transformation; growing SME sector; institutional BNPL demand. |
|
Sharjah |
13.2% |
Price-conscious consumers; interest-free BNPL resonates strongly; rising e-commerce adoption. |
|
Others |
6.8% |
Nascent BNPL adoption; growing smartphone-based financial service usage across Northern Emirates. |
Dubai's 48.6% leadership reflects its status as the MENA region's e-commerce and fintech capital. Abu Dhabi at 31.4% benefits from government-backed digital transformation and growing SME BNPL adoption.
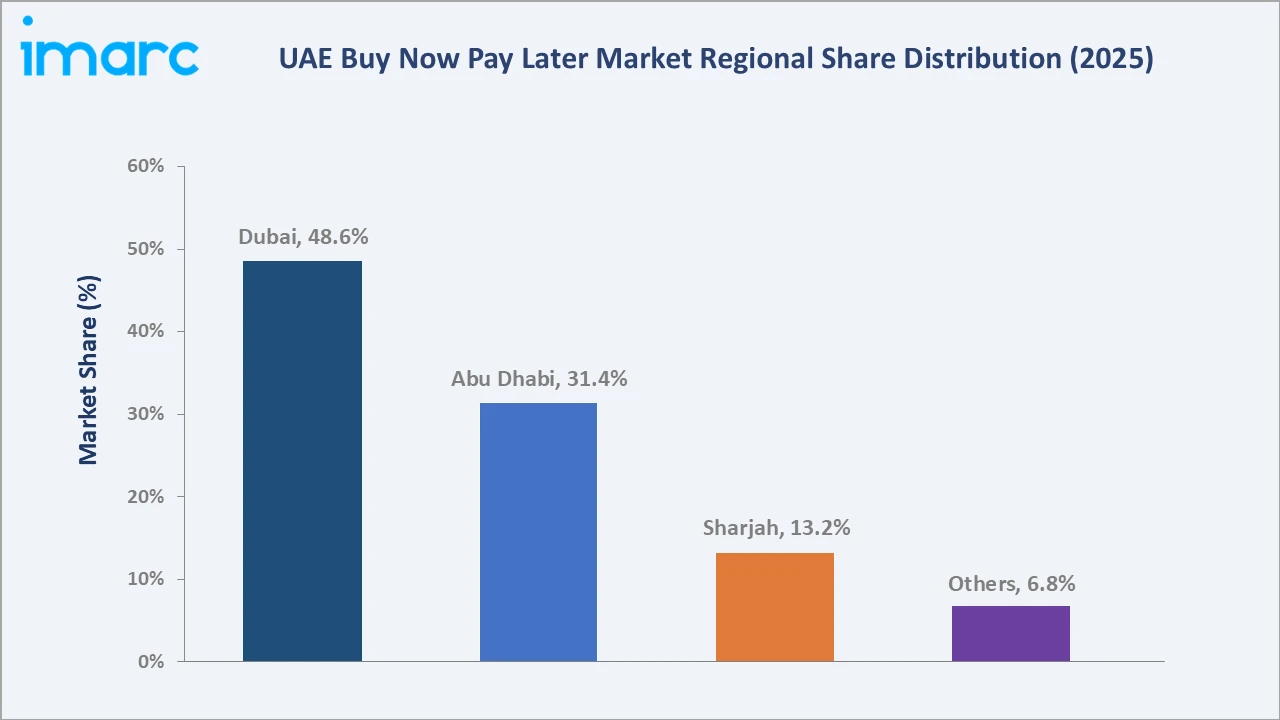
Sharjah at 13.2% represents a value-conscious consumer market where interest-free installment plans resonate strongly. The remaining emirates collectively contribute 6.8%, with growth accelerating as digital payment infrastructure expands beyond UAE's three primary markets.
Competitive Landscape
The UAE BNPL competitive landscape is dynamic and increasingly concentrated among a small number of well-funded regional players. Competition is intensifying through merchant acquisition, product differentiation, and geographic expansion across MENA markets.
| Company | Key Products/Services | Market Position | Core Strength |
|---|---|---|---|
| Tabby FZ-LLC | Pay in 4, Pay over time | Market Leader | Largest merchant network across GCC; seamless checkout integration across fashion, beauty, and electronics. |
| Tamara | Pay Later | Strong Challenger | Sharia-compliant model with strong UAE and Saudi Arabia merchant partnerships across lifestyle sectors. |
| Cashew Technology Software L.L.C. | Buy Now, Pay Later (BNPL) solution | Niche Player | SME merchant focus in UAE and MENA; flexible merchant fee structures; co-branded credit products. |
Key players include Tabby FZ-LLC, Tamara, Cashew Technology Software L.L.C., and others.
Key Company Profiles
Tabby FZ-LLC
Tabby FZ-LLC is the UAE's leading BNPL platform, operating across the GCC with the region's largest merchant network. The company offers interest-free split payment solutions integrating seamlessly with major e-commerce platforms and in-store POS systems.
- Key Products: Pay in 4, Pay over time
- Strategic Focus: Expanding merchant network beyond retail into travel, healthcare, and education verticals; deploying AI-driven credit decisioning to improve approval rates while managing credit risk effectively. Tabby FZ-LLC is also investing in loyalty and rewards infrastructure to increase repeat purchase frequency among its active consumer base and reduce customer churn across its GCC markets. The company plans to deepen banking partnerships to enhance its underwriting capabilities, enabling higher credit limits and improved approval rates for premium consumer segments.
Tamara
Tamara is a leading MENA-focused BNPL provider offering Sharia-compliant, interest-free installment solutions to consumers and merchants across the UAE and Saudi Arabia. The company focuses on fashion, beauty, and lifestyle retail verticals.
- Key Products: Pay Later
- Strategic Focus: Strengthening Sharia-compliant product credentials; expanding cross-border BNPL for UAE consumers shopping on international platforms; deepening integration with UAE's luxury retail ecosystem. Tamara Tech is pursuing strategic integrations with major UAE marketplace platforms to expand BNPL availability across a broader range of product categories beyond fashion and lifestyle. The company is also developing Arabic-language consumer education content to drive adoption among less digitally-savvy UAE demographic segments and expand its total addressable user base.
Market Concentration Analysis
The UAE BNPL market is moderately concentrated, with Tabby FZ-LLC and Tamara commanding an estimated 55-65% combined share of total BNPL transaction volume. The remaining share is distributed among other key olayers.
Concentration is evolving through two forces: continued Tabby FZ-LLC merchant network expansion deepening its lead, while Tamara's Sharia-compliant positioning introduces competitive fragmentation pressure at the premium consumer segment.
Investment & Growth Opportunities
Highest Growth Segments
Online (approximately 25.2% CAGR), point of sales (approximately 18.9% CAGR), SME’s (approximately 25.8% CAGR), cross-border e-commerce BNPL, and Sharia-compliant B2B BNPL represent UAE's highest-growth investment vectors through 2034.
Emerging Investment Opportunities
UAE's B2B BNPL segment enabling businesses to offer BNPL to their own clients is growing at 28-32% annually. White-label BNPL infrastructure for UAE banks and retailers presents a scalable investment model with lower customer acquisition costs than consumer-facing platforms.
Investment Themes
- Healthcare and elective medical BNPL platform investment, capturing UAE's USD 8 Billion-plus healthcare market where installment-based payment adoption remains under 10%, offering substantial first-mover advantage.
- AI-powered credit scoring infrastructure for UAE's underserved expatriate population, enabling BNPL providers to improve approval rates and reduce defaults through alternative data underwriting.
- Cross-border BNPL enabling UAE consumers to shop internationally with split-payment functionality, capitalizing on UAE's USD 12 Billion-plus cross-border e-commerce spend.
Future Market Outlook (2026-2034)
The UAE BNPL market is projected to grow from USD 72.97 Million in 2026 to USD 407.29 Million by 2034, at a CAGR of 23.17% during 2026-2034. The market's milestone of USD 167.95 Million by 2030 marks a structural inflection, as BNPL transitions from a niche to a mainstream payment method.
Three structural forces define UAE BNPL market growth through 2034: regulatory framework maturation enabling broader financial inclusion; AI-driven credit infrastructure reducing underwriting costs and expanding approval rates; and vertical expansion into healthcare, travel, and education creating new high-value transaction pools.
Research Methodology
Primary Research
Primary research comprised structured interviews with UAE BNPL industry stakeholders, including BNPL platform CEOs, Chief Risk Officers, Merchant Acquisition Directors, UAE banking partners, CBUAE regulatory contacts, and consumer survey data from UAE BNPL users across Dubai, Abu Dhabi, and Sharjah.
Secondary Research
Secondary research encompassed UAE Central Bank payment statistics, CBUAE annual reports, company investor presentations, UAE e-commerce market reports, fintech industry publications, IMF UAE economic data, and regional payment network transaction data. Over 45 secondary sources were reviewed.
Forecasting Models
Market revenue forecasts were developed using a merchant transaction volume model: UAE active BNPL merchant base multiplied by average monthly transaction volume and average order value, with adjustments for channel, enterprise size, and vertical-specific adoption rates.
UAE Buy Now Pay Later Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Channels Covered | Online, Point of Sale (POS) |
| Enterprise Sizes Covered | Large Enterprises, Small and Medium-sized Enterprises |
| End Uses Covered | Consumer Electronics, Fashion and Garment, Healthcare, Leisure and Entertainment, Retail, Others |
| Regions Covered | Dubai, Abu Dhabi, Sharjah, Others |
| Companies Covered | Tabby FZ-LLC, Tamara, Cashew Technology Software L.L.C., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the UAE buy now pay later market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the UAE buy now pay later market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the UAE buy now pay later industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the UAE Buy Now Pay Later Market Report
UAE BNPL market size stood at USD 72.97 Million in 2026, driven by rising e-commerce penetration, a digitally savvy young consumer base, and increasing fintech-bank collaborations supported by CBUAE regulatory oversight.
UAE BNPL market grows at 23.17% CAGR during 2026-2034, reaching USD 407.29 Million by 2034. Growth is sustained by e-commerce expansion, Sharia-compliant product adoption, and vertical expansion into healthcare and education.
Online leads at 72.6% through UAE's dominant e-commerce ecosystem, with BNPL deeply integrated at digital checkout across fashion, electronics, and lifestyle platforms including Amazon.ae and Noon.
Large Enterprises lead at 61.8% through established merchant infrastructure and high transaction volumes. SMEs at 38.2% are the fastest-growing segment at approximately 25.8% CAGR, supported by accessible API-first BNPL platforms.
Dubai leads at 48.6% through UAE's largest e-commerce ecosystem, highest fintech concentration, and advanced digital payment infrastructure. Abu Dhabi at 31.4% follows, supported by government-backed digital transformation initiatives.
Leading companies include Tabby FZ-LLC, Tamara, Cashew Technology Software L.L.C., and others.
UAE BNPL market is projected to reach approximately USD 167.95 Million by 2030, driven by healthcare and travel vertical expansion, AI-powered credit decisioning improving approval rates, and accelerating SME merchant adoption.
Three priority investment opportunities: healthcare and elective medical BNPL platform development; white-label B2B BNPL infrastructure for UAE banks and large retailers; and cross-border e-commerce BNPL for UAE consumers shopping on international platforms.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade