
Retail Market Size, Share, Trends and Forecast by Product, Distribution Channel, and Region, 2026-2034
Global Retail Market Size, Share, Trends & Forecast (2026-2034)
The global retail market size grew from USD 31.67 Trillion in 2025 to USD 33.27 Trillion in 2026 and is projected to reach USD 50.01 Trillion by 2034, growing at a CAGR of 5.05% during 2026-2034. Rising incomes, urbanization, and the rapid spread of digital and omnichannel shopping are supporting steady growth. In the United States, e-commerce reached 17.1% of total retail sales in the second quarter of 2026, showing how quickly spending is moving online.
Wider access to digital payments, expanding modern retail formats in emerging economies, and faster delivery continue to broaden demand. Food and beverages dominate at 40.7%. Supermarkets and hypermarkets lead distribution channels at 39.8%. Asia Pacific commands 36.8% of the global market share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 31.67 Trillion |
|
Market Size (2026) |
USD 33.27 Trillion |
|
Forecast Market Size (2034) |
USD 50.01 Trillion |
|
CAGR (2026-2034) |
5.05% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Product |
Food and Beverages (40.7%, 2025) |
|
Dominant Distribution Channel |
Supermarkets and Hypermarkets (39.8%, 2025) |
|
Leading Region |
Asia Pacific (36.8%, 2025) |
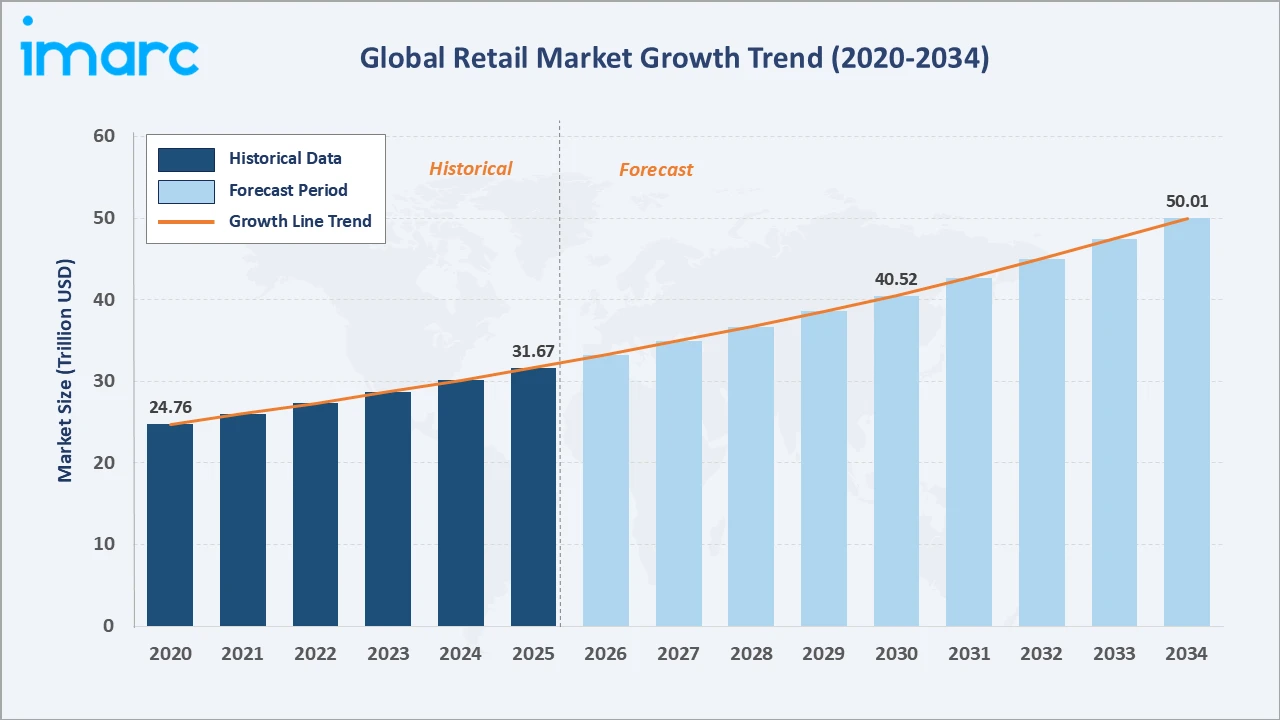
The global retail market size increased from USD 24.76 Trillion in 2020 to USD 31.67 Trillion in 2025 and is estimated to reach USD 33.27 Trillion in 2026. The market is further expected to grow to USD 40.52 Trillion by 2030 and USD 50.01 Trillion by 2034. Growth reflects both rising consumption volumes and higher prices, with emerging markets adding the newest shoppers.
To get more information on this market, Request Sample
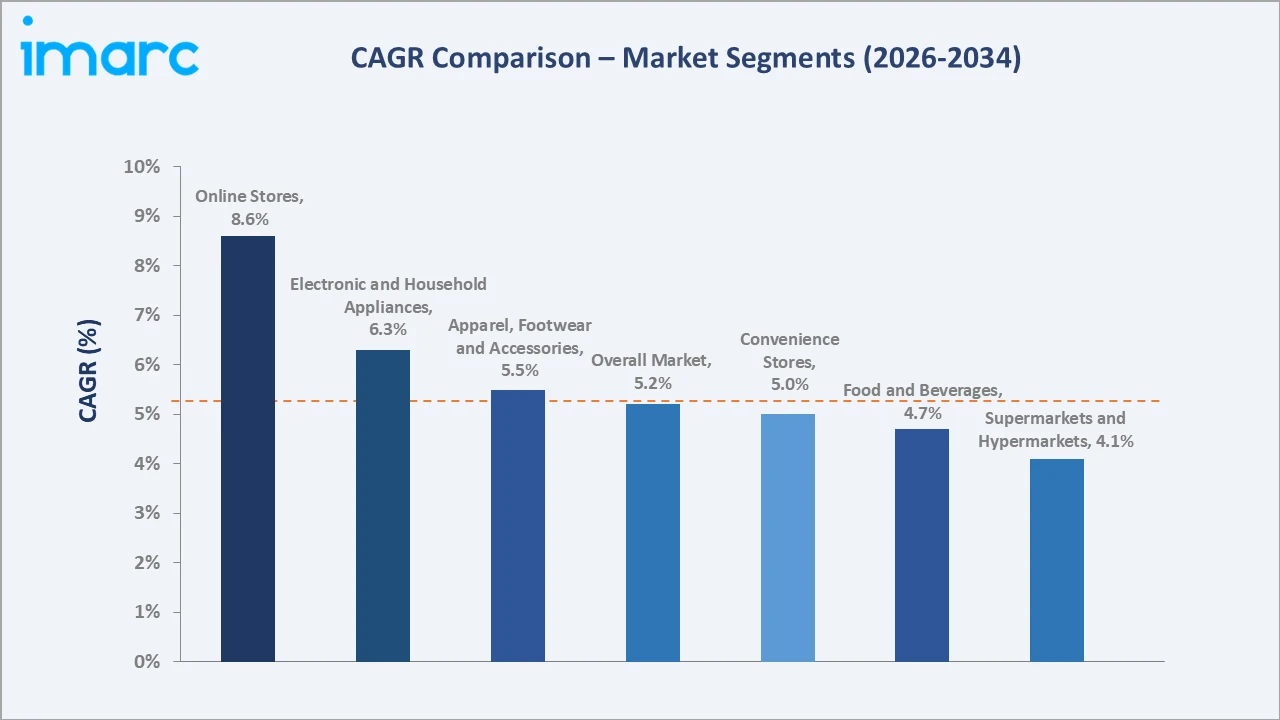
Online stores are expected to grow fastest at ~8.6% CAGR, supported by mobile shopping, quick commerce, and marketplace expansion. Electronic and household appliances follow at ~6.3% CAGR as connected devices, smart home products, and easy financing lift spending on durable goods.
Executive Summary
The global retail market expanded from USD 31.67 Trillion in 2025 to an estimated USD 33.27 Trillion in 2026. Retail is shifting from separate store and online businesses toward connected omnichannel models in which shoppers browse, buy, collect, and return across channels. Large retailers are investing in e-commerce, retail media, membership programs, and automation, while value-focused formats gain share as households watch budgets. The market is projected to reach USD 50.01 Trillion by 2034. Food and beverages at 40.7% leads as an everyday need. Supermarkets and hypermarkets at 39.8% remain the main shopping destination. Asia Pacific leads regionally at 36.8%.
Key Market Insights
|
Insight |
Data |
|
Dominant Product |
Food and Beverages - 40.7% share (2025) |
|
Dominant Distribution Channel |
Supermarkets and Hypermarkets - 39.8% market share (2025) |
|
Leading Region |
Asia Pacific - 36.8% share (2025) |
|
Market Opportunity |
Online grocery and quick commerce; retail media networks; private label expansion; modern retail growth in emerging Asian and African markets |
Key Analytical Observations Supporting the Above Data:
- Food and Beverages at 40.7%: Food and beverages dominate because groceries are bought frequently by every household regardless of income. Fresh produce, packaged foods, dairy, and drinks generate steady traffic for supermarkets, convenience stores, and online grocery platforms, making the category the backbone of global retail spending.
- Supermarkets and Hypermarkets at 39.8%: Supermarkets and hypermarkets lead due to their wide assortment, competitive prices, and one-stop convenience. Many chains now combine large stores with click-and-collect and home delivery, reinforcing their central role.
- Asia Pacific at 36.8%: Asia Pacific leads regionally due to its huge populations in China, India, Indonesia, and Japan, rising middle-class incomes, and the world’s most advanced mobile commerce ecosystems.
Global Retail Market Overview
Retail is the final link between producers and consumers, covering everything from groceries and medicines to clothing, furniture, and electronics. The industry ranges from global chains and online marketplaces to millions of small independent shops, street vendors, and family-run stores, particularly in emerging economies.
The industry ecosystem links manufacturers, wholesalers, retailers, logistics providers, payment companies, technology vendors, and consumers. Macroeconomic factors include household income, employment, inflation, interest rates, consumer confidence, and trade policy, all of which shape what people buy, how often, and through which channels.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
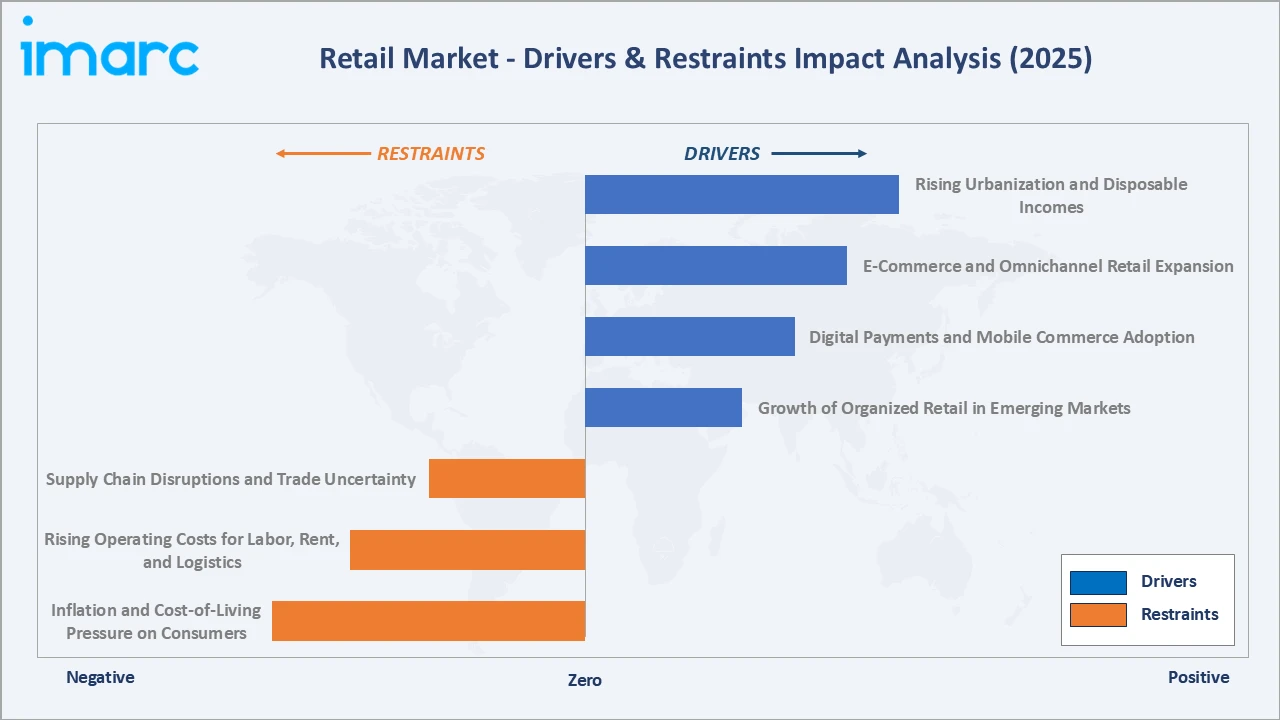
- Rising Urbanization and Disposable Incomes: Growing urban populations and rising household incomes are expanding the number of consumers who shop regularly at modern retail outlets. City dwellers tend to spend more on packaged foods, personal care, apparel, and electronics, and they have easier access to supermarkets, malls, and fast delivery services. As middle-class households grow in emerging economies, spending is shifting from basic necessities toward branded, premium, and convenience-oriented products, lifting both the volume and value of retail sales. Growth in dual-income households and smaller family sizes also increases demand for convenience foods, ready meals, and time-saving services.
- E-Commerce and Omnichannel Retail Expansion: Online shopping continues to gain share as consumers value convenience, wider choice, and easy price comparison. Retailers are combining physical stores with websites, mobile apps, and marketplaces, allowing customers to buy online and collect in store, return items across channels, and receive same-day delivery. This omnichannel approach increases shopping frequency, improves customer loyalty, and helps retailers reach shoppers well beyond the catchment area of their physical stores. Data from online and store transactions also helps retailers plan assortments, staff stores, and position inventory closer to demand.
- Digital Payments and Mobile Commerce Adoption: Smartphones, digital wallets, real-time payment systems, and contactless cards are making transactions faster and easier, both online and in stores. Mobile commerce is especially strong in markets where consumers skipped desktop computers and moved straight to smartphones. Buy-now-pay-later options and integrated loyalty programs further encourage spending, while digital payments give retailers valuable data to personalize offers and manage inventory more accurately. Lower cash handling costs and faster checkout also improve store efficiency and reduce losses from theft and errors.
- Growth of Organized Retail in Emerging Markets: In many developing economies, a large share of retail still takes place in small, independent, and informal stores. Modern supermarkets, convenience chains, specialty stores, and online platforms are steadily expanding into these markets, supported by improving infrastructure, policy reforms, and investment from domestic and international retailers. This shift improves product quality, pricing transparency, and choice for consumers while creating significant long-term growth for organized retail operators. Rising consumer awareness of food safety, brand authenticity, and after-sales service further supports the move toward organized formats.
Market Restraints
- Inflation and Cost-of-Living Pressure on Consumers: Higher prices for food, energy, and housing reduce the share of household income available for discretionary purchases such as apparel, furniture, and electronics. Shoppers respond by trading down to cheaper brands, buying smaller quantities, and delaying big-ticket purchases. While value retailers may benefit, overall volume growth slows and retailers face pressure to protect margins without losing price-sensitive customers. Prolonged inflation can also change shopping habits for years, with consumers remaining loyal to discount formats even after price growth eases.
- Rising Operating Costs for Labor, Rent, and Logistics: Retailers face higher wages, rising store rents in prime locations, increased energy bills, and the growing cost of fulfilling online orders. Last-mile delivery, product returns, and warehouse automation require significant investment, and these costs are difficult to pass fully onto consumers in a highly competitive market. Smaller retailers with limited scale are particularly exposed to these pressures. Labor shortages in warehousing, delivery, and store operations can further raise costs and limit service quality during peak seasons.
- Supply Chain Disruptions and Trade Uncertainty: Global retail depends on long, complex supply chains that can be disrupted by shipping delays, port congestion, extreme weather, geopolitical tensions, and changing tariffs. Such disruptions can cause stock shortages, higher import costs, and excess inventory when demand shifts unexpectedly. Retailers are diversifying suppliers and building more resilient networks, but these steps add cost and complexity. Holding higher safety stock to manage uncertainty also ties up working capital and warehouse space.
Market Opportunities
- Retail Media Networks and Data Monetization: Retailers with large customer bases and rich purchase data can sell targeted advertising to brands on their websites, apps, and in-store screens. Retail media offers high-margin revenue that helps fund price investments and digital growth, and it allows brands to reach shoppers at the point of purchase with measurable results. Growth in in-store digital screens and connected TV advertising is widening the reach of these networks beyond online channels.
- Private Label and Value-Focused Formats: Store brands offer shoppers quality products at lower prices and give retailers higher margins and stronger loyalty. Hard discounters, warehouse clubs, and off-price formats are well placed to win budget-conscious households, while premium private labels help retailers differentiate in categories such as fresh food, beauty, and home goods. Strong private label programs also give retailers more control over sourcing, quality, and sustainability standards.
Market Challenges
- Intense Competition and Margin Pressure: Retailers compete with global marketplaces, discount chains, direct-to-consumer brands, and social commerce sellers, often on price. Constant promotions, free delivery expectations, and price transparency online keep margins thin, and retailers without scale, a clear value proposition, or a loyal customer base face growing risk of losing market share. Fast-moving trends driven by social media also shorten product life cycles and increase the risk of unsold inventory.
- Data Privacy, Cybersecurity, and Regulatory Compliance: As retailers collect more customer data through apps, loyalty programs, and online transactions, they face stricter privacy rules and growing cyber risks. Data breaches can damage trust and result in large fines, while compliance with diverse consumer protection, product safety, and labeling regulations across countries adds operational complexity. Retailers must invest continually in security systems, staff training, and governance to keep pace with evolving threats and rules.
Emerging Market Trends
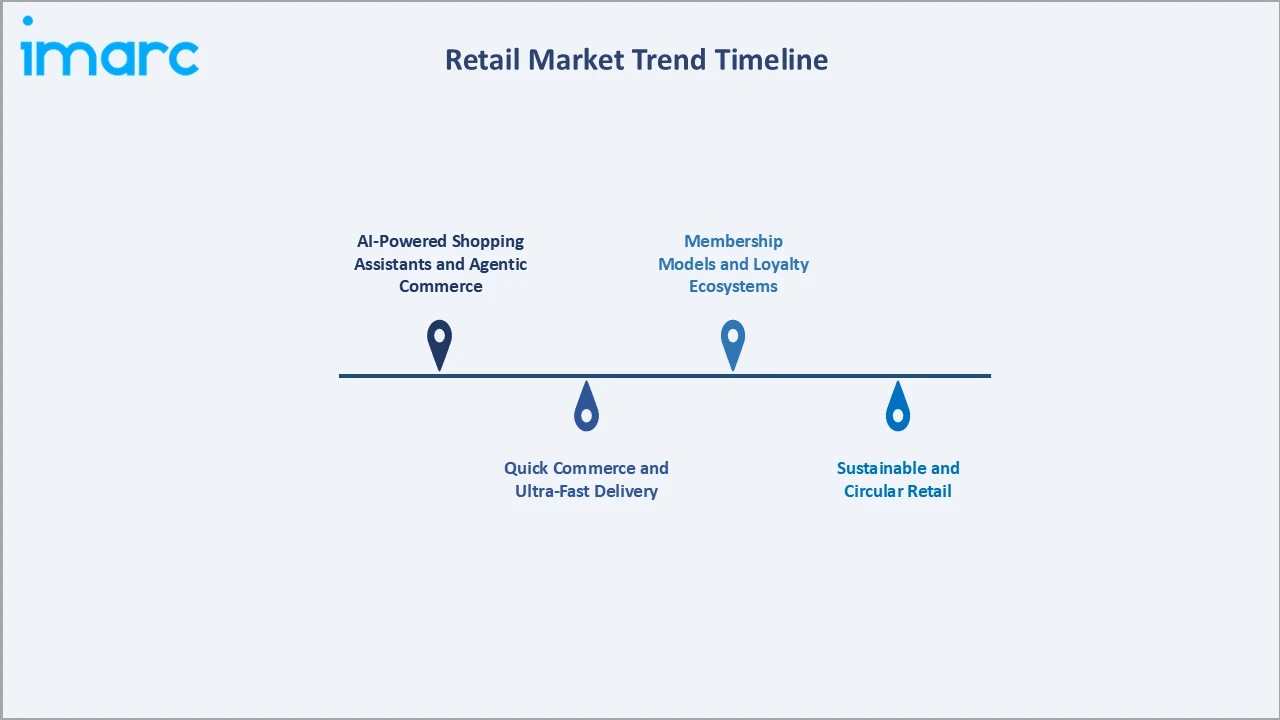
1. AI-Powered Shopping Assistants and Agentic Commerce
Retailers are deploying AI assistants that answer product questions, compare options, build shopping lists, and increasingly complete purchases on behalf of customers. These tools make product discovery faster and more personal, and they are expected to change how shoppers search for and buy products. Retailers that integrate AI into search, recommendations, and customer service can lift conversion rates and basket sizes while reducing service costs. Over time, retailers will also need to ensure their products are easy for third-party AI agents to find, compare, and purchase.
2. Quick Commerce and Ultra-Fast Delivery
Delivery of groceries and daily essentials within minutes or a few hours is becoming common in dense urban areas. Dark stores, micro-fulfillment centers, and store-based picking allow retailers to meet rising expectations for speed. Quick commerce is reshaping convenience retail, encouraging smaller and more frequent orders and pushing traditional chains to upgrade their own delivery capabilities. Profitability remains a key focus, with operators refining order sizes, delivery fees, and store density to make the model sustainable.
3. Membership Models and Loyalty Ecosystems
Paid memberships and loyalty programs that bundle free delivery, discounts, streaming, and exclusive offers are becoming central to retail strategy. These programs generate recurring fee income, increase visit frequency, and provide rich customer data. Retailers are linking memberships with payments, partner brands, and personalized offers to build long-term relationships rather than one-off transactions. Well-designed programs also reduce reliance on heavy discounting by rewarding loyalty with service and convenience rather than price alone.
4. Sustainable and Circular Retail
Consumers and regulators are pushing retailers to reduce packaging waste, cut emissions, and offer more sustainable products. Resale, repair, rental, and refill services are expanding, particularly in apparel, electronics, and home goods. Retailers are also investing in energy-efficient stores, cleaner transport, and supply chain transparency to meet sustainability targets and appeal to environmentally conscious shoppers. Clear product labeling on origin, materials, and carbon impact is also becoming a point of differentiation for leading retailers. Retailers that build credible take-back and resale programs can also attract new customers and create additional revenue from returned and pre-owned products.
Industry Value Chain Analysis
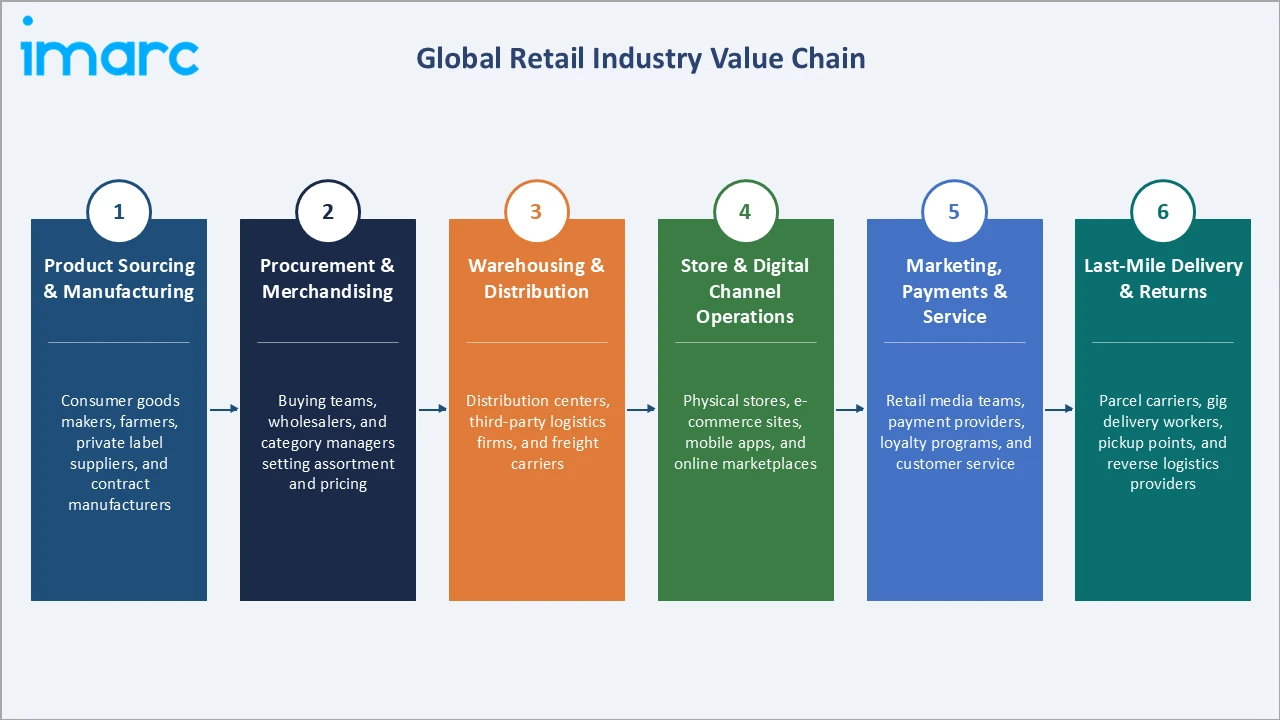
The retail value chain runs from product sourcing and manufacturing through procurement, warehousing, store and digital operations, marketing, and final delivery. Value is increasingly captured by retailers that control customer relationships, data, and efficient logistics, rather than by those relying only on physical store networks.
|
Stage |
Key Participants |
|
Product Sourcing & Manufacturing |
Consumer goods makers, farmers, private label suppliers, and contract manufacturers |
|
Procurement & Merchandising |
Buying teams, wholesalers, and category managers setting assortment and pricing |
|
Warehousing & Distribution |
Distribution centers, third-party logistics firms, and freight carriers |
|
Store & Digital Channel Operations |
Physical stores, e-commerce sites, mobile apps, and online marketplaces |
|
Marketing, Payments & Service |
Retail media teams, payment providers, loyalty programs, and customer service |
|
Last-Mile Delivery & Returns |
Parcel carriers, gig delivery workers, pickup points, and reverse logistics providers |
Last-mile delivery is the most consequential stage of the chain today. It is often the most expensive part of fulfilling an online order and has a direct impact on customer satisfaction. Retailers are using stores as fulfilment hubs, automated warehouses, and route optimization to lower costs while meeting demand for faster delivery.
Technology Landscape in the Global Retail Industry
Artificial Intelligence and Data Analytics
Retailers use AI and advanced analytics to forecast demand, set prices, plan assortments, personalize marketing, and manage inventory across stores and warehouses. Machine learning models help reduce stockouts and waste, particularly in fresh food. Generative AI is also improving product search, content creation, and customer service, allowing retailers to serve shoppers more efficiently and at greater scale. Computer vision tools also help monitor shelf availability, detect pricing errors, and reduce shrinkage in stores.
Store Automation and Smart Checkout
Self-checkout kiosks, scan-and-go apps, electronic shelf labels, computer vision, and inventory-scanning robots are reducing labor needs and improving the in-store experience. Cashier less store formats allow shoppers to pick items and leave, with payment handled automatically. These technologies help retailers manage rising labor costs while freeing staff to focus on customer service and online order picking. Digital signage and mobile apps linked to store inventory also help shoppers find products and promotions more quickly.
Supply Chain Automation and Fulfilment Technology
Automated warehouses, robotic picking systems, micro-fulfilment centres, and real-time inventory tracking allow retailers to process online orders faster and more accurately. Route optimization software and electric delivery vehicles are reducing last-mile costs and emissions. Integrated order management platforms give retailers a single view of stock across stores, warehouses, and suppliers. Predictive analytics helps retailers anticipate demand spikes and position stock ahead of seasonal peaks and promotions.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Product | Food and Beverages | 40.7% | 2025 |
| Distribution Channel | Supermarkets and Hypermarkets | 39.8% | 2025 |
| Region | Asia Pacific | 36.8% | 2025 |

By Product
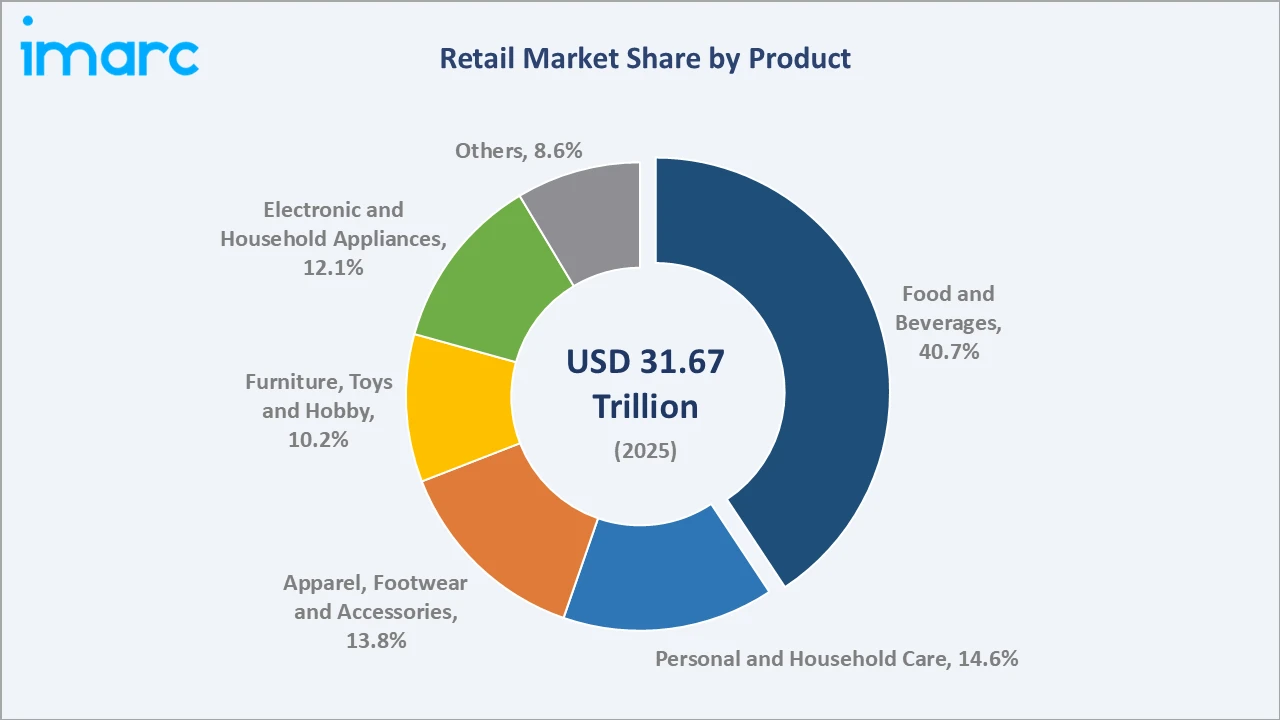
Food and beverages leads at 40.7% (2025). Groceries are bought frequently by every household, giving the category stable demand through economic cycles. Growth in packaged, ready-to-eat, and fresh foods, along with online grocery delivery, keeps food and beverages at the centre of global retail.
To access detailed market analysis, Request Sample
Personal and household care at 14.6% is growing at ~5.4% CAGR, supported by hygiene awareness and premium beauty. Apparel, footwear and accessories at 13.8% grow at ~5.5%, electronic and household appliances at 12.1% at ~6.3%, furniture, toys and hobby at 10.2% at ~4.9%, and others at 8.6% at ~5.6%.
By Distribution Channel
Supermarkets and hypermarkets lead at 39.8% (2025). Their broad assortment, competitive prices, and one-stop shopping make them the main destination for weekly household purchases. Many chains are adding online ordering, delivery, and click-and-collect services to defend their position.
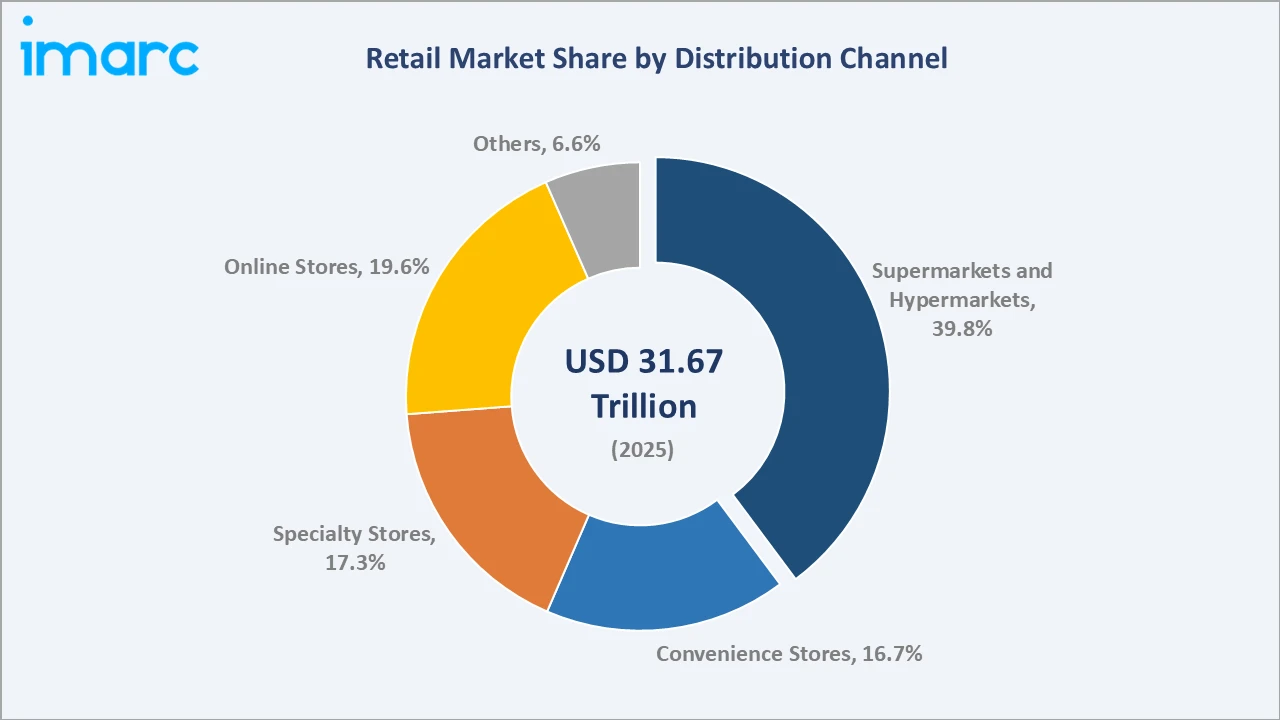
Online stores at 19.6% are growing fastest at ~8.6% CAGR, driven by mobile shopping and quick delivery. Specialty stores at 17.3% grow at ~4.2%, convenience stores at 16.7% at ~5.0% through urban top-up shopping, and others at 6.6% at ~3.4%.
Regional Market Insights
| Region | Share (2025) | Key Global Retail Market Drivers & Characteristics |
|---|---|---|
| Asia Pacific | 36.8% | Large populations, rising middle-class incomes, and highly developed mobile commerce in China, India, and Southeast Asia. |
| North America | 27.4% | High per capita spending, strong big-box and warehouse club formats, and fast-growing omnichannel sales. |
| Europe | 23.1% | Mature grocery market, strong discount chains, and strict consumer protection and sustainability rules. |
| Latin America | 7.1% | Expanding modern retail, rising e-commerce, and growing use of digital payments in Brazil and Mexico. |
| Middle East and Africa | 5.6% | Young populations, new malls and hypermarkets in the Gulf, and early-stage organized retail in Africa. |
Asia Pacific's 36.8% market leadership reflects China's vast consumer market, India's fast-growing organized retail sector, and Southeast Asia's young, mobile-first shoppers. North America's 27.4% reflects high household spending, strong retail chains, and advanced omnichannel and membership models.
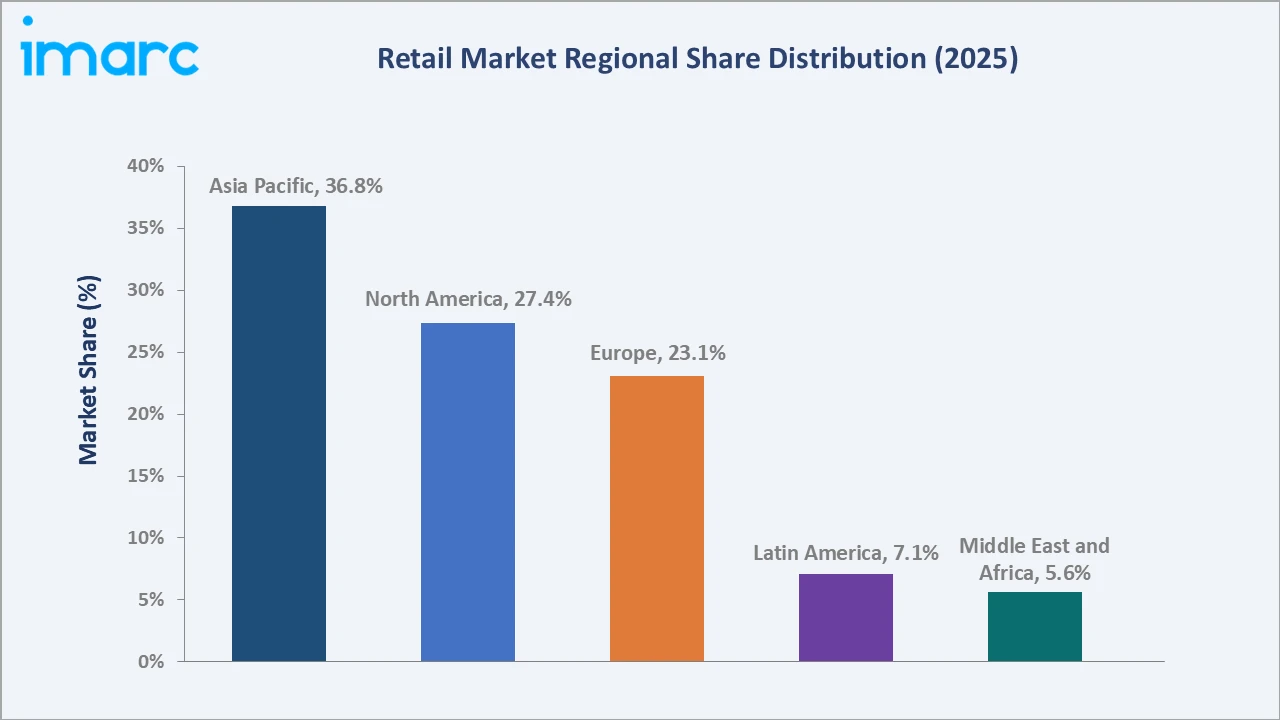
Europe's 23.1% reflects a mature, highly competitive grocery sector led by discounters. Latin America's 7.1% and Middle East and Africa's 5.6% are smaller, but rising incomes, urbanization, and growing digital adoption give both regions strong long-term growth potential.
Competitive Landscape
The global retail market is highly fragmented, with large international chains and online platforms competing alongside millions of local stores. Leading players compete on price, convenience, assortment, delivery speed, and customer loyalty, while investing heavily in technology, logistics, and membership programs.
| Company | Key Brands | Market Position | Core Strength |
|---|---|---|---|
| Walmart Inc. | Equate, Free Assembly, Athletic Works | Market Leader | The largest retailer by revenue, with a vast store network and fast-growing e-commerce. |
| Amazon.com Inc. | Amazon's Alexa+, Kindle, Echo | Market Leader | A dominant online marketplace backed by an extensive fulfillment network. |
| Costco Wholesale Corporation | Costco, Kirkland Signature | Strong Challenger | A membership warehouse model with high renewal rates and strong private label. |
| Alibaba Group Holding Limited | Taobao, Tmall, AliExpress, Freshippo | Innovator | Leading e-commerce ecosystem in China with integrated payments and logistics. |
| JD.com Inc. | JD Ehome, JD Logistics, 7FRESH | Innovator | Self-operated e-commerce with an in-house logistics network. |
| Schwarz Corporate Affairs GmbH & Co. KG | Lidl, Kaufland | Strong Challenger | A leading European grocery group built on an efficient discount model. |
| The Kroger Co. | Kroger Brand, Simple Truth, Home Chef | Strong Challenger | A major U.S. supermarket operator with strong private labels and retail media. |
The most important competitive dynamic is the race to combine physical stores, e-commerce, and data. Retailers with scale, strong logistics, and loyal membership bases are gaining share, while smaller chains face pressure to specialize, partner, or consolidate.
Key Company Profiles
Walmart Inc.
Walmart Inc., headquartered in Bentonville, Arkansas, is a multinational retail corporation operating a global network of physical stores and e-commerce platforms. The company offers a wide range of products, including groceries, apparel, electronics, household essentials, and health and personal care products.
- Key Brands: Walmart, Sam's Club, Walmart+, Flipkart, Walmart Connec Equate, Free Assembly, Athletic Works.
- Recent Developments: In fiscal 2026, Walmart generated USD 150.4 Billion in global e-commerce sales, up 24%, while membership fee revenue rose 15.5%.
- Strategic Focus: Expanding e-commerce, advertising, and membership income while investing in supply chain automation and AI.
Amazon.com Inc.
Amazon.com Inc., headquartered in Seattle, Washington, is a multinational technology and e-commerce company operating across online retail, cloud computing, digital streaming, and artificial intelligence. The company offers a broad range of products and services to consumers, businesses, and organisations worldwide.
- Key Brands: Amazon's Alexa+, Kindle, Echo.
- Recent Developments: Amazon said its Rufus AI shopping assistant was used by more than 300 million customers and delivered about USD 12 Billion in incremental annualized sales in 2025.
- Strategic Focus: Speeding up delivery, expanding grocery and quick commerce, and using AI to improve shopping.
Costco Wholesale Corporation
Costco Wholesale Corporation, headquartered in Issaquah, Washington, is a multinational membership-based warehouse retailer offering a wide range of products, including groceries, electronics, household essentials, apparel, and health and personal care items. The company operates warehouse clubs and e-commerce platforms, focusing on providing quality products at competitive prices.
- Key Brands: Costco, Kirkland Signature, Costco Business Center, Costco Next.
- Recent Developments: Digitally enabled comparable sales rose 20.9% in fiscal 2026, as online ordering complemented warehouse traffic.
- Strategic Focus: Opening new warehouses, growing membership, and expanding digital and delivery services.
Market Concentration Analysis
The global retail market is highly fragmented. Even the largest players, Walmart and Amazon, together generated about USD 1.4 Trillion in revenue, under 5% of the global retail market size. Millions of small independent stores and regional chains still account for most retail sales, especially across Asia, Africa, and Latin America.
Market concentration is evolving through two opposing forces: large retailers are gaining share through e-commerce, memberships, and acquisitions, while marketplaces, social commerce, and direct-to-consumer brands lower entry barriers and keep the market competitive.
Investment & Growth Opportunities
Highest Growth Segments
Online stores (~8.6% CAGR through mobile and quick commerce), electronic and household appliances (~6.3% CAGR through smart home adoption), Middle East and Africa (~6.7% CAGR through urbanization), and Asia Pacific (~6.4% CAGR through middle-class growth) represent the highest-growth investment areas in the global retail market through 2034.
Emerging Investment Opportunities
Retail media networks are one of the most promising emerging opportunities. Retailers with large digital audiences can earn high-margin advertising income from brands, and investment in data platforms, in-store screens, and measurement tools can unlock significant new revenue.
Investment Themes
- Fulfillment automation and last-mile logistics: Automated warehouses, micro-fulfillment centers, and delivery networks offer long-term returns as online and same-day orders grow.
- Organized retail expansion in emerging markets: Modern grocery, convenience, and specialty chains in India, Southeast Asia, and Africa offer strong growth as shoppers move from informal stores.
Future Market Outlook (2026-2034)
The global retail market is projected to grow from USD 31.67 Trillion in 2025 to USD 33.27 Trillion in 2026, reaching USD 50.01 Trillion by 2034, registering a CAGR of 5.05% during 2026-2034. The anchor value of USD 40.52 Trillion in 2030 marks a point at which omnichannel shopping and AI-assisted buying should be standard practice across major markets.
Three structural forces define global retail market growth through 2034: rising consumption in emerging economies; the continued shift to digital and omnichannel shopping; and investment in automation, data, and logistics that improves efficiency and customer experience.
Research Methodology
Primary Research
Primary research comprised structured interviews with retail industry stakeholders, including retail executives, category managers, supply chain and logistics specialists, technology vendors, and consumer goods manufacturers, along with consumer survey inputs from all major regions.
Secondary Research
Secondary research covered company annual reports and investor presentations, government retail and e-commerce statistics, trade data, regulatory publications, and industry association reports. Over 50 credible secondary sources were reviewed, compared, and cross-checked for accuracy.
Forecasting Models
Market revenue forecasts were developed using a consumption-based model: population by region multiplied by per capita retail spending for each product and channel, adjusted for income growth, inflation, and channel shifts, with segment results aggregated to total market value.
Retail Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Trillion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Products Covered | Food and Beverages, Personal and Household Care, Apparel, Footwear and Accessories, Furniture, Toys and Hobby, Electronic and Household Appliances, Others |
| Distribution Channels Covered | Supermarkets and Hypermarkets, Convenience Stores, Specialty Stores, Online Stores, Others |
| Regions Covered | Asia Pacific, Europe, North America, Latin America, Middle East and Africa |
| Countries Covered | United States, Canada, Germany, France, United Kingdom, Italy, Spain, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Mexico |
| Companies Covered | Walmart Inc., Amazon.com Inc., Costco Wholesale Corporation, Alibaba Group Holding Limited, JD.com Inc., Schwarz Corporate Affairs GmbH & Co. KG, The Kroger Co., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the retail market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the global retail market.
- The study maps the leading, as well as the fastest-growing, regional markets. It further enables stakeholders to identify the key country-level markets within each region.
- Porter's five forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the retail industry and its attractiveness.
- The competitive landscape allows stakeholders to understand their competitive environment and provides insight into the current positions of key players in the market.
Frequently Asked Questions About the Retail Market Report
The global retail market size is estimated at USD 33.27 Trillion in 2026, supported by rising incomes, urbanization, and the growth of omnichannel shopping.
The global retail market grows at 5.05% CAGR during 2026-2034, reaching USD 50.01 Trillion by 2034.
Food and beverages leads at 40.7%, supported by frequent, essential household purchases.
Supermarkets and hypermarkets lead at 39.8%, owing to their wide assortment, competitive prices, and one-stop convenience.
Asia Pacific leads at 36.8%, driven by large populations, rising incomes, and advanced mobile commerce.
Leading companies include Walmart Inc., Amazon.com Inc., Costco Wholesale Corporation, Alibaba Group Holding Limited, JD.com Inc., Schwarz Corporate Affairs GmbH & Co. KG, and The Kroger Co., among others.
The global retail market size is projected to reach approximately USD 40.52 Trillion by 2030, with online stores taking a larger share of sales.
Three priority opportunities stand out: retail media networks, fulfillment automation and last-mile logistics, and organized retail expansion in emerging markets.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade