Saudi Arabia Building Materials Market Size, Share, Trends and Forecast by Type, Application, and Region, 2026-2034
Saudi Arabia Building Materials Market Size, Share, Trends & Forecast (2026-2034)
The Saudi Arabia building materials market grew from USD 185.4 Billion in 2025 to USD 187.7 Billion in 2026 and is projected to reach USD 207.0 Billion by 2034, growing at a CAGR of 1.24% during 2026-2034. The market is driven by sustained Vision 2030 infrastructure investment, giga-project construction activity, and the National Housing Program that positions the kingdom as one of the largest building materials consumers. Cement leads at 36.8% by type, residential dominates at 43.6% by application, and the Northern and Central region commands the largest regional share at 38.5% in 2025.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 185.4 Billion |
|
Market Size (2026) |
USD 187.7 Billion |
|
Forecast Market Size (2034) |
USD 207.0 Billion |
|
CAGR (2026-2034) |
1.24% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Type |
Cement (36.8%, 2025) |
|
Dominant Application |
Residential (43.6%, 2025) |
|
Leading Region |
Northern and Central Region (38.5%, 2025) |
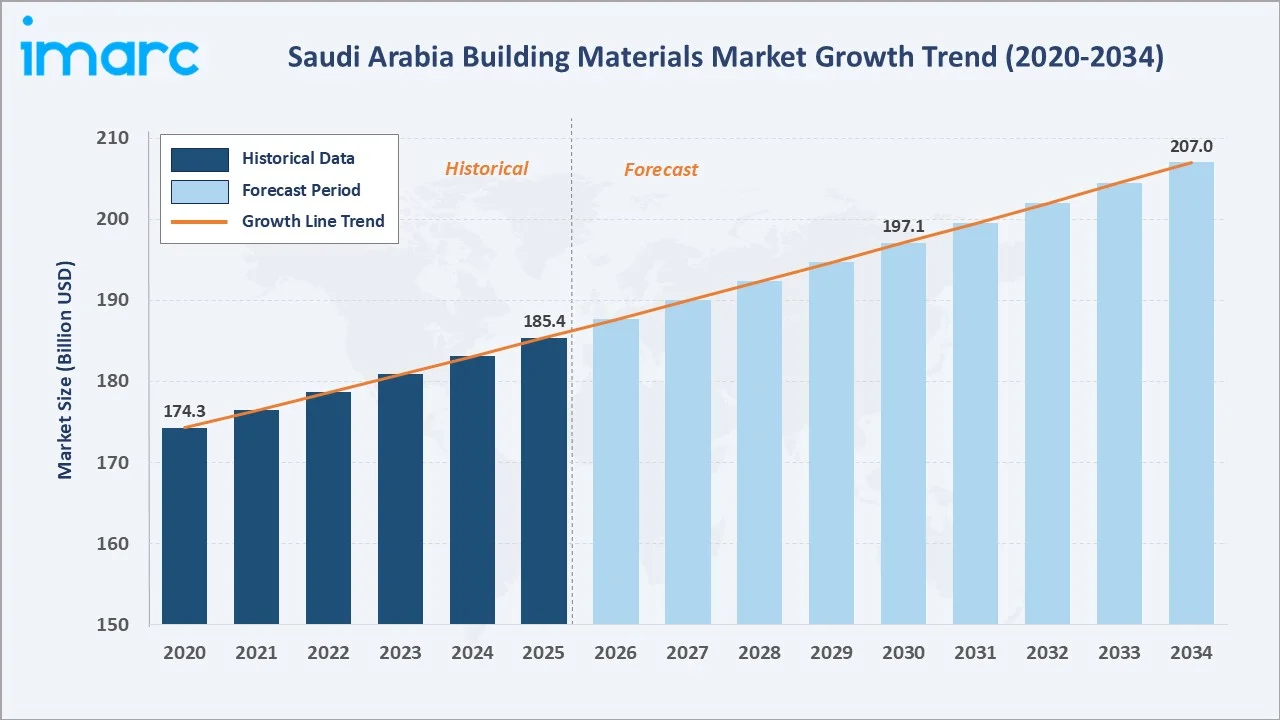
The Saudi Arabia building materials market grew from USD 174.3 Billion in 2020 to USD 185.4 Billion in 2025, and further to USD 187.7 Billion in 2026, reflecting steady demand growth driven by sustained government capital expenditure, giga-project material procurement, and private sector residential construction. The market is projected to reach USD 197.1 Billion by 2030 before reaching USD 207.0 Billion by 2034.
To get more information on this market, Request Sample
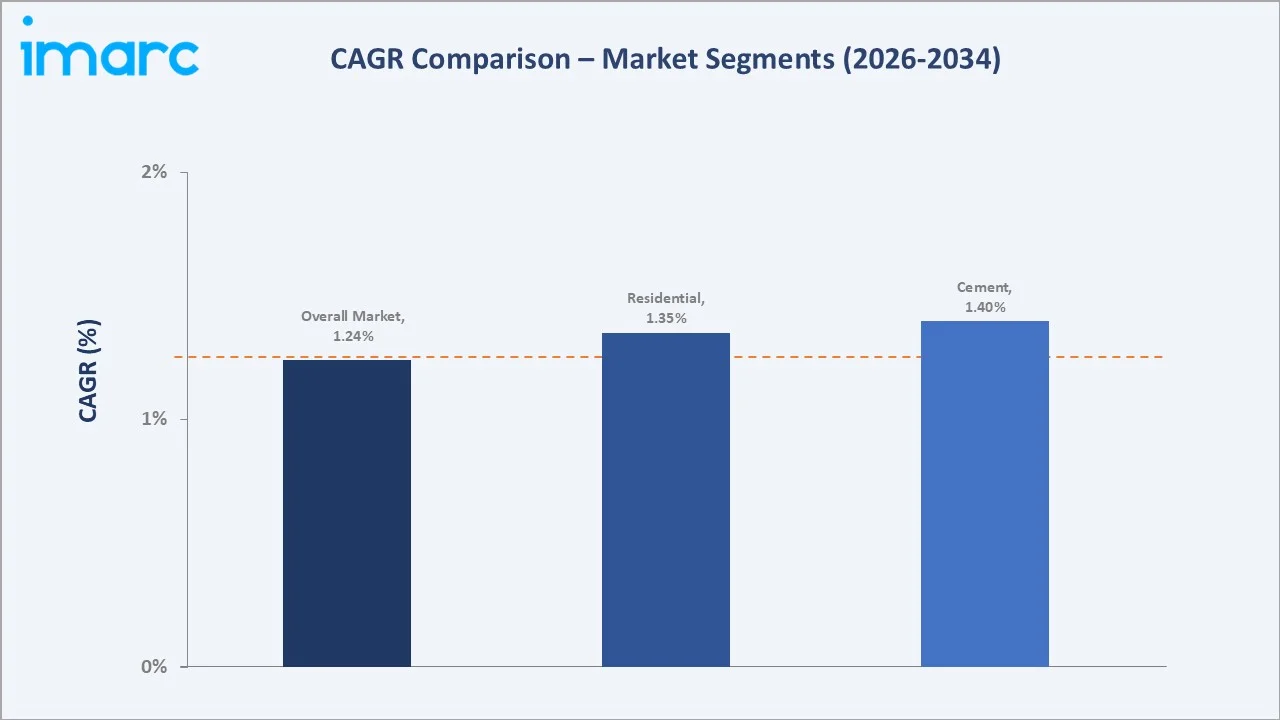
Cement is growing at a 1.4% CAGR, reflecting Saudi Arabia position as one of the top countries in cement production capacity, where domestic demand and giga-project demand continue to sustain throughput. Residential application at 1.35% CAGR reflects the National Housing Program and residential development programs generating sustained building materials consumption across the kingdom.
Executive Summary
The Saudi Arabia building materials market is one of the largest and most strategically important construction material markets, underpinned by sustained Vision 2030 investment programs, a portfolio of giga-projects that collectively represent the most concentrated construction activity on the planet, and a National Housing Program generating sustained residential building materials demand.
Cement at 36.8% leads by material type, reflecting its fundamental role in all construction applications from residential foundations through commercial structures to giga-project infrastructure. By application, residential at 43.6% leads, driven by the National Housing Program and other PIF-backed residential communities, and organic urban housing demand from Saudi Arabia growing population. The Northern and Central region leads at 38.5%, anchored by Riyadh as the national capital concentration of Vision 2030 administrative capital, and Sedra and other PIF residential programs.
Key Market Insights
|
Insight |
Data |
|
Dominant Type |
Cement - 36.8% share (2025) |
|
Dominant Application |
Residential - 43.6% share (2025) |
|
Leading Region |
Northern and Central Region - 38.5% (2025) |
|
Key Market Opportunity |
Vision 2030 megaprojects, residential and commercial construction, infrastructure development, tourism and hospitality projects, sustainable/green materials, prefabrication and modular construction, and advanced construction technologies. |
Key Analytical Observations Supporting the Above Data:
- Cement at 36.8%: Cement dominates Saudi Arabia building materials market because concrete, the primary construction material for all structural applications, is cement-based, and Saudi Arabia building stock is overwhelmingly cast-in-situ or precast reinforced concrete.
- Residential at 43.6%: Residential application leads because Saudi Arabia National Housing Program, Roshn and PIF-backed residential community developments represent the kingdom's largest capital deployment program in the residential sector, and organic Saudi population growth generates sustained baseline housing demand requiring consistent building materials consumption across all material categories.
- Northern and Central Region at 38.5%: Riyadh and the central region lead because the city concentrates the highest capital expenditure density of any Saudi region that requires cement, steel, aggregate, and finishing materials at program scale across the national capital region.
Saudi Arabia Building Materials Market Overview
The Saudi Arabia building materials market encompasses the production, import, distribution, and sale of all construction material categories including cement, aggregates (sand, gravel, crushed stone), bricks and masonry units, structural steel, glass, insulation, cladding, roofing, flooring, plumbing and HVAC materials, and specialty construction products. The market serves residential, commercial, and industrial construction applications across all four major geographic regions, with giga-project procurement representing the most prominent single demand category in recent years.
Saudi Arabia building materials market is structurally unique in the global context because of its simultaneous exposure to the largest concentration of concurrent mega-projects, a government-backed residential housing program operating at national scale, and an emerging sustainability agenda requiring green building materials including carbon-negative concrete and low-embodied-carbon alternatives.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
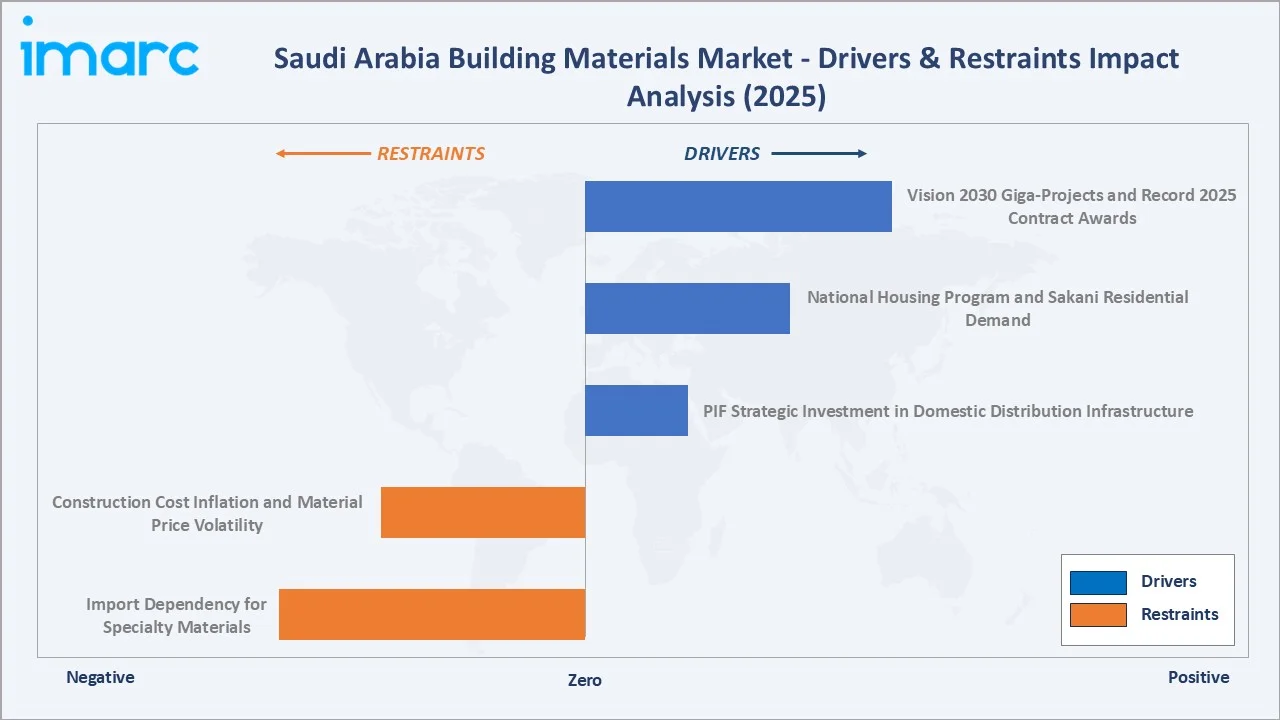
- Vision 2030 Giga-Projects and Record 2025 Contract Awards: Saudi Arabia’s giga-projects drove a 20% increase in contract awards to $196 billion in 2025, with transportation, commercial, residential, and industrial construction collectively representing the largest categories. This extraordinary demand concentration positions Saudi Arabia as the primary driver of global building materials supply chain capacity planning for cement, steel, and aggregate producers.
- National Housing Program and Sakani Residential Demand: Saudi Arabia’s Housing Program has increased homeownership from 47% in 2016 to over 65.4%, surpassing the 2025 target and accelerating housing-sector development; it is building multiple large-scale fully modular residential communities, and the Sakani affordable housing initiative continues generating sustained residential construction activity requiring consistent building materials supply.
- PIF Strategic Investment in Domestic Distribution Infrastructure: PIF acquisition of a 30% stake in Masdar for Building Materials Company in February 2025 signals strategic government intent to reinforce domestic building materials supply chains, develop the national distribution network, and accelerate digital transformation across the construction materials sector.
Market Restraints
- Construction Cost Inflation and Material Price Volatility: Construction cost inflation raises the prices of key materials such as cement, steel, aluminum, and concrete, increasing overall project costs. Material price volatility makes budgeting and cost forecasting more difficult for contractors and developers. Higher input costs can reduce profit margins, delay projects, and increase final construction prices. This may also discourage smaller developers and slow the pace of new construction activity.
- Import Dependency for Specialty Materials: Despite Saudi Arabia significant domestic cement and steel production capacity, advanced building materials including high-performance glass, specialty insulation, architectural cladding systems, advanced roofing membranes, and precision-engineered components for giga-project applications are predominantly imported from Europe, North America, and Asia. This import dependency creates supply chain risk, longer procurement lead times, and currency exposure.
Market Opportunities
- Carbon-Negative and Green Building Materials: Saudi Arabia recorded the highest regional score of 76.31 points, while certifying over 1.03 million sq. meters of sustainable building space, creating a first-mover market for green concrete alternatives as Saudi Arabia Green Initiative commitments progressively incentivize low-carbon construction. The Saudi cement industry transition toward green cement technologies represents both a regulatory compliance requirement and a premium product market development opportunity as sustainability credentials become procurement decision criteria.
- Digital Transformation of Building Materials Supply Chains: PIF investment in Masdar specifically prioritizes accelerating digital transformation through adoption of the latest technologies and solutions across the building materials distribution network. Digital procurement platforms, BIM-integrated materials scheduling, IoT-enabled inventory management at construction sites, and e-commerce building materials marketplaces are progressively reducing friction in construction materials supply chains, improving delivery precision, and enabling data-driven procurement decisions that reduce wastage and optimize delivery timing at complex multi-phase giga-project sites.
Market Challenges
- Giga-Project Restructuring and Demand Volatility: The ongoing restructuring of NEOM scope creates material demand volatility for cement and steel producers who have built or contracted production capacity based on peak giga-project demand projections. Domestic producers must manage the risk of over-capacity in specific material categories if giga-project programs are modified or phased more conservatively than originally planned.
- Saudization and Local Content Compliance Requirements: Saudi Arabia National Transformation Program Saudization requirements and local content regulations mandate increasing percentages of Saudi-sourced labor and materials across construction projects. For building materials specifically, this creates pressure on international specialty material importers to establish Saudi manufacturing or distribution partnerships while simultaneously creating market opportunity for domestic producers and distributors, including Masdar, that can credibly supply locally produced or locally warehoused materials meeting SASO quality standards.
Emerging Market Trends
1. Integrated Construction Material Supply
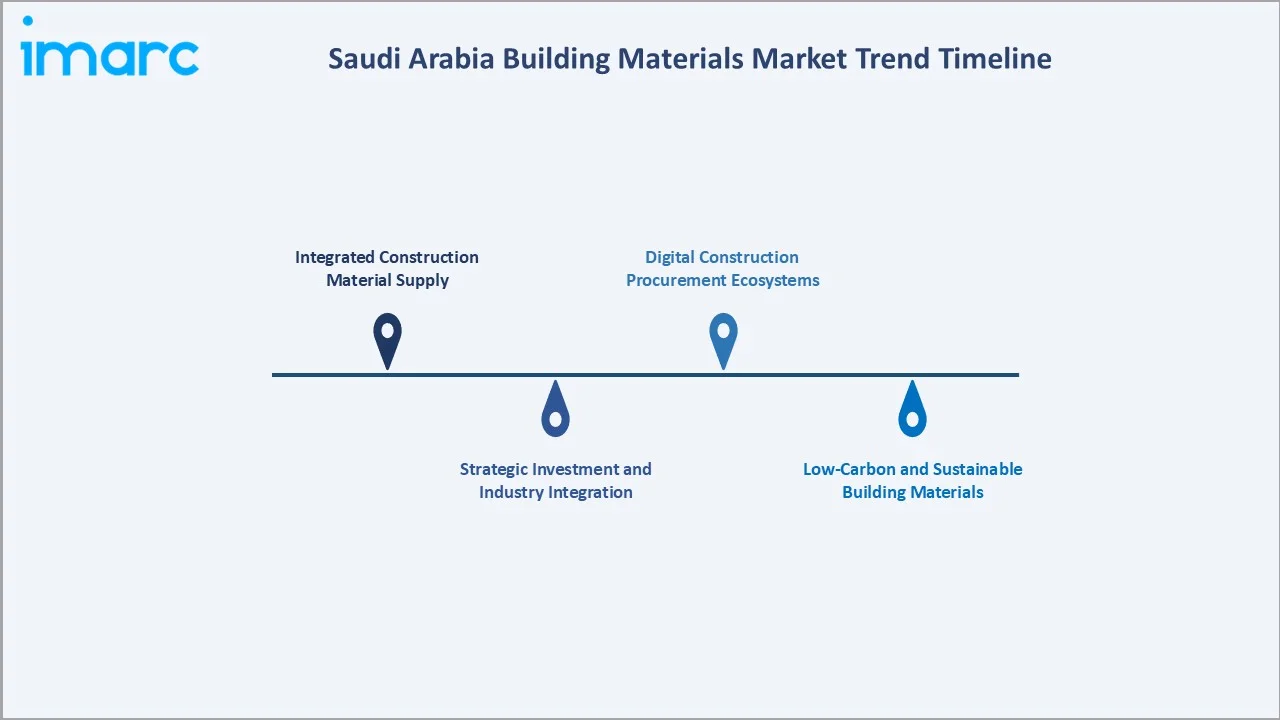
In August 2026, Masdar opened a fully integrated construction and building materials facility in Madinah, strengthening its presence in Saudi Arabia. The facility supplies a broad range of steel, timber, insulation, plumbing, electrical products, hardware, chemicals, and fasteners to various industries. The launch reflects a growing trend toward integrated, one-stop building material supply solutions in Saudi Arabia. Expanding facilities improve the availability of diverse materials and support faster project execution. This trend is driven by rising demand from large-scale infrastructure, residential, and giga-project developments.
2. Strategic Investment and Industry Integration
In September 2026, Saudi-based platform Fitting secured $1.1 million in its second Seed funding round, backed by a strategic investor from the construction materials, contracting, and real estate sectors, supporting its next stage of growth. The funding highlights growing strategic investment in Saudi Arabia’s building materials and construction ecosystem, particularly from established industry players. This trend indicates increasing collaboration between material suppliers, contractors, and real estate developers to strengthen market capabilities.
3. Digital Construction Procurement Ecosystems
In September 2026, Elm and ROSHN Group partnered to launch ANMA, an integrated B2B digital platform for construction procurement in Saudi Arabia. The platform will connect developers, contractors, manufacturers, and suppliers, improving procurement efficiency and strengthening supply-chain integration across the construction sector. The launch highlights the growing shift toward digital procurement platforms in Saudi Arabia’s building materials market. B2B marketplaces are connecting developers, contractors, manufacturers, and suppliers through a unified procurement ecosystem.
4. Low-Carbon and Sustainable Building Materials
In January 2025, Saudi Arabia launched the NovusCrete Consortium, an initiative focused on advancing sustainable concrete production and reducing carbon emissions in the construction sector. The program aims to drive innovation and support the adoption of lower-carbon building materials. This highlights the growing shift toward low-carbon concrete and sustainable construction materials in Saudi Arabia. Industry players are increasingly investing in technologies that reduce the carbon footprint of cement and concrete production.
Industry Value Chain Analysis
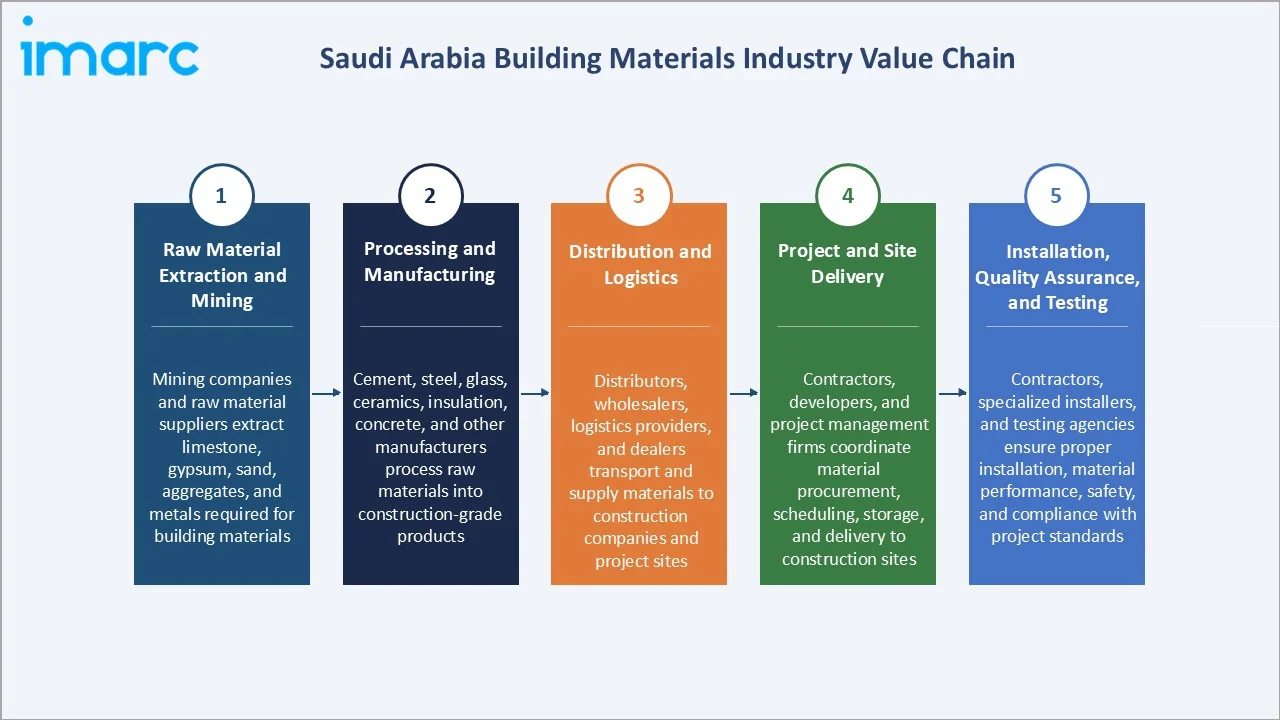
The Saudi Arabia building materials value chain spans five integrated stages from raw material extraction through installation and quality assurance. The processing and manufacturing stage captures the highest value addition, transforming commodity limestone, silica, iron ore, and aggregate minerals into precision-specified cement, steel, glass, and prefabricated components whose technical performance characteristics directly determine structural safety and building longevity.
|
Stage |
Key Participants |
|
Raw Material Extraction and Mining |
Mining companies and raw material suppliers extract limestone, gypsum, sand, aggregates, and metals required for building materials. |
|
Processing and Manufacturing |
Cement, steel, glass, ceramics, insulation, concrete, and other manufacturers process raw materials into construction-grade products. |
|
Distribution and Logistics |
Distributors, wholesalers, logistics providers, and dealers transport and supply materials to construction companies and project sites. |
|
Project and Site Delivery |
Contractors, developers, and project management firms coordinate material procurement, scheduling, storage, and delivery to construction sites. |
|
Installation, Quality Assurance, and Testing |
Contractors, specialized installers, and testing agencies ensure proper installation, material performance, safety, and compliance with project standards. |
The distribution and logistics stage is strategically critical in Saudi Arabia building materials value chain, given the kingdom's geographic scale spanning the concentration of major construction programs in geographically dispersed locations, including NEOM in the northwest, Red Sea Global on the western coast, and Eastern Region industrial programs.
Technology Landscape in the Saudi Arabia Building Materials Industry
3D Printing and Additive Construction Technology
Saudi Arabia giga-projects are pioneering construction-scale 3D printing technology, with the Saudi government actively promoting 3D printing as a focus domain for giga-project construction innovation. Additive construction, using large-format concrete 3D printers to produce structural walls, façades, and components directly from digital models, reduces formwork requirements, minimizes concrete waste, and enables complex geometric forms impossible with conventional casting.
Carbon-Negative and Supplementary Cementitious Materials
Carbon-negative materials aim to reduce or offset more carbon emissions than are generated during their production, supporting low-carbon construction. Supplementary cementitious materials such as fly ash, slag, and natural pozzolans can partially replace conventional cement and lower emissions. Their adoption is increasing as the construction industry seeks more sustainable, cost-efficient, and environmentally friendly building solutions.
BIM-Integrated Materials Management and Digital Procurement
BIM integration enables construction teams to digitally plan, track, and manage material requirements throughout a project lifecycle. Digital procurement platforms streamline supplier selection, ordering, inventory tracking, and delivery coordination. This improves cost control, material availability, transparency, and project efficiency while reducing delays and material waste.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Type |
Cement |
36.8% |
2025 |
|
Application |
Residential |
43.6% |
2025 |
|
Region |
Northern and Central Region |
38.5% |
2025 |

By Type
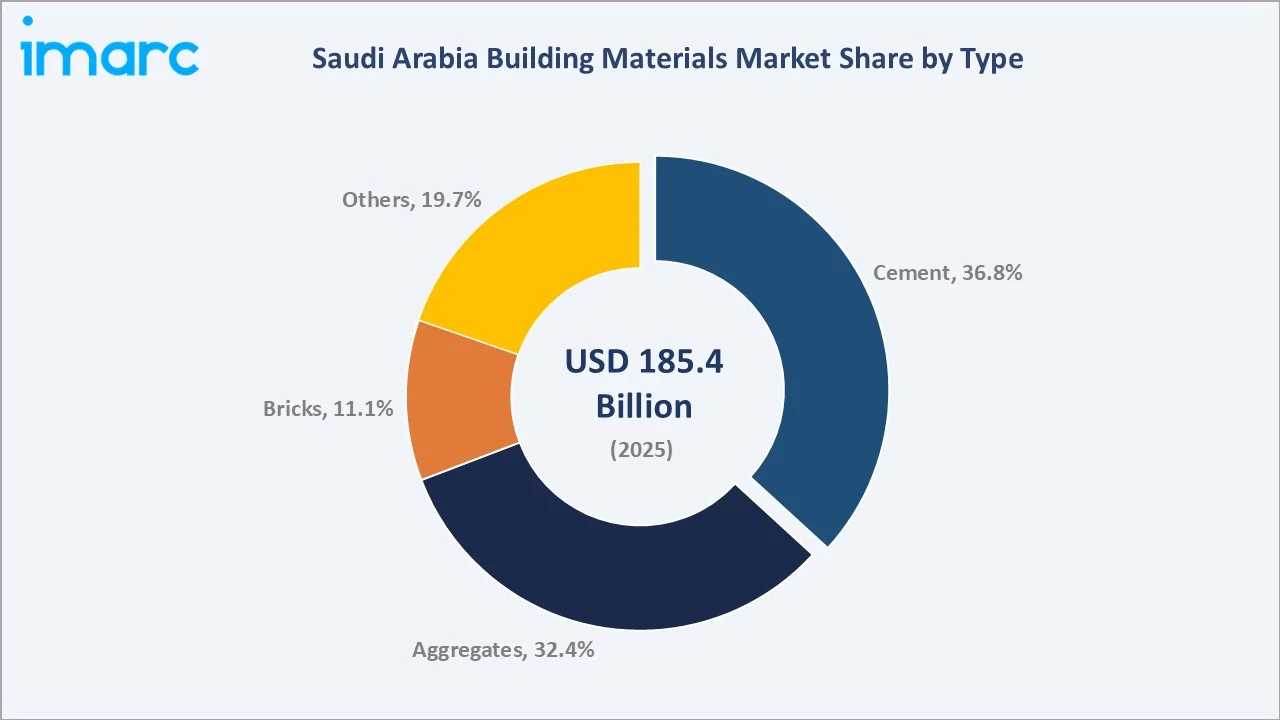
Cement leads at 36.8% in 2025, reflecting its foundational role in all construction applications. Saudi Arabia maintains one of the top cement production capacities, with domestic demand and giga-project programs including NEOM creating extraordinary ongoing demand.
To access detailed market analysis, Request Sample
Aggregates at 32.4% are the volumetrically largest building material category, representing the sand, gravel, and crushed stone that constitute the majority of concrete by weight and road base construction by volume. Bricks at 11.1% serve masonry partition walls and façade applications, while others at 19.7% encompass structural steel, glass, insulation, cladding, roofing, plumbing, electrical conduit, and specialty finishing materials whose individual segments are growing faster than commodity materials as construction quality standards rise.
By Application
Residential leads at 43.6% in 2025, driven by the National Housing Program, Roshn and PIF-backed large-scale residential community developments, the Sakani affordable housing initiative, and organic population-driven housing demand.
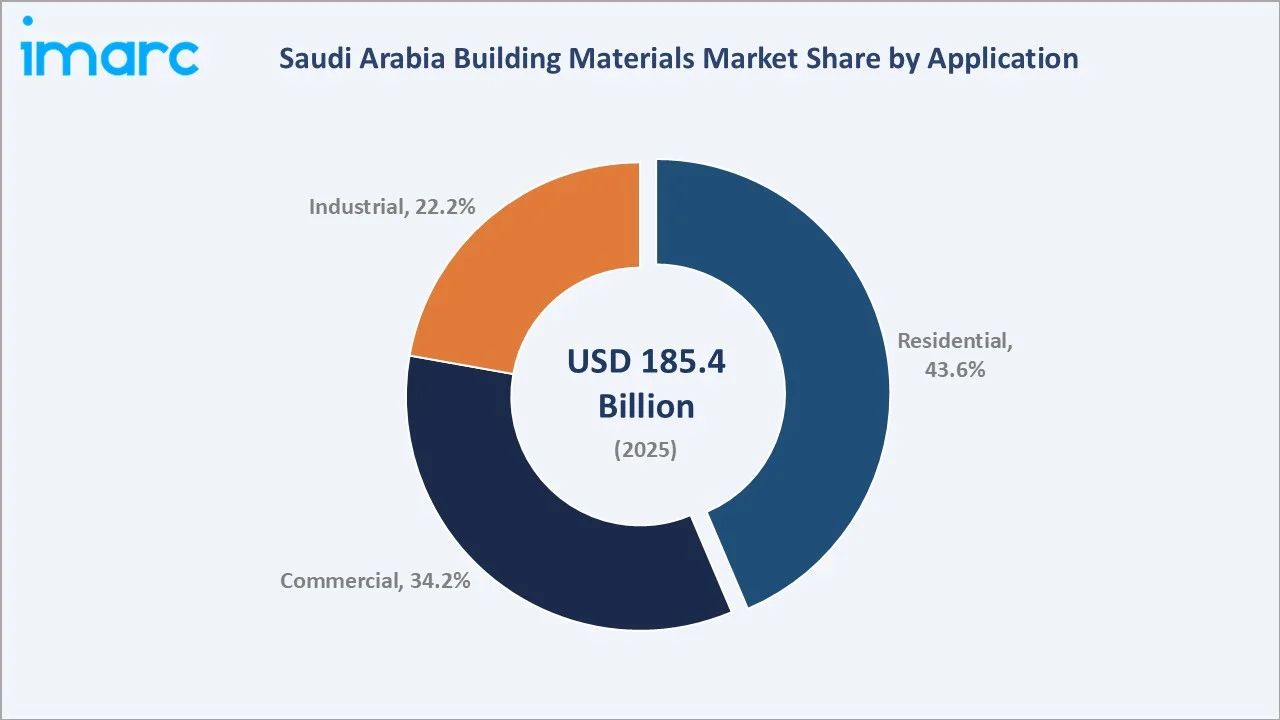
Commercial at 34.2% encompasses office buildings, retail centers, hotels, entertainment venues, educational facilities, and healthcare buildings across Saudi Arabia Vision 2030 entertainment, tourism, and knowledge economy programs. Industrial at 22.2% serves manufacturing facility construction, logistics warehousing, data center development, energy sector infrastructure, and petrochemical facility expansions.
Regional Market Insights
|
Region |
Share (2025) |
Key Saudi Arabia Building Materials Market Drivers & Characteristics |
|
Northern and Central Region |
38.5% |
Largest regional market, supported by major urban development, government infrastructure programs, and large-scale construction projects. |
|
Western Region |
30.7% |
Strong demand driven by residential, commercial, tourism, hospitality, and large development projects in key cities. |
|
Eastern Region |
19.4% |
Supported by industrial, energy, logistics, and commercial construction activity, creating steady demand for building materials. |
|
Southern Region |
11.4% |
Emerging market supported by infrastructure expansion, residential development, and regional urbanization initiatives. |
Saudi Arabia’s building materials market is led by the Northern and Central region, accounting for 38.5%, supported by major urban and infrastructure development. The Western region represents 30.7%, driven by residential, commercial, tourism, and hospitality projects.
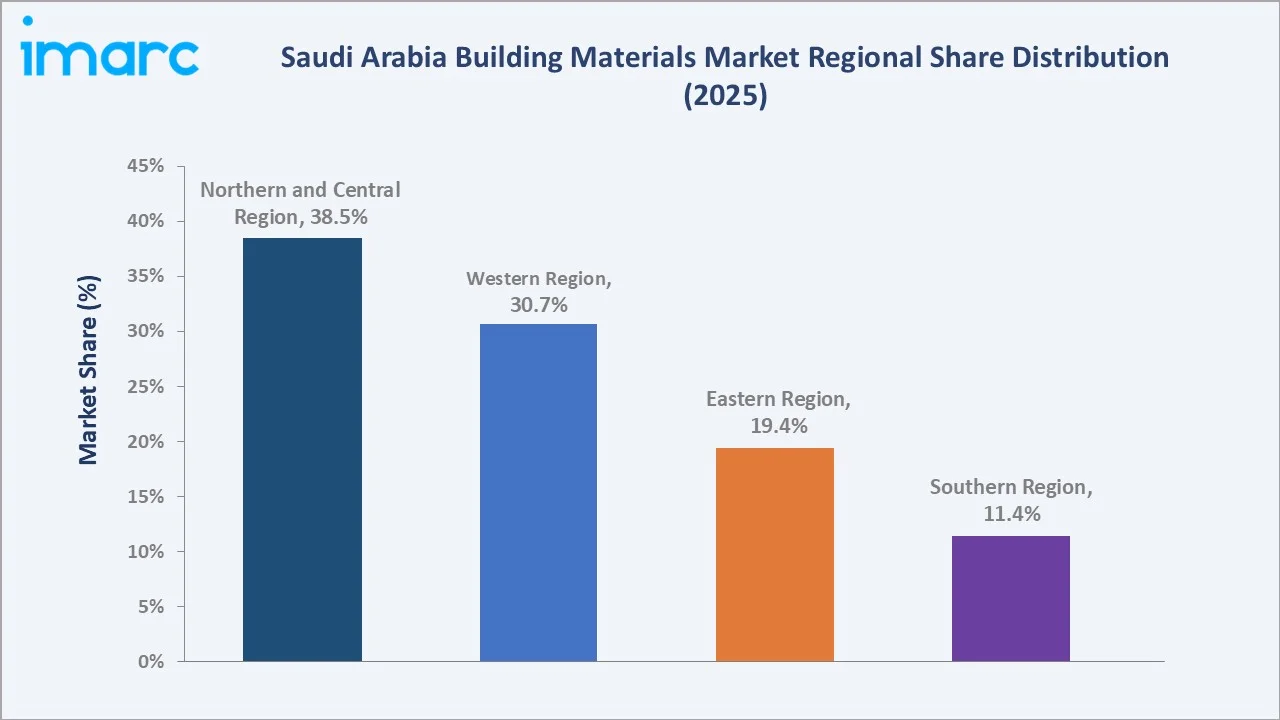
The Eastern region holds 19.4%, supported by industrial, energy, logistics, and commercial construction activity. The Southern region accounts for 11.4%, with demand supported by infrastructure and residential development.
Competitive Landscape
The Saudi Arabia building materials market competitive landscape features domestic cement producers as the primary cement supply tier alongside key structural materials producers. International brands provide technical expertise and specialty cement products, while quality standards and local content requirements create competitive barriers that favor established domestic producers.
|
Company |
Key Offerings |
Market Position |
Core Strength |
|
Saudi Cement |
Cement Clinker, Sulfate Resistant Cement (SRC, Type V), Ordinary Portland Cement (OPC, Type I) |
Market Leader |
Saudi Cement Company (Saudi Cement) is a foundational pioneer and a market leader in efficiency, quality, and profitability within Saudi Arabia’s heavy building materials sector. |
|
Masdar |
Wooden Sheets, Rebars, Insulation, Aggregates |
Market Leader |
Masdar Building Materials plays a leading role as Saudi Arabia's premier one-stop distributor and supplier of construction and building products. |
|
Zamil Group Holding Company |
Silicone sealants, Locks and hinges for aluminum doors, Packaging tape |
Established Player |
Zamil Group Holding Company plays a foundational and leading role in Saudi Arabia's building materials, construction, and heavy industrial sectors. |
|
HOLCIM |
ECOPlanet low-carbon cement, Aggneo aggregates, ECOPact low-carbon concrete, DYNAMax ultimate high-performance concrete |
Established Player |
Holcim operates as a key global and regional participant in the building materials sector, though its direct physical manufacturing footprint in Saudi Arabia is complemented largely through regional trade, global standards, and market recognition. |
|
Al Jouf Cement Company |
Ordinary Portland Cement, Sulphate Resistant Cement, Pozzolana Portland Cement |
Challenger |
Al Jouf Cement Company plays a vital role in Saudi Arabia's building materials and construction sector, particularly in the northern regions and mega-development projects. |
The competitive landscape is being reshaped by the PIF Masdar investment establishing a distribution champion at national scale, and by the escalating sustainability requirements of the Saudi Arabia Green Building Code progressively favoring producers with certified green cement products.
Key Company Profiles
Saudi Cement
Saudi Cement Company is a leading Saudi cement producer serving the Kingdom’s construction and infrastructure sectors. The company manufactures and supplies cement and related products for residential, commercial, and large-scale infrastructure projects. It benefits from established production capabilities, distribution networks, and access to key construction markets. Saudi Cement focuses on operational efficiency, product quality, sustainability, and meeting growing domestic construction demand.
- Key Offerings: Cement Clinker, Sulfate Resistant Cement (SRC, Type V), Ordinary Portland Cement (OPC, Type I).
- Strategic Focus: Expanding production efficiency, maintaining high product quality, and strengthening its supply capabilities to meet rising construction demand. The company also emphasizes sustainability, operational optimization, and supporting Saudi Arabia’s infrastructure and Vision 2030 development projects.
Al Jouf Cement Company
Al Jouf Cement Company is a Saudi cement manufacturer supplying products to the Kingdom’s construction and infrastructure sectors. The company operates cement production facilities serving residential, commercial, and infrastructure projects. Its regional presence supports demand across northern Saudi Arabia and other domestic markets. Al Jouf Cement focuses on production efficiency, product quality, distribution capabilities, and sustainable manufacturing practices to strengthen its market position.
- Key Offerings: Ordinary Portland Cement, Sulphate Resistant Cement, Pozzolana Portland Cement.
- Strategic Focus: Improving production efficiency, optimizing costs, and strengthening distribution capabilities to serve Saudi Arabia’s growing construction demand. The company also aims to support infrastructure and housing development while enhancing product quality and operational sustainability.
Market Concentration Analysis
The Saudi Arabia building materials market is moderately concentrated, with domestic cement producers collectively dominating the largest single material segment, while the structural steel rebar market is dominated by integrated petrochemical feedstock advantage. Masdar investment is progressively centralizing distribution market share around a single national network champion rather than the fragmented regional distributor landscape that previously characterized Saudi building materials trading.
Advanced and specialty building materials segments are considerably more fragmented, with international brands and specialty material importers competing alongside domestic producers for technically demanding project specifications. Market concentration is expected to increase modestly at the distribution tier as PIF investment enables aggressive branch network expansion and digital platform development.
Investment & Growth Opportunities
Highest Growth Segments
Cement is growing at a 1.4% CAGR, where domestic demand and giga-project demand continue to sustain throughput. Residential application at 1.35% CAGR.
Investment Themes
- Domestic Manufacturing of Specialty Building Materials: Investment in Saudi Arabia-based manufacturing of specialty insulation, architectural glazing, high-performance cladding, and advanced concrete admixtures reduces import dependency, provides local content compliance, and captures the advanced materials market growth within a domestic production framework.
- Digital Distribution Platform Development: Investment in BIM-integrated digital procurement platforms for building materials distribution enables data-driven procurement decision support for construction contractors, improving supply chain efficiency, reducing materials waste, and capturing the value-added services revenue stream.
Future Market Outlook (2026-2034)
The Saudi Arabia building materials market stood at USD 185.4 Billion in 2025 and is projected to grow from USD 187.7 Billion in 2026 to USD 207.0 Billion by 2034, exhibiting a CAGR of 1.24% during 2026-2034. The market is expected to reach an intermediate milestone of approximately USD 197.1 Billion by 2030, as Expo 2030 Riyadh venue construction reaches completion, NEOM Phase I structural construction produces peak materials consumption, and the stadium and hospitality infrastructure construction begins generating building materials procurement at program scale in the Northern and Central Region.
Three structural forces will define Saudi Arabia building materials market through 2034. First, the sustained capital allocation from Vision 2030 and its successor programs creates a policy-guaranteed floor under building materials demand that insulates the market from cyclical economic headwinds. Second, the PIF strategic investment in building materials supply chain infrastructure signals sustained sovereign wealth fund commitment to developing the domestic building materials industry as a permanent competitive advantage for Saudi Arabia construction sector, rather than relying on material imports for complex and high-value applications. Third, the sustainability transformation of Saudi Arabia building materials procurement will progressively shift material specifications toward certified low-carbon and green products, creating a premium market tier.
Research Methodology
Primary Research
Primary research comprised structured consultations with cement company commercial directors and production managers, building materials distributor executives, including management team discussions, construction contractor procurement specialists, Saudi Arabia Ministry of Municipal, Rural Affairs and Housing advisors, quality certification officers, and PIF investment team members in the construction and building materials sector. These discussions validated market sizing, assessed giga-project demand impact on cement and aggregate supply dynamics, identified sustainability transition timelines, and provided competitive intelligence on distributor market share and brand positioning across Saudi Arabia regions.
Secondary Research
Secondary research drew on IMARC Group Saudi Arabia building materials and cement market databases, PIF press release announcements, global steel consumption and NEOM cement contract, Saudi Arabia building materials sector analysis, Saudi Arabia advanced building materials market analysis, and company financial filings and press releases.
Forecasting Models
Market forecasts incorporated Vision 2030 capital expenditure program phasing with Expo 2030 Riyadh and FIFA 2034 milestone construction timelines, NEOM construction phase demand modeling for cement and steel, residential sector demand projections from National Housing Program and population growth models, commercial and industrial construction GDP-linked demand projections, green building materials penetration rate modeling under Saudi Green Building Code evolution, and macroeconomic indicators including Saudi Arabia non-oil GDP growth and construction sector investment trajectory through 2034.
Saudi Arabia building materials Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Aggregates, Cement, Bricks, Others |
| Applications Covered | Residential, Commercial, Industrial |
| Regions Covered | Northern and Central Region, Western Region, Eastern Region, Southern Region |
| Companies Covered | Saudi Cement, Masdar, Zamil Group Holding Company, HOLCIM, Al Jouf Cement Company, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Saudi Arabia building materials market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Saudi Arabia building materials market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Saudi Arabia building materials industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Saudi Arabia Building Materials Market Report
The Saudi Arabia building materials market reached USD 187.7 Billion in 2026, driven by PIF acquiring a 30% stake in Masdar for Building Materials to reinforce domestic supply chains, and sustained residential construction demand from the National Housing Program.
The market is projected to grow at a CAGR of 1.24% during 2026-2034, reflecting a large and mature market base where steady Vision 2030 capital deployment sustains demand growth alongside sustainability-driven material specification evolution and the Expo 2030 Riyadh and FIFA 2034 event infrastructure programs.
The market is projected to reach approximately USD 197.1 Billion by 2030, as Expo 2030 Riyadh venue construction reaches completion, NEOM Phase I peak construction activity sustains materials demand, and FIFA 2034 stadium infrastructure construction begins generating incremental building materials procurement.
Cement leads with a 36.8% share in 2025, reflecting Saudi Arabia position as one of the top countries in cement production capacity, domestic demand, and giga-project programs, including NEOM, generating specific long-term cement supply contracts.
Residential leads with a 43.6% share in 2025, driven by the National Housing Program to access homeownership, PIF-backed residential communities generating consistent large-scale construction activity, and organic Saudi population growth sustaining baseline housing demand.
The Northern and Central region leads with a 38.5% share in 2025, anchored by Riyadh concentration of Vision 2030 administrative programs, Riyadh venue infrastructure, PIF residential programs, and FIFA 2034 World Cup stadium construction creating the highest density of concurrent construction programs in the kingdom.
Key players include Saudi Cement, Masdar, Zamil Group Holding Company, HOLCIM, and Al Jouf Cement Company, among others.
The market is projected to reach USD 207.0 Billion by 2034, driven by sustained Vision 2030 capital deployment, progressive green building materials adoption under Saudi Green Initiative requirements, PIF distribution network expansion, and advanced building materials growth.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade