Saudi Arabia Construction Equipment Market Size, Share, Trends and Forecast by Solution Type, Equipment Type, Type, Application, Industry, and Region, 2026-2034
Saudi Arabia Construction Equipment Market Size, Share, Trends & Forecast (2026-2034)
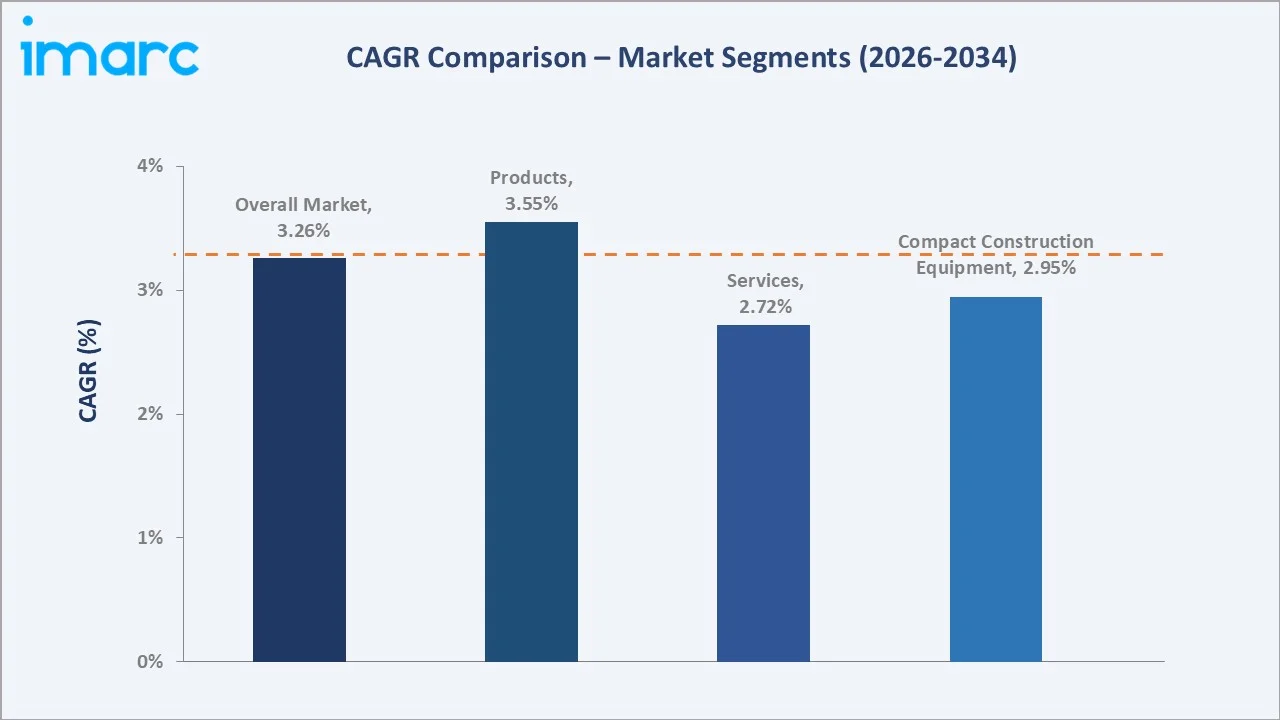
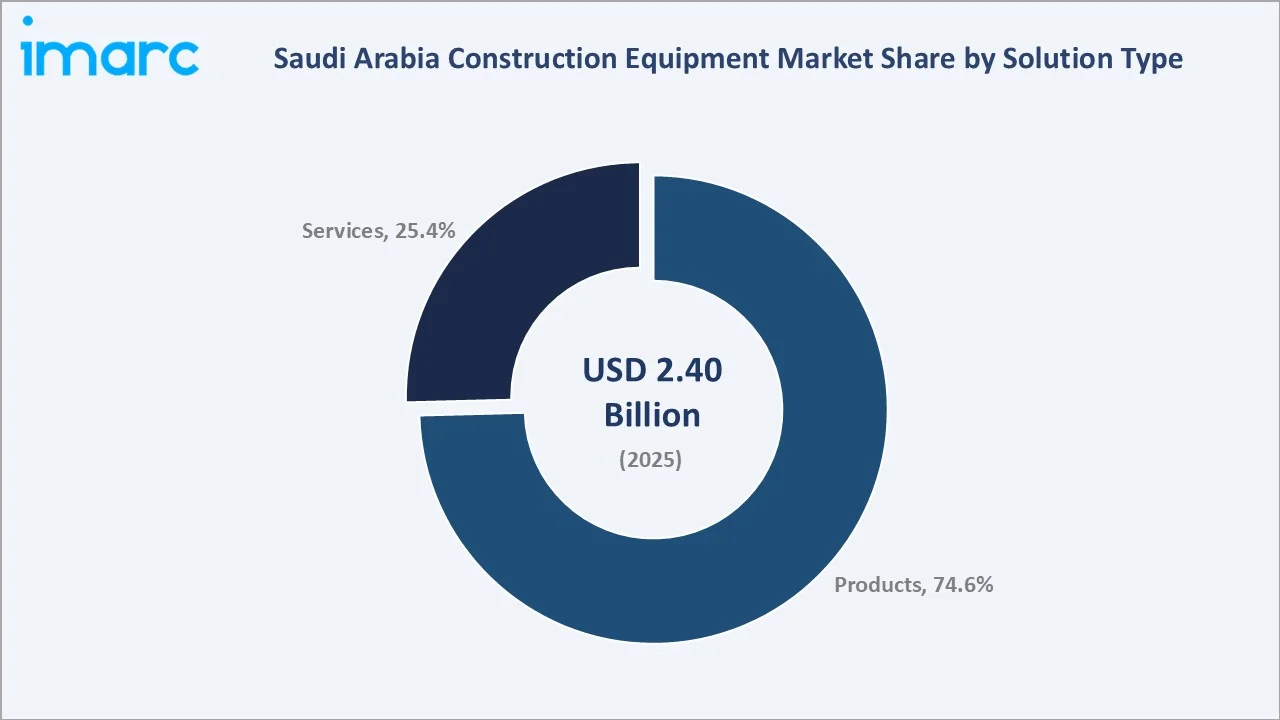
The Saudi Arabia construction equipment market grew from USD 2.40 Billion in 2025 to USD 2.47 Billion in 2026 and is projected to reach USD 3.20 Billion by 2034, growing at a CAGR of 3.26% during 2026-2034. The market is driven by Vision 2030 giga-project investments, government housing programs, and port expansion. Products lead at 74.6%. Heavy Construction Equipment dominates at 68.3%. Northern & Central Region commands 43.8% of national market share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 2.40 Billion |
|
Market Size (2026) |
USD 2.47 Billion |
|
Forecast Market Size (2034) |
USD 3.20 Billion |
|
CAGR (2026-2034) |
3.26% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Solution Type |
Products (74.6%, 2025) |
|
Dominant Equipment Type |
Heavy Construction Equipment (68.3%, 2025) |
|
Leading Region |
Northern & Central Region (43.8%, 2025) |
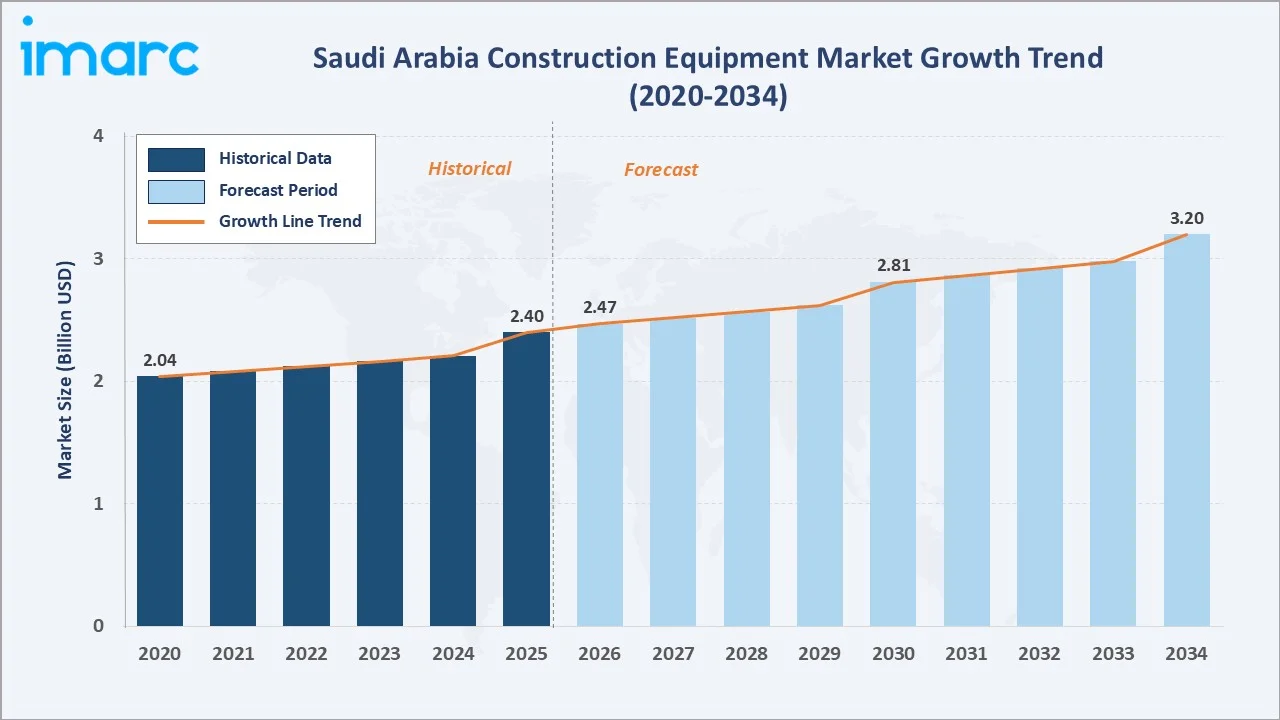
The Saudi Arabia construction equipment market size increased from USD 2.04 Billion in 2020 to USD 2.40 Billion in 2025 and is estimated to reach USD 2.47 Billion in 2026. The market is further expected to grow to USD 2.81 Billion by 2030 and USD 3.20 Billion by 2034. The market's commercial significance is underpinned by the Kingdom's trillion-dollar infrastructure pipeline, the largest in the region.
To get more information on this market, Request Sample
The Products segment commands the dominant share through direct equipment procurement by contractors and project developers. Heavy Construction Equipment leads at 68.3% through its critical role in excavation, earthmoving, and large-scale infrastructure development. Vision 2030 infrastructure pipeline continues to attract major global OEMs to expand Saudi operations and service networks.
Executive Summary
The Saudi Arabia construction equipment market expanded from USD 2.40 Billion in 2025 to an estimated USD 2.47 Billion in 2026, positioning it among the leading construction equipment markets in the GCC. Market growth is driven by unprecedented infrastructure investment under Vision 2030, residential construction expansion, and port modernization. The market is projected to reach USD 3.20 Billion by 2034. Products at 74.6% lead through direct procurement. Heavy Construction Equipment at 68.3% reflects large-scale project demand. Northern & Central Region leads at 43.8%.
Key Market Insights
|
Insight |
Data |
|
Dominant Solution Type |
Products – 74.6% share (2025) |
|
Dominant Equipment Type |
Heavy Construction Equipment – 68.3% market share (2025) |
|
Leading Region |
Northern & Central Region – 43.8% share (2025) |
|
Market Opportunity |
Vision 2030 giga-project pipeline; housing program expansion; port & logistics infrastructure; digital construction technology adoption |
Key Analytical Observations Supporting the Above Data:
- Products at 74.6%: The products segment dominates due to large-scale direct equipment purchases by contractors involved in Vision 2030 giga-projects. Procurement of excavators, cranes, loaders, and dozers for NEOM, Qiddiya, and Red Sea Project sites drives sustained high-volume product sales.
- Heavy Construction Equipment at 68.3%: Heavy construction equipment leads due to the massive earthmoving, excavation, and material handling requirements of Saudi Arabia's mega-infrastructure projects. The scale of giga-project site preparation and urban development demands large-capacity machinery across all project phases.
- Northern & Central Region at 43.8%: The Northern & Central Region dominates as Riyadh hosts NEOM's administrative infrastructure, the King Salman International Airport project, and the highest concentration of government capital expenditure across urban, transport, and institutional construction projects.
Saudi Arabia Construction Equipment Market Overview
Saudi Arabia construction equipment market is positioned at the intersection of the region's largest government infrastructure spending program and one of the world's most ambitious economic transformation agendas. Vision 2030's trillion-dollar project pipeline creates multi-year structural demand for excavators, cranes, loaders, and specialized construction machinery.
Saudi Arabia's construction equipment ecosystem integrates global OEM imports, local distributor networks, equipment rental operators, and government-aligned procurement channels. Macroeconomic factors include Vision 2030 capital deployment, oil revenue reinvestment into infrastructure, rising non-oil GDP diversification, and expanding private sector construction activity.
Market Dynamics
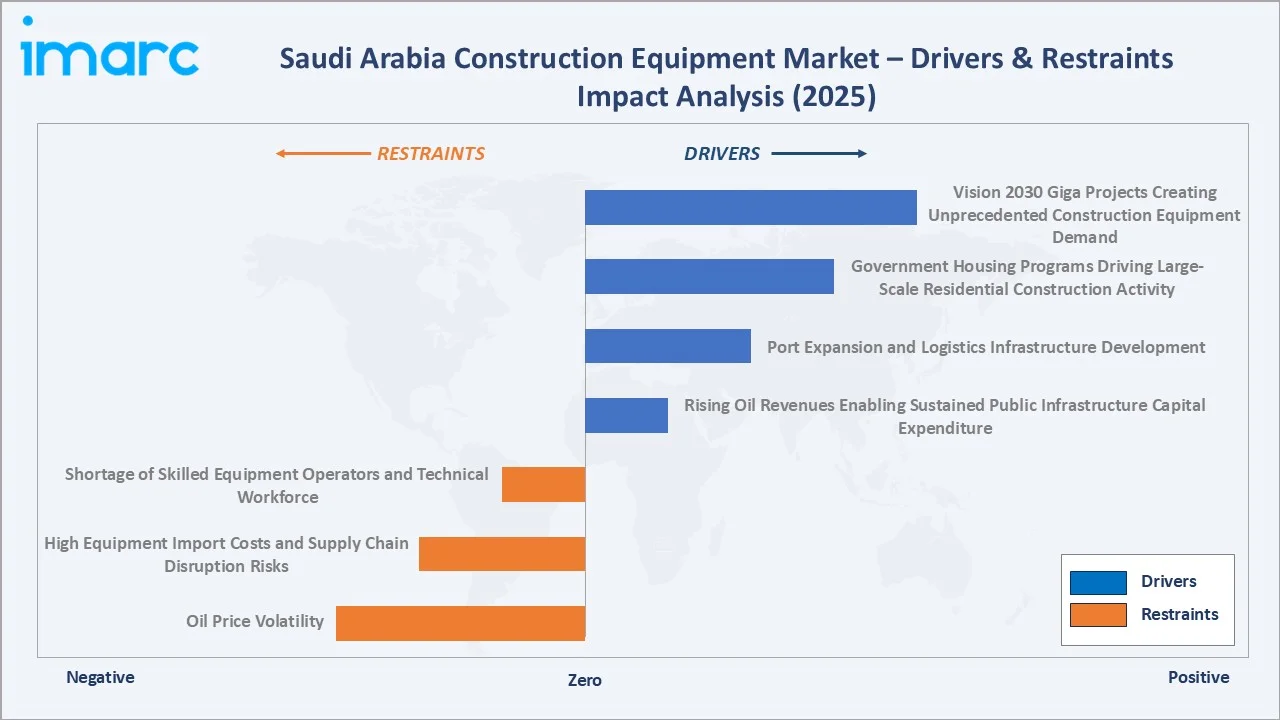
To evaluate market opportunities, Request Sample
Market Drivers
- Vision 2030 Giga Projects Creating Unprecedented Construction Equipment Demand: Saudi Arabia's Vision 2030 program includes NEOM, Qiddiya, Red Sea Project, and Diriyah—collectively representing one of the world's largest infrastructure investment pipelines. NEOM alone employs over 140,000 workers and requires massive earthmoving, crane, and material handling equipment. The King Salman International Airport project in Riyadh, targeting 120 million passenger annual capacity, requires extensive civil construction machinery. These giga-projects collectively sustain multi-year forward order books for global OEMs operating in the Kingdom.
- Government Housing Programs Driving Large-Scale Residential Construction Activity: Saudi Arabia's Housing Program targets 70% homeownership by 2030, requiring construction of over 115,000 additional residences annually. The Sakani program has signed nearly 800,000 contracts for ready-made homes, self-construction projects, and off-plan units. The young demographic—45% of Saudi citizens under 20—creates persistent structural housing demand. This residential construction boom drives demand for excavators, loaders, bulldozers, and concrete equipment across all four regions. The housing sector has become the market's second-largest demand driver after mega-infrastructure projects.
- Port Expansion and Logistics Infrastructure Development: Saudi Arabia's ambition to strengthen its position as a regional logistics hub is driving investments in port expansion, logistics parks, warehouses, and freight infrastructure. The development and modernization of these facilities are increasing demand for material handling equipment such as forklifts, reach stackers, cranes, and automated handling systems. Growing container volumes and the adoption of efficient, technology-enabled logistics operations are expected to sustain equipment procurement over the forecast period.
- Rising Oil Revenues Enabling Sustained Public Infrastructure Capital Expenditure: Continued government spending on transportation, construction, urban development, and industrial infrastructure under Vision 2030 is supporting demand for construction and material handling equipment. Investments in large-scale infrastructure projects, economic diversification initiatives, and logistics development are creating a steady pipeline of equipment requirements. Expanding non-oil economic activity is also helping strengthen overall construction and industrial demand, providing equipment suppliers with greater long-term market opportunities.
Market Restraints
- Oil Price Volatility: Oil price fluctuations remain the primary risk to Saudi Arabia's government capital expenditure plans, given that oil revenues represent over 50% of government income. A sustained oil price decline can trigger construction budget revisions, project delays, or phasing changes that reduce near-term equipment demand. While Vision 2030 aims to reduce oil dependency, the construction market remains indirectly linked to sovereign oil revenues. Project developers and equipment suppliers experience demand uncertainty during periods of energy price volatility, affecting procurement planning and inventory management.
- High Equipment Import Costs and Supply Chain Disruption Risks: Saudi Arabia imports the majority of its construction equipment from global OEMs in North America, Europe, Japan, and China, creating currency exchange risk and logistics cost exposure. Global supply chain disruptions—affecting semiconductor availability for advanced equipment controls—can delay deliveries and inflate costs for Saudi project developers. High import duties on certain equipment categories increase total cost of ownership, creating pricing pressure on project budgets. These supply chain complexities favor established OEMs with strong local warehousing and service parts inventory.
- Shortage of Skilled Equipment Operators and Technical Workforce: Saudi Arabia faces a structural deficit of certified heavy equipment operators and qualified technical maintenance personnel for advanced construction machinery. The Kingdom's Saudization targets create recruitment challenges for equipment operators, historically sourced from South Asia and Southeast Asia. Skilled operator shortages increase project completion timelines and add operational cost pressure. OEMs are investing in operator training centers—XCMG opened a training center in Dammam—but workforce gap closure requires sustained multi-year investment.
Market Opportunities
- Electric and Hybrid Construction Equipment Adoption Aligned with Vision 2030 Sustainability Goals: Saudi Arabia's Vision 2030 sustainability agenda creates demand for electric and hybrid construction equipment as project owners increasingly mandate lower-carbon construction practices. Global OEMs are developing electric excavators, loaders, and handling equipment specifically for Middle East operating conditions. Saudi project developers can reduce fuel costs through electrified equipment adoption. The Kingdom's renewable energy expansion plans provide the low-carbon power infrastructure necessary to support large-scale electric equipment charging infrastructure at project sites.
- Digital Construction Technology Integration Creating Demand for Smart Equipment: AI-powered equipment monitoring, GPS-guided machine control, and IoT-enabled fleet management are becoming standard requirements for large Saudi projects. Smart construction equipment improves productivity, reduces fuel consumption, and enables remote monitoring of equipment deployed across geographically dispersed giga-project sites. OEMs offering integrated digital construction solutions can command premium pricing and longer-term service contracts. Saudi project developers investing in BIM-aligned construction methodologies create growing demand for precision-guided equipment.
Market Challenges
- Extreme Climate Conditions Increasing Equipment Maintenance Costs and Operational Downtime: Saudi Arabia's extreme heat—summer temperatures regularly exceed 45°C—accelerates equipment wear, increases cooling system maintenance requirements, and reduces daily productive operating hours. Sandstorm events damage air filtration systems, hydraulic components, and electronic control units, increasing unplanned maintenance expenses. Equipment operators face reduced productivity during peak summer months, affecting project timelines. OEMs must provide desert-rated equipment specifications and robust service infrastructure to maintain uptime standards expected by Saudi project developers.
- Intense Competition from Value-Priced Chinese Manufacturers Compressing Market Margins: Chinese OEMs including SANY, XCMG, and Zoomlion are aggressively expanding Saudi Arabia market share through competitive pricing, improving product quality, and expanding local service infrastructure. Price-sensitive project developers and rental operators are increasingly adopting Chinese-manufactured equipment for standard earthmoving applications. This pricing competition compresses margins for established global OEMs and forces service-led differentiation strategies. The competitive intensity from Chinese manufacturers is expected to increase as they deepen Saudi market presence.
Emerging Market Trends
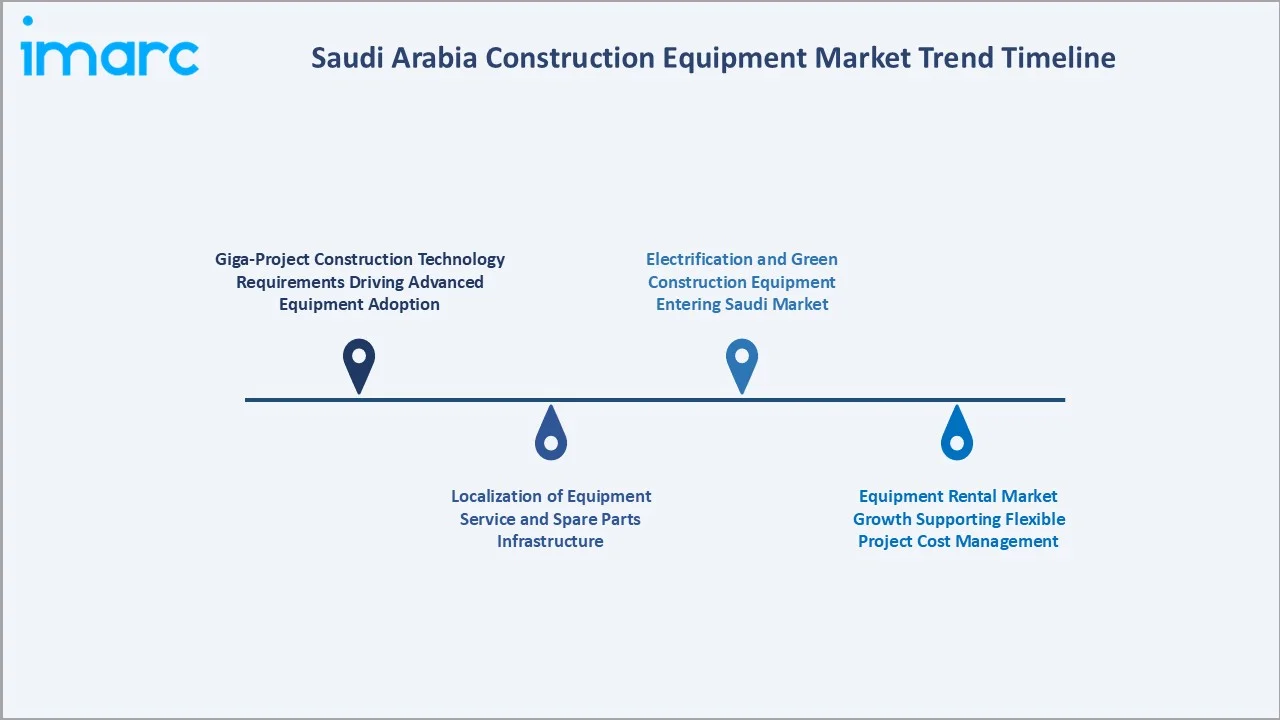
1. Giga-Project Construction Technology Requirements Driving Advanced Equipment Adoption
Saudi Arabia's giga-projects demand precision-guided, high-productivity construction equipment beyond standard specifications. NEOM's complex terrain, Red Sea Project's coastal environment, and Qiddiya's entertainment infrastructure require specialized machinery integrating GPS machine control, real-time productivity monitoring, and remote fleet management. These requirements elevate the equipment quality threshold and favor technologically advanced OEMs.
2. Localization of Equipment Service and Spare Parts Infrastructure
Global OEMs are systematically expanding Saudi Arabia service infrastructure to capture the multi-year maintenance revenue from Vision 2030 equipment deployments. XCMG established its Saudi Arabia subsidiary and opened a Dammam service center. Arabian Trucks & Construction Equipment (ATEC) began construction of a new Hitachi facility. These investments reflect a structural commitment to Saudi market depth.
3. Equipment Rental Market Growth Supporting Flexible Project Cost Management
Saudi Arabia's construction equipment rental market is growing as project developers optimize capital allocation across concurrent mega-project phases. Rental operators provide equipment flexibility for contractors managing variable machinery requirements across project phases. The rental model reduces upfront procurement costs for mid-tier contractors participating in Vision 2030 project subcontracting chains, expanding the total addressable market for equipment suppliers.
4. Electrification and Green Construction Equipment Entering Saudi Market
Saudi Arabia's net-zero commitment and Vision 2030 sustainability goals are creating early demand for hybrid and electric construction equipment. Port expansion projects are adopting electrified yard cranes—as seen at Jeddah Islamic Port's South Container Terminal. Major OEMs are introducing electric-ready equipment variants for Saudi markets, anticipating regulatory and procurement requirements for lower-emission construction machinery through 2030.
Industry Value Chain Analysis
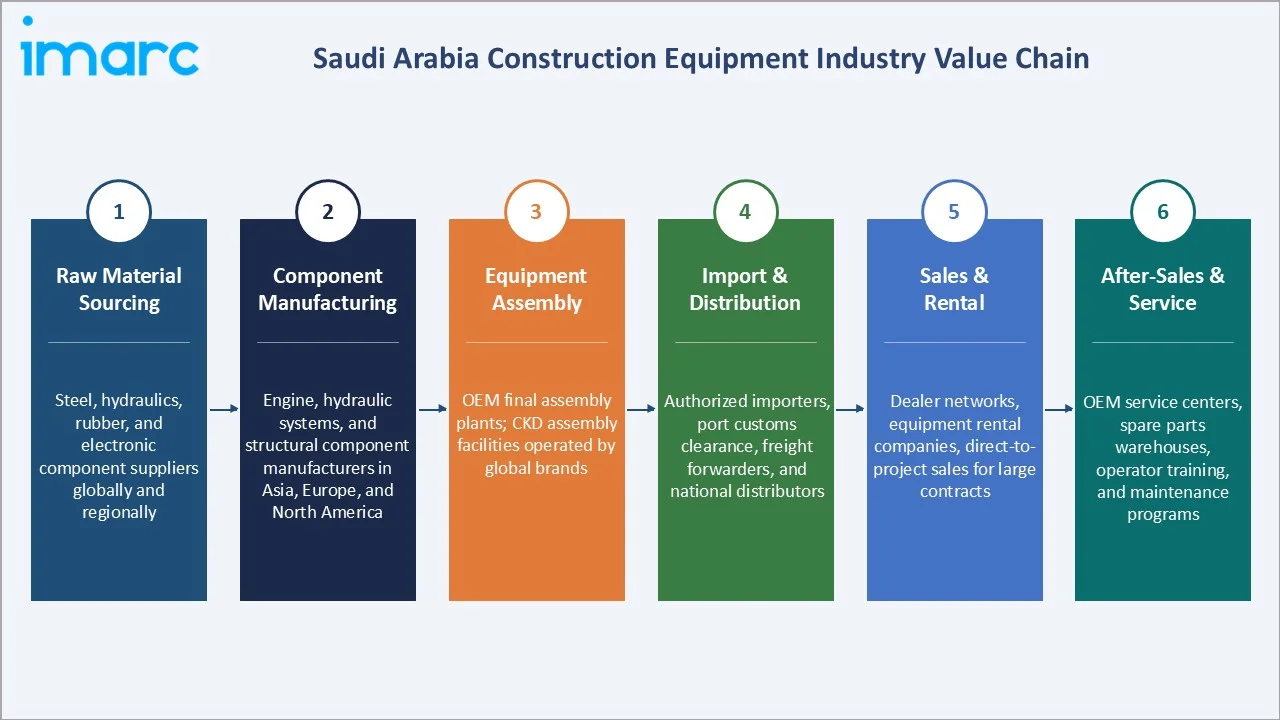
Saudi Arabia construction equipment value chain is predominantly import-oriented, with global OEMs supplying fully built equipment through authorized distributor networks. The value chain's commercial structure is shaped by Vision 2030 procurement volumes, which have attracted OEMs to invest in local service infrastructure, parts warehousing, and operator training centers.
|
Stage |
Key Participants |
|
Raw Material Sourcing |
Steel, hydraulics, rubber, and electronic component suppliers globally and regionally |
|
Component Manufacturing |
Engine, hydraulic systems, and structural component manufacturers in Asia, Europe, and North America |
|
Equipment Assembly |
OEM final assembly plants; CKD assembly facilities operated by global brands |
|
Import & Distribution |
Authorized importers, port customs clearance, freight forwarders, and national distributors |
|
Sales & Rental |
Dealer networks, equipment rental companies, direct-to-project sales for large contracts |
|
After-Sales & Service |
OEM service centers, spare parts warehouses, operator training, and maintenance programs |
The after-sales service and spare parts stage represents the highest-margin segment of the value chain. OEMs with established Saudi service networks capture recurring maintenance revenue from the large equipment fleet deployed across Vision 2030 project sites. Local service depth is becoming a primary purchasing criterion for large-project equipment procurement decisions.
Technology Landscape in the Saudi Arabia Construction Equipment Industry
GPS Machine Control and Precision Grading Technology
GPS-guided machine control systems enable centimeter-accurate earthmoving and grading operations, reducing rework and improving productivity at Saudi giga-project sites. Caterpillar's GRADE with 3D and Komatsu's intelligent Machine Control are being deployed on NEOM and major road construction sites. These technologies reduce equipment operating hours per unit of work completed, improving project economics while maintaining precision requirements.
Telematics and Remote Fleet Management Systems
IoT-enabled telematics platforms provide real-time monitoring of equipment location, utilization, fuel consumption, and predictive maintenance alerts across large construction fleets deployed on geographically dispersed Saudi project sites. Fleet management software enables project managers to optimize equipment allocation, reduce idle time, and schedule preventive maintenance to minimize unplanned downtime. XCMG's smart construction platform and Caterpillar's VisionLink are examples deployed in the Saudi market.
Electric and Hybrid Drive Systems for Construction Equipment
Hybrid and electric drive systems are entering Saudi Arabia's construction equipment market through port electrification projects and early-adopter contractor programs aligned with Vision 2030 sustainability mandates. Volvo CE's electric compact equipment range and Liebherr's electrified crawler crane models represent the leading edge of zero-emission construction machinery entering the Kingdom. Battery technology advances are progressively extending electric equipment duty cycle compatibility with Saudi Arabia's high-temperature operating environment.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Solution Type |
Products |
74.6% |
2025 |
|
Equipment Type |
Heavy Construction Equipment |
68.3% |
2025 |
|
Type |
🔒 |
🔒 |
2025 |
|
Application |
🔒 |
🔒 |
2025 |
|
Industry |
🔒 |
🔒 |
2025 |
|
Region |
Northern & Central Region |
43.8% |
2025 |

By Solution Type
Products lead at 74.6% (2025). The products segment encompasses direct equipment procurement by contractors, project developers, and government agencies—representing the dominant commercial mode for Saudi Arabia's large-scale infrastructure projects. The segment's commanding share reflects the capital-intensive nature of Vision 2030 construction activity, where project scale justifies outright equipment ownership rather than rental.
To access detailed market analysis, Request Sample
Services at 25.4% is growing through expanding equipment rental, maintenance contracts, and integrated project support services. The services segment benefits from Vision 2030 project complexity, which requires specialist operator services and fleet management capabilities beyond direct equipment procurement. The segment is expected to grow faster than the products segment as rental market penetration increases.
By Equipment Type
Heavy Construction Equipment leads at 68.3% (2025). This segment encompasses excavators, large cranes, bulldozers, and heavy loaders essential for the earthmoving, excavation, and site preparation requirements of Saudi Arabia's mega-infrastructure projects. The segment's dominance reflects the scale of Vision 2030 construction activity, where giga-project site preparation requires heavy-duty machinery in high volumes.
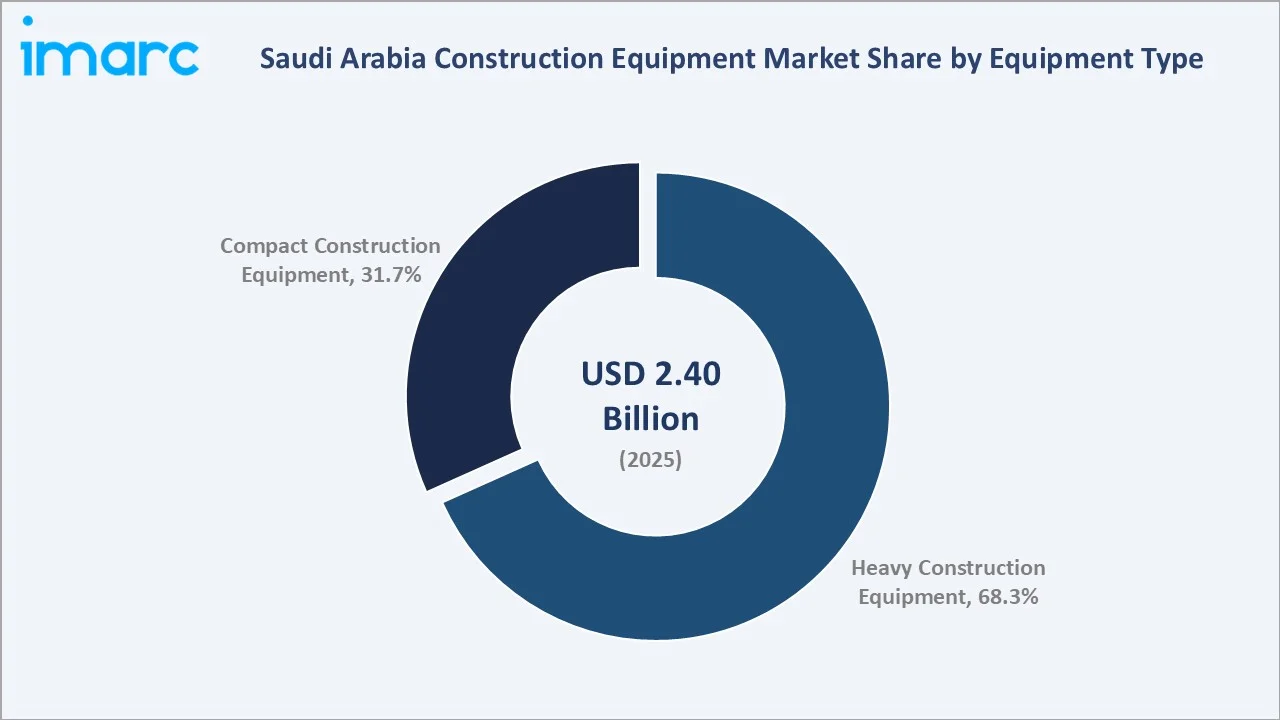
Compact Construction Equipment at 31.7% serves residential construction, utility infrastructure, and confined urban construction applications. The segment benefits from Saudi Arabia's housing program, which drives demand for mini-excavators, skid-steer loaders, and compact track loaders across residential development sites. Compact equipment adoption is also growing in logistics and port applications requiring maneuverability in constrained operating environments.
Regional Market Insights
|
Region |
Share (2025) |
Key Saudi Arabia Construction Equipment Market Drivers & Characteristics |
|
Northern & Central Region |
43.8% |
Riyadh's massive giga-project pipeline, government institutional procurement, and NEOM-linked equipment demand drive the Kingdom's largest regional market. |
|
Western Region |
27.6% |
Jeddah port expansion, Red Sea Project, and rapid residential construction in Makkah and Madinah fuel sustained equipment demand. |
|
Eastern Region |
18.5% |
Oil and gas infrastructure investment, petrochemical plant construction, and Dammam industrial zone development support consistent equipment procurement. |
|
Southern Region |
10.1% |
Growing connectivity infrastructure, border region development programs, and expanding logistics corridors contribute to rising equipment utilization. |
Northern & Central Region's 43.8% market leadership reflects Riyadh's position as the administrative hub of Vision 2030 capital deployment, with NEOM coordination, King Salman International Airport construction, and Qiddiya development all driving regional equipment demand. Western Region's 27.6% reflects Jeddah port expansion, Red Sea Project construction, and Makkah and Madinah residential and hospitality development.
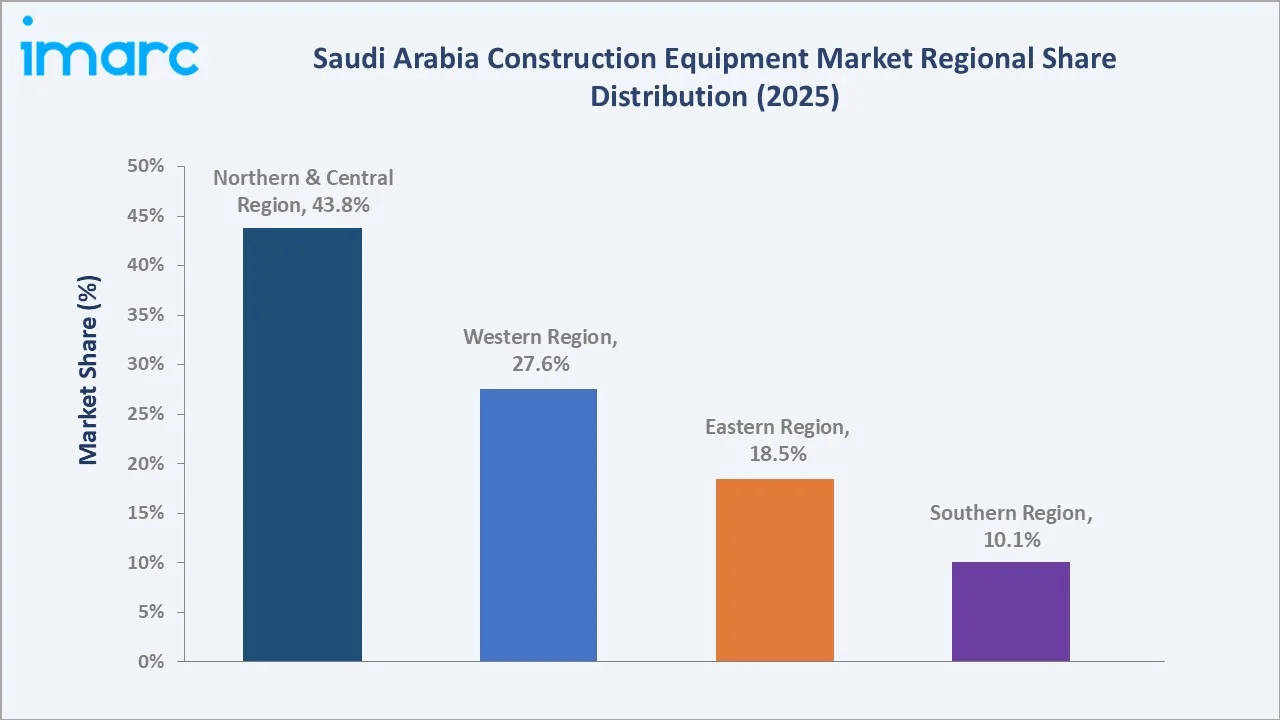
Eastern Region's 18.5% is sustained by oil and gas infrastructure investment, petrochemical plant construction in Jubail Industrial City, and Dammam port logistics development. Southern Region's 10.1% represents the most nascent regional market, growing through border region infrastructure programs and expanding logistics corridor development connecting the Kingdom's southern provinces.
Competitive Landscape
Saudi Arabia construction equipment market competitive landscape is characterized by dominance from global OEMs through established dealer networks, superior technology, and comprehensive after-sales infrastructure. Chinese manufacturers are rapidly gaining market share through competitive pricing and expanding local service investment, increasing competitive intensity across standard earthmoving equipment categories.
|
Company |
Key Brands |
Market Position |
Core Strength |
|
Caterpillar |
Cat, Progress Rail, Solar Turbines, Perkins, SEM |
Market Leader |
A globally recognized manufacturer of construction and mining equipment with an extensive dealer network, strong aftermarket support, and broad product portfolio across all heavy equipment categories. |
|
Komatsu Ltd. |
Dozers, Electric rope shovels, Excavators, Motor graders, Trucks, Wheel loaders |
Market Leader |
A leading construction equipment manufacturer known for advanced technology integration, fuel-efficient machinery, and robust service infrastructure supporting large infrastructure projects. |
|
Liebherr-International Deutschland GmbH |
Excavators, Dozers, Trucks, Tower Cranes, Mobile and Crawler Cranes |
Strong Challenger |
A diversified equipment manufacturer renowned for high-capacity cranes, earthmoving machinery, and material handling solutions used in complex construction environments. |
|
SANY Group |
Excavators, Concrete Machinery, Cranes, Port Machinery, Road Machinery, Mining Machinery, Trucks |
Strong Challenger |
A rapidly expanding Chinese equipment manufacturer with competitive pricing, growing product quality, and active market presence across excavators, cranes, and concrete equipment. |
|
XCMG Group |
Hoisting Machinery, Earthmoving Machinery, Mining Machinery, Underground Mining Machinery, Road Building Machinery, Concrete Machinery, Special Vehicles, Truck, Drilling Machinery |
Strong Challenger |
A Chinese construction equipment manufacturer with an established Saudi Arabia subsidiary, expanding service network, and increasing penetration in major Vision 2030 giga-projects. |
Key players include Caterpillar, Komatsu Ltd., Liebherr-International Deutschland GmbH, SANY Group, XCMG Group, and others.
Key Company Profiles
Caterpillar
Caterpillar is the world's leading manufacturer of construction and mining equipment, diesel and natural gas engines, industrial gas turbines, and diesel-electric locomotives, with a comprehensive product portfolio serving Saudi Arabia's infrastructure and energy sectors.
- Key Brands: Cat, Progress Rail, Solar Turbines, Perkins, SEM
- Strategic Focus: Maintaining market leadership through technology-led product differentiation, including GPS machine control, telematics, and autonomous equipment solutions tailored for large-scale Saudi infrastructure projects. Caterpillar prioritizes building long-term project partnerships with major Saudi contractors and government project authorities to secure multi-year equipment supply agreements, while expanding its financing and rental service offerings to address diverse procurement preferences across the Saudi market.
Komatsu Ltd.
Komatsu Ltd. is a leading global manufacturer of construction, mining, and utility equipment, recognized for its intelligent machine control technology, fuel-efficient machinery, and robust global service infrastructure with strong presence across Saudi Arabia's major project segments.
- Key Brands: Dozers, Electric rope shovels, Excavators, Motor graders, Trucks, Wheel loaders
- Strategic Focus: Advancing intelligent construction technology integration to differentiate from Chinese competitors through superior productivity, lower fuel consumption, and GPS-guided precision capabilities aligned with Saudi giga-project requirements. Komatsu focuses on strengthening its authorized dealer relationships across all four Saudi regions, expanding its parts inventory and technical service capability to minimize equipment downtime on time-critical Vision 2030 project sites, while selectively targeting high-value project procurement opportunities in the earthmoving and mining equipment categories.
Market Concentration Analysis
Saudi Arabia construction equipment market is moderately concentrated at the premium end, with the key players collectively commanding an estimated 45-55% of the market by value. Chinese OEMs are estimated to hold 15-20% combined value share, with their volume share significantly higher in standard earthmoving equipment categories.
Market concentration is evolving toward greater fragmentation as Chinese manufacturers expand Saudi market presence through local subsidiaries, dealer networks, and service investments. The rental market segment shows higher fragmentation with multiple local operators competing alongside OEM-affiliated rental programs. Price-competitive procurement by mid-tier contractors is accelerating the shift toward value-priced Chinese equipment in non-critical project applications.
Investment & Growth Opportunities
Highest Growth Segments
Heavy Construction Equipment (~3.4% CAGR through giga-project earthmoving demand), electric and hybrid equipment (~above-market CAGR through sustainability mandates), equipment rental services (~above-market CAGR through flexible procurement growth), Northern & Central Region (~3.65% CAGR through Riyadh mega-development), and digital construction technology services (~above-market CAGR through smart project adoption) represent Saudi Arabia's highest-growth construction equipment investment vectors through 2034.
Emerging Investment Opportunities
Saudi Arabia's construction equipment maintenance and repair services market, growing alongside the expanding in-Kingdom equipment fleet, represents an attractive investment for OEM-independent service operators. Investors can access this through authorized service center networks, operator training academies, and equipment fleet management platform development aligned with the Kingdom's growing digital construction infrastructure.
Investment Themes
- Localized service and spare parts infrastructure for Vision 2030 fleet management: OEMs and independent service operators investing in in-Kingdom spare parts warehousing, mobile service teams, and technician training programs can capture high-margin recurring revenue from the growing construction equipment fleet across Saudi Arabia's four regions.
- Electric and sustainable construction equipment distribution and service: Early positioning in electric and hybrid construction equipment distribution, charging infrastructure, and specialist service capabilities creates first-mover advantage in a market segment expected to grow significantly through Vision 2030's sustainability mandate and Saudi Arabia's renewable energy expansion.
Future Market Outlook (2026-2034)
The Saudi Arabia construction equipment market is projected to grow from USD 2.40 Billion in 2025 to USD 2.47 Billion in 2026, reaching USD 3.20 Billion by 2034, registering a CAGR of 3.26% during 2026-2034. The market anchor value of USD 2.81 Billion in 2030 represents a structural milestone driven by NEOM's final construction phases, housing program completion, and port infrastructure commissioning.
Three structural forces define Saudi Arabia construction equipment market growth through 2034: Vision 2030's trillion-dollar infrastructure pipeline sustaining multi-year equipment demand across all categories; Saudi Arabia's housing program creating persistent residential construction equipment requirements through 2030; and the Kingdom's logistics hub ambition driving sustained port and warehouse infrastructure equipment procurement beyond 2030.
Research Methodology
Primary Research
Primary research comprised structured interviews with Saudi Arabia construction equipment market stakeholders, including equipment dealers and distributors, major project contractors, equipment rental operators, OEM regional managers, and government project procurement officers across all four Saudi regions.
Secondary Research
Secondary research encompassed Saudi Ports Authority project reports, Vision 2030 program documents, company annual reports, Ministry of Housing program data, Saudi Contractors Authority publications, equipment import trade data, and investor presentations. Over 50 secondary sources reviewed.
Forecasting Models
Market revenue forecasts were developed using a project-based demand model: Saudi Arabia's active construction project pipeline valued by construction phase, multiplied by equipment intensity ratios per project type, aggregated by equipment category and region. Vision 2030 capital expenditure schedules were used as primary forward-demand indicators.
Saudi Arabia Construction Equipment Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Solution Types Covered | Products, Services |
| Equipment Types Covered | Heavy Construction Equipment, Compact Construction Equipment |
| Types Covered | Loader, Cranes, Forklift, Excavator, Dozers, Others |
| Applications Covered | Excavation and Mining, Lifting and Material Handling, Earth Moving, Transportation, Others |
| Industries Covered | Oil and Gas, Construction and Infrastructure, Manufacturing, Mining, Others |
| Regions Covered | Northern and Central Region, Western Region, Eastern Region, Southern Region |
| Companies Covered | Caterpillar, Komatsu Ltd., Liebherr-International Deutschland GmbH, SANY Group, XCMG Group, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC's industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Saudi Arabia construction equipment market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Saudi Arabia construction equipment market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Saudi Arabia construction equipment industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Saudi Arabia Construction Equipment Market Report
Saudi Arabia construction equipment market size is estimated at USD 2.47 Billion in 2026, driven by Vision 2030 infrastructure investment, government housing programs, and port expansion projects sustaining broad equipment demand across all major categories.
Saudi Arabia construction equipment market grows at 3.26% CAGR during 2026-2034, reaching USD 3.20 Billion by 2034. Growth is sustained by the multi-year Vision 2030 project pipeline, residential construction demand, and port logistics infrastructure expansion.
Products leads at 74.6% through direct equipment procurement by contractors and project developers involved in Vision 2030 giga-projects, housing developments, and infrastructure programs.
Heavy Construction Equipment leads at 68.3% through the earthmoving, excavation, and large-scale material handling requirements of Saudi Arabia's mega-infrastructure project pipeline.
Northern & Central Region leads at 43.8% through Riyadh's concentration of Vision 2030 capital expenditure, giga-project coordination, and the Kingdom's highest density of concurrent large-scale construction projects.
Leading companies include Caterpillar, Komatsu Ltd., Liebherr-International Deutschland GmbH, SANY Group, XCMG Group, and others.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade