
Saudi Arabia E-commerce Shipping Market Size, Share, Trends and Forecast by Service, Business, Destination, End-Use Industry, and Region, 2026-2034
Saudi Arabia E-commerce Shipping Market Size, Share, Trends & Forecast (2026-2034)
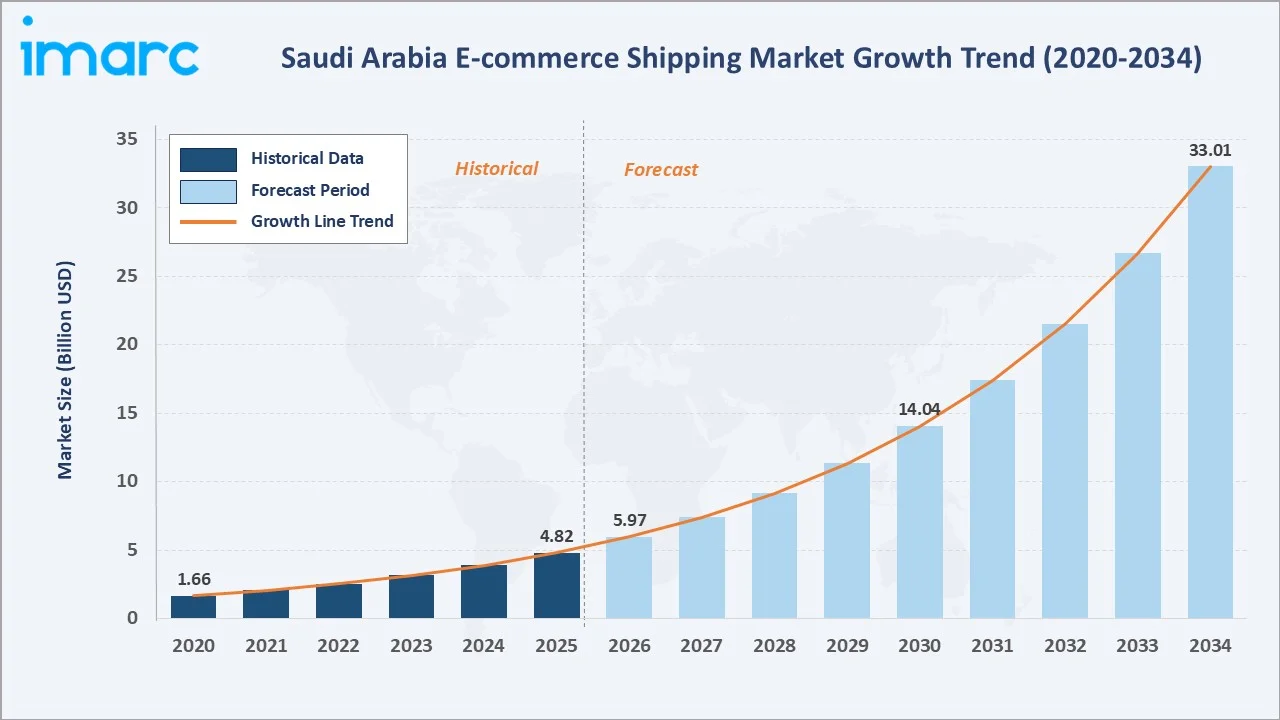
The Saudi Arabia e-commerce shipping market grew from USD 4.82 Billion in 2025 to USD 5.97 Billion in 2026 and is projected to reach USD 33.01 Billion by 2034, growing at a CAGR of 23.84% during 2026-2034. The market is driven by Vision 2030 infrastructure investment, a young digitally native population, and rapid mobile commerce penetration. Saudi Arabia has a predominantly young population, with around 69.4% of Saudi citizens below the age of 35 and nearly one-third under 15 years old. This digitally engaged demographic is accelerating market growth. B2C dominates at 74.6%, fashion & apparel leads at 31.5% by end-use industry, and the Northern & Central region commands the largest regional share at 48.2%.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 4.82 Billion |
|
Market Size (2026) |
USD 5.97 Billion |
|
Forecast Market Size (2034) |
USD 33.01 Billion |
|
CAGR (2026-2034) |
23.84% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Business |
B2C (74.6%, 2025) |
|
Dominant End-Use Industry |
Fashion & Apparel (31.5%, 2025) |
|
Leading Region |
Northern & Central Region (48.2%, 2025) |
The Saudi Arabia e-commerce shipping market grew from USD 1.66 Billion in 2020 to USD 4.82 Billion by 2025 and is estimated to reach USD 5.97 Billion in 2026. The market is projected to reach USD 14.04 Billion by 2030 and USD 33.01 Billion by 2034.
To get more information on this market, Request Sample
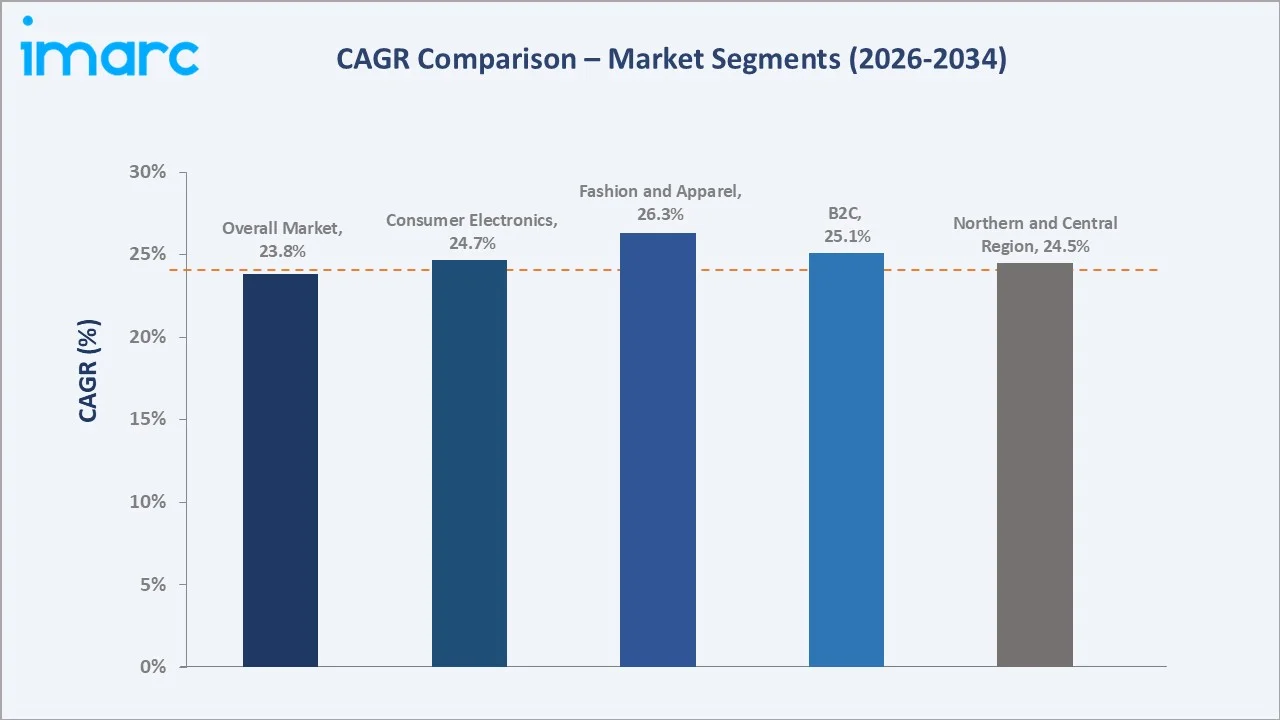
B2C segment grows at ~25.1% CAGR through consumer platform dominance. Fashion & apparel logistics expands at ~26.3% CAGR through social commerce and influencer-driven purchasing. Consumer electronics grows at ~24.7% CAGR through Saudi Arabia's tech-savvy consumer base.
Executive Summary
The Saudi Arabia e-commerce shipping market is one of the fastest-growing logistics verticals in the Middle East, underpinned by Vision 2030's commitment to building a world-class logistics infrastructure and diversifying the Kingdom's economy. Saudi Arabia's strategic ambition to become a global logistics hub by 2030, supported by its position bridging Asia, Europe, and Africa, further amplifies the sector's structural growth trajectory. B2C leads at 74.6%. Fashion & apparel leads end-use demand at 31.5%. The Northern & Central region leads regionally at 48.2%.
Key Market Insights
|
Insight |
Data |
|
Dominant Business |
B2C - 74.6% share (2025) |
|
Dominant End-Use Industry |
Fashion & Apparel - 31.5% share (2025) |
|
Leading Region |
Northern & Central Region - 48.2% (2025) |
|
Key Market Opportunity |
Rural e-commerce expansion is underserved by logistics under Vision 2030 digitization programs. |
Key Analytical Observations Supporting the Above Data:
- B2C at 74.6%: Consumer-facing e-commerce platforms drive shipping volumes. Amazon.sa and Noon collectively account for a significant share of daily parcel deliveries. Saudi consumers' preference for next-day and same-day delivery pushes carriers to invest in hyperlocal fulfillment hubs, with same-day delivery penetration.
- Fashion & Apparel at 31.5%: Social commerce platforms and influencer-driven buying generate high order frequency. Return rates create significant reverse logistics opportunities for carriers with efficient returns infrastructure.
- Northern & Central Region at 48.2%: Riyadh's 7.5 million population and corporate concentration make it the single largest demand center, housing the majority of Saudi Arabia's mega-fulfillment warehouses and accounting for nearly half of all annual e-commerce parcel movements.
Saudi Arabia E-Commerce Shipping Market Overview
The Saudi Arabia e-commerce shipping market encompasses all logistics and delivery services facilitating online trade, including domestic parcel delivery, cross-border freight forwarding, warehousing, fulfillment, value-added packaging, and returns management. The ecosystem serves B2C consumer deliveries and B2B corporate shipments across fashion & apparel, consumer electronics, beauty & personal care, home appliances, furniture, and other categories. The National Industrial Development and Logistics Program (NIDLP) targets increasing the Kingdom’s industrial GDP from approximately SAR 226 billion in 2016 to SAR 895 billion by 2030, directly benefiting e-commerce shipping providers through expanded port capacity, automated customs, and smart logistics zone development.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
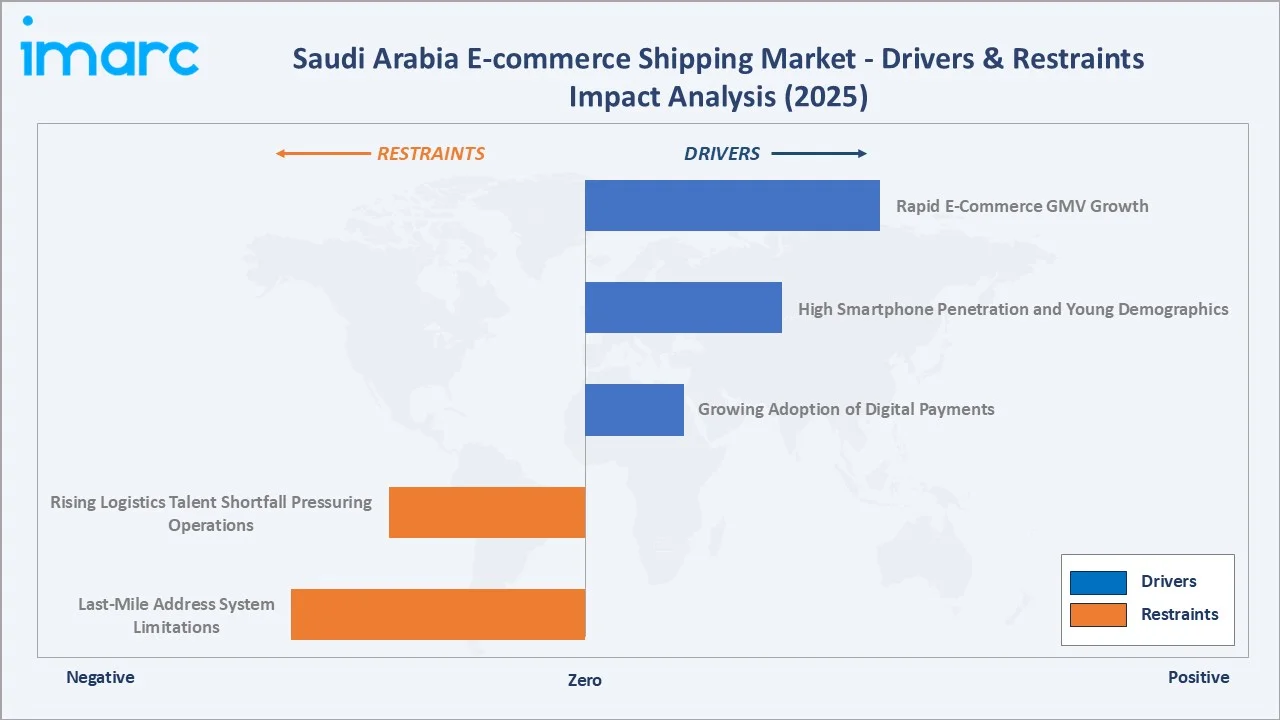
- Rapid E-Commerce GMV Growth: Each percentage point of GMV growth directly translates into incremental shipping volume, providing secular demand tailwinds for all market participants. Platform investments in user experience and delivery speed continue expanding addressable e-commerce demand annually.
- High Smartphone Penetration and Young Demographics: Saudi Arabia has a predominantly young population, with approximately 69.4% of Saudi citizens below the age of 35 and nearly one-third under the age of 15, with smartphone penetration exceeding 98%. Mobile commerce's share of online orders, generating delivery density supporting urban hub-based last-mile economics and rapid same-day delivery scaling.
- Growing Adoption of Digital Payments: According to the Saudi Central Bank (SAMA), electronic payments represented 85% of total retail payments in Saudi Arabia in 2025, increasing from 79% in 2024. The number of electronic transactions also rose significantly, reaching 14.6 billion in 2025 compared with 12.6 billion in the previous year. Increasing use of digital wallets, cards, and other electronic payment methods is simplifying online transactions and reducing dependence on cash-based purchases. Seamless payment integration improves checkout convenience and supports higher e-commerce conversion rates.
Market Restraints
- Last-Mile Address System Limitations: Traditional Saudi addressing relies on informal landmarks and coordinates rather than standardized addresses. While the unified addressing project covers most urban areas, rural and peri-urban coverage gaps persist, increasing delivery failure rates versus mature markets and raising per-successful-delivery costs materially.
- Rising Logistics Talent Shortfall Pressuring Operations: Rapid market growth outpaced the available supply of qualified logistics professionals. The sector faces a skilled labor gap, elevating operational costs and constraining the scaling speed of carriers seeking to expand rapidly across all Saudi regions during the forecast period.
Market Opportunities
- Drone and Autonomous Vehicle Delivery: In September 2025, Saudi Arabia conducted a pioneering drone-based parcel delivery trial in Jeddah, jointly supported by GACA and the Transport General Authority (TGA). The initiative aims to enhance delivery efficiency, promote innovative logistics solutions, and support the Kingdom’s broader digital transformation and logistics modernization objectives. These technologies represent the commercialization window, with potential to reduce last-mile delivery costs for urban high-density zones, transforming last-mile economics and enabling economically viable rural delivery on a scale.
- Cold Chain E-Commerce Logistics: Grocery and pharmaceutical online delivery require specialized temperature-controlled fulfillment. Cold chain e-commerce shipping represents a high-margin niche with minimal current competition, offering significant first-mover advantage for specialized carriers.
Market Challenges
- Intense Price Competition from Platform-Owned Logistics: Platform-owned logistics arms are internalizing deliveries, reducing volumes available to third-party carriers. Aggressive pricing from global carriers is compressing margins for domestic players lacking scale advantages, requiring ongoing efficiency investment to sustain viable carrier economics through 2034.
- Regulatory Compliance and Data Privacy Burden: Saudi Arabia's regulatory compliance requires digital shipping platforms to invest in data security infrastructure. Compliance costs create an operational burden for smaller technology-first carriers and logistics startups, with ongoing regulatory evolution requiring continuous adaptation investment.
Emerging Market Trends
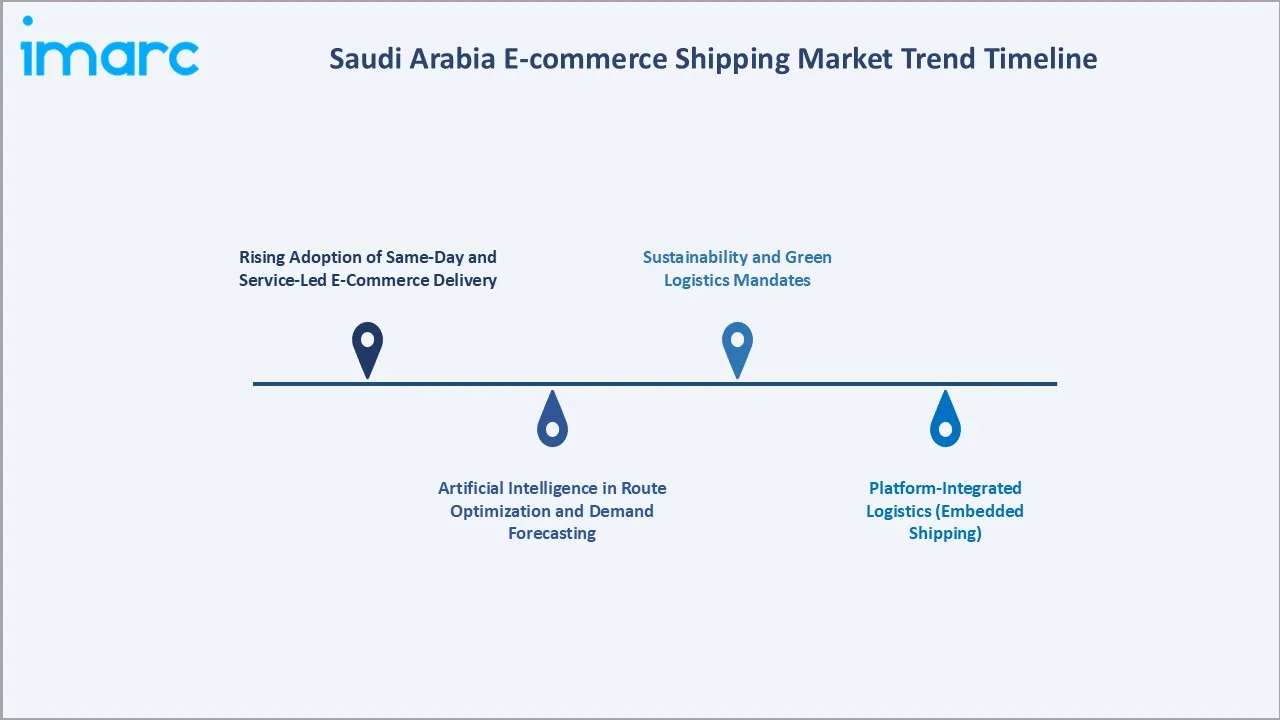
1. Rising Adoption of Same-Day and Service-Led E-Commerce Delivery
In April 2026, Kanaa launched in Saudi Arabia with a mobile-first, service-oriented shopping model. The platform offers curated product discovery, same-day delivery, extended warranties, and seamless navigation, addressing growing consumer demand for faster, more reliable, and convenient online shopping experiences. The launch highlights a shift toward same-day delivery, mobile-first shopping, and enhanced post-purchase services. This is encouraging logistics providers to develop faster, technology-enabled last-mile fulfillment capabilities across Saudi Arabia.
2. Artificial Intelligence in Route Optimization and Demand Forecasting
E-commerce shipping providers are increasingly adopting AI to analyze traffic, delivery locations, parcel volumes, and historical demand patterns to optimize delivery routes and forecast shipment demand. These technologies help reduce delivery times and transportation costs while improving fleet utilization and inventory planning. Growing same-day and next-day delivery expectations are further accelerating AI adoption across Saudi Arabia’s e-commerce logistics ecosystem.
3. Sustainability and Green Logistics Mandates
Growing sustainability priorities are encouraging e-commerce shipping providers in Saudi Arabia to adopt electric delivery vehicles, optimized transportation routes, sustainable packaging, and energy-efficient fulfillment facilities. These initiatives help reduce emissions and fuel consumption while improving operational efficiency. The trend aligns with the Kingdom’s broader environmental and sustainability objectives under Vision 2030.
4. Platform-Integrated Logistics (Embedded Shipping)
E-commerce platforms are integrating shipping APIs directly into seller dashboards, enabling real-time rate shopping, automated label printing, and shipment tracking without leaving the platform interface. This trend shifts bargaining power toward platform-native logistics solutions and away from standalone carriers dependent on individual shipper relationships, requiring rapid API capability development.
Industry Value Chain Analysis
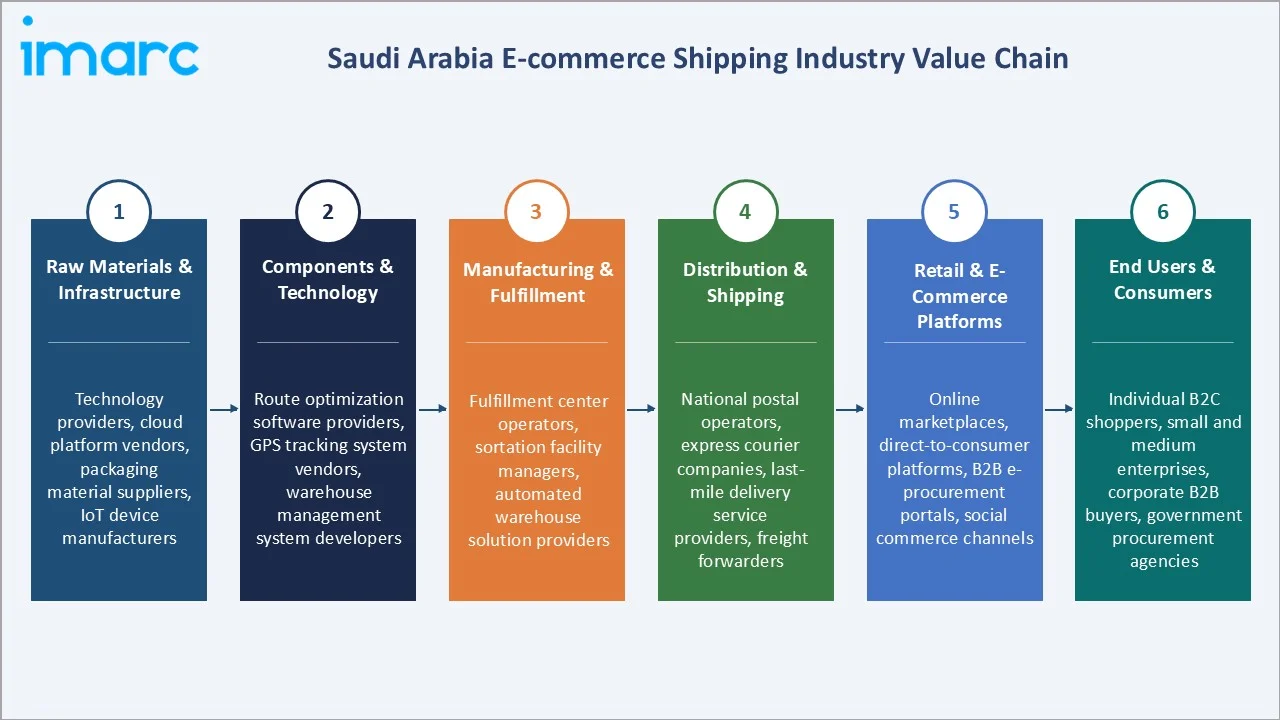
The Saudi Arabia e-commerce shipping value chain integrates raw materials & infrastructure, components & technology, manufacturing & fulfillment, distribution & shipping, retail & e-commerce platforms, and end users & consumers.
|
Stage |
Key Players |
|
Raw Materials & Infrastructure |
Technology providers, cloud platform vendors, packaging material suppliers, IoT device manufacturers. |
|
Components & Technology |
Route optimization software providers, GPS tracking system vendors, warehouse management system developers. |
|
Manufacturing & Fulfillment |
Fulfillment center operators, sortation facility managers, automated warehouse solution providers. |
|
Distribution & Shipping |
National postal operators, express courier companies, last-mile delivery service providers, freight forwarders. |
|
Retail & E-Commerce Platforms |
Online marketplaces, direct-to-consumer platforms, B2B e-procurement portals, social commerce channels. |
|
End Users & Consumers |
Individual B2C shoppers, small and medium enterprises, corporate B2B buyers, government procurement agencies. |
Distribution and shipping represent the most operationally complex and cost-intensive stage, accounting for an estimated 48-53% of total shipping cost in urban Saudi Arabia. Operators investing in urban micro-warehousing, AI routing, and electric vehicles are compressing last-mile costs and improving delivery success rates in major cities.
Technology Landscape in the Saudi Arabia E-Commerce Shipping Industry
AI-Powered Logistics Management Platforms
The Saudi Arabia e-commerce shipping technology sector is undergoing rapid transformation as AI-native platforms challenge traditional carrier models. AI platforms process real-time traffic, order density, and weather data to dynamically reroute delivery fleets, improving both cost efficiency and delivery SLA compliance for enterprise e-commerce clients.
Drone and Autonomous Delivery Technology
In January 2025, Matternet received approval from Saudi Arabia’s General Authority of Civil Aviation (GACA) to operate its M2 delivery drone, marking the country’s first authorization of its kind. The approval follows GACA’s recognition of the M2’s FAA Type Certification as meeting Saudi airworthiness requirements. Drone delivery also addresses Saudi Arabia's address gap in peri-urban areas, enabling delivery to GPS coordinates rather than requiring formal street addresses.
Smart Warehousing and Robotics
Automated fulfillment centers with robotic picking systems reduce per-order fulfillment costs. Saudi Arabia's low energy costs support warehouse automation economics, creating favorable return on investment versus global peers and incentivizing further automation capital allocation. Mega-fulfillment centers setting a new operational standard for the market.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Service |
🔒 |
🔒 |
2025 |
|
Business |
B2C |
74.6% |
2025 |
|
Destination |
🔒 |
🔒 |
2025 |
|
End-Use Industry |
Fashion and Apparel |
31.5% |
2025 |
|
Region |
Northern and Central Region |
48.2% |
2025 |

By Business
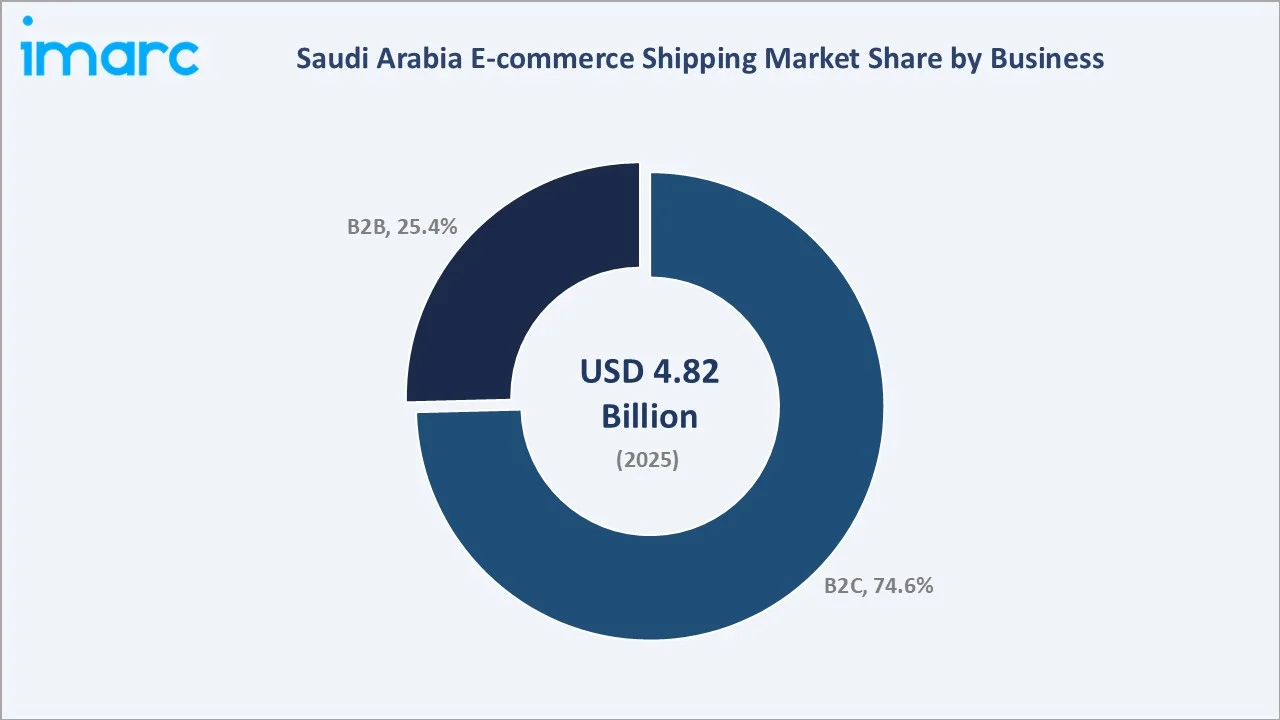
B2C commands 74.6%, driven by the dominance of consumer-facing e-commerce platforms generating tens of millions of annual parcel deliveries. The B2C segment benefits from high delivery frequency, urban address density, and Saudi consumers' growing appetite for same-day and next-day delivery services.
To access detailed market analysis, Request Sample
B2B holds 25.4% in 2025, encompassing corporate procurement, industrial supplies, and inter-business merchandise shipments. B2B shipping commands higher average shipment weights and values, generating premium freight revenue per consignment. The B2B segment is growing as Saudi businesses increasingly procure supplies digitally, aided by Vision 2030's SME digitization initiative covering Saudi SMEs.
By End-Use Industry
Fashion & apparel leads at 31.5% in 2025, reflecting Saudi Arabia's vibrant online fashion market buoyed by social commerce platforms and influencer marketing. High return rates generate secondary reverse logistics volume, making this a dual-revenue opportunity for carriers with efficient returns handling infrastructure.
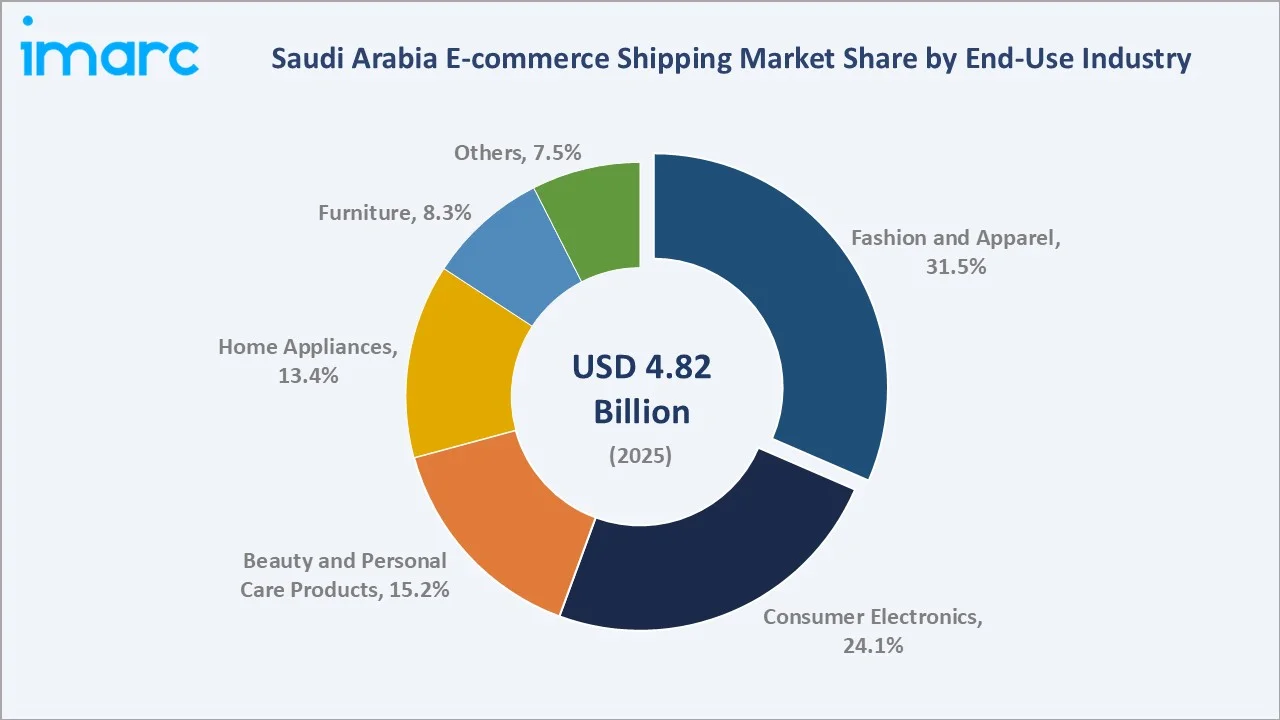
Consumer electronics at 24.1% is driven by Saudi Arabia's tech-forward consumer base, with smartphones, tablets, and smart home device online sales accelerating. Beauty & personal care products at 15.2% benefit from Saudi women's expanded consumer freedom and social commerce platforms. Home appliances at 13.4% reflects Saudi Arabia's large household formation rate tied to Vision 2030 housing development. Furniture at 8.3% grows through specialized large-item delivery platforms requiring white-glove delivery and assembly services.
Regional Market Insights
|
Region |
Share (2025) |
Key Saudi Arabia E-Commerce Shipping Market Drivers & Characteristics |
|
Northern & Central Region |
48.2% |
Reflecting Riyadh's commercial dominance, highest consumer density, largest fulfillment warehouse concentration, and expanding metro logistics corridors. |
|
Western Region |
23.5% |
Reflecting gateway advantages for cross-border imports, pilgrimage economy seasonal shipping surges, and strong trade corridor logistics demand. |
|
Eastern Region |
18.1% |
Reflecting petrochemical sector B2B industrial shipments, Gulf port-proximate free zone warehousing, and growing corporate e-procurement volumes. |
|
Southern Region |
10.2% |
Reflecting emerging e-commerce adoption, lowest infrastructure density, and the highest growth potential as Vision 2030 rural digitization programs expand delivery access. |
The Northern & Central region's 48.2% share reflects Riyadh's unmatched density of corporate headquarters, retail distribution centers, and a high consumer population. The Western region's 23.5% is anchored by Saudi Arabia's primary import gateway.
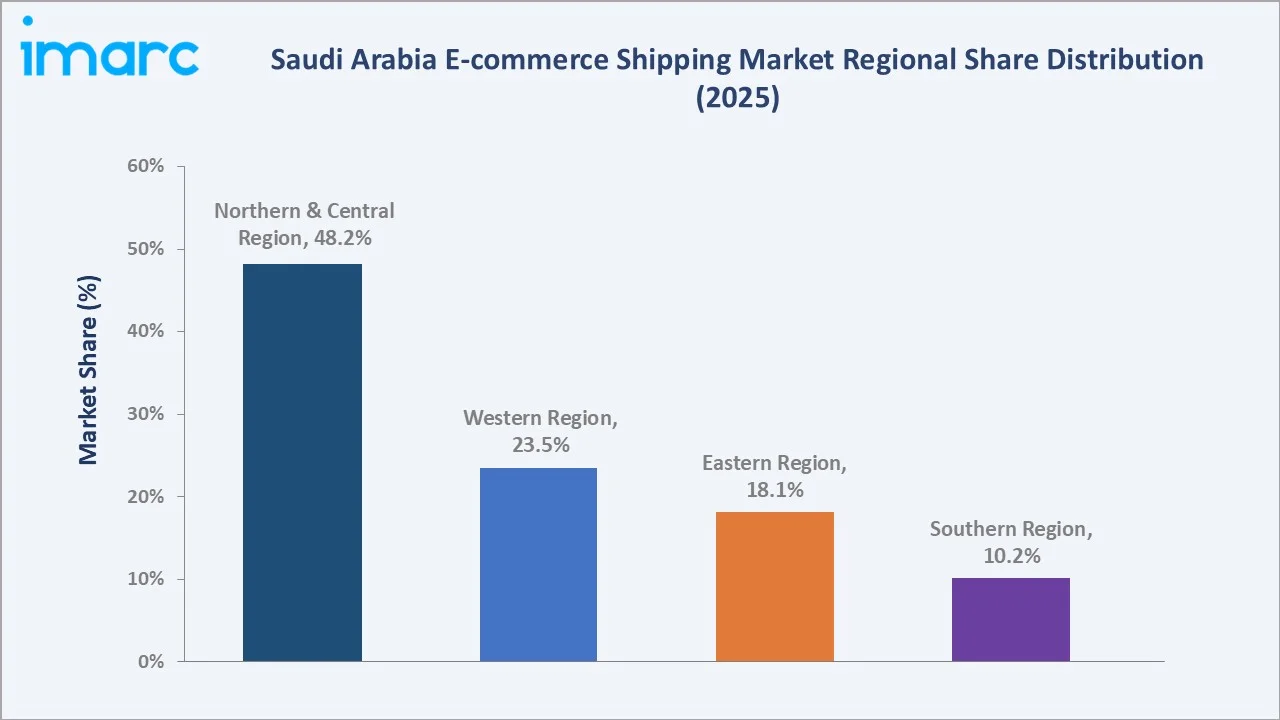
The Eastern region's 18.1% is supported by petrochemical sector B2B logistics and free zone warehousing. The Southern region at 10.2% represents the highest growth potential as Vision 2030 rural digitization investments build first-time e-commerce access for underserved communities, supported by expanding mobile payment infrastructure and carrier network investment throughout the forecast period.
Competitive Landscape
The Saudi Arabia e-commerce shipping market features a competitive ecosystem spanning global express carriers, government-backed national postal operators, platform-owned logistics arms, and technology-first domestic startups. Market leadership is contested across delivery speed, geographic coverage, technology capability, pricing, and e-commerce platform integration depth.
|
Company |
Key Offerings |
Market Position |
Core Strength |
|
Saudi Post | SPL |
Last mile delivery options, Shipping to doorstep |
Market Leader |
Saudi Post | SPL acts as the primary national logistics backbone for e-commerce shipping in Saudi Arabia. |
|
DHL Group |
DHL Express Commerce |
Market Leader |
DHL Group drives e-commerce shipping in Saudi Arabia by combining its global logistics network with local expertise. |
|
FedEx |
FedEx Ship Manager |
Market Leader |
FedEx plays a vital role in Saudi Arabia's e-commerce shipping by providing direct-serve logistics infrastructure, cross-border services, and digital tools. |
|
United Parcel Service of America, Inc. |
UPS Shipping |
Established Player |
Connects the Kingdom to global e-commerce markets by providing fast cross-border shipping, freight services, and customs clearance. |
|
J&T Express |
Express Shipping |
Challenger |
J&T Express acts as a major end-to-end logistics and cross-border delivery backbone for Saudi Arabia’s booming e-commerce market |
Companies across the competitive landscape are investing in AI logistics management technology, EV fleet electrification, mobile-first delivery experience platforms, and e-commerce API integration capabilities. The market is expected to see continued consolidation among traditional carriers alongside rapid growth from platform-owned logistics arms targeting the B2C parcel market.
Key Company Profiles
Saudi Post | SPL
Saudi Post | SPL is a leading postal and logistics service provider in Saudi Arabia, offering domestic and international parcel delivery, e-commerce shipping, fulfillment, and last-mile services. The company operates an extensive distribution network supporting online retailers and consumers across the Kingdom. Its digital tracking, delivery, and logistics solutions position SPL as a key participant in Saudi Arabia’s growing e-commerce shipping market.
- Key Offerings: Last mile delivery options, Shipping to doorstep.
- Strategic Focus: Strengthening its e-commerce logistics capabilities through expanded last-mile delivery networks, fulfillment services, parcel lockers, and digitally enabled shipment management. The company emphasizes faster delivery, nationwide coverage, automation, and cross-border logistics to address growing online parcel volumes and support Saudi Arabia’s development as a regional logistics hub.
DHL Group
DHL Group is a global logistics company providing express delivery, parcel shipping, freight transportation, e-commerce logistics, and supply chain solutions. In Saudi Arabia, the company supports online retailers through domestic and cross-border delivery, customs clearance, fulfillment, and shipment-tracking services. Its international logistics network and technology-enabled operations position DHL as a key participant in the Saudi Arabia e-commerce shipping market.
- Key Offerings: DHL Express Commerce.
- Strategic Focus: Strengthening its e-commerce logistics presence in Saudi Arabia through expanded fulfillment capacity, cross-border connectivity, and technology-enabled last-mile delivery. The company emphasizes automation, digital shipment visibility, faster delivery, and sustainable logistics solutions to improve operational efficiency and meet evolving online retailer and consumer requirements.
Market Concentration Analysis
The Saudi Arabia e-commerce shipping market is moderately concentrated, with the top five players collectively accounting for an estimated 58-63% of total market revenue in 2025. Government-backed Saudi Post holds structural advantages in rural coverage and COD processing, while global carriers lead premium cross-border segments. Platform-owned logistics arms are rapidly capturing B2C parcel volumes from traditional third-party carriers, structurally reshaping the competitive landscape.
The market's 23.84% CAGR is attracting new entrants, including platform-native logistics arms and technology-first startups, progressively fragmenting the mid-market and urban last-mile segments. Consolidation is expected in the 2028-2032 period as scale advantages become decisive for profitability. Platform-integrated logistics is projected to capture high B2C delivery volumes by 2034, restructuring competitive dynamics and revenue pools across the market significantly.
Investment & Growth Opportunities
Highest Growth Segments
Fashion & apparel logistics (~26.3% CAGR), B2C same-day delivery hyperlocal fulfillment (~25.1% CAGR), consumer electronics express shipping (~24.7% CAGR), cross-border e-commerce facilitation (~24.0% CAGR), cold chain e-commerce logistics, and rural delivery infrastructure development represent the highest-growth investment vectors in the Saudi Arabia e-commerce shipping market through 2034.
Investment Themes
- Smart Warehousing and Robotics: Automated fulfillment centers with robotic picking systems reduce per-order fulfillment costs. Saudi Arabia's low energy costs support warehouse automation economics, creating favorable ROI versus global peers and incentivizing further capital allocation to automated logistics infrastructure throughout the forecast period.
- Electric Vehicle Last-Mile Fleet: Government EV mandates and subsidies create favorable fleet electrification economics. EV operators benefit from fuel cost reduction versus petrol, favorable regulatory treatment, and growing ESG investor emphasis on logistics sustainability credentials, increasingly important for institutional capital access and enterprise client procurement.
Future Market Outlook (2026-2034)
The Saudi Arabia e-commerce shipping market is projected to grow from USD 4.82 Billion in 2025 to USD 5.97 Billion in 2026, reaching USD 33.01 Billion by 2034, exhibiting a CAGR of 23.84% during 2026-2034. The market is projected to reach an anchor value of USD 14.04 Billion by 2030, representing the mid-period milestone at which Vision 2030 infrastructure investments achieve operational maturity and platform-integrated logistics capture mainstream B2C parcel volumes across the Kingdom.
Three structural forces will define the Saudi Arabia e-commerce shipping market through 2034. First, Vision 2030's logistics infrastructure investment will compress delivery costs, expand rural reach, and integrate Saudi Arabia into global trade networks at unprecedented scale. Second, demographic momentum from Saudi Arabia's young, digitally native population will sustain high e-commerce adoption rates and delivery frequency well beyond the forecast horizon. Third, technology innovation from AI routing, autonomous vehicles, and drone delivery will progressively expand the market's addressable scope by enabling economically viable delivery to previously underserved geographies and consumer segments across the Kingdom.
Research Methodology
Primary Research
Primary research comprised in-depth interviews with Saudi e-commerce logistics executives, last-mile delivery operations managers, e-commerce platform supply chain directors, Saudi Customs Authority representatives, and Vision 2030 logistics project leads. These discussions validated market size estimates, segment demand dynamics, carrier competitive positioning, and technology adoption trajectories for the 2026-2034 forecast period.
Secondary Research
Secondary research encompassed Saudi Customs Authority trade statistics, Saudi e-payment volume data, IMARC Group proprietary logistics databases, annual reports and press releases of key market participants, and industry publications covering Saudi e-commerce and logistics market developments through 2025.
Forecasting Models
Forecasting models incorporated historical e-commerce GMV growth correlations with shipping volume, Vision 2030 infrastructure investment disbursement schedules, technology adoption curves for AI routing and EV fleets, demographic drivers of e-commerce penetration, and macroeconomic indicators. Both bottom-up parcel volume modeling and top-down revenue projection approaches were cross-validated for forecast consistency across all segments and regions.
Saudi Arabia E-commerce Shipping Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Services Covered |
|
| Businesses Covered | B2B, B2C |
| Destinations Covered | Domestic, International/Cross Border |
| End-Use Industries Covered | Fashion and Apparel, Consumer Electronics, Home Appliances, Furniture, Beauty and Personal Care Products, Others |
| Regions Covered | Northern and Central Region, Western Region, Eastern Region, Southern Region |
| Companies Covered | Saudi Post | SPL, DHL Group, FedEx, United Parcel Service of America, Inc., J&T Express, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Saudi Arabia e-commerce shipping market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Saudi Arabia e-commerce shipping market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Saudi Arabia e-commerce shipping industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Saudi Arabia E-commerce Shipping Market Report
The Saudi Arabia e-commerce shipping market reached USD 5.97 Billion in 2026, driven by Vision 2030 logistics investment, rising B2C e-commerce demand, and improving cross-border customs clearance.
The Saudi Arabia e-commerce shipping market is projected to grow at a CAGR of 23.84% during 2026-2034, making it one of the fastest-growing logistics markets, supported by digital commerce expansion and government infrastructure mandates under Vision 2030.
The market is projected to reach USD 14.04 Billion by 2030, representing the mid-period milestone reflecting Vision 2030 infrastructure maturity, platform-integrated logistics mainstream adoption, and expanded rural delivery reach across all Saudi regions.
B2C leads with a 74.6% share in 2025, through consumer-facing platforms driving tens of millions of annual parcel deliveries, supported by high mobile commerce penetration of all online orders.
Fashion & apparel leads with a 31.5% share in 2025, fueled by social commerce platforms, influencer-driven buying behavior, and expanding online fashion participation among Saudi consumers, generating both primary delivery and reverse logistics demand at low return rates.
The Northern & Central region leads with a 48.2% share in 2025, anchored by Riyadh's population density, corporate concentration, and the Kingdom's highest e-commerce order volumes per capita, supported by extensive logistics infrastructure investment.
Key players include Saudi Post | SPL, DHL Group, FedEx, United Parcel Service of America, Inc., and J&T Express, among others.
The Saudi Arabia e-commerce shipping market is projected to reach USD 33.01 Billion by 2034, driven by sustained e-commerce GMV growth, Vision 2030 infrastructure completion, drone and autonomous delivery commercialization, and cross-border trade expansion.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade