
Saudi Arabia E-commerce Warehousing Market Size, Share, Trends and Forecast by Product, Business Type, Component, and Region, 2026-2034
Saudi Arabia E-commerce Warehousing Market Size, Share, Trends & Forecast (2026-2034)
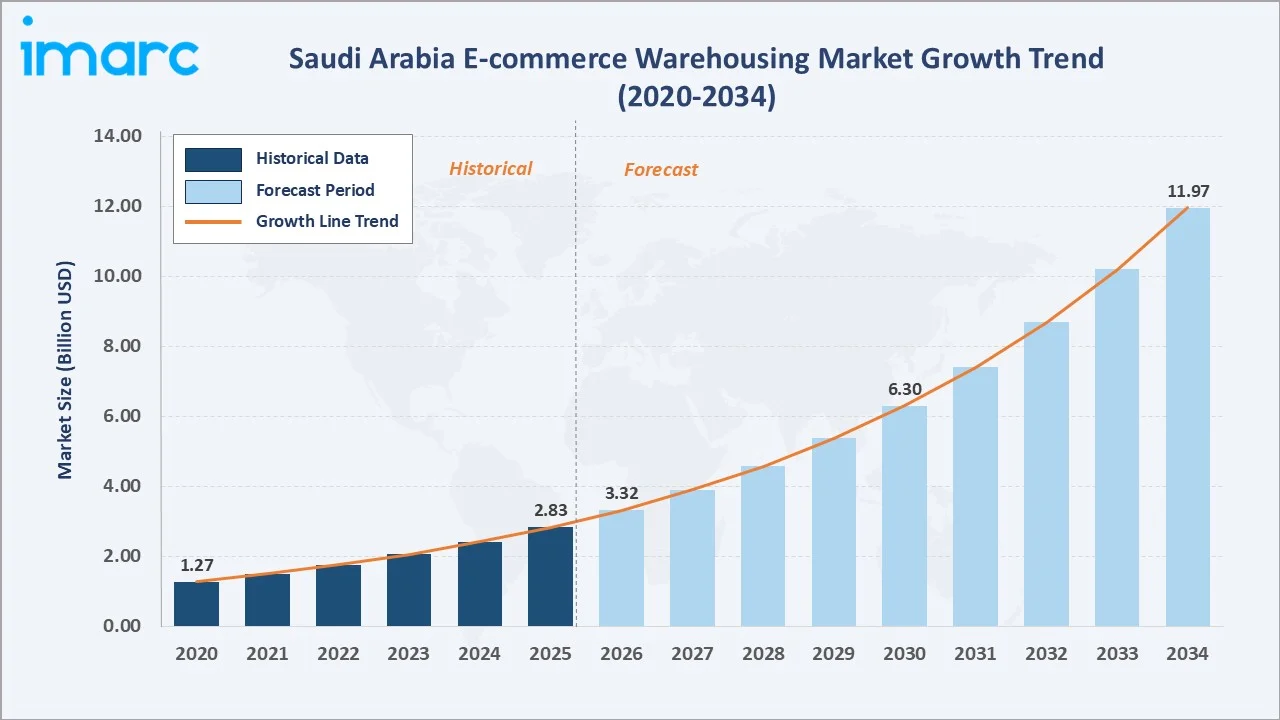
The Saudi Arabia e-commerce warehousing market grew from USD 2.83 Billion in 2025 to USD 3.32 Billion in 2026 and is projected to reach USD 11.97 Billion by 2034, exhibiting a CAGR of 17.39% during 2026-2034. The market is driven by surging e-commerce adoption, Vision 2030 logistics infrastructure investment, and growing demand for last-mile fulfilment solutions across the Kingdom.
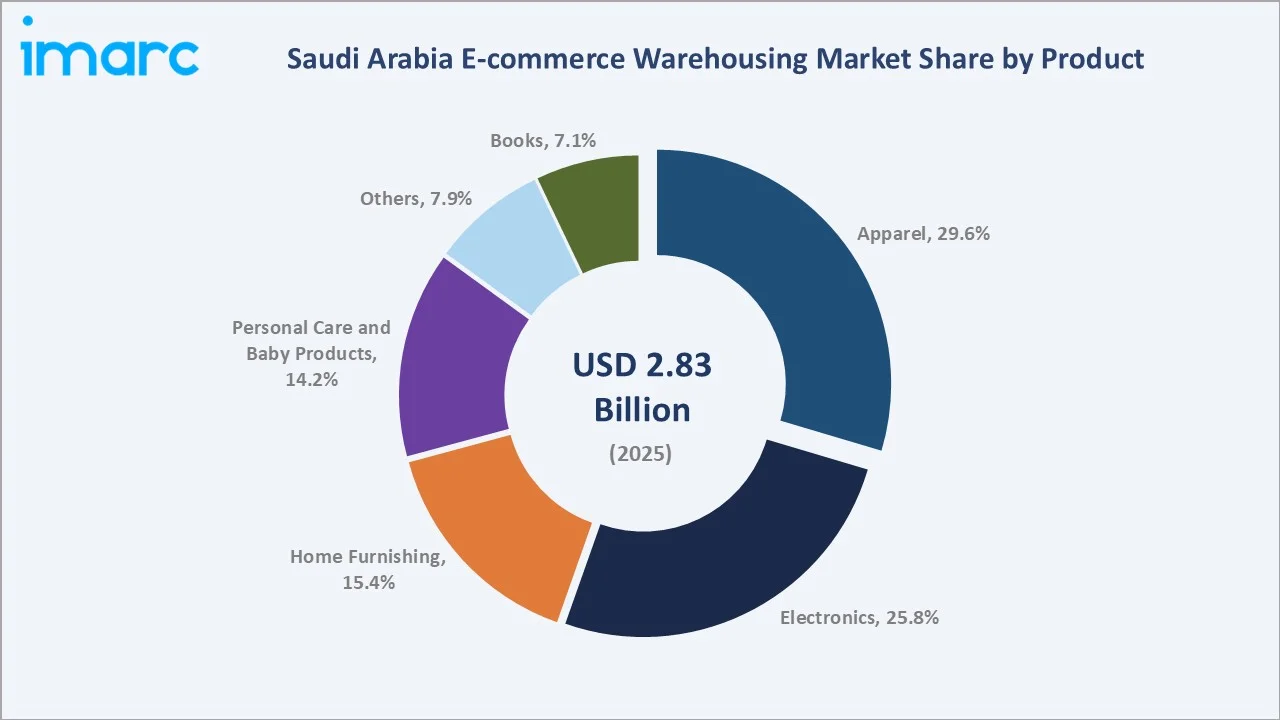
Apparel leads the product segment at 29.6%, B2C dominates the business type at 76.4%, and Northern and Central Region commands 48.2% market share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 2.83 Billion |
|
Market Size (2026) |
USD 3.32 Billion |
|
Forecast Market Size (2034) |
USD 11.97 Billion |
|
CAGR (2026-2034) |
17.39% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Largest Region |
Northern and Central Region (48.2%, 2025) |
|
Second Largest Region |
Western Region (23.5%, 2025) |
|
Leading Product |
Apparel (29.6%, 2025) |
|
Leading Business Type |
B2C (76.4%, 2025) |
The Saudi Arabia e-commerce warehousing market size increased from USD 1.27 Billion in 2020 to USD 2.83 Billion in 2025 and is estimated to reach USD 3.32 Billion in 2026. The market is further expected to grow to USD 6.30 Billion by 2030 and USD 11.97 Billion by 2034. Market expansion has demonstrated consistency across both historical and forecast phases. The accelerated momentum in the 2026-2034 window is supported by accelerating cross-border trade, rising domestic e-commerce penetration, and sustained government-led infrastructure investment.
To get more information on this market, Request Sample
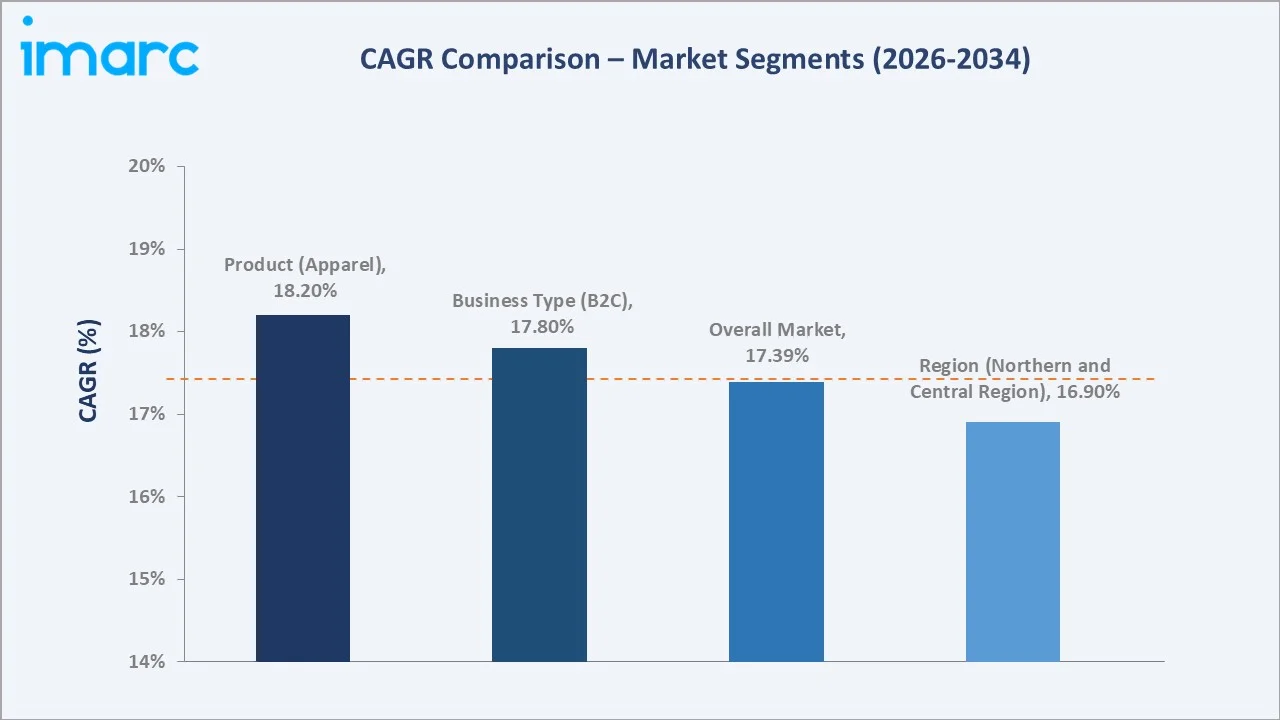
CAGR trajectories across product and business type sub-segments, together with regional patterns, show apparel and Southern Region expanding faster than the overall 17.39% market CAGR, driven by a lower base effect, accelerating e-commerce adoption in underserved areas, and rising fulfilment infrastructure investment across high-growth corridors.
Executive Summary
The Saudi Arabia e-commerce warehousing market expanded from USD 2.83 Billion in 2025 to an estimated USD 3.32 Billion in 2026. The market expansion is anchored by the Kingdom's accelerating digital commerce adoption, supported by a young, tech-savvy population and widespread smartphone usage.
Apparel holds the leading product-level share at 29.6% in 2025, reflecting frequent online purchases, broad product variety, and the need for efficient warehousing and fulfillment to manage diverse sizes, styles, and seasonal inventory. B2C dominates business type at 76.4%, reflecting the consumer-centric nature of e-commerce growth in the Kingdom. Northern and Central Region commands 48.2% of regional demand, anchored by Riyadh's position as the country's commercial and logistical nerve center.
Key Market Insights
|
Insight |
Data |
|
Leading Product |
Apparel – 29.6% share (2025) |
|
Second Largest Product |
Electronics – 25.8% share (2025) |
|
Leading Business Type |
B2C – 76.4% share (2025) |
|
Second Largest Business Type |
B2B – 23.6% share (2025) |
|
Leading Region |
Northern and Central Region – 48.2% share (2025) |
|
Second Largest Region |
Western Region – 23.5% share (2025) |
|
Top Companies |
Saudi Post, Aramex PJSC, DHL AG, Amazon.com, Inc. |
Key Analytical Observations Expanding On the Data Above:
- Apparel dominance at 29.6% is supported by fast fashion cycles, high product return rates, and the need for dedicated fulfilment centers with advanced SKU management and reverse logistics capabilities.
- Electronics at 25.8% is driven by premium consumer electronics adoption and growing demand for white-glove delivery and specialized warehousing environments.
- B2C leadership at 76.4% reflects the rapid adoption of online retail platforms and marketplace models, including local and international players expanding their Saudi footprint.
- B2B at 23.6% remains significant, driven by wholesale distributors, medical supplies logistics, and industrial goods players requiring bulk storage and freight-optimized facilities.
- Northern and Central Region at 48.2% is supported by Riyadh's dense consumer base, superior road infrastructure, and concentration of major distribution hubs serving the broader GCC.
Saudi Arabia E-commerce Warehousing Market Overview
E-commerce warehousing refers to the specialized storage, inventory management, order fulfilment, and dispatch operations that support online retail transactions. In Saudi Arabia, this encompasses a broad ecosystem spanning consumer goods, electronics, fashion, food and beverage, and cross-border merchandise categories.
The Saudi ecosystem integrates technology providers, logistics operators, regulatory authorities, payment gateways, and fulfilment specialists. The sector is increasingly focused on improving inventory visibility, order processing efficiency, and delivery coordination to support rising online retail activity.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
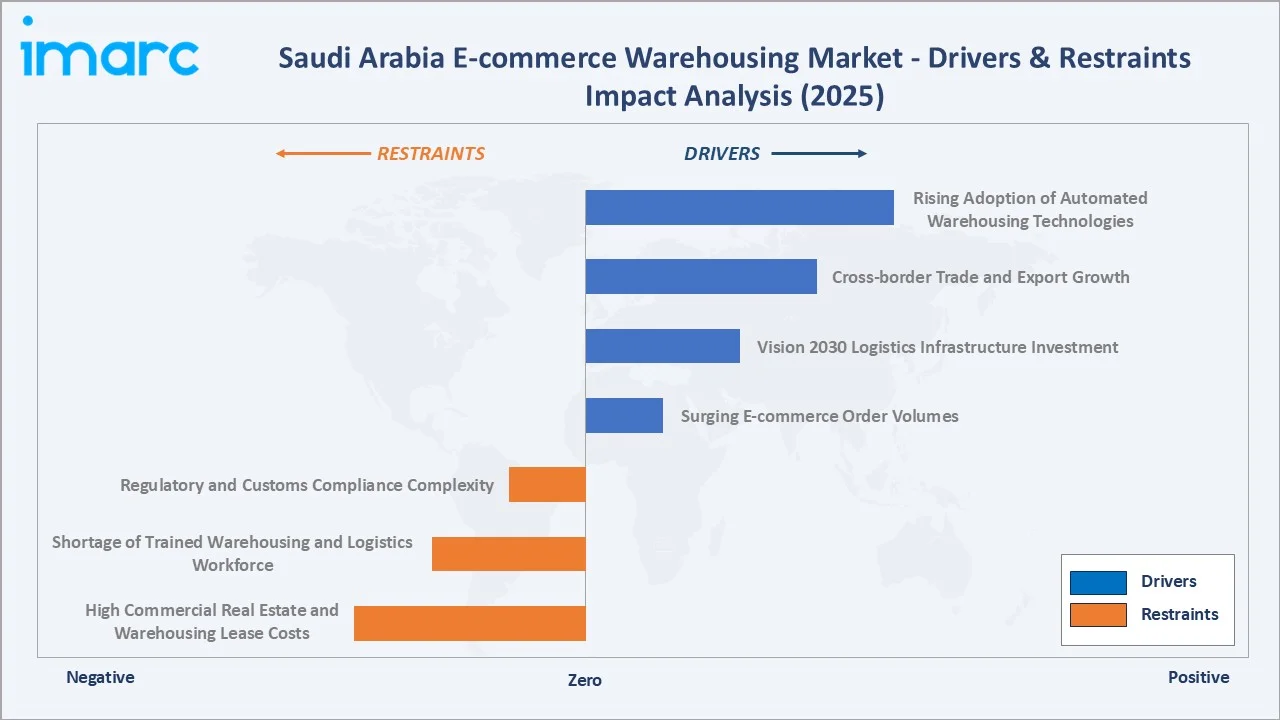
- Surging E-commerce Order Volumes: Rising online shopping activity is increasing the number of orders requiring storage, picking, packing, and dispatch across the country. As per IMARC Group, the Saudi Arabia e-commerce market grew from USD 251.3 Billion in 2025 to USD 290.8 Billion in 2026. Higher order frequency is encouraging businesses to expand warehousing capacity and improve fulfillment capabilities.
- Vision 2030 Logistics Infrastructure Investment: Ongoing investments under Vision 2030 are strengthening logistics infrastructure, distribution networks, and warehouse facilities across Saudi Arabia. Improved connectivity and logistics capabilities are supporting the development of more efficient e-commerce fulfillment networks.
- Cross-border Trade and Export Growth: Growing demand for Saudi products internationally and the importation of global consumer goods are driving dedicated bonded and cross-border warehousing capacity, particularly near major ports and customs-clearance zones.
- Rising Adoption of Automated Warehousing Technologies: Increasing deployment of automated storage and retrieval systems, conveyor lines, and warehouse management system (WMS) platforms is improving fulfilment efficiency and reducing per-unit operating costs.
Market Restraints
- High Commercial Real Estate and Warehousing Lease Costs: Premium logistics real estate in Riyadh and Jeddah commands elevated lease rates, creating cost pressures for smaller e-commerce operators seeking compliant and well-located fulfilment space.
- Shortage of Trained Warehousing and Logistics Workforce: Despite Saudization policies, a persistent gap in trained logistics professionals continues to constrain operational scale-up for some operators.
- Regulatory and Customs Compliance Complexity: Evolving import and customs regulations, including mandatory product labelling requirements and halal certification norms, add layers of operational complexity and cost to warehousing and fulfilment processes.
Market Opportunities
- Development of Dedicated E-commerce Logistics Parks: Government-supported logistics zone development around King Salman Energy Park and NEOM provides significant opportunity for purpose-built e-commerce warehousing clusters with advanced infrastructure.
- Cold Chain Expansion for Grocery and Healthcare E-commerce: Rising online grocery delivery and pharmaceutical e-commerce adoption is creating demand for temperature-controlled warehousing, a segment that remains significantly underdeveloped relative to overall e-commerce growth.
Market Challenges
- Last-Mile Delivery Complexity in Low-Density Areas: Serving outlying and rural communities in a geographically vast country adds operational cost and complexity to fulfilment operations, challenging the unit economics of e-commerce delivery beyond major urban centers.
- Scalability and Real-Time Inventory Visibility: As order volumes grow rapidly, maintaining real-time stock accuracy across multiple fulfilment points and integrating with diverse e-commerce platform APIs remain persistent operational challenges for warehouse operators.
Emerging Market Trends
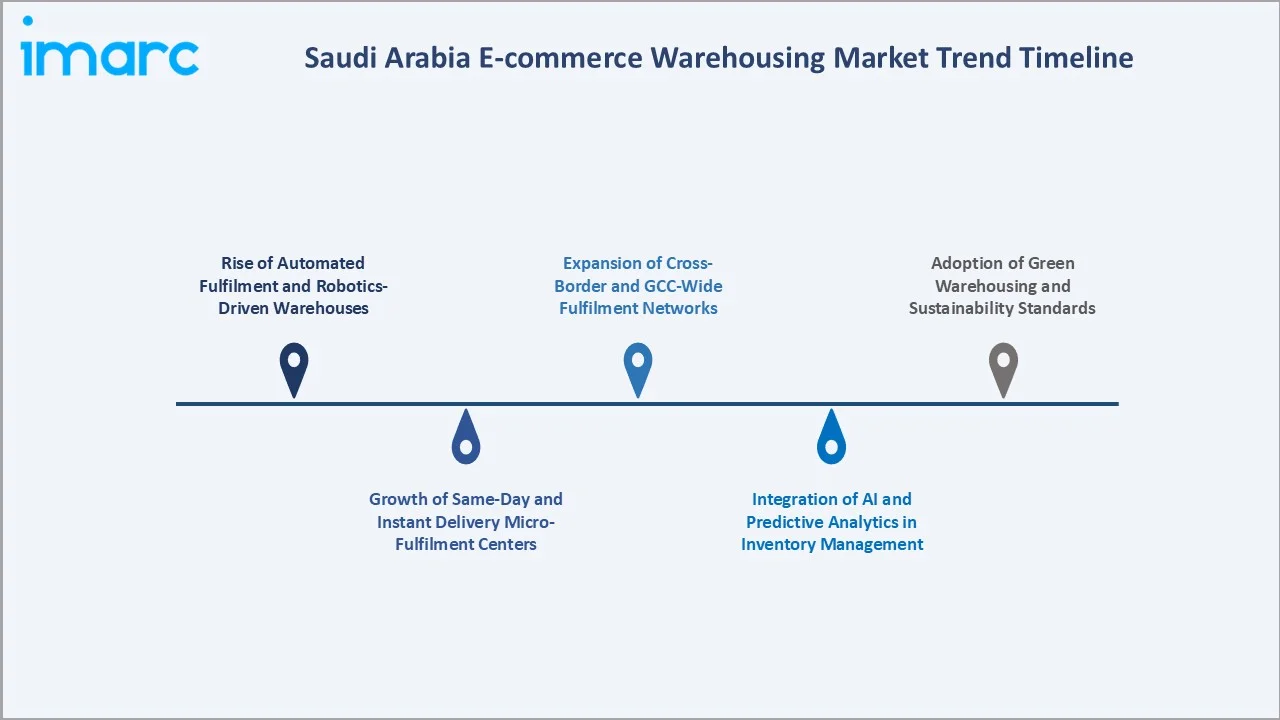
1. Rise of Automated Fulfilment and Robotics-Driven Warehouses
E-commerce operators and 3PL providers in Saudi Arabia are increasingly integrating robotic picking, automated conveyor systems, and goods-to-person technology into their fulfilment facilities. This reduces labor dependency and improves throughput, particularly during peak retail periods such as Ramadan and White Friday shopping events.
2. Growth of Same-Day and Instant Delivery Micro-Fulfilment Centers
Consumer expectations for ultra-fast delivery windows are driving the proliferation of urban micro-fulfilment centers located within densely populated city districts. These smaller, technology-dense facilities allow e-commerce platforms to promise same-day or two-hour delivery windows to customers in Riyadh, Jeddah, and Dammam.
3. Integration of AI and Predictive Analytics in Inventory Management
AI and machine learning (ML) tools are being adopted across Saudi warehousing operations to improve demand forecasting, replenishment planning, and seasonal inventory positioning. These technologies help reduce overstock and stockout situations, directly improving fulfilment accuracy and customer satisfaction.
4. Expansion of Cross-Border and GCC-Wide Fulfilment Networks
Saudi-based e-commerce operators and logistics providers are expanding their warehousing footprints to serve neighboring GCC markets, leveraging proximity and customs streamlining under the GCC Free Trade Agreement to offer competitive delivery timelines across the broader region.
5. Adoption of Green Warehousing and Sustainability Standards
Growing corporate sustainability commitments are driving investment in energy-efficient warehouse designs, LED lighting retrofits, solar panel integration, and electric last-mile delivery fleets. Several logistics operators have announced net-zero logistics targets aligned with the Kingdom's own carbon neutrality ambitions.
Industry Value Chain Analysis
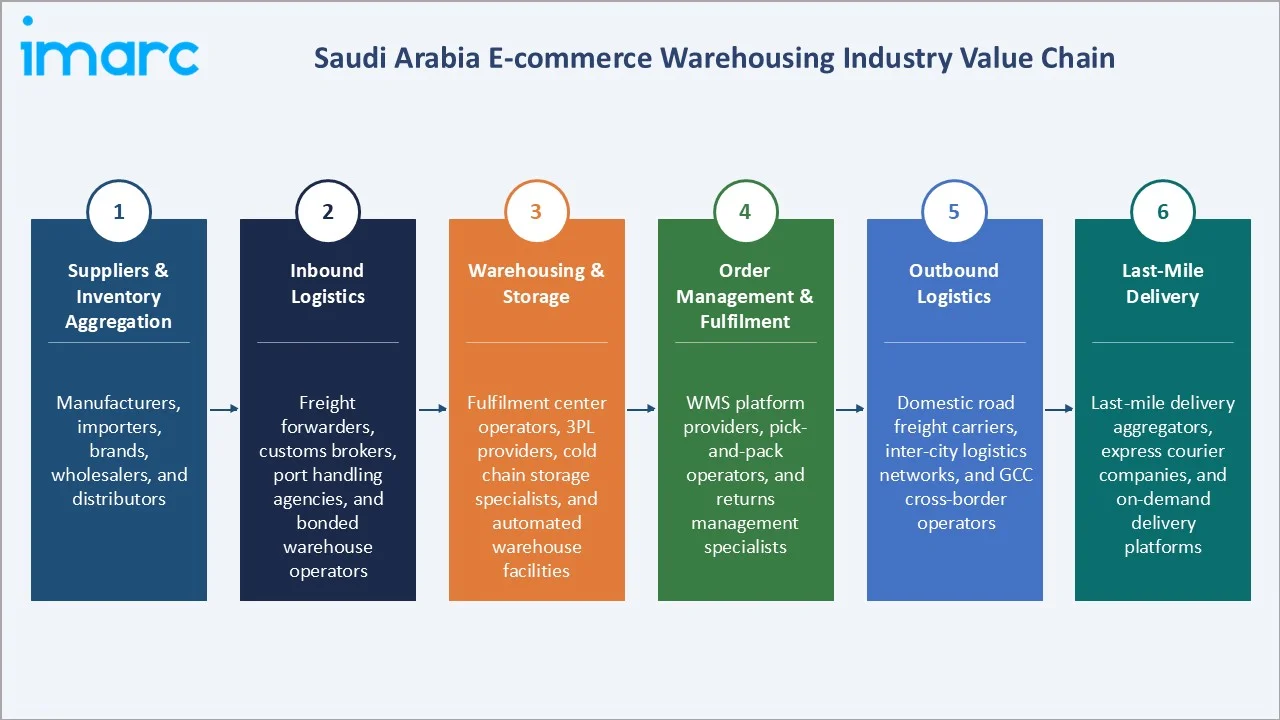
The Saudi Arabia e-commerce warehousing value chain spans six core stages, from upstream suppliers and inventory aggregation through consumer delivery and lifecycle support. Each stage integrates technology, physical infrastructure, and compliance requirements that collectively define the market's operational complexity and value-creation dynamics.
|
Stage |
Key Players / Examples |
|
Suppliers & Inventory Aggregation |
Manufacturers, importers, brands, wholesalers, and distributors |
|
Inbound Logistics |
Freight forwarders, customs brokers, port handling agencies, and bonded warehouse operators |
|
Warehousing & Storage |
Fulfilment center operators, 3PL providers, cold chain storage specialists, and automated warehouse facilities |
|
Order Management & Fulfilment |
WMS platform providers, pick-and-pack operators, and returns management specialists |
|
Outbound Logistics |
Domestic road freight carriers, inter-city logistics networks, and GCC cross-border operators |
|
Last-Mile Delivery |
Last-mile delivery aggregators, express courier companies, and on-demand delivery platforms |
Vertically integrated logistics operators that control both warehousing and last-mile delivery assets are best positioned to capture margin across multiple stages of the chain. Pure-play warehousing providers that partner with specialized last-mile carriers can compete effectively in the middle stages.
Technology Landscape in the Saudi Arabia E-commerce Warehousing Industry
WMS Adoption
Cloud-based WMS platforms are enabling real-time inventory tracking, multi-channel order orchestration, and automated replenishment workflows. Leading platforms are increasingly integrating with Saudi e-commerce marketplaces via API to synchronize stock levels and fulfil orders with minimal manual intervention.
Robotics and Automation
Robotic picking systems, autonomous mobile robots for goods transport within warehouses, and automated sorting lines are being deployed by major 3PL providers and large e-commerce operators. These technologies reduce per-order picking costs and enable continuous 24-hour operation.
AI and Demand Forecasting
AI tools are increasingly used for SKU-level demand forecasting, dynamic slotting, and seasonal inventory pre-positioning. These capabilities directly reduce overstock risk and enable more efficient space utilization within fulfilment centers.
IoT and Real-Time Tracking
IoT sensors embedded in warehouse environments monitor temperature, humidity, and asset location in real time. Cold chain e-commerce operators rely on these systems to maintain product integrity for food, pharmaceuticals, and beauty products throughout the storage and dispatch cycle.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Product |
Apparel |
29.6% |
2025 |
|
Business Type |
B2C |
76.4% |
2025 |
|
Component |
🔒 |
🔒 |
2025 |
|
Region |
Northern and Central Region |
48.2% |
2025 |

By Product
Apparel commands a 29.6% majority share in 2025, driven by high order frequency, seasonal demand variability, and the complexity of size and color SKU management that requires sophisticated fulfilment infrastructure. Fashion e-commerce in Saudi Arabia has benefited from rising female workforce participation and changing social norms that have broadened the consumer base for online fashion purchases.
To access detailed market analysis, Request Sample
Electronics holds the second position at 25.8%, reflecting Saudi Arabia's strong consumer appetite for smartphones, laptops, gaming equipment, and smart home devices. The segment demands specialized storage environments and careful inventory management due to high product value and theft risk.
By Business Type
B2C dominates with a 76.4% share, reflecting the consumer-facing nature of e-commerce in Saudi Arabia. The B2C segment is driven by marketplace platforms, direct-to-consumer brand websites, and social commerce channels that generate high-frequency, small-parcel fulfilment requirements across the country.
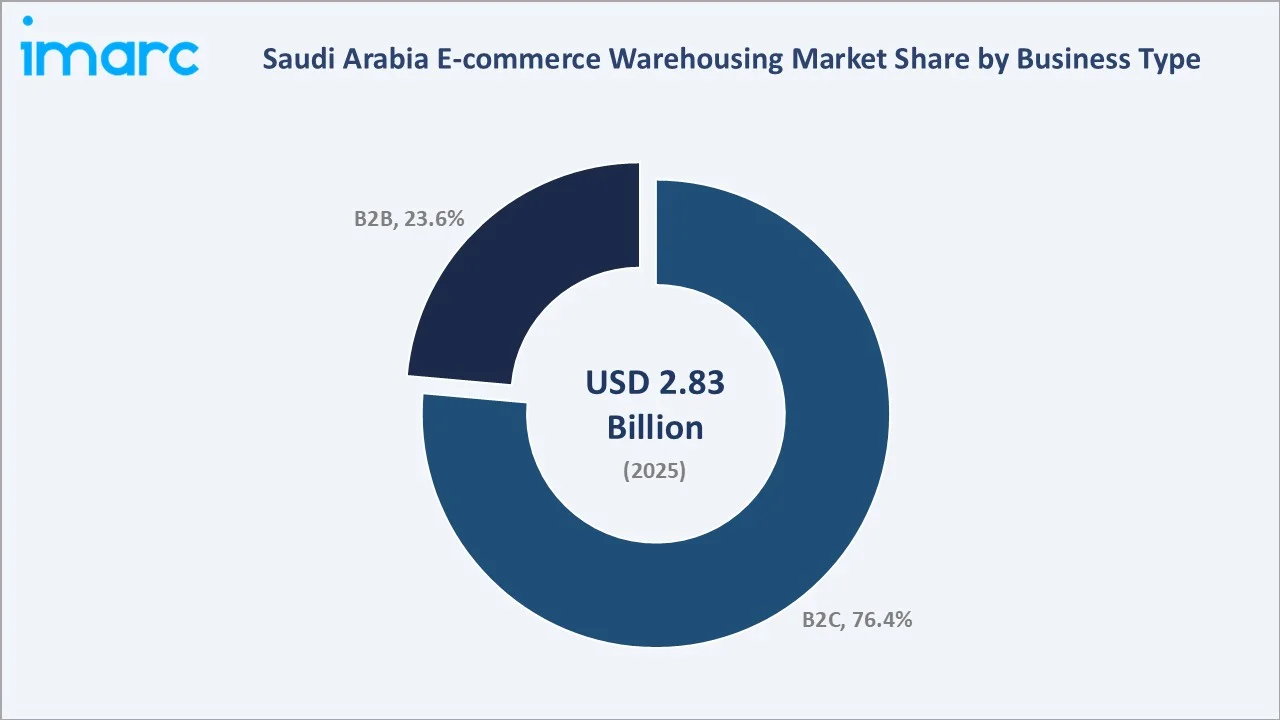
B2B at 23.6% serves wholesale buyers, institutional procurement teams, and business supply chains. This segment is characterized by larger average order volumes, pallet-level storage requirements, and lower order frequency compared to B2C. B2B e-commerce adoption is accelerating in the Kingdom, particularly in industrial supplies, office equipment, and healthcare categories.
Regional Market Insights
|
Region |
Share (2025) |
Key Growth Drivers |
|
Northern and Central Region |
48.2% |
Large consumer population, concentration of logistics hubs, strong road infrastructure, and Riyadh's commercial dominance |
|
Western Region |
23.5% |
Major port access via Jeddah, high tourist traffic, growing retail base, and proximity to Red Sea trade routes |
|
Eastern Region |
18.1% |
Industrial and energy sector activity, port infrastructure, and growing consumer base in Dammam and Al Khobar |
|
Southern Region |
10.2% |
Expanding population centers, improving road connectivity, and increasing digital payment adoption |
Northern and Central Region holds 48.2% share in 2025, anchored by Riyadh's status as the country's commercial capital and the epicentre of consumer demand, logistics infrastructure, and e-commerce platform operations.
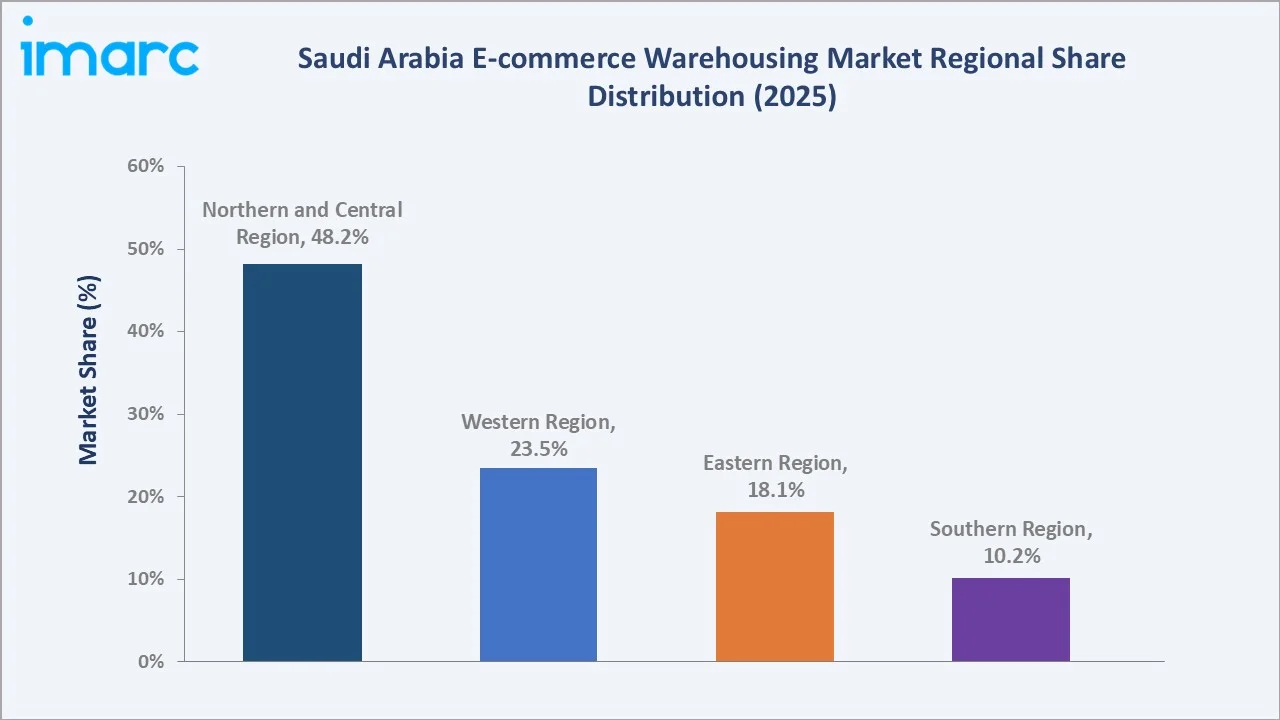
Western Region holds 23.5% in 2025, supported by Jeddah's historic role as the Kingdom's primary seaport gateway and its large consumer market. The region is a critical entry point for imported goods and hosts major 3PL fulfilment hubs serving both domestic consumers and GCC export flows.
Competitive Landscape
The Saudi Arabia e-commerce warehousing market is moderately concentrated, with a mix of established logistics conglomerates, international 3PL providers, and emerging Saudi-founded last-mile specialists competing across fulfilment, storage, and delivery capabilities. The market is evolving rapidly as operators invest in technology integration, multi-city fulfilment networks, and specialized vertical warehousing solutions.
|
Company Name |
Brand / Key Product |
Position |
Strategic Focus |
|
Saudi Post |
Naqel Express |
Leader |
Expanding domestic fulfilment network and e-commerce logistics capabilities across Saudi Arabia |
|
Aramex PJSC |
Aramex Shop & Ship |
Leader |
Scaling cross-border e-commerce logistics and last-mile delivery across the GCC |
|
DHL AG |
DHL Fulfillment |
Leader |
Strengthening technology-driven warehousing and integrated supply chain solutions |
|
Amazon.com, Inc. |
Amazon FBA |
Challenger |
Expanding proprietary fulfilment center network and same-day delivery capabilities |
Key players include Saudi Post, Aramex PJSC, DHL AG, and Amazon.com, Inc., among others.
Key Company Profiles
Saudi Post
Saudi Post is the national postal and logistics services provider of Saudi Arabia, headquartered in Riyadh. The company operates an extensive domestic network covering all regions of the Kingdom and has strategically expanded its e-commerce fulfilment and last-mile delivery capabilities to serve the rapidly growing domestic online retail sector.
- Product Portfolio: Integrated e-commerce logistics platform covering parcel delivery, fulfilment center operations, return management, and B2B freight services.
- Recent Developments: Saudi Post continues to strengthen its logistics network and enhance its service offerings across the Kingdom, investing in infrastructure and technology to support growing e-commerce demand.
- Strategic Focus: Broadening its nationwide fulfilment network to deliver faster, more reliable e-commerce logistics services to businesses and consumers across all regions of Saudi Arabia.
Aramex PJSC
Aramex PJSC is a leading global provider of logistics and transportation solutions headquartered in Dubai, UAE, with a significant and expanding operational presence across Saudi Arabia. The company serves e-commerce, retail, and corporate clients across the GCC and beyond through its integrated domestic and international logistics network.
- Product Portfolio: Cross-border e-commerce delivery, domestic last-mile logistics, Shop & Ship international shopping service, and warehousing and fulfilment solutions.
- Recent Developments: Aramex PJSC continues to invest in its logistics network and delivery infrastructure across Saudi Arabia, enhancing its operational capabilities and service coverage to meet growing e-commerce demand in the Kingdom.
- Strategic Focus: Deepening its logistics presence across Saudi Arabia by growing cross-border e-commerce delivery capabilities and strengthening last-mile connectivity throughout the GCC.
DHL AG
DHL AG is the publicly listed parent company of the DHL Group, one of the world's largest logistics organizations. In Saudi Arabia, DHL AG's Supply Chain division operates integrated warehouse management, value-added services, and distribution solutions for major retail, e-commerce, and industrial clients.
- Product Portfolio: Contract logistics, warehouse management, e-commerce fulfilment, cold chain services, and supply chain technology integration.
- Recent Developments: DHL AG continues to expand its logistics footprint and warehousing capabilities in Saudi Arabia, supporting the Kingdom's growing e-commerce sector and logistics infrastructure development objectives.
- Strategic Focus: Advancing its warehousing and supply chain capabilities in the Kingdom by deploying technology-driven logistics solutions tailored to the needs of e-commerce and retail operators.
Market Concentration Analysis
The Saudi Arabia e-commerce warehousing market is moderately concentrated, with the top four operators accounting for a substantial share of total fulfilment center capacity and e-commerce logistics revenue.
Barriers to entry include high capital requirements for warehouse construction or long-term lease commitments, the need for technology integration with major e-commerce platforms, and the operational complexity of managing multi-city last-mile delivery networks. These barriers favor established operators and limit rapid market entry by smaller players.
Consolidation is gradually increasing as major 3PL providers acquire regional courier and storage operators to broaden their Saudi fulfilment capabilities. The trend toward vertical integration, where operators control warehousing, sorting, and last-mile delivery within a single service offering, is gaining momentum among leading market participants.
Investment & Growth Opportunities
Fastest-Growing Segments
Apparel is expanding fastest among product categories, driven by rising female consumer participation in online fashion purchasing and a proliferation of fast fashion and international brand platforms entering the Saudi Arabia market.
Emerging Markets
Southern Region is the fastest growing regional market, benefiting from its comparatively smaller base, expanding population centers, and accelerating e-commerce infrastructure rollout into previously underserved areas. Eastern Region is also growing above the market average, with Dammam and Al Khobar attracting increasing logistics investment as industrial and consumer demand converges in the eastern corridor.
Venture & Investment Trends
Investment activity is concentrated in automated fulfilment infrastructure, cold chain warehousing, and technology-enabled last-mile logistics. Saudi sovereign wealth and private equity capital is increasingly flowing into logistics technology platforms, including WMS providers, delivery management software, and IoT-enabled warehouse monitoring solutions.
Future Market Outlook (2026-2034)
The Saudi Arabia e-commerce warehousing market is projected to grow from USD 2.83 Billion in 2025 to USD 3.32 Billion in 2026, reaching USD 11.97 Billion by 2034, registering a CAGR of 17.39% during 2026-2034.
Four forces will shape the market through 2034: continued e-commerce adoption across new consumer demographics; accelerating rollout of automated fulfilment technology by major operators; sustained government investment in logistics infrastructure under Vision 2030; and growing cross-border trade demand linking Saudi Arabia to GCC, Asian, and European markets.
By 2034, e-commerce warehousing in Saudi Arabia is expected to be characterized by AI-driven fulfilment networks, widespread same-day delivery coverage across all major cities, significant cold chain capacity expansion, and a growing share of B2B e-commerce driving new warehousing demand from industrial and healthcare sectors.
Research Methodology
Primary Research
Primary research included structured interviews with e-commerce fulfilment executives, logistics technology providers, 3PL operators, regulatory officials, and regional e-commerce platform managers. These interactions provided qualitative insights on market dynamics, competitive positioning, and near-term growth expectations.
Secondary Research
Secondary sources included Saudi Customs Authority reports, General Authority for Statistics publications, Ministry of Commerce trade data, National Transportation and Logistics Strategy documentation, industry associations, and publicly available financial disclosures from major listed logistics companies operating in the Kingdom.
Forecasting Models
Market forecasts used top-down and bottom-up modelling frameworks combining e-commerce transaction volume data, warehousing capacity utilization trends, logistics infrastructure investment pipelines, and macroeconomic indicators including GDP growth, consumer expenditure, and trade flow projections.
Saudi Arabia E-commerce Warehousing Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Products Covered | Electronics, Apparel, Home Furnishing, Personal Care and Baby Products, Books, Others |
| Business Types Covered | B2B, B2C |
| Components Covered | Hardware Equipment, Software |
| Regions Covered | Northern and Central Region, Western Region, Eastern Region, Southern Region |
| Companies Covered | Saudi Post, Aramex PJSC, DHL AG, Amazon.com, Inc., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Saudi Arabia e-commerce warehousing market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Saudi Arabia e-commerce warehousing market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Saudi Arabia e-commerce warehousing industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Saudi Arabia E-commerce Warehousing Market Report
The Saudi Arabia e-commerce warehousing market size is estimated at USD 3.32 Billion in 2026, driven by rising online retail activity, Vision 2030 logistics investments, and expanding last-mile delivery demand.
The market is projected to grow at a CAGR of 17.39% from 2026-2034, reaching USD 11.97 Billion, supported by e-commerce volume growth and warehousing automation adoption.
Apparel leads the product segment with a 29.6% share in 2025, driven by high order frequency, fashion e-commerce growth, and complex SKU management requirements across fulfilment operations.
B2C dominates the business type segment with a 76.4% share in 2025, reflecting strong consumer marketplace activity and direct-to-consumer brand growth in the Kingdom.
Northern and Central Region commands a 48.2% share in 2025, anchored by Riyadh's commercial infrastructure and consumer density.
Leading players include Saudi Post, Aramex PJSC, DHL AG, and Amazon.com, Inc., among others.
Robotics, automated sorting, and WMS platforms are improving order accuracy and throughput, reducing labor costs and enabling 24-hour fulfilment operations.
Key drivers include surging e-commerce order volumes, government logistics investment, cross-border trade growth, and rising consumer demand for fast delivery.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade