
Saudi Arabia Elderly Care Products Market Size, Share, Trends and Forecast by Product, Usage, End User, and Region, 2026-2034
Saudi Arabia Elderly Care Products Market Size, Share, Trends & Forecast (2026-2034)
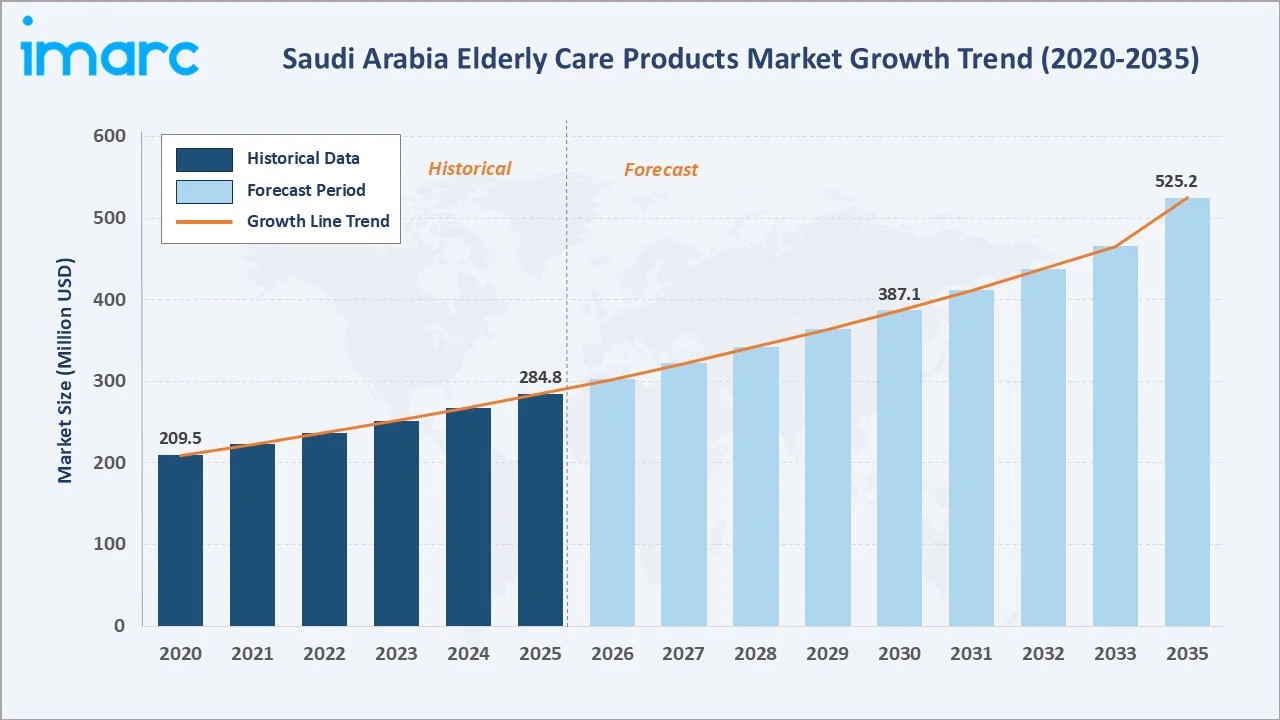
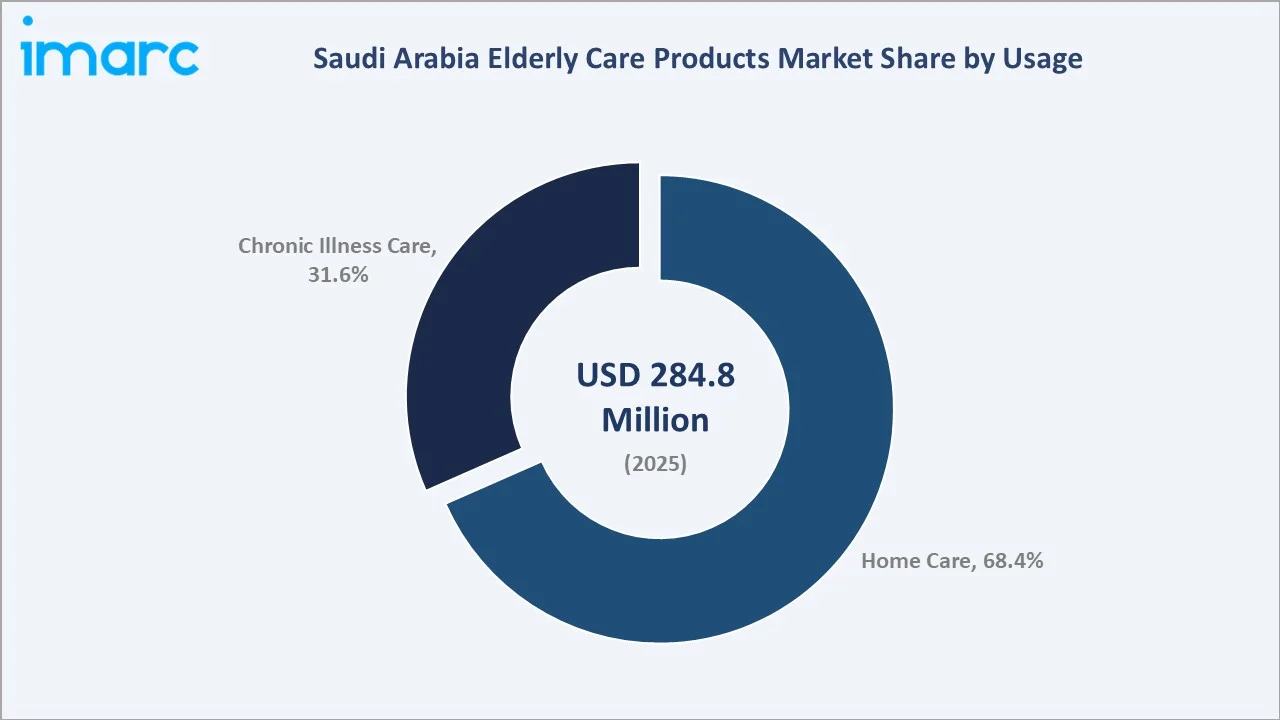
The Saudi Arabia elderly care products market reached USD 284.8 Million in 2025 and is projected to reach USD 525.2 Million by 2034, growing at a CAGR of 6.33% during 2026-2034. Growth rests on a rapidly expanding senior population and sustained Vision 2030 healthcare investment. GASTAT reported that residents aged 65 and above numbered close to 988,000 in 2024, out of a total population of 35.3 million. Home care dominates usage at 68.4% share. Home health care leads end-user demand at 46.3%. The Western Region leads regionally at 35.7%.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 284.8 Million |
|
Forecast Market Size (2034) |
USD 525.2 Million |
|
CAGR (2026-2034) |
6.33% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Largest Usage Segment |
Home Care (68.4%, 2025) |
|
Largest End User Segment |
Home Health Care (46.3%, 2025) |
|
Dominant Region |
Western Region (35.7%, 2025) |
The market expanded from USD 209.5 Million in 2020 to USD 284.8 Million in 2025. It is anchored at USD 387.1 Million in 2030 and forecast to reach USD 525.2 Million by 2034. Growth accelerates through the decade as home healthcare licensing widens and disposable incomes among family caregivers rise.
To get more information on this market, Request Sample
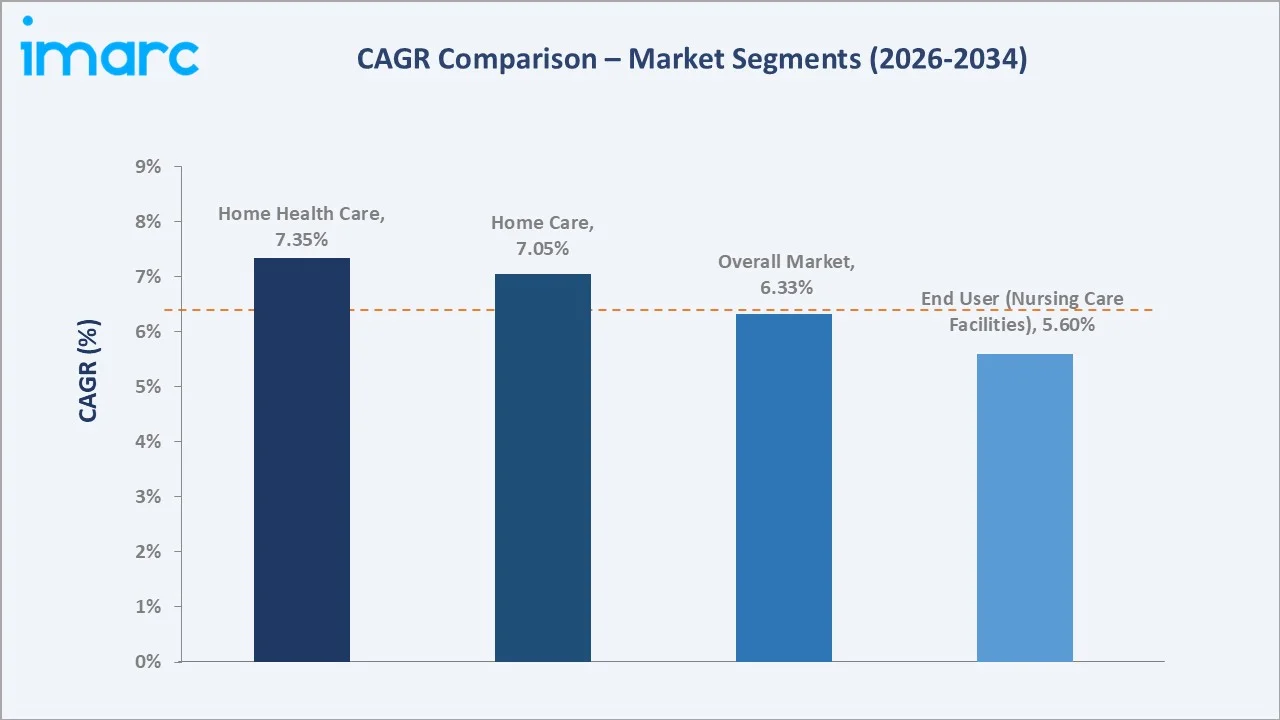
Home health care grows fastest among end-user categories at roughly 7.35% CAGR (2026-2034), supported by an expanding base of Ministry of Health-licensed home healthcare establishments. Home care as a usage category advances at about 7.05% CAGR against 4.75% for chronic illness care, reflecting the Kingdom's policy shift toward ageing-in-place models.
Executive Summary
The Saudi Arabia elderly care products market reached USD 284.8 Million in 2025. The market is demand-driven by demographic transition rather than by a large existing base. GASTAT recorded just 2.8% of the population aged 65 and above in 2024, yet this cohort is expanding faster than any other age bracket as life expectancy climbs toward 76.91 years. The market is projected to reach USD 525.2 Million by 2034 at a 6.33% CAGR, among the faster-growing healthcare product categories in the Gulf.
Home care commands 68.4% of the 2025 market as families increasingly favour in-home mobility aids, incontinence products and monitoring devices over institutional placement. Home health care represents 46.3% of end-user demand, ahead of hospital at 34.8% and nursing care facilities at 18.9%. The Western Region leads at 35.7%, followed closely by the Northern and Central Region at 32.4%.
Vision 2030's USD 65 Billion healthcare infrastructure commitment, rising chronic disease prevalence and growing private-sector participation in home healthcare licensing are expected to sustain double-digit growth pockets through 2034, even as the overall senior population base remains proportionally small.
Key Market Insights
|
Insight |
Data |
|
Largest Usage Segment |
Home Care - 68.4% share (2025) |
|
Leading End User |
Home Health Care - 46.3% share (2025) |
|
Fastest Growing End User |
Home Health Care - ~7.35% CAGR (2026-2034) |
|
Dominant Region |
Western Region - 35.7% share (2025) |
|
Market Opportunity |
AI-enabled remote monitoring and smart mobility devices |
Key Analytical Observations Supporting the Above Data:
- Home Care leads at 68.4% share (2025) on ageing-in-place preference: GASTAT data shows only 2.8% of residents are aged 65 and above, so families largely manage elderly relatives at home rather than in institutional settings, sustaining demand for in-home mobility and monitoring products.
- Chronic Illness Care holds 31.6% on rising non-communicable disease burden: GASTAT's Health Status Statistics Publication 2024 put diagnosed diabetes prevalence at approximately 9.1% among adults, a chronic-disease base that anchors demand for monitoring devices and daily-living aids.
- Home Health Care is the dominant end user at 46.3%: Ministry of Health licensing of home healthcare providers has widened under Vision 2030, allowing families to access professional caregiving support without hospital admission.
- Hospital demand at 34.8% reflects tertiary-care referral patterns: Government and private hospitals remain the first point of contact for acute geriatric complications, sustaining institutional procurement of mobility and monitoring equipment.
- Western Region leads at 35.7% on population density and healthcare infrastructure: Jeddah, Makkah and Madinah concentrate hospital capacity and private distributor networks that support elderly care product availability.
- Regulatory compliance shapes market entry: All medical devices require Medical Device Marketing Authorization (MDMA) from the Saudi Food and Drug Authority (SFDA), which favours established manufacturers with dedicated in-country authorized representatives.
Saudi Arabia Elderly Care Products Market Overview
The Saudi Arabia elderly care products market covers mobility aids, incontinence and personal hygiene products, patient monitoring devices, hospital beds and daily-living aids used across home, hospital and nursing-care settings. Supply is largely import-driven, sourced from manufacturers in the United States, Europe and China through SFDA-licensed distributors. End use spans home healthcare providers, government and private hospitals, nursing care facilities and family caregivers. Products fall under SFDA oversight, which requires Medical Device Marketing Authorization before commercial distribution. Macroeconomic influences include Vision 2030 diversification, an USD 65 Billion healthcare infrastructure commitment and a resident population GASTAT placed at 35.3 million in 2024, with seniors aged 65 and above still just 2.8% of the total but rising steadily.
Market Dynamics
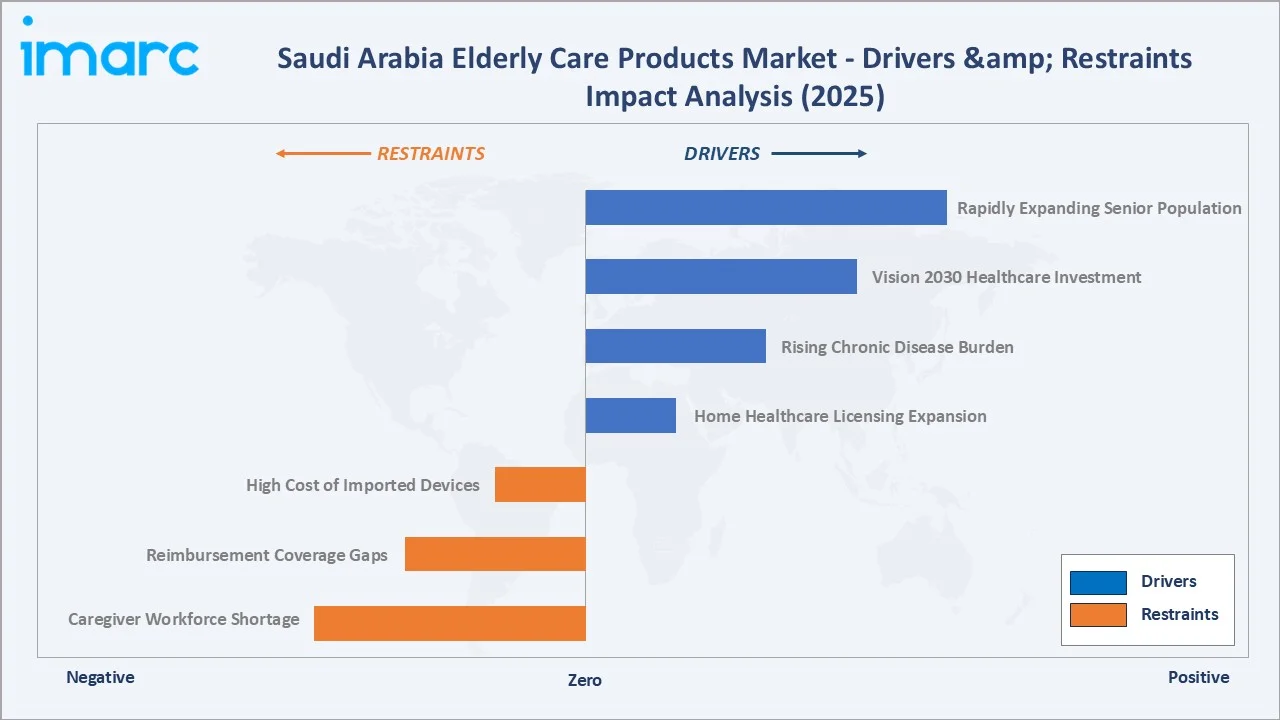
Growth in the Saudi Arabia elderly care products industry is shaped by an accelerating senior population and expanding home healthcare licensing, offset by high import costs and a constrained geriatric caregiving workforce.
To access detailed market analysis, Request Sample
Market Drivers
- Rapidly Expanding Senior Population: GASTAT recorded close to 988,000 residents aged 65 and above in 2024, and rising life expectancy of 76.91 years is set to widen this base steadily through 2034.
- Vision 2030 Healthcare Investment: The Ministry of Health has committed over USD 65 Billion toward healthcare infrastructure, with private-sector participation targeted to rise from 40% to 65%.
- Rising Chronic Disease Burden: GASTAT's Health Status Statistics Publication 2024 reported approximately 9.1% diagnosed diabetes prevalence among adults, sustaining demand for monitoring and daily-living support products.
- Home Healthcare Licensing Expansion: Baraya Extended Care secured USD 124 Million in funding in July 2025 to expand long-term care facilities and home health service offerings across the Kingdom.
Market Restraints
- High Cost of Imported Devices: Near-total reliance on imported mobility and monitoring equipment exposes distributors to freight and currency risk, while SFDA MDMA documentation adds compliance cost per product.
- Caregiver Workforce Shortage: Geriatric-trained nursing capacity remains limited relative to demand, even as the Saudi Commission for Health Specialties expands its Geriatric Medicine Fellowship Program.
- Reimbursement Coverage Gaps: Elderly care products are not uniformly covered under private insurance schemes, pushing a larger share of the purchase burden onto individual households.
Market Opportunities
- AI-Enabled Remote Monitoring: The Ministry of Health's 'Jam AI' initiative, launched in February 2025, invites innovators to build AI-based tools for elderly and women's healthcare, opening space for connected monitoring products.
- Public-Private Partnerships in Long-Term Care: The 2023 Elderly Care Strategy covers new facilities, caregiver training and community support systems, creating procurement opportunities for equipment suppliers.
Market Challenges
- Limited Awareness Outside Major Cities: Product awareness and distributor reach concentrate in Riyadh, Jeddah and Dammam, leaving smaller cities underserved relative to their ageing populations.
- Cultural Preference for Family Caregiving: Strong extended-family caregiving norms can delay adoption of assistive and monitoring products until conditions become advanced, compressing the addressable window for early intervention.
Emerging Market Trends
Four trends define the Saudi Arabia elderly care products market outlook through 2034: digital health integration, home healthcare licensing, smart mobility design and geriatric workforce professionalisation.
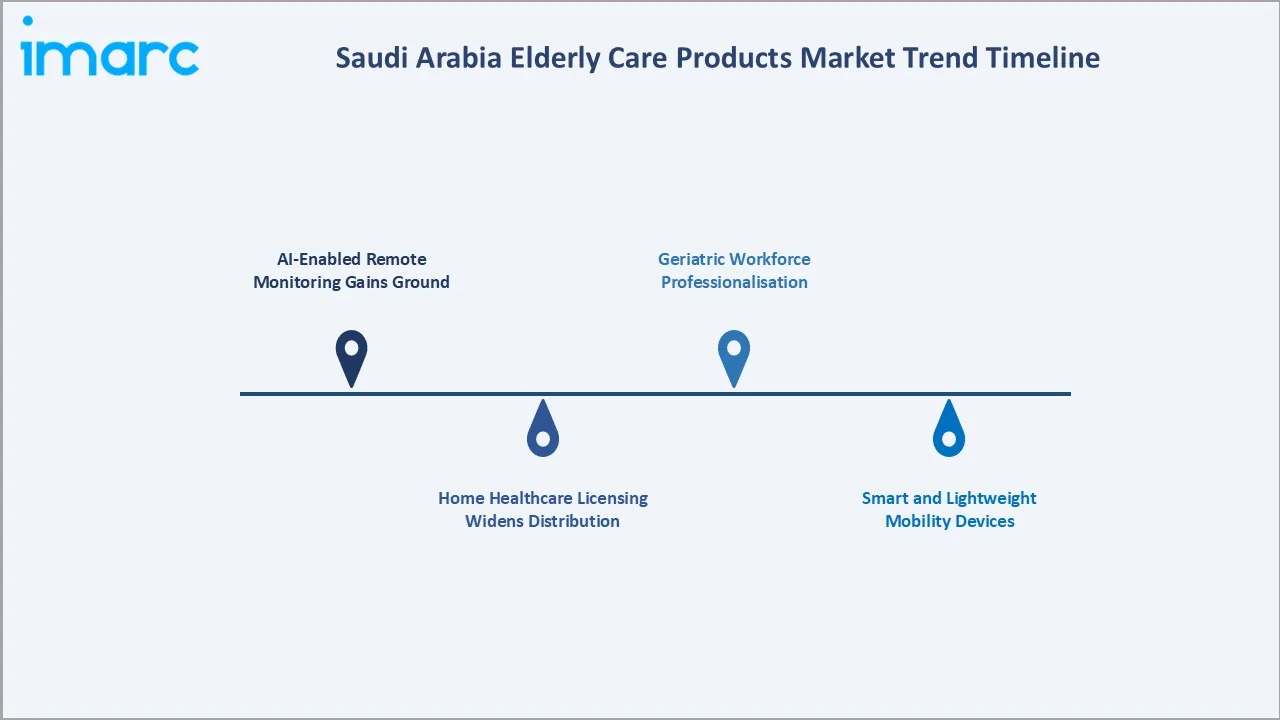
1. AI-Enabled Remote Monitoring Gains Ground
The Ministry of Health's Jam AI initiative is accelerating pilot deployments of AI-based fall-detection and vital-sign monitoring tools. Home-based sensor products are increasingly bundled with digital health platforms such as Sehhaty.
2. Home Healthcare Licensing Widens Distribution
Expanding Ministry of Health licensing of home healthcare providers is creating new institutional buying channels for mobility aids, hospital beds and incontinence products beyond traditional pharmacy retail.
3. Smart and Lightweight Mobility Devices
Manufacturers are introducing lighter-weight wheelchairs and rollators with foldable frames suited to smaller Saudi apartments, alongside power-assist options that extend independent mobility for frail seniors.
4. Geriatric Workforce Professionalisation
The Saudi Geriatric Medicine Fellowship Program, established under the Saudi Commission for Health Specialties, is training specialist geriatricians, which is gradually improving clinical guidance on product selection and usage.
Industry Value Chain Analysis
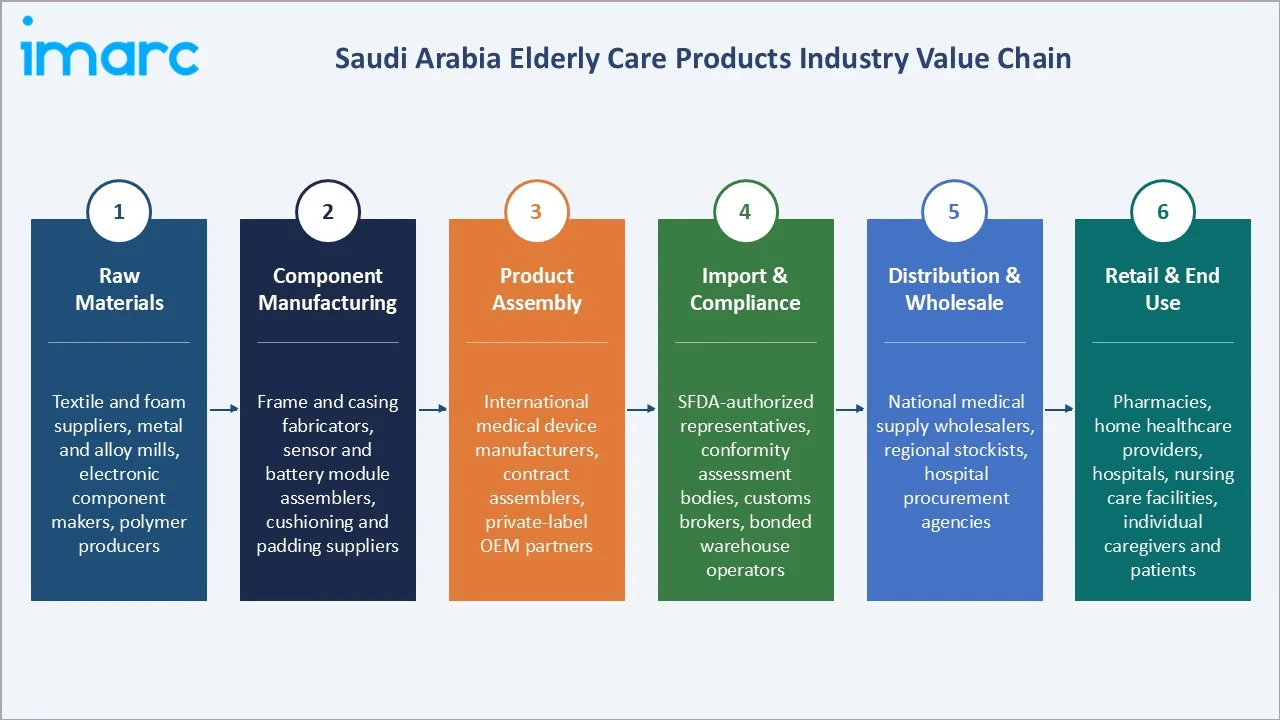
The Saudi Arabia elderly care products value chain runs from imported raw materials and components, through overseas manufacturing and SFDA compliance, into multi-tier Saudi distribution and a delivery base spanning hospitals, home healthcare providers and retail pharmacies.
|
Stage |
Key Participants |
|
Raw Materials |
Textile and foam suppliers, metal and alloy mills, electronic component makers, polymer producers |
|
Component Manufacturing |
Frame and casing fabricators, sensor and battery module assemblers, cushioning and padding suppliers |
|
Product Assembly |
International medical device manufacturers, contract assemblers, private-label OEM partners |
|
Import and Compliance |
SFDA-authorized representatives, conformity assessment bodies, customs brokers, bonded warehouse operators |
|
Distribution and Wholesale |
National medical supply wholesalers, regional stockists, hospital procurement agencies |
|
Retail and End Use |
Pharmacies, home healthcare providers, hospitals, nursing care facilities, individual caregivers and patients |
Margin concentrates at the distribution and home healthcare delivery stages, where compliance expertise and last-mile service capability matter most to institutional buyers.
Technology Landscape in the Saudi Arabia Elderly Care Products Industry
Smart Mobility Engineering
Power-assist wheelchairs and foldable rollators increasingly integrate lightweight alloy frames and adjustable ergonomics, extending independent movement for seniors with limited upper-body strength.
Remote Monitoring and Digital Health
Wearable and bedside sensors that track falls, heart rate and sleep patterns are being piloted under the Jam AI initiative, feeding data into caregiver and clinician dashboards.
Materials Innovation in Incontinence Care
Super-absorbent polymer cores and breathable, skin-friendly outer layers are improving comfort and reducing skin-irritation complaints among long-term users of incontinence products.
Automation in Nursing and Home Care
Electric profiling beds, automated patient lifts and pressure-relief mattresses are gaining adoption in nursing facilities and licensed home healthcare settings, reducing manual-handling injury risk for caregivers.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Product Type |
🔒 |
🔒 |
2025 |
|
Usage |
Home Care |
68.4% |
2025 |
|
End User |
Home Health Care |
46.3% |
2025 |
|
Region |
Western Region |
35.7% |
2025 |

By Usage
Home care dominates at 68.4% market share in 2025 and grows at about 7.05% CAGR through 2034. Families increasingly manage chronic and age-related conditions at home, supported by wider access to mobility aids and monitoring products.
To access detailed market analysis, Request Sample
Chronic illness care accounts for 31.6% and grows at roughly 4.75% CAGR. This segment concentrates on products supporting diabetes, cardiovascular and mobility-limiting conditions managed under clinical supervision.
By End User
Home health care leads with 46.3% share in 2025. Ministry of Health licensing of home healthcare establishments, deeper caregiver availability and family preference for in-home management sustain the segment's lead at roughly 7.35% CAGR.
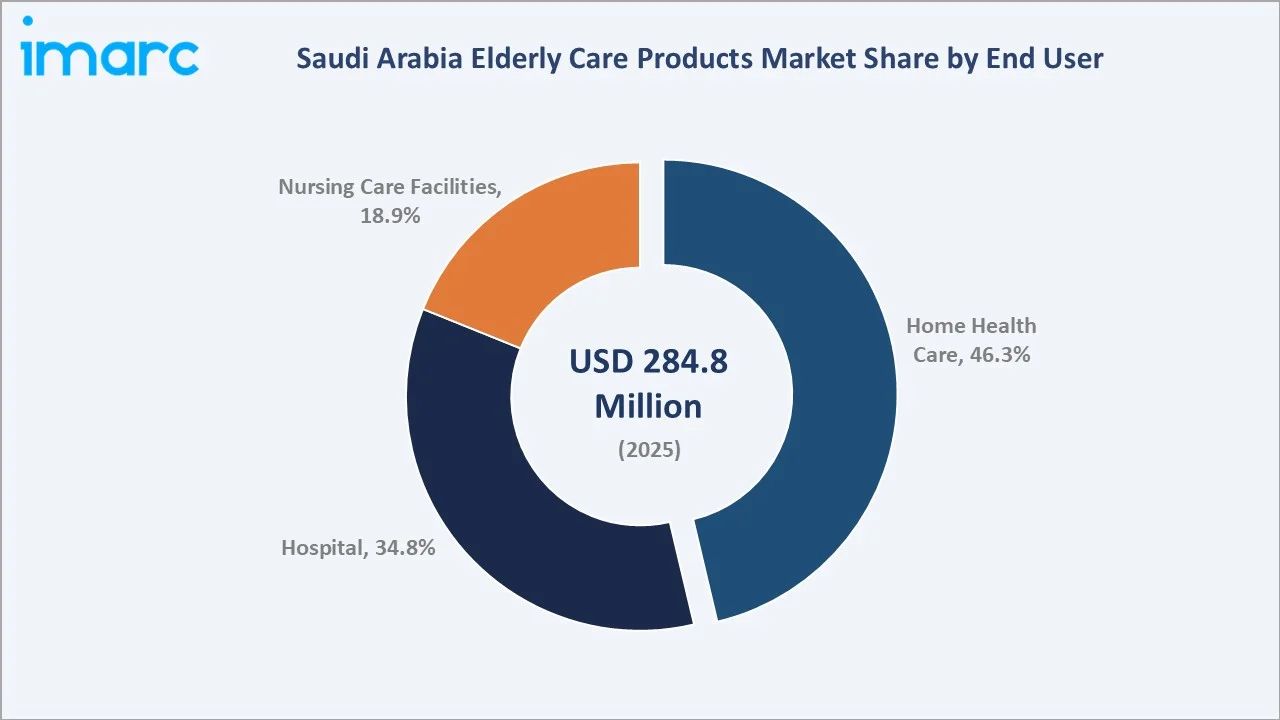
Hospital holds 34.8% and grows at about 5.15% CAGR, anchored by tertiary geriatric care. Nursing care facilities account for 18.9%, expanding at roughly 5.60% CAGR as the 2023 Elderly Care Strategy adds new licensed capacity.
Regional Market Insights
|
Region |
Share (2025) |
Key Growth Drivers & Characteristics |
|
Western Region |
35.7% |
Largest hospital and private-clinic density around Jeddah, Makkah and Madinah; strong pharmacy retail network; sizeable expatriate and pilgrim-linked healthcare demand; major port gateway supporting import distribution |
|
Northern and Central Region |
32.4% |
Riyadh's population concentration and status as the Kingdom's private-healthcare investment hub; highest density of Ministry of Health-licensed home healthcare providers; strong corporate and institutional procurement |
|
Eastern Region |
20.1% |
Industrial and energy-sector workforce with high expatriate concentration; organised hospital clusters in the Dammam metropolitan area; steady institutional procurement through corporate health schemes |
|
Southern Region |
11.8% |
Smaller and more dispersed elderly population; traditional retail and limited specialist distribution; improving connectivity supporting gradual access expansion |
The Western Region's 35.7% share in 2025 reflects Jeddah's status as a commercial and healthcare gateway, alongside Makkah and Madinah's dense resident and long-stay visitor populations that widen the addressable base for home and institutional elderly care.
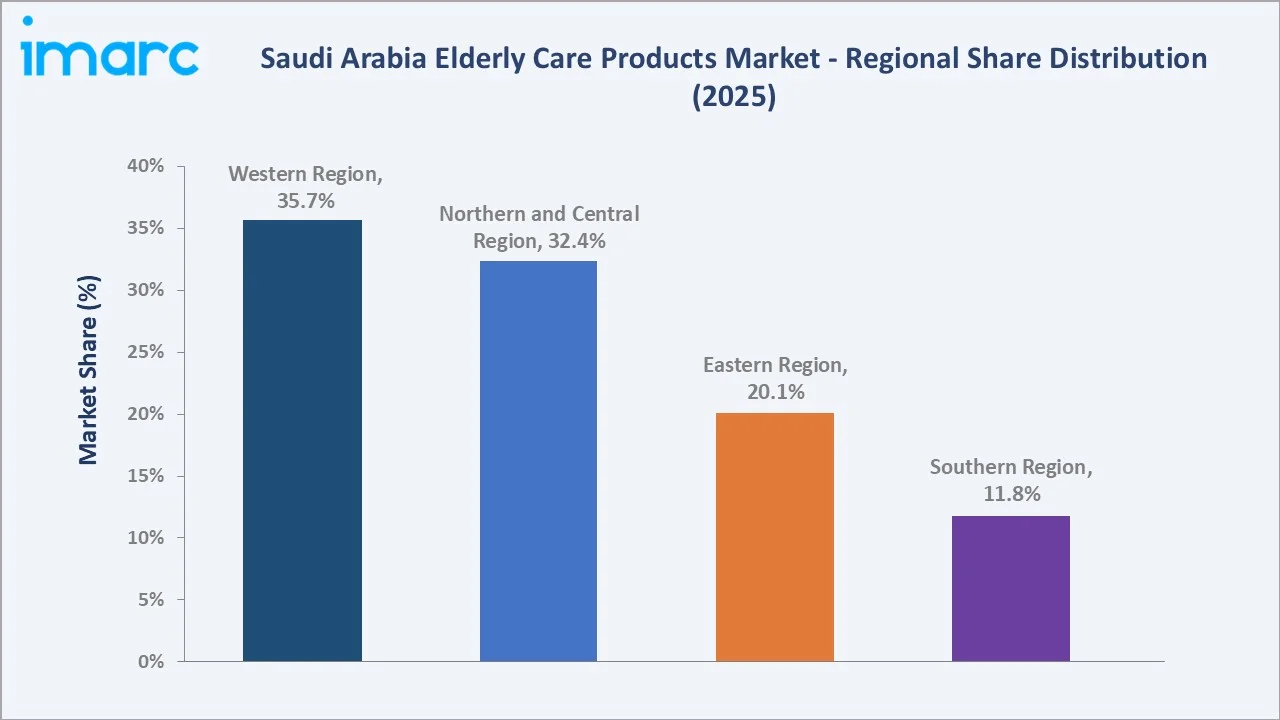
The Northern and Central Region holds 32.4%, anchored by Riyadh's concentration of private hospitals and home healthcare licensing activity. The Eastern Region's 20.1% is supported by an organised healthcare network serving its industrial workforce, while the Southern Region accounts for 11.8% on a smaller and more traditional care base.
Competitive Landscape
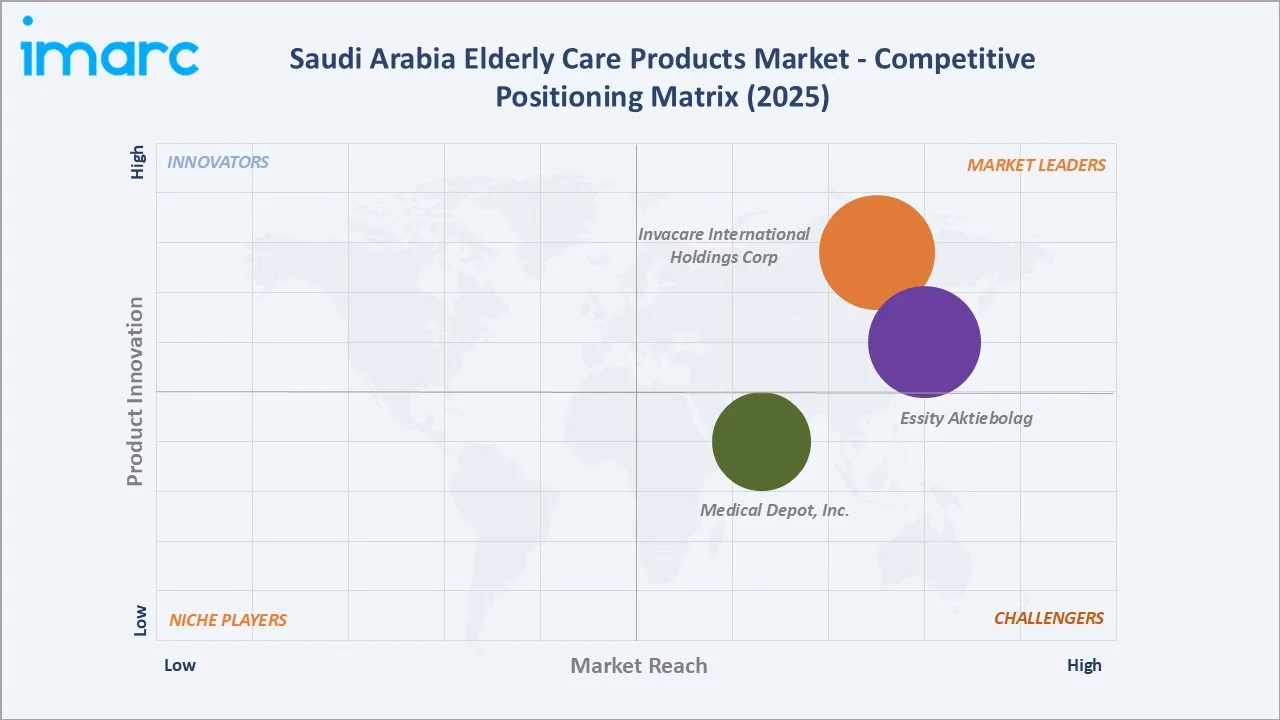
The Saudi Arabia elderly care products market is moderately consolidated among global durable medical equipment and hygiene product manufacturers, with fragmentation among regional distributors and private-label importers.
|
Company Name |
Brand / Product Line |
Market Position |
Core Strength |
|
Essity Aktiebolag |
TENA Incontinence Care |
Market Leader |
Global incontinence-care specialist with the TENA brand in production since 1960; deep clinical distribution relationships with hospitals and care facilities |
|
Invacare International Holdings Corp |
Invacare Mobility, Invacare Beds |
Market Leader |
Global leader in wheelchairs and home medical equipment distributing to 80-plus countries; broad mobility and seating product range |
|
Medical Depot, Inc. |
Beds, Mobility |
Strong Challenger |
Diversified durable medical equipment portfolio spanning mobility, beds and respiratory products, with active Middle East distribution |
Positioning splits along two axes. Essity and Invacare combine global brand recognition with clinical-grade product depth, while Invacare International Holdings Corp and Medical Depot, Inc. compete on distribution breadth and institutional procurement relationships across hospitals and home healthcare providers.
Key Company Profiles
Essity Aktiebolag (TENA)
Essity is a global hygiene and health company whose TENA brand has specialised in incontinence-care products since 1960. The company supplies pads, briefs and skin-care lines used across home and institutional elderly care settings worldwide.
- Product Portfolio: TENA ProSkin, TENA Silhouette, TENA Slip, and others.
- Recent Development: In 2025, Essity launched TENA ProSkin Stretch Day & Night, an incontinence product designed to make changing easier for both patients and healthcare professionals. Its stretchable design helps caregivers put on and remove the product more easily, while supporting patient comfort and skin care. Essity positioned the product as a way to reduce the workload and cost of continence care, particularly in healthcare and elderly-care settings where efficient patient handling is important.
- Strategic Focus: Clinical-grade skin protection and digital continence-care solutions for care facilities.
Invacare International Holdings Corp
Invacare is a global leader in home and long-term-care medical products, tracing its roots to 1885. The company manufactures and distributes wheelchairs, mobility scooters, hospital beds and seating products across more than 80 countries.
- Product Portfolio: Invacare manual and power wheelchairs, home care beds, patient lifts, and others.
- Recent Developments: In 2026, Invacare launched the new Aquatec Pure range of showering and toileting solutions, expanding its portfolio of personal-care products for people with reduced mobility. The range is designed for home and healthcare settings, with simple and affordable solutions intended to promote greater independence in everyday personal care. The products are particularly relevant to elderly-care environments, where showering and toileting can be challenging for people with limited mobility and can increase caregiver assistance requirements. The launch strengthens Invacare’s offering beyond mobility equipment into daily living and personal-care solutions for older adults and individuals requiring long-term care.
- Strategic Focus: Broad mobility and seating range supported by international distributor networks.
Medical Depot, Inc.
Medical Depot, Inc., founded in 2000 and headquartered in Port Washington, New York, manufactures a comprehensive line of durable medical equipment marketed across North America, Europe, the Middle East and Asia.
- Product Portfolio: Mobility products, bariatric equipment, homecare beds, bath safety products, and others.
- Strategic Focus: Portfolio diversification through acquisitions and design-led product innovation.
Market Concentration Analysis
The Saudi Arabia elderly care products market shows moderate concentration among branded durable medical equipment and hygiene product suppliers, alongside pronounced fragmentation in the value-tier import segment.
Global brands led by Essity Aktiebolag, Invacare International Holdings Corp and Medical Depot, Inc. together account for a meaningful share of institutional and pharmacy-channel sales, while no single company approaches dominant share of total market volume.
Fragmentation is heaviest among unbranded mobility aids and basic incontinence products imported by smaller distributors. Consolidation is occurring at the distribution and home-healthcare delivery layer as importers broaden multi-brand portfolios to spread SFDA compliance costs across more SKUs.
Investment & Growth Opportunities
Fastest Growing Segments
Home health care (~7.35% CAGR) and home care usage (~7.05% CAGR) represent the highest-growth vectors through 2034, as licensing expansion and ageing-in-place preference outpace institutional-channel growth.
Emerging Market Opportunities
Public-private partnerships tied to the 2023 Elderly Care Strategy offer an underexploited channel for equipment suppliers, particularly in secondary cities where distributor coverage remains thin relative to population growth.
Investment Themes
- Digital-first home healthcare distribution: Building direct and institutional supply relationships with Ministry of Health-licensed home healthcare providers captures the fastest-growing delivery channel.
- AI-enabled monitoring devices: Aligning product development with the Jam AI initiative positions suppliers for early government-backed pilot adoption.
- Compliance-led import consolidation: Scale importers that amortise SFDA MDMA certification across broad portfolios can secure exclusive distribution agreements and improve landed-cost competitiveness.
Future Market Outlook (2026-2034)
The Saudi Arabia elderly care products market is projected to grow from USD 284.8 Million in 2025 to USD 525.2 Million by 2034 at a 6.33% CAGR, passing USD 387.1 Million in 2030. Growth will be led by home-based care delivery rather than institutional expansion.
Three forces anchor the trajectory. First, the senior population base, though still just 2.8% of residents, is expanding faster than any other age cohort as life expectancy rises. Second, Vision 2030's healthcare investment continues to widen licensed home healthcare capacity. Third, digital health tools emerging from the Jam AI initiative are expected to improve early detection and sustained product usage among ageing residents.
Research Methodology
Primary Research
Primary research comprised structured interviews with industry stakeholders during 2025, including elderly care product importers and distributors, home healthcare provider administrators in Riyadh, Jeddah and Dammam, hospital procurement managers, and SFDA regulatory consultants.
Secondary Research
Secondary research drew on GASTAT publications covering population and health status statistics, Ministry of Health Vision 2030 documentation, SFDA medical device regulation and MDMA guidelines, and company disclosures from Essity Aktiebolag, Invacare International Holdings Corp and Medical Depot, Inc.
Forecasting Models
Value forecasts were built bottom-up from senior population estimates, chronic disease prevalence and usage-segment penetration rates. Segment outputs were cross-checked against regional healthcare infrastructure data and reconciled to a top-down market total, yielding a blended 6.33% CAGR for 2026-2034.
Saudi Arabia Elderly Care Products Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Products Covered | Incontinence Product, Consumables, Assistive Devices, Nutritional Supplements |
| Usages Covered | Home Care, Chronic Illness Care |
| End Users Covered | Hospital, Nursing Care Facilities, Home Health Care |
| Regions Covered | Northern and Central Region, Western Region, Eastern Region, Southern Region |
| Companies Covered | Essity Aktiebolag, Invacare International Holdings Corp, Medical Depot, Inc., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Saudi Arabia elderly care products market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Saudi Arabia elderly care products market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Saudi Arabia elderly care products industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Saudi Arabia Elderly Care Products Market Report
The Saudi Arabia elderly care products market reached USD 284.8 Million in 2025, supported by a rapidly expanding senior population and rising Vision 2030 healthcare investment.
The market is projected to grow at a 6.33% CAGR during 2026-2034, reaching USD 525.2 Million by 2034, driven by home healthcare licensing and chronic disease prevalence.
Home Care leads with 68.4% share in 2025, as families increasingly manage age-related conditions at home rather than through institutional placement.
Home Health Care holds the largest share at 46.3% in 2025, benefiting from expanding Ministry of Health licensing of home healthcare establishments.
Home Health Care grows fastest at roughly 7.35% CAGR through 2034, supported by widening licensed home healthcare capacity across the Kingdom.
The Western Region leads with 35.7% share in 2025, anchored by Jeddah's healthcare infrastructure and Makkah and Madinah's dense resident populations.
Leading companies include Essity Aktiebolag, Invacare International Holdings Corp and Medical Depot, Inc., among others.
GASTAT recorded 2.8% of residents aged 65 and above in 2024. This small but fast-growing cohort drives sustained replacement and first-time purchase demand.
Elderly care medical devices fall under SFDA oversight. Products require Medical Device Marketing Authorization (MDMA) before commercial distribution in the Kingdom.
The market is projected to reach approximately USD 387.1 Million by 2030, supported by rising home healthcare licensing and chronic disease management demand.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade