Saudi Arabia Environmental Consulting Services Market Size, Share, Trends, and Forecast by Service, Medium, Vertical, and Region, 2026-2034
Saudi Arabia Environmental Consulting Services Market Size, Share, Trends & Forecast (2026-2034)
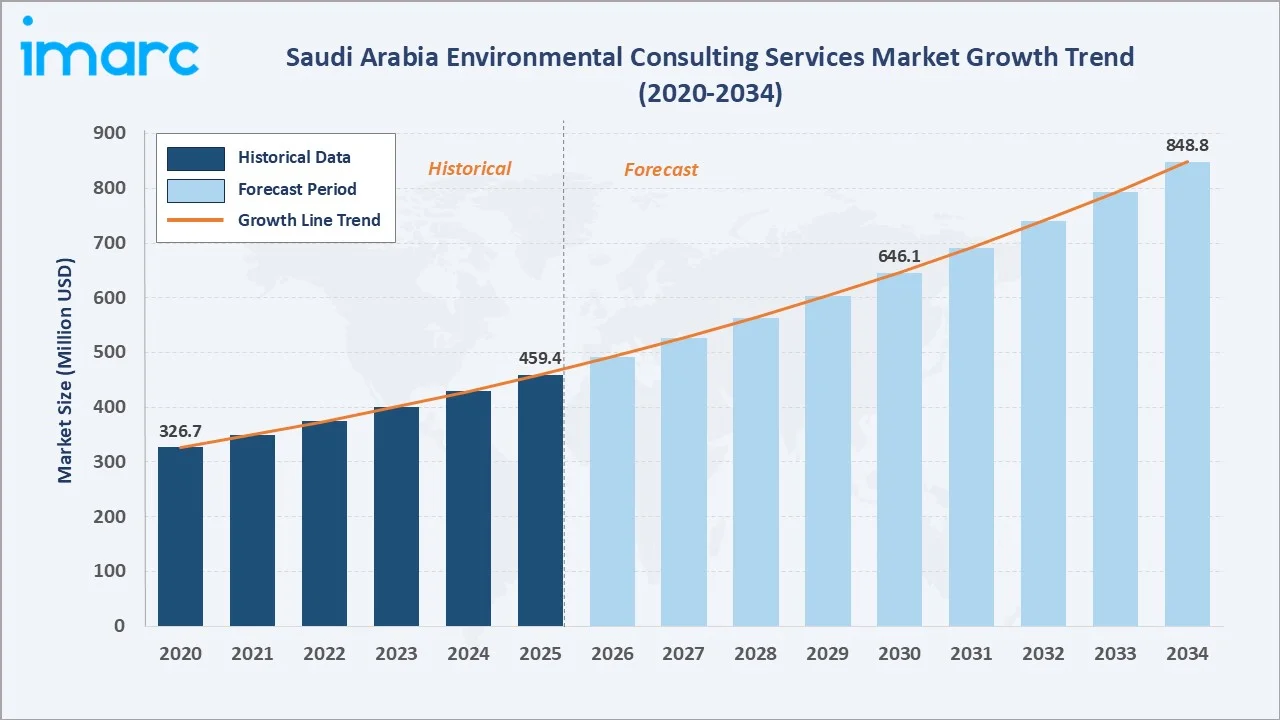
The Saudi Arabia environmental consulting services market size increased from USD 459.4 Million in 2025 to USD 491.9 Million in 2026 and is projected to reach USD 848.8 Million by 2034, growing at a CAGR of 7.06% during 2026-2034. The market is driven by Vision 2030 giga-project environmental impact assessments, the expanding renewable energy transition, and rapid industrialization. Saudi Arabia’s industrial production index increased by 5.1% year-on-year in 2025. This growth is supporting demand for environmental consulting services as companies require environmental impact assessments, permitting support, emissions monitoring, waste management planning, and regulatory compliance solutions. Water management leads at 57.6% by medium, energy and utilities dominate at 29.8% by vertical, and the Northern and Central region commands the largest share at 42.8%.
Market Snapshot
|
Metric |
Value |
| Base Year Market Size (2025) |
USD 459.4 Million |
| Market Size (2026) | USD 491.9 Million |
|
Forecast Market Size (2034) |
USD 848.8 Million |
|
CAGR (2026-2034) |
7.06% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Medium |
Water Management (57.6%, 2025) |
|
Dominant Vertical |
Energy and Utilities (29.8%, 2025) |
|
Leading Region |
Northern and Central Region (42.8%, 2025) |
The Saudi Arabia environmental consulting services market has grown from USD 326.7 Million in 2020 to USD 459.4 Million in 2025 and an estimated USD 491.9 Million in 2026, driven by progressive regulatory enforcement, Vision 2030 environmental requirements, and growing enterprise awareness of environmental liabilities. The market is projected to reach USD 646.1 Million by 2030 and USD 848.8 Million by 2034.
To get more information on this market, Request Sample
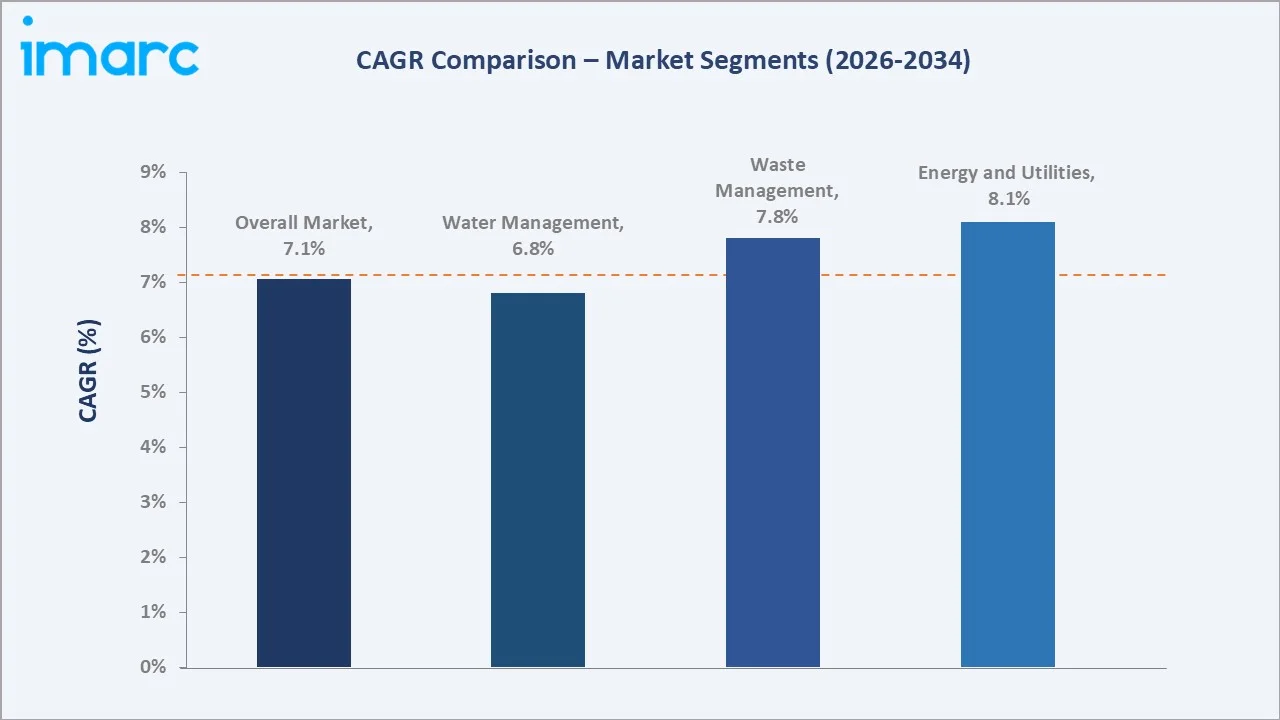
Energy and utilities grow at ~8.1% CAGR through renewable energy transition environmental permitting. Waste management grows at ~7.8% CAGR through circular economy and waste-to-energy program advisory. Water management grows at ~6.8% CAGR through desalination expansion and wastewater reuse compliance consulting.
Executive Summary
The Saudi Arabia environmental consulting services market is experiencing robust and accelerating growth, underpinned by the Kingdom's ambitious environmental transformation agenda embedded within Vision 2030 and reinforced by international climate commitments. Saudi Arabia's renewable energy transition, targeting 50% renewable electricity by 2030, generates permitting, environmental assessment, and monitoring requirements for new solar and wind installations. Water management leads at 57.6% through water scarcity challenges and regulatory requirements. Energy and utilities lead at 29.8% by vertical through renewable transition advisory. Northern & Central region leads regionally at 42.8%.
Key Market Insights
|
Insight |
Data |
|
Dominant Medium |
Water Management - 57.6% share (2025) |
|
Dominant Vertical |
Energy and Utilities - 29.8% share (2025) |
|
Leading Region |
Northern & Central Region - 42.8% (2025) |
|
Key Market Opportunities |
Environmental impact assessments, regulatory compliance consulting, emissions and air-quality management, waste and water management, and decarbonization consulting across Saudi Arabia’s expanding industrial sector. |
Key Analytical Observations Supporting the Above Data:
- Water Management at 57.6%: Water Management dominates because Saudi Arabia faces one of the most acute freshwater scarcity challenges, with renewable freshwater resources among the lowest per capita globally. The Kingdom's extensive desalination program, wastewater treatment and reuse initiatives, agricultural water efficiency programs, and stringent industrial wastewater discharge regulations create persistent high-value demand for water management consulting.
- Energy and Utilities at 29.8%: Energy and utilities lead through the environmental consulting requirements of Saudi Arabia's renewable energy transition, which involves ecological surveys for new solar projects across desert and coastal habitats, environmental permitting for transmission infrastructure, ongoing environmental monitoring programs for operational plants, and decommissioning planning for retired fossil fuel facilities.
- Northern & Central Region at 42.8%: The Northern and Central region commands due to the concentration of federal environmental regulatory bodies, combined with the highest density of mega-project developments in the Northern regions and industrial zone concentration.
Saudi Arabia Environmental Consulting Services Market Overview
The Saudi Arabia environmental consulting services market encompasses professional advisory services addressing environmental compliance, assessment, monitoring, and management across industrial, government, and infrastructure client segments. Core service categories include environmental impact assessment (EIA) and strategic environmental assessment (SEA), environmental permitting and regulatory compliance, environmental monitoring and testing programs, environmental management system (EMS) design and implementation, environmental auditing and due diligence, remediation and contaminated site management, water resource management, waste management and circular economy advisory, climate change and carbon management consulting, ecological services and biodiversity assessment, and sustainability reporting and ESG advisory.
Services are delivered across two primary mediums: water management (addressing water resource quality, wastewater treatment, desalination environmental impact, and water reuse) and waste management (addressing solid waste, hazardous waste, e-waste, and waste-to-energy advisory).
Market Dynamics
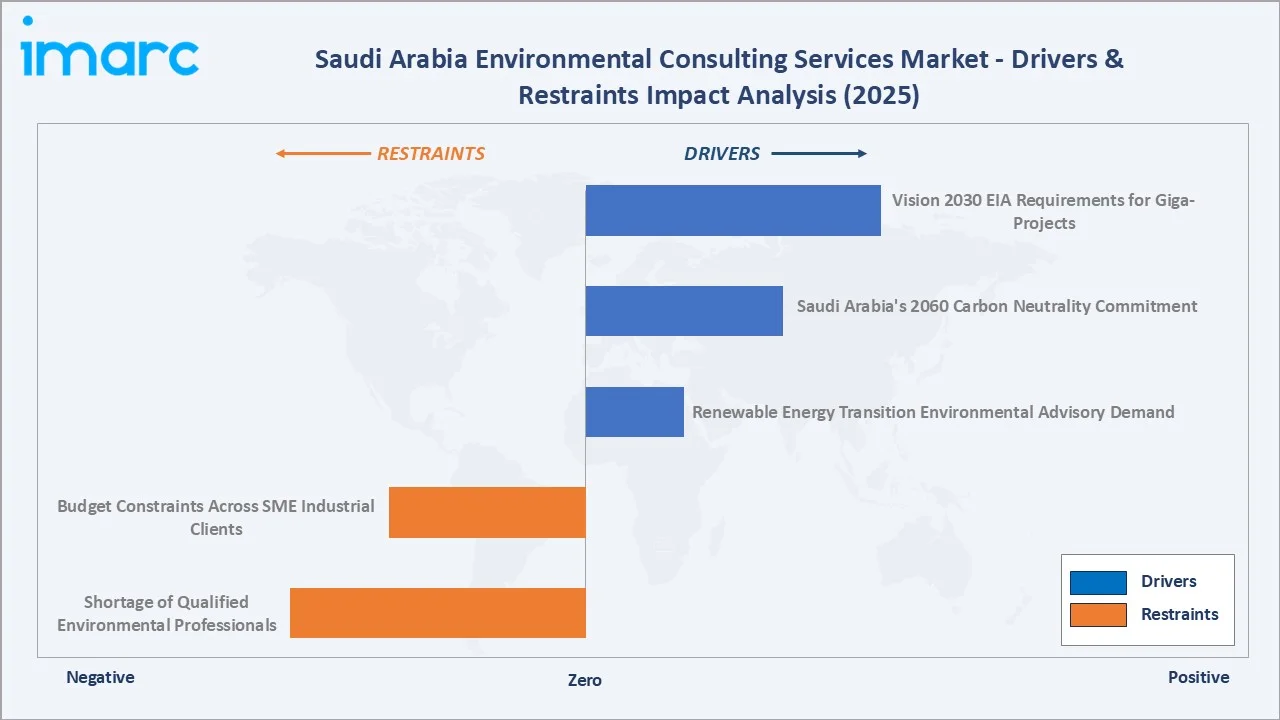
To evaluate market opportunities, Request Sample
Market Drivers
- Vision 2030 EIA Requirements for Giga-Projects: Saudi Arabia's Vision 2030 mega-projects require comprehensive environmental assessments under regulations that mandate baseline ecological studies, impact prediction, mitigation planning, and ongoing monitoring programs. NEOM's 26,500 km² development footprint in a significant desert ecosystem requires years of environmental baseline monitoring, fauna and flora surveys, habitat connectivity planning, and marine environment assessments for its Red Sea coastline.
- Saudi Arabia's 2060 Carbon Neutrality Commitment: The Saudi Green Initiative's commitment to Net Zero emissions by 2060 creates sustained demand for carbon accounting, decarbonization strategy consulting, nature-based solutions advisory, and sustainability reporting services. Emissions reduction programs, sustainability transformation, and mandatory reporting requirements for listed Saudi companies are generating corporate sustainability advisory demand.
- Renewable Energy Transition Environmental Advisory Demand: The 58.7 GW renewable energy target by 2030 generates significant environmental consulting demand across EIA for solar farm sites, avian and wildlife impact assessment, visual impact assessment for landscape-sensitive areas, noise monitoring for wind projects, construction environmental management plans for transmission infrastructure, and operational environmental monitoring programs.
Market Restraints
- Shortage of Qualified Environmental Professionals: Saudi Arabia faces a significant shortage of domestic environmental scientists, hydrogeologists, ecologists, and environmental engineers with the specialized expertise required for complex environmental consulting assignments. Reliance on expatriate professionals increases project costs, creates knowledge transfer challenges, and constrains the ability to build sustainable domestic environmental consulting capacity.
- Budget Constraints Across SME Industrial Clients: Smaller industrial facilities and construction companies with limited environmental compliance budgets tend to engage minimal environmental consulting services, often focused exclusively on mandatory regulatory submissions rather than proactive environmental management programs. Price sensitivity in the lower-end market segment compresses margins for consulting firms serving SME clients and limits the scope of services that can be sold.
Market Opportunities
- ESG Advisory and Corporate Sustainability Reporting: Saudi Arabia's capital market authority's ESG disclosure requirements for listed companies, combined with growing investor pressure from sovereign wealth funds and international capital markets, are creating substantial demand for corporate sustainability strategy, reporting advisory, supply chain environmental due diligence, and science-based targets development. This represents the fastest-emerging service category in Saudi Arabia's environmental consulting market, with demand growing across all major industries.
- Nature-Based Solutions and Biodiversity Advisory: Saudi Arabia's Saudi Green Initiative commitment to restoring 74 million hectares of degraded land and rehabilitating coastal and marine ecosystems creates substantial demand for ecological restoration consulting, biodiversity monitoring, coastal and wetland management advisory, and nature-based carbon project development. These nature-based solution services represent premium-priced advisory work that differentiates specialist firms from conventional compliance consultants.
Market Challenges
- Complex Multi-Stakeholder Regulatory Environment: Environmental consulting projects in Saudi Arabia often require navigating overlapping jurisdictions, creating coordination complexity that extends project timelines and increases client costs. The evolving nature of Saudi environmental regulations, with frequent updates to EIA requirements, monitoring standards, and compliance thresholds, requires continuous regulatory expertise investment by consulting firms.
- Competition from Engineering Consultancies Offering Environmental Add-Ons: Large international engineering and infrastructure consultancies compete with specialist environmental firms by offering environmental services as part of broader multi-disciplinary infrastructure advisory contracts. This bundling strategy can disadvantage specialist environmental consultants in procurement competitions where clients prefer single-vendor contracts for integrated project delivery.
Emerging Market Trends
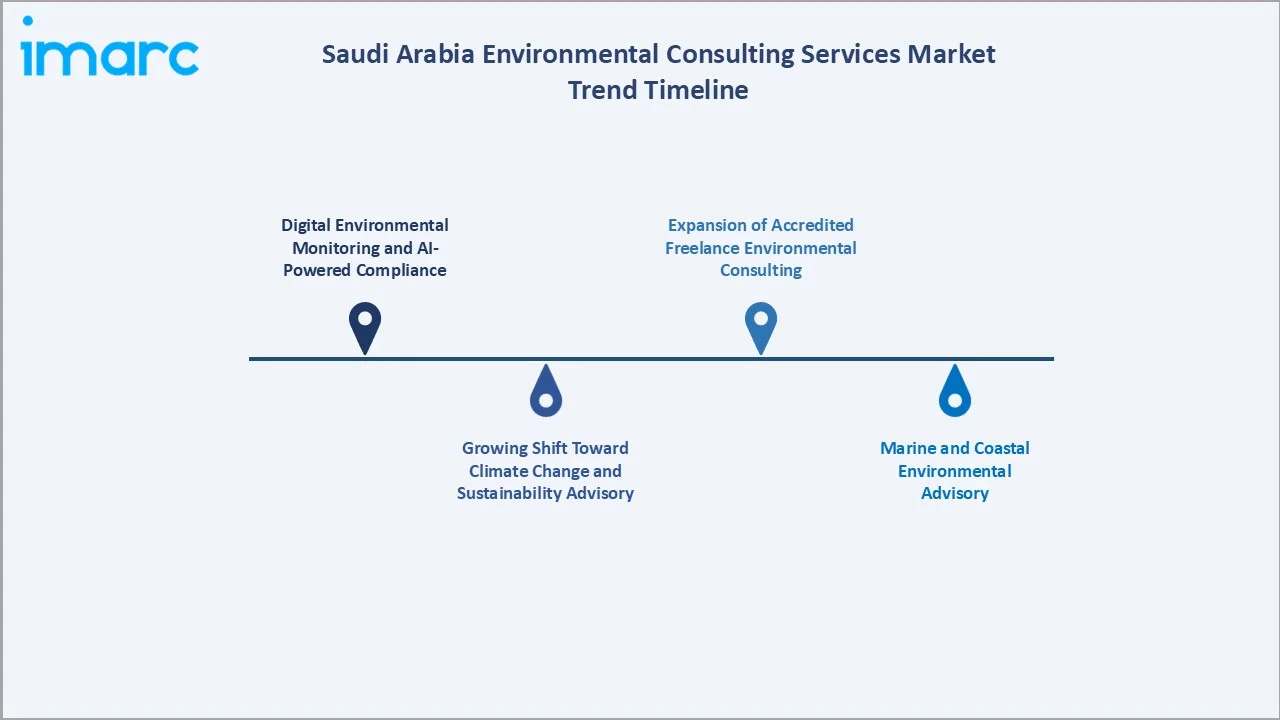
1. Digital Environmental Monitoring and AI-Powered Compliance
Digital transformation is reshaping environmental monitoring in Saudi Arabia through IoT sensor networks, satellite remote sensing, drone-based surveys, and AI-powered data analytics. Real-time environmental monitoring platforms that integrate air quality, water quality, noise, and biodiversity data are enabling more efficient and cost-effective compliance monitoring for industrial facilities and large-scale development projects.
2. Growing Shift Toward Climate Change and Sustainability Advisory
Environmental consulting in Saudi Arabia is expanding beyond traditional compliance services toward climate strategy, ESG advisory, decarbonization, and sustainability reporting. In March 2025, Staterra expanded its Climate Change & Sustainability consulting services in Saudi Arabia to support organizations in aligning with Vision 2030 and global climate objectives. The enhanced offering addresses rising demand for sustainability expertise, regulatory alignment, and improved environmental performance. This shift is being supported by Vision 2030 sustainability priorities and growing corporate demand for alignment with national and international environmental standards.
3. Expansion of Accredited Freelance Environmental Consulting
In June 2026, the National Centre for Environmental Compliance (NCEC) qualified 99 Saudi professionals to provide environmental consulting services and prepare Environmental Management Plans for more than 60 low-impact facilities. The initiative aims to formalize the sector, improve service efficiency, expand local expertise, and strengthen environmental compliance across Saudi Arabia. This trend is expanding access to environmental management plan preparation and compliance services, particularly for low-impact facilities, while improving market formalization and local consulting capacity.
4. Marine and Coastal Environmental Advisory
Saudi Arabia's extensive 2,640 km coastline is creating specialized demand for marine environmental consulting. Coral reef assessment, seagrass and mangrove habitat monitoring, marine mammal impact assessment, hydrodynamic modeling for coastal development, and marine protected area management planning are specialist services with growing demand from the Kingdom's coastal mega-project developments.
Industry Value Chain Analysis
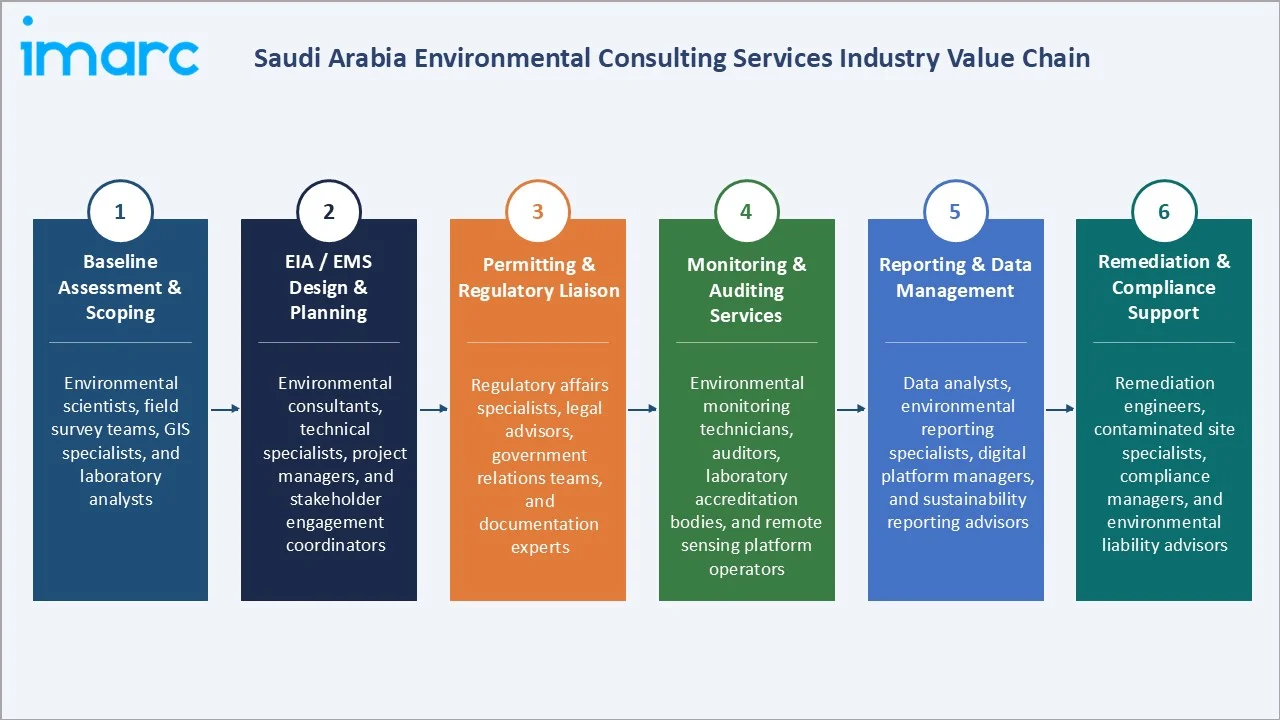
The Saudi Arabia environmental consulting services value chain integrates baseline assessment and scoping, EIA and EMS design and planning, permitting and regulatory liaison, monitoring and auditing services, reporting and data management, and remediation and compliance support across water management, waste management, and vertical industry segments.
|
Stage |
Key Participants |
|
Baseline Assessment & Scoping |
Environmental scientists, field survey teams, GIS specialists, and laboratory analysts. |
|
EIA / EMS Design & Planning |
Environmental consultants, technical specialists, project managers, and stakeholder engagement coordinators. |
|
Permitting & Regulatory Liaison |
Regulatory affairs specialists, legal advisors, government relations teams, and documentation experts. |
|
Monitoring & Auditing Services |
Environmental monitoring technicians, auditors, laboratory accreditation bodies, and remote sensing platform operators. |
|
Reporting & Data Management |
Data analysts, environmental reporting specialists, digital platform managers, and sustainability reporting advisors. |
|
Remediation & Compliance Support |
Remediation engineers, contaminated site specialists, compliance managers, and environmental liability advisors. |
Permitting and regulatory liaison represents the highest-value knowledge-intensive stage in the Saudi Arabia environmental consulting value chain, as successful navigation of multi-stakeholder Saudi regulatory processes requires both technical environmental expertise and relationship capital with regional environmental authorities. Consulting firms with established regulatory relationships, track records of successful EIA approvals for complex projects, and deep familiarity with Saudi environmental law interpretation create durable competitive advantages that sustain premium fee positioning.
Technology Landscape in the Saudi Arabia Environmental Consulting Industry
Environmental Monitoring Technology and IoT Platforms
Advanced environmental monitoring technology is transforming service delivery in Saudi Arabia's environmental consulting market. Continuous ambient air quality monitoring networks, automated wastewater discharge monitoring systems, and remote groundwater quality sensors enable real-time compliance verification that traditional periodic sampling programs cannot achieve. Drone-mounted multispectral cameras and LiDAR systems enable rapid large-area vegetation assessment, coastal mapping, and industrial facility inspection at scales and costs that fundamentally expand the reach of environmental monitoring programs across Saudi Arabia's vast geographic territory.
GIS and Remote Sensing Analytics
Geographic information system (GIS) platforms and open-source alternatives provide foundational spatial analysis capabilities for environmental impact assessment, habitat mapping, pollution dispersion modeling, and environmental monitoring network optimization. Satellite remote sensing and commercial high-resolution imagery enable change detection analysis for vegetation loss monitoring, coastal erosion assessment, and urban expansion environmental impact tracking across Saudi Arabia's rapidly developing landscape. AI-powered image classification algorithms are progressively automating environmental change detection tasks previously requiring intensive manual interpretation.
Environmental Management Software and Digital Reporting
Enterprise environmental, health and safety (EHS) management software platforms are being adopted by Saudi industrial facilities to manage environmental compliance obligations, permit conditions, monitoring data, and audit findings in integrated digital systems. The NCEC's development of digital environmental compliance reporting portals is progressively requiring industrial clients to adopt compatible environmental data management systems, creating consulting demand for system selection, implementation, and integration services aligned with government digital reporting standards.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Service |
🔒 |
🔒 |
2025 |
|
Medium |
Water Management |
57.6% |
2025 |
|
Vertical |
Energy and Utilities |
29.8% |
2025 |
|
Region |
Northern and Central Region |
42.8% |
2025 |

By Medium
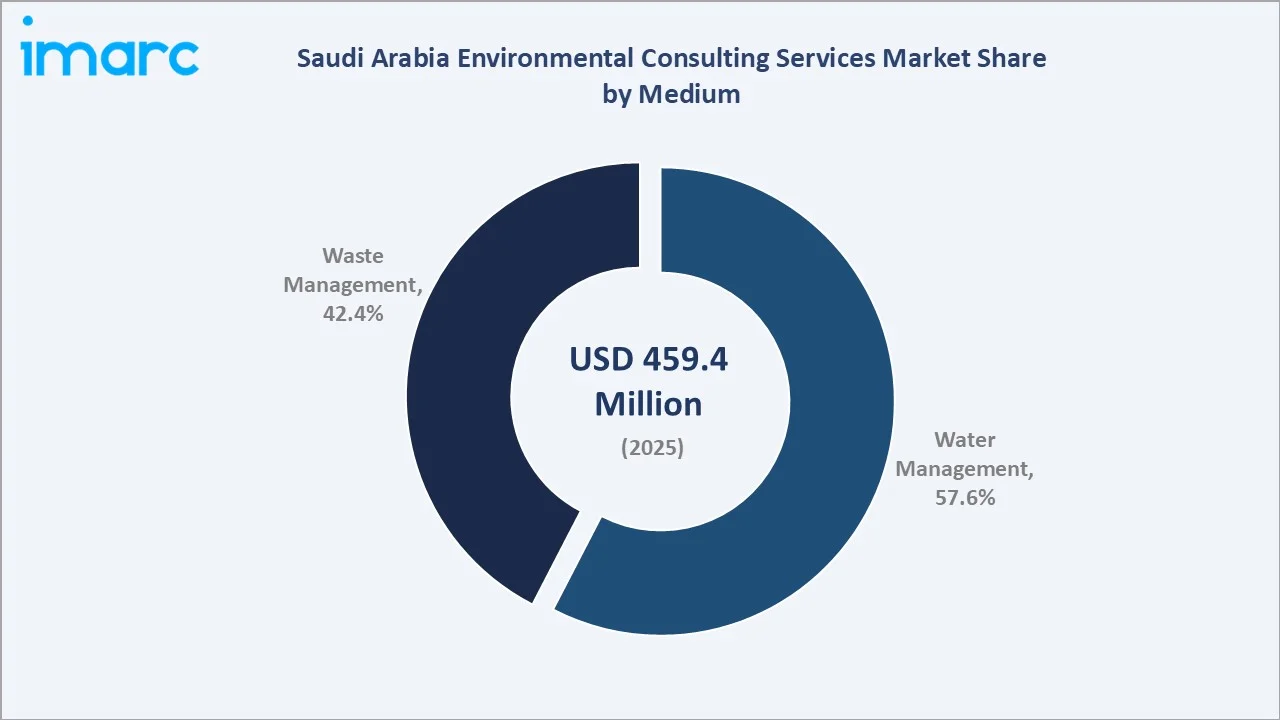
Water management leads at 57.6% (2025), driven by Saudi Arabia's acute freshwater scarcity, extensive desalination infrastructure environmental management requirements, industrial wastewater discharge compliance regulations, and Vision 2030 water efficiency program advisory.
To access detailed market analysis, Request Sample
Waste management at 42.4% reflects growing demand driven by the national waste management targets, increasing industrial waste generation from Vision 2030 manufacturing expansion, hazardous waste management compliance requirements for petrochemical and industrial clients, and emerging circular economy and waste-to-energy advisory services.
By Vertical
Energy and utilities lead at 29.8% (2025), through renewable energy transition EIA and permitting, Saudi Aramco's environmental compliance programs, utility infrastructure environmental monitoring, and energy sector decarbonization advisory aligned with Saudi Arabia's commitments.
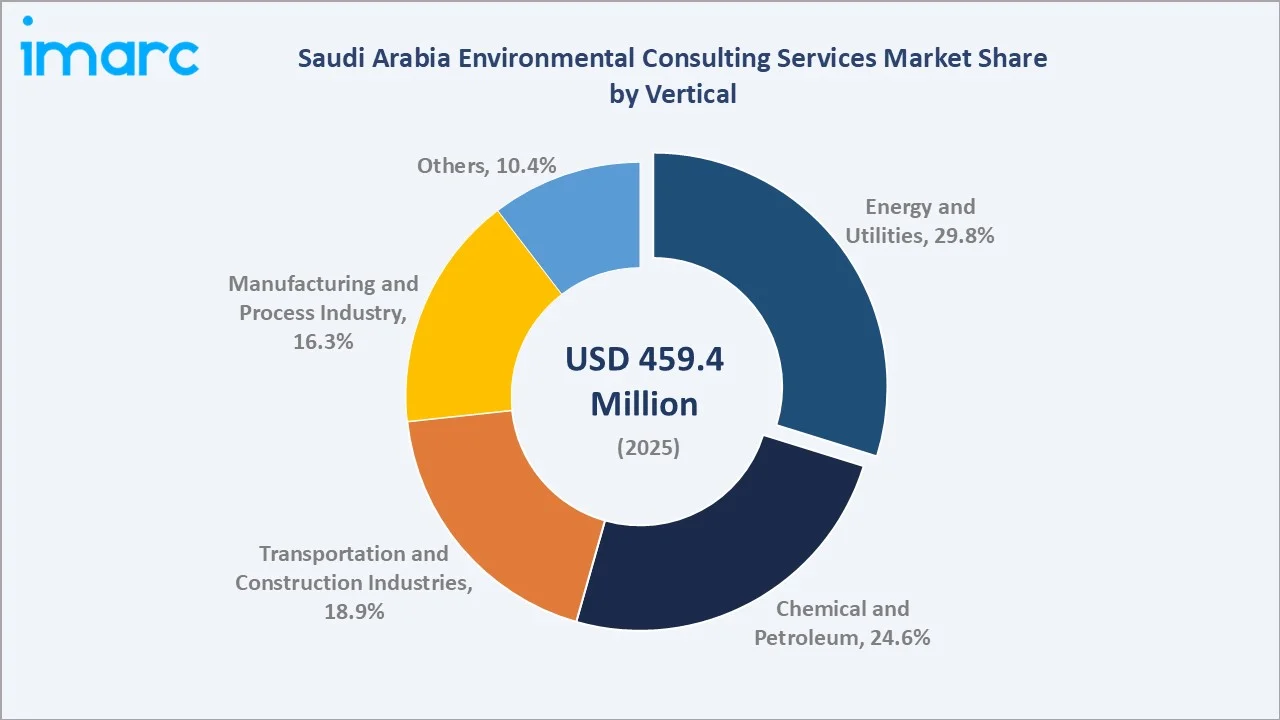
Chemical and petroleum at 24.6% reflects extensive environmental compliance programs, refinery and petrochemical facility EIA requirements, and growing sustainability reporting advisory. Transportation and construction at 18.9% serve mega-project EIA requirements. Manufacturing and process Industry at 16.3% reflects industrial zone environmental compliance.
Regional Market Insights
|
Region |
Share (2025) |
Key Saudi Arabia Environmental Consulting Services Market Drivers & Characteristics |
|
Northern & Central Region |
42.8% |
Reflecting the concentration of federal environmental regulatory bodies, Vision 2030 mega-project developments, and large industrial zones generating the Kingdom's highest environmental consulting service procurement volumes. |
|
Western Region |
24.7% |
Reflecting the Red Sea Project's extensive marine environmental assessment requirements, Makkah and Madinah urban expansion environmental compliance, Jeddah industrial zone compliance programs, and coastal ecosystem consulting demand. |
|
Eastern Region |
21.3% |
Reflecting Eastern Province oil field environmental programs, industrial city environmental compliance obligations, and petrochemical facility monitoring and audit services. |
|
Southern Region |
11.2% |
Reflecting growing environmental consulting demand from Vision 2030 regional development programs, ecotourism environmental management, industrial compliance, and agricultural environmental advisory. |
The Northern and Central region's 42.8% leadership reflects Riyadh's concentration of federal government environmental regulatory bodies alongside the NEOM project management offices whose development program requires one of the world's largest single-project environmental consulting programs. The Western region's 24.7% reflects the Red Sea Project's exceptional marine environmental consulting requirements in a globally significant coral reef ecosystem, combined with Jeddah's extensive industrial activity generating the Western Region's large compliance consulting base.
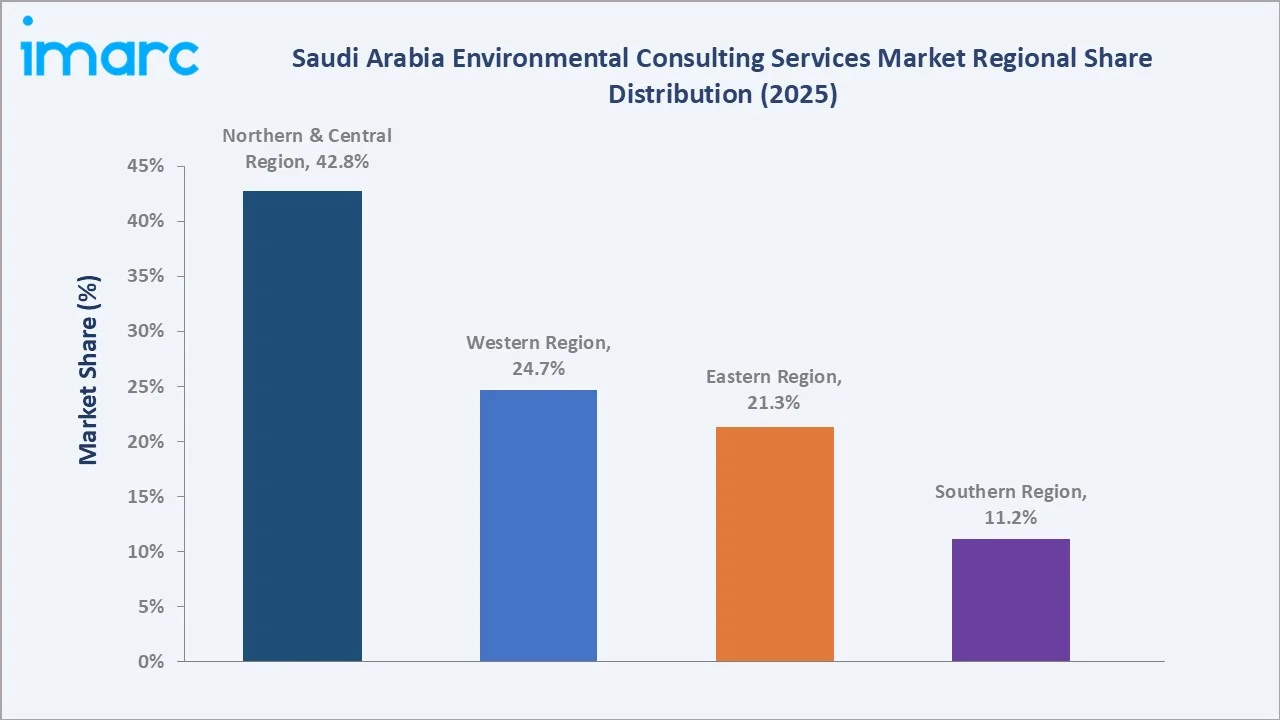
The Eastern region's 21.3% is anchored by one of the most extensive industrial environmental management programs globally, alongside the industrial cities that host some of the largest petrochemical complexes in the world requiring comprehensive environmental monitoring and compliance programs. The Southern region at 11.2% represents growing consulting demand as Vision 2030 regional development programs expand commercial activity.
Competitive Landscape
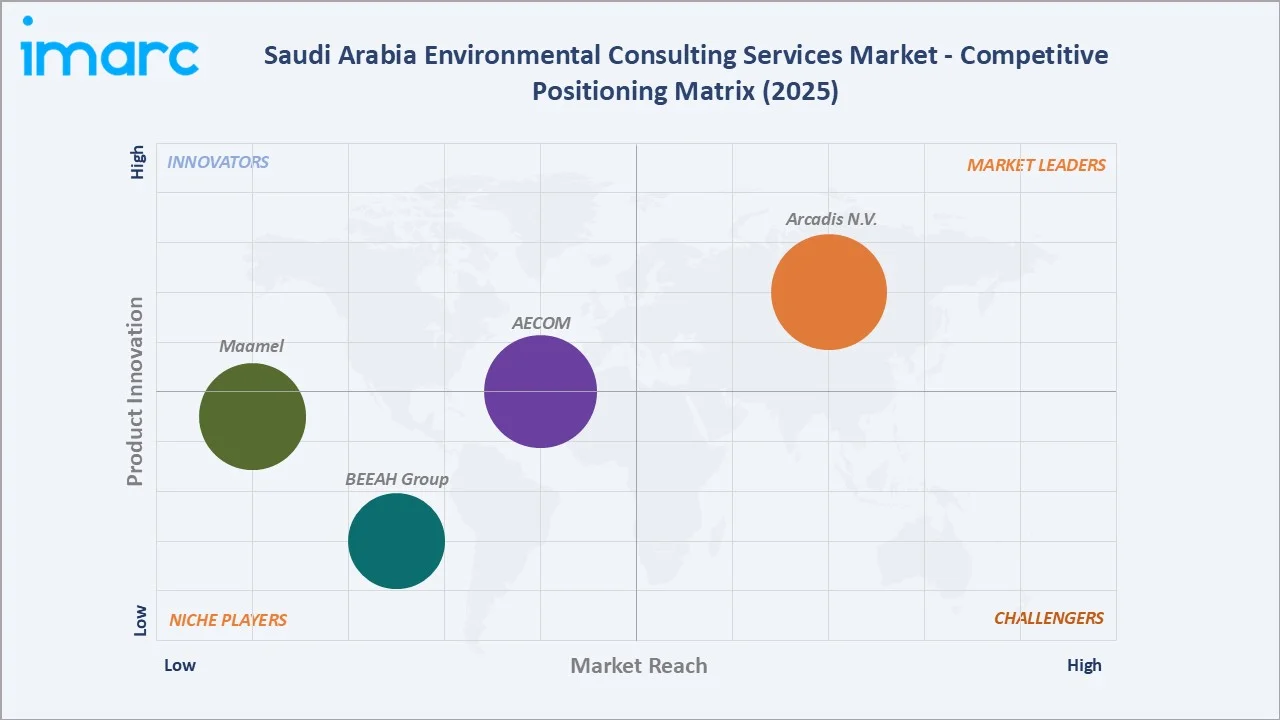
The Saudi Arabia environmental consulting services market is moderately concentrated, led by international multidisciplinary consultancies with global environmental expertise and established Saudi government relationships, alongside specialist environmental firms with deep technical expertise in specific service lines. Competition is driven by technical capability, regulatory knowledge depth, track record with Saudi clients, international accreditation, and ability to mobilize specialist personnel for complex multi-disciplinary assignments.
|
Company |
Key Services |
Market Position |
Core Strength |
|
Arcadis N.V. |
Environmental consulting services for complex projects |
Market Leader |
Arcadis N.V. provides critical environmental engineering, project management, and sustainability advisory services for major infrastructure and development projects across Saudi Arabia. |
|
AECOM |
EHS Management Consulting and Compliance |
Established Player |
AECOM acts as a leading infrastructure and environmental consulting partner in Saudi Arabia, supporting sustainable development and regulatory compliance for the Kingdom's mega-projects. |
|
BEEAH Group |
Waste Management Consultancy, Environmental Studies |
Niche Player |
BEEAH Group drives environmental sustainability and waste management transformation in Saudi Arabia through strategic partnerships, zero-waste infrastructure, and localized advisory services. |
|
Maamel |
Environmental Impact Assessment (EIA), Environmental Management System, Waste Management |
Established Player |
The National Laboratory Company Ltd. (MAAMEL) delivers environmental consulting and technical field services across Saudi Arabia through its specialized subsidiary, Arabian Environmental Science Ltd. Company (Arensco) |
Companies across the competitive landscape are investing in digital environmental monitoring capabilities, climate and ESG advisory service lines, local Saudi talent development, and specialist technical expertise in high-demand areas including marine ecology, carbon accounting, and circular economy advisory. The market is expected to attract additional specialist environmental consulting firms as Saudi Arabia's regulatory sophistication and environmental program scale continue to expand.
Key Company Profiles
Arcadis N.V.
Arcadis N.V. is a design, engineering, and management consulting firm with dedicated water and environmental consulting practices that are highly relevant to Saudi Arabia's environmental challenges. Arcadis Arabia serves Saudi Arabia's water sector clients with internationally recognized water resource management, water quality consulting, and environmental advisory services. Arcadis' global water leadership, recognized through multiple international awards for water management innovation, provides Saudi clients with access to leading-edge water management expertise and international best-practice benchmarking that domestic consultants cannot match.
- Key Services: Environmental consulting services for complex projects.
- Strategic Focus: Strengthening Arcadis Arabia's position as the leading water-environment consulting firm in Saudi Arabia through expansion of desalination and water reuse environmental advisory services, developing digital water management and smart utility consulting capabilities aligned with Saudi Arabia's National Water Strategy, and building an independent Saudi Arabia water consulting practice with local technical leadership.
Maamel
Maamel is an environmental services provider operating in Saudi Arabia, supporting organizations with environmental assessment, compliance, monitoring, and sustainability-related requirements. The company serves industrial, commercial, and infrastructure clients seeking to meet regulatory obligations and improve environmental performance. Its service portfolio contributes to the growing demand for specialized environmental consulting across the Kingdom.
- Key Services: Environmental Impact Assessment (EIA), Environmental Management System, Waste Management.
- Strategic Focus: Strengthening its environmental consulting capabilities through compliance support, environmental monitoring, and sustainability-oriented services. Its strategy emphasizes helping Saudi organizations meet regulatory requirements while improving environmental performance and operational efficiency.
Market Concentration Analysis
The Saudi Arabia environmental consulting services market exhibits moderate concentration at the major project level, with international firms collectively commanding approximately 40-45% of total market revenues through their large government and client relationships. The remaining market share is distributed among specialist environmental firms, engineering consultancies with environmental add-on services, and domestic Saudi environmental companies serving the mid-market compliance segment. Market concentration is expected to remain moderate through 2034, with new service lines in ESG, climate, and nature-based solutions creating opportunities for specialist entrants alongside established multi-disciplinary consultancies.
Investment & Growth Opportunities
Highest Growth Segments
ESG and corporate sustainability advisory, climate change decarbonization strategy, marine and coastal environmental consulting, circular economy and waste-to-energy advisory, and digital environmental monitoring platforms represent the highest-growth investment vectors in the Saudi Arabia environmental consulting services market through 2034.
Investment Themes
- Saudi national environmental talent development: Investing in structured graduate development programs for Saudi environmental scientists, ecologists, and engineers addresses the critical Saudization compliance challenge while building domestic technical capability. Firms that build credible Saudi national workforce pipelines gain competitive advantage in government procurement evaluation criteria that increasingly weight local content and knowledge transfer commitments.
- Digital environmental monitoring platform investment: Developing proprietary digital environmental monitoring platforms integrated with digital reporting requirements creates recurring revenue service models and switching cost advantages. IoT sensor network deployment, satellite remote sensing analytics, and cloud-based environmental data management platforms generate subscription revenue streams that complement traditional project-based consulting fees.
Future Market Outlook (2026-2034)
The Saudi Arabia environmental consulting services market is projected to grow from USD 459.4 Million in 2025 to USD 491.9 Million in 2026, reaching USD 848.8 Million by 2034, exhibiting a CAGR of 7.06% during 2026-2034. The market is projected to reach an anchor value of USD 646.1 Million by 2030, representing the mid-period milestone at which Saudi Arabia's 2030 NDC commitments create peak demand for carbon accounting and climate advisory alongside Vision 2030 mega-project environmental monitoring programs reaching full operational scale.
Three structural forces will define the Saudi Arabia environmental consulting market through 2034. First, the progressive maturation and enforcement intensification of Saudi Arabia's environmental regulatory framework will continuously expand the institutional mandate for professional environmental consulting. Second, Saudi Arabia's climate commitments will generate a sustained and growing advisory demand stream that is largely independent of project-specific development activity. Third, Vision 2030's long-term infrastructure development pipeline ensures sustained project-level environmental consulting demand through 2034.
Research Methodology
Primary Research
Primary research comprised in-depth interviews with environmental consulting firm partners and technical directors, Saudi government environmental agency officials, environmental managers at Saudi industrial companies, and industry association representatives. These discussions validated market size estimates, assessed service demand trends by medium and vertical, evaluated competitive dynamics, and provided insights into regulatory developments and future market evolution.
Secondary Research
Secondary research encompassed environmental regulation publications, company annual reports, Saudi Green Initiative program documentation, Vision 2030 environmental chapter publications, major environmental consulting firm annual reports, ESG disclosure requirements, and industry publications covering GCC and Saudi Arabia environmental services markets.
Forecasting Models
Forecasting models incorporated historical environmental consulting market revenue trends, regulatory enforcement expansion trajectories, Vision 2030 development investment schedules, corporate sustainability reporting adoption rates, and macroeconomic indicators including industrial production growth and environmental compliance budget trends across key vertical sectors.
Saudi Arabia Environmental Consulting Services Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Services Covered | Investment Assessment and Auditing, Permitting and Compliance, Project and Information Management Monitoring and Testing, Others |
| Mediums Covered | Water Management, Waste Management |
| Verticals Covered | Energy and Utilities, Chemical and Petroleum, Manufacturing and Process Industry, Transportation and Construction Industries, Others |
| Regions Covered | Northern and Central Region, Western Region, Eastern Region, Southern Region |
| Companies Covered | Arcadis N.V., AECOM, BEEAH Group, Maamel, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Saudi Arabia environmental consulting services market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Saudi Arabia environmental consulting services market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Saudi Arabia environmental consulting services industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Saudi Arabia Environmental Consulting Services Market Report
The Saudi Arabia environmental consulting services market size is estimated at USD 491.9 Million in 2026, driven by Vision 2030 EIA requirements, Saudi Arabia's 2060 Net Zero commitment generating decarbonization advisory demand, enforcement intensification driving compliance consulting, and renewable energy transition environmental permitting requirements.
The Saudi Arabia environmental consulting services market is projected to grow at a CAGR of 7.06% during 2026-2034, sustained by regulatory enforcement expansion, ESG and climate advisory demand growth, ongoing mega-project environmental monitoring, and progressive adoption of digital environmental management systems.
The market is projected to reach approximately USD 646.1 Million by 2030, representing the mid-period milestone at which Saudi Arabia's 2030 targets create peak climate advisory demand and Vision 2030 mega-project monitoring programs reach full operational scale simultaneously.
Water management leads with a 57.6% share in 2025, through Saudi Arabia's acute freshwater scarcity challenges, extensive desalination infrastructure environmental management requirements, industrial wastewater discharge compliance regulations, and Vision 2030 water efficiency program advisory for clients.
Energy and utilities lead with a 29.8% share in 2025, through renewable energy transition EIA and permitting requirements for new solar installations, environmental compliance programs, utility infrastructure monitoring, and energy sector decarbonization advisory aligned with Saudi Arabia's commitments.
The Northern and Central region leads with a 42.8% share in 2025, driven by the concentration of federal environmental regulatory bodies, Vision 2030 mega-project developments, large industrial zones, and the highest density of environmental consulting procurement centers in the Kingdom.
Key companies include Arcadis N.V., AECOM, BEEAH Group, and Maamel, among others.
The Saudi Arabia environmental consulting services market is projected to reach USD 848.8 Million by 2034, driven by regulatory maturation, expanded ESG advisory requirements, climate consulting growth, and sustained project-level demand from Saudi Arabia's long-term infrastructure development pipeline.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade