Saudi Arabia Forging Market Size, Share, Trends and Forecast by Technique, Material, Industry, and Region, 2026-2034
Saudi Arabia Forging Market Size, Share, Trends & Forecast (2026-2034)
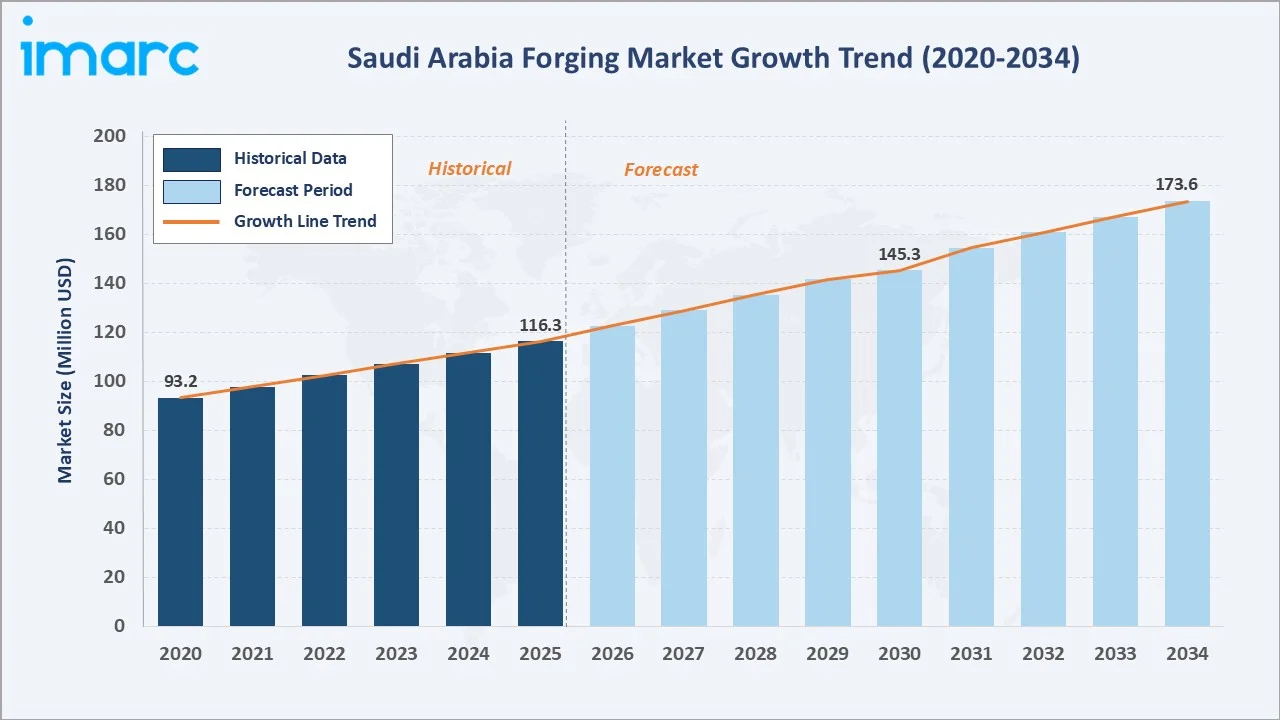
The Saudi Arabia forging market reached USD 116.3 Million in 2025 and is projected to reach USD 173.6 Million by 2034, growing at a CAGR of 4.55% during 2026-2034. The market is driven by Saudi Vision 2030 industrial diversification, expanding oil and gas sector requirements, and growing local content mandates under IKTVA. Closed Die Forging dominates at 51.8%. Steel Alloys lead material at 47.3%. Eastern Region commands 39.4% of the market share.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 116.3 Million |
|
Forecast Market Size (2034) |
USD 173.6 Million |
|
CAGR (2026-2034) |
4.55% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Technique |
Closed Die Forging (51.8%, 2025) |
|
Dominant Material |
Steel Alloys (47.3%, 2025) |
|
Leading Region |
Eastern Region (39.4%, 2025) |
The Saudi Arabia forging market expanded from USD 93.2 Million in 2020 to USD 116.3 Million in 2025, anchored at USD 145.3 Million in 2030, and forecast to reach USD 173.6 Million by 2034. Vision 2030 industrial initiatives and oil sector expansion supported consistent above-trend growth throughout 2022-2025.
To get more information on this market, Request Sample
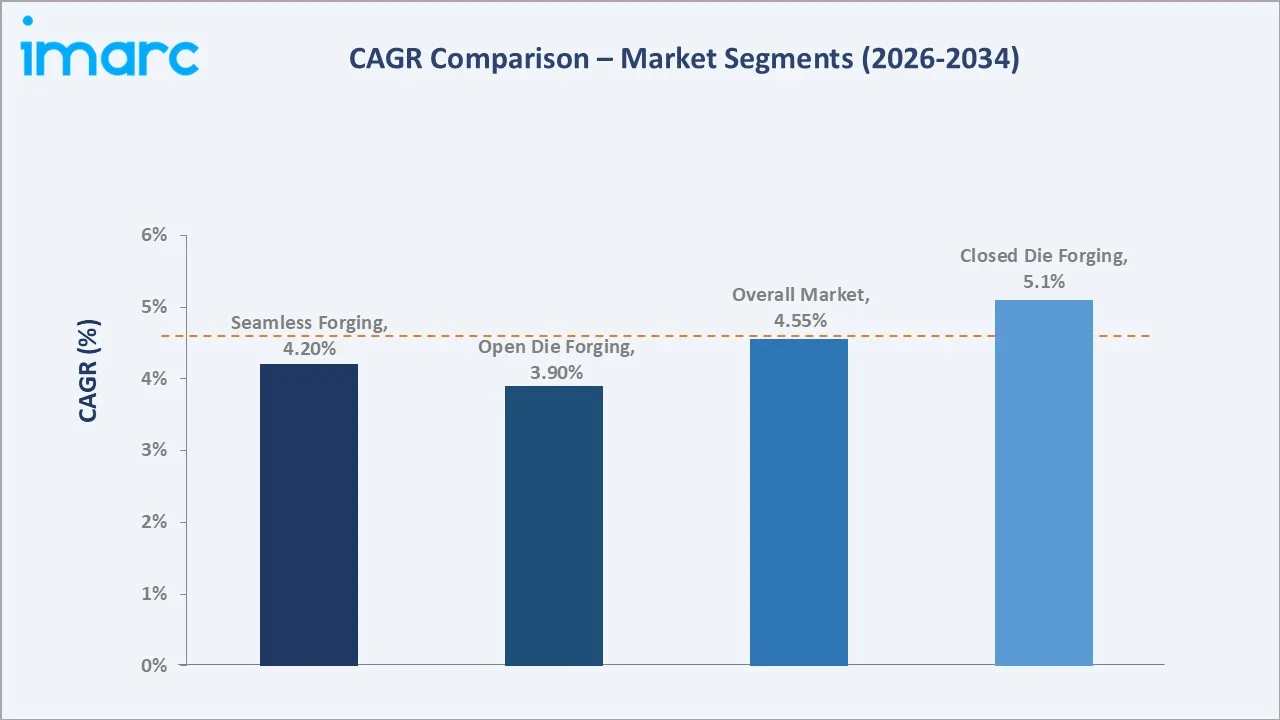
Closed Die Forging grows steadily at ~5.1% CAGR supported by precision component demand from oil and gas and aerospace. Steel Alloys maintain dominance through infrastructure and heavy industry requirements. Eastern Region leads through concentrated industrial activity around Jubail and Dammam.
Executive Summary
The Saudi Arabia forging market reached USD 116.3 Million in 2025, representing a strategically important intersection of industrial manufacturing, energy sector supply chain, and Vision 2030 diversification objectives. The market encompasses forged components across technique, material, industry, and regional dimensions.
Closed Die Forging at 51.8% dominates through precision requirements of oil and gas components. Steel Alloys at 47.3% lead through structural and mechanical applications across industries. Eastern Region at 39.4% leads through the concentration of industrial zones and Aramco supply chain activity.
Key Market Insights
|
Insight |
Data |
|
Dominant Technique |
Closed Die Forging - 51.8% share (2025) |
|
Dominant Material |
Steel Alloys - 47.3% market share (2025) |
|
Leading Region |
Eastern Region - 39.4% market share |
|
Market Opportunity |
Vision 2030 industrial zones; IKTVA local content; oil & gas MRO; aerospace defense procurement; heavy equipment manufacturing |
Key Analytical Observations Supporting the Above Data:
- Closed Die Forging at 51.8%: The closed die forging segment dominates due to its ability to produce near-net-shape components with superior mechanical properties, preferred for high-precision parts used in oil and gas valves, flanges, and aerospace structural elements, aligning with Aramco stringent vendor qualification standards.
- Steel Alloys at 47.3%: Steel alloys dominate because of their widespread applicability across oil and gas, heavy equipment, and construction. Their availability through HADEED and cost efficiency support adoption across both domestic and export-oriented forging operations.
- Eastern Region at 39.4%: Eastern Region leads through its industrial concentration in Jubail Industrial City, proximity to oil fields, and established supplier networks serving Saudi Aramco and SABIC operations.
Saudi Arabia Forging Market Overview
The Saudi Arabia forging market encompasses the production of forged metal components across closed die, open die, and seamless forging techniques using steel alloys, aluminum alloys, nickel-based alloys, and titanium alloys for automotive, aerospace, railway, heavy equipment, and wind power industries.
Macroeconomic factors include Saudi Vision 2030 industrial diversification, rising local content requirements under IKTVA, government investment in downstream manufacturing, and expanding energy sector capital expenditure programs creating sustained demand for locally forged components.
Market Dynamics
To evaluate market opportunities, Request Sample
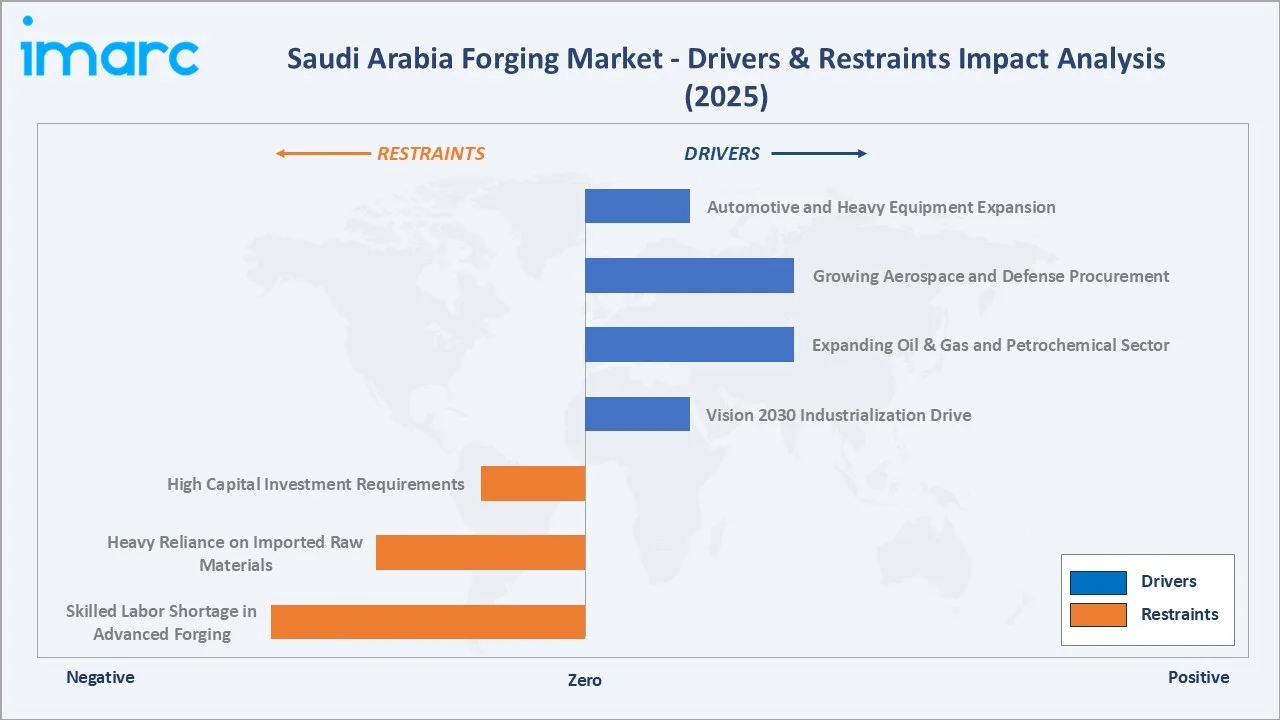
Market Drivers
- Vision 2030 Industrialization Drive: Saudi Vision 2030 is increasing investment in domestic manufacturing and industrial infrastructure. Government programs support establishment of forging facilities to reduce import dependence for critical industrial components. The NIDLP actively allocates capital toward forging and metal fabrication segments to develop an internationally competitive manufacturing base.
- Expanding Oil & Gas and Petrochemical Sector: Saudi Aramco and SABIC ongoing capital expenditure programs require substantial volumes of forged valves, flanges, fittings, and pressure vessel components. Planned refinery expansions and new petrochemical complexes under Vision 2030 create sustained multi-year demand for domestically sourced forged components meeting international API and ASME standards.
- Growing Aerospace and Defense Procurement: Saudi Arabia expanding defense budget and Vision 2030 push to localize 50% of defense spending create growing demand for precision forgings. The Saudi Arabian Military Industries (SAMI) framework encourages domestic manufacturing partnerships for aerospace structural components, engine parts, and landing gear components.
- Automotive and Heavy Equipment Expansion: New automotive manufacturing investments and heavy equipment production initiatives under Vision 2030 increase demand for forged drivetrain, suspension, and structural components. NEOM and Red Sea project construction activities also drive demand for forged components in construction equipment and infrastructure machinery.
Market Restraints
- High Capital Investment Requirements: Establishing advanced forging facilities requires significant capital investment in forge presses, heat treatment equipment, and quality inspection systems. High financing costs and long payback periods create barriers for new market entrants, limiting competitive dynamics and capacity expansion in price-sensitive segments.
- Heavy Reliance on Imported Raw Materials: Saudi Arabia lacks domestic iron ore production, creating dependence on imported steel billets, aluminum ingots, and specialty alloys. Supply chain disruptions and commodity price volatility increase production cost unpredictability, reducing margin stability for forging operators.
- Skilled Labor Shortage in Advanced Forging: Advanced forging operations require metallurgical expertise, CNC programming skills, and NDT certification that are scarce in the domestic workforce. Dependence on expatriate technical staff increases operational costs and creates workforce continuity risks.
Market Opportunities
- IKTVA Local Content Expansion: Saudi Aramco IKTVA program mandates increasing local content percentages in procurement. Forging companies achieving IKTVA certification gain preferential access to Aramco substantial supply chain, creating a structural revenue opportunity for domestically established forging operations with API-compliant quality systems.
- Advanced Alloy Forging for Aerospace: Growing defense and commercial aerospace activity creates demand for titanium and nickel-based alloy forgings. Building capability in advanced alloy forging positions Saudi manufacturers for high-value export markets and long-term supply agreements with international aerospace OEMs.
Market Challenges
- International Competition and Certification Requirements: Saudi forging companies compete with established international producers from India, China, and Europe who offer lower per-unit costs through scale. Meeting international certification requirements such as NADCAP for aerospace forgings requires sustained investment in quality systems.
- Technology Gap in Advanced Forging Techniques: Advanced isothermal forging and precision closed die processes for aerospace components require simulation software, specialized tooling, and tightly controlled process parameters beyond current domestic capabilities.
Emerging Market Trends
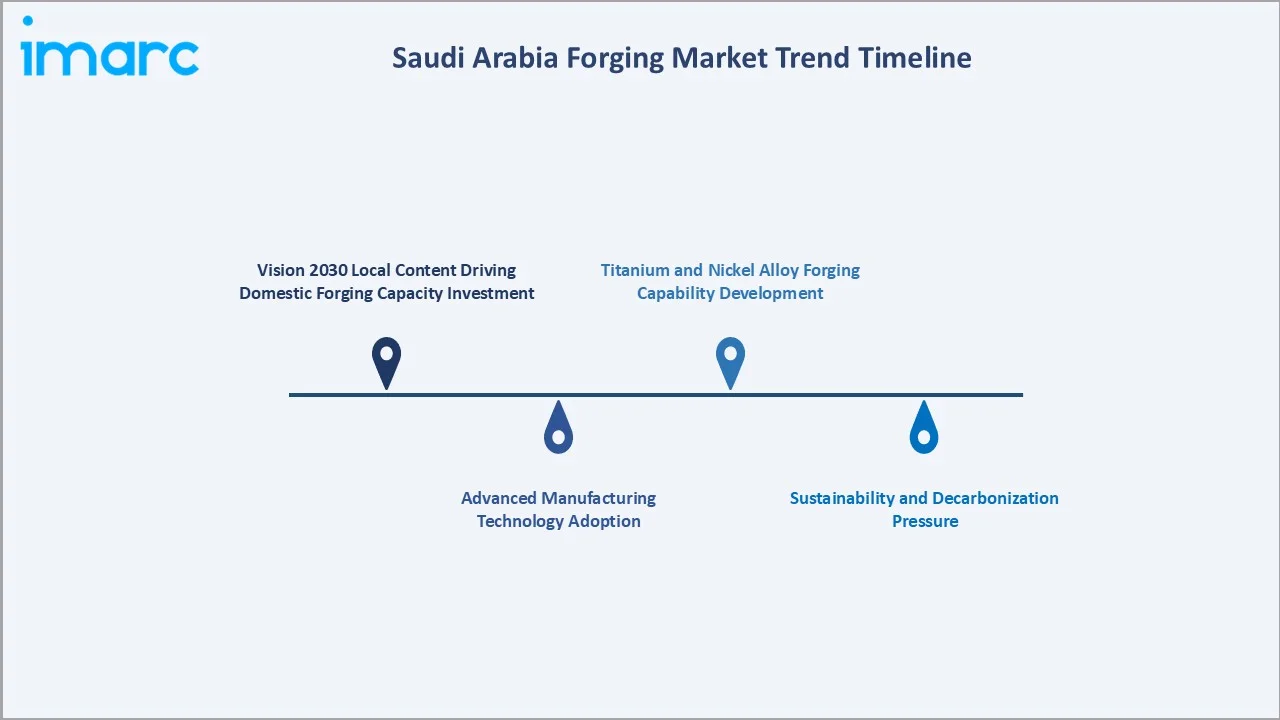
1. Vision 2030 Local Content Driving Domestic Forging Capacity Investment
IKTVA and National Industrial Development programs accelerate domestic forging capacity addition. International forging companies are establishing joint ventures with Saudi partners to qualify for Aramco vendor lists, transferring technology and creating knowledge infrastructure for advanced forging operations within the Kingdom.
2. Advanced Manufacturing Technology Adoption
Saudi forging companies are adopting simulation software, automated forge presses, and real-time process monitoring to improve dimensional accuracy and reduce reject rates. Several Jubail-based forging facilities announced in 2025 capital investment programs for CNC vertical machining centers and advanced ultrasonic testing equipment.
3. Sustainability and Decarbonization Pressure
Saudi Aramco 2030 net-zero emissions ambition and international customer ESG requirements are driving forging operators to invest in energy-efficient furnace technology and waste heat recovery. Induction heating systems and regenerative burner technology reduce energy consumption and carbon intensity of forging operations.
4. Titanium and Nickel Alloy Forging Capability Development
Growing aerospace defense procurement and NEOM project requirements are creating demand for advanced alloy forgings previously sourced entirely through imports. Strategic capability development in titanium and nickel alloy forging enables Saudi manufacturers to capture higher-margin defense and aerospace contracts within the Vision 2030 supply chain localization framework.
Industry Value Chain Analysis
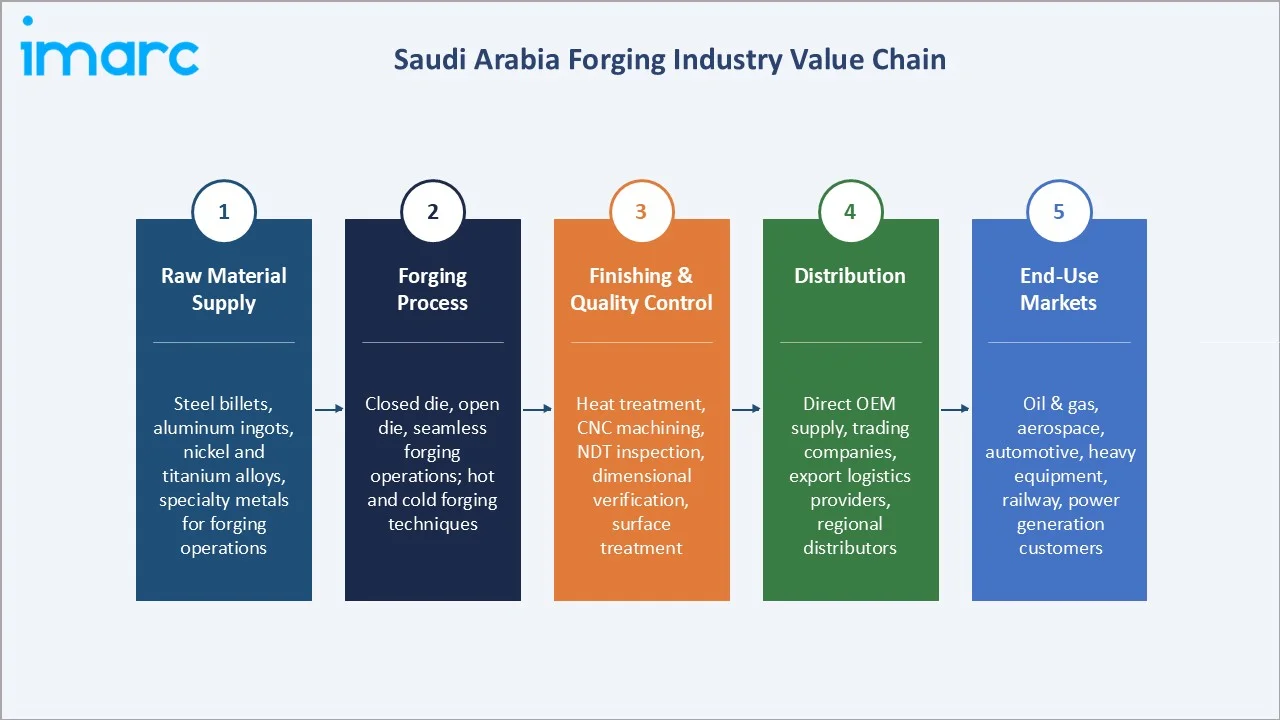
The Saudi Arabia forging value chain integrates raw material sourcing, forging process operations, finishing and quality control, distribution, and end-use market delivery across a structured set of participants aligned to national industrial development and energy sector supply chain requirements.
|
Stage |
Key Participants |
|
Raw Material Supply |
Steel billets, aluminum ingots, nickel and titanium alloys, specialty metals for forging operations |
|
Forging Process |
Closed die, open die, and seamless forging operations; hot and cold forging techniques for precision components |
|
Finishing & Quality Control |
Heat treatment, CNC machining, NDT inspection, dimensional verification, and surface treatment services |
|
Distribution |
Direct OEM supply channels, trading companies, export logistics providers, and regional distributors |
|
End-Use Markets |
Oil and gas operators, aerospace and defense agencies, automotive OEMs, heavy equipment manufacturers, and power generation companies |
Technology Landscape in the Saudi Arabia Forging Industry
Closed Die Forging Technology
Closed die forging technology enables the production of near-net-shape components with superior dimensional accuracy and mechanical properties by confining the workpiece between shaped dies during the forging process. This technology is critical for producing high-pressure valves, flanges, fittings, and structural aerospace components to API 6A and ASME standards required by Saudi Aramco and SABIC vendor qualification programs. As demand for precision-forged components in oil and gas and aerospace defense applications expands under Vision 2030, closed die forging technology investment in Saudi Arabia is accelerating. In 2025, several Jubail-based forging facilities announced capital programs for advanced closed die press capacity and simulation-aided die design.
Advanced Alloy Forging Technology
Advanced alloy forging technology encompasses isothermal forging, precision hot forging, and near-net-shape processing of titanium alloys, nickel-based superalloys, and high-strength aluminum alloys for aerospace, defense, and high-temperature oil and gas service applications. These processes require tightly controlled furnace atmospheres, precise temperature management, and specialized die materials to achieve the microstructural properties demanded by NADCAP and aerospace OEM specifications. Saudi Arabia is investing in advanced alloy forging capability under Vision 2030 defense localization programs, with titanium and nickel alloy forging growing at ~5.2% and ~4.9% CAGR respectively during 2026-2034, driven by growing SAMI procurement and aerospace supply chain localization targets.
Automated Forge Press and CNC Integration
Automated forge press and CNC integration technology enables real-time monitoring, closed-loop process control, and dimensional verification across forging operations. Servo-hydraulic press systems with programmable stroke profiles improve repeatability and reduce material waste in high-volume oil and gas component production. CNC vertical machining centers integrated with ultrasonic NDT inspection allow forging facilities to achieve the dimensional tolerances and traceability documentation required for Aramco IKTVA vendor qualification and API certification. In 2025, Saudi forging manufacturers accelerated investment in automated forge press capacity and integrated CNC machining lines to improve yield rates and reduce dependence on expatriate technical labor in precision forging operations.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Technique |
Closed Die Forging |
51.8% |
2025 |
|
Material |
Steel Alloys |
47.3% |
2025 |
|
Industry |
🔒 |
🔒 |
2025 |
|
Region |
Eastern Region |
39.4% |
2025 |

By Technique
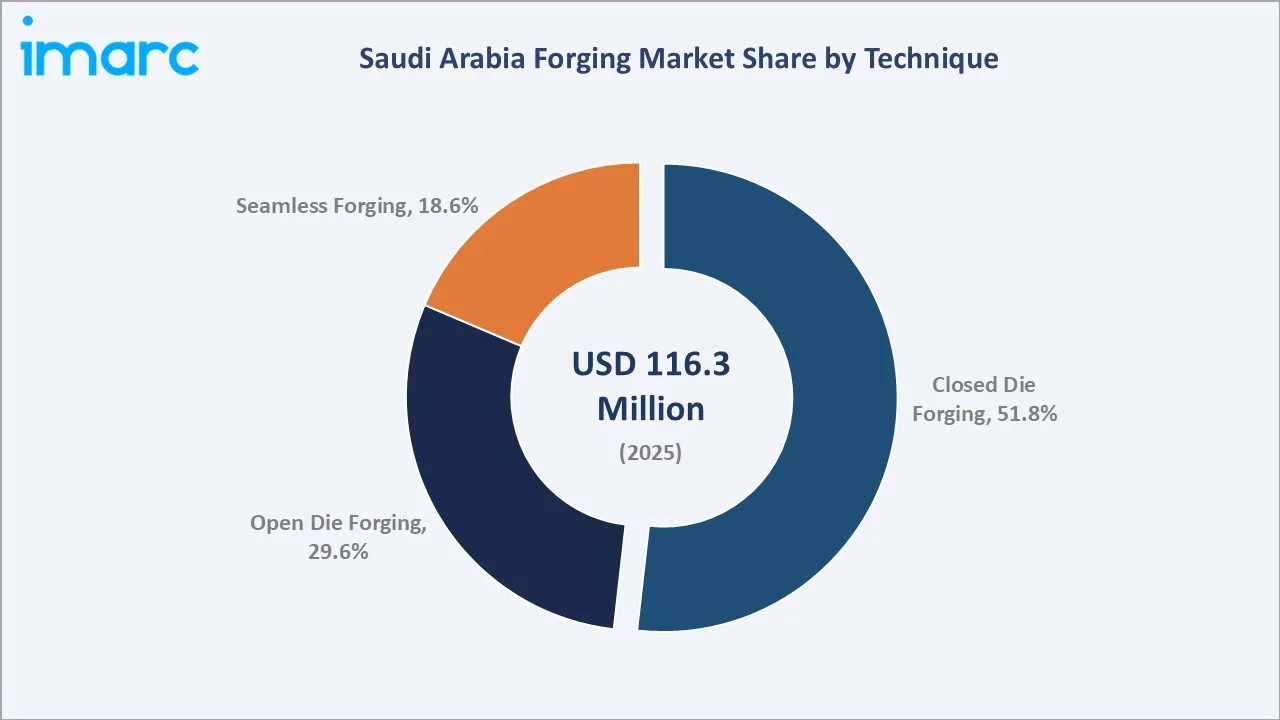
Closed Die Forging leads at 51.8% (2025). The closed die forging segment dominates through its ability to produce high-precision near-net-shape components required by oil and gas valves, flanges, and aerospace structural applications. Closed Die Forging grows at ~5.1% CAGR during 2026-2034, driven by increasing API and ASME compliance requirements across Aramco vendor supply chains and growing aerospace defense procurement under Vision 2030.
To access detailed market analysis, Request Sample
Open Die Forging at 29.6% serves heavy industrial applications requiring large cross-section forgings. Open Die Forging grows at ~3.9% CAGR through demand for heavy shafts, cylinders, and pressure vessel blanks from refining and power generation sectors. Seamless Forging at 18.6% addresses pipeline and pressure vessel ring applications critical to refining and petrochemical sectors, growing at ~4.2% CAGR.
By Material
Steel Alloys lead at 47.3% (2025). Steel alloys dominate through their cost efficiency and broad applicability across oil and gas, heavy equipment, and construction applications. HADEED domestic steel production provides supply chain stability for carbon and alloy steel forgings. Steel Alloys grow at ~4.3% CAGR during 2026-2034, maintaining segment leadership through sustained oil and gas and infrastructure investment.
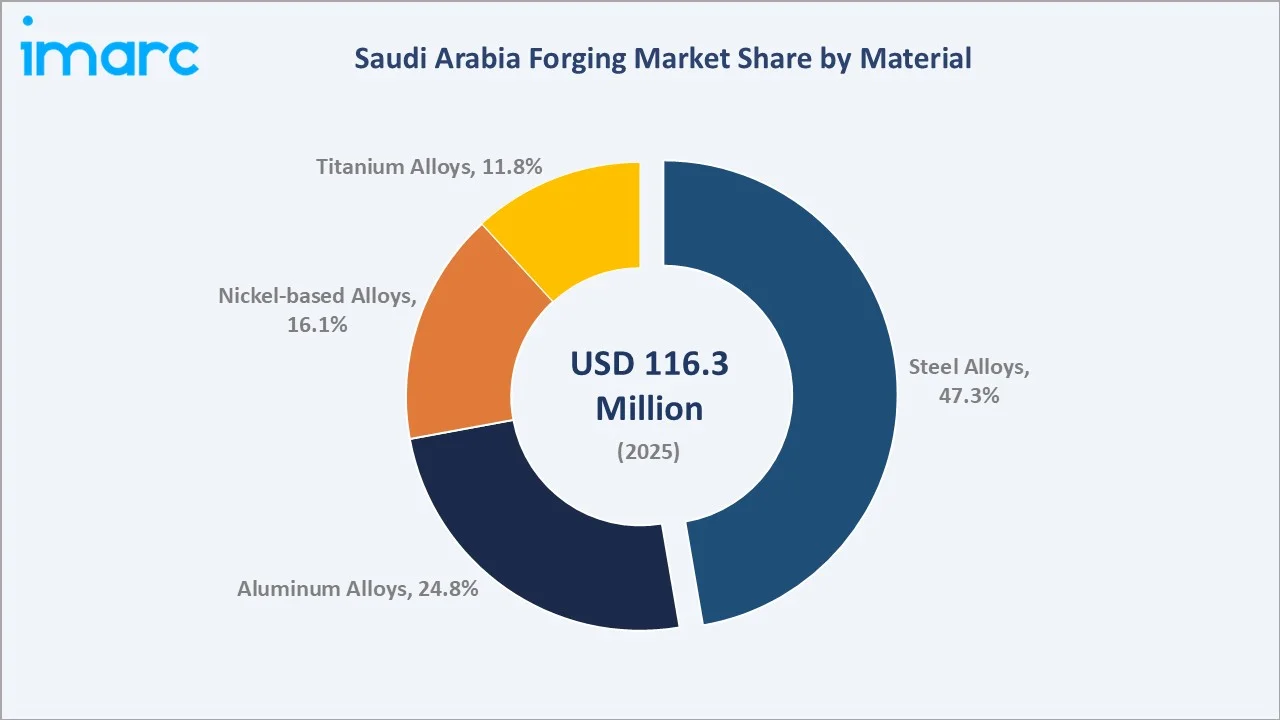
Aluminum Alloys at 24.8% reflect growing automotive and aerospace demand, growing at ~5.5% CAGR - the fastest among all material segments - through Vision 2030 automotive manufacturing expansion and lightweighting demand. Nickel-based Alloys at 16.1% serve high-temperature oil and gas and gas turbine applications, growing at ~4.9% CAGR. Titanium Alloys at 11.8% address aerospace and defense precision component requirements, growing at ~5.2% CAGR as Vision 2030 defense localization programs expand.
Regional Market Insights
|
Region |
Share (2025) |
Key Saudi Arabia Forging Market Drivers & Characteristics |
|
Eastern Region |
39.4% |
Driven by concentration of Saudi Aramco operations, Jubail Industrial City, and established petrochemical and heavy industry supply chains requiring locally forged components. |
|
Northern and Central Region |
28.6% |
Driven by Riyadh industrial zones, government procurement centers, and Vision 2030 industrial diversification programs allocating manufacturing investment across the central corridor. |
|
Western Region |
21.3% |
Supported by Jeddah industrial estates, port-related industrial activity, marine infrastructure demand, and growing manufacturing investments targeting export-oriented forging production. |
|
Southern Region |
10.7% |
Emerging industrial projects, NEOM project adjacency, and new Special Economic Zones supporting manufacturing growth in a historically underserved industrial region. |
Eastern Region 39.4% market leadership is anchored by Saudi Aramco extensive vendor qualification programs, Jubail Industrial City dense petrochemical and heavy industry cluster, and decades of industrial infrastructure investment creating a forging demand ecosystem unmatched in other Saudi regions.
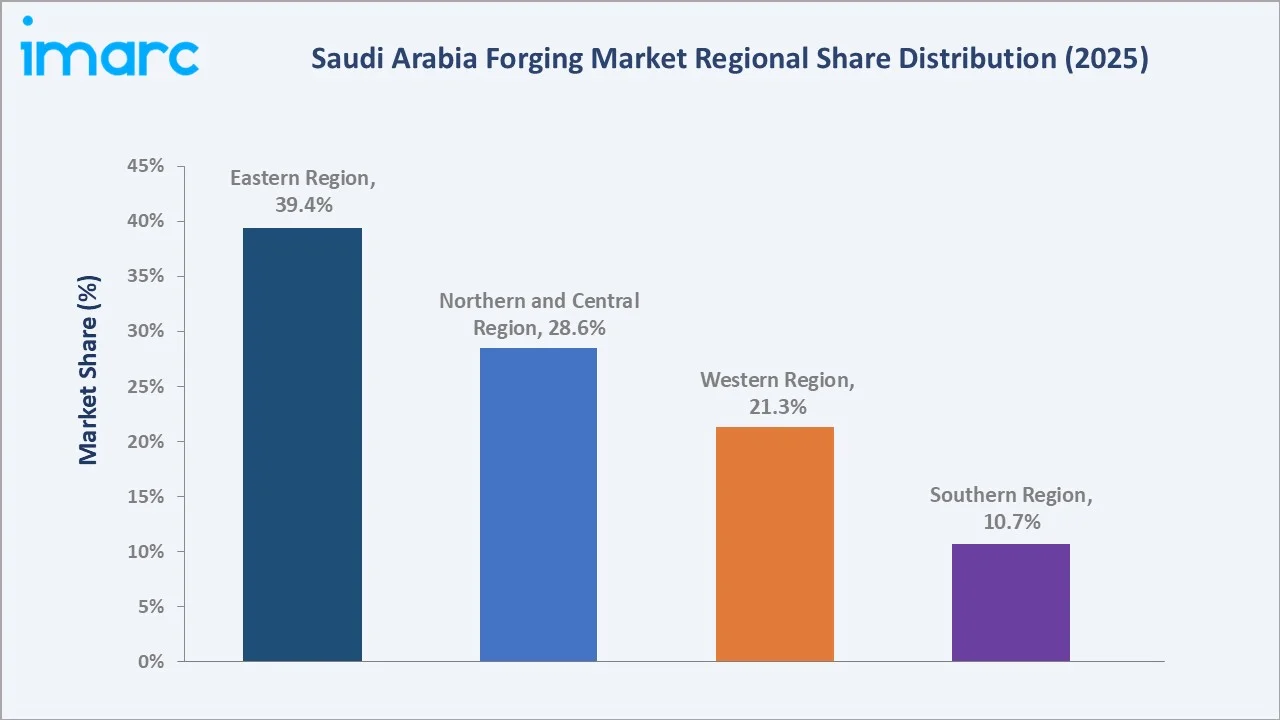
Northern and Central Region 28.6% reflects Riyadh expanding industrial base and government procurement concentration. Western Region 21.3% captures Jeddah growing manufacturing sector and marine infrastructure demand. Southern Region at 10.7% represents the fastest-growing regional opportunity under NEOM project supply chain development.
Competitive Landscape
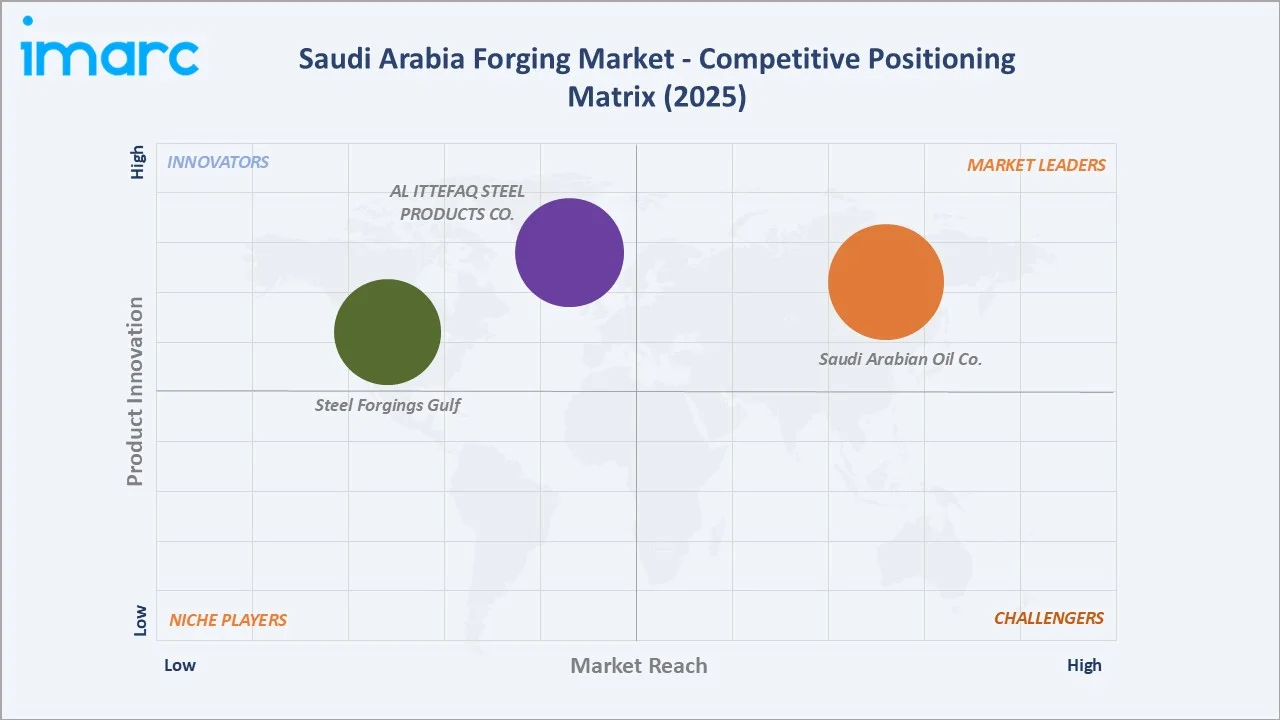
The Saudi Arabia forging market competitive landscape encompasses distinct tiers: domestic forging manufacturers, joint venture operations with international partners, and imported forgings from global suppliers qualifying against Aramco and SAMI vendor requirements.
|
Company Name |
Key Products |
Market Position |
Core Strength |
|
Saudi Arabian Oil Co. |
Steel forging |
Market Leader |
Integrated supply chain position with direct Aramco procurement access and API/ASME certification capability. |
|
AL ITTEFAQ STEEL PRODUCTS CO. |
Carbon steel forgings, pipes, flanges |
Established Player |
Vertically integrated steel processing with forging capability serving Saudi infrastructure and energy sectors. |
|
Steel Forgings Gulf |
Forged fittings, flanges, buttweld fittings |
Established Player |
Leading MENA supplier of API, ASTM, ASME-compliant steel components to oil and gas, petrochemical, and power sectors; Aramco and ADNOC approved with 10+ years MENA presence. |
Vision 2030 supply chain localization creates structural competitive advantage for domestically established forging operations with IKTVA certification. Consolidation is occurring at the technology platform tier through joint ventures between domestic industrial groups and international precision forging specialists.
Key Company Profiles
Saudi Arabian Oil Co.
Saudi Arabian Oil Co. operates as the integrated engineering arm of Saudi Aramco, managing vendor qualification, technical specifications, and supply chain development for all forged components used across Aramco exploration, production, and downstream operations.
- Key Products: API 6A wellhead components, pressure-rated flanges, valve bodies, pipeline fittings.
- Recent Developments: In August 2026, Saudi Aramco announced agreements and a Memorandum of Understanding (MoU) with French companies with a potential combined value of more than $3.7 billion. The partnerships cover drilling equipment, Oil Country Tubular Goods (OCTG), and collaboration in industrial AI, virtual twins, digital twins and related technologies. The initiatives are expected to strengthen Aramco’s supply-chain resilience, improve operational efficiency, support technology transfer and develop industrial capabilities in Saudi Arabia and France.
- Strategic Focus: Maximizing IKTVA-compliant domestic forging supply while maintaining API and ASME certification standards for critical oil and gas service components.
AL ITTEFAQ STEEL PRODUCTS CO.
AL ITTEFAQ STEEL PRODUCTS CO. operates vertically integrated steel processing facilities in Saudi Arabia, encompassing electric arc furnace steelmaking, rolling, and forging operations. The group supplies steel forgings, pipes, and structural components to oil and gas, construction, and heavy industry customers across the Kingdom.
- Key Products: Carbon steel forgings, seamless pipes, flanges, and structural components for oil and gas and construction sectors.
- Strategic Focus: Expanding forging capacity and certification scope to qualify for Aramco and SABIC vendor lists, capturing local content program requirements across the oil and gas supply chain.
Steel Forgings Gulf
Steel Forgings Gulf (SFG) is a leading supplier of high-quality steel components, headquartered in the Hamriyah Free Zone, Sharjah, UAE. With over 10 years of operations across the MENA region, SFG serves oil and gas companies, petrochemical plants, power generation entities, water treatment facilities, and heavy engineering firms
- Key Products: Forged fittings, reinforced branch fittings (OLETs), buttweld fittings, flanges, pipes and tubes, steel plates, valves, fasteners, and filtration equipment and instrumentation.
- Strategic Focus: Delivering high-quality, competitively priced steel components to oil and gas, petrochemical, power generation, and desalination customers across the MENA region, with rigorous third-party inspection and full traceability documentation for every order.
Market Concentration Analysis
The Saudi Arabia forging market is moderately fragmented at the production tier, with Saudi Aramco vendor qualification requirements and IKTVA certification creating structured competitive barriers. Domestic forging capacity meets approximately 35-45% of total forged component demand, with the remainder sourced through certified international suppliers.
Market concentration is increasing at the technology capability tier through joint venture partnerships between domestic industrial groups and international precision forging specialists seeking access to Saudi energy sector procurement.
Investment & Growth Opportunities
Highest Growth Segments
Closed die precision forging for defense (~5.1% CAGR from small base), and seamless forging for pipeline infrastructure (~4.2% CAGR) represent the highest-growth Saudi forging investment vectors through 2034.
Emerging Investment Opportunities
The Vision 2030 defense localization target of 50% domestic sourcing represents the largest near-term premium forging opportunity. Forging companies achieving NADCAP certification for aerospace and SAMI vendor qualification are positioned for above-market revenue growth as defense procurement volumes increase.
Investment Themes
- IKTVA-certified precision forging facilities capturing Aramco supply chain revenue: Facilities achieving Aramco IKTVA certification and API 6A qualification gain preferential access to multi-year procurement frameworks. Companies investing in API-compliant quality systems and IKTVA documentation by 2026-2027 are positioned to capture Aramco planned local content spend acceleration.
- Advanced alloy forging joint ventures targeting aerospace defense export: Joint ventures combining domestic industrial infrastructure with international precision forging technology address the growing aerospace defense market. Saudi-international JV models receiving SAMI support gain both technology transfer and guaranteed initial procurement volumes.
Future Market Outlook (2026-2034)
The Saudi Arabia forging market is projected to grow from USD 116.3 Million in 2025 to USD 173.6 Million by 2034, delivering a 4.55% CAGR over the forecast period. The market anchor value of USD 145.3 Million in 2030 represents a Saudi forging industry completing its first phase of capacity expansion under Vision 2030 industrial programs.
Three structural forces define Saudi forging market growth through 2034. Vision 2030 industrial diversification mandates create government-backed forging investment demand that is policy-mandated and multi-year committed. IKTVA local content requirements structurally increase domestic procurement share for certified Saudi forging operations. Energy sector expansion under Aramco 2030 production targets creates sustained demand for high-specification forged components.
Research Methodology
Primary Research
Primary research comprised structured interviews with 45+ industry stakeholders (2025) including Plant Directors; Procurement Managers; Business Development Executives; Saudi Aramco Vendor Qualification Officers; Vision 2030 program administrators; and regional forging market specialists across the Eastern, Western, and Central regions.
Secondary Research
Secondary research encompassed Saudi industrial development publications; SABIC and HADEED annual reports; Saudi Aramco IKTVA program documents; GCC manufacturing statistics; API and ASME certification databases; Vision 2030 industrial program reports; SAMI procurement frameworks. Over 55 secondary sources reviewed.
Forecasting Models
Market revenue forecasts developed using a segment bottom-up model: (i) technique segment component; (ii) material segment component; (iii) regional demand component cross-validated against top-down macro industrial output indicators from Saudi Ministry of Industry and Vision 2030 program tracking reports.
Saudi Arabia Forging Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Techniques Covered | Closed Die Forging, Open Die Forging, Seamless Forging |
| Materials Covered | Nickel-Based Alloys, Titanium Alloys, Aluminum Alloys, Steel Alloys |
| Industries Covered | Automotive, Aerospace, Railway, Heavy Equipment, Wind Power |
| Regions Covered | Northern and Central Region, Western Region, Eastern Region, Southern Region |
| Companies Covered | Saudi Arabian Oil Co., AL ITTEFAQ STEEL PRODUCTS CO., Steel Forgings Gulf, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Saudi Arabia forging market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Saudi Arabia forging market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Saudi Arabia forging industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Saudi Arabia Forging Market Report
The Saudi Arabia forging market reached USD 116.3 Million in 2025. The market is driven by Vision 2030 industrial diversification, oil and gas sector expansion, and growing IKTVA local content requirements. Rising demand for precision-forged components in aerospace, defense, and automotive sectors further supports market growth.
The market grows at 4.55% CAGR during 2026-2034, reaching USD 173.6 Million by 2034. Titanium and aluminum alloy forging segments grow fastest through aerospace defense procurement and automotive lightweighting demand under Vision 2030 manufacturing programs.
Closed Die Forging leads at 51.8% through precision component requirements for oil and gas valves, flanges, and aerospace structural elements requiring near-net-shape dimensional accuracy and superior mechanical properties demanded by API 6A and ASME standards.
Steel Alloys lead at 47.3% through their widespread applicability across oil and gas, heavy equipment, and construction applications, supported by domestic HADEED production enabling cost-competitive supply across the industrial spectrum.
Eastern Region leads at 39.4% through the concentration of Saudi Aramco operations, Jubail Industrial City, and established petrochemical and heavy industry supply chains requiring locally forged components with Aramco vendor qualification.
Leading companies include Saudi Arabian Oil Co., AL ITTEFAQ STEEL PRODUCTS CO. and Steel Forgings Gulf, among others.
The market is projected to reach approximately USD 145.3 Million by 2030, with IKTVA local content requirements driving increased domestic procurement, advanced alloy forging capability becoming commercially operational, and aerospace defense joint ventures completing initial qualification phases under SAMI frameworks.
Vision 2030 creates multi-dimensional demand stimulus through IKTVA local content mandates structurally increasing domestic forging procurement, defense localization targets creating premium forging demand, and industrial zone development attracting international forging technology partners to establish Saudi-based manufacturing operations through 2034.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade