Saudi Arabia Hair Growth Products Market Size, Share, Trends and Forecast by Product Type, Gender, Age Group, Distribution Channel, and Region, 2026-2034
Saudi Arabia Hair Growth Products Market Size, Share, Trends & Forecast (2026-2034)
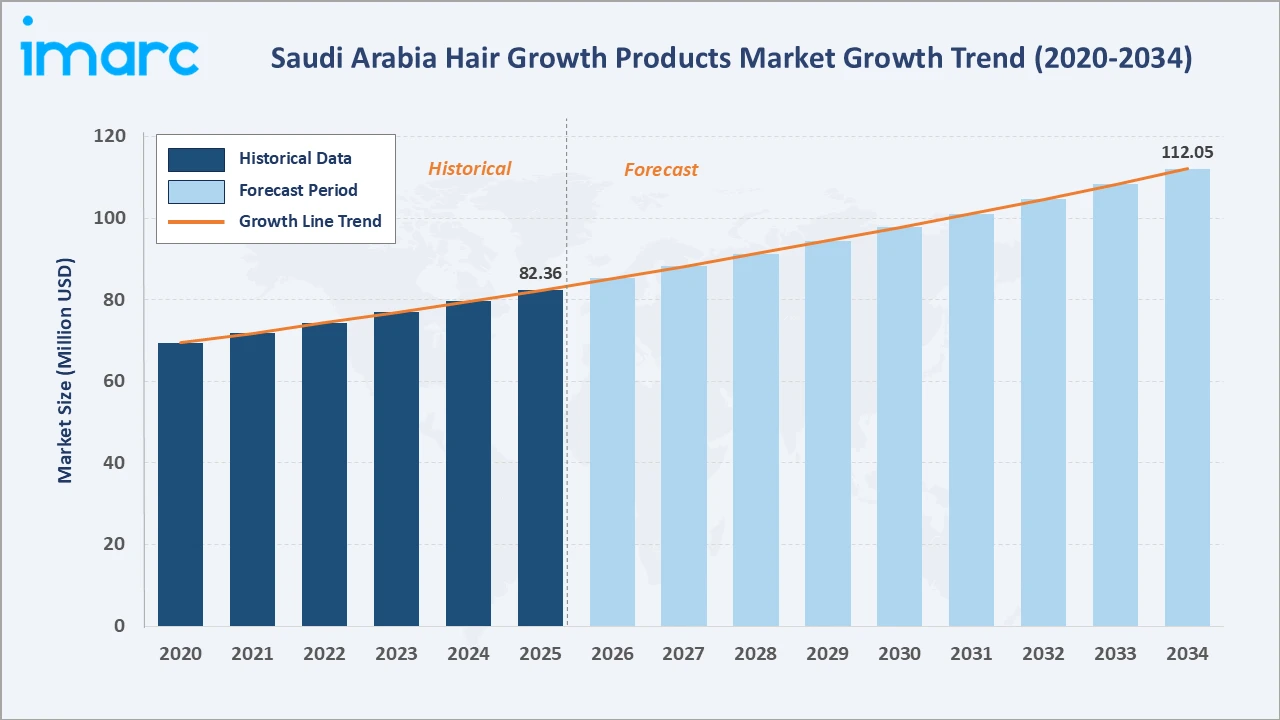
The Saudi Arabia hair growth products market grew from USD 82.36 Million in 2025 to USD 85.22 Million in 2026 and is projected to reach USD 112.05 Million by 2034, exhibiting a CAGR of 3.48% during 2026-2034. Rising consumer awareness of hair health, expanding middle-class expenditure on personal care, and surging demand for clinically validated hair growth formulations are the primary forces shaping market growth.
Shampoos and conditioners lead the product type segment at 32.0%, women account for 58.0% of the gender segment, and Northern and Central Region commands 38.0% of regional share.
Market Snapshot
| Metric | Value |
|---|---|
| Base Year Market Size (2025) | USD 82.36 Million |
| Market Size (2026) | USD 85.22 Million |
| Forecast Market Size (2034) | USD 112.05 Million |
| CAGR (2026-2034) | 3.48% |
| Base Year | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Largest Region | Northern and Central Region (38.0%, 2025) |
| Second Largest Region | Western Region (32.0%, 2025) |
| Leading Product Type | Shampoos and Conditioners (32.0%, 2025) |
| Leading Gender | Women (58.0%, 2025) |
The Saudi Arabia hair growth products market size increased from USD 69.41 Million in 2020 to USD 82.36 Million in 2025 and is estimated to reach USD 85.22 Million in 2026. The market is further expected to grow to USD 97.72 Million by 2030 and USD 112.05 Million by 2034. The market is underpinned by a young, beauty-conscious population, rising disposable incomes, and increasing adoption of premium hair care solutions across Saudi urban centers.
To get more information on this market, Request Sample
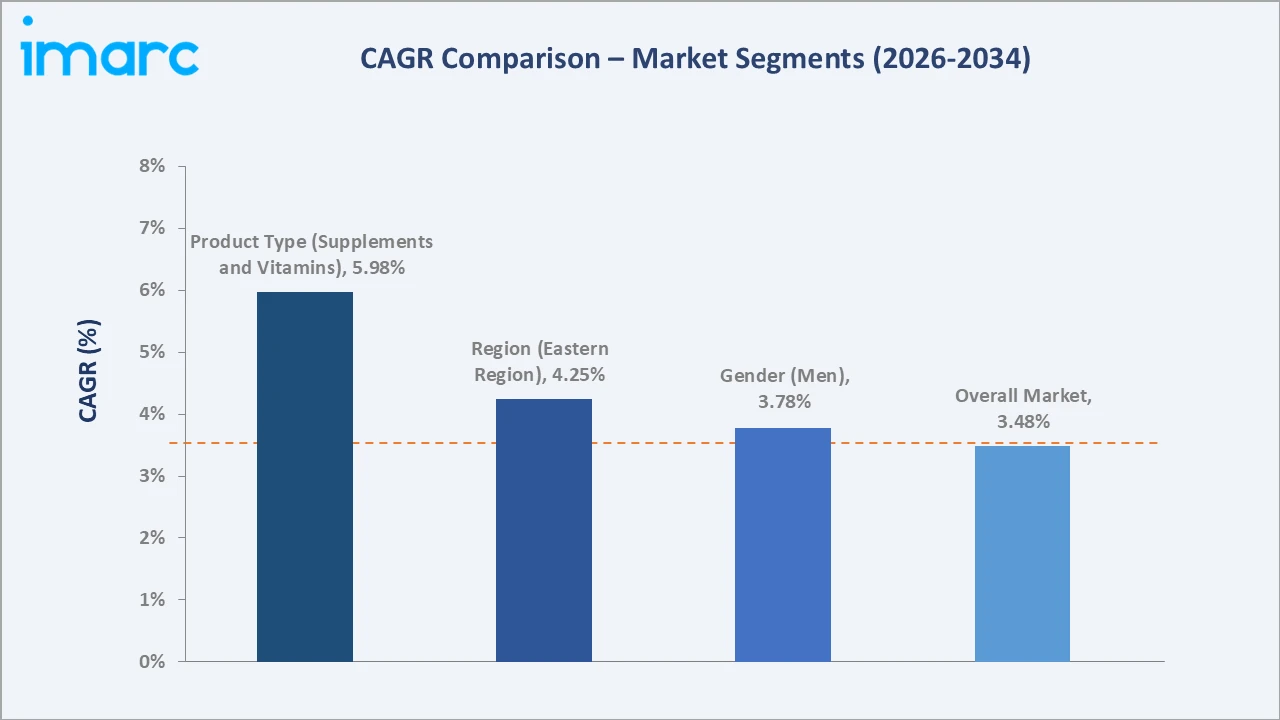
CAGR trajectories across product type, gender, and regional sub-segments show supplements and vitamins and Eastern Region expanding faster than the overall 3.48% market CAGR, driven by rising consumer preference for targeted treatments and expanding urban retail infrastructure.
Executive Summary
The Saudi Arabia hair growth products market expanded from USD 82.36 Million in 2025 to an estimated USD 85.22 Million in 2026, positioning it among the steadily growing personal care markets in the GCC region. The market's momentum is supported by heightened consumer focus on scalp health, increasing availability of professional-grade hair care products, and rising online retail penetration across Saudi Arabia.
Shampoos and conditioners command 32.0% product type share, driven by daily-use demand and wide availability across pharmacy chains, hypermarkets, and e-commerce platforms. Women account for 58.0% of gender-based demand, aligned with higher personal care engagement and growing preference for premium formulations. Northern and Central Region leads at 38.0%, anchored by Riyadh's concentrated urban retail infrastructure.
Key Market Insights
| Insight | Data |
|---|---|
| Leading Product Type | Shampoos and Conditioners – 32.0% share (2025) |
| Second Largest Product Type | Serums – 25.0% share (2025) |
| Leading Gender | Women – 58.0% share (2025) |
| Second Largest Gender | Men – 42.0% share (2025) |
| Leading Region | Northern and Central Region – 38.0% share (2025) |
| Second Largest Region | Western Region – 32.0% share (2025) |
| Top Companies | L'Oréal S.A., Procter & Gamble Co., Unilever PLC, Henkel AG & Co. KGaA |
Key Analytical Observations Expanding On the Data Above:
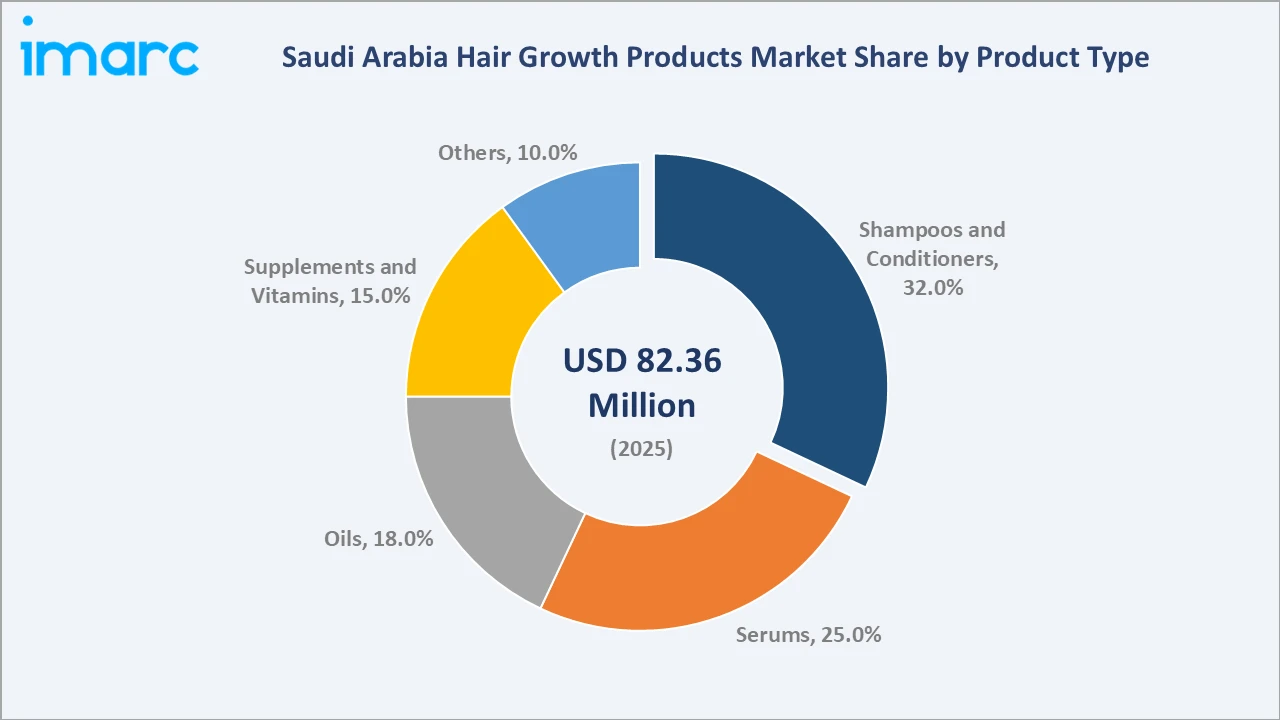
- Shampoos and conditioners at 32.0% dominate because they are the most frequently purchased hair care category, with strong brand recall, high repeat purchase rates, and broad accessibility across all demographic groups in Saudi Arabia.
- Serums at 25.0% reflect growing consumer preference for targeted, ingredient-focused solutions addressing hair thinning, breakage, and scalp health, categories with higher per-unit value and rising digital marketing visibility.
- Women dominance at 58.0% is aligned with historically higher engagement in premium personal care categories, more diverse hair care needs, and greater adoption of multi-step hair growth regimens involving serums, oils, and dedicated treatments.
- Men share at 42.0% is expanding as male grooming awareness rises, with dedicated hair loss shampoos and serums targeting androgenetic alopecia gaining wider marketing support and retail shelf presence in Saudi Arabia.
- Northern and Central Region at 38.0% leads due to Riyadh's urban concentration, high-income population, and strong modern retail and pharmacy infrastructure enabling premium product accessibility.
Saudi Arabia Hair Growth Products Market Overview
Hair growth products encompass a range of formulations designed to address hair thinning, hair loss, and scalp health concerns, including shampoos, conditioners, serums, oils, and nutritional supplements. These products function by stimulating follicular activity, supplying essential nutrients to the hair shaft, improving scalp circulation, and reducing dihydrotestosterone (DHT) activity, a key hormonal factor contributing to pattern hair loss.
The Saudi Arabia ecosystem integrates raw material suppliers, cosmetic manufacturers, contract formulators, specialized distributors, pharmacy chains, hypermarkets, specialty beauty retailers, and direct-to-consumer e-commerce platforms. Regulatory bodies under the Saudi Food and Drug Authority (SFDA) form the compliance layer, ensuring safety and efficacy standards across prescription and over-the-counter hair growth product categories.
Market Dynamics
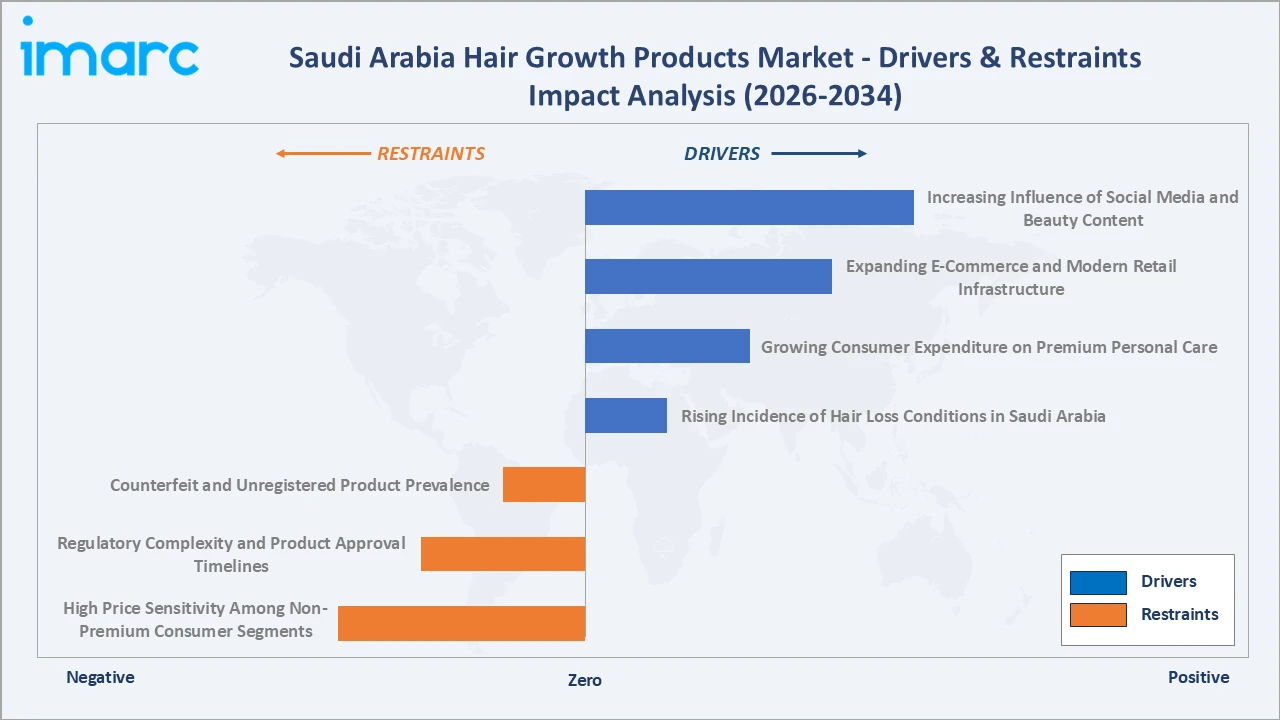
To evaluate market opportunities, Request Sample
Market Drivers
- Rising Incidence of Hair Loss Conditions in Saudi Arabia: Increasing urbanization, dietary changes, and environmental stress factors are contributing to a higher prevalence of alopecia and androgenetic hair loss, expanding demand for targeted hair growth treatments.
- Growing Consumer Expenditure on Premium Personal Care: Rising disposable incomes under Saudi Arabia's Vision 2030 economic diversification framework have elevated personal care spending. Consumers are increasingly trading up to clinical-grade serums, biotin-fortified supplements, and premium shampoo formulations from established international brands.
- Expanding E-Commerce and Modern Retail Infrastructure: As per IMARC Group, the Saudi Arabia e-commerce market grew from USD 251.3 Billion in 2025 to USD 290.8 Billion in 2026. The rapid growth of online retail platforms is widening consumer access to international and niche hair growth brands previously unavailable through traditional brick-and-mortar retail.
- Increasing Influence of Social Media and Beauty Content: Saudi Arabia has one of the highest social media penetration rates globally. Beauty influencers and dermatologists are actively promoting hair growth products through social media platforms, accelerating product discovery and shortening the consideration-to-purchase journey for hair care consumers. As per GASTAT's survey, in Saudi Arabia, engaging in social networking sites emerged as the top online activity in 2026, comprising 99.7% of all internet users, with identical rates for both males and females.
Market Restraints
- High Price Sensitivity Among Non-Premium Consumer Segments: A significant portion of Saudi consumers, particularly in lower-income brackets and non-urban areas, remain price-sensitive, limiting market penetration for premium hair growth products positioned at higher price points.
- Regulatory Complexity and Product Approval Timelines: SFDA requirements for cosmetic product registration, ingredient compliance, and labeling standards create administrative and time barriers for international brands entering the Saudi market, slowing product launch timelines.
- Counterfeit and Unregistered Product Prevalence: The presence of counterfeit hair care products in informal retail channels and online marketplaces undermines consumer trust, disrupts genuine brand positioning, and creates unfair price competition for registered, compliant manufacturers.
Market Opportunities
- Development of Halal-Certified Hair Growth Product Lines: Growing consumer preference for halal-compliant personal care products represents a significant product development opportunity. Brands formulating alcohol-free and ethically sourced hair growth products aligned with Islamic consumer values can access a differentiated and underserved market segment.
- Expanding Distribution Through Pharmacy and Dermatology Channels: Increasing collaboration between manufacturers and Saudi pharmacy chains for professional recommendation programs and in-clinic placement creates premium positioning and higher-conversion distribution opportunities.
Market Challenges
- Market Education for Clinical Hair Growth Products: A knowledge gap among Saudi consumers regarding the clinical mechanisms of hair growth products leads to skepticism about product efficacy, with preference for traditional remedies over evidence-based treatments limiting premium product uptake.
- Fragmented Supply Chain for Specialized Ingredients: Sourcing specialized active ingredients, including minoxidil, keratin, biotin, and plant-derived DHT blockers, requires international procurement subject to supply chain disruption, currency fluctuation, and ingredient compliance certification requirements.
Emerging Market Trends
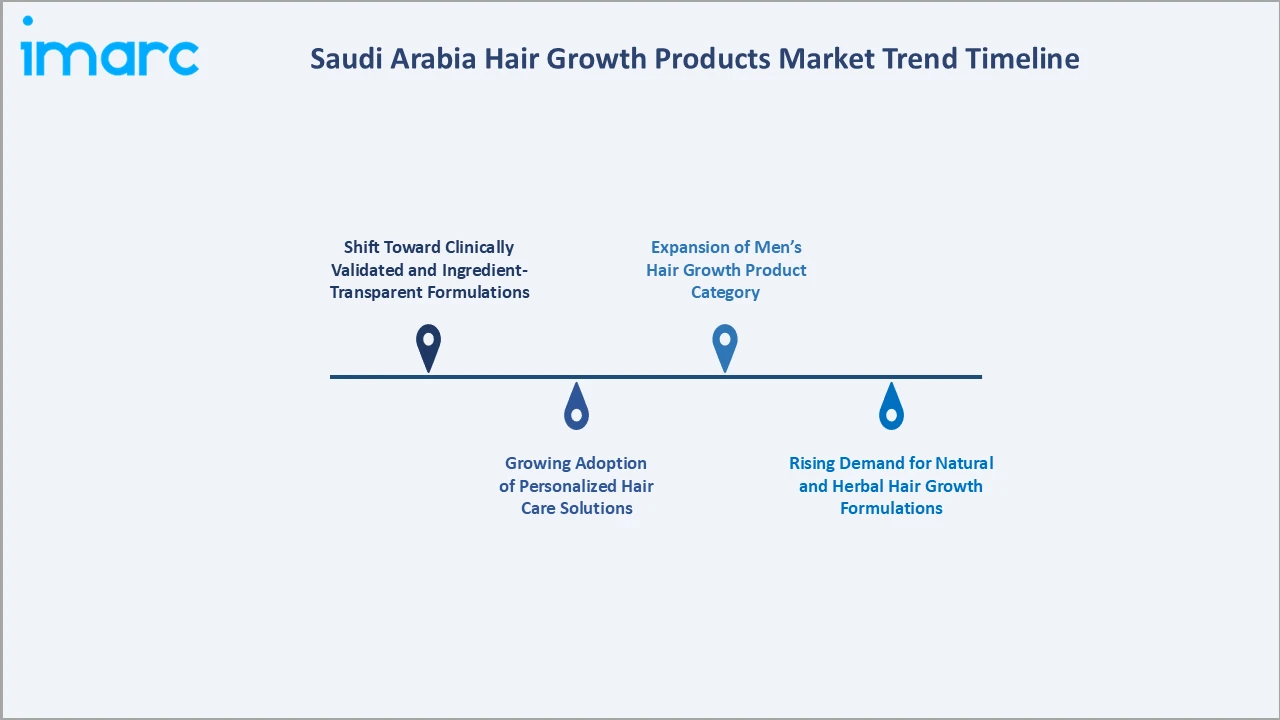
1. Shift Toward Clinically Validated and Ingredient-Transparent Formulations
Saudi consumers are increasingly seeking products with clearly disclosed active ingredients and clinically tested efficacy claims. Brands offering ingredient transparency by listing concentrations of biotin, niacinamide, rosemary extract, and DHT-blocking compounds are gaining consumer preference as product awareness rises and dermatologist recommendations become more influential in purchasing decisions.
2. Growing Adoption of Personalized Hair Care Solutions
Personalized hair growth regimens, developed through online consultations or scalp analysis tools, are gaining consumer interest across Saudi Arabia. These solutions enable consumers to select targeted formulations based on their specific hair concerns, scalp conditions, and treatment requirements.
3. Rising Demand for Natural and Herbal Hair Growth Formulations
Consumer preference is shifting toward products formulated with plant-derived ingredients, including black seed (Nigella sativa) oil, argan oil, fenugreek, and rosemary, reflecting growing alignment between Saudi cultural heritage ingredients and modern cosmetic efficacy standards. Natural formulations also benefit from alignment with halal consumer values.
4. Expansion of Men's Hair Growth Product Category
Historically underdeveloped, the men's grooming and hair growth segment is expanding rapidly. Dedicated male-oriented shampoos, serums, and supplement lines are gaining retail shelf space and online visibility as grooming awareness rises among Saudi men under 35, supported by targeted digital advertising and increased influencer engagement.
Industry Value Chain Analysis
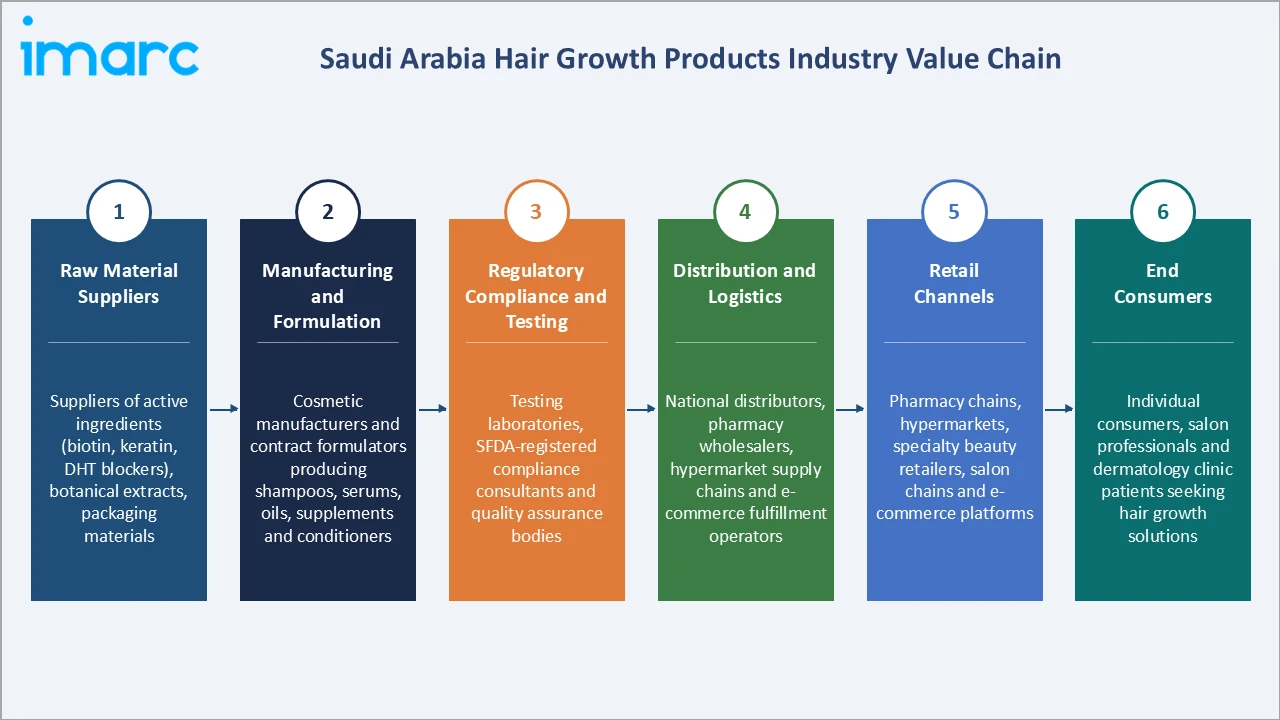
The Saudi Arabia hair growth products value chain spans six stages, from raw material sourcing through retail and end-consumer delivery. Manufacturing, formulation, and regulatory compliance stages capture the highest value-add, while distribution channel relationships and SFDA certification increasingly determine competitive positioning in this regulatory-driven market.
| Stage | Key Players / Examples |
|---|---|
| Raw Material Suppliers | Suppliers of active ingredients (biotin, keratin, DHT blockers), botanical extracts, packaging materials, and specialty chemical compounds |
| Manufacturing and Formulation | Cosmetic manufacturers and contract formulators producing shampoos, serums, oils, supplements, and conditioners for brand owners |
| Regulatory Compliance and Testing | Testing laboratories, SFDA-registered compliance consultants, and quality assurance bodies supporting product registration and safety certification |
| Distribution and Logistics | National distributors, pharmacy wholesalers, hypermarket supply chains, and e-commerce fulfillment operators managing product flow |
| Retail Channels | Pharmacy chains, hypermarkets, specialty beauty retailers, salon chains, and e-commerce platforms serving end consumers |
| End Consumers | Individual consumers, salon professionals, and dermatology clinic patients seeking hair growth and hair loss prevention solutions |
Vertically integrated operators controlling manufacturing, regulatory compliance, and distribution are positioned to capture greater margin than single-stage players dependent on third-party formulators and commodity distributors.
Technology Landscape in the Saudi Arabia Hair Growth Products Industry
Biotechnology and DHT-Blocking Formulations
Advanced biotechnology enables the development of more targeted DHT-blocking compounds derived from plant-based and synthetic sources. These formulations, used in premium shampoos and serums, are gaining clinical validation and consumer acceptance in the Saudi market, driven by rising awareness of androgenetic alopecia management.
Stem Cell and Growth Factor Technology
Emerging hair growth products utilizing stem cell-derived growth factors and peptides are entering premium-tier market positions. These technologies stimulate dormant hair follicles and support scalp regeneration, representing a high-value innovation area for clinical-grade product positioning in Saudi Arabia's premium personal care channel.
Nanotechnology-Based Serum Delivery Systems
Nanotechnology is improving the bioavailability and scalp penetration of active hair growth ingredients. Nano-encapsulated formulations containing keratin, caffeine, and plant extracts enable more efficient follicular delivery, enhancing product efficacy and supporting premium pricing in the serums sub-segment.
Nutraceutical Innovation for Ingestible Hair Growth Products
The supplements and vitamins segment benefits from advances in nutraceutical formulation, including liposomal delivery of biotin, collagen peptides, saw palmetto, and marine-derived proteins. These ingestible formats are gaining popularity among Saudi consumers seeking comprehensive, inside-out hair health solutions.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Product Type | Shampoos and Conditioners | 32.0% | 2025 |
| Gender | Women | 58.0% | 2025 |
| Age Group | 🔒 | 🔒 | 2025 |
| Distribution Channel | 🔒 | 🔒 | 2025 |
| Region | Northern and Central Region | 38.0% | 2025 |

By Product Type
Shampoos and conditioners command a 32.0% majority share in 2025, driven by daily consumer use, strong brand availability across pharmacy and hypermarket channels, and broad applicability across age groups and hair concerns. The segment benefits from established consumer habits and high repeat purchase frequency, making it the most commercially accessible category for both international and regional brands operating in Saudi Arabia.
To access detailed market analysis, Request Sample
Serums at 25.0% represent the second-largest and fastest-growing sub-segment, supported by rising consumer preference for concentrated, active ingredient formulations that directly target hair growth and scalp health concerns.
By Gender
Women account for 58.0% of gender-based market share in 2025, shaped by higher personal care expenditure, more diverse hair types requiring specialized treatment, and greater adoption of multi-step hair care regimens involving dedicated growth serums, oils, and conditioning treatments.
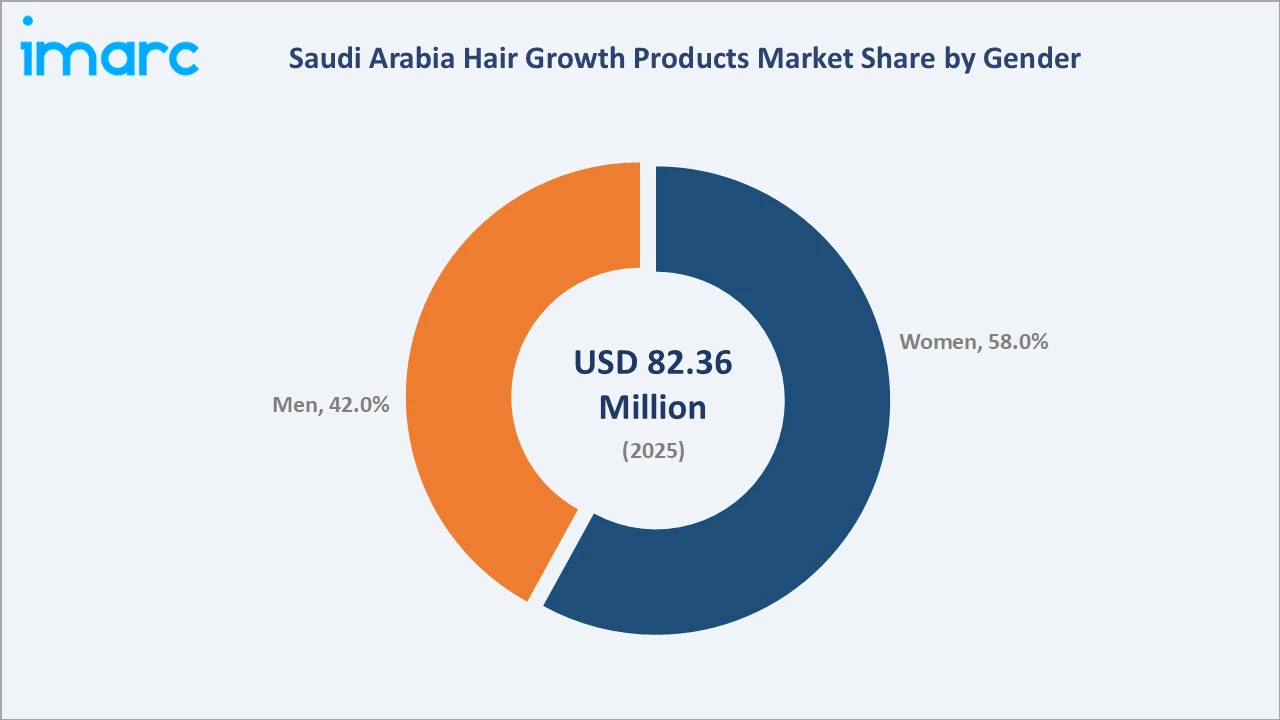
Men represent 42.0% of the market in 2025, with the segment expanding as male grooming awareness rises and targeted hair loss products gain wider marketing support and retail shelf presence across Saudi Arabia.
Regional Market Insights
| Region | Share (2025) | Key Growth Drivers |
|---|---|---|
| Northern and Central Region | 38.0% | Large urban population in Riyadh, high-income consumer base, concentrated modern retail infrastructure, strong beauty awareness, and wide availability of international hair care brands |
| Western Region | 32.0% | Jeddah's cosmopolitan consumer base, significant expatriate population, well-developed specialty beauty retail, and established pharmacy chains with strong hair care ranging |
| Eastern Region | 20.0% | Growing urban middle class in Dammam and Al Khobar, expanding modern retail presence, rising consumer awareness of hair health, and increasing online shopping adoption |
| Southern Region | 10.0% | Emerging consumer market in Asir and Jizan regions, improving retail infrastructure, gradual adoption of premium personal care, and expanding e-commerce access |
Northern and Central Region at 38.0% in 2025 leads the regional landscape, anchored by Riyadh's large and high-income urban population and the strong concentration of modern retail, pharmacy, and specialty beauty channels enabling premium product access.
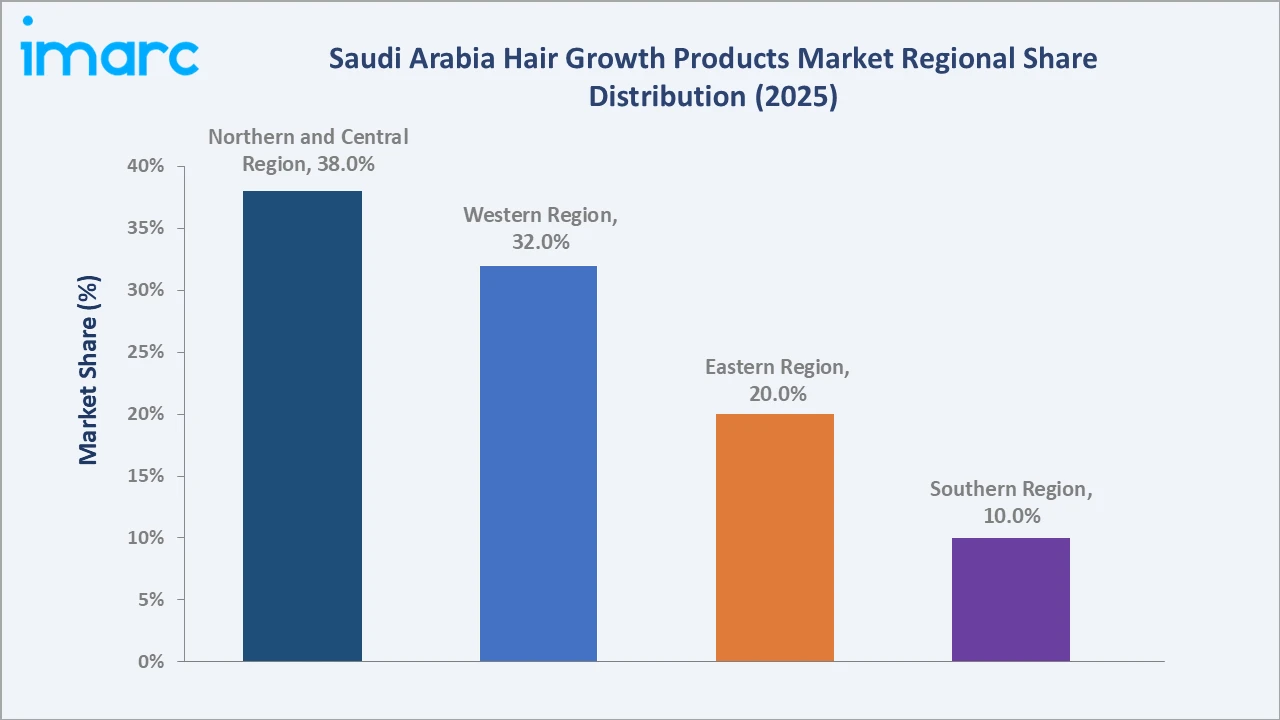
Western Region at 32.0% is supported by high consumer spending, strong retail distribution networks, and growing demand for premium hair care products in major urban centers.
Competitive Landscape
The Saudi Arabia hair growth products market is moderately competitive, with multinational personal care conglomerates, specialty hair care brands, and regional distributors competing on formulation depth, brand equity, retail channel coverage, and digital marketing effectiveness. Product efficacy credentials, SFDA compliance, halal certification, and price positioning form the key competitive differentiators across the market.
| Company Name | Brand / Key Product | Position | Strategic Focus |
|---|---|---|---|
| L'Oréal S.A. | Kérastase | Leader | Expanding premium hair growth portfolio through clinical ingredient research and growing specialist retail and salon distribution in Saudi Arabia |
| Procter & Gamble Co. | Pantene Pro-V | Leader | Strengthening hair strengthening and growth-focused product lines through consumer education and wide multi-channel retail distribution |
| Unilever PLC | Dove | Leader | Scaling hair health product offerings through accessible pricing, wide retail penetration, and growing digital consumer engagement in Saudi Arabia |
| Henkel AG & Co. KGaA | Schwarzkopf | Challenger | Building premium salon-quality hair care presence and expanding professional recommendation programs through salon partnerships and pharmacy distribution |
Key players include L'Oréal S.A., Procter & Gamble Co., Unilever PLC, and Henkel AG & Co. KGaA, among others.
Key Company Profiles
L'Oréal S.A.
L'Oréal S.A. is a French multinational personal care corporation headquartered in Clichy, Hauts-de-Seine. The company operates a diversified portfolio of professional, consumer, and active cosmetics brands with a significant presence in the Saudi Arabia hair care market through its premium Kérastase product line.
- Product Portfolio: Premium hair growth shampoos, serums, and scalp treatment products under the Kérastase brand, including the Kérastase Genesis range targeting hair loss prevention.
- Recent Developments: L'Oréal S.A. continues to expand its active ingredient research capabilities and strengthen its professional salon distribution networks across Saudi Arabia and the broader GCC region.
- Strategic Focus: Building clinical credibility for premium hair growth formulations through dermatologist partnerships, ingredient science communication, and expanding salon and pharmacy distribution across Saudi Arabia.
Procter & Gamble Co.
Procter & Gamble Co. is a United States-based consumer goods corporation headquartered in Cincinnati, Ohio. The company operates numerous brands, including hair strengthening and anti-breakage formulations within its Pantene Pro-V Miracles range.
- Product Portfolio: Pantene Pro-V Miracles shampoos, conditioners, and hair masks targeting hair strengthening, growth support, and anti-hair fall benefits, distributed across hypermarkets, pharmacy chains, and e-commerce platforms in Saudi Arabia.
- Recent Developments: The company continues to invest in consumer marketing campaigns emphasizing hair health science and expand product availability through Saudi Arabia's e-commerce channels.
- Strategic Focus: Driving consumer adoption of hair-strengthening product systems and building brand loyalty through digital content marketing and wide retail channel distribution across Saudi Arabia.
Unilever PLC
Unilever PLC is a British-Dutch multinational consumer goods company headquartered in London, United Kingdom. Unilever's Dove hair care range, including hair fall rescue products, maintains broad consumer reach across Saudi Arabia's hypermarket and online retail channels.
- Product Portfolio: Dove Hair Fall Rescue and Dove Nourishing Secrets hair care product lines targeting hair strengthening and scalp nourishment, available through hypermarkets, pharmacies, and digital retail platforms in Saudi Arabia.
- Recent Developments: Unilever PLC continues to expand its digital-first marketing strategy and strengthen sustainable sourcing commitments for personal care product formulations across its Saudi Arabia operations.
- Strategic Focus: Scaling accessible hair health product lines through broad multi-channel retail distribution and growing digital consumer engagement, with emphasis on sustainable formulation and ingredient transparency.
Market Concentration Analysis
The Saudi Arabia hair growth products market is moderately fragmented, with multinational personal care leaders, including L'Oréal S.A., Procter & Gamble Co., and Unilever PLC, holding significant combined market share alongside regional distributors and specialty hair care brands.
Barriers to entry include SFDA product registration requirements, halal certification compliance, investment in brand equity and consumer marketing, and the complexity of establishing effective multi-channel distribution across Saudi Arabia's diverse retail landscape. These factors favor established multinationals with existing regulatory infrastructure and distribution relationships.
Consolidation is at an early stage, driven by multinational players acquiring specialty hair care brands and regional distributors forming exclusive agreements with international product lines. The growing e-commerce channel is partially lowering distribution entry barriers for new brands while simultaneously intensifying price competition across mass-market product segments.
Investment & Growth Opportunities
Fastest-Growing Segments
Supplements and vitamins are expected to grow at an above-average rate, supported by growing alignment of hair health with overall wellness consumption and expanding pharmacy and e-commerce distribution of ingestible hair growth solutions.
Emerging Markets
Eastern Region is the fastest-growing regional market, supported by an expanding urban middle-class consumer base in Dammam and Al Khobar and improving modern retail infrastructure. Rising awareness of hair health and increasing access to specialized personal care products are further supporting regional market expansion.
Venture & Investment Trends
Investment activity is concentrated in clinical-ingredient-backed hair growth serums and supplements, halal-certified product line development for GCC market expansion, and digital-first direct-to-consumer brand building through social media marketing. Capital is also flowing into e-commerce platform partnerships enabling international hair growth brands to enter Saudi Arabia without requiring immediate physical distribution infrastructure.
Future Market Outlook (2026-2034)
The Saudi Arabia hair growth products market is projected to grow from USD 82.36 Million in 2025 to USD 85.22 Million in 2026, reaching USD 112.05 Million by 2034, registering a CAGR of 3.48% during 2026-2034.
Four forces will shape the market through 2034 continued growth in consumer awareness of hair health and clinical product efficacy; increasing availability of halal-certified and natural ingredient formulations; expanding e-commerce and digital marketing reach enabling new brand entry; and rising investment in the serums and supplements segments as consumers adopt multi-step hair growth regimens.
By 2034, the Saudi Arabia hair growth products market is expected to be characterized by a mix of multinational consumer goods companies, specialist hair care brands, and emerging regional players competing on ingredient innovation, digital brand engagement, and omnichannel retail presence. Continued economic development and urban population growth will sustain consumer expenditure growth across all product type segments through the forecast period.
Research Methodology
Primary Research
Primary research included structured discussions with dermatologists, salon professionals, retail buyers, and personal care product distributors operating in Saudi Arabia, validating market sizing, segment mix, and regional demand patterns across the hair growth products ecosystem.
Secondary Research
Secondary sources included Saudi Food and Drug Authority (SFDA) product registration data, Saudi General Authority for Statistics reports on personal care expenditure, and public disclosures from listed consumer goods companies operating in Saudi Arabia.
Forecasting Models
Market forecasts used top-down and bottom-up models combining Saudi population growth projections, personal care expenditure per capita estimates, product adoption rate assumptions, and segment-level penetration forecasts. Scenario analysis addressed changes in consumer preference, regulatory developments, and e-commerce channel growth rates.
Saudi Arabia Hair Growth Products Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Product Types Covered | Shampoos and Conditioners, Serums, Oils, Supplements and Vitamins, Others |
| Genders Covered | Men, Women |
| Age Groups Covered | Under 35, 35 to 50, Above 50 |
| Distribution Channels Covered | Online, Offline |
| Regions Covered | Northern and Central Region, Western Region, Eastern Region, Southern Region |
| Companies Covered | L'Oréal S.A., Procter & Gamble Co., Unilever PLC, Henkel AG & Co. KGaA, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Saudi Arabia hair growth products market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Saudi Arabia hair growth products market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Saudi Arabia hair growth products industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Saudi Arabia Hair Growth Products Market Report
The Saudi Arabia hair growth products market size is estimated at USD 85.22 Million in 2026, driven by rising consumer awareness of hair health, expanding modern retail availability, and growing adoption of premium hair growth formulations.
The market is projected to grow at a CAGR of 3.48% from 2026-2034, reaching USD 112.05 Million, supported by increasing personal care expenditure and expanding product availability across e-commerce and pharmacy channels.
Shampoos and conditioners dominate the market at 32.0% product type share in 2025, driven by everyday consumer use and broad availability across hypermarkets, pharmacy chains, and online retail platforms.
Women represent 58.0% of gender-based market demand in 2025, driven by higher personal care engagement and greater adoption of comprehensive multi-step hair growth treatment regimens.
Northern and Central Region commands 38.0% share in 2025, led by Riyadh's large urban consumer base, high-income population, and concentrated modern retail and pharmacy infrastructure supporting premium product access.
Eastern Region is the fastest-growing region, supported by an expanding middle-class consumer base in Dammam and Al Khobar, improving retail infrastructure, and rising consumer awareness of hair care products.
Key players include L'Oréal S.A., Procter & Gamble Co., Unilever PLC, and Henkel AG & Co. KGaA, among others.
Key drivers include rising incidence of hair loss conditions, growing consumer expenditure on premium personal care, expanding e-commerce availability, and social media influence on product discovery and purchase decisions.
Key trends include rising demand for clinically validated formulations, growth in personalized hair care, increasing adoption of natural and herbal products, and rapid expansion of the men's hair growth product category.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade