
Saudi Arabia Luxury Residential Real Estate Market Size, Share, Trends and Forecast by Type and Region, 2026-2034
Saudi Arabia Luxury Residential Real Estate Market Size, Share, Trends & Forecast (2026-2034)
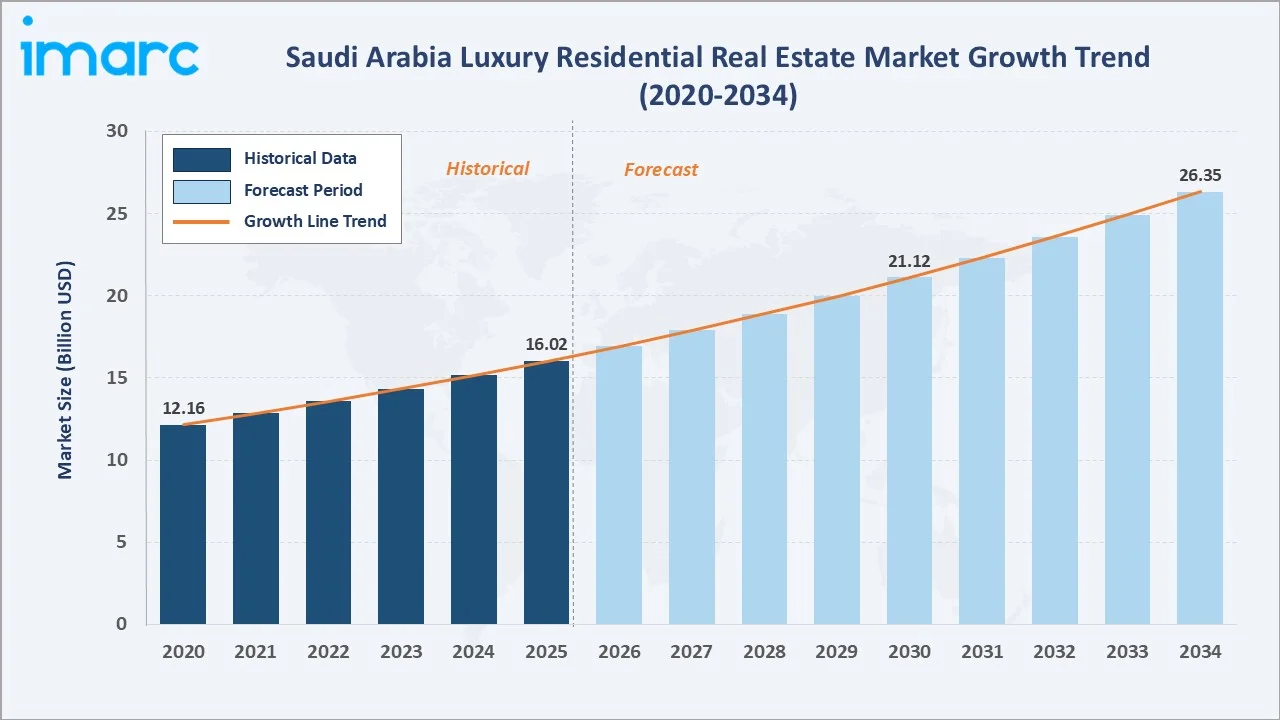
The Saudi Arabia luxury residential real estate market reached USD 16.02 Billion in 2025 and is projected to reach USD 26.35 Billion by 2034, growing at a CAGR of 5.68% during 2026-2034. The market is driven by Vision 2030's homeownership target of 70%, driving premium residential investment; PIF mega-projects creating luxury branded residences in NEOM, Diriyah, and Red Sea destinations; rising household incomes and a young, affluent Saudi population seeking quality residential assets; and the transparent regulatory framework attracting domestic and international capital. Villas and landed houses lead at 63.8% by type, and the Northern and Central region commands the largest share at 40.6%.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 16.02 Billion |
|
Forecast Market Size (2034) |
USD 26.35 Billion |
|
CAGR (2026-2034) |
5.68% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Type |
Villas and Landed Houses (63.8%, 2025) |
|
Leading Region |
Northern and Central Region (40.6%, 2025) |
The Saudi Arabia luxury residential real estate market has grown from USD 12.16 Billion in 2020 to USD 16.02 Billion in 2025, reflecting consistent expansion driven by Vision 2030's housing sector transformation and rising affluence. The market is projected to reach USD 21.12 Billion by 2030 and USD 26.35 Billion by 2034.
To get more information on this market, Request Sample
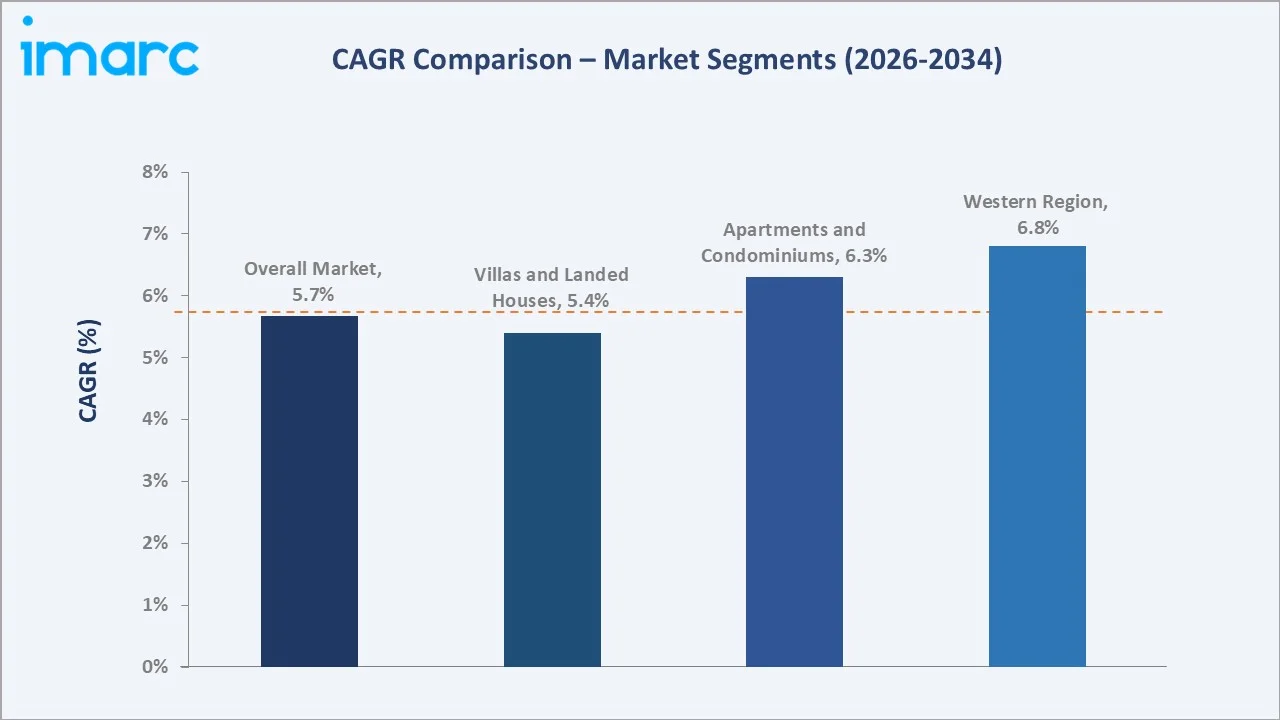
Western region grows at ~6.8% CAGR through Red Sea branded residences and Jeddah waterfront premium apartment development. Apartments and condominiums grow at ~6.3% CAGR through urban luxury high-rise adoption in Riyadh and Jeddah. Villas and landed houses grow at ~5.4% CAGR through sustained landed property preference and community development.
Executive Summary
The Saudi Arabia luxury residential real estate market is undergoing a comprehensive transformation driven by Vision 2030's housing sector reforms, demographic shifts, and the emergence of an entirely new category of luxury residential product in globally unique destination settings. Villas and landed houses lead at 63.8% through Saudi cultural preference for private, spacious landed properties. Northern & Central region leads regionally at 40.6%.
Key Market Insights
|
Insight |
Data |
|
Dominant Type |
Villas and Landed Houses - 63.8% share (2025) |
|
Leading Region |
Northern & Central Region - 40.6% (2025) |
|
Key Market Opportunities |
Growing demand for branded luxury residences and high-end gated communities, supported by Vision 2030, rising affluent households, foreign ownership reforms, and large-scale lifestyle developments |
Key Analytical Observations Supporting the Above Data:
- Villas and Landed Houses at 63.8%: Villas and landed properties dominate through deeply rooted cultural preferences for spacious, private, and family-oriented living environments. Saudi family structures, typically large extended families requiring multiple bedrooms, private courtyards, and dedicated spaces for male and female social segregation, are naturally suited to villa formats that apartments cannot replicate.
- Northern & Central Region at 40.6%: The Northern and Central region leads through Riyadh's position as Saudi Arabia's capital, largest urban center, and primary high-income professional concentration. Vision 2030 program offices concentrated in Riyadh are generating high-income professional employment that sustains luxury residential demand.
Saudi Arabia Luxury Residential Real Estate Market Overview
The Saudi Arabia luxury residential real estate market encompasses premium residential properties priced at the upper segment of the market, including luxury villas and landed house compounds, premium apartments and condominiums in high-rise towers and branded residences, and ultra-luxury estate properties in exclusive gated communities and PIF-backed destination developments. The market serves Saudi high-net-worth individuals (HNWIs), affluent Saudi professionals and executives, Saudi royal family and business family members, and increasingly international HNWI buyers in designated investment zones. Vision 2030's housing sector targets drive both supply investment and demand facilitation through mortgage finance expansion that collectively sustain the luxury tier's growth trajectory.
Market Dynamics
To evaluate market opportunities, Request Sample
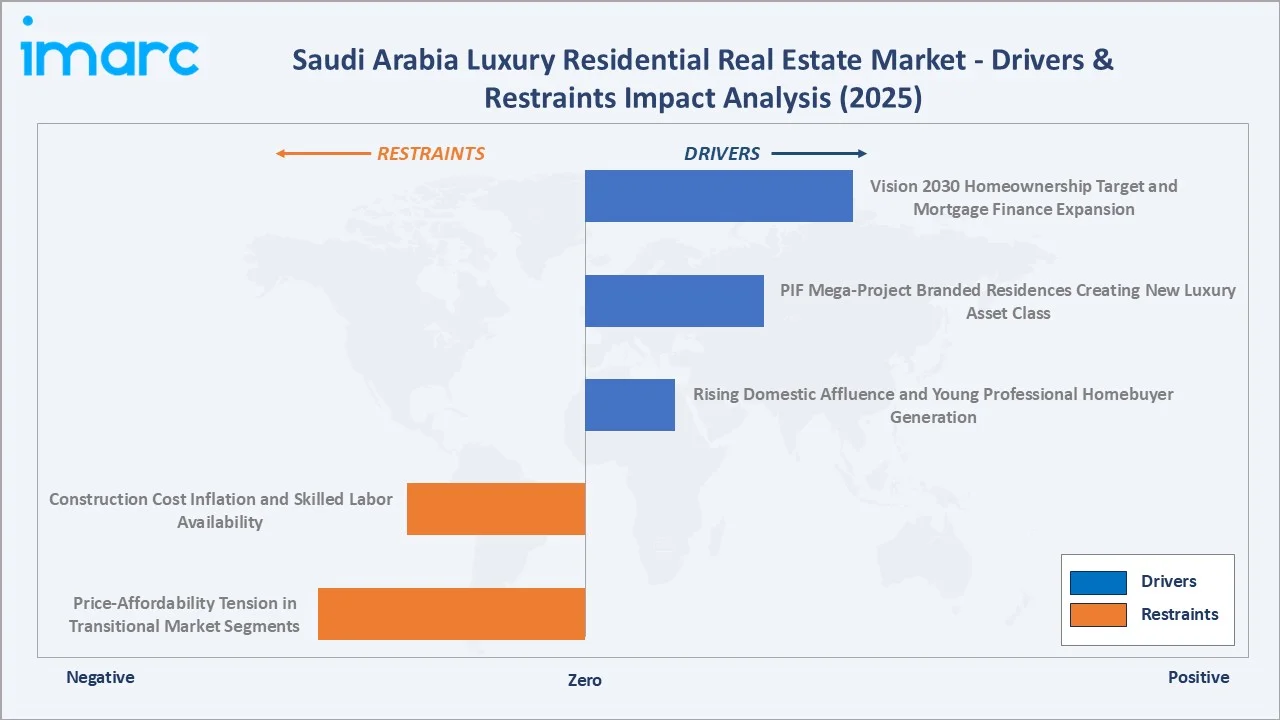
Market Drivers
- Vision 2030 Homeownership Target and Mortgage Finance Expansion: Saudi Arabia's Vision 2030 targets a 70% homeownership rate by 2030. The Saudi mortgage market growth is directly enabling aspirational luxury buyers to participate in premium transactions that previously required full cash. REGA's unified property registration system reduces transaction friction, enabling faster luxury property sales and increasing market liquidity.
- PIF Mega-Project Branded Residences Creating New Luxury Asset Class: The PIF's development through NEOM, Red Sea Global, and Diriyah Gate Development Authority is creating a genuinely new category of Saudi luxury residential asset: internationally branded residences in globally unique locations. NEOM's THE LINE residential units, Sindalah island villas, and Leyja canyon resort residences; Red Sea Project's island eco-luxury residences; and Diriyah's heritage luxury townhouses each represent unprecedented luxury residential value propositions that cannot be replicated elsewhere. These trophy assets attract UHNW buyer interest from regional and international markets.
- Rising Domestic Affluence and Young Professional Homebuyer Generation: Saudi Arabia's Vision 2030 programs are generating a growing cohort of high-income Saudi professionals employed in financial services, technology, energy, healthcare, and government advisory roles that command salaries enabling luxury residential participation. Saudi millennials (33.2%) and Gen Z (26.5%), educated internationally and returning to career opportunities in the transformed Kingdom, are driving luxury apartment and villa purchases in planned communities that reflect modern design aesthetics, smart home technology, and community amenities that traditional Saudi residential neighborhoods did not offer.
Market Restraints
- Construction Cost Inflation and Skilled Labor Availability: Saudi Arabia's unprecedented simultaneous construction activity across giga-projects, Vision 2030 infrastructure programs, and residential developments creates severe competition for construction materials, skilled trades, and project management resources. Material cost inflation and labor market tightness increase luxury residential development costs, compressing developer margins and pushing unit pricing above optimal absorption levels in some market segments.
- Price-Affordability Tension in Transitional Market Segments: Saudi Arabia's luxury residential market is experiencing rapid price appreciation in premium locations that is outpacing income growth for mid-to-upper income households not yet meeting true wealth thresholds. Riyadh's premium villa prices have increased substantially, narrowing the addressable buyer pool and extending sales periods for developers seeking maximum pricing.
Market Opportunities
- Integrated Luxury Coastal Developments: In September 2026, PIF launched Gulf Coast Development Company to develop an integrated tourism and residential destination along the Al-Khafji coast, addressing rising demand for premium accommodation and tourism offerings in Saudi Arabia’s Eastern Province. This launch creates opportunities for luxury residential projects integrated with tourism and lifestyle amenities along Saudi Arabia’s Al-Khafji coast. The initiative can attract private-sector and regional investment while addressing growing demand for premium accommodation and residential offerings in the northern Eastern Province.
- Smart Home and Sustainable Luxury Premium Positioning: Saudi Arabia's technology-savvy luxury homebuyer increasingly demands integrated smart home automation, AI-driven building management, solar energy integration, and sustainable material specifications as standard features in premium properties. Developers incorporating these technologies can command pricing premiums while differentiating from conventional luxury competitors. NEOM's residential specifications are setting technology standards that will influence broader market expectations.
Market Challenges
- Secondary Market Liquidity and Price Transparency Development: Saudi Arabia's luxury residential secondary market remains less liquid than established international luxury property markets, with limited price discovery mechanisms, fewer qualified real estate agents specializing in luxury transactions, and buyers who historically preferred direct developer sales. Building a deeper secondary market with transparent pricing indices, professional luxury brokerage services, and reliable transaction data is essential for market maturity that supports long-term investor confidence.
- Giga-Project Delivery Timeline Risk and Buyer Confidence: Off-plan luxury residential sales in NEOM, Diriyah, and Red Sea giga-projects face buyer confidence challenges related to delivery timeline uncertainty given the unprecedented scale and complexity of these developments. Buyers considering purchases in projects with 5-10+ year delivery horizons require reassurance through completion guarantees, escrow structures, and phased delivery transparency that traditional Saudi real estate practice has not consistently provided.
Emerging Market Trends
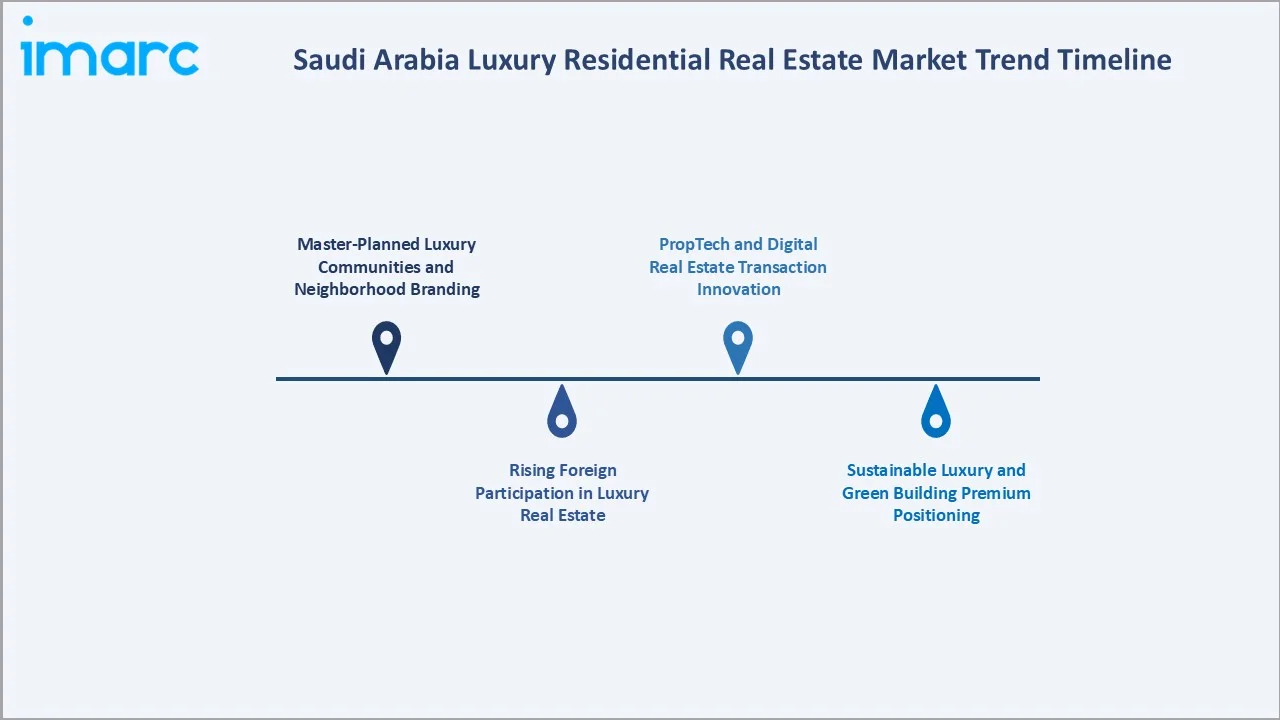
1. Master-Planned Luxury Communities and Neighborhood Branding
Saudi Arabia's luxury residential market is experiencing a fundamental shift from individual villa and apartment transactions in established urban neighborhoods to community-based luxury living in master-planned developments with comprehensive amenities. This community model creates premium pricing power through controlled supply and exclusive membership dynamics.
2. Rising Foreign Participation in Luxury Real Estate
In June 2026, REGA launched the Saudi Properties portal, enabling eligible foreign individuals and companies to apply digitally for property ownership in Saudi Arabia. The initiative supports the Foreign Real Estate Ownership Law and Vision 2030 objectives to attract foreign investment and diversify the economy. This is expected to broaden the investor base and stimulate demand for premium and luxury residential properties in designated ownership zones.
3. PropTech and Digital Real Estate Transaction Innovation
Saudi Arabia's luxury real estate market is progressively adopting property technology solutions that improve transaction efficiency and market transparency. REGA's online property registration system enables faster title transfer, virtual property tours are becoming standard for international buyer engagement, and digital escrow platforms improve off-plan transaction security. Saudi PropTech startups are digitizing property search and transaction workflows, with luxury market applications improving buyer research, developer marketing reach, and secondary market liquidity.
4. Sustainable Luxury and Green Building Premium Positioning
Saudi Arabia's Vision 2030 commitment to environmental sustainability is progressively influencing luxury residential development specifications toward LEED certification, solar energy integration, water recycling systems, and sustainable material sourcing. Luxury buyers with international experience increasingly expect green building standards as baseline requirements rather than premium features. Developers achieving LEED Gold or Platinum certification for luxury communities command marketing differentiation and increasing buyer willingness to pay environmental premiums that justify the incremental development cost.
Industry Value Chain Analysis
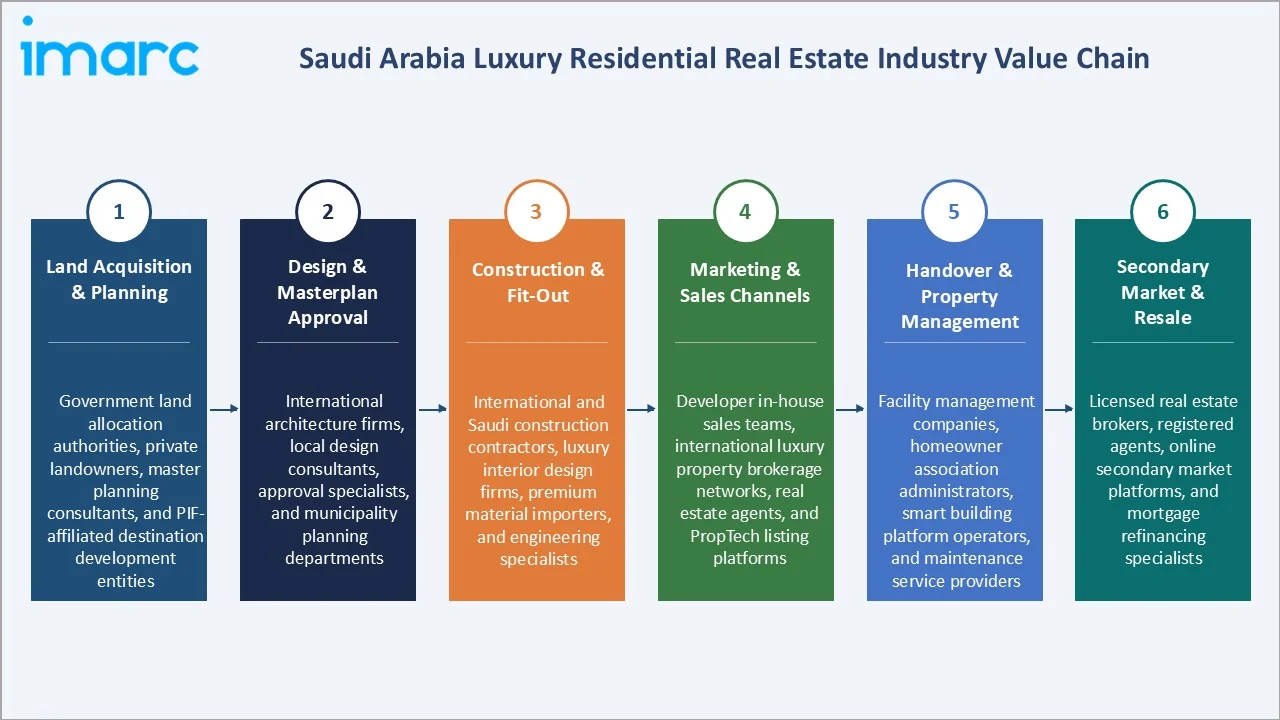
The Saudi Arabia luxury residential real estate value chain integrates land acquisition and master planning, design and planning approval, construction and premium fit-out, marketing and sales channel management, property handover and management, and secondary market and resale activity across villa and apartment product segments.
|
Stage |
Key Participants |
|
Land Acquisition & Planning |
Government land allocation authorities, private landowners, master planning consultants, and PIF-affiliated destination development entities. |
|
Design & Masterplan Approval |
International architecture firms, local design consultants, approval specialists, and municipality planning departments. |
|
Construction & Fit-Out |
International and Saudi construction contractors, luxury interior design firms, premium material importers, and engineering specialists. |
|
Marketing & Sales Channels |
Developer in-house sales teams, international luxury property brokerage networks, real estate agents, and PropTech listing platforms. |
|
Handover & Property Management |
Facility management companies, homeowner association administrators, smart building platform operators, and maintenance service providers. |
|
Secondary Market & Resale |
Licensed real estate brokers, registered agents, online secondary market platforms, and mortgage refinancing specialists. |
Design and masterplan approval represents a critical value chain stage in Saudi Arabia's luxury residential market, as the quality of architectural vision, community planning, and environmental integration directly determines the premium positioning achievable at sale and the long-term value appreciation of luxury properties.
Technology Landscape in the Saudi Arabia Luxury Residential Real Estate Industry
Smart Home and Building Automation Technology
Saudi Arabia's luxury residential developments are increasingly incorporating integrated smart home platforms that control lighting, climate, security, entertainment, and energy management through unified app-based interfaces. Premium smart home systems are specified in top-tier villa compounds, while NEOM's residential specifications incorporate AI-driven building management that learns occupant preferences and optimizes environmental conditions autonomously. Saudi luxury buyers's familiarity with high-end technology creates strong demand for smart home integration as a standard expectation rather than an optional upgrade in the premium residential segment.
PropTech and Digital Transaction Platforms
Saudi Arabia's real estate transaction technology ecosystem is maturing rapidly under REGA's digital transformation program. International PropTech platforms are serving the Saudi luxury market's increasingly international buyer audience with virtual property tours, digital documentation, and remote transaction completion capabilities.
Sustainable Building Technology
Saudi Arabia's extreme climate creates strong economic and comfort rationales for advanced building envelope, HVAC, and renewable energy technologies in luxury residential construction. High-performance glazing systems that mitigate heat gain while maintaining natural light, district cooling systems connected to PV-powered chiller plants, and greywater recycling systems are progressively entering the specifications of premium Saudi villa and apartment developments. These technologies reduce operating costs for luxury homeowners while enabling LEED certification claims that increasingly influence luxury buyer decision-making.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Type |
Villas and Landed Houses |
63.8% |
2025 |
|
Region |
Northern and Central Region |
40.6% |
2025 |

By Type
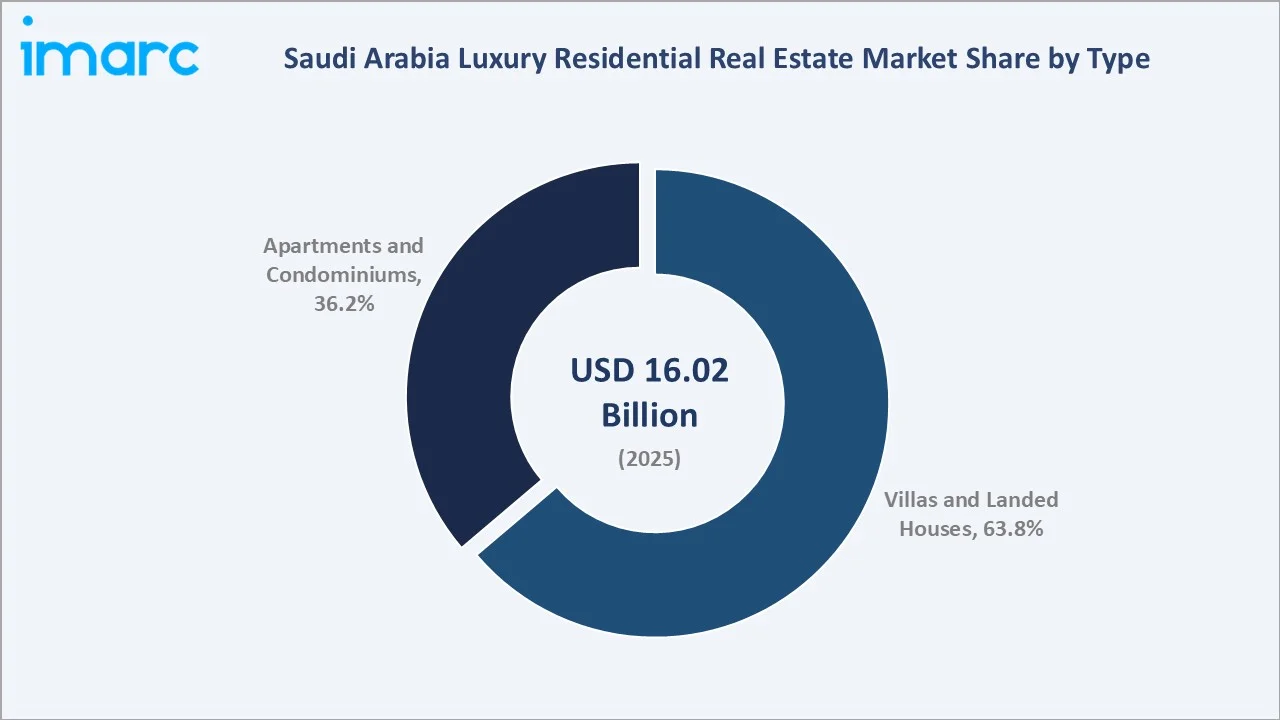
Villas and landed houses lead at 63.8% (2025), through Saudi Arabia's deep cultural preference for private, spacious, and family-oriented landed residential environments that provide the space and privacy requirements of large Saudi family households.
To access detailed market analysis, Request Sample
Apartments and condominiums at 36.2% are growing at ~6.3% CAGR through the emergence of luxury high-rise towers in Riyadh's and Jeddah's corniche, international buyer demand for urban luxury residences, and younger Saudi professionals selecting premium apartments as their primary lifestyle accommodation. Branded residences within hotel developments represent the fastest-growing luxury apartment sub-segment.
Regional Market Insights
|
Region |
Share (2025) |
Key Saudi Arabia Luxury Residential Real Estate Market Drivers & Characteristics |
|
Northern & Central Region |
40.6% |
Reflecting Riyadh's dominant position as Saudi Arabia's capital city with the highest concentration of HNWIs, government officials, corporate executives, and Diriyah Gate's heritage luxury residential development creating ultra-premium asset demand. |
|
Western Region |
29.3% |
Reflecting Jeddah's historically cosmopolitan luxury residential culture, Red Sea Project's emerging branded residence market, Makkah and Madinah's premium religious tourism residential economy, and Al-Ula luxury heritage residential development. |
|
Eastern Region |
18.7% |
Reflecting a large high-income oil industry professional community and the established luxury residential communities of the Eastern Province compound culture. |
|
Southern Region |
11.4% |
Reflecting a growing premium mountain residential market serving domestic lifestyle property buyers, Asir Province property appreciation, and an emerging second-home luxury market for Riyadh and Jeddah residents seeking cool climate retreats. |
The Northern and Central region's 40.6% dominance reflects Riyadh's concentration of Saudi Arabia's highest-earning households who collectively represent the primary buyer pool for the Kingdom's premium villa compounds and luxury tower residences. The Western region's 29.3% reflects Jeddah's historically more open social environment and long tradition of cosmopolitan luxury real estate, augmented by the transformative impact of Red Sea Global's branded residence components that are creating entirely new luxury residential geography.
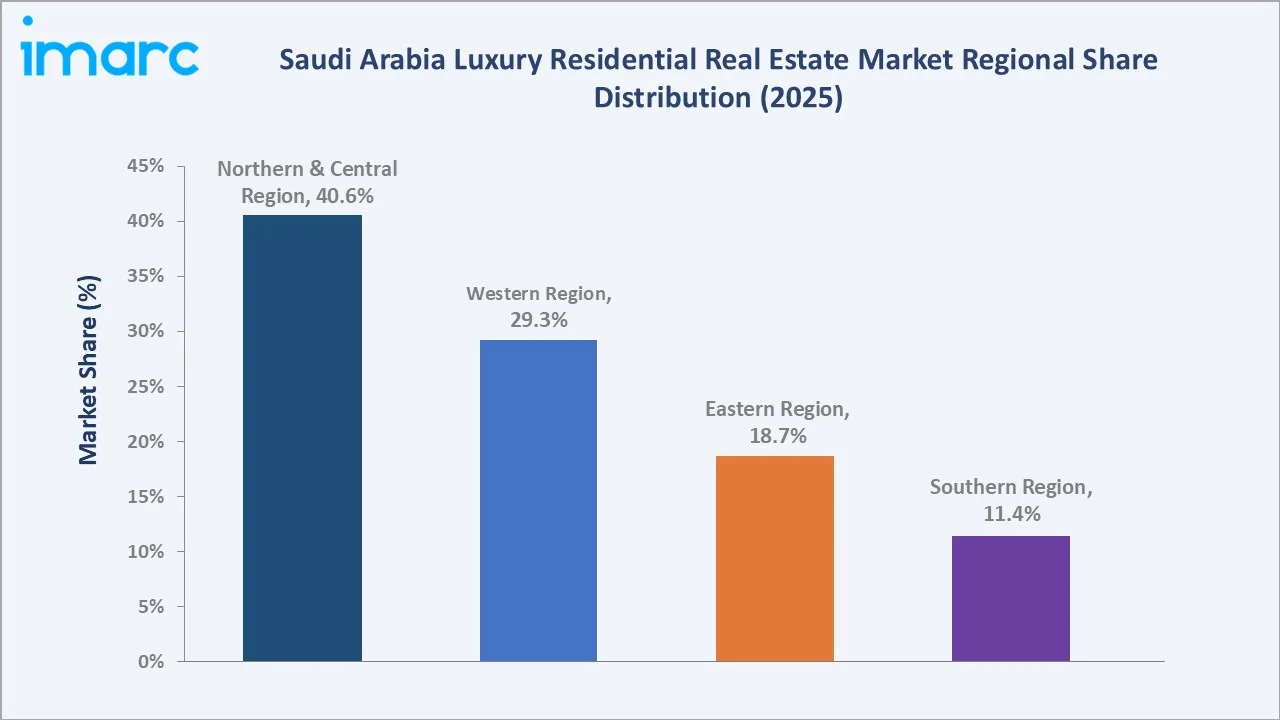
The Eastern region's 18.7% is underpinned by global operations requiring luxury executive accommodation across its Dhahran, Ras Tanura, and Jubail campuses, alongside the Al Khobar and Dammam private residential market serving the Eastern Province's concentration of oil industry professionals. The Southern region at 11.4% represents a growing market with distinctive appeal: Abha's green mountain environment is increasingly valued by domestic luxury buyers seeking second homes in a cool-climate setting during the extreme summer heat that limits coastal and desert residential desirability.
Competitive Landscape
The Saudi Arabia luxury residential real estate market features a competitive mix of the PIF-backed national developers, established Saudi private developers, international brands, and diversified developers. PIF-backed entities benefit from land allocation and policy alignment advantages that create structural competitive differentiation.
|
Company |
Key Offerings |
Market Position |
Core Strength |
|
ROSHN Group |
SEDRA, ALAROUS |
Market Leader |
ROSHN Group acts as a key national developer backed by the Public Investment Fund (PIF) to reshape Saudi Arabia's residential real estate sector and support Vision 2030. |
|
Dar Al Arkan |
Rayana, Wadi Safar, Shams Ar Riyadh, Al Munsiyah, Al Falah, Al Maseef, Al Rabie, Al Tawoun |
Market Leader |
Dar Al Arkan is one of Saudi Arabia's largest and most influential publicly listed property developers, driving the evolution of luxury residential real estate in the Kingdom. |
|
Kingdom Holding Company |
Four Seasons, Jeddah Economic Company (JEC) |
Established Player |
Kingdom Holding Company shapes Saudi Arabia's luxury real estate and mixed-use urban sector through landmark developments, strategic landbanks, and high-end hospitality integration. |
|
Diriyah Company |
Manazel AlHadawi, Raffles Residences, Corinthia Residences, The Ritz-Carlton Residences |
Established Player |
The Diriyah Company acts as the master developer spearheading the Diriyah giga-project, shaping Saudi Arabia’s ultra-luxury residential and branded real estate sector |
Companies across the competitive landscape are investing in international design partnerships, branded residence hotel affiliations, smart home technology integration, and sustainable building certification programs that differentiate their luxury residential offerings in an increasingly competitive market. The PIF's expanding direct development role creates both competitive pressure for private developers and partnership opportunities for branded residence and community management collaborations.
Key Company Profiles
ROSHN Group
ROSHN Group, wholly owned by Saudi Arabia's Public Investment Fund (PIF), is the Kingdom's national residential real estate developer mandated to develop homes across Saudi Arabia's major cities through master-planned communities that combine affordable, mid-market, and premium residential products within thoughtfully designed neighborhoods. ROSHN's luxury residential offering is anchored by its SEDRA community in northern Riyadh and ALAROUS, its Western Region master-planned development.
- Key Offerings: SEDRA, ALAROUS.
- Strategic Focus: Delivering SEDRA and ALAROUS initial product release to establish ROSHN's luxury residential brand credibility, developing smart home integration standards for all premium product tiers, expanding ROSHN's community management platform to deliver hospitality-grade residential living services, and building ROSHN's international brand awareness through global luxury real estate exhibition presence.
Dar Al Arkan
Dar Al Arkan is a real estate development company and Saudi Arabia's largest publicly traded real estate developer and the leading private sector brand in luxury residential development. The company has developed various units across Saudi Arabia's major cities and has pioneered branded residence development in the Kingdom through international hotel brand management agreement partnerships. The company's established sales network, brand recognition, and experience with off-plan luxury sales make it the benchmark for private sector luxury residential marketing in Saudi Arabia.
- Key Offerings: Rayana, Wadi Safar, Shams Ar Riyadh, Al Munsiyah, Al Falah, Al Maseef, Al Rabie, Al Tawoun.
- Strategic Focus: Expanding Dar Al Arkan's branded residence portfolio through additional international hotel brand partnerships that differentiate its luxury apartment offering and attract international HNWI buyers, growing Red Sea coastal residential development as the Western Region luxury second-home market develops, and enhancing Dar Al Arkan's digital sales and PropTech capabilities to serve international buyer engagement.
Market Concentration Analysis
The Saudi Arabia luxury residential real estate market exhibits moderate concentration, with PIF-backed entities and private developers collectively commanding significant development market share through their land access advantages and scale. Established private sector competitors have meaningful portfolios. Market concentration is moderate rather than high because the luxury residential market encompasses a diverse geography, established Riyadh and Jeddah luxury neighborhoods, giga-project destination residences, Eastern Province executive housing, and mountain retreat markets, each served by different competitive sets.
Investment & Growth Opportunities
Highest Growth Segments
Luxury apartments and branded residences (~6.3% CAGR), Western region Red Sea branded villa communities, NEOM ultra-luxury residential products, Diriyah heritage luxury townhouses, mountain retreat second-home properties, and foreign HNWI-eligible investment zones represent the highest-growth investment vectors in the Saudi Arabia luxury residential real estate market through 2034.
Investment Themes
- Branded residence hotel partnership development: Partnering with international luxury hotel brands to create branded residence components within Saudi hotel projects generates price premiums over unbranded equivalents while reducing marketing costs through the hotel brand's existing HNWI buyer database. The Saudi luxury hotel development pipeline creates abundant partnership opportunities for residential developers seeking to differentiate their product and attract international buyer interest.
- Foreign HNWI buyer market development for giga-project residences: Establishing dedicated international sales and marketing programs targeting GCC, Arab diaspora, and Asian HNWI buyers for Red Sea, NEOM, and Diriyah branded residences creates a demand layer independent of domestic Saudi market cyclicality. These international luxury buyers represent natural purchaser targets for Saudi Arabia's emerging ultra-luxury residential offer.
Future Market Outlook (2026-2034)
The Saudi Arabia luxury residential real estate market is projected to grow from USD 16.02 Billion in 2025 to USD 26.35 Billion by 2034, exhibiting a CAGR of 5.68% during 2026-2034. The market is projected to reach an anchor value of USD 21.12 Billion by 2030, representing the mid-period milestone at which Vision 2030's homeownership target nears attainment, giga-project residential products achieve initial delivery, and foreign ownership reforms begin generating meaningful international buyer transaction volumes.
Three structural forces will define the Saudi Arabia luxury residential real estate market through 2034. First, Vision 2030's homeownership policy ecosystem will progressively expand the qualified buyer pool for luxury residential properties as wealth creation from Vision 2030 programs generates new HNWI household formation. Second, the progressive opening of Saudi Arabia's luxury residential market to international buyers through foreign ownership reforms, Premium Residency programs, and special economic zone property rights will introduce international demand dynamics that have historically been absent from the Saudi market. Third, the delivery of transformational PIF-backed luxury residential products in NEOM, Diriyah, Red Sea, and AMAALA will create globally competitive ultra-luxury residential assets that attract international attention disproportionate to their unit volume.
Research Methodology
Primary Research
Primary research comprised in-depth interviews with luxury real estate developers, REGA officials, mortgage finance specialists, international luxury property brokers active in Saudi Arabia, and wealth management advisors serving Saudi HNWI clients. These discussions validated market size estimates, assessed property type demand dynamics, evaluated competitive positioning, and provided insights into foreign ownership reform implementation and future market evolution.
Secondary Research
Secondary research encompassed REGA property registration statistics, mortgage market data, REDF annual program performance reports, Vision 2030 housing sector publications, PIF portfolio disclosures for giga-project developments, leading developer annual reports, luxury residential market research, and industry publications tracking GCC premium property market trends.
Forecasting Models
Forecasting models incorporated historical luxury residential transaction value trends, Vision 2030 homeownership target timelines, mortgage market growth projections, wealth creation from Vision 2030 economic programs, giga-project residential delivery schedules, and foreign ownership reform implementation pace assumptions. Both top-down wealth creation modeling and bottom-up transaction volume and average value estimates were cross-validated for consistency.
Saudi Arabia Luxury Residential Real Estate Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical and Forecast Trends, Industry Catalysts and Challenges, Segment-Wise Historical and Predictive Market Assessment:
|
| Types Covered | Apartments and Condominiums, Villas and Landed Houses |
| Regions Covered | Northern and Central Region, Western Region, Eastern Region, Southern Region |
| Companies Covered | ROSHN Group, Dar Al Arkan, Kingdom Holding Company, Diriyah Company, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Saudi Arabia luxury residential real estate market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Saudi Arabia luxury residential real estate market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Saudi Arabia luxury residential real estate industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Saudi Arabia Luxury Residential Real Estate Market Report
The Saudi Arabia luxury residential real estate market reached USD 16.02 Billion in 2025, driven by Vision 2030's 70% homeownership target, PIF mega-project branded residence development, foreign ownership reforms opening the market to international HNWIs, rising domestic affluence, and REGA's transparent regulatory framework.
The Saudi Arabia luxury residential real estate market is projected to grow at a CAGR of 5.68% during 2026-2034, sustained by mortgage market deepening, giga-project residential delivery, progressive foreign HNWI buyer market development, and branded residence market emergence.
The market is projected to reach approximately USD 21.12 Billion by 2030, representing the mid-period milestone at which Vision 2030's homeownership target approaches attainment, giga-project residential products achieve initial delivery, and foreign ownership reform begins generating international buyer transaction volumes.
The Saudi Arabia luxury residential real estate market is projected to reach USD 26.35 Billion by 2034, driven by sustained domestic wealth creation, a mature, branded residence market, established international buyer participation, and Saudi Arabia's recognition as a global luxury residential destination.
Villas and landed houses lead with a 63.8% share in 2025, through Saudi Arabia's deep cultural preference for private, spacious, and family-oriented landed residential environments suited to Saudi family household structures and social customs.
The Northern and Central region leads with a 40.6% share in 2025, driven by Riyadh's concentration of HNWIs, government officials, corporate executives, and the emerging Diriyah Gate heritage luxury residential development creating ultra-premium asset demand adjacent to the capital.
Key players include ROSHN Group, Dar Al Arkan, Kingdom Holding Company, and Diriyah Company, among others.
Luxury apartments and condominiums are growing at ~6.3% CAGR through the emergence of branded residences in hotel developments, international HNWI buyer demand for urban luxury investment properties, younger Saudi professional buyers preferring contemporary apartment living, and Riyadh and Jeddah corniche premium high-rise tower development creating new urban luxury residential supply.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade