Saudi Arabia Medical Imaging Equipment Market Size, Share, Trends and Forecast by Equipment Type, Modality, Application, End User, and Region, 2026-2034
Saudi Arabia Medical Imaging Equipment Market Size, Share, Trends & Forecast (2026-2034)
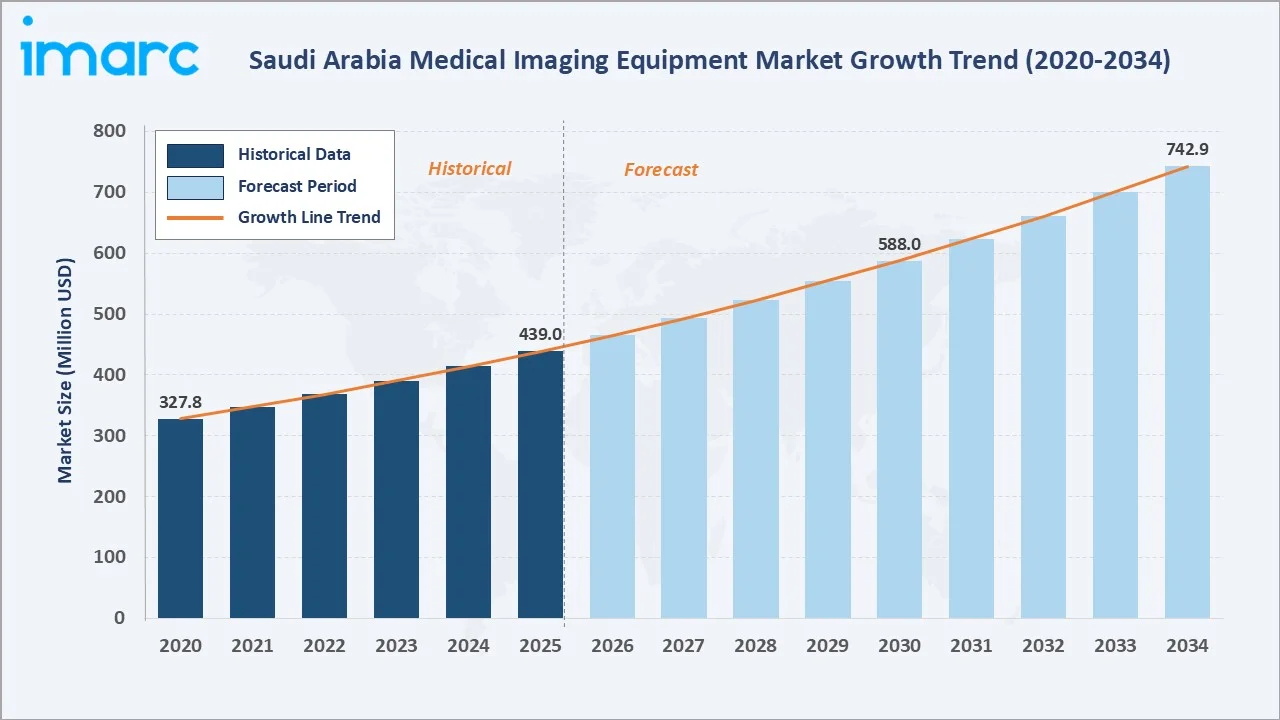
The Saudi Arabia medical imaging equipment market grew from USD 439.0 Million in 2025 to USD 465.4 Million in 2026 and is projected to reach USD 742.9 Million by 2034, growing at a CAGR of 6.02% during 2026-2034. The market is driven by Vision 2030's SAR 500 billion healthcare investment program, rising prevalence of non-communicable diseases including cardiovascular disease, diabetes, and oncology requiring increased diagnostic imaging, AI-integrated imaging platform adoption enhancing diagnostic accuracy, expanding private healthcare sector investment, and NEOM's smart hospital initiative introducing next-generation medical imaging facilities. Stand-alone devices lead at 61.8% by modality, hospitals dominate at 57.3% by end user, and the Northern and Central region holds the largest share at 43.2%.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 439.0 Million |
| Market Size (2026) | USD 465.4 Million |
|
Forecast Market Size (2034) |
USD 742.9 Million |
|
CAGR (2026-2034) |
6.02% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Modality |
Stand-Alone Devices (61.8%, 2025) |
|
Dominant End User |
Hospitals (57.3%, 2025) |
|
Leading Region |
Northern and Central Region (43.2%, 2025) |
The Saudi Arabia medical imaging equipment market has grown from USD 327.8 Million in 2020 to USD 439.0 Million in 2025 and an estimated USD 465.4 Million in 2026, reflecting consistent expansion driven by healthcare infrastructure development and rising disease burden. The market is projected to reach USD 588.0 Million by 2030 and USD 742.9 Million by 2034.
To get more information on this market, Request Sample
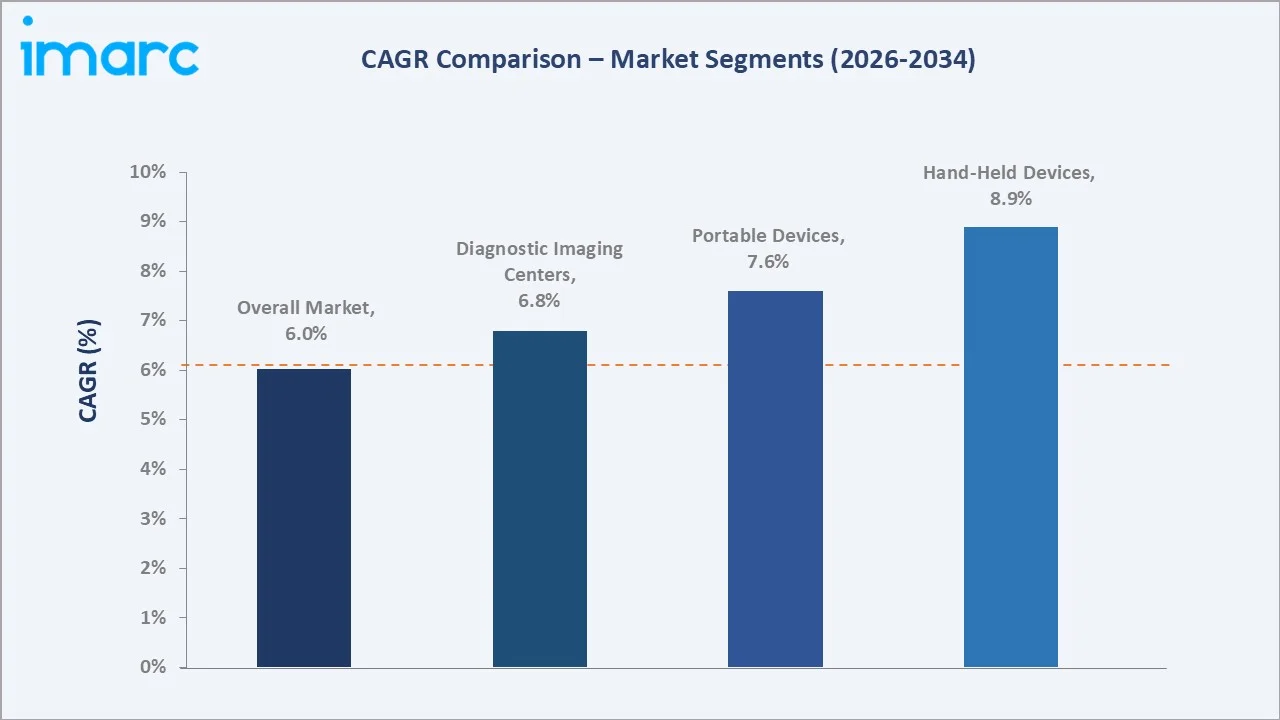
Hand-held devices grow at ~8.9% CAGR through point-of-care ultrasound and portable diagnostic adoption. Portable devices grow at ~7.6% CAGR through mobile imaging unit and emergency department demand. Diagnostic imaging centers grow at ~6.8% CAGR through private sector investment in outpatient imaging.
Executive Summary
The Saudi Arabia medical imaging equipment market is experiencing sustained and structurally driven growth, anchored by one of the most ambitious healthcare system transformation programs under Vision 2030. The concurrent rise in non-communicable disease burden is intensifying imaging utilization per capita across existing facilities and accelerating the clinical case for advanced modality investment in CT, MRI, PET-CT, and mammography. Stand-alone devices lead at 61.8% through hospital-grade stationary imaging system demand. Hospitals lead at 57.3% as the primary institutional end users. Northern & Central region leads regionally at 43.2%.
Key Market Insights
|
Insight |
Data |
|
Dominant Modality |
Stand-Alone Devices - 61.8% share (2025) |
|
Dominant End User |
Hospitals - 57.3% share (2025) |
|
Leading Region |
Northern & Central Region - 43.2% (2025) |
|
Key Market Opportunities |
Expansion of advanced diagnostic imaging infrastructure, rising adoption of AI-enabled imaging systems, growth in private healthcare facilities, and increasing demand for MRI, CT, ultrasound, and digital radiography equipment. |
Key Analytical Observations Supporting the Above Data:
- Stand-Alone Devices at 61.8%: Stand-alone devices dominate because the majority of imaging equipment procurement is for newly built and expanding hospitals and tertiary care centers that require full-specification, high-throughput stationary imaging systems.
- Hospitals at 57.3%: Hospitals command the largest end user share because Saudi Arabia's healthcare system is predominantly hospital-centric, with MOH hospitals serving as primary diagnostic referral destinations for the population. Saudi hospital radiology departments are the single largest institutional buyers of advanced imaging equipment, procuring complete modality suites spanning CT, MRI, X-ray, fluoroscopy, ultrasound, and nuclear medicine.
- Northern & Central Region at 43.2%: The Northern and Central region leads through Riyadh's concentration of Saudi Arabia's largest and most advanced tertiary hospitals. The region also hosts the highest density of private hospital groups and diagnostic imaging center chains procuring advanced imaging for medical research programs.
Saudi Arabia Medical Imaging Equipment Market Overview
The Saudi Arabia medical imaging equipment market encompasses diagnostic imaging devices used across hospitals, diagnostic imaging centers, specialty clinics, ambulatory surgical centers, and research institutions. Equipment categories include CT systems (multi-slice CT scanners, spectral CT), X-ray systems (digital radiography, fluoroscopy, C-arms), MRI systems (1.5T, 3.0T, ultra-high field), ultrasound systems (2D, 3D/4D, Doppler, CEUS), nuclear imaging equipment (PET-CT, SPECT-CT, gamma cameras), mammography equipment (digital, tomosynthesis, contrast-enhanced), contrast media injectors, and C-arms and fluoroscopy devices. Vision 2030's health sector targets create the clinical rationale that drives imaging equipment investment across all facility categories.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
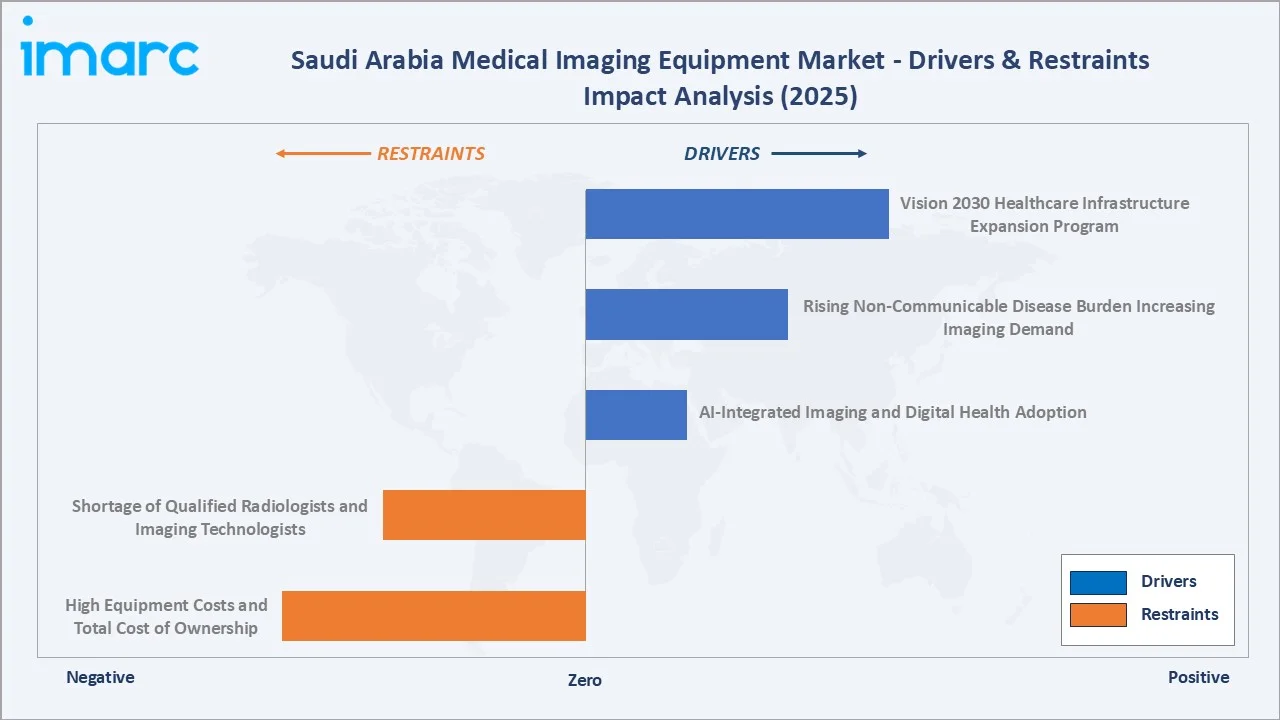
- Vision 2030 Healthcare Infrastructure Expansion Program: Saudi Arabia's government has committed SAR 500 billion to healthcare sector transformation under Vision 2030, funding construction of new hospitals, upgrading of existing facilities, and installation of advanced medical equipment. Each new hospital opening requires complete radiology department equipment procurement, typically including CT, MRI, X-ray, ultrasound, and mammography systems.
- Rising Non-Communicable Disease Burden Increasing Imaging Demand: Saudi Arabia faces a heavy non-communicable disease burden, with diabetes affecting over 25% of adults, cardiovascular disease as the leading cause of mortality, and cancer incidence increasing with lifestyle changes. These conditions require repeated diagnostic imaging across their management lifecycle - CT and PET-CT for oncology staging, cardiac MRI and nuclear cardiology for heart disease, and ultrasound and mammography for diabetes-related complications and breast cancer screening. Per-scan utilization rates are increasing independently of population growth, multiplying imaging equipment demand.
- AI-Integrated Imaging and Digital Health Adoption: Saudi Arabia's healthcare digital transformation agenda drives adoption of AI-powered imaging platforms that embed clinical decision support, automated measurement, workflow optimization, and remote reading capabilities within imaging equipment. Leading Saudi hospitals are specifying AI-integrated CT, MRI, and X-ray systems as standard procurement requirements. These AI-enabled platforms command significant pricing premiums, supporting market value growth beyond volume expansion.
Market Restraints
- High Equipment Costs and Total Cost of Ownership: Advanced medical imaging equipment represents high-value capital expenditure. These high acquisition costs, combined with expensive installation, infrastructure upgrading, and annual maintenance contracts, create financial barriers for smaller hospitals and specialty clinics seeking to expand imaging capabilities, constraining market penetration in the mid and lower tiers of the healthcare system.
- Shortage of Qualified Radiologists and Imaging Technologists: Saudi Arabia faces a significant shortage of qualified radiologists, nuclear medicine physicians, and imaging technologists relative to its installed equipment base and clinical workload. The radiology workforce gap constrains imaging throughput, limits the full utilization of advanced equipment capabilities, and creates quality bottlenecks in diagnostic reporting.
Market Opportunities
- Point-of-Care Ultrasound and Hand-Held Imaging Expansion: The growing adoption of hand-held and portable ultrasound devices in emergency departments, intensive care units, and primary healthcare settings represents the fastest-growing equipment segment. In February 2026, Supporting Saudi Arabia’s Vision 2030 healthcare digitalization agenda, Mindray collaborated with SEHA Virtual Hospital to deploy an intelligent ultrasound solution. The initiative combines the Premium Hand-Carried Ultrasound System M9 with the MiCo+ Medical Imaging IT platform to enhance diagnostic capabilities and improve the quality and accessibility of healthcare services across the Kingdom. Point-of-care ultrasound enables rapid bedside assessment without radiology department scheduling, improving emergency and critical care workflows.
- Teleradiology and Remote Reporting Service Development: Saudi Arabia's geographic spread and radiology workforce shortage create structural demand for teleradiology platforms that route imaging studies from underserved regional hospitals to centralized radiologist reading pools. Investing in teleradiology infrastructure alongside equipment deployment enables equipment utilization optimization across hospital networks, improving both diagnostic throughput and the economic justification for advanced equipment investment at regional facilities.
Market Challenges
- Regulatory Compliance and Registration Process Complexity: Medical device registration requirements, while progressively streamlining, still require significant documentation, testing data, and establishment licensing compliance from manufacturers seeking Saudi market access. The complexity of registration, combined with import and Saudization requirements, creates lead time and cost barriers for smaller equipment manufacturers seeking to compete with established OEMs that have maintained relationships and registration portfolios.
- Equipment Maintenance and Service Network Gaps in Secondary Cities: Saudi Arabia's large geographic territory creates equipment service and maintenance challenges for hospital facilities in secondary and tertiary cities distant from major OEM service centers. Equipment downtime due to inadequate local service capacity has real clinical and financial consequences for hospital operations. OEMs that invest in service network expansion across Saudi Arabia's regions gain competitive advantages in procurement decisions where service reliability is a critical evaluation criterion.
Emerging Market Trends
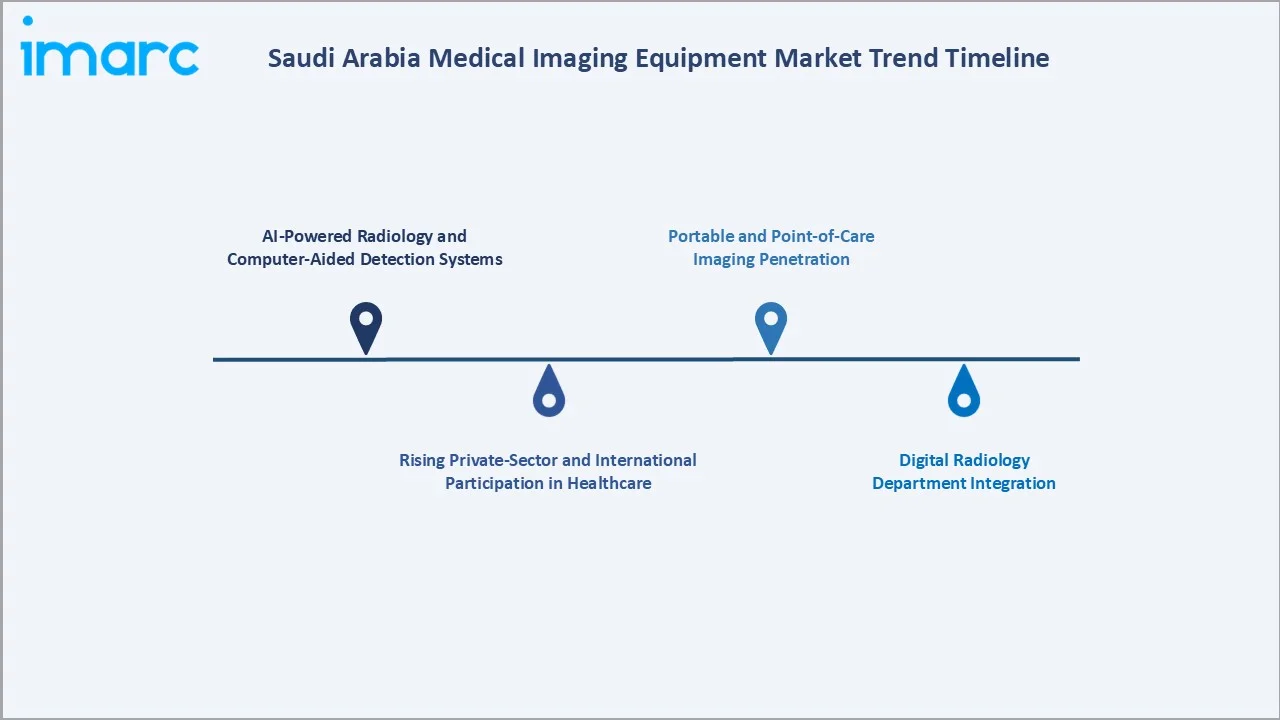
1. AI-Powered Radiology and Computer-Aided Detection Systems
Artificial intelligence integration in medical imaging is the most significant technology transition reshaping Saudi Arabia's market. AI algorithms embedded in CT scanners and MRI systems enable automated lesion detection, organ segmentation, quantitative analysis, and workflow prioritization that improve radiologist productivity and diagnostic accuracy.
2. Rising Private-Sector and International Participation in Healthcare
Saudi Arabia is increasingly attracting private and international hospital operators as it expands healthcare capacity under Vision 2030. In September 2026, Saudi Arabia’s Ministry of Health authorized AKDITAL Group to open AKDITAL Hospitals Al Olaya in Riyadh, marking the group’s entry into the Kingdom. The launch supports Saudi Arabia’s ongoing healthcare expansion under Vision 2030, which is encouraging greater private-sector investment and participation from international healthcare operators. This trend is supporting new hospital development, greater competition, and demand for advanced medical technologies and diagnostic imaging equipment.
3. Portable and Point-of-Care Imaging Penetration
The COVID-19 pandemic demonstrated the clinical and operational value of portable and hand-held imaging equipment for infection control, bedside assessment, and emergency triage. Saudi hospitals accelerated portable ultrasound and mobile X-ray procurement during the pandemic, and this trend has continued as clinicians recognize the workflow benefits of point-of-care imaging. Hand-held ultrasound devices are entering Saudi emergency medicine, critical care, and rural primary health care environments.
4. Digital Radiology Department Integration
Saudi Arabia's hospitals are progressively upgrading from legacy analog and CR-based radiology workflows to fully digital radiology environments with integrated PACS (Picture Archiving and Communication Systems) and RIS (Radiology Information Systems). This digital transformation creates parallel demand for imaging equipment replacement as older analog and CR systems are retired, and for new PACS/RIS infrastructure investments that enable enterprise imaging data management.
Industry Value Chain Analysis
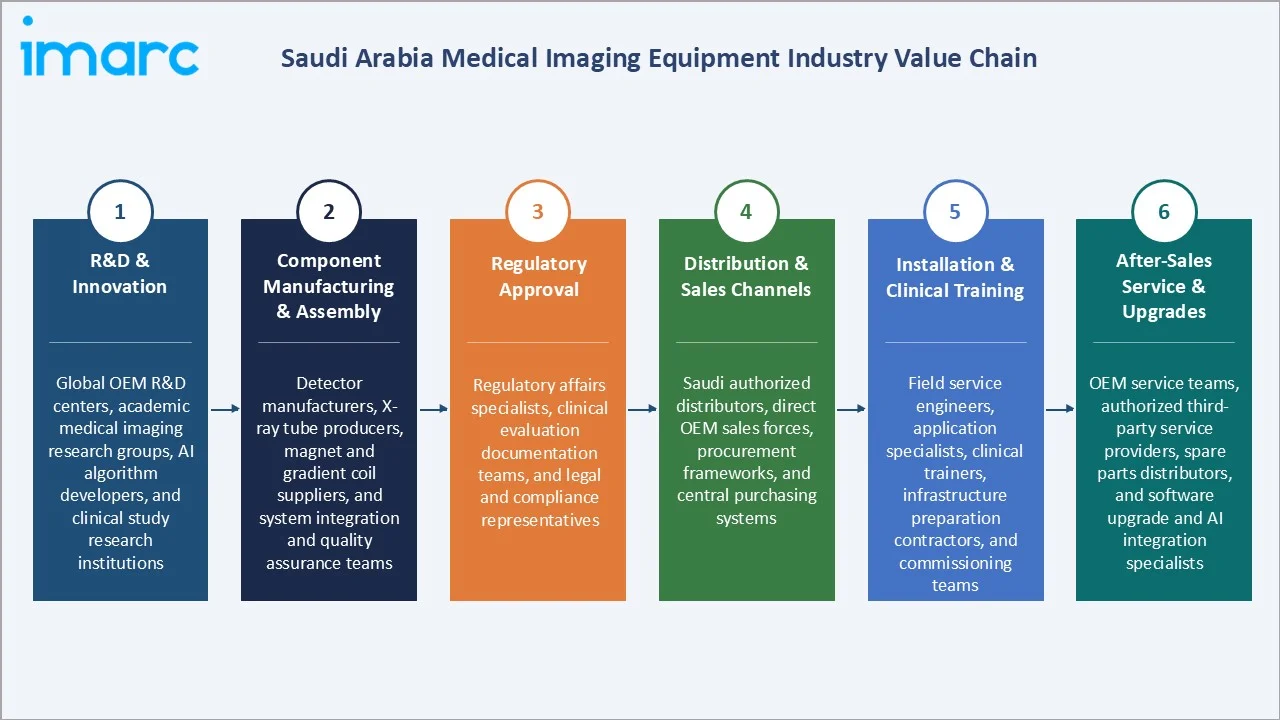
The Saudi Arabia medical imaging equipment value chain integrates research and development, component manufacturing and system assembly, regulatory approval, distribution and sales channels, clinical installation and training, and after-sales service and equipment upgrades across hospital, diagnostic center, and specialty clinic end-user segments.
|
Stage |
Key Participants |
|
R&D & Innovation |
Global OEM R&D centers, academic medical imaging research groups, AI algorithm developers, and clinical study research institutions. |
|
Component Manufacturing & Assembly |
Detector manufacturers, X-ray tube producers, magnet and gradient coil suppliers, and system integration and quality assurance teams. |
|
Regulatory Approval |
Regulatory affairs specialists, clinical evaluation documentation teams, and legal and compliance representatives. |
|
Distribution & Sales Channels |
Saudi authorized distributors, direct OEM sales forces, procurement frameworks, and central purchasing systems. |
|
Installation & Clinical Training |
Field service engineers, application specialists, clinical trainers, infrastructure preparation contractors, and commissioning teams. |
|
After-Sales Service & Upgrades |
OEM service teams, authorized third-party service providers, spare parts distributors, and software upgrade and AI integration specialists. |
After-sales service and equipment upgrades represent a strategically critical value chain stage in Saudi Arabia's medical imaging market, as the availability of reliable local service support is a primary procurement evaluation criterion for Saudi hospital biomedical engineering departments. OEMs that maintain dedicated Saudi Arabia field service teams with adequate spare parts inventory, fast response time SLAs, and remote diagnostics capabilities command significant competitive advantages and sustain long-term customer relationships through equipment lifecycle upgrade cycles.
Technology Landscape in the Saudi Arabia Medical Imaging Equipment Industry
Advanced CT and MRI Platform Technology
Saudi Arabia's leading tertiary hospitals are procuring the most advanced available CT and MRI platforms to support complex diagnostic and research applications. Spectral CT (photon-counting CT and dual-energy CT) enables tissue characterization and material decomposition beyond conventional CT's capability, improving diagnosis of liver disease, renal masses, and vascular conditions highly prevalent in Saudi Arabia. Ultra-high field 7T MRI, while primarily research-grade, is being specified by university hospital research facilities. Clinical 3T MRI with advanced neurological, cardiac, and oncological application packages is the standard specification for new Saudi tertiary hospital MRI rooms.
Digital X-ray and Fluoroscopy Technology
Saudi Arabia's radiology departments are completing the transition from film-based and computed radiography (CR) X-ray to direct digital radiography (DR) systems with flat-panel detector technology. Wireless DR detectors enable rapid multi-room imaging workflows that maximize radiography throughput in busy Saudi hospital radiology departments. Robotic C-arm systems and large-format flat-panel fluoroscopy suites are being installed in Saudi cardiac catheterization laboratories, interventional radiology departments, and endoscopy suites, driven by growing interventional procedure volumes.
Ultrasound and Point-of-Care Technology
Ultrasound technology innovation is rapidly expanding the clinical application range and care setting penetration of ultrasound imaging in Saudi Arabia. Premium ultrasound platforms enable advanced applications including contrast-enhanced ultrasound, elastography, and 3D/4D fetal imaging that are increasingly demanded by Saudi obstetrics, hepatology, and gastroenterology services. Hand-held ultrasound, portable ultrasound, and trolley-based point-of-care ultrasound systems are expanding imaging access to emergency rooms, primary care centers, and remote regional clinics.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Equipment Type |
🔒 |
🔒 |
2025 |
|
Modality |
Stand-Alone Devices |
61.8% |
2025 |
|
Application |
🔒 |
🔒 |
2025 |
|
End User |
Hospitals |
57.3% |
2025 |
|
Region |
Northern and Central Region |
43.2% |
2025 |

By Modality
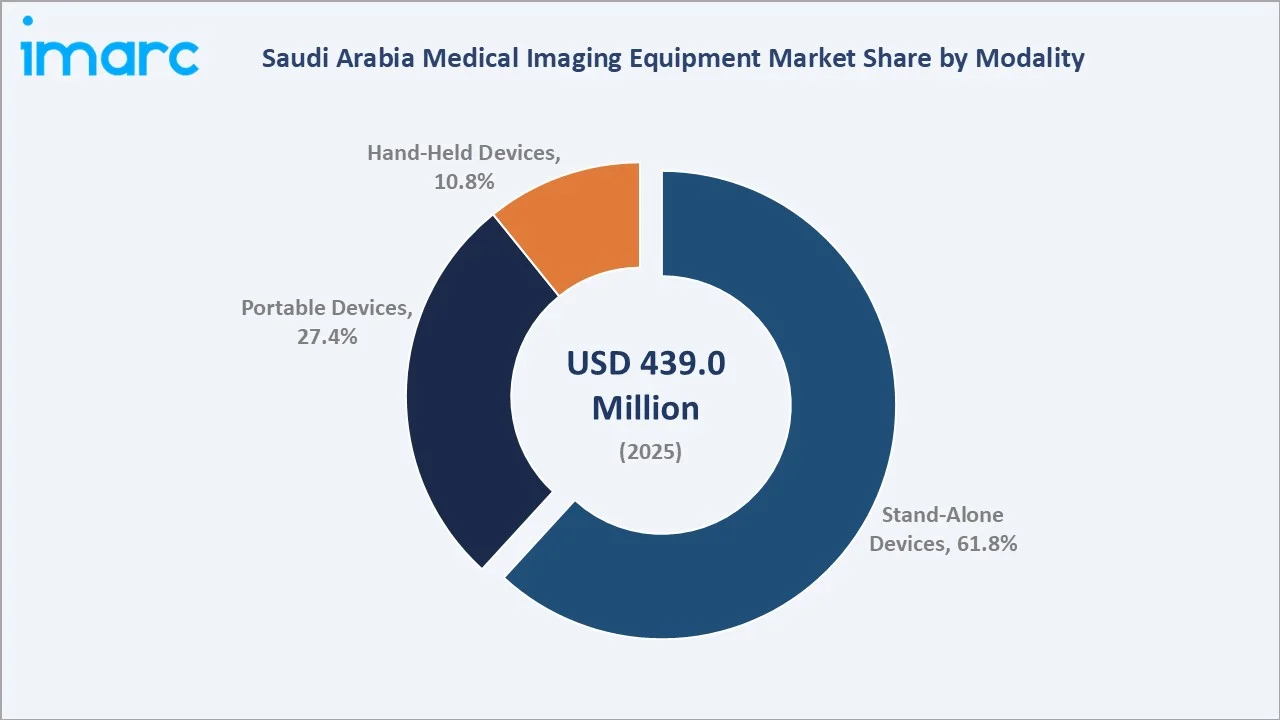
Stand-alone devices lead at 61.8% (2025), driven by hospital radiology department procurement of full-specification stationary CT, MRI, X-ray, and nuclear medicine systems that deliver the throughput, image quality, and workflow integration required for tertiary care diagnostic services.
To access detailed market analysis, Request Sample
Portable devices at 27.4% represent a growing segment through mobile X-ray, portable ultrasound, and mobile CT adoption in ICUs, emergency departments, and multi-site hospital networks. Hand-held devices at 10.8% are the fastest-growing modality at ~8.9% CAGR, driven by point-of-care ultrasound adoption and expanding primary healthcare center equipment programs under Vision 2030.
By End User
Hospitals lead at 57.3% (2025), as the primary institutional buyers of advanced imaging equipment through central procurement and private hospital groups requiring complete radiology department equipment suites for new and upgraded facilities.
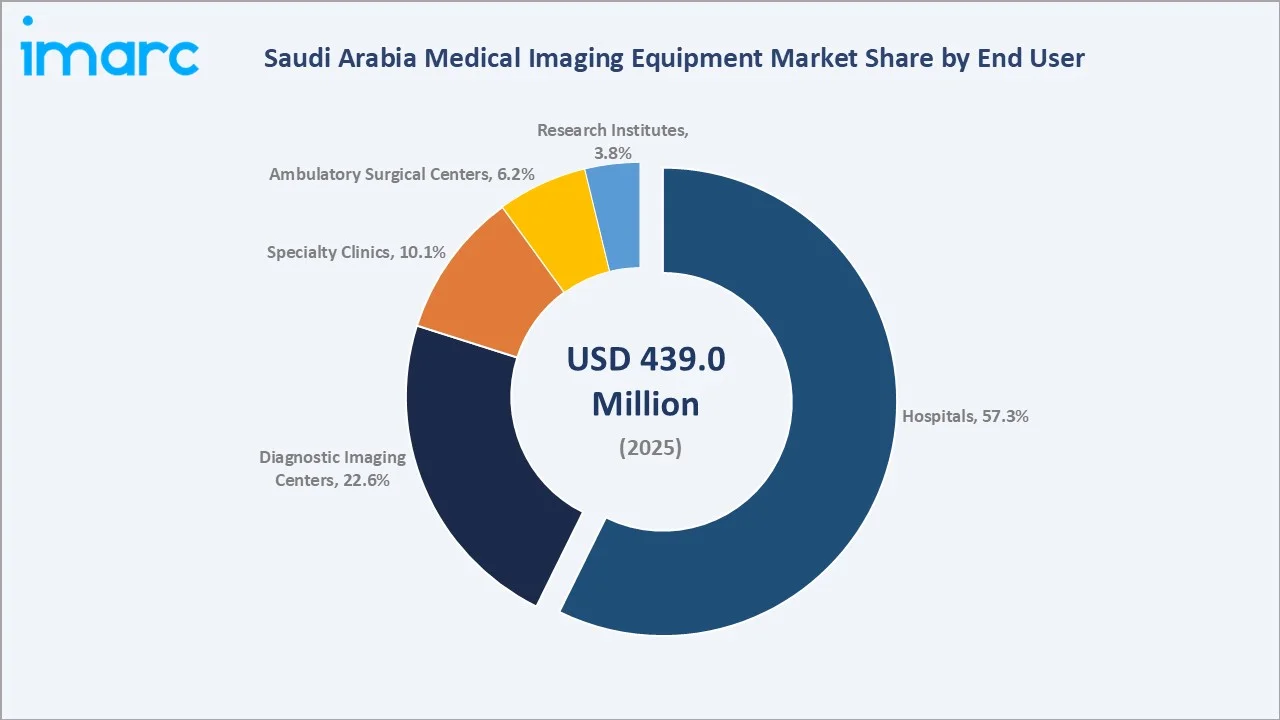
Diagnostic imaging centers at 22.6% reflect the growing private outpatient imaging market driven by healthcare privatization and insurance coverage expansion. Specialty clinics at 10.1% serve orthopedics, cardiology, and oncology specialist practices. Ambulatory surgical centers at 6.2% require C-arms and fluoroscopy for image-guided procedures. Research institutes at 3.8% include university medical schools with advanced imaging research programs.
Regional Market Insights
|
Region |
Share (2025) |
Key Saudi Arabia Medical Imaging Equipment Market Drivers & Characteristics |
|
Northern & Central Region |
43.2% |
Reflecting the concentration of Saudi Arabia's largest tertiary hospitals, national guard health facilities, major private hospital groups, and research institutions in Riyadh, generating the highest imaging equipment procurement volumes in the Kingdom. |
|
Western Region |
24.9% |
Reflecting Jeddah's large private hospital network, Makkah and Madinah healthcare infrastructure serving pilgrimage populations, and growing diagnostic imaging center chain expansion serving the large population. |
|
Eastern Region |
20.8% |
Reflecting advanced imaging facilities, private hospital and diagnostic center growth, and industrial city medical facility equipment programs. |
|
Southern Region |
11.1% |
Reflecting hospital upgrades under Vision 2030 regional healthcare equity programs, NEOM-related healthcare facility development, and primary healthcare center portable imaging equipment procurement. |
The Northern and Central region's 43.2% leadership reflects Riyadh's extraordinary healthcare facility density, including the hospital network and diagnostic centers. The Western region's 24.9% reflects Jeddah's large and growing private healthcare market, Makkah and Madinah's significant healthcare infrastructure serving over pilgrimage visitors, and academic and research imaging programs.
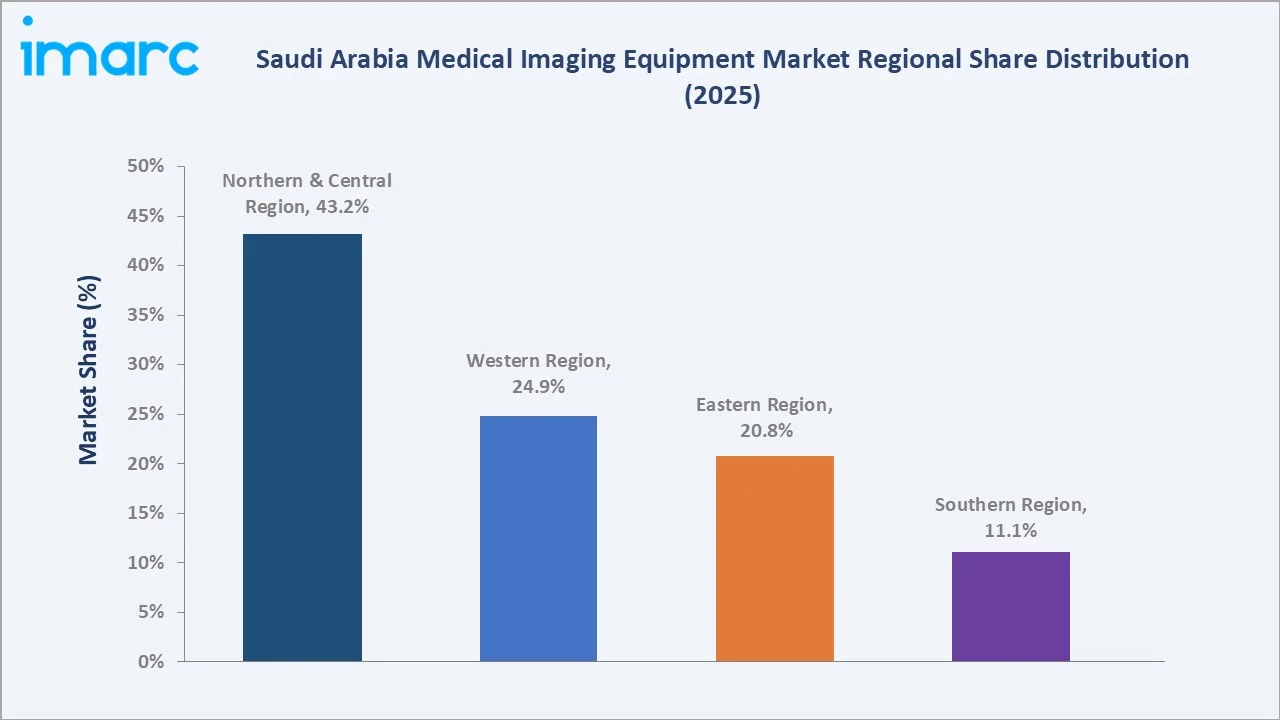
The Eastern region's 20.8% is anchored by world-class medical facilities with advanced imaging capabilities, and the region's large private hospital and diagnostic center market serving the Eastern Province's high-income professional population. The Southern region at 11.1% represents growing equipment demand as Vision 2030 regional healthcare equity programs fund hospital upgrades and primary healthcare center expansion across southern provinces.
Competitive Landscape
The Saudi Arabia medical imaging equipment market is dominated by global OEMs with established Saudi Arabia operations, product registration portfolios, and local service support networks. Competition is driven by technology differentiation, Saudi government procurement relationship depth, regulatory compliance, local service infrastructure, and pricing competitiveness in MOH tenders.
|
Company |
Key Products |
Market Position |
Core Strength |
|
GE HealthCare |
Bone and metabolic health, Computed tomography, Fluoroscopy, Invasive cardiology, Magnetic resonance imaging, Mammography, Molecular imaging |
Market Leader |
GE HealthCare plays a major role in supplying advanced medical imaging, AI diagnostics, and digital healthcare solutions across Saudi Arabia in alignment with Saudi Vision 2030. |
|
Siemens Healthineers AG |
Angiography, Computed Tomography, Endovascular Robotics, Fluoroscopy Equipment, Imaging for Radiation Therapy, Robotic X-ray, Ultrasound Machines |
Market Leader |
Siemens Healthineers acts as a leading provider of advanced medical imaging systems, technology management, and digital health solutions in Saudi Arabia to support the country's healthcare transformation. |
|
Koninklijke Philips N.V. |
Magnetic Resonance Imaging, Computed Tomography, Radiography, Fluoroscopy |
Market Leader |
Koninklijke Philips N.V. acts as a major market leader and strategic technology partner providing advanced diagnostic and multimodal imaging equipment across Saudi Arabia. |
|
Canon Inc. |
Angiography, Computed Tomography, Magnetic Resonance, Ultrasound, X-ray, Molecular Imaging |
Established Player |
Canon Inc., operating primarily through its subsidiary Canon Medical Systems, plays a pivotal role in Saudi Arabia's medical imaging equipment sector. |
|
FUJIFILM Holdings Corporation |
X-ray Imaging Devices, Ultrasound Systems, Endoscopy, In Vitro Diagnostics, MRI and CT |
Established Player |
FUJIFILM Holdings Corporation operates as a major strategic player in Saudi Arabia’s medical imaging equipment sector, driving the market's shift toward AI-powered software, national digital integration, and preventative healthcare. |
Companies across the competitive landscape are investing in AI imaging software integration, Saudi Arabia service network expansion, regulatory affairs capabilities, and application specialist teams that support clinical workflow optimization for Saudi hospital customers.
Key Company Profiles
GE HealthCare
GE HealthCare is the largest medical imaging equipment supplier in Saudi Arabia by market revenue and installed base breadth. GE HealthCare's Saudi Arabia operations serve the major private hospital groups with the industry's broadest imaging portfolio spanning CT, MRI, ultrasound, nuclear medicine, and interventional X-ray. GE HealthCare's Saudi Arabia service organization maintains dedicated field service engineers and a parts distribution center that enables rapid equipment uptime restoration.
- Key Products: Bone and metabolic health, Computed tomography, Fluoroscopy, Invasive cardiology, Magnetic resonance imaging, Mammography, Molecular imaging.
- Strategic Focus: Expanding AI platform adoption across Saudi hospital customers by demonstrating radiology workflow efficiency and diagnostic quality improvements, growing portable and hand-held ultrasound market share in Saudi primary healthcare and emergency department applications, and strengthening GE HealthCare's position in NEOM smart hospital specifications.
Siemens Healthineers AG
Siemens Healthineers is one of the leading medical technology companies with a premier position in Saudi Arabia across advanced imaging modalities. Siemens Healthineers' Saudi Arabia business serves the Kingdom's most demanding healthcare environments, with cardiac, trauma, and oncology centers, and MRI platforms supporting neurological, musculoskeletal, and cancer staging imaging programs. Siemens Healthineers' digital platform enables remote service, performance benchmarking, and clinical workflow analytics for Saudi hospital network administrators.
- Key Products: Angiography, Computed Tomography, Endovascular Robotics, Fluoroscopy Equipment, Imaging for Radiation Therapy, Robotic X-ray, Ultrasound Machines.
- Strategic Focus: Advancing photon-counting CT adoption in Saudi Arabia's most advanced hospitals as a next-generation CT technology differentiator, developing Saudi Arabia-specific AI imaging applications addressing the NCD disease burden, including cardiac CT and lung cancer CT screening programs, and expanding Siemens Healthineers' NEOM healthcare facility presence as a strategic priority.
Market Concentration Analysis
The Saudi Arabia medical imaging equipment market exhibits moderate-to-high concentration, with GE HealthCare, Siemens Healthineers AG, and Koninklijke Philips N.V., collectively commanding approximately 55-60% of total market revenues through their broad multi-modality portfolios and established MOH and private healthcare relationships. Other established players account for approximately 25-30% of market share, while price-competitive Asian manufacturers are growing their share in mid-market segments. Concentration is expected to remain stable through 2034, with AI integration capabilities becoming an increasingly important differentiator that favors established OEMs with advanced R&D resources.
Investment & Growth Opportunities
Highest Growth Segments
Hand-held devices (~8.9% CAGR), portable devices (~7.6% CAGR), AI-integrated imaging platforms, diagnostic imaging centers (private sector), mammography for breast cancer screening programs, and PET-CT for oncology represent the highest-growth investment vectors in the Saudi Arabia medical imaging equipment market through 2034.
Investment Themes
- AI imaging software and platform development for Saudi market: Developing AI clinical decision support applications specifically validated for disease presentations prevalent in the Saudi population, including obesity-related conditions, cardiovascular disease, diabetes complications, and cancer types with elevated Saudi incidence, creates differentiated value propositions for imaging equipment that cannot be replicated by AI algorithms developed from non-representative patient populations.
- Diagnostic imaging center chain investment: The rapid growth of private diagnostic imaging centers driven by insurance coverage expansion and healthcare privatization creates franchise and chain model investment opportunities. Standardized imaging center concepts with optimized equipment configurations, operational protocols, and teleradiology reporting can scale rapidly across Saudi Arabia's cities and towns, capturing the growing outpatient imaging market without the capital intensity of hospital development.
Future Market Outlook (2026-2034)
The Saudi Arabia medical imaging equipment market is projected to grow from USD 439.0 Million in 2025 to USD 465.4 Million in 2026 and is forecast to reach USD 742.9 Million by 2034 , exhibiting a CAGR of 6.02% during 2026-2034. The market is projected to reach an anchor value of USD 588.0 Million by 2030, representing the mid-period milestone at which Vision 2030's hospital construction program reaches completion and new facility equipment installations generate peak procurement volumes.
Three structural forces will define the Saudi Arabia medical imaging equipment market through 2034. First, Vision 2030's healthcare infrastructure expansion will deliver the largest single batch of new hospital facilities in Saudi Arabia's history through 2030. Second, AI integration will become the primary basis of medical imaging equipment differentiation and premium pricing through 2034. Third, the rising NCD burden will sustain above-baseline imaging utilization growth that multiplies scan volumes from the expanding installed equipment base.
Research Methodology
Primary Research
Primary research comprised in-depth interviews with hospital biomedical engineering directors, radiology department heads, medical imaging OEM Saudi Arabia country managers, registered distributors, and healthcare market analysts. These discussions validated market size estimates, assessed equipment demand trends by modality and end user, evaluated competitive dynamics, and provided insights into Vision 2030 procurement programs and future market evolution.
Secondary Research
Secondary research encompassed annual health statistics publications, registered medical device database, healthcare performance indicators, Saudi Vision 2030 health sector reports, leading OEM annual reports and Saudi Arabia investor presentations, radiology workforce data, and industry publications covering GCC and Saudi Arabia medical device market developments.
Forecasting Models
Forecasting models incorporated historical medical imaging equipment market revenue trends, Vision 2030 hospital construction and equipment procurement schedules, NCD burden and imaging utilization projections, private healthcare sector investment growth, and AI technology adoption penetration curves. Both top-down macro-healthcare-investment and bottom-up facility-level equipment procurement models were cross-validated for consistency.
Saudi Arabia Medical Imaging Equipment Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report | Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Equipment Types Covered | Computed Tomography (CT) Systems, X-Ray Systems, MRI Systems, Ultrasound Systems, Nuclear Imaging Equipment, Mammography Equipment, Contrast Media Injectors, C-Arms & Fluoroscopy Devices |
| Modalities Covered | Stand-Alone Devices, Portable Devices, Hand-Held Devices |
| Applications Covered | Oncology, Cardiology, Orthopedics, Neurology, Dentistry, Gynecology |
| End Users Covered | Hospitals, Diagnostic Imaging Centers, Ambulatory Surgical Centers, Specialty Clinics, Research Institutes |
| Regions Covered | Northern and Central Region, Western Region, Eastern Region, Southern Region |
| Companies Covered | GE HealthCare, Siemens Healthineers AG, Koninklijke Philips N.V., Canon Inc., FUJIFILM Holdings Corporation, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Saudi Arabia medical imaging equipment market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Saudi Arabia medical imaging equipment market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Saudi Arabia medical imaging equipment industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Saudi Arabia Medical Imaging Equipment Market Report
The Saudi Arabia medical imaging equipment market size is estimated at USD 465.4 Million in 2026, driven by Vision 2030's SAR 500 billion healthcare investment program, rising NCD burden increasing imaging demand, AI-integrated imaging platform adoption, private healthcare sector expansion, and NEOM smart hospital development.
The Saudi Arabia medical imaging equipment market is projected to grow at a CAGR of 6.02% during 2026-2034, sustained by the Vision 2030 hospital construction pipeline, AI imaging system upgrade cycles, rising NCD screening and monitoring demand, diagnostic imaging center chain growth, and portable device expansion.
The market is projected to reach approximately USD 588.0 Million by 2030, representing the mid-period milestone at which Vision 2030's hospital construction program reaches completion, generating peak new facility equipment installation procurement volumes across CT, MRI, X-ray, and ultrasound modalities.
Stand-alone devices lead with a 61.8% share in 2025, driven by hospital radiology department procurement of full-specification stationary CT, MRI, X-ray, and nuclear medicine systems that deliver the throughput, image quality, and enterprise workflow integration required for tertiary care diagnostic services.
Hospitals dominate with a 57.3% share in 2025, as the primary institutional buyers of advanced imaging equipment through central procurement programs and private hospital groups requiring complete radiology department equipment suites for new and upgraded facilities.
The Northern and Central region leads with a 43.2% share in 2025, driven by Riyadh's concentration of the Kingdom's largest tertiary hospitals, national guard healthcare facilities, private hospital groups, and research institutions generating the highest imaging equipment procurement volumes in Saudi Arabia.
Key players include GE HealthCare, Siemens Healthineers AG, Koninklijke Philips N.V., Canon Inc., and FUJIFILM Holdings Corporation, among others.
The Saudi Arabia medical imaging equipment market is projected to reach USD 742.9 Million by 2034, driven by continued facility expansion, AI equipment upgrade cycles from early Vision 2030 hospitals, a growing diagnostic imaging center market, and progressive hand-held and portable device penetration into primary healthcare settings.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade