
Saudi Arabia Olive Oil Market Size, Share, Trends and Forecast by Type, Distribution Channel, Application, and Region, 2026-2034
Saudi Arabia Olive Oil Market Size, Share, Trends & Forecast (2026-2034)
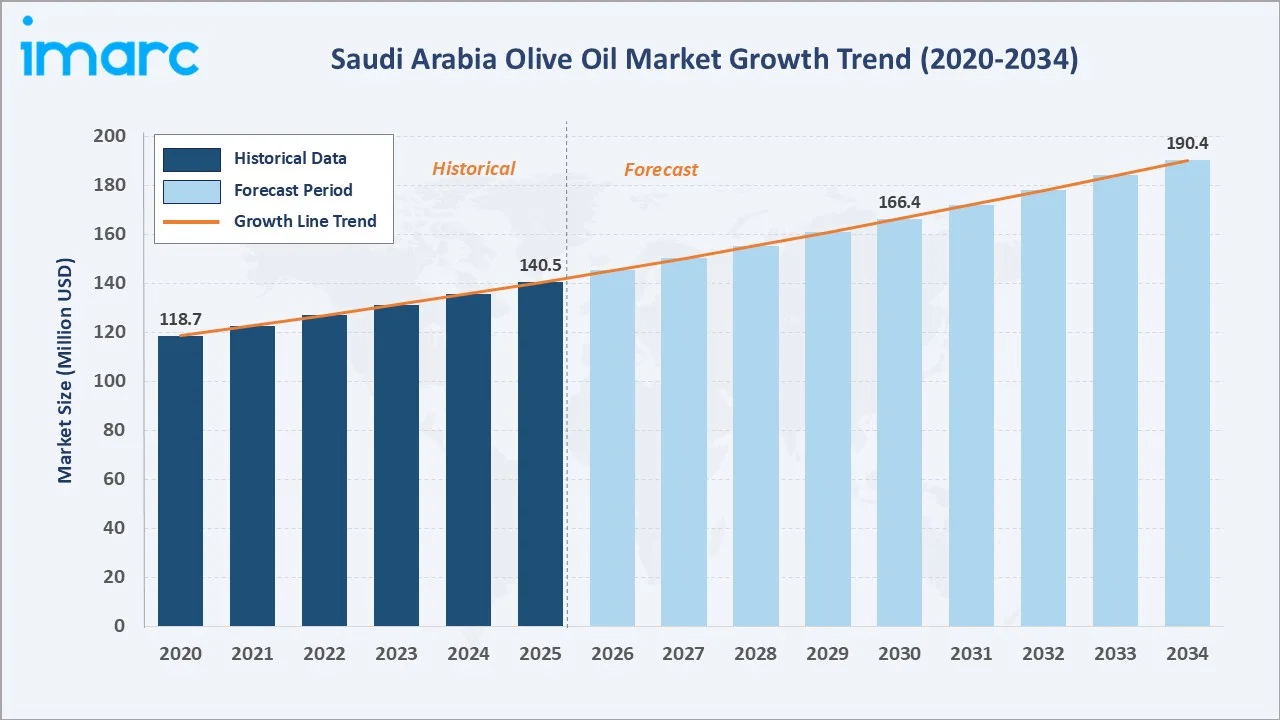
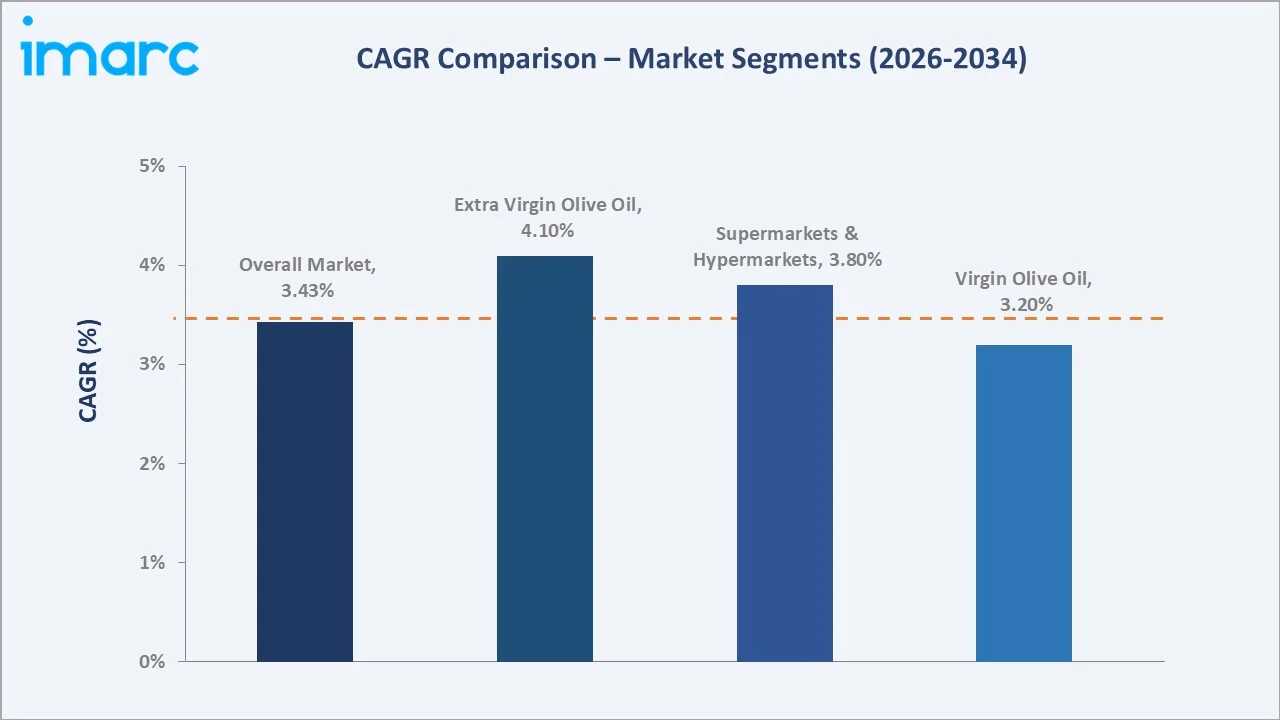
The Saudi Arabia olive oil market reached USD 140.5 Million in 2025 and is projected to reach USD 190.4 Million by 2034, growing at a CAGR of 3.43% during 2026-2034. The market is driven by rising health consciousness, a growing expat population, and Vision 2030 retail modernization. Extra Virgin Olive Oil leads at 41.6%, and Supermarkets & Hypermarkets dominate distribution at 52.7%. The Northern and Central Region commands 38.6% of market share.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 140.5 Million |
|
Forecast Market Size (2034) |
USD 190.4 Million |
|
CAGR (2026-2034) |
3.43% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Type |
Extra Virgin Olive Oil (41.6%, 2025) |
|
Dominant Distribution Channel |
Supermarkets and Hypermarkets (52.7%, 2025) |
|
Leading Region |
Northern and Central Region (38.6%, 2025) |
The market expanded from USD 118.7 Million in 2020 to USD 140.5 Million in 2025, anchored at USD 166.4 Million in 2030 and forecast to reach USD 190.4 Million by 2034. Saudi Arabia's Vision 2030 modernization, rising health awareness, and growing expatriate community drove consistent market expansion throughout the historical period.
To get more information on this market, Request Sample
Extra Virgin Olive Oil at 41.6% and Supermarkets & Hypermarkets at 52.7% are the dominant segments. The Northern and Central Region commands 38.6%, reflecting the concentration of population, modern retail infrastructure, and purchasing power in Riyadh and surrounding areas.
Executive Summary
The Saudi Arabia olive oil market reached USD 140.5 Million in 2025, representing a premium edible oil category driven by growing health consciousness, Mediterranean diet adoption, and an expanding expatriate population. Olive oil is positioned as a healthy cooking oil alternative across Saudi Arabia's modern retail and foodservice sectors. The market is projected to reach USD 190.4 Million by 2034.
Extra Virgin Olive Oil at 41.6% dominates through premium positioning and health benefit awareness. Supermarkets and Hypermarkets at 52.7% lead distribution through their broad reach, promotional pricing, and wide brand selection. The Northern and Central Region at 38.6% leads through Riyadh's affluent urban consumer base, high expat concentration, and modern retail density.
Key Market Insights
|
Insight |
Data |
|
Dominant Type |
Extra Virgin Olive Oil – 41.6% share (2025) |
|
Dominant Distribution Channel |
Supermarkets and Hypermarkets – 52.7% market share (2025) |
|
Leading Region |
Northern and Central Region – 38.6% market share (2025) |
|
Market Opportunity |
Premium EVOO growth; online channel expansion; health-positioned product launches; Saudi domestic production development |
Key Analytical Observations Supporting the Above Data:
- Extra Virgin Olive Oil at 41.6%: EVOO dominates through rising health consciousness among Saudi consumers, who associate it with Mediterranean diet benefits including cardiovascular health and antioxidant properties.
- Supermarkets and Hypermarkets at 52.7%: Supermarkets and hypermarkets dominate olive oil distribution through their ability to stock multiple brands, price grades, and volume formats in one location.
- Northern and Central Region at 38.6%: The Northern and Central Region leads through Riyadh's high-income urban consumer base, significant expatriate population from Mediterranean countries, and the highest concentration of modern supermarket and hypermarket outlets in the Kingdom, generating the highest per-capita olive oil purchasing volumes nationally.
Saudi Arabia Olive Oil Market Overview
The Saudi Arabia olive oil market encompasses the import, distribution, and retail sale of virgin, refined, extra virgin, and pomace olive oil grades across supermarkets, convenience stores, online platforms, and foodservice channels. The ecosystem integrates Mediterranean olive oil producers, Saudi importers and distributors, modern retail chains, and an increasingly health-conscious consumer base.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
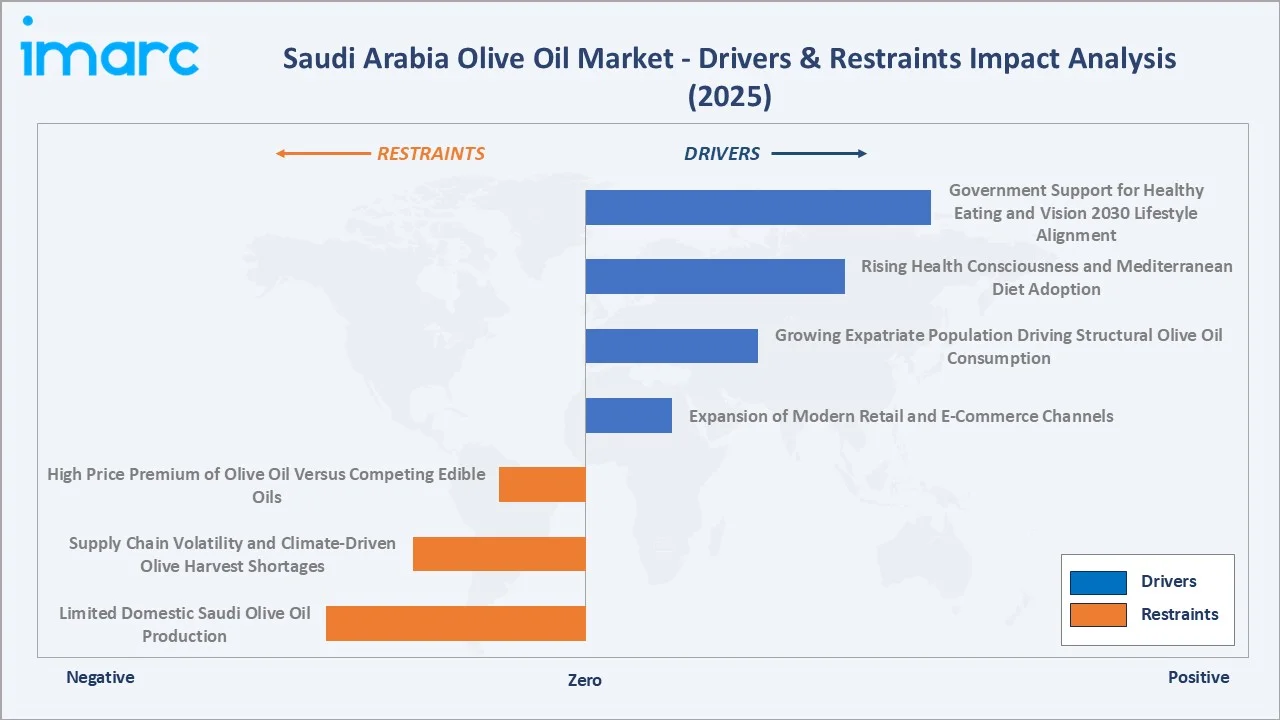
- Government Support for Healthy Eating and Vision 2030 Lifestyle Alignment: Saudi Arabia's Vision 2030 health and wellness programs, including the National Transformation Program's focus on reduced non-communicable disease prevalence, align with olive oil's positioning as a heart-healthy dietary fat. Government health campaigns promoting Mediterranean-style eating patterns create institutional demand support for olive oil category growth across Saudi retail channels. The Saudi Food and Drug Authority's (SFDA) proactive food labeling and health claim regulations increasingly enable olive oil brands to communicate specific health benefits to Saudi consumers, including cardiovascular protection and anti-inflammatory properties.
- Rising Health Consciousness and Mediterranean Diet Adoption: Saudi consumers are increasingly adopting Mediterranean diet principles associated with cardiovascular health, weight management, and anti-inflammatory nutrition. Extra virgin olive oil's established health benefit profile creates a premium purchasing rationale that sustains demand above general edible oil consumption growth rates. Growing physician recommendation of olive oil substitution over saturated fats, combined with expanding Saudi social media health and wellness content promoting EVOO-based cooking, creates strong consumer education pathways.
- Growing Expatriate Population Driving Structural Olive Oil Consumption: Saudi Arabia's expatriate population of over 12 million, including significant communities from Mediterranean countries such as Lebanon, Syria, Jordan, Egypt, and European nations, brings established olive oil consumption habits that drive consistent market demand independent of Saudi consumer adoption rates. Expatriate communities represent the highest per-capita olive oil consumers in the Saudi market, with household olive oil consumption rates matching Mediterranean country averages. As Vision 2030 economic diversification attracts additional skilled expatriate workers across technology, entertainment, and professional services sectors, the expatriate consumer base for olive oil expands organically without requiring consumer adoption campaigns.
- Expansion of Modern Retail and E-Commerce Channels: Saudi Arabia's rapid modern retail expansion under Vision 2030, including new hypermarket openings, premium grocery formats, and specialty food retailer entries, increases olive oil shelf visibility and consumer touchpoints across urban areas. Online grocery platforms provide additional channel access for premium olive oil brands.
Market Restraints
- High Price Premium of Olive Oil Versus Competing Edible Oils: Olive oil's significant price premium versus sunflower, canola, and vegetable oils limits market penetration among price-sensitive Saudi consumer segments. The price gap constrains household olive oil usage from premium occasional use to everyday cooking adoption across middle-income households. Saudi Arabia's broader edible oil market is dominated by low-cost alternatives that are deeply embedded in traditional Saudi cooking practices.
- Supply Chain Volatility and Climate-Driven Olive Harvest Shortages: Mediterranean olive oil production is highly sensitive to drought, extreme heat events, and the natural biennial yield cycle of olive trees. Supply disruptions in major producing regions translate directly into Saudi Arabia's import-dependent market through price spikes, brand-level shortages, and consumer trade-down behaviors. The 2022-2024 period exemplified this vulnerability, with Spanish and Italian olive harvest failures driving global olive oil prices to record levels that significantly impacted Saudi retail shelf prices.
- Limited Domestic Saudi Olive Oil Production: Saudi Arabia has a nascent olive cultivation sector, primarily in the Al-Jouf region, but domestic production meets only a small fraction of market demand. The absence of a significant domestic olive oil industry limits the development of Saudi-origin premium brands that could command premium positioning and reduce import price exposure. Al-Jouf's olive cultivation program, while growing, faces challenges including water scarcity constraints, high production costs relative to Mediterranean origins, and limited processing and bottling infrastructure.
Market Opportunities
- Premium Certified Origin and Organic EVOO Growth: Growing Saudi urban consumer interest in certified origin (PDO/PGI) and organic extra virgin olive oil creates a premium market tier with strong margin opportunity for established international brands and specialist importers. Health-positioned premium EVOO commands 30-60% price premiums over standard grades. Saudi Arabia's premium food retail expansion, including Carrefour Market premium aisles, specialty organic stores, and high-end grocery formats catering to Vision 2030 lifestyle consumers, provides premium EVOO brands with growing shelf access.
- Online Grocery Channel Growth: Saudi Arabia's online grocery market, one of the fastest-growing in the GCC region, creates significant distribution opportunity for premium olive oil brands seeking to reach health-conscious consumers outside traditional hypermarket channels. Online platforms enable subscription models and bundle promotions. Platforms including Noon, Nana, and Carrefour Online provide olive oil brands with search-driven discovery by health benefit keywords, subscription purchasing for regular users, and data-driven consumer targeting unavailable through offline retail.
Market Challenges
- Consumer Taste Preference for Local and Regional Edible Oils: Traditional Saudi and GCC cooking practices are built around locally preferred edible oils including ghee, corn oil, and sunflower oil, which have deep household penetration and do not require the consumer behavior change that olive oil adoption demands. Taste profile differences limit substitution rates among traditional Saudi home cooks. Olive oil's distinctive flavor profile, while valued in Western and Mediterranean cooking contexts, requires recipe adaptation that traditional Saudi household cooks may not readily undertake.
- Counterfeit and Adulteration Risk: Olive oil adulteration is a well-documented global problem that is particularly challenging to detect at the retail consumer level. Saudi consumers who experience adulterated products may reduce premium olive oil spending or switch to alternative health-positioned oils. Saudi Arabia's SFDA has progressively strengthened olive oil authenticity standards and import testing requirements, but the high volume of olive oil imports from multiple origins makes systematic adulteration detection challenging.
Emerging Market Trends
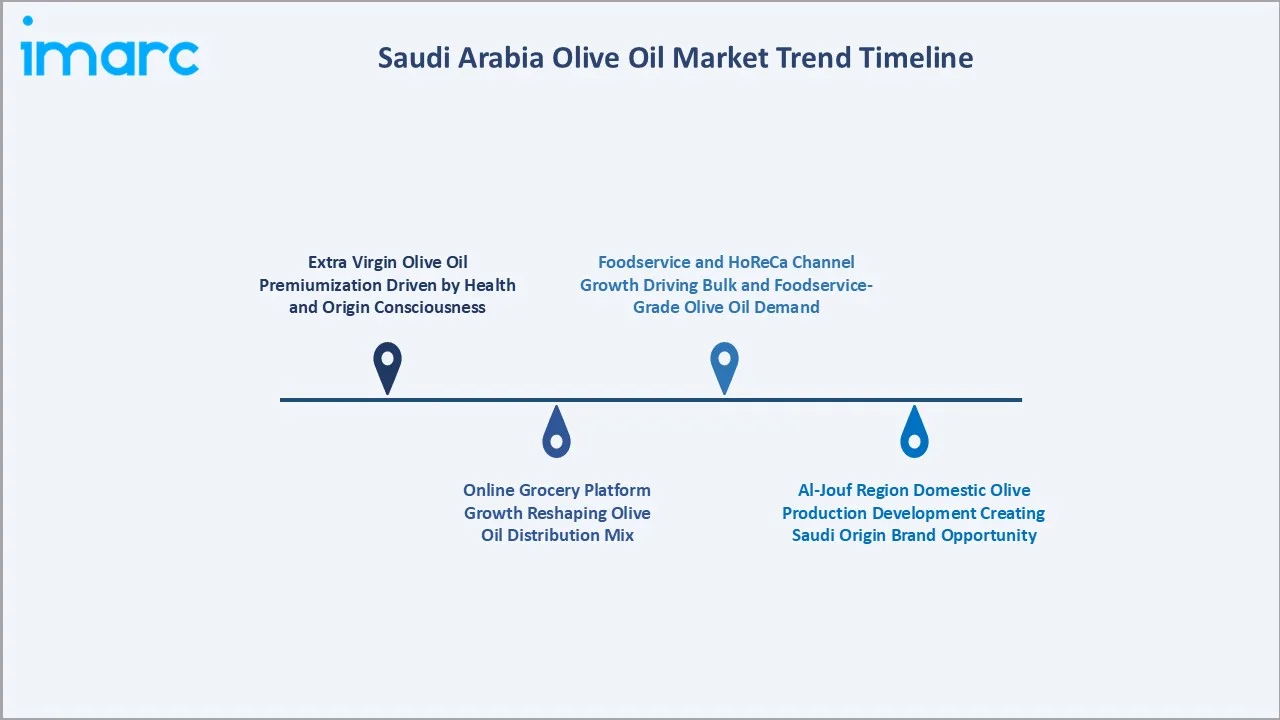
1. Extra Virgin Olive Oil Premiumization Driven by Health and Origin Consciousness
Saudi consumer demand is shifting from standard olive oil grades toward extra virgin olive oil, driven by growing awareness of polyphenol content, cardiovascular health benefits, and origin traceability. Premium EVOO brands with certified designations of origin, harvest date labeling, and organic certification are gaining shelf space in premium Saudi supermarket formats, commanding 30-60% price premiums over standard EVOO grades and capturing share from established commodity brands.
2. Online Grocery Platform Growth Reshaping Olive Oil Distribution Mix
Saudi Arabia's rapid online grocery adoption, sustained post-pandemic as a primary shopping channel for premium food categories, is accelerating olive oil brand discovery among health-conscious consumers. Noon, Nana, and Carrefour Online provide premium olive oil brands with health benefit keyword search visibility and subscription purchasing that drives repeat consumption at cadences unavailable through offline impulse purchasing.
3. Al-Jouf Region Domestic Olive Production Development Creating Saudi Origin Brand Opportunity
Saudi Arabia's Al-Jouf region, home to the world's largest contiguous olive plantation developed by Almarai and other agricultural investors, is progressively increasing domestic olive oil production volumes. Saudi-origin olive oil brands, positioned on national pride, traceability, and freshness advantages over imported products, are emerging as a premium growth segment within the broader Saudi olive oil market.
4. Foodservice and HoReCa Channel Growth Driving Bulk and Foodservice-Grade Olive Oil Demand
Saudi Arabia's foodservice sector expansion under Vision 2030, including new hotel developments, restaurant licensing, and the entertainment sector growth, is creating growing institutional demand for foodservice-grade olive oil across fine dining, Mediterranean-cuisine restaurants, and premium hotel kitchens. This B2B demand channel provides volume stability and pricing differentiation from retail consumer channels.
Industry Value Chain Analysis
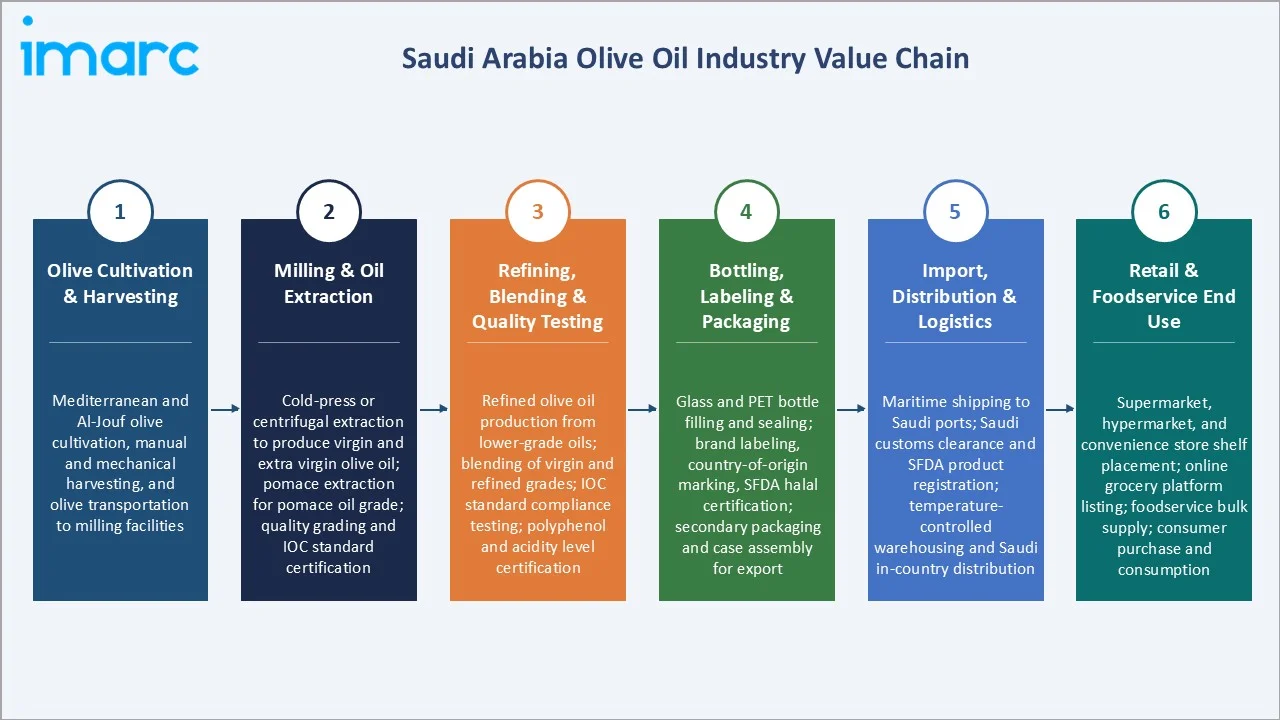
The Saudi Arabia olive oil value chain integrates Mediterranean olive grove cultivation and harvesting, oil extraction milling, refining and blending, bottling and packaging, import logistics and customs, Saudi in-country distribution, retail shelf placement, and end-consumer purchase. The entire upstream production and processing chain is import-dependent, with in-country value addition primarily occurring at the distribution, retail, and foodservice integration stages.
|
Stage |
Key Participants |
|
Olive Cultivation & Harvesting |
Mediterranean and Al-Jouf olive cultivation, manual and mechanical harvesting, and olive transportation to milling facilities |
|
Milling & Oil Extraction |
Cold-press or centrifugal extraction to produce virgin and extra virgin olive oil; pomace extraction for pomace oil grade; quality grading and IOC standard certification |
|
Refining, Blending & Quality Testing |
Refined olive oil production from lower-grade oils; blending of virgin and refined grades; IOC standard compliance testing; polyphenol and acidity level certification |
|
Bottling, Labeling & Packaging |
Glass and PET bottle filling and sealing; brand labeling, country-of-origin marking, SFDA halal certification; secondary packaging and case assembly for export |
|
Import, Distribution & Logistics |
Maritime shipping to Saudi ports; Saudi customs clearance and SFDA product registration; temperature-controlled warehousing and Saudi in-country distribution |
|
Retail & Foodservice End Use |
Supermarket, hypermarket, and convenience store shelf placement; online grocery platform listing; foodservice bulk supply; consumer purchase and consumption |
The import and distribution stage represents the most commercially active in-country value chain tier, where Saudi olive oil importers negotiate annual supply contracts with Mediterranean producers, manage SFDA product registration, and develop retailer relationships that determine shelf space allocation and promotional positioning for international brands across the Saudi market.
Technology Landscape in the Saudi Arabia Olive Oil Market
Cold-Press Extraction Technology and Polyphenol Preservation
Cold-press extraction technology, conducted at temperatures below 27°C, preserves olive oil's natural polyphenol content, flavor compounds, and nutritional properties that define EVOO quality. Saudi consumer awareness of cold-press designation as a quality indicator is growing, driving premiumization toward certified cold-press EVOO brands. Producers investing in continuous two-phase decantation systems achieve superior polyphenol retention that supports premium price positioning in Saudi health-conscious retail channels.
Authentication and Anti-Adulteration Technology Protecting Category Integrity
Nuclear magnetic resonance (NMR) spectroscopy, DNA-based origin traceability, and near-infrared spectroscopy are increasingly deployed by quality-focused olive oil producers and Saudi SFDA import testing laboratories to authenticate olive oil grade and geographical origin claims. These technologies are critical for protecting premium EVOO category integrity, as adulteration detection capabilities directly influence consumer trust and regulatory compliance requirements for brands operating in the Saudi market.
Digital Supply Chain and QR-Code Traceability Enabling Consumer Transparency
Leading European olive oil producers deployed QR-code-enabled supply chain traceability systems allowing Saudi consumers to verify harvest date, grove origin, mill certification, and polyphenol content via smartphone scan. These digital transparency tools address Saudi consumer adulteration concerns and enable premium brand differentiation that supports higher price points in competitive hypermarket environments.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Type |
Extra Virgin Olive Oil |
41.6% |
2025 |
|
Distribution Channel |
Supermarkets and Hypermarkets |
52.7% |
2025 |
|
Application |
🔒 |
🔒 |
2025 |
|
Region |
Northern and Central Region |
38.6% |
2025 |

By Type
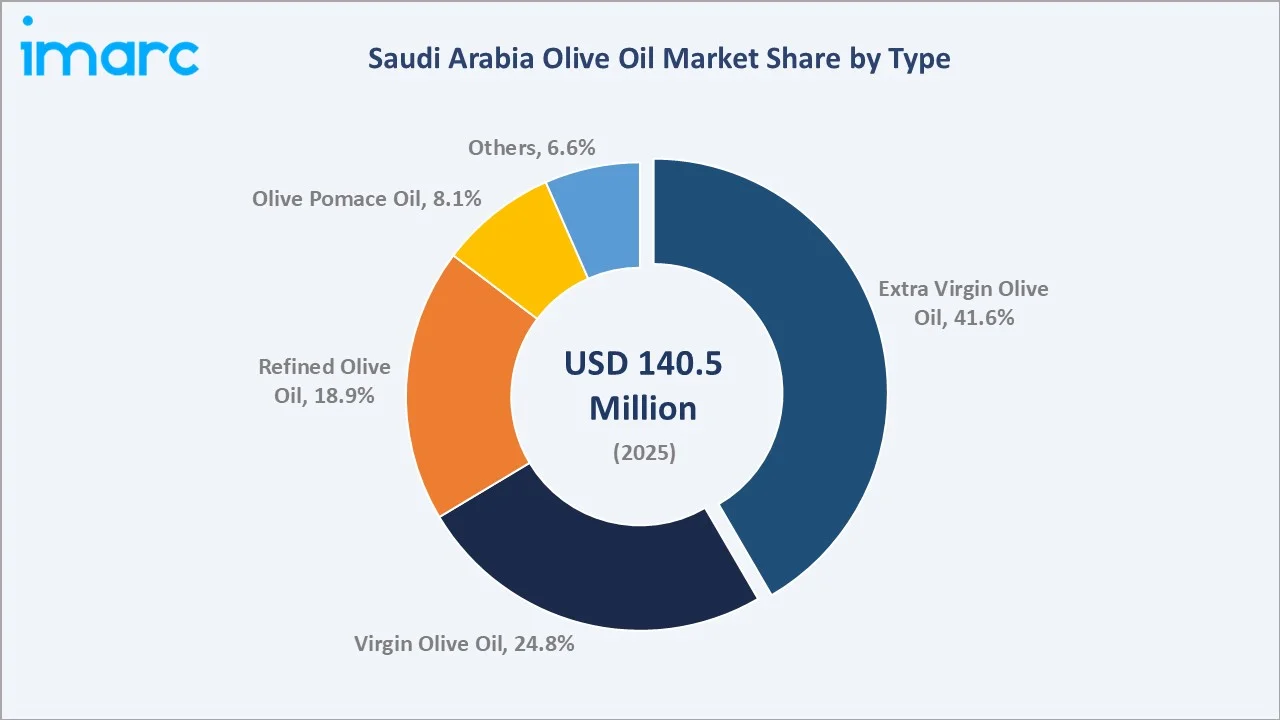
Extra Virgin Olive Oil leads at 41.6% in 2025, driven by health consciousness, premium positioning, and growing consumer awareness of polyphenol health benefits. EVOO's certification requirements, distinctive flavor, and health claim eligibility create strong brand differentiation drivers that sustain its market leadership throughout the forecast period.
To access detailed market analysis, Request Sample
Virgin Olive Oil at 24.8% captures the mid-premium segment. Refined Olive Oil at 18.9% serves price-sensitive and cooking-volume applications. Olive Pomace Oil at 8.1% addresses commercial foodservice and institutional buyers seeking the lowest-cost olive oil grade. Others at 6.6% capture specialty blends and organic variants.
By Distribution Channel
Supermarkets and Hypermarkets lead at 52.7% in 2025, providing the broadest brand selection, promotional pricing, and category visibility that drives both planned and impulse olive oil purchasing. Saudi Arabia's expanding modern retail network under Vision 2030 reinforces this channel's dominant position throughout the forecast period.
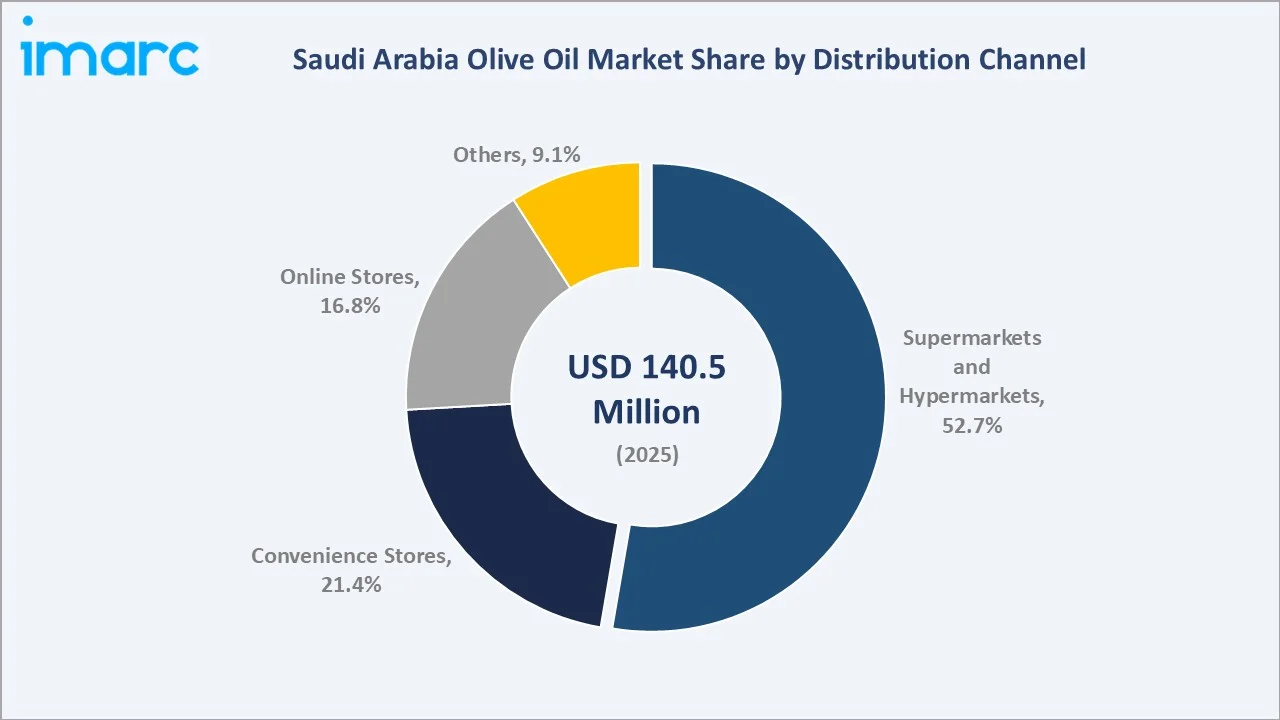
Convenience Stores at 21.4% capture neighborhood and impulse purchasing, particularly for smaller bottle formats. Online Stores at 16.8% represent the fastest-growing channel, driven by premium EVOO subscription purchasing and health-conscious consumers seeking brand research capabilities unavailable in offline retail. Others at 9.1% include foodservice, specialty retailers, and direct import channels.
Regional Market Insights
|
Region |
Share (2025) |
Key Olive Oil Market Drivers & Characteristics |
|
Northern and Central Region |
38.6% |
Riyadh's affluent urban base, highest expat concentration, and densest modern retail network generate the highest per-capita olive oil purchasing volumes nationally |
|
Western Region |
29.4% |
Jeddah and Makkah's cosmopolitan population, Mediterranean-heritage expats, tourism infrastructure, and premium retail growth drive strong olive oil demand |
|
Eastern Region |
20.3% |
Aramco employee communities, high-income professional population, and Dammam's growing modern retail sector sustain above-average olive oil consumption per household |
|
Southern Region |
11.7% |
Emerging market with growing modern retail, Vision 2030 regional investment, and rising health awareness driving olive oil category development from a smaller base |
The Northern and Central Region, at 38.6%, leads through Riyadh's concentration of affluent Saudi households, Mediterranean-heritage expatriate communities, and premium hypermarket formats stocking broad olive oil assortments. The Western Region, at 29.4%, reflects Jeddah's cosmopolitan character and Makkah's international visitor population generating diverse olive oil demand.
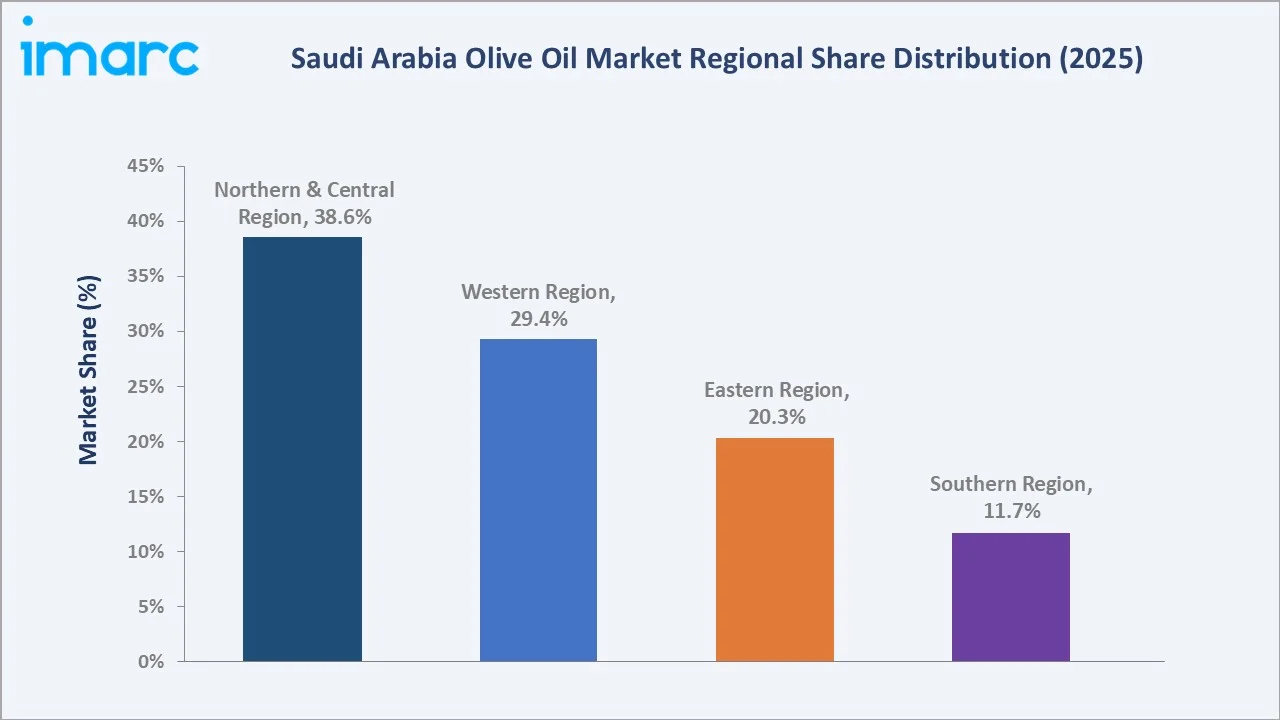
The Eastern Region, at 20.3%, is sustained by Saudi Aramco's multinational employee community and the Eastern Province's high-income professional population, which exhibits above-average premium cooking oil purchasing. The Southern Region, at 11.7%, represents a growing but early-stage market primarily driven by Vision 2030 regional development and rising health consciousness among younger Saudi consumers.
Competitive Landscape
The Saudi Arabia olive oil market competitive landscape is moderately concentrated with global Mediterranean olive oil brands, regional specialty importers, and emerging domestic Saudi producers competing for market share.
|
Company Name |
Key Products |
Market Position |
Core Strength |
|
Deoleo |
Bertolli, Carapelli, Carbonell |
Market Leader |
Deoleo is a Spain-based multinational and the world's largest olive oil company, with Bertolli and Carbonell among the best-recognized olive oil brands in Saudi Arabia's supermarket and hypermarket retail channels. |
|
Sovena |
Olivari, Andorinha, Fontoliva |
Market Leader |
Sovena is a Portugal-based global olive oil producer and one of the largest olive oil bottlers globally, supplying Saudi Arabia through its established Mediterranean-origin EVOO and refined olive oil brand portfolio. |
|
Borges International Group, S.L.U. |
Borges Olive Oil range |
Strong Challenger |
Borges International Group is a Spain-based food company and one of the largest olive oil exporters, with an established Saudi Arabia presence across supermarket and specialty retail channels. |
|
Pompeian |
Pompeian Olive Oil range |
Emerging Player |
Pompeian is a US-based olive oil company with a certified quality EVOO portfolio, expanding its Saudi Arabia presence through modern retail channels and health-positioned marketing to urban Saudi consumers. |
Key players include Deoleo, Sovena, Borges International Group, S.L.U., Pompeian, and others.
Key Company Profiles
Deoleo
Deoleo is a Spain-based multinational food group and the world's largest olive oil company, marketing iconic brands including Bertolli, Carapelli, and Carbonell. The company holds market-leading positions in olive oil across more than 100 countries, with Bertolli and Carbonell being among the most recognized olive oil brands in Saudi Arabia's modern retail channels.
- Key Products: Bertolli (Extra Virgin, Classic, and Originale ranges), Carbonell (EVOO, Virgin, and Refined grades), Carapelli (premium Italian EVOO range).
- Strategic Focus: Strengthening premium EVOO brand positioning across Saudi Arabia's expanding hypermarket retail network through health benefit communication, origin certification, and digital traceability. Deoleo is targeting the growing Saudi health-conscious consumer segment through EVOO-specific marketing campaigns that emphasize Bertolli and Carbonell's Mediterranean origin, quality certification, and cardiovascular health positioning. The company is also investing in sustainable olive oil supply chain development to support its long-term premium brand credentials in environmentally conscious retail environments.
Sovena
Sovena is a Portugal-based global food group and one of the world's largest olive oil producers and bottlers, with integrated operations spanning olive grove cultivation, oil extraction, refining, bottling, and global distribution. The company supplies the Saudi Arabian market through its established Olivari and Andorinha brand portfolio across supermarket and hypermarket channels.
- Key Products: Olivari (EVOO and refined olive oil), Andorinha (Portuguese EVOO and virgin olive oil), Fontoliva (blended and refined olive oil).
- Strategic Focus: Expanding Saudi Arabia retail distribution through integrated producer-to-retailer supply chain advantages that enable competitive pricing without compromising EVOO quality credentials. Sovena is targeting premium EVOO segment growth in Saudi Arabia by leveraging its integrated production model, which provides supply security and price stability advantages versus pure-importer competitors dependent on third-party olive oil procurement. The company is also developing private label olive oil supply relationships with Saudi hypermarket chains as a volume market entry complementing its branded product retail strategy.
Market Concentration Analysis
The Saudi Arabia olive oil market is moderately concentrated, with European multinational brands collectively accounting for approximately 50-60% of retail olive oil revenue. Market concentration is moderately high at the premium EVOO tier, where established European brands with origin certification and health positioning dominate retail shelf space and consumer brand recognition.
Market concentration is expected to moderate through the forecast period as Saudi domestic olive oil production from the Al-Jouf region scales, regional specialty importers expand their brand portfolios, and online grocery platforms lower the channel entry barrier for smaller international premium EVOO brands seeking Saudi market access without traditional retail distribution relationships.
Investment & Growth Opportunities
Highest Growth Segments
Online olive oil channel (~5.5% CAGR), premium certified EVOO (~4.8% CAGR), organic olive oil (~6%+ CAGR from small base), Saudi-origin domestic olive oil (~8%+ CAGR from small base), and foodservice-grade bulk olive oil (~4.2% CAGR) represent the highest-growth investment vectors through 2034.
Emerging Investment Opportunities
Al-Jouf domestic olive oil production scale-up represents the most structurally differentiated opportunity, combining Vision 2030 agricultural investment incentives, Saudi-origin premium positioning, and supply chain independence from Mediterranean climate volatility. Saudi-origin EVOO brands command premium narrative positioning unavailable to imported brands on freshness, national pride, and traceability dimensions.
Investment Themes
- Premium EVOO health positioning as margin enhancement strategy: Certified origin, organic, and polyphenol-rich EVOO grades command 30-60% retail price premiums that sustain brand margins even as commodity olive oil pricing faces competitive pressure from expanding retailer private label programs.
- E-commerce channel investment enabling direct consumer health education: Online grocery platforms in Saudi Arabia provide premium olive oil brands with health benefit communication, subscription purchasing, and consumer data collection capabilities that are structurally unavailable through offline retail channels, creating durable competitive advantages for brands investing in digital channel development.
Future Market Outlook (2026-2034)
The Saudi Arabia olive oil market is projected to grow from USD 140.5 Million in 2025 to USD 190.4 Million by 2034, delivering a 3.43% CAGR over the forecast period. The market's anchor value of USD 166.4 Million in 2030 represents the Saudi olive oil industry at its commercial modernization phase, with Vision 2030 retail expansion completing its primary buildout and online grocery channels achieving mainstream consumer penetration.
Three structural forces define Saudi Arabia olive oil market growth through 2034. The demographic and lifestyle shift among Saudi Arabia's young urban population toward health-conscious premium food consumption creates a growing domestic consumer base for EVOO adoption independent of the expatriate consumption that currently anchors market volumes. Vision 2030's retail modernization creates new distribution touchpoints and promotional platforms that increase olive oil category visibility among mainstream Saudi consumers. The progressive development of domestic Saudi olive oil production in Al-Jouf creates a new high-interest Saudi-origin premium brand tier that may accelerate broader category interest and consumption rates.
Research Methodology
Primary Research
Primary research comprised structured interviews with 40+ industry stakeholders (2025), including olive oil importers and distributors; Saudi retail category managers; SFDA food import compliance specialists; foodservice procurement directors; and Saudi consumer health and nutrition professionals.
Secondary Research
Secondary research encompassed SFDA food import statistics; Saudi General Authority for Statistics household expenditure surveys; International Olive Council (IOC) world olive oil production and trade data; Saudi Ministry of Commerce retail sector reports; company annual reports and investor presentations; and over 50 secondary sources reviewed.
Forecasting Models
Market revenue forecasts developed using a bottom-up channel-based demand model: (i) population and household olive oil consumption rate by consumer segment; (ii) distribution channel share trajectory; (iii) average retail price by olive oil grade and channel; (iv) expatriate community consumption volume by region; (v) foodservice sector growth rate contribution to total olive oil volumes.
Saudi Arabia Olive Oil Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Virgin Olive Oil, Refined Olive Oil, Extra Virgin Olive Oil, Olive Pomace Oil, Others |
| Distribution Channels Covered | Supermarkets and Hypermarkets, Convenience Stores, Online Stores, Others |
| Applications Covered | Food and Beverage, Pharmaceuticals, Cosmetics, Others |
| Regions Covered | Northern and Central Region, Western Region, Eastern Region, Southern Region |
| Companies Covered | Deoleo, Sovena, Borges International Group, S.L.U., Pompeian, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Saudi Arabia olive oil market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Saudi Arabia olive oil market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Saudi Arabia olive oil industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Saudi Arabia Olive Oil Market Report
The Saudi Arabia olive oil market reached USD 140.5 Million in 2025, driven by Extra Virgin Olive Oil leading at 41.6%, Supermarkets and Hypermarkets dominating distribution at 52.7%, and the Northern and Central Region commanding 38.6% through Riyadh's affluent consumer base, high expatriate concentration, and dense modern retail network.
The market grows at 3.43% CAGR during 2026-2034, reaching USD 190.4 Million by 2034. Growth reflects rising health consciousness, Mediterranean diet adoption, Vision 2030 retail expansion, growing expatriate population, and rapidly expanding online grocery channel penetration driving premium EVOO adoption.
Extra Virgin Olive Oil leads at 41.6% in 2025, driven by rising health consciousness, cardiovascular benefit awareness, and premium positioning in expanding Saudi hypermarket health food sections. EVOO grows fastest at approximately 4.1% CAGR through 2034 driven by premiumization and certified origin adoption.
Supermarkets and Hypermarkets lead at 52.7% in 2025, providing the broadest brand selection, promotional pricing, and category visibility that drives planned and impulse olive oil purchasing. Online Stores at 16.8% are the fastest-growing channel as health-conscious Saudi consumers seek premium EVOO brand research before purchasing.
The Northern and Central Region leads at 38.6% through Riyadh's affluent urban consumer base, the highest concentration of Mediterranean-heritage expatriates, and the densest modern supermarket and hypermarket network generating the highest per-capita olive oil purchasing volumes in the Kingdom.
Leading companies include Deoleo, Sovena, Borges International Group, S.L.U., Pompeian, and others.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade