Saudi Arabia Plumbing Fixtures Market Size, Share, Trends, and Forecast by Product, Location, Application, Distribution Channel, End User, and Region, 2026-2034
Saudi Arabia Plumbing Fixtures Market Size, Share, Trends & Forecast (2026-2034)
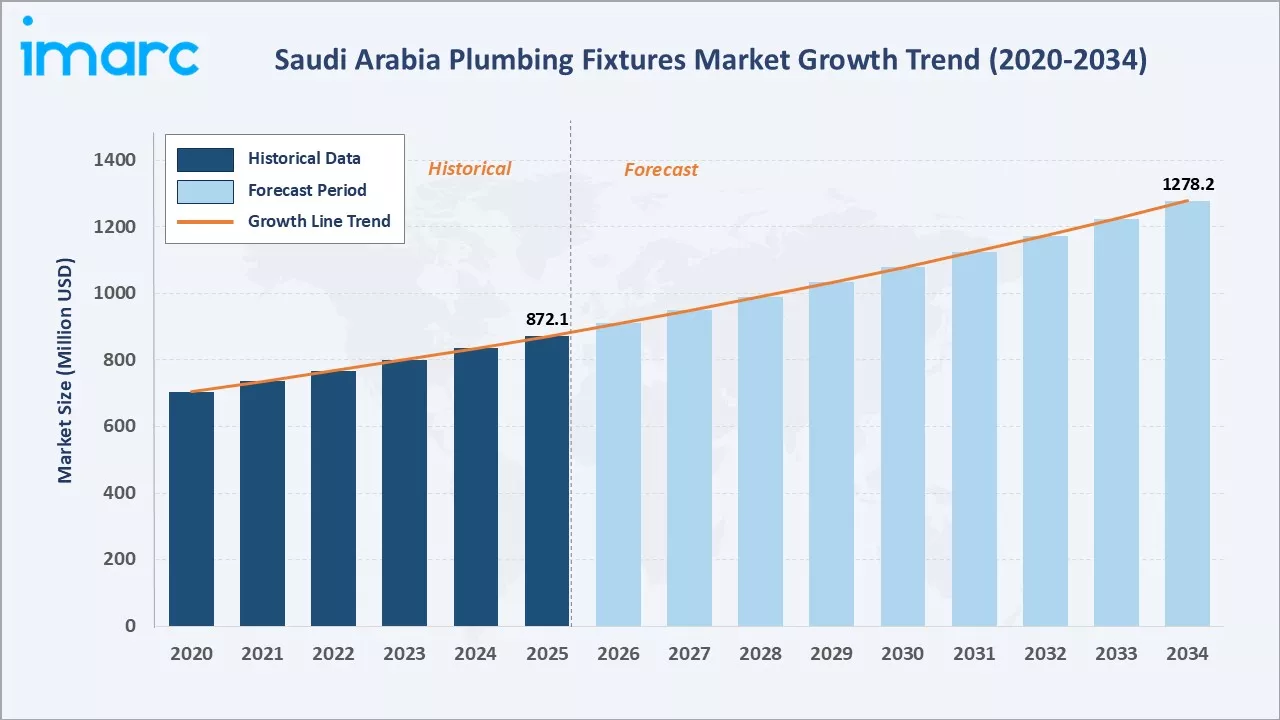
The Saudi Arabia plumbing fixtures market grew from USD 872.1 Million in 2025 to USD 909.9 Million in 2026 and is projected to reach USD 1,278.2 Million by 2034, exhibiting a CAGR of 4.34% during 2026-2034. Rising construction activity driven by Vision 2030 megaprojects, rapid urbanization, and expansion of Saudi Arabia's hospitality and tourism sectors are the primary forces shaping market growth.
Toilets lead the product segment at 25.0%, residential dominates the end user segment at 65.0%, and Northern and Central Region commands 48.2% of regional share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 872.1 Million |
|
Market Size (2026) |
USD 909.9 Million |
|
Forecast Market Size (2034) |
USD 1,278.2 Million |
|
CAGR (2026-2034) |
4.34% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
| Largest Region |
Northern and Central Region (48.2%, 2025) |
| Second Largest Region |
Western Region (23.5%, 2025) |
|
Leading Product |
Toilets (25.0%, 2025) |
| Leading End User | Residential (65.0%, |
The Saudi Arabia plumbing fixtures market size increased from USD 705.2 Million in 2020 to USD 872.1 Million in 2025 and is estimated to reach USD 909.9 Million in 2026. The market is further expected to grow to USD 1078.4 Million by 2030 and USD 1,278.2 Million by 2034. The market is commercially underpinned by one of the region's most dynamic construction pipelines, a rapidly growing population base, and sustained government investment in residential, commercial, and hospitality infrastructure across the Kingdom.
To get more information on this market, Request Sample
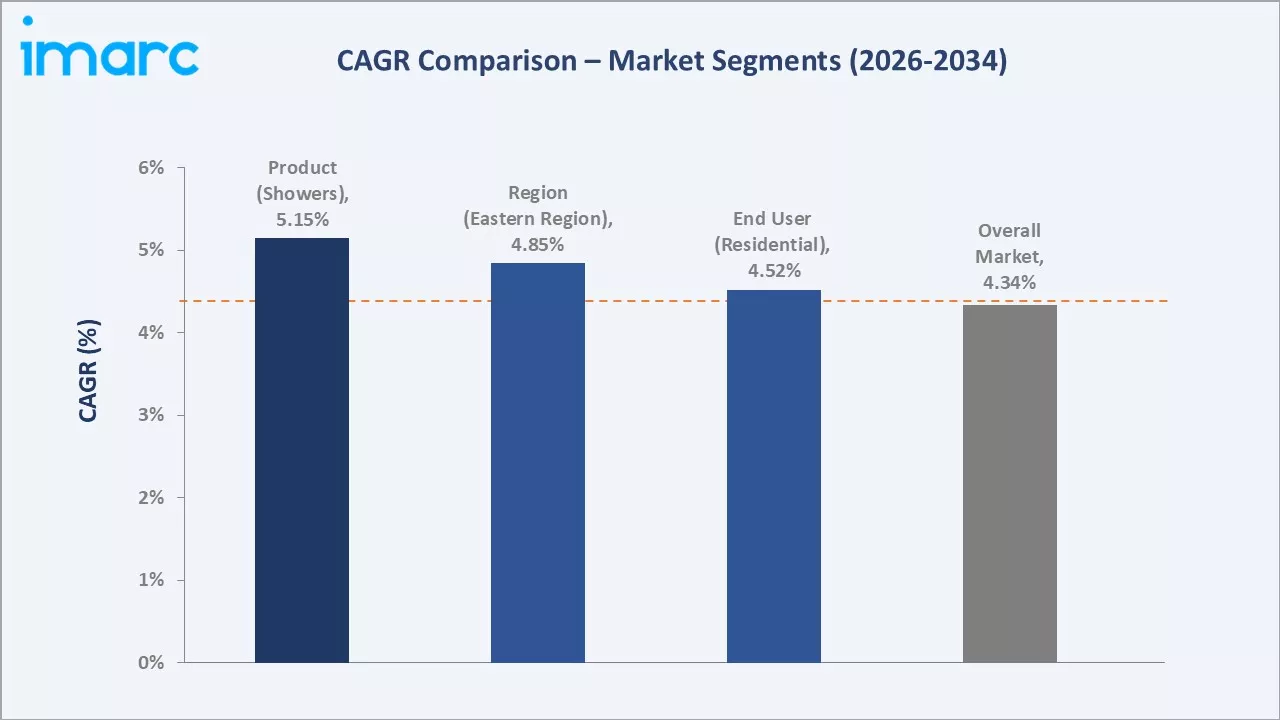
CAGR trajectories across product, end user, and regional sub-segments show showers and Eastern Region expanding faster than the overall 4.34% market CAGR, driven by premiumization trends and rising infrastructure investment.
Executive Summary
The Saudi Arabia plumbing fixtures market expanded from USD 872.1 Million in 2025 to an estimated USD 909.9 Million in 2026, positioning it among the region's fastest-growing building materials segments. The market is supported by Vision 2030's construction pipeline, rising domestic demand, and sustained investment in hospitality and commercial infrastructure.
Toilets command 25.0% product share, reflecting their essential role across all construction categories and consistent replacement demand in Saudi Arabia's maturing residential base. Residential accounts for 65.0% of end user demand, underscoring the primacy of housing construction in driving plumbing fixture sales. Northern and Central Region leads with 48.2% of market share in 2025, anchored by Riyadh's large-scale urban development projects, government housing programs, and concentration of commercial real estate activity.
Key Market Insights
|
Insight |
Data |
| Leading Product |
Toilets – 25.0% share (2025) |
| Second Largest Product | Faucets and Taps – 20.0% share (2025) |
| Leading End User | Residential – 65.0% share (2025) |
| Second Largest End User | Commercial – 35.0% share (2025) |
| Leading Region |
Northern and Central Region – 48.2% share (2025) |
| Second Largest Region |
Western Region – 23.5% share (2025) |
| Top Companies | LIXIL Corporation, Kohler Co., TOTO Ltd. |
Key Analytical Observations Expanding On the Data Above:
- Toilets dominance at 25.0% reflects the essential and non-discretionary nature of sanitary ware, driving consistent demand across residential, commercial, and hospitality construction projects in Saudi Arabia.
- Faucets and taps at 20.0% are growing as end users upgrade to premium water-efficient and sensor-based fixtures, supported by Saudi Arabia's water conservation regulations and rising consumer preference for design-led plumbing products.
- Residential leadership at 65.0% is driven by Saudi Arabia's large-scale government housing programs, rapidly growing population, and significant residential construction activity under Vision 2030 urban development initiatives.
- Commercial at 35.0% is supported by rapid expansion of hospitality, healthcare, education, and office construction projects across the Kingdom, particularly in Riyadh, Jeddah, and NEOM.
- Northern and Central Region at 48.2% leads due to Riyadh's primacy as Saudi Arabia's economic capital and the concentration of Vision 2030 megaprojects, government housing, and commercial real estate in and around the capital.
Saudi Arabia Plumbing Fixtures Market Overview
Plumbing fixtures refer to exchangeable devices that connect to a plumbing system for delivery and drainage of water, encompassing bathtubs, sinks, toilets, showers, faucets and taps, and drainage systems. In Saudi Arabia, these products serve residential, commercial, hospitality, healthcare, and industrial end users, underpinning the country's construction and infrastructure development programs.
The Saudi Arabian ecosystem integrates raw material suppliers, component manufacturers, plumbing fixture producers, distributors and wholesalers, fit-out contractors, and end users across residential and non-residential segments. Government bodies, along with international certification bodies, technology providers, and logistics operators, form the supporting layer enabling a compliant, increasingly specification-driven plumbing fixture market across the Kingdom.
Market Dynamics
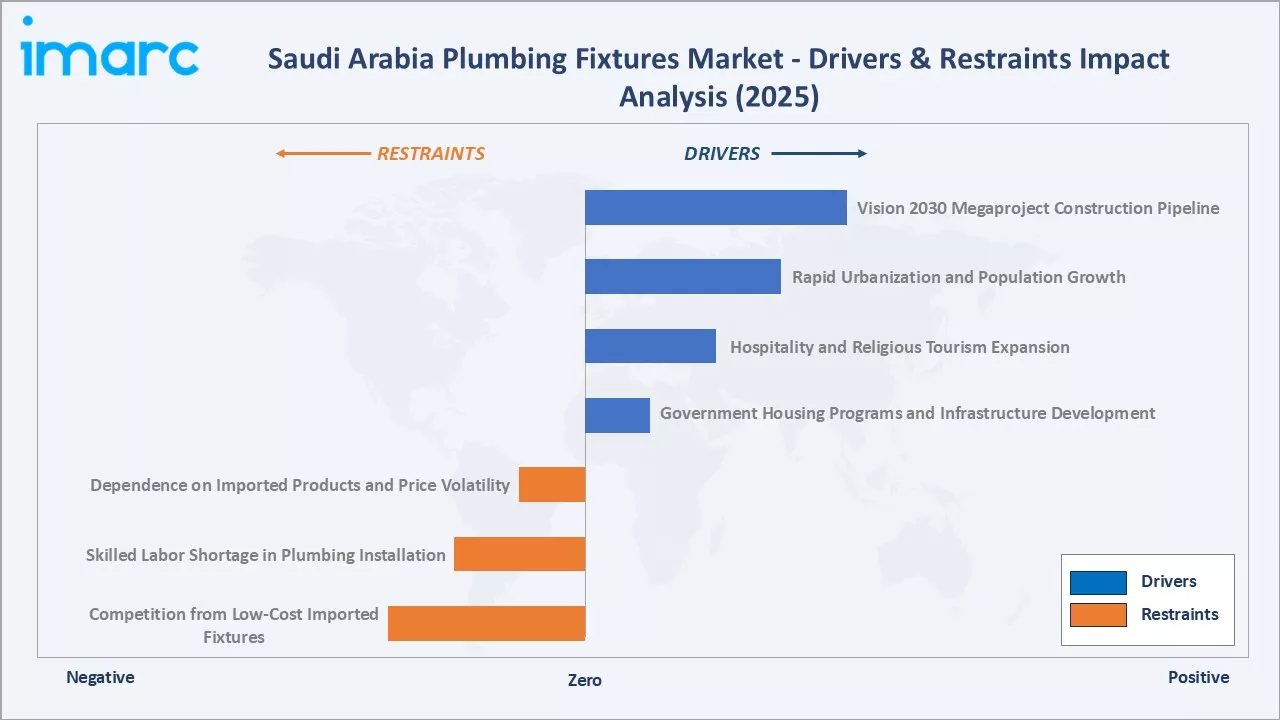
To evaluate market opportunities, Request Sample
Market Drivers
- Vision 2030 Megaproject Construction Pipeline: Saudi Arabia's Vision 2030 program encompasses an extensive portfolio of giga-projects, including NEOM, the Red Sea Project, Qiddiya, and ROSHN residential communities. These projects generate substantial demand for plumbing fixtures across residential, hospitality, and commercial categories.
- Rapid Urbanization and Population Growth: In 2025, Saudi Arabia's urban population represented approximately 84% of its total population, one of the highest urbanization rates in the Middle East. Combined with a relatively young population base and growing household formation, this supports sustained residential construction activity and ongoing demand for plumbing fixture replacement and upgrade across the Kingdom.
- Hospitality and Religious Tourism Expansion: Tourism in Saudi Arabia reached 123 Million visitors in 2025, comprising 29.3 Million international visitors and 93.3 Million local travelers. Saudi Arabia's Vision 2030 tourism target is driving unprecedented hotel and hospitality infrastructure development, particularly in Makkah, Madinah, and the Red Sea coastline. High-specification plumbing fixtures are a standard requirement for hotel and resort construction, supporting premium segment growth in the market.
- Government Housing Programs and Infrastructure Development: Saudi Arabia's government-led housing initiatives aim to increase homeownership and expand residential housing supply across the Kingdom. Investments in residential infrastructure and new housing developments generate demand for plumbing fixtures, including faucets, sanitary ware, showers, and bathroom fittings.
Market Restraints
- Dependence on Imported Products and Price Volatility: Saudi Arabia imports a significant proportion of its plumbing fixtures from international manufacturers, exposing the market to currency fluctuation risks, supply chain disruptions, and import cost escalation. Dependence on imported components and finished goods creates margin pressure for local distributors.
- Skilled Labor Shortage in Plumbing Installation: Availability of adequately trained plumbing installation professionals remains a structural challenge across Saudi Arabia, particularly outside major urban centers. Shortages of skilled labor can delay project timelines and affect fixture installation quality, creating friction across the value chain.
- Competition from Low-Cost Imported Fixtures: Influx of low-cost plumbing fixtures from Asian manufacturers exerts downward pricing pressure on mid-range segments, challenging established international brands and domestic distributors who compete on value rather than premium specification.
Market Opportunities
- Smart and Water-Efficient Fixture Adoption: Rising consumer awareness of water scarcity is creating demand for low-flow, sensor-based, and smart-connected plumbing fixtures. Manufacturers offering IoT-enabled and water-conserving products are well-positioned to capture a growing premium segment, particularly in commercial and hospitality applications.
- Localization and Manufacturing Under Vision 2030: Saudi Arabia's industrial strategy under Vision 2030 encourages localization of manufacturing, including building materials and fixtures. Establishing local production or assembly facilities can reduce import dependence, improve lead times, and qualify manufacturers for government procurement programs.
Market Challenges
- Project Delivery Timelines and Demand Volatility: Large-scale construction projects in Saudi Arabia are subject to phasing changes, budget revisions, and regulatory timeline adjustments, creating demand variability that challenges supply chain planning for plumbing fixture distributors and manufacturers supplying project-based segments.
- Specification Complexity and Regulatory Compliance: Increasing adoption of the Saudi Building Code and international green building standards across commercial and hospitality segments is raising specification requirements for plumbing fixtures, requiring distributors and contractors to invest in product knowledge, certification compliance, and after-sales service capabilities.
Emerging Market Trends
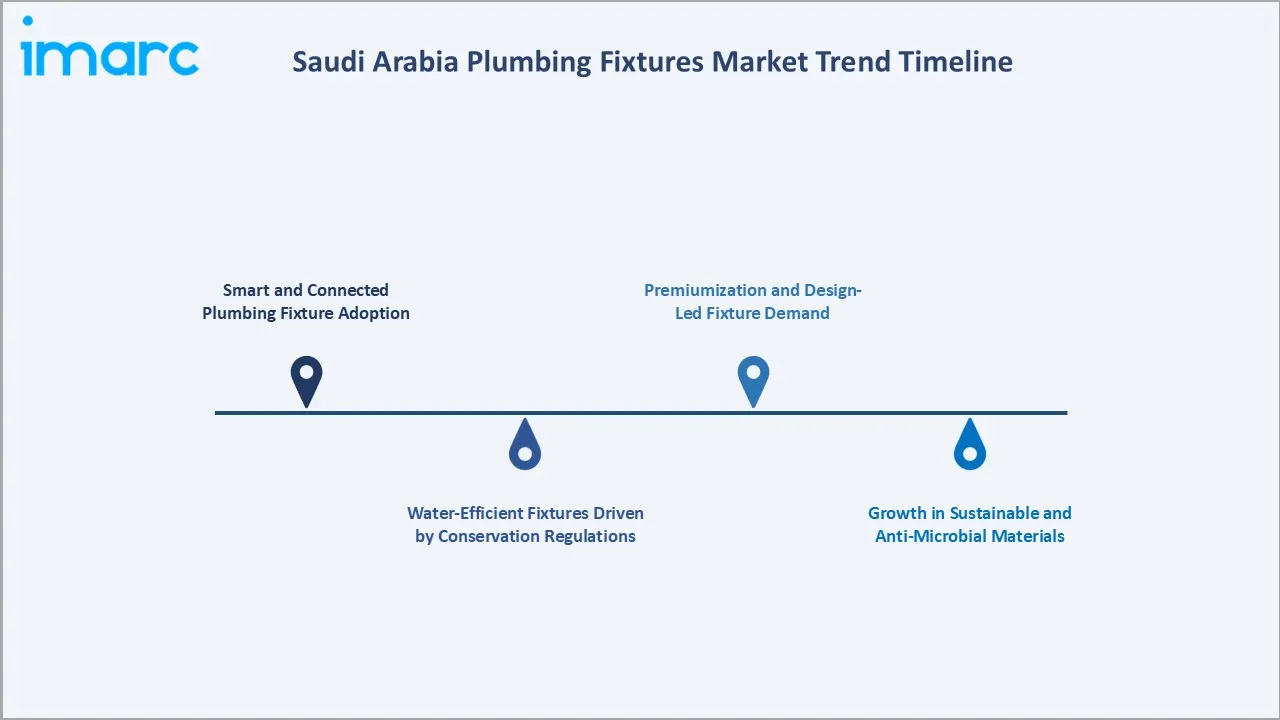
1. Smart and Connected Plumbing Fixture Adoption
Sensor-based faucets, touchless flush systems, and IoT-enabled plumbing monitoring platforms are gaining adoption across Saudi Arabia's commercial, hospitality, and premium residential segments. Integration of smart home and building management systems with plumbing fixtures is accelerating, particularly in giga-projects and high-specification hotel developments.
2. Water-Efficient Fixtures Driven by Conservation Regulations
Saudi Arabia's National Water Strategy and ongoing reform of water tariff structures are driving adoption of low-flow and water-saving plumbing fixtures across residential and commercial segments. Regulatory requirements tied to green building certification programs are embedding water-efficiency specifications into construction procurement standards. Fixture manufacturers offering certified low-flow products are benefiting from growing specification requirements across government and hospitality construction projects.
3. Premiumization and Design-Led Fixture Demand
Rising consumer income levels, the influence of international interior design trends, and growth of Saudi Arabia's premium residential and hospitality segments are driving demand for design-led, high-specification plumbing fixtures. Categories including statement bathtubs, rainfall showerheads, and designer faucet ranges are growing at above-market rates, particularly in villa and luxury apartment developments in Riyadh, Jeddah, and the Red Sea coast.
4. Growth in Sustainable and Anti-Microbial Materials
Demand for anti-microbial coatings, recycled content materials, and sustainably manufactured fixtures is growing across Saudi Arabia's healthcare, hospitality, and institutional construction segments. Manufacturers investing in product innovation for durability, hygiene compliance, and reduced environmental impact are gaining traction in a market increasingly influenced by health consciousness and sustainability mandates.
Industry Value Chain Analysis
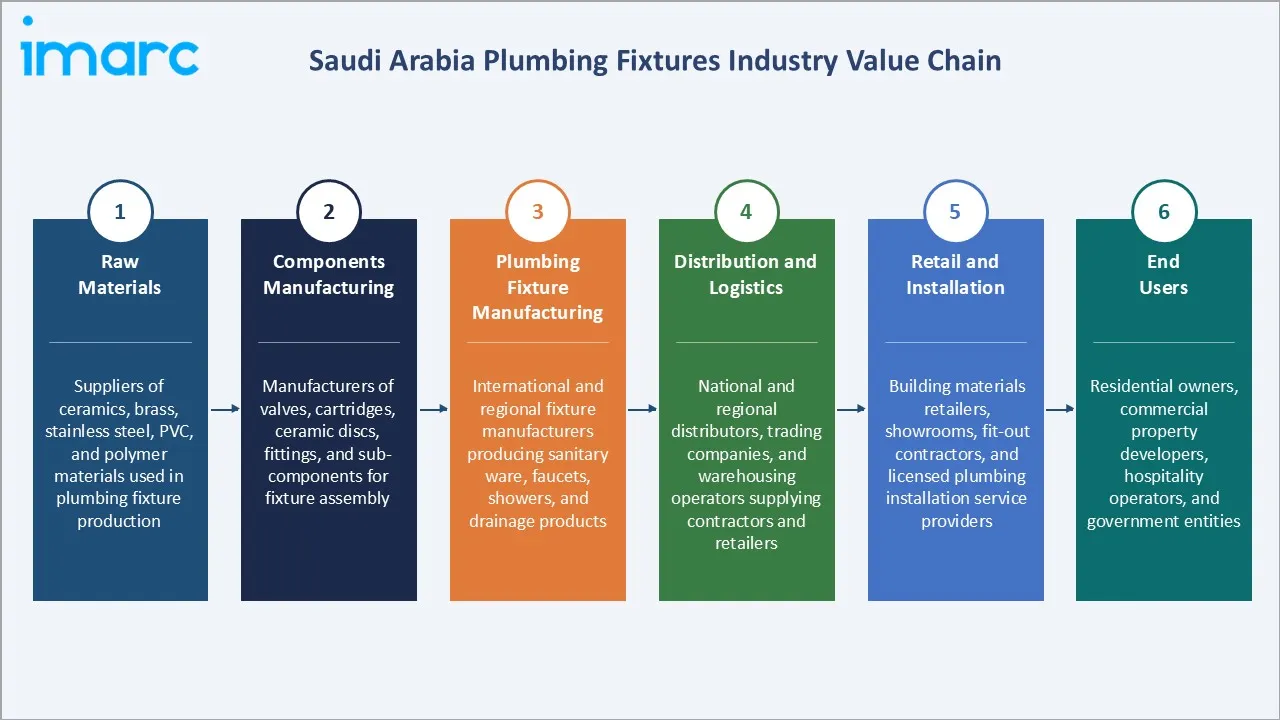
The Saudi Arabia plumbing fixtures value chain spans six stages, from raw material sourcing through end-user installation. Manufacturing, distribution, and specification stages capture the highest value-add, while compliance with Saudi Building Code requirements and green building certifications increasingly determines competitive position in a specification-driven market.
|
Stage |
Key Players / Examples |
| Raw Materials | Suppliers of ceramics, brass, stainless steel, PVC, and polymer materials used in plumbing fixture production |
| Components Manufacturing | Manufacturers of valves, cartridges, ceramic discs, fittings, and sub-components for fixture assembly |
| Plumbing Fixture Manufacturing | International and regional fixture manufacturers producing sanitary ware, faucets, showers, and drainage products |
| Distribution and Logistics | National and regional distributors, trading companies, and warehousing operators supplying contractors and retailers |
| Retail and Installation | Building materials retailers, showrooms, fit-out contractors, and licensed plumbing installation service providers |
| End Users | Residential owners, commercial property developers, hospitality operators, healthcare facilities, and government entities |
Vertically integrated manufacturers, particularly those controlling in-house production facilities, proprietary product designs, and established contractor and specifier relationships, are positioned to capture disproportionate margin and volume share compared with distributors dependent on imported third-party product lines.
Technology Landscape in the Saudi Arabia Plumbing Fixtures Industry
Smart Connectivity and IoT Integration
Smart-connected plumbing fixtures incorporating sensor-based controls, remote monitoring, and integration with building management systems are gaining adoption across commercial and hospitality segments in Saudi Arabia. Touchless faucets, smart shower systems with programmable water temperature and flow controls, and IoT-enabled leak detection systems are increasingly specified for new hotel, healthcare, and mixed-use developments across the Kingdom's giga-projects.
Water Efficiency and Conservation Technology
Low-flow faucets, dual-flush toilets, pressure-compensating showerheads, and greywater recycling-compatible drain systems are growing in adoption, driven by Saudi Arabia's water conservation regulations and green building certification requirements. Manufacturers are integrating aerator technology and advanced flow regulation systems to meet regulatory compliance and consumer preference for water-saving products.
Automation in Manufacturing
Leading international plumbing fixture manufacturers supplying the Saudi Arabia market are investing in automated ceramic casting, robotic glazing systems, and digitally controlled precision manufacturing to improve product consistency, reduce lead times, and support sustainable production practices. Automation investments also reduce per-unit production cost, supporting competitive positioning in price-sensitive mid-market segments.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
| Product | Toilets | 25.0% | 2025 |
| Location | 🔒 | 🔒 | 2025 |
|
Application |
🔒 | 🔒 | 2025 |
| Distribution Channel | 🔒 | 🔒 | 2025 |
| End User | Residential | 65.0% | 2025 |
|
Region |
Northern and Central Region |
48.2% |
2025 |

By Product
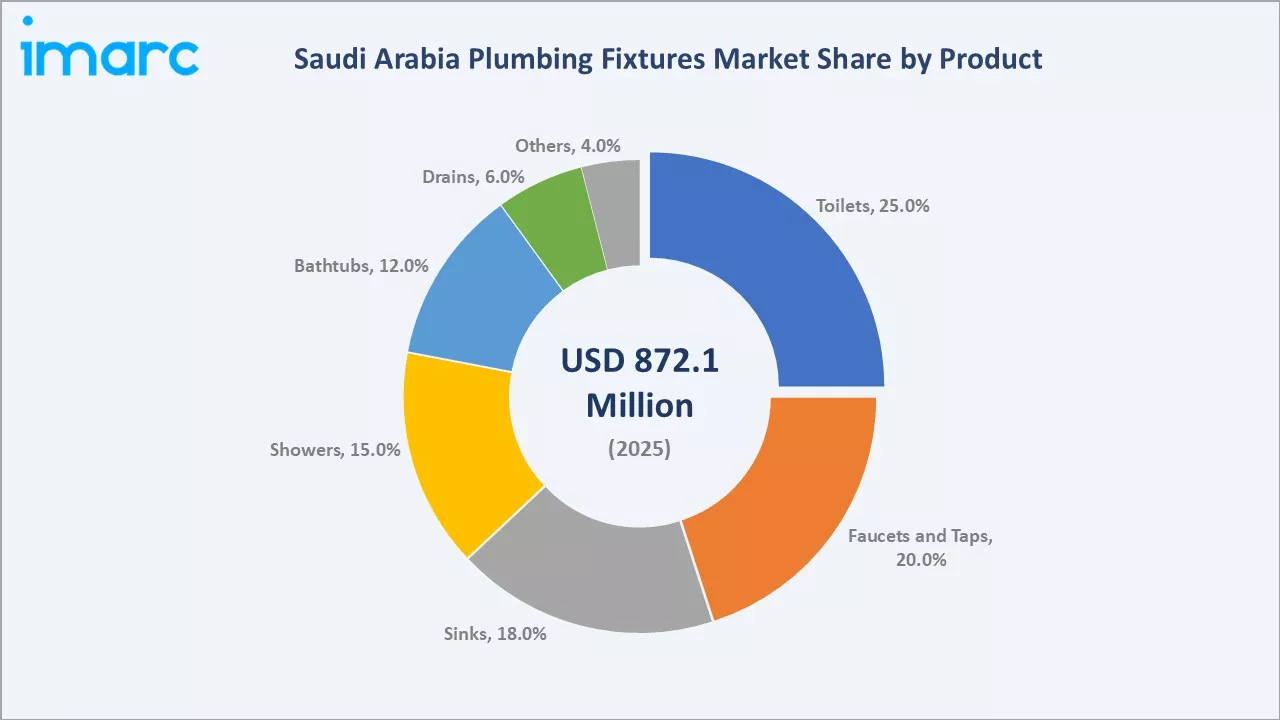
Toilets command a 25.0% majority share in 2025, driven by their universal presence across all construction categories and high volumes in Saudi Arabia's residential and commercial construction pipeline. The segment benefits from consistent replacement demand as the Kingdom's maturing building stock undergoes renovation and upgrading cycles across established residential areas.
To access detailed market analysis, Request Sample
Faucets and taps at 20.0% are the second-largest product segment, supported by the high per-unit volume of faucet installations across kitchens, bathrooms, and commercial spaces, and growing demand for premium and sensor-based products.
By End User
Residential represents 65.0% of the market in 2025, directly reflecting Saudi Arabia's large and growing housing construction sector. Government housing programs, private residential developments, and villa and apartment construction across major cities generate consistent demand for plumbing fixtures across all product categories.
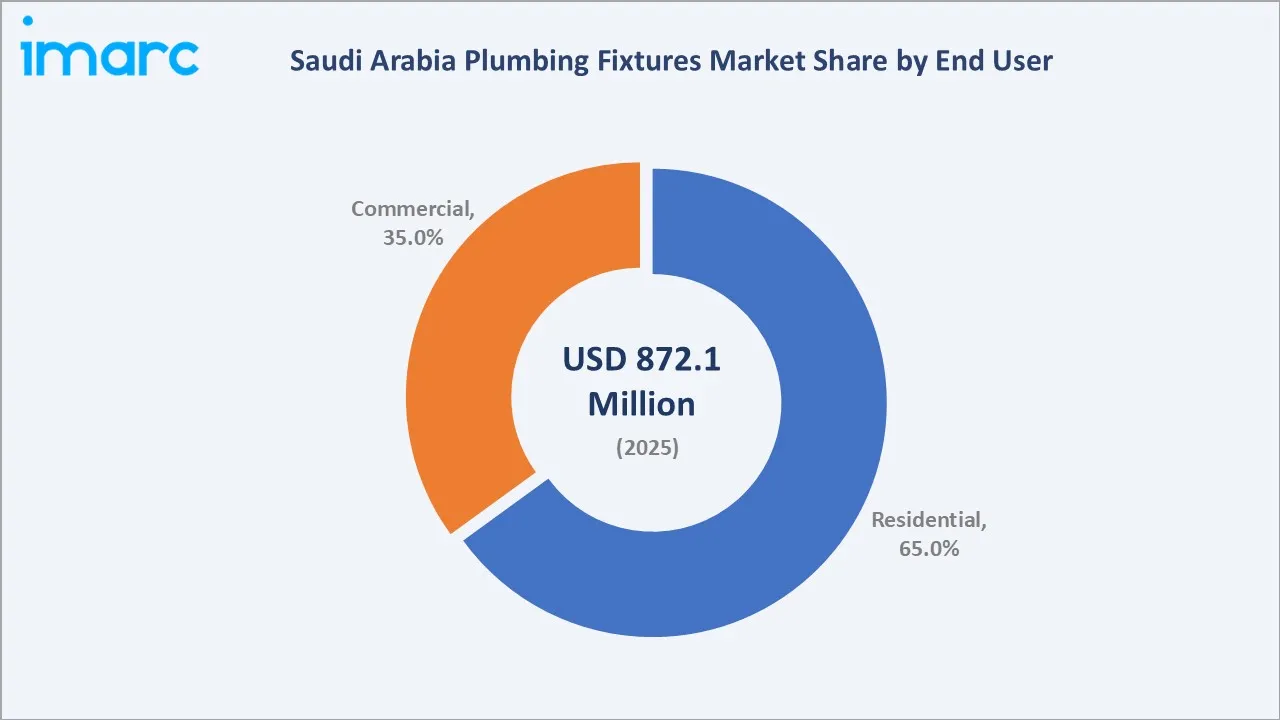
Commercial at 35.0% encompasses hospitality, healthcare, education, and office construction, all requiring higher-specification and more durable plumbing fixtures than standard residential applications.
Regional Market Insights
|
Region |
Share (2025) |
Key Growth Drivers |
|
Northern and Central Region |
48.2% |
Concentration of Vision 2030 megaprojects around Riyadh, government housing programs, large commercial and mixed-use real estate, and institutional construction activity |
|
Western Region |
23.5% |
Supporting widespread food import gateway operations, Jeddah food manufacturing cluster, and Makkah-Madinah pilgrim food supply chain processing infrastructure |
|
Eastern Region |
18.1% |
Dammam and Al Khobar residential growth and industrial and commercial construction tied to the energy sector |
|
Southern Region |
10.2% |
Growing residential construction in Abha and Jizan, government-supported infrastructure development, and rising domestic tourism driving hospitality construction |
Northern and Central Region at 48.2% in 2025 leads the regional landscape, anchored by Riyadh's primacy as Saudi Arabia's economic capital and the unprecedented concentration of giga-projects, government housing, and commercial construction in and around the capital.
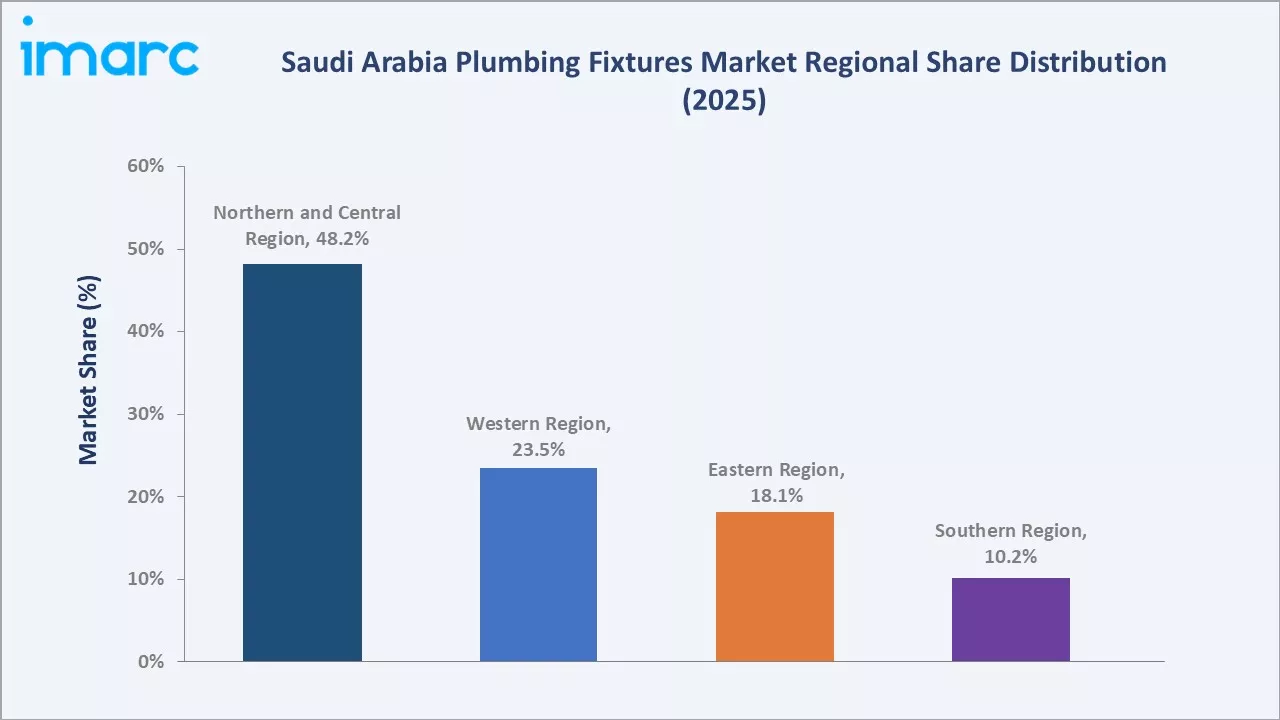
Western Region at 23.5% is supported by ongoing residential and commercial construction, hospitality infrastructure development in Makkah and Madinah, and investments in tourism-related projects along the Red Sea coastline.
Competitive Landscape
The Saudi Arabia plumbing fixtures market is moderately fragmented, with a mix of established global fixture manufacturers, regional distributors, and specialty brands competing on product range, specification quality, distribution reach, and after-sales service capability. Brand reputation, Saudi Building Code compliance, and proximity to key project specification processes form the primary competitive differentiators.
|
Company |
Brand / Key Product |
Market Position |
Core Strength |
| LIXIL Corporation | GROHE, American Standard | Leader | Expanding premium and commercial fixture portfolio through brand investment and project specification across Saudi Arabia's giga-projects |
| Kohler Co. | Kohler | Leader | Strengthening premium positioning through design-led product development and hospitality sector partnerships |
| TOTO Ltd. | TOTO | Challenger | Expanding luxury and smart toilet specification in premium residential and hospitality segments, targeting high-specification giga-project developments |
Key players include LIXIL Corporation, Kohler Co., and TOTO Ltd., among others.
Key Company Profiles
LIXIL Corporation
LIXIL Corporation is a Japanese multinational housing and building materials manufacturer headquartered in Tokyo, Japan. The company owns global fixture brands including GROHE, and American Standard, and maintains a substantial presence in the Saudi Arabian market through its broad portfolio of faucets, toilets, showers, and sanitary ware products.
- Product Portfolio: Premium and standard range faucets, toilets, sanitary ware, shower systems, and plumbing fittings under the GROHE and American Standard brands, serving residential, commercial, and hospitality segments.
- Recent Developments: The company continues to expand its product portfolio in water-efficient and smart-connected fixtures, advancing specification activity across Saudi Arabia's commercial and hospitality construction pipeline.
- Strategic Focus: Strengthening brand presence and distribution reach across Saudi Arabia through specification partnerships, project engagement, and investment in water-efficient and design-led product ranges.
Kohler Co.
Kohler Co. is a United States-based privately held manufacturing company headquartered in Kohler, Wisconsin, with a global presence in kitchen and bath products. The company operates in Saudi Arabia through authorized distributors and showrooms, targeting the premium residential and commercial hospitality segments.
- Product Portfolio: Premium toilets, baths, faucets, showers, sinks, and bathroom furniture under the Kohler brand, serving luxury residential, high-specification commercial, and hospitality segments in Saudi Arabia.
- Recent Developments: The company continues to introduce new design-led and water-efficient fixture ranges for the Saudi Arabia market, with growing activity in commercial project specification across giga-projects and luxury residential developments.
- Strategic Focus: Building premium brand positioning and commercial specification activity across Saudi Arabia's luxury residential, hospitality, and mixed-use development segments through design innovation and project partnerships.
TOTO Ltd.
TOTO Ltd. is a Japanese sanitary ware manufacturer headquartered in Kitakyushu, Japan, known globally for its advanced washlet technology and high-specification toilet and bathroom fixture systems. The company is growing its presence in Saudi Arabia's premium residential and hospitality segments.
- Product Portfolio: Advanced toilet systems including washlet and smart toilet ranges, luxury faucets, shower systems, and sanitary ware under the TOTO brand, targeting premium residential and hospitality applications.
- Recent Developments: The company is expanding its distribution and showroom presence in Saudi Arabia, targeting high-specification residential and hospitality projects, particularly within giga-project developments requiring premium bathroom fixture specifications.
- Strategic Focus: Building specification activity in Saudi Arabia's luxury residential and high-end hospitality segments through advanced washlet and smart toilet technology, premium design aesthetics, and project-specific specification support.
Market Concentration Analysis
The Saudi Arabia plumbing fixtures market is moderately fragmented, with the top international manufacturers collectively accounting for a significant but not dominant share of market value, reflecting the presence of a large number of mid-tier and local distributors serving diverse product categories and price points.
Barriers to market leadership include the breadth of product categories required to serve all segments, the need for established distribution networks across Saudi Arabia's geographically diverse regions, and the ability to engage effectively in construction project specification processes that often determine large-scale procurement decisions. Companies with established brand recognition, broad distribution coverage, and active project specification teams hold structural competitive advantages.
Consolidation trends are emerging as global fixture manufacturers invest in strengthening their Saudi Arabian distribution networks, establishing local showrooms and training centers, and pursuing specification partnerships with large construction and fit-out contractors. Strategic partnerships between international manufacturers and local distribution groups are becoming an increasingly common structure for scaling market presence efficiently.
Investment & Growth Opportunities
Fastest-Growing Segments
Showers are expanding fastest among product sub-segments, driven by premiumization trends, adoption of rainfall and multi-function shower systems, and growing consumer investment in bathroom design across Saudi Arabia's mid-to-premium residential segment.
Emerging Markets
Eastern Region represents the fastest-growing regional market, supported by growing industrial and residential construction activities. The region offers significant untapped opportunities for distributors able to establish local service infrastructure ahead of the anticipated expansion in construction activity.
Venture & Investment Trends
Investment activity is concentrated in smart fixture development and distribution, localized warehousing and showroom operations, water-efficient product certification, and specification engagement programs targeting large construction and hospitality projects. Capital is also flowing into digital platforms connecting fixture brands with contractors, interior designers, and project managers, improving brand reach in a market where specification often determines procurement outcomes.
Future Market Outlook (2026-2034)
The Saudi Arabia plumbing fixtures market is projected to grow from USD 872.1 Million in 2025 to USD 909.9 Million in 2026, reaching USD 1,278.2 Million by 2034, registering a CAGR of 4.34% during 2026-2034.
Four forces will shape the market through 2034 continued execution of Vision 2030 construction megaprojects generating sustained demand across all fixture categories; growing adoption of smart and water-efficient fixtures driven by regulation and consumer preference; expansion of premium residential and hospitality construction supporting above-market growth in design-led and high-specification product segments; and increasing localization of supply chains, reducing lead times and improving service capability for large project procurement.
By 2034, the Saudi Arabia plumbing fixtures market is expected to be characterized by a mature competitive landscape with established global brands competing alongside strengthened regional distributors, a growing premium segment driven by giga-project and hospitality construction, and increasing product standardization around water-efficiency and smart connectivity requirements.
Research Methodology
Primary Research
Primary research included structured discussions with plumbing fixture distributors, construction project procurement managers, interior design professionals, fit-out contractors, and building materials retailers across Saudi Arabia, validating market sizing, segment mix, regional demand patterns, and competitive positioning in the Saudi Arabia plumbing fixtures ecosystem.
Secondary Research
Secondary sources included Saudi General Authority for Statistics (GASTAT) construction data, Saudi Building Code publications, Ministry of Municipal and Rural Affairs reports, Vision 2030 program disclosures, and public disclosures from listed plumbing fixture manufacturers and construction companies operating in Saudi Arabia.
Forecasting Models
Market forecasts used top-down and bottom-up models combining Saudi Arabia construction output projections, residential unit completion estimates, commercial construction pipeline data, fixture penetration rate assumptions, and replacement cycle demand analysis. Scenario analysis addressed Vision 2030 project execution pace, oil price sensitivity on government construction budgets, and technology adoption rates for smart and water-efficient fixtures.
Saudi Arabia Plumbing Fixtures Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Products Covered | Bathtubs, Sinks, Toilets, Showers, Faucets and Taps, Drains, Others |
| Locations Covered | Bathroom, Kitchen, Others |
| Applications Covered | New Construction, Repair and Renovation |
| Distribution Channels Covered | Online, Offline |
| End Users Covered | Residential, Commercial |
| Regions Covered | Northern and Central Region, Western Region, Eastern Region, Southern Region |
| Companies Covered | LIXIL Corporation, Kohler Co., TOTO Ltd., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Saudi Arabia plumbing fixtures market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Saudi Arabia plumbing fixtures market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Saudi Arabia plumbing fixtures industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Saudi Arabia Plumbing Fixtures Market Report
The Saudi Arabia plumbing fixtures market size is estimated at USD 909.9 Million in 2026, driven by Vision 2030 megaprojects, rapid urbanization, and growing hospitality and commercial construction across the Kingdom.
The market is projected to grow at a CAGR of 4.34% from 2026-2034, reaching USD 1,278.2 Million, supported by sustained construction activity and rising demand for premium and water-efficient fixtures.
Toilets dominate the market at 25.0% product share in 2025, driven by their universal presence across residential, commercial, and hospitality construction, and consistent replacement demand across Saudi Arabia's building stock.
Residential represents 65.0% of the market in 2025, driven by Saudi Arabia's large-scale government housing programs, private residential development, and high volumes of villa and apartment construction across major cities.
Northern and Central Region commands 48.2% share in 2025, led by Riyadh's primacy as the economic capital and the concentration of Vision 2030 megaprojects, government housing, and commercial construction.
Key players include LIXIL Corporation, Kohler Co., and TOTO Ltd., among others.
Key drivers include Vision 2030 megaproject construction, rapid urbanization, hospitality sector expansion, government housing programs, and rising consumer demand for premium, water-efficient, and smart plumbing fixtures.
Key trends include adoption of smart and sensor-based fixtures, demand for water-efficient products, premiumization in residential and hospitality segments, and localization of supply chains under Vision 2030 industrial strategy.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade