
Saudi Arabia Smart Agriculture Market Size, Share, Trends and Forecast by Agriculture Type, Offering, Farm Size, and Region, 2026-2034
Saudi Arabia Smart Agriculture Market Size, Share, Trends & Forecast (2026-2034)
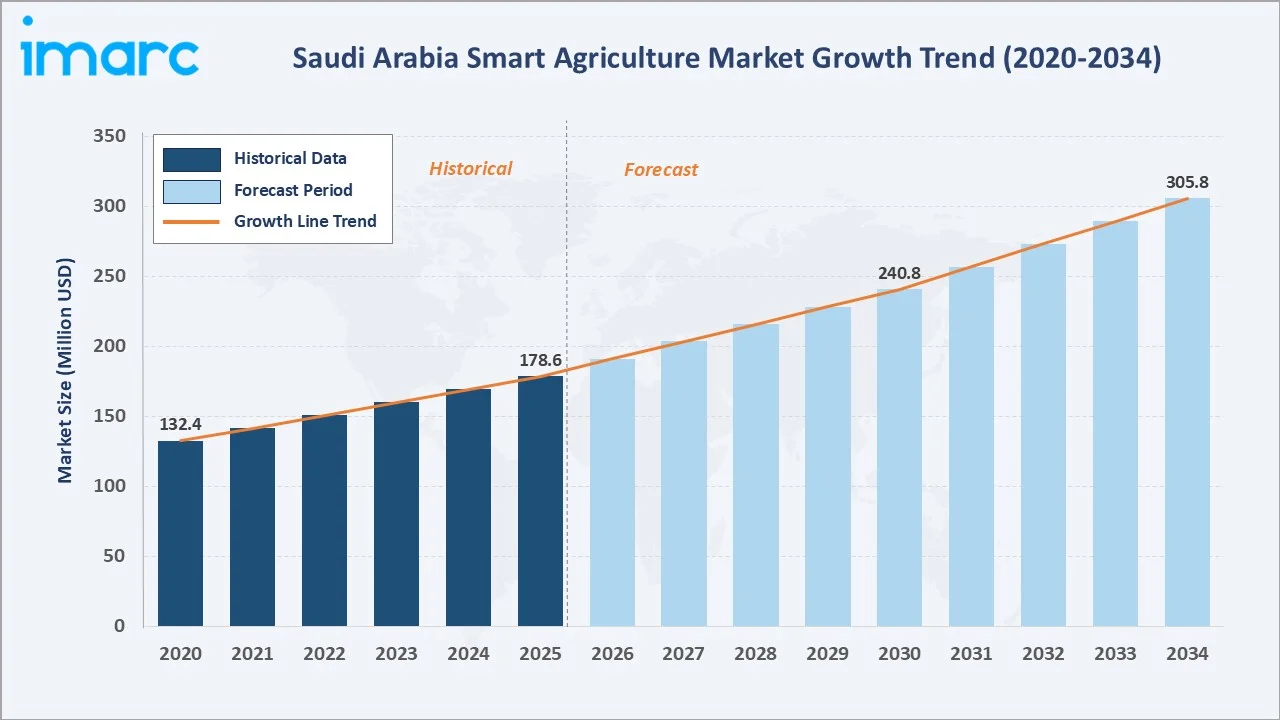
The Saudi Arabia smart agriculture market reached USD 178.6 Million in 2025 and is projected to reach USD 305.8 Million by 2034, growing at a CAGR of 6.16% during 2026-2034. The market is driven by Vision 2030 agricultural modernization, acute water scarcity challenges, and government-backed food security investments. Saudi Arabia cultivates approximately 1.2 million hectares of agricultural land, with smart agriculture adoption accelerating across precision farming, smart greenhouse, and livestock monitoring segments. Precision Farming dominates at 48.6%. Hardware leads offering at 52.8%. Northern and Central Region commands 37.6% of the market share.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 178.6 Million |
|
Forecast Market Size (2034) |
USD 305.8 Million |
|
CAGR (2026-2034) |
6.16% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Agriculture Type |
Precision Farming (48.6%, 2025) |
|
Dominant Offering |
Hardware (52.8%, 2025) |
|
Leading Region |
Northern and Central Region (37.6%, 2025) |
The Saudi Arabia smart agriculture market expanded from USD 132.4 Million in 2020 to USD 178.6 Million in 2025, anchored at USD 240.8 Million in 2030, and forecast to reach USD 305.8 Million by 2034. Vision 2030's National Agriculture Development Program catalyzed unprecedented government investment in domestic food production technology. Post-2022 food security strategy acceleration sustained above-trend smart agriculture market growth through 2023-2025.
To get more information on this market, Request Sample
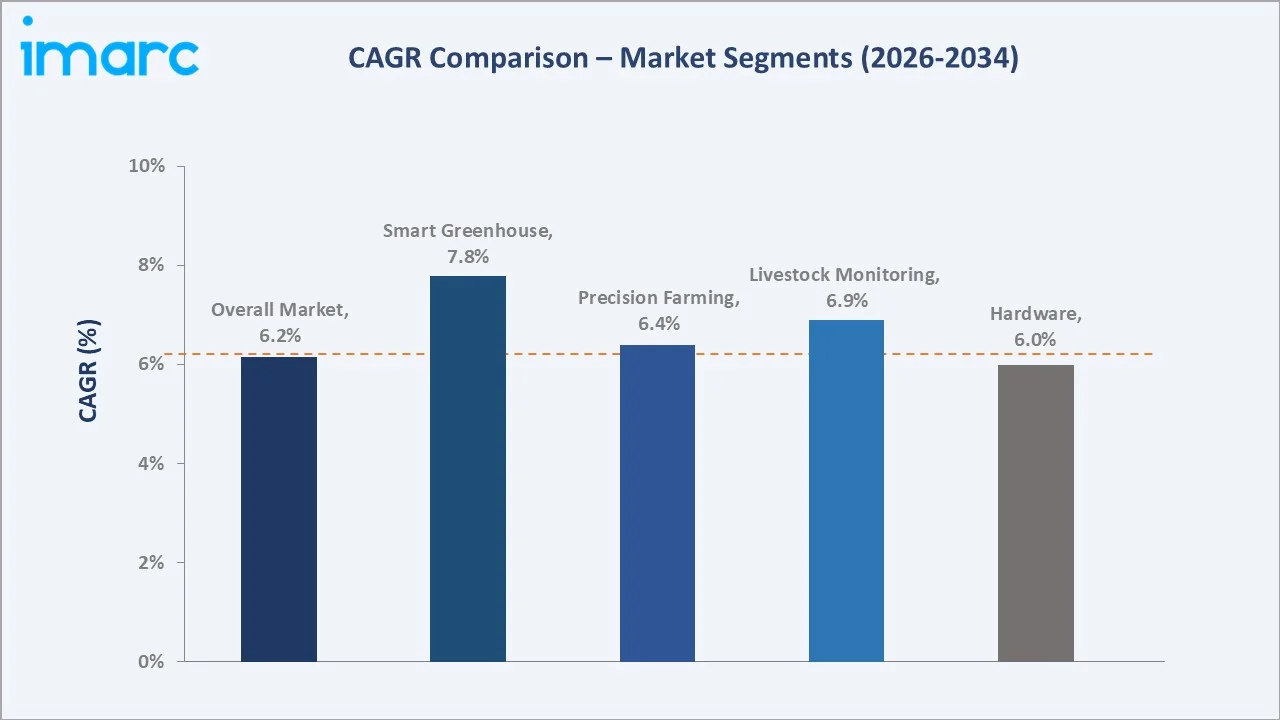
Smart Greenhouse grows fastest at ~7.8% CAGR as controlled-environment agriculture expands viability in Saudi Arabia's arid regions where temperature and water management technology determines growing feasibility. Precision Farming grows at ~6.4% CAGR through large-scale commercial farming economics and government-backed precision agriculture adoption.
Executive Summary
The Saudi Arabia smart agriculture market reached USD 178.6 Million in 2025, representing one of the region's most strategically significant intersections of agriculture, technology, and food security investment. The market encompasses precision farming solutions, smart greenhouse technologies, livestock monitoring systems, and integrated digital agriculture platforms that support data-driven crop and livestock management.
Precision Farming at 48.6% dominates through GPS precision, drone monitoring, and AI-driven crop analytics. Hardware at 52.8% leads offering through foundational role of sensors, drones, and IoT devices. Northern and Central Region at 37.6% leads through government agricultural investment concentration and agri-tech cluster development.
Key Market Insights
|
Insight |
Data |
|
Dominant Agriculture Type |
Precision Farming – 48.6% share (2025) |
|
Dominant Offering |
Hardware – 52.8% market share (2025) |
|
Leading Region |
Northern and Central Region – 37.6% market share |
|
Market Opportunity |
AI-driven crop analytics; drone-based monitoring; smart irrigation; precision livestock management; agri-fintech integration |
Key Analytical Observations Supporting the Above Data:
- Precision Farming at 48.6%: Precision farming dominates due to strong government support under Vision 2030, GPS-guided irrigation, drone-based monitoring, and AI analytics enabling resource-efficient crop production. These solutions help Saudi farmers maximize yields while minimizing water usage in water-scarce environments.
- Hardware at 52.8%: Hardware leads because physical sensors, drones, IoT devices, and precision equipment form the foundational infrastructure for all smart agriculture applications. Without hardware deployment, software and service layers cannot function, making it the largest and most essential component.
- Northern and Central Region at 37.6%: The region dominates due to concentration of government agricultural programs, presence of major agri-tech hubs, and large-scale precision farming pilots supported by Vision 2030 national agriculture modernization initiatives.
Saudi Arabia Smart Agriculture Market Overview
The Saudi Arabia smart agriculture market encompasses the deployment, integration, and operation of all digital and precision technologies used for commercial crop production, livestock management, and agricultural resource optimization across the Kingdom. The market includes hardware devices, software platforms, and professional services supporting data-driven farming decisions.
Macroeconomic factors include acute water scarcity, government food security mandates, Vision 2030 agricultural transformation programs, and increasing investments in controlled-environment agriculture. Climate extremes, arable land constraints, and subsidy reforms are accelerating smart agriculture adoption nationwide.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
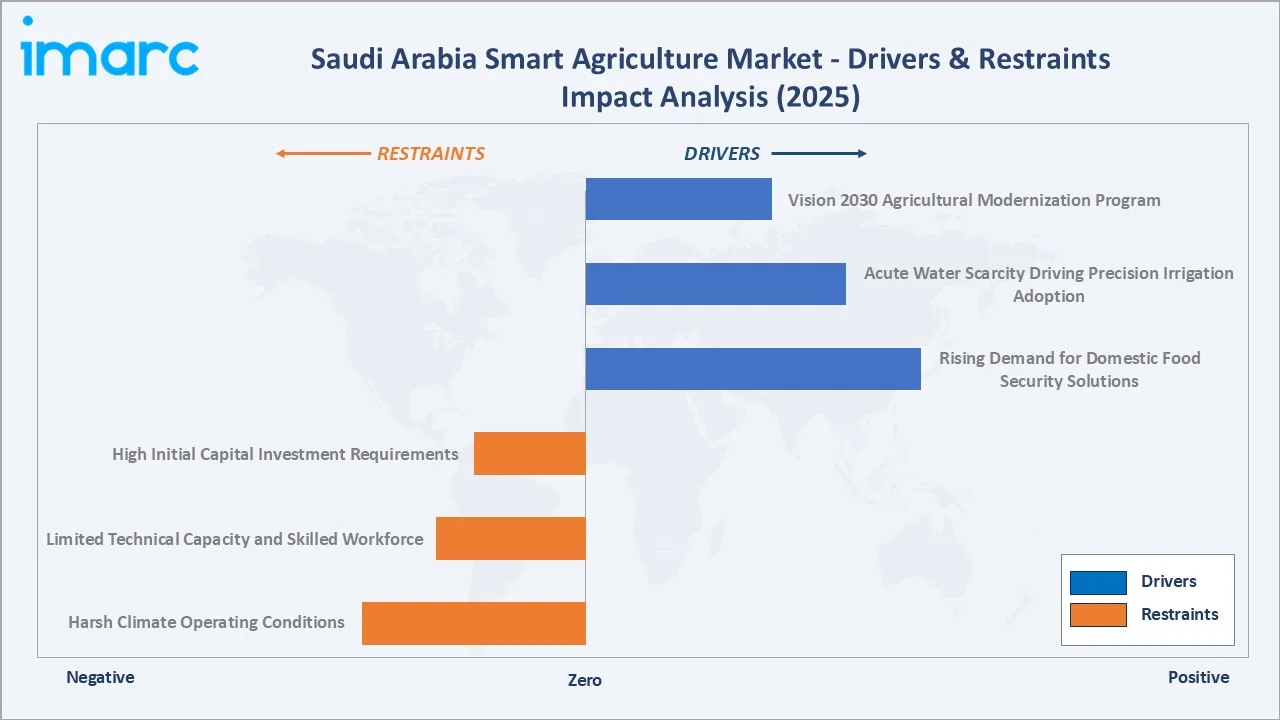
- Vision 2030 Agricultural Modernization Program: Vision 2030's National Agricultural Development Program is channeling multi-billion riyal investments into smart farming infrastructure, precision agriculture subsidies, and agri-tech startup ecosystems. Government programs are mandating technology adoption to improve productivity and reduce import dependency, driving demand for precision farming hardware, software, and services.
- Acute Water Scarcity Driving Precision Irrigation Adoption: Saudi Arabia's extreme water scarcity creates urgent demand for precision irrigation, soil moisture sensors, and water-efficient smart greenhouse solutions. Smart agriculture's documented 30-50% water use reduction versus conventional farming creates a compelling economic case for adoption. Government mandates for agricultural water efficiency are accelerating uptake across all farm scales.
- Rising Demand for Domestic Food Security Solutions: Saudi Arabia imports approximately 80% of its food requirements, creating food security vulnerability driving government-mandated domestic production expansion. Smart agriculture technologies enable higher yields per unit of scarce arable land and water. Investment in drone monitoring, AI crop analytics, and precision planting is supported by food security program funding.
- National Smart City and Digital Infrastructure Integration: Saudi Arabia's mega-project developments include integrated smart agriculture components utilizing advanced IoT, AI, and robotics. National 5G rollout enables real-time data transmission from remote agricultural areas, creating the connectivity backbone for large-scale IoT sensor deployment across previously unconnected agricultural zones.
Market Restraints
- High Initial Capital Investment Requirements: High initial capital in precision agriculture hardware, GPS equipment, drone fleets, and IoT sensor infrastructure makes adoption challenging for small and medium-scale Saudi farmers. Implementation costs can represent multiple years of farm revenue. Financing constraints and uncertain payback periods slow adoption among smaller agricultural operators.
- Limited Technical Capacity and Skilled Workforce: Saudi agriculture's transition to technology-intensive operations requires agronomists, data scientists, and precision agriculture technicians in limited supply. Operating drone fleets, interpreting AI recommendations, and maintaining IoT networks require skills not traditionally present in agricultural communities, resulting in lower adoption rates.
- Harsh Climate Operating Conditions: Extreme heat, sandstorms, and humidity create accelerated wear and reliability challenges for precision agriculture electronics, sensors, and drone equipment. Operating temperatures frequently exceed equipment design specifications, reducing hardware lifespan and increasing maintenance costs, which raises the total cost of ownership.
Market Opportunities
- Solar-Powered Precision Agriculture Solutions: Saudi Arabia's abundant solar resources enable solar-powered IoT sensor networks, autonomous farm equipment, and off-grid precision agriculture systems that reduce operational energy costs and improve feasibility in remote agricultural zones.
- Vertical Farming and Controlled Environment Agriculture: Saudi Arabia's climate extremes drive investment in vertical farms and smart greenhouses enabling year-round production of fresh vegetables and herbs. Government initiatives fund controlled-environment agriculture infrastructure as falling LED and climate control costs improve economics.
Market Challenges
- Fragmented Farm Structure and Adoption Coordination: Saudi Arabia's agricultural landscape includes large commercial farms and numerous small traditional farms, creating fragmented technology adoption patterns and limiting economies of scale. Coordinating deployment across diverse operators with different capabilities is operationally complex.
Emerging Market Trends
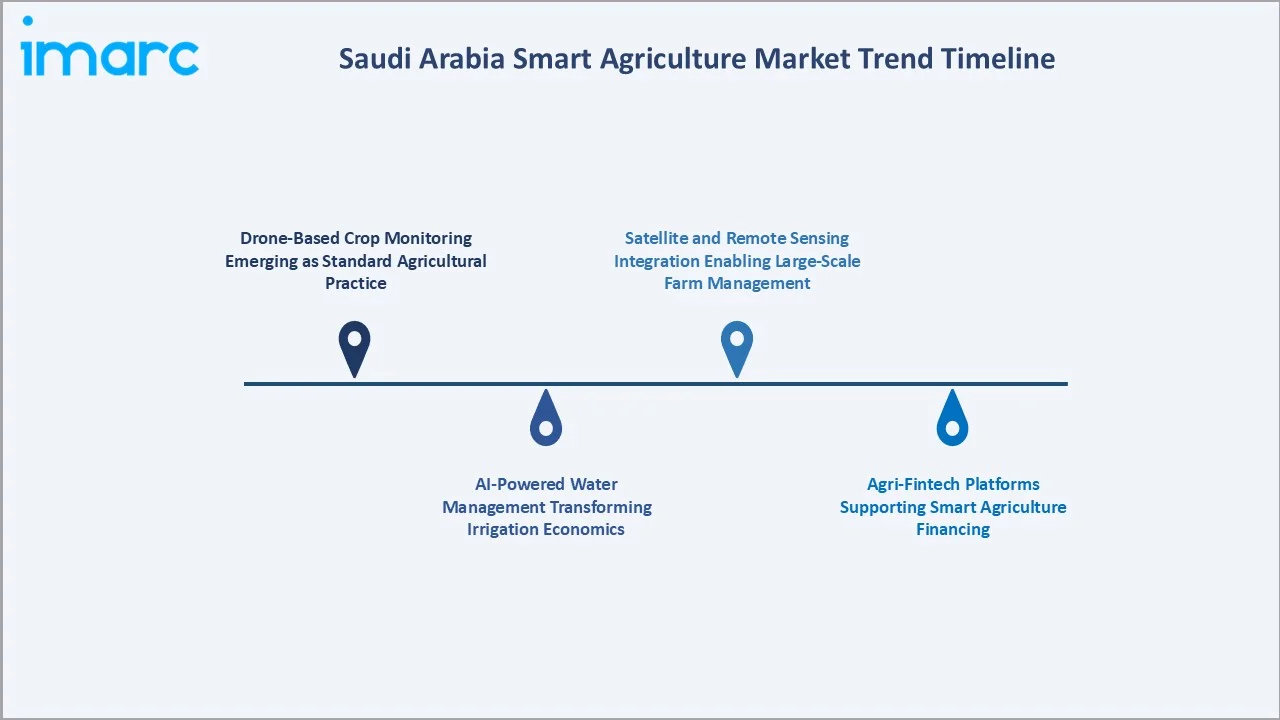
1. Drone-Based Crop Monitoring Emerging as Standard Agricultural Practice
Drone-based crop monitoring is becoming standard practice across Saudi commercial farms, providing real-time imagery for crop health assessment, irrigation optimization, and precision spraying. Multi-spectral drone sensors enable early detection of water stress, nutrient deficiencies, and pest outbreaks. Government programs are subsidizing drone procurement for qualified Saudi agricultural operators.
2. AI-Powered Water Management Transforming Irrigation Economics
AI-driven soil moisture monitoring and precision irrigation achieve documented water savings of 30-50% versus conventional flood irrigation in Saudi conditions. Machine learning models integrating weather forecasting, crop growth stages, and soil sensors automate irrigation scheduling. As water scarcity intensifies, AI water management is becoming the single highest-return smart agriculture investment.
3. Satellite and Remote Sensing Integration Enabling Large-Scale Farm Management
Satellite imagery and remote sensing enable centralized monitoring of vast agricultural areas across Saudi Arabia's geographically dispersed farming regions. Cloud-based satellite analytics platforms provide weekly or daily crop health indices for farm management decision support. Cost reductions in satellite data access have made remote sensing commercially viable for medium-scale farms.
4. Agri-Fintech Platforms Supporting Smart Agriculture Financing
Digital agricultural lending and insurance platforms enable Saudi farmers to finance smart agriculture equipment through crop-performance-linked loan products. Agri-fintech integration is reducing the capital barrier to precision agriculture adoption among medium-scale farmers. Government-backed agricultural finance programs are incorporating smart farming technology as a qualification criterion.
Industry Value Chain Analysis
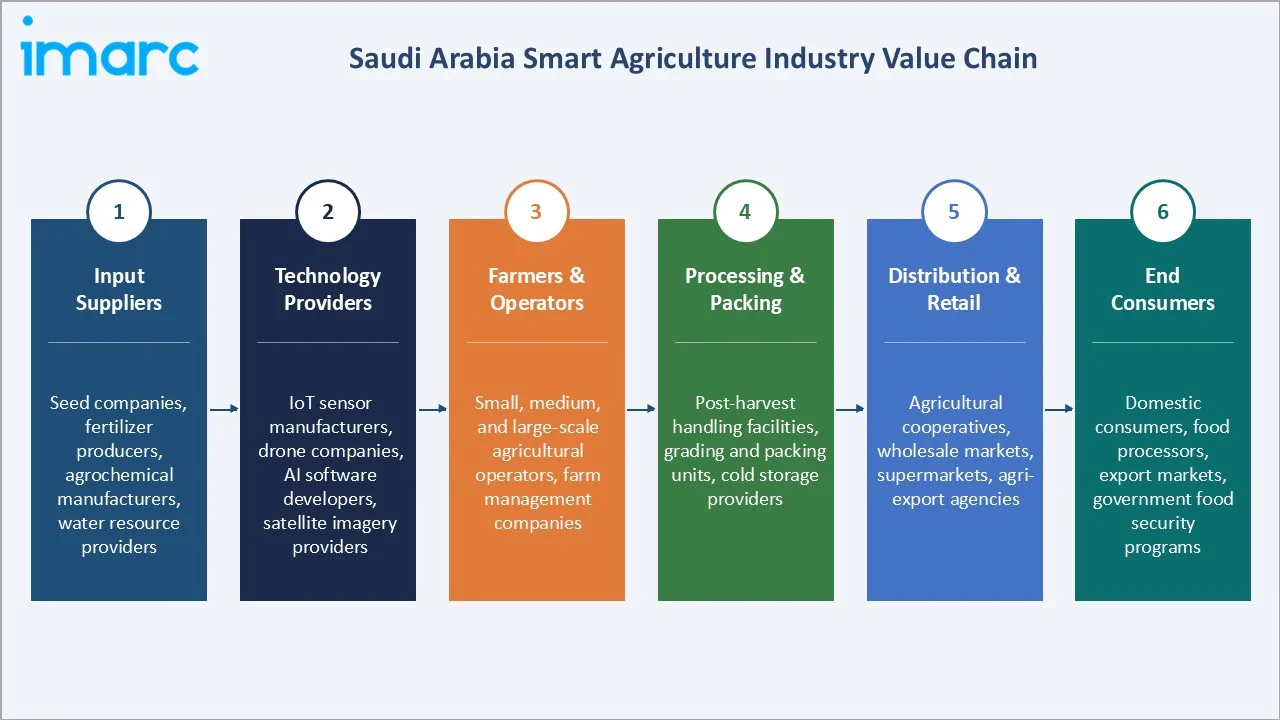
The Saudi Arabia smart agriculture value chain integrates input supply, technology provision, farm operations, processing, distribution, and end consumer supply. Each stage contributes distinct value shaped by Vision 2030 mandates, water scarcity constraints, and food security imperatives.
|
Stage |
Key Participants |
|
Input Suppliers |
Seed companies, fertilizer producers, agrochemical manufacturers, water resource providers |
|
Technology Providers |
IoT sensor manufacturers, drone companies, AI software developers, satellite imagery providers |
|
Farmers & Operators |
Small, medium, and large-scale agricultural operators, farm management companies |
|
Processing & Packing |
Post-harvest handling facilities, grading and packing units, cold storage providers |
|
Distribution & Retail |
Agricultural cooperatives, wholesale markets, supermarkets, agri-export agencies |
|
End Consumers |
Domestic consumers, food processors, export markets, government food security programs |
The technology provision stage is the value chain's most commercially dynamic and differentiated phase, where AI analytics, IoT sensor networks, and precision equipment suppliers generate the highest margins. The farm operations layer is where Saudi precision agriculture creates resource efficiency advantage versus conventional farming.
Technology Landscape in the Saudi Arabia Smart Agriculture Industry
Precision Irrigation and Soil Sensing Technology
Precision irrigation combining soil moisture sensors, weather data, and AI scheduling is the highest-adoption smart agriculture technology in Saudi Arabia due to acute water scarcity. Drip irrigation with IoT control achieves water savings of 40-60% versus conventional systems. Soil sensing networks enable real-time root zone moisture monitoring supporting evidence-based irrigation management.
Drone and UAV Agricultural Monitoring
Agricultural drones equipped with multi-spectral, thermal, and RGB cameras enable crop health monitoring, yield estimation, and precision chemical application across Saudi farms. Autonomous drone missions reduce labor requirements for field scouting while improving crop stress detection accuracy. Fixed-wing UAVs monitor large commercial farm areas while multirotor drones support precision spraying.
AI and Big Data Crop Management Platforms
AI-powered crop management platforms integrate satellite imagery, drone data, weather forecasting, and soil sensors to provide actionable agronomic recommendations. Machine learning models trained on Saudi crop performance data improve yield prediction accuracy and early stress detection. Cloud-based platforms enable centralized management of multiple farm locations.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
CAGR (2026-2034) |
Year |
|
Agriculture Type |
Precision Farming |
48.6% |
~6.4% |
2025 |
|
Farm Size |
🔒 |
🔒 |
🔒 |
2025 |
|
Offering |
Hardware |
52.8% |
~6.0% |
2025 |
|
Region |
Northern and Central Region |
37.6% |
~6.16% |
2025 |

By Agriculture Type
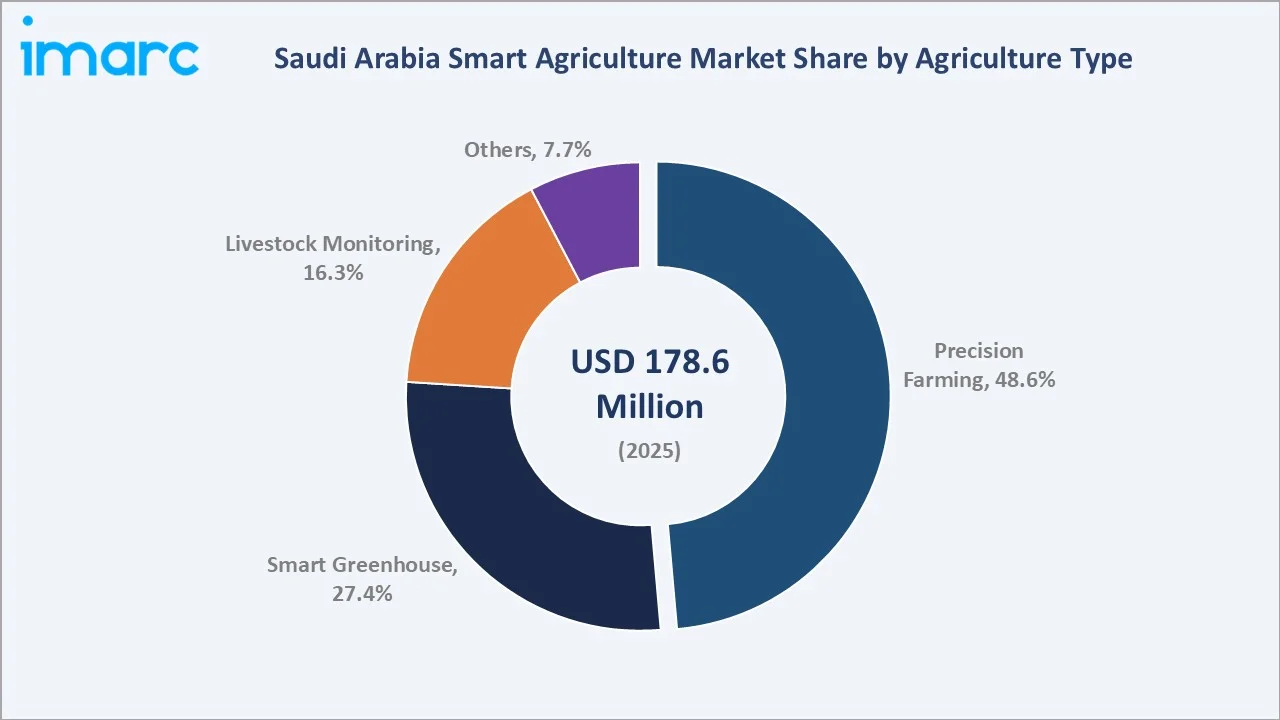
Precision Farming leads at 48.6% (2025) growing at ~6.4% CAGR (2026-2034). The segment encompasses GPS-guided equipment, drone monitoring platforms, AI crop analytics, precision irrigation systems, and farm management software deployed across Saudi commercial and government farms.
To access detailed market analysis, Request Sample
Smart Greenhouse at 27.4% grows fastest at ~7.8% CAGR through controlled-environment agriculture expansion enabling year-round vegetable production in arid Saudi conditions. Livestock Monitoring at 16.3% grows at ~6.9% CAGR through RFID tracking and biometric sensor adoption. Others at 7.7% covers aquaponics, vertical farming, and emerging agri-tech categories.
By Offering
Hardware leads at 52.8% (2025) growing at ~6.0% CAGR (2026-2034). The segment encompasses IoT sensors, drones, GPS equipment, weather stations, smart irrigation controllers, and precision machinery forming the foundational technology infrastructure for all smart agriculture applications.
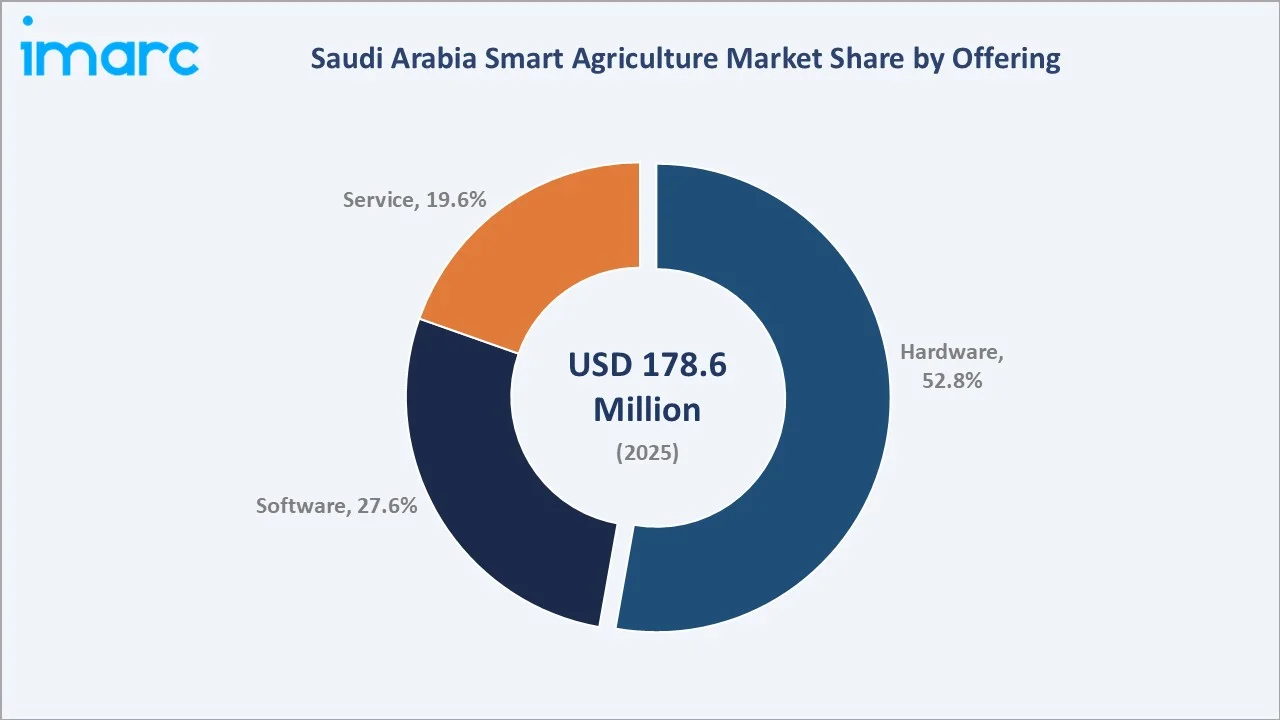
Software at 27.6% grows fastest at ~7.2% CAGR through farm management platforms, AI analytics tools, and precision agriculture applications enabling intelligence-driven decision-making. Service at 19.6% grows at ~5.8% CAGR including consulting, implementation, maintenance, training, and data analytics services.
Regional Market Insights
|
Region |
Share (2025) |
Key Smart Agriculture Market Drivers & Characteristics |
|
Northern and Central Region |
37.6% |
Driven by strong government agricultural investment, presence of key smart farming hubs, and advanced irrigation infrastructure under Vision 2030. |
|
Western Region |
26.8% |
Supported by growing agri-tech adoption, proximity to Red Sea trade routes, and expanding food production under national food security programs. |
|
Eastern Region |
22.1% |
Driven by oil-revenue-funded agricultural modernization, petrochemical industry support for agri-tech, and large-scale precision farming pilots. |
|
Southern Region |
13.5% |
Supported by favorable climatic conditions for certain crops, government subsidies for rural agricultural development, and rising adoption of smart irrigation. |
The Northern and Central Region's 37.6% market leadership is anchored by Riyadh's role as the national agricultural policy center and the concentration of government-funded agri-tech pilot programs. The Western Region's 26.8% reflects the Makkah and Madinah agricultural hinterlands and Red Sea coastal aquaculture smart technology adoption.
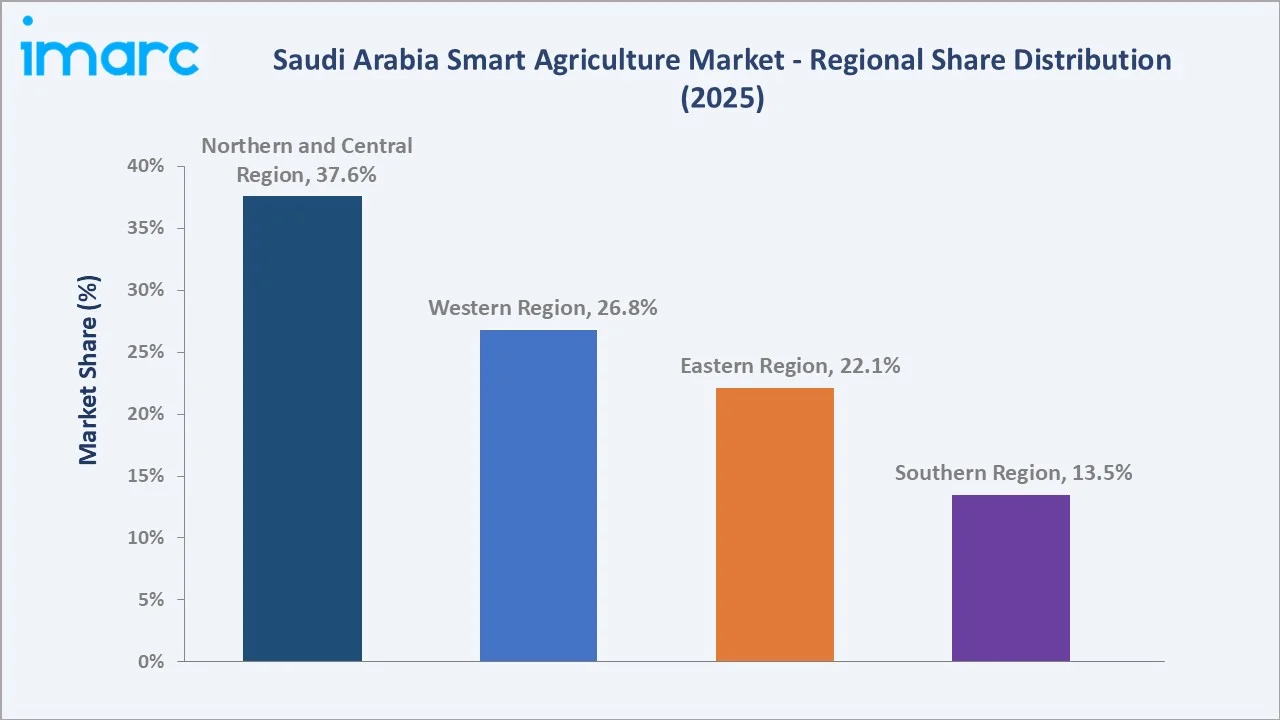
The Eastern Region's 22.1% encompasses large commercial farm operations supported by petrochemical-industry adjacent infrastructure and Eastern Province government agricultural initiatives. The Southern Region at 13.5% represents the mountainous Aseer and Jazan regions with favorable climatic conditions enabling rain-fed and smart-assisted crop cultivation.
Competitive Landscape
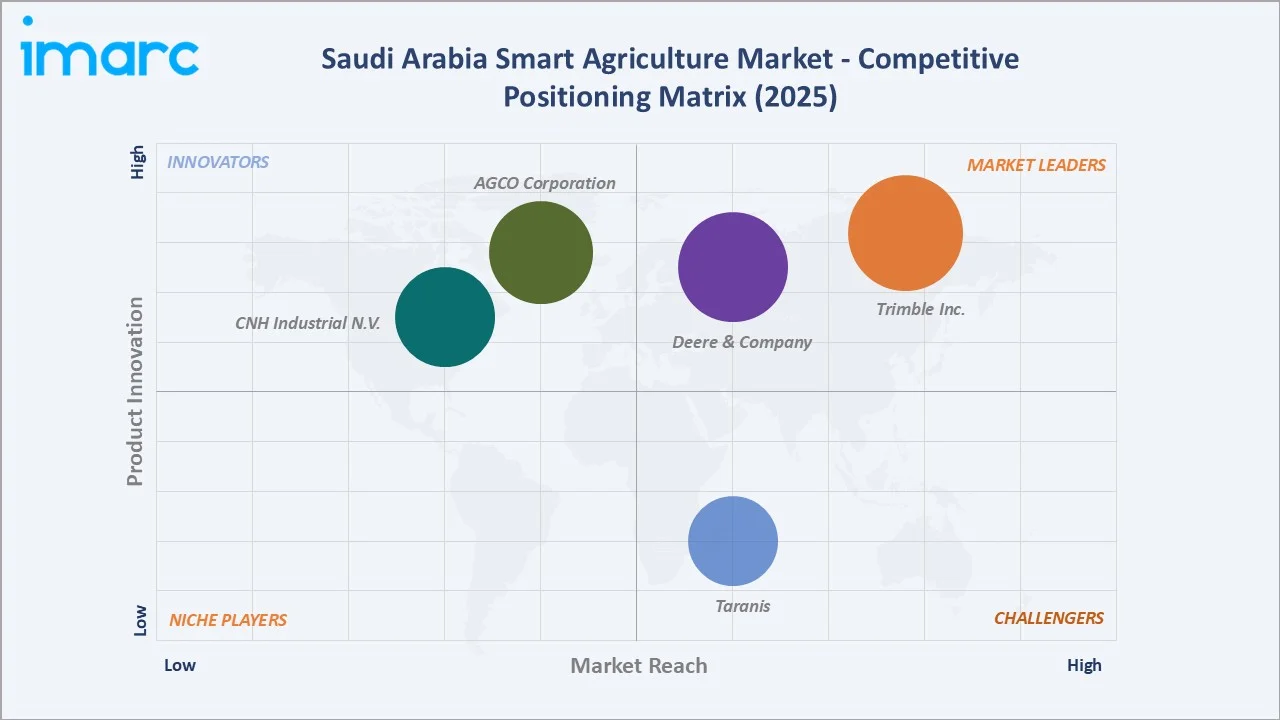
The Saudi Arabia smart agriculture competitive landscape encompasses international precision agriculture technology leaders, regional agri-tech specialists, and emerging Saudi startups. Market structure reflects the dominance of international technology companies providing hardware and platforms alongside local implementation and service partners.
|
Company Name |
Key Products |
Market Position |
Core Strength |
|
Trimble Inc. |
Trimble Ag Software, GreenSeeker |
Market Leader |
Integrated precision agriculture solutions with GPS, remote sensing, and data analytics for crop optimization. |
|
Deere & Company |
Operations Center, ExactApply, See & Spray |
Market Leader |
Comprehensive farm management ecosystem combining equipment, connectivity, and AI-driven precision agriculture. |
|
AGCO Corporation |
Fuse Technology |
Established Player |
Smart farming solutions spanning planting, spraying, and harvest automation with integrated data platforms. |
|
CNH Industrial N.V. |
AFS Connect, PLM Intelligence Platform |
Established Player |
Precision agriculture technologies with advanced telematics, fleet management, and automated field operations. |
|
Taranis |
Scout, Advisor |
Emerging Player |
AI-powered aerial imagery and crop intelligence platform enabling early pest, disease, and stress detection. |
International technology providers hold dominant positions through superior hardware capability, established AI platforms, and global precision agriculture customer relationships. Local Saudi agri-tech companies are gaining share through Vision 2030 localization requirements, agricultural ministry partnerships, and domain knowledge in Saudi-specific farming conditions.
Key Company Profiles
Trimble Inc.
Trimble Inc. is a leading global provider of positioning, modeling, connectivity, and data analytics solutions for precision agriculture. The company offers comprehensive GPS guidance, drone monitoring, and farm management software platforms serving commercial agricultural operators worldwide.
- Key Products: Trimble Ag Software, WeedSeeker Precision Sprayer, GreenSeeker Crop Sensing System.
- Recent Developments: In March 2025, Trimble and PTx Trimble announced the availability of Trimble IonoGuard for the precision agriculture industry. The technology is designed to improve RTK GNSS signal tracking and positioning performance, particularly during solar-storm events. This is relevant to smart agriculture because high-accuracy GNSS positioning supports precision guidance, planting, spraying, harvesting and other automated farm operations. PTx Trimble describes its portfolio as covering guidance, autonomy, precision spraying, connected farming, data management and sustainability.
- Strategic Focus: Concentrated on integrated precision agriculture ecosystems combining GPS guidance, autonomous equipment, AI analytics, and cloud-based farm management platforms for commercial agricultural operations.
Deere & Company
John Deere is a world-leading manufacturer of agricultural machinery and precision farming technology, offering comprehensive smart agriculture solutions spanning equipment, connectivity platforms, and AI-driven agronomic tools for large-scale commercial farming.
- Key Products: Operations Center Farm Management Platform, ExactApply Nozzle Control System, See & Spray Ultimate.
- Recent Developments: In January 2025, John Deere unveiled its next generation of autonomous agricultural machinery at CES 2025, including the Autonomous 9RX tractor designed for large-scale farming. The tractor incorporates advanced computer vision, artificial intelligence and multiple cameras to provide 360-degree visibility and enable autonomous navigation during tillage operations. Farmers can remotely monitor the machine and manage operating parameters through the John Deere Operations Center Mobile application.
- Strategic Focus: Centers on fully integrated autonomous farming ecosystems where connected equipment, data platforms, and AI agronomic intelligence converge to enable precision agriculture at commercial scale.
AGCO Corporation
AGCO Corporation is a global manufacturer and distributor of agricultural equipment and precision farming technology, providing integrated smart agriculture solutions spanning planting, crop management, and harvest automation supported by advanced data connectivity platforms.
- Key Products: Fuse Technology Platform, Fieldview Compatible Precision Systems, Grain Smart Storage Management.
- Recent Developments: In February 2025, AGCO launched enhanced AI-powered crop monitoring capabilities enabling real-time agronomic recommendations for precision nutrient and irrigation management.
- Strategic Focus: Focused on connecting farm equipment, field data, and agronomic intelligence through unified digital platforms that improve farm productivity while reducing input costs and environmental impact.
Market Concentration Analysis
The Saudi Arabia smart agriculture market is moderately fragmented at the farm operations tier, with diverse operator sizes ranging from large commercial farms to small traditional holdings. Technology suppliers are moderately concentrated, with international precision agriculture leaders holding dominant hardware and software positions. Market concentration is increasing at the AI analytics platform tier through partnerships and consolidation.
Investment & Growth Opportunities
Highest Growth Segments
Smart Greenhouse (~7.8% CAGR), AI water management software (~15% CAGR from small base), drone precision spraying (~10% CAGR), vertical farming (~20% CAGR from near-zero base), precision livestock monitoring (~7.2% CAGR), and agri-fintech platforms (~18% CAGR) represent the highest-growth Saudi smart agriculture investment vectors through 2034.
Emerging Investment Opportunities
Saudi Arabia's food security program represents the largest near-term smart agriculture investment opportunity. Technology companies establishing preferred supplier relationships with Saudi Ministry of Environment, Water and Agriculture procurement offices are positioned for above-market revenue growth as government disbursement accelerates under Vision 2030.
Investment Themes
- Solar-powered precision agriculture infrastructure: Saudi Arabia's solar abundance enables solar-powered IoT sensor networks, autonomous equipment charging, and off-grid smart greenhouse operations that reduce operating costs versus grid-dependent alternatives, improving ROI timelines for technology adoption.
- AI agronomic advisory platform development: AI crop management has documented benefits of 20-35% yield improvement in Saudi conditions. Cloud-based AI platform subscriptions create above-hardware-margin recurring revenue aligned with Vision 2030 digital agriculture mandates.
Future Market Outlook (2026-2034)
The Saudi Arabia smart agriculture market is projected to grow from USD 178.6 Million in 2025 to USD 305.8 Million by 2034, delivering a 6.16% CAGR over the forecast period. The market's anchor value of USD 240.8 Million in 2030 represents Saudi smart agriculture at its most transformative inflection since Vision 2030 inception, with AI crop management achieving mainstream deployment and smart greenhouse viability expanding significantly.
Three structural forces define Saudi smart agriculture growth through 2034. Food security as a national security imperative creates government-backed technology investment demand that is policy-mandated and multi-decade. Water scarcity creates an existential need for precision irrigation and smart greenhouse that is permanent and intensifying. Technology cost reduction is making precision agriculture commercially viable for medium and small farms.
Research Methodology
Primary Research
Primary research comprised structured interviews with 45+ industry stakeholders (2025) including Chief Technology Officers, Business Development Directors, Agricultural Technology Specialists, commercial farm CEOs, and regional agri-tech market specialists based in Saudi Arabia and the GCC.
Secondary Research
Secondary research encompassed Saudi Ministry of Environment, Water and Agriculture publications; Vision 2030 agricultural program data; GCC agri-tech industry reports; precision agriculture technology publications; company annual reports; Saudi food security strategy documents. Over 50 secondary sources reviewed.
Forecasting Models
Market revenue forecasts developed using a segment bottom-up model: (i) hardware component; (ii) software component; (iii) services component, calibrated to Saudi-specific adoption rates, government program disbursement timelines, and regional agricultural investment patterns.
Saudi Arabia Smart Agriculture Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Agriculture Types Covered | Precision Farming, Livestock Monitoring, Smart Greenhouse, Others |
| Offerings Covered | Hardware, Software, Service |
| Farm Sizes Covered | Small, Medium, Large |
| Regions Covered | Northern and Central Region, Western Region, Eastern Region, Southern Region |
| Companies Covered | Trimble Inc., Deere & Company, AGCO Corporation, CNH Industrial N.V., Taranis, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Saudi Arabia smart agriculture market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Saudi Arabia smart agriculture market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Saudi Arabia smart agriculture industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Saudi Arabia Smart Agriculture Market Report
The Saudi Arabia smart agriculture market reached USD 178.6 Million in 2025. The market is driven by Vision 2030 agricultural modernization, acute water scarcity, and government-backed food security investments. Advancements in precision irrigation, drone monitoring, AI crop analytics, and smart greenhouse technology are further supporting market growth.
The market grows at 6.16% CAGR during 2026-2034, reaching USD 305.8 Million by 2034. Smart Greenhouse grows fastest at ~7.8% CAGR through controlled-environment agriculture expansion. Software segment grows at ~7.2% CAGR driven by AI farm management platform adoption.
Precision Farming leads at 48.6% through GPS precision, drone monitoring, AI analytics, and precision irrigation advantages in water-scarce Saudi agricultural conditions. It grows at ~6.4% CAGR during the forecast period, supported by ongoing Vision 2030 precision agriculture subsidies.
Hardware leads at 52.8% growing at ~6.0% CAGR through the foundational role of IoT sensors, drones, GPS equipment, and smart irrigation controllers in enabling all smart agriculture applications across precision farming, smart greenhouse, and livestock monitoring segments.
The Northern and Central Region leads at 37.6% through concentration of government agricultural programs, agri-tech hub development, and large-scale precision farming pilots under Vision 2030 national agriculture modernization initiatives.
Leading companies include Trimble Inc., Deere & Company, AGCO Corporation, CNH Industrial N.V., and Taranis, among others.
The market is projected to reach approximately USD 240.8 Million by 2030, with AI water management achieving commercial mainstream adoption, smart greenhouse deployment scaling significantly, and precision livestock monitoring expanding across Saudi commercial livestock operations.
Vision 2030's National Agriculture Development Program is the primary demand catalyst, channeling government investment into precision agriculture subsidies, agri-tech startup support, and technology adoption requirements for government-affiliated agricultural operations, creating the policy foundation for sustained market growth through 2034.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade