
Saudi Arabia Superfood Market Size, Share, Trends and Forecast by Product Type, Application, Distribution Channel, and Region, 2026-2034
Saudi Arabia Superfood Market Size, Share, Trends & Forecast (2026-2034)
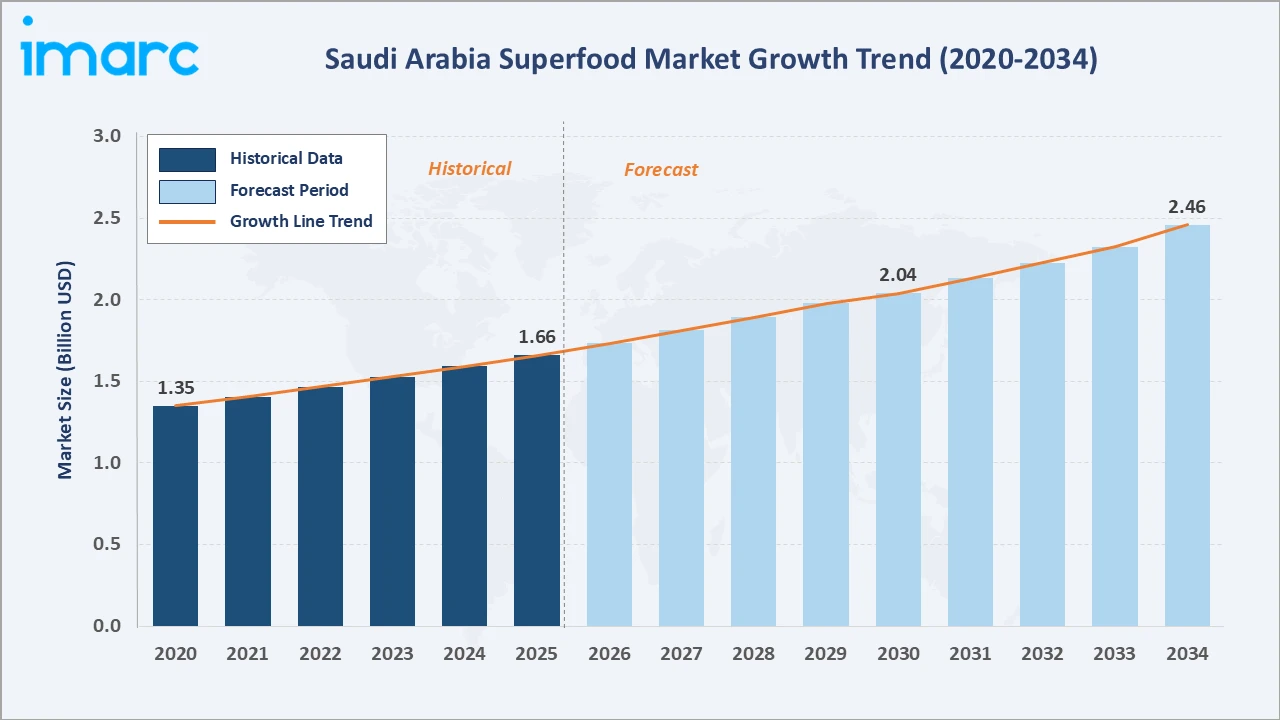
The Saudi Arabia superfood market grew from USD 1.66 Billion in 2025 to USD 1.73 Billion in 2026 and is projected to reach USD 2.46 Billion by 2034, exhibiting a CAGR of 4.22% during 2026-2034. Growth is anchored in rising health awareness, a heavy chronic-disease burden, and Vision 2030 wellness reforms. Government data show adult obesity at 23.1% and diabetes at 9.1% of people aged 15 and above in 2024, pushing consumers toward nutrient-dense foods. Fruits lead product demand at 31.8%, while beverages dominate applications at 29.5% in 2025. The Northern and Central Region holds the largest regional share at 38.4%, supported by Riyadh's affluent, urban, and youthful population base.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 1.66 Billion |
|
Market Size (2026) |
USD 1.73 Billion |
|
Forecast Market Size (2034) |
USD 2.46 Billion |
|
CAGR (2026-2034) |
4.22% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Largest Product Type |
Fruits (31.8%, 2025) |
|
Leading Application |
Beverages (29.5%, 2025) |
|
Dominant Region |
Northern & Central Region (38.4%, 2025) |
The Saudi Arabia superfood market expanded from USD 1.35 Billion in 2020 to USD 1.66 Billion in 2025 and an estimated USD 1.73 Billion in 2026. It is anchored at USD 2.04 Billion in 2030 and forecast to reach USD 2.46 Billion by 2034. This steady climb reflects a structural shift in Saudi diets, as preventive nutrition moves from a niche urban trend into mainstream household purchasing behaviour.
To get more information on this market, Request Sample
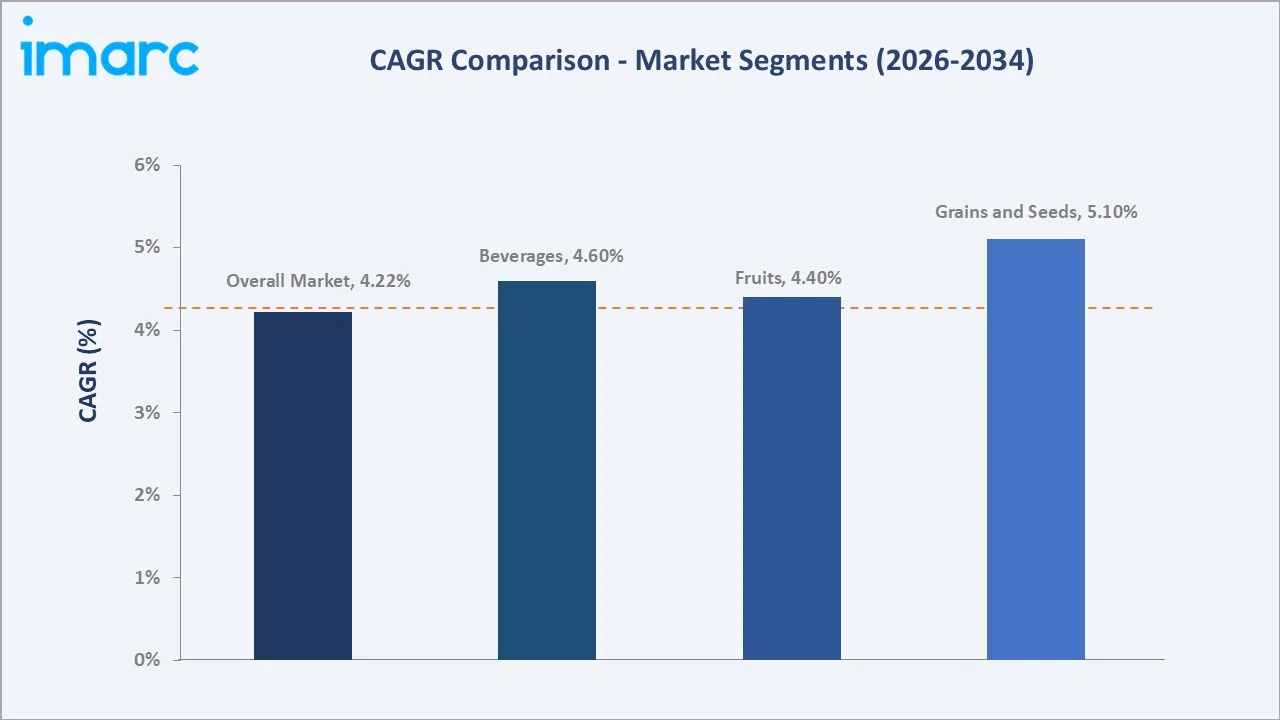
Growth is uneven across segments. Grains and seeds, supplements, and functional beverages outpace the market average, reflecting demand for plant protein, immunity support, and on-the-go nutrition. Meat-based superfoods grow slower, as plant-forward diets gain traction among younger Saudi consumers.
Executive Summary
The Saudi Arabia superfood market expanded from USD 1.66 Billion in 2025 to an estimated USD 1.73 Billion in 2026 driven by a sharp rise in health consciousness and one of the world's highest chronic-disease burdens. According to GASTAT's 2024 data, 23.1% of Saudis aged 15 and above are obese and 45.1% are overweight, while only 10.2% consume the recommended five daily servings of fruits and vegetables. These gaps create strong demand for nutrient-dense foods.
The market is projected to reach USD 2.46 Billion by 2034 at a 4.22% CAGR. Growth is reinforced by Vision 2030's Quality of Life Program and the SFDA's Healthy Food Strategy, which promote balanced diets and cleaner labels. A young population, with roughly a quarter aged 18-24, adopts wellness trends quickly through social media and digital retail.
Fruits command 31.8% of product demand in 2025, valued for antioxidants and everyday familiarity. Beverages lead applications at 29.5%, as smoothies and functional drinks gain popularity. The Northern and Central Region dominates at 38.4%, anchored by Riyadh's affluence, while the Western Region benefits from tourism and pilgrimage-driven consumption.
Key Market Insights
|
Insight |
Data |
|
Largest Product Type |
Fruits - 31.8% share (2025) |
|
Leading Application |
Beverages - 29.5% share (2025) |
|
Fastest Growing Product Type |
Grains and Seeds (~5.1% CAGR) |
|
Dominant Region |
Northern & Central Region - 38.4% (2025) |
|
Top Companies |
Almarai Company, Nestlé S.A., PepsiCo, Inc., and Green Spot |
|
Market Opportunity |
Local sourcing and functional product innovation |
Key Analytical Observations Supporting The Above Data:
- Fruits lead at 31.8% (2025): Berries, dates, and citrus dominate purchases as consumers seek familiar, antioxidant-rich options. Local date varieties give the segment a distinctly Saudi character and year-round availability.
- Beverages lead applications at 29.5% (2025): Smoothies, cold-pressed juices, and functional drinks suit a hot climate and busy lifestyles. PepsiCo's move to lower-sugar formulations in Saudi Arabia reflects this shift.
- Grains and seeds grow fastest (~5.1% CAGR): Chia, quinoa, flaxseed, and oats gain share on plant-protein and digestive-health demand, supported by rising vegan and gluten-free interest among urban Saudis.
- Northern and Central Region dominates at 38.4% (2025): Riyadh concentrates the highest incomes, retail density, and young professionals, sustaining premium superfood purchasing across supermarkets and online channels.
Saudi Arabia Superfood Market Overview
Saudi Arabia's superfood market covers nutrient-dense foods, such as fruits, vegetables, grains and seeds, herbs and roots, and select meat products, positioned for health benefits beyond basic nutrition. Demand spans beverages, supplements, ready-to-eat foods, and bakery items sold through supermarkets, specialty stores, and fast-growing online channels.
The market is largely import-driven, relying on global suppliers for chia, quinoa, berries, and similar inputs. It operates under the Saudi Food and Drug Authority (SFDA), which sets nutrition labelling, safety, and quality standards. Macroeconomic support comes from Vision 2030's diversification agenda, rising incomes, and a national push toward healthier diets and food security.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
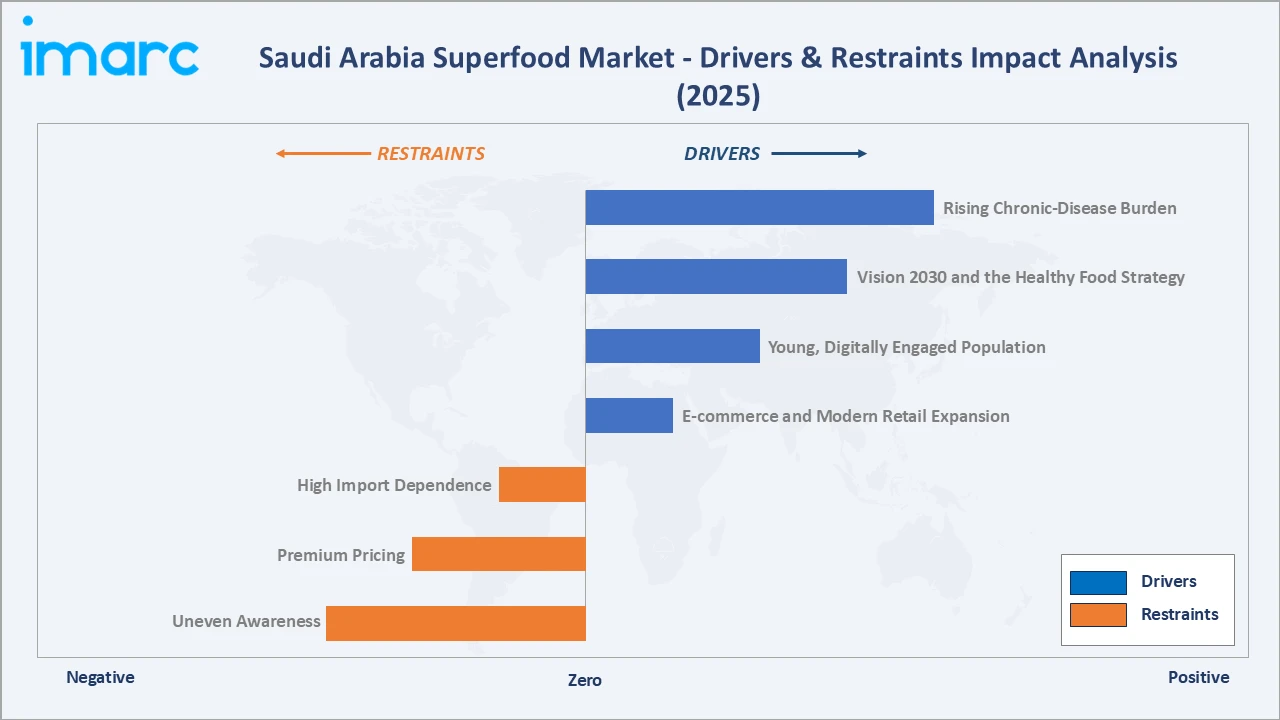
- Rising Chronic-Disease Burden: GASTAT reported adult obesity at 23.1% and overweight at 45.1% in 2024, while diabetes affects roughly a quarter of adults. This drives sustained demand for preventive, nutrient-dense foods.
- Vision 2030 and the Healthy Food Strategy: The SFDA banned partially hydrogenated oils, becoming the first country in the Eastern Mediterranean Region to do so, and launched the Healthy Saudi Plate in 2020 to promote fruits and vegetables.
- Young, Digitally Engaged Population: With about 25% of residents aged 18-24, wellness trends spread quickly through social media, fitness culture, and influencer-led marketing across Riyadh, Jeddah, and Dammam.
- E-commerce and Modern Retail Expansion: Electronic payments reached 79% of retail transactions in 2024, and Mada e-commerce sales hit USD 52.64 Billion, up 25.8%, widening access to imported and premium superfoods.
Market Restraints
- High Import Dependence: Most superfood inputs are imported, exposing retail prices to currency swings, freight costs, and global supply disruptions that can dampen price-sensitive demand.
- Premium Pricing: Superfoods often carry a cost premium over conventional foods, limiting mass-market penetration among lower-income and expatriate households.
- Uneven Awareness: Beyond popular items like dates and berries, many consumers remain unfamiliar with the specific benefits of quinoa, spirulina, or matcha, slowing broader adoption.
Market Opportunities
- Local Cultivation and Sourcing: Vision 2030 food-security goals support domestic production of dates, herbs, and greenhouse crops, reducing import reliance and creating export potential across the GCC.
- Functional Product Innovation: Superfood-infused beverages, snack bars, and supplements tailored to immunity, gut health, and weight management represent high-margin white space for manufacturers.
Market Challenges
- Price Competition and Substitution: Overlapping superfood claims across chia, flaxseed, and quinoa fragment demand and pressure brands to differentiate on quality and provenance.
- Regulatory and Labelling Compliance: Meeting SFDA nutrition, allergen, and health-claim requirements raises product-development costs, particularly for smaller importers and local start-ups.
Emerging Market Trends
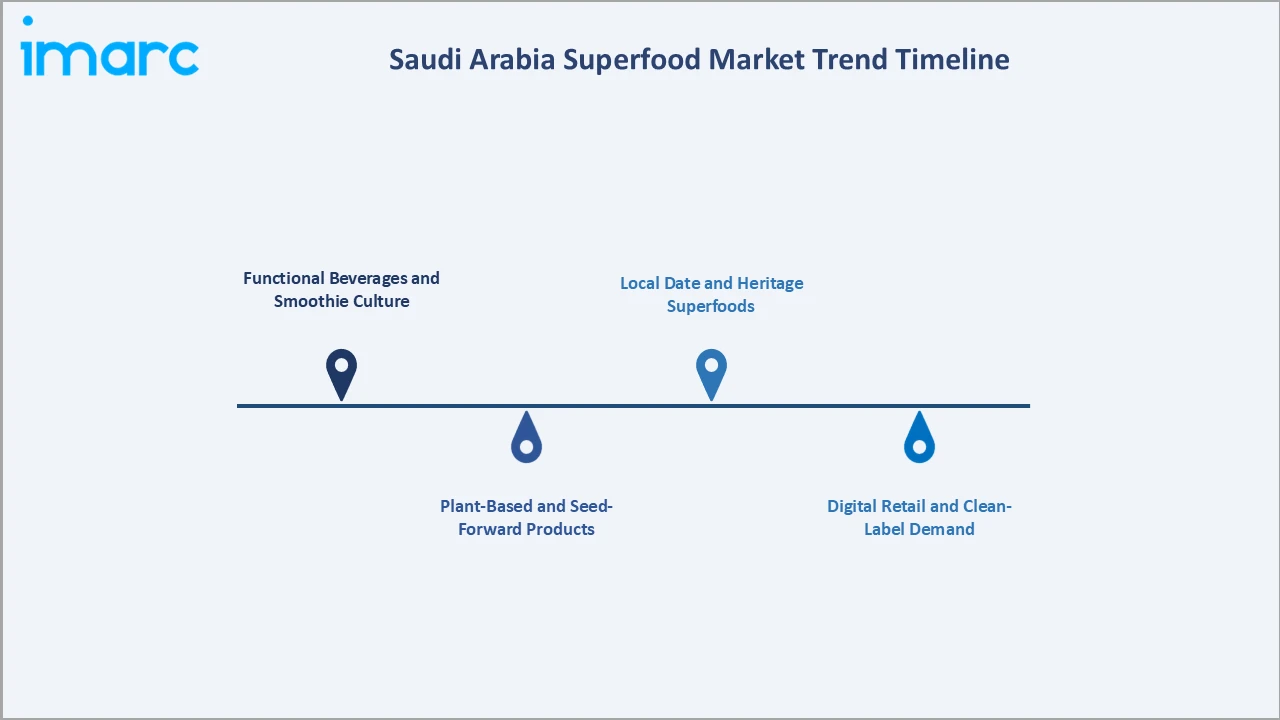
1. Functional Beverages and Smoothie Culture
Superfood beverages lead application demand at 29.5% in 2025. Cold-pressed juices, smoothie bowls, and fortified drinks featuring chia, matcha, and berries suit the climate and appeal to time-pressed urban consumers seeking convenient nutrition.
2. Plant-Based and Seed-Forward Products
Grains and seeds are the fastest-growing product type at roughly 5.1% CAGR. Rising vegan and flexitarian interest, alongside a growing number of plant-based cafes in major cities, is normalizing quinoa, oats, and flaxseed in everyday diets.
3. Local Date and Heritage Superfoods
Saudi brands are repositioning dates, camel milk, and regional herbs as premium superfoods. This blends cultural familiarity with modern wellness messaging, giving domestic players a differentiated, locally sourced value proposition.
4. Digital Retail and Clean-Label Demand
Online sales are expanding rapidly as consumers scan labels for organic, no-preservative, and high-protein claims. Mandatory nutrition labelling under SFDA rules accelerates the shift toward transparent, clean-label superfood products.
Industry Value Chain Analysis
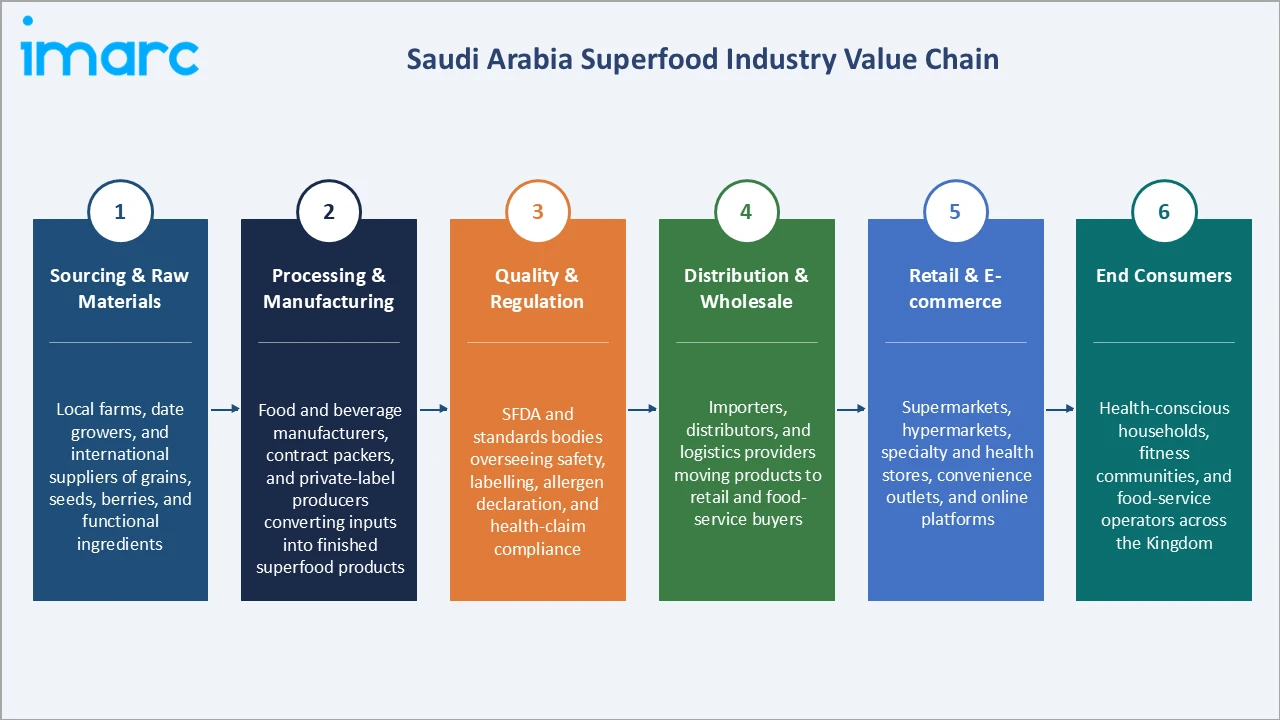
Saudi Arabia's superfood value chain runs from global and local ingredient sourcing through processing, regulatory compliance, multi-tier distribution, and end-consumer retail across both offline and online channels. Understanding each stage clarifies where value is created and where margins are captured.
|
Stage |
Key Participants |
|
Sourcing & Raw Materials |
Local farms, date growers, and international suppliers of grains, seeds, berries, and functional ingredients |
|
Processing & Manufacturing |
Food and beverage manufacturers, contract packers, and private-label producers converting inputs into finished superfood products |
|
Quality & Regulation |
SFDA and standards bodies overseeing safety, labelling, allergen declaration, and health-claim compliance |
|
Distribution & Wholesale |
Importers, distributors, and logistics providers moving products to retail and food-service buyers |
|
Retail & E-commerce |
Supermarkets, hypermarkets, specialty and health stores, convenience outlets, and online platforms |
|
End Consumers |
Health-conscious households, fitness communities, and food-service operators across the Kingdom |
Value flows downstream from sourcing to the consumer, with regulation acting as a gatekeeper at every stage. As direct-to-consumer online channels grow, traditional importer and distributor margins face pressure, encouraging brands to shorten the chain and build closer consumer relationships.
Technology Landscape in the Saudi Arabia Superfood Industry
Ingredient and Formulation Innovation
Manufacturers increasingly use cold-press extraction, freeze-drying, and micro-encapsulation to preserve nutrients in beverages and supplements. These techniques protect antioxidants and omega-3 content, extending shelf life in the Kingdom's warm climate while retaining functional benefits.
Fortification and Functional Nutrition
Fortifying everyday foods with vitamins, probiotics, and plant proteins is a growing focus. Local leaders such as Almarai apply nutrient-profiling systems aligned with SFDA standards, embedding health classification into product development to meet rising consumer expectations.
Digital Retail and Traceability
E-commerce platforms, quick-commerce dark stores, and app-based grocery delivery are reshaping access to superfoods. Digital labelling, QR-based traceability, and AI-driven demand forecasting help brands reduce spoilage and reassure consumers about sourcing and authenticity.
Market Segmentation Analysis
The report covers following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Product Type |
Fruits |
31.8% |
2025 |
|
Application |
Beverages |
29.5% |
2025 |
|
Distribution Channel |
🔒 |
🔒 |
2025 |
|
Region |
Northern and Central Region |
38.4% |
2025 |

By Product Type
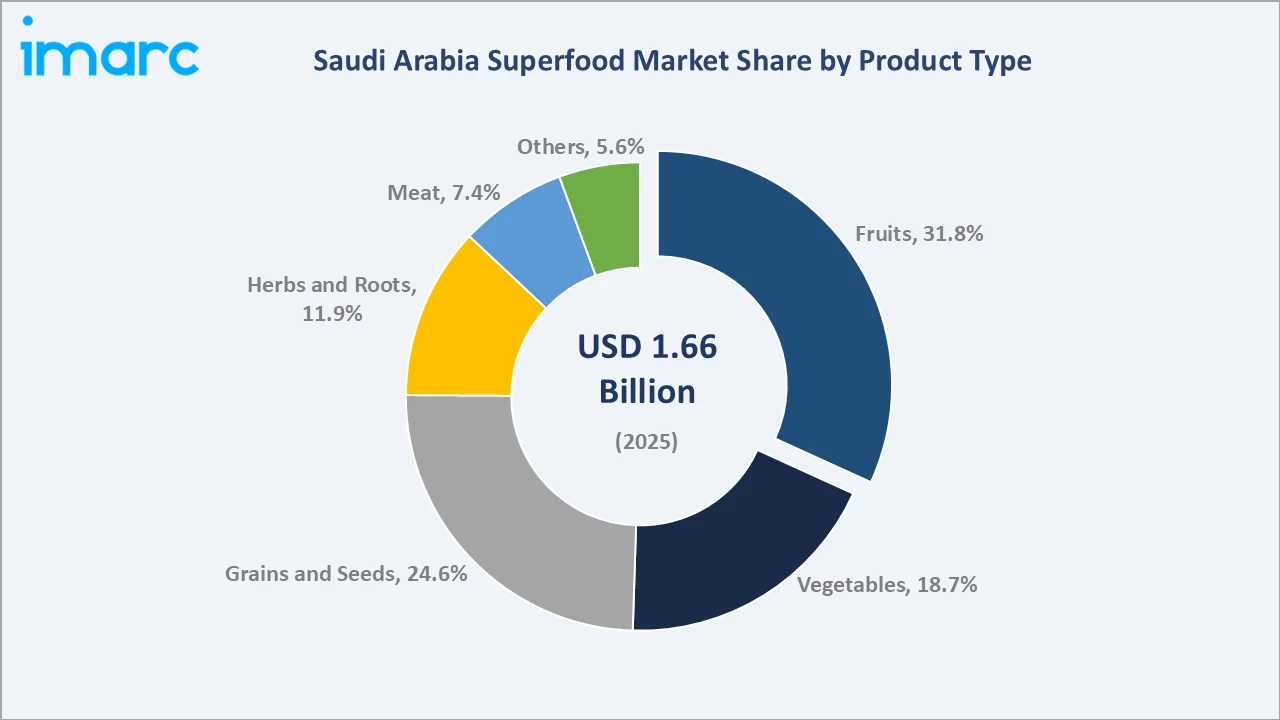
Fruits dominate at 31.8% market share in 2025. Berries, citrus, and locally grown dates anchor the segment, valued for antioxidants, fiber, and everyday versatility across snacking, beverages, and bakery uses. Familiarity and broad availability keep fruits at the center of Saudi superfood consumption.
To access detailed market analysis, Request Sample
Grains and seeds follow at 24.6% and grow fastest at roughly 5.1% CAGR, propelled by chia, quinoa, oats, and flaxseed demand tied to plant protein and gut health. Vegetables hold 18.7%, herbs and roots 11.9%, and meat 7.4%, while other superfoods account for 5.6% of the 2025 market.
By Application
Beverages lead applications at 29.5% in 2025. Smoothies, cold-pressed juices, and fortified functional drinks align with a hot climate and on-the-go lifestyles, making beverages the most accessible entry point for superfood consumption among younger Saudis.
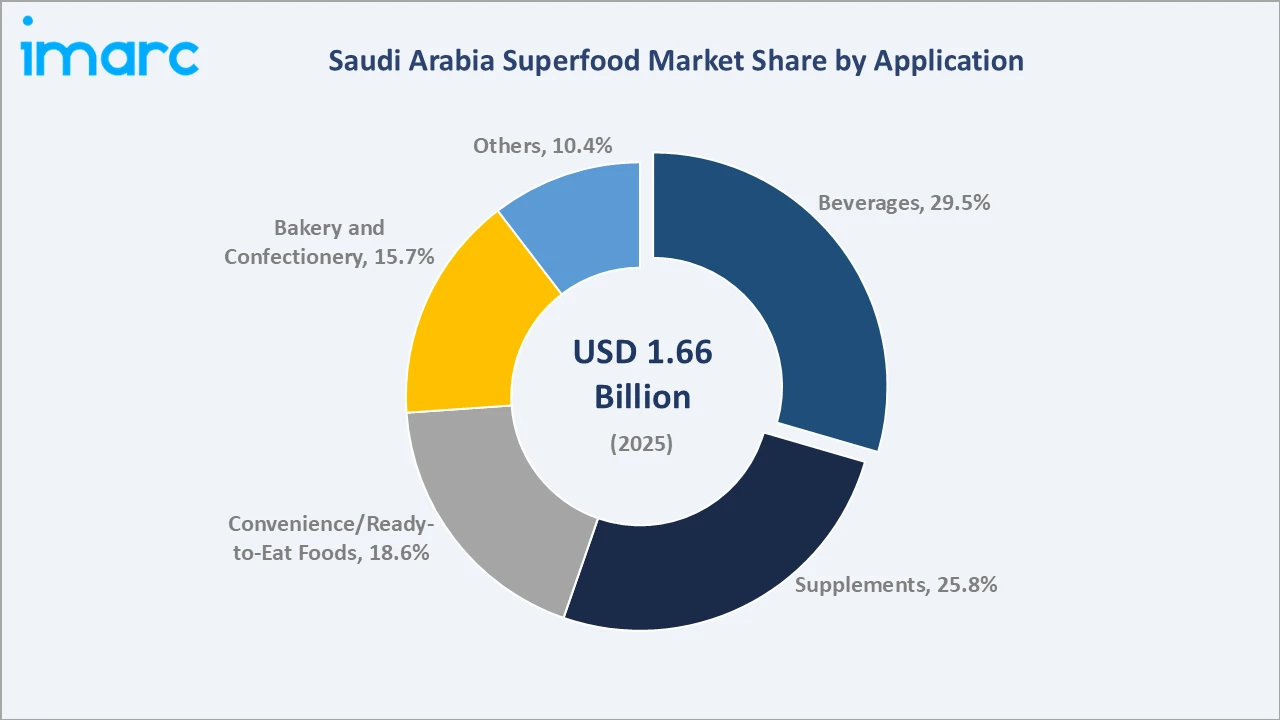
Supplements hold 25.8%, reflecting demand for capsules, powders, and protein blends targeting immunity and fitness goals. Convenience and ready-to-eat foods account for 18.6%, bakery and confectionery for 15.7%, and other applications for 10.4%, underscoring how superfoods now span the full Saudi food basket.
Regional Market Insights
|
Region |
Share 2025 |
Key Characteristics |
|
Northern & Central Region |
38.4% |
Highest income and retail density around Riyadh; large young professional base; strong e-commerce adoption and premium superfood demand |
|
Western Region |
29.1% |
Tourism and pilgrimage traffic around Jeddah, Makkah, and Madinah; hospitality demand; growing wellness and specialty retail presence |
|
Eastern Region |
20.3% |
Affluent industrial workforce and expatriate communities; strong hypermarket networks; steady demand for functional and imported superfoods |
|
Southern Region |
12.2% |
Emerging health awareness and infrastructure development; gradual retail modernization supporting rising superfood accessibility |
The Northern and Central Region leads at 38.4% in 2025, reflecting Riyadh's role as the economic capital with the highest concentration of affluent, health-aware consumers and modern retail. Population growth and rising incomes compound demand for premium superfood products.
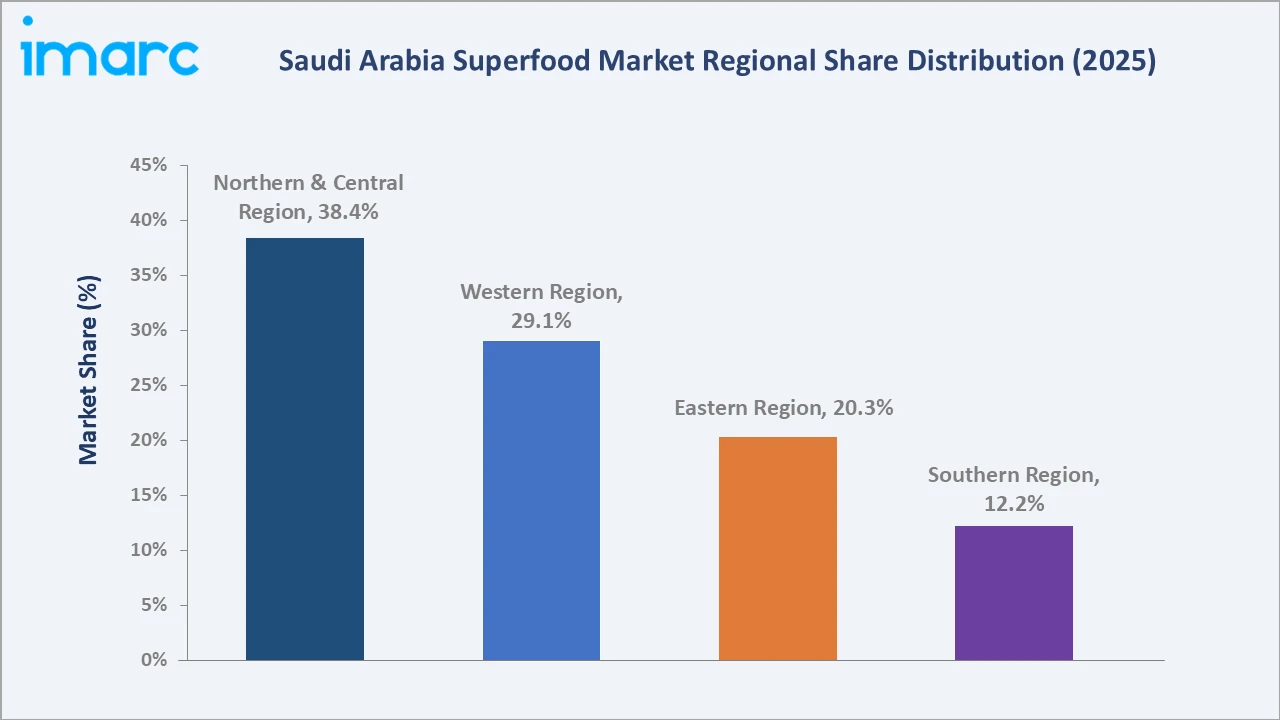
The Western Region follows at 29.1%, supported by year-round pilgrimage and tourism traffic that lifts food-service and retail demand. The Eastern Region holds 20.3% on the strength of its industrial economy and expatriate base, while the Southern Region accounts for 12.2% as awareness and retail infrastructure steadily expand.
Competitive Landscape
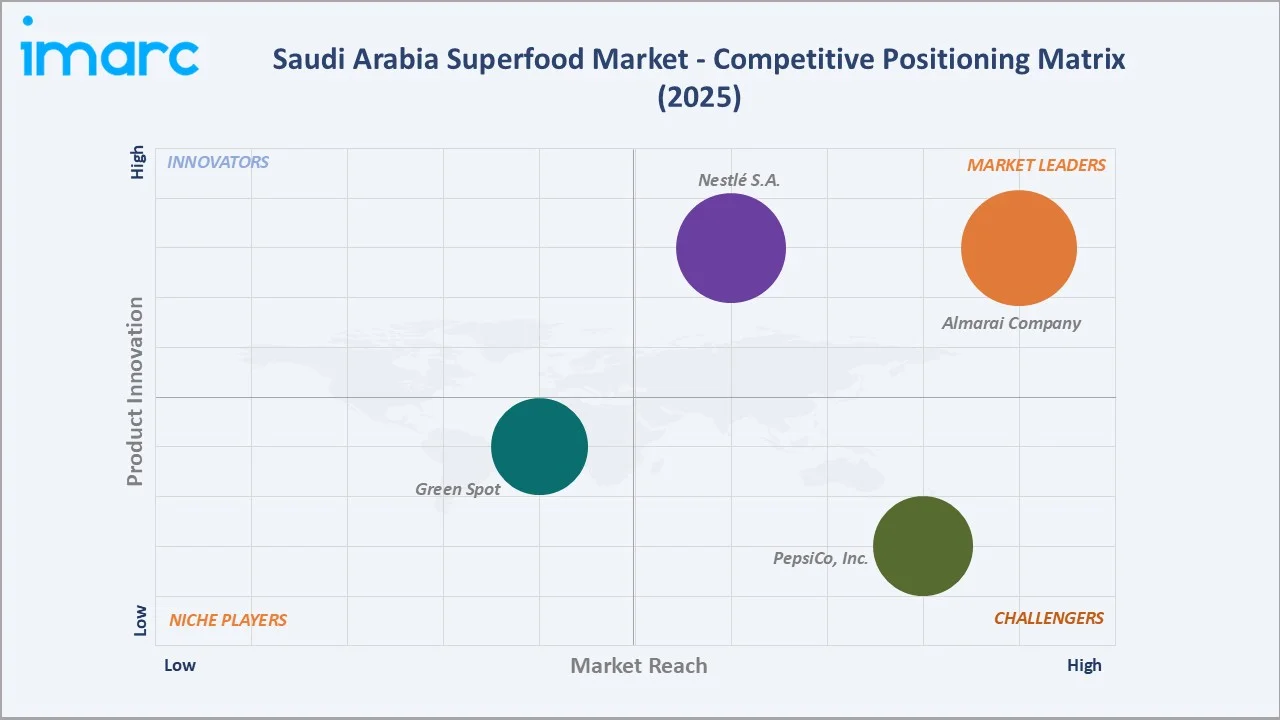
The Saudi superfood market is moderately fragmented. Large diversified food companies lead through scale and distribution, while specialized health-food brands and local start-ups compete on authenticity, provenance, and niche functional positioning.
|
Company Name |
Brand / Product Line |
Market Position |
Core Strength |
|
Almarai Company |
Farm's Select |
Market Leader |
World-class vertically integrated supply chain, a strict quality control protocol, a deep alignment with Saudi Vision 2030 for national food security |
|
Nestlé S.A. |
Nestlé Health Science (Garden of Life, Pure Encapsulations) |
Market Leader |
Science-backed nutrition, heavy local infrastructure investment, and targeted premiumization tailored to the health-conscious, young GCC demographic |
|
PepsiCo, Inc. |
Quaker |
Strong Challenger |
R&D investment tailored to local agricultural crops, and functional, low-calorie portfolio expansions that align with Saudi Vision 2030 |
|
Green Spot |
Natureland, Born Winner, Clearspring (Retailer) |
Niche Player |
Kingdom's first dedicated healthy marketplace, offering a highly curated selection of organic, keto, sugar-free, and gluten-free products |
Competition is bifurcated. Global and regional majors dominate mainstream retail through fortified mainstream products, while agile local brands lead in date-based snacks, seed mixes, and premium wellness cafes, using Saudi provenance as a differentiator.
Key Company Profiles
Almarai Company
Almarai is the largest food and beverage manufacturer in the MENA region and the leading local player in health-oriented nutrition. The company utilizes a nutrient profiling system that aligns with Saudi Food and Drug Authority (SFDA) standards to ensure premium nutritional value.
- Product Portfolio: Farm's Select juice blends, including super beetroot, super pomegranate, super orange, super grapes and berries, and super pineapple, among others.
- Strategic Focus: Farm-to-table quality, local sourcing, and expansion of nutritious, health-positioned product categories across the GCC.
Nestlé S.A.
Nestlé is a global nutrition, health, and wellness leader with a long-standing Saudi presence. Its portfolio spans fortified beverages, cereals, and health-science nutrition products distributed widely across the Kingdom.
- Product Portfolio: Nestlé Health Science certified organic, non-GMO, and raw whole-food superfood powders, vitamins, and protein supplements.
- Strategic Focus: Localized manufacturing, regional exports, and expansion of science-based functional nutrition.
PepsiCo, Inc.
PepsiCo holds a strong Saudi position through its Quaker and beverage portfolios. Its pep+ strategy prioritizes healthier formulations, positioning oats, grains, and lower-sugar drinks within the wellness trend.
- Product Portfolio: Quaker supergrain-based hot cereals, oats, and granolas.
- Strategic Focus: Portfolio reformulation, oats and grain-based nutrition, and convenient functional snacking.
Market Concentration Analysis
The Saudi superfood market is moderately concentrated at the top and fragmented below it. A handful of large diversified players, led by Almarai, Nestlé, and PepsiCo, hold significant combined share in mainstream retail through scale, distribution, and marketing reach.
Below the leaders, the market is highly fragmented. Numerous local start-ups, health-food specialists, and imported niche brands compete across date snacks, seed mixes, and functional beverages. No single brand dominates the specialty segment, keeping competitive intensity high.
Consolidation is gradual. Global manufacturers pursue local production and distribution agreements, while local champions expand health portfolios organically and through partnerships, steadily reshaping the competitive structure toward integrated, nutrition-focused players.
Investment & Growth Opportunities
Fastest Growing Segments
Grains and seeds (~5.1% CAGR), supplements (~5.0%), and functional beverages (~4.6%) represent the highest-growth vectors through 2034. Plant protein, immunity support, and convenient nutrition anchor demand, offering attractive margins for innovators.
Emerging Opportunities
Vision 2030 food-security incentives support local cultivation of dates, herbs, and greenhouse crops, reducing import dependence. Domestic value-added processing could position Saudi Arabia as a regional superfood hub serving GCC markets.
Investment Themes
- Local Superfood Production: Investing in date-based ingredients, greenhouse farming, and processing capacity to cut import reliance and capture provenance value.
- Digital Health Retail: Building online and quick-commerce platforms that pair superfood curation with nutrition content and subscription models.
- Functional Product R&D: Developing fortified beverages, supplements, and clean-label snacks tailored to Saudi taste and health priorities.
Future Market Outlook (2026-2034)
The Saudi superfood market is forecast to expand from USD 1.66 Billion in 2025 to USD 1.73 Billion in 2026, and reaching USD 2.46 Billion by 2034 at a CAGR of 4.22%. The USD 2.04 Billion milestone expected in 2030 will be shaped by deepening health awareness, functional-product innovation, and Vision 2030 wellness reforms.
Three forces anchor the trajectory. A persistent chronic-disease burden sustains preventive-nutrition demand; a young, digital population accelerates trend adoption; and government nutrition policy keeps steering diets toward healthier, cleaner-label choices. Local sourcing and e-commerce will increasingly define competitive advantage.
Research Methodology
Primary Research
Primary research comprised structured interviews with food and beverage manufacturers, superfood importers and distributors, health-store and supermarket managers, and nutrition specialists across Riyadh, Jeddah, and Dammam, capturing pricing, demand, and channel dynamics.
Secondary Research
Secondary research drew on GASTAT health and nutrition statistics, SFDA regulatory publications, Saudi Central Bank (SAMA) e-commerce data, Vision 2030 program documentation, and company annual and sustainability reports, cross-referenced for consistency and reliability.
Forecasting Models
Market estimates combine bottom-up demand modelling by product type, application, and region with top-down validation against national consumption and retail data. Forecasts incorporate health-trend adoption curves, income growth, and e-commerce penetration.
Saudi Arabia Superfood Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report | Exploration of Historical and Forecast Trends, Industry Catalysts and Challenges, Segment-Wise Historical and Predictive Market Assessment:
|
| Product Types Covered | Fruits, Vegetables, Grains and Seeds, Herbs and Roots, Meat, Others |
| Applications Covered | Bakery and Confectionery, Beverages, Supplements, Convenience/Ready-to-Eat Foods, Others |
| Distribution Channels Covered | Supermarkets and Hypermarkets, Convenience Stores, Specialty Stores, Independent Small Grocery Stores, Online Sales, Others |
| Regions Covered | Northern and Central Region, Western Region, Eastern Region, Southern Region |
| Companies Covered | Almarai Company, Nestlé S.A., PepsiCo, Inc., Green Spot, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Saudi Arabia superfood market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Saudi Arabia superfood market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Saudi Arabia superfood industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Saudi Arabia Superfood Market Report
The Saudi Arabia superfood market size is estimated at USD 1.73 Billion in 2026, driven by rising health awareness, a high chronic-disease burden, and Vision 2030 wellness reforms promoting nutrient-dense diets.
The market is projected to grow at a 4.22% CAGR during 2026-2034, reaching USD 2.46 Billion by 2034, supported by functional-product innovation and expanding e-commerce access.
Fruits lead at 31.8% share in 2025, valued for antioxidants and everyday versatility, with berries, citrus, and locally grown dates anchoring consumption across the Kingdom.
Beverages lead applications at 29.5% in 2025, as smoothies, cold-pressed juices, and functional drinks suit the hot climate and busy, health-conscious urban lifestyles.
Grains and seeds grow fastest at roughly 5.1% CAGR, driven by chia, quinoa, oats, and flaxseed demand tied to plant protein and digestive-health trends.
The Northern and Central Region leads with 38.4% share in 2025, anchored by Riyadh's high incomes, retail density, and young, health-aware consumer base.
Leading players include Almarai Company, Nestlé S.A., PepsiCo, Inc., and Green Spot, alongside numerous local health-food brands and start-ups.
Vision 2030's Quality of Life Program and the SFDA Healthy Food Strategy promote balanced diets, cleaner labels, and food security, directly boosting superfood demand and local production.
Rising obesity (23.1% of adults in 2024), high diabetes rates, a young digital population, and government nutrition campaigns are the main forces driving superfood adoption.
The market is expected to reach USD 2.04 Billion by 2030, supported by deepening health awareness, functional-product innovation, and rapid growth of online grocery channels.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade