
Saudi Arabia Textile Chemicals Market Size, Share, Trends and Forecast by Fiber Type, Product Type, Application, and Region, 2026-2034
Saudi Arabia Textile Chemicals Market Size, Share, Trends & Forecast (2026-2034)
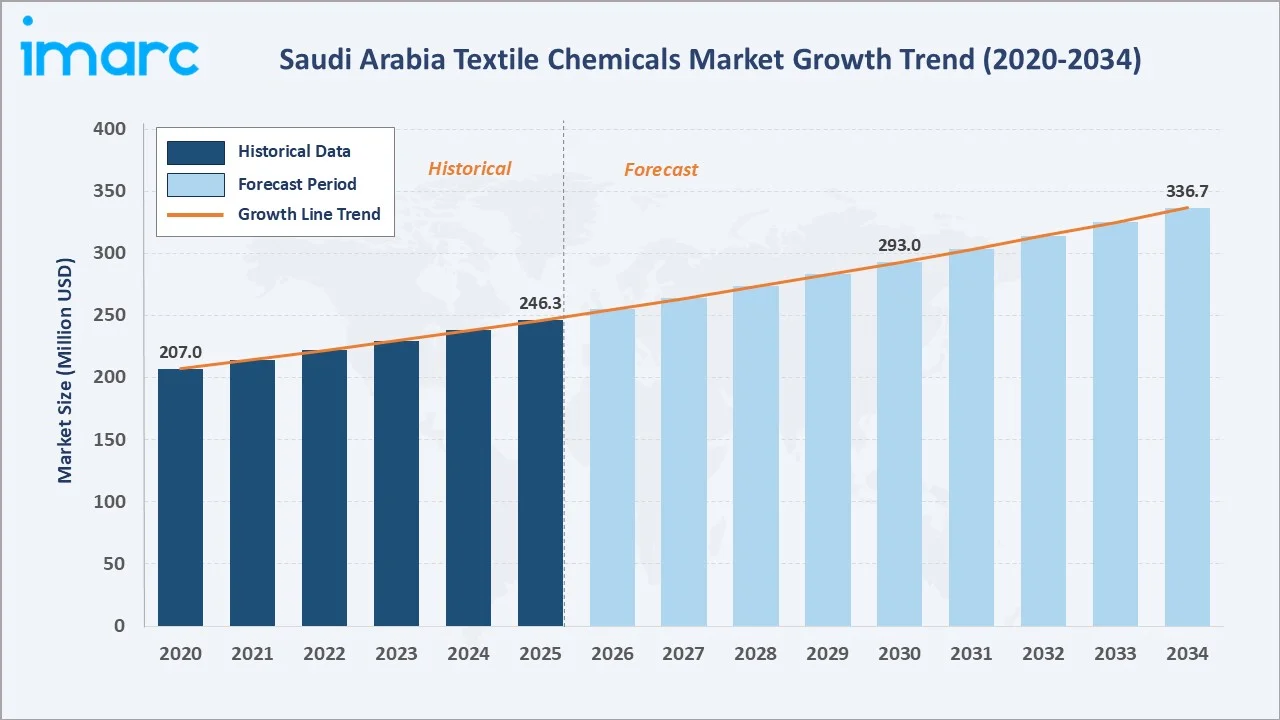
The Saudi Arabia textile chemicals market reached USD 246.3 Million in 2025 and is projected to reach USD 336.7 Million by 2034, growing at a CAGR of 3.54% during 2026-2034. The market is driven by Vision 2030's industrial localization agenda expanding domestic textile manufacturing, growing apparel and home furnishing consumption, and rising investment in technical textile manufacturing. Saudi Arabia’s urban population accounted for approximately 85.17% of the total population in 2024. This high level of urbanization is supporting the market by increasing demand for apparel, home textiles, furnishings, carpets, and other textile products across major urban centers. Synthetic fiber leads at 66.8% by fiber type, apparel dominates at 39.7% by application, and the Western region holds the largest regional share at 35.2%.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 246.3 Million |
|
Forecast Market Size (2034) |
USD 336.7 Million |
|
CAGR (2026-2034) |
3.54% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Fiber Type |
Synthetic Fiber (66.8%, 2025) |
|
Dominant Application |
Apparels (39.7%, 2025) |
|
Leading Region |
Western Region (35.2%, 2025) |
The Saudi Arabia textile chemicals market has grown from USD 207.0 million in 2020 to USD 246.3 million in 2025, reflecting steady expansion underpinned by Vision 2030's diversification of the non-oil industrial base and growing domestic demand for finished textile products. The market is projected to reach USD 293.0 million by 2030 and USD 336.7 million by 2034.
To get more information on this market, Request Sample
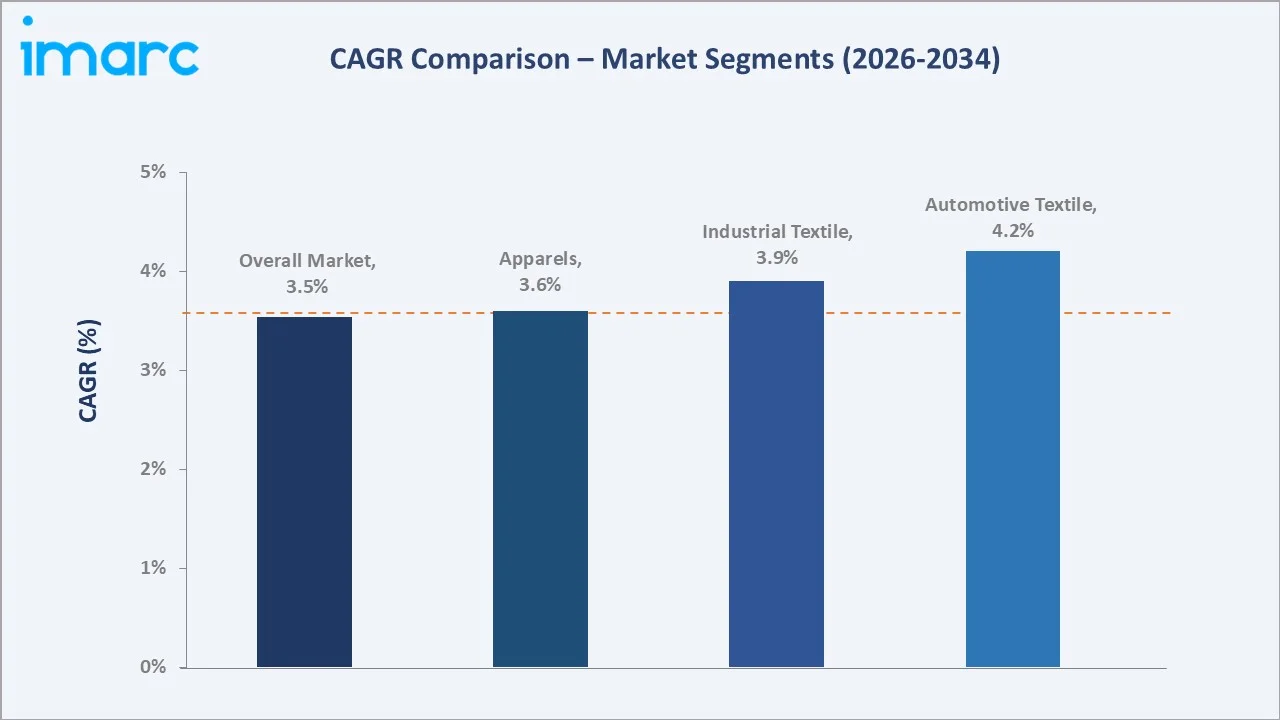
Automotive textiles grow at ~4.2% CAGR through NEOM and giga-project vehicle interior demand. Industrial textile grows at ~3.9% CAGR through technical textile manufacturing expansion. Apparels grow at ~3.6% CAGR through domestic garment production and hospitality uniform procurement.
Executive Summary
The Saudi Arabia textile chemicals market is witnessing sustained growth, anchored by the Kingdom's Vision 2030 industrial diversification agenda that has positioned textile and apparel manufacturing as a priority sector for non-oil economic development. Saudi Arabia's government is investing heavily in industrial city infrastructure, offering tax incentives and financing to attract textile manufacturers to economic zones. Synthetic fiber leads at 66.8% through polyester and nylon processing chemical demand. Apparel leads at 39.7% by application through domestic garment manufacturing demand. Western region leads regionally at 35.2%.
Key Market Insights
|
Insight |
Data |
|
Dominant Fiber Type |
Synthetic Fiber - 66.8% share (2025) |
|
Dominant Application |
Apparels - 39.7% share (2025) |
|
Leading Region |
Western Region - 35.2% share (2025) |
|
Key Growth Driver |
Vision 2030 industrial localization and textile manufacturing expansion |
|
Key Innovation Trend |
Eco-friendly and sustainable textile chemical formulations |
Key Analytical Observations Supporting the Above Data:
- Synthetic Fiber at 66.8%: Synthetic fibers dominate textile chemical consumption because polyester, nylon, acrylic, and spandex processing requires specialized chemical treatments for fiber preparation, texturizing, dyeing, and finishing that differ substantially from natural fiber processing.
- Apparels at 39.7%: Apparel manufacturing leads application demand through Saudi Arabia's domestic garment production serving both retail consumers and large institutional buyers, including government, military, hospitality, and healthcare sectors requiring uniforms and workwear.
- Western Region at 35.2%: The Western region, encompassing Jeddah and the broader Makkah/Madinah province, commands the largest regional share due to its concentration of textile and garment manufacturing facilities, proximity to Red Sea ports for chemical imports, and the largest domestic apparel retail and home furnishing market in the Kingdom.
Saudi Arabia Textile Chemicals Market Overview
The Saudi Arabia textile chemicals market encompasses chemical products used across the complete textile processing lifecycle, including fiber preparation, spinning, weaving, knitting, dyeing, printing, and finishing. Product categories include coating and sizing chemicals (starch, PVA, acrylic polymer systems), finishing agents (softeners, wrinkle-resist agents, flame retardants, antimicrobial finishes, UV absorbers), colorants and auxiliaries (reactive, disperse, vat, and acid dyes with associated leveling, fixing, and dispersing agents), surfactants (wetting, emulsifying, cleaning, and anti-foaming agents), and desizing agents (amylase enzymes, oxidative desizing systems). The market serves apparel manufacturing, home furnishing production, industrial textile fabrication, and automotive interior textile processing across Saudi Arabia's expanding manufacturing base.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
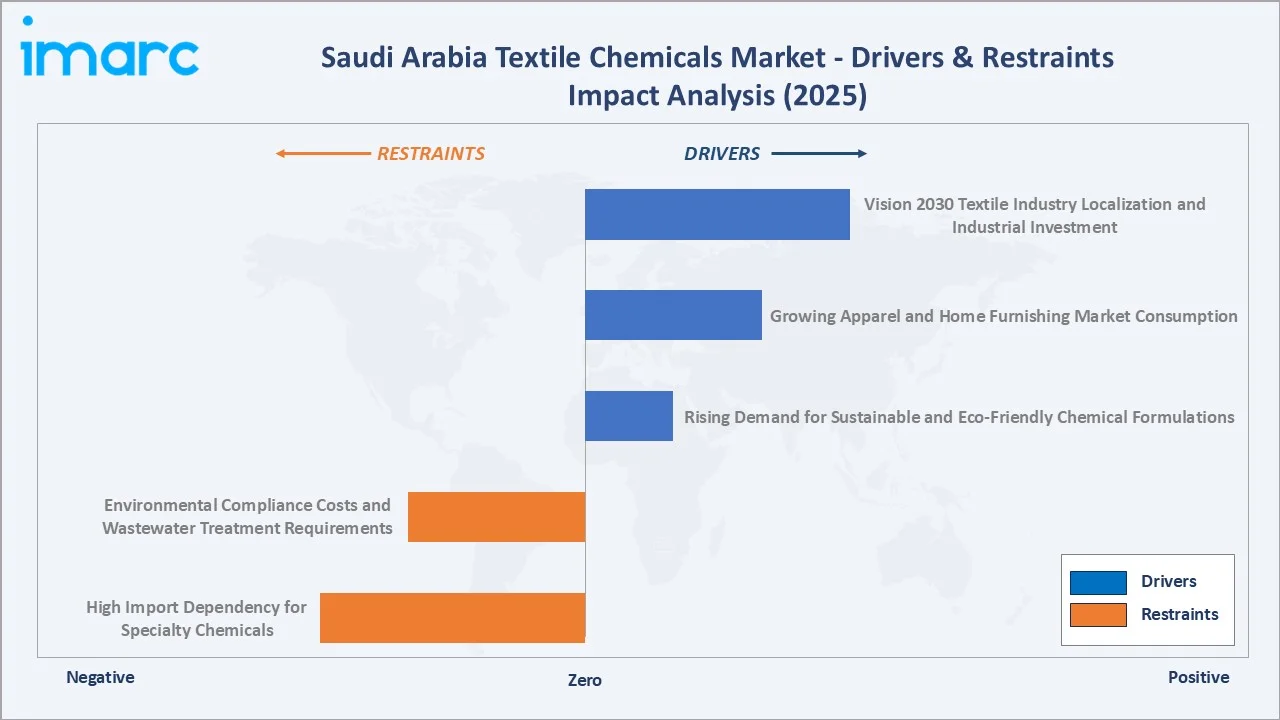
- Vision 2030 Textile Industry Localization and Industrial Investment: Saudi Arabia's Vision 2030 has identified textile and apparel manufacturing as a priority sector for industrial diversification, with the government providing SIDF financing, infrastructure at special economic zones, and content localization requirements for government procurement.
- Growing Apparel and Home Furnishing Market Consumption: As of May 2026, Saudi Arabia’s total population stands at approximately 37.59 million, of which around 32.10 million people reside in urban areas. Saudi Arabia's large and young population, rising household incomes, and expanding hospitality infrastructure are driving sustained growth in apparel and home furnishing demand. The premium hotel and resort developments under Vision 2030 mega-projects generate significant procurement of high-specification home furnishing textiles requiring advanced chemical treatments for performance, durability, and aesthetic quality that command premium pricing.
- Rising Demand for Sustainable and Eco-Friendly Chemical Formulations: Growing awareness of environmental and health impacts of conventional textile chemicals, combined with international buyer sustainability requirements and evolving regulatory standards, is driving demand for eco-certified, low-impact chemical formulations. Brands procuring from Saudi textile manufacturers increasingly require chemical compliance documentation, creating market differentiation opportunities for suppliers of certified sustainable formulations.
Market Restraints
- High Import Dependency for Specialty Chemicals: Saudi Arabia's textile chemicals market is highly dependent on imported specialty formulations from Europe, Asia, and the USA, with domestic production limited primarily to commodity surfactants and basic sizing agents. This import dependency creates supply chain vulnerability to freight disruptions, currency fluctuations, and geopolitical trade issues, while limiting the development of competitive domestic chemical manufacturing capacity.
- Environmental Compliance Costs and Wastewater Treatment Requirements: Increasingly stringent regulations on textile chemical wastewater discharge require manufacturers to invest in effluent treatment infrastructure that significantly increases operating costs. Compliance with international chemical standards for export-oriented production adds additional formulation and documentation costs.
Market Opportunities
- Technical Textile Manufacturing Development: Saudi Arabia's industrial strategy includes developing technical textile production for medical, defense, construction, and infrastructure applications that require specialized high-performance chemical treatments. In November 2025, KAST GmbH & Co. and Saudi Arabia’s KAI launched a Bahrain-based joint venture to strengthen regional production of fibreglass reinforcements and technical textiles for more durable and sustainable construction.
- Domestic Chemical Blending and Formulation Capacity: Vision 2030's localization content targets create commercial opportunity for establishing domestic textile chemical blending and formulation operations in Saudi Arabia. Local production would reduce import costs, improve supply chain responsiveness, create local employment, and qualify for government procurement preferences, building a sustainable competitive advantage for operators willing to invest in Kingdom-based production.
Market Challenges
- Skilled Technical Workforce Shortage for Chemical Application: The effective application of specialty textile chemicals requires trained technical personnel with expertise in fiber chemistry, process optimization, and quality control. Saudi Arabia faces a shortage of textile chemistry professionals, requiring reliance on expatriate technical staff or international training programs, increasing operational costs and creating knowledge transfer challenges for newly established domestic textile manufacturing operations.
- Competition from Lower-Cost Regional Textile Manufacturing Hubs: Saudi Arabia's textile manufacturers compete with lower-cost production bases for regional and global apparel sourcing budgets. Maintaining chemical treatment quality while controlling production costs relative to these competitive markets is a persistent challenge that constrains the pace of Saudi textile manufacturing expansion and associated chemical demand growth.
Emerging Market Trends
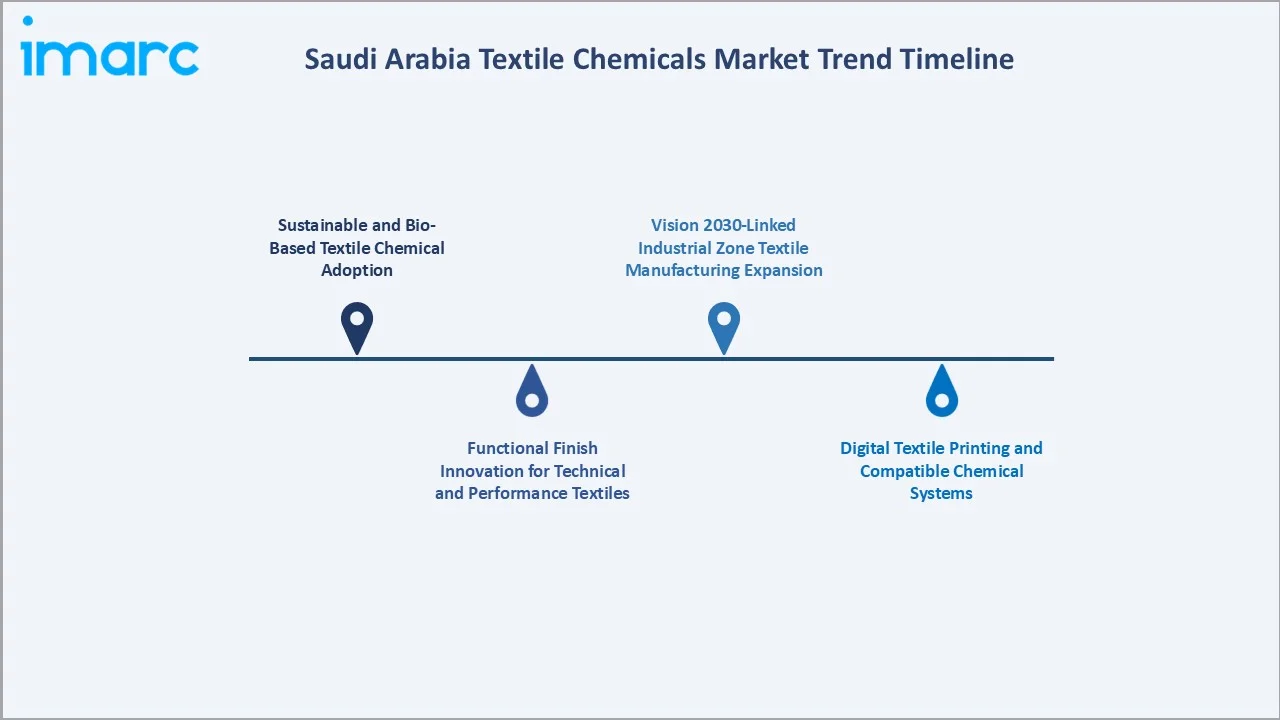
1. Sustainable and Bio-Based Textile Chemical Adoption
The shift toward sustainable textile chemistry is gaining momentum in Saudi Arabia, driven by international buyer requirements and growing domestic environmental consciousness. Bio-based sizing agents derived from modified starches and natural polymers, enzyme-based desizing and scouring systems that replace aggressive chemical processes, and waterless or reduced-water dyeing technologies are progressively entering the Saudi market. In November 2025, the Saudi Fashion Commission launched the Red Sea Seaweed Project at the Misk Global Forum, introducing a sustainable bio-textile made from Red Sea marine algae and developed into fashion garments at The Lab. The initiative supports the Commission’s efforts to promote sustainable materials and strengthen Saudi Arabia’s next-generation fashion ecosystem.
2. Functional Finish Innovation for Technical and Performance Textiles
Growing demand for performance textiles in Saudi Arabia's hospitality, healthcare, military, and industrial sectors is driving adoption of advanced functional chemical finishes. Antimicrobial finishes for hospital and hotel textiles, moisture-wicking treatments for athletic and workwear applications, flame-retardant systems for upholstery and institutional textiles, and UV-protective coatings for outdoor and automotive applications represent expanding specialty niches within the Saudi textile chemicals market. These functional finishes command significant premium pricing over commodity chemical treatments.
3. Vision 2030-Linked Industrial Zone Textile Manufacturing Expansion
The development of industrial cities is progressively creating the manufacturing infrastructure for Saudi textile industry expansion. New garment manufacturing facilities, technical textile producers, and home furnishing manufacturers establishing operations in these zones are creating clusters of chemical demand that simplify distribution logistics for international suppliers and justify the establishment of local distribution warehousing and technical service capabilities.
4. Digital Textile Printing and Compatible Chemical Systems
Digital textile printing adoption is growing in Saudi Arabia's apparel and home furnishing textile sectors, driven by on-demand production capabilities, reduced minimum order quantities, and the ability to produce complex designs without the screen preparation costs of conventional printing. Digital printing requires specialized ink formulations and pre-treatment and post-treatment chemical systems that differ from conventional printing auxiliaries, creating a new specialty chemical sub-segment with growing Saudi market application.
Industry Value Chain Analysis
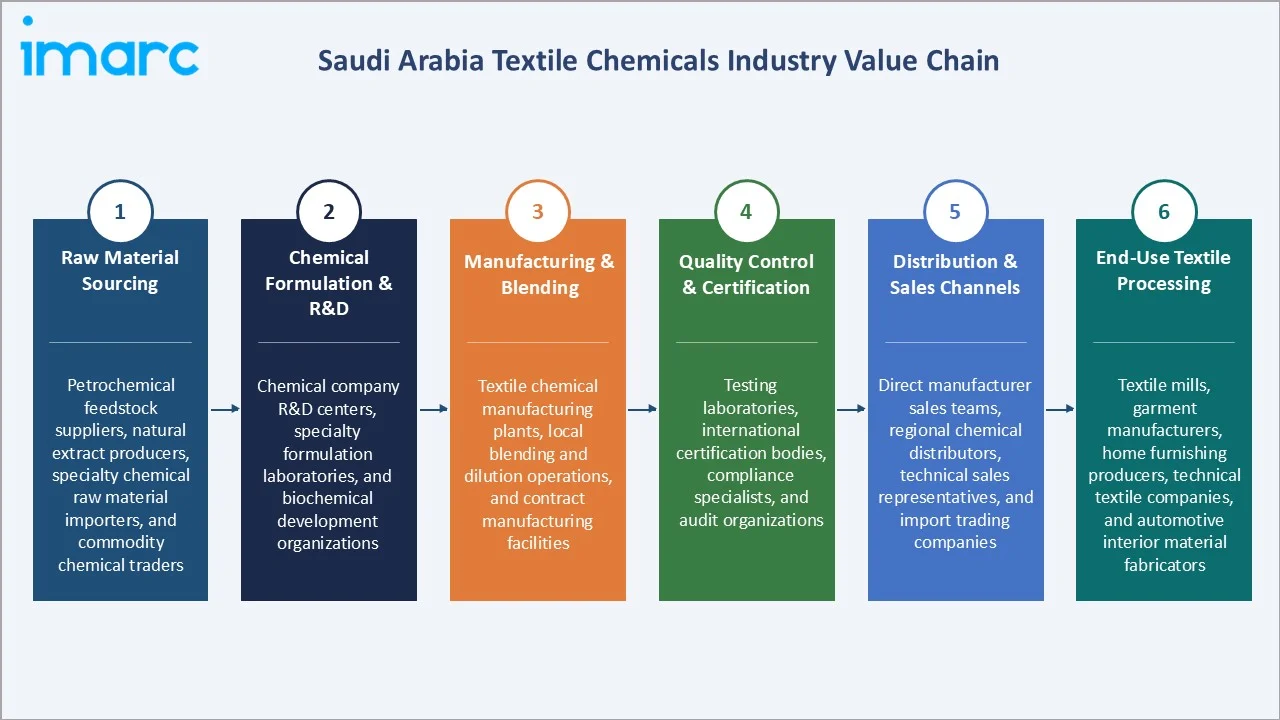
The Saudi Arabia textile chemicals value chain integrates raw material sourcing, chemical formulation and R&D, manufacturing and blending, quality control and certification, distribution and sales channels, and end-use textile processing across fiber preparation, dyeing, printing, and finishing operations.
|
Stage |
Key Participants |
|
Raw Material Sourcing |
Petrochemical feedstock suppliers, natural extract producers, specialty chemical raw material importers, and commodity chemical traders. |
|
Chemical Formulation & R&D |
Chemical company R&D centers, specialty formulation laboratories, and biochemical development organizations. |
|
Manufacturing & Blending |
Textile chemical manufacturing plants, local blending and dilution operations, and contract manufacturing facilities. |
|
Quality Control & Certification |
Testing laboratories, international certification bodies, compliance specialists, and audit organizations. |
|
Distribution & Sales Channels |
Direct manufacturer sales teams, regional chemical distributors, technical sales representatives, and import trading companies. |
|
End-Use Textile Processing |
Textile mills, garment manufacturers, home furnishing producers, technical textile companies, and automotive interior material fabricators. |
Chemical formulation and R&D represent the highest value-added stage in the Saudi Arabia textile chemicals value chain, as innovative formulations that improve textile performance, reduce environmental impact, and simplify processing operations command premium pricing and create barriers to competitive substitution. Leading suppliers invest substantially in formulation R&D that delivers measurable performance advantages, building long-term customer relationships based on technical value creation rather than commodity pricing.
Technology Landscape in the Saudi Arabia Textile Chemicals Industry
Advanced Chemical Finishing Technology
Modern textile chemical finishing technology is advancing rapidly in performance, sustainability, and process efficiency dimensions relevant to the Saudi market. Nanotechnology-enabled finishes that deliver antimicrobial, UV-protective, and water-repellent properties at lower application volumes are gaining commercial adoption. Plasma and ultrasonic treatment technologies that can replace chemical pre-treatment steps are emerging as efficiency-improving alternatives. Low-temperature and low-liquor-ratio chemical processing systems reduce energy and water consumption, directly addressing Saudi Arabia's strategic interest in resource efficiency under its Vision 2030 environmental sustainability commitments.
Digital Process Control and Industry 4.0 Integration
Digital process control systems integrating IoT sensors, AI-driven recipe optimization, and automated chemical dispensing are improving textile chemical application consistency and efficiency in advanced Saudi textile facilities. Automated color management systems using spectrophotometric measurement and AI recipe formulation are reducing dye and chemical waste while improving color consistency across production runs. These digital manufacturing capabilities are increasingly required for quality assurance in export-oriented production and for Saudi Aramco and government procurement technical textile specifications.
Eco-Chemistry and Green Formulation Technology
The development of environmentally benign textile chemical formulations using renewable raw materials, reduced hazardous substance profiles, and closed-loop recyclability is the defining technology transition shaping the global textile chemicals industry. In Saudi Arabia, this trend is driven by regulatory evolution and international buyer requirements.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Fiber Type |
Synthetic Fiber |
66.8% |
2025 |
|
Product Type |
🔒 |
🔒 |
2025 |
|
Application |
Apparels |
39.7% |
2025 |
|
Region |
Western Region |
35.2% |
2025 |

By Fiber Type
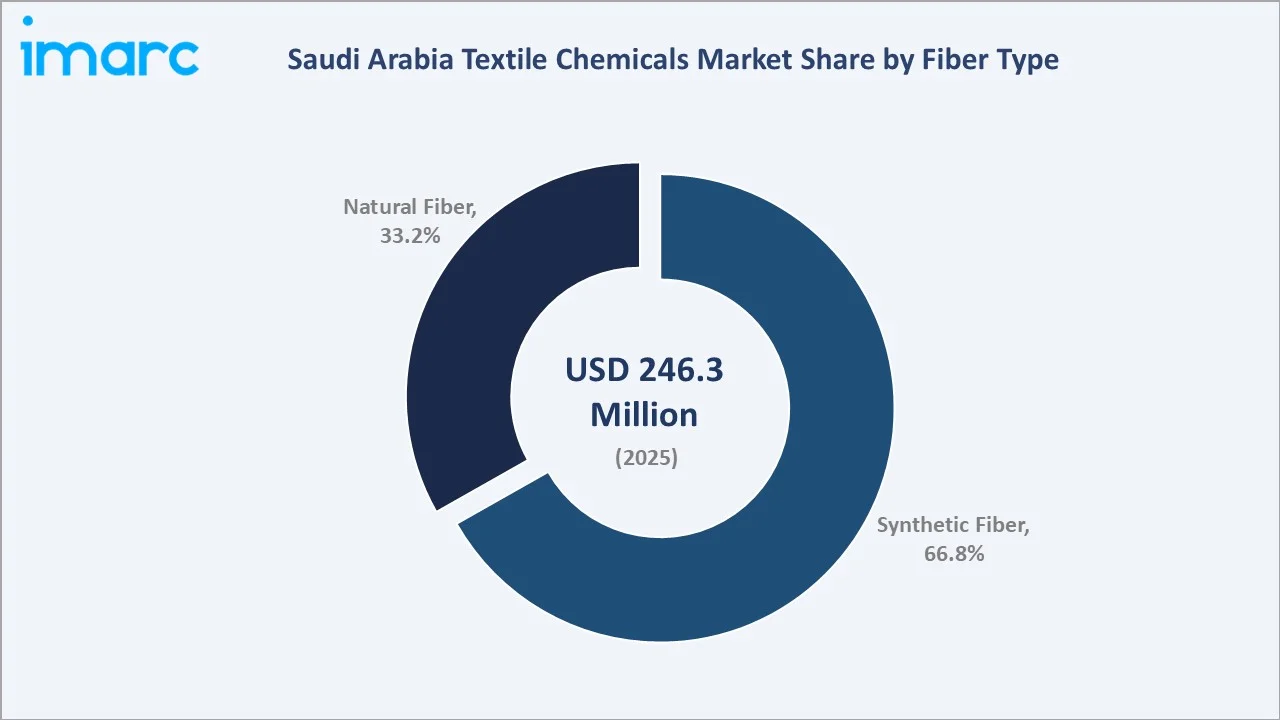
Synthetic fiber leads at 66.8% (2025), driven by the dominant use of polyester, nylon, and blended synthetic fabrics in Saudi Arabia's apparel, home furnishing, and technical textile manufacturing operations that require specialized dyeing, finishing, and performance chemical treatment systems.
To access detailed market analysis, Request Sample
Natural fiber at 33.2% reflects the continued use of cotton, wool, and natural fiber blends in premium apparel, traditional Saudi thobes, and luxury home furnishing textiles where natural fiber aesthetics and comfort properties are preferred. Natural fiber processing requires distinct chemical systems for scouring, bleaching, mercerizing, and reactive dyeing that represent a technically specialized and competitively differentiated sub-market for textile chemical suppliers serving Saudi manufacturers.
By Application
Apparels lead at 39.7% (2025), through domestic garment manufacturing serving retail, institutional uniform, and workwear markets, supported by Vision 2030's localization incentives and government procurement requirements for Saudi-made textile products.
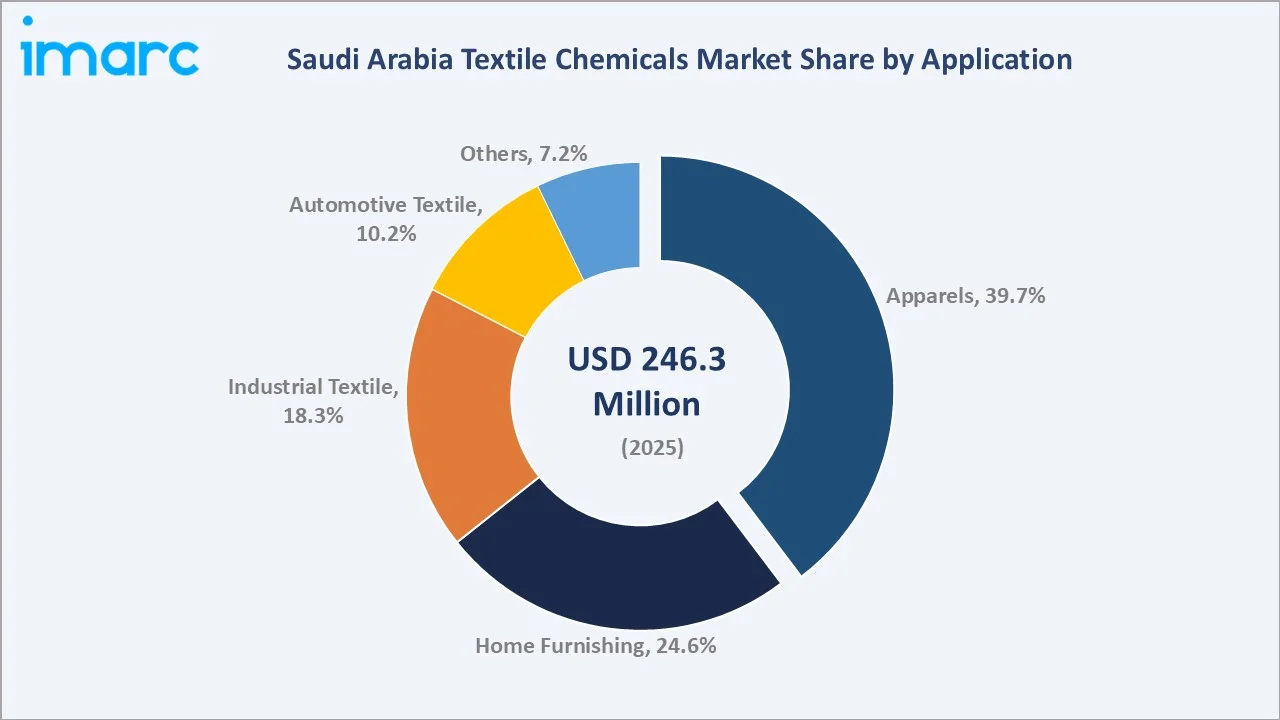
Home furnishing at 24.6% reflects growing demand from Vision 2030 hospitality and real estate mega-projects for performance-treated home textiles in hotels, resorts, and luxury residential developments. Industrial textile at 18.3% serves construction, geotextile, medical, and filtration applications. Automotive textile at 10.2% is the fastest-growing segment at ~4.2% CAGR through vehicle interior fabric demand.
Regional Market Insights
|
Region |
Share (2025) |
Key Saudi Arabia Textile Chemicals Market Drivers & Characteristics |
|
Western Region |
35.2% |
Reflecting the concentration of textile and garment manufacturing facilities in Jeddah, proximity to Red Sea ports for chemical imports, and the largest domestic apparel and home furnishing retail market in the Kingdom. |
|
Northern & Central Region |
31.9% |
Reflecting Riyadh's industrial zone textile manufacturers, government procurement-linked apparel production, and the capital's concentration of administrative and commercial establishments generating institutional textile demand. |
|
Eastern Region |
21.4% |
Reflecting petrochemical feedstock availability supporting synthetic fiber processing chemical demand, industrial city textile operations in Jubail, and growing technical textile manufacturing serving the energy sector. |
|
Southern Region |
11.5% |
Reflecting smaller-scale textile manufacturing and traditional craft textile production in Asir and Jazan provinces, with growing home furnishing demand from residential development and hospitality infrastructure investment. |
The Western region's 35.2% leadership is anchored by Jeddah's established textile and garment manufacturing cluster and its strategic role as Saudi Arabia's primary commercial port, enabling efficient chemical imports. The Northern and Central region's 31.9% reflects Riyadh's growing industrial base and the concentration of government-linked textile procurement for uniforms, workwear, and institutional furnishings across the capital's large public sector employer base.
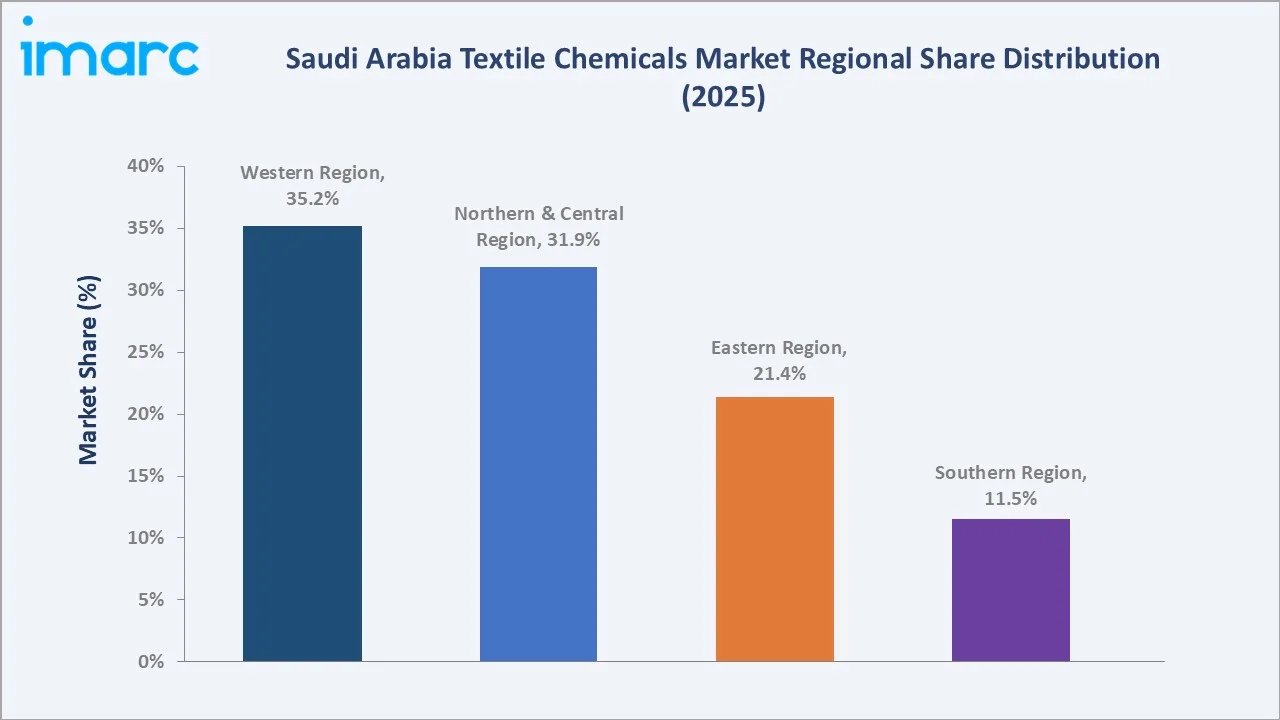
The Eastern region's 21.4% benefits from its petrochemical industrial base that provides advantaged feedstock access for synthetic fiber chemical production and creates natural demand for industrial and technical textile chemicals serving the energy sector's workwear and safety textile requirements. The Southern region at 11.5% reflects smaller but growing textile activity in Asir and Jazan provinces, where government investment in tourism and agricultural development is stimulating hospitality textile demand.
Competitive Landscape
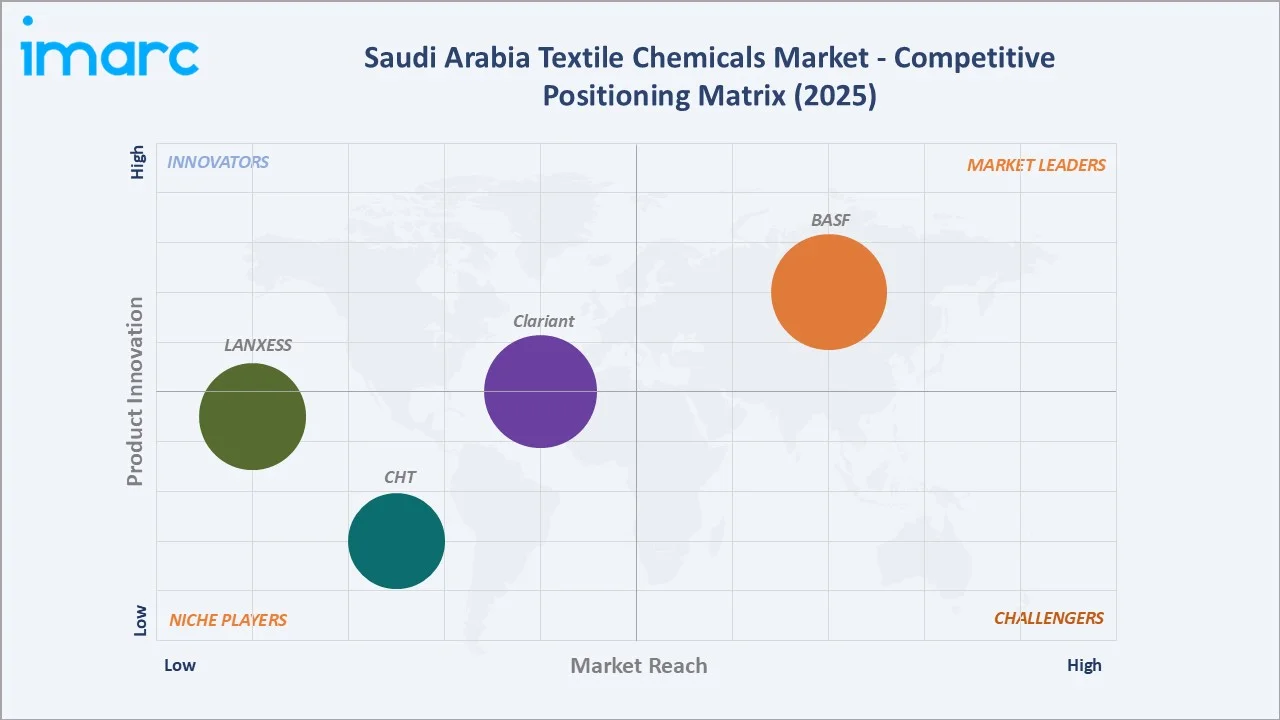
The Saudi Arabia textile chemicals market is moderately concentrated, dominated by international specialty chemical companies with established Saudi commercial operations, alongside regional distributors serving as market intermediaries. Competition is driven by technical performance differentiation, application support capabilities, eco-compliance credentials, and pricing competitiveness.
|
Company |
Key Offerings |
Market Position |
Core Strength |
|
BASF |
Ultramid Polyamide (PA) for fibers, Ultramid Ccycled, Elastollan TPU, loopamid |
Market Leader |
Operating through BASF Saudi Arabia, based in Al-Khobar, the company provides essential chemical inputs to local industries, aligning with regional manufacturing goals |
|
Clariant |
Clariant’s Nylostab S-EED |
Established Player |
Clariant operates in Saudi Arabia primarily through joint ventures focusing on masterbatches and regional polymer/petrochemical integration. |
|
LANXESS |
Silvadur |
Established Player |
The role of LANXESS in the Saudi Arabian textile chemicals market is shaped entirely by its strategic position as a specialty additives and material protection provider. |
|
CHT |
BeSo BRIGHT, BeSo COOL, BeSo DRY, BeSoFRESH |
Niche Player |
The CHT acts as a specialty chemical partner providing sustainable auxiliaries, dyeing solutions, and functional finishes that support modern regional textile manufacturing and technical fabric development. |
Companies across the competitive landscape are investing in sustainable product portfolio development, local technical service capabilities, application laboratory establishment, and eco-compliance documentation systems. The market is expected to attract increasing participation from Asian specialty chemical producers as Saudi textile manufacturing volume grows and justifies direct market investment.
Key Company Profiles
BASF
BASF, the largest chemical company, maintains a significant commercial presence in Saudi Arabia through BASF Saudi Arabia, serving the Kingdom's industrial, construction, and textile chemical markets. In textile chemicals, BASF's Textile Chemicals division provides a comprehensive portfolio spanning fiber preparation, sizing, dyeing auxiliaries, printing binders, and finishing agents for both natural and synthetic fiber processing. The company's technical application expertise and strong service capabilities position it as the benchmark reference for textile chemical quality in the Saudi market.
- Key Offerings: Ultramid Polyamide (PA) for fibers, Ultramid Ccycled, Elastollan TPU, loopamid.
- Strategic Focus: Advancing sustainable textile chemistry product registration and application development for Saudi market conditions, expanding local technical service capabilities to support growing Saudi textile manufacturing base, and developing custom formulation programs for Vision 2030 priority textile applications including technical and automotive textiles.
Clariant
Clariant, a focused specialty chemicals company, serves the Saudi Arabia textile chemicals market through its Colorants and Functional Minerals business units. Clariant's textile chemical portfolio for Saudi Arabia includes fluorescent brightening agents widely used in fabric bleaching and whitening, specialty dyeing auxiliaries for synthetic fiber processing, and functional finishing agents for performance textile applications. The company's regional technical representation provides Saudi textile manufacturers with application support and formulation optimization services.
- Key Offerings: Clariant’s Nylostab S-EED.
- Strategic Focus: Strengthening Clariant's Saudi Arabia market position through enhanced technical application support, advancing eco-compliant product registrations under regulatory standards, and developing Clariant's fluorocarbon-free functional finish portfolio for Saudi textile producers transitioning away from PFAS-based water repellent treatments.
Market Concentration Analysis
The Saudi Arabia textile chemicals market exhibits moderate concentration, with international specialty chemical leaders including BASF and Clariant collectively accounting for approximately 50-55% of total market revenues in 2025. The remaining share is distributed among regional distributors, domestic blending operations, and smaller specialty suppliers. Market concentration is expected to remain moderate through 2034, with increasing Asian chemical producer participation as Saudi textile manufacturing volume grows and creates more attractive commercial scale for direct market investment.
Investment & Growth Opportunities
Highest Growth Segments
Automotive textile chemicals (~4.2% CAGR), industrial and technical textile chemicals (~3.9% CAGR), sustainable and bio-based chemical formulations, functional finishes for hospitality and medical textiles, and digital printing chemical systems represent the highest-growth investment vectors in the Saudi Arabia textile chemicals market through 2034.
Investment Themes
- Domestic chemical blending and formulation operations: Establishing local blending facilities for textile auxiliaries qualifies for Vision 2030 content localization benefits, reduces import logistics costs, improves supply chain reliability for Saudi textile manufacturers, and positions suppliers for preferred supplier status in government textile procurement programs that increasingly favor Saudi-produced inputs.
- Sustainable chemistry portfolio development for export markets: Developing and registering compliant and eco-certified textile chemical formulations positions suppliers for growing demand from Saudi textile manufacturers targeting European and US premium brands that mandate chemical management program compliance as a supplier qualification criterion.
Future Market Outlook (2026-2034)
The Saudi Arabia textile chemicals market is projected to grow from USD 246.3 Million in 2025 to USD 336.7 Million by 2034, exhibiting a CAGR of 3.54% during 2026-2034. The market is projected to reach an anchor value of USD 293.0 Million by 2030, representing the mid-period milestone at which Vision 2030 textile manufacturing localization programs begin delivering meaningful industrial capacity additions that translate into incremental chemical demand volumes.
Three structural forces will define the Saudi Arabia textile chemicals market through 2034. First, Vision 2030's industrial diversification agenda will progressively increase domestic textile and garment manufacturing capacity. Second, the mix shift toward higher-value technical and specialty chemical formulations will support revenue growth in excess of pure volume trends. Third, sustainability compliance requirements will reshape the Saudi textile chemicals market's product portfolio composition through 2034.
Research Methodology
Primary Research
Primary research comprised in-depth interviews with textile chemical manufacturers, regional distributors, Saudi textile mill purchasing managers, technical application specialists, regulatory experts, and industry analysts. These discussions validated market size estimates, assessed demand trends across fiber type and application segments, evaluated competitive dynamics, and provided insights into regulatory developments and future market evolution in the Saudi Arabia textile chemicals market.
Secondary Research
Secondary research encompassed product certification databases, Saudi Ministry of Commerce industrial statistics, investment program reports, Vision 2030 industrial development announcements, international textile chemical company annual reports, and industry publications focused on Middle East textile and chemical markets.
Forecasting Models
Forecasting models incorporated historical textile chemicals market revenue trends, Saudi textile manufacturing capacity investment projections, application segment growth rates, fiber type consumption evolution, and regional industrial development timelines. Both top-down macro-industry and bottom-up segment-specific approaches were applied and cross-validated to ensure forecast consistency with Vision 2030 industrial development program schedules.
Saudi Arabia Textile Chemicals Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report | Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Fiber Types Covered | Natural Fiber, Synthetic Fiber |
| Product Types Covered | Coating and Sizing Chemicals, Finishing Agents, Colorants and Auxiliaries, Surfactants, Desizing Agents, Others |
| Applications Covered | Home Furnishing, Apparels, Industrial Textile, Automotive Textile, Others |
| Regions Covered | Northern and Central Region, Western Region, Eastern Region, Southern Region |
| Companies Covered | BASF, Clariant, LANXESS, CHT, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Saudi Arabia textile chemicals market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Saudi Arabia textile chemicals market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Saudi Arabia textile chemicals industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Saudi Arabia Textile Chemicals Market Report
The Saudi Arabia textile chemicals market reached USD 246.3 Million in 2025, driven by Vision 2030 industrial localization, growing apparel and home furnishing manufacturing demand, automotive textile sector expansion, and rising adoption of sustainable chemical formulations across Saudi textile processing operations.
The Saudi Arabia textile chemicals market is projected to grow at a CAGR of 3.54% during 2026-2034, sustained by Vision 2030 textile manufacturing capacity expansion, application mix shift toward higher-value technical chemicals, and sustainable formulation adoption driving premium revenue growth.
The market is projected to reach approximately USD 293.0 Million by 2030, representing the mid-period milestone at which Vision 2030 textile manufacturing localization programs deliver meaningful capacity additions and functional specialty chemical adoption expands across hospitality, automotive, and industrial textile applications.
Synthetic fiber leads with a 66.8% share in 2025, driven by the dominant use of polyester, nylon, and synthetic blends in Saudi apparel, home furnishing, and technical textile manufacturing that requires specialized dyeing, finishing, and performance chemical treatment systems for synthetic fiber substrates.
Apparels lead with a 39.7% share in 2025, through domestic garment manufacturing serving retail, institutional uniform, and workwear markets, supported by Vision 2030 localization incentives and government procurement requirements favoring Saudi-manufactured textile products.
The Western region leads with a 35.2% share in 2025, anchored by Jeddah's established textile and garment manufacturing cluster, Red Sea port accessibility for chemical imports, and the Kingdom's largest domestic apparel and home furnishing retail consumption market.
Key players include BASF, Clariant, LANXESS, and CHT, among others.
The Saudi Arabia textile chemicals market is projected to reach USD 336.7 Million by 2034, driven by continued industrial capacity expansion, application diversification into technical and automotive textile segments, and premium sustainable chemical formulation adoption aligned with international buyer eco-compliance requirements.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade