
Saudi Arabia Used Truck Market Size, Share, Trends and Forecast by Vehicle Type, Sales Channel, End User, and Region, 2026-2034
Saudi Arabia Used Truck Market Size, Share, Trends & Forecast (2026-2034)
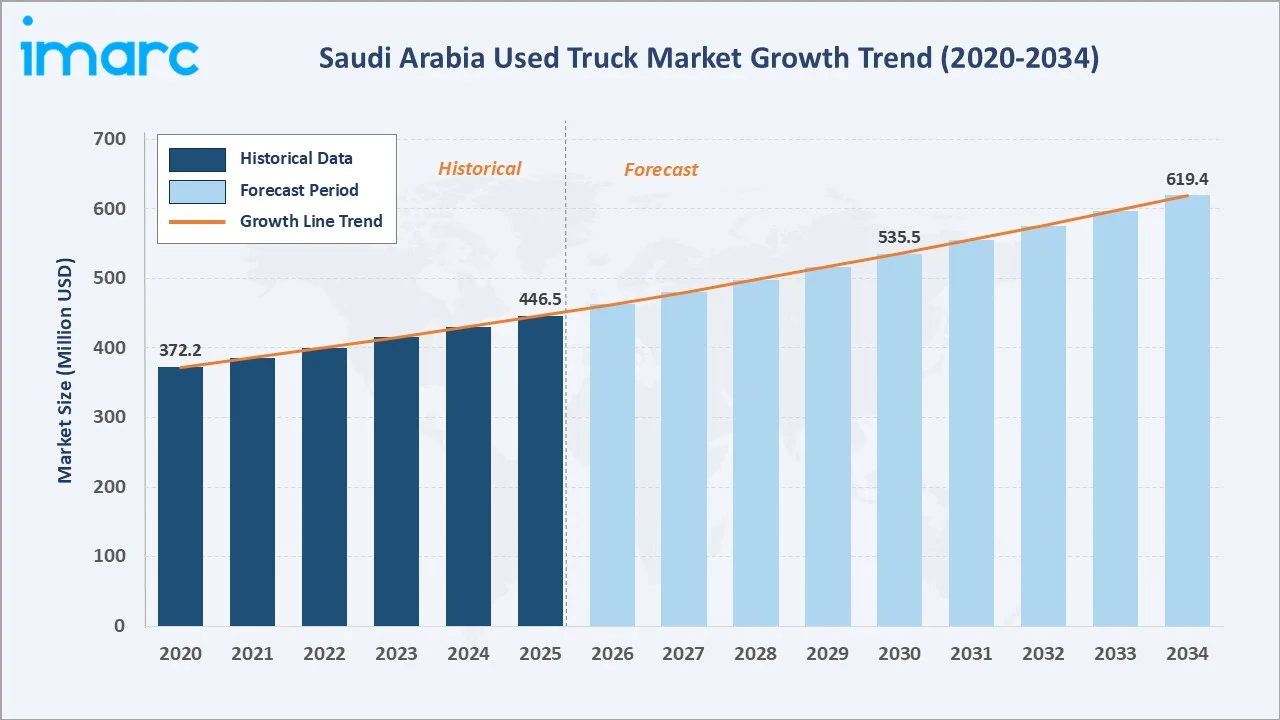
The Saudi Arabia used truck market reached USD 446.5 Million in 2025 and is projected to reach USD 619.4 Million by 2034, growing at a CAGR of 3.71% during 2026-2034. The market is driven by Vision 2030's infrastructure and construction boom, cost efficiency advantages of pre-owned trucks attracting SMEs and logistics operators, and the expanding e-commerce and last-mile delivery sector. Saudi Arabia remained the Middle East’s largest construction market in 2025, supported by Vision 2030 mega-projects, housing, transport, utilities, and industrial expansion, with active and announced projects valued at over USD 1 trillion. These mega-projects are increasing the need for heavy-duty trucks to transport construction materials, machinery, and equipment. Heavy-duty trucks lead at 46.8% by vehicle type, independent dealers dominate at 49.3% by sales channel, and the Northern and Central region commands the largest regional share at 42.5%.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 446.5 Million |
|
Forecast Market Size (2034) |
USD 619.4 Million |
|
CAGR (2026-2034) |
3.71% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Vehicle Type |
Heavy-Duty Trucks (46.8%, 2025) |
|
Dominant Sales Channel |
Independent Dealer (49.3%, 2025) |
|
Leading Region |
Northern and Central Region (42.5%, 2025) |
The Saudi Arabia used truck market has grown from USD 372.2 Million in 2020 to USD 446.5 Million in 2025, reflecting consistent growth driven by Vision 2030 construction activity, logistics sector expansion, and a well-established culture of fleet rotation among Saudi commercial vehicle operators. The market is projected to reach USD 535.5 Million by 2030 and USD 619.4 Million by 2034.
To get more information on this market, Request Sample
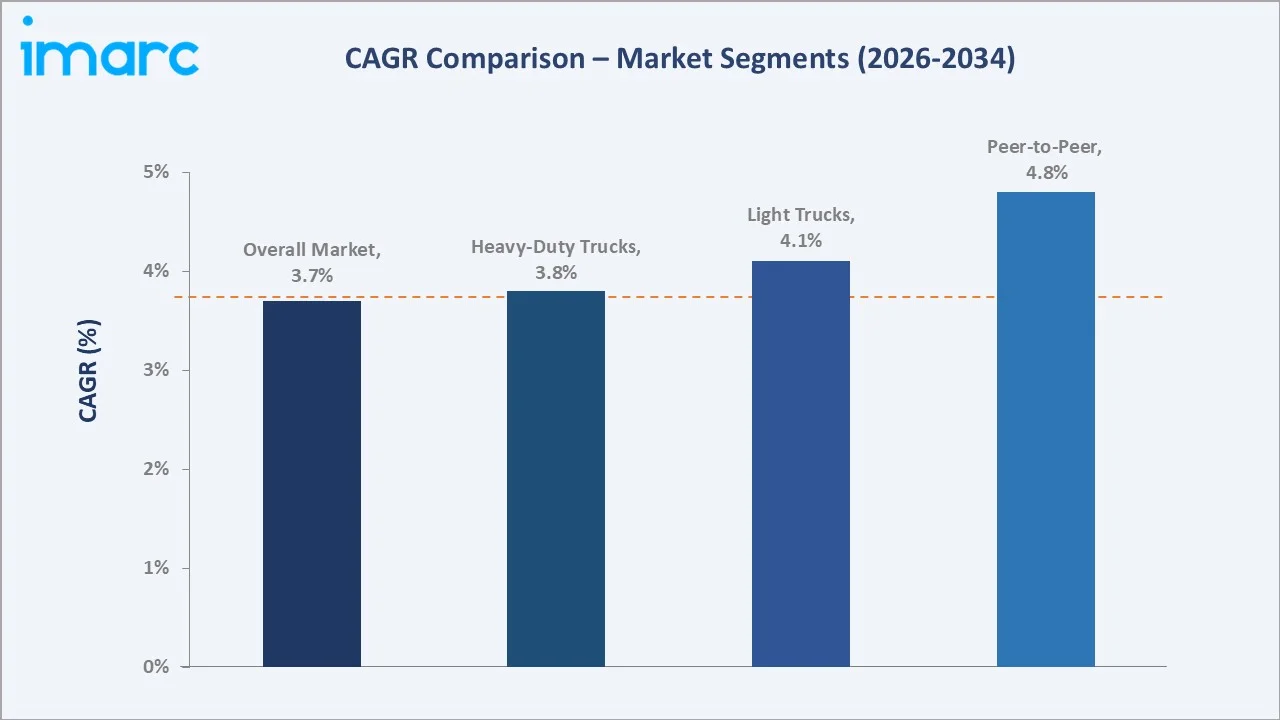
Peer-to-peer channel grows at ~4.8% CAGR through digital platform adoption and direct seller-buyer connectivity. Light trucks grow at ~4.1% CAGR through e-commerce and last-mile delivery demand. Heavy-duty trucks grow at ~3.8% CAGR through construction and logistics sector fleet rotation.
Executive Summary
The Saudi Arabia used truck market is witnessing sustained and commercially robust growth, underpinned by the Kingdom's position as the largest commercial vehicle market in the Arab world and the structural demand created by Vision 2030's unprecedented construction, logistics, and industrial development programs. Saudi Arabia's commercial trucking sector encompasses hundreds of thousands of registered trucks serving construction, oil and gas field services, general freight haulage, retail distribution, agricultural transport, and cross-border GCC trade functions.
The market for pre-owned trucks is deeply embedded in Saudi commercial fleet management culture, as fleet operators, particularly SMEs and owner-operators, systematically replace aging vehicles with younger used models rather than new trucks, creating a persistent and predictable secondary market with well-established pricing, inspection, and financing ecosystems. Independent dealers represent the backbone of the used truck market, operating extensive physical lots across Riyadh, Jeddah, Dammam, and regional centers where buyers can inspect, negotiate, and finance purchases in a single interaction. Heavy-duty trucks lead at 46.8% through construction and logistics fleet rotation demand. Independent dealer leads at 49.3% by sales channel through nationwide dealer network reach. Northern & Central region leads regionally at 42.5%.
Key Market Insights
|
Insight |
Data |
|
Dominant Vehicle Type |
Heavy-Duty Trucks - 46.8% share (2025) |
|
Dominant Sales Channel |
Independent Dealer - 49.3% share (2025) |
|
Leading Region |
Northern & Central Region - 42.5% (2025) |
|
Key Growth Driver |
Vision 2030 construction mega-project heavy truck demand |
Key Analytical Observations Supporting the Above Data:
- Heavy-Duty Trucks at 46.8%: Heavy-duty trucks dominate through the concentrated demand from construction contractors operating dump trucks, mixer trucks, flatbed trailers, and concrete pump trucks across Vision 2030 mega-project sites.
- Independent Dealer at 49.3%: Independent dealers command through their flexibility, negotiation accessibility, and extensive inventory variety that allows buyers to source specific truck configurations, years, and price points not available through franchised networks.
- Northern & Central Region at 42.5%: The Northern and Central region leads through Riyadh's concentration of large construction contractor fleets, logistics company headquarters, and wholesale trade businesses requiring regular commercial vehicle procurement.
Saudi Arabia Used Truck Market Overview
The Saudi Arabia used truck market encompasses the buying, selling, and trading of pre-owned commercial vehicles with gross vehicle weight (GVW), spanning light trucks, medium-duty trucks, and heavy-duty trucks. The market serves construction, oil and gas field services, freight transport, agricultural logistics, municipal services, and retail distribution sectors. Distribution channels include independent dealers (used vehicle lots), franchised dealer certified pre-owned programs, and peer-to-peer platforms and private sales.
Key market participants include large fleet operators disposing of aging vehicles, construction companies cycling equipment, dealer networks maintaining inventory across multiple locations, digital marketplaces facilitating P2P transactions, and financial institutions providing used vehicle financing. Vision 2030's logistics and transportation sector development targets, including creating Saudi Arabia as a global logistics hub, directly support the commercial trucking ecosystem that drives used truck market turnover.
Market Dynamics
To evaluate market opportunities, Request Sample
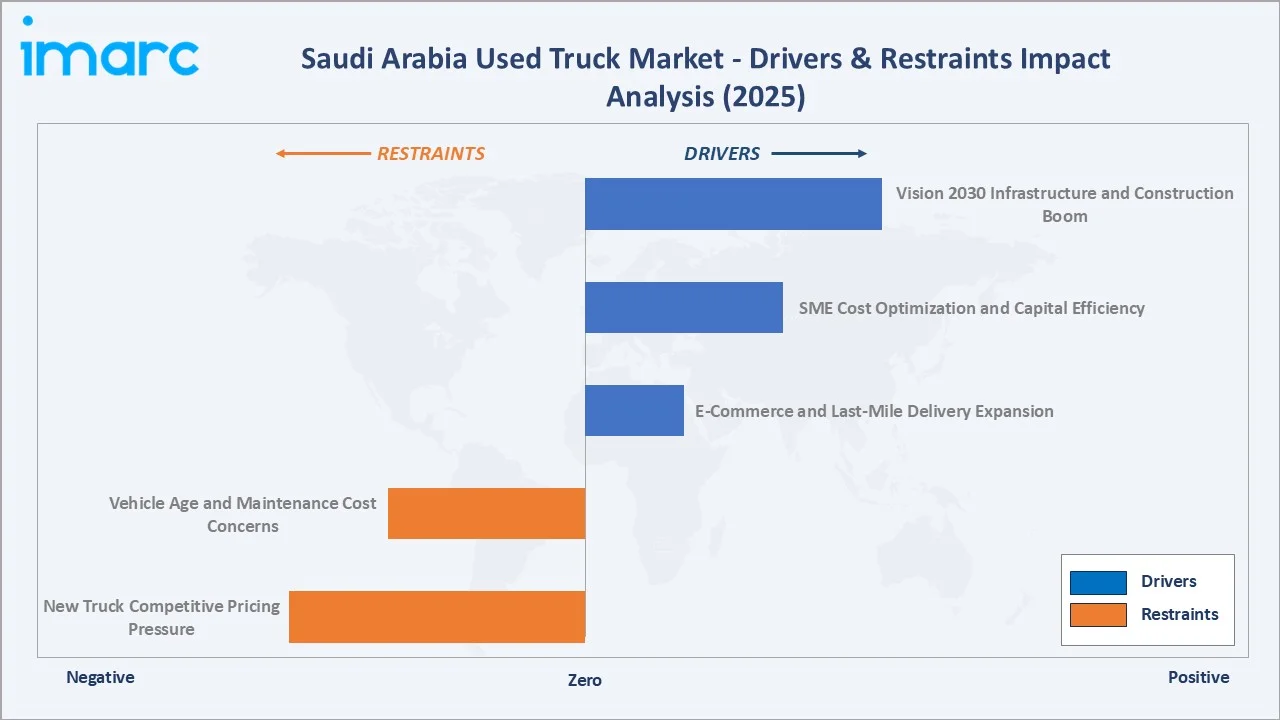
Market Drivers
- Vision 2030 Infrastructure and Construction Boom: Saudi Arabia's Vision 2030 mega-projects require enormous quantities of construction-category commercial vehicles including dump trucks, mixer trucks, flatbed trailers, and crane trucks, for site operations. Saudi Arabia’s construction sector remained the Middle East’s largest in 2025, driven by Vision 2030 mega-projects, housing, transport, utilities, and industrial development. Active project values exceed USD 1.3 trillion, while the sector contributes around 6–7% of GDP, sustaining persistent demand for heavy-duty commercial vehicles, with used trucks serving the majority of mid-size contractor fleet requirements at significantly lower capital outlay than new vehicle procurement.
- SME Cost Optimization and Capital Efficiency: The number of registered SMEs increased by around 71%, rising from approximately 700,000 in 2016 to more than 1.2 million in 2024. SMEs systematically choose used trucks over new for fleet acquisition due to substantially lower capital requirements, immediate availability without delivery lead times, and acceptable performance for most operational requirements. Vision 2030's SME development programs are expanding the SME fleet operator base, directly increasing used truck demand as new business registrations require commercial vehicle procurement within available capital constraints.
- E-Commerce and Last-Mile Delivery Expansion: Saudi Arabia's e-commerce sector growth is driving massive expansion in last-mile delivery operations requiring light commercial trucks. The majority of delivery fleet expansion occurs through used light truck procurement as logistics SMEs balance fleet growth requirements with capital constraints.
Market Restraints
- Vehicle Age and Maintenance Cost Concerns: Buyers of older used trucks face elevated maintenance costs, unplanned downtime risks, and difficulty sourcing spare parts for discontinued models. The Saudi used truck market includes significant inventory of vehicles aged 7-15 years where depreciation in purchase price may be offset by higher operating costs. Limited formal vehicle inspection infrastructure beyond registration checks creates information asymmetry between sellers and buyers regarding vehicle condition.
- New Truck Competitive Pricing Pressure: Chinese truck manufacturers are offering new trucks at price points increasingly competitive with quality used options from European brands. The entry of aggressively priced new trucks narrows the traditional price advantage of used vehicles, particularly for buyers prioritizing reliability and warranty coverage over initial capital cost minimization.
Market Opportunities
- Certified Pre-Owned Truck Program Development: The used truck market currently lacks widespread certified pre-owned programs with standardized inspection, reconditioning, and limited warranty coverage. Establishing OEM-backed or independent certified pre-owned programs with transparent vehicle history, multi-point inspection reports, and short-term mechanical warranties would significantly expand the buyer base among fleet managers previously reluctant to purchase used vehicles without quality assurances.
- Digital Platform and Online Auction Marketplace Growth: The progressive adoption of digital marketplaces for used truck transactions is expanding geographic market reach, improving price transparency, and reducing transaction friction. Online platforms and specialized truck auction platforms can connect truck owners in remote areas with buyers nationwide, unlocking inventory previously inaccessible to conventional dealer distribution networks.
Market Challenges
- Financing Accessibility for Used Truck Buyers: Commercial vehicle financing for used trucks remains more restrictive than new truck financing, with Saudi banks and captive finance companies offering lower LTV ratios, shorter tenors, and higher interest rates for pre-owned commercial vehicles. This limits the purchasing capacity of smaller fleet operators and individual owner-operators, constraining transaction values and market volume growth.
- Import Regulations and Quality Control for Used Vehicle Imports: Saudi customs regulations impose age restrictions and technical standards on used vehicle imports, limiting the supply of certain foreign-sourced used truck categories. The complexity of documentation requirements for imported used trucks creates administrative barriers that increase transaction costs and limit the availability of certain high-demand used truck models in the Saudi market.
Emerging Market Trends
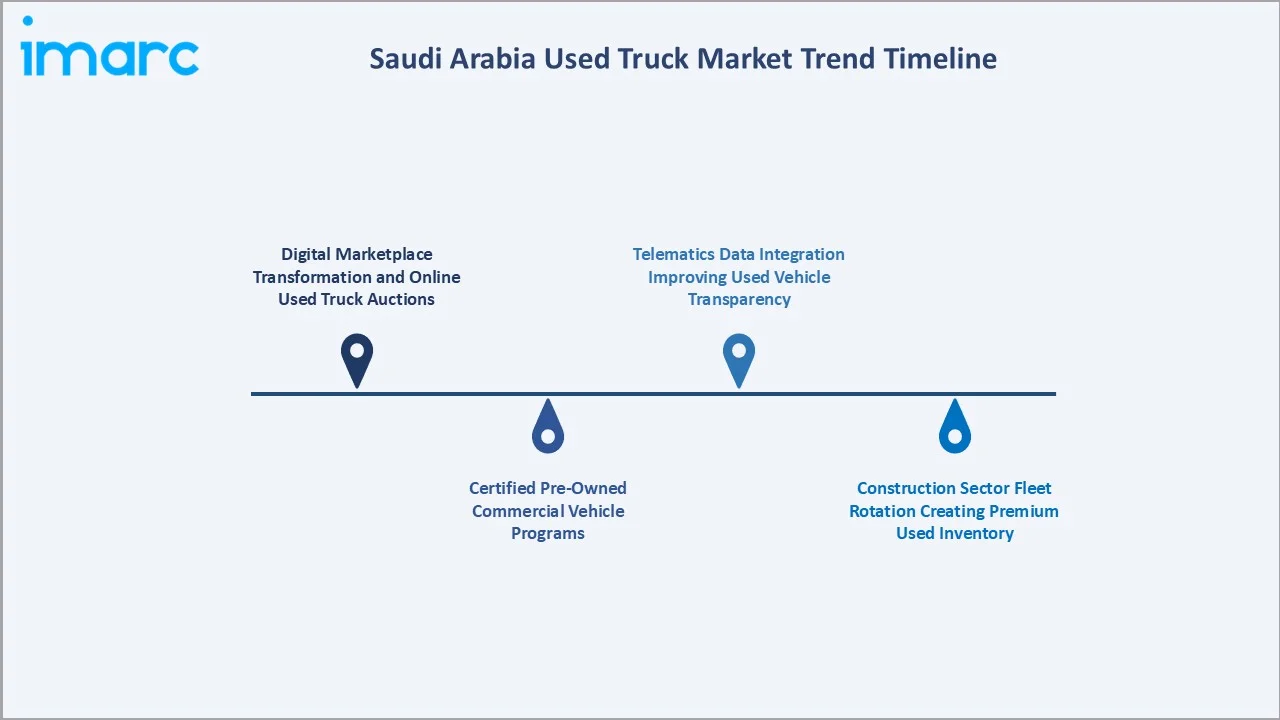
1. Digital Marketplace Transformation and Online Used Truck Auctions
The Saudi used truck market is undergoing progressive digital transformation as platforms and specialized auction platforms expand their commercial vehicle inventory and transaction volumes. These platforms provide buyers with extensive vehicle photographs, specifications, and asking prices that enable remote evaluation before physical inspection, dramatically expanding the geographic reach of the market beyond traditional regional dealer clusters. Online auction formats introduced by several platforms enable competitive price discovery that benefits both buyers seeking fair value and sellers maximizing disposal proceeds.
2. Certified Pre-Owned Commercial Vehicle Programs
Franchised truck dealers and manufacturer-affiliated networks are developing certified pre-owned commercial vehicle programs that provide buyers with standardized inspection reports, reconditioning documentation, and limited warranty coverage. These programs command premium pricing above comparable independent dealer inventory but address the significant buyer concern about used truck reliability and maintenance risk. The growing adoption of CPO programs is progressively formalizing the used truck market and expanding the buyer demographic beyond experienced fleet managers.
3. Telematics Data Integration Improving Used Vehicle Transparency
The growing adoption of telematics and fleet management systems on Saudi commercial vehicles is creating documented service and utilization histories that improve used truck transaction transparency. Buyers of telematics-equipped used trucks can access verified odometer data, maintenance records, driving behavior profiles, and geographic utilization histories that enable more accurate vehicle condition assessment. This data availability is progressively narrowing the information asymmetry between sellers and buyers that has historically constrained used truck market confidence.
4. Construction Sector Fleet Rotation Creating Premium Used Inventory
Vision 2030's mega-project construction boom has generated significant quantities of premium used construction vehicles as major contractors’ complete project phases and rotate fleet. Well-maintained trucks from large construction companies with documented maintenance histories, relatively low mileage, and known operational conditions represent the highest-quality used truck inventory segment. This premium inventory supply, generated by fleet rotation from international-standard construction companies, is elevating the average quality of used trucks available in the Saudi market.
Industry Value Chain Analysis
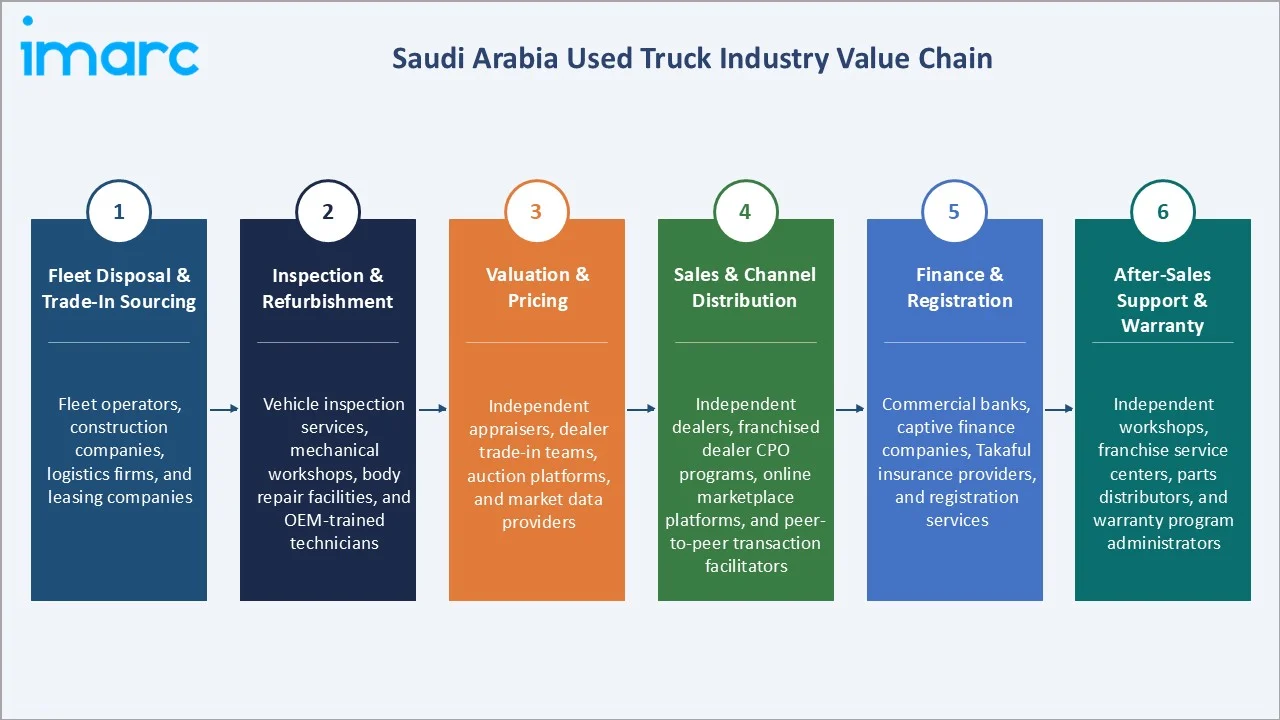
The Saudi Arabia used truck value chain integrates fleet disposal and trade-in sourcing, inspection and refurbishment, valuation and pricing, sales and channel distribution, vehicle financing and registration, and after-sales support and warranty services across heavy-duty, medium-duty, and light truck vehicle categories.
|
Stage |
Key Participants |
|
Fleet Disposal & Trade-In Sourcing |
Fleet operators, construction companies, logistics firms, and leasing companies. |
|
Inspection & Refurbishment |
Vehicle inspection services, mechanical workshops, body repair facilities, and OEM-trained technicians. |
|
Valuation & Pricing |
Independent appraisers, dealer trade-in teams, auction platforms, and market data providers. |
|
Sales & Channel Distribution |
Independent dealers, franchised dealer CPO programs, online marketplace platforms, and peer-to-peer transaction facilitators. |
|
Finance & Registration |
Commercial banks, captive finance companies, Takaful insurance providers, and registration services. |
|
After-Sales Support & Warranty |
Independent workshops, franchise service centers, parts distributors, and warranty program administrators. |
Inspection and refurbishment represent the most value-adding stage in the Saudi used truck value chain, as the quality of pre-sale reconditioning directly determines resale price premium, buyer confidence, and inventory turnover velocity. Dealers that invest in systematic multi-point inspection, documented refurbishment, and professional presentation of used truck inventory command higher margins and faster sales cycles than dealers offering as-is vehicles with minimal buyer assurance.
Technology Landscape in the Saudi Arabia Used Truck Industry
Digital Marketplace and E-Commerce Platform Technology
Saudi Arabia's used truck market is increasingly served by digital marketplace platforms that aggregate inventory listings, facilitate buyer-seller communication, and provide market pricing intelligence. Specialized heavy equipment and truck auction platforms, including Saudi-based operations and global platforms, provide online bidding capability for fleet disposal and institutional selling.
Vehicle Inspection and Condition Reporting Technology
Digital vehicle inspection tools, including standardized mobile inspection applications, diagnostic connectivity, and cloud-based condition reporting platforms, are progressively improving used truck inspection transparency. Vehicle history platforms in Saudi Arabia are at early development stages compared to mature markets but are growing as telematics adoption increases and digital service record maintenance becomes standard among fleet operators.
Fleet Management and Telematics Technology
The growing adoption of fleet management systems and regional platforms by Saudi logistics and construction companies is creating documented vehicle utilization data that enhances used truck transaction transparency. Telematics-equipped trucks with verified mileage, maintenance records, and operational histories command premium used pricing. As telematics adoption reaches critical mass in the Saudi commercial fleet market, the quality and reliability of used truck condition data will progressively improve, supporting market confidence and enabling more accurate risk-adjusted pricing for financing institutions.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Vehicle Type |
Heavy-Duty Trucks |
46.8% |
2025 |
|
Sales Channel |
Independent Dealer |
49.3% |
2025 |
|
End User |
🔒 |
🔒 |
2025 |
|
Region |
Northern and Central Region |
42.5% |
2025 |

By Vehicle Type
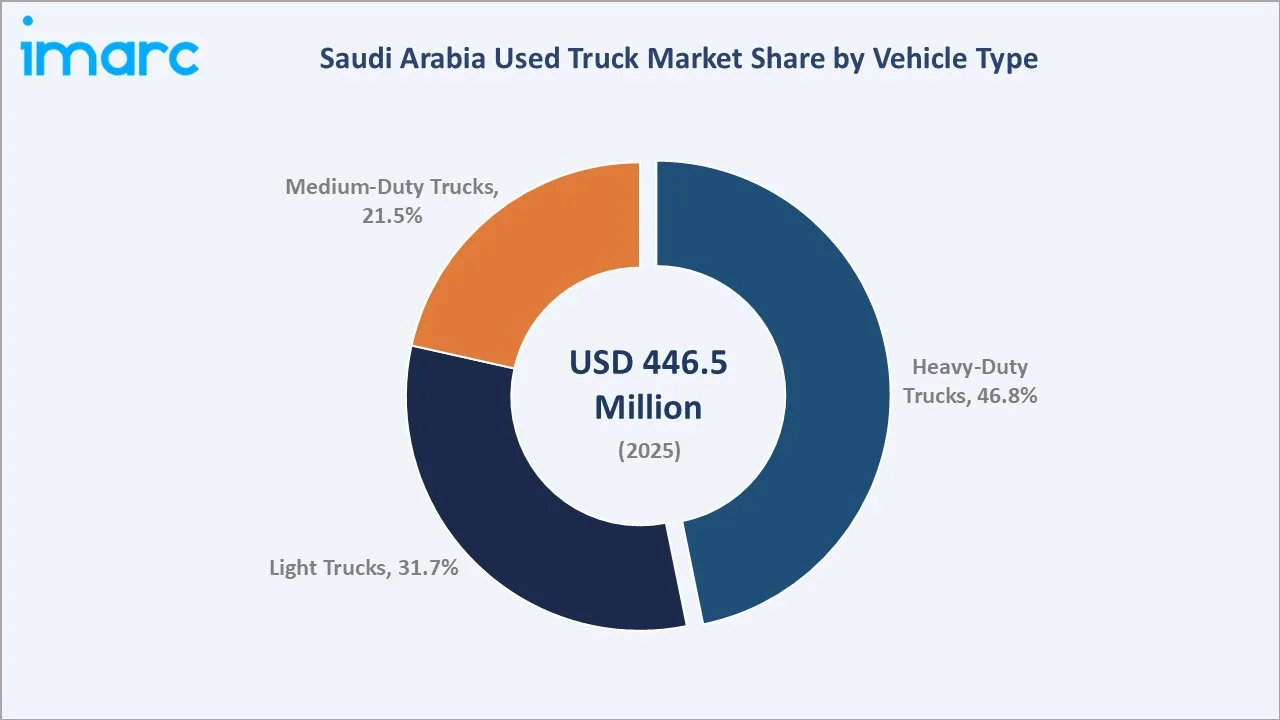
Heavy-duty trucks lead at 46.8% (2025), driven by construction mega-project fleet demand, long-haul freight transport operations, and the high unit values that make used procurement significantly more capital-efficient than new heavy-duty truck acquisition.
To access detailed market analysis, Request Sample
Light trucks at 31.7% reflect the rapidly growing e-commerce delivery, municipal services, and retail distribution demand for light commercial vehicles. The fastest-growing sub-segment by absolute unit volume, light used trucks are accessible to a broader buyer base, including individual owner-operators and micro-enterprises entering the delivery services market. Medium-duty trucks at 21.5% serve regional distribution, food and beverage logistics, and construction material delivery applications.
By Sales Channel
Independent dealers lead at 49.3% (2025), through nationwide dealer networks providing extensive inventory variety, negotiation flexibility, and integrated financing and registration services that enable buyers to complete purchases efficiently.
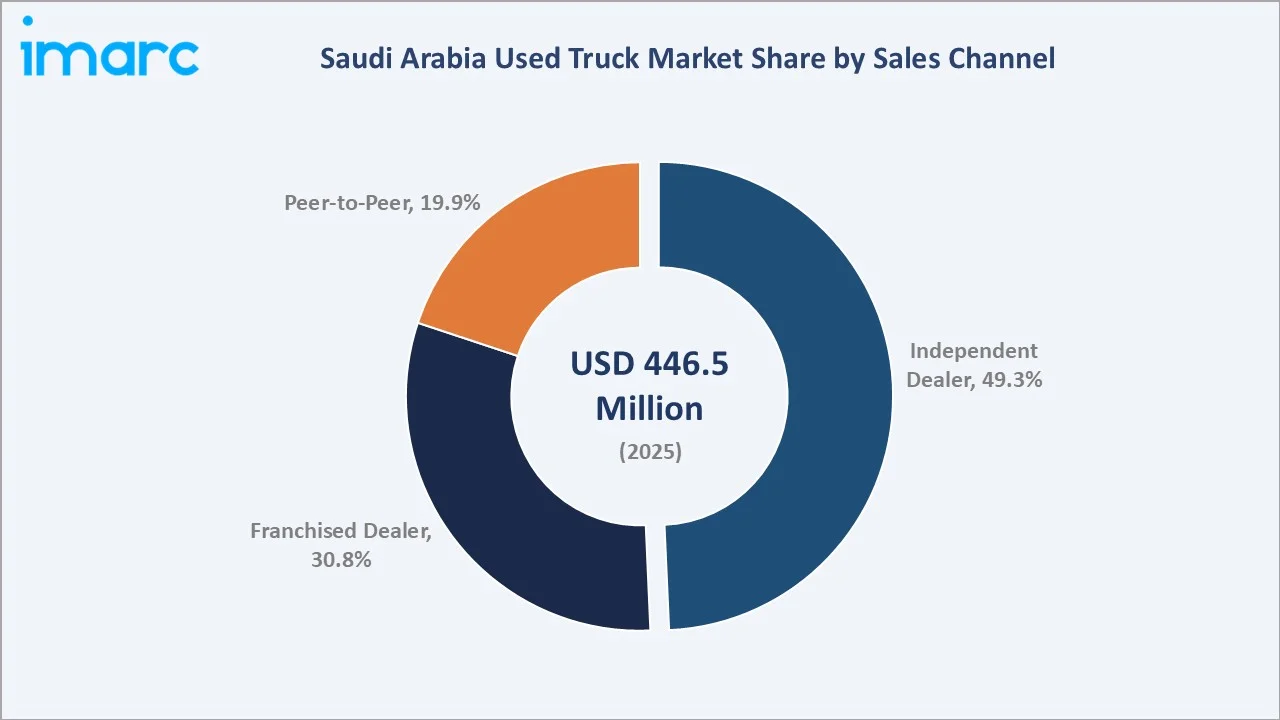
Franchised dealers at 30.8% serve buyers prioritizing brand assurance, certified pre-owned programs, and manufacturer-backed warranty coverage for used trucks. Peer-to-peer at 19.9% represents the fastest-growing channel at ~4.8% CAGR through digital platform adoption enabling direct owner-to-buyer transactions.
Regional Market Insights
|
Region |
Share (2025) |
Key Saudi Arabia Used Truck Market Drivers & Characteristics |
|
Northern & Central Region |
42.5% |
Reflecting the concentration of construction contractor fleets serving Vision 2030 mega-projects, logistics company headquarters, and Saudi Arabia's largest wholesale and retail distribution networks requiring regular commercial fleet procurement and rotation. |
|
Western Region |
24.6% |
Reflecting Jeddah's role as Saudi Arabia's primary seaport driving significant import cargo truck demand, the Makkah and Madinah pilgrimage infrastructure logistics requirements, and the Red Sea Project coastal construction and supply chain operations. |
|
Eastern Region |
21.8% |
Reflecting extensive oil field service vehicle fleet rotation, the industrial city construction and maintenance truck demand, and the region's large petrochemical and logistics sector commercial vehicle operations. |
|
Southern Region |
11.1% |
Reflecting growing construction activity driven by Vision 2030 regional development programs and agricultural transport demand in the Kingdom's primary agricultural provinces. |
The Northern and Central region's 42.5% leadership reflects Riyadh's dual role as Saudi Arabia's largest construction activity center and its primary domestic logistics hub. The concentration of major contractor companies, government construction program offices, and long-haul freight operators headquartered in Riyadh generates the Kingdom's highest commercial vehicle procurement volume. The Western region's 24.6% reflects Jeddah Port's critical role as the gateway for container imports requiring inland distribution trucks, combined with the scale of construction and hospitality infrastructure serving religious tourism at unprecedented levels.
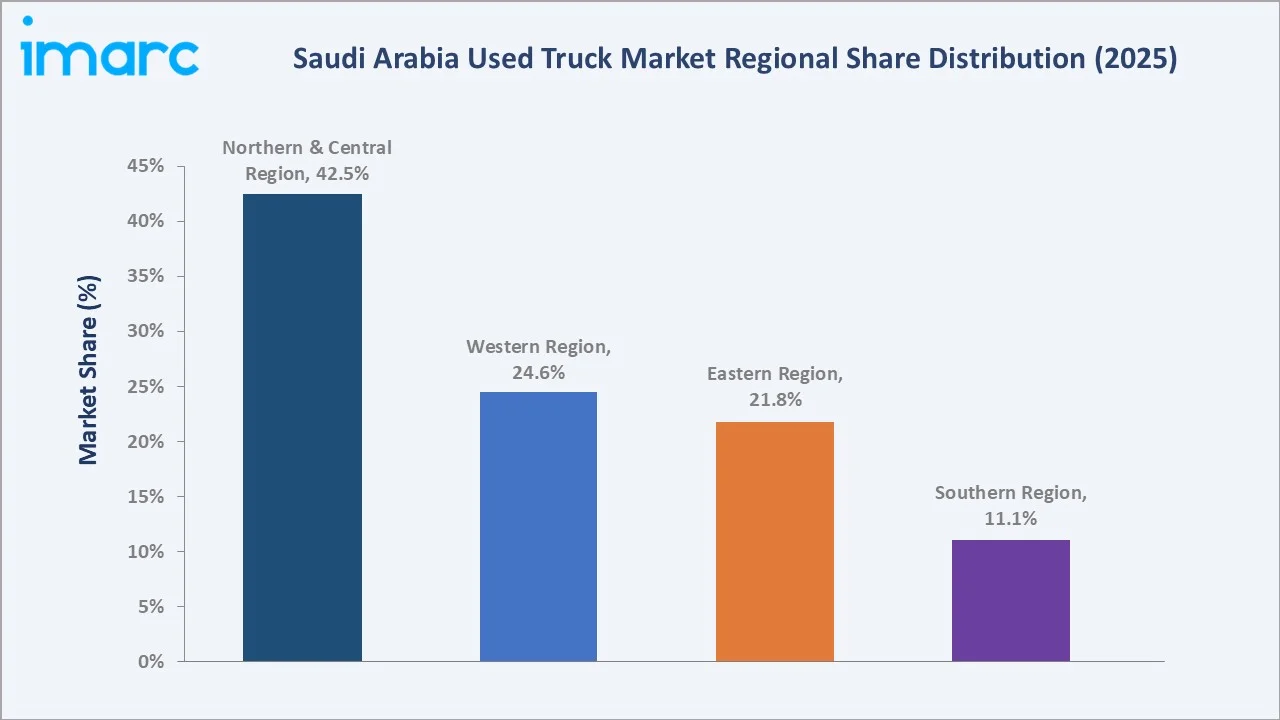
The Eastern region's 21.8% captures the unique demand profile of Saudi Arabia's oil economy heartland, where fleet operational scale creates one of the largest single-organization commercial vehicle fleet rotation programs. The Southern region at 11.1% reflects growing government investment in regional development that is progressively expanding commercial activity and associated truck demand in provinces previously underserved by established dealer networks.
Competitive Landscape
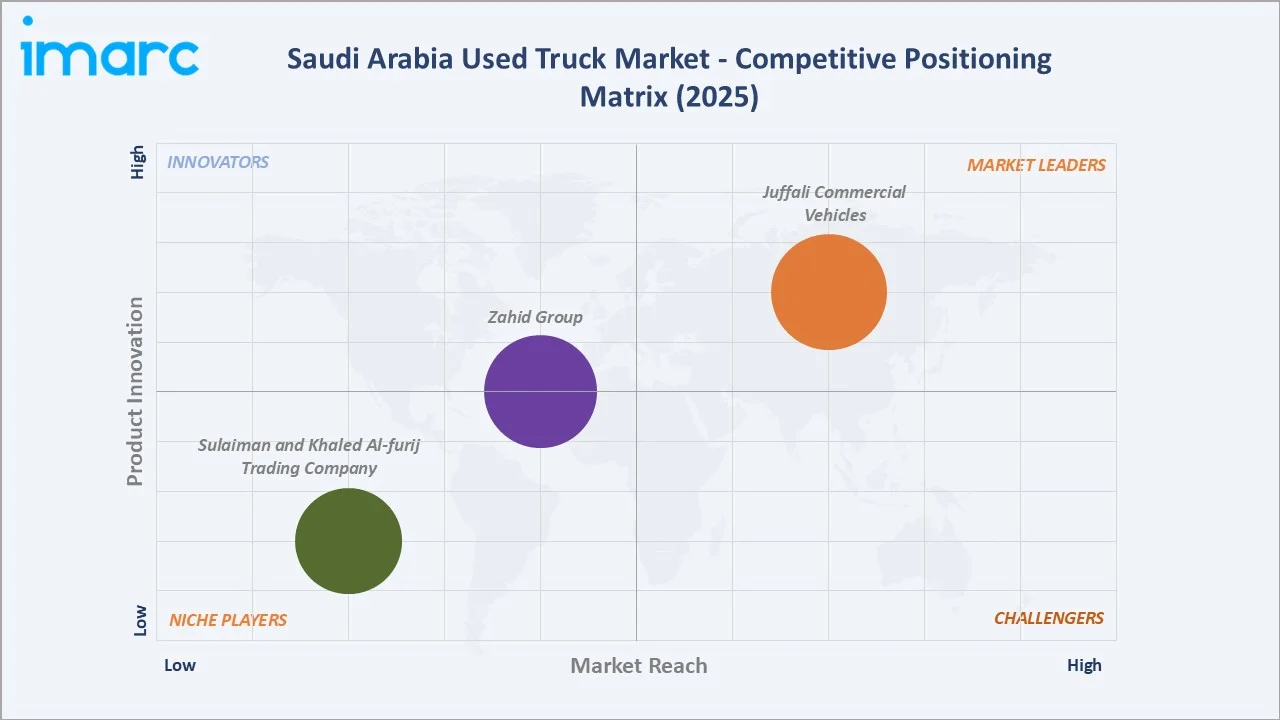
The Saudi Arabia used truck market is moderately fragmented, with established automotive groups providing structured franchised channels, while a large number of independent dealers operating across regional commercial vehicle zones serve the dominant independent dealer segment. Digital platforms are introducing new competitive dynamics by enabling inventory aggregation and price transparency that were previously unavailable in the traditional physical dealer market.
|
Company |
Key Brands |
Market Position |
Core Strength |
|
Juffali Commercial Vehicles |
JuffaliTrucks |
Market Leader |
Juffali Commercial Vehicles transforms the Saudi pre-owned truck market through JuffaliTrucks, offering specialized importing, trade-ins, inspections, and comprehensive regional support for commercial vehicles. |
|
Zahid Group |
Zahid Tractor |
Established Player |
Zahid Group, through its flagship company Zahid Tractor, acts as a leading provider and exclusive distributor of major commercial vehicle brands in Saudi Arabia. |
|
Sulaiman and Khaled Al-furij Trading Company |
Al Furij Heavy Equipment & Trucks |
Niche Player |
Sulaiman and Khaled Al-furij Trading Company operates Al Furij Heavy Equipment & Trucks as a major regional trading enterprise and auctioneer specializing in new and used commercial vehicles, trucks, and heavy machinery in Saudi Arabia and the Gulf region |
Companies across the competitive landscape are investing in certified pre-owned program development, digital platform capabilities, financing product innovation, and inventory quality improvement to capture growing buyer demand for assured used truck purchases. The market is expected to see progressive formalization as digital platforms and CPO programs raise quality and transparency standards across all sales channels.
Key Company Profiles
Juffali Commercial Vehicles
Juffali Commercial Vehicles is a well-established participant in Saudi Arabia’s commercial vehicle market, with activities spanning new and pre-owned trucks, after-sales services, spare parts, and fleet support. Through its used-truck operations, the company serves logistics, construction, transportation, and industrial customers seeking reliable and cost-effective vehicle solutions. Its broad service network and association with leading commercial vehicle brands strengthen its position in the Saudi used truck market.
- Key Brands: JuffaliTrucks.
- Strategic Focus: Strengthening its pre-owned truck portfolio, expanding customer access to reliable and cost-effective vehicles, and enhancing after-sales and fleet support services across Saudi Arabia.
Zahid Group
Zahid Group is a prominent participant in Saudi Arabia’s commercial vehicle and heavy equipment sector, serving customers across transportation, logistics, construction, and industrial applications. The company provides access to a broad range of truck solutions, supported by vehicle distribution, maintenance, spare parts, and fleet services. Its strong local presence and established commercial vehicle network support its role in the Saudi used truck market.
- Key Brands: Zahid Tractor.
- Strategic Focus: Strengthening its presence in Saudi Arabia’s used truck market by offering reliable pre-owned commercial vehicles supported by comprehensive maintenance, spare parts, and after-sales services. Its strategy emphasizes fleet reliability, customer value, and lifecycle support.
Market Concentration Analysis
The Saudi Arabia used truck market exhibits moderate fragmentation, with the franchised dealer segment moderately concentrated around major automotive groups while the independent dealer segment is highly fragmented across hundreds of small and medium independent operators. Digital platforms are introducing new aggregation dynamics that are progressively consolidating market visibility without consolidating physical inventory ownership. Market concentration at the franchise level is expected to remain moderate through 2034, while platform-level consolidation may increase as digital transaction volumes grow.
Investment & Growth Opportunities
Highest Growth Segments
Peer-to-peer digital channel (~4.8% CAGR), light trucks for e-commerce delivery (~4.1% CAGR), certified pre-owned heavy-duty truck programs, used truck digital auction platforms, and integrated financing solutions for independent used truck buyers represent the highest-growth investment vectors in the Saudi Arabia used truck market through 2034.
Investment Themes
- Certified pre-owned truck program development: Establishing standardized certified pre-owned programs with defined inspection criteria, reconditioning standards, and limited warranty coverage creates buyer confidence that can expand the addressable market beyond experienced fleet managers to include first-time used commercial vehicle buyers. CPO programs command price premiums over comparable as-is inventory while improving inventory turnover velocity.
- Digital used truck marketplace platform investment: Building or investing in specialized used commercial truck digital platforms with vehicle history integration, financing pre-approval, inspection service booking, and structured transaction facilitation creates scalable marketplace businesses that benefit from increasing digital transaction volume.
Future Market Outlook (2026-2034)
The Saudi Arabia used truck market is projected to grow from USD 446.5 Million in 2025 to USD 619.4 Million by 2034, exhibiting a CAGR of 3.71% during 2026-2034. The market is projected to reach an anchor value of USD 535.5 Million by 2030, representing the mid-period milestone at which Vision 2030 mega-project construction activity reaches peak deployment and the fleet rotation cycles from 2020-2025 new truck purchases begin generating premium used inventory.
Three structural forces will define the Saudi Arabia used truck market through 2034. First, the progressive completion of Vision 2030 mega-project construction phases will sustain heavy-duty used truck demand as construction companies rotate their fleets at 5-7 year intervals and as completed infrastructure projects generate new logistics distribution requirements. Second, the digitalization of the Saudi used truck market through platforms and emerging specialized commercial vehicle marketplaces will progressively improve market efficiency, reduce transaction friction, and expand geographic market reach. Third, the developing certified pre-owned ecosystem will progressively formalize the used truck market and expand the addressable buyer base.
Research Methodology
Primary Research
Primary research comprised in-depth interviews with used truck dealers, fleet managers at construction and logistics companies, franchised truck dealer sales executives, online platform representatives, vehicle financing officers, and automotive industry analysts. These discussions validated market size estimates, assessed vehicle type and channel demand dynamics, evaluated competitive positioning, and provided insights into regulatory developments and future market evolution in the Saudi Arabia used truck market.
Secondary Research
Secondary research encompassed vehicle registration data, commercial vehicle fleet statistics, Saudi customs import data for used vehicles, franchised dealer group annual reports, automotive industry publications focused on GCC commercial vehicle markets, and digital platform transaction volume disclosures.
Forecasting Models
Forecasting models incorporated historical used truck market revenue trends, Vision 2030 construction and logistics investment projections, commercial vehicle fleet size and rotation rate analysis, digital platform adoption curves, and macroeconomic indicators including Saudi GDP growth, construction sector investment, and e-commerce market expansion rates.
Saudi Arabia Used Truck Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical and Forecast Trends, Industry Catalysts and Challenges, Segment-Wise Historical and Predictive Market Assessment:
|
| Vehicle Types Covered | Light Trucks, Medium-Duty Trucks, Heavy-Duty Trucks |
| Sales Channels Covered | Franchised Dealer, Independent Dealer, Peer-to-Peer |
| End Users Covered | Construction, Oil and Gas, Others |
| Regions Covered | Northern and Central Region, Western Region, Eastern Region, Southern Region |
| Companies Covered | Juffali Commercial Vehicles, Zahid Group, Sulaiman and Khaled Al-furij Trading Company, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Saudi Arabia used truck market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Saudi Arabia used truck market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Saudi Arabia used truck industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Saudi Arabia Used Truck Market Report
The Saudi Arabia used truck market reached USD 446.5 Million in 2025, driven by Vision 2030 construction mega-project heavy vehicle demand, SME cost optimization through used over new truck procurement, expanding e-commerce delivery light truck demand, growing cross-border trade, and progressive digitalization of used truck marketplaces.
The Saudi Arabia used truck market is projected to grow at a CAGR of 3.71% during 2026-2034, sustained by Vision 2030 construction activity, fleet rotation from 2020-2025 new truck purchases generating premium used inventory, digital marketplace growth expanding market reach, and certified pre-owned program development broadening buyer demographics.
The market is projected to reach approximately USD 535.5 Million by 2030, representing the mid-period milestone at which Vision 2030 mega-project construction reaches peak deployment, fleet rotation from early 2020s purchases generate high-quality used inventory, and digital platforms approach mainstream adoption for commercial truck transactions.
Heavy-duty trucks lead with a 46.8% share in 2025, through construction mega-project fleet demand, long-haul freight transport requirements, and the capital efficiency advantage of used over new heavy-duty truck procurement for mid-size Saudi construction companies and freight operators.
Independent dealers dominate with a 49.3% share in 2025, through nationwide dealer networks providing extensive multi-brand inventory variety, negotiation flexibility, integrated financing facilitation, and the physical inspection experience that buyers require for commercial vehicle purchases.
The Northern and Central region leads with a 42.5% share in 2025, driven by Riyadh's concentration of construction contractor fleets, logistics company headquarters, and Saudi Arabia's largest domestic freight distribution networks requiring regular commercial vehicle procurement and fleet rotation.
Key players include Juffali Commercial Vehicles, Zahid Group, and Sulaiman and Khaled Al-furij Trading Company, among others.
The Saudi Arabia used truck market is projected to reach USD 619.4 Million by 2034, driven by sustained logistics sector expansion, construction fleet rotation cycles, progressive certified pre-owned program adoption expanding buyer demographics, and digital platform maturation improving market efficiency and transaction volumes.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade