
Silicon Photonics Market Size, Share, Trends and Forecast by Product, Component, Application, and Region, 2026-2034
Global Silicon Photonics Market Size, Share, Trends & Forecast (2026-2034)
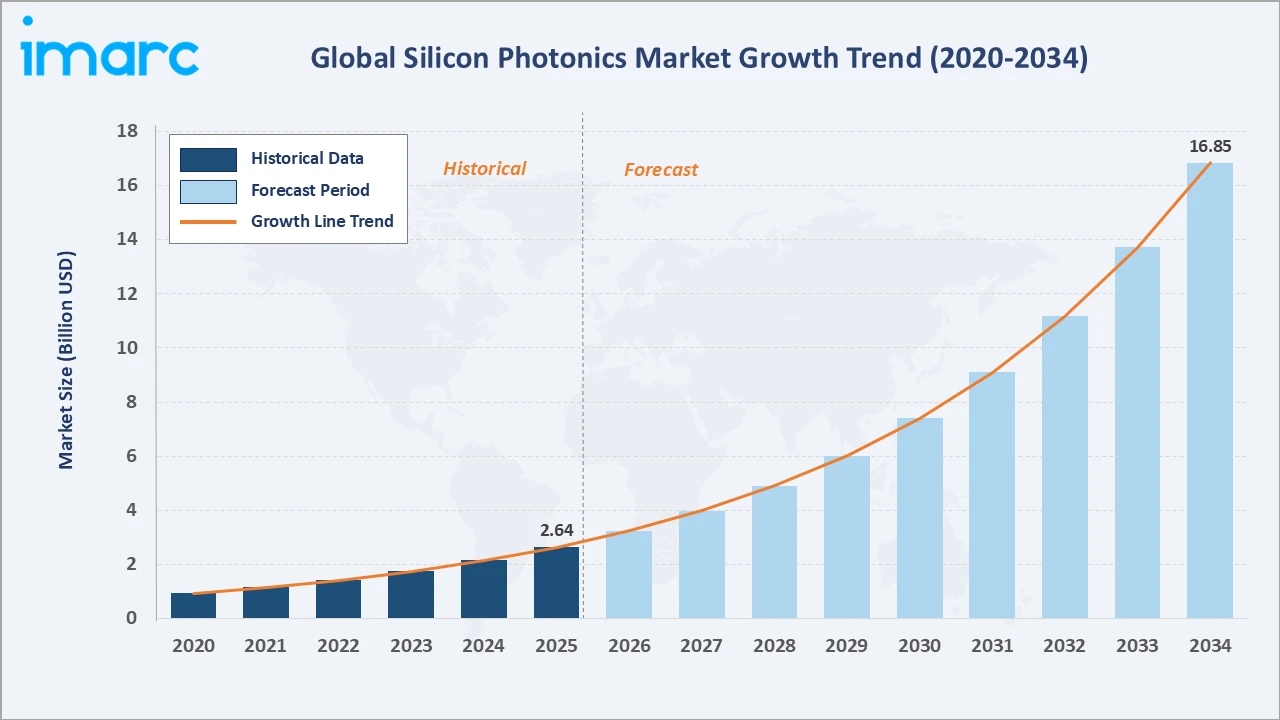
The global silicon photonics market grew from USD 2.64 Billion in 2025 to USD 3.25 Billion in 2026 and is projected to reach USD 16.85 Billion by 2034, growing at a CAGR of 22.9% during 2026-2034. The market is fueled by surging hyperscale data center investment, rapid AI infrastructure scale-out, and 5G optical front-haul build-outs that collectively demand ultra-high-bandwidth, energy-efficient photonic interconnects. Transceivers lead product demand at 37.5%, lasers dominate the component segment at 32.0%, and Asia-Pacific commands the largest regional share at 45.4% in 2025.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 2.64 Billion |
|
Market Size (2026) |
USD 3.25 Billion |
|
Forecast Market Size (2034) |
USD 16.85 Billion |
|
CAGR (2026-2034) |
22.9% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Product |
Transceivers (37.5%, 2025) |
|
Dominant Component |
Laser (32.0%, 2025) |
|
Leading Region |
Asia-Pacific (45.4%, 2025) |
The silicon photonics market grew from USD 0.94 Billion in 2020 to USD 2.64 Billion in 2025, and further to USD 3.25 Billion in 2026, reflecting sustained adoption across cloud, AI, and telecom infrastructure. The market is projected to reach USD 7.40 Billion by 2030 before reaching USD 16.85 Billion by 2034.
To get more information on this market, Request Sample
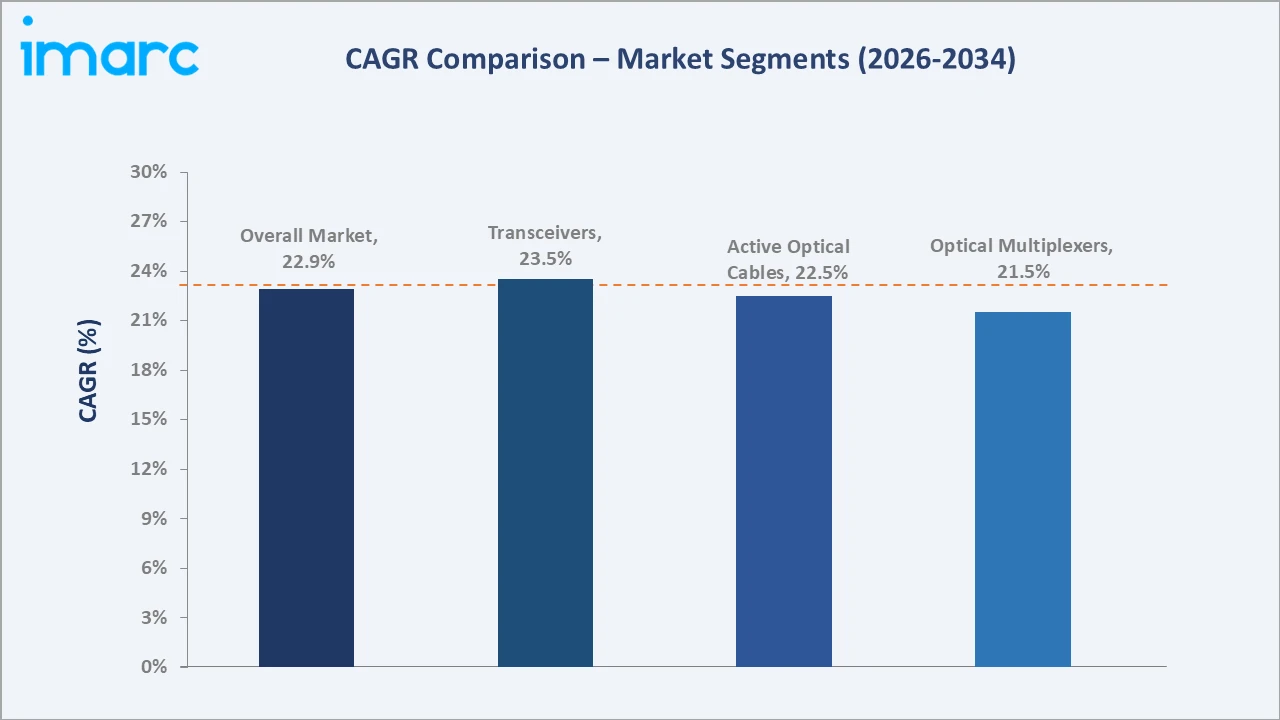
Transceivers grow at approximately 23.5% CAGR, propelled by continuous 400G-to-800G bandwidth upgrades in data center switching fabrics. Active optical cables are expanding at 22.5% CAGR, driven by low-power intra-rack AI cluster connectivity demand. Optical multiplexers advance at 21.5% CAGR as DWDM channel counts scale in metro and long-haul transport networks.
Executive Summary
The silicon photonics industry is on a sustained high-growth trajectory, underpinned by exponential AI workload expansion, hyperscale cloud infrastructure investment, and next-generation 5G network buildouts. The market growth is driven by rapid transceiver adoption at 400G speeds, growing co-packaged optics programs, and the emergence of silicon photonic platforms across sensing and high-performance computing applications beyond core telecommunications.
Transceivers at 37.5% lead by product type, underscoring optical data transfer primacy in AI and cloud infrastructure. Lasers at 32.0% dominate the component level as the essential light source enabling photonic signal generation across all module types. Asia-Pacific commands a 45.4% regional share, anchored by the largest semiconductor foundry concentration and rapidly growing data center pipelines across the region.
Key Market Insights
|
Insight |
Data |
|
Dominant Product |
Transceivers – 37.5% share (2025) |
|
Dominant Component |
Laser – 32.0% share (2025) |
|
Leading Region |
Asia-Pacific – 45.4% (2025) |
|
Key Market Opportunity |
Co-packaged optics and transceiver adoption for AI data center switching represent the highest-value near-term growth catalyst for silicon photonic component and module suppliers through 2034. |
Key Analytical Observations Supporting the Above Data:
- Transceivers at 37.5%: Optical transceivers are the highest-volume silicon photonic product, enabling 400G/800G data center switch-to-server connectivity. Each AI training cluster requires high optical transceiver ports, sustaining strong volume demand as cluster deployments scale.
- Lasers at 32.0%: Lasers are the foundational photonic component providing the coherent light source for modulation, multiplexing, and signal transmission. Advanced edge-emitting and external-cavity designs enable higher output power and narrower linewidth necessary for coherent DWDM systems.
- Asia-Pacific at 45.4%: The region benefits from the world's largest semiconductor foundry capacity, a rapidly growing hyperscale data center pipeline, and government-backed 5G fiber front-haul deployment programs.
Global Silicon Photonics Market Overview
The silicon photonics market encompasses the design, fabrication, packaging, and deployment of photonic devices manufactured using compatible silicon-on-insulator processes. Core components include SOI waveguides, germanium photodetectors, silicon optical modulators, on-chip lasers, and WDM filters integrated into modules and subsystems for high-speed optical data transmission.
The ecosystem spans semiconductor foundries, fabless chip designers, module assemblers, test and measurement providers, and system integrators serving cloud and hyperscale data center operators, telecom carriers, HPC system builders, defense agencies, and life sciences companies, with optical transceiver ports deployed globally in data centers.
Market Dynamics
To evaluate market opportunities, Request Sample
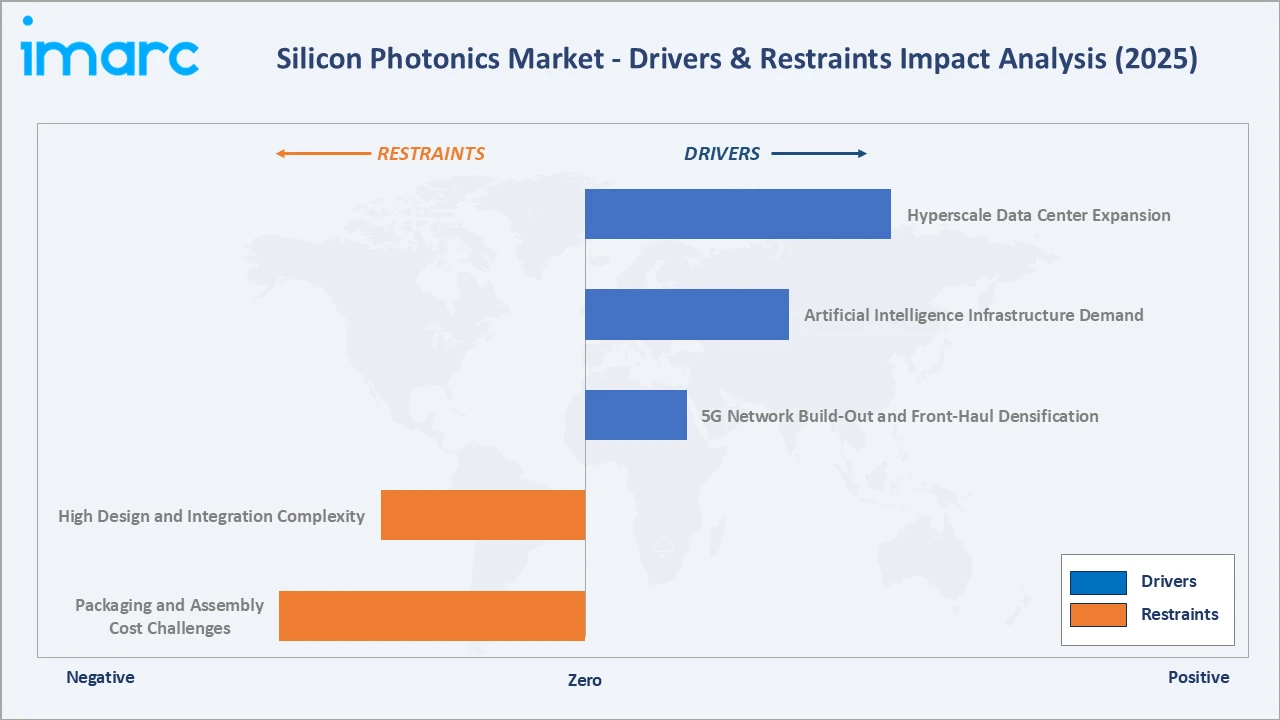
Market Drivers
- Hyperscale Data Center Expansion: Global capital expenditure on data centers is expected to surpass $3 trillion by 2030, with leading cloud providers deploying optical interconnects at scale. Each new generation of AI training clusters requires higher optical port density, directly expanding addressable silicon photonic transceiver and co-packaged optics volumes.
- Artificial Intelligence Infrastructure Demand: AI accelerator clusters require ultra-high-bandwidth optical interconnects between GPUs, CPUs, and memory, creating unprecedented silicon photonic content per rack. The GPU optical interconnect segment growth provides sustained demand pull for silicon photonic transceiver and CPO module solutions.
- 5G Network Build-Out and Front-Haul Densification: The global expansion of 5G continues, with around 390 networks launched and population coverage reaching 60% by the end of 2025. Outside mainland China, coverage is projected to rise from 50% in 2025 to approximately 85% by 2031. 5G network deployment requires dense WDM coherent optical front-haul and back-haul links where silicon photonics provide superior integration density and power efficiency.
Market Restraints
- High Design and Integration Complexity: Silicon photonics chip design requires multidisciplinary expertise spanning photonics, semiconductor physics, and high-frequency electronics, creating significant talent and IP barriers. Integration of active and passive photonic components on a single die involves complex process trade-offs that extend development timelines and increase design costs.
- Packaging and Assembly Cost Challenges: Precision fiber attachment, edge coupling, and hermetic sealing in photonic module assembly add significant manufacturing cost. Yield management in photonic packaging remains a technical and commercial challenge limiting gross margin improvement for module suppliers at current production volumes.
Market Opportunities
- Co-Packaged Optics for AI Accelerators: CPO integrates silicon photonic modules directly onto networking ASIC packages, reducing electrical interconnect length and enabling high bandwidth density improvement versus pluggable modules. Leading cloud providers are targeting CPO deployment in next-generation AI cluster infrastructure, creating a structural demand upgrade cycle.
- Photonic Sensing and LiDAR Applications: Silicon photonics is expanding into LiDAR, medical biosensing, and environmental monitoring markets where CMOS manufacturing compatibility enables volume production at costs unachievable with traditional photonic components, with the automotive LiDAR silicon photonics segment growing.
Market Challenges
- Laser Integration Limitations: Efficient on-chip laser integration on silicon remains technically challenging due to silicon's indirect bandgap, requiring hybrid bonding of III-V semiconductor laser sources. This adds process complexity, yield uncertainty, and cost that limit the pace of fully integrated photonic chip commercialization at mainstream data center volumes.
- Standardization Fragmentation: Absence of unified standards for silicon photonic process design kits, packaging interfaces, and testing methodologies creates interoperability challenges. Fragmented process platforms limit second-sourcing options for fabless designers and constrain the scalability of the photonic chip supply chain across diverse end applications.
Emerging Market Trends
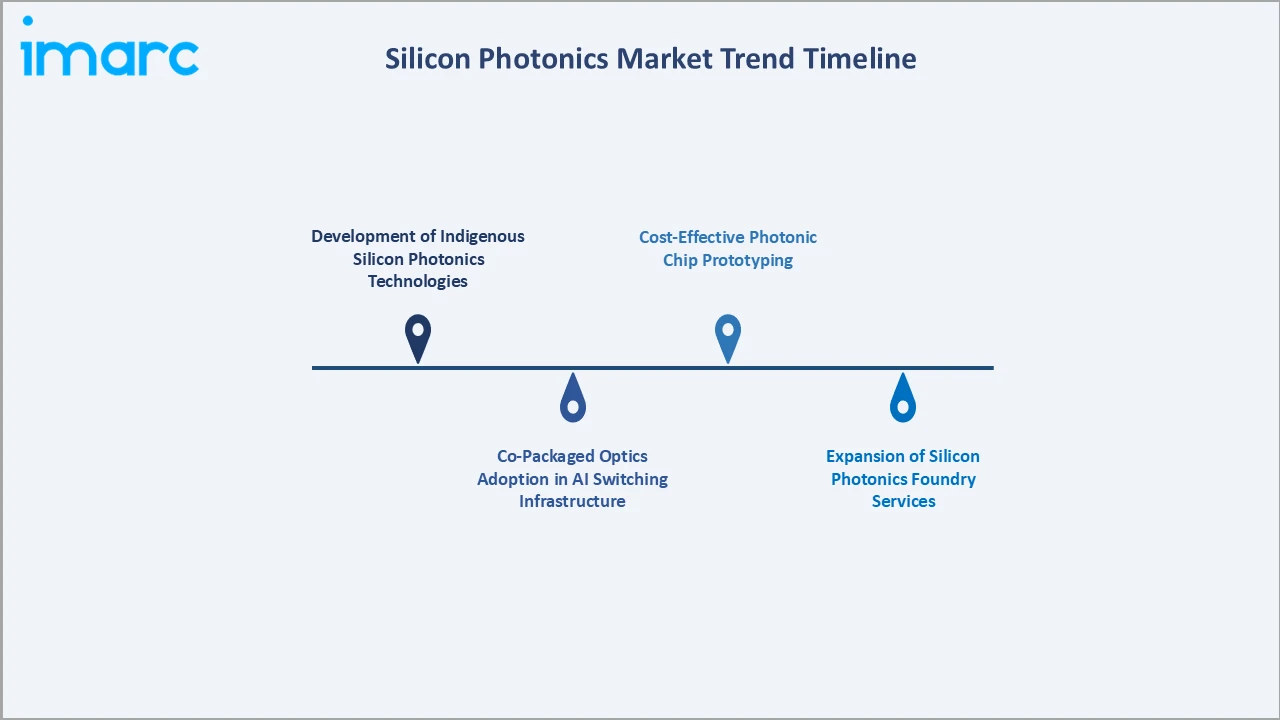
1. Development of Indigenous Silicon Photonics Technologies
In April 2026, India’s MeitY launched two indigenously developed silicon photonics solutions at IIT Madras: a Photonics Process Design Kit (PDK) and a universal packaged photonic integrated circuit (PPIC) test engine, strengthening domestic semiconductor capabilities and supporting photonics research and development. This launch highlights the trend toward strengthening local chip-design capabilities and accelerating photonics research and commercialization.
2. Co-Packaged Optics Adoption in AI Switching Infrastructure
Co-packaged optics (CPO) eliminates the electrical signal degradation of pluggable transceiver interfaces by directly integrating optical modules onto networking ASIC packages. This approach enables substantial bandwidth density and power efficiency improvements critical for next-generation AI cluster switching fabrics. Technology is progressing from development programs to early commercial deployments, with broad hyperscale adoption across leading cloud infrastructure buildouts.
3. Cost-Effective Photonic Chip Prototyping
The growing availability of multi-project wafer (MPW) services is making silicon photonics fabrication more accessible and cost-effective for researchers and businesses. In October 2026, SiPhotonIC launched its Silicon-on-Insulator (SOI) Multi-Project Wafer (MPW) service, offering researchers and businesses more affordable and accessible silicon photonics fabrication and prototyping services.
4. Expansion of Silicon Photonics Foundry Services
The entry of major semiconductor manufacturers into silicon photonics foundry services reflects a growing shift toward integrating optical technologies into advanced semiconductor manufacturing. In April 2026, Samsung Electronics entered the silicon photonics foundry market, expanding its semiconductor manufacturing portfolio to address rising demand for high-speed, energy-efficient data transmission in AI data centers. The launch highlights rising industry investment in high-speed, energy-efficient optical interconnects to support increasing data transmission demands in AI data centers.
Industry Value Chain Analysis
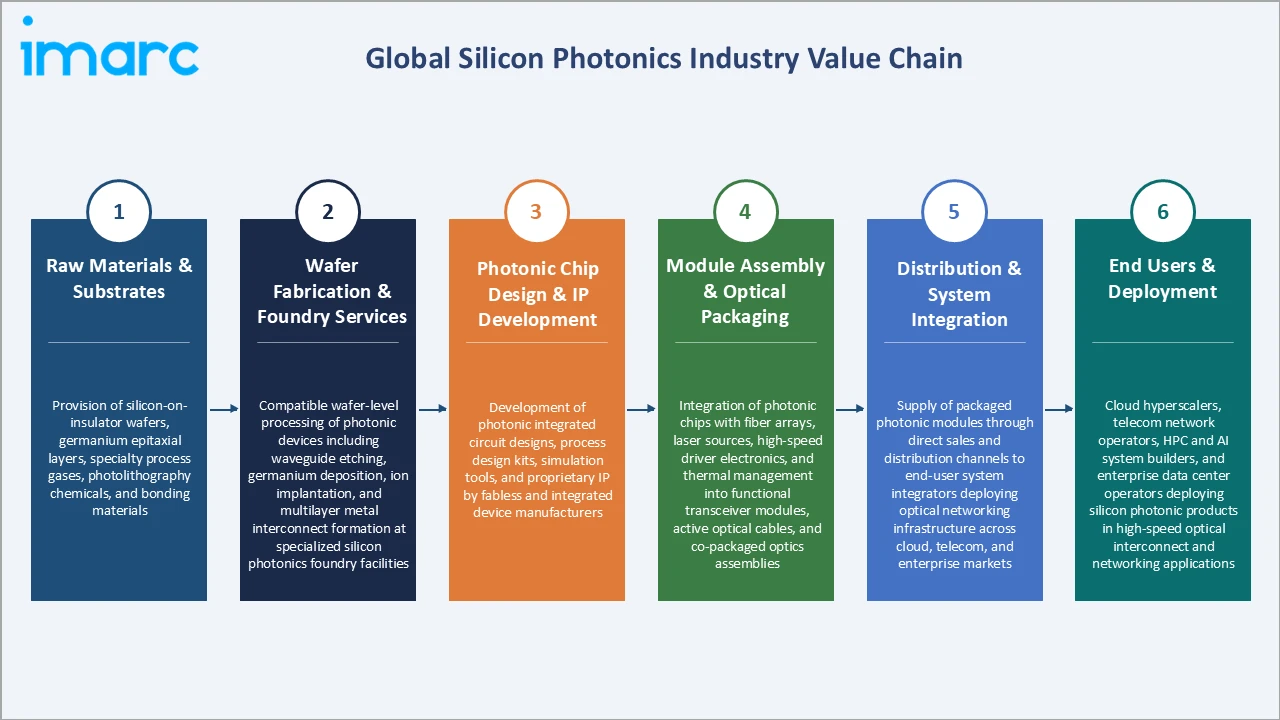
The silicon photonics value chain spans six integrated stages from raw material sourcing through end-user system deployment. The highest value addition occurs at the chip design and module packaging stages, where proprietary photonic circuit architectures and precision fiber-to-chip coupling processes create durable competitive advantages across the supply chain.
|
Stage |
Key Activities & Description |
|
Raw Materials & Substrates |
Provision of silicon-on-insulator wafers, germanium epitaxial layers, specialty process gases, photolithography chemicals, and bonding materials. |
|
Wafer Fabrication & Foundry Services |
Compatible wafer-level processing of photonic devices including waveguide etching, germanium deposition, ion implantation, and multilayer metal interconnect formation at specialized silicon photonics foundry facilities. |
|
Photonic Chip Design & IP Development |
Development of photonic integrated circuit designs, process design kits, simulation tools, and proprietary IP by fabless and integrated device manufacturers. |
|
Module Assembly & Optical Packaging |
Integration of photonic chips with fiber arrays, laser sources, high-speed driver electronics, and thermal management into functional transceiver modules, active optical cables, and co-packaged optics assemblies. |
|
Distribution & System Integration |
Supply of packaged photonic modules through direct sales and distribution channels to end-user system integrators deploying optical networking infrastructure across cloud, telecom, and enterprise markets. |
|
End Users & Deployment |
Cloud hyperscalers, telecom network operators, HPC and AI system builders, and enterprise data center operators deploying silicon photonic products in high-speed optical interconnect and networking applications. |
The photonic chip design and module packaging stages hold the greatest strategic significance, as proprietary photonic circuit architectures and precision assembly know-how create durable competitive advantages within the silicon photonics value chain.
Technology Landscape in the Silicon Photonics Industry
Silicon-on-Insulator (SOI) Platform Technology
SOI wafers are the foundational substrate for silicon photonics, enabling low-loss optical waveguide fabrication through high refractive index contrast between the silicon guiding layer and buried oxide cladding. Advances in SOI wafer processing have significantly reduced silicon photonic chip manufacturing cost per die, enabling competitive transceiver module pricing at data center deployment volumes. SOI platform maturity underpins ongoing product innovation in both transceiver and sensing photonic applications.
Germanium Photodetector Integration
Germanium-on-silicon photodetectors provide broadband optical detection at telecommunications wavelengths with bandwidths exceeding 70 GHz, enabling 100G-per-lane operation within monolithically integrated silicon photonic receiver circuits. CMOS process compatibility allows germanium photodetectors to be co-fabricated with silicon waveguides and modulators on a single wafer, eliminating assembly steps and reducing module cost. Ongoing improvements in germanium deposition uniformity and dark current reduction are advancing receiver sensitivity in high-speed photonic systems.
Co-Packaged Optics and Advanced Packaging
Flip-chip bonding, silicon photonic interposers, and ultra-high-precision edge-coupling with fiber arrays represent the advanced packaging layer enabling co-packaged optics module assembly at terabit-per-second optical bandwidth. These precision packaging technologies are critical for meeting the signal integrity and density requirements of next-generation AI and cloud switching fabrics and represent an area of active development by leading semiconductors and module manufacturers targeting deployment timelines.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Product | Transceivers | 37.5% | 2025 |
| Component | Laser | 32.0% | 2025 |
| Application | IT and Telecommunications | 43.8% | 2025 |
| Region | Asia-Pacific | 45.4% | 2025 |

By Product
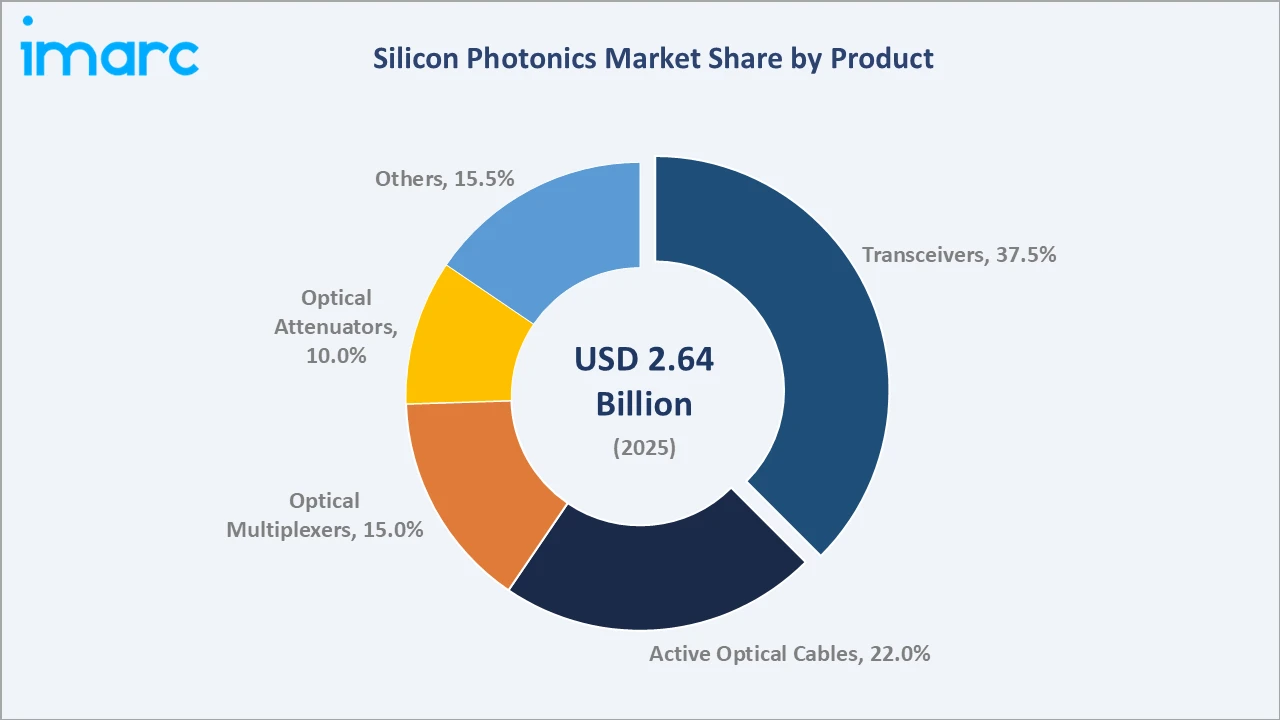
Transceivers lead at 37.5% in 2025, reflecting the primacy of high-speed optical data transfer in cloud and AI infrastructure. Continuous bandwidth upgrades from transceiver standards increase silicon photonic integration per module generation, sustaining transceiver leadership through 2034 as AI cluster optical port density requirements continue to escalate.
To access detailed market analysis, Request Sample
Active optical cables at 22.0% serve the intra-rack and rack-to-rack AI server connectivity market, providing power-efficient optical links at distances where copper cables face signal integrity constraints. Optical multiplexers at 15.0% enable WDM channel aggregation across metro and long-haul networks. Optical attenuators at 10.0% and others at 15.5% address test, sensing, and specialty photonic system requirements.
By Component
Lasers dominate at 32.0% in 2025, reflecting their role as the indispensable light source in every silicon photonic system. Advanced edge-emitting lasers provide the optical power and spectral purity needed for high-fidelity and coherent DWDM modulation. Optical waveguides at 25.0% are the ubiquitous passive routing element enabling on-chip signal propagation with losses below 1.5 dB/cm in optimized SOI platforms.
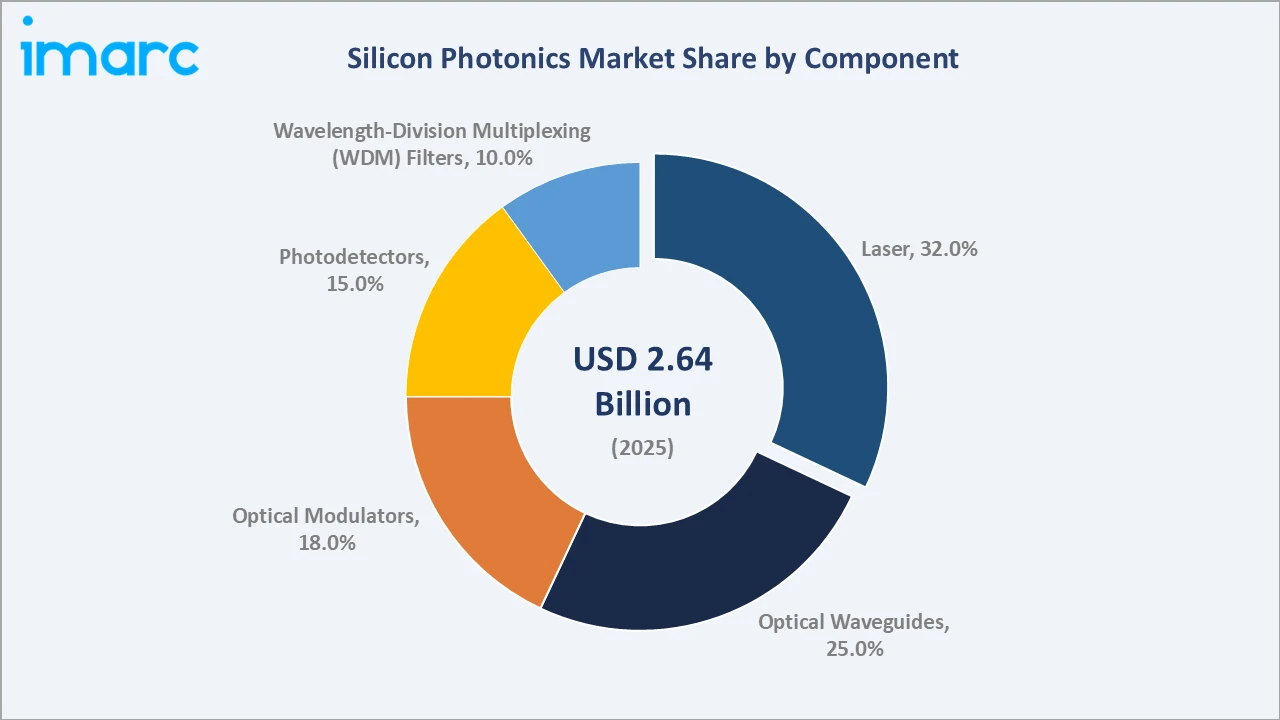
Optical modulators at 18.0% convert electrical data signals into modulated optical waveforms at speeds up to 100 Gbaud, representing the highest-value active silicon photonic component in transceiver chip architectures. Photodetectors at 15.0% provide high-sensitivity optical-to-electrical conversion. Wavelength-division multiplexing (WDM) filters at 10.0% enable wavelength channel multiplexing and demultiplexing in coherent optical systems.
Regional Market Insights
|
Region |
Share (2025) |
Key Market Characteristics |
|
Asia-Pacific |
45.4% |
Largest semiconductor foundry concentration, rapidly expanding hyperscale data center pipelines, and growing 5G optical front-haul network investments across leading economies. |
|
North America |
28.0% |
Home to leading cloud hyperscalers deploying AI infrastructure at scale, a strong fabless silicon photonics design ecosystem, and significant public and private R&D investment in photonics. |
|
Europe |
18.0% |
Growing optical telecom network modernization programs, active photonics research ecosystem, and increasing focus on domestic semiconductor photonics capability development. |
|
Latin America |
4.6% |
Expanding fiber broadband infrastructure deployment and growing cloud adoption by enterprise and government sectors driving early-stage silicon photonics demand across the region. |
|
Middle East & Africa |
4.0% |
Rising hyperscale and sovereign data center investments, large-scale fiber broadband expansion programs, and growing technology infrastructure development across Gulf markets. |
Asia-Pacific regional leadership at 45.4% reflects the geographic concentration of silicon photonic foundry capacity and hyperscale data center investments. North America at 28.0% draws strength from its leading cloud infrastructure operators, advanced photonics research institutions, and a deep fabless chip design ecosystem driving continuous product innovation.
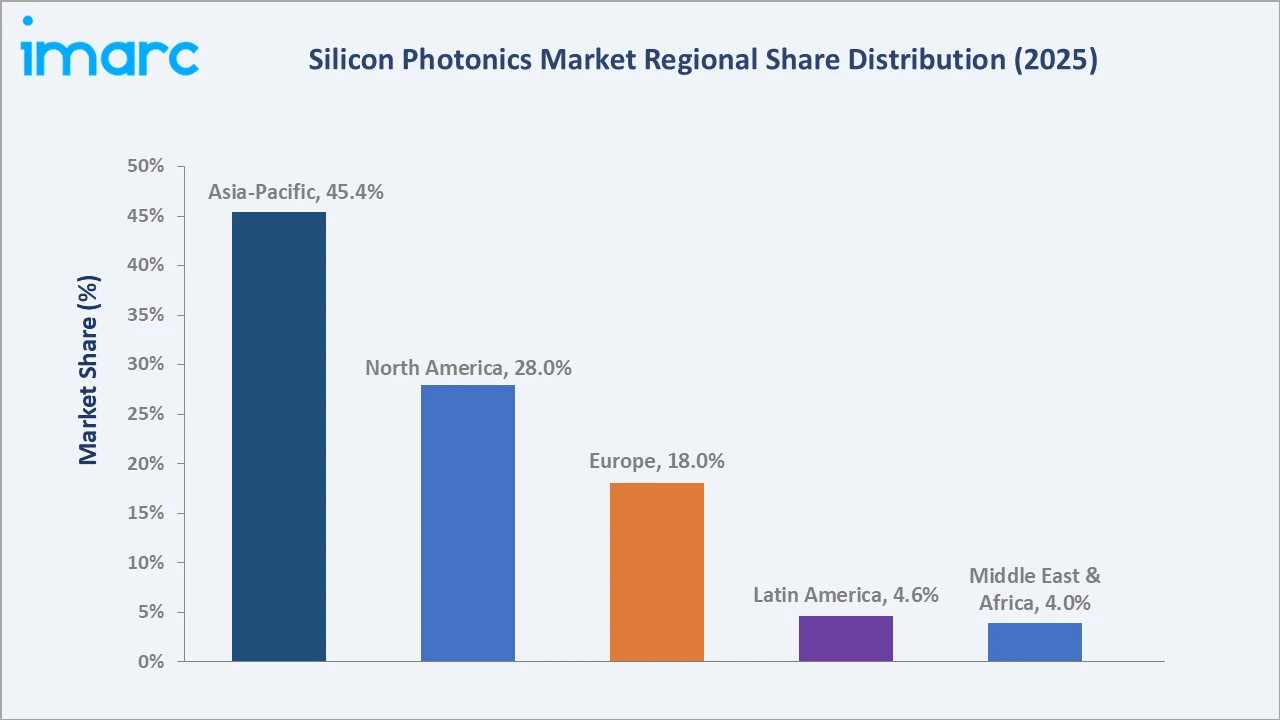
Europe at 18.0% is supported by telecom network upgrade programs and an active photonic chip research ecosystem. Latin America at 4.6% and Middle East & Africa at 4.0% are early-stage but growing markets, driven by broadband infrastructure investment and expanding enterprise cloud adoption that creates incremental demand for optical networking equipment containing silicon photonic components.
Competitive Landscape
The silicon photonics market is moderately concentrated, with integrated device manufacturers and large-scale module suppliers commanding significant revenue share in transceiver and coherent optical categories, while a growing number of fabless and foundry-based providers are expanding competitive dynamics across sensing, computing, and communications applications.
| Company | Key Offerings | Market Position | Core Strength |
|---|---|---|---|
| Intel Corporation | Intel Silicon Photonics | Market Leader | Intel Corporation is a pioneer in silicon photonics, integrating light-based (optical) data transmission directly onto silicon-based microelectronics. |
| Cisco Systems, Inc. | 1.6T transceivers, 800G transceivers, 400G transceivers, 200G transceivers | Market Leader | Cisco Systems, Inc. uses silicon photonics to integrate optical and electrical components into a single CMOS-compatible silicon substrate. |
| Broadcom Inc. | Ethernet Switch CPO, CPO for XPU Interconnect | Established Player | Broadcom Inc. is a leading developer in silicon photonics and Co-Packaged Optics (CPO), using light-based data transmission. |
| Lumentum Operations LLC | CW Lasers for Silicon Photonics Transceivers | Established Player | Lumentum Operations LLC is known for continuous wave (CW) lasers that act as the foundational, unmodulated light sources for silicon photonics (SiPh) transceivers. |
| NVIDIA Corporation | NVIDIA Quantum-X InfiniBand Photonics Switch, NVIDIA Spectrum-X Ethernet Photonics Switches | Innovator | NVIDIA uses silicon photonics in its networking switches through co-packaged optics (CPO), replacing traditional external pluggable transceivers with optical engines integrated directly onto the switch application-specific integrated circuit (ASIC) package. |
Competition is intensifying as hyperscaler CPO programs create demand for deeply integrated photonic solutions. Differentiation increasingly centers on packaging innovation, electronic-photonic co-design, and vertical integration of laser sources within silicon photonic platforms to address system requirements.
Key Company Profiles
Intel Corporation
Intel Corporation is a leading semiconductor company with a significant silicon photonics presence through its data center and networking product divisions. The company serves cloud, telecom, and high-performance computing markets with silicon photonic transceivers manufactured using its advanced CMOS fabrication process. Its manufacturing scale and semiconductor engineering expertise enable high-volume photonic module production aligned with hyperscale data center interconnect roadmaps.
- Key Offerings: Intel Silicon Photonics.
- Strategic Focus: Scaling silicon photonics manufacturing volume, advancing co-packaged optics integration for next-generation AI switching fabrics, and expanding silicon photonics foundry services to third-party photonic chip designers.
Cisco Systems, Inc.
Cisco Systems, Inc. is a networking technology leader with a substantial silicon photonics presence. The company serves cloud service providers, telecom operators, and enterprise data center operators with coherent optical modules and pluggable transceivers leveraging silicon photonic integration for performance and cost efficiency across metro and long-haul optical network deployments.
- Key Offerings: 1.6T transceivers, 800G transceivers, 400G transceivers, 200G transceivers.
- Strategic Focus: Integrating silicon photonics across its optical networking portfolio, expanding pluggable optics for metro and data center interconnect, and leveraging photonic IC capabilities for next-generation routing and optical transport systems.
Market Concentration Analysis
The silicon photonics market exhibits moderate concentration in transceiver and coherent optical module segments, where established integrated manufacturers and large-scale module suppliers collectively account for a significant majority of organized market revenue. This concentration is supported by the capital-intensive nature of photonic chip fabrication, precision module assembly requirements, and the multi-year hyperscaler qualification cycles that create durable barriers for new market entrants seeking to compete at data center deployment volumes.
The broader silicon photonics ecosystem, encompassing component suppliers, open-access foundry service providers, and emerging application-specific photonic chip developers, is more fragmented, with numerous specialized players addressing distinct applications in sensing, healthcare, defense, and quantum photonics. This fragmentation creates ongoing opportunities for focused innovation and niche market leadership as silicon photonics applications diversify beyond core data center and telecom segments.
Investment & Growth Opportunities
Highest Growth Segments
Transceivers are growing at 23.5% CAGR, active optical cables are expanding at 22.5% CAGR, and optical multiplexers are growing at 21.5% CAGR.
Investment Themes
- AI Data Center Optical Infrastructure: Structural expansion of AI training and inference infrastructure creates multi-year demand visibility for silicon photonic transceivers and CPO suppliers. Companies with hyperscaler qualification, product readiness, and co-packaged optics program engagement benefit from long-duration demand supported by cloud capital expenditure commitments spanning multiple years and GPU cluster generations.
- Photonic Foundry Platform Development: Open-access silicon photonics foundry platforms enabling ecosystem-wide photonic chip development are creating foundry service revenue streams. Investment in photonic process design kit development, multi-project wafer programs, and advanced packaging capability positions foundry service providers at the center of a rapidly expanding photonic chip design ecosystem targeting diverse applications across data center, sensing, and quantum markets.
Future Market Outlook (2026-2034)
The silicon photonics market grew from USD 2.64 Billion in 2025 to USD 3.25 Billion in 2026, reaching USD 16.85 Billion by 2034, exhibiting a CAGR of 22.9% during 2026-2034. The market is expected to reach approximately USD 7.40 Billion by 2030 as AI infrastructure investments peak and co-packaged optics deployments begin at commercial scale across leading hyperscale cloud and AI switching platform architectures.
Three structural forces will define the silicon photonics market through 2034. First, continued AI infrastructure investment will sustain high-volume demand for silicon photonic transceivers and CPO modules. Second, the technology transition from pluggable to co-packaged optics will structurally increase silicon photonic content per networking system beyond simple port count expansion. Third, application diversification into LiDAR, biosensing, quantum photonics, and defense will create additional revenue streams that reduce cyclical dependence on the data center infrastructure cycle and extend sustainable double-digit growth through 2034.
Research Methodology
Primary Research
Primary research comprised structured consultations with silicon photonics chip designers, optical module manufacturers, hyperscale data center procurement specialists, telecom network equipment vendors, and semiconductor foundry technology managers. These discussions validated market sizing, assessed technology adoption timelines, and provided insight into competitive positioning, product roadmaps, and demand dynamics across data center, telecom, and emerging sensing application markets.
Secondary Research
Secondary research drew on published data from company annual reports and investor presentations, trade publications including Light Reading, Lightwave, and Fiber Systems, and government semiconductor R&D program announcements. Historical market data from 2020 through 2025 was cross-validated across primary and secondary sources to ensure consistency and analytical integrity.
Forecasting Models
Market forecasts were developed using bottom-up and top-down modeling incorporating historical optical transceiver generation adoption rates, hyperscale data center capital expenditure projections, 5G network build-out timelines, co-packaged optics commercialization roadmaps, and silicon photonics foundry capacity expansion plans across the forecast horizon.
Silicon Photonics Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Products Covered | Transceivers, Active Optical Cables, Optical Multiplexers, Optical Attenuators, Others |
| Components Covered | Optical Waveguides, Optical Modulators, Photodetectors, Wavelength-Division Multiplexing (WDM) Filters, Laser |
| Applications Covered | IT and Telecommunications, Consumer Electronics, Healthcare and Life Sciences, Commercial, Defense and Security, Others |
| Regions Covered | Asia Pacific, Europe, North America, Latin America, Middle East and Africa |
| Countries Covered | United States, Canada, Germany, France, United Kingdom, Italy, Spain, Russia, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Mexico |
| Companies Covered | Intel Corporation, Cisco Systems, Inc., Broadcom Inc., Lumentum Operations LLC, NVIDIA Corporation, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the silicon photonics market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the global silicon photonics market.
- The study maps the leading, as well as the fastest-growing, regional markets. It further enables stakeholders to identify the key country-level markets within each region.
- Porter's Five Forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the silicon photonics industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Silicon Photonics Market Report
The silicon photonics market reached USD 3.25 Billion in 2026, driven by hyperscale data center expansion, AI infrastructure investments, and accelerating 5G optical interconnect deployments globally.
The market is projected to grow at a CAGR of 22.9% during 2026-2034, supported by AI data center bandwidth scaling, co-packaged optics adoption, and photonic application diversification into sensing.
The market is projected to reach approximately USD 7.40 Billion by 2030, driven by AI cluster deployments, 800G transceiver upgrades, and early commercial volumes of co-packaged optics.
Transceivers lead with a 37.5% share in 2025, driven by continuous data center bandwidth upgrades and rising optical port density requirements in AI GPU cluster infrastructure globally.
Lasers lead with a 32.0% component share in 2025, reflecting their critical role as the essential light source enabling photonic signal generation across all transceiver and module applications.
Asia-Pacific leads with a 45.4% share in 2025, supported by the world's largest semiconductor foundry capacity and rapidly expanding hyperscale data center and 5G infrastructure investments.
Key players include Intel Corporation, Cisco Systems, Inc., Broadcom Inc., Lumentum Operations LLC, and NVIDIA Corporation, among others.
The market is projected to reach USD 16.85 Billion by 2034, driven by AI infrastructure scaling, 1.6T transceiver commercialization, CPO adoption, and photonic sensing application growth.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade