Singapore Pharmaceutical Market Size, Share, Trends and Forecast by Type, Nature, and Region, 2026-2034
Singapore Pharmaceutical Market Size, Share, Trends & Forecast (2026-2034)
The Singapore pharmaceutical market grew from USD 7.80 Billion in 2025 to USD 8.20 Billion in 2026 and is projected to reach USD 12.31 Billion by 2034, growing at a CAGR of 5.09% during 2026-2034. An ageing population, strong government support, and growing biologics manufacturing are supporting steady growth. About 20.7% of Singapore citizens were aged 65 and above in June 2025, raising long-term demand for medicines.
Universal healthcare financing, a trusted regulatory system, and Singapore’s role as a regional biomedical hub continue to strengthen demand. Pharmaceutical drugs dominate at 69.8%. Conventional products lead the nature segment at 85.0%. The West commands 35.8% of national market share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 7.80 Billion |
|
Market Size (2026) |
USD 8.20 Billion |
|
Forecast Market Size (2034) |
USD 12.31 Billion |
|
CAGR (2026-2034) |
5.09% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Type |
Pharmaceutical Drugs (69.8%, 2025) |
|
Dominant Nature |
Conventional (85.0%, 2025) |
|
Leading Region |
West (35.8%, 2025) |
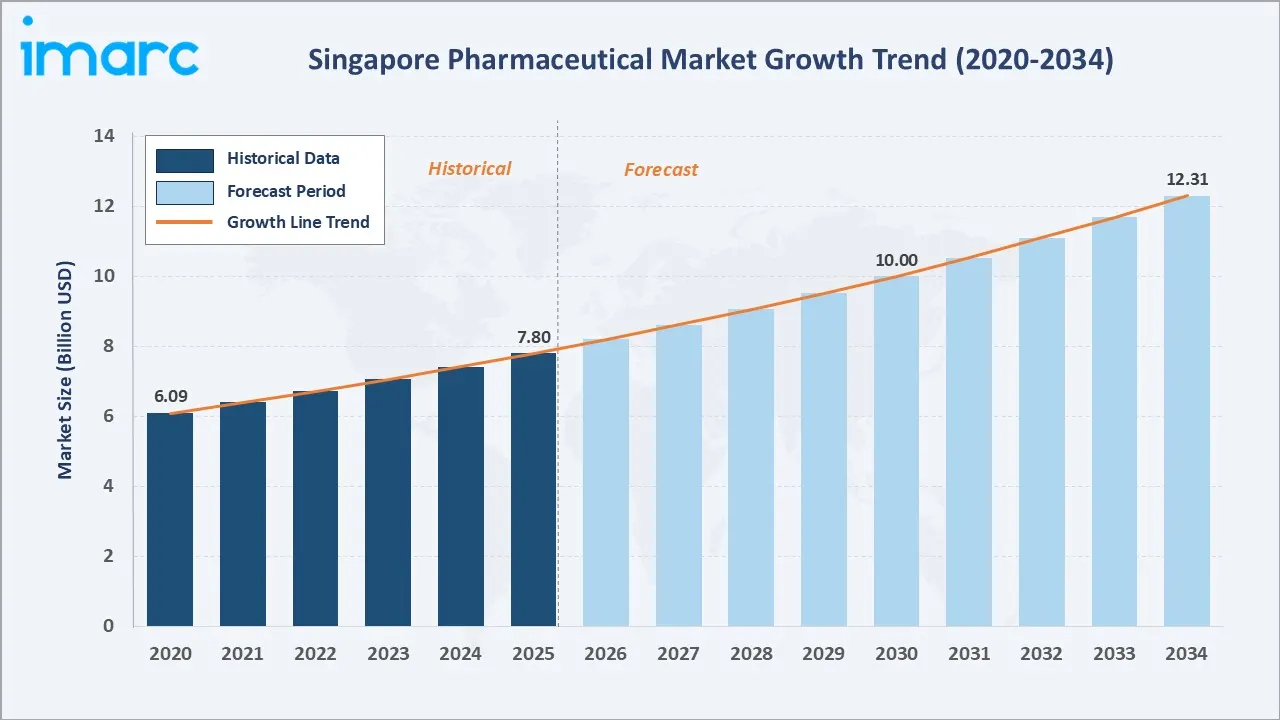
The Singapore pharmaceuticals market increased from USD 6.09 Billion in 2020 to USD 7.80 Billion in 2025 and is estimated to reach USD 8.20 Billion in 2026. The market is further expected to grow to USD 10.00 Billion by 2030 and USD 12.31 Billion by 2034. Growth reflects rising domestic demand for chronic and specialty medicines alongside Singapore’s expanding role as a regional supply base.
To get more information on this market, Request Sample
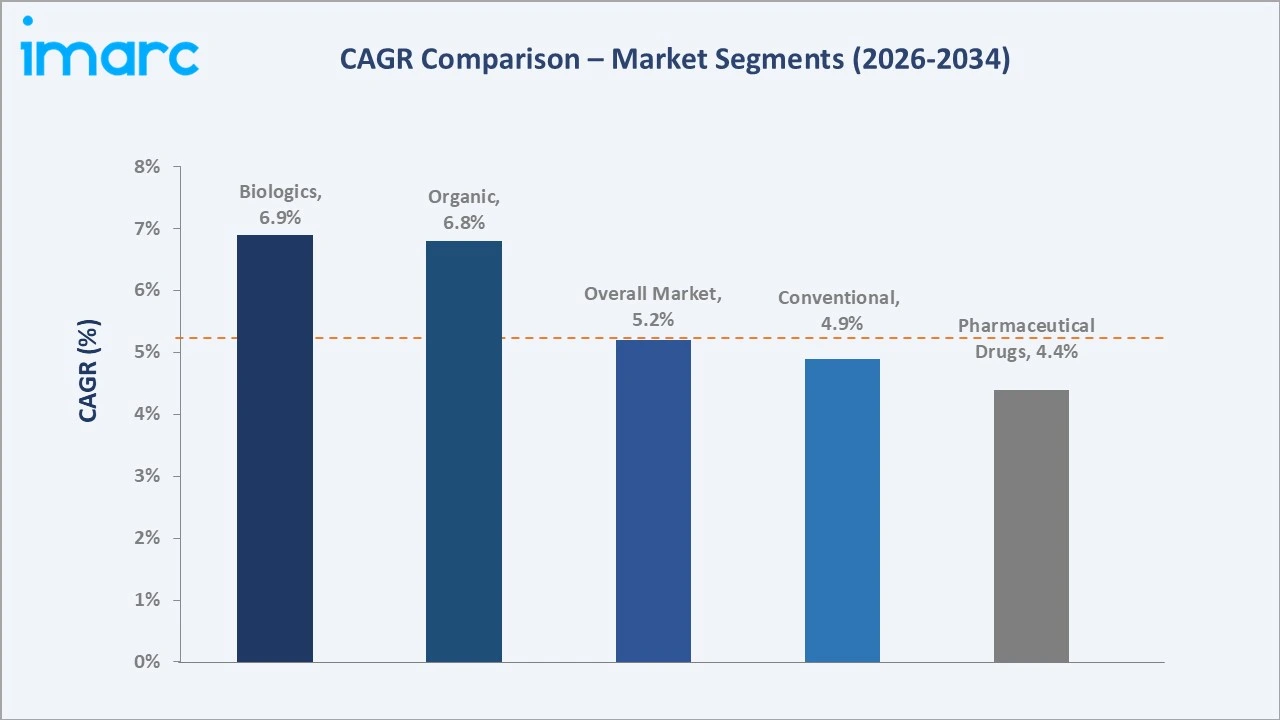
Biologics are expected to grow fastest at ~6.9% CAGR, supported by demand for cancer, immunology, and rare disease therapies. Organic products follow at ~6.8% CAGR as interest in plant-based and naturally derived formulations rises among health-conscious consumers.
Executive Summary
The Singapore pharmaceutical market expanded from USD 7.80 Billion in 2025 to an estimated USD 8.20 Billion in 2026. The pharmaceutical industry Singapore has developed over three decades now spans research, advanced manufacturing, and regional distribution, with global firms using the country as a base for Asia. Domestic demand is rising as the population ages and chronic conditions become more common, while public programs shift care toward prevention. The market is projected to reach USD 12.31 Billion by 2034. Pharmaceutical drugs at 69.8% lead through broad use in everyday care. Conventional products at 85.0% dominate prescribing. The West leads regionally at 35.8%.
Key Market Insights
|
Insight |
Data |
|
Dominant Type |
Pharmaceutical Drugs - 69.8% share (2025) |
|
Dominant Nature |
Conventional - 85.0% market share (2025) |
|
Leading Region |
West - 35.8% share (2025) |
|
Market Opportunity |
Biologics and antibody-drug conjugates; precision medicine for Asian populations; digital pharmacy and telehealth; plant-based and naturally derived products |
Key Analytical Observations Supporting the Above Data:
- Pharmaceutical Drugs at 69.8%: Pharmaceutical drugs dominate because small-molecule medicines remain the first line of treatment for most conditions, from diabetes and hypertension to infections and pain. They are widely available, well understood by prescribers, and supported by large generic supply.
- Conventional at 85.0%: Conventional products lead because hospitals, polyclinics, and general practitioners rely on clinically proven, regulator-approved medicines. Public subsidy lists and treatment guidelines are built around these products.
- West at 35.8%: The West leads regionally due to its large population base, major public hospitals, and the concentration of pharmaceutical manufacturing in Tuas Biomedical Park and Jurong.
Singapore Pharmaceutical Market Overview
Singapore is a small but highly developed pharmaceutical market with high healthcare standards, strong public institutions, and a well-funded health system. Patients receive care through public hospitals, polyclinics, private clinics, and retail pharmacies, while the country also serves as a manufacturing and logistics base for medicines sold across Asia and beyond. Most pharmaceutical output is exported, while the domestic market is served by a mix of locally made and imported medicines.
The industry ecosystem links research institutes, pharmaceutical companies in Singapore, contract manufacturers, wholesalers, regulators, and healthcare providers. Macroeconomic factors include healthcare spending, population ageing, insurance coverage, government research funding, and global trade conditions, all of which shape demand and investment. Every pharmaceutical in Singapore must be registered with the national regulator before sale, which keeps product quality and safety standards high.
Market Dynamics
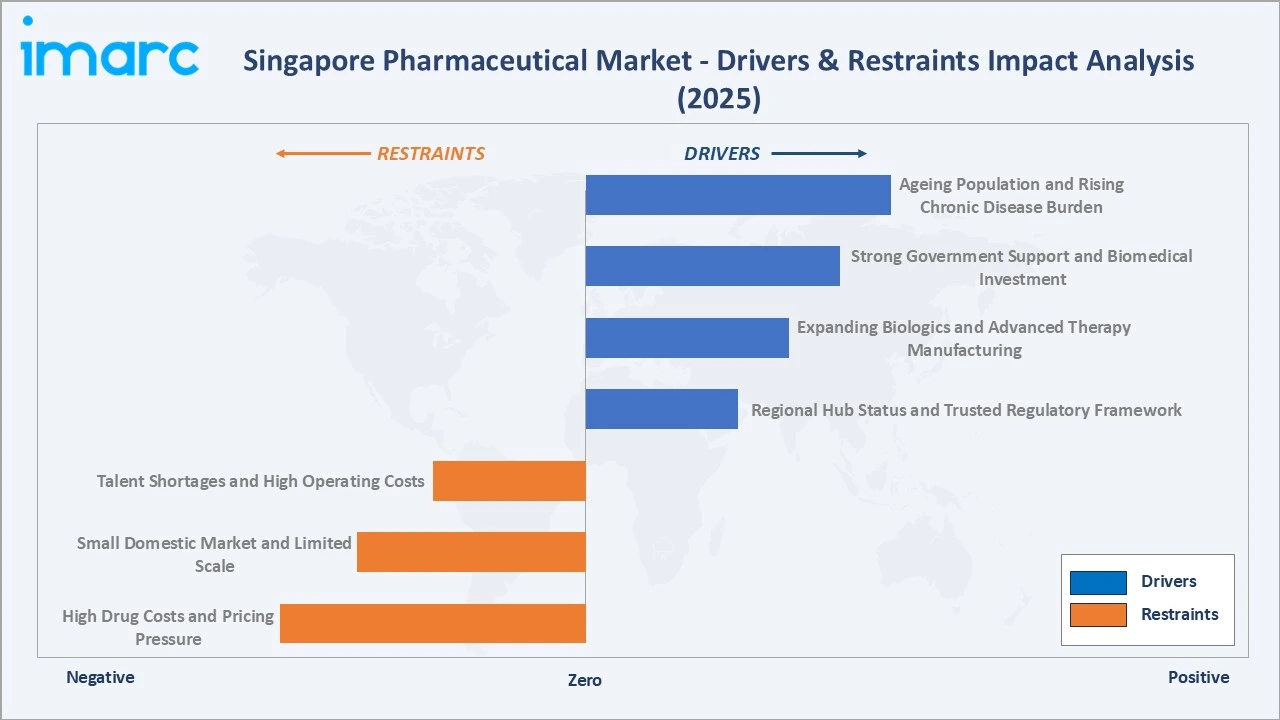
To evaluate market opportunities, Request Sample
Market Drivers
- Ageing Population and Rising Chronic Disease Burden: Singapore’s population is ageing quickly, and older adults typically use more medicines for long-term conditions such as diabetes, hypertension, high cholesterol, heart disease, and cancer. As the number of seniors grows, demand for prescription drugs, specialty therapies, and long-term disease management rises steadily. Greater health awareness and earlier diagnosis are also bringing more patients into treatment, supporting sustained growth across both hospital and community pharmacy channels. Rising life expectancy also means patients take medicines for more years, and many manage several conditions at once, which increases the number of prescriptions per person and the need for coordinated medication management.
- Strong Government Support and Biomedical Investment: The government has positioned biomedical sciences as a key economic pillar, offering research funding, investment incentives, ready-built industrial infrastructure, and talent development programs. Public research agencies and universities work closely with industry on drug discovery and manufacturing innovation. This long-term policy support gives global and local companies the confidence to invest in research centers, manufacturing plants, and regional headquarters in the country. Clear industrial planning, fast approvals for new facilities, and close coordination between government agencies further reduce the time needed to move from investment decision to commercial production.
- Expanding Biologics and Advanced Therapy Manufacturing: Singapore is building strong capabilities in biologics, vaccines, antibody-drug conjugates, and cell and gene therapies. New and expanded facilities are adding high-value production capacity and attracting specialized suppliers and service providers. Local availability of advanced therapies also improves access for patients, while the manufacturing base supports skilled jobs and deepens the wider life sciences ecosystem. Growing pipelines of complex medicines at global companies are expected to keep adding demand for this kind of specialized capacity over the coming decade.
- Regional Hub Status and Trusted Regulatory Framework: Singapore’s strategic location, world-class logistics, and strong intellectual property protection make it an attractive base for serving Asia-Pacific markets. Its regulator is known for rigorous yet efficient review processes, and its approvals are often used as a reference by neighboring countries. This reputation encourages companies to launch new medicines, run clinical trials, and centralize regional supply operations in Singapore. Political stability, a business-friendly legal system, and strong air and sea connectivity add to the appeal for companies managing time-sensitive medicine supply across many countries.
Market Restraints
- High Drug Costs and Pricing Pressure: Innovative medicines, especially biologics and cancer therapies, are expensive, and public payers are focused on value for money. Health technology assessments, subsidy listing decisions, and price negotiations can limit the prices companies achieve and slow the adoption of new treatments. Patients may also face significant out-of-pocket costs for medicines not covered by subsidy schemes. Budget pressure from an ageing population is likely to keep cost control high on the policy agenda, encouraging wider use of generics and biosimilars where clinically appropriate.
- Small Domestic Market and Limited Scale: With a population of around six million, Singapore’s domestic demand is modest compared with larger Asian markets. Some companies prioritize bigger markets for product launches, and the cost of registering and marketing a product may be high relative to local sales. Growth therefore depends partly on Singapore’s role as a regional hub rather than domestic consumption alone. Changes in regional demand or competition from other Asian manufacturing locations can therefore influence investment and growth in the local industry.
- Talent Shortages and High Operating Costs: Advanced pharmaceutical manufacturing requires specialized engineers, scientists, and quality professionals, and competition for this talent is intense. High land, labor, and utility costs also raise the cost of operating in Singapore. Companies must balance these costs against the benefits of quality, reliability, and regulatory reputation. Firms are investing in automation, training partnerships, and workforce development programs to reduce reliance on scarce skills and keep operations competitive over the long term.
Market Opportunities
- Precision Medicine and Genomics: Large genomic research programs focused on Asian populations are creating opportunities for targeted therapies, companion diagnostics, and personalized treatment. Pharmaceutical companies can use these insights to develop medicines better suited to patients across the region. Partnerships between drug developers, hospitals, and research institutes can speed the translation of genetic insights into clinical trials and approved therapies, while data-driven treatment selection can improve outcomes and reduce wasted spending on ineffective medicines.
- Digital Health, Telemedicine, and E-Pharmacy: Growing use of telemedicine, electronic prescriptions, and online pharmacy services is making it easier for patients to access medicines and follow treatment plans. Digital tools also support medication adherence and chronic disease management programs. As digital literacy rises among older adults, these services are expected to reach a much larger share of patients, creating new channels for pharmaceutical companies to support patients after a medicine is prescribed and to improve long-term treatment results.
Market Challenges
- Patent Expiries and Generic Competition: As key branded medicines lose patent protection, lower-cost generics and biosimilars enter the market and quickly reduce prices. Companies must replace lost revenue with new products, which requires sustained investment in research and late-stage pipelines. Biosimilar entry for major biologic therapies is expected to intensify price competition in hospital settings, although it also widens patient access and frees up healthcare budgets for newer innovative treatments.
- Supply Chain and Geopolitical Risks: Singapore relies heavily on imported raw materials and global trade routes. Shipping disruptions, trade tensions, and export restrictions can affect the availability of ingredients and finished medicines, encouraging companies and authorities to build safety stocks and diversify suppliers. Building regional manufacturing redundancy, holding strategic stockpiles of critical medicines, and improving supply visibility through digital tracking are becoming priorities for both industry and public health planners.
Emerging Market Trends
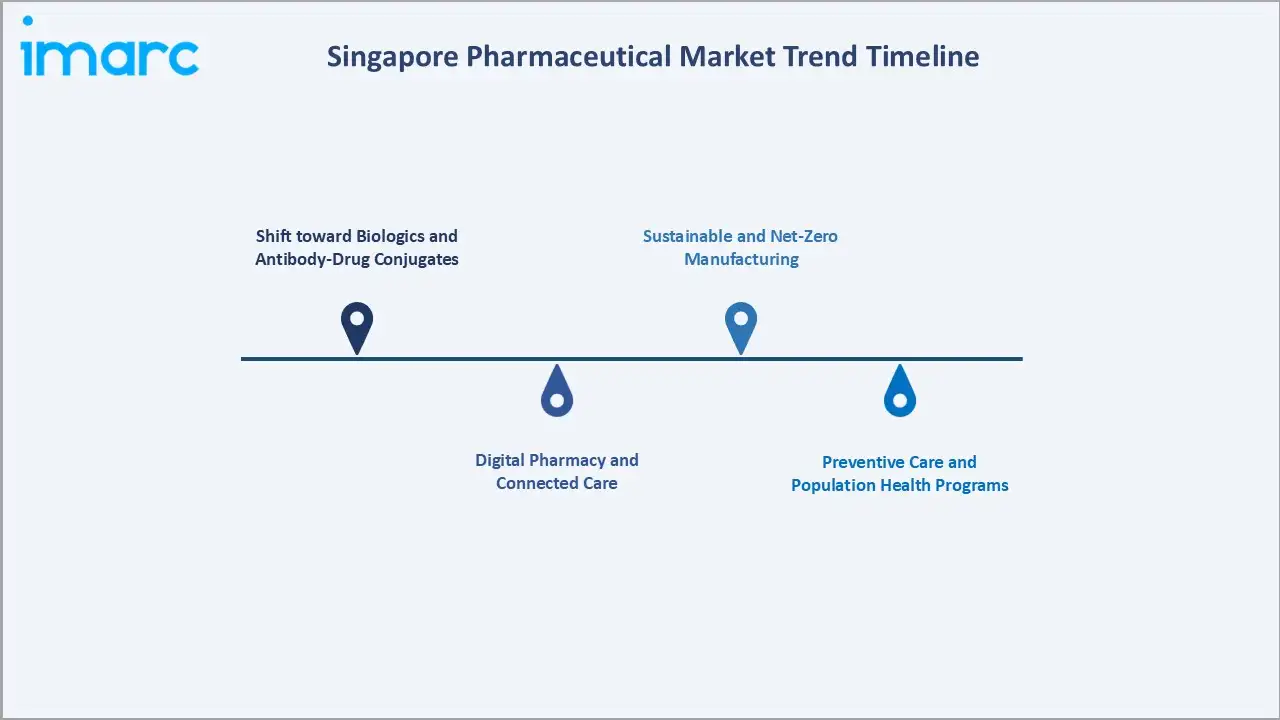
1. Shift toward Biologics and Antibody-Drug Conjugates
Manufacturing and demand are moving toward complex biologic medicines, including monoclonal antibodies, vaccines, and antibody-drug conjugates that deliver targeted cancer treatment. These products require advanced facilities, specialized skills, and strict quality systems. Their growth is raising the value of production in Singapore and expanding treatment options for patients with cancer, immune disorders, and rare diseases. As more of these products move from clinical development to commercial supply, demand for specialized talent, analytical testing, and sterile fill-finish capacity is expected to rise in parallel.
2. Digital Pharmacy and Connected Care
Telemedicine consultations, online medicine delivery, electronic health records, and mobile health apps are changing how patients receive and manage medicines. These tools improve convenience, support adherence, and help healthcare providers monitor chronic conditions remotely, especially for elderly and busy working patients. Integration of pharmacy services with national health records also allows clinicians to review medication histories more easily, reducing the risk of duplication and harmful drug interactions.
3. Sustainable and Net-Zero Manufacturing
Pharmaceutical manufacturers are designing plants that use less energy and water, generate less waste, and rely more on renewable power. Green chemistry, solvent recovery, and digital process controls are becoming standard. Sustainability is now a key factor in site selection and investment decisions for global companies. Facilities that combine energy efficiency with automation and smart building systems can also lower operating costs over their lifetime, offsetting part of the higher upfront investment.
4. Preventive Care and Population Health Programs
Healthcare policy is shifting from treating illness to preventing it, with greater focus on screening, vaccination, early diagnosis, and long-term management through family doctors. This shift supports steady demand for chronic disease medicines and vaccines while encouraging better use of medicines in the community. Closer collaboration between family doctors, pharmacists, and hospitals is expected to improve continuity of care and help patients manage long-term conditions with fewer complications and hospital admissions.
Industry Value Chain Analysis
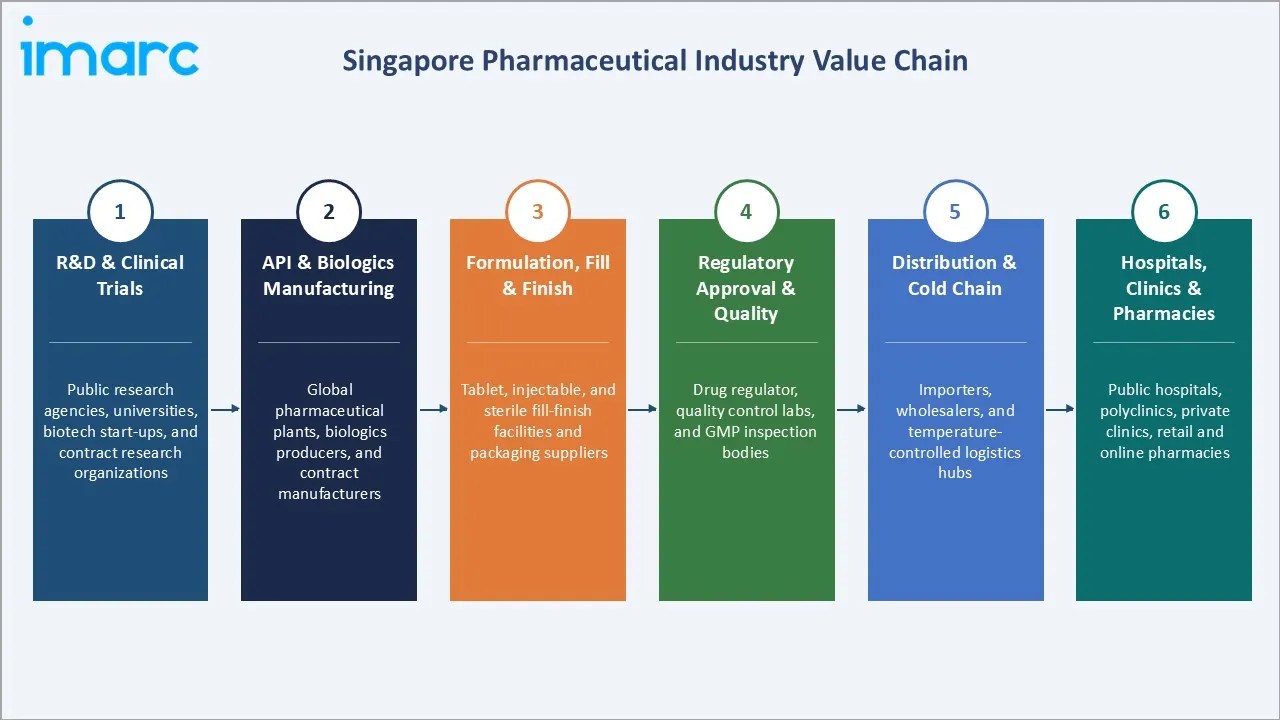
The Singapore pharmaceutical value chain spans research and clinical trials, active ingredient and biologics manufacturing, formulation and fill-finish, regulatory approval, cold-chain distribution, and dispensing through hospitals, clinics, and pharmacies. Value is concentrated in advanced manufacturing and in the innovation that creates new medicines.
|
Stage |
Key Participants |
|
R&D & Clinical Trials |
Public research agencies, universities, biotech start-ups, and contract research organizations |
|
API & Biologics Manufacturing |
Global pharmaceutical plants, biologics producers, and contract manufacturers |
|
Formulation, Fill & Finish |
Tablet, injectable, and sterile fill-finish facilities and packaging suppliers |
|
Regulatory Approval & Quality |
Drug regulator, quality control labs, and GMP inspection bodies |
|
Distribution & Cold Chain |
Importers, wholesalers, and temperature-controlled logistics hubs |
|
Hospitals, Clinics & Pharmacies |
Public hospitals, polyclinics, private clinics, retail and online pharmacies |
Advanced manufacturing is the most consequential stage of the chain. Large active ingredient and biologics plants generate most of the industry’s output value and exports, and they anchor a wider network of suppliers, service providers, and skilled jobs that support the whole ecosystem. Distribution is also critical, as many biologics and vaccines require uninterrupted cold-chain handling from the factory to the patient.
Technology Landscape in the Singapore Pharmaceutical Industry
Continuous Manufacturing and Industry 4.0
Pharmaceutical plants are adopting continuous manufacturing, automation, process analytical technology, and digital twins to improve quality, speed, and efficiency. Real-time monitoring allows faster release of products and reduces waste. These technologies help manufacturers offset high labor costs and maintain the reliability expected of a global supply base. Advanced data platforms also strengthen compliance with good manufacturing practice requirements by providing complete, traceable records for every production batch.
Biologics, Cell, and Gene Therapy Platforms
Single-use bioreactors, flexible modular facilities, and advanced purification systems are enabling efficient production of biologics and vaccines. New platforms for cell and gene therapies, mRNA, and antibody-drug conjugates require highly controlled environments and specialized handling of potent compounds, opening a new generation of high-value manufacturing. Flexible multi-product facilities allow manufacturers to switch between products more quickly, helping them respond to changing demand and to support smaller-volume specialty and orphan medicines.
AI in Drug Discovery and Digital Health
Artificial intelligence and data analytics are being used to identify drug targets, design molecules, optimize clinical trials, and predict patient responses. In healthcare delivery, digital records, e-prescriptions, and remote monitoring tools help clinicians track outcomes and improve how medicines are used. Combining real-world data with clinical evidence is expected to support more efficient drug development and better-informed subsidy and treatment decisions over time.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Type |
Pharmaceutical Drugs |
69.8% |
2025 |
|
Nature |
Conventional |
85.0% |
2025 |
|
Region |
West |
35.8% |
2025 |

By Type
Pharmaceutical drugs lead at 69.8% (2025). Small-molecule medicines treat most common conditions, including diabetes, hypertension, infections, and pain. Their affordability, ease of use, and wide availability through hospitals, clinics, and pharmacies keep them central to care. Generic versions of widely used medicines also help control costs for patients and public healthcare institutions.
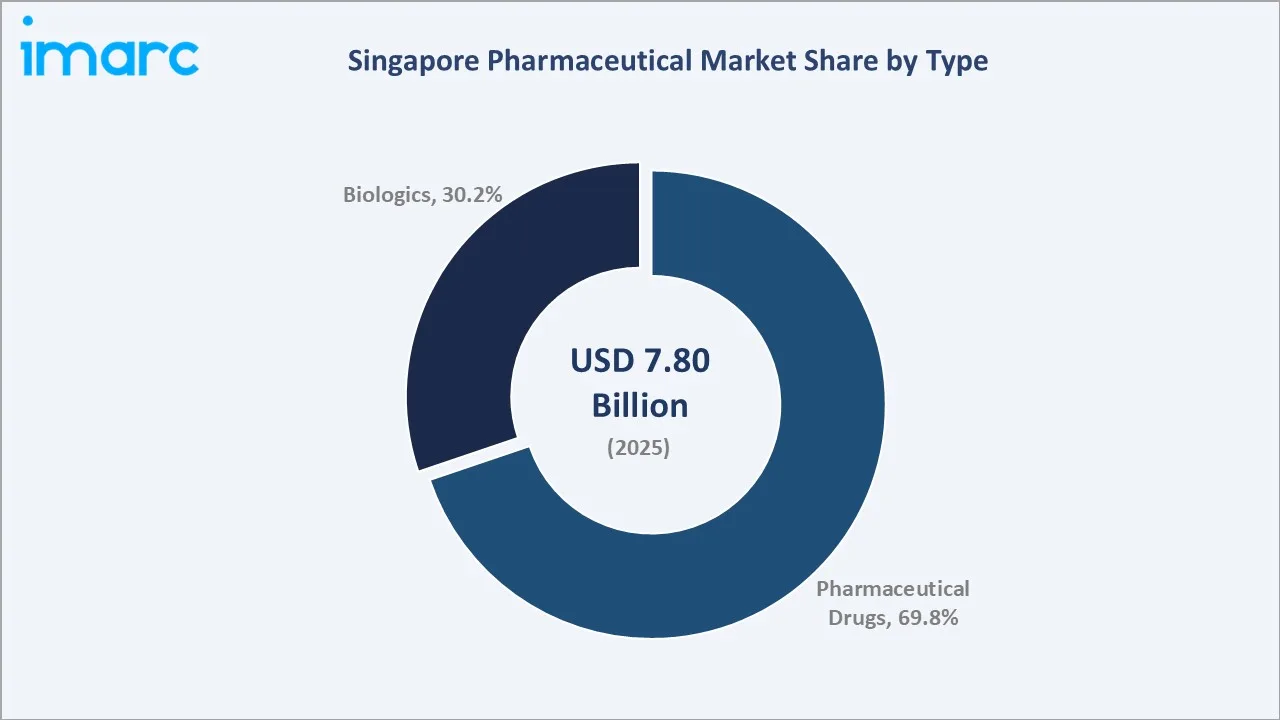
To access detailed market analysis, Request Sample
Biologics at 30.2% are growing fastest at ~6.9% CAGR, driven by cancer, autoimmune, and rare disease treatments. Expanding local manufacturing of antibodies, vaccines, and conjugates, along with growing biosimilar availability, supports rising use.
By Nature
Conventional products lead at 85.0% (2025). Hospitals and clinics rely on clinically proven, regulator-approved medicines, and national subsidy lists and treatment guidelines are built around them. Their established safety and efficacy keep them dominant. Prescribers and patients place high trust in these medicines, supported by long clinical experience and strong safety monitoring.
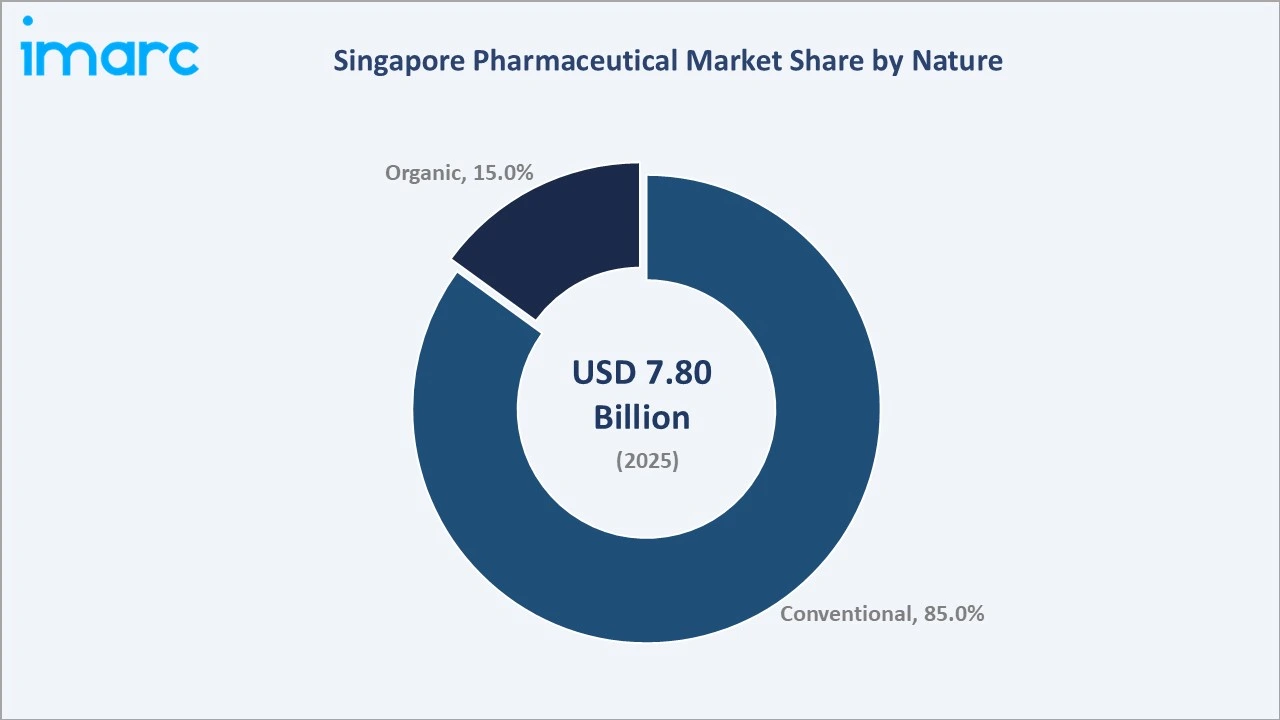
Organic products at 15.0% are growing at ~6.8% CAGR, supported by consumer interest in plant-based, naturally derived, and clean-label formulations, particularly in supplements, wellness, and complementary health products.
Regional Market Insights
|
Region |
Share (2025) |
Key Singapore Pharmaceutical Market Drivers & Characteristics |
|
West |
35.8% |
Manufacturing hub in Tuas and Jurong, large housing estates, and major public hospitals. |
|
Central |
30.4% |
Research and business districts, specialist hospitals, and dense retail pharmacy networks. |
|
North-East |
13.2% |
Young families in new towns, expanding hospitals, and growing community clinics. |
|
East |
11.8% |
Mature estates with older residents, regional hospitals, and air logistics links. |
|
North |
8.8% |
Growing population in northern towns and new integrated health campuses. |
The West's 35.8% market leadership reflects its large residential population and the concentration of pharmaceutical manufacturing in Tuas Biomedical Park and Jurong. The Central region's 30.4% reflects its research clusters, specialist hospitals, and high density of private clinics and pharmacies. Strong demand for premium and specialty medicines in the Central region is supported by private hospitals and medical tourism.
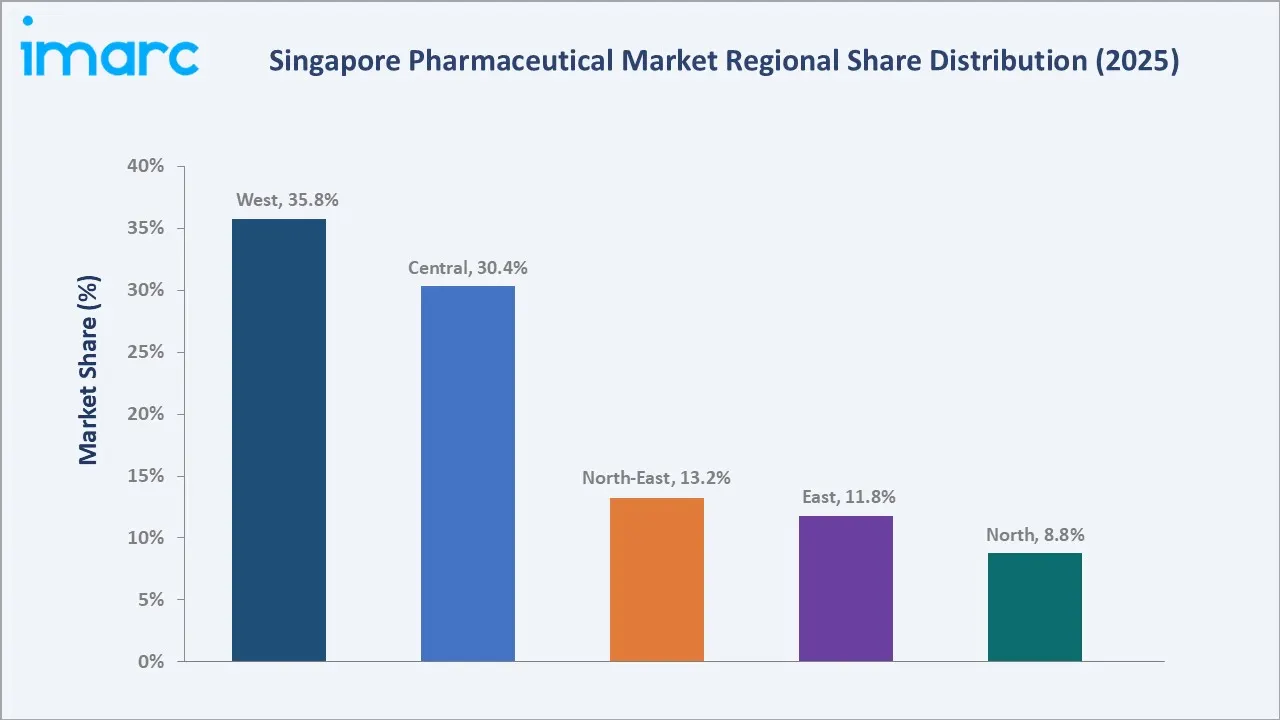
The North-East's 13.2% and the East's 11.8% reflect growing and ageing residential populations served by regional hospitals. The North's 8.8% is the smallest share, but new healthcare facilities and population growth support steady demand. Ongoing housing development and better transport links are expected to lift healthcare demand in these regions over the forecast period.
Competitive Landscape
The Singapore pharmaceutical market is led by global pharmaceutical companies that combine local manufacturing with commercial operations, alongside generic suppliers, regional distributors, and biotech start-ups. Competition centers on innovation, product pipelines, manufacturing quality, and access to public subsidy lists. Many pharmaceutical companies in Singapore also use the country as a launch market and regional headquarters for Southeast Asia.
|
Company |
Key Brands |
Market Position |
Core Strength |
|
Pfizer Inc. |
Ibrance, Prevnar 20, Eliquis, Paxlovid |
Market Leader |
Large API manufacturing base in Tuas and a broad specialty portfolio. |
|
AstraZeneca |
Tagrisso, Imfinzi, Forxiga, Enhertu |
Market Leader |
Strong oncology pipeline and upcoming ADC production in Singapore. |
|
GSK plc |
Shingrix, Arexvy, Trelegy Ellipta |
Market Leader |
Three local manufacturing sites with leading vaccines capabilities. |
|
Novartis AG |
Entresto, Kisqali, Cosentyx |
Strong Challenger |
Biologics manufacturing in Singapore and innovative medicines focus. |
|
Amgen Inc. |
Repatha, Prolia, Evenity |
Innovator |
Advanced biologics manufacturing and biotechnology expertise. |
|
Sanofi |
Dupixent, Lantus, Toujeo |
Strong Challenger |
Immunology and diabetes strength with vaccines expertise. |
|
Merck & Co., Inc. |
Keytruda, Gardasil 9, Januvia |
Strong Challenger |
Leading immuno-oncology and vaccines portfolio. |
The most important competitive dynamic is the move toward complex biologics and specialty medicines. Companies with local manufacturing, strong pipelines, and subsidy listings are best placed to grow, while generic suppliers compete mainly on price. Partnerships with local research institutes, hospitals, and contract manufacturers are becoming an important way for companies to strengthen their position.
Key Company Profiles
Pfizer Inc.
Pfizer Inc. is one of the largest pharmaceutical companies in Singapore. It has operated in Singapore since 1964 and runs an active pharmaceutical ingredient plant and a regional headquarters for emerging Asian markets.
- Key Brands: Ibrance, Prevnar 20, Eliquis, Paxlovid.
- Recent Developments: Pfizer opened an SGD 1 billion extension of its API facility in Tuas Biomedical Park, producing small-molecule ingredients for oncology, pain, and antibiotic medicines.
- Strategic Focus: Expanding automated manufacturing and supplying global markets from its Singapore base.
AstraZeneca
AstraZeneca is a UK-based global biopharmaceutical company focused on the discovery, development, and commercialisation of innovative medicines, with a strong presence in oncology and other major therapeutic areas.
- Key Brands: Tagrisso, Imfinzi, Forxiga, Enhertu.
- Recent Developments: AstraZeneca plans to invest USD 1.5 billion in Singapore to establish its first end-to-end antibody-drug conjugate (ADC) manufacturing facility, with operations targeted to begin in 2029. The facility is designed to achieve zero carbon emissions from its first day of operations, supporting sustainable pharmaceutical manufacturing.
- Strategic Focus: Building advanced cancer medicine supply capacity and sustainable manufacturing in Asia.
GSK plc
GSK plc has been present in Singapore for more than 60 years. It operates three manufacturing sites in Jurong, Quality Road, and Tuas, including Singapore’s first vaccines plant.
- Key Brands: Shingrix, Arexvy, Trelegy Ellipta.
- Recent Developments: GSK opened a SGD 44 million high-potency manufacturing and testing facility at its Jurong site for next-generation cancer treatments.
- Strategic Focus: Expanding vaccines and specialty medicines manufacturing while advancing digital and sustainable production.
Market Concentration Analysis
The Singapore pharmaceutical market is moderately concentrated in innovative medicines, where a group of global companies holds a large share of hospital and specialty sales. The generic segment is more fragmented, with many regional suppliers and distributors competing for public tenders and pharmacy sales. Distribution networks are also consolidating, as larger wholesalers invest in cold-chain capacity and digital ordering systems to serve hospitals and pharmacies more efficiently.
Market concentration is evolving through two opposing forces: large investments in biologics and specialty manufacturing strengthen leading global players, while patent expiries, biosimilars, and new biotech entrants increase competition. Public procurement and subsidy decisions also influence market shares, as products listed on national formularies gain wider use in public institutions.
Investment & Growth Opportunities
Highest Growth Segments
Biologics (~6.9% CAGR through specialty therapies), organic products (~6.8% CAGR through natural health demand), the West (~5.8% CAGR through manufacturing and population growth), and the North (~5.5% CAGR through new healthcare facilities) represent the highest-growth investment areas in the Singapore pharmaceutical market through 2034.
Emerging Investment Opportunities
Antibody-drug conjugates and cell and gene therapies are among the most promising opportunities. Singapore’s skilled workforce, regulatory reputation, and infrastructure make it well suited for these complex products, and each new pharmaceutical in Singapore manufactured at scale strengthens its position as an Asian supply hub.
Investment Themes
- Contract development and manufacturing capacity: Demand from biotech firms for outsourced biologics, ADC, and sterile fill-finish capabilities offers long-term growth.
- Digital pharmacy and chronic care platforms: Telehealth, e-pharmacy, and adherence tools serve a growing elderly population and support the shift of the Singapore pharmaceuticals market toward community-based care.
Future Market Outlook (2026-2034)
The Singapore pharmaceutical market is projected to grow from USD 7.80 Billion in 2025 to USD 8.20 Billion in 2026, reaching USD 12.31 Billion by 2034, registering a CAGR of 5.09% during 2026-2034. The anchor value of USD 10.00 Billion in 2030 marks a point at which biologics should account for a larger share of sales. By then, digital pharmacy services and preventive care programs should also be well established across the population.
Three structural forces define Singapore pharmaceutical market growth through 2034: rising demand from an ageing population; continued investment in advanced manufacturing; and the shift toward preventive, digital, and personalized care.
Research Methodology
Primary Research
Primary research comprised structured interviews with industry stakeholders, including pharmaceutical executives, manufacturing and quality specialists, hospital pharmacists, distributors, and regulatory consultants, along with inputs from healthcare providers across all regions of Singapore.
Secondary Research
Secondary research covered company annual reports, government health and population statistics, trade data, regulatory publications, and industry association reports. Over 50 credible secondary sources were reviewed, compared, and cross-checked for accuracy.
Forecasting Models
Market revenue forecasts were developed using a demand-based model: patient population by therapy area multiplied by treatment rates and average medicine spending for each type and nature, with segment results aggregated to total market value. Assumptions were expertly validated.
Singapore Pharmaceutical Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report | Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered |
|
| Natures Covered | Organic, Conventional |
| Regions Covered | North-East, Central, West, East, North |
| Companies Covered | Pfizer Inc., AstraZeneca, GSK plc, Novartis AG, Amgen Inc., Sanofi, Merck & Co., Inc., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Singapore pharmaceutical market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Singapore pharmaceutical market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Singapore pharmaceutical industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Singapore Pharmaceutical Market Report
The Singapore pharmaceutical market size is estimated at USD 8.20 Billion in 2026, supported by an ageing population, government support, and growing biologics use.
The Singapore pharmaceutical market grows at 5.09% CAGR during 2026-2034, reaching USD 12.31 Billion by 2034.
Pharmaceutical drugs lead at 69.8%, supported by their wide use in treating common and chronic conditions.
Conventional products lead at 85.0%, owing to their proven efficacy and central role in treatment guidelines.
The West leads at 35.8%, driven by its large population and pharmaceutical manufacturing clusters.
Leading companies include Pfizer Inc., AstraZeneca, GSK plc, Novartis AG, Amgen Inc., Sanofi, and Merck & Co., Inc., among others.
The Singapore pharmaceutical market is projected to reach approximately USD 10.00 Billion by 2030, with biologics gaining share.
Three priority opportunities stand out: antibody-drug conjugates and advanced therapies, contract manufacturing capacity, and digital pharmacy and chronic care platforms.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade