
United States 3D Printing Market Size, Share, Trends and Forecast by Component, Process, Technology, Application, Vertical, and Region, 2026-2034
United States 3D Printing Market Size, Share, Trends & Forecast (2026-2034)
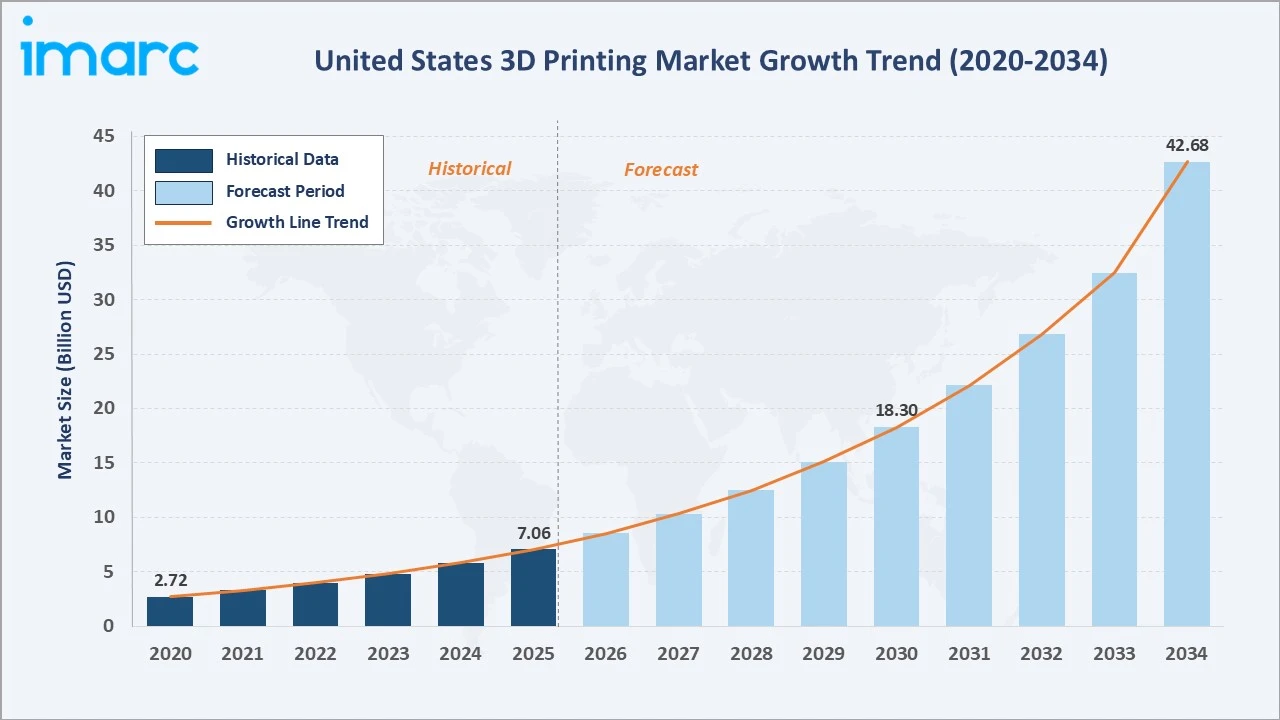
The US 3D printing market grew from USD 7.06 Billion in 2025 and is estimated at USD 8.54 Billion in 2026, projected to reach USD 42.68 Billion by 2034, growing at a CAGR of 21.03% during 2026-2034. The 3D printing United States market is driven by rapid technology adoption across aerospace, healthcare, and industrial manufacturing. Increasing demand for rapid prototyping, on-demand parts production, and supply chain digitization continues to accelerate additive manufacturing integration. Growing investments from defense and aerospace primes in metal AM for lightweighted structural components are a critical demand driver.
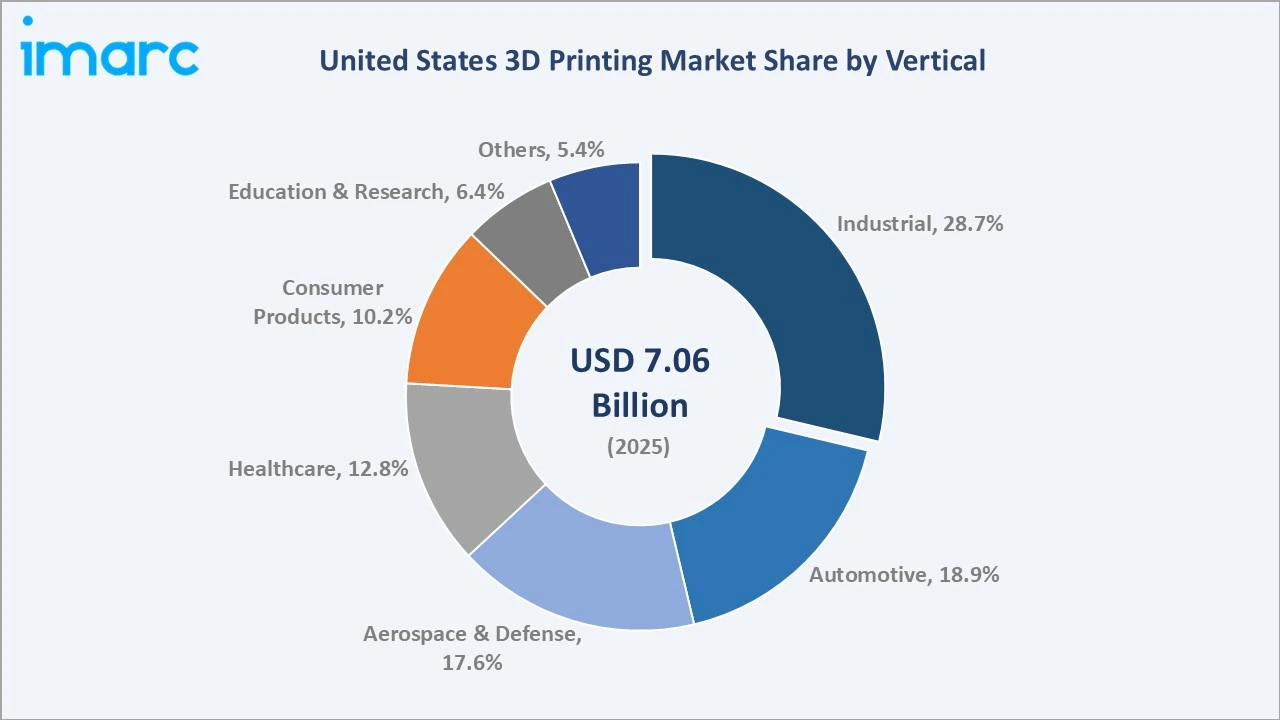
The expansion of bioprinting in medical device production and surgical planning further broadens total addressable market size. Software advances in generative design and simulation are reducing barriers to AM adoption across verticals. Prototyping dominates at 46.8% of applications, Industrial commands 28.7% by vertical, and Northeast leads regionally at 28.4%.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 7.06 Billion |
|
Market Size (2026) |
USD 8.54 Billion |
|
Forecast Market Size (2034) |
USD 42.68 Billion |
|
CAGR (2026-2034) |
21.03% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Application |
Prototyping (46.8%, 2025) |
|
Dominant Vertical |
Industrial (28.7%, 2025) |
|
Leading Region |
Northeast (28.4%, 2025) |
The US 3D printing market size increased from USD 2.72 Billion in 2020 to USD 7.06 Billion in 2025. The market is estimated at USD 8.54 Billion in 2026, expected to grow to USD 18.33 Billion by 2030 and USD 42.68 Billion by 2034. The United States remains the world's largest additive manufacturing market, underpinned by strong R&D investment, established industrial base, and early enterprise adoption of advanced manufacturing technologies.
To get more information on this market, Request Sample
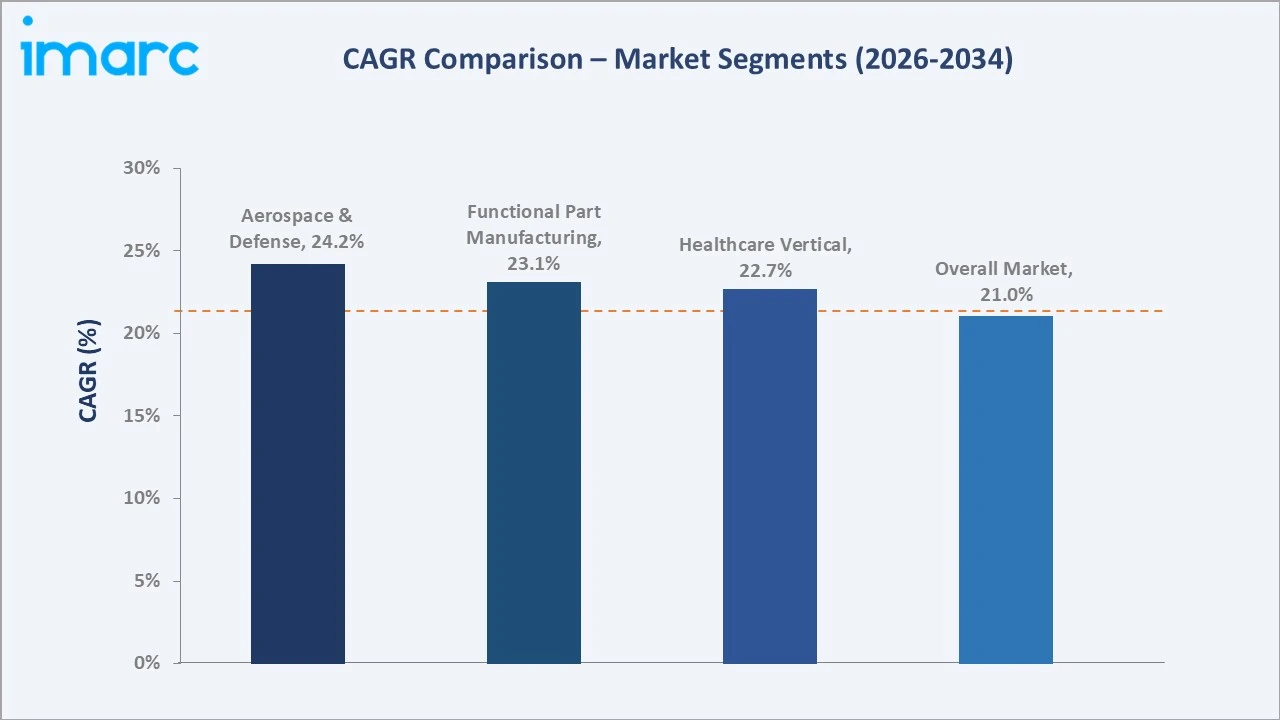
Aerospace and Defense vertical grows fastest at ~24.2% CAGR through DoD additive manufacturing program scaling, certified flight hardware production adoption by US defense primes, and lightweighted metal AM structural component qualification under military specifications. Healthcare grows at ~22.7% CAGR driven by FDA clearances for patient-specific implants, hospital in-house AM center expansions, and bioprinting commercialization accelerating clinical deployment of 3D-printed surgical guides and anatomical models. Industrial Machinery at ~21.5% CAGR through rapid tooling adoption, spare parts digitization replacing legacy inventory, and on-demand manufacturing integration into US factory automation workflows.
Executive Summary
The US 3D printing market expanded from USD 7.06 Billion in 2025 to an estimated USD 8.54 Billion in 2026, driven by accelerating enterprise adoption across aerospace, defense, healthcare, and automotive sectors. The 3D printing United States market continues to benefit from strong federal investment in advanced manufacturing, Department of Defense additive manufacturing programs, and growing adoption of metal AM for production applications. The convergence of AI-powered generative design with advanced AM hardware is enabling engineers to produce geometrically complex, lightweight parts that traditional manufacturing cannot achieve. Healthcare institutions are deploying patient-specific implants and surgical guides at scale, while aerospace primes are transitioning from prototyping to certified flight hardware production. Digital supply chain initiatives are accelerating demand for distributed on-demand manufacturing capabilities across industrial verticals.
The market is projected to reach USD 42.68 Billion by 2034, registering a CAGR of 21.03% during 2026-2034. Prototyping leads applications at 46.8%, Industrial leads verticals at 28.7%, and Northeast leads regionally at 28.4%.
Key Market Insights
|
Insight |
Data |
|
Dominant Application |
Prototyping – 46.8% share (2025) |
|
Dominant Vertical |
Industrial – 28.7% market share (2025) |
|
Leading Region |
Northeast – 28.4% share (2025) |
|
Market Opportunity |
Metal AM adoption; healthcare bioprinting; aerospace lightweighting; distributed manufacturing via digital supply chains |
Key Analytical Observations Supporting the Above Data:
- Prototyping at 46.8%: Dominates due to established rapid prototyping workflows across industrial, automotive, and consumer product design cycles. Short iteration cycles and material breadth make AM the preferred prototyping technology across US enterprises.
- Industrial Vertical at 28.7%: Industrial segment leadership reflects broad adoption of AM for custom tooling, jigs, fixtures, and low-volume specialty parts, driven by total cost of ownership advantages over traditional manufacturing for complex geometries.
- Northeast at 28.4%: Reflects concentration of technology companies, medical institutions, defense contractors, and advanced manufacturing firms in the Boston-New York-Philadelphia corridor driving premium adoption.
United States 3D Printing Market Overview
The US 3D printing market is the world's largest additive manufacturing market, supported by the broadest installed base of AM hardware, the deepest pool of AM-trained engineers, and the strongest federal investment in advanced manufacturing technology. The market encompasses polymer, metal, ceramic, and composite additive manufacturing systems.
The US 3D printing market serves aerospace and defense, healthcare, automotive, industrial, consumer products, and education verticals through prototyping, functional part manufacturing, and tooling applications. The United States leads globally in metal AM adoption and bioprinting technology development.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
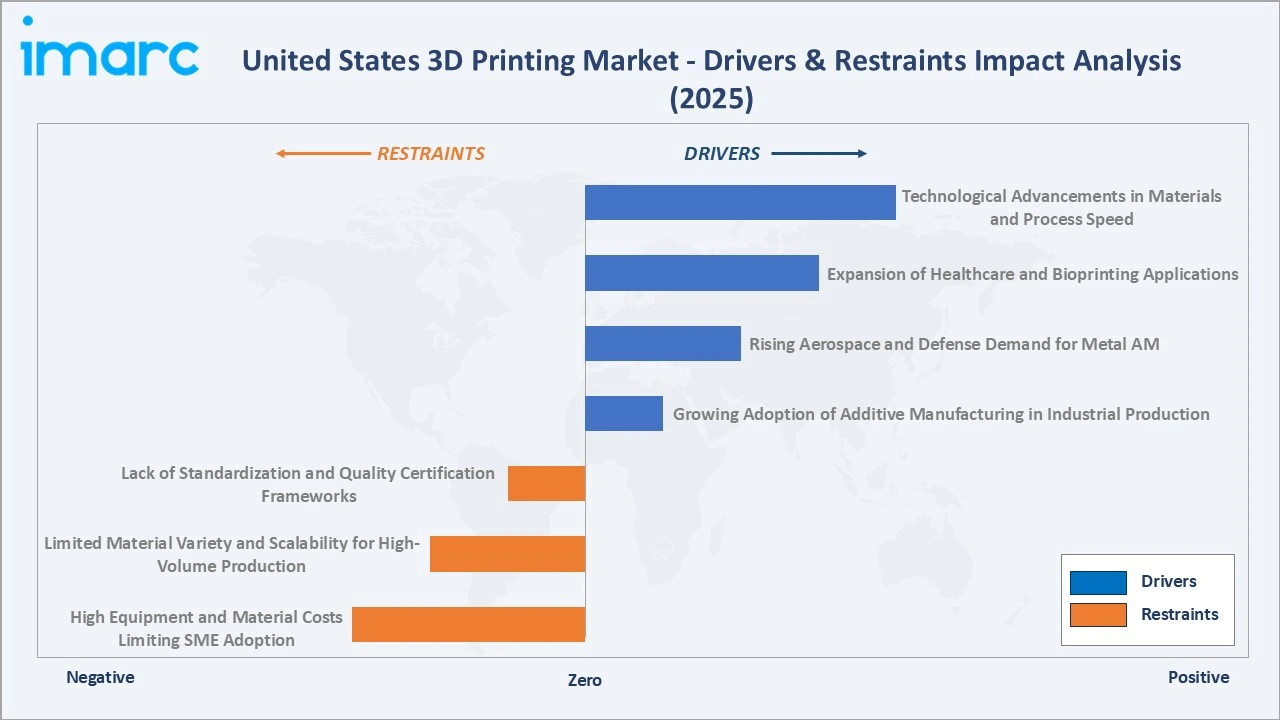
- Growing Adoption of Additive Manufacturing in Industrial Production: Enterprises are transitioning from prototyping to end-use part production, driven by total cost advantages for complex geometries, low-volume requirements, and supply chain flexibility. This shift expands the total addressable market for the US 3D printing market beyond traditional prototyping applications. Manufacturers are increasingly deploying AM for on-demand spare parts, reducing inventory carrying costs and production downtime. The growing availability of production-grade AM systems with validated repeatability metrics is accelerating enterprise deployment across discrete manufacturing industries.
- Rising Aerospace and Defense Demand for Metal AM: Aerospace primes and defense contractors are adopting metal additive manufacturing for lightweighted structural components, heat exchangers, and bracket assemblies. DoD programs promoting AM adoption and FAA certification pathways for AM flight hardware are accelerating aerospace segment penetration in the 3D printing United States market. Programs such as the Air Force's Advanced Manufacturing Olympics and NASA's in-space manufacturing initiatives are validating AM for mission-critical applications. Long-term supply agreements between AM hardware OEMs and defense primes are creating multi-year revenue visibility and expanding the certified AM parts catalog across platforms.
- Expansion of Healthcare and Bioprinting Applications: Patient-specific medical implants, surgical guides, dental prosthetics, and pharmaceutical applications are driving healthcare AM adoption. FDA regulatory frameworks for medical AM are maturing, reducing approval timelines and expanding the clinical deployment pipeline for bioprinted products. Hospital networks are establishing in-house AM centers for on-demand surgical planning models and patient-customized orthopedic devices. Growing reimbursement recognition for AM-produced medical devices is improving healthcare provider economics and accelerating procurement.
- Technological Advancements in Materials and Process Speed: New high-performance polymers, metal alloys, and composite materials are expanding application addressability. Process speed improvements through parallel printing, binder jetting, and Digital Light Synthesis technologies are enabling production-scale AM economics across industrial verticals. Continuous investment in material characterization databases and simulation tools is reducing qualification timelines for new AM materials. The commercialization of multi-material and functionally graded AM systems is unlocking application categories that single-material processes cannot address.
Market Restraints
- High Equipment and Material Costs Limiting SME Adoption: Industrial AM systems and specialty materials carry significant capital and operating costs that limit small and medium enterprise adoption. Total cost of ownership relative to conventional manufacturing remains unfavorable for high-volume, low-complexity parts, constraining market expansion beyond premium segments. The recurring cost of proprietary materials under OEM-locked ecosystems adds ongoing expenditure that reduces return on investment for cost-sensitive manufacturers. Leasing and as-a-service business models are beginning to address access barriers, but broader SME adoption requires further equipment cost reduction.
- Limited Material Variety and Scalability for High-Volume Production: Current AM material portfolios lack the breadth of conventional manufacturing inputs, limiting application addressability. Production throughput constraints relative to injection molding and CNC machining restrict AM penetration in high-volume manufacturing applications within the US 3D printing market. Material qualification for regulated applications is time-intensive, as each new alloy or polymer formulation requires independent testing and certification documentation. The absence of a standardized material data exchange format across AM platforms increases qualification burden for multi-supplier manufacturing environments.
- Lack of Standardization and Quality Certification Frameworks: Inconsistent part quality across machines, operators, and material batches creates quality assurance challenges for regulated industries. The absence of universal AM quality standards complicates certification for aerospace, medical, and defense applications, slowing production adoption. While ASTM and ISO have published foundational AM standards, sector-specific standards for flight hardware and medical implants remain incomplete, creating manufacturer-specific qualification requirements. Non-destructive testing and in-process monitoring capabilities must mature further before automated quality assurance can replace manual inspection at production scale.
Market Opportunities
- Digital Supply Chain and Distributed Manufacturing: The transition to digital-first supply chains is creating demand for distributed on-demand AM production networks. Parts-on-demand platforms that eliminate inventory, reduce lead times, and localize production represent a structural growth opportunity for service bureau and platform business models within the 3D printing United States market. MRO providers, military logistics commands, and industrial equipment manufacturers are converting physical spare parts libraries into secure digital inventories accessible from certified production nodes globally. Intellectual property protection technologies including blockchain-based file authentication and encrypted print licenses are removing adoption barriers for proprietary part owners.
- Bioprinting and Regenerative Medicine Applications: Advances in bioink materials and organ-on-chip technologies are opening transformative opportunities in regenerative medicine. Federal funding for biofabrication research and growing venture capital investment in bioprinting startups signal an emerging high-value application segment with decades-long growth potential. Clinical-stage bioprinting companies are advancing vascularized tissue constructs toward human trials, with commercial skin graft and cartilage repair products approaching market entry. Long-term success in printing functional organs would represent a category-defining breakthrough, significantly expanding the total addressable market of the US 3D printing market.
Market Challenges
- Post-Processing Complexity and Labor Intensity: Most AM processes require significant post-processing including support removal, surface finishing, heat treatment, and inspection, adding cost and time that partially offsets AM speed advantages. Automating post-processing remains a major technical challenge limiting AM economics in production environments. Robotic de-powdering, automated support removal, and integrated heat treatment systems are under active development but have not yet reached widespread commercial deployment. Until post-processing automation reaches parity with AM print speed improvements, total cycle time and labor cost will continue to constrain the economics of high-volume AM production.
- Skilled Workforce Gap in Additive Manufacturing: The rapid growth of the US 3D printing market has outpaced workforce development, creating a shortage of AM-trained engineers, technicians, and quality specialists. Closing the skills gap requires sustained investment in educational programs and corporate training pipelines aligned to production AM requirements. Community college and university AM programs are expanding but face curriculum standardization challenges, as AM technology evolves faster than academic course development cycles. Industry consortia and AM-specific apprenticeship programs are emerging as near-term responses, but systemic workforce development will require multi-year investment from both public and private stakeholders.
Emerging Market Trends
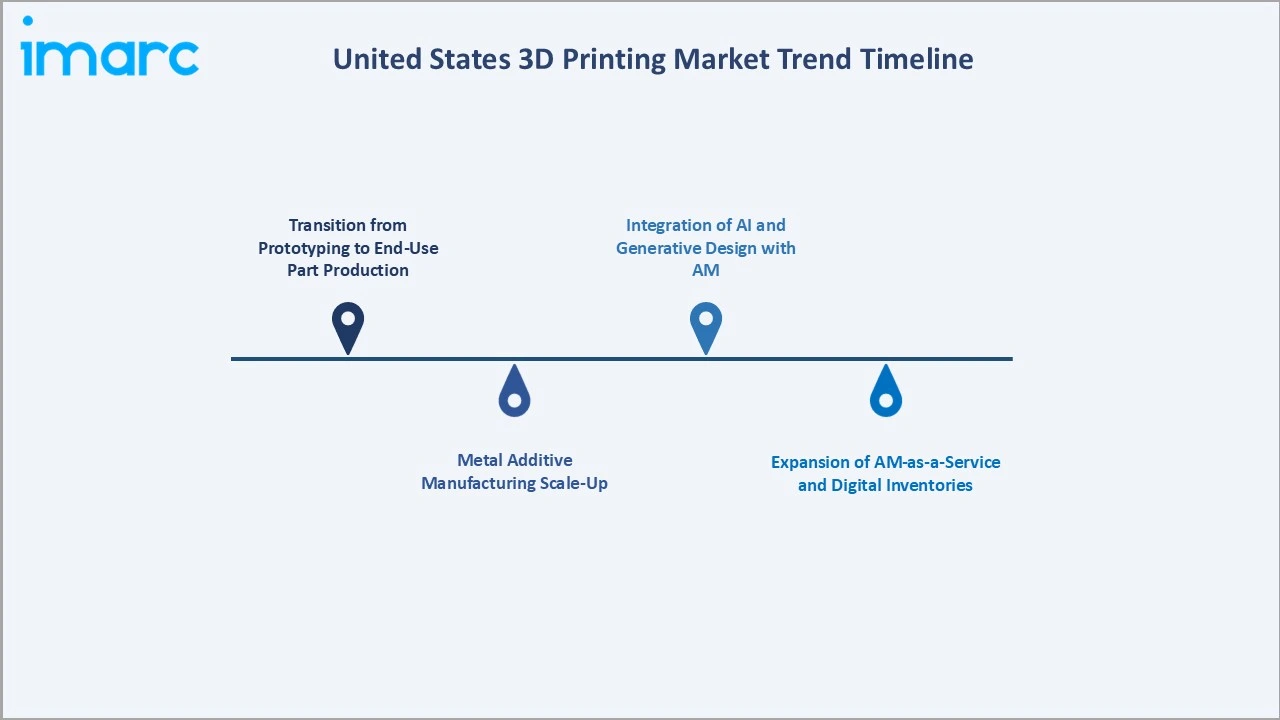
1. Transition from Prototyping to End-Use Part Production
Industrial and aerospace customers are deploying AM for certified production parts as material properties, process repeatability, and certification frameworks mature. This transition is the most significant structural shift in the US 3D printing market, expanding addressable revenue per customer from prototyping budgets to capital expenditure programs. As part qualification processes become more streamlined, enterprises are achieving faster time-to-production for AM-manufactured components across automotive, consumer goods, and defense applications. The increasing availability of AM-specific design guidelines and process validation software is reducing the engineering effort required to certify new parts, lowering the barrier to production AM adoption across verticals.
Companies investing early in production AM are establishing durable competitive advantages through cycle time reduction, weight savings on shipped products, and the ability to economically manufacture low-volume variants that conventional tooling cannot justify. This competitive differentiation is accelerating peer adoption across manufacturing industries and sustaining above-market growth in the functional part manufacturing application segment.
2. Integration of AI and Generative Design with AM
AI-powered generative design tools are producing geometrically optimized part designs that can only be manufactured via additive processes. The convergence of generative software with metal and polymer AM hardware is enabling engineers to achieve weight, thermal, and structural performance levels unreachable by conventional manufacturing. Design for additive manufacturing (DfAM) automation tools are reducing the specialized engineering expertise required to leverage AM geometry freedoms, democratizing access to topology-optimized designs across a wider engineer population. AI-driven process parameter optimization is also improving first-part success rates, reducing material waste and machine time in production deployments.
The growing integration of AM software with PLM and ERP platforms is enabling seamless digital thread traceability from initial design through production and quality inspection. This end-to-end data continuity is particularly critical for regulated industries, where complete manufacturing records are required for certification, and is positioning AI-enhanced AM as a compliance-enabling technology in aerospace and medical device production.
3. Metal Additive Manufacturing Scale-Up
Binder jetting, laser powder bed fusion, and directed energy deposition technologies are achieving production economics at scale, driven by Boeing, GE Aerospace, and Raytheon Technologies deployments. Metal AM revenue is growing fastest within the 3D printing United States market, with aerospace and defense applications leading adoption. Continued investment in multi-laser LPBF systems and high-throughput binder jetting platforms is driving cost-per-part reductions that expand the economically addressable application space. Feedstock quality consistency and alloy qualification programs run by material suppliers and standards bodies are providing the validated material data manufacturers need to deploy metal AM with confidence.
The development of in-situ process monitoring and closed-loop control systems is improving metal AM part quality consistency, reducing rejection rates that previously increased effective production costs. As machine reliability, build speed, and material costs continue to improve through the forecast period, metal AM is expected to achieve broad economic competitiveness with CNC machining for low-to-medium volume complex part production in the 3D printing United States market.
4. Expansion of AM-as-a-Service and Digital Inventories
Cloud-based AM service bureaus and digital inventory platforms are enabling enterprises to convert physical spare parts into on-demand digital assets. MRO providers, military logistics commands, and industrial equipment manufacturers are adopting digital warehousing to reduce inventory carrying costs and improve supply chain resilience. Secure digital part libraries with certified print instructions allow organizations to produce parts on-demand at distributed locations, eliminating minimum order quantities and obsolescence risk associated with traditional inventory models. The economics of digital inventory are particularly compelling for long-tail spare parts with unpredictable demand patterns and high per-unit logistics costs.
Platform business models aggregating AM capacity across certified production nodes are creating network effects that improve order fulfillment speed and geographic coverage. As the number of qualified AM production facilities grows and digital rights management technology matures, the addressable market for AM-as-a-service will expand significantly, providing an additional high-margin revenue stream alongside hardware and materials within the US 3D printing market.
Industry Value Chain Analysis
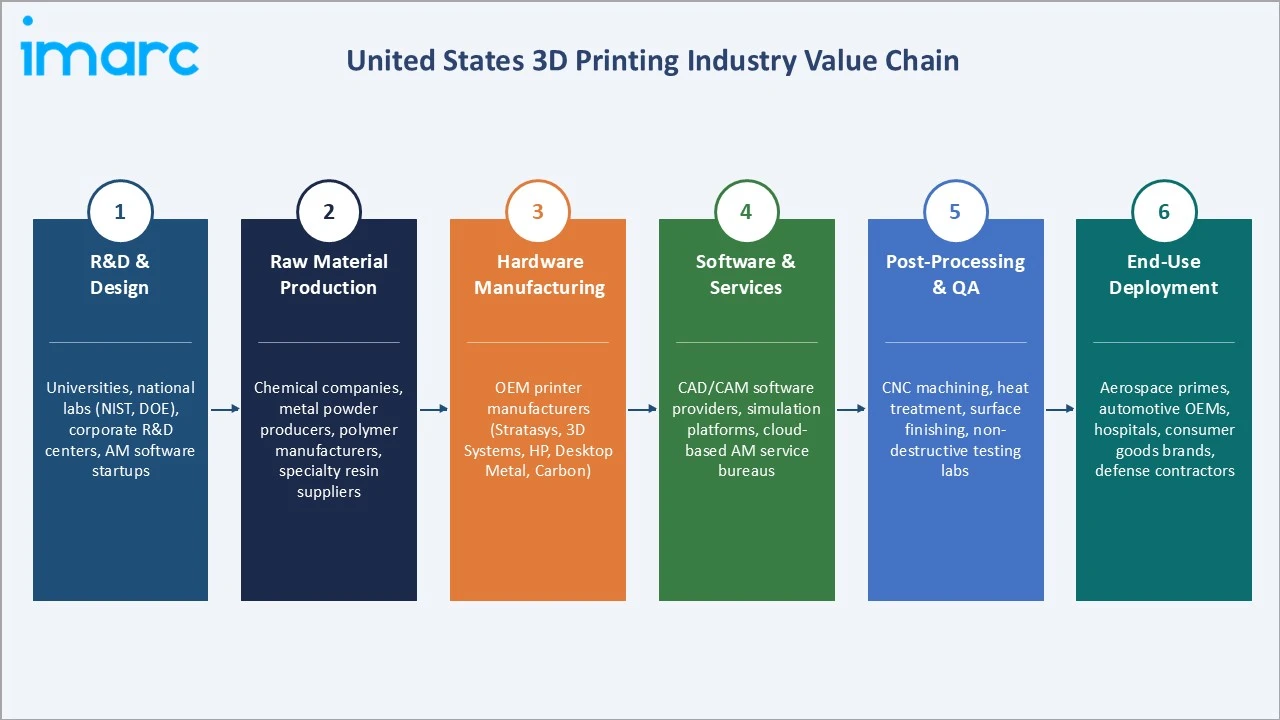
The US 3D printing market value chain integrates materials science, hardware engineering, software development, post-processing services, and end-use application deployment into a complex ecosystem spanning startups, industrial conglomerates, and federal research institutions.
|
Stage |
Key Participants |
|
R&D & Design |
Universities, national labs (NIST, DOE), corporate R&D centers, AM software startups |
|
Raw Material Production |
Chemical companies, metal powder producers, polymer manufacturers, specialty resin suppliers |
|
Hardware Manufacturing |
OEM printer manufacturers (Stratasys, 3D Systems, HP, Desktop Metal, Carbon) |
|
Software & Services |
CAD/CAM software providers, simulation platforms, cloud-based AM service bureaus |
|
Post-Processing & QA |
CNC machining, heat treatment, surface finishing, non-destructive testing labs |
|
End-Use Deployment |
Aerospace primes, automotive OEMs, hospitals, consumer goods brands, defense contractors |
The end-use deployment stage is commercially decisive for the US 3D printing market, as enterprise adoption decisions by aerospace primes, hospital systems, and automotive OEMs create multi-year hardware, material, and service contracts that sustain growth across the entire value chain.
Technology Landscape in the US 3D Printing Industry
Polymer Additive Manufacturing Technologies
Fused deposition modeling (FDM), stereolithography (SLA), selective laser sintering (SLS), and Digital Light Synthesis (DLS) are the dominant polymer AM technologies in the US market. Material advances in high-performance engineering polymers, continuous fiber composites, and biocompatible resins are expanding production application addressability across aerospace, healthcare, and industrial verticals in the US 3D printing market. Next-generation photopolymer resins with engineering-grade mechanical properties and chemical resistance are enabling structural end-use applications previously limited to thermoplastic extrusion systems. Investment in high-temperature polymer systems capable of replacing metal in thermal management applications is further broadening the addressable application space for polymer AM in the 3D printing United States market. Multi-material polymer systems that deposit rigid, flexible, and support materials simultaneously are enabling integrated assembly designs that reduce part counts and assembly labor in industrial production environments.
Metal Additive Manufacturing Technologies
Laser powder bed fusion (LPBF), binder jetting, directed energy deposition (DED), and bound metal deposition are accelerating metal AM adoption in the US market. GE Aerospace's LEAP engine fuel nozzle, Boeing's titanium structural components, and Raytheon's heat exchangers exemplify production-scale metal AM deployment transforming the 3D printing United States competitive landscape. Advances in multi-laser LPBF systems are delivering build rate improvements that reduce per-part cost, making metal AM economically competitive with precision CNC machining across a wider range of complex geometries. Directed energy deposition systems are gaining adoption for large-format structural component fabrication and in-field repair of high-value components in energy, naval, and aerospace maintenance applications. Emerging cold spray and electrochemical AM processes are expanding the metal AM technology portfolio, addressing applications where thermal distortion from fusion processes limits feasibility.
Software and Digital Thread Technologies
CAD/CAM software, simulation platforms, build preparation tools, and quality management systems form the digital backbone of US AM operations. Generative design, topology optimization, and digital twin technologies are driving differentiation, enabling design-for-AM workflows that produce superior structural and thermal performance in production parts. Build simulation software that predicts thermal residual stresses, distortion, and support structure requirements before physical printing is reducing material waste and machine time for high-value metal AM production. Process monitoring and anomaly detection systems leveraging machine learning are improving in-process quality assurance, enabling real-time intervention that prevents defective builds from consuming full machine cycles. The maturation of AM-specific model-based definition (MBD) standards is enabling fully digital part qualification workflows that will significantly accelerate certification timelines for regulated industries within the US 3D printing market.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Application |
Prototyping |
46.8% |
2025 |
|
Component |
Printer |
🔒 |
2025 |
|
Process |
Direct Energy Deposition |
🔒 |
2025 |
|
Technology |
Stereolithography |
🔒 |
2025 |
|
Vertical |
Industrial |
28.7% |
2025 |
|
Region |
Northeast |
28.4% |
2025 |

By Vertical
Industrial leads at 28.7% (2025). The industrial vertical encompasses custom tooling, jigs, fixtures, machine components, and low-volume specialty parts. Broad enterprise adoption across manufacturing facilities drives consistent demand for polymer and metal AM systems throughout the forecast period.
To access detailed market analysis, Request Sample
Aerospace and Defense at 17.6% grows fastest at ~24.2% CAGR through DoD AM programs and certified flight hardware production scaling. Healthcare at 12.8% grows at ~22.7% CAGR driven by patient-specific implants and bioprinting regulatory approvals.
By Application
Prototyping leads at 46.8% (2025), reflecting the established role of AM in product development workflows across all verticals. Prototyping adoption is universal among US industrial enterprises, automotive OEMs, and consumer product companies.
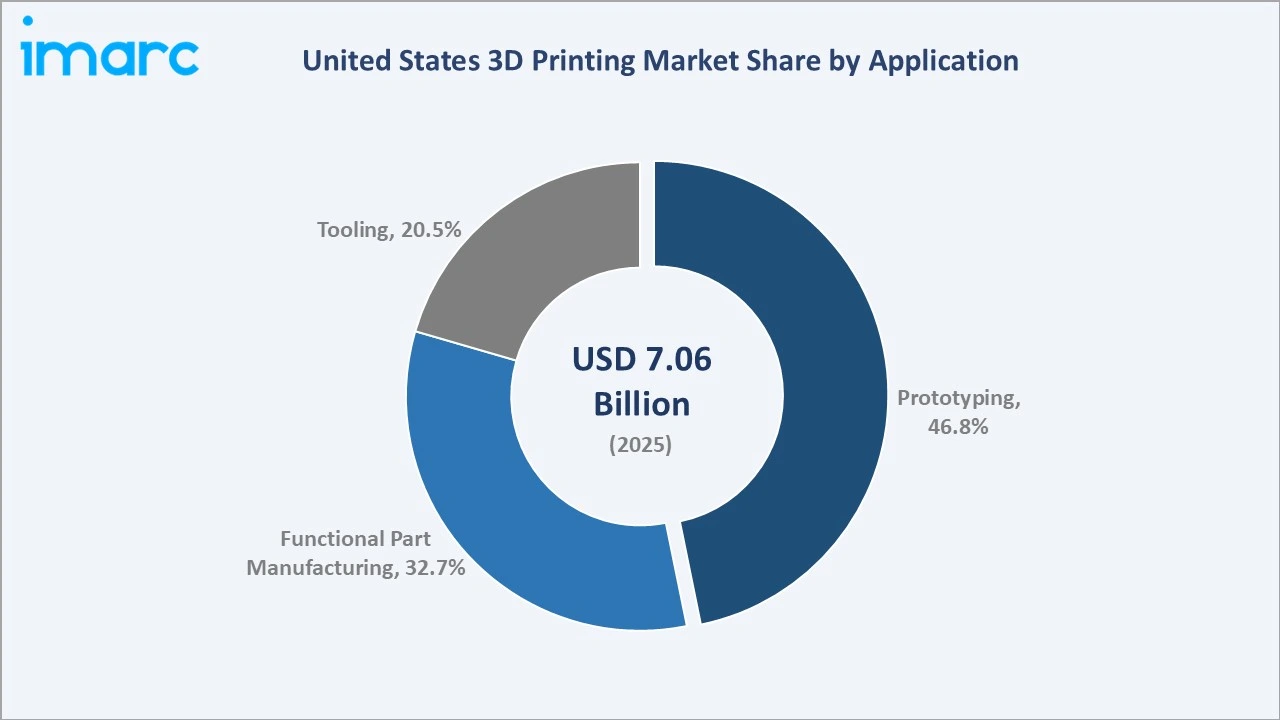
Functional Part Manufacturing at 32.7% is the fastest-growing application segment, driven by enterprise transitions from prototyping to production in the US 3D printing market. Tooling at 20.5% benefits from custom tooling economics advantages over traditional machining for low-volume and complex geometry requirements.
Regional Market Insights
|
Region |
Share (2025) |
Key US 3D Printing Market Drivers & Characteristics |
|
Northeast |
28.4% |
Home to major technology clusters (Boston, New York), leading medical institutions, defense contractors, and early-adopter industrial manufacturers driving premium AM adoption. |
|
West |
27.6% |
Silicon Valley innovation ecosystem, aerospace and defense supply chains (Boeing, Lockheed Martin), and concentration of AM software and hardware startups accelerating adoption. |
|
South |
25.8% |
Strong aerospace and defense manufacturing base (Texas, Florida), automotive supplier networks, and growing energy sector AM applications in oil and gas equipment. |
|
Midwest |
18.2% |
Traditional automotive manufacturing hub (Michigan, Ohio) rapidly integrating AM for tooling, prototyping, and spare parts, with growing industrial machinery adoption. |
Northeast's 28.4% market leadership reflects the Boston-Cambridge biomedical AM cluster, New York's consumer product design sector, and Connecticut's aerospace and defense manufacturing base anchored by Pratt & Whitney and Sikorsky deployments. West's 27.6% is driven by Silicon Valley's AM software ecosystem, Boeing and SpaceX's Southern California production deployments, and Pacific Northwest aerospace manufacturing.
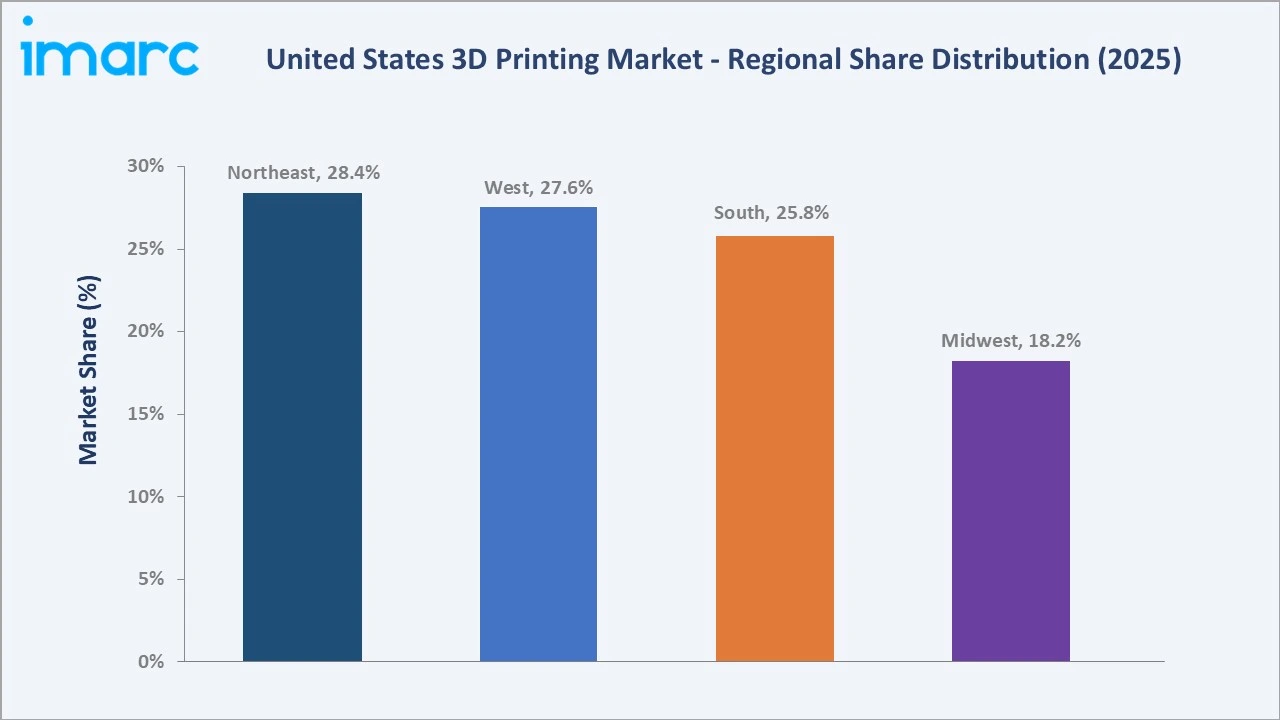
South's 25.8% reflects Texas's oil and gas AM adoption, Florida's aerospace and space AM deployment, and growing industrial clusters in Georgia and North Carolina. Midwest's 18.2% is growing above the market CAGR as Michigan's automotive OEMs accelerate AM integration for tooling and spare parts.
Competitive Landscape
The US 3D printing market competitive landscape features a mix of established AM OEMs, high-growth technology innovators, and service bureau platforms. Competition is intensifying as industrial conglomerates including HP and GE enter the market with high-throughput production systems targeting displacement of traditional manufacturing.
|
Company |
Key Products |
Market Position |
Core Strength |
|
Stratasys Ltd. |
FDM, PolyJet, SAF, Neo stereolithography systems |
Market Leader |
Global leader in polymer AM systems for industrial, aerospace, and healthcare applications with the broadest installed base. |
|
3D Systems Corporation |
SLA, SLS, DMP metal, Figure 4 systems |
Strong Challenger |
Pioneer of 3D printing offering comprehensive solutions spanning dental, healthcare, aerospace, and industrial manufacturing. |
|
Desktop Metal Inc. |
Studio System, Production System, binder jetting |
Innovator |
Disrupting metal AM with office-friendly and high-throughput production binder jetting systems for mass manufacturing applications. |
|
Carbon Inc. |
Carbon DLS (Digital Light Synthesis) systems |
Innovator |
Pioneering continuous liquid interface production (CLIP) technology enabling production-grade polymer parts with superior mechanical properties. |
|
HP Inc. |
Multi Jet Fusion (MJF) |
Strong Challenger |
Leveraging 2D printing expertise to deliver high-speed multi-material polymer and metal AM systems targeting production scale. |
The competitive landscape is evolving as material science innovators, software platform companies, and manufacturing-as-a-service providers create new value chain positions in the US 3D printing market. This is intensifying differentiation competition beyond hardware, with materials ecosystems, software subscriptions, and service bureau networks becoming primary competitive dimensions.
Key Company Profiles
Stratasys Ltd.
Stratasys Ltd. is the global leader in polymer additive manufacturing, offering FDM, PolyJet, SAF, and Neo stereolithography platforms for industrial, aerospace, healthcare, and education applications in the US 3D printing market.
- Key Products: Fortus industrial FDM systems, J Series PolyJet printers, SAF H350 production system, Neo stereolithography systems, Origin One photopolymer platform.
- Recent Developments: In September 2026, Stratasys announced that its additive manufacturing solutions would be deployed across more than 20 General Motors (GM) manufacturing facilities in the United States. The rollout will use industrial 3D printing to produce customized manufacturing tools, helping improve production efficiency, reduce tooling costs, and accelerate factory-floor operations.
- Strategic Focus: Expanding production AM capabilities, deepening aerospace and defense certifications, growing subscription software revenue, and expanding its materials portfolio for high-performance engineering applications.
3D Systems Corporation
3D Systems Corporation is a pioneer of additive manufacturing, offering a comprehensive portfolio spanning SLA, SLS, DMP metal, and Figure 4 systems for dental, healthcare, aerospace, and industrial manufacturing applications.
- Key Products: ProX DMP metal systems, Figure 4 photopolymer production platform, SLA 750 systems, ProJet MJP printers, Next Dent dental AM systems.
- Recent Developments: In August 2026, 3D Systems Corporation received a US$9 million contract award from the U.S. Air Force to develop an advanced large-format metal 3D printing system. The initiative aims to advance high-efficiency additive manufacturing for large, complex metal components, supporting U.S. defense production capabilities and strengthening domestic aerospace and defense supply chains.
- Strategic Focus: Deepening vertical integration in healthcare and dental, expanding DMP metal AM for aerospace and defense, and growing its on-demand manufacturing services business.
Market Concentration Analysis
The US 3D printing market is moderately concentrated at the hardware level, with Stratasys, 3D Systems, and HP collectively representing an estimated 45-50% of industrial AM system revenues. Service bureau and software segments are more fragmented, with numerous regional and specialized players competing on technology, certification, and vertical expertise.
Market concentration is shifting as production-focused challengers including Desktop Metal, Carbon, and HP pursue displacement of Stratasys and 3D Systems in high-volume applications. Software and materials companies are emerging as structurally important positions, as printer OEM margins face commoditization pressure and recurring materials and software revenues grow in importance within the US 3D printing market.
Investment & Growth Opportunities
Highest Growth Segments
Aerospace and Defense Vertical (~24.2% CAGR through DoD programs and flight hardware certification), Healthcare Vertical (~22.7% CAGR through bioprinting and patient-specific devices), Functional Part Manufacturing (~23.1% CAGR through production AM transition), and Metal AM platforms represent the US 3D printing market's highest-growth investment vectors through 2034.
Emerging Investment Opportunities
The digital inventory and distributed manufacturing platform segment represents the US 3D printing market's most transformative commercial opportunity. Enterprises converting physical spare parts inventories into on-demand digital assets are creating subscription revenue models that generate recurring cash flows beyond hardware and material transactional revenues.
Investment Themes
- Metal AM production platform scaling: Binder jetting and LPBF production systems targeting automotive, aerospace, and industrial displacement of conventional metal manufacturing represent the highest-value investment category in the 3D printing United States market, with demonstrated unit economics at production scale.
- Bioprinting and medical AM regulatory pathway: FDA approval pathway maturation for AM-produced medical devices and bioprinted tissues represents a decade-long growth investment theme with potential to create entirely new medical product categories within the US 3D printing market.
Future Market Outlook (2026-2034)
The US 3D printing market is projected to grow from USD 7.06 Billion in 2025 to USD 8.54 Billion in 2026, reaching USD 18.33 Billion by 2030 and USD 42.68 Billion by 2034, registering a CAGR of 21.03% during 2026-2034. The inflection from prototyping to production-scale AM deployment marks the defining structural shift of the forecast period in the 3D printing United States market.
Three forces define growth through 2034: enterprise transitions from prototyping to production AM creating multiplicative per-customer revenue expansion; metal AM economics reaching parity with conventional manufacturing across a widening range of applications; and healthcare bioprinting advancing toward clinical deployment, opening a new high-value market segment within the US 3D printing market.
Research Methodology
Primary Research
Primary research comprised structured interviews with US 3D printing market stakeholders including AM hardware manufacturers, material suppliers, service bureau operators, enterprise AM adopters, and subject matter experts across aerospace, healthcare, and industrial verticals. Surveys were conducted across Northeast, West, South, and Midwest regions.
Secondary Research
Secondary research encompassed ASTM and ISO AM standards documentation, Department of Defense additive manufacturing roadmaps, FDA guidance documents for AM medical devices, company annual reports, patent filings, and industry association publications. Over 50 secondary sources were reviewed covering the US 3D printing market.
Forecasting Models
Market revenue forecasts were developed using a vertical-application matrix model: AM system shipment volumes by technology type multiplied by average system prices and material consumption rates, supplemented by a productivity multiplier for service bureau revenue and software subscription growth components.
United States 3D Printing Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report | Exploration of Historical and Forecast Trends, Industry Catalysts and Challenges, Segment-Wise Historical and Predictive Market Assessment:
|
| Components Covered |
|
| Processes Covered | Binder Jetting, Directed Energy Deposition, Material Extrusion, Material Jetting, Powder Bed Fusion, Sheet Lamination, Others. |
| Technologies Covered | Stereolithography, Selective Laser Sintering, Electron Beam Melting, Fused Deposition Modeling, Laminated Object Manufacturing, Others |
| Applications Covered | Prototyping, Tooling, Functional Part Manufacturing |
| Verticals Covered | Consumer Products, Industrial, Aerospace and Defense, Automotive, Healthcare, Education and Research, Others |
| Regions Covered | Northeast, Midwest, South, West |
| Companies Covered | Stratasys Ltd., 3D Systems Corporation, Desktop Metal Inc., Carbon Inc., HP Inc., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the United States 3D printing market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the United States 3D printing market.
- The study maps the leading, as well as the fastest-growing, regional markets.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the United States 3D printing industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the United States 3D Printing Market Report
The US 3D printing market size is estimated at USD 8.54 Billion in 2026, driven by accelerating enterprise adoption across aerospace, defense, healthcare, and industrial manufacturing verticals. The transition from prototyping to production AM applications is expanding total addressable market size significantly.
The US 3D printing market grows at a CAGR of 21.03% during 2026-2034, reaching USD 42.68 Billion by 2034. Growth is driven by metal AM production scaling, healthcare bioprinting expansion, and digital supply chain adoption across the 3D printing United States market.
Prototyping leads at 46.8% through universal adoption in product development workflows across automotive, consumer products, aerospace, and industrial design cycles, driven by AM speed, geometry freedom, and iteration cost advantages over conventional prototyping methods.
Industrial leads at 28.7% through broad adoption of AM for custom tooling, jigs, fixtures, and specialty parts across US manufacturing facilities, driven by total cost advantages for low-volume and geometrically complex applications in the US 3D printing market.
Northeast leads at 28.4% through the Boston biomedical AM cluster, Connecticut aerospace manufacturing base, and New York consumer product design sector driving premium AM adoption across healthcare, aerospace, and industrial verticals in the 3D printing United States market.
Leading companies include Stratasys Ltd., 3D Systems Corporation, Desktop Metal Inc., Carbon Inc., and HP Inc., among others.
The US 3D printing market is projected to reach USD 18.33 Billion by 2030, with metal AM production systems, aerospace and defense applications, and healthcare bioprinting growing fastest, as enterprises complete prototyping-to-production AM transitions across industrial verticals.
Three priority investment themes: Metal AM production platform scaling targeting displacement of conventional manufacturing at production economics; healthcare bioprinting regulatory pathway advancing toward clinical deployment; and digital inventory and distributed manufacturing platforms creating recurring subscription revenue models in the 3D printing United States market.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade