
United States Dental Insurance Market Size, Share, Trends and Forecast by Type, Coverage, Demographics, End User, and Region, 2026-2034
United States Dental Insurance Market Size, Share, Trends & Forecast (2026-2034)
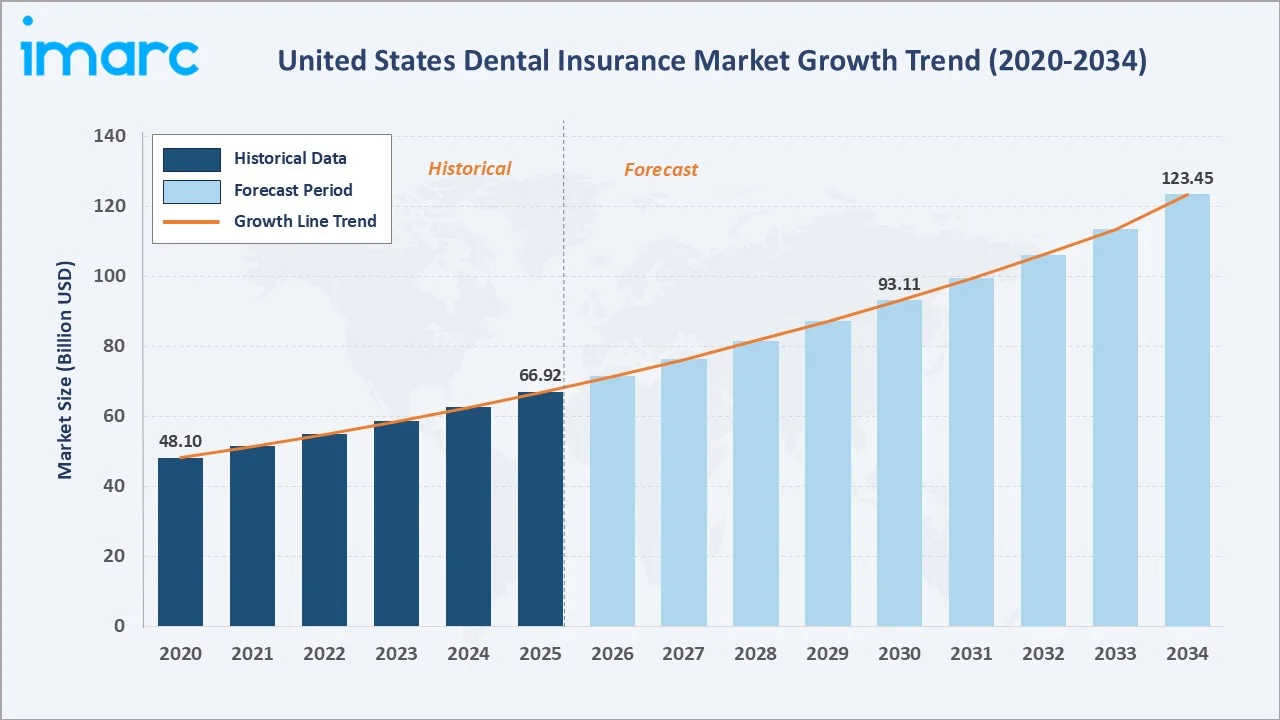
The United States dental insurance market grew from USD 66.92 Billion in 2025 to USD 71.49 Billion in 2026 and is projected to reach USD 123.45 Billion by 2034, exhibiting a CAGR of 6.83%. Growing awareness around preventive oral care is reinforcing steady market expansion alongside rising employer-sponsored plan penetration.
Preventive leads the type segment at 44.6%, dental preferred provider organizations command 52.8% of coverage, and South anchors the regional landscape at 36.2%.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 66.92 Billion |
|
Market Size (2026) |
USD 71.49 Billion |
|
Forecast Market Size (2034) |
USD 123.45 Billion |
|
CAGR (2026-2034) |
6.83% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Largest Region |
South (36.2%, 2025) |
|
Second Largest Region |
West (24.7%, 2025) |
|
Leading Type |
Preventive (44.6%, 2025) |
|
Leading Coverage |
Dental Preferred Provider Organizations (52.8%, 2025) |
The United States dental insurance market expanded from USD 48.10 Billion in 2020 to USD 66.92 Billion in 2025 and is estimated to reach USD 71.49 Billion in 2026. The market is further expected to grow to USD 93.11 Billion by 2030 and USD 123.45 Billion by 2034, driven by aging demographics, expanding dental service organization networks, and the integration of dental benefits within broader health insurance packages.
To get more information on this market, Request Sample
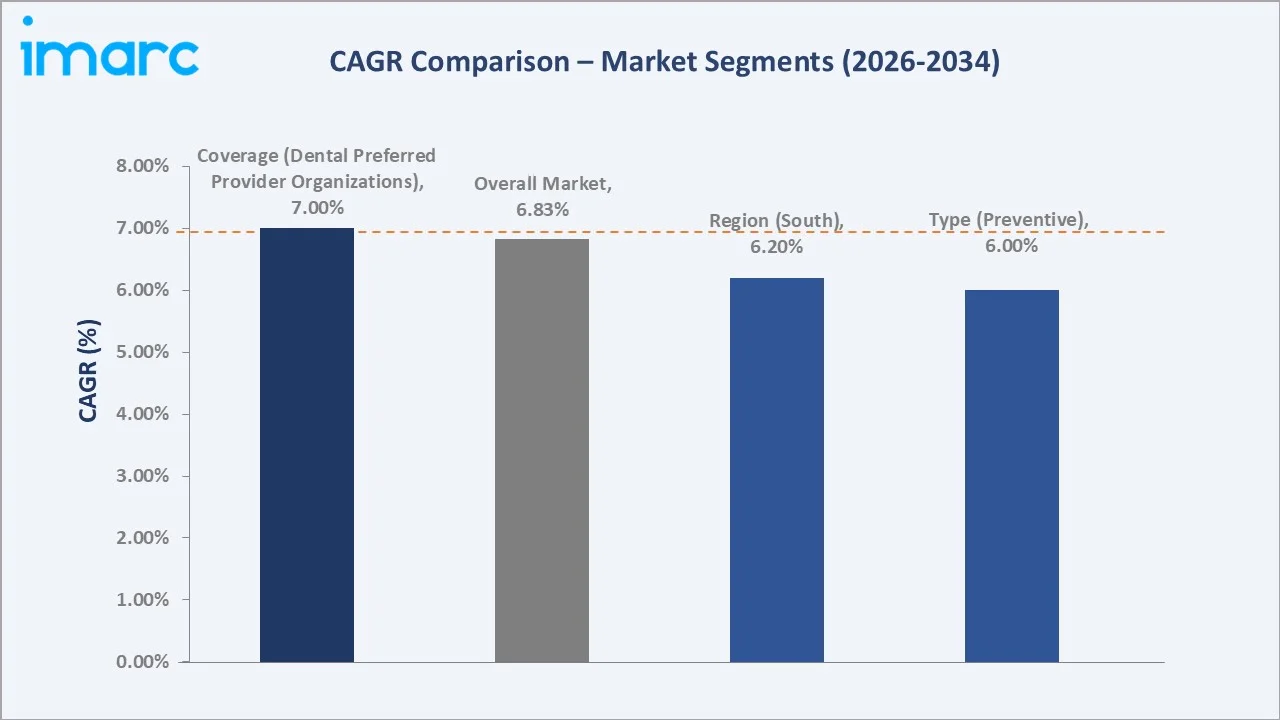
CAGR trajectories across type and coverage sub-segments, together with regional patterns, show Northeast and major dental insurance segments are expanding faster than the overall 6.83% market CAGR, while preventive and dental preferred provider organizations maintain leading revenue shares. Evolving consumer preferences and broader coverage adoption are expected to support sustained demand across both established and emerging segments.
Executive Summary
The United States dental insurance market expanded from USD 66.92 Billion in 2025 to an estimated USD 71.49 Billion in 2026. The industry has undergone structural transformation, driven by the expansion of employer-sponsored dental benefits, growing consumer awareness around preventive oral health, and the rising footprint of dental service organizations streamlining access to in-network care.
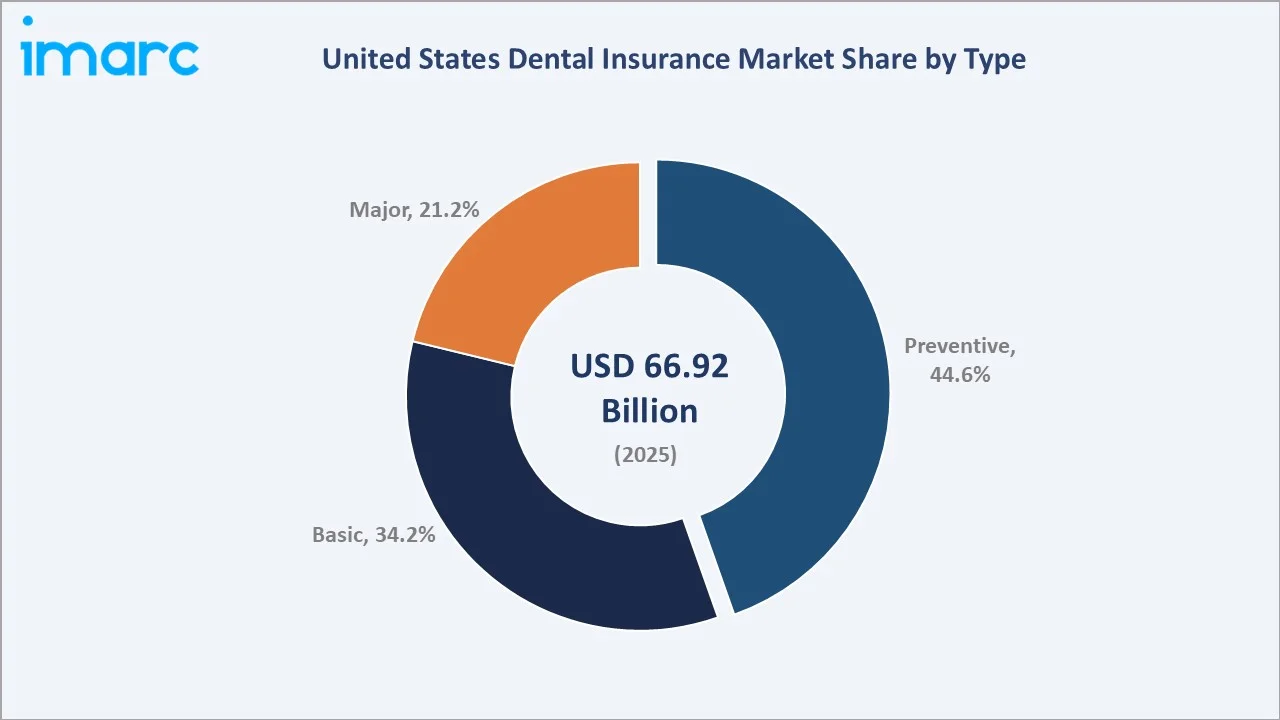
Preventive dominates the type segment at 44.6% in 2025, reflecting policyholder preference for routine cleanings, examinations, and X-rays that are typically fully covered under most plans. Dental preferred provider organizations account for 52.8% of coverage, reinforcing consumer preference for flexible, wide-network plans. South leads the regional landscape at 36.2%, anchored by a large working-age population and a high concentration of employer group plan enrollment.
Key Market Insights
|
Insight |
Data |
|
Leading Type |
Preventive - 44.6% share (2025) |
|
Second Largest Type |
Basic - 34.2% share (2025) |
|
Leading Coverage |
Dental Preferred Provider Organizations - 52.8% share (2025) |
|
Second Largest Coverage |
Dental Health Maintenance Organizations - 24.7% share (2025) |
|
Leading Region |
South - 36.2% share (2025) |
|
Second Largest Region |
West - 24.7% share (2025) |
|
Top Companies |
UnitedHealth Group Incorporated, The Cigna Group, Elevance Health, Inc., MetLife, Inc. |
Key Analytical Observations Expanding On the Data Above:
- Preventive dominance at 44.6% reflects the structural design of most dental insurance products, which cover routine cleanings, oral examinations, and X-rays at 100% co-insurance, incentivizing enrollment and annual utilization as a standard benefit.
- Basic at 34.2% includes fillings, simple extractions, and periodontal maintenance. Its substantial share reflects the recurring need for restorative and routine periodontal procedures among covered policyholders.
- Dental preferred provider organizations hold 52.8% share, underpinned by their broad in-network dentist availability, cost flexibility for out-of-network visits, and widespread adoption among employer group benefit programs.
- Dental health maintenance organizations share at 24.7% reflects their emphasis on preventive care, lower out-of-pocket costs, and coordinated provider networks, making them attractive to cost-conscious policyholders and employer-sponsored plans.
- South leads regional share at 36.2% in 2025, driven by its large working-age population, rapid metropolitan growth, high employer group plan enrollment rates across healthcare, retail, and logistics sectors, and increasing dental service organization penetration expanding access to covered dental services.
United States Dental Insurance Market Overview
Dental insurance encompasses financial products that cover the costs associated with preventive, diagnostic, basic, and major dental procedures. These include routine cleanings, fillings, extractions, root canals, crowns, orthodontics, and oral surgery, delivered through a network of contracted dentists under various plan structures.
The United States dental insurance ecosystem integrates a diverse set of actors. Insurance carriers, third-party administrators, dental service organizations, employer HR functions, state insurance regulators, and federal program administrators collaborate to deliver coverage at scale. Macroeconomic factors, including employment levels, employer benefit spending decisions, regulatory policy, and demographic aging, directly shape enrollment trends and plan utilization patterns.
Market Dynamics
To evaluate market opportunities, Request Sample
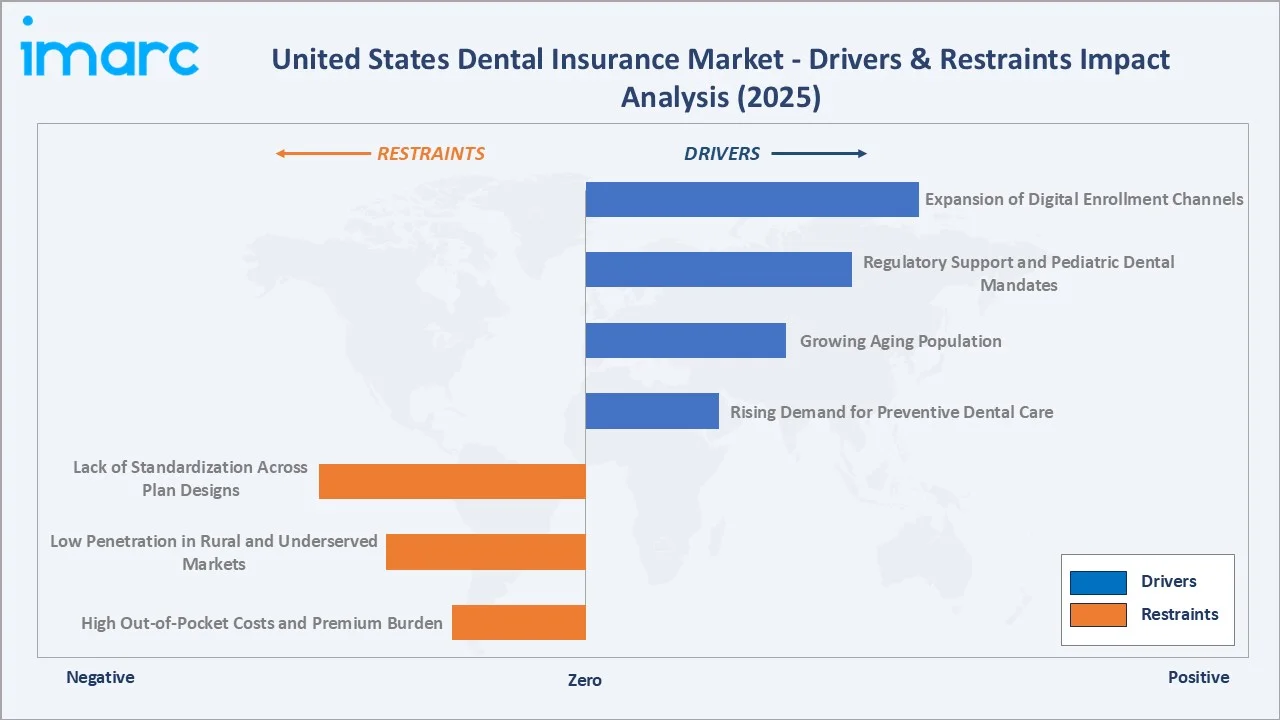
Market Drivers
- Rising Demand for Preventive Dental Care: Growing consumer awareness of the relationship between oral health and systemic conditions, including cardiovascular disease, diabetes, and pregnancy outcomes, is increasing demand for preventive dental coverage.
- Growing Aging Population: The aging of the United States population is driving increased demand for restorative and major dental procedures, including crowns, dentures, bridges, and implants. As per US Census Bureau, the count of Americans aged 65 and older will exceed double over the next four decades, hitting 80 Million by 2040.
- Regulatory Support and Pediatric Dental Mandates: Regulatory requirements for pediatric dental coverage are expanding access to dental benefits among children and families. Public health programs and state-level coverage initiatives are also increasing dental benefit availability among lower-income populations, supporting broader enrollment and utilization of covered dental services.
- Expansion of Digital Enrollment Channels: Increasing use of online platforms for comparing, selecting, and enrolling in dental insurance plans is simplifying access to coverage and improving consumer engagement. Digital tools also enable insurers to offer personalized plan options and streamline enrollment processes, supporting broader market penetration.
Market Restraints
- High Out-of-Pocket Costs and Premium Burden: Despite broad plan availability, high deductibles, co-insurance requirements, and annual maximum benefit caps limit utilization for lower-income and cost-sensitive enrollees.
- Low Penetration in Rural and Underserved Markets: Access to in-network dental providers remains limited in rural and lower-density markets, reducing the value proposition of dental insurance plans dependent on contracted networks.
- Lack of Standardization Across Plan Designs: Significant variation in plan terms, coverage definitions, deductible structures, and waiting period requirements across carriers and states creates complexity for consumers and employers.
Market Opportunities
- Growth of Employer-Sponsored Dental Coverage: Increasing emphasis on employee wellness and preventive healthcare is encouraging employers to enhance benefits packages with dental coverage, creating opportunities for insurers to expand group enrollment and introduce flexible plans tailored to different workforce needs.
- Expansion of Individual and Family Dental Plans on Exchanges: Federal and state health insurance exchanges provide an underpenetrated channel for standalone dental plan enrollment. Increasing consumer awareness of exchange-available dental options, combined with premium tax credits for lower-income households, offers carriers an opportunity to grow individual plan enrollment and diversify beyond the employer group channel.
Market Challenges
- Rising Claims Costs and Actuarial Pricing Pressures: Increasing utilization of major dental procedures, rising dental provider fees, and inflationary pressure on clinical materials are contributing to higher average claims costs per member. Insurers face actuarial pricing challenges in balancing premium competitiveness with claims adequacy, particularly in major and restorative procedure categories.
- Provider Network Adequacy and Retention: Recruiting and retaining sufficient in-network dental providers, particularly specialists such as endodontists and periodontists, remains an ongoing challenge for carriers. Network gaps reduce plan value, increase out-of-network cost exposure for enrollees, and can negatively affect carrier ratings and employer plan renewal decisions.
Emerging Market Trends
1. Integration of Dental Benefits within Senior Health Plans
Insurers are increasingly embedding dental coverage within senior health plans as a supplementary benefit for older adults. High availability of dental benefits among enrollees reflects growing demand for affordable dental coverage in this population. This trend is expected to continue as the eligible senior population expands through 2034, supporting growth in the dental insurance market.
2. Digital Claims Processing and Member Self-Service Platforms
Insurers are investing in digital claims submission portals, real-time eligibility verification, and mobile-first member engagement platforms. These investments reduce administrative costs, accelerate claims resolution cycles, and improve enrollee satisfaction scores. The transition to electronic claims and automated adjudication is becoming a competitive differentiator, particularly in the employer group market where HR administrators demand efficient benefit management tools.
3. Growing Demand for Orthodontic and Cosmetic Coverage Expansion
Consumer demand for orthodontic benefits, including adult orthodontics and clear aligner coverage, is driving plan design innovation. Carriers are launching enhanced dental products with higher annual maximums and explicit orthodontic coverage tiers to attract millennial and Gen Z enrollees seeking comprehensive coverage.
Industry Value Chain Analysis
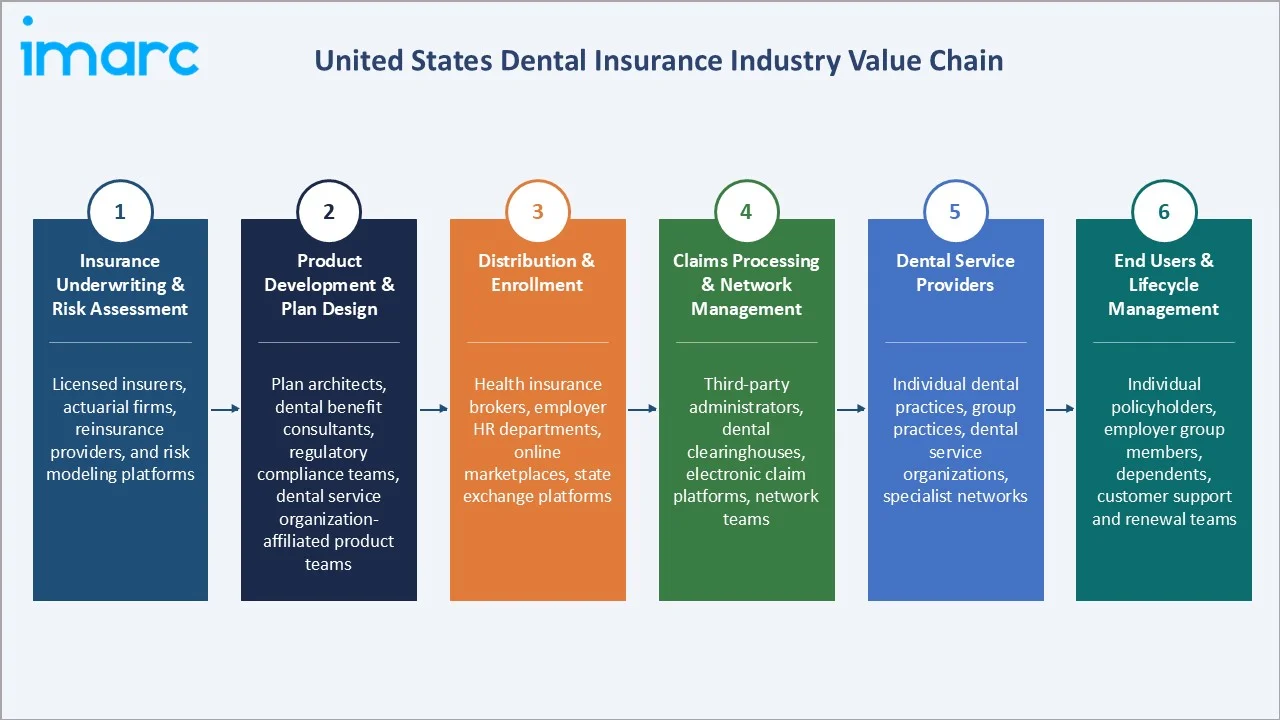
The United States dental insurance value chain spans six stages, from premium collection and risk underwriting through product design, distribution, claims management, dental service delivery, and end-user lifecycle management. Each stage represents a functional layer through which financial and clinical value flows between carriers, intermediaries, providers, and policyholders.
|
Stage |
Key Players / Examples |
|
Insurance Underwriting & Risk Assessment |
Licensed insurers, actuarial firms, reinsurance providers, and risk modeling platforms supporting plan pricing |
|
Product Development & Plan Design |
Plan architects, dental benefit consultants, regulatory compliance teams, and dental service organization-affiliated product teams |
|
Distribution & Enrollment |
Health insurance brokers, employer HR departments, online marketplaces, and state exchange platforms |
|
Claims Processing & Network Management |
Third-party administrators, dental clearinghouses, electronic claim platforms, and network relations teams |
|
Dental Service Providers |
Individual dental practices, group practices, dental service organizations, and specialist referral networks |
|
End Users & Lifecycle Management |
Individual policyholders, employer group members, dependents, and customer support and renewal teams |
Vertically integrated carriers, particularly those owning or closely partnering with dental service organizations, are positioned to capture greater margin at multiple value chain stages by combining underwriting, network management, and direct care delivery.
Technology Landscape in the United States Dental Insurance Industry
Digital Claims Processing and Automation
Insurers are transitioning from paper-based claims adjudication to fully electronic claims submission and processing platforms. Electronic data interchange standards and automated adjudication engines are reducing claims processing time from weeks to days, improving provider satisfaction and reducing administrative overhead for carriers and dental offices alike.
AI-Driven Underwriting and Fraud Detection
AI and machine learning (ML) models are being deployed across underwriting, claims review, and fraud detection functions. AI-powered systems analyze claims patterns, treatment histories, and provider billing profiles to flag anomalous claims in real time, reducing fraudulent payouts and improving actuarial accuracy in premium setting and risk segmentation.
Member-Facing Digital Platforms and Telehealth Integration
Carriers are investing in mobile applications, member portals, and virtual consultation tools that allow enrollees to locate in-network providers, verify benefits, submit claims, and access telehealth-enabled oral health triage services. These platforms improve member engagement, reduce call center costs, and support proactive preventive care messaging that drives utilization of lower-cost benefit categories.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Type |
Preventive |
44.6% |
2025 |
|
Coverage |
Dental Preferred Provider Organizations |
52.8% |
2025 |
|
Demographics |
🔒 |
🔒 |
2025 |
|
End User |
🔒 |
🔒 |
2025 |
|
Region |
South |
36.2% |
2025 |

By Type
Preventive commands a 44.6% majority share in 2025, driven by the standard plan design feature of 100% coverage for routine oral examinations, professional cleanings, and bitewing X-rays.
To access detailed market analysis, Request Sample
Basic represents 34.2% of the market in 2025, encompassing fillings, simple extractions, and non-surgical periodontal treatments. Its substantial contribution reflects the recurring need for restorative and periodontal care, which supports consistent utilization of basic dental benefits.
By Coverage
Dental preferred provider organizations hold 52.8% share in 2025, reflecting broad consumer and employer preference for flexible plan designs that allow both in-network and out-of-network care with differentiated reimbursement rates.
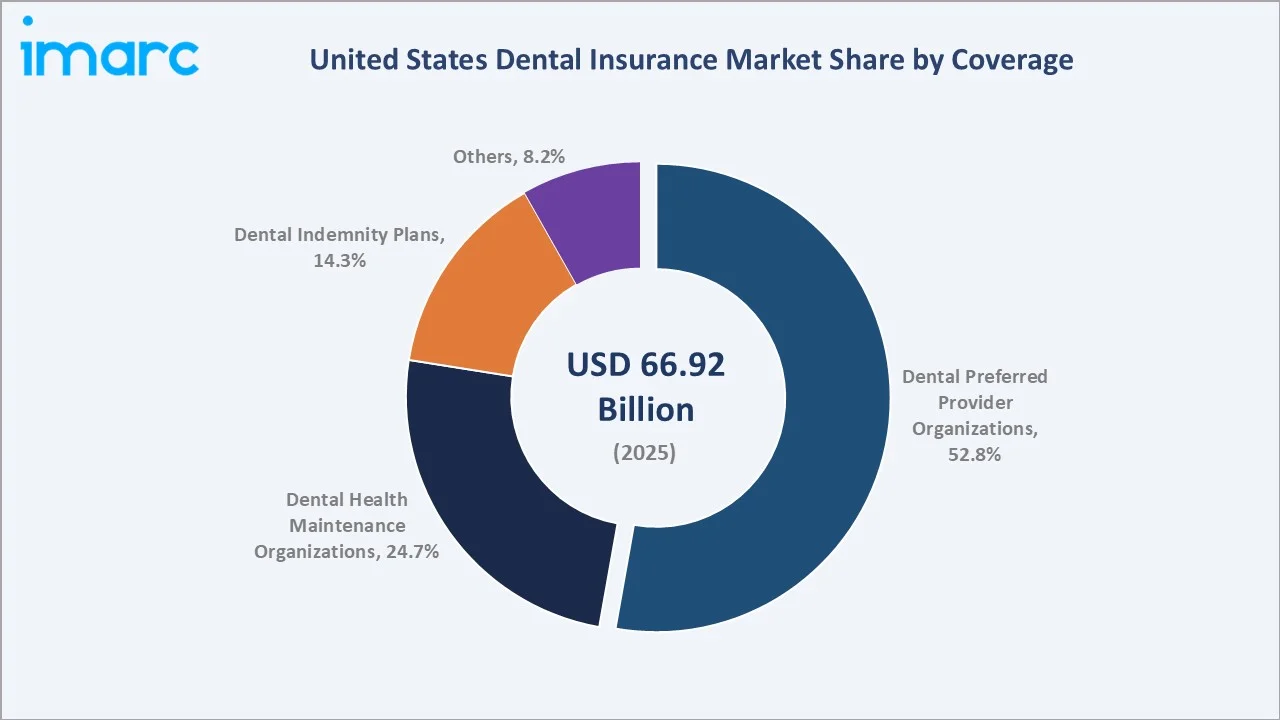
Dental health maintenance organizations account for 24.7% in 2025, offering lower premium costs in exchange for care restricted to a defined in-network panel.
Regional Market Insights
|
Region |
Share (2025) |
Key Growth Drivers |
|
South |
36.2% |
High population density, large employer base, growing demand for employer-sponsored group dental plans, and strong presence of dental service organizations |
|
West |
24.7% |
High-income urban populations, strong private dental insurance uptake, expanding tech sector employer benefits, and growing individual plan enrollment |
|
Midwest |
20.3% |
Stable employer-sponsored insurance market, manufacturing and industrial workforce dental coverage, and steady population growth in metropolitan areas |
|
Northeast |
18.8% |
High insurance awareness, densely regulated insurance market, aging population with elevated dental care needs, and strong standalone plan adoption |
South leads the regional landscape at 36.2% in 2025, anchored by its large and growing working-age population, high employer group dental plan enrollment across healthcare, logistics, and retail sectors, and the rapid expansion of dental service organization networks in suburban and secondary metropolitan markets.
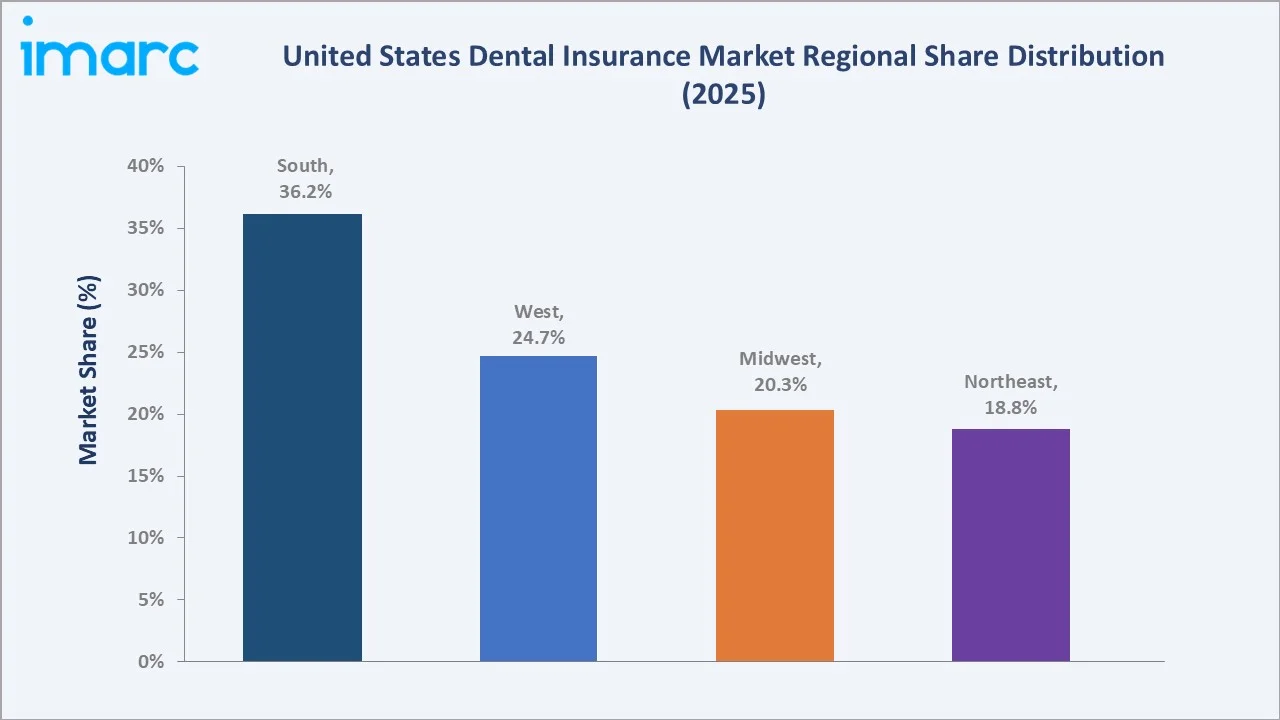
West accounts for 24.7% of market share in 2025, supported by high household incomes in coastal metropolitan markets, strong employer benefit programs among technology and financial services sectors, and growing individual plan enrollment.
Competitive Landscape
The United States dental insurance market is moderately concentrated, with a small group of large diversified health insurers and specialized dental carriers collectively accounting for the majority of enrolled lives and premium revenue. The competitive landscape is characterized by the dominance of integrated health and dental benefit platforms, broad in-network provider panel development, and active employer group plan renewal management.
|
Company Name |
Brand / Key Product |
Position |
Strategic Focus |
|
UnitedHealth Group Incorporated |
UnitedHealthcare Dental |
Leader |
Expanding integrated dental-medical benefit platforms and growing employer and individual plan enrollment |
|
The Cigna Group |
Cigna Dental |
Leader |
Strengthening preferred provider organization dental network depth and enhancing digital claims and member engagement tools |
|
Elevance Health, Inc. |
Anthem |
Leader |
Growing employer group dental plan penetration and investing in preventive care incentive programs |
|
MetLife, Inc. |
MetLife Dental |
Challenger |
Broadening employer-sponsored dental benefit offerings and investing in digital plan management platforms |
Key players include UnitedHealth Group Incorporated, The Cigna Group, Elevance Health, Inc., and MetLife, Inc., among others.
Key Company Profiles
UnitedHealth Group Incorporated
UnitedHealth Group Incorporated is a diversified health and well-being company headquartered in Minnetonka, Minnesota. Its UnitedHealthcare operating division is one of the largest dental benefit administrators in the United States, serving individuals, employer groups, and government program participants across all 50 states.
- Product Portfolio: Comprehensive dental benefit plans under the UnitedHealthcare Dental brand, covering preventive, basic, and major procedures under preferred provider organization, health maintenance organization, and indemnity structures, distributed through employer groups, individual enrollment, and Medicare Advantage bundles.
- Recent Developments: The company has continued to strengthen its dental benefit capabilities, investing in network expansion, digital member tools, and integrated health solutions to support employer and individual plan growth.
- Strategic Focus: Driving growth in employer and individual dental enrollment by advancing integrated health-dental benefit platforms and building deeper provider network relationships across all coverage segments.
The Cigna Group
The Cigna Group is a global health services company headquartered in Bloomfield, Connecticut. Its Cigna Healthcare division serves millions of enrollees across group and individual markets with a broad in-network provider panel spanning preferred provider and health maintenance organization plan structures.
- Product Portfolio: Cigna Dental plans covering preventive, basic, and major procedures under preferred provider organization and health maintenance organization structures, with enhanced options for orthodontic coverage and bundled dental-vision benefit packages.
- Recent Developments: The company has continued to advance its dental product capabilities, focusing on digital service improvements, member engagement tools, and network management to support employer and individual plan performance.
- Strategic Focus: Broadening preferred provider organization network reach and upgrading digital claims administration and member communication tools to reinforce employer group plan loyalty and widen coverage access.
Elevance Health, Inc.
Elevance Health, Inc. is a health benefits company headquartered in Indianapolis, Indiana. It delivers dental benefits through its affiliated Anthem plans across multiple states.
- Product Portfolio: Dental coverage plans under the Anthem brand, spanning preventive, basic, and major procedures, with employer group plan customization options for plan design, deductibles, and annual maximum thresholds.
- Recent Developments: The company has continued to broaden its dental benefit integration within its commercial and Medicare Advantage health plan offerings, investing in network development and digital member service capabilities.
- Strategic Focus: Increasing employer group dental plan adoption by channeling investment into preventive care programs and delivering coordinated health-dental benefit packages that lower long-term claims expenditure.
Market Concentration Analysis
The United States dental insurance market is moderately concentrated, with the top carriers accounting for a substantial proportion of total enrolled lives and premium revenue. A handful of large diversified health insurers and specialized dental carriers dominate the employer group segment, while the individual market features a broader range of participants including regional carriers, not-for-profit dental benefit organizations, and Medicaid managed care entities.
Barriers to entry in the dental insurance market include regulatory licensing requirements, capital requirements for maintaining actuarially sound claims reserves, the complexity of building and managing large in-network provider panels, and established renewal relationships between large carriers and employer group clients.
Consolidation is gradually increasing as large diversified health insurers integrate dental benefits within broader benefit bundles and acquire regional dental carriers to expand geographic coverage. Additionally, this trend is reshaping the competitive landscape and provider network structures.
Investment & Growth Opportunities
Fastest-Growing Segments
Major is expanding at an above-average CAGR among type categories, driven by aging demographics and increasing demand for complex restorative and replacement dental procedures. Carriers and investors focusing on major dental product innovation and network specialist depth are positioned to capture disproportionate segment growth.
Emerging Markets
Northeast is the fastest growing region within the United States dental insurance market, supported by its high-income demographics, strong individual plan uptake, dense regulatory framework, and above-average aging population with elevated restorative dental needs.
Venture & Investment Trends
Investment activity is concentrated in digital dental insurance platforms, technology-enabled claims management, provider network solutions, and data-driven tools that improve plan administration and member engagement. Increasing adoption of digital healthcare services is creating opportunities for investments focused on operational efficiency, personalized coverage, and streamlined member experiences.
Future Market Outlook (2026-2034)
The United States dental insurance market is projected to grow from USD 66.92 Billion in 2025 to USD 71.49 Billion in 2026, reaching USD 123.45 Billion by 2034, registering a CAGR of 6.83% during 2026-2034.
Four structural forces will shape the market through 2034: aging population and rising dental needs; growing emphasis on preventive oral healthcare; evolving regulations and expanded coverage access; and increasing digitalization of enrollment and services.
By 2034, dental insurance in the United States is expected to be defined by integrated benefit platforms, digital-first member engagement, and expanded coverage tiers addressing cosmetic, orthodontic, and implant procedures. Carriers with differentiated network relationships, superior actuarial capabilities, and robust digital infrastructure will be best positioned to capture market share in a growing but increasingly competitive landscape.
Research Methodology
Primary Research
Primary research included structured interviews with dental insurance executives, dental benefits consultants, employer HR and benefits administrators, dental service organization operators, and independent dental practitioners. These interviews provided qualitative insight into enrollment trends, plan design evolution, network management strategies, and policyholder utilization patterns across coverage types and regions.
Secondary Research
Secondary sources included National Association of Insurance Commissioners publications, Centers for Medicare & Medicaid Services enrollment data, Affordable Care Act exchange plan data, American Dental Association health policy reports, Kaiser Family Foundation insurance analysis, employer benefit survey data from the Society for Human Resource Management, and publicly available regulatory filings from major insurance carriers.
Forecasting Models
Market forecasts were developed using top-down and bottom-up modeling approaches incorporating dental enrollment trends by plan type, claims cost trajectories, premium growth rates, demographic aging projections, employer benefit adoption surveys, and Medicaid dental expansion program enrollment data.
United States Dental Insurance Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report | Exploration of Historical and Forecast Trends, Industry Catalysts and Challenges, Segment-Wise Historical and Predictive Market Assessment:
|
| Types Covered | Major, Basic, Preventive |
| Coverages Covered | Dental Preferred Provider Organizations, Dental Health Maintenance Organizations, Dental Indemnity Plans, Others |
| Demographics Covered | Senior Citizens, Adults, Minors |
| End Users Covered | Individuals, Corporates |
| Regions Covered | Northeast, Midwest, South, West |
| Companies Covered | UnitedHealth Group Incorporated, The Cigna Group, Elevance Health, Inc., MetLife, Inc., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the United States dental insurance market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the United States dental insurance market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the United States dental insurance industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the United States Dental Insurance Market Report
The United States dental insurance market size is estimated at USD 71.49 Billion in 2026, driven by rising employer-sponsored plan penetration and growing consumer awareness around preventive oral health.
The market is projected to grow at a CAGR of 6.83% from 2026-2034, reaching USD 123.45 Billion, supported by aging demographics, rising preventive care demand, and expanding dental coverage.
Preventive is the largest type segment, holding 44.6% of the market in 2025. This leadership is driven by standard plan designs that cover routine cleanings, oral examinations, and X-rays at 100% co-insurance.
Dental preferred provider organizations represent the largest coverage, commanding 52.8% of the market in 2025. Employer and consumer preference for flexible plan structures that allow both in-network and out-of-network access at differentiated reimbursement rates continues to underpin preferred provider organization dominance across group and individual market segments.
South leads the regional landscape at 36.2% in 2025, anchored by its large working-age population, high employer group plan enrollment rates, and rapid dental service organization network expansion across suburban and secondary metropolitan markets.
Northeast is the fastest growing region, driven by high household incomes, strong individual plan uptake, a well-regulated insurance environment, and an aging population with above-average demand for restorative and major dental procedures.
Key players include UnitedHealth Group Incorporated, The Cigna Group, Elevance Health, Inc., and MetLife, Inc., among others.
Digital enrollment platforms and automated claims processing are reducing administrative delays while making plan selection and reimbursement more efficient. AI, predictive analytics, and tele-dentistry are also enabling personalized coverage, fraud detection, remote consultations, and more targeted preventive care.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade