
United States Fintech Market Size, Share, Trends and Forecast by Deployment Mode, Technology, Application, End User, and Region, 2026-2034
United States Fintech Market Size, Share, Trends & Forecast (2026-2034)
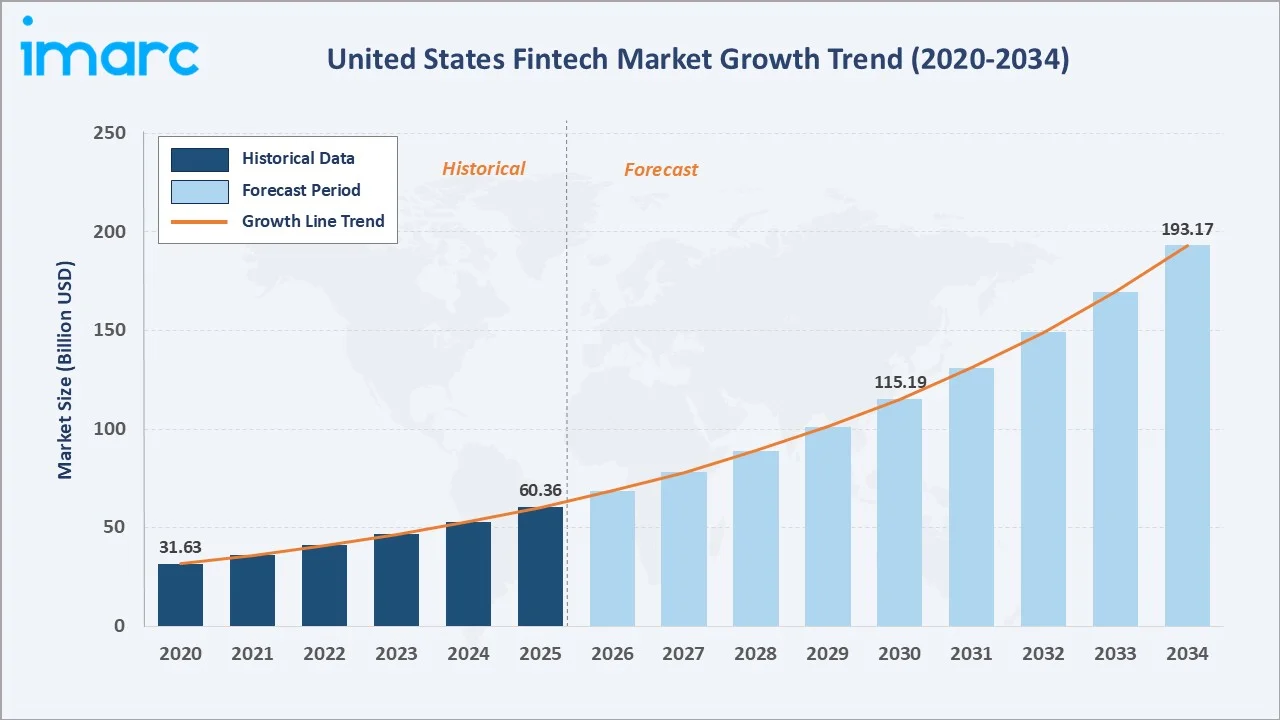
The United States fintech market reached USD 60.36 Billion in 2025 and is projected to reach USD 193.17 Billion by 2034, growing at a CAGR of 13.80% during 2026-2034. The market is driven by accelerating AI and generative AI adoption across financial services, rising embedded finance and digital payment volumes, open banking API ecosystem expansion, and growing cloud-first fintech deployment. In the United States, 91% of Gen Z consumers adopt digital wallets, and 41% use them more than five times per month. This high level of adoption is accelerating the shift toward cashless and alternative payment methods, encouraging fintech companies, banks, and payment service providers to expand mobile payment capabilities, improve digital payment infrastructure, and introduce more seamless and personalized financial services. Cloud-based deployment leads at 64.8%. Banking leads end user at 42.5%. The West region leads regionally at 31.7%.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 60.36 Billion |
|
Forecast Market Size (2034) |
USD 193.17 Billion |
|
CAGR (2026-2034) |
13.80% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Deployment Mode |
Cloud-based (64.8%, 2025) |
|
Leading End User |
Banking (42.5%, 2025) |
|
Leading Region |
West (31.7%, 2025) |
The US fintech market size has grown robustly from USD 31.63 Billion in 2020 to USD 60.36 Billion in 2025, driven by the COVID-19-accelerated digital financial services transition, the explosive growth of embedded payments, buy now pay later (BNPL) platforms, digital lending, robo-advisory wealth management, and insurtech solutions. The market is projected to reach USD 115.19 Billion by 2030 and USD 193.17 Billion by 2034.
To get more information on this market, Request Sample
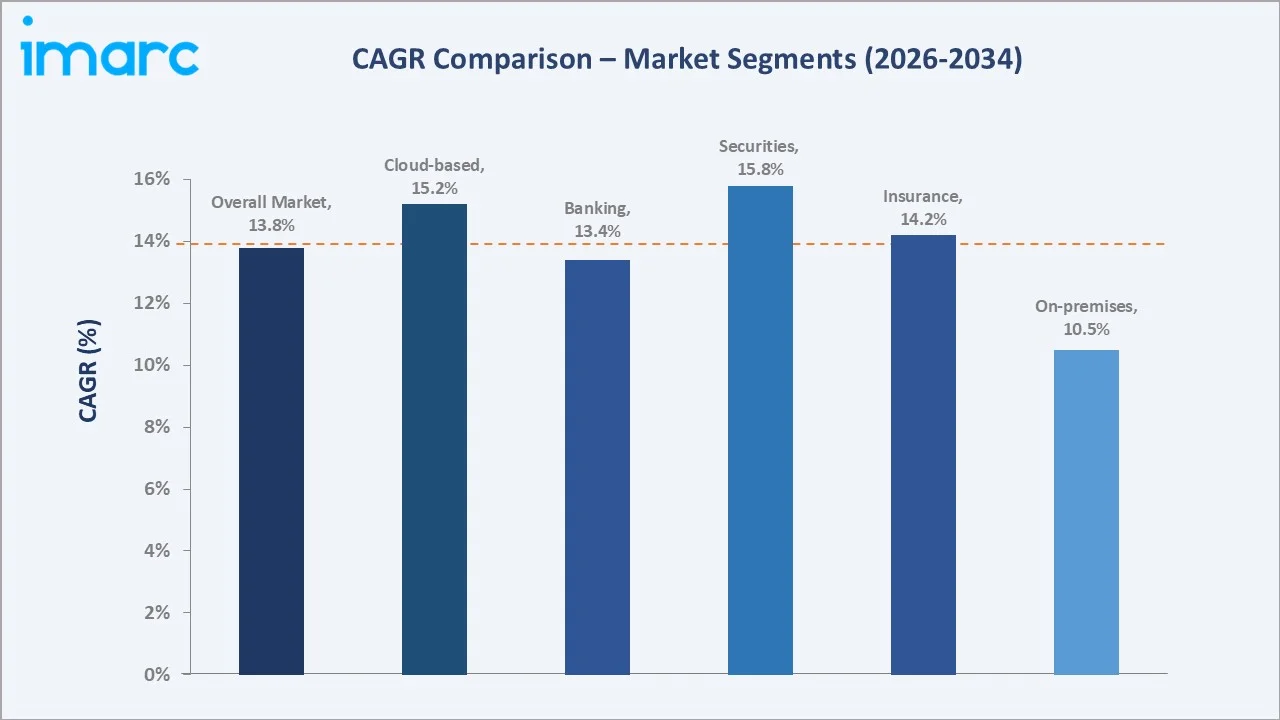
Cloud-based deployment grows at ~15.2% CAGR as financial institutions accelerate cloud migration of core banking, insurance underwriting, and securities trading platforms. Banking end user grows at ~13.4% CAGR through neobanking, digital lending, and AI-powered credit decisioning adoption. The securities segment grows fastest at ~15.8% CAGR through AI-driven trading, robo-advisory, and blockchain-based settlement innovation.
Executive Summary
The fintech market in the US is the largest and most dynamic financial technology ecosystem, characterized by a venture capital funding environment, a highly digitally literate consumer base, and a complex but innovation-supportive regulatory framework. The US fintech market trends has fundamentally transformed how Americans manage payments, access credit, invest wealth, purchase insurance, and engage with financial institutions through mobile-first, AI-powered digital platforms.
Cloud-based deployment at 64.8% reflects the overwhelming shift toward AWS, Microsoft Azure, and Google Cloud-native financial services infrastructure that enables the agility, scalability, and cost efficiency driving US fintech's competitive advantage over traditional financial institution IT architectures. Banking leads end user at 42.5%, driven by neobanking platforms, digital lending marketplaces, and AI-powered core banking transformation programs at both challenger banks and incumbent institutions. The West region leads at 31.7% through Silicon Valley's dominant venture ecosystem and the Bay Area concentration of major fintech platforms.
Key Market Insights
|
Insight |
Data |
|
Dominant Deployment Mode |
Cloud-based - 64.8% share (2025) |
|
Leading End User |
Banking - 42.5% share (2025) |
|
Leading Region |
West - 31.7% share (2025) |
|
Market Opportunity |
GenAI banking; embedded finance; open banking API; DeFi; RegTech automation |
Key Analytical Observations Supporting the Above Data:
- Cloud-based at 64.8%: Cloud-based deployment dominates through superior scalability, reduced infrastructure costs, faster API integration capabilities, and the ability to rapidly deploy AI/ML models and generative AI capabilities without on-premises hardware investment. Major cloud providers have developed specialized compliance-grade cloud environments that address regulatory concerns previously limiting cloud adoption in banking and insurance.
- Banking at 42.5%: Banking dominates as the US banking sector represents the largest addressable fintech market through digital transformation of core banking, payments, lending, KYC/AML compliance, and customer experience platforms.
- West Region at 31.7%: The West leads through Silicon Valley's unrivaled concentration of fintech venture capital, engineering talent, and platform companies. California alone houses hundreds of fintech startups, while the Pacific Northwest contributes significant cloud infrastructure and B2B financial software capabilities.
United States Fintech Market Overview
The United States fintech market encompasses all technology-driven financial services solutions spanning payments and fund transfer, digital lending, insurance technology (insurtech), wealth management automation (wealthtech), banking-as-a-service (BaaS), regulatory technology, and blockchain/DeFi applications. Solutions are deployed across cloud-based (SaaS, PaaS, IaaS) and on-premises architectures, serving banking, insurance, securities, and other financial services end users.
Market Dynamics
To evaluate market opportunities, Request Sample
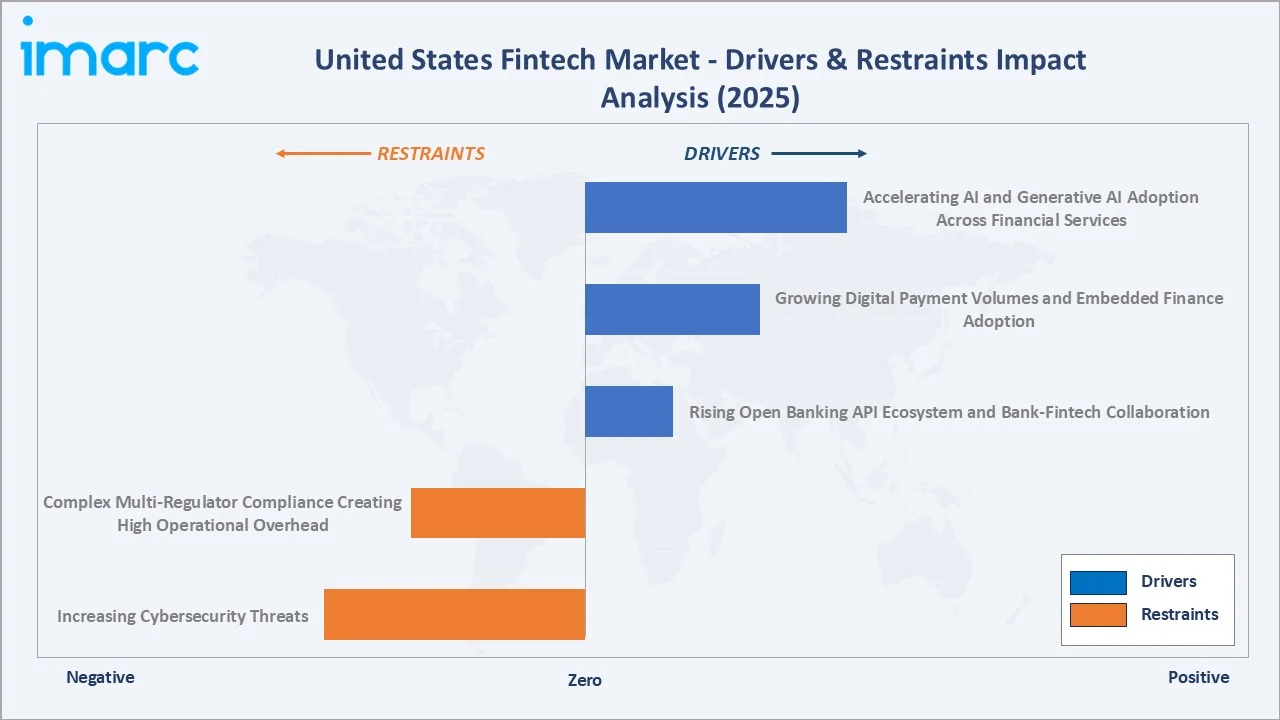
Market Drivers
- Accelerating AI and Generative AI Adoption Across Financial Services: Generative AI, through large language models deployed across customer service, credit underwriting, fraud detection, regulatory document analysis, and personalized financial advice, is the most powerful demand accelerator in the US fintech market. Bank of America's Erica AI assistant surpassed 1.5 billion client interactions as of July 2023, exemplifying AI's transformational impact on US fintech market value creation.
- Growing Digital Payment Volumes and Embedded Finance Adoption: Nearly 90% of US consumers now use contactless payments. US digital payment transaction values continue expanding at double-digit rates as contactless payments, peer-to-peer transfer platforms, real-time payments, and embedded finance integration in e-commerce, ride-sharing, and retail platforms create new payment touchpoints.
- Rising Open Banking API Ecosystem and Bank-Fintech Collaboration: The rising open banking API ecosystem and growing bank-fintech collaboration enable secure, consent-based sharing of financial data and seamless integration of third-party services. APIs allow fintech companies to build innovative solutions across digital payments, lending, personal finance, and embedded banking while leveraging established banking infrastructure. Stronger partnerships between banks and fintech providers are also reducing product-development timelines and improving personalized digital experiences, thereby expanding fintech adoption and strengthening the overall financial services ecosystem.
Market Restraints
- Complex Multi-Regulator Compliance Creating High Operational Overhead: US fintechs navigate a uniquely fragmented regulatory environment where consumer protection rules, banking supervision, securities regulation, deposit insurance requirements, derivatives oversight, and state money transmitter licensing collectively create compliance obligations that can consume 20-30% of fintech startup operational budgets.
- Increasing Cybersecurity Threats: The US fintech sector processes trillions of dollars in financial transactions and houses sensitive consumer financial data, making it a primary target for sophisticated cyberattacks, including ransomware, account takeover fraud, API attacks, and social engineering campaigns.
Market Opportunities
- Generative AI Financial Services Applications and RegTech Automation: Generative AI applications in US financial services, including AI-powered regulatory compliance document generation, automated examination response systems, intelligent contract review, and personalized banking advisor chatbots, represent a multibillion-dollar market opportunity. US fintech companies developing proprietary LLM-based applications for banking operations, insurance claims processing, and securities research automation are positioned to capture significant efficiency gains and revenue growth.
- Underserved and Unbanked Population Financial Inclusion: In the United States, 22% of adults earning less than $25,000 annually were unbanked, compared with just 1% of adults with annual incomes of $100,000 or more, representing a significant addressable market for fintech financial inclusion solutions. Mobile-first neobanks, earned wage access platforms, credit-builder products, and microfinance lending applications targeting the underserved American consumer represent high-growth market segments with strong social impact positioning that is increasingly attractive to both mission-driven investors and impact-focused regulatory frameworks.
Market Challenges
- Talent Competition and Fintech Engineering Workforce Costs: US fintech companies compete intensively with Big Tech, traditional financial institutions, and defense contractors for senior software engineers, ML researchers, quantitative analysts, and financial services compliance specialists. Average compensation for senior fintech engineers is creating significant human capital cost pressures that challenge fintech unit economics and contribute to the sector's ongoing focus on AI-driven operational automation as a talent efficiency strategy.
- Venture Capital Market Normalization and Funding Environment Adjustment: Tighter funding conditions and valuation resets can make it harder for early-stage fintech firms to secure capital, potentially delaying product development and market expansion. Moreover, capital is increasingly concentrated among established and high-performing companies, intensifying funding competition across the fintech ecosystem.
Emerging Market Trends
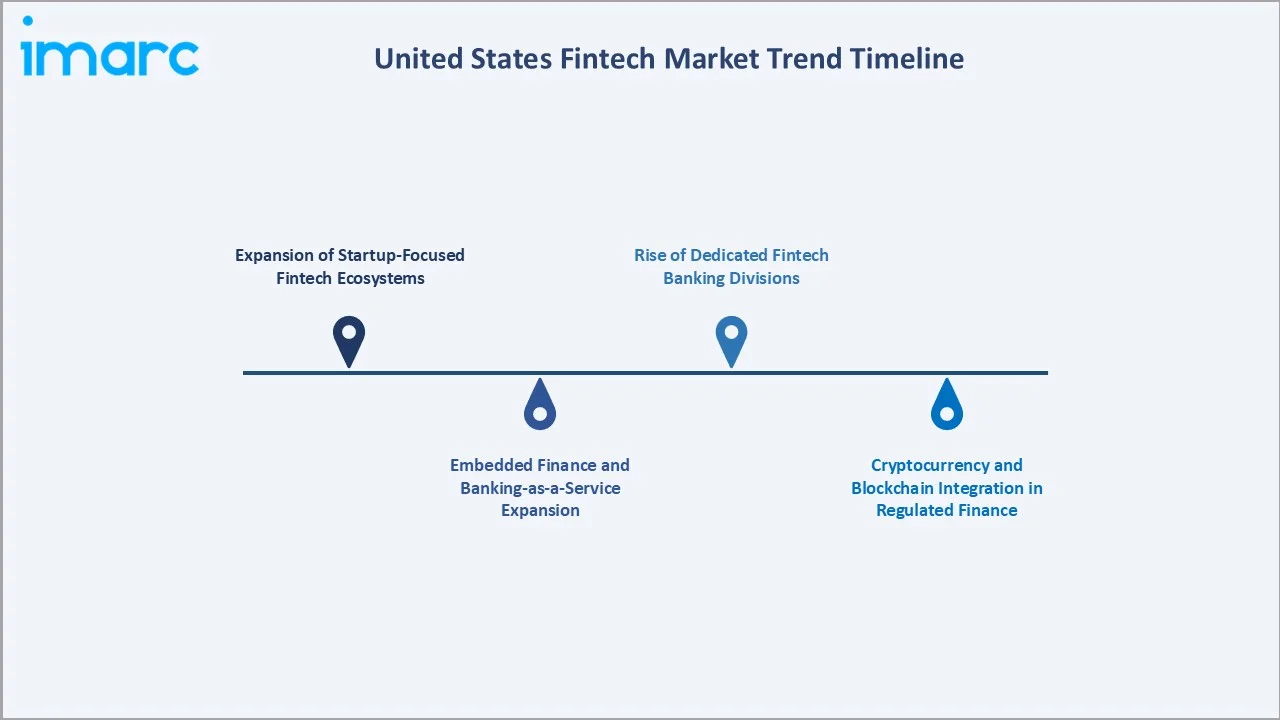
1. Expansion of Startup-Focused Fintech Ecosystems
In August 2026, Money20/20 announced an expanded Startup Hub at Money20/20 USA, providing fintech startups with greater access to investors, banks, technology firms, enterprise partners, and media. The initiative aims to support startup growth through founder showcases, curated networking, industry events, and partnership opportunities. The expansion of such platforms highlights a growing trend toward stronger collaboration between fintech startups, investors, banks, and technology providers. This ecosystem-based approach is helping emerging companies gain funding access, build strategic partnerships, and accelerate the commercialization of innovative financial solutions.
2. Embedded Finance and Banking-as-a-Service Expansion
Embedded finance, the integration of financial services directly into non-financial platforms including e-commerce, mobility, healthcare, and software applications, is the most significant structural market expansion trend reshaping US fintech. Banking-as-a-service providers enable non-bank technology companies to offer checking accounts, debit cards, lending, and insurance directly within their platforms through fintech API infrastructure.
3. Rise of Dedicated Fintech Banking Divisions
In June 2026, US-based Capital Community Bank (CCBank) launched Quill Bank, a dedicated fintech banking division aimed at strengthening its presence in the fintech sector. Positioned as a banking backbone for fintech partners, Quill Bank will leverage CCBank’s regulatory, operational, and relationship-banking expertise while offering fintech companies a more specialized and tailored banking platform. The launch reflects a growing trend among traditional banks to create specialized units tailored to fintech companies. These divisions combine banking infrastructure and regulatory expertise with fintech-focused services, supporting deeper bank-fintech collaboration and faster deployment of digital financial products.
4. Cryptocurrency and Blockchain Integration in Regulated Finance
The regulatory environment for cryptocurrency and blockchain in US financial services shifted significantly, with growing OCC guidance on bank crypto custody activities, and bipartisan Congressional progress on stablecoin and crypto market structure legislation. This regulatory clarification is enabling a new generation of blockchain-based fintech applications in securities settlement, stablecoin-based cross-border payments, and tokenized asset management that are expanding the US fintech market into previously inaccessible institutional finance applications.
Industry Value Chain Analysis
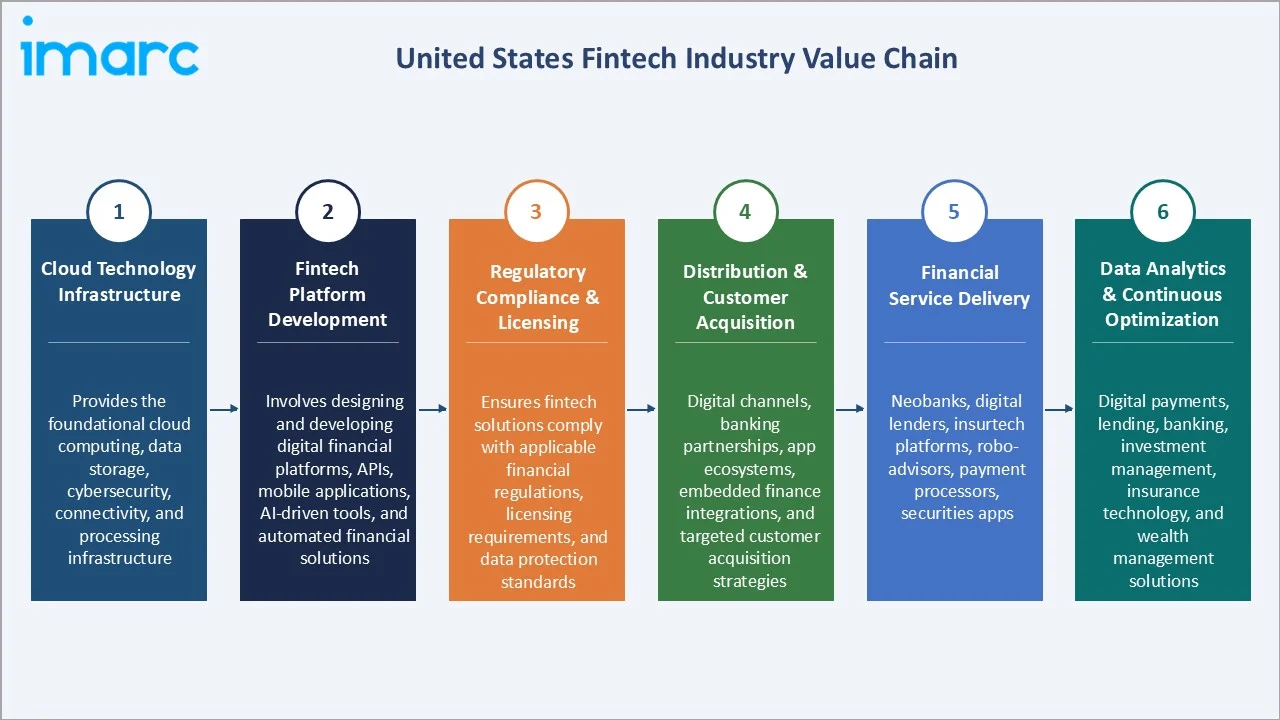
The US fintech market value chain integrates cloud technology infrastructure, fintech platform development, regulatory compliance and licensing, distribution and customer acquisition, financial service delivery, and data analytics and continuous optimization.
|
Stage |
Key Participants |
|
Cloud Technology Infrastructure |
Provides the foundational cloud computing, data storage, cybersecurity, connectivity, and processing infrastructure. |
|
Fintech Platform Development |
Involves designing and developing digital financial platforms, APIs, mobile applications, AI-driven tools, and automated financial solutions. |
|
Regulatory Compliance & Licensing |
Ensures fintech solutions comply with applicable financial regulations, licensing requirements, and data protection standards. |
|
Distribution & Customer Acquisition |
Digital channels, banking partnerships, app ecosystems, embedded finance integrations, and targeted customer acquisition strategies. |
|
Financial Service Delivery |
Neobanks, digital lenders, insurtech platforms, robo-advisors, payment processors, securities apps. |
|
Data Analytics & Continuous Optimization |
Digital payments, lending, banking, investment management, insurance technology, and wealth management solutions. |
Financial service delivery and data analytics represent the highest-value stages, as the quality of customer experience, risk decisioning, and personalization directly determines customer retention and lifetime value. Regulatory compliance is the most capital-intensive stage for early-stage fintechs, consuming disproportionate engineering and legal resources relative to the compliance infrastructure available at scale for incumbents.
Technology Landscape in the United States Fintech Industry
Artificial Intelligence and Machine Learning
AI and machine learning represent the foundational technology layer of US fintech competitive differentiation, enabling real-time fraud detection processing millions of transactions per second, AI-powered credit underwriting replacing manual review with algorithmic decisioning, personalized financial product recommendation engines, intelligent regulatory compliance monitoring, and generative AI customer service automation. The convergence of LLMs with financial services data is creating AI-native financial services applications that deliver personalization and accuracy levels previously impossible with rule-based systems.
Blockchain and Distributed Ledger Technology
Blockchain and distributed ledger technology enable secure, transparent, and decentralized recording of financial transactions, reducing reliance on traditional intermediaries. In fintech, the technology supports applications such as digital payments, cross-border transactions, asset tokenization, smart contracts, and transaction verification while improving efficiency and traceability.
RegTech and Compliance Automation Technology
Regulatory technology (RegTech) has emerged as one of the fastest-growing US fintech subsectors, driven by escalating BSA/AML compliance costs and the complexity of multi-jurisdictional regulatory reporting requirements. AI-powered transaction monitoring, automated suspicious activity report (SAR) generation, real-time KYC/identity verification through biometric authentication and document verification platforms, and generative AI-based regulatory change management tools are enabling US financial institutions to address compliance requirements at lower cost and higher accuracy than human-intensive legacy approaches.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Deployment Mode |
Cloud-based |
64.8% |
2025 |
|
Technology |
🔒 |
🔒 |
2025 |
|
Application |
🔒 |
🔒 |
2025 |
|
End User |
Banking |
42.5% |
2025 |
|
Region |
West |
31.7% |
2025 |

By Deployment Mode
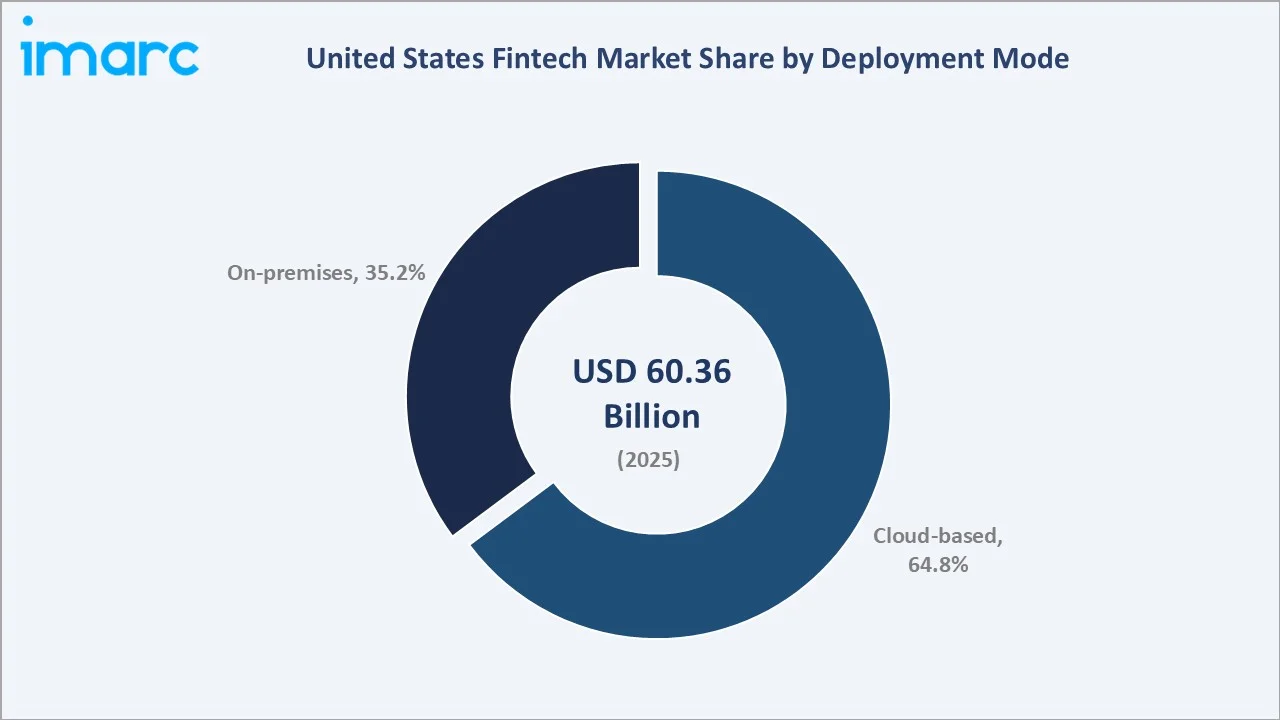
Cloud-based deployment dominates at 64.8% (2025), reflecting the overwhelming shift toward SaaS, PaaS, and IaaS-based financial services platforms that deliver superior scalability, faster product iteration, and elastic cost structures compared to on-premises alternatives. Cloud-based fintech grows at ~15.2% CAGR through 2034, driven by accelerating cloud migration of core banking systems at major US banks.
To access detailed market analysis, Request Sample
On-premises deployment retains a 35.2% share, primarily in systemically important financial institutions (SIFIs) with legacy core banking systems requiring significant transformation investment, high-frequency trading firms with strict latency requirements, and financial institutions in sectors with specific regulatory examination access requirements. On-premises grows at ~10.5% CAGR as legacy modernization programs partially offset migration to the cloud, particularly in securities clearing, insurance underwriting, and government-regulated financial operations.
By End User
Banking leads at 42.5% (2025) through the digital transformation of retail banking, commercial lending, corporate treasury management, and investment banking operations.
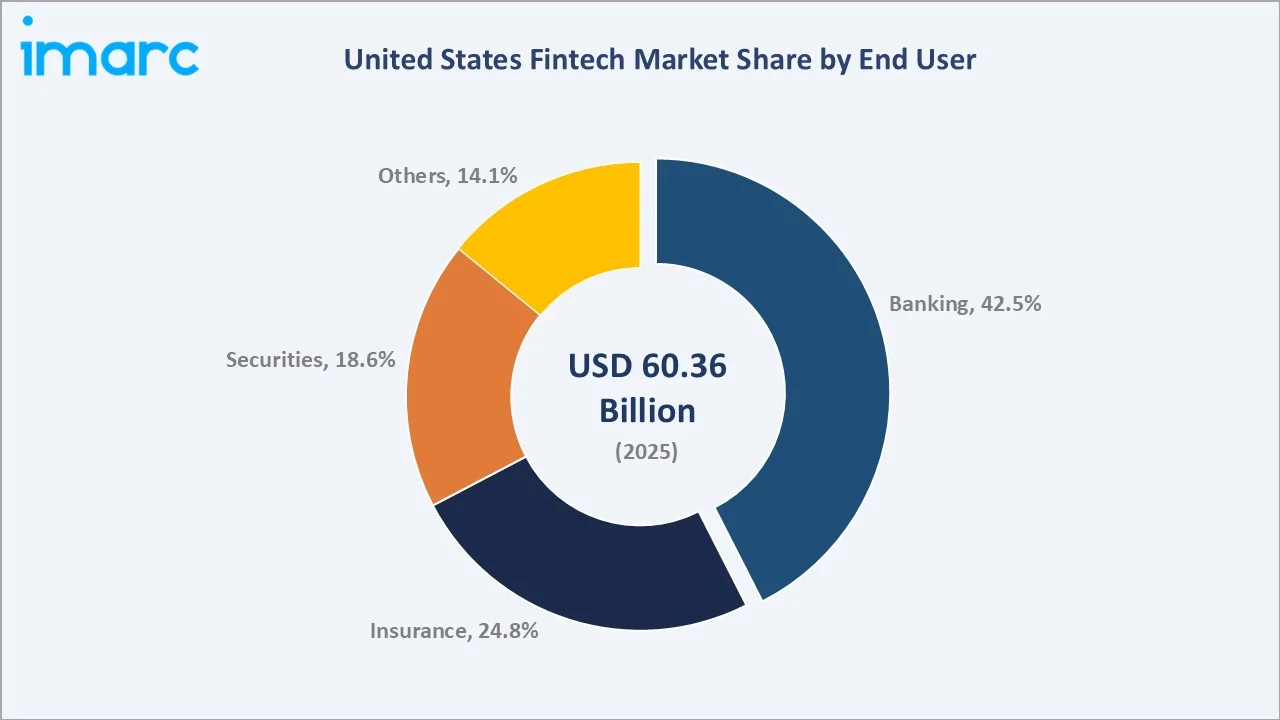
Insurance at 24.8% reflects rapid insurtech adoption across property & casualty, health, life, and specialty insurance lines through AI-powered underwriting, digital claims processing, and embedded insurance distribution. Securities at 18.6% is growing fastest at ~15.8% CAGR through AI-driven quantitative trading, robo-advisory wealth management platforms, blockchain-based settlement, and SEC-approved digital asset investment products. Others at 14.1% encompass payments, cryptocurrency exchanges, mortgage technology, and proptech-adjacent financial services.
Regional Market Insights
|
Region |
Share (2025) |
Key United States Fintech Market Drivers & Characteristics |
|
West |
31.7% |
Benefits from a mature technology ecosystem, strong venture capital availability, and a large concentration of fintech startups and skilled technology talent. |
|
Northeast |
27.4% |
Supported by its established financial services sector, strong banking presence, and growing collaboration between traditional financial institutions and fintech companies. |
|
South |
24.6% |
Emerging as a fast-growing fintech hub, supported by business-friendly environments, relatively lower operating costs, and expanding technology ecosystems. |
|
Midwest |
16.3% |
Benefits from an established banking network, comparatively affordable talent, and increasing adoption of digital banking and fintech solutions among regional financial institutions. |
The West Region's 31.7% dominance reflects Silicon Valley's structural advantages: the world's deepest fintech venture capital ecosystem, the highest concentration of senior fintech engineering talent, proximity to major consumer technology platform potential distribution partners, and the entrepreneurial culture. The Northeast's 27.4% reflects New York City's unique position as both the nation's largest financial services market and a major fintech innovation hub.
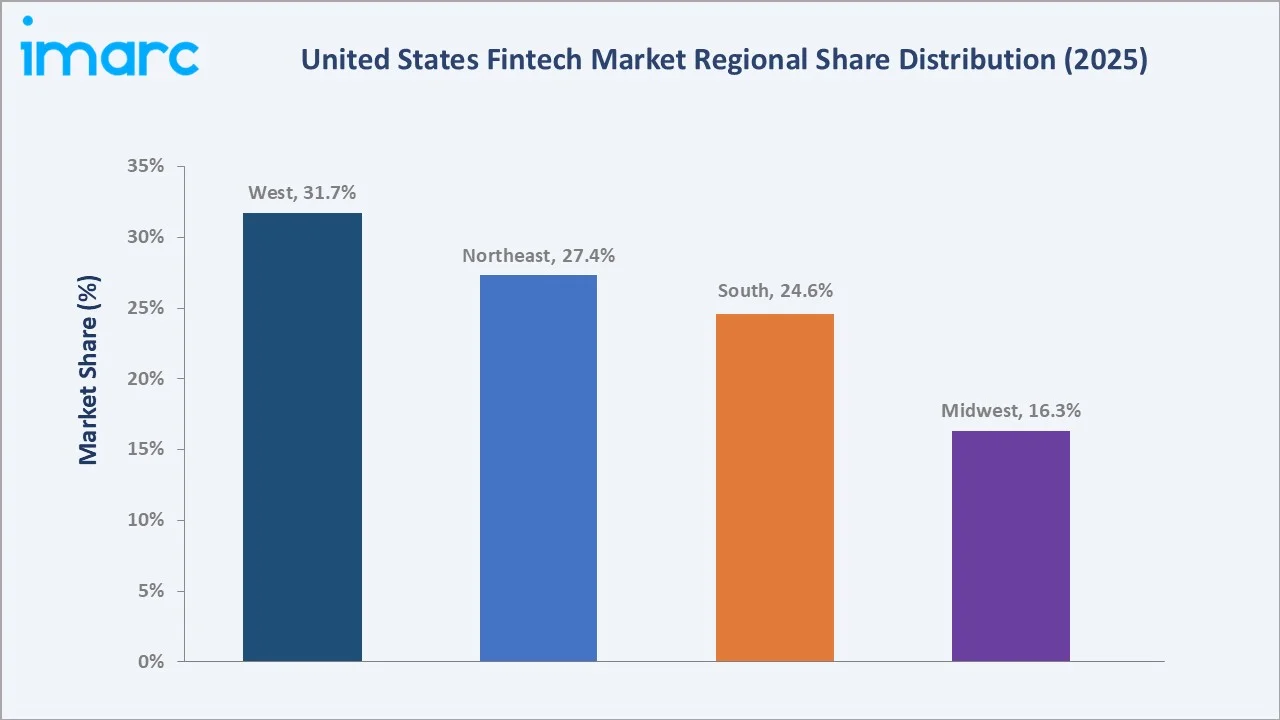
The South's 24.6% share reflects the most dynamic regional growth trajectory in the US fintech market, driven by Austin's rapid fintech ecosystem development and Atlanta's deep-rooted payment processing heritage. The Midwest's 16.3% is anchored by Chicago's institutional market strengths in derivatives fintech, financial data services, and B2B banking technology solutions serving the US heartland's commercial banking and agricultural finance sectors.
Competitive Landscape
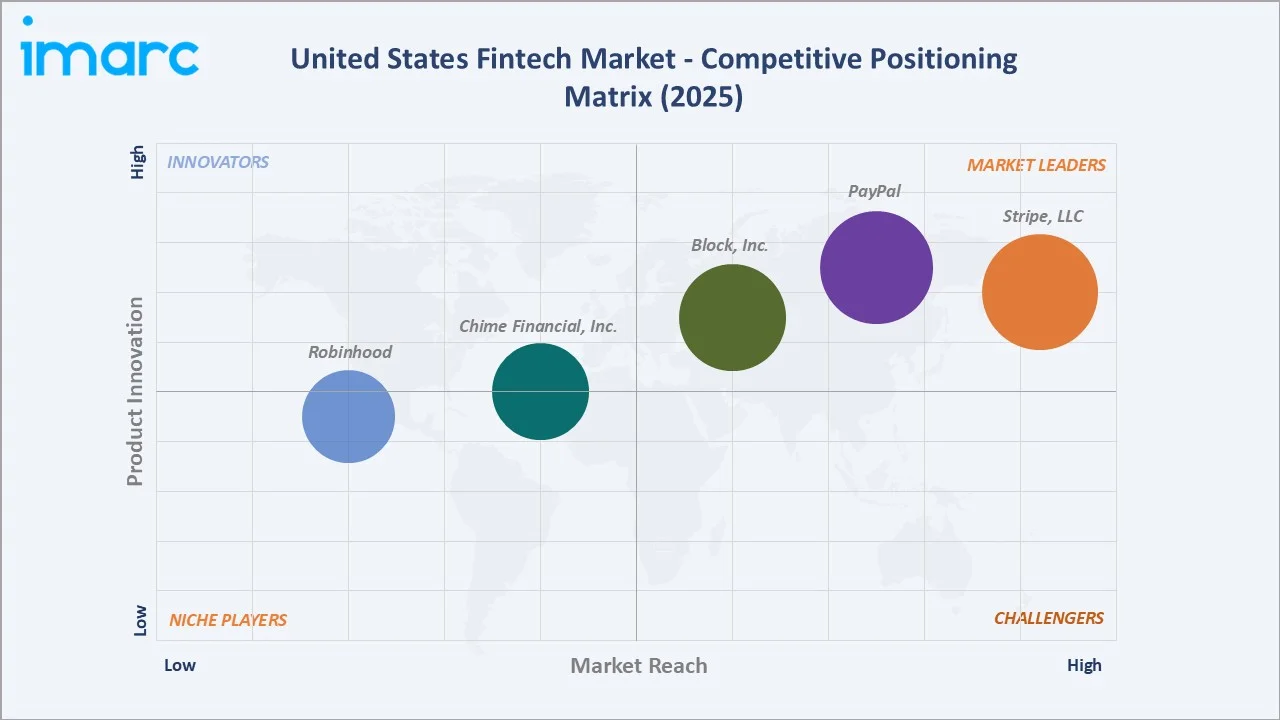
The United States fintech market features a multi-tier competitive structure encompassing global payment giants, consumer fintech platforms, financial infrastructure providers, vertical specialists, and emerging AI-native fintech companies. Competition centers on product innovation velocity, AI capability depth, regulatory compliance expertise, partnership network breadth, and customer acquisition economics.
|
Company |
Key Offerings |
Market Position |
Core Strength |
|
Stripe, LLC |
Neobanks, Remittance operators, Trading and digital brokerages, Financial SaaS, Payments infrastructure |
Market Leader |
Stripe, LLC serves as a primary financial infrastructure provider in the United States fintech market, powering online transactions, payment processing, and embedded financial services. |
|
PayPal |
PayPal Braintree, PayPal payments, PayPal Pay Later, Venmo |
Market Leader |
PayPal processes digital commerce, enabling peer-to-peer payments, and supplying backend processing for merchants. |
|
Block, Inc. |
Square, Cash App, Afterpay |
Market Leader |
Block, Inc. operates a dual-ecosystem model that serves both individual consumers and merchants. |
|
Chime Financial, Inc. |
Fee-Free Banking, Chime Card |
Established Player |
Reshaping how everyday consumers interact with banking services by eliminating traditional fees. |
|
Robinhood |
Robinhood Crypto, Robinhood Gold, Robinhood Cash Card |
Established Player |
Robinhood plays a foundational role in United States fintech by pioneering commission-free retail investing and accelerating the shift toward digital-first financial apps. |
The competitive landscape is rapidly being reshaped by AI capability differentiation, with companies deploying proprietary LLM-based financial analysis tools, AI-powered underwriting, and generative AI customer experience platforms establishing durable competitive advantages over companies without AI-native product architectures. Strategic M&A activity is consolidating capabilities around payments-banking, lending-deposits, and investment-insurance product bundles.
Key Company Profiles
Stripe, LLC
Stripe, LLC is the most valuable private fintech company and the dominant US payment infrastructure platform powering millions of businesses. Stripe's developer-first API approach fundamentally democratized payment infrastructure, enabling any company to accept payments, manage subscriptions, issue cards, and build financial products without proprietary banking relationships.
- Key Offerings: Neobanks, Remittance operators, Trading and digital brokerages, Financial SaaS, Payments infrastructure.
- Strategic Focus: Expanding Stripe Treasury's banking-as-a-service capabilities to enable any business to embed financial products, scaling AI fraud prevention across global payment networks, pursuing IPO readiness while expanding in high-growth international markets.
PayPal
PayPal is the largest consumer digital payment company, operating through its PayPal wallet, Venmo P2P platform, Braintree payment gateway, and others. PayPal pioneered consumer digital payments in the early internet era, evolving from eBay's payment processor to an independent financial services platform serving both consumer and merchant segments. Venmo's US users, PayPal's BNPL Pay Later offering, and the Braintree gateway serving enterprise merchants position PayPal across critical points of US commerce infrastructure.
- Key Offerings: PayPal Braintree, PayPal payments, PayPal Pay Later, Venmo.
- Strategic Focus: Driving PayPal branded checkout monetization through AI-personalized checkout experiences, expanding Venmo's monetization through Venmo Business and debit card, growing PayPal's BNPL market share, deploying AI for transaction fraud reduction and customer churn prevention.
Market Concentration Analysis
The US fintech market is moderately fragmented at the company level but highly concentrated within specific product categories. Stripe and PayPal collectively dominate US online merchant payment processing infrastructure. The market is experiencing consolidation through strategic M&A as mature fintech platforms seek to add capabilities and distribution channels. Overall, the market's high growth rate is sustaining fragmentation by continuously expanding addressable market segments faster than consolidation dynamics concentrate them.
Investment & Growth Opportunities
Highest Growth Segments
Securities end user fintech (~15.8% CAGR est.), cloud-based deployment platform (~15.2% CAGR est.), AI/generative AI financial services applications, open banking API infrastructure, and embedded finance/banking-as-a-service platforms represent the US fintech market's highest-priority investment vectors through 2034.
Investment Themes
- Generative AI Financial Services Platform Investment: Companies developing proprietary LLM-based financial services applications, from AI-powered loan underwriting and fraud detection to generative AI regulatory compliance and personalized wealth management advisory, represent the highest-growth investment opportunity in the US fintech market. Enterprise fintech software companies embedding GenAI across banking, insurance, and securities platforms are positioned to capture the high annual efficiency value that AI automation will generate in US financial services through 2034.
- Open Banking API Ecosystem and Data Infrastructure: Companies positioned in the data infrastructure layer, enabling the flow of consumer financial data between institutions and fintech apps with consent, are positioned to benefit from mandatory regulatory adoption that creates durable revenue streams as every major US financial institution becomes an API-accessible data provider.
Future Market Outlook (2026-2034)
The United States fintech market is projected to grow from USD 60.36 Billion in 2025 to USD 193.17 Billion by 2034, delivering a 13.80% CAGR over the forecast period through generative AI financial services adoption, open banking API ecosystem expansion, embedded finance mainstreaming, real-time payment infrastructure scaling, and blockchain-based asset tokenization. The market's anchor value of USD 115.19 Billion in 2030 represents the inflection point at which AI-native fintech platforms achieve institutional-scale deployment across US banking, insurance, and securities markets, and real-time payment infrastructure reaches critical mass across the US financial system.
Three structural forces are expected to define the US fintech market through 2034. First, AI will transform from a competitive differentiator to a baseline operational requirement across every US fintech category. Second, open banking will create the US API economy for financial services, unlocking consumer-permissioned financial data access at institutional scale. Third, the convergence of blockchain technology, stablecoin infrastructure, and tokenized real-world assets will create new fintech market segments in securities settlement, cross-border payments, and democratized alternative asset investment that collectively represent multi-hundred-billion-dollar market opportunities.
Research Methodology
Primary Research
Primary research comprised in-depth interviews with senior executives from fintech companies, financial technology investors, incumbent bank technology leaders, regulatory affairs specialists, fintech accelerator operators, and industry analysts specializing in the US financial technology sector. Discussions validated market size estimates, assessed deployment mode and end user segment dynamics, evaluated competitive positioning, and gathered qualitative insights on AI adoption rates, open banking policy implications, and regional market development across the US fintech ecosystem.
Secondary Research
Secondary research encompassed company annual reports and investor presentations, fintech charter guidance, digital asset regulatory frameworks, financial inclusion surveys, venture capital investment databases, fintech industry association publications, and reputable market intelligence publications. These resources analyzed market trends, regulatory developments, technology adoption trajectories, and competitive positioning across the US fintech industry.
Forecasting Models
Forecasting models were developed using historical market revenue data (2020-2025), AI adoption rate projections across financial services sectors, cloud migration velocity data, open banking regulatory timeline analysis, real-time payment scaling trajectory, VC investment trend extrapolation, and macroeconomic financial services spending indicators. The analysis incorporated both top-down and bottom-up approaches, validated through primary research cross-referencing, to generate reliable US fintech market forecasts through 2034.
United States Fintech Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical and Forecast Trends, Industry Catalysts and Challenges, Segment-Wise Historical and Predictive Market Assessment:
|
| Deployment Modes Covered | On-premises, Cloud-based |
| Technologies Covered | Application Programming Interface, Artificial Intelligence, Blockchain, Robotic Process Automation, Data Analytics, Others |
| Applications Covered | Payment and Fund Transfer, Loans, Insurance and Personal Finance, Wealth Management, Others |
| End Users Covered | Banking, Insurance, Securities, Others |
| Regions Covered | Northeast, Midwest, South, West |
| Companies Covered | Stripe, LLC, PayPal , Block, Inc., Chime Financial, Inc., Robinhood, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the United States fintech market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the United States fintech market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the United States fintech industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the United States Fintech Market Report
The United States fintech market reached USD 60.36 Billion in 2025, driven by generative AI adoption across financial services, growing embedded finance and digital payment volumes, real-time payment infrastructure scaling, and accelerating cloud-based fintech deployment across banking, insurance, and securities end users.
The market is projected to grow at a CAGR of 13.80% during 2026-2034, reaching USD 193.17 Billion by 2034, driven by AI-native fintech platform adoption, open banking API ecosystem expansion, embedded finance mainstreaming, and blockchain-based asset tokenization across US financial services.
Cloud-based deployment leads at 64.8% (2025), growing at ~15.2% CAGR through cloud-native neobanking, AI/ML model deployment advantages, open banking API integration efficiency, and major US financial institution cloud migration programs accelerating cloud-first fintech adoption.
Banking leads at 42.5% (2025) through neobanking growth, digital lending expansion, AI-powered core banking transformation, and real-time payment infrastructure adoption.
The West region leads at 31.7% (2025) through Silicon Valley's world-dominant fintech venture capital concentration, Bay Area technology talent density, and the headquarters of Stripe, Chime, Robinhood, Brex, Marqeta, and hundreds of fintech platforms.
Leading companies include Stripe, LLC, PayPal, Block, Inc., Chime Financial, Inc., and Robinhood, among others.
The market is projected to reach approximately USD 115.19 Billion by 2030, representing the inflection point where AI-native fintech platforms achieve institutional-scale deployment, real-time payments reach critical mass, and open banking creates the US API economy for financial services.
AI, particularly generative AI, is transforming US fintech through automated customer service replacing human contact centers, AI credit underwriting enabling profitable serving of credit-invisible consumers, AI fraud detection processing millions of transactions per second, personalized wealth advisory at scale, and RegTech automation reducing BSA/AML compliance costs for financial institutions deploying AI-powered compliance monitoring.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade