
United States Genetic Testing Market Size, Trends and Forecast by Type, Technology, Application, and Region, 2026-2034
United States Genetic Testing Market Size, Share, Trends & Forecast (2026-2034)
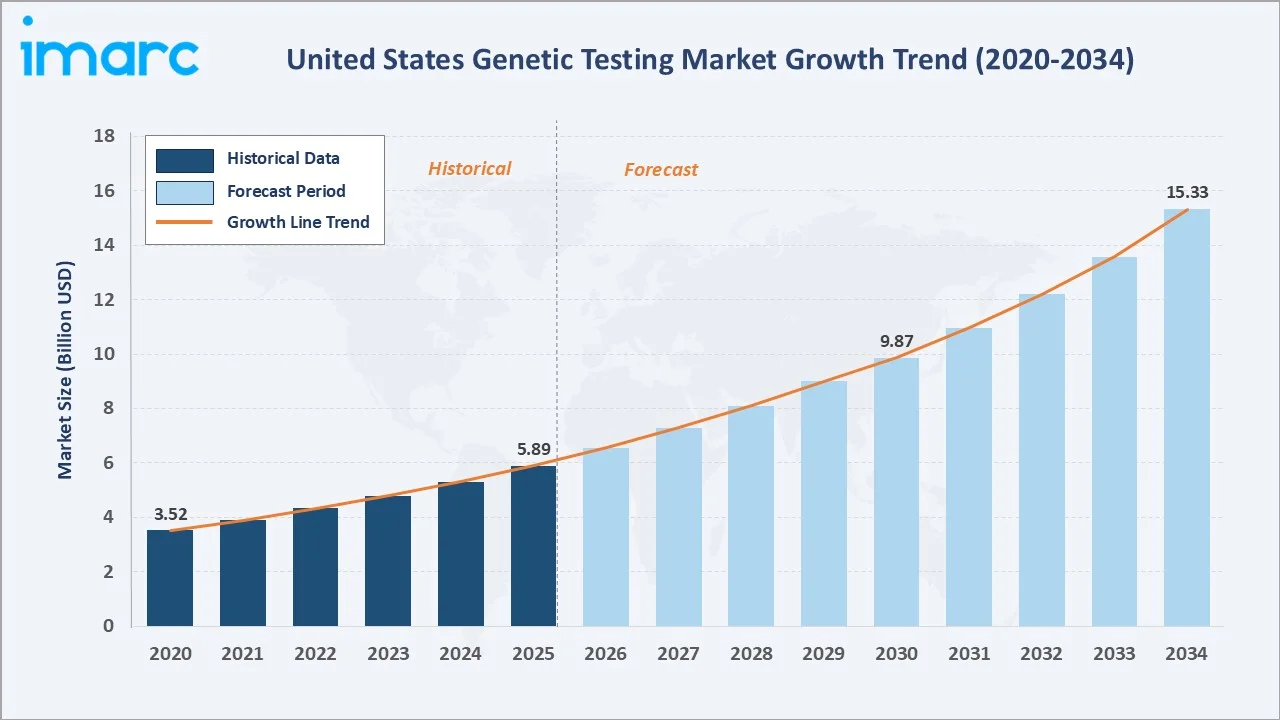
The United States genetic testing market reached USD 5.89 Billion in 2025 and is projected to reach USD 15.33 Billion by 2034, exhibiting a growth rate (CAGR) of 10.87% during 2026-2034. The us genetic testing market is driven by rising prevalence of chronic and genetic diseases, notable advancements in next-generation sequencing (NGS) technology, growing consumer interest in direct-to-consumer (DTC) testing, a growing focus on precision and personalized medicine, and growing oncology diagnostics applications.
Cancer Diagnosis dominates the application segment at 42.8% in 2025, driven by BRCA screening and tumor profiling in oncology. Molecular Testing leads technology at 58.7%, underpinned by rapid NGS platform adoption. The South region leads regionally at 36.8%, anchored by dense healthcare infrastructure across Texas, Florida, and Georgia.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 5.89 Billion |
|
Forecast Market Size (2034) |
USD 15.33 Billion |
|
CAGR (2026-2034) |
10.87% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Technology |
Molecular Testing (58.7%,, 2025) |
| Dominant Application |
Cancer Diagnosis (42.8%, 2025) |
|
Leading Region |
South (36.8%, 2025) |
The market expanded from an estimated USD 3.52 Billion in 2020 to USD 5.89 Billion in 2025, supported by accelerating NGS adoption and growing insurance coverage for genetic diagnostics. The market is anchored at an estimated USD 9.87 Billion in 2030 and is projected to reach USD 15.33 Billion by 2034, with AI-powered diagnostics and liquid biopsy driving the sustained growth trajectory.
To get more information on this market, Request Sample
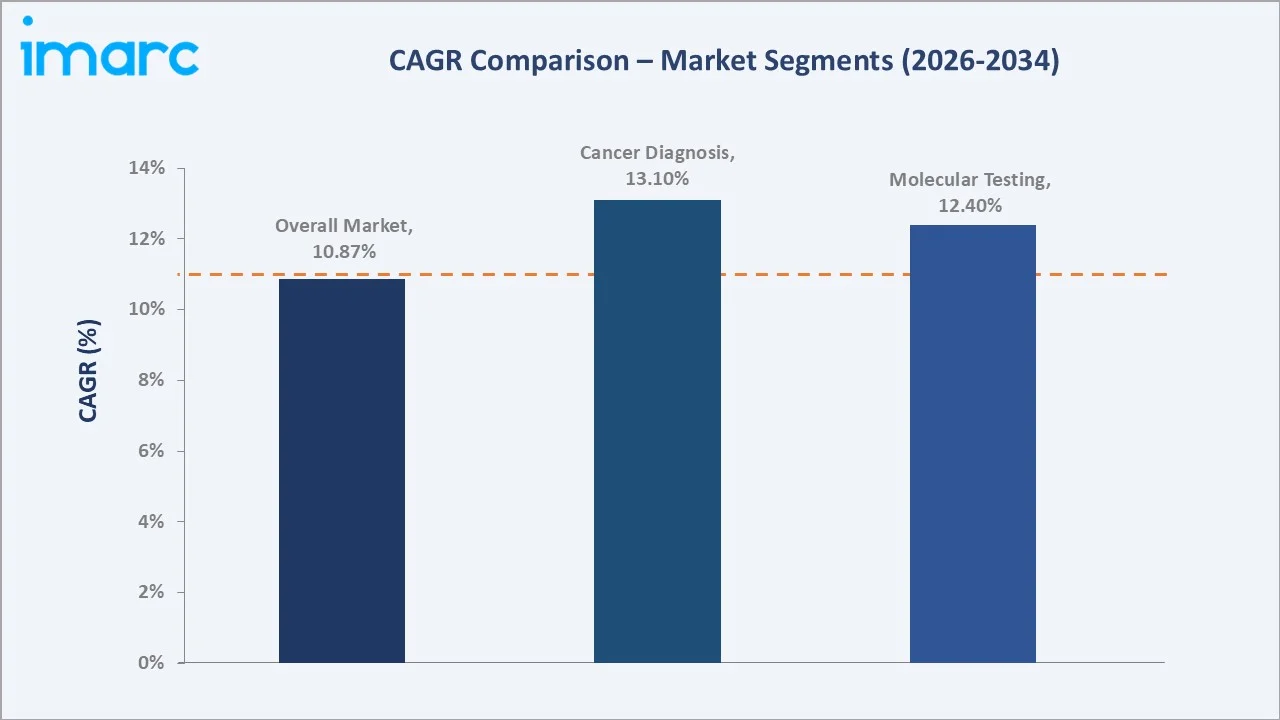
Molecular Testing and Cancer Diagnosis are set to grow fastest through 2034, outpacing the overall market CAGR of 10.87% as next-generation sequencing costs continue declining and companion diagnostic mandates expand. The South and West regions also grow above the market average as biotech investment and healthcare infrastructure continue to scale.
Executive Summary
The United States genetic testing market reached USD 5.89 Billion in 2025, representing the world's largest single-country genetic diagnostics market, underpinned by fundamental strength in NGS technology, oncology companion diagnostics, and a growing consumer genomics ecosystem. Genetic testing in the United States performs a role extending well beyond clinical diagnosis, functioning as a preventive health tool, pharmacogenomic guide, and consumer wellness product across a broad, multi-application market. The market is projected to reach USD 15.33 Billion by 2034.
Molecular Testing at 58.7% dominates by capturing the rapidly expanding NGS-powered segment that enables comprehensive multi-gene panels for oncology, rare disease, and pharmacogenomics in a single workflow. Cancer Diagnosis at 42.8% leads through BRCA testing and tumor mutational burden analysis. The South at 36.8% leads nationally through dense hospital networks and high chronic disease prevalence driving diagnostic demand.
Key Market Insights
|
Insight |
Data |
|
Dominant Technology |
Molecular Testing - 58.7% share (2025) |
|
Dominant Application |
Cancer Diagnosis - 42.8% share (2025) |
|
Leading Region |
South - 36.8% share (2025) |
|
Market Opportunity |
AI diagnostics; liquid biopsy; DTC expansion; pharmacogenomics |
Key Analytical Observations Supporting the Above Data:
- Molecular Testing at 58.7%: This segment dominates as NGS technology dramatically reduces per-test costs, enabling broad clinical deployment across cancer, rare disease, and pharmacogenomics. Its compatibility with multi-gene panels and whole-genome sequencing workflows reinforces segment leadership. Rapid throughput improvements and the proliferation of FDA-cleared NGS-based companion diagnostics further sustain its dominant and expanding market position.
- Cancer Diagnosis at 42.8%: The oncology application leads due to BRCA1/2 testing, tumor profiling, and companion diagnostic requirements linked to FDA-approved targeted therapies. Growing adoption of liquid biopsy and circulating tumor DNA for non-invasive cancer monitoring adds incremental volume. Expanded genetic counseling integration and payer coverage for hereditary cancer panels continue to deepen this segment's market penetration across hospital and clinic settings.
- South at 36.8%: Texas, Florida, and Georgia anchor this region through major hospital networks, rising chronic disease burden, and growing biotech investment supporting genetic diagnostics infrastructure. Expanding insurance coverage for genetic tests and an aging population driving predictive testing demand amplify regional growth within the united states genetic testing market Size landscape.
United States Genetic Testing Market Overview
The United States genetic testing market encompasses diagnostic, predictive, and consumer genomics services utilizing DNA sequencing, chromosomal analysis, and biochemical assays. Applications span oncology, rare disease, cardiovascular, reproductive, pharmacogenomic, and direct-to-consumer wellness testing, covering clinical laboratory and consumer market segments.
The ecosystem integrates biotech innovators, laboratory service providers, healthcare networks, and regulatory bodies including the FDA and CMS. Federal reimbursement policies and NGS regulatory pathways shape the market's structural growth dynamics.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
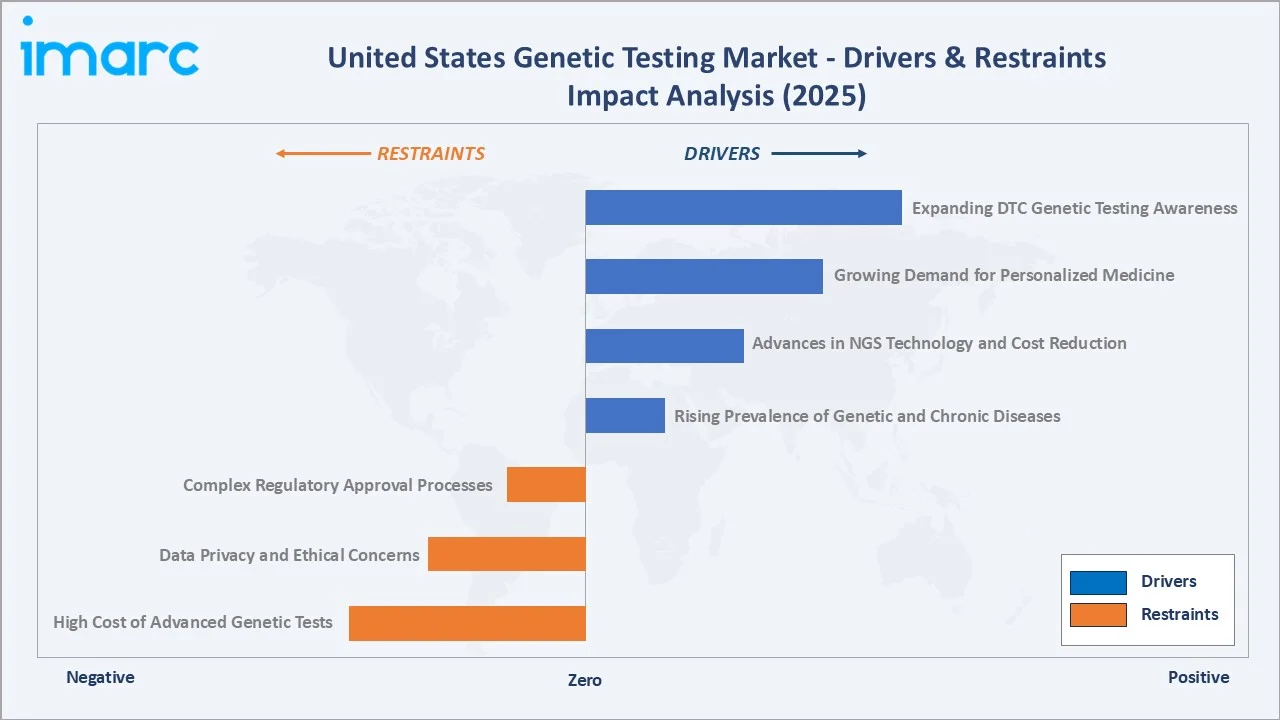
- Rising Prevalence of Genetic and Chronic Diseases: Increasing incidence of hereditary cancers, cardiovascular conditions, and rare genetic disorders directly expands demand for diagnostic and predictive genetic testing across clinical specialties. Growing physician adoption of genetic screening protocols in oncology, cardiology, and reproductive medicine strengthens test volumes. Multi-gene panel ordering per patient is rising as clinical guidelines increasingly mandate genetic workups for hereditary disease risk assessment.
- Advances in NGS Technology and Cost Reduction: Next-generation sequencing has reduced whole-genome sequencing costs from millions of dollars to under USD 1,000, enabling broad clinical and consumer deployment at commercially viable price points. Rapid throughput improvements and panel expansion allow laboratories to offer comprehensive multi-gene tests faster and more affordably than ever before. Continued cost deflation across NGS instruments, reagents, and bioinformatics is expected to sustain the United States genetic testing market Growth through the forecast period.
- Growing Demand for Personalized Medicine: Precision medicine approaches require genetic profiling to guide treatment selection, particularly in oncology and pharmacogenomics, driving sustained multi-test ordering per patient. Payers and health systems are progressively embedding genetic testing into care pathways, expanding the addressable market across clinical specialties and primary care. FDA approvals of genetically guided therapies with companion diagnostic requirements support sustained mandatory testing volume.
- Expanding DTC Genetic Testing Awareness: Consumer-facing platforms dramatically increased public awareness of genetic health information, expanding testing demand well beyond clinical settings into the general consumer market. DTC platforms broadening from ancestry into health risk, pharmacogenomics, and wellness insights are widening the addressable market to millions of non-clinical consumers annually.
Market Restraints
- High Cost of Advanced Genetic Tests: Despite NGS cost reductions, comprehensive multi-gene panels and whole-genome sequencing remain expensive for uninsured or underinsured patients, limiting broad population-level access. Inconsistent payer coverage policies across commercial insurers and Medicare create access barriers that constrain adoption in cost-sensitive patient populations and lower-income demographics across the us genetic testing market.
- Data Privacy and Ethical Concerns: Genetic information is uniquely sensitive, raising patient concerns about data security, insurer discrimination, and third-party data sharing by genomics companies. Regulatory uncertainty around data governance frameworks and genetic information non-discrimination protections creates barriers to DTC adoption. Ethical debates around predictive testing for life insurance and employment continue to limit consumer willingness to share genomic data with commercial genomics platforms.
- Complex Regulatory Approval Processes: FDA oversight of laboratory-developed tests (LDTs) and evolving regulatory frameworks create compliance costs and uncertain approval timelines that constrain new test launches. Changing regulatory requirements for LDTs introduce risk for smaller specialized laboratories with limited compliance infrastructure and resources. Lengthy clinical validation requirements and complex reimbursement coding processes add time-to-market delays that slow adoption of innovative genetic testing technologies into routine care.
Market Opportunities
- AI-Powered Genomic Diagnostics: Artificial intelligence and machine learning platforms are improving variant interpretation accuracy, enabling faster clinical reporting, and identifying novel disease associations across large genomic datasets. AI-driven diagnostic tools reduce pathologist workload and interpretation variability while enabling scalable high-volume clinical NGS workflows. Healthcare systems and laboratory networks are actively investing in AI-genomics integration as a core operational priority.
- Liquid Biopsy and Non-Invasive Testing: Cell-free DNA and circulating tumor DNA technologies enable cancer screening and treatment monitoring through blood draws, significantly reducing procedural barriers to early detection. Expanding FDA-cleared liquid biopsy applications represent a structurally growing opportunity for oncology diagnostic providers and testing laboratories. The non-invasive nature of liquid biopsy supports broader integration into routine cancer screening programs nationwide.
Market Challenges
- Reimbursement Uncertainty: Coverage policies for newer genetic tests remain inconsistent across commercial payers and Medicare, creating revenue uncertainty for laboratory providers planning commercial launches. Prolonged coverage determination processes and frequent coding changes add administrative burden that disproportionately affects smaller independent laboratories across the united states genetic testing market.
- Workforce and Interpretation Gaps: Demand for genetic counselors and clinical genomicists significantly exceeds available supply, creating interpretation bottlenecks that slow test adoption in clinical settings. Insufficient training infrastructure for primary care physicians in genomic medicine limits the integration of genetic testing into routine preventive care pathways. Growing test volumes and panel complexity further strain clinical genetics workforce capacity.
Emerging Market Trends
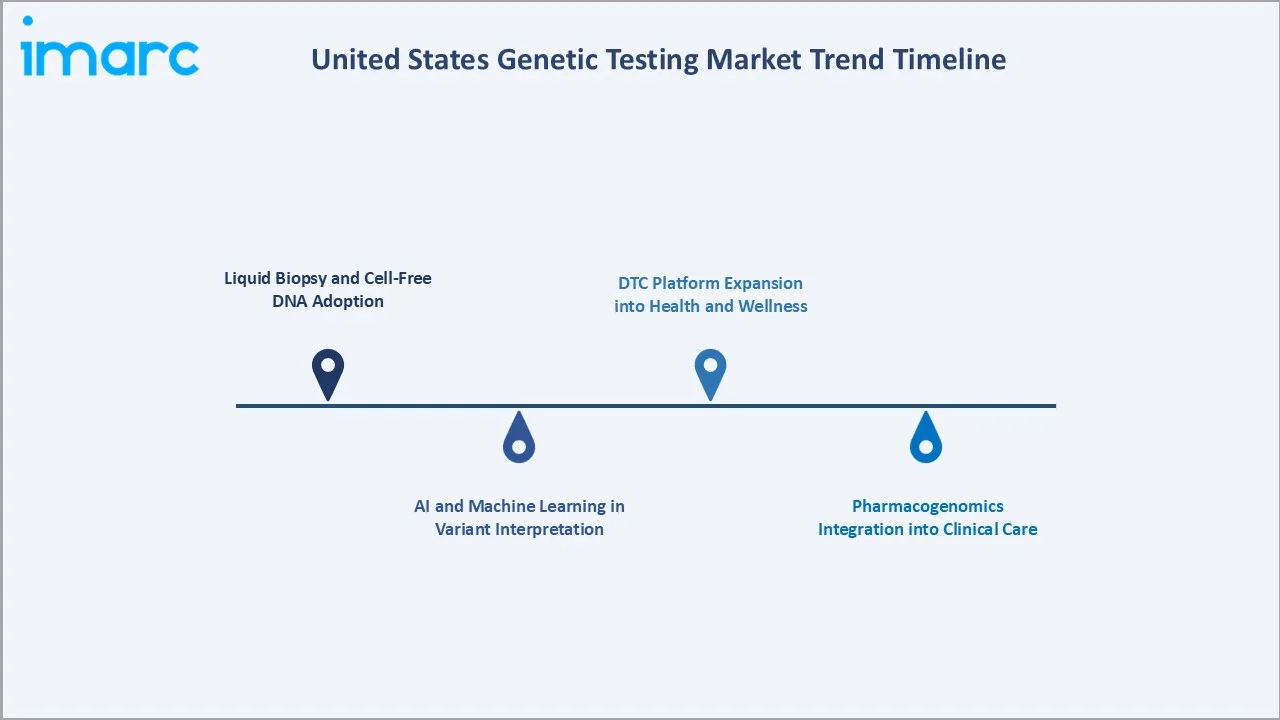
1. Liquid Biopsy and Cell-Free DNA Adoption
Liquid biopsy tests using circulating tumor DNA are transitioning from research use to routine clinical oncology practice, enabling non-invasive cancer detection, treatment monitoring, and minimal residual disease assessment. FDA approvals for blood-based cancer screening are expanding clinical utility well beyond traditional tissue biopsy settings.
2. AI and Machine Learning in Variant Interpretation
Artificial intelligence platforms are significantly improving the speed and accuracy of genomic variant pathogenicity classification, reducing expert workload and enabling scalable clinical reporting at high volume. AI-assisted tools are being embedded into laboratory information systems across major reference laboratories as a core workflow component.
3. Pharmacogenomics Integration into Clinical Care
Pharmacogenomic testing, which guides drug selection and dosing based on patient genetic profiles, is being embedded into electronic health record systems and hospital formulary protocols for psychiatry, oncology, and primary care specialties. This integration drives multi-test ordering per patient and strengthens the clinical value proposition for genetic platforms.
4. DTC Platform Expansion into Health and Wellness
Direct-to-consumer platforms are broadening from ancestry into carrier screening, health predisposition, and polygenic risk scores, forming partnerships with healthcare systems to bridge consumer-generated genetic data into clinical workflows. This consumer-to-clinical pipeline is creating a new scalable patient acquisition model for the broader genetic testing ecosystem.
Industry Value Chain Analysis
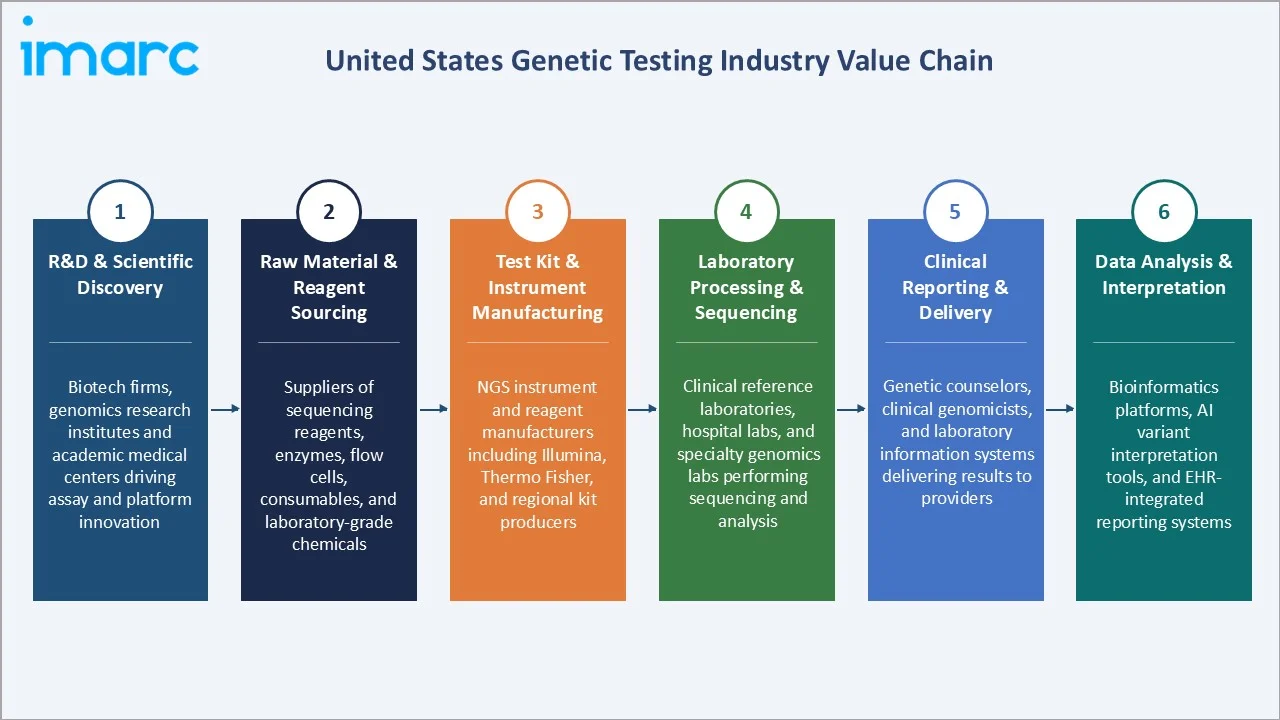
The United States genetic testing value chain spans R&D and scientific discovery, raw material and reagent sourcing, test kit and instrument manufacturing, laboratory processing and sequencing, clinical reporting and delivery, and data analysis and interpretation. Each stage is shaped by regulatory compliance requirements, reimbursement policies, and technology performance standards that define commercial viability.
|
Stage |
Key Participants |
| R&D & Scientific Discovery | Biotech firms, genomics research institutes, and academic medical centers driving assay and platform innovation |
| Raw Material & Reagent Sourcing | Suppliers of sequencing reagents, enzymes, flow cells, consumables, and laboratory-grade chemicals |
| Test Kit & Instrument Manufacturing | NGS instrument and reagent manufacturers including Illumina, Thermo Fisher, and regional kit producers |
| Laboratory Processing & Sequencing | Clinical reference laboratories, hospital labs, and specialty genomics labs performing sequencing and analysis |
| Clinical Reporting & Delivery | Genetic counselors, clinical genomicists, and laboratory information systems delivering results to providers |
| Data Analysis & Interpretation | Bioinformatics platforms, AI variant interpretation tools, and EHR-integrated reporting systems |
Quality and safety oversight is embedded throughout the chain, with FDA clearance requirements shaping product development timelines and CMS coverage policies determining test adoption at the laboratory and clinical delivery stages.
Technology Landscape in the United States Genetic Testing Industry
Next-Generation Sequencing (NGS)
NGS represents the most transformative technology in genetic testing, enabling rapid and cost-effective sequencing of entire genomes or targeted gene panels at clinical scale. Its compatibility with cancer profiling, rare disease diagnosis, and pharmacogenomics makes it the primary growth engine across the Molecular Testing segment and the broader market.
CRISPR-Based Diagnostic Platforms
CRISPR-based diagnostic tools including SHERLOCK and DETECTR are emerging as highly sensitive and specific molecular detection methods for genetic mutations and pathogens. Their potential for point-of-care deployment and rapid detection is attracting significant R&D investment within the clinical and consumer diagnostics sectors.
AI-Assisted Genomic Analysis
Machine learning algorithms trained on large genomic datasets are enabling automated variant pathogenicity classification and population-level risk prediction with increasing clinical accuracy. Integration into laboratory information systems is improving diagnostic turnaround times and reducing interpretation variability across laboratory networks.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Type |
🔒 | 🔒 |
2025 |
| Technology | Molecular Testing | 58.7% |
2025 |
|
Application |
Cancer Diagnosis |
42.8% |
2025 |
|
Region |
South | 36.8% |
2025 |

By Technology
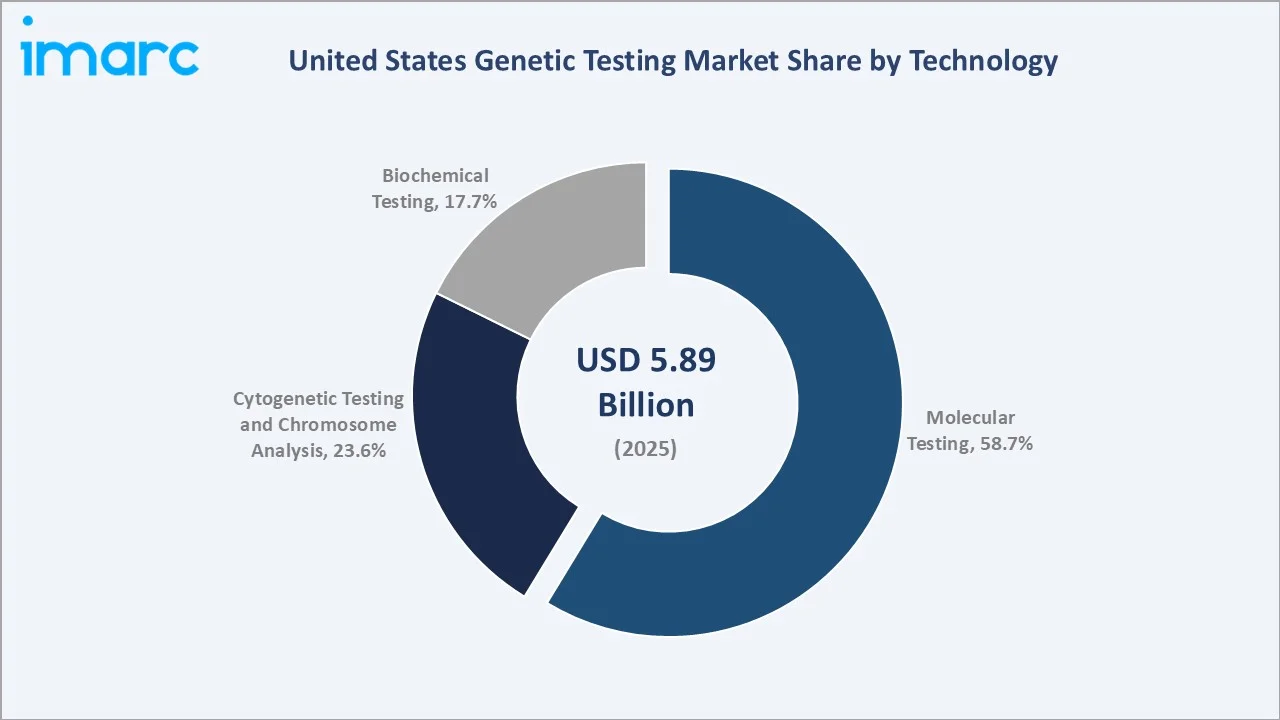
Molecular Testing leads at 58.7% in 2025, driven by NGS-powered cancer, rare disease, and pharmacogenomic panels that cover hundreds of clinically relevant genes in a single workflow. This segment's growth outpaces the overall united states genetic testing market Trends as test panels expand and sequencing costs continue to fall.
To access detailed market analysis, Request Sample
Cytogenetic Testing and Chromosome Analysis holds 23.6%, anchored by karyotyping and chromosomal microarray applications for prenatal diagnosis, hematologic malignancies, and constitutional disorders. Biochemical Testing at 17.7% encompasses metabolic disorder screening, particularly newborn screening panels mandated across all U.S. states.
By Application
Cancer Diagnosis leads at 42.8% in 2025, anchored by hereditary cancer syndrome testing, tumor mutational burden analysis, and companion diagnostic requirements for FDA-approved targeted oncology therapies. This segment's clinical centrality reflects the FDA's growing approval pipeline of genetically-guided cancer treatment protocols.
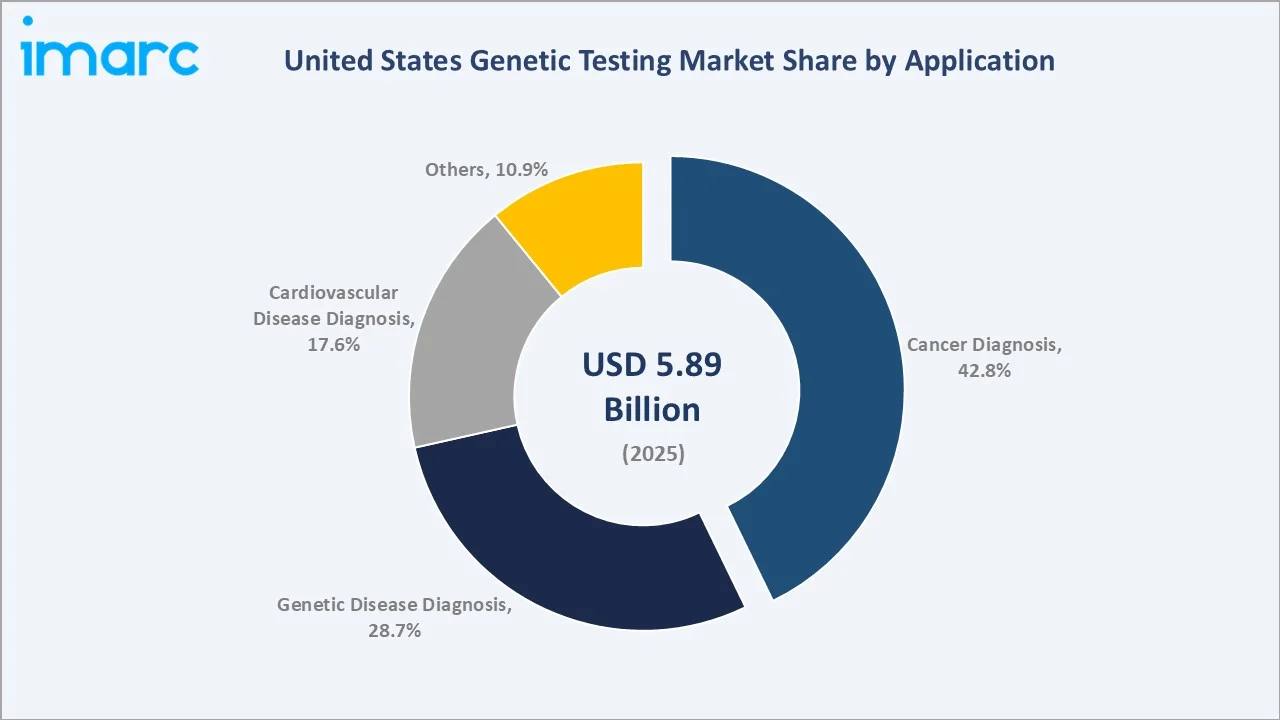
Genetic Disease Diagnosis at 28.7% spans rare Mendelian disorders, prenatal and newborn screening, and carrier testing for heritable conditions. Cardiovascular Disease Diagnosis at 17.6% covers familial hypercholesterolemia, inherited arrhythmias, and cardiomyopathy panels. Others, including pharmacogenomics and ancestry testing, account for 10.9%.
Regional Market Insights
|
Region |
Share (2025) |
Key Market Drivers & Characteristics |
| South |
36.8% |
Driven by high chronic disease burden, dense hospital networks, and rising biotech investment |
| West |
25.7% |
Supported by Silicon Valley genomics ecosystem, California DTC leadership, and strong R&D |
| Northeast |
19.6% |
Driven by leading academic medical centers, Boston and New York research infrastructure |
| Midwest |
17.9% |
Supported by growing clinical genomics networks and healthcare biotech synergies in IL, MN, OH |
The South at 36.8% leads through the healthcare infrastructure concentration in Texas, Florida, and Georgia, combined with high prevalence of chronic diseases—diabetes, cardiovascular conditions, and cancers—that drive predictive and diagnostic genetic testing demand across clinical and preventive care settings.
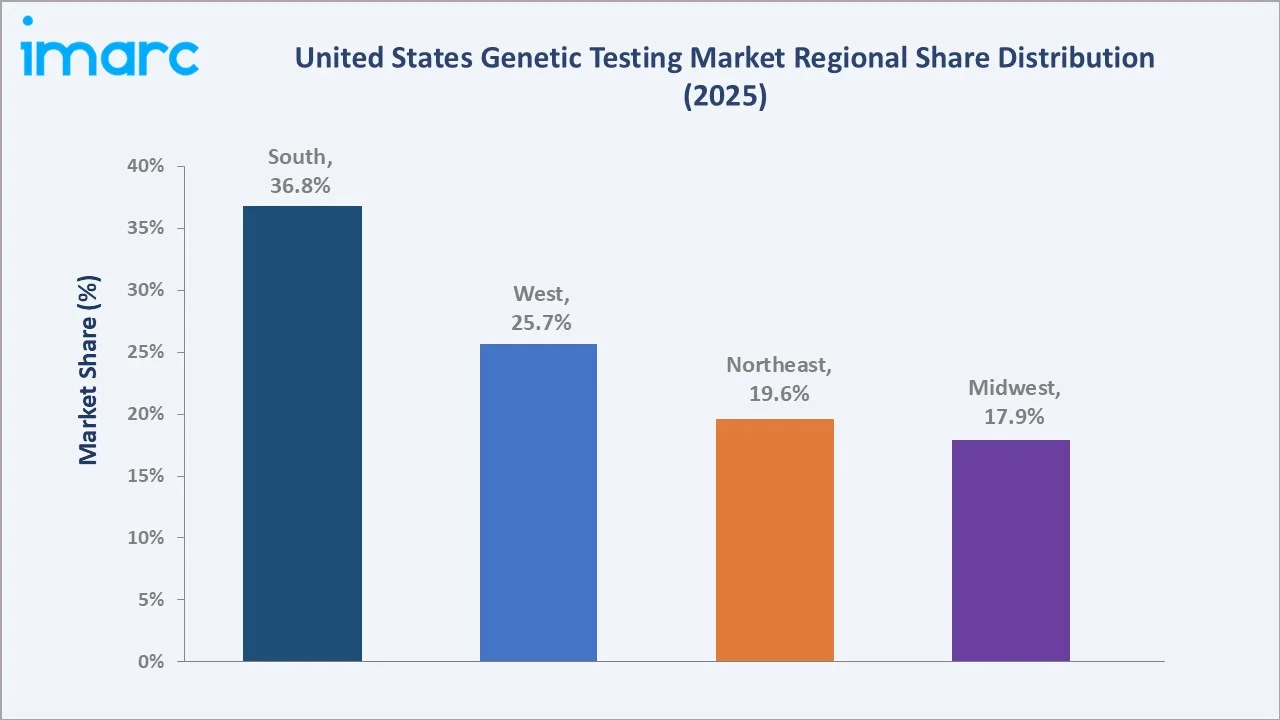
The West at 25.7% is anchored by California's dense biotech and life sciences ecosystem, including Silicon Valley-based genomics innovators and consumer DTC platforms. The Northeast at 19.6% benefits from leading academic medical centers in Boston, New York, and Philadelphia, with high specialist density and strong insurance coverage. The Midwest at 17.9% reflects steady growth through clinical genomics integration in major hospital systems across Illinois, Minnesota, and Ohio.
Competitive Landscape
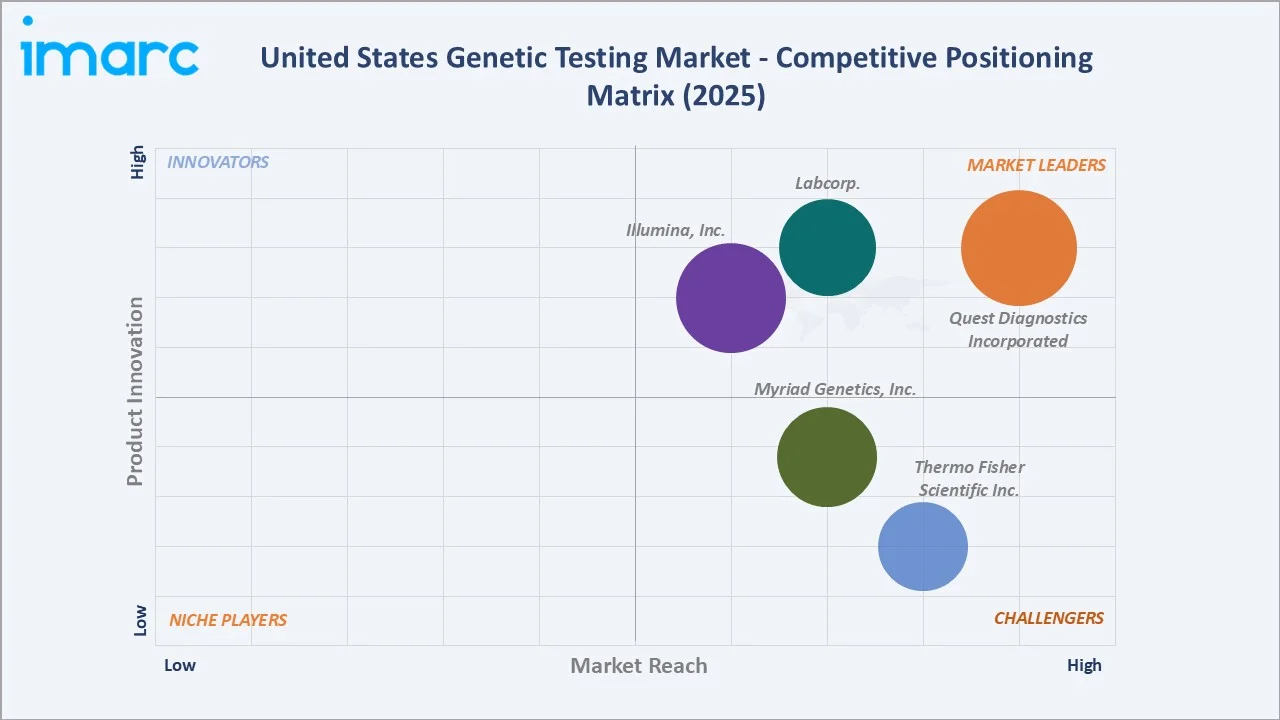
The United States genetic testing market competitive landscape is highly competitive, with global and domestic players vying for market leadership. It features three distinct tiers: large integrated diagnostics conglomerates with national laboratory networks, specialized oncology and rare-disease genetics firms, and consumer-facing DTC genomics platforms with large proprietary genetic databases.
|
Company Name |
Key Products / Brands |
Market Position |
Core Strength |
| Quest Diagnostics Incorporated |
Clinical lab testing, hereditary cancer panels, molecular diagnostics |
Market Leader |
Quest Diagnostics Incorporated holds the largest U.S. clinical lab network with national physician and consumer reach. |
| Labcorp. | Hereditary cancer panels, NIPT, pharmacogenomics, clinical genomics |
Market Leader |
Labcorp combines comprehensive genetic test breadth with a vertically integrated laboratory and clinical services network. |
| Myriad Genetics, Inc. |
BRACAnalysis, MyRisk hereditary cancer, GeneSight pharmacogenomics | Strong Challenger | Myriad Genetics pioneered hereditary cancer genetics in the U.S. with the dominant BRCA testing market position. |
| Illumina, Inc. | NovaSeq, NextSeq platforms, sequencing kits, DRAGEN bioinformatics | Market Leader | Illumina dominates NGS instrument and reagent supply, enabling the entire genetic testing laboratory ecosystem. |
| Thermo Fisher Scientific Inc. |
Ion Torrent sequencing, clinical kits, laboratory instruments and reagents | Strong Challenger | Thermo Fisher Scientific provides a broad NGS and molecular diagnostics instrument and reagent portfolio. |
Key players include Quest Diagnostics Incorporated, Labcorp., Myriad Genetics, Inc., Illumina, Inc., Thermo Fisher Scientific Inc., and others.
Key Company Profiles
Quest Diagnostics Incorporated
Quest Diagnostics Incorporated is the largest U.S. clinical laboratory company, with a national network of patient service centers and high-throughput processing capabilities supporting genetic testing across oncology, reproductive health, and pharmacogenomics.
- Key Products: Hereditary cancer panels, non-invasive prenatal testing (NIPT), pharmacogenomics, cytogenetics, and molecular oncology panels delivered through a national clinical network.
- Recent Development: In September 2025, Quest Diagnostics introduced an advanced pharmacogenomic (PGx) laboratory testing service in collaboration with Coriell Life Sciences to help clinicians use patients’ genetic information to guide medication selection and dosing. The offering evaluates 17 genes and 4 HLA alleles associated with clinically actionable gene–drug interactions and provides information on predicted drug response.
- Strategic Focus: Expanding the genetic test menu through technology partnerships, AI-powered reporting integration, and value-based care pathway embedding across hospital and payer networks. Quest is investing in DTC testing expansion, laboratory automation, and digital health platforms to capture growth across clinical and consumer segments.
Myriad Genetics, Inc.
Myriad Genetics, Inc. is a precision medicine company that pioneered hereditary cancer genetic testing in the United States with the BRACAnalysis test, holding a leading position in BRCA testing and hereditary cancer panel diagnostics. The company also operates GeneSight, a leading pharmacogenomics platform, and has expanded into prenatal and cardiovascular genetic testing through strategic acquisitions.
- Key Products: BRACAnalysis CDx, MyRisk hereditary cancer panel, GeneSight pharmacogenomics, Prequel prenatal screening, and RiskScore polygenic risk assessment tools for breast cancer and melanoma.
- Strategic Focus: Expanding pharmacogenomics into mainstream psychiatry and primary care while defending hereditary cancer panel market leadership against growing NGS panel competition. Myriad is broadening its companion diagnostic partnerships with biopharmaceutical companies and investing in polygenic risk score product development to capture emerging preventive medicine market opportunities and sustain long-term revenue diversification.
Market Concentration Analysis
The United States genetic testing market is moderately concentrated at the integrated diagnostics level, with the key players commanding a leading share of routine clinical genetic test volume. Market concentration is expected to remain broadly stable through 2034.
Investment & Growth Opportunities
Highest Growth Segments
Cancer Diagnosis (~13.1% CAGR) and Molecular Testing (~12.4% CAGR) represent the highest-growth investment vectors through 2034, both outpacing the overall market CAGR of 10.87% as companion diagnostics proliferate and NGS panel adoption accelerates across oncology centers and reference laboratories nationally.
Emerging Investment Opportunities
AI-powered diagnostic platforms and liquid biopsy cancer screening represent the market's most structurally attractive emerging themes, supported by regulatory momentum and favorable reimbursement signals from CMS and commercial payers.
Investment Themes
- AI and Bioinformatics Platform Investment: Automating variant interpretation and clinical report generation offers significant margin improvement and capacity scaling opportunities for laboratory operators facing high-volume NGS workflow demands. Early-mover advantages in AI-genomics integration are expected to compound as training datasets expand and model accuracy improves.
- DTC-to-Clinical Pipeline Development: Building integrated platforms that convert consumer-generated genetic data into physician-ordered diagnostic follow-up creates a scalable patient acquisition and recurring test volume model with lower customer acquisition costs than traditional clinical marketing approaches.
Future Market Outlook (2026-2034)
The United States genetic testing market is projected to grow from USD 5.89 Billion in 2025 to USD 15.33 Billion by 2034, delivering a steady 10.87% CAGR over the forecast period. The market's anchor value of an estimated USD 9.87 Billion in 2030 represents a diagnostics industry in accelerating structural expansion, with NGS cost deflation, AI-assisted reporting, and liquid biopsy adoption anchoring growth even as traditional genetic disease testing matures.
AI-powered genomic diagnostics and whole-genome sequencing are expected to achieve wider mainstream clinical adoption by 2030, while pharmacogenomic integration into electronic health records will drive multi-test ordering per patient. Three forces will define market growth through 2034: expansion of oncology companion diagnostics, integration of genetic testing into preventive care, and maturation of AI-assisted clinical genomics.
Research Methodology
Primary Research
Primary research comprised structured interviews with laboratory executives, oncology geneticists, genetic counselors, payer policy specialists, and industry association representatives, providing first-hand insight into clinical adoption trends, pricing dynamics, and competitive positioning across the value chain.
Secondary Research
Secondary research encompassed company annual reports, FDA approval databases, CMS reimbursement schedules, NIH funding disclosures, industry publications, and peer-reviewed genomics literature, cross-verified across multiple independent sources to ensure data reliability and analytical accuracy.
Forecasting Models
Market revenue forecasts were developed using a bottom-up test-volume model incorporating disease prevalence trends, clinical guideline adoption rates, payer coverage expansion forecasts, and technology cost curve projections for NGS and downstream analytical platforms across all segments and regions.
United States Genetic Testing Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical and Forecast Trends, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Predictive and Presymptomatic Testing, Carrier Testing, Prenatal and Newborn Testing, Diagnostic Testing, Pharmacogenomic Testing, Others |
| Technologies Covered |
|
| Applications Covered | Cancer Diagnosis, Genetic Disease Diagnosis, Cardiovascular Disease Diagnosis, Others |
| Regions Covered | Northeast, Midwest, South, West |
| Companies Covered | Quest Diagnostics Incorporated, Labcorp., Myriad Genetics, Inc., Illumina, Inc., Thermo Fisher Scientific Inc., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the United States genetic testing market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the United States genetic testing market.
- Porter's Five Forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the United States genetic testing industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the United States Genetic Testing Market Report
The United States genetic testing market reached USD 5.89 Billion in 2025, driven by the Molecular Testing segment dominant at 58.7%, Cancer Diagnosis leading applications at 42.8%, strong NGS technology adoption, and the U.S. large and growing oncology diagnostics and consumer genomics base.
The United States genetic testing market grows at a 10.87% CAGR during 2026-2034, reaching USD 15.33 Billion by 2034. This growth reflects sustained NGS cost deflation, expanding oncology companion diagnostic mandates, and continued DTC platform expansion despite regulatory and reimbursement uncertainty.
Molecular Testing leads at 58.7%, capturing NGS-powered cancer profiling, rare disease diagnosis, and pharmacogenomics demand. This segment grows at an above-market CAGR of approximately 12.4% through 2034 through premium panel adoption and whole-genome sequencing deployment across hospital and reference laboratory settings.
Cancer Diagnosis leads at 42.8% through BRCA testing, tumor mutational burden analysis, and FDA-cleared companion diagnostics linked to targeted oncology therapies. Cancer Diagnosis grows fastest at approximately 13.1% CAGR through 2034 as liquid biopsy adoption accelerates and oncology panel ordering expands.
The South leads at 36.8% through Texas, Florida, and Georgia's concentrated healthcare infrastructure and high chronic disease prevalence. The West at 25.7% follows on California's biotech and DTC genomics ecosystem, alongside strong secondary contribution from the Northeast at 19.6%.
Leading companies include Quest Diagnostics Incorporated, Labcorp., Myriad Genetics, Inc., Illumina, Inc., Thermo Fisher Scientific Inc., and others.
Three priority investment opportunities stand out: AI-assisted genomic interpretation platform development, liquid biopsy cancer screening infrastructure, and DTC-to-clinical pipeline expansion all capturing the highest-growth, highest per-unit-value segments within the market through 2034.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade