United States Industrial Enzymes Market Size, Share, Trends and Forecast by Product, Source, Application, and Region, 2026-2034
United States Industrial Enzymes Market Size, Share, Trends & Forecast (2026-2034)
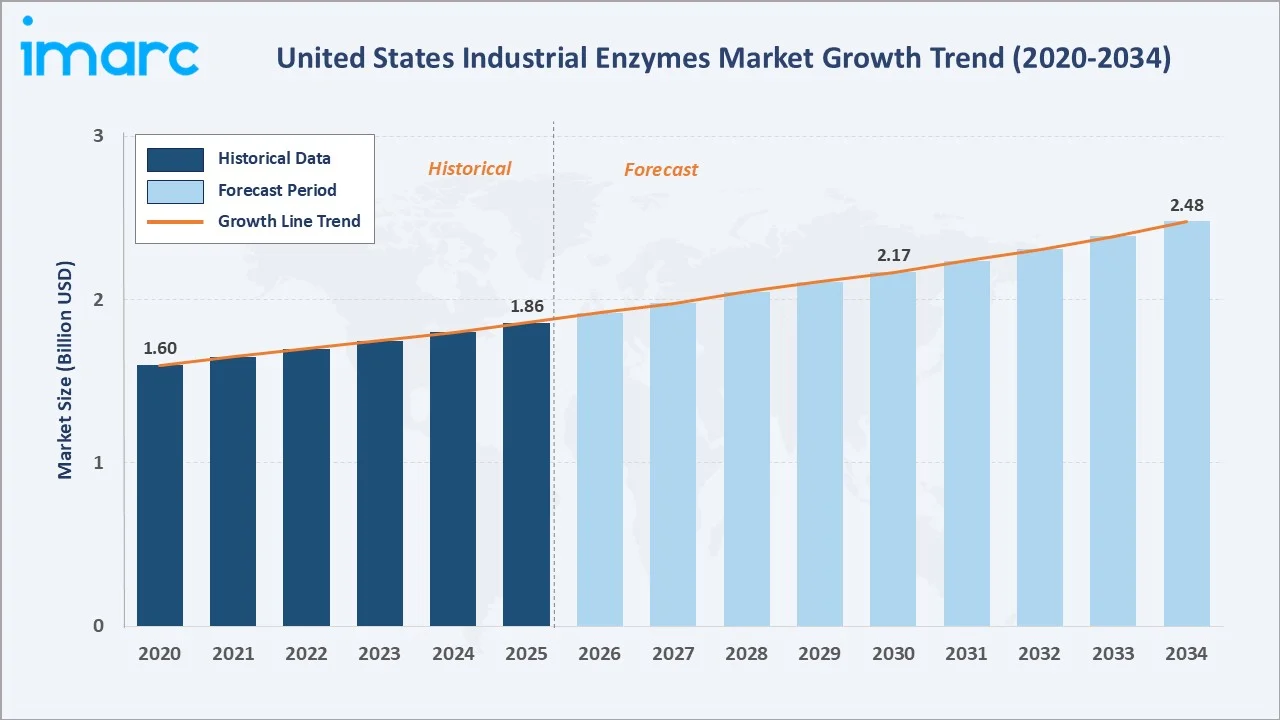
The United States industrial enzymes market grew from USD 1.86 Billion in 2025 to USD 1.92 Billion in 2026 and is projected to reach USD 2.48 Billion by 2034, growing at a CAGR of 3.13% during 2026-2034. The market is driven by rising demand from food and beverage processing, expanding biofuel production mandates, and increasing adoption of enzyme-based solutions across detergent, animal feed, and textile applications.
Carbohydrates dominate at 32.5%. Microorganisms lead the source segment at 72.5%. The West leads regionally at 27.5%. Growing interest in sustainable industrial processes and green chemistry is creating additional momentum across the US enzyme market.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 1.86 Billion |
|
Market Size (2026) |
USD 1.92 Billion |
|
Forecast Market Size (2034) |
USD 2.48 Billion |
|
CAGR (2026-2034) |
3.13% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Product |
Carbohydrates (32.5%, 2025) |
|
Dominant Source |
Microorganisms (72.5%, 2025) |
|
Leading Region |
West (27.5%, 2025) |
The US industrial enzymes market increased from USD 1.60 Billion in 2020 to USD 1.86 Billion in 2025 and is estimated to reach USD 1.92 Billion in 2026. The market is further projected to reach USD 2.17 Billion by 2030 and USD 2.48 Billion by 2034. The US industrial enzymes market is characterized by high R&D intensity, consolidated supplier base, and broad multi-sector enzyme demand.
To get more information on this market, Request Sample
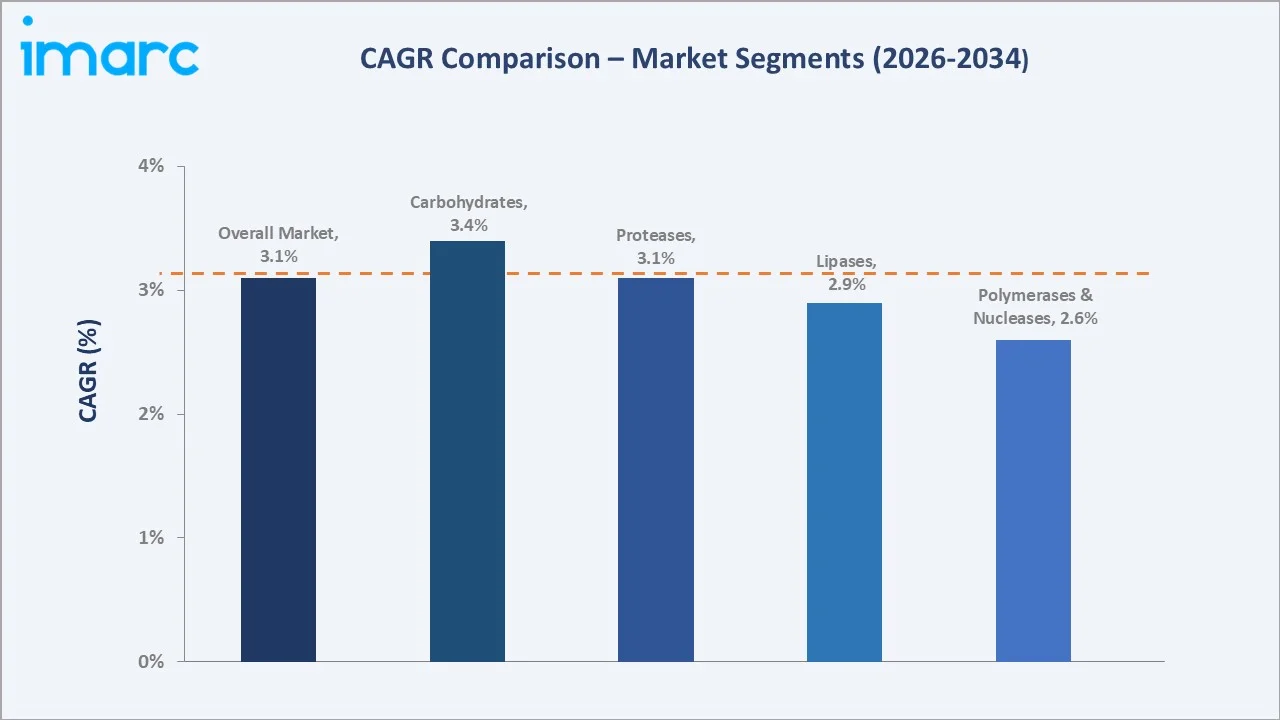
Carbohydrates grow at ~3.4% CAGR through expanding corn processing and bioethanol demand. Microorganism-sourced enzymes drive ~3.3% CAGR through scalable fermentation and lower cost-per-unit advantages over plant and animal-derived alternatives.
Executive Summary
The United States industrial enzymes market expanded from USD 1.86 Billion in 2025 to an estimated USD 1.92 Billion in 2026, driven by robust food and beverage processing activity, expanding bioenergy programs, and growing adoption across animal feed and detergent sectors. Microorganisms production dominates supply at 72.5%, reflecting the cost and scalability advantages of fermentation-based technologies.
Carbohydrates command 32.5% market share, reflecting their broad applicability in starch processing, baking, brewing, and biofuel ethanol production. The West leads regionally at 27.5% due to its advanced biotechnology infrastructure, biofuel mandates, and significant food and beverage processing base.
Key Market Insights
|
Insight |
Data |
|
Dominant Product |
Carbohydrates - 32.5% share (2025) |
|
Dominant Source |
Microorganisms - 72.5% market share (2025) |
|
Leading Region |
West - 27.5% share (2025) |
|
Market Opportunity |
Biofuel enzyme applications; food-grade specialty enzymes; animal feed phytases; detergent enzyme innovation; green chemistry biorefinery integration |
Key Analytical Observations Supporting the Above Data:
- Carbohydrates at 32.5%: Carbohydrates dominate due to extensive use in starch hydrolysis for sweetener production, ethanol fermentation, baking improvement, and brewing applications. US corn wet-milling and bioenergy sectors sustain high-volume carbohydrase consumption. Growing demand for high-fructose corn syrup and bioethanol reinforces this segment leadership.
- Microorganisms at 72.5%: Microbial fermentation yields higher enzyme volumes at lower cost compared to plant and animal sources. Precision strain development and recombinant DNA technologies enable high-activity enzyme production. Microbial enzymes offer superior thermal and pH stability, making them preferred for industrial processing conditions.
- West at 27.5%: The West leads through California's advanced food technology cluster, significant biofuel production capacity, and high concentration of enzyme R&D centers. Washington and Oregon's growing bioenergy and specialty food sectors further reinforce the region's enzyme consumption leadership.
United States Industrial Enzymes Market Overview
The United States industrial enzymes market sits at the intersection of biotechnology, sustainable manufacturing, and multi-sector industrial processing. The commercial structure is shaped by concentrated enzyme supplier relationships, strong regulatory frameworks for GRAS-classified industrial enzymes, and expanding end-use applications across food, energy, and specialty sectors.
The market ecosystem connects fermentation technology companies, specialty chemical distributors, and a diverse range of industrial end-users spanning food processing, biofuels, detergents, animal nutrition, textiles, and pharmaceuticals. Enzyme engineering advances continue to broaden the performance envelope and commercial viability of industrial enzyme applications.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
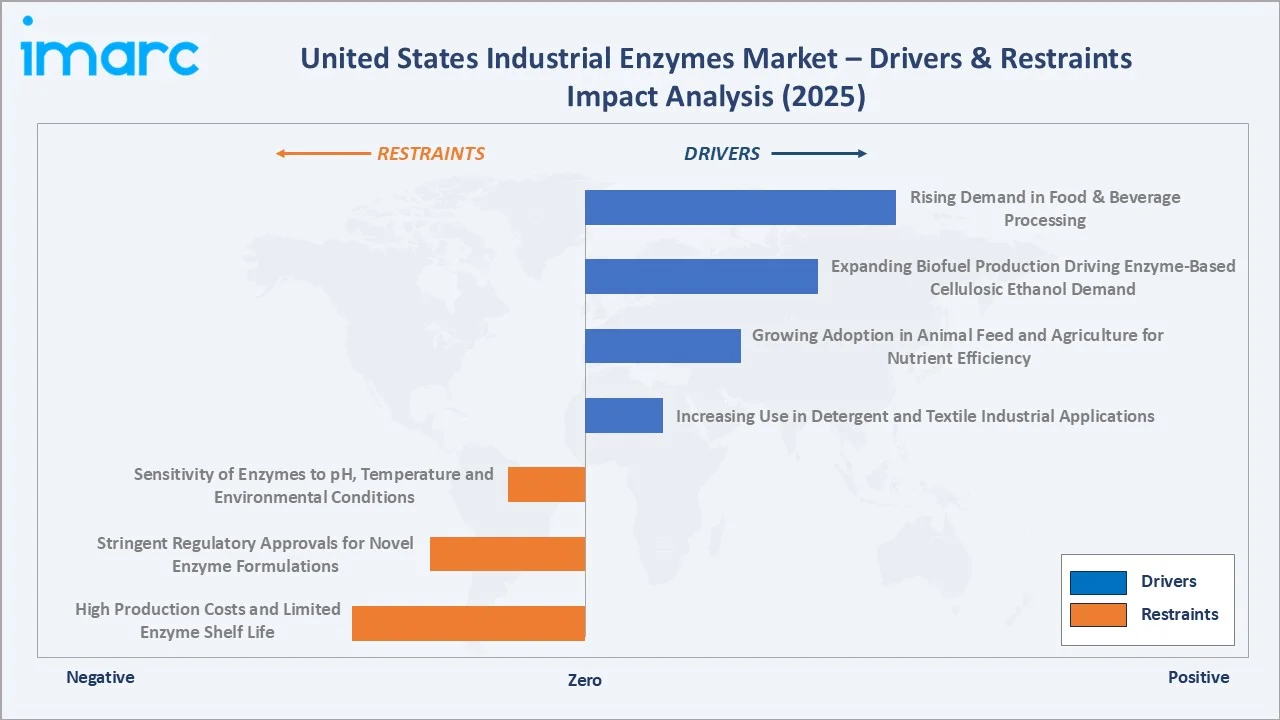
- Rising Demand in Food & Beverage Processing: The food and beverage sector is the largest end-use segment for industrial enzymes, driving consistent demand for carbohydrates, proteases, and lipases. The US food processing industry's scale creates substantial and stable enzyme consumption volumes. Growing demand for clean-label, naturally processed foods is expanding enzyme applications in bread improvement, dairy processing, juice clarification, and beverage production. Continuous industry investment in operational efficiency further supports enzymatic processing adoption.
- Expanding Biofuel Production Driving Enzyme-Based Cellulosic Ethanol Demand: The Renewable Fuel Standard and state-level biofuel mandates generate sustained demand for cellulosic and starch-based ethanol enzymes. Advances in cellulase and hemicellulase efficiency are improving biofuel conversion economics. The US biofuel sector consumed significant enzyme volumes for corn-to-ethanol processing in 2025. Government incentives for second-generation biofuels are creating new cellulase market opportunities beyond conventional starch processing.
- Growing Adoption in Animal Feed and Agriculture for Nutrient Efficiency: Phytase and protease enzymes are widely adopted in US poultry and swine feed to improve phosphorus utilization and reduce feed costs. Growing livestock production volumes and rising demand for cost-efficient feed formulations sustain enzyme adoption. Enzyme supplementation improves feed conversion ratios, reducing production costs. Increasing regulatory pressure to reduce phosphorus discharge from livestock operations strengthens phytase adoption across the US animal agriculture sector.
- Increasing Use in Detergent and Textile Industrial Applications: Protease, amylase, and lipase enzymes are essential active components in commercial laundry and dishwashing detergent formulations. The US detergent sector's high production volumes generate substantial enzyme demand. Textile processing enzymes, including cellulases and laccases, are being adopted to improve fabric quality and reduce chemical usage. Growing consumer preference for biodegradable, environmentally responsible cleaning products is expanding enzyme-based formulation adoption.
Market Restraints
- High Production Costs and Limited Enzyme Shelf Life: Industrial enzyme production through fermentation requires sophisticated bioreactor systems, downstream processing, and controlled storage conditions. High capital and operational costs constrain adoption among smaller industrial processors. Enzyme shelf life limitations necessitate cold-chain logistics and careful inventory management, adding supply chain complexity and cost. Price sensitivity in commodity applications limits premium enzyme product penetration and constrains margins for suppliers.
- Stringent Regulatory Approvals for Novel Enzyme Formulations: FDA GRAS determinations and EPA biotechnology notifications require extensive safety documentation for novel enzyme products. The regulatory approval timeline for new microbial strains or genetically modified enzyme sources can span multiple years, delaying commercialization. Compliance requirements increase development costs for enzyme manufacturers. Evolving regulations around genetically modified organisms affect certain recombinant enzyme approvals and market access pathways.
- Sensitivity of Enzymes to pH, Temperature and Environmental Conditions: Industrial enzymes exhibit narrow optimal activity windows requiring precise process control. Exposure to suboptimal pH, temperature extremes, or inhibitory compounds rapidly reduces enzymatic activity and effectiveness. Process variability in customer operations can limit enzyme performance consistency. Developing robust, thermostable enzyme variants adds significant R&D investment requirements and may not be commercially viable for all application segments.
Market Opportunities
- Development of Thermostable and Extreme-Condition Enzyme Variants: Research into extremophile-derived and engineered enzymes with enhanced thermal stability creates commercial opportunities in high-temperature industrial processes. Thermostable enzyme variants reduce cooling requirements and improve process integration flexibility. Directed evolution and computational protein engineering are accelerating thermostable enzyme development. Applications in starch liquefaction, biofuel processing, and industrial cleaning benefit substantially from elevated-temperature enzyme stability.
- Expanding Wastewater Treatment and Environmental Remediation Applications: Industrial enzyme adoption in wastewater treatment for organic matter degradation, biofilm control, and nutrient removal is an emerging growth area. Environmental regulations driving industrial facilities to improve effluent quality support enzyme-based treatment solution adoption. Enzyme cocktails for complex organic compound degradation represent commercially differentiated specialty offerings. Growing corporate sustainability commitments are increasing investment in biotechnology-based environmental solutions.
Market Challenges
- Competition from Chemical Substitutes and Alternative Process Technologies: Chemical catalysts and conventional processing alternatives remain entrenched in many industrial applications where enzyme adoption is economically marginal. Price pressures from chemical substitutes constrain enzyme market penetration in cost-sensitive segments. Demonstrating total-cost-of-ownership advantages over chemical alternatives requires customer education and technical partnership investment. Incumbent process technology changeover costs create adoption inertia that slows enzyme market penetration timelines.
- Supply Chain Concentration and Raw Material Availability Risks: The US industrial enzyme market relies on a limited number of large-scale fermentation producers for the majority of enzyme supply. Supply chain disruptions affecting primary enzyme manufacturers create significant availability risks across end-use sectors. Raw material cost volatility for fermentation substrates including corn and grain-based feedstocks creates margin pressure. Geographic concentration of enzyme manufacturing facilities amplifies regional supply disruption risk exposure.
Emerging Market Trends
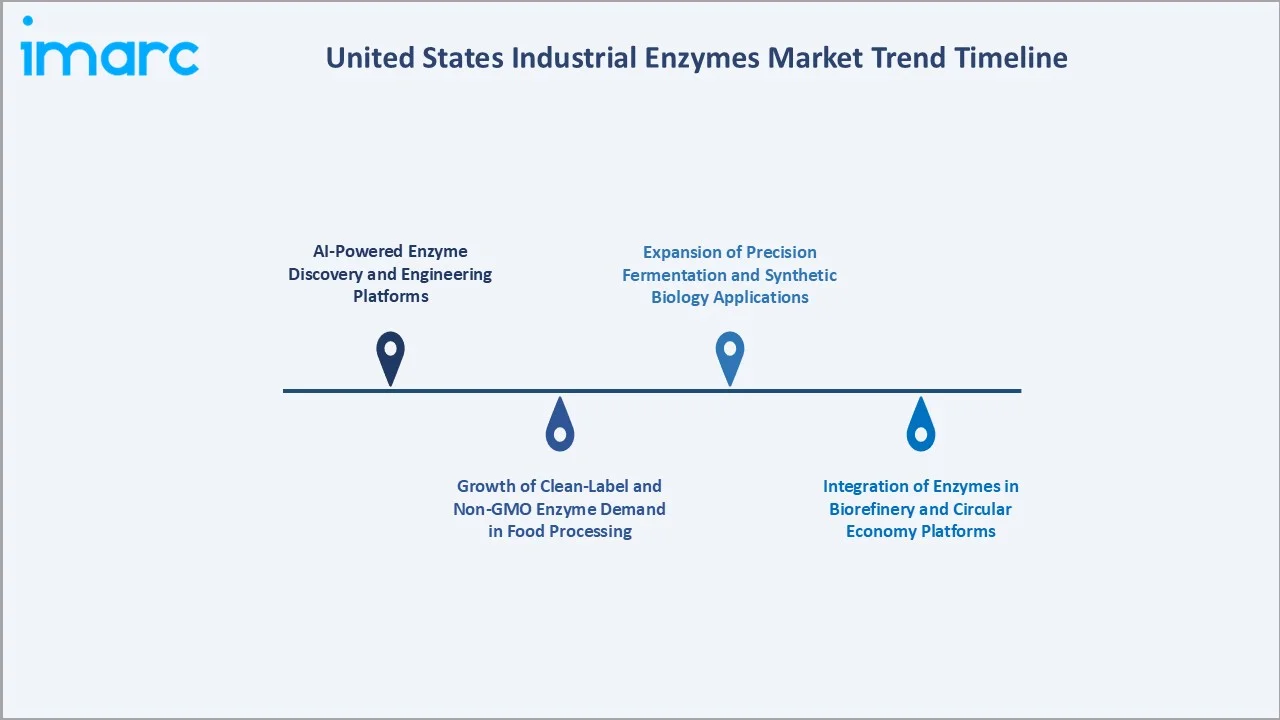
1. AI-Powered Enzyme Discovery and Engineering Platforms
Computational protein engineering and AI-driven enzyme optimization are compressing development timelines from years to months. Novonesis launched its AI-Enzyme Designer platform to accelerate enzyme discovery for industrial applications. Machine learning models predict enzyme performance across novel substrates and conditions, enabling more targeted development.
2. Expansion of Precision Fermentation and Synthetic Biology Applications
Precision fermentation enables production of complex, high-value enzyme variants previously not commercially viable. Synthetic biology tools are enabling the programming of microbial hosts for multi-enzyme production. US biotech companies are investing in cell-free enzyme systems and chassis organisms for specialty enzyme manufacturing.
3. Growth of Clean-Label and Non-GMO Enzyme Demand in Food Processing
Consumer demand for natural, minimally processed foods is driving adoption of plant-derived and non-recombinant enzyme formulations. Food manufacturers are reformulating products to replace chemical processing aids with enzyme-based alternatives. USDA organic and non-GMO certification requirements are shaping enzyme sourcing strategies.
4. Integration of Enzymes in Biorefinery and Circular Economy Platforms
Enzyme cascades for lignocellulosic biomass conversion are central to emerging biorefinery business models. US cellulosic ethanol and bio-based chemical companies are integrating multi-enzyme systems for complete biomass valorization. Enzyme-enabled waste stream upcycling aligns with corporate sustainability and circular economy commitments.
Industry Value Chain Analysis
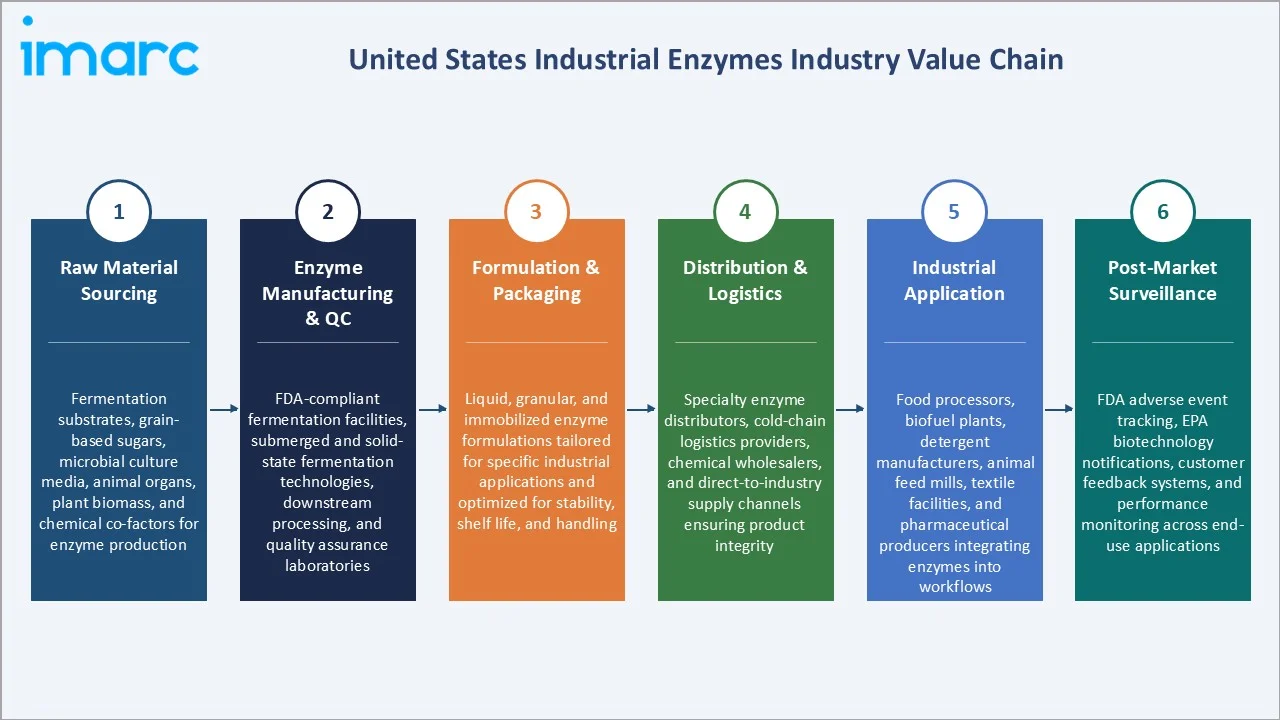
The United States industrial enzymes value chain spans multiple highly specialized stages, from raw material procurement through post-market application monitoring, with quality and regulatory compliance requirements enforced at each link. The concentrated manufacturing segment and fragmented application base define the commercial structure of the market.
|
Stage |
Key Participants |
|
Raw Material Sourcing |
Fermentation substrates, grain-based sugars, microbial culture media, animal organs, plant biomass, and chemical co-factors for enzyme production. |
|
Enzyme Manufacturing & QC |
FDA-compliant fermentation facilities, submerged and solid-state fermentation technologies, downstream processing, and quality assurance laboratories. |
|
Formulation & Packaging |
Liquid, granular, and immobilized enzyme formulations tailored for specific industrial applications and optimized for stability, shelf life, and handling. |
|
Distribution & Logistics |
Specialty enzyme distributors, cold-chain logistics providers, chemical wholesalers, and direct-to-industry supply channels ensuring product integrity. |
|
Industrial Application |
Food processors, biofuel plants, detergent manufacturers, animal feed mills, textile facilities, and pharmaceutical producers integrating enzymes into workflows. |
|
Post-Market Surveillance |
FDA adverse event tracking, EPA biotechnology notifications, customer feedback systems, and performance monitoring across end-use applications. |
Fermentation manufacturing carries the highest technical and capital intensity. FDA GRAS determinations and EPA biotechnology notifications govern commercial enzyme launches. Distribution through specialty chemical and biotechnology distributors enables market access for smaller enzyme producers without direct sales infrastructure in the US industrial enzymes market.
Technology Landscape in the United States Industrial Enzymes Industry
Fermentation and Bioprocess Technology
Submerged liquid fermentation and solid-state fermentation remain the primary enzyme production platforms, with continuous improvements in titer, yield, and downstream processing efficiency. Advanced fed-batch and continuous fermentation processes are improving production economics. In January 2025, Novonesis completed the acquisition of DSM-Firmenich's enzyme alliance stake, reinforcing fermentation technology leadership.
Enzyme Engineering and Directed Evolution
Directed evolution, rational design, and computational protein engineering are enabling the development of enzyme variants with improved activity, thermostability, and substrate specificity. High-throughput screening platforms enable rapid enzyme variant evaluation. AI-assisted enzyme engineering is reducing development costs and timelines for industrial enzyme products.
Immobilized Enzyme and Continuous Processing Technology
Enzyme immobilization technologies enable reuse, continuous processing integration, and improved operational economics for high-value applications. Carrier-bound, cross-linked, and encapsulated enzyme formats are expanding commercial viability in fine chemical and pharmaceutical applications. Immobilized enzyme systems are particularly relevant for enzymatic biodiesel and specialty sugar production in the US market.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Product |
Carbohydrates |
32.5% |
2025 |
|
Source |
Microorganisms |
72.5% |
2025 |
|
Application |
🔒 |
🔒 |
2025 |
|
Region |
West |
27.5% |
2025 |

By Product
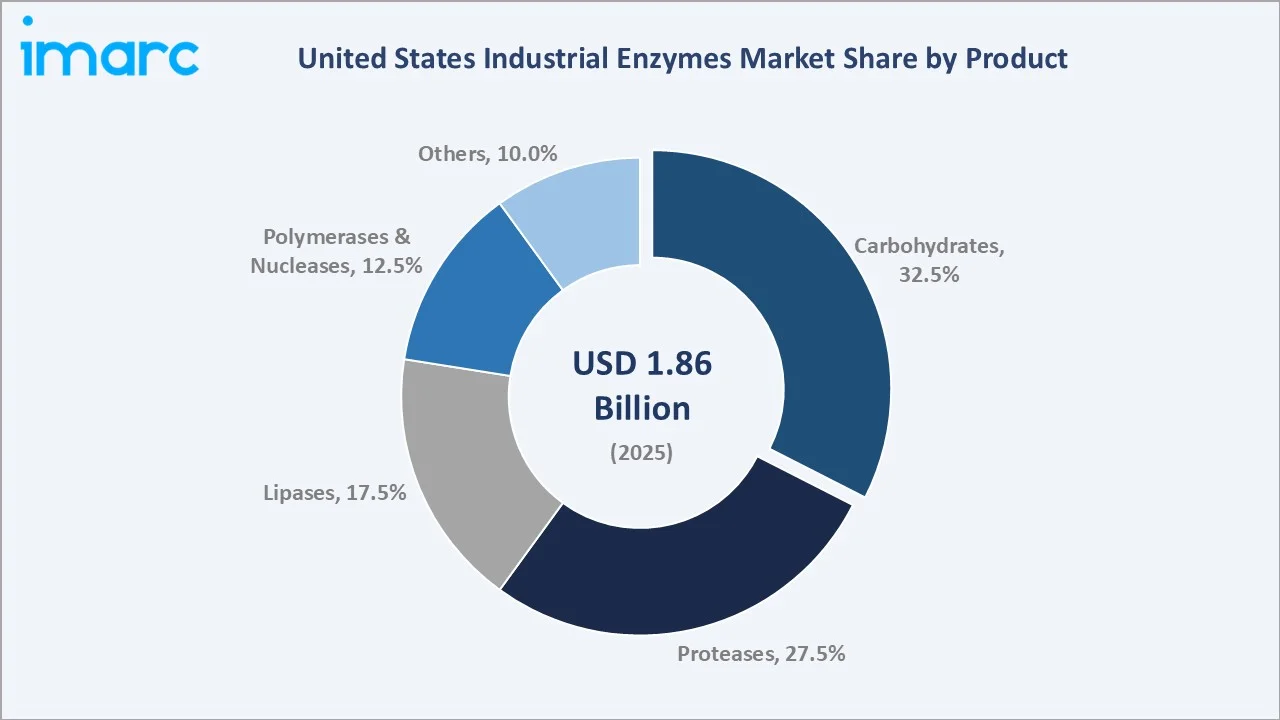
Carbohydrates lead at 32.5% (2025). This segment encompasses amylases, cellulases, hemicellulases, and pectinases used extensively in starch processing, brewing, baking, biofuel ethanol production, and fruit juice clarification across the United States.
To access detailed market analysis, Request Sample
Proteases at 27.5% are widely deployed in detergent formulations, meat tenderization, leather processing, and pharmaceutical applications. Lipases at 17.5% serve the food, pharmaceutical, and biodiesel sectors. Polymerases and nucleases at 12.5% support diagnostic, pharmaceutical, and molecular biology applications. Others at 10.0% include oxidoreductases and specialty enzymes for niche industrial uses.
By Source
Microorganisms lead at 72.5% (2025). Microbial enzymes produced via bacterial, fungal, and yeast fermentation offer superior production scalability, consistent purity, and high specific activity compared to plant or animal alternatives, making them the dominant commercial source for US industrial enzyme supply.
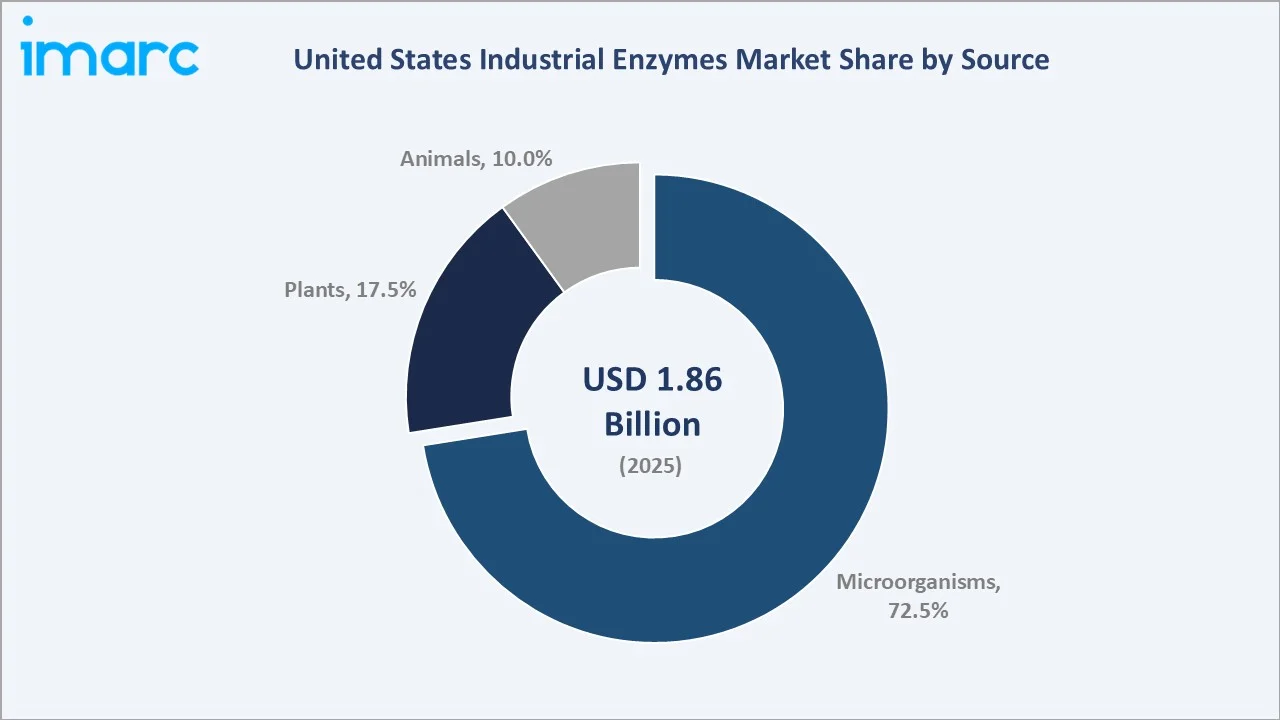
Plant-sourced enzymes at 17.5% include papain, bromelain, and malt amylases used in food processing and brewing. Animal-sourced enzymes at 10.0% include rennet, pancreatin, and lipases for dairy, pharmaceutical, and specialty applications where specific biological source requirements are critical.
Regional Market Insights
|
Region |
Share (2025) |
Key US Industrial Enzymes Market Drivers & Characteristics |
|
West |
27.5% |
Leading US industrial enzyme region driven by advanced biotech infrastructure in California and Washington, high biofuel production capacity, and significant food and beverage processing activity. |
|
South |
26.5% |
Strong enzyme demand from bioenergy crop processing, poultry and livestock feed applications, and growing specialty food manufacturing facilities across Texas and surrounding states. |
|
Midwest |
25.5% |
Core agricultural processing hub generating substantial enzyme demand from corn wet-milling, soy processing, ethanol production, and large-scale animal feed manufacturing operations. |
|
Northeast |
20.5% |
Research-intensive region with high concentration of pharmaceutical, nutraceutical, and specialty enzyme applications supported by academic biotechnology centers and contract manufacturers. |
The West's 27.5% leadership reflects California's large food technology cluster, significant biofuel capacity in the Pacific Northwest, and high concentration of enzyme R&D and biotech manufacturing. Biofuel and food sector enzyme demand converge in the region, supporting diverse product portfolio adoption across carbohydrase and protease categories.
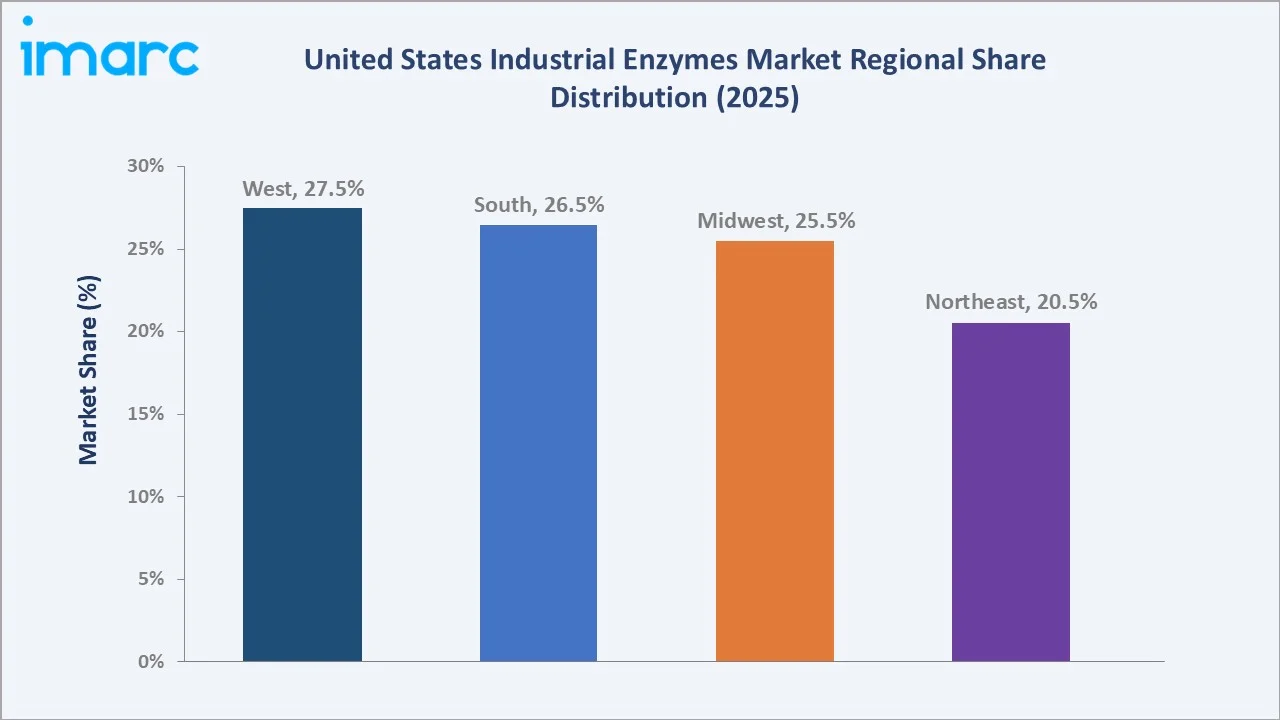
The South's 26.5% reflects strong agricultural enzyme demand from poultry and livestock feed processing in Texas, North Carolina, and Georgia, complemented by growing bioenergy enzyme consumption. The Midwest's 25.5% is driven by corn wet-milling, ethanol production, and soy processing - creating dense carbohydrase and protease demand across the agricultural heartland.
Competitive Landscape
The United States industrial enzymes market features a moderately concentrated competitive structure, with a small number of multinational enzyme specialists commanding significant market positions alongside specialist mid-tier players. Competition centers on enzyme performance, application expertise, regulatory compliance, and supply chain reliability.
|
Company |
Key Products |
Market Position |
Core Strength |
|
International Flavors & Fragrances Inc. |
Food enzymes, specialty biocatalysts, industrial biotech |
Strong Challenger |
International Flavors & Fragrances offers a comprehensive enzyme range for food, feed, and industrial applications with strong US manufacturing infrastructure. |
|
BASF |
Animal feed enzymes, technical enzymes, specialties |
Strong Challenger |
BASF delivers targeted enzyme solutions for animal nutrition and specialty industrial applications, leveraging its chemical manufacturing expertise and established US distribution network. |
|
Amano Enzyme Inc. |
Proteases, lipases, carbohydrates, specialty enzymes |
Specialist |
Amano Enzyme Inc. supplies high-performance specialty enzymes for food and pharmaceutical applications, drawing on decades of fermentation expertise and customized enzyme engineering capabilities. |
|
Advanced Enzyme Technologies |
Human health, animal health, industrial enzymes |
Niche Player |
Advanced Enzyme Technologies provides targeted enzyme solutions across human health, animal nutrition, and industrial segments, with growing US market penetration through distribution partnerships. |
Key players include International Flavors & Fragrances Inc., BASF, Amano Enzyme Inc., Advanced Enzyme Technologies, and others.
Key Company Profiles
International Flavors & Fragrances Inc.
International Flavors & Fragrances Inc. is a major US industrial enzyme provider with a comprehensive portfolio spanning food processing, animal nutrition, industrial biotech, and specialty fermentation-derived enzyme applications.
- Key Products: Specialty food enzymes, brewing enzymes, dairy processing enzymes, baking enzymes, industrial biotech enzymes, and fermentation-derived specialty biocatalysts, among others.
- Strategic Focus: Leveraging combined IFF and DuPont N&B application expertise to develop integrated ingredient and enzyme solutions for food manufacturers, extracting commercial synergies from combined biotechnology and flavors capabilities. IFF is investing in application centers to co-develop customized enzyme solutions with US food, feed, and industrial customers. The company is targeting clean-label and specialty fermented ingredient enzyme solutions as high-value growth vectors.
BASF
BASF is a leading provider of animal nutrition enzymes and specialty technical enzymes in the United States, leveraging its global chemical manufacturing network and established US distribution infrastructure to serve the animal feed, biofuels, and specialty industrial enzyme segments.
- Key Products: Natuphos phytase, Natugrain feed enzyme blend, specialty technical enzymes, and industrial bioprocess enzyme formulations for animal nutrition and selected industrial applications, among others.
- Strategic Focus: Strengthening animal nutrition enzyme leadership through performance-differentiated phytase and multi-enzyme blend products, expanding biofuels enzyme offerings aligned with US Renewable Fuel Standard demand, and deepening technical service support for US industrial enzyme customers. BASF is pursuing targeted portfolio expansion in specialty and high-value technical enzyme categories for US industrial and pharmaceutical customers. The company is investing in sustainable enzyme manufacturing processes aligned with its corporate carbon neutrality objectives.
Market Concentration Analysis
The US industrial enzymes market is highly concentrated at the fermentation manufacturing level, with key players commanding an estimated 40-45% share of US industrial enzyme supply by value. The application-specific segments show greater fragmentation, with specialist players holding strong niche positions in baking, feed, and pharmaceutical enzyme categories.
Market concentration is evolving through two dynamics: leading manufacturers consolidating through mergers and expanding application portfolios, while the specialty enzyme segment is seeing new entrant activity from synthetic biology and precision fermentation startups targeting performance-differentiated enzyme products for high-value applications.
Investment & Growth Opportunities
Highest Growth Segments
Cellulases for second-generation biofuels (~5-6% CAGR), specialty food processing enzymes (~3.8% CAGR), phytase for animal feed (~3.5% CAGR), wastewater treatment enzymes (~4% CAGR), and thermostable carbohydrates for high-temperature processing (~4.2% CAGR) represent the highest-growth investment opportunities in the US industrial enzymes market through 2034.
Emerging Investment Opportunities
Precision fermentation enzyme platforms represent the most commercially dynamic emerging investment area, enabling production of high-performance enzyme variants not accessible through conventional fermentation. Enzyme cascade development for biorefinery biomass valorization represents a structurally growing investment opportunity aligned with US bioenergy policy.
Investment Themes
- Thermostable and engineered enzyme development: Enzyme engineering platforms targeting high-temperature and extreme-condition variants unlock new application segments and premium pricing, with strong IP protection opportunities and sustainable competitive moats.
- US biofuel and biorefinery enzyme supply chain investment: Cellulosic ethanol capacity expansion under RFS mandates creates growing cellulase and hemicellulase demand, requiring supply chain investment and local manufacturing scale-up to ensure availability and cost competitiveness.
Future Market Outlook (2026-2034)
The United States industrial enzymes market is projected to grow from USD 1.86 Billion in 2025 to USD 1.92 Billion in 2026, reaching USD 2.48 Billion by 2034, at a CAGR of 3.13% during 2026-2034. The USD 2.17 Billion milestone in 2030 reflects structural acceleration as biorefinery enzyme demand, thermostable enzyme adoption, and precision fermentation commercialization converge.
Three structural forces define market growth through 2034: sustained food and beverage processing enzyme demand providing a stable commercial base; expanding biofuel and biorefinery enzyme consumption driven by renewable energy policy; and the premium enzyme category growth enabled by AI-assisted enzyme engineering and precision fermentation technology deployment.
Research Methodology
Primary Research
Primary research comprised structured interviews with US industrial enzyme market participants including R&D directors, application scientists, procurement managers at food processors, biofuel producers, and detergent manufacturers, and business development executives at enzyme suppliers across Northeast, South, West, and Midwest regions.
Secondary Research
Secondary research encompassed FDA GRAS notification databases, EPA biotech notification records, USDA biofuel production statistics, company annual reports and investor presentations, peer-reviewed enzyme research literature, and trade association data. Over 50 secondary sources were reviewed to support market sizing and forecasting.
Forecasting Models
Revenue forecasts were developed using a bottom-up demand aggregation model: US enzyme consumption volumes by end-use sector multiplied by average selling prices across product categories and source segments. Growth adjustments applied for biofuel policy evolution, food sector enzyme penetration trends, and technology-driven performance improvement effects.
United States Industrial Enzymes Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical and Forecast Trends, Industry Catalysts and Challenges, Segment-Wise Historical and Predictive Market Assessment:
|
| Products Covered |
|
| Sources Covered | Plants, Animals, Microorganisms |
| Applications Covered | Food and Beverages, Detergents, Animal Feed, Biofuels, Textiles, Pulp and Paper, Nutraceuticals, Personal Care and Cosmetics, Wastewater Treatment, Others |
| Regions Covered | Northeast, Midwest, South, West |
| Companies Covered | International Flavors & Fragrances Inc., BASF, Amano Enzyme Inc., Advanced Enzyme Technologies, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the United States industrial enzymes market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the United States industrial enzymes market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the United States industrial enzymes industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the United States Industrial Enzymes Market Report
The United States industrial enzymes market size reached USD 1.92 Billion in 2026, driven by strong demand from food processing, biofuel production, animal feed, and detergent applications across diverse industrial sectors.
The United States industrial enzymes market is projected to grow at a CAGR of 3.13% during 2026-2034, reaching USD 2.48 Billion by 2034, supported by expanding biofuel mandates, growing food enzyme penetration, and emerging biorefinery and wastewater treatment applications.
Carbohydrates lead at 32.5% through extensive use in starch hydrolysis, bioethanol production, baking improvement, and brewing applications. High US corn processing and biofuel production volumes sustain consistent carbohydrase demand across the country.
Microorganisms lead at 72.5% through scalable fermentation production, superior enzyme activity profiles, and lower production costs compared to plant and animal-derived alternatives. Advances in microbial engineering continue to expand the performance envelope of fermentation-derived industrial enzymes.
The West leads at 27.5% through California's food technology cluster, significant Pacific Northwest biofuel capacity, and high concentration of enzyme R&D and biotech manufacturing facilities driving diverse enzyme product adoption.
Leading companies include International Flavors & Fragrances Inc., BASF, Amano Enzyme Inc., Advanced Enzyme Technologies, and others.
The United States industrial enzymes market is projected to reach approximately USD 2.17 Billion by 2030, with biofuel enzymes and specialty food processing enzymes representing the fastest-growing segments driven by renewable energy policy and clean-label food trends. The US industrial enzymes market is poised for steady expansion as bioenergy mandates and food sector enzyme adoption strengthen through 2034.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade