
United States Industrial Gases Market Size, Share, Trends and Forecast by Type, Application, Supply Mode, and Region, 2026-2034
United States Industrial Gases Market Size, Share, Trends & Forecast (2026-2034)
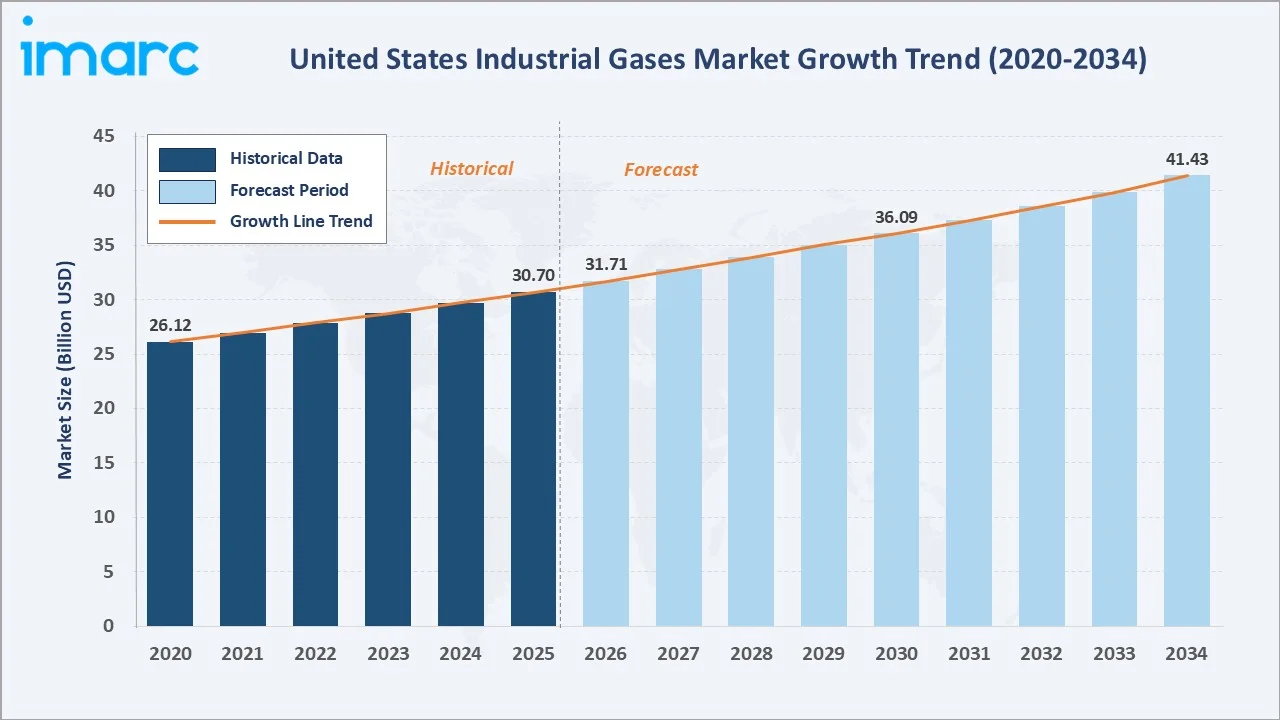
The US industrial gases market grew from USD 30.70 Billion in 2025 to USD 31.71 Billion in 2026 and is projected to reach USD 41.43 Billion by 2034, growing at a CAGR of 3.28% during 2026-2034. The market is driven by rising industrial demand, technological advances in gas production and distribution, healthcare sector growth, and energy transition toward clean hydrogen.
Nitrogen leads at 28.6% by type. Manufacturing dominates at 27.5% by application. The South region commands 36.5% of the national market share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 30.70 Billion |
|
Market Size (2026) |
USD 31.71 Billion |
|
Forecast Market Size (2034) |
USD 41.43 Billion |
|
CAGR (2026-2034) |
3.28% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Type |
Nitrogen (28.6%, 2025) |
|
Dominant Application |
Manufacturing (27.5%, 2025) |
|
Leading Region |
South (36.5%, 2025) |
The United States industrial gases market size increased from USD 26.12 Billion in 2020 to USD 30.70 Billion in 2025 and is estimated to reach USD 31.71 Billion in 2026. The market is further expected to grow to USD 36.09 Billion by 2030 and USD 41.43 Billion by 2034.
To get more information on this market, Request Sample
The United States industrial gases market is commercially significant as a foundational input industry that underpins manufacturing, healthcare, energy, and chemical processing. Its growth is structurally tied to industrial output, clean energy investment, and demographic-driven healthcare expansion.
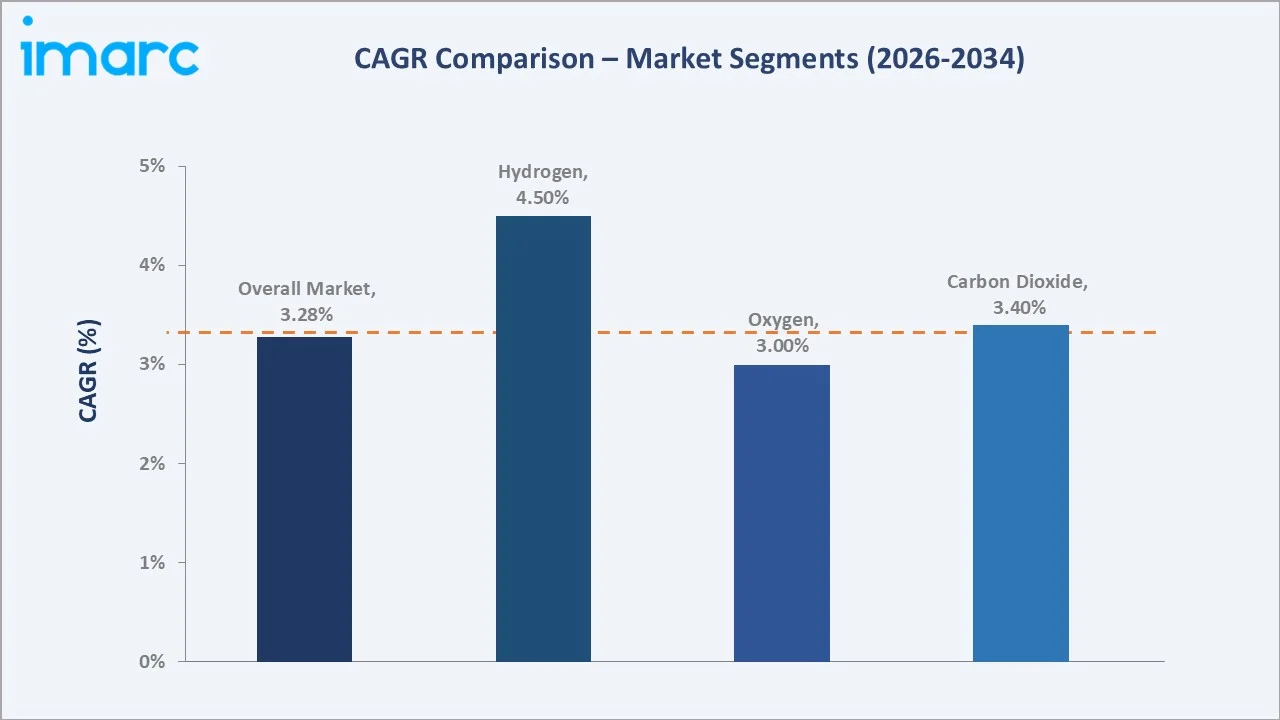
Hydrogen is the fastest-growing type at approximately 4.5% CAGR, driven by clean energy mandates and DOE investment. Nitrogen maintains dominant volume share through food, electronics, and oil and gas applications across all forecast years.
Executive Summary
The United States industrial gases market expanded from USD 30.70 Billion in 2025 to an estimated USD 31.71 Billion in 2026, driven by stable cross-sector industrial demand, rapid healthcare adoption, and accelerating clean energy transitions. The market is projected to reach USD 41.43 Billion by 2034.
Nitrogen leads at 28.6% by type given its extensive use in ammonia production, food preservation, electronics, and oil and gas. Manufacturing at 27.5% reflects the sector's role as the primary industrial gas consumer across metal fabrication, chemicals, and electronics manufacturing.
The South region leads at 36.5%, anchored by Texas's petrochemical complex, Louisiana's chemical manufacturing, and Florida's healthcare and aerospace sectors. The Midwest at 25.5% reflects its dense manufacturing and agricultural industrial base.
Key Market Insights
|
Insight |
Data |
|
Dominant Type |
Nitrogen – 28.6% share (2025) |
|
Dominant Application |
Manufacturing – 27.5% share (2025) |
|
Leading Region |
South – 36.5% share (2025) |
|
Market Opportunity |
Clean hydrogen production, carbon capture & storage, semiconductor specialty gases, medical gas expansion, green energy applications |
Key Analytical Observations Supporting the Above Data:
- Nitrogen at 28.6%: Nitrogen dominates due to its critical role in ammonia production for fertilizers, food processing inert atmospheres, electronics manufacturing, and oil and gas pipeline purging. The USGS reports the US produced 14 million metric tons of ammonia in 2023, underlining nitrogen's central industrial importance across diverse end-use markets.
- Manufacturing at 27.5%: Manufacturing leads application demand as oxygen, nitrogen, and argon are essential for metal fabrication, chemical synthesis, and electronics production. The sector's 11.4 million jobs and growing decarbonization investment sustain industrial gas demand, with the DOE's industrial decarbonization push further reinforcing gases' role in efficiency and carbon reduction.
- South at 36.5%: The South leads regionally due to Texas's massive petrochemical and refining complex, which is the single largest regional industrial gas consumer in the United States. Louisiana's chemical manufacturing, Florida's healthcare growth, and the region's expanding aerospace and energy sectors further anchor the South's commanding market position.
United States Industrial Gases Market Overview
The United States industrial gases market operates at the intersection of energy, manufacturing, healthcare, and clean technology. It is a foundational industrial input market that supplies atmospheric and specialty gases to virtually every sector of the American economy, from steel mills and semiconductor fabs to hospitals and hydrogen fuel cell projects.
The market ecosystem integrates air separation units, steam reformers, electrolyzer operators, cylinder manufacturers, bulk tanker logistics networks, and pipeline distribution infrastructure. Macroeconomic factors supporting market growth include industrial output growth, clean energy policy investment, expanding healthcare infrastructure, and semiconductor manufacturing reshoring initiatives.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
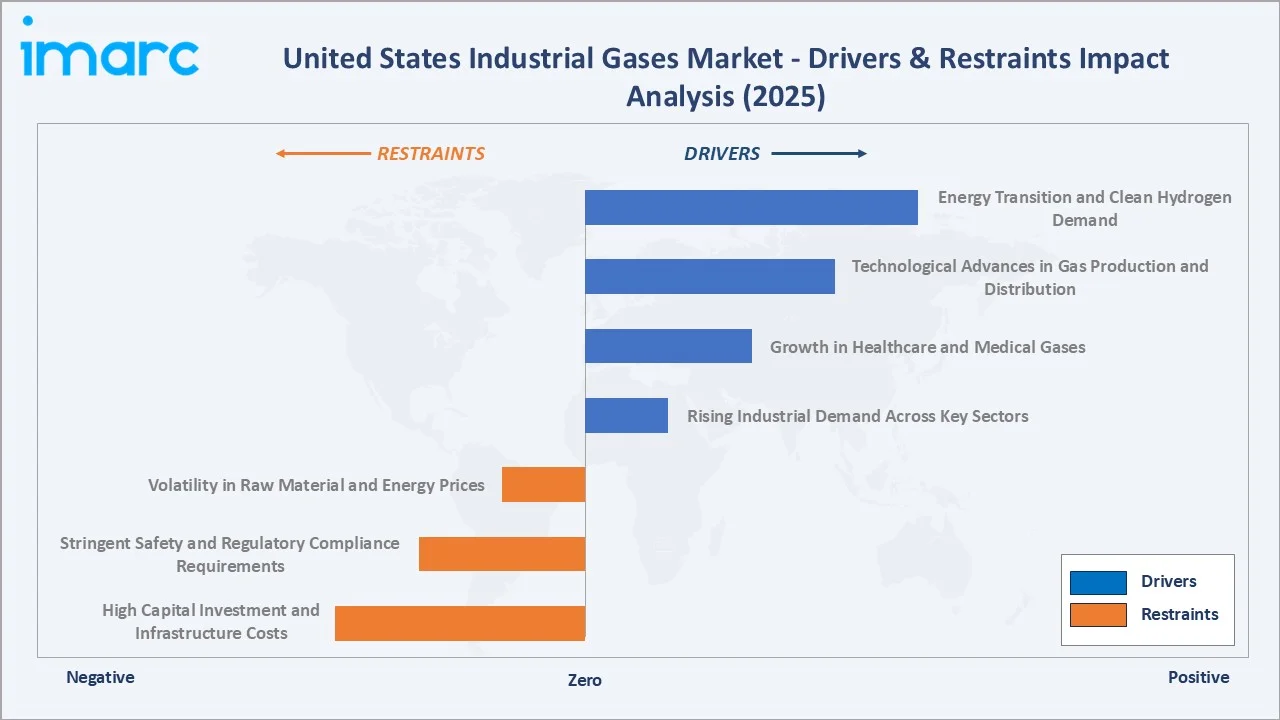
- Rising Industrial Demand Across Key Sectors: Industrial gases are essential inputs across manufacturing, chemicals, metallurgy, food and beverage, and electronics. Manufacturing sector growth, driven by reshoring of semiconductor and clean energy production, creates structural demand for oxygen, nitrogen, and argon. The DOE's industrial decarbonization program is further directing investment toward gas-intensive processes. U.S. manufacturing contributes over 12 million jobs and growing capital expenditure in advanced industries continues to expand industrial gas consumption volumes across the production value chain.
- Technological Advances in Gas Production and Distribution: Advances in cryogenic air separation, membrane separation, pressure swing adsorption, and electrolysis-based hydrogen generation are improving production efficiency and reducing unit costs, expanding addressable markets. The U.S. DOE awarded USD 750 Million to 52 clean hydrogen projects across 24 states in March 2024, accelerating hydrogen production technology scale-up. Advances in remote monitoring, predictive maintenance, and digital supply chain management are also improving reliability and reducing distribution costs across the market ecosystem.
- Growth in Healthcare and Medical Gases: The healthcare sector's structural growth is driving sustained demand for medical oxygen, nitrous oxide, nitrogen, and specialty medical gas mixtures used in respiratory therapy, anesthesia, cryotherapy, and critical care. An aging U.S. population, expansion of hospitals and outpatient surgical centers, and the post-COVID-19 investment in respiratory care infrastructure are all reinforcing this demand vector.
- Energy Transition and Clean Hydrogen Demand: The transition to cleaner energy is creating significant new demand for industrial hydrogen in low-carbon applications including fuel cells, power generation, and transportation. The DOE's Hydrogen Earthshot initiative, targeting USD 1 per kilogram clean hydrogen by 2031, combined with private sector investment in hydrogen production facilities, is creating a structurally new demand growth vector.
Market Restraints
- High Capital Investment and Infrastructure Costs: Industrial gas production requires substantial capital investment in air separation plants, hydrogen production facilities, cryogenic storage, and pipeline infrastructure. The capital-intensive nature of the business creates high barriers to entry and compresses returns during construction and ramp-up phases. Small and mid-sized industrial customers often face high minimum purchase commitments or connection costs that restrict their ability to access on-site or pipeline supply modes, limiting addressable market expansion in certain segments.
- Stringent Safety and Regulatory Compliance Requirements: Industrial gases—particularly compressed, cryogenic, and flammable gases such as oxygen, hydrogen, and acetylene—are subject to extensive safety regulations from the DOT, OSHA, EPA, and the Compressed Gas Association (CGA). Compliance with transport regulations, storage standards, personnel training requirements, and environmental permits increases operational costs for producers and distributors. Regulatory changes, particularly EPA mandates on HFC reduction and carbon emissions, require continuous investment in compliant technologies and processes.
- Volatility in Raw Material and Energy Prices: Industrial gas production, particularly through air separation and steam methane reforming, is highly energy-intensive. Natural gas price volatility directly impacts the production cost of hydrogen and other hydrocarbon-derived gases. Electricity price fluctuations affect air separation operating costs, which can compress margins when industrial gas contract prices lag energy cost increases. Supply chain disruptions affecting specialty gases and cylinder components can also create availability and cost challenges for industrial customers.
Market Opportunities
- Clean Hydrogen and Carbon Capture Scale-Up: The bipartisan infrastructure and climate legislation is channeling billions toward clean hydrogen production and carbon capture and storage infrastructure. The DOE's hydrogen hubs program and industrial decarbonization initiative represent material demand creation for industrial gas companies able to supply low-carbon hydrogen and CO2 management solutions. This represents a multi-decade structural growth opportunity for market leaders with capital and technology assets positioned to serve these emerging clean energy value chains.
- Semiconductor and Electronics Manufacturing Expansion: The CHIPS and Science Act is driving over USD 52 Billion in semiconductor manufacturing investment, including new fab construction in Arizona, Ohio, Texas, and New York. Semiconductor fabs are intensive consumers of ultra-high-purity specialty gases including nitrogen, oxygen, hydrogen, argon, and process gases. This reshoring trend represents a sustained incremental demand creation opportunity for industrial gas companies serving the electronics manufacturing segment.
Market Challenges
- Energy Intensity and Carbon Footprint of Gas Production: Air separation and steam methane reforming are highly energy-intensive processes with significant carbon footprints. As industrial customers increasingly require sustainability certifications and Scope 3 emissions data, industrial gas producers face pressure to decarbonize their own operations while serving customers with low-carbon gas solutions. The capital and operational cost of transitioning to green production methods represents a long-duration industry-wide challenge.
- Supply Chain Complexity and Logistics Constraints: The distribution of cryogenic and compressed gases requires specialized tanker fleets, cylinder management infrastructure, and trained logistics personnel. Driver shortages, aging cylinder inventory, and increasing urban delivery regulations create distribution cost and reliability challenges. Long-distance pipeline infrastructure, while efficient at scale, requires multi-decade planning and permitting processes, limiting the speed at which supply can be extended to new geographic markets.
Emerging Market Trends
1. Clean Hydrogen as the United States Industrial Gas Market's Most Commercially Transformative Growth Vector
The growing focus on clean hydrogen is creating new opportunities for the U.S. industrial gas market. Federal incentives, private-sector investment, and increasing interest in low-carbon energy are supporting the development of hydrogen production, storage, transportation, and distribution infrastructure. Industrial gas companies are expected to play an important role in supplying hydrogen and related technologies, creating a new source of long-term demand.
2. Carbon Capture and Storage Integration Creating New Industrial Gas Revenue Streams
The expansion of carbon capture, utilization, and storage (CCUS) projects is creating additional opportunities for industrial gas companies. These projects require specialized capabilities for CO₂ capture, purification, compression, transportation, and storage. Growing efforts by industries to reduce carbon emissions and comply with environmental targets are expected to increase demand for CO₂-related services and infrastructure over the forecast period.
3. Semiconductor Manufacturing Reshoring Driving Ultra-High-Purity Specialty Gas Demand
The expansion of semiconductor manufacturing in the United States is strengthening demand for ultra-high-purity specialty gases used in chip fabrication processes. Government incentives, domestic manufacturing initiatives, and investments in new semiconductor facilities are encouraging gas suppliers to expand production and distribution infrastructure near manufacturing hubs. This trend is expected to provide sustained growth opportunities for specialty industrial gases used in advanced electronics manufacturing.
4. Healthcare Sector Structural Growth Sustaining Medical Gas Market Expansion
An aging U.S. population and expanding healthcare infrastructure are creating durable demand growth for medical oxygen, specialty gas mixtures, and cryogenic medical applications. The COVID-19 pandemic exposed vulnerabilities in medical gas supply chains, prompting hospital systems and regulators to invest in more resilient on-site and backup supply systems, creating incremental demand for industrial gas companies.
Industry Value Chain Analysis
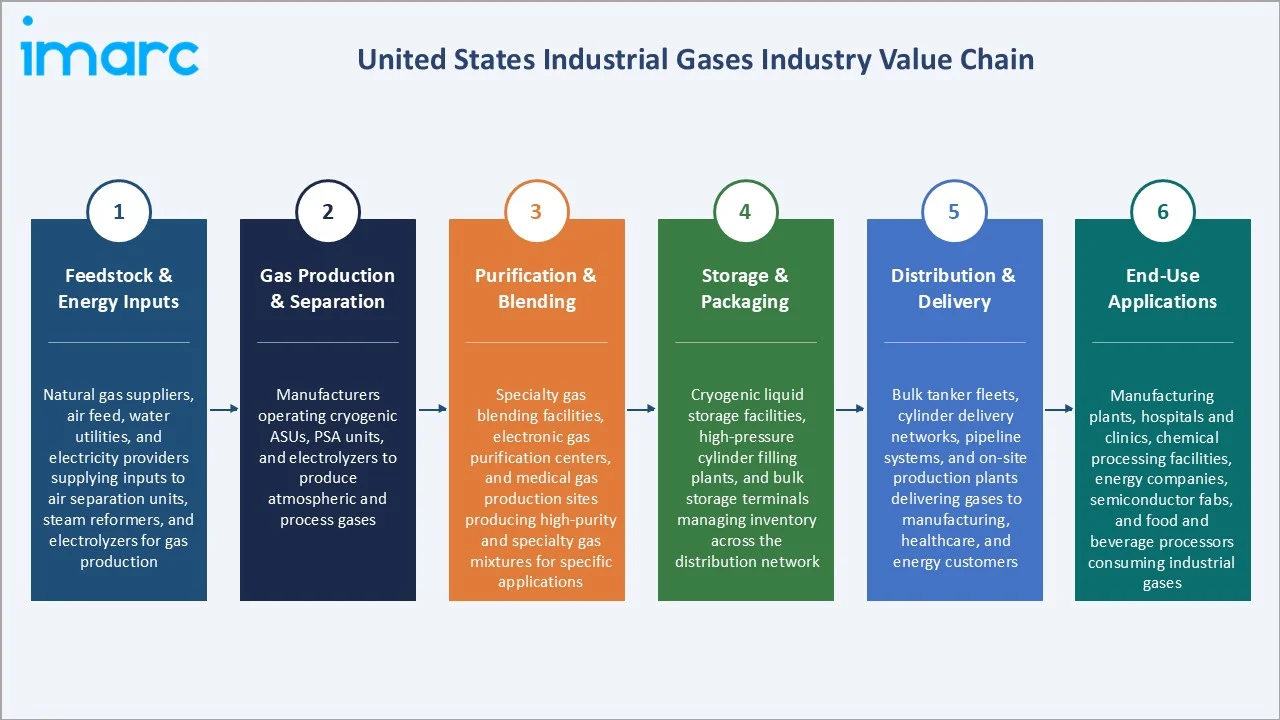
The United States industrial gases value chain is highly integrated, with major players spanning multiple stages from production through distribution. The capital intensity of production infrastructure and the logistics complexity of gas delivery create significant scale advantages for integrated operators.
|
Stage |
Key Participants |
|
Feedstock & Energy Inputs |
Natural gas suppliers, air feed, water utilities, and electricity providers supplying inputs to air separation units, steam reformers, and electrolyzers for gas production |
|
Gas Production & Separation |
Manufacturers operating cryogenic ASUs, PSA units, and electrolyzers to produce atmospheric and process gases |
|
Purification & Blending |
Specialty gas blending facilities, electronic gas purification centers, and medical gas production sites producing high-purity and specialty gas mixtures for specific applications |
|
Storage & Packaging |
Cryogenic liquid storage facilities, high-pressure cylinder filling plants, and bulk storage terminals managing inventory across the distribution network |
|
Distribution & Delivery |
Bulk tanker fleets, cylinder delivery networks, pipeline systems, and on-site production plants delivering gases to manufacturing, healthcare, and energy customers |
|
End-Use Applications |
Manufacturing plants, hospitals and clinics, chemical processing facilities, energy companies, semiconductor fabs, and food and beverage processors consuming industrial gases |
The distribution and delivery stage is the industrial gases value chain's most commercially consequential stage, where companies invest in logistics infrastructure, customer support, and digital monitoring to retain long-term supply contracts with industrial end users.
Technology Landscape in the United States Industrial Gases Industry
Air Separation and Cryogenic Production Technology
Cryogenic air separation units (ASUs) remain the dominant production technology for atmospheric gases, using fractional distillation at extremely low temperatures to separate nitrogen, oxygen, and argon. Modern large-scale ASUs deliver significant energy efficiency improvements over legacy plants, reducing per-unit production costs and supporting the economic viability of on-site and pipeline supply models.
Hydrogen Production and Electrolysis Technology
Steam methane reforming is the primary commercial hydrogen production technology, while proton exchange membrane electrolysis is the leading green hydrogen pathway gaining rapid adoption. DOE-backed electrolyzer programs and falling renewable electricity costs are accelerating the commercial scale-up of electrolysis-based hydrogen production, enabling industrial gas companies to serve clean energy customers with low-carbon hydrogen supply.
Digital Monitoring and Smart Distribution Technology
Industrial gas companies are deploying IoT-enabled remote monitoring systems, predictive maintenance platforms, and digital supply chain management tools across their production and distribution networks. Real-time telemetry on cylinder inventory, bulk storage levels, and customer usage patterns enables proactive replenishment, reduces emergency delivery costs, and improves customer satisfaction across manufacturing, healthcare, and energy segments.
Market Segmentation Analysis
The report covers the following segments:
|
Segment |
Leading Segment |
Market Share |
Year |
|
Type |
Nitrogen |
28.6% |
2025 |
|
Application |
Manufacturing |
27.5% |
2025 |
|
Supply Mode |
Packaged |
45.7% |
2025 |
|
Region |
South |
36.5% |
2025 |

By Type
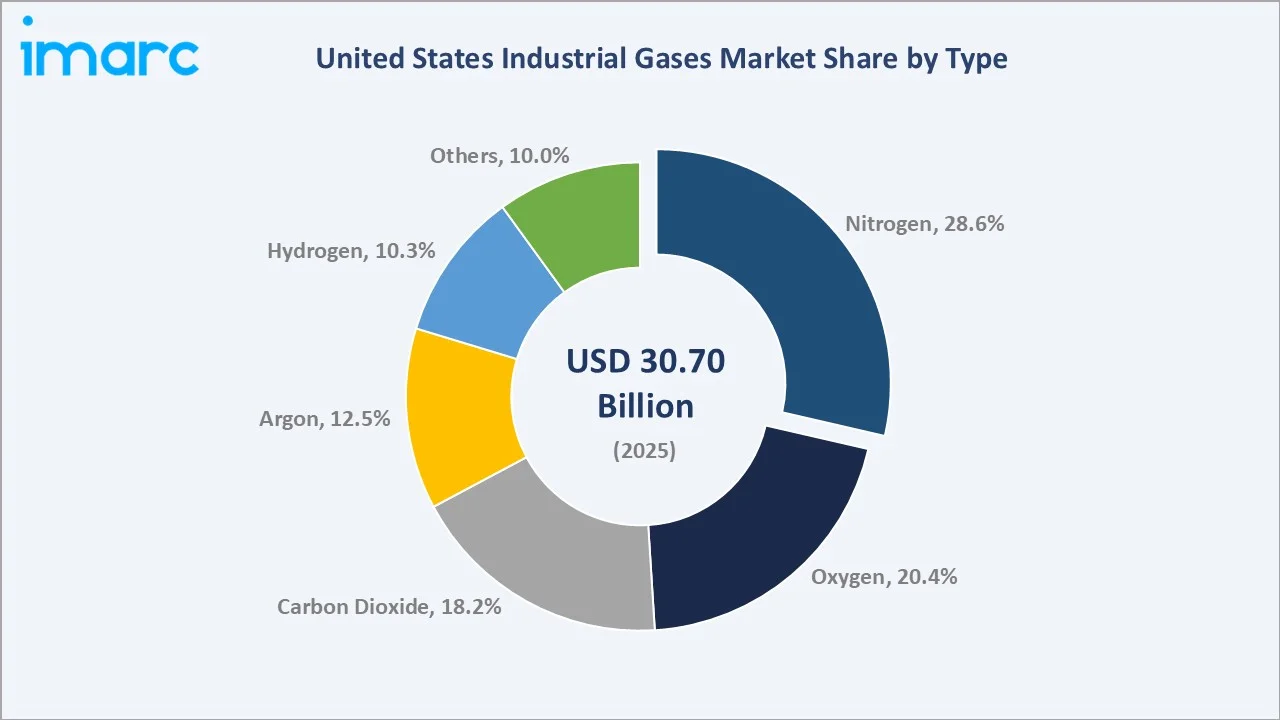
The nitrogen segment, leading at 28.6%, encompasses the United States' most commercially broad industrial gas application profile, covering ammonia fertilizer production, food and beverage inert atmospheres, electronics manufacturing blanketing, and oil and gas pipeline purging.
To access detailed market analysis, Request Sample
Oxygen at 20.4% serves steel, healthcare, and chemical processing. Carbon dioxide at 18.2% is growing through food preservation and CCS. Hydrogen at 10.3% is the fastest-growing type at ~4.5% CAGR through clean energy mandates and industrial decarbonization investment.
By Application
The manufacturing segment, leading at 27.5%, is the dominant consumer of industrial gases, requiring oxygen, nitrogen, and argon across metal fabrication, chemical production, and electronics manufacturing.
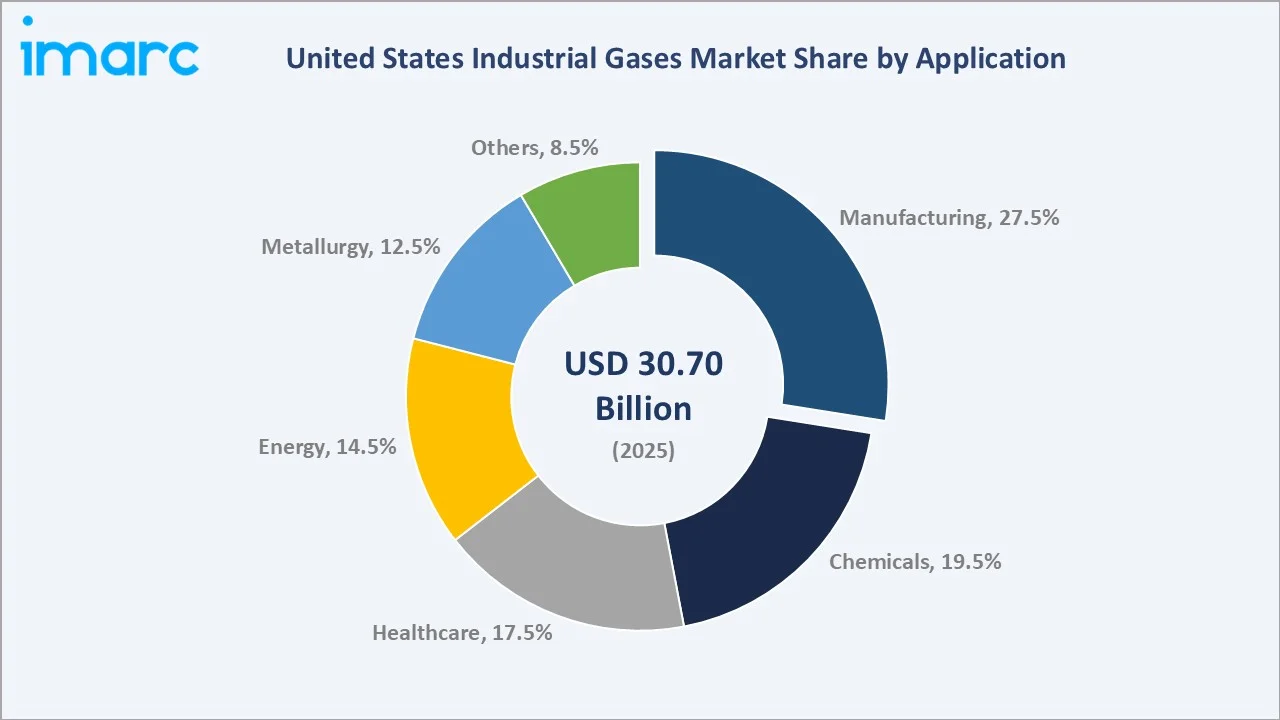
Chemicals at 19.5% reflects industrial gas use in petrochemical synthesis and specialty chemical production. Healthcare at 17.5% is growing through aging demographics and expanding medical infrastructure. Energy at 14.5% is driven by hydrogen for refining and clean fuel applications.
Regional Market Insights
|
Region |
Share (2025) |
Key Market Drivers & Characteristics |
|
South |
36.5% |
Driven by Texas petrochemical and refining complex, Louisiana chemical manufacturing, Florida healthcare growth, and aerospace and energy sector industrial gas demand. |
|
Midwest |
25.5% |
Reflects dense manufacturing, automotive, agricultural, and steel production base across Ohio, Michigan, Illinois, and Indiana driving broad-spectrum industrial gas consumption. |
|
West |
21.5% |
Supporting semiconductor manufacturing in Arizona, technology-driven specialty gas demand in California, and renewable energy and hydrogen projects across the Pacific Coast states. |
|
Northeast |
16.5% |
Rising pharmaceutical, biotech, and research institution demand for medical and specialty gases in New York, New Jersey, Massachusetts, and Pennsylvania. |
The South's 36.5% market leadership reflects the concentration of America's largest petrochemical complex along the Gulf Coast, where industrial gases are consumed at scale in refining, chemicals, and ammonia production. Texas alone is the single largest US state industrial gas market. The Midwest's 25.5% reflects its foundational role as America's manufacturing heartland, with steel, auto, and chemical sectors all relying on large-volume atmospheric gas supply.
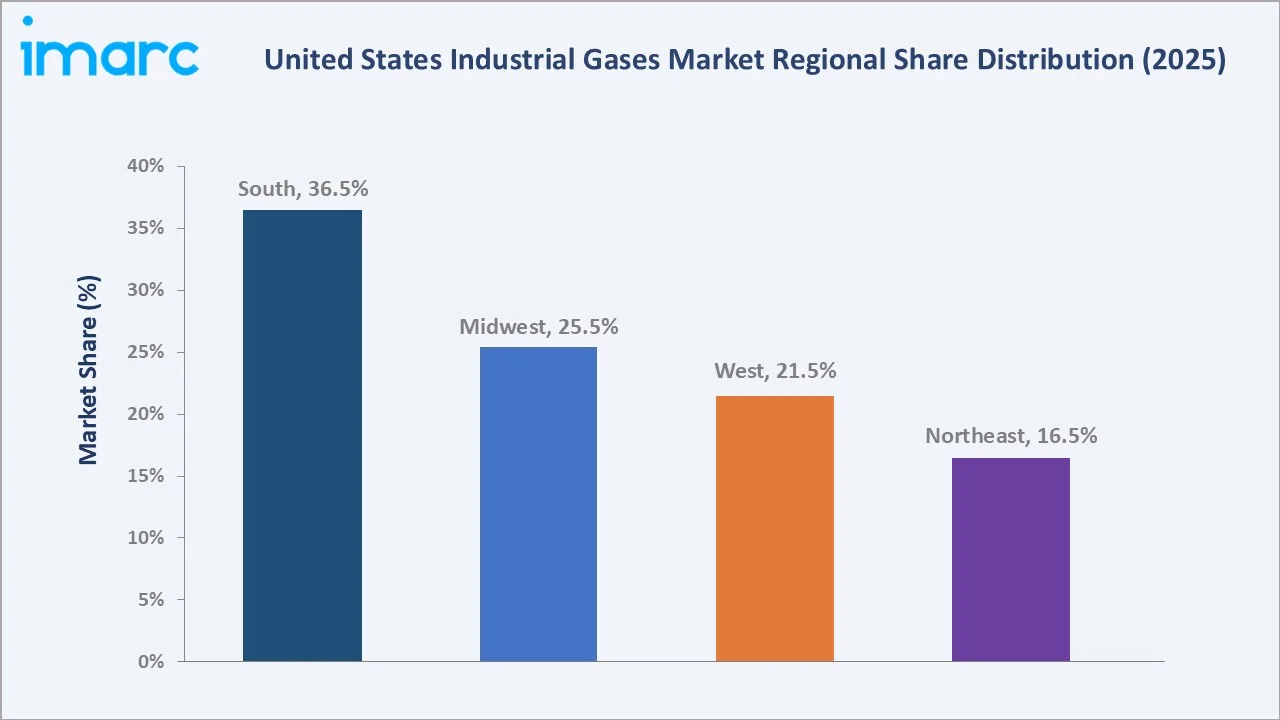
The West's 21.5% reflects California's diversified industrial and technology base and the rapid expansion of semiconductor manufacturing in Arizona, which is creating new ultra-high-purity specialty gas demand. The Northeast's 16.5% is characterized by higher-margin specialty and medical gas consumption, with pharmaceutical and biotech clusters in New Jersey and Massachusetts sustaining premium segment growth.
Competitive Landscape
The United States industrial gases market competitive landscape is highly consolidated, with a small number of globally integrated producers controlling the majority of production, distribution, and specialty gas capacity.
|
Company |
Key Products/Services |
Market Position |
Core Strength |
|
Air Products and Chemicals, Inc. |
Argon, Carbon dioxide, Carbon Monoxide, Helium, Hydrogen, Nitrogen, Oxygen, Krypton, Neon, Xenon |
Market Leader |
Leading industrial gas company with extensive production and distribution infrastructure across key US markets |
|
Linde PLC |
Argon, Carbon Dioxide, Helium, Hydrogen, Nitrogen, Oxygen |
Market Leader |
Global industrial gas supplier with broad US operational presence across manufacturing, energy, and healthcare |
|
Air Liquide |
Argon, Carbon Dioxide, Helium, Hydrogen, Nitrogen, Oxygen |
Market Leader |
Internationally established industrial gas provider with a strong US footprint across industrial and medical segments |
|
MESSER SE & CO. KGAA |
Acetylene, Argon, Carbon Dioxide, Oxygen, Nitrogen, Hydrogen |
Strong Challenger |
Expanding US industrial gas presence serving manufacturing and healthcare sectors across regional markets |
Key players include Air Products and Chemicals, Inc., Linde PLC, Air Liquide, MESSER SE & CO. KGAA, and others.
Key Company Profiles
Air Products and Chemicals, Inc.
Air Products and Chemicals, Inc. is headquartered in Allentown, Pennsylvania, and is the largest industrial hydrogen supplier in the world. The company produces and distributes atmospheric gases, process gases, and specialty gases to industrial, energy, and electronics customers across the United States and globally.
- Key Products: Argon, Carbon dioxide, Carbon Monoxide, Helium, Hydrogen, Nitrogen, Oxygen, Krypton, Neon, Xenon, and others
- Recent Developments: In August 2026, Air Products announced the development of enhanced hydrogen capabilities at its laboratory facilities, supporting research and testing related to hydrogen technologies and applications. The initiative strengthens the company's technical capabilities in hydrogen production, processing, and utilization while supporting the development of solutions for emerging clean-energy applications.
- Strategic Focus: Maintaining global hydrogen leadership through large-scale clean hydrogen infrastructure investment while sustaining core atmospheric gas market position across manufacturing, healthcare, and energy. Air Products is positioning clean hydrogen and carbon capture as its primary long-term growth platforms, with significant capital deployment planned across the US and international markets through 2030 and beyond.
Linde PLC
Linde is the world's largest industrial gas company, with extensive US operations spanning atmospheric gas production, specialty gases, engineering services, and carbon capture technology. Its US business includes the legacy Praxair infrastructure and an expansive Gulf Coast industrial gas pipeline network.
- Key Products: Argon, Carbon Dioxide, Helium, Hydrogen, Nitrogen, Oxygen, and others
- Strategic Focus: Leveraging its unmatched Gulf Coast pipeline infrastructure and global engineering capabilities to win large-scale industrial supply contracts while investing in carbon capture and clean hydrogen to position itself as the leading partner for industrial decarbonization. Linde's on-site production capabilities give it a structural advantage in high-volume supply contracts with major chemical, refining, and steel customers across the Southern United States.
Market Concentration Analysis
The United States industrial gases market is highly concentrated, with the key players collectively commanding the majority of atmospheric gas production capacity and large-scale industrial supply contracts. This triopolistic structure reflects decades of capital-intensive infrastructure building and consolidation.
Market concentration is being maintained at the top through continued expansion by the three global majors while niche and specialty gas segments are increasingly accessible to specialized players such as Matheson Tri-Gas and Messer Group. The distribution segment through Airgas, Inc. provides a distinct competitive layer serving smaller industrial and healthcare customers through its branch network.
Investment & Growth Opportunities
Highest Growth Segments
Clean hydrogen (~4.5% CAGR), carbon dioxide for CCS applications (~3.8% CAGR), ultra-high-purity semiconductor specialty gases (~4.2% CAGR), medical gases (~3.6% CAGR), and healthcare segment industrial gas demand (~3.5% CAGR) represent the highest-growth investment vectors in the United States industrial gases market through 2034.
Emerging Investment Opportunities
The clean hydrogen market, driven by DOE funding and energy transition mandates, represents the single most commercially significant emerging investment opportunity. Large-scale electrolysis and carbon capture integration are creating new revenue streams for industrial gas companies willing to invest in next-generation production infrastructure beyond traditional air separation economics.
Investment Themes
- Clean hydrogen production infrastructure investment targeting both industrial and energy sector decarbonization: DOE's Hydrogen Earthshot and hydrogen hub programs create a structured government-supported demand creation mechanism that reduces investment risk for large-scale hydrogen projects at the industrial gas majors' scale.
- Ultra-high-purity specialty gas facility development serving CHIPS Act-driven semiconductor manufacturing reshoring: New fab construction in Arizona, Ohio, and Texas creates durable decade-long demand anchors for specialty gas supply that justify large capital investment in purification and distribution infrastructure close to customer sites.
Future Market Outlook (2026-2034)
The United States industrial gases market is projected to grow from USD 30.70 Billion in 2025 to USD 31.71 Billion in 2026, reaching USD 41.43 Billion by 2034 at a CAGR of 3.28%. The market's anchor value of USD 36.09 Billion by 2030 reflects an industrial gas market at a structural inflection point where clean energy and advanced manufacturing co-invest with the traditional industrial base.
Three structural forces define market growth through 2034: the energy transition creating new hydrogen and CO2 management demand vectors that expand the total addressable market beyond traditional atmospheric gas consumption; semiconductor manufacturing reshoring creating concentrated specialty gas demand in new geographic clusters; and healthcare sector expansion sustaining baseline medical gas demand growth across all forecast years.
Research Methodology
Primary Research
Primary research comprised structured interviews with United States industrial gas industry stakeholders, including production plant managers, distribution executives, procurement directors, regulatory specialists, and end-user purchasing managers across manufacturing, healthcare, energy, and chemical sectors.
Secondary Research
Secondary research encompassed DOE, EPA, USGS, and EIA publications, company annual reports, industry association data from CGA and GAWDA, patent filings, import-export statistics, and investor presentations. Over 60 secondary sources were reviewed across government, industry, and commercial databases.
Forecasting Models
Market revenue forecasts were developed using a bottom-up industrial output model: US industrial production by sector multiplied by sector-specific gas intensity ratios and average price per unit, aggregated across application segments. Clean energy policy investment multipliers applied to hydrogen and carbon capture segments.
United States Industrial Gases Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Nitrogen, Oxygen, Carbon Dioxide, Argon, Hydrogen, Others |
| Applications Covered | Manufacturing, Metallurgy, Energy, Chemicals, Healthcare, Others |
| Supply Modes Covered | Packaged, Bulk, On-Site |
| Regions Covered | Northeast, Midwest, South, West |
| Companies Covered | Air Products and Chemicals, Inc., Linde PLC, Air Liquide, MESSER SE & CO. KGAA, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the United States industrial gases market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the United States industrial gases market.
- Porter's Five Forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the United States industrial gases industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the United States Industrial Gases Market Report
The United States industrial gases market was valued at USD 31.71 Billion in 2026. The market is driven by rising demand across manufacturing, healthcare, chemicals, and energy sectors, combined with technological advances in gas production and distribution and government investment in clean energy and hydrogen technologies.
The US industrial gases market is projected to exhibit a CAGR of 3.28% during 2026-2034, reaching USD 41.43 Billion by 2034. Growth is sustained by healthcare expansion, clean hydrogen investment, semiconductor manufacturing reshoring, and the structural shift toward industrial decarbonization through gas-based solutions.
Nitrogen leads at 28.6% through its dominant role in ammonia production, food processing, electronics manufacturing, and oil and gas applications. The US produces 14 million metric tons of ammonia annually, driven by nitrogen demand, cementing its leading position across the forecast period.
Manufacturing leads at 27.5% through broad-based demand for oxygen, nitrogen, and argon in metal fabrication, chemical production, and electronics manufacturing. The sector's 11 million-plus jobs and growing capital investment in advanced manufacturing processes sustain its dominant application position.
The South leads at 36.5% through Texas's massive petrochemical and refining complex, Louisiana's chemical manufacturing base, and the region's expanding healthcare and aerospace sectors. The Gulf Coast's concentration of industrial gas infrastructure anchors the South's commercial leadership in the national market.
Leading companies in the United States industrial gas market include Air Products and Chemicals, Inc., Linde PLC, Air Liquide, MESSER SE & CO. KGAA, and others.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade