
United States Industrial Valves Market Size, Share, Trends and Forecast by Product Type, Functionality, Material Size, End Use Industry, and Region, 2026-2034
United States Industrial Valves Market Size, Share, Trends & Forecast (2026-2034)
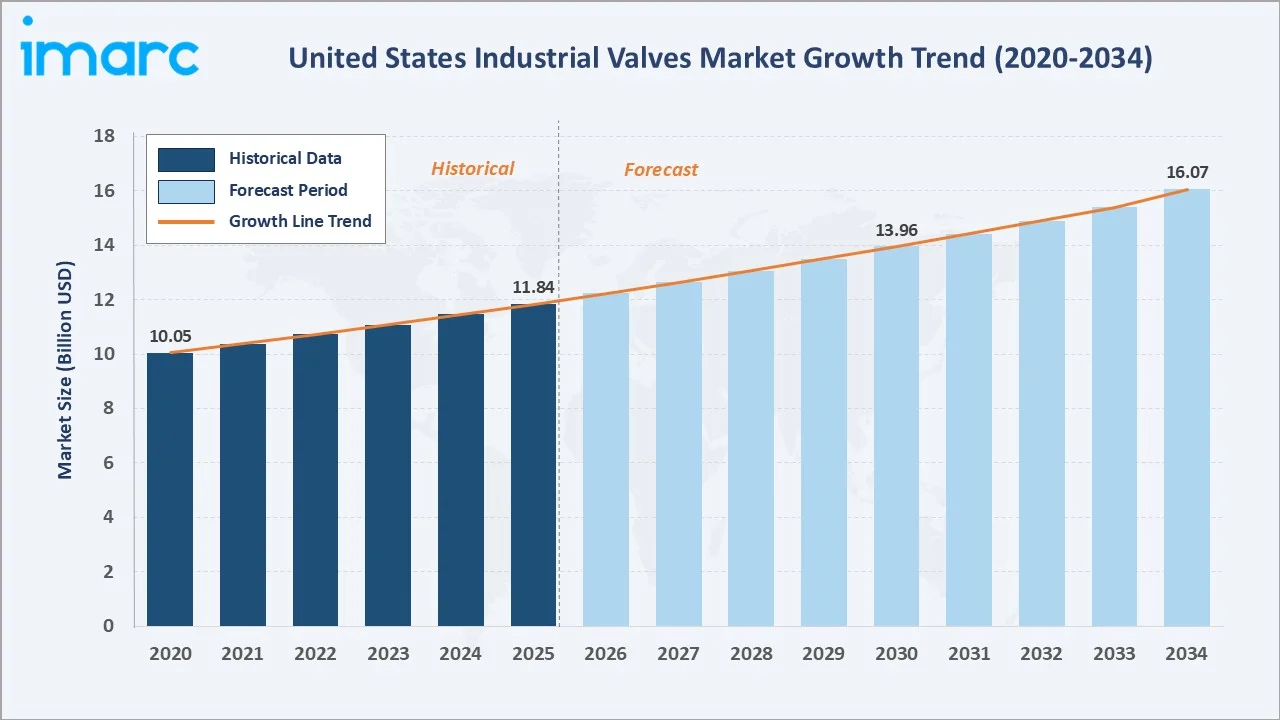
The US industrial valve market grew from USD 11.84 Billion in 2025 and is estimated to reach USD 12.24 Billion in 2026. The market is further projected to reach USD 16.07 Billion by 2034, growing at a CAGR of 3.35% during 2026-2034. The market is driven by expanding oil and gas infrastructure, aging pipeline replacement programs, and growing investments in water and wastewater treatment. Industrial automation adoption and smart valve technology integration are further accelerating market expansion. On-Off/Isolation Valves dominate at 62.0%. Steel leads material segments at 48.0%. The South commands 38.0% of the national market share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 11.84 Billion |
|
Market Size (2026) |
USD 12.24 Billion |
|
Forecast Market Size (2034) |
USD 16.07 Billion |
|
CAGR (2026-2034) |
3.35% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Functionality |
On-Off/Isolation Valves (62.0%, 2025) |
|
Dominant Material |
Steel (48.0%, 2025) |
|
Leading Region |
South (38.0%, 2025) |
The US industrial valves market size increased from USD 10.05 Billion in 2020 to USD 11.84 Billion in 2025 and is estimated to reach USD 12.24 Billion in 2026. The market is further expected to grow to USD 13.96 Billion by 2030 and USD 16.07 Billion by 2034. The US industrial valve market is commercially significant among global valve markets, driven by extensive pipeline infrastructure, robust oil and gas sector investments, and systematic water infrastructure modernization programs.
To get more information on this market, Request Sample
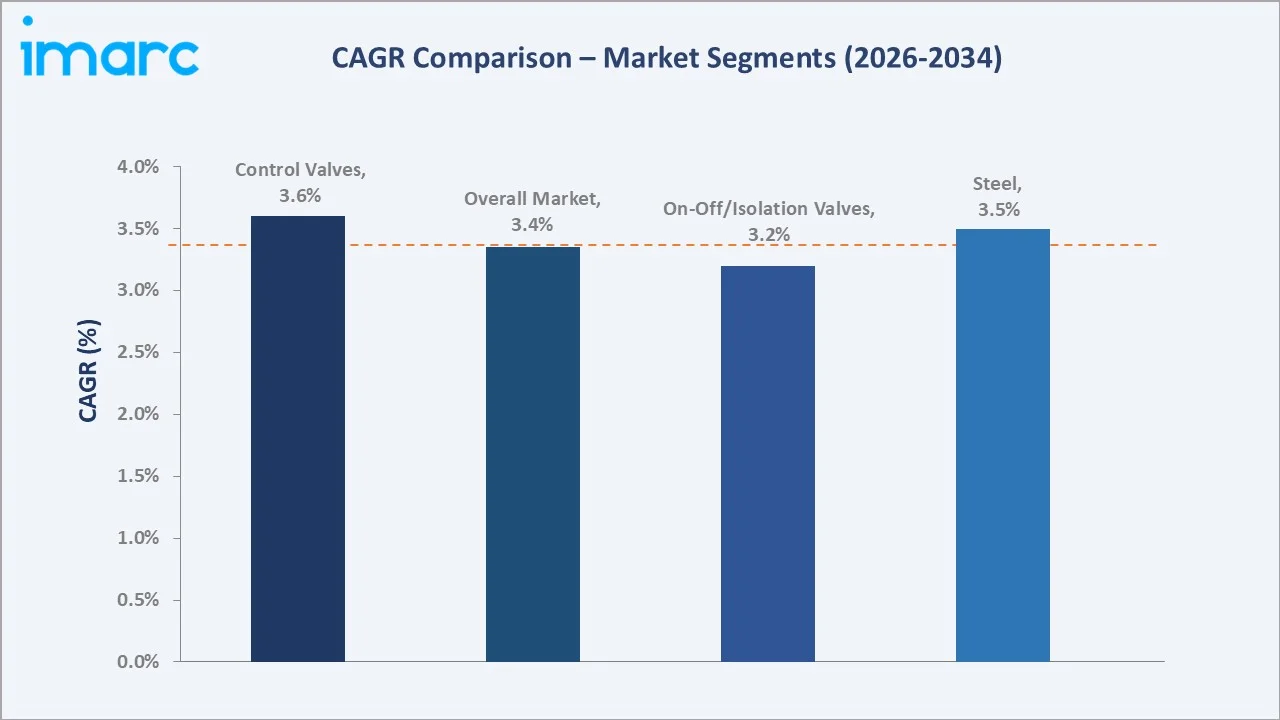
The Control Valves segment grows fastest at ~3.6% CAGR through industrial automation adoption, process optimization in chemical and petrochemical industries, and rising demand for precision flow control. Alloy-based valves grow at ~4.1% CAGR through high-performance requirements in extreme-temperature and corrosive-environment applications.
Executive Summary
The US industrial valve market expanded from USD 11.84 Billion in 2025 to an estimated USD 12.24 Billion in 2026, positioning it among the world's largest national industrial valve markets by value. The market's scale is underpinned by the country's extensive pipeline network, robust oil and gas sector, and growing investments in water infrastructure modernization. The market is projected to reach USD 16.07 Billion by 2034.
On-Off/Isolation Valves at 62.0% lead through commercial dominance in pipeline and process isolation applications. Steel at 48.0% reflects the preferred material choice for high-pressure industrial applications. The South at 38.0% leads regionally due to concentrated oil and gas infrastructure.
Key Market Insights
|
Insight |
Data |
|
Dominant Functionality |
On-Off/Isolation Valves - 62.0% share (2025) |
|
Dominant Material |
Steel - 48.0% market share (2025) |
|
Leading Region |
South - 38.0% share (2025) |
|
Market Opportunity |
Smart valve technology; water infrastructure modernization; energy transition investments; industrial automation and IIoT integration |
Key Analytical Observations Supporting the Above Data:
- On-Off/Isolation Valves at 62.0%: This segment dominates due to its critical role in pipeline isolation, maintenance operations, and emergency shut-off across oil and gas, water, and chemical industries. The high installed base in existing infrastructure ensures sustained replacement demand.
- Steel at 48.0%: Steel valves dominate due to superior strength, pressure resistance, and durability in high-temperature and high-pressure industrial environments. Widespread use in oil and gas, power generation, and chemical processing supports segment leadership.
- South at 38.0%: The South leads regionally due to concentrated oil and gas production, refining, and petrochemical processing facilities. Texas, Louisiana, and Oklahoma account for highest valve demand through extensive pipeline networks.
United States Industrial Valves Market Overview
The US industrial valve market is commercially positioned at the intersection of mature industrial infrastructure and emerging smart manufacturing. The market's commercial structure is characterized by high replacement demand from aging infrastructure, regulatory compliance requirements, and growing adoption of intelligent valve systems across process industries.
The US industrial valve ecosystem integrates domestic manufacturing, specialized distribution networks, MRO procurement channels, and project-based capital expenditure. Macroeconomic factors include infrastructure investment legislation, energy sector capital expenditure cycles, and industrial production growth.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
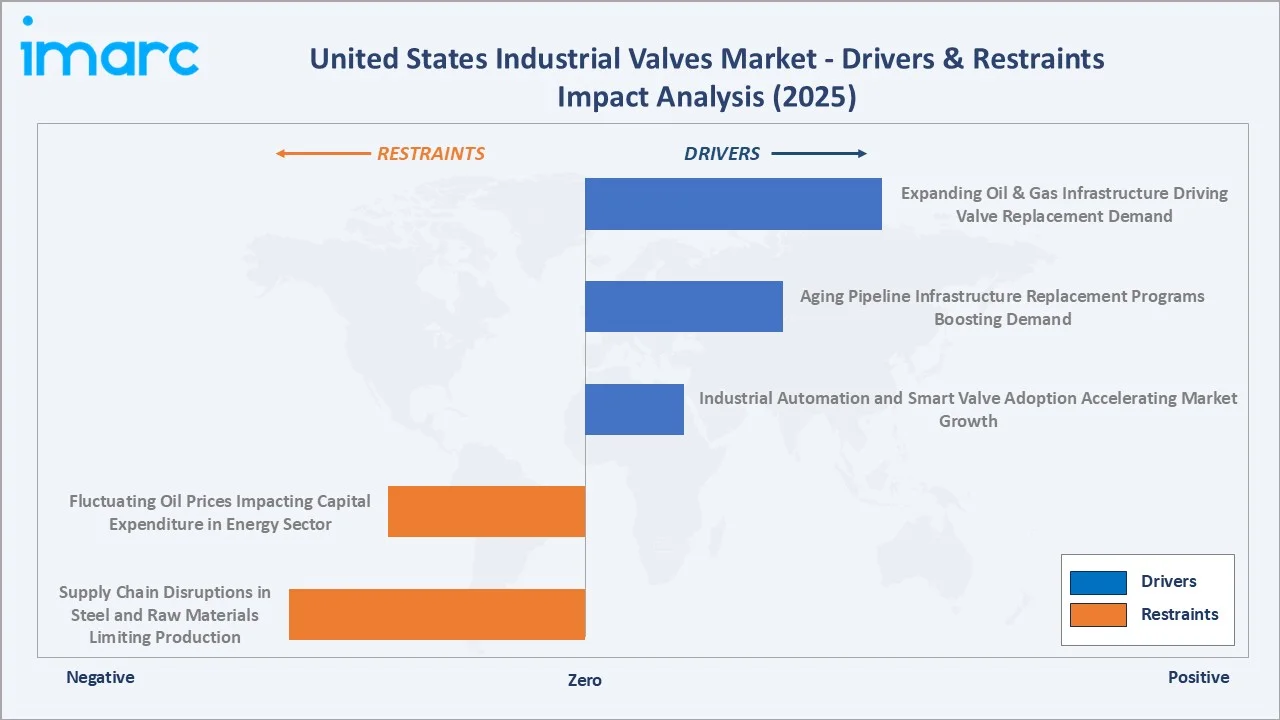
- Expanding Oil & Gas Infrastructure Driving Valve Replacement Demand: The United States oil and gas sector continues to expand its production and transportation infrastructure, creating sustained demand for industrial valves across pipeline, refinery, and processing applications. Ongoing capital investments in LNG export facilities and midstream infrastructure are driving procurement of high-performance gate, ball, and check valves. Shale oil and gas production expansion further supports demand for durable, high-pressure rated valve solutions.
- Growing Water & Wastewater Treatment Investments Increasing Valve Procurement: Federal and state-level investments in water infrastructure modernization are generating significant demand for industrial valves. Municipal utilities are procuring butterfly, gate, and check valves for pipe rehabilitation, pump station upgrades, and treatment facility expansions. Growing urban population and aging water distribution systems sustain long-term replacement valve demand across the United States.
- Industrial Automation and Smart Valve Adoption Accelerating Market Growth: Increasing adoption of industrial automation, process control systems, and IIoT technologies is driving demand for intelligent and smart valves equipped with actuators, sensors, and remote monitoring capabilities. Manufacturing plants, chemical facilities, and power generation stations are investing in automated valve solutions to improve process efficiency and ensure regulatory compliance.
- Aging Pipeline Infrastructure Replacement Programs Boosting Demand: The United States has one of the world's most extensive pipeline networks, with significant portions requiring rehabilitation or replacement due to age and regulatory compliance requirements. Pipeline operators are executing multi-year integrity management programs including valve replacement and upgrade activities, creating structured recurring demand for high-specification industrial valves.
Market Restraints
- Supply Chain Disruptions in Steel and Raw Materials Limiting Production: Industrial valve manufacturers face ongoing supply chain vulnerabilities in steel, stainless steel, and specialized alloy materials. Global steel price volatility and trade policy uncertainties impact manufacturing costs and lead times, creating pricing pressure and cost unpredictability across the US industrial valve supply chain.
- Fluctuating Oil Prices Impacting Capital Expenditure in Energy Sector: The industrial valve market's significant exposure to oil and gas capital expenditure creates cyclical demand sensitivity to crude oil price movements. Energy companies reduce capital spending during periods of low oil prices, directly impacting valve procurement budgets for new projects and maintenance programs.
- Stringent Environmental Regulations Increasing Compliance Costs: EPA and state environmental regulations governing fugitive emissions, leak detection, and valve performance standards are increasing compliance costs for manufacturers and end users. Low emission valve certifications and methane emissions compliance require ongoing valve system upgrades, adding operational costs for end users.
Market Opportunities
- Energy Transition Infrastructure Creating New Valve Application Segments: The US energy transition to hydrogen and carbon capture infrastructure is creating new valve application segments. Hydrogen distribution and storage, carbon dioxide pipeline transportation, and geothermal energy development require specialized valve solutions, representing high-value growth opportunities for manufacturers with technical expertise in corrosion-resistant and cryogenic designs.
- Smart Manufacturing and Industry 4.0 Driving Intelligent Valve System Demand: The US manufacturing sector's adoption of Industry 4.0 technologies is creating demand for intelligent valve systems with digital communication protocols. This technology upgrade cycle represents a high-margin growth opportunity for valve manufacturers with digital product portfolios.
Market Challenges
- Skilled Workforce Shortage in Valve Installation and Maintenance: The US industrial sector faces a growing shortage of skilled workers for valve installation, commissioning, and maintenance. An aging workforce and reduced vocational training create operational constraints for end users managing large valve installations, increasing the cost of specialized valve service contracts.
- Price Competition from Low-Cost Imported Valves: Import competition from low-cost manufacturers creates pricing pressure on domestic US valve producers, particularly in commodity valve categories. While US manufacturers maintain technical advantages in high-specification applications, price-sensitive procurement in standard categories challenges domestic market share and margin sustainability.
Emerging Market Trends
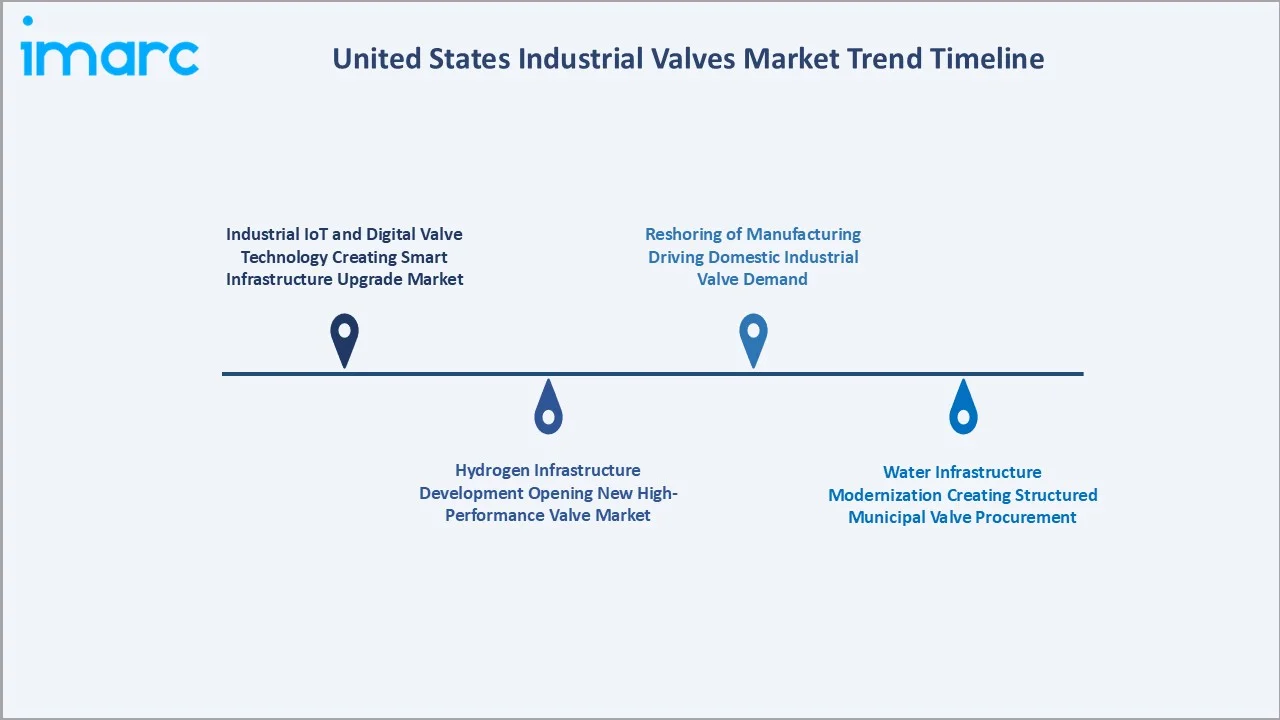
1. Industrial IoT and Digital Valve Technology Creating Smart Infrastructure Upgrade Market
Digital valve technology integration is driving demand for smart valve solutions equipped with sensors, actuators, and wireless communication capabilities. Industrial IoT adoption enables real-time monitoring, predictive maintenance, and remote operation across oil and gas, chemical, and power generation facilities. This digital transformation is creating a premium segment within the broader US industrial valve market.
2. Hydrogen Infrastructure Development Opening New High-Performance Valve Market
The United States' accelerating hydrogen economy development is creating specialized demand for hydrogen-compatible industrial valves. Hydrogen service requires valves with specific material compatibility, low-permeability sealing, and high-pressure rating capabilities. This emerging application segment represents a structurally new valve procurement category driven by federal clean energy investments and private hydrogen infrastructure development.
3. Water Infrastructure Modernization Creating Structured Municipal Valve Procurement
Federal infrastructure investment legislation is generating multi-year structured municipal valve procurement programs across the United States. Water utilities are executing systematic pipe rehabilitation and treatment facility expansions requiring large-volume valve procurement. This infrastructure-driven demand creates predictable, long-term purchasing cycles for butterfly, gate, and check valve manufacturers with established utility relationships.
4. Reshoring of Manufacturing Driving Domestic Industrial Valve Demand
The US manufacturing reshoring trend, accelerated by supply chain diversification strategies and government incentives, is expanding industrial valve demand across pharmaceutical, semiconductor, battery, and advanced manufacturing facilities. New domestic manufacturing plant construction requires comprehensive valve system installations for process fluid control and safety applications.
Industry Value Chain Analysis
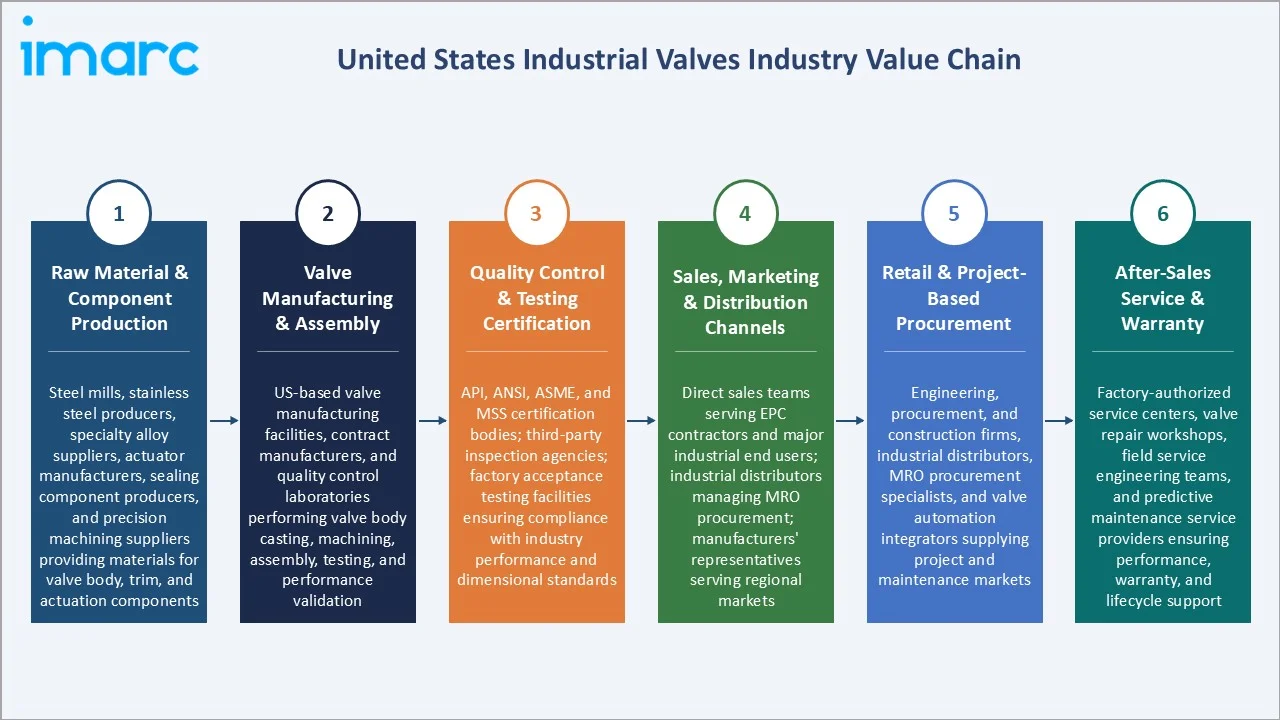
The US industrial valve value chain is one of the most technically specialized of any industrial goods category. The value chain's commercial structure creates competitive differentiation at each stage, from raw material selection through end-user service and maintenance, where performance reliability, regulatory compliance, and application engineering capability determine supplier selection.
|
Stage |
Key Participants |
|
Raw Material & Component Production |
Steel mills, stainless steel producers, specialty alloy suppliers, actuator manufacturers, sealing component producers, and precision machining suppliers providing materials for valve body, trim, and actuation components |
|
Valve Manufacturing & Assembly |
US-based valve manufacturing facilities, contract manufacturers, and quality control laboratories performing valve body casting, machining, assembly, testing, and performance validation |
|
Quality Control & Testing Certification |
API, ANSI, ASME, and MSS certification bodies; third-party inspection agencies; factory acceptance testing facilities ensuring compliance with industry performance and dimensional standards |
|
Sales, Marketing & Distribution Channels |
Direct sales teams serving EPC contractors and major industrial end users; industrial distributors managing MRO procurement; manufacturers' representatives serving regional markets |
|
Retail & Project-Based Procurement |
Engineering, procurement, and construction firms, industrial distributors, MRO procurement specialists, and valve automation integrators supplying project and maintenance markets |
|
After-Sales Service & Warranty |
Factory-authorized service centers, valve repair workshops, field service engineering teams, and predictive maintenance service providers ensuring performance, warranty, and lifecycle support |
The quality control and certification stage is the US industrial valve value chain's most commercially consequential regulatory gate, where API, ANSI, and ASME compliance certification serves as the entry requirement for oil and gas, power generation, and municipal water procurement, creating a structural barrier that limits competitive entry from non-certified suppliers.
Technology Landscape in the United States Industrial Valves Industry
Conventional Valve Technologies
Conventional gate, globe, ball, butterfly, and check valve technologies continue to serve foundational procurement requirements across oil and gas, water, chemical, and power generation industries. These proven valve designs provide reliable performance across standard pressure and temperature service conditions, with continuous material and sealing improvements extending service life and reducing total cost of ownership for end users.
Smart Valve and Intelligent Actuation Technology
Smart valve and intelligent actuation technology are integrating conventional valve bodies with digital control, diagnostic, and communication capabilities. Electric and pneumatic actuators with embedded position feedback, torque monitoring, and wireless communication enable real-time process visibility. Integration with plant-wide asset management systems is transforming valve maintenance from time-based to condition-based programs, reducing operational costs and unplanned downtime.
Advanced Material and Coating Technologies
Advanced material technologies including duplex stainless steel, super duplex alloys, titanium, and specialized polymer coatings are expanding valve service capabilities in corrosive and high-temperature applications. Thermal spray coatings, hard facing, and ceramic lining technologies extend valve trim life in abrasive service conditions. These material innovations support above-average growth in alloy-based valve segments serving technically demanding industrial applications.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Product Type |
🔒 |
🔒 |
2025 |
|
Functionality |
On-Off/Isolation Valves |
62.0% |
2025 |
|
Material |
Steel |
48.0% |
2025 |
|
Size |
🔒 |
🔒 |
2025 |
|
End Use Industry |
🔒 |
🔒 |
2025 |
|
Region |
South |
38.0% |
2025 |

By Functionality
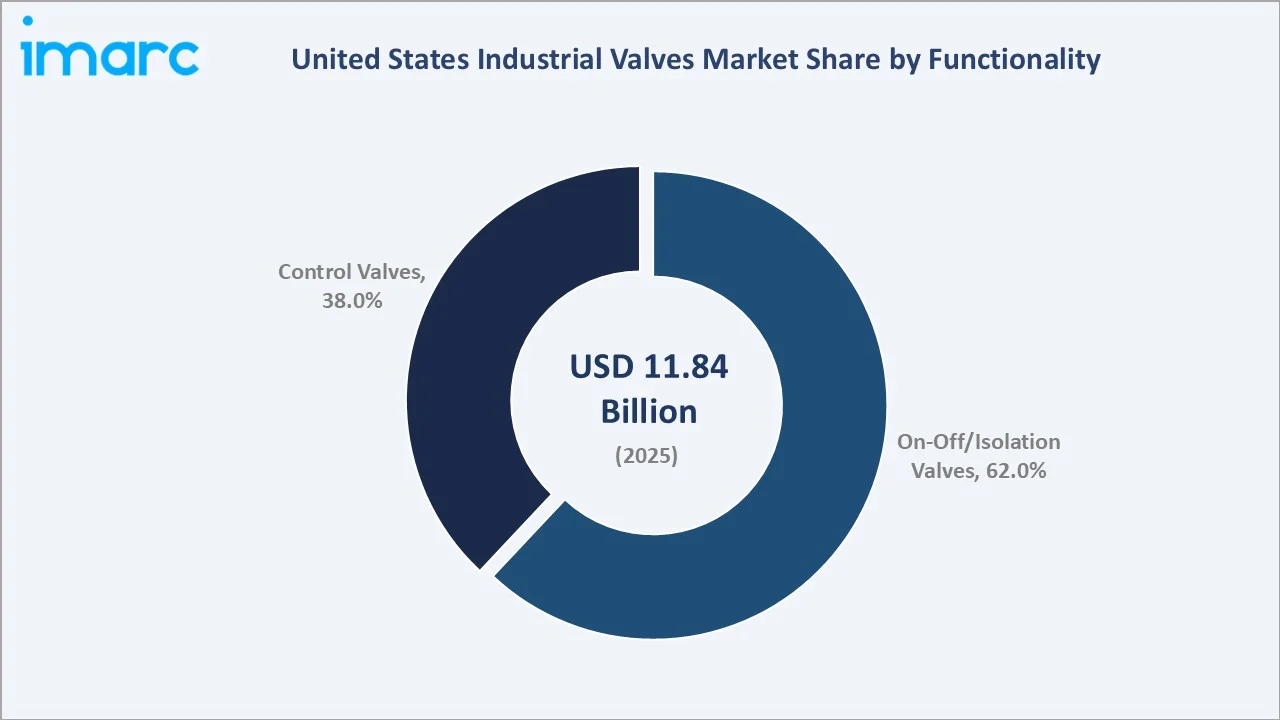
On-Off/Isolation Valves lead at 62.0% (2025). This segment encompasses the most commercially essential valve function, providing pipeline isolation, emergency shut-off, and maintenance isolation across oil and gas transmission, water distribution, chemical processing, and power generation applications. The installed base across US industrial infrastructure sustains consistent replacement and maintenance procurement above new project demand.
To access detailed market analysis, Request Sample
Control Valves at 38.0% represent the highest-technology segment, growing at ~3.6% CAGR through industrial automation investment, process optimization requirements, and digital valve system upgrades. Control valves serve precision flow regulation, pressure reduction, and temperature control applications across chemical, pharmaceutical, and power generation sectors.
By Material
Steel leads at 48.0% (2025). The steel segment serves the US industrial valve market's highest-pressure and highest-temperature service requirements across oil and gas, power generation, and chemical processing. Carbon steel and stainless steel valve bodies provide the strength, machinability, and weldability required for ASME and API pressure vessel compliance across critical service valve applications.
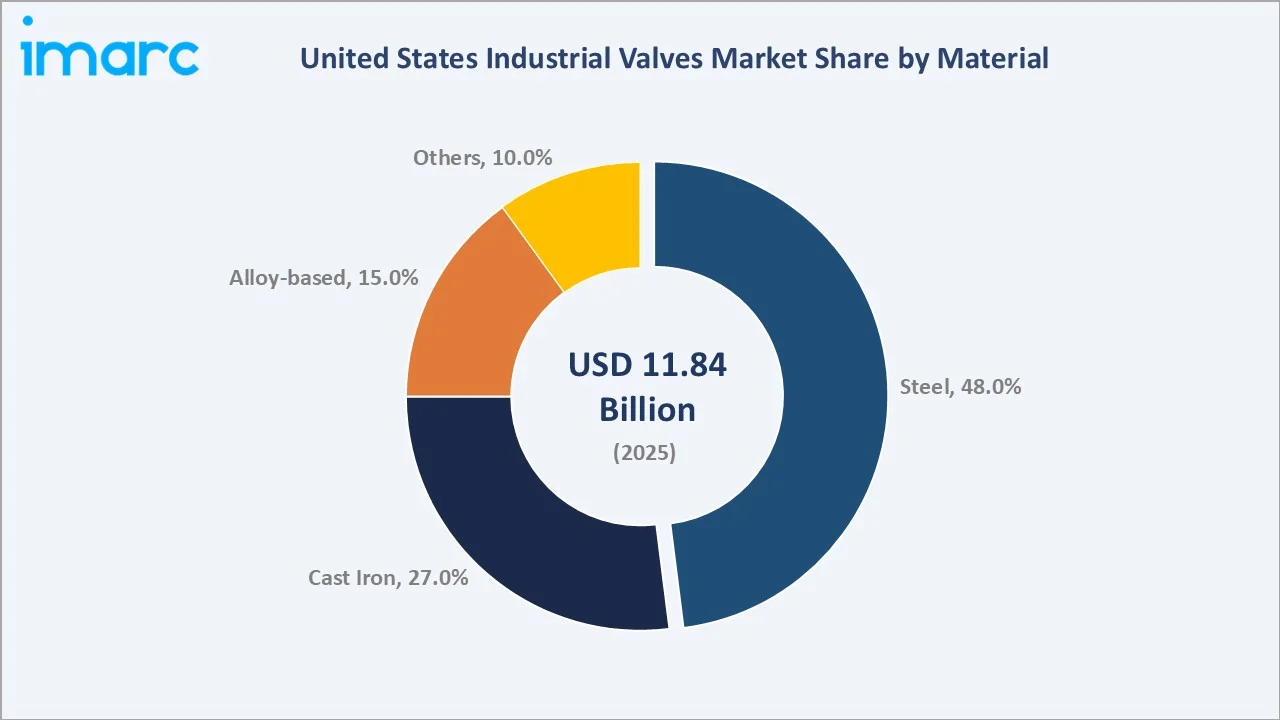
Cast Iron at 27.0% serves lower-pressure water, HVAC, and general industrial applications with cost-effective valve solutions. Alloy-based at 15.0% grows fastest at ~4.1% CAGR through high-performance requirements in corrosive and extreme-temperature service conditions. Others at 10.0% includes bronze, PVC, and specialty polymer valves for water, pharmaceutical, and chemical service.
Regional Market Insights
|
Region |
Share (2025) |
Key United States Industrial Valves Market Drivers & Characteristics |
|
South |
38.0% |
Driven by concentrated oil and gas production, refining, and petrochemical processing infrastructure in Texas, Louisiana, and Oklahoma. |
|
West |
27.0% |
Supporting widespread adoption of water infrastructure valves and process industry applications across California and Pacific states. |
|
Midwest |
20.0% |
Reflects manufacturing, chemical processing, and agricultural water management valve demand across the industrial heartland. |
|
Northeast |
15.0% |
Rising pharmaceutical, semiconductor, and water infrastructure investments are supporting premium valve segment growth. |
The South's 38.0% market leadership reflects Texas's oil and gas infrastructure concentration, Louisiana's refinery and petrochemical complex density, and Gulf Coast LNG export facility construction activity. The West's 27.0% reflects California's water infrastructure investment programs and Pacific states' manufacturing sector valve procurement.
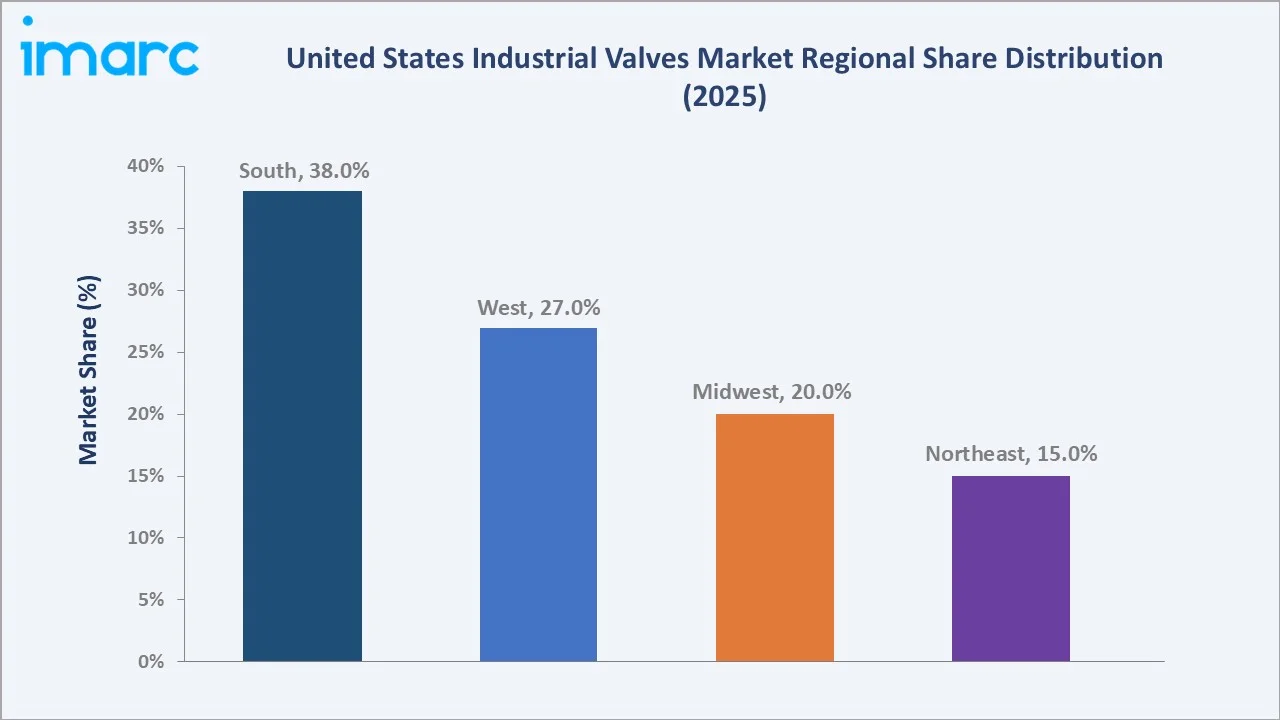
The Midwest's 20.0% reflects Illinois, Ohio, and Michigan's chemical processing, automotive, food and beverage manufacturing valve demand. The Northeast's 15.0% is growing in specialty valve applications, with pharmaceutical, semiconductor, and water infrastructure investments in Massachusetts, New Jersey, and New York creating demand for high-specification, high-purity, and precision control valve solutions.
Competitive Landscape
The US industrial valve market competitive landscape is technically differentiated by application specialization, certification compliance, and service network density. The premium segment creates a separate competitive structure. Competition is intensifying through smart valve technology integration, energy transition application development, and aftermarket service expansion.
|
Company |
Key Brands |
Market Position |
Core Strength |
|
Emerson Electric Co. |
Fisher, Bettis, Keystone, ASCO |
Market Leader |
Emerson Electric Co. is the dominant industrial valve and flow control technology provider in the US market, leading through its Fisher brand control valve portfolio and comprehensive automation solutions. |
|
Flowserve Corporation |
Durco, Edward Valves, Valves |
Strong Challenger |
Flowserve Corporation is a major player in the US industrial valve market, combining valve manufacturing, pump, and seal solutions for oil and gas, chemical, and power generation industries. |
|
Crane Co. |
Jenkins, Pacific Valves, Stockham |
Strong Challenger |
Crane Co. plays a significant role in the US industrial valve market through its diversified valve brand portfolio serving commercial, industrial, and specialty fluid control applications. |
|
Velan Inc. |
Valve |
Strong Challenger |
Velan Inc. serves the US industrial valve market through high-performance gate, globe, check, and ball valve product lines for oil and gas, power generation, and chemical processing. |
The competitive landscape's most commercially significant dynamic is the smart valve technology differentiation race, where leading players are investing in digital valve diagnostics, wireless communication, and IIoT integration capabilities to create service-based competitive moats, transforming traditional valve procurement relationships into long-term technology partnership contracts.
Key Company Profiles
Emerson Electric Co.
Emerson Electric Co. is the leading industrial automation and flow control technology company in the United States, with a dominant position in the industrial valve market through its Fisher brand control valve portfolio and Bettis actuator product line.
- Key Brands: Fisher, Bettis, Daniel, Keystone, ASCO, among others.
- Strategic Focus: Maintaining market leadership in the US industrial valve market through Fisher brand control valve dominance, digital valve technology integration, and expanding aftermarket service revenue through valve performance management contracts.
Flowserve Corporation
Flowserve Corporation is a recognized provider of flow control products and services, with a strong US industrial valve market presence through its diversified valve brand portfolio serving oil and gas, chemical, and power generation industries.
- Key Brands: Flowserve, Durco, Edward Valves, Vogt Valves.
- Strategic Focus: Leveraging integrated valve, pump, and seal portfolio and digital service capabilities to expand customer relationships in oil and gas, chemical, and power generation end markets.
Crane Co.
Crane Co. is a diversified industrial manufacturer with a strong US industrial valve market presence through its Crane Valve Group, serving commercial, industrial, and specialty fluid control applications.
- Key Brands: Crane, Jenkins, Pacific Valves, Stockham.
- Recent Developments: In 2025, Crane’s XOMOX, WTA and KROMBACH valves received TA-Luft 2021 certification for fugitive-emission control. The certification applies to valve products designed to meet stringent requirements for limiting fugitive emissions. The development is relevant to industrial valve applications in chemical processing, refining and other process industries, where leakage prevention and emissions control are important operating requirements.
- Strategic Focus: Maintaining competitive position through diversified valve application coverage, technical compliance in regulated industry sectors, and expanding aftermarket service capabilities across the installed valve base.
Market Concentration Analysis
The US industrial valve market is moderately concentrated at the premium technical segments, with Emerson Electric Co. commanding an estimated 18-22% of the US industrial control valve market by value through Fisher brand dominance, and moderately fragmented in standard commercial valve categories. The market's technical complexity and certification requirements create structural concentration pressure limiting new entrant participation in high-specification segments.
Market concentration is evolving through two opposing forces: leading players' smart valve technology investments creating above-product differentiation that sustains premium market positions; while standard commercial valve segment commoditization is increasing through import competition and independent distribution channel consolidation.
Investment & Growth Opportunities
Highest Growth Segments
Alloy-based valves (~4.1% CAGR through specialty application growth), Control Valves (~3.6% CAGR through industrial automation adoption), smart and intelligent valve systems (~6-8% CAGR from emerging technology base), hydrogen service valves (~12-15% CAGR through energy transition infrastructure), and water infrastructure valves (~4.5% CAGR through federal investment programs) represent the US industrial valve market's highest-growth investment vectors through 2034.
Emerging Investment Opportunities
The US hydrogen economy infrastructure development, growing at above-market CAGR from a small base, represents the highest-growth new application segment. The hydrogen valve market requires specialized technical capabilities in hydrogen-compatible materials and sealing technologies, creating barrier-to-entry protection for qualified valve manufacturers.
Investment Themes
- Smart valve technology platform investment for US process industry digital transformation: The US process industry's Industry 4.0 adoption creates a sustained investment opportunity in intelligent valve systems, digital positioners, and valve asset management software. Smart valve platforms command premium pricing and create long-term service revenue streams.
- Water infrastructure valve supply chain positioning for federal investment program capture: Multi-year federal water infrastructure investment programs represent a predictable, government-funded valve demand stream. Valve manufacturers and distributors with established relationships with major municipal utilities and infrastructure contractors are best positioned to capture this structured procurement opportunity.
Future Market Outlook (2026-2034)
The US industrial valve market is projected to grow from USD 11.84 Billion in 2025 to USD 12.24 Billion in 2026, reaching USD 16.07 Billion by 2034, registering a CAGR of 3.35% during 2026-2034. The market's anchor value of USD 13.96 Billion in 2030 represents a structural technology transition, where smart valve systems, energy transition applications, and water infrastructure modernization become primary growth drivers alongside traditional oil and gas infrastructure maintenance.
Three structural forces define US industrial valve market growth through 2034: the energy transition creating new hydrogen, carbon capture, and renewable energy valve application segments; federal infrastructure investment programs sustaining water and wastewater treatment valve demand through multi-year procurement cycles; and industrial automation adoption transforming valve procurement from component purchasing to intelligent system investment.
Research Methodology
Primary Research
Primary research comprised structured interviews with US industrial valve industry stakeholders, including Procurement Directors, Plant Managers, Valve Specification Engineers, EPC project managers, MRO procurement specialists, and industrial distributor representatives across South, West, Midwest, and Northeast US regions, covering oil and gas, water, chemical, and power generation end users.
Secondary Research
Secondary research encompassed US industrial production data, pipeline infrastructure statistics, EPA and DOT regulatory publications, company annual reports, industrial valve trade association publications, investor presentations, and infrastructure investment program documentation. Over 50 secondary sources reviewed.
Forecasting Models
Market revenue forecasts were developed using an end-user sector capital expenditure model: US industrial production by sector multiplied by valve intensity ratios and average procurement value per installation, creating total market revenue by segment aggregation. Infrastructure investment program multiplier applied across water and pipeline segments.
United States Industrial Valves Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical and Forecast Trends, Industry Catalysts and Challenges, Segment-Wise Historical and Predictive Market Assessment:
|
| Product Types Covered | Gate Valve, Globe Valve, Butterfly Valve, Ball Valve, Check Valve, Plug Valve, Others |
| Functionalities Covered | On-Off/Isolation Valves, Control Valves |
| Materials Covered | Steel, Cast Iron, Alloy Based, Others |
| Sizes Covered | Up to 1”, 1”-6”, 7”-25”, 26”-50”, 51” and Above |
| End Use Industries Covered | Oil and Gas, Power, Pharmaceutical, Water and Wastewater Treatment, Chemical, Food and Beverage, Others |
| Regions Covered | Northeast, Midwest, South, West |
| Companies Covered | Emerson Electric Co., Flowserve Corporation, Crane Co., Velan Inc., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the United States industrial valves market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the United States industrial valves market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the United States industrial valves industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the United States Industrial Valves Market Report
The US industrial valve market size is estimated at USD 12.24 Billion in 2026, driven by expanding oil and gas infrastructure, aging pipeline replacement programs, and growing federal investments in water and wastewater treatment modernization. Industrial automation adoption and smart valve technology integration are further supporting market expansion.
The US industrial valve market grows at 3.35% CAGR during 2026-2034, reaching USD 16.07 Billion by 2034. Overall growth is sustained by infrastructure replacement demand, energy transition application development, industrial automation investment, and federal water infrastructure program funding.
On-Off/Isolation Valves lead at 62.0% through the dominant requirement for pipeline isolation, emergency shut-off, and maintenance isolation across oil and gas, water distribution, and chemical processing applications. The extensive installed base ensures sustained replacement procurement above new project demand.
Steel leads at 48.0% through the dominant requirement for high-pressure, high-temperature service across oil and gas, power generation, and chemical processing applications. Carbon steel and stainless-steel valve bodies provide ASME and API compliance capability required for critical service valve procurement.
The South leads at 38.0% through Texas's oil and gas infrastructure concentration, Louisiana's refinery and petrochemical complex density, and Gulf Coast LNG export facility construction driving the highest regional valve procurement volume.
Leading companies include Emerson Electric Co., Flowserve Corporation, Crane Co. and Velan Inc, among others.
The US industrial valve market is projected to reach approximately USD 13.96 Billion by 2030, with smart valve technology adoption creating premium product mix improvement, energy transition infrastructure driving new application segment development, and federal water infrastructure investments sustaining structured procurement growth.
Three priority investment opportunities: smart valve technology platform development for US process industry digital transformation, water infrastructure valve supply chain positioning for federal investment program capture, and hydrogen service valve technical capability development for energy transition infrastructure applications.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade