
United States Plant Based Protein Market Size, Share, Trends and Forecast by Source, Type, Nature, Application, and Region, 2026-2034
United States Plant Based Protein Market Size, Share, Trends & Forecast (2026-2034)
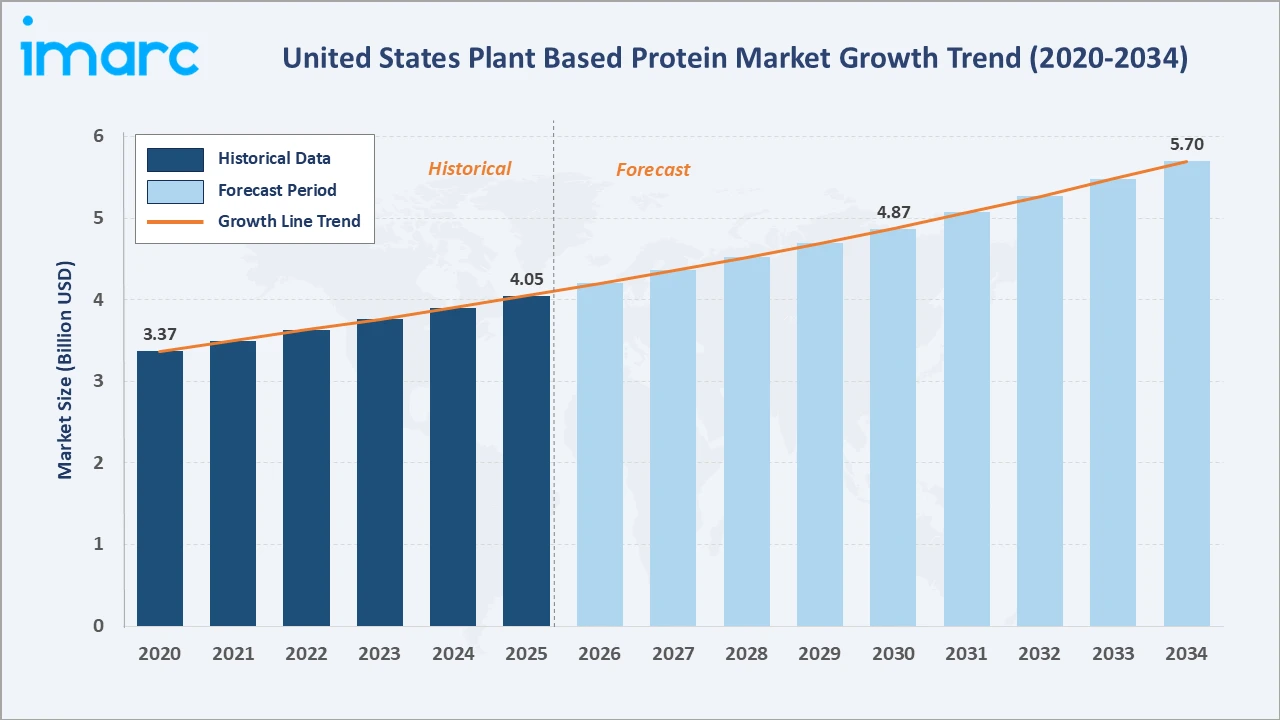
The United States plant based protein market grew from USD 4.05 Billion in 2025 to USD 4.20 Billion in 2026 and is projected to reach USD 5.70 Billion by 2034, growing at a CAGR of 3.76% during 2026-2034. Rising interest in high-protein diets, flexitarian eating, and sustainable food choices continue to support demand. ADM notes that 66% of consumers globally look to increase their protein intake, with soy and pea proteins key drivers of this shift.
Ongoing ingredient innovation, clean-label reformulation, and use in hybrid meat and dairy alternative products continue to broaden the plant-based protein market in the US. Soy dominates sources at 42.5%. Concentrates lead types at 42.5%. The West commands 36.5% of national market share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 4.05 Billion |
|
Market Size (2026) |
USD 4.20 Billion |
|
Forecast Market Size (2034) |
USD 5.70 Billion |
|
CAGR (2026-2034) |
3.76% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Source |
Soy (42.5%, 2025) |
|
Dominant Type |
Concentrates (42.5%, 2025) |
|
Leading Region |
West (36.5%, 2025) |
The US plant based protein market size increased from USD 3.37 Billion in 2020 to USD 4.05 Billion in 2025 and is estimated to reach USD 4.20 Billion in 2026. The market is further expected to grow to USD 4.87 Billion by 2030 and USD 5.70 Billion by 2034. Growth reflects steady adoption across meat alternatives, dairy alternatives, beverages, bars, and sports nutrition.
To get more information on this market, Request Sample
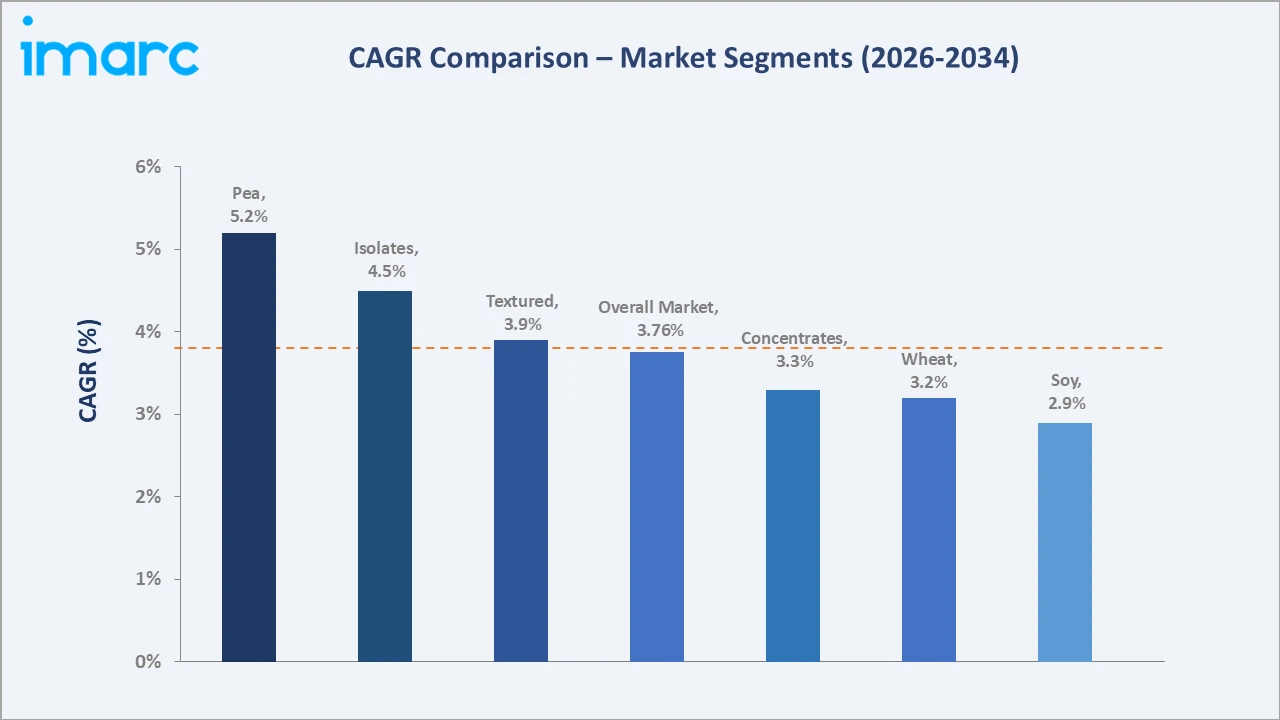
Pea protein is expected to grow fastest at ~5.2% CAGR, supported by allergen-friendly positioning and improved taste. Isolates follow at ~4.5% CAGR as beverage, nutrition, and dairy alternative brands seek high-protein, clean-tasting ingredients.
Executive Summary
The United States plant based protein market expanded from USD 4.05 Billion in 2025 to an estimated USD 4.20 Billion in 2026. After rapid growth and a period of correction in plant-based meat, demand is shifting toward functional ingredients used in high-protein foods, beverages, nutrition products, and hybrid meat products. Ingredient suppliers are launching cleaner-tasting isolates, textured proteins, and new sources to meet formulator needs. The market is projected to reach USD 5.70 Billion by 2034. Soy at 42.5% leads sources. Concentrates at 42.5% lead types. The West leads regionally at 36.5%.
Key Market Insights
|
Insight |
Data |
|
Dominant Source |
Soy - 42.5% share (2025) |
|
Dominant Type |
Concentrates - 42.5% market share (2025) |
|
Leading Region |
West - 36.5% share (2025) |
|
Market Opportunity |
Clean-tasting pea isolates; hybrid meat and dairy products; sports and medical nutrition; fermentation-derived and novel plant proteins |
Key Analytical Observations Supporting the Above Data:
- Soy at 42.5%: Soy dominates because it offers a complete amino acid profile, strong functionality, large domestic supply, and cost advantages. Soy protein is widely used in meat alternatives, meat extension, bakery, beverages, and nutrition products.
- Concentrates at 42.5%: Concentrates lead because they provide good protein content and functionality at lower cost than isolates, making them suitable for meat extension, bakery, snacks, and processed foods.
- West at 36.5%: The West leads regionally due to strong health and sustainability awareness, a high concentration of plant-based food brands, and early consumer adoption in California, Washington, and Oregon.
United States Plant Based Protein Market Overview
Plant based proteins are derived from sources such as soy, pea, wheat, rice, fava bean, and chickpea. They are processed into concentrates, isolates, and textured forms and used in meat and dairy alternatives, protein beverages, bars, bakery, snacks, and sports and medical nutrition. Plant proteins serve both as primary protein sources and as functional ingredients that improve texture, emulsification, and water binding.
The industry ecosystem links crop growers, protein processors, technology partners, food and beverage manufacturers, regulators, retailers, foodservice operators, and consumers. Macroeconomic factors include crop prices, consumer spending, health trends, and food innovation investment, all of which shape demand. Federal dietary guidance and growing scientific evidence on plant-based diets also influence consumer choices.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
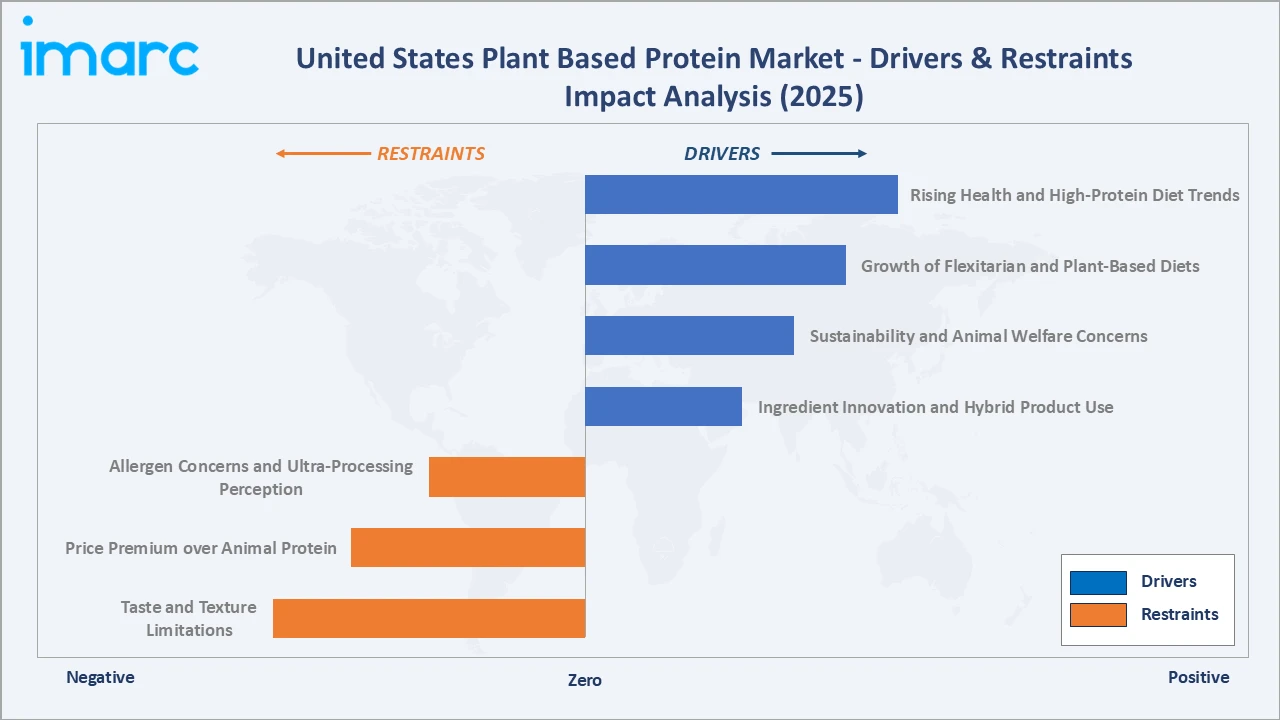
- Rising Health and High-Protein Diet Trends: Consumers are seeking more protein in their diets for muscle health, weight management, satiety, and healthy aging. High-protein beverages, bars, snacks, and fortified foods increasingly use plant proteins alongside or instead of dairy proteins, expanding demand beyond traditional meat alternatives. Growing interest in fitness, active lifestyles, and healthy aging is broadening the consumer base for protein products across age groups. Weight management trends, including the use of GLP-1 medications, are also increasing demand for protein-dense foods that help preserve muscle mass while reducing overall calorie intake. Protein claims on packaging have become a major purchase driver, encouraging brands to add plant proteins to everyday foods such as pasta, cereals, and snacks. E-commerce and direct-to-consumer brands have made protein powders and specialty products widely accessible across the country.
- Growth of Flexitarian and Plant-Based Diets: A growing number of Americans are reducing meat and dairy consumption without fully eliminating animal products. Flexitarian consumers buy plant-based milks, yogurts, meat alternatives, and protein products regularly, supporting steady ingredient demand across retail and foodservice. Younger consumers in particular are open to trying new protein sources and formats. Restaurants, schools, and corporate cafeterias are adding plant-based options to menus, creating demand for versatile ingredients that can be used in many dishes. Plant-based dairy alternatives, including oat, soy, and pea milks, remain well established in household routines. Plant-based options are also expanding in convenience stores and quick-service restaurant chains.
- Sustainability and Animal Welfare Concerns: Concerns about greenhouse gas emissions, land and water use, and animal welfare encourage consumers and food companies to include more plant proteins. Many brands have sustainability targets that favor plant-based ingredients in new product development. Retailers and foodservice companies are also setting targets to increase plant-based offerings. Life cycle assessments that show lower emissions for plant proteins support marketing claims and procurement decisions. Investors and corporate buyers increasingly consider environmental impact when choosing protein ingredients. Consumers increasingly look for certifications such as non-GMO and organic when buying plant-based products.
- Ingredient Innovation and Hybrid Product Use: Suppliers are launching cleaner-tasting isolates, improved textured proteins, and new sources such as fava bean and chickpea. Hybrid meat products that blend plant and animal proteins are opening new applications and volumes for plant protein ingredients. Ingredient companies are also offering application support to help manufacturers reformulate products quickly. Partnerships between suppliers and food brands are accelerating the development of better-tasting and more affordable products. Advances in processing are also lowering production costs, helping close the price gap with animal proteins. Domestic processing capacity for pea and other pulses has expanded significantly over the past decade.
Market Restraints
- Taste and Texture Limitations: Some plant proteins have beany or earthy flavors and textures that differ from animal proteins. Achieving the right taste and mouthfeel can require masking agents and complex formulations, limiting repeat purchases of some plant-based products. Improving taste remains the most important factor in winning back consumers who tried plant-based products but did not continue buying them. Ingredient suppliers are investing heavily in flavor research and processing improvements to address this challenge. Texture remains a particular challenge in whole-cut meat alternatives and cheese analogues. Ongoing research into fermentation and enzyme technologies is helping address these limitations.
- Price Premium over Animal Protein: Many plant-based meat and dairy alternatives remain more expensive than conventional products. Price-sensitive consumers may limit purchases, slowing growth in retail categories. Higher processing costs for isolates and specialty proteins also add to finished product prices. Inflation in food prices has made consumers more cautious about paying premiums for alternative products. Retail promotions and private label products are helping make plant-based foods more affordable. Larger production volumes are also expected to lower costs over the forecast period. Value-oriented product lines are also helping attract budget-conscious households to plant-based options. Bulk foodservice formats and private label ranges are further expanding access to affordable plant protein products across the country.
- Allergen Concerns and Ultra-Processing Perception: Soy and wheat are major allergens, and some consumers view plant-based foods as highly processed. These perceptions can reduce appeal among health-focused buyers. Clean-label formulations and transparent ingredient lists are increasingly important to address these concerns. Communicating nutritional benefits clearly can help overcome negative perceptions about processing. Pea and other non-allergen proteins are gaining share partly because of these concerns.
Market Opportunities
- Sports, Medical, and Healthy Aging Nutrition: Demand for protein supplements, ready-to-drink beverages, and medical nutrition products creates opportunities for high-quality plant protein isolates and blends. Plant proteins that are easy to digest and free from major allergens are particularly attractive for these applications. Partnerships with sports nutrition and healthcare brands can help suppliers reach these growing segments. Aging populations are also increasing demand for easy-to-digest protein in clinical and senior nutrition.
- Novel Sources and Fermentation Technologies: Fava bean, chickpea, mung bean, and fermentation-derived proteins offer new functional and nutritional profiles, supporting product differentiation. These sources can also reduce dependence on soy and pea and improve supply chain resilience. Early-stage companies are actively commercializing these ingredients with support from investors and larger partners. Regulatory approvals and consumer education will be important for wider adoption of novel proteins.
Market Challenges
- Supply Chain and Crop Price Volatility: Weather, trade policies, and crop prices can affect the availability and cost of soy, pea, and other protein crops, impacting ingredient pricing. Diversifying sourcing and investing in domestic processing can help reduce these risks. Long-term contracts with growers also help stabilize supply and pricing for processors. Climate-related weather events can also affect crop quality and protein content, adding to sourcing complexity.
- Slowing Plant-Based Meat Sales: Retail sales of plant-based meat have softened in recent years, requiring brands and suppliers to focus on taste, value, and new applications. Ingredient suppliers are therefore expanding into beverages, nutrition, bakery, and hybrid products to sustain growth. Brands are also repositioning products around taste, protein content, and value rather than meat replacement alone. Innovation in taste and texture is expected to help stabilize and grow plant-based meat sales over time.
Emerging Market Trends
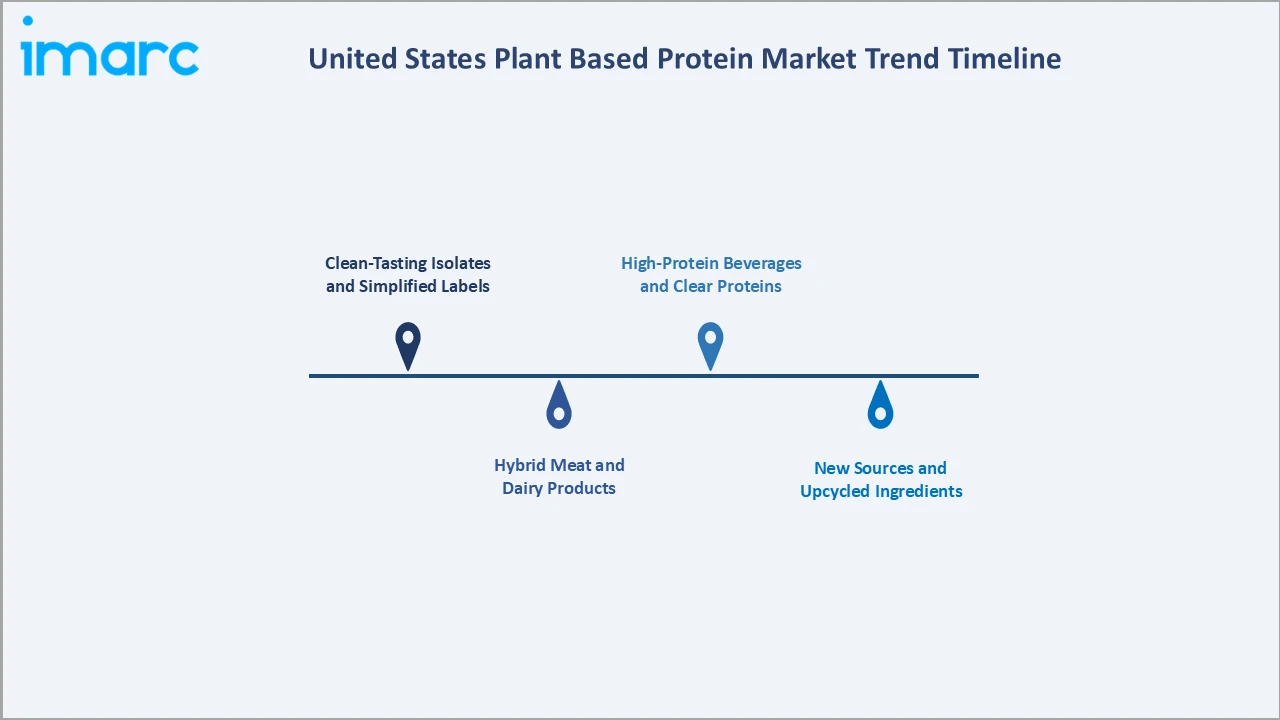
1. Clean-Tasting Isolates and Simplified Labels
Suppliers are introducing pea and other plant protein isolates with neutral taste and smooth texture that can be labeled simply. These ingredients reduce the need for flavor maskers and support clean-label beverages, dairy alternatives, and nutrition products. Improved taste is helping brands increase protein content without compromising flavor, supporting repeat purchases. Simplified labels also appeal to consumers who prefer recognizable ingredients. Sports nutrition brands are increasingly using pea and blended plant proteins in powders and drinks.
2. Hybrid Meat and Dairy Products
Food manufacturers are combining plant proteins with meat or dairy to improve nutrition, cost, and sustainability while keeping familiar taste. Hybrid products are attracting mainstream consumers who are not ready to switch fully to plant-based foods. Foodservice operators are using hybrid products to reduce costs and meet sustainability goals without changing menus significantly. Blended burgers, sausages, and dairy products are increasingly available in retail stores. Hybrid products can deliver familiar taste while reducing saturated fat and environmental impact.
3. High-Protein Beverages and Clear Proteins
Ready-to-drink protein shakes, clear protein drinks, and protein-fortified coffee and snacks are expanding uses of plant proteins. Hydrolyzed and highly soluble proteins support lighter, refreshing formats. Plant proteins are also appearing in savory snacks, cereals, and baked goods, expanding everyday consumption occasions. Clear protein beverages appeal to consumers seeking lighter alternatives to traditional shakes. Protein bars and snack bites using plant proteins continue to grow in convenience channels.
4. New Sources and Upcycled Ingredients
Brands are exploring fava bean, chickpea, potato, canola, and upcycled proteins from food processing side streams. These sources diversify supply and offer unique functional and sustainability benefits. Regenerative agriculture and traceable sourcing programs are also gaining attention among sustainability-focused brands. Upcycled ingredients help reduce food waste and support circular economy goals. Potato, canola, and sunflower proteins are also being developed as functional alternatives for specific applications. Collaboration between universities, startups, and established suppliers is accelerating the commercialization of these new ingredients.
Industry Value Chain Analysis
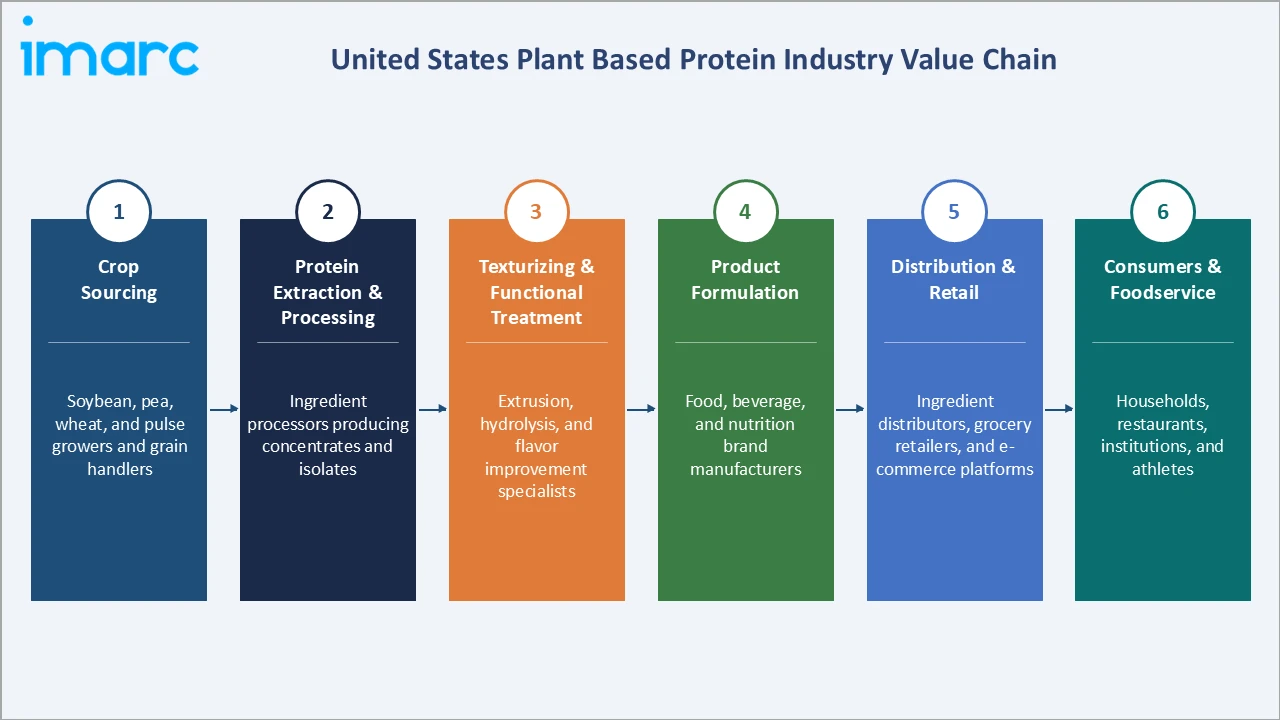
The United States plant based protein value chain spans crop sourcing, protein extraction and processing, texturizing and functional treatment, product formulation, distribution and retail, and consumers and foodservice. Value is concentrated in processing technology and application expertise. Strong relationships between suppliers and food manufacturers are essential for developing successful products. Distribution and retail partners also influence product visibility and consumer access.
|
Stage |
Key Participants |
|
Crop Sourcing |
Soybean, pea, wheat, and pulse growers and grain handlers |
|
Protein Extraction & Processing |
Ingredient processors producing concentrates and isolates |
|
Texturizing & Functional Treatment |
Extrusion, hydrolysis, and flavor improvement specialists |
|
Product Formulation |
Food, beverage, and nutrition brand manufacturers |
|
Distribution & Retail |
Ingredient distributors, grocery retailers, and e-commerce platforms |
|
Consumers & Foodservice |
Households, restaurants, institutions, and athletes |
Protein extraction and processing is the most consequential stage of the chain. Processing technology determines protein purity, taste, functionality, and cost, giving suppliers with advanced facilities and application expertise a strong advantage. Product formulation is also critical, as manufacturers must balance taste, texture, nutrition, and cost to win consumers. Technical support and co-development services are increasingly important differentiators for suppliers. Packaging, branding, and clear nutrition claims also play an important role in consumer acceptance of plant protein products.
Technology Landscape in the United States Plant Based Protein Industry
Wet and Dry Fractionation
Wet extraction produces high-purity isolates, while dry fractionation creates concentrates with lower energy and water use. Improvements in both processes are raising quality and reducing costs. Air classification and membrane filtration technologies are also improving efficiency and protein recovery. Process innovation helps improve taste and reduce environmental impact at the same time.
Extrusion and Texturization
High- and low-moisture extrusion transform plant proteins into fibrous textures that mimic meat. Advanced extrusion enables whole-cut and chunk formats with better bite and juiciness. Shear cell technology and 3D printing are emerging tools for creating more realistic textures. Extruded proteins are widely used in foodservice for burgers, nuggets, and ground meat alternatives.
Flavor Improvement, Hydrolysis, and Fermentation
Enzymatic hydrolysis, fermentation, and flavor removal technologies reduce off-flavors and improve solubility. Precision and biomass fermentation are emerging as complementary sources of high-quality protein. Digital tools and artificial intelligence are also being used to screen ingredients and optimize formulations. Combining multiple proteins also helps balance amino acids, taste, and texture.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Source | Soy | 42.5% | 2025 |
| Type | Concentrates | 42.5% | 2025 |
| Nature | 🔒 | 🔒 | 2025 |
| Application | 🔒 | 🔒 | 2025 |
| Region | West | 36.5% | 2025 |

By Source
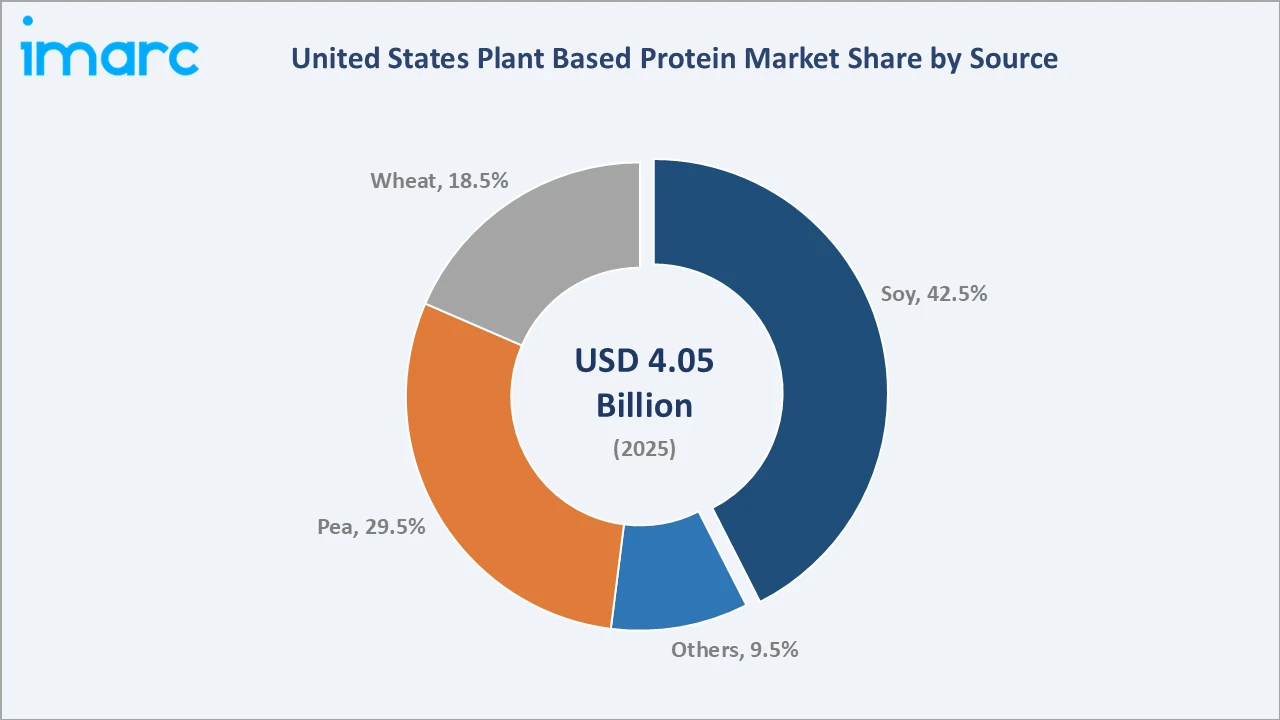
Soy leads at 42.5% (2025). Its complete amino acid profile, strong functionality, abundant domestic supply, and cost competitiveness make it the most widely used plant protein in US food manufacturing. Soy protein concentrates and isolates are widely used in meat extension, bakery, and nutrition products.
To access detailed market analysis, Request Sample
Pea at 29.5% is growing fastest at ~5.2% CAGR, supported by allergen-friendly positioning. Wheat at 18.5% is growing at ~3.2%, and others at 9.5%, including rice, fava bean, and chickpea, are growing at ~4.8%. Pea protein growth is supported by new isolates with improved taste and solubility. Wheat protein remains important in bakery and meat alternative applications for its elasticity and binding properties.
By Type
Concentrates lead at 42.5% (2025). They offer good protein content and functionality at a lower cost than isolates, making them popular in meat extension, bakery, snacks, and processed foods.
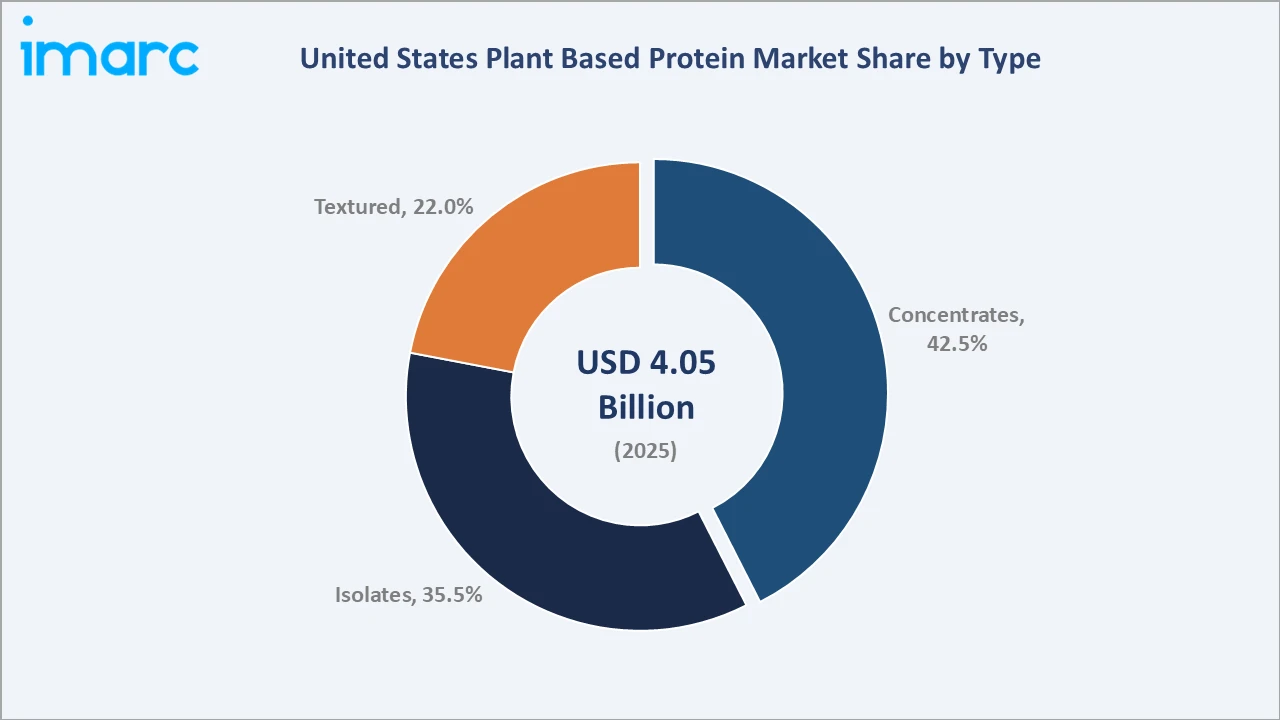
Isolates at 35.5% are growing at ~4.5% CAGR, driven by beverages and nutrition products. Textured proteins at 22.0% are growing at ~3.9%, supported by meat alternatives and hybrid products. Textured proteins are increasingly used in foodservice and prepared meals as well as retail products. Isolates are favored in beverages and nutrition products for their high protein content and smooth texture.
Regional Market Insights
|
Region |
Share (2025) |
Key United States Plant Based Protein Market Drivers & Characteristics |
|
West |
36.5% |
Strong health and sustainability awareness and many plant-based brands in California. |
|
South |
27.5% |
Large population, growing flexitarian demand, and food manufacturing in Texas and Florida. |
|
Midwest |
21.5% |
Soybean and pea production base and major protein processing facilities. |
|
Northeast |
14.5% |
Urban consumers and strong retail and foodservice demand in New York and Boston. |
The West's 36.5% market leadership reflects strong health and sustainability awareness, a large number of plant-based food brands, and early consumer adoption. The South's 27.5% reflects a large and growing population and expanding food manufacturing.
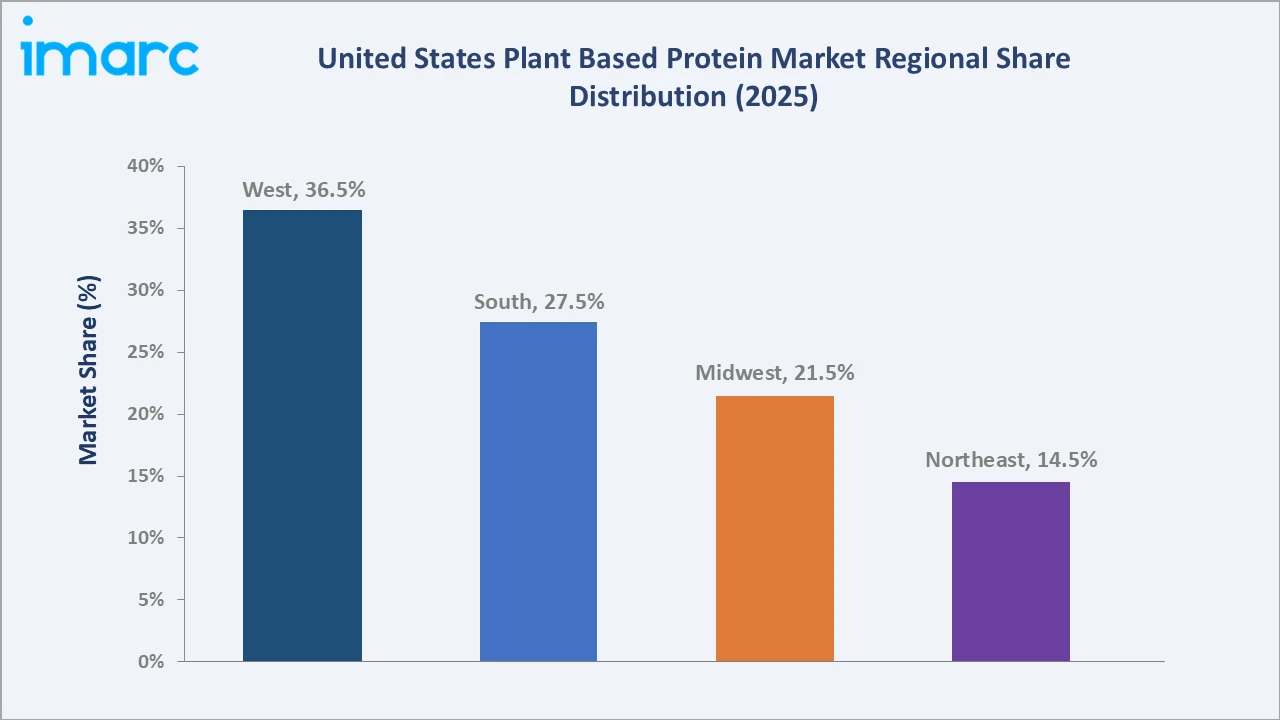
The Midwest's 21.5% reflects its crop production base and major processing facilities. The Northeast's 14.5% is the smallest share, but strong urban demand and foodservice adoption support steady growth. Retailers and restaurants in major cities continue to expand plant-based offerings in the region. The Midwest also benefits from investments in new processing facilities close to raw material supply.
Competitive Landscape
The US plant based protein market includes large agribusiness and ingredient companies, specialized plant protein producers, and emerging technology firms. Competition centers on protein quality, taste, functionality, supply security, pricing, and application support. Many suppliers operate innovation centers to help customers develop new products faster. Long-term supply agreements with large food brands are a key source of competitive advantage. Smaller suppliers often compete by focusing on specific sources, organic certification, or specialized processing methods. Strategic investments in new processing plants and application centers are expected to continue as suppliers position themselves for long-term demand growth.
| Company | Key Brands | Market Position | Core Strength |
|---|---|---|---|
| ADM | ProFam, Arcon, TVP | Market Leader | Broad soy and pea protein portfolio with decades of experience. |
| Roquette Frères | NUTRALYS | Market Leader | Leading pea protein producer with large-scale capacity. |
| Puris | Puris pea protein, H2-IZO, ClearP | Innovator | US-grown pea protein with vertical integration. |
| Bunge | PurePro, Response, Alpha, and Procon | Strong Challenger | Global oilseed processing and supply chain scale. |
| Kerry Group plc | TexFlex, Plantfare, Plenti | Innovator | Taste and nutrition expertise for formulation. |
| The Scoular Company | Chickpea Protein, Faba Protein, Mung Bean Protein | Strong Challenger | Ingredient sourcing and supply chain network. |
| Burcon | Pea Protein, Fava Protein, Sunflower Protein | Niche Player | Specialty protein processing technologies. |
The most important competitive dynamic is the race to improve taste and functionality while keeping costs competitive. Suppliers with strong application labs, diverse sources, and reliable supply are best placed to win customers in the us plant-based protein market.
Key Company Profiles
ADM
ADM’s work in plant-based proteins dates back to the 1960s, when it introduced the world’s first textured vegetable protein, and it offers soy and pea protein ingredients for food and beverage manufacturers.
- Key Brands: ProFam, Arcon, TVP.
- Recent Developments: In May 2026, ADM launched eight new soy and pea protein ingredients in North America and Europe, including ProFam soy protein isolates, Arcon soy protein concentrates, and a pea flour.
- Strategic Focus: Expanding regionally sourced plant proteins for meat extension, hybrid products, and dairy alternatives.
Roquette Frères
Roquette opened the world’s largest pea protein plant in Canada in 2021 and supplies NUTRALYS plant proteins to food manufacturers across North America.
- Key Brands: NUTRALYS pea, wheat, and fava bean proteins.
- Recent Developments: In February 2026, Roquette launched NUTRALYS Pea 850F, a pea protein isolate with a more neutral taste for plant-based formulations.
- Strategic Focus: Expanding its NUTRALYS portfolio for plant-based, hybrid, and high-protein foods and beverages.
Puris
Puris cultivates plant-based foods and ingredients from US-based organic and non-GMO sources, specializing in pea protein, pea starch, and pea fiber.
- Key Brands: Puris pea protein, H2-IZO, ClearP.
- Recent Developments: In 2026, Puris launched H2-IZO, a pea protein designed for high-protein beverages and dairy alternatives with a smoother, lighter sensory experience.
- Strategic Focus: Expanding into new formats, including ClearP hydrolyzed pea protein launched in March 2026 for beverages, confections, and snacks.
Market Concentration Analysis
The US plant based protein market is moderately concentrated, with large agribusiness and ingredient companies holding significant shares in soy and pea proteins. Specialized producers and technology startups compete in niche sources and premium applications.
Market concentration is evolving through two opposing forces: leading suppliers expand portfolios and capacity, while new sources and fermentation technologies attract new entrants. Acquisitions and partnerships are also shaping the competitive landscape as companies seek new technologies and capacity. Price competition is intense in commodity soy concentrates but less so in specialty isolates.
Investment & Growth Opportunities
Highest Growth Segments
Pea (~5.2% CAGR through allergen-friendly demand), others (~4.8% CAGR through novel sources), isolates (~4.5% CAGR through beverages and nutrition), and the West (~4.1% CAGR through early adoption) represent the highest-growth investment areas in the united states plant based protein market through 2034.
Emerging Investment Opportunities
Clean-tasting isolates and hybrid product ingredients are among the most promising opportunities, enabling broader use of plant proteins in mainstream foods and beverages. Investments in domestic processing capacity and application centers also offer strong returns.
Investment Themes
- Domestic pea and pulse processing: Local capacity improves supply security and traceability.
- Fermentation and novel proteins: New technologies offer differentiated taste and nutrition.
Future Market Outlook (2026-2034)
The US plant based protein market is projected to grow from USD 4.05 Billion in 2025 to USD 4.20 Billion in 2026, reaching USD 5.70 Billion by 2034, registering a CAGR of 3.76% during 2026-2034. The anchor value of USD 4.87 Billion in 2030 marks a point at which hybrid and high-protein products should be mainstream. By then, new protein sources and fermentation-based ingredients should also be widely available.
Three structural forces define plant based protein market in the US growth through 2034: rising high-protein consumption; flexitarian and sustainable diets; and continuous ingredient innovation. Together, these forces support steady growth across sources, types, and regions over the forecast period.
Research Methodology
Primary Research
Primary research comprised structured interviews with industry stakeholders, including ingredient suppliers, food and beverage manufacturers, distributors, nutritionists, and retailers across all US regions.
Secondary Research
Secondary research covered company websites and press releases, USDA data, trade publications, and industry reports. Over 50 credible secondary sources were reviewed, compared, and cross-checked for accuracy and consistency across datasets.
Forecasting Models
Market revenue forecasts were developed using a demand-based model: protein ingredient volumes by application and region multiplied by average prices for each source and type, with segment results aggregated to total market value. Assumptions were validated through detailed discussions with experienced industry experts, ingredient suppliers, and food manufacturers, distributors, and retail buyers across all major regions of the United States.
United States Plant Based Protein Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Sources Covered | Soy, Wheat, Pea, Others |
| Types Covered | Concentrates, Isolates, Textured |
| Natures Covered | Conventional, Organic |
| Applications Covered |
|
| Regions Covered | Northeast, Midwest, South, West |
| Companies Covered | ADM, Roquette Frères, Puris, Bunge, Kerry Group plc, The Scoular Company, Burcon, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the United States plant based protein market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the United States plant based protein market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the United States plant based protein industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the United States Plant Based Protein Market Report
The us plant based protein market size is estimated at USD 4.20 Billion in 2026, supported by high-protein and flexitarian diet trends.
The market grows at 3.76% CAGR during 2026-2034, reaching USD 5.70 Billion by 2034.
Soy leads at 42.5%, owing to its complete amino acid profile and cost advantages.
Concentrates lead at 42.5%, offering good functionality at lower cost.
The West leads at 36.5%, driven by strong health and sustainability awareness.
Leading companies include ADM, Roquette Frères, Puris, Bunge, Kerry Group plc, The Scoular Company, and Burcon, among others.
The market is projected to reach approximately USD 4.87 Billion by 2030.
Key trends include clean-tasting isolates, hybrid products, high-protein beverages, and new protein sources.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade