
United States Wine Market Size, Share, Trends and Forecast by Product Type, Color, Distribution Channel, and Region, 2026-2034
United States Wine Market Size, Share, Trends & Forecast (2026-2034)
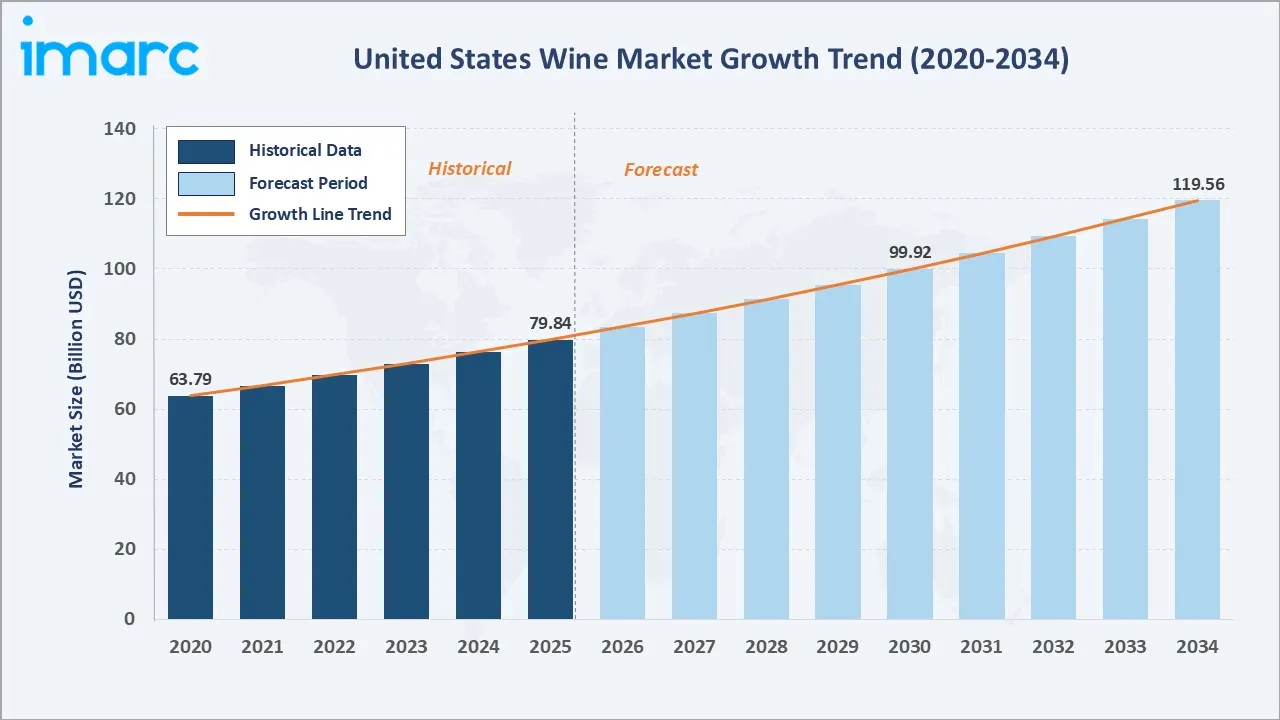
The United States wine market grew from USD 79.84 Billion in 2025 to USD 83.50 Billion in 2026 and is projected to reach USD 119.56 Billion by 2034, growing at a CAGR of 4.59% during 2026-2034. Market growth is driven by the rising consumer preference for premium and craft wines, expanding direct-to-consumer (DTC) sales channels, and growing wine tourism across key viticultural regions. Still wine leads with a 71.6% product type share, red wine commands 47.8% by color, and the South region holds the largest regional share at 28.6% in 2025.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 79.84 Billion |
|
Market Size (2026) |
USD 83.50 Billion |
|
Forecast Market Size (2034) |
USD 119.56 Billion |
|
CAGR (2026-2034) |
4.59% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Product Type |
Still Wine (71.6%, 2025) |
|
Dominant Color |
Red Wine (47.8%, 2025) |
|
Leading Region |
South (28.6%, 2025) |
The United States wine market grew from USD 63.79 Billion in 2020 to USD 79.84 Billion in 2025, and further to USD 83.50 Billion in 2026, reflecting consistent demand across premium, table, and sparkling wine categories. The market is projected to reach USD 99.92 Billion by 2030 before reaching USD 119.56 Billion by 2034.
To get more information on this market, Request Sample
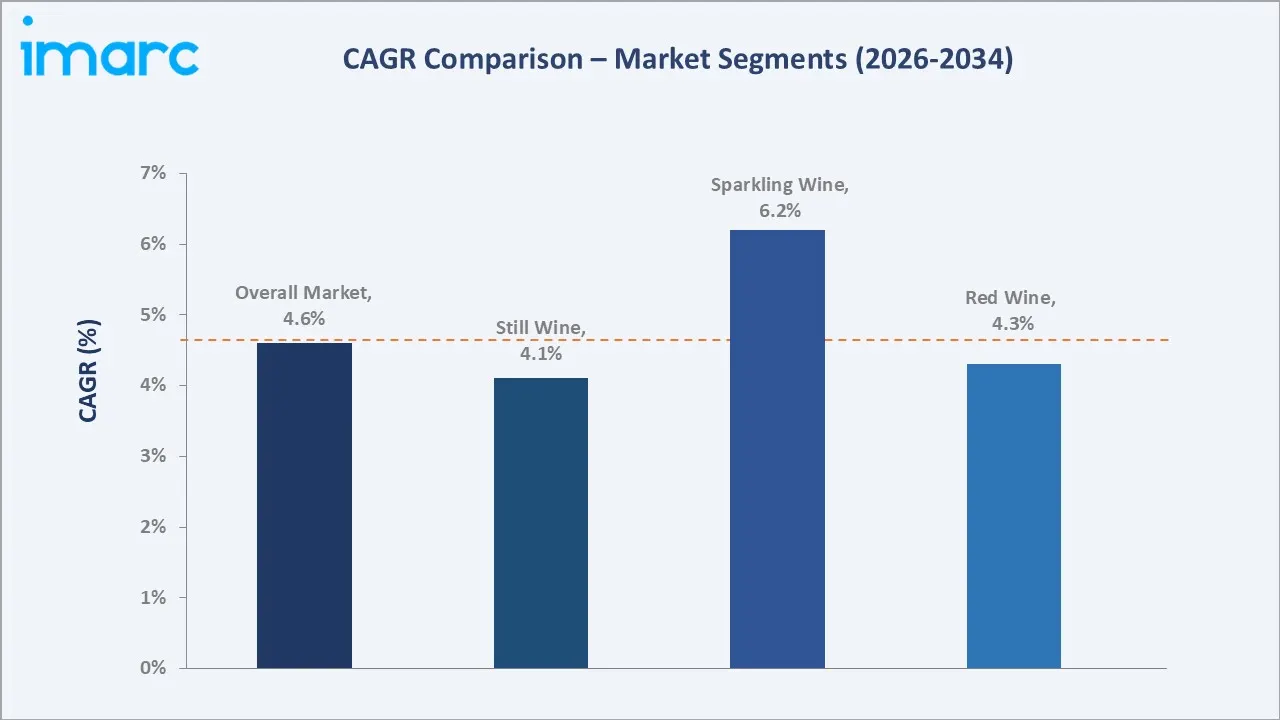
Sparkling wine is the fastest-growing product type segment at 6.2% CAGR, fueled by premiumization and prosecco-style consumption trends. Still wine, at 4.1% CAGR, retains the dominant volume share.
Executive Summary
The United States wine market is one of the largest wine-consuming markets by value, supported by a deeply established wine culture, a diverse domestic viticultural base spanning a broad retail and hospitality distribution network. The market is on a consistent growth trajectory, underpinned by premiumization trends, expanding e-commerce and DTC sales channels, and growing consumer interest in sustainable and organic wine production.
Still wine leads at 71.6%, covering the broadest consumption base across casual and premium occasions. Red wine holds the largest color segment at 47.8% in 2025, underpinned by its broad consumer base. The South region commands 28.6% in 2025, supported by local wine culture, tourism, and a growing regional winery ecosystem.
Key Market Insights
|
Insight |
Data |
|
Dominant Product Type |
Still Wine – 71.6% share (2025) |
|
Dominant Color |
Red Wine – 47.8% share (2025) |
|
Leading Region |
South – 28.6% (2025) |
|
Key Market Opportunity |
Premiumization, DTC channel expansion, and growing low-alcohol wine demand are creating high-margin, structurally expanding growth opportunities across all product and color segments. |
Key Analytical Observations Supporting the Above Data:
- Still Wine at 71.6%: Still wine dominates because it is the foundational consumption category for both at-home dining and on-trade restaurant occasions, encompassing the broadest range of varietals, price points, and regional origins that serve the full spectrum of US wine consumers.
- Red Wine at 47.8%: Red wine commands the largest color share due to its established consumer base across premium varietals.
- South Region at 28.6%: The South's regional leadership reflects growing consumer wine culture, supported by expanding local winery ecosystems, wine tourism activity, and strong hospitality sector consumption in major cities.
United States Wine Market Overview
The United States wine market encompasses production, distribution, and retail of all wine categories across on-trade and off-trade channels. The market serves consumers across the full price spectrum, supported by a broad distribution network of wholesalers, retailers, restaurants, and DTC platforms. The industry ecosystem spans grape growers, winery facilities, national distributors, specialty retail chains, online platforms, and hospitality buyers. The market operates within a three-tier distribution system, with increasing exceptions for DTC and e-commerce channels.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
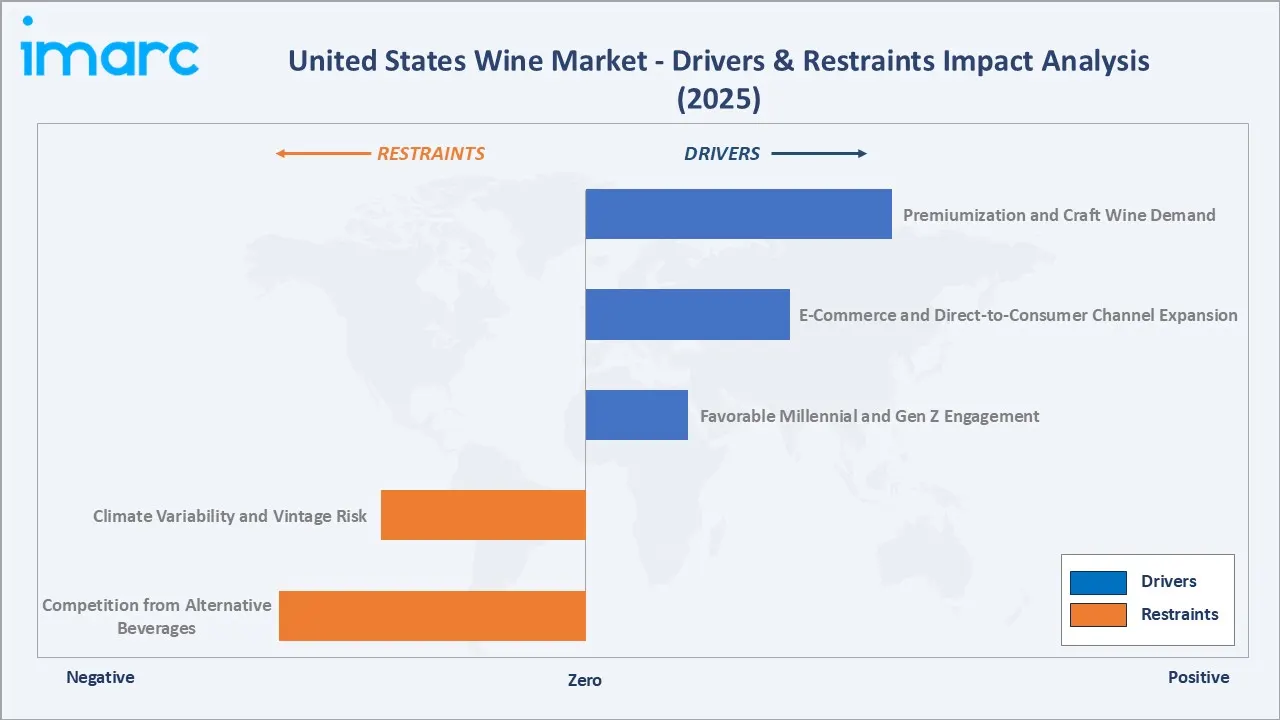
- Premiumization and Craft Wine Demand: Consumers are consistently trading up to premium wine price tiers, growing faster than the overall market. This trend drives higher revenue per unit across both retail and on-trade channels.
- E-Commerce and Direct-to-Consumer Channel Expansion: Online and DTC channels, including winery wine clubs and subscription models, are growing as state-level regulatory changes enable broader digital distribution. DTC shipment volumes have grown substantially since 2020, providing wineries with higher-margin revenue alternatives to traditional wholesale.
- Favorable Millennial and Gen Z Engagement: In 2025, the US had approximately 72.95 million Millennials, accounting for around 22% of the total population. Millennials represent the largest wine-consuming cohort, engaging with wine through digital discovery, restaurant occasions, and premium gifting. Their preference for authentic, story-driven brands supports growth in craft and estate wines at premium price points.
Market Restraints
- Climate Variability and Vintage Risk: Changing climate conditions, including drought, wildfires, and temperature extremes, affect grape quality and yield across key US viticultural regions, creating supply unpredictability and quality inconsistency that can constrain premium wine production volumes and increase input costs for wineries.
- Competition from Alternative Beverages: Craft spirits, ready-to-drink cocktails, and hard seltzers compete directly with wine for millennial consumers, limiting wine's ability to grow its share of total alcohol consumption.
Market Opportunities
- Low-Alcohol and Non-Alcoholic Wine Segment: Growing consumer health consciousness is driving demand for low-alcohol and non-alcoholic wine alternatives. In March 2026, Butter Wines launched ButterZero, a new range of non-alcoholic wines containing less than 0.5% alcohol and up to 65 calories per glass. The range includes four varieties: Sparkling Rosé, Sauvignon Blanc, Chardonnay, and Pinot Noir, priced at a suggested retail price of $12.99 per 750 mL bottle. This launch illustrates the commercial opportunity, as mainstream brands and retailers invest in building dedicated no-alcohol and low-alcohol wine ranges to capture the wellness-driven consumer segment.
- Organic and Sustainable Wine Production: Consumer demand for environmentally certified wines is growing, with organic, biodynamic, and sustainably farmed wine labels commanding premium shelf placement and pricing. Certified sustainable vineyard acreage is increasing, creating a differentiated product segment with strong long-term demand visibility as sustainability becomes a baseline expectation.
Market Challenges
- Complex Multi-State Regulatory Environment: The US wine market operates under a complex patchwork of state-level distribution laws, alcohol control board regulations, and DTC shipping restrictions that vary significantly by state. Navigating this regulatory complexity adds operational costs and limits the ability of smaller wineries to access direct distribution across all states efficiently.
- Import Competition and Consumer Price Sensitivity: Imports from France, Italy, Spain, and Argentina compete across all price segments. In value retail categories, international wines frequently offer competitive pricing that pressures domestic producer margins, particularly below USD 15 per bottle.
Emerging Market Trends
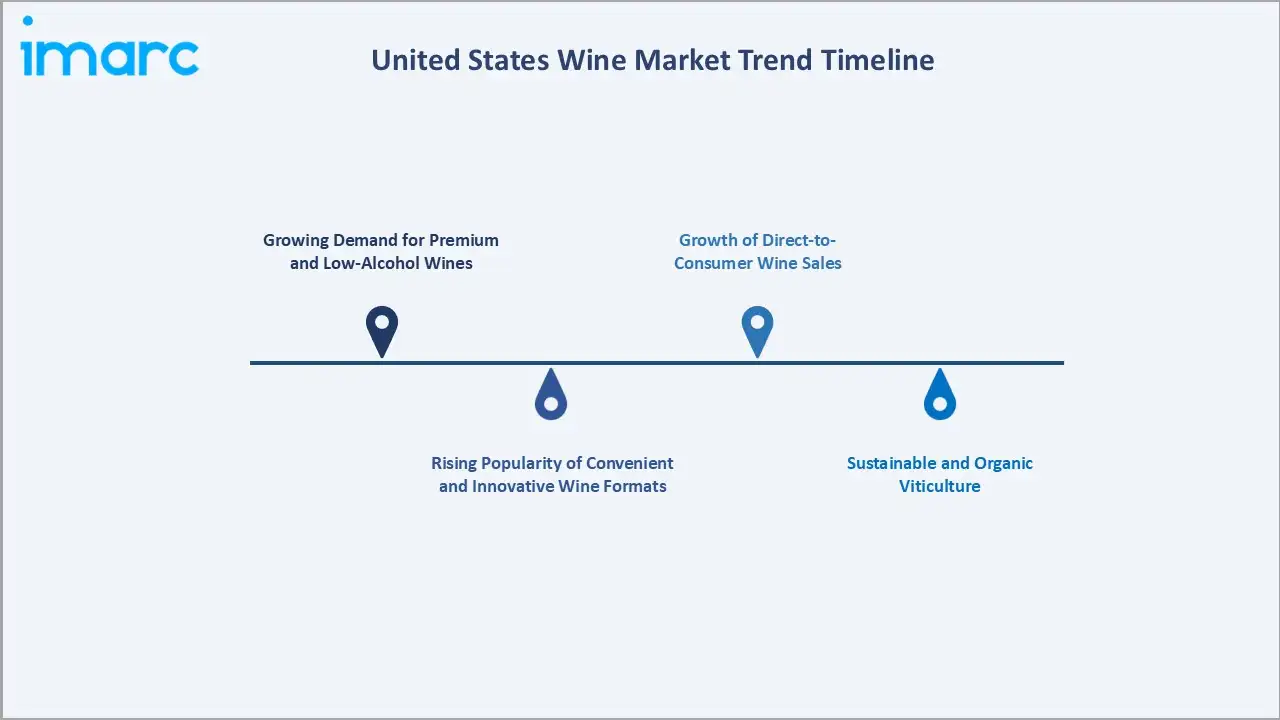
1. Growing Demand for Premium and Low-Alcohol Wines
Consumers are exploring diverse flavors and health-conscious options, encouraging brands to introduce alcohol-free wines, refreshing white blends, and new product varieties to attract a broader customer base. In October 2026, Meiomi launched Meiomi Blanc White Wine, a premium white blend expanding its presence in the growing white wine category. Made from California’s Central Coast grapes, it combines unoaked Chardonnay, Viognier, and Malvasia to deliver a smooth, balanced, and refreshing taste.
2. Rising Popularity of Convenient and Innovative Wine Formats
Brands are launching innovative products such as premium sparkling rosé to attract younger consumers and meet demand for affordable, versatile, and easy-to-serve wine options. In July 2026, Gratsi, a leading US boxed wine brand, launched a Provence-crafted Sparkling Rosé. The launch follows its recognition as the country’s No. 1 boxed wine in USA TODAY’s Readers’ Choice Awards for the second consecutive year.
3. Growth of Direct-to-Consumer Wine Sales
In October 2026, AVIVO Wines introduced the First Taste Trio, an online-exclusive pack featuring full-size bottles of its White, Rosé, and Red wines for $49 delivered. The offer targets new customers, providing an easy way to sample the brand’s food-friendly wine range. This trend is expanding consumer access to diverse wine varieties while strengthening brand engagement and online purchasing.
4. Sustainable and Organic Viticulture
Growing consumer and regulatory pressure for environmental transparency in wine production is accelerating the adoption of certified organic, biodynamic, and sustainably farmed vineyard practices. Certified sustainable wine labels are gaining premium shelf space in major retail chains and commanding price premiums over comparable conventional wines, creating structural incentive for broader vineyard certification adoption.
Industry Value Chain Analysis
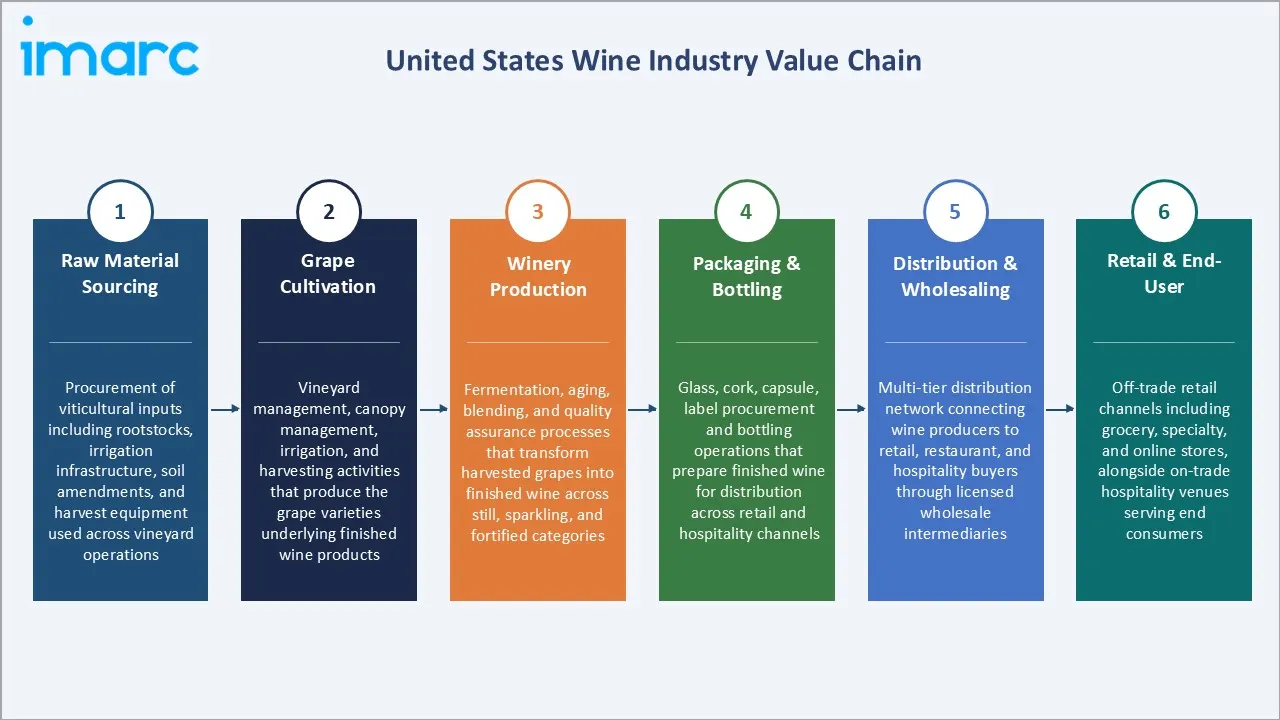
The United States wine market value chain spans six integrated stages from raw material sourcing through end-user consumption. The highest value addition occurs at the winery production stage, where varietal expertise, appellation provenance, and brand positioning create pricing power that distinguishes premium producers from commodity suppliers.
|
Stage |
Description |
| Raw Material Sourcing | Procurement of viticultural inputs including rootstocks, irrigation infrastructure, soil amendments, and harvest equipment used across vineyard operations. |
| Grape Cultivation | Vineyard management, canopy management, irrigation, and harvesting activities that produce the grape varieties underlying finished wine products. |
| Winery Production | Fermentation, aging, blending, and quality assurance processes that transform harvested grapes into finished wine across still, sparkling, and fortified categories. |
| Packaging & Bottling | Glass, cork, capsule, label procurement and bottling operations that prepare finished wine for distribution across retail and hospitality channels. |
| Distribution & Wholesaling | Multi-tier distribution network connecting wine producers to retail, restaurant, and hospitality buyers through licensed wholesale intermediaries. |
| Retail & End-User | Off-trade retail channels including grocery, specialty, and online stores, alongside on-trade hospitality venues serving end consumers. |
The winery production stage holds the greatest strategic significance. Producers investing in premium appellation sourcing and skilled winemaking create durable brand equity and pricing power difficult for competitors to replicate.
Technology Landscape in the United States Wine Industry
Precision Viticulture and Smart Vineyard Management
Vineyard operators are increasingly deploying drone-based canopy monitoring, soil moisture sensing, and satellite imaging to optimize irrigation, predict harvest timing, and manage vine stress with data-driven precision. These technologies improve grape quality consistency and reduce water and input costs across large vineyard operations in key growing regions.
Dealcoholization and Wine Processing Innovation
Advanced membrane filtration, spinning cone column, and vacuum distillation technologies enable producers to manufacture low-alcohol and non-alcoholic wines retaining the aroma, flavor, and mouthfeel of full-strength products. Investment in dealcoholization capacity is expanding rapidly as producers respond to structurally growing health-conscious consumer demand.
E-Commerce and DTC Platform Technologies
AI-powered wine recommendation engines, subscription personalization, and data-driven DTC marketing platforms are transforming consumer discovery and repeat purchase behavior. These technologies improve retention for wine clubs and enable smaller producers to access national consumer audiences without traditional wholesale distribution intermediaries.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Product Type |
Still Wine |
71.6% |
2025 |
|
Color |
Red Wine |
47.8% |
2025 |
|
Distribution Channel |
Off-Trade |
🔒 |
2025 |
|
Region |
South |
28.6% |
2025 |

By Product Type
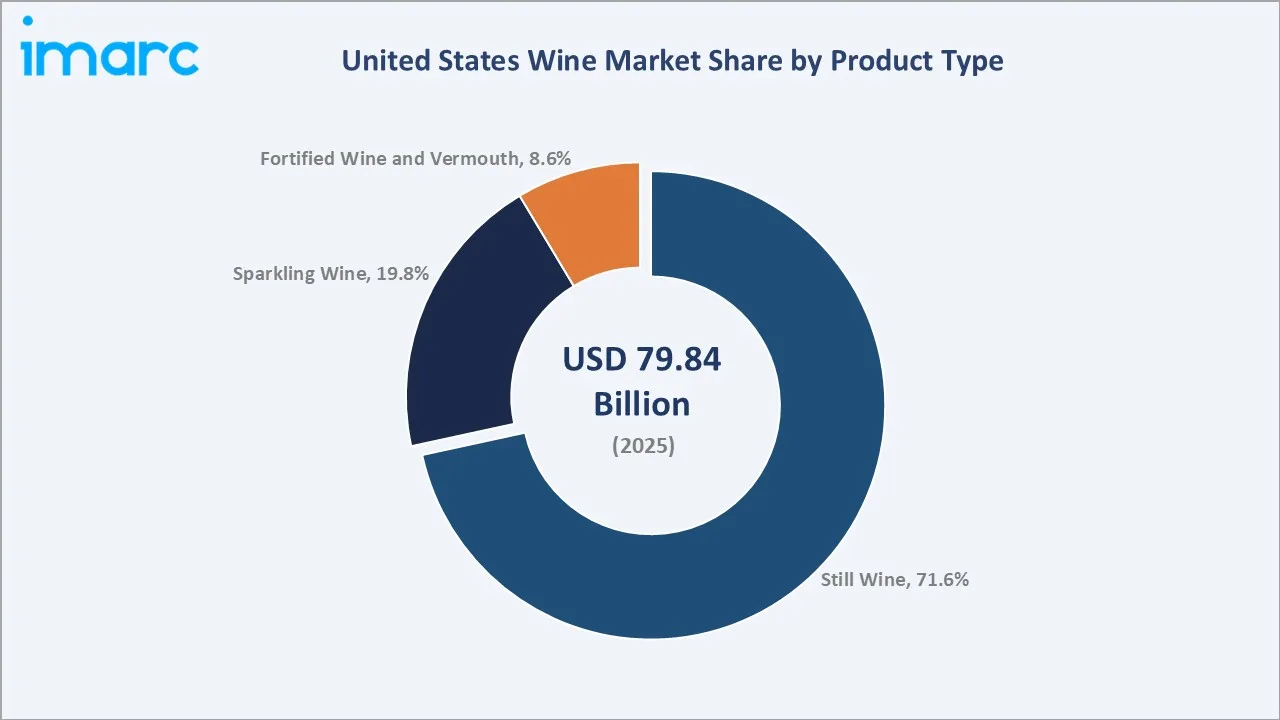
Still wine leads at 71.6% in 2025, reflecting dominance as the primary consumption category across casual, premium, and luxury occasions. It encompasses the broadest range of varietals, appellations, and price points, providing consistent volume across all retail and on-trade channels.
To access detailed market analysis, Request Sample
Sparkling wine at 19.8% is the fastest-growing segment, fueled by demand for prosecco and domestic sparkling labels. Fortified wine and vermouth at 8.6% serve the craft cocktail and aperitivo segment, with growing bartender adoption in premium on-trade venues.
By Color
Red wine commands the largest segment share at 47.8% in 2025, driven by the established consumer base for Cabernet Sauvignon, Pinot Noir, Merlot, and Zinfandel varietals across premium and mid-range price points.
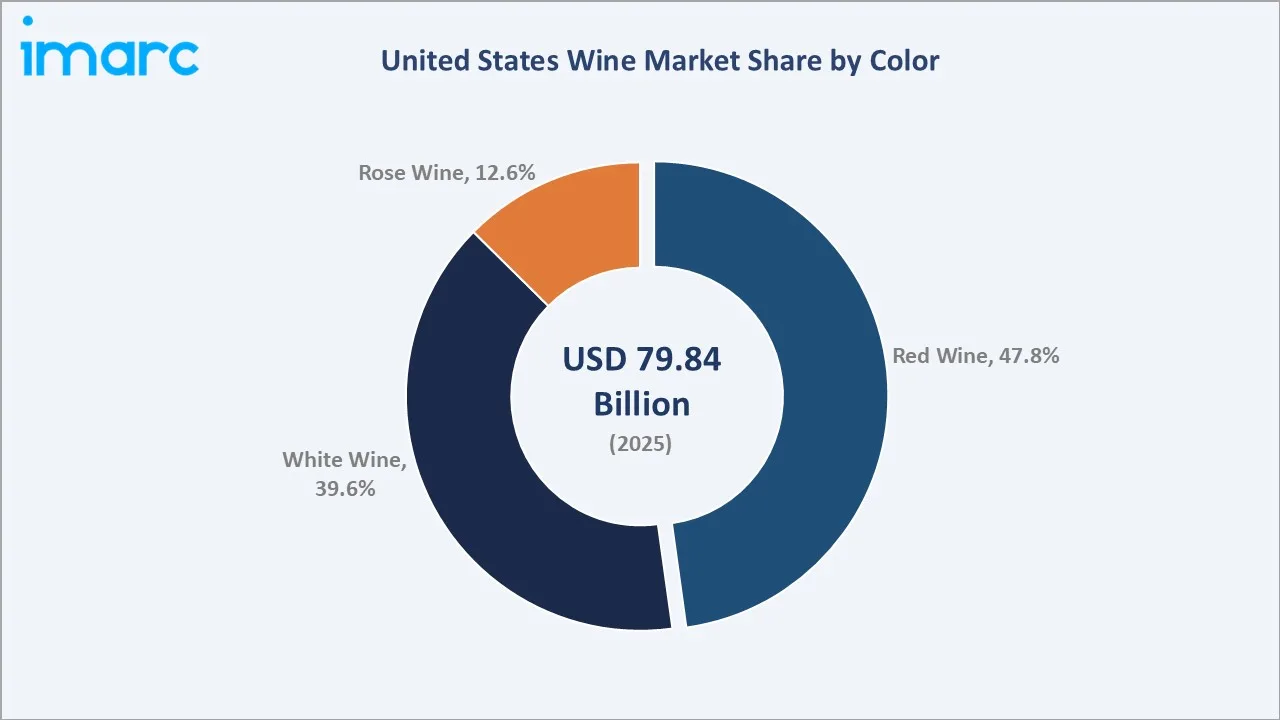
White wine at 39.6% is driven by Chardonnay, Sauvignon Blanc, and Pinot Grigio versatility across dining and casual occasions. Rosé wine at 12.6% has grown steadily, supported by year-round consumption normalization and premium packaging appealing to younger demographics.
Regional Market Insights
|
Region |
Share (2025) |
Key Drivers & Characteristics |
| South | 28.6% | Largest regional wine market, reflecting strong hospitality consumption, growing local winery ecosystems, and expanding wine tourism activity across southern states. |
| West | 27.4% | Anchored by California's dominant wine production and consumption base, with Washington and Oregon contributing premium varietal supply and strong regional consumer wine loyalty. |
| Northeast | 23.8% | Driven by high-income urban consumer concentration in metropolitan areas, strong on-trade hospitality demand, and growing interest in domestic premium labels. |
| Midwest | 20.2% | Supported by consistent at-home consumption demand, growing craft wine interest, and expanding regional winery activity that supplements national brand distribution. |
The South leads at 28.6%, reflecting strong hospitality consumption and growing wine tourism. Texas and Virginia are the fastest-growing domestic producing states, supporting both regional identity and on-premises category development. The West holds 27.4%, anchored by California's dominant viticultural and consumption base.
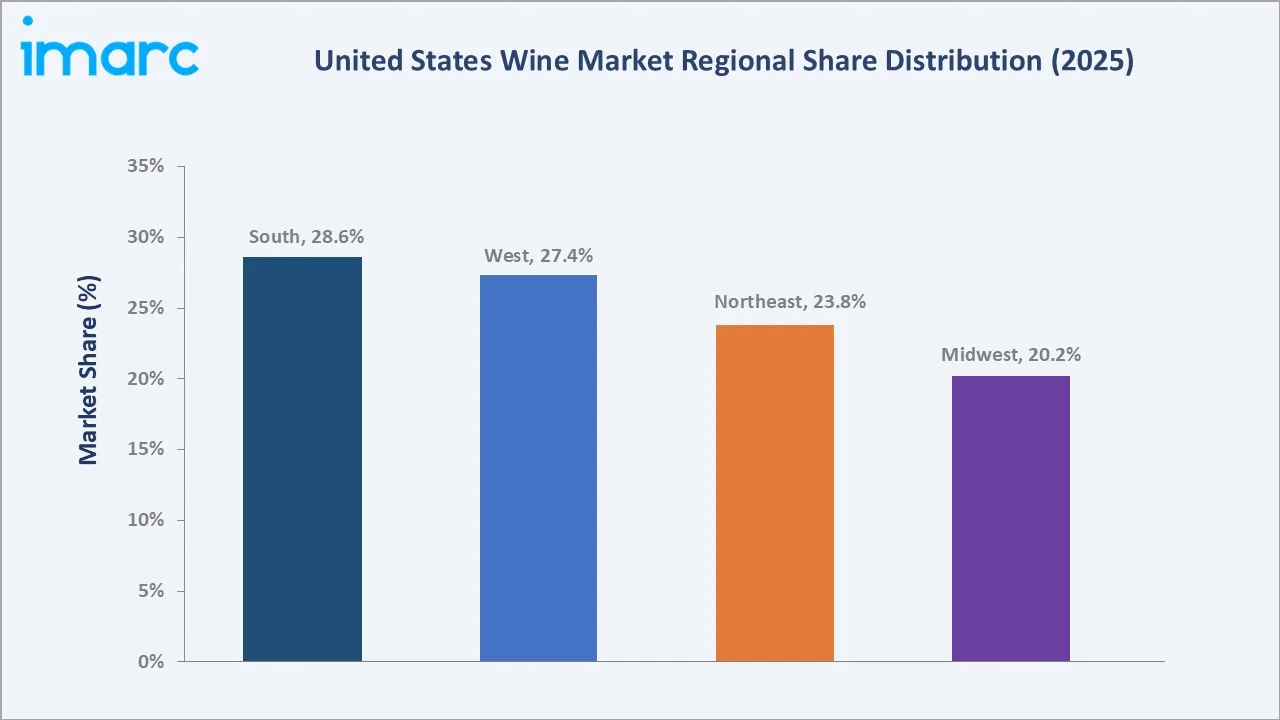
The Northeast commands 23.8%, driven by dense urban concentration. These markets exhibit strong on-premises consumption, premium retailing, and wine club membership. The Midwest accounts for 20.2%, driven by at-home consumption and a growing regional winery presence. The region's market is concentrated in everyday and mid-tier price segments, with increasing local winery tourism contributing to category awareness.
Competitive Landscape
The United States wine market is moderately consolidated at the top tier, with a small number of large national producers and importers commanding significant volume and retail share.
|
Company |
Key Brands |
Market Position |
Core Strength |
| E. & J. Gallo Winery | Barefoot, Alamos, Allegrini, Blackstone, Ballatore | Market Leader | E. & J. Gallo Winery (GALLO) is the largest family-owned winery in the United States and the largest wine producer by volume. |
| Constellation Brands, Inc. | Kim Crawford, The Prisoner, UNSHACKLED, Harvey & Harriet, SALDO | Market Leader | Constellation Brands, Inc. plays a major role in the United States wine market by shifting its strategy away from mass-market brands to focus exclusively on higher-end, higher-margin fine wines. |
| The Wine Group | Franzia, Cupcake, Chloe, Flip Flop, Foxhorn, Benziger | Established Player | The Wine Group is one of the largest wine suppliers and producers in the United States, managing a huge number of brands. |
| Treasury Wine Estates Ltd | Penfolds, DAOU Vineyards, Frank Family Vineyards, Squealing Pig | Established Player | Treasury Wine Estates Ltd plays a major role in the United States wine market as a leading grower, producer, and marketer of luxury and premium wine brands. |
| Trinchero Family Estates | Ménage à Trois, Sutter Home, Joel Gott Wines, FRE | Challenger | Trinchero Family Estates operates as one of the largest wineries and the largest family-owned wine company in the United States. |
Competition is intensifying across premium segments as large producers invest in brand equity, DTC development, and sustainability programs. Smaller estate producers focus on regional leadership and experiential marketing through tasting rooms to compete effectively against national brands.
Key Company Profiles
E. & J. Gallo Winery
E. & J. Gallo Winery is one of the largest family-owned wineries and the leading wine company in the United States by production volume and market share. The company serves consumers across the full price spectrum from value to ultra-premium, with an extensive portfolio of owned brands and imported labels. Its national distribution infrastructure and retail partnerships provide unmatched market access across all US wine consumption channels.
- Key Brands: Barefoot, Alamos, Allegrini, Blackstone, Ballatore.
- Strategic Focus: Expanding its premium and ultra-premium portfolio presence through brand acquisition, estate vineyard investment, and DTC channel development. The company also emphasizes sustainable production practices, packaging innovation, and international market expansion.
Constellation Brands, Inc.
Constellation Brands, Inc. is a leading premium wine, spirits, and beer producer with a portfolio of high-equity wine brands. The company has strategically repositioned its wine portfolio toward the premium and luxury segments, divesting value-tier brands to focus on higher-margin labels. Its strong on-trade and specialty retail relationships support the premiumization strategy across key US consumption channels.
- Key Offerings: Kim Crawford, The Prisoner, UNSHACKLED, Harvey & Harriet, SALDO.
- Strategic Focus: Strengthening its premium and luxury wine portfolio through strategic acquisitions, brand investment, and DTC channel expansion. The company also prioritizes sustainable operations, digital consumer engagement, and international distribution growth.
Market Concentration Analysis
The United States wine market exhibits moderate concentration at the national brand level, where large producers command significant organized retail and wholesale distribution share. This concentration is most pronounced in value and mid-premium segments, where scale advantages in production and marketing limit smaller producers.
Consolidation over the past decade has further reinforced leading players through portfolio expansion. The broader market, encompassing estate and boutique producers, is significantly fragmented, with most of the US wineries serving regional or DTC-only markets. This fragmentation creates opportunities for digital platforms and subscription services to aggregate small-producer supply and improve consumer discovery.
Investment & Growth Opportunities
Highest Growth Segments
Sparkling wine at approximately 6.2% CAGR is the fastest-growing segment, driven by millennial preferences and prosecco accessibility. Low-alcohol and non-alcoholic wine represents the highest-margin growth opportunity, expanding structurally as health-conscious behavior reshapes wine consumption through 2034.
Investment Themes
- DTC Channel Infrastructure: Significant investment opportunity exists in building DTC wine club, e-commerce, and tasting room infrastructure as the channel's structural growth advantage over traditional wholesale continues. Winery technology platforms, subscription management tools, and direct consumer data capabilities represent high-return investment areas for producers at all scale levels.
- Sustainable and Organic Wine Production: Consumer demand for certified sustainable, organic, and biodynamic wine labels is growing, with these products commanding meaningful price premiums in specialty retail and premium on-trade channels. Investment in vineyard certification, sustainable winery operations, and green packaging positions producers favorably with both premium consumers and environmentally focused retail buyers.
Future Market Outlook (2026-2034)
The United States wine market grew from USD 79.84 Billion in 2025 to USD 83.50 Billion in 2026, reaching USD 119.56 Billion by 2034, exhibiting a CAGR of 4.59% during 2026-2034 period. The market is expected to reach an intermediate milestone of approximately USD 99.92 Billion by 2030, as premiumization trends, DTC channel expansion, and the structural growth of sparkling and low-alcohol wine categories drive sustained above-GDP revenue growth.
Three structural forces will define the US wine market through 2034. First, continued premiumization will shift revenue mix toward higher-margin premium and luxury segments, improving industry profitability. Second, DTC channel growth will restructure distribution economics, enabling more producers to capture direct margins. Third, product innovation in low-alcohol and sparkling categories will expand the addressable consumer market.
Research Methodology
Primary Research
Primary research comprised structured interviews with winery executives, wine distributor management teams, retail wine buyers, sommelier professionals, DTC platform operators, and wine industry trade association representatives. These consultations validated market sizing, regional demand dynamics, channel trends, and competitive positioning across the US wine market.
Secondary Research
Secondary research drew on production and import statistics and company annual reports and investor presentations. Historical data spanning 2020-2025 was cross-validated across primary and secondary sources.
Forecasting Models
Forecasts were developed using bottom-up and top-down modeling incorporating historical growth rates, channel shift analysis, import projections, premiumization assumptions, DTC penetration rates, demographic cohort analysis, and macroeconomic indicators including disposable income growth.
United States Wine Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report | Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Product Types Covered | Still Wine, Sparkling Wine, Fortified Wine and Vermouth |
| Colors Covered | Red Wine, Rose Wine, White Wine |
| Distribution Channels Covered |
|
| Regions Covered | Northeast, Midwest, South, West |
| Companies Covered | E. & J. Gallo Winery, Constellation Brands, Inc., The Wine Group, Treasury Wine Estates Ltd, Trinchero Family Estates, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the United States wine market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the United States wine market.
- Porter's five forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the United States wine industry and its attractiveness.
- The competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the United States Wine Market Report
The United States wine market reached USD 83.50 Billion in 2026, driven by premiumization, expanding DTC channels, and consistent consumer demand across still, sparkling, and rosé categories.
The market is projected to grow at a CAGR of 4.59% during 2026-2034, supported by premiumization, DTC channel expansion, and structural growth in sparkling and low-alcohol wine segments.
The market is projected to reach approximately USD 99.92 Billion by 2030, driven by sustained premiumization, sparkling wine growth, and DTC channel expansion across major US wine-consuming regions.
Still wine leads with a 71.6% share in 2025, reflecting its dominance as the primary consumption category across casual, premium, and luxury occasion segments throughout the US market.
Red wine leads with a 47.8% share in 2025, driven by established consumer demand for Cabernet Sauvignon, Pinot Noir, and Merlot varietals across premium and mid-range retail price points.
The South region leads with a 28.6% share in 2025, reflecting strong hospitality consumption, growing regional wine tourism, and an expanding local winery ecosystem across southern states.
Key players include E. & J. Gallo Winery, Constellation Brands, Inc., The Wine Group, Treasury Wine Estates Ltd, and Trinchero Family Estates, among others.
The market is projected to reach USD 119.56 Billion by 2034, driven by premiumization, DTC channel growth, sparkling wine expansion, and increasing demand for sustainable and organic wine products.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade