
Asia Pacific Gold Nanoparticles Market Size, Share, Trends and Forecast by Type, Application, End Use Industry, and County, 2026-2034
Asia Pacific Gold Nanoparticles Market Size, Share, Trends & Forecast (2026-2034)
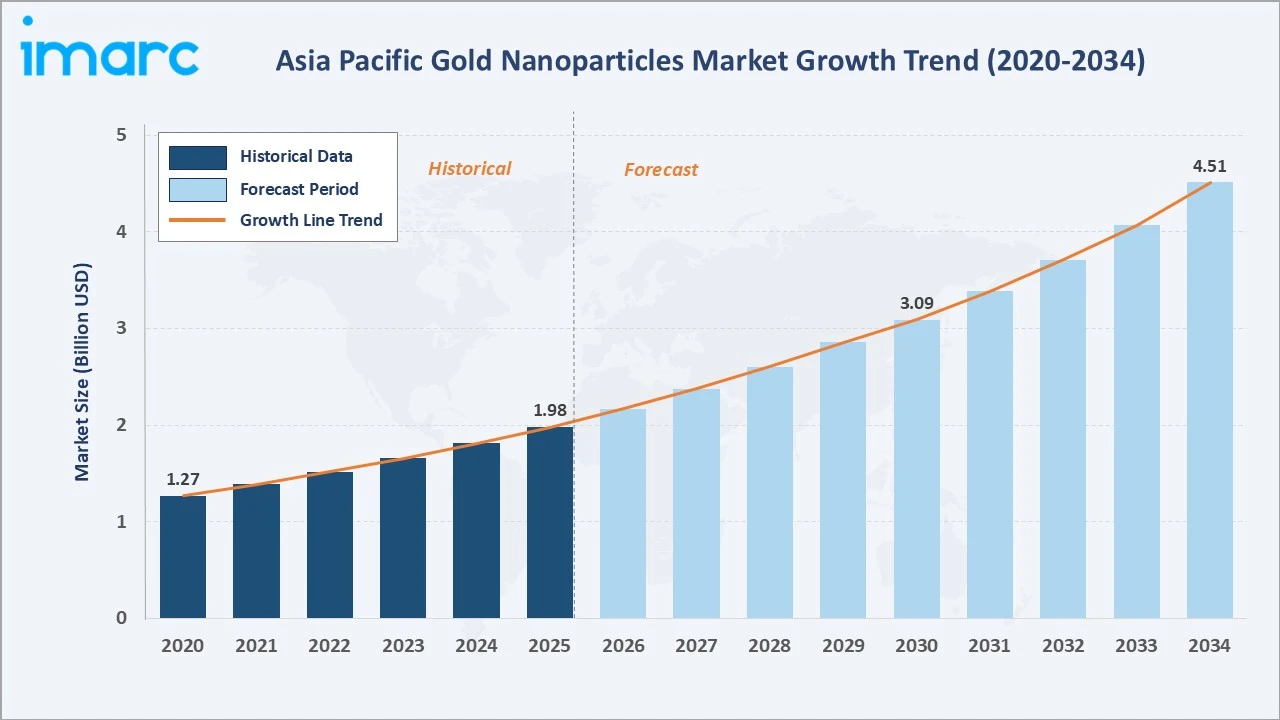
The Asia Pacific gold nanoparticles market grew from USD 1.98 Billion in 2025 to USD 2.16 Billion in 2026 and is projected to reach USD 4.51 Billion by 2034, growing at a CAGR of 9.28% during 2026-2034. Rapid expansion of biomedical diagnostics, increasing adoption in semiconductor fabrication, and strong government investment in nanotechnology research across China, Japan, and South Korea underpin the market. Healthcare leads at 46.3% by end use industry, water-soluble gold nanoparticles account for 47.6% by type, and China commands the largest regional share at 41.8% in 2025.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 1.98 Billion |
|
Market Size (2026) |
USD 2.16 Billion |
|
Forecast Market Size (2034) |
USD 4.51 Billion |
|
CAGR (2026-2034) |
9.28% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Type |
Water Soluble (47.6%, 2025) |
|
Dominant End Use Industry |
Healthcare (46.3%, 2025) |
|
Leading Country |
China (41.8%, 2025) |
The Asia Pacific gold nanoparticles market grew from USD 1.27 Billion in 2020 to USD 1.98 Billion in 2025 and further to USD 2.16 Billion in 2026, driven by sustained biomedical research activity, advancing electronics miniaturization, and growing nanotechnology investments across the region. The market is projected to reach USD 3.09 Billion by 2030 before reaching USD 4.51 Billion by 2034.
To get more information on this market, Request Sample
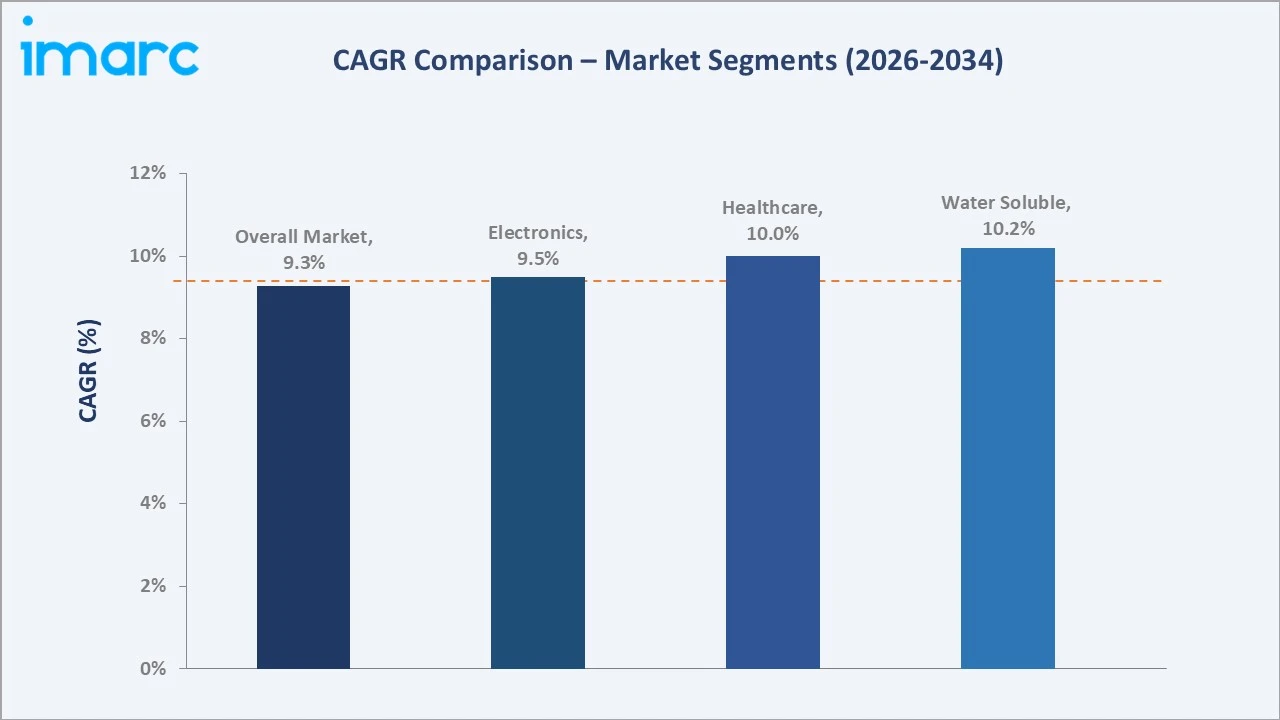
Water-soluble gold nanoparticles grow at 10.2% CAGR, driven by expanding biomedical diagnostics applications and targeted drug delivery adoption across healthcare systems in China, Japan, and South Korea. Healthcare end use grows at 10.0% CAGR, supported by rising incidence of cancer and infectious diseases accelerating diagnostic platform investment.
Executive Summary
The Asia Pacific gold nanoparticles market is on a high-growth trajectory, supported by accelerating biomedical diagnostics demand, expanding electronics applications, and significant government-backed nanotechnology research programs across the region. The market has grown steadily from USD 1.27 Billion in 2020, driven by post-pandemic investment in healthcare infrastructure, rising cancer diagnostics demand, and the rapid scaling of semiconductor and display manufacturing requiring advanced nanomaterials across China, Japan, and South Korea.
Healthcare leads end-use industry at 46.3% in 2025, underpinned by increasing adoption of gold nanoparticle-based lateral flow assays, immunoassay kits, photothermal therapy agents, and targeted drug delivery platforms. Water-soluble gold nanoparticles account for 47.6% of the type segment due to compatibility across most biomedical and analytical chemistry applications. China dominates regionally at 41.8%, reflecting the scale of its pharmaceutical, electronics, and chemical manufacturing sectors.
Key Market Insights
|
Insight |
Data |
|
Dominant Type |
Water Soluble - 47.6% share (2025) |
|
Dominant End Use Industry |
Healthcare - 46.3% share (2025) |
|
Leading Country |
China - 41.8% (2025) |
|
Key Market Opportunity |
Biomedical diagnostics scale-up and Asia Pacific semiconductor investments are creating strong, sustained demand across healthcare and electronics end-use segments. |
Key Analytical Observations Supporting the Above Data:
- Water Soluble at 47.6%: Water-soluble gold nanoparticles dominate because they are directly compatible with biomedical applications, lateral flow assays, immunodiagnostics, and drug delivery, where aqueous dispersion is essential. Their biocompatibility and surface functionalization versatility further reinforce adoption across diagnostic and therapeutic research.
- Healthcare at 46.3%: Healthcare leads because Asia Pacific faces a substantial and growing burden of cancer, infectious diseases, and chronic conditions, driving large-scale investment in advanced diagnostics and precision medicine platforms.
- China at 41.8%: China's regional leadership reflects the scale of its pharmaceutical manufacturing base, government-backed nanotechnology R&D programs, electronics manufacturing ecosystem, and growing domestic demand for advanced diagnostic tools.
Asia Pacific Gold Nanoparticles Market Overview
The Asia Pacific gold nanoparticles market encompasses the synthesis, processing, distribution, and application of gold nanoparticles across healthcare, electronics, chemicals, and research sectors. Gold nanoparticles exhibit unique optical, electronic, and surface chemical properties attributable to quantum and surface effects at the nanoscale, including localized surface plasmon resonance (LSPR), high surface-area-to-volume ratios, and tunable surface functionalization.
These properties make them indispensable across lateral flow assay diagnostics, photothermal cancer therapy, conductive ink formulations, catalytic applications, and advanced chemical sensing. The market is served by an ecosystem of chemical raw material suppliers, specialized nanoparticle manufacturers, specialty chemical distributors, and a diverse end-user base spanning hospitals, electronics OEMs, research laboratories, and chemical producers across China, Japan, South Korea, India, and Australia.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
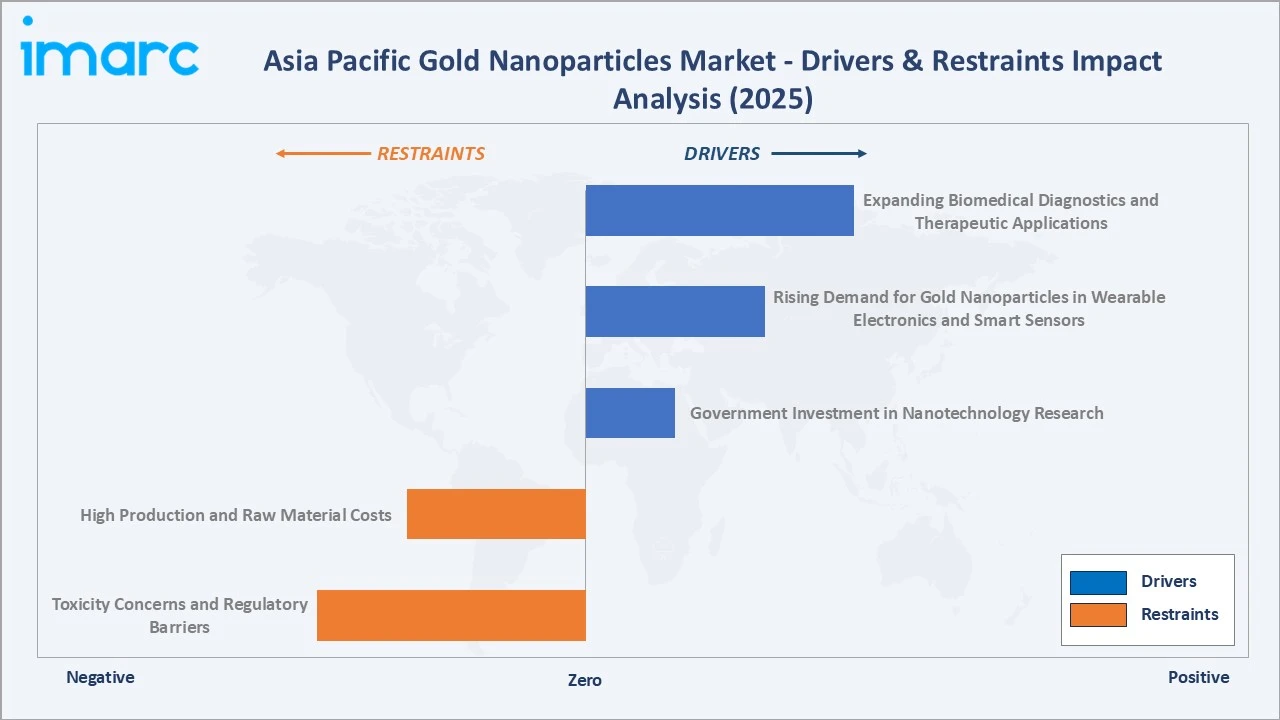
- Expanding Biomedical Diagnostics and Therapeutic Applications: Asia Pacific's healthcare sector is rapidly adopting gold nanoparticle-based lateral flow assays, immunodiagnostic kits, and photothermal therapy agents, driven by increasing cancer incidence and the scaling of point-of-care diagnostic infrastructure.
- Rising Demand for Gold Nanoparticles in Wearable Electronics and Smart Sensors: Advancements in gold nanoparticle-based flexible films are expanding their potential applications in self-powered wearable electronics and smart sensors across Asia Pacific. In May 2026, Scientists at the Institute of Nano Science and Technology (INST), Mohali, developed an ultrathin, flexible film embedded with gold nanoparticles that converts minor temperature variations into electricity, enabling self-powered wearable electronics and smart sensors.
- Government Investment in Nanotechnology Research: China's national nanotechnology programs, Japan's national initiatives, and South Korea's National Nanotechnology Initiative collectively allocate substantial annual R&D budgets toward nanomaterial development. Government-backed research funding directly stimulates demand for high-purity gold nanoparticles across academic institutions, national laboratories, and industrial R&D centers across the region.
Market Restraints
- High Production and Raw Material Costs: Gold's intrinsic commodity price volatility directly impacts gold nanoparticle production economics, with gold spot prices influencing material costs across the entire manufacturing value chain. High production costs remain a constraint on adoption at volume-sensitive price points, particularly for chemical and industrial applications where alternative nanomaterials are available.
- Toxicity Concerns and Regulatory Barriers: Regulatory uncertainty around nanomaterial safety standards, including potential cytotoxicity concerns at certain size ranges and surface chemistries, creates adoption barriers in pharmaceutical and food-contact applications. Evolving nanomaterial regulations across jurisdictions add compliance complexity for manufacturers operating across multiple Asia Pacific markets.
Market Opportunities
- Theranostics and Precision Medicine Growth: The convergence of diagnostics and therapy in cancer treatment is creating a high-value opportunity for gold nanoparticle-based theranostic platforms that combine imaging contrast, photothermal therapy, and targeted drug delivery. Asia Pacific's growing precision oncology market presents significant upside for advanced gold nanoparticle applications.
- Advanced Electronics and 5G Infrastructure Buildout: The ongoing 5G network rollout and next-generation semiconductor device scaling across Asia Pacific are creating new demand for gold nanoparticle-based conductive materials in advanced packaging, photonic interconnects, and nano-antenna applications, offering premium market access for specialized nanoparticle formulations.
Market Challenges
- Scale-Up and Reproducibility in Manufacturing: Achieving consistent particle size distributions, surface chemistry, and stability properties at industrial production scales remains a significant technical challenge. Batch-to-batch variability in gold nanoparticle synthesis can affect end-product performance in precision diagnostics and electronics, limiting adoption in quality-sensitive applications and constraining production efficiency.
- Competition from Alternative Nanomaterials: Silver nanoparticles, platinum group nanomaterials, and carbon-based nanomaterials offer functional alternatives in certain applications at lower raw material cost. Market growth can face pressure in cost-sensitive segments where gold's premium over alternatives is not fully justified by performance advantages, particularly in industrial chemical and catalysis applications.
Emerging Market Trends
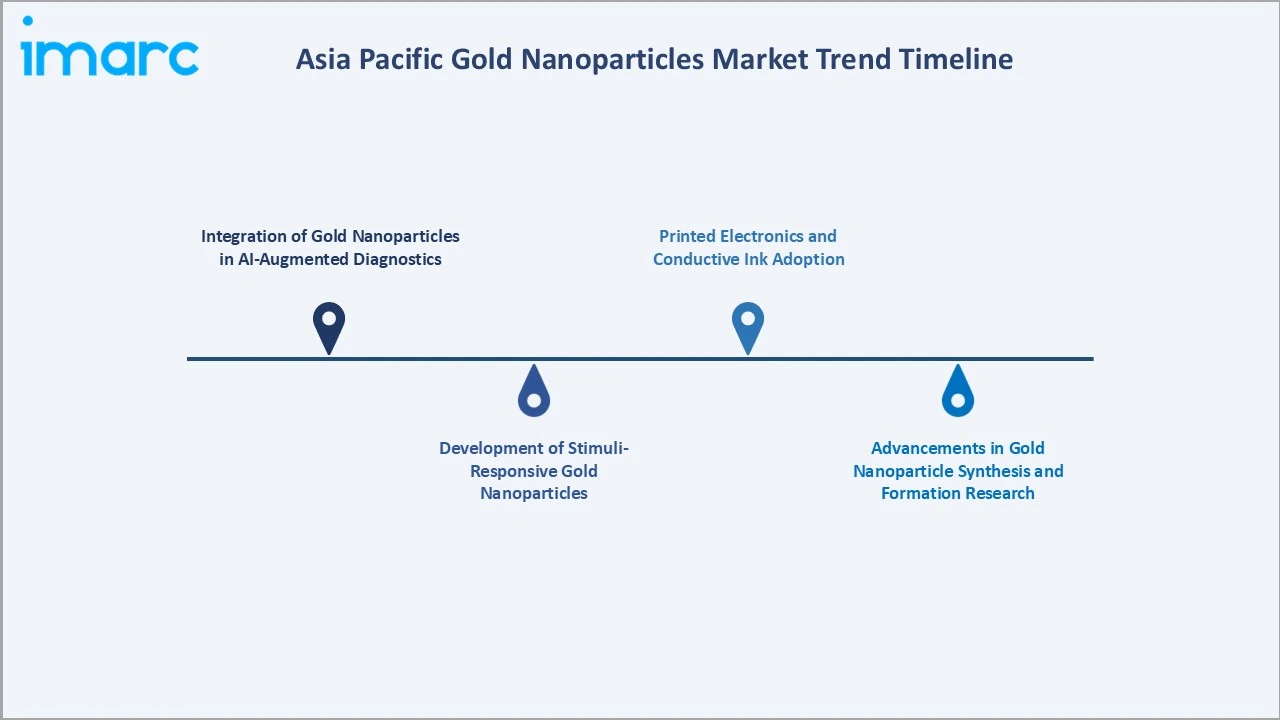
1. Integration of Gold Nanoparticles in AI-Augmented Diagnostics
Asia Pacific's diagnostics sector is increasingly integrating gold nanoparticle-based biosensor arrays with AI-driven data analysis platforms for multiplexed pathogen detection and cancer biomarker identification. AI-augmented lateral flow assay readers incorporating gold nanoparticle-labeled antibody systems are being deployed across hospitals and point-of-care settings in China and Japan, enabling quantitative readouts from traditional qualitative immunoassay formats. This integration is expanding the market from simple diagnostic reagent supply to high-value sensor system components, with diagnostics platform companies increasing their gold nanoparticle consumption volumes.
2. Development of Stimuli-Responsive Gold Nanoparticles
In May 2026, Researchers at Tohoku University in Japan discovered that certain gold nanoparticles exhibit fluid-like properties, allowing them to alter their structures in response to heat and pressure. This finding could advance biomedical engineering, intelligent surfaces, drug delivery systems, and microfluidic technologies. These stimuli-responsive properties could support advancements in biomedical engineering, targeted drug delivery, intelligent surfaces, and microfluidic devices, expanding the application scope of gold nanoparticles in healthcare and advanced technologies.
3. Printed Electronics and Conductive Ink Adoption
Asia Pacific's printed electronics sector is adopting gold nanoparticle-based conductive inks for flexible substrate printing, RFID antenna fabrication, and biosensor electrode production, driven by the region's world-leading consumer electronics manufacturing base. South Korea and Japan's display and flexible electronics industries are driving demand for sub-20nm gold nanoparticle formulations with precisely controlled surface stabilization for inkjet-printable conductive traces.
4. Advancements in Gold Nanoparticle Synthesis and Formation Research
In January 2026, Chinese researchers identified how gold nanoparticles form on pyrite surfaces, discovering that a dense liquid layer at the pyrite-water interface facilitates gold nucleation, growth, and accumulation even at extremely low concentrations. The findings provide new insights into gold ore formation from dilute gold-bearing solutions. These findings could support innovations in nanoparticle synthesis techniques and material engineering, expanding research opportunities across the Asia Pacific gold nanoparticles market.
Industry Value Chain Analysis
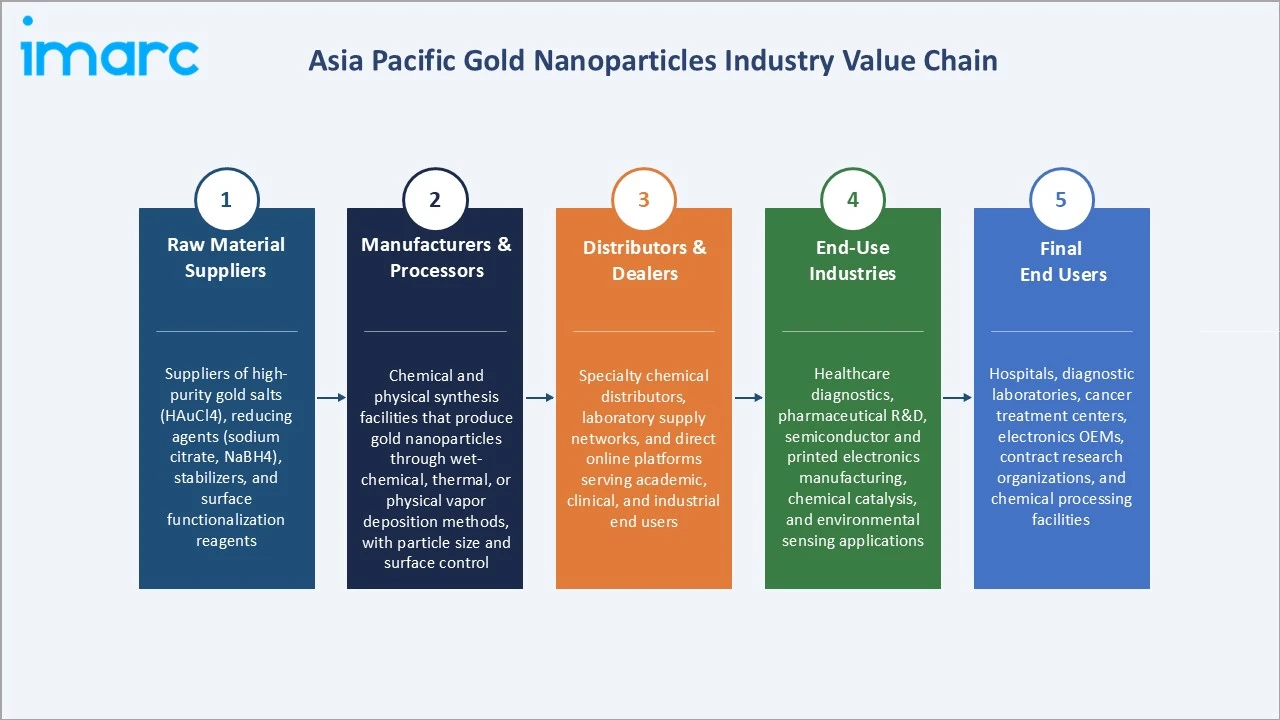
The Asia Pacific gold nanoparticles industry value chain spans from the mining and refining of gold raw material inputs through specialized nanoparticle synthesis and surface functionalization, to distribution across diverse end-use industries.
|
Stage |
Description |
|
Raw Material Suppliers |
Suppliers of high-purity gold salts (HAuCl4), reducing agents (sodium citrate, NaBH4), stabilizers, and surface functionalization reagents. |
|
Manufacturers & Processors |
Chemical and physical synthesis facilities that produce gold nanoparticles through wet-chemical, thermal, or physical vapor deposition methods, with particle size and surface control. |
|
Distributors & Dealers |
Specialty chemical distributors, laboratory supply networks, and direct online platforms serving academic, clinical, and industrial end users. |
|
End-Use Industries |
Healthcare diagnostics, pharmaceutical R&D, semiconductor and printed electronics manufacturing, chemical catalysis, and environmental sensing applications. |
|
Final End Users |
Hospitals, diagnostic laboratories, cancer treatment centers, electronics OEMs, contract research organizations, and chemical processing facilities. |
The manufacturers and processors stage represents the most value-added stage and involves advanced synthesis techniques, precise particle size and shape control, surface functionalization, and quality optimization to meet application-specific requirements. These capabilities improve nanoparticle performance, consistency, and functionality, enabling manufacturers to command higher prices for specialized products used in healthcare diagnostics, pharmaceuticals, electronics, and catalysis.
Technology Landscape in the Asia Pacific Gold Nanoparticles Market
Synthesis & Processing Technologies
Wet-chemical synthesis, primarily citrate reduction and seed-mediated growth, remains the dominant production method. Physical vapor deposition and laser ablation methods are gaining traction for electronics-grade applications requiring tighter size control and ultra-high purity. Hydrothermal synthesis routes are being adopted by manufacturers in China and South Korea for scalable production of anisotropic nanostructures, including nanorods and nanotriangles.
Surface Chemistry & Functionalization
Surface functionalization is the primary value-addition step in gold nanoparticle manufacturing, enabling application-specific performance. PEGylation, antibody conjugation, aptamer attachment, and small molecule surface modification are the dominant functionalization approaches for biomedical-grade formulations. Silica-encapsulation and polymer coating technologies are expanding for electronics and industrial applications requiring enhanced stability and process compatibility.
Analytics, Characterization & Automation
Advanced characterization, including dynamic light scattering (DLS), transmission electron microscopy (TEM), nanoparticle tracking analysis (NTA), and zeta potential measurement, is now standard in quality control workflows across Asia Pacific manufacturers. Automation of synthesis and quality testing is accelerating at scale-up facilities in China and Japan, reducing batch-to-batch variability and enabling reproducible GMP-compliant production for diagnostic-grade formulations. Machine learning-assisted synthesis optimization is an emerging technology trend among leading regional manufacturers targeting tighter size distribution control.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Type |
Water Soluble |
47.6% |
2025 |
|
Application |
Imaging |
🔒 |
2025 |
|
End Use Industry |
Healthcare |
46.3% |
2025 |
|
Country |
China |
41.8% |
2025 |

By Type
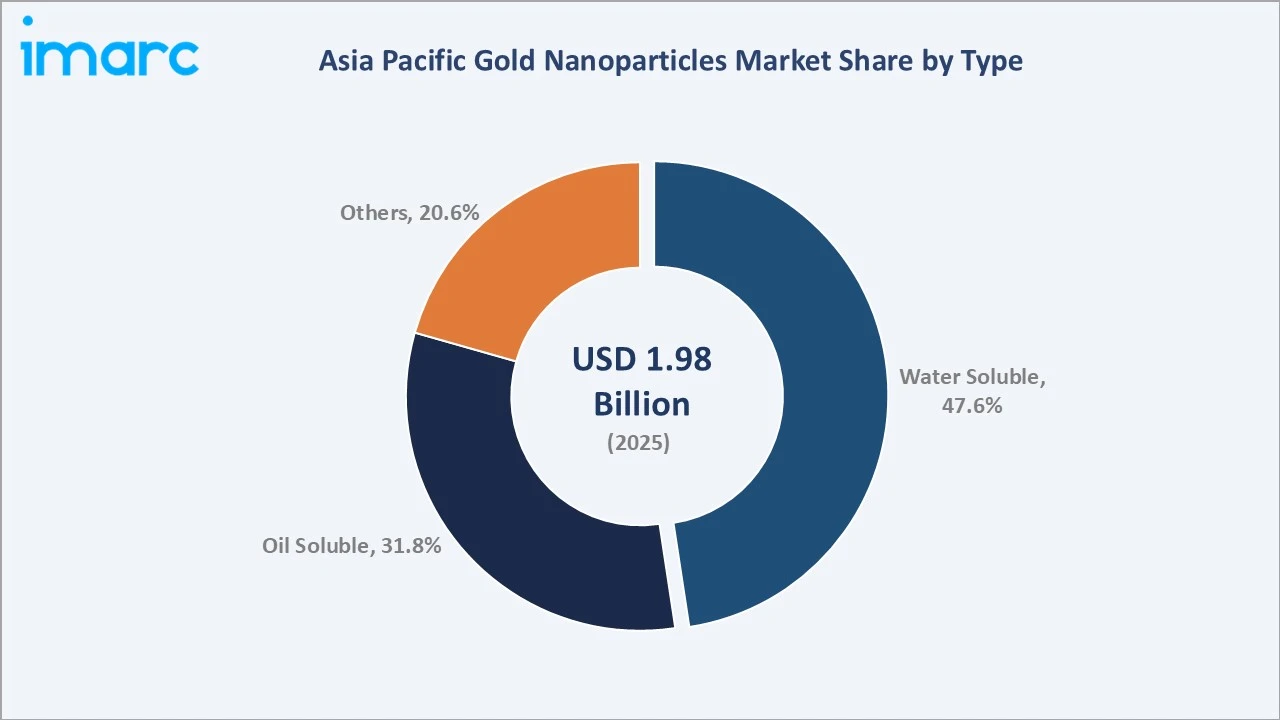
Water soluble nanoparticles lead at 47.6% in 2025, reflecting their dominant role in biomedical applications where aqueous dispersion compatibility, bioconjugation capacity, and biological stability are essential. Water-soluble formulations, typically citrate-stabilized or PEG-functionalized, are the primary reagent form for lateral flow assays, immunoassay kits, and drug delivery research across Asia Pacific's healthcare and diagnostics sectors.
To access detailed market analysis, Request Sample
Oil-soluble at 31.8% serve electronics and specialty chemical applications where organic solvent compatibility is required for conductive ink formulations, thin-film deposition, and surface coating processes. Others at 20.6% include specialty surface-functionalized formulations, amine, thiol, and antibody-conjugated, serving advanced research and pharmaceutical development applications.
By End Use Industry
Healthcare leads at 46.3% in 2025, driven by widespread adoption in lateral flow assay diagnostics, immunohistochemistry, photothermal cancer therapy research, and targeted drug delivery studies across Asia Pacific's rapidly expanding healthcare infrastructure. The region's growing pharmaceutical contract manufacturing and clinical research organization sector further reinforces gold nanoparticle demand in biomedical applications.
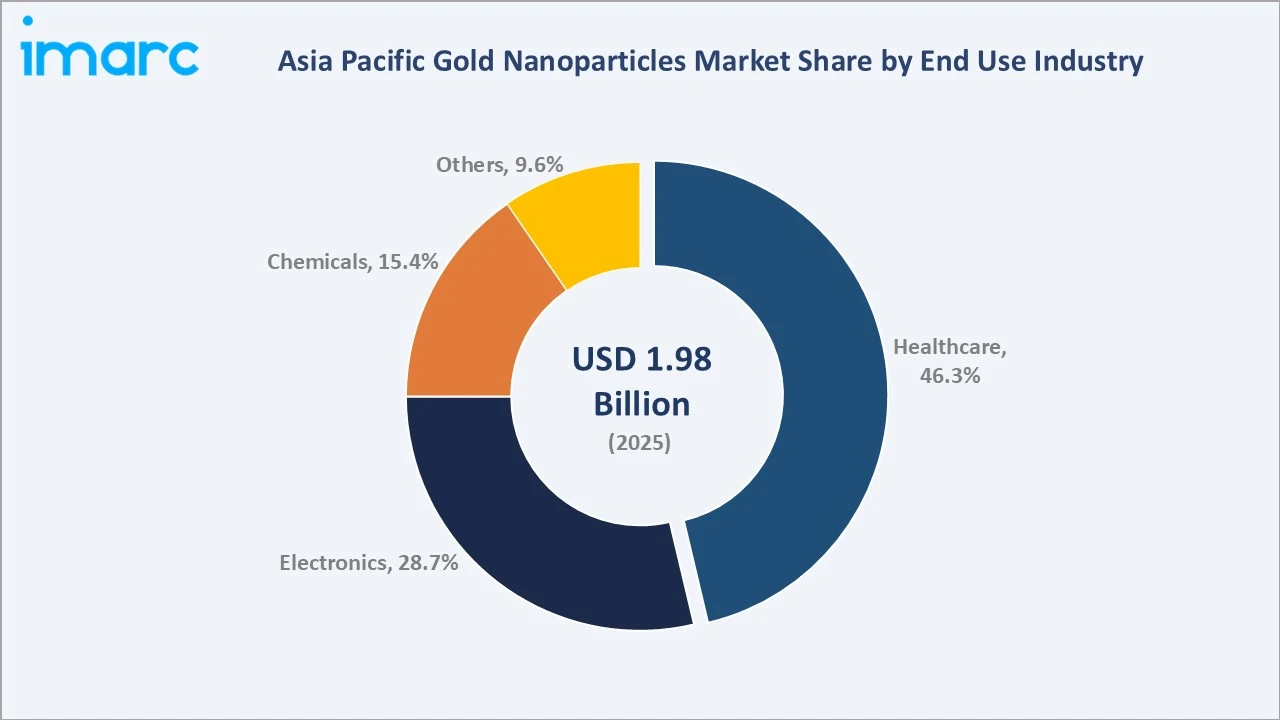
Electronics at 28.7% is the second-largest segment, driven by gold nanoparticle-based conductive inks, semiconductor packaging materials, and photonic component applications in Asia Pacific's world-leading electronics manufacturing base. Chemicals at 15.4% encompass catalytic applications, chemical sensing, and specialty chemical formulations. Others at 9.6% include environmental monitoring, food safety testing, and cosmetics applications.
Regional Market Insights
|
Country |
Share (2025) |
Key Asia Pacific Gold Nanoparticles Market Drivers & Characteristics |
|
China |
41.8% |
Reflecting the scale of pharmaceutical and biotechnology manufacturing, expanding semiconductor fabrication investment, strong government nanotechnology R&D funding, and a growing domestic diagnostics market. |
|
Japan |
18.6% |
Reflecting leading electronics and precision manufacturing sectors, advanced biomedical research infrastructure, and sustained R&D investment in nanomaterial applications for healthcare and electronics. |
|
South Korea |
13.7% |
Reflecting a highly advanced semiconductor and display manufacturing base, strong clinical research activity in oncology diagnostics, and government-supported nanotechnology commercialization programs. |
|
India |
11.9% |
Reflecting a rapidly growing pharmaceutical and contract research sector, increasing academic and institutional nanotechnology research investment, and growing adoption in diagnostic kit manufacturing. |
|
Australia |
5.6% |
Reflecting advanced university research programs in nanomedicine and nanomaterials, a growing medical device sector, and increasing adoption in environmental monitoring applications. |
|
Indonesia |
4.8% |
Reflecting a developing pharmaceutical manufacturing base and growing laboratory infrastructure investment, with increasing demand for diagnostic-grade gold nanoparticle reagents. |
|
Others |
3.6% |
Including Vietnam, Thailand, Malaysia, and other emerging economies with developing research and diagnostics infrastructure. |
China leads with a 41.8% share in 2025, underpinned by large-scale pharmaceutical and biotechnology manufacturing, rapidly expanding semiconductor fabrication capacity, and strong national investment in nanotechnology research and development. Japan accounts for 18.6% of the market in 2025, supported by world-class precision manufacturing capabilities, advanced biomedical research institutions, and a mature electronics fabrication supply chain. South Korea holds a 13.7% share in 2025, anchored by its globally significant semiconductor and display panel manufacturing base.
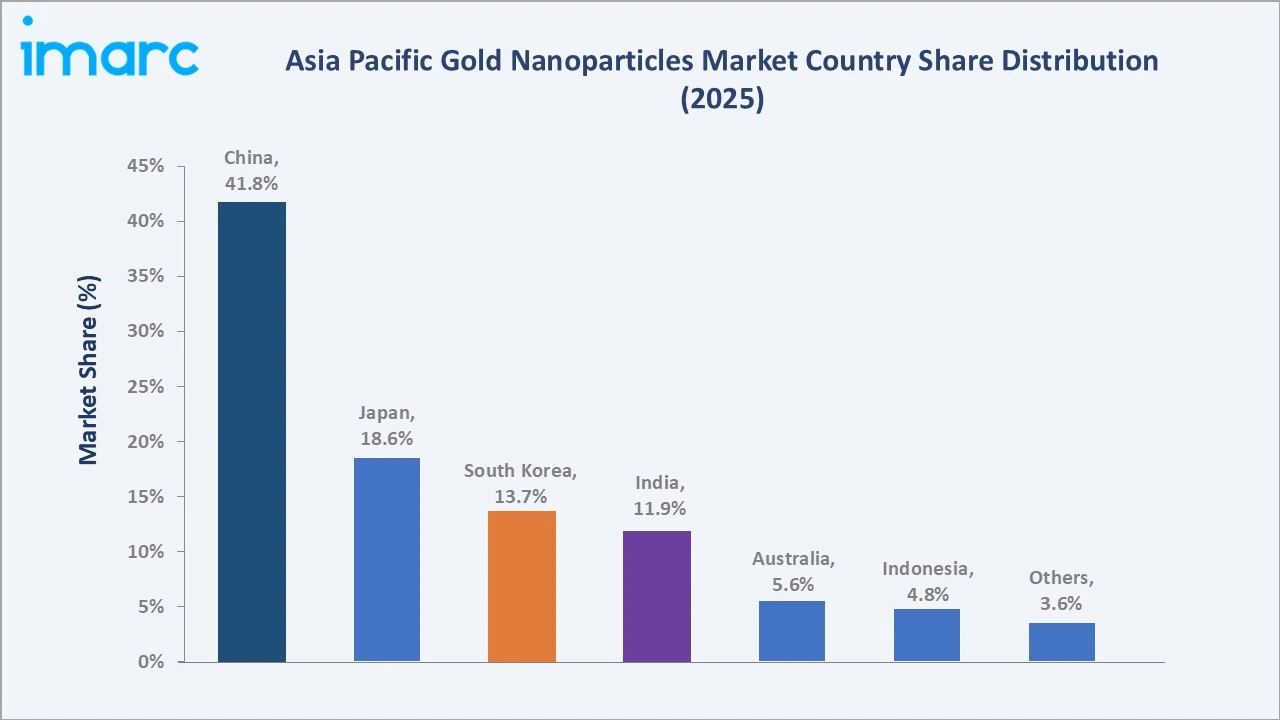
India represents 11.9% of the market in 2025 and is the fastest-growing major country segment, driven by rapid expansion of pharmaceutical contract manufacturing, rising academic and institutional nanotechnology research investment, and increasing domestic production of diagnostic kits for infectious disease screening are the primary demand drivers.
Australia contributes 5.6% of the market in 2025, driven by a highly developed university research ecosystem in nanomedicine and environmental monitoring, combined with a growing medical device and in-vitro diagnostics sector. Indonesia at 4.8% represents an emerging market with developing pharmaceutical manufacturing capacity and growing laboratory infrastructure investment, supported by increasing demand for diagnostic-grade reagents in healthcare applications. The remaining countries collectively account for 3.6% and are at early stages of nanotechnology research and diagnostics infrastructure development.
Competitive Landscape
The Asia Pacific gold nanoparticles market is moderately concentrated, with a mix of established precious metals companies with nanoparticle product lines, global specialty chemical suppliers, and dedicated nanoparticle manufacturers.
|
Company |
Key Products |
Market Position |
Core Strength |
|
TANAKA PRECIOUS METAL GROUP Co., Ltd. |
Gold Nanoshell Particles |
Market Leader |
TANAKA PRECIOUS METAL GROUP Co., Ltd. plays a leading role in the Asia-Pacific region through the development, production, and supply of high-purity gold nanoparticles. |
|
Merck KGaA |
Gold Nanoparticles |
Market Leader |
Merck KGaA (operating through Sigma-Aldrich) acts as a leading supplier of high-purity, research-grade, and monodisperse gold nanoparticles. |
|
Nanopartz Inc. |
Spherical Gold Nanoparticles |
Innovator |
Nanopartz Inc. plays a vital role in the APAC gold nanoparticles market as a premier supplier of highly customized, monodisperse gold nanomaterials used in high-growth research and industrial applications. |
|
Fortis Life Sciences, LLC. |
Gold Nanoparticles |
Challenger |
Fortis Life Sciences, LLC. is recognized as one of the prominent players in the production, supply, and contract development of gold nanoparticles. |
|
Ted Pella, Inc. |
PELCO Gold Nanoparticles |
Niche Player |
Ted Pella, Inc. plays a major role as a leading supplier and standardizer of premium gold nanoparticles, supporting the Asia Pacific region, which is currently the fastest-growing gold nanoparticles market. |
Competition is intensifying as established precious metals companies expand their specialty nanoparticle product lines, while dedicated nanoparticle manufacturers deepen their biomedical-grade product portfolios. The competitive divide between commodity-grade industrial nanoparticles and premium biomedical or electronics-grade certified formulations is creating distinct competitive tiers, with differentiation based on size monodispersity, surface chemistry control, regulatory documentation, and application-specific validation data.
Key Company Profiles
TANAKA PRECIOUS METAL GROUP Co., Ltd.
TANAKA PRECIOUS METAL GROUP Co., Ltd. is a precious metals group, with operations spanning industrial precious metals, refining, recycling, and related technologies. The company supplies gold, platinum, silver, and other precious metal products for diverse industrial applications. Through its specialized group companies, it supports technological development across electronics, semiconductors, healthcare, and advanced materials. Its precious metal nanoparticle portfolio includes gold nanoparticles and gold nanoshell particles with controlled particle sizes and surface properties.
- Key Products: Gold Nanoshell Particles.
- Strategic Focus: Expanding gold nanoparticle product lines for electronics miniaturization, biomedical diagnostics, and photocatalysis, while leveraging integrated precious metals supply for competitive cost positioning.
Nanopartz Inc.
Nanopartz Inc. is a nanotechnology company specializing in the development and production of gold nanoparticles and other advanced nanomaterials. The company offers a range of gold nanospheres, nanorods, nanoshells, and nanocages with different sizes and surface functionalization options. Its products serve applications across biomedical research, diagnostics, imaging, sensing, and photothermal therapy. Nanopartz focuses on providing specialized nanoparticle solutions for research institutions, laboratories, and industrial customers.
- Key Products: Spherical Gold Nanoparticles.
- Strategic Focus: Expanding its gold nanoparticle portfolio through product innovation, particle size customization, and advanced surface functionalization technologies. The company emphasizes developing high-quality nanomaterials for biomedical research, diagnostic applications, imaging, and sensing, supporting the evolving requirements of research institutions and industrial customers across the Asia Pacific region.
Market Concentration Analysis
The Asia Pacific gold nanoparticles market exhibits moderate concentration, with a tiered competitive structure comprising large integrated precious metals processors, global specialty chemical and life science distributors, and dedicated nanoparticle manufacturers. The leading tier, primarily precious metals processing companies with integrated synthesis capabilities operating in Japan and China, collectively commands high organized regional market revenue in 2025. Their competitive advantage lies in upstream raw material integration, established quality systems, and long-standing supply relationships with major industrial and diagnostic end users across the region.
Market fragmentation increases progressively in the biomedical and diagnostics segment, where numerous specialized manufacturers, academic spin-offs, and regional distributors compete on the basis of application validation, surface chemistry customization, and regulatory documentation rather than scale or price. This structural dynamic creates sustained opportunities for differentiated niche suppliers to capture premium margins in certified reference-grade and IVD-grade gold nanoparticle formulations. Consolidation is expected to gradually increase as global life science distribution groups acquire specialized nanoparticle manufacturers to deepen their advanced materials product portfolios and respond to growing demand for validated diagnostic reagent supply chains.
Investment & Growth Opportunities
Highest Growth Segments
The highest growth segments include water-soluble gold nanoparticles at 10.2% CAGR and healthcare end use grows at 10.0% CAGR.
Investment Themes
- Biomedical-Grade Gold Nanoparticle Platforms: Growing demand for validated, regulatory-compliant gold nanoparticle formulations for IVD diagnostics and clinical research creates a premium investment opportunity in certified biomedical-grade nanoparticle production, surface functionalization, and application-specific validation services across Asia Pacific's expanding diagnostics market.
- Green Synthesis Capacity Expansion: Investment in bio-assisted and green chemistry gold nanoparticle synthesis facilities offers dual value in cost reduction and sustainability positioning, with growing pharmaceutical and food-grade application markets in India and Australia specifically seeking certified green-synthesis supply chains for regulatory approval pathways.
Future Market Outlook (2026-2034)
The Asia Pacific gold nanoparticles market grew from USD 1.98 Billion in 2025 to USD 2.16 Billion in 2026, reaching USD 4.51 Billion by 2034, exhibiting a CAGR of 9.28% during 2026-2034. The market is expected to reach an intermediate milestone of approximately USD 3.09 Billion by 2030, as the convergence of biomedical diagnostics scaling, semiconductor technology advancement, and government-supported nanotechnology commercialization programs reaches peak activity across the region's major economies.
Three structural forces will define the Asia Pacific gold nanoparticles market through 2034. First, the continued expansion of Asia Pacific's healthcare diagnostics infrastructure will sustain healthcare as the dominant and fastest-growing end-use segment. Second, the ongoing semiconductor technology scaling cycle and expansion of printed electronics into flexible displays, wearable devices, and IoT sensors will progressively increase electronics-grade gold nanoparticle demand. Third, China's continued dominance, driven by government-backed nanotechnology industrialization will reinforce Asia Pacific's leadership in global gold nanoparticle consumption and manufacturing capacity through the forecast period.
Research Methodology
Primary Research
Primary research comprised structured consultations with gold nanoparticle manufacturers, specialty chemical suppliers, diagnostic kit developers, electronics materials procurement managers, pharmaceutical R&D directors, and academic nanotechnology researchers across China, Japan, South Korea, and India. These discussions validated market sizing estimates, assessed regional demand dynamics, identified key application trends, and provided insights into competitive positioning, pricing structures, and capacity investment plans across the Asia Pacific gold nanoparticles sector.
Secondary Research
Secondary research drew on published data including government nanotechnology program documentation, national science agency research reports, company annual reports and investor communications, patent databases, academic journal publications on gold nanoparticle synthesis and applications, industry association reports, and trade publication analyses of the specialty chemicals and nanomaterials markets. Historical market data spanning 2020 through 2025 was cross-validated across primary and secondary sources to ensure accuracy.
Forecasting Models
Market forecasts were developed using bottom-up and top-down modeling incorporating historical sector growth rates, end-use industry volume demand projections, government nanotechnology R&D expenditure trends, healthcare diagnostics market growth models, electronics manufacturing output projections, capacity expansion announcements by major producers, green synthesis technology adoption curves, and macroeconomic indicators including regional GDP growth, industrial output indices, and healthcare expenditure benchmarks across major Asia Pacific economies.
Asia Pacific Gold Nanoparticles Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Water Soluble, Oil Soluble, Others |
| Applications Covered | Imaging, Targeted Drug Delivery, Sensors, In Vitro Diagnostics, Probes, Catalysis, Others |
| End Use Industries Covered | Electronics, Healthcare, Chemicals, Others |
| Countries Covered | China, Japan, India, South Korea, Australia, Indonesia, Others |
| Companies Covered | TANAKA PRECIOUS METAL GROUP Co., Ltd., Merck KGaA, Nanopartz Inc., Fortis Life Sciences, LLC., Ted Pella, Inc., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Asia Pacific gold nanoparticles market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the Asia Pacific gold nanoparticles market.
- Porter's Five Forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Asia Pacific gold nanoparticles industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Asia Pacific Gold Nanoparticles Market Report
The Asia Pacific gold nanoparticles market reached USD 2.16 Billion in 2026, driven by expanding biomedical diagnostics adoption, electronics miniaturization, and growing government nanotechnology research investments.
The market is projected to grow at a CAGR of 9.28% during 2026-2034, supported by sustained healthcare diagnostics demand, electronics sector growth, and expanding nanotechnology research applications across the region.
The market is projected to reach approximately USD 3.09 Billion by 2030, driven by peak biomedical diagnostics platform adoption, electronics manufacturing expansion, and maturing nanotechnology commercialization programs across Asia Pacific.
Water-soluble gold nanoparticles lead with a 47.6% share in 2025, driven by their dominant role in biomedical diagnostics, drug delivery research, and analytical chemistry applications across Asia Pacific's healthcare sector.
Healthcare leads with a 46.3% share in 2025, driven by lateral flow assay diagnostics, immunohistochemistry, photothermal therapy research, and targeted drug delivery application demand across Asia Pacific's expanding healthcare infrastructure.
China leads with a 41.8% share in 2025, reflecting the scale of its pharmaceutical manufacturing base, semiconductor fabrication investment, government nanotechnology R&D programs, and large domestic diagnostics market demand.
Key players include TANAKA PRECIOUS METAL GROUP Co., Ltd., Merck KGaA, Nanopartz Inc., Fortis Life Sciences, LLC, and Ted Pella, Inc., among others.
The market is projected to reach USD 4.51 Billion by 2034, driven by sustained healthcare diagnostics growth, electronics miniaturization demand, advanced materials applications, and expanding nanotechnology industrial adoption across the region.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade