
Asia Pacific Induction Motor Market Size, Share, Trends and Forecast by Product Type, End Use Sector, and Country, 2026-2034
Asia Pacific Induction Motor Market Size, Share, Trends & Forecast (2026-2034)
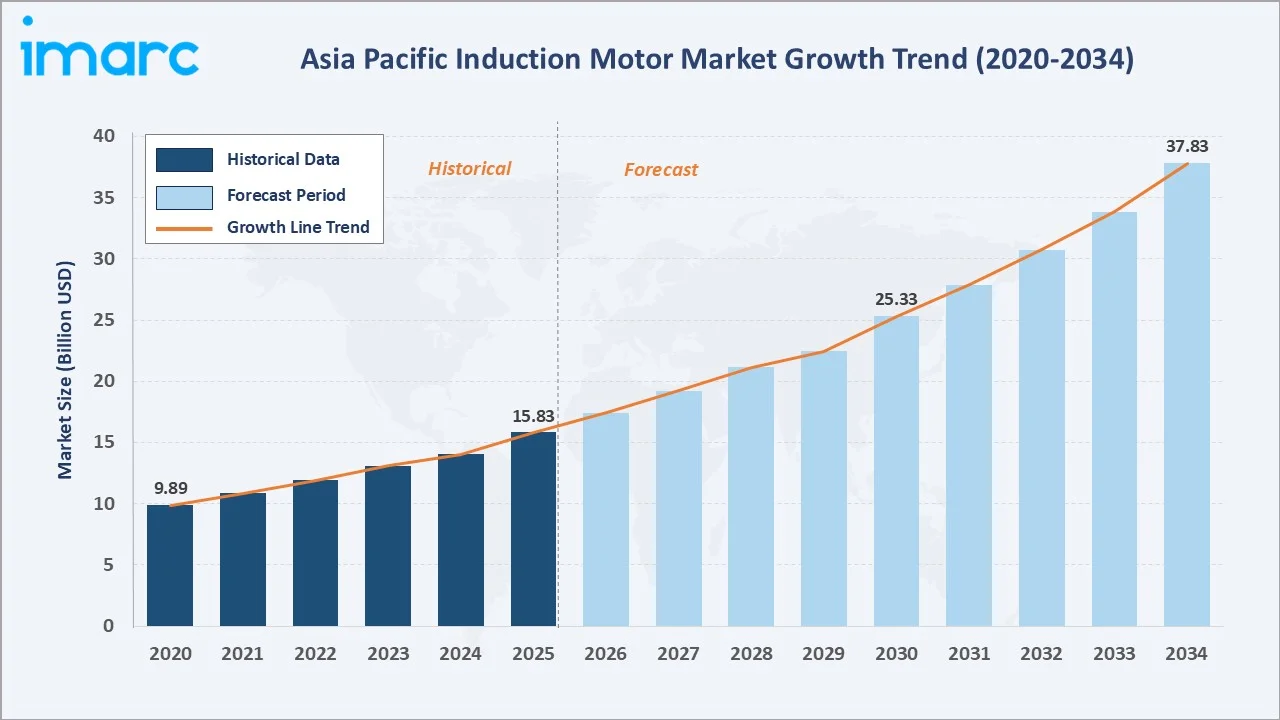
The Asia Pacific induction motor market grew from USD 15.83 Billion in 2025 to USD 17.83 Billion in 2026 and is projected to reach USD 37.83 Billion by 2034, growing at a CAGR of 9.86% during 2026-2034. Growth is driven by rapid industrialization, rising demand for energy-efficient motors, and expanding automation across China, India, and Japan. Induction motor demand is further supported by the region's growing renewable energy infrastructure and government initiatives promoting energy conservation across manufacturing and utility sectors.
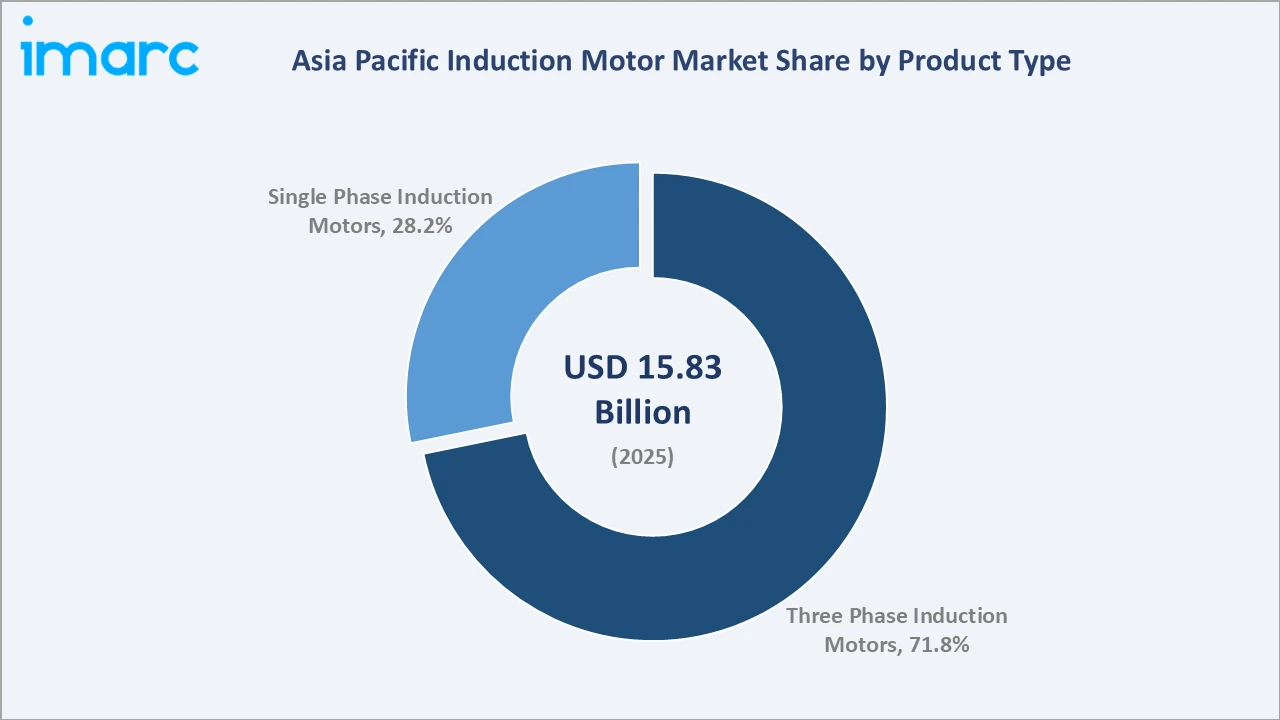
Three phase induction motors lead the product type segment at 71.8% share, while the industrial sector dominates end-use demand at 63.7%, reflecting the region's expanding manufacturing base and continued investment in automated production systems.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 15.83 Billion |
| Market Size (2026) | USD 17.83 Billion |
|
Forecast Market Size (2034) |
USD 37.83 Billion |
|
CAGR (2026-2034) |
9.86% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Product Type |
Three Phase Induction Motors (71.8%, 2025) |
|
Dominant End Use Sector |
Industrial (63.7%, 2025) |
|
Leading Country |
China (34.6%, 2025) |
The market expanded from USD 9.89 Billion in 2020 to USD 15.83 Billion in 2025 and an estimated USD 17.83 Billion in 2026, supported by rising industrial automation and energy-efficiency mandates, anchored at USD 25.33 Billion in 2030 and forecast to reach USD 37.83 Billion by 2034 as renewable energy integration and smart motor adoption continue to accelerate demand across the region. The post-pandemic recovery in manufacturing output established a durable baseline of industrial motor demand that has continued to compound as automation investment and energy-efficiency regulation expand across China, India, and Southeast Asia.
To get more information on this market, Request Sample
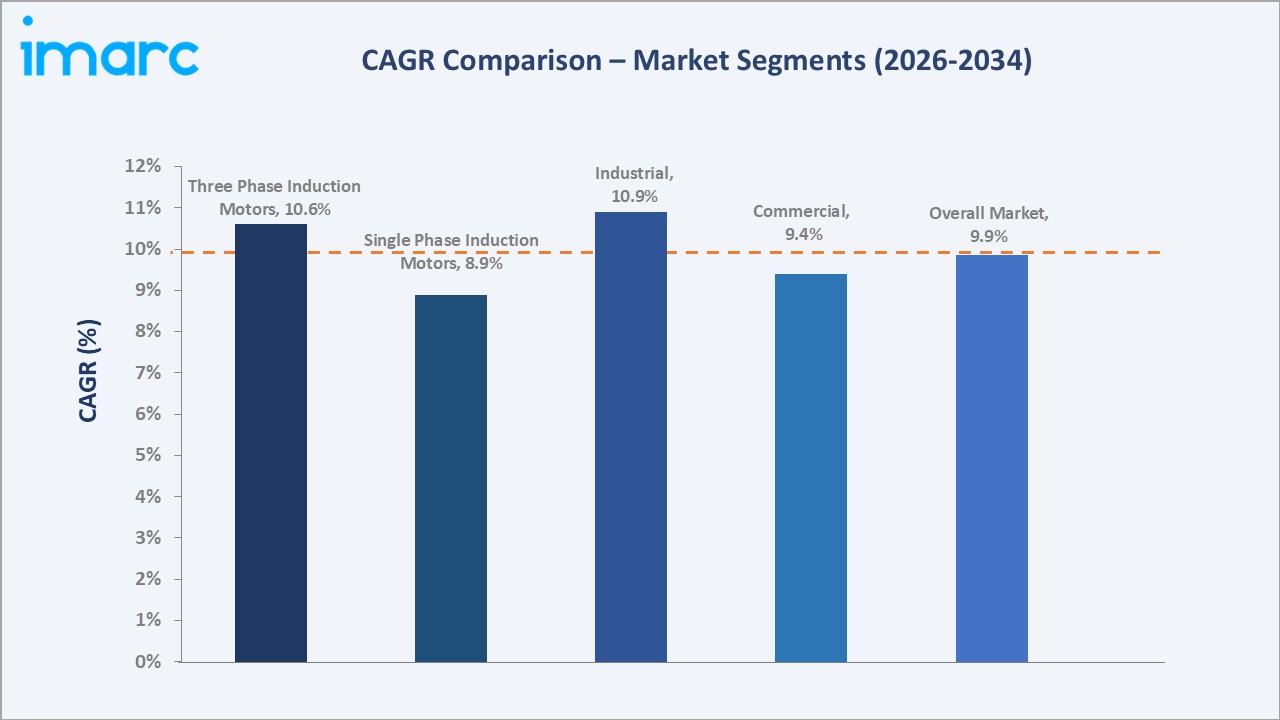
Three phase induction motors grow fastest at approximately 10.6% CAGR as industrial and commercial facilities increasingly standardize on three-phase power systems for their superior efficiency and reliability. The industrial end-use sector grows at approximately 10.9% CAGR as manufacturing automation and Industry 4.0 adoption continue to expand across the region's leading industrial economies.
Executive Summary
The Asia Pacific induction motor market, which increased from USD 15.83 Billion in 2025 to an estimated USD 17.83 Billion in 2026, representing the region's position as the global center of industrial manufacturing and electric motor consumption. The induction motor is the foundational electromechanical component powering the vast majority of the region's industrial machinery, pumps, compressors, and HVAC systems, performing the reliable, low-maintenance torque generation that underpins modern manufacturing and infrastructure. The market is projected to reach USD 37.83 Billion by 2034.
Three phase induction motors at 71.8% dominate through their superior efficiency, balanced power delivery, and widespread adoption across heavy industrial applications. The industrial sector at 63.7% leads through extensive use in manufacturing, automation, and heavy machinery across the region's expanding production base. China at 34.6% leads regionally through its position as the world's largest manufacturing hub, supported by India's rapidly growing industrial base and Japan's advanced automation and robotics sectors.
Key Market Insights
|
Insight |
Data |
|
Dominant Product Type |
Three Phase Induction Motors - 71.8% share (2025) |
|
Dominant End Use Sector |
Industrial - 63.7% share (2025) |
|
Leading Country |
China - 34.6% share (2025) |
|
Market Opportunity |
IE3/IE4 premium-efficiency motors; smart motor IoT integration; renewable energy-linked motor demand |
Key Analytical Observations Supporting the Above Data:
- Three Phase Induction Motors at 71.8%: Three phase motors dominate due to their superior efficiency, balanced power supply, and robust performance in heavy-duty industrial applications such as pumps, compressors, and conveyors. Their widespread adoption across manufacturing, oil and gas, and mining sectors by major industrial operators further strengthens segment demand. Continued investment in industrial automation across China and India is reinforcing this segment's structural leadership position.
- Industrial at 63.7%: The industrial sector dominates due to the extensive use of induction motors in manufacturing, heavy machinery, and automation applications across the region's expanding production base. With global manufacturing output continuing to shift toward Asia Pacific, industrial motor procurement generates substantial and sustained demand. Rising adoption of robotics and automated production lines is further reinforcing the industrial sector's leadership position.
- China at 34.6%: China leads through its position as the world's largest manufacturing hub and its extensive industrial base spanning automotive, electronics, and heavy machinery production. In 2025, China's continued investment in smart factory infrastructure generated substantial additional demand for high-efficiency induction motors. This highlights how manufacturing scale and automation investment are reinforcing China's structural leadership position.
Asia Pacific Induction Motor Market Overview
The Asia Pacific induction motor market encompasses the design, manufacture, and supply of AC electric motors that use electromagnetic induction to generate rotational torque, spanning single phase and three phase configurations deployed across industrial, commercial, and residential applications including pumps, compressors, fans, conveyors, HVAC systems, and home appliances.
The ecosystem integrates raw material and component suppliers, induction motor manufacturers, OEM equipment integrators, distribution and system integration partners, and regulatory bodies overseeing motor efficiency standards across the region. Macroeconomic factors include rapid industrialization, rising electricity costs, government energy-efficiency mandates, and continued investment in renewable energy and smart manufacturing infrastructure.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
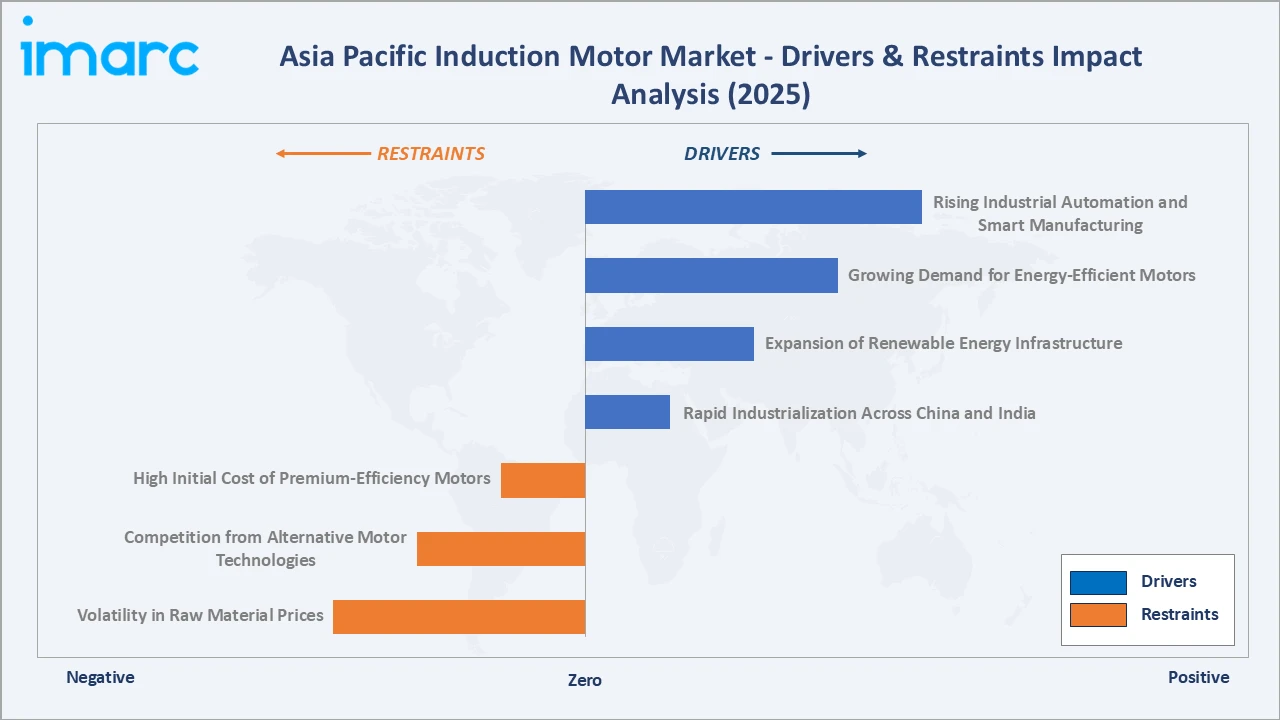
- Rising Industrial Automation and Smart Manufacturing: The increasing adoption of automated production systems and Industry 4.0 technologies across China, India, and Japan is boosting demand for reliable, energy-efficient induction motors. Automated systems rely heavily on induction motors to power conveyors, pumps, and robotic machinery, driving sustained procurement across manufacturing facilities. Rising investment in smart factory infrastructure has further incentivized manufacturers to develop IoT-enabled motor solutions. Government-backed industrial modernization programs across the region are also accelerating automation adoption among small and medium enterprises.
- Growing Demand for Energy-Efficient Motors: Rising electricity costs and stricter energy-efficiency regulations are accelerating the shift toward IE3 and IE4 premium-efficiency induction motors across industrial and commercial applications. Governments across the region are implementing minimum energy performance standards that mandate higher-efficiency motor specifications. This regulatory push is compelling manufacturers to expand their premium-efficiency product lines. Rising awareness of long-term operational cost savings is further reinforcing the shift toward energy-efficient motor adoption among industrial buyers.
- Expansion of Renewable Energy Infrastructure: The region's growing investment in wind and solar energy projects is generating substantial demand for induction motors used in turbine systems, grid support equipment, and renewable energy infrastructure. Induction motors are particularly well-suited to renewable energy applications due to their ability to operate efficiently under variable load conditions. Continued expansion of offshore wind projects across China and Japan is creating additional structural demand. Government renewable energy targets across India and Southeast Asia are further accelerating this demand pool.
- Rapid Industrialization Across China and India: Continued industrial expansion across China and India's manufacturing, automotive, and electronics sectors is driving sustained demand for induction motors used in production machinery and heavy equipment. Rising foreign direct investment in regional manufacturing capacity is further expanding the addressable market for industrial motor suppliers. India's Production Linked Incentive scheme has notably accelerated domestic manufacturing capacity additions. This industrialization trend is expected to sustain robust motor demand growth throughout the forecast period.
Market Restraints
- High Initial Cost of Premium-Efficiency Motors: Premium IE3 and IE4 efficiency induction motors carry significantly higher upfront costs compared to standard-efficiency alternatives, limiting adoption among cost-sensitive buyers in emerging markets such as Indonesia and parts of India. This price premium often extends payback periods beyond what smaller industrial operators are willing to accept. This dynamic continues to sustain demand for standard-efficiency motors among price-sensitive commercial and residential buyers.
- Competition from Alternative Motor Technologies: The growing adoption of permanent magnet synchronous motors and other advanced motor technologies in specific high-performance applications is creating competitive pressure on induction motor demand in premium segments. These alternative technologies often offer superior power density and efficiency in specialized applications such as electric vehicles. This competitive dynamic is compelling induction motor manufacturers to invest in efficiency improvements to maintain their cost-performance advantage.
- Volatility in Raw Material Prices: Fluctuating prices for copper, electrical steel, and aluminum used in induction motor manufacturing create margin pressure and pricing uncertainty for manufacturers across the value chain. Extended raw material lead times during periods of global supply disruption further complicate production planning. Manufacturers with vertically integrated component sourcing are better positioned to manage this volatility than smaller regional competitors.
Market Opportunities
- Smart Motor and IoT-Enabled Monitoring Systems: Growing demand for predictive maintenance and real-time performance monitoring presents an opportunity for manufacturers to develop induction motors embedded with sensors and connectivity modules. Integrated diagnostic capabilities and remote performance tracking are increasingly differentiating premium industrial motor lines.
- India's Expanding Manufacturing and Infrastructure Investment: India's rapidly growing manufacturing base, supported by the Production Linked Incentive scheme and expanding infrastructure development, presents a substantial volume opportunity for both premium and value-tier induction motor manufacturers. Regional manufacturers with localized production and pricing strategies are well positioned to capture this emerging demand pool.
Market Challenges
- Intensifying Price Competition from Regional Manufacturers: Local and regional motor manufacturers are increasingly offering cost-competitive alternatives to established global brands, compressing pricing power and margins for international Tier-1 players operating across Asia Pacific markets. Global brands are responding by accelerating regional manufacturing localization to maintain price competitiveness.
- Fragmented Regulatory and Efficiency Standards Across Regional Markets: Varying minimum energy performance standards, safety certifications, and import duties across China, India, Japan, and Southeast Asia complicate cross-border product launches for manufacturers. Manufacturers with dedicated regional compliance teams hold a meaningful speed-to-market advantage over smaller competitors.
Emerging Market Trends
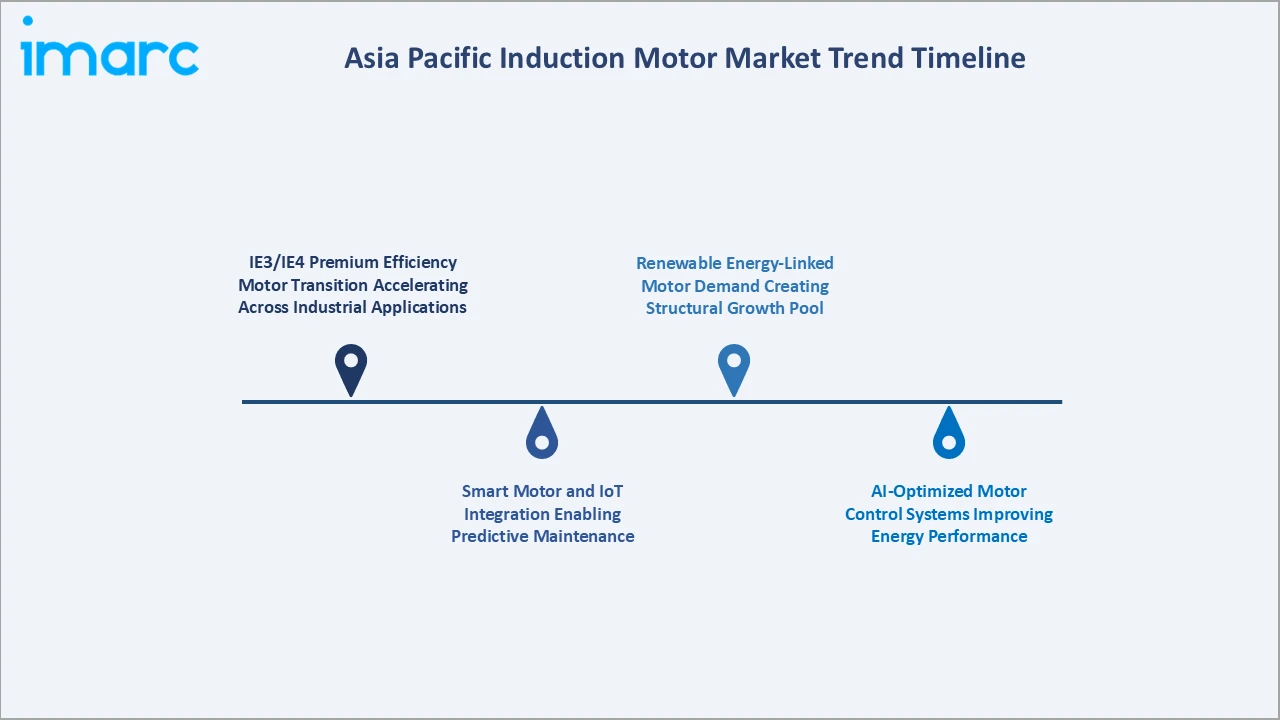
1. IE3/IE4 Premium Efficiency Motor Transition Accelerating Across Industrial Applications
Adoption of IE3 and IE4 premium-efficiency induction motors is accelerating as governments across the region implement stricter minimum energy performance standards for industrial motor applications. This is driving manufacturers to redesign motor windings, cooling systems, and rotor construction to reduce energy losses while maintaining torque performance. Improved manufacturing processes and economies of scale are also gradually narrowing the cost premium between standard and premium-efficiency motors, broadening adoption across mid-tier industrial buyers.
2. Smart Motor and IoT Integration Enabling Predictive Maintenance
Smart motor and IoT integration is emerging as manufacturers embed sensors and connectivity modules directly into induction motor housings, enabling real-time monitoring of temperature, vibration, and power consumption. This design trend can enhance predictive maintenance capabilities, reducing unplanned downtime for industrial operators. As Industry 4.0 adoption continues to expand, demand is rising for induction motors with integrated diagnostic and connectivity features.
3. Renewable Energy-Linked Motor Demand Creating Structural Growth Pool
Renewable energy-linked motor demand is emerging as wind and solar infrastructure expansion across China, India, and Japan creates sustained procurement for induction motors used in turbine yaw systems, pitch control, and grid support equipment. This demand pool is structurally distinct from traditional industrial motor procurement, offering manufacturers a growing high-value application segment as regional renewable energy capacity additions continue to accelerate.
4. AI-Optimized Motor Control Systems Improving Energy Performance
AI-optimized motor control systems are emerging as variable frequency drives increasingly incorporate machine learning algorithms to dynamically adjust motor speed and torque based on real-time load conditions. This design trend can meaningfully reduce energy consumption in variable-load industrial applications such as pumps and compressors. As energy costs continue to rise across the region, demand is increasing for intelligent motor control solutions that optimize performance without requiring motor hardware replacement.
Industry Value Chain Analysis
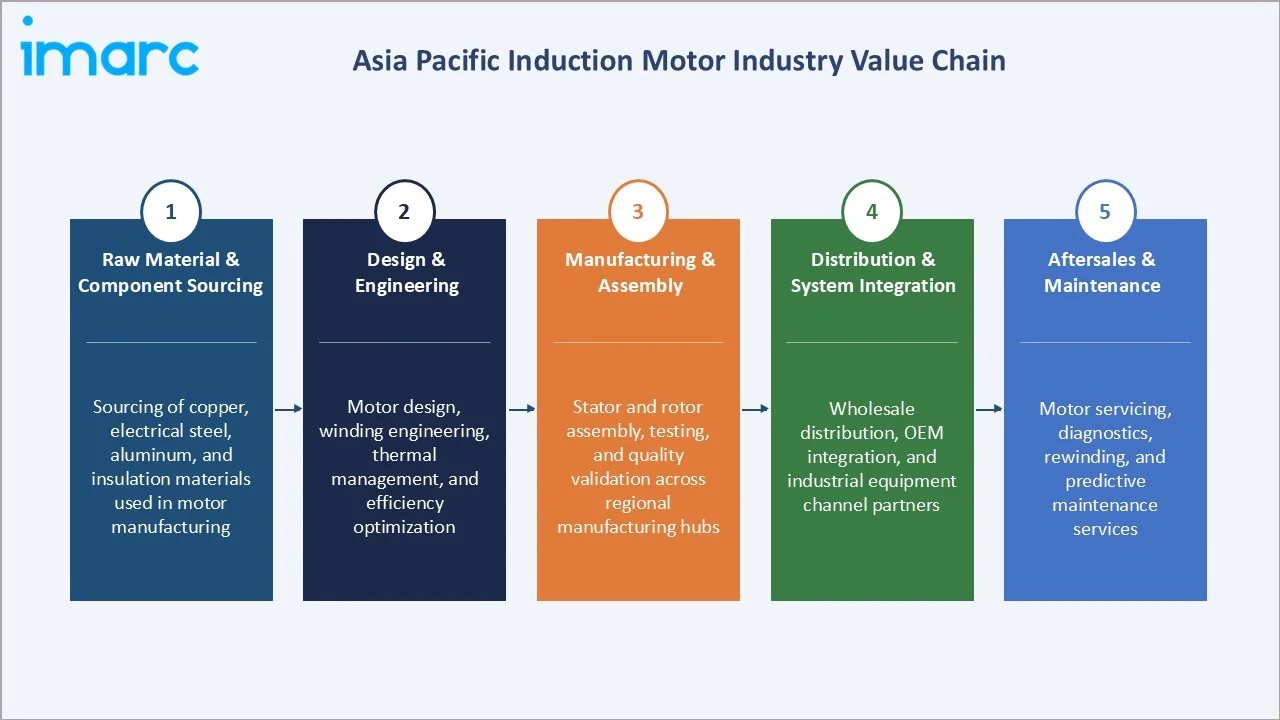
The Asia Pacific induction motor value chain integrates raw material and component sourcing, product design and engineering, manufacturing and assembly, distribution and system integration, and aftersales support and maintenance.
|
Stage |
Key Participants |
|
Raw Material & Component Sourcing |
Sourcing of copper, electrical steel, aluminum, and insulation materials used in motor manufacturing |
|
Design & Engineering |
Motor design, winding engineering, thermal management, and efficiency optimization |
|
Manufacturing & Assembly |
Stator and rotor assembly, testing, and quality validation across regional manufacturing hubs |
|
Distribution & System Integration |
Wholesale distribution, OEM integration, and industrial equipment channel partners |
|
Aftersales & Maintenance |
Motor servicing, diagnostics, rewinding, and predictive maintenance services |
The value chain's commercial architecture continues to consolidate toward integrated motor-drive system offerings as leading manufacturers seek to capture greater value through combined hardware and control system sales.
Technology Landscape in the Asia Pacific Induction Motor Industry
Premium-Efficiency IE3/IE4 Motor Technology
Premium-efficiency IE3 and IE4 motor technology offers reduced energy losses through optimized winding design, improved core materials, and enhanced cooling systems. These motors enable lower operating costs and reduced carbon emissions, making them increasingly preferred for industrial applications with continuous operation requirements. Their compatibility with variable frequency drive systems is further accelerating adoption across energy-conscious industrial buyers.
Variable Frequency Drive Integration Technology
Variable frequency drive integration technology enables precise speed and torque control for induction motors, significantly improving energy efficiency in variable-load applications such as pumps, fans, and compressors. This technology allows motors to operate at optimal efficiency across a wide range of operating conditions rather than running at fixed speed, delivering substantial energy savings for industrial and commercial end users.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Product Type |
Three Phase Induction Motors |
71.8% |
2025 |
|
End Use Sector |
Industrial |
63.7% |
2025 |
|
Country |
China |
34.6% |
2025 |

By Product Type
Three phase induction motors lead the product type segment at 71.8% in 2025, driven by their superior efficiency and widespread adoption across heavy industrial and commercial applications requiring robust, continuous-duty performance.
To access detailed market analysis, Request Sample
Single phase induction motors hold 28.2% share, supported by widespread use in residential appliances, small commercial equipment, and light-duty applications where simplified electrical infrastructure is preferred.
By End Use Sector
The industrial sector leads at 63.7% in 2025, reflecting extensive use of induction motors in manufacturing, heavy machinery, and automation applications across the region's expanding industrial base.
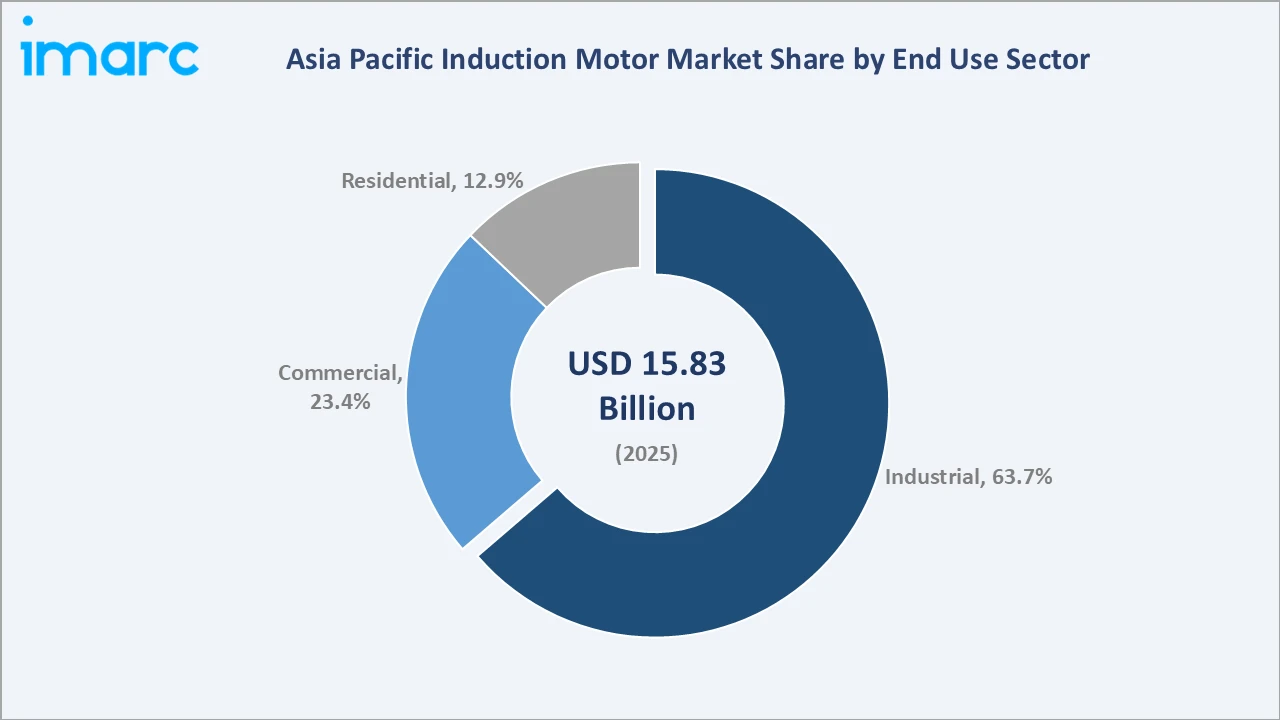
The commercial sector holds 23.4% share, supported by demand from HVAC systems, elevators, and commercial equipment, while the residential sector accounts for 12.9% through continued use in home appliances such as washing machines and water pumps.
Regional Market Insights
|
Country |
Share (2025) |
Key Market Characteristics |
|
China |
34.6% |
Leading market driven by extensive manufacturing capacity, a large industrial base, and continued automation investment |
|
India |
20.8% |
Driven by rapid industrialization, expanding manufacturing incentives, and rising infrastructure development |
|
Japan |
14.7% |
Supported by advanced robotics and electronics manufacturing and strong technology leadership among domestic manufacturers |
|
South Korea |
10.8% |
Driven by a mature electronics and automotive manufacturing base with high automation penetration |
|
Indonesia |
8.1% |
Supported by growing industrial investment and expanding manufacturing infrastructure |
|
Australia |
6.2% |
Driven by mining, resource processing, and infrastructure development requiring robust motor systems |
|
Others |
4.8% |
Emerging industrial markets across the wider Asia Pacific region with rising manufacturing investment |
China, at 34.6%, leads through its extensive manufacturing capacity and continued industrial automation investment. India, at 20.8%, reflects rapid industrialization and expanding domestic manufacturing incentives supporting sustained motor demand growth.
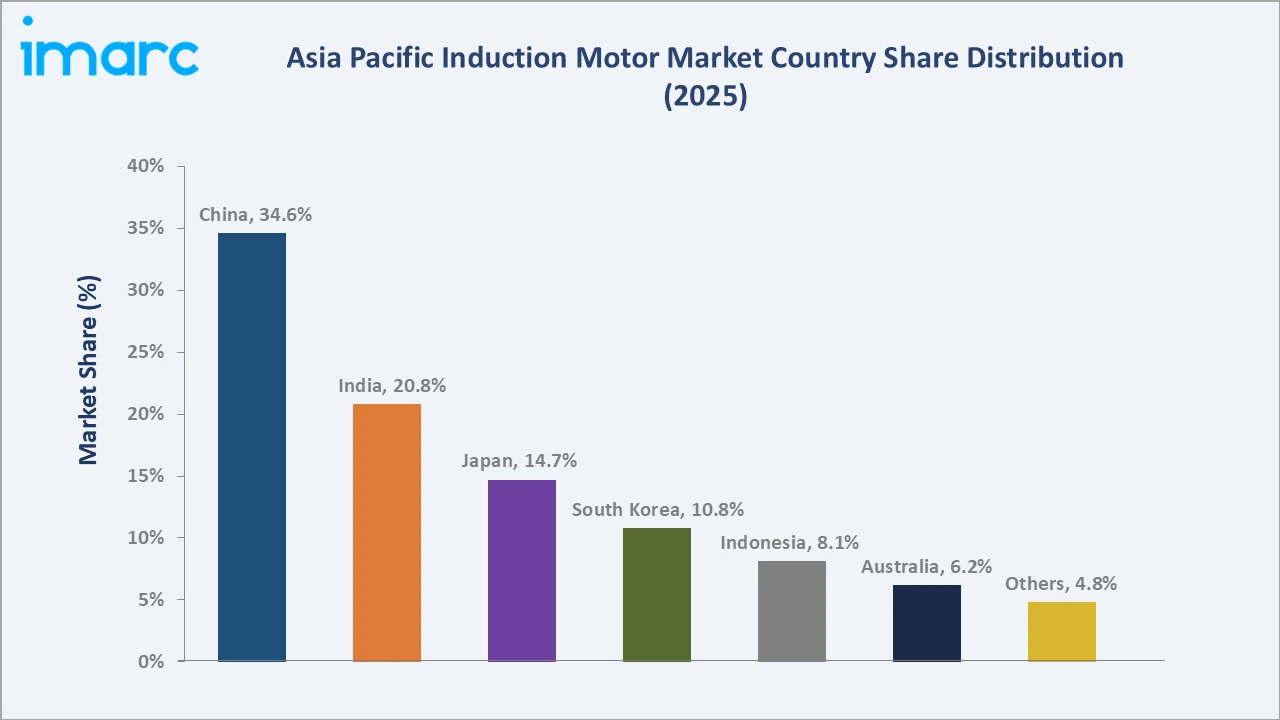
Japan, at 14.7%, and South Korea, at 10.8%, represent structurally important markets driven by advanced robotics and electronics manufacturing, respectively. Indonesia, Australia, and other regional markets collectively contribute the remaining share through steady industrial and resource-sector motor demand.
Competitive Landscape
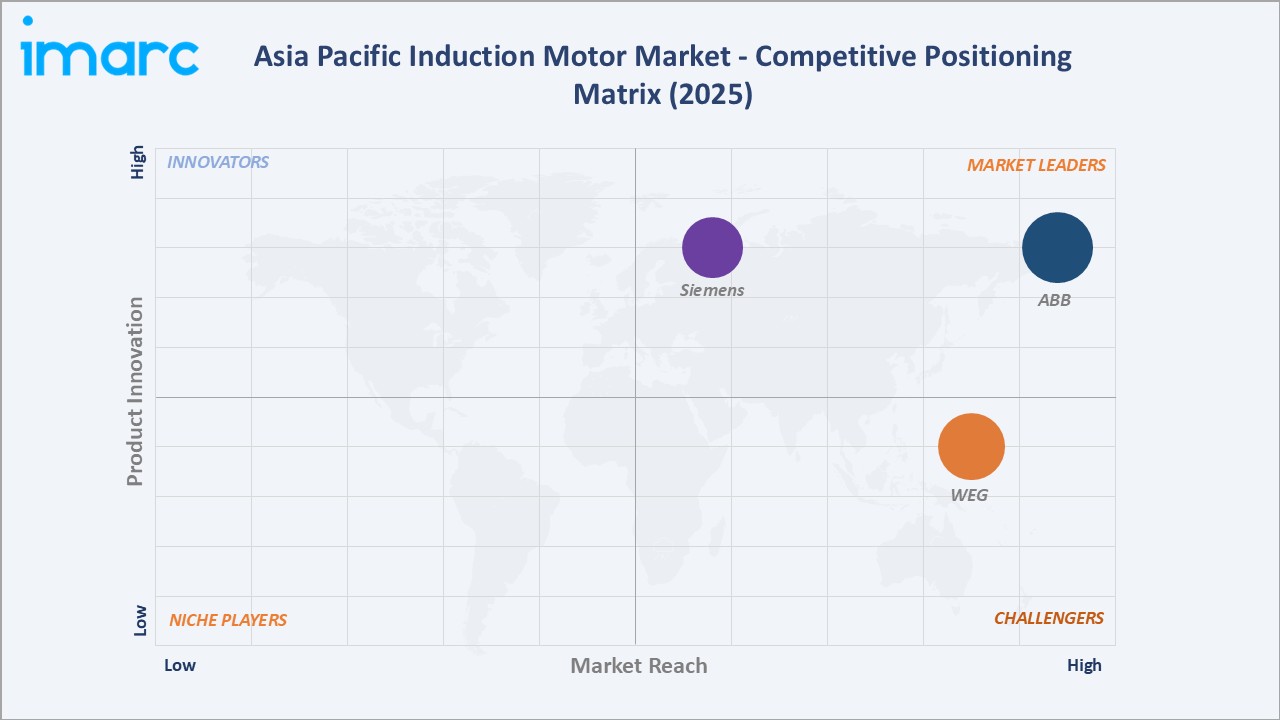
The Asia Pacific induction motor market competitive landscape is moderately consolidated, comprising global industrial conglomerates, specialized motor manufacturers, and regional producers competing across multiple efficiency tiers and application segments.
|
Company Name |
Key Products |
Market Position |
Core Strength |
|
ABB |
Rib cooled motor, Modular Induction Motors, Modular Slip-Ring Motors, MV Titanium |
Market Leader |
Global leader in industrial motors with extensive premium-efficiency product portfolio and strong regional distribution |
|
Siemens |
SIMOTICS L, SIMOTICS M, SIMOTICS S, SIMOTICS T |
Market Leader |
Comprehensive motor and drive systems portfolio with strong industrial automation integration |
|
WEG |
W60 Line, WGM20 Line, Wound Rotor Induction Motors, W60 Vertical, HGF |
Strong Challenger |
Broad induction motor portfolio with strong presence across industrial and commercial applications |
Key players include ABB, Siemens, WEG, and others.
Key Company Profiles
ABB
ABB is a global leader in industrial technology with an extensive induction motor portfolio spanning standard and premium-efficiency motors sold across Asia Pacific through both direct sales and distributor networks.
- Key Products: Rib cooled motor, Modular Induction Motors, Modular Slip-Ring Motors, MV Titanium
- Strategic Focus: Expanding premium-efficiency induction motor lineups tailored to energy-conscious industrial and commercial buyers across the region. The company continues to deepen partnerships with regional system integrators to strengthen distribution reach across emerging Southeast Asian markets. It is also investing in smart motor technology integration to support predictive maintenance and Industry 4.0 adoption among industrial customers.
Siemens
Siemens is a global industrial technology company with a strong presence in the induction motor market through its comprehensive motor and drive systems portfolio serving industrial automation customers across Asia Pacific.
- Key Products: SIMOTICS L, SIMOTICS M, SIMOTICS S, SIMOTICS T
- Strategic Focus: Strengthening its integrated motor-drive systems portfolio and expanding distribution across China, India, and Japan's industrial automation segments. The company is prioritizing partnerships with regional system integrators to improve solution deployment and after-sales support. Continued investment in digital twin and IoT-enabled motor monitoring technology remains central to its competitive positioning.
Market Concentration Analysis
The Asia Pacific induction motor market is moderately consolidated, with the key players collectively accounting for a meaningful share of premium and mid-tier segment revenue. Regional and local manufacturers account for a substantial share of entry-level and value-tier volume, particularly across India and Indonesia. Market concentration is expected to remain broadly stable over the forecast period as regional manufacturers continue to gain share in price-sensitive segments while global brands retain leadership in the premium-efficiency and industrial-grade product tiers. Continued investment in local manufacturing capacity is likely to reinforce the position of established players within the premium segment, even as new entrants target underserved price points across emerging Southeast Asian markets.
Investment & Growth Opportunities
Highest Growth Segments
Three phase induction motors (~10.6% CAGR), industrial end-use applications (~10.9% CAGR), premium-efficiency IE3/IE4 motors, and renewable energy-linked motor demand represent the highest-growth investment vectors through 2034.
Emerging Investment Opportunities
Smart motor and IoT-enabled monitoring systems represent the market's highest per-unit-value emerging opportunity, as predictive maintenance-enabled induction motors command significant price premiums over standard consumer-grade equivalents, with regional Industry 4.0 adoption creating a structurally growing demand pool through 2034.
Future Market Outlook (2026-2034)
The Asia Pacific induction motor market is projected to grow from USD 15.83 Billion in 2025 to USD 17.83 Billion in 2026 and is forecast to reach USD 37.83 Billion by 2034, delivering a 9.86% CAGR over the forecast period. The market's anchor value of USD 25.33 Billion in 2030 represents an inflection point at which premium-efficiency motors are expected to have become the dominant specification across mid-tier and industrial segments, smart motor IoT integration will have reached greater scale, and renewable energy-linked motor demand will have achieved wider mainstream adoption across the region's leading industrial economies.
Two structural forces define market growth through 2034 with strong confidence. The region's compounding industrialization and automation investment creates a self-reinforcing demand cycle where manufacturing capacity expansion begets motor procurement, which begets further automation investment. The renewable energy infrastructure build-out across China, India, and Japan creates an additive demand pool above the already substantial industrial and commercial motor base across the region's manufacturing economies.
Research Methodology
Primary Research
Primary research comprised structured interviews with industry stakeholders, including product managers, regional distribution partners, industrial automation specialists, and system integration executives across China, India, Japan, and South Korea.
Secondary Research
Secondary research encompassed company annual reports, regional industrial association data, energy-efficiency regulatory filings, and motor technology industry publications covering the Asia Pacific region.
Forecasting Models
Market revenue forecasts were developed using a bottom-up model incorporating regional industrial output estimates, average motor spend per facility by product type and end-use sector, and premiumization trend adjustments across the historical and forecast periods.
Asia Pacific Induction Motor Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report | Exploration of Historical and Forecast Trends, Industry Catalysts and Challenges, Segment-Wise Historical and Predictive Market Assessment:
|
| Product Types Covered | Single-Phase Induction Motors, Three-Phase Induction Motors |
| End Use Sectors Covered | Industrial, Residential, Commercial |
| Countries Covered | China, Japan, India, South Korea, Australia, Indonesia, Others |
| Companies Covered | ABB, Siemens, WEG, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Asia Pacific induction motor market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the Asia Pacific induction motor market.
- Porter's five forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Asia Pacific induction motor industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Asia Pacific Induction Motor Market Report
The Asia Pacific induction motor market size is estimated at USD 17.83 Billion in 2026, driven by the three phase induction motor segment dominant at 71.8%, the industrial sector leading at 63.7%, and China commanding the largest country share at 34.6% through its extensive manufacturing base and continued automation investment.
The market grows at a 9.86% CAGR during 2026-2034, reaching USD 37.83 Billion by 2034. This growth reflects rising industrial automation, expanding renewable energy infrastructure, and continued energy-efficiency regulation across the region.
Three phase induction motors lead at 71.8% share, driven by their superior efficiency and widespread adoption in heavy industrial applications. This segment grows at approximately 10.6% CAGR through continued industrial automation investment and expanding manufacturing capacity.
The industrial sector leads at 63.7% through extensive use in manufacturing, heavy machinery, and automation applications, creating sustained procurement expansion. Industrial demand grows fastest at approximately 10.9% CAGR through continued Industry 4.0 adoption.
China leads at 34.6% through its extensive manufacturing capacity, strong industrial base, and continued automation and smart factory investment.
Leading companies include ABB, Siemens, WEG, and others.
The market is projected to reach approximately USD 25.33 Billion by 2030, with premium-efficiency motors becoming the dominant specification across mid-tier and industrial segments and smart motor IoT integration achieving wider mainstream adoption.
Priority investment opportunities include smart motor IoT-enabled monitoring system development, premium-efficiency IE3/IE4 motor technology innovation, and expansion into renewable energy-linked motor applications across China, India, and Japan.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade