Australia 3D Printing Market Size, Share, Trends and Forecast by Technology, Process, Material, Offering, Application, End-User, and Region, 2026-2034
Australia 3D Printing Market Size, Share, Trends & Forecast (2026-2034)
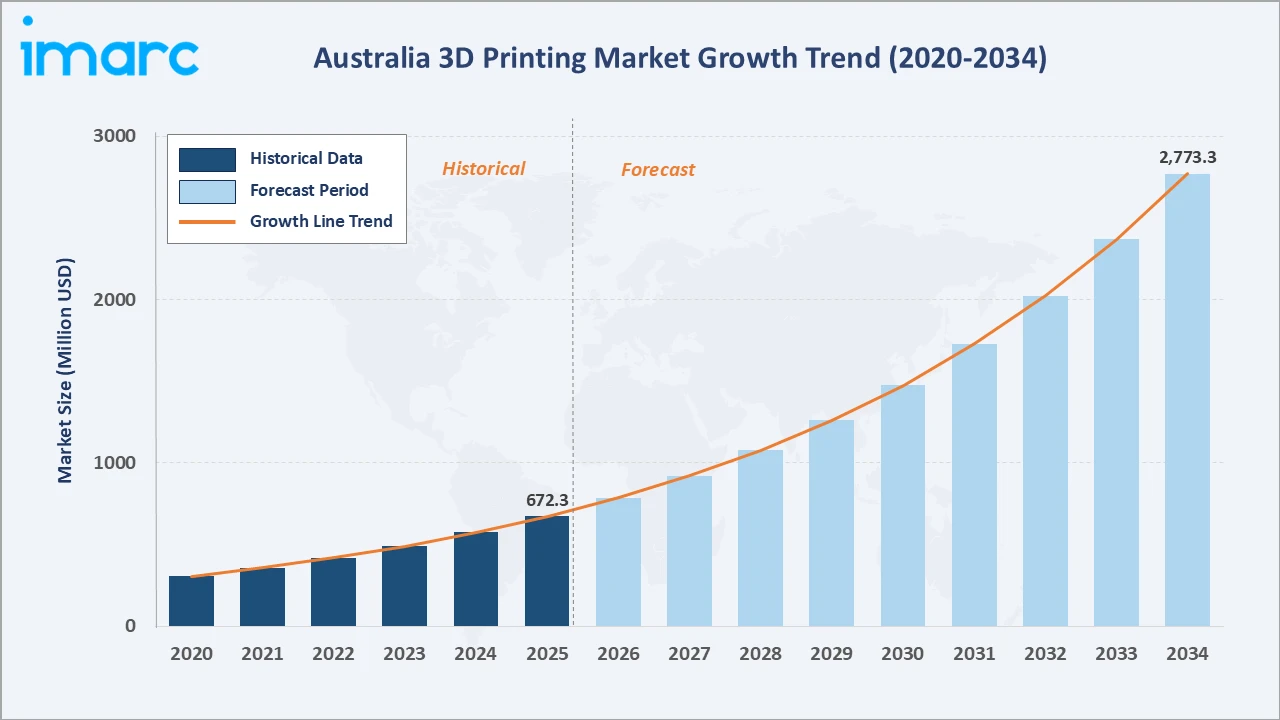
The Australia 3D printing market grew from USD 672.3 Million in 2025 to USD 787.0 Million in 2026 and is projected to reach USD 2,773.3 Million by 2034, growing at a CAGR of 17.05% during 2026-2034. Demand is widening as aerospace, defense, medical, mining and general engineering users move additive processes from experimental use into qualified production. Rising output of metal and polymer parts, together with growing local capacity in powders, printers and contract services, is deepening the domestic supply base. Supporting growth factors include adoption of digital design, material innovation and defense localization. Fused deposition modeling dominates at 28.6%. Prototyping leads at 46.2%. Australia Capital Territory & New South Wales commands 36.5% of the regional market share.
Market Snapshot
| Metric | Value |
|---|---|
| Base Year Market Size (2025) | USD 672.3 Million |
| Market Size (2026) | USD 787.0 Million |
| Forecast Market Size (2034) | USD 2,773.3 Million |
| CAGR (2026-2034) | 17.05% |
| Base Year | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Dominant Technology | Fused Deposition Modeling (28.6%, 2025) |
| Dominant Application | Prototyping (46.2%, 2025) |
| Leading Region | Australia Capital Territory & New South Wales (36.5%, 2025) |
The market size increased from USD 306.0 Million in 2020 to USD 672.3 Million in 2025 and is estimated to reach USD 787.0 Million in 2026. The market is expected to grow to USD 1,477.3 Million by 2030 and USD 2,773.3 Million by 2034.
To get more information on this market, Request Sample
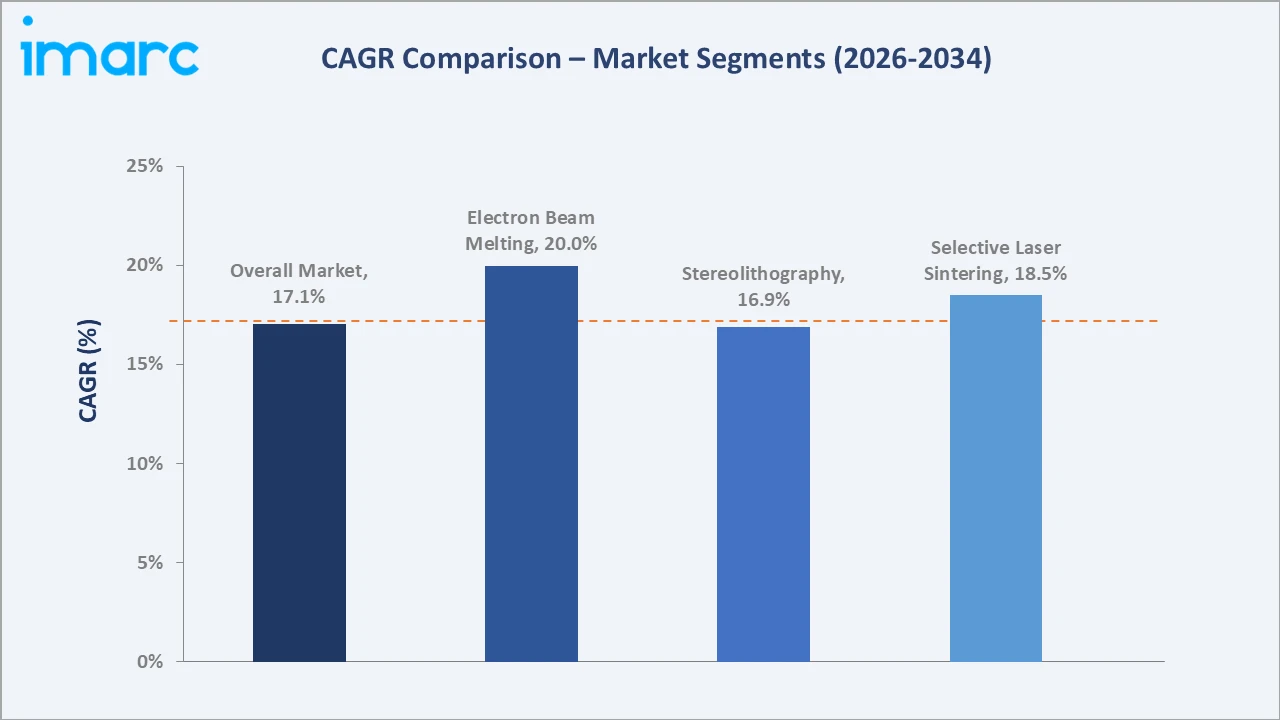
Electron beam melting at ~20.0% CAGR and selective laser sintering at ~18.5% CAGR are the fastest-growing technologies, supported by qualified metal part demand in aerospace and medical uses and by rising functional polymer production. Both gain from the additive manufacturing market shift toward end-use parts.
Executive Summary
The market expanded from USD 672.3 Million in 2025 to an estimated USD 787.0 Million in 2026, with demand anchored in rapid prototyping for product developers, tooling support for manufacturers and a growing pipeline of certified end-use parts for aerospace, defense, medical and resources customers. The fastest-developing areas are metal powder bed and electron beam processes, functional part manufacturing and high-resolution polymer systems, each outpacing the overall market because they combine higher part value with qualification requirements that favor experienced service providers.
Local capability building, defense sovereignty priorities and the need for rapid spare part supply across distant operating sites are widening the customer base. The market is projected to reach USD 2,773.3 Million by 2034. Fused deposition modeling at 28.6% leads through low machine cost and wide material choice. Prototyping at 46.2% reflects design iteration demand across industries. Australia Capital Territory & New South Wales lead regionally at 36.5%.
Key Market Insights
| Insight | Data |
|---|---|
| Dominant Technology | Fused Deposition Modeling - 28.6% share (2025) |
| Dominant Application | Prototyping - 46.2% market share (2025) |
| Leading Region | Australia Capital Territory & New South Wales - 36.5% share (2025) |
| Market Opportunity | Defense and sovereign manufacturing, metal part qualification, on-site spare part production, medical and dental customization. |
Key Analytical Observations Supporting the Above Data:
- Fused Deposition Modeling at 28.6%: Affordable machines, broad thermoplastic choice and simple operation make this process the entry point for schools, workshops and design teams, sustaining the largest installed base across the country.
- Prototyping at 46.2%: Product developers use additive builds to compress design cycles and validate form and fit before tooling spend, so prototyping remains the highest-volume use across engineering, consumer and medical device firms.
- Australia Capital Territory & New South Wales at 36.5%: Dense clusters of research institutes, defense agencies, hospitals and advanced manufacturers create concentrated demand for both equipment and specialist service bureaus.
Australia 3D Printing Market Overview
The Australia 3D printing market combines machine suppliers, material producers, software vendors and service bureaus serving a geographically dispersed customer base. Polymer processes dominate unit volume, while metal systems carry higher value in aerospace, defense, mining and medical applications. A distinctive feature of the 3D printing industry in Australia is the presence of locally developed metal technologies, including wire arc, cold spray and powder production, alongside imported polymer and powder bed platforms sold through distributors.
Universities and research organizations act as technology incubators, training engineers and validating new materials. Customers range from hobbyists and schools to defense primes and hospital groups. Remote operations in resources and logistics value printing parts on demand, since shipping lead times are long. Standards, qualification and skilled operators remain the gating factors for scaling production use.
Market Dynamics
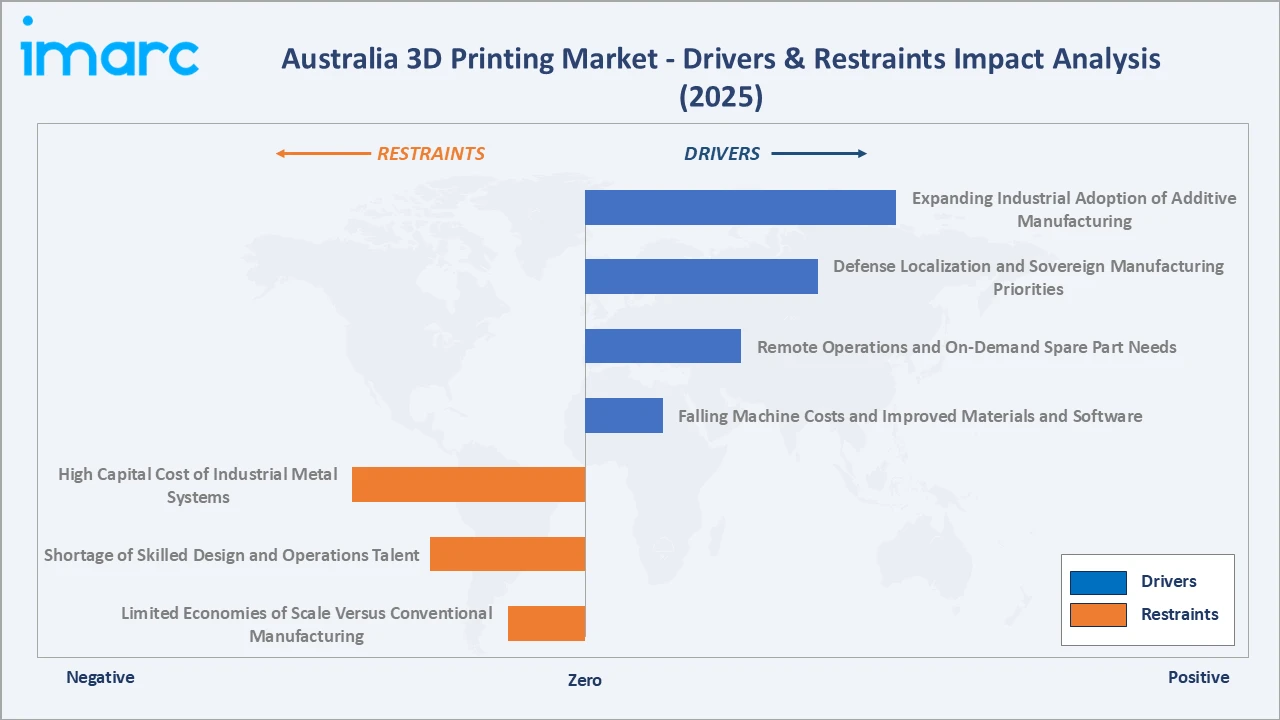
To evaluate market opportunities, Request Sample
Market Drivers
- Expanding Industrial Adoption of Additive Manufacturing: Manufacturers across aerospace, defense, automotive, energy and medical devices are moving beyond concept models toward jigs, fixtures and end-use components. Additive methods remove tooling costs for low-volume parts, shorten design cycles and permit geometries that conventional machining cannot achieve.
- Defense Localization and Sovereign Manufacturing Priorities: According to the Australian Bureau of Statistics (ABS), the defense industry generated $11.9 billion in gross value added (GVA) for the Australian economy in 2023–24. Government emphasis on domestic industrial capability is encouraging investment in local metal additive manufacturing, powder supply and repair technologies. Defense customers value the ability to produce and certify parts closer to the point of need, reducing dependence on long overseas supply lines.
- Remote Operations and On-Demand Spare Part Needs: Mining, resources, marine and infrastructure operators work in locations where waiting for replacement parts causes costly downtime. Printing a part on site or at a nearby bureau shortens delivery from weeks to days and reduces warehouse stock. Portable and rugged systems, along with digital part libraries, make this model increasingly practical.
- Falling Machine Costs and Improved Materials and Software: Desktop and professional systems have become cheaper, more reliable and easier to operate, widening access for schools, startups and workshops. Broader material portfolios, including engineering thermoplastics, photopolymers, metal powders and composites, enable more applications. Improved slicing, simulation and design software reduce failed builds and speed up learning.
Market Restraints
- High Capital Cost of Industrial Metal Systems: Industrial metal printers, inert gas handling, powder management and post-processing equipment require substantial upfront investment, and installation demands specialized facilities. Smaller firms often struggle to justify these costs without secured contract volumes. Financing is harder because machine residual values are uncertain as technology evolves quickly.
- Shortage of Skilled Design and Operations Talent: Effective additive production requires expertise in design for additive manufacturing, materials science, process control and post-processing. The local talent pool is small relative to demand, and training pipelines take time to mature. Companies often rely on imported expertise or invest heavily in in-house training.
- Limited Economies of Scale Versus Conventional Manufacturing: For higher volumes, injection molding, casting and machining still deliver lower unit costs and faster throughput. Build speed, part size limits and surface finish requirements restrict additive methods in mass production. Imported machines and materials add freight and currency exposure.
Market Opportunities
- Expansion of 3D Printing Applications in High-Rise Construction: In June 2026, Luyten unveiled ASCEND, the world's first 3D-printed tower crane platform, capable of printing concrete structures up to 100 meters tall, advancing the application of 3D printing in high-rise construction. Its ability to print concrete structures up to 100 meters tall is expected to accelerate the adoption of additive manufacturing in high-rise buildings and infrastructure development.
- Healthcare Customization and Dental Applications: Patient-specific implants, surgical guides, prosthetics and dental aligners and models benefit from the design freedom of additive manufacturing. Hospitals and dental laboratories increasingly operate in-house printing capabilities, creating demand for biocompatible materials, validated workflows and training.
- Distributed Production and Digital Inventory Models: Companies are exploring digital warehouses where part files are stored and printed near the point of use. This model reduces inventory, shortens delivery times and supports resilience against supply disruption. Logistics, utilities, mining and marine operators are natural early adopters.
Market Challenges
- Qualification and Standards Complexity: Printed parts for safety-critical use must pass rigorous testing, and standards continue to evolve across materials and processes. Each new material, machine, or build orientation may require fresh validation, adding time and cost.
- Material and Powder Supply Dependence: Many specialty powders, resins and filaments are imported, exposing buyers to price swings, lead time variability and shipping delays. Material properties can vary between batches, affecting part consistency.
- Intellectual Property and Data Security Concerns: Digital part files can be copied or altered, raising worries about intellectual property protection and counterfeit parts. Defense and medical users demand secure data handling and traceability.
Emerging Market Trends
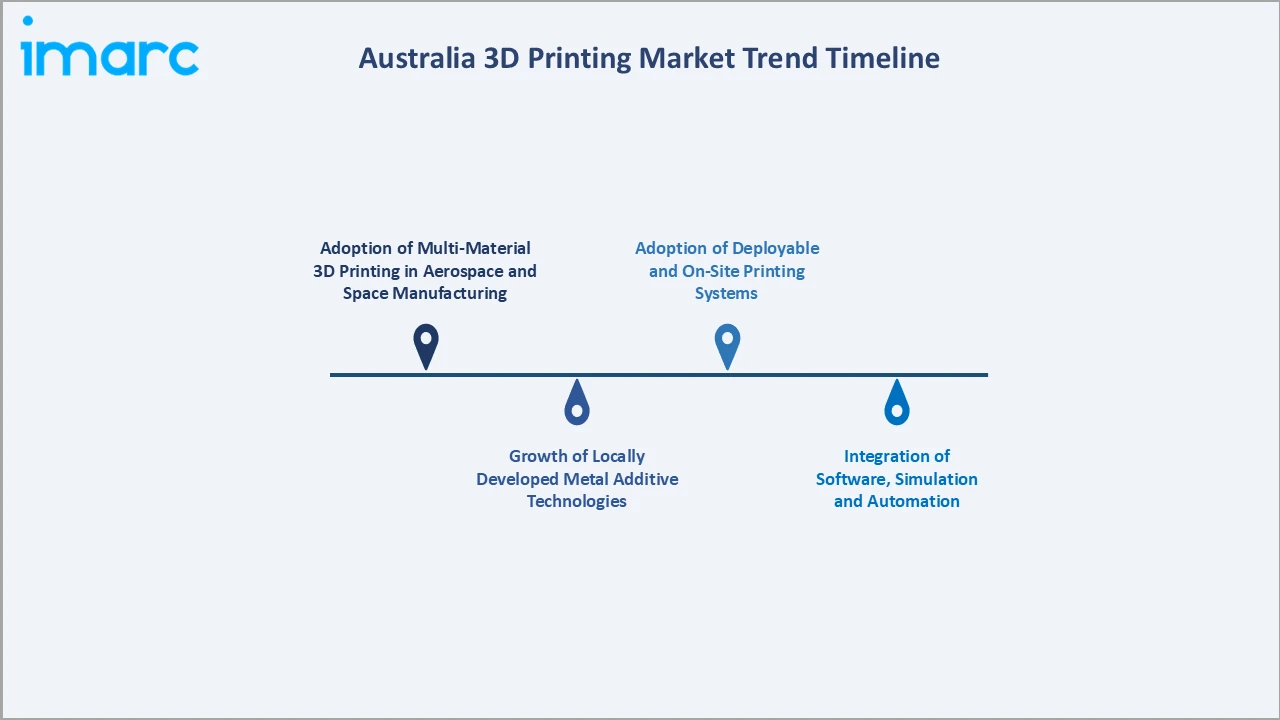
1. Adoption of Multi-Material 3D Printing in Aerospace and Space Manufacturing
In September 2025, Australia achieved a milestone in sovereign space manufacturing with the successful 3D printing of its first bimetal rocket thruster. Developed by Space Machines Company and manufactured at CSIRO's Lab22 facility, the thruster will power the Australian-made Optimus Viper spacecraft for on-orbit servicing and logistics missions. This development is expected to encourage the adoption of multi-material metal 3D printing for complex spacecraft components, propulsion systems, and other high-performance space applications.
2. Growth of Locally Developed Metal Additive Technologies
Domestic companies are commercializing wire arc additive manufacturing, cold spray deposition and metal powder production aimed at defense, marine and resources customers. These technologies are suited to large components, repairs and rugged field deployment, areas where conventional powder bed systems face limits. Export contracts and government support are helping these firms scale. The trend strengthens local intellectual property and creates a differentiated national position in the 3D printing industry in Australia, supported by growing links between technology developers, universities and end users.
3. Adoption of Deployable and On-Site Printing Systems
Rugged and containerized printing systems are being tested for mines, naval vessels and field maintenance camps. They allow operators to produce replacement parts without waiting for freight, supporting uptime and cutting inventory. Digital part libraries and remote engineering support complement the hardware. As confidence in printed spares grows, operators expand from trial parts to routine replacement programs. This trend links additive manufacturing directly to operational resilience, which is a persuasive commercial argument for asset-heavy industries with long supply lines.
4. Integration of Software, Simulation and Automation
Build preparation, simulation, automated nesting and post-processing workflows are becoming more integrated, reducing manual effort and failed builds. Cloud platforms enable instant quoting, remote monitoring and fleet management across several machines. Automation of depowdering, support removal and surface finishing addresses bottlenecks that limit throughput. Providers that combine hardware, software and services into a unified workflow can serve more demanding customers and lower per-part cost, supporting wider acceptance of additive production beyond specialist teams.
Industry Value Chain Analysis
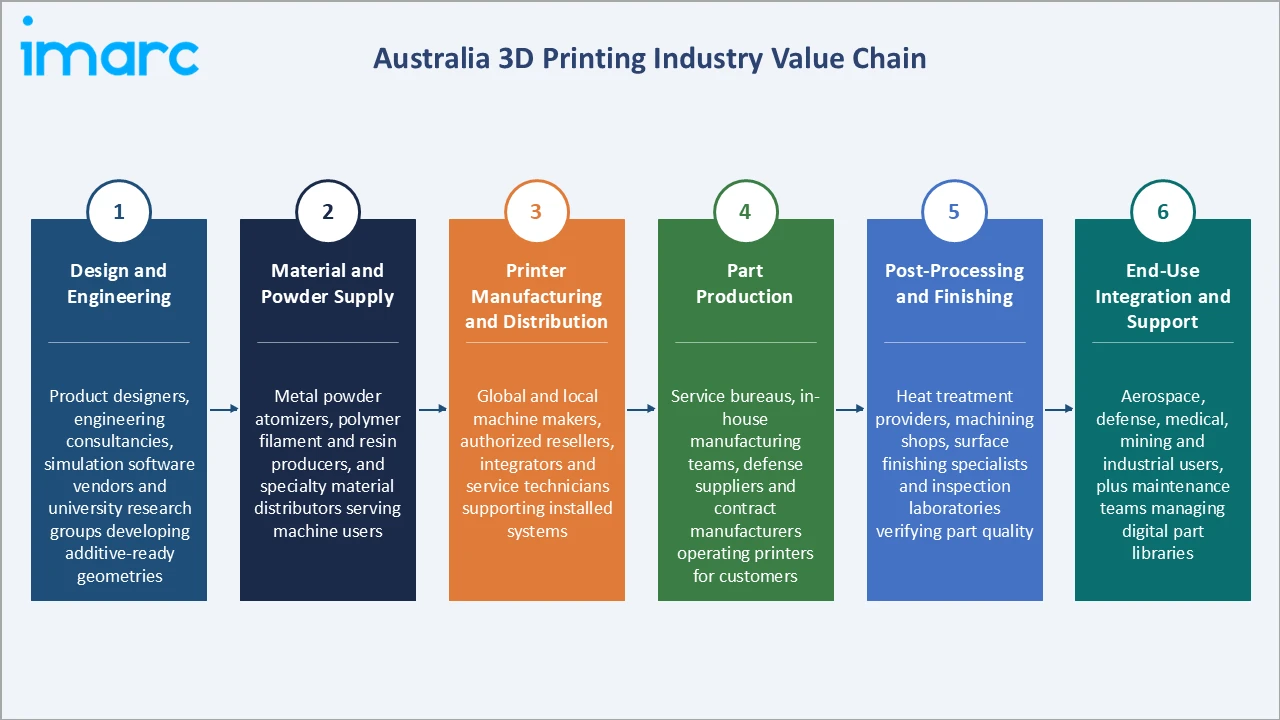
The industry value chain spans design and engineering, material and powder supply, printer manufacturing and distribution, part production, post-processing and finishing, and end-use integration and support. Value accumulates as digital designs are converted into qualified physical parts, with materials expertise and quality assurance determining how reliably components reach demanding customers.
| Stage | Key Participants |
|---|---|
| Design and Engineering | Product designers, engineering consultancies, simulation software vendors and university research groups developing additive-ready geometries. |
| Material and Powder Supply | Metal powder atomizers, polymer filament and resin producers, and specialty material distributors serving machine users. |
| Printer Manufacturing and Distribution | Global and local machine makers, authorized resellers, integrators and service technicians supporting installed systems. |
| Part Production | Service bureaus, in-house manufacturing teams, defense suppliers and contract manufacturers operating printers for customers. |
| Post-Processing and Finishing | Heat treatment providers, machining shops, surface finishing specialists and inspection laboratories verifying part quality. |
| End-Use Integration and Support | Aerospace, defense, medical, mining and industrial users, plus maintenance teams managing digital part libraries. |
Part production is the most commercially critical stage, because qualified process control and quality documentation convert digital files into certified, reliable components. Providers that master this step capture the strongest customer loyalty and pricing power.
Technology Landscape in the Australia 3D Printing Industry
Fused Deposition Modeling
Fused deposition modeling extrudes heated thermoplastic filament layer by layer and remains the most accessible process for prototyping, jigs and low-cost functional parts. Machines range from desktop units to large-format industrial systems using engineering polymers and fiber-reinforced composites. Low operating cost, simple handling and broad material choice sustain its leading installed base across schools, workshops and factories.
Stereolithography and Digital Light Processing
Stereolithography and digital light processing cure liquid photopolymer resin with lasers or projected light to deliver fine detail and smooth surfaces. They are widely used for dental models, jewelry patterns, medical device prototypes and precise tooling. Newer resins add toughness, heat resistance and biocompatibility, expanding functional use. Faster projection engines and automated washing and curing stations reduce labor and improve throughput.
Selective Laser Sintering
Selective laser sintering fuses polymer powder, commonly nylon, with a laser to build durable parts without support structures, allowing dense nesting and efficient batch production. It is favored for functional prototypes, small series production, enclosures and complex assemblies. Improved powder reuse, better process control and growing material choices are lowering cost per part.
Electron Beam Melting and Metal Additive Processes
Electron beam melting uses a high-energy beam in a vacuum to fuse metal powder, producing dense parts with low residual stress, notably in titanium and other reactive alloys. It suits aerospace components and orthopedic implants where material integrity is critical. Alongside it, laser powder bed, wire arc and cold spray processes address different part sizes and repair needs.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Technology | Fused Deposition Modeling | 28.6% | 2025 |
| Process | 🔒 | 🔒 | 2025 |
| Material | 🔒 | 🔒 | 2025 |
| Offering | 🔒 | 🔒 | 2025 |
| Application | Prototyping | 46.2% | 2025 |
| End-User | 🔒 | 🔒 | 2025 |
| Region | Australia Capital Territory & New South Wales | 36.5% | 2025 |

By Technology
Fused deposition modeling leads at 28.6% (2025). Low machine and material cost, easy operation and a wide choice of thermoplastics make it the default choice for design studios, schools and workshops. Its flexibility across prototypes, fixtures and light production supports a broad and recurring user base.
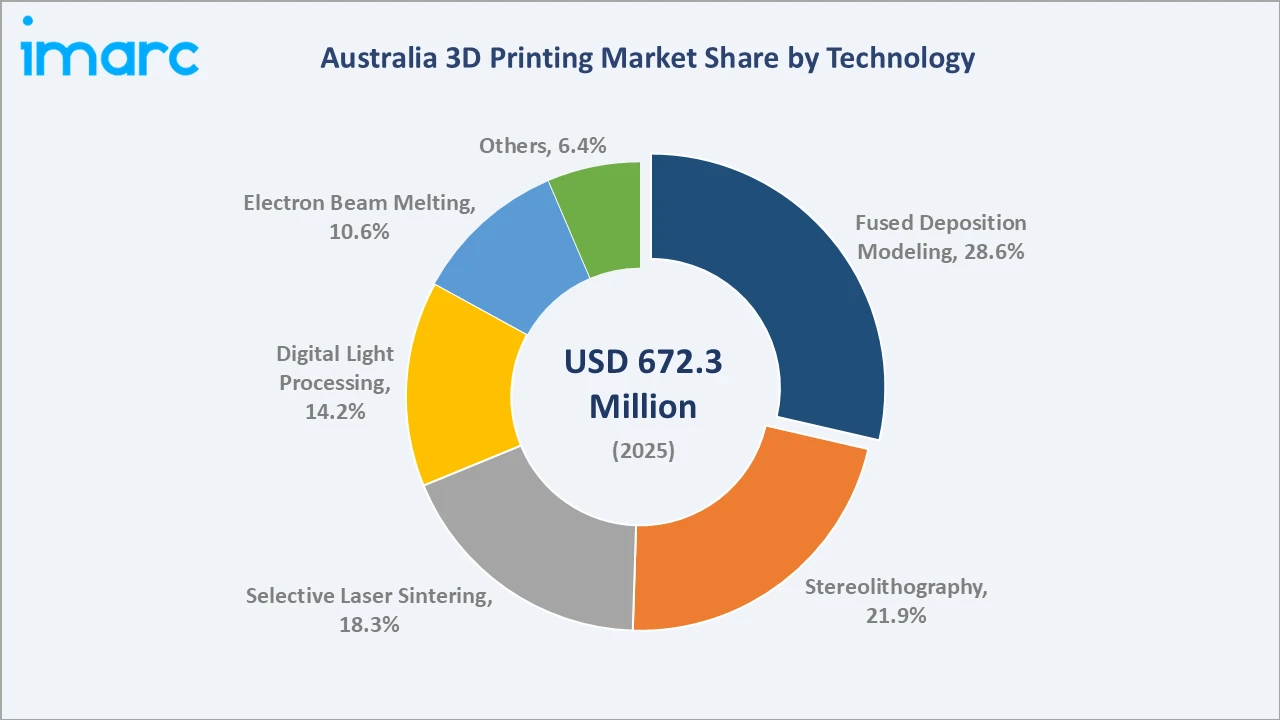
To access detailed market analysis, Request Sample
Electron beam melting at 10.6% is the fastest-growing technology at ~20.0% CAGR. Demand for dense, certified titanium and alloy parts in aerospace, defense and orthopedic use is rising, while local powder supply and qualification support are improving. Stereolithography at 21.9%, selective laser sintering at 18.3%, digital light processing at 14.2%, and others account for 6.4%.
By Application
Prototyping leads at 46.2% (2025). Product developers rely on fast, low-cost physical models to test design, fit and function before committing to tooling. Short iteration cycles and wide industry use, from consumer products to medical devices, keep prototyping the largest source of printing volume.
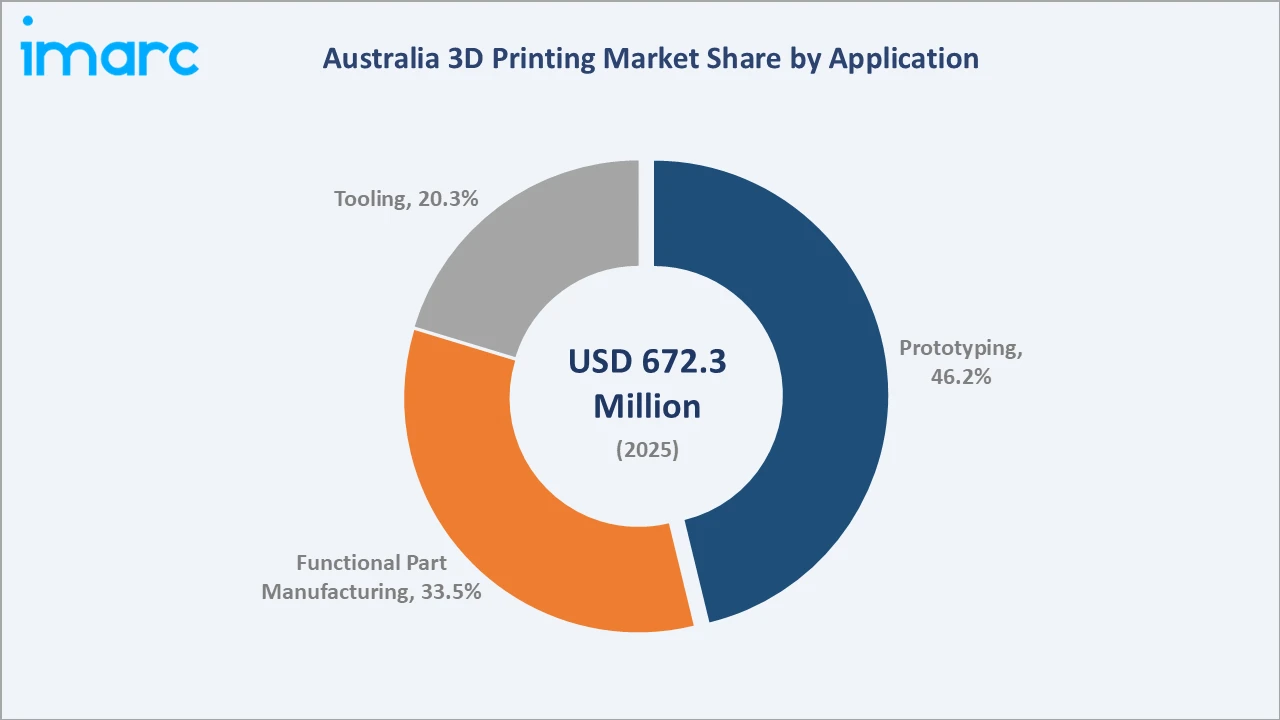
Functional part manufacturing at 33.5% is the fastest-growing application at ~19.4% CAGR. Improved materials, process monitoring and qualification pathways let manufacturers use printed parts in final assemblies. Spare part needs at remote sites and low-volume production economics further support rapid expansion of this application. The tooling segment accounts for 20.3%.
Regional Market Insights
| Region | Share (2025) | Key Drivers & Characteristics |
|---|---|---|
| Australia Capital Territory & New South Wales | 36.5% | Research institutes, defense agencies, hospitals and advanced manufacturers concentrated in the region. |
| Victoria & Tasmania | 25.8% | Strong aerospace, automotive and medical device base around Melbourne, plus university research collaboration. |
| Queensland | 17.9% | Mining services, marine and defense suppliers, and growing advanced manufacturing clusters. |
| Western Australia | 11.4% | Resources sector demands on-site spare parts and maintenance, plus emerging metal additive service providers. |
| Northern Territory & Southern Australia | 8.4% | Defense shipbuilding and industry programs, plus remote operations needing rapid part supply. |
Australia Capital Territory & New South Wales holds 36.5% of the Australia 3D printing market, supported by dense research, defense and healthcare customers that sustain demand for equipment and service bureaus. Victoria & Tasmania account for 25.8%, driven by aerospace, automotive and medical device manufacturing that anchors the additive manufacturing market in the southeast.
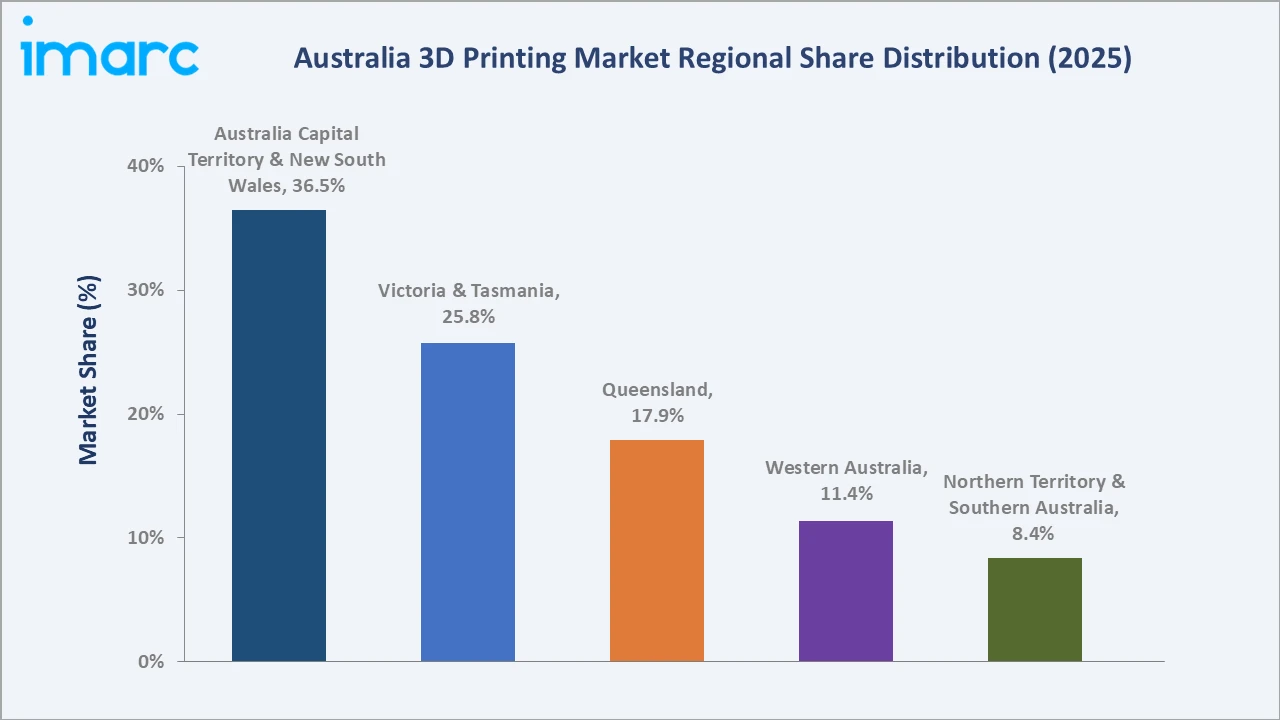
Queensland contributes 17.9% through mining services, marine and defense suppliers. Western Australia holds 11.4%, shaped by resources operators seeking on-site parts. Northern Territory & Southern Australia accounts for 8.4%, supported by defense shipbuilding programs and remote operations.
Competitive Landscape
The competitive landscape is fragmented and segmented by technology and customer type. Local metal additive specialists compete for defense, marine and resources contracts, global polymer machine makers sell through authorized resellers, and service bureaus compete on turnaround, quality systems and material range. Competition turns on qualification, technical support, material access and the ability to deliver certified parts.
| Company | Key Offerings | Market Position | Core Strength |
|---|---|---|---|
| AML3D Limited | ARCEMY systems, WAM Materials | Market Leader | AML3D Limited plays a pioneering and strategic role in the Australian and global additive manufacturing (3D printing) market as a leader in large-scale metal 3D printing. |
| SPEE3D | XSPEE3D, WarpSPEE3D, LightSPEE3D | Innovator | SPEE3D plays a pioneering and high-impact role in Australia's metal 3D printing and advanced manufacturing sectors, driven by its proprietary Cold Spray Additive Manufacturing (CSAM) technology. |
| Aurora Labs | Laser Powder Bed Fusion (LPBF) | Innovator | Aurora Labs plays a key role in Australia's advanced manufacturing, aerospace, and defense sectors by shifting from a pure 3D-printer developer into a specialized metal 3D-printing and propulsion systems manufacturer. |
| 3D Systems, Inc. | 3D Printers, 3D Printing Materials | Established Player | 3D Systems, Inc. operates in the Australian additive manufacturing market as an enterprise technology and solutions provider, supporting local industrial, medical, and aerospace sectors through direct regional presence, local service bureaus, and authorized distribution channels. |
Global suppliers compete on breadth, reliability and installed base, while local innovators compete on differentiated processes and proximity to government customers. Both groups are expanding service offerings and certification credentials, because qualified parts and technical support, rather than machine price alone, increasingly determine contract wins. Partnerships between technology developers, universities and defense primes are further shaping which suppliers reach production scale.
Key Company Profiles
AML3D Limited
AML3D is a metal additive manufacturing company that develops and operates wire arc additive manufacturing systems for large, high-integrity components. It holds a leading position in the domestic market for defense and marine metal printing, with growing activity abroad.
- Key Offerings: ARCEMY systems, WAM Materials.
- Key Developments: In July 2024, AML3D Limited secured an A$0.28 million order from Century Engineering, an Australian defense and industrial supplier, to upgrade an existing robotic welding system into an advanced ARCEMY metal 3D printing system. The project involves a comprehensive refurbishment, incorporating modern Wire-Arc Additive Manufacturing (WAAM) components and the latest ARCEMY software.
- Strategic Focus: Concentrating on defense and naval customers, deepening qualification and certification, and expanding printing capacity, while selling ARCEMY systems to selected partners. Its strategy emphasizes recurring contract manufacturing revenue alongside machine sales.
SPEE3D
SPEE3D is an Australian technology company specializing in the development and manufacturing of advanced metal 3D printing systems. The company uses patented Cold Spray Additive Manufacturing (CSAM) technology to produce high-quality metal components rapidly and cost-effectively. Its solutions cater to diverse industries, including defense, aerospace, mining, maritime, and industrial manufacturing, with a focus on on-demand production and reducing supply chain dependencies.
- Key Offerings: XSPEE3D, WarpSPEE3D, LightSPEE3D.
- Key Developments: In November 2026, SPEE3D, an Australian metal manufacturing technology company, commenced Phase One of its NodeZERO facility in Darwin, Northern Territory. The facility marks the first of 50 rapidly deployable factories planned across the Asia-Pacific region under its CriticalSPEE3D initiative, aimed at enabling on-site production of essential metal components. The initial phase is now accessible to founding members, including organizations requiring critical parts across Northern Australia and other regions.
- Strategic Focus: Emphasizes technological innovation, production scalability, and the development of portable metal 3D printing solutions to support on-demand manufacturing, reduce supply chain lead times, and strengthen domestic manufacturing capabilities.
Market Concentration Analysis
The market is fragmented. No single supplier commands a dominant share, and the leading local metal additive specialist holds an estimated 5% to 10% of overall market value, while global polymer machine makers, resellers and numerous service bureaus share the remainder. Differences in technology, material and customer segment limit direct competition across the full market.
Two opposing forces are reshaping concentration. Incumbent global suppliers and larger service groups are consolidating through acquisitions, reseller expansion and bundled hardware, material and software offerings. Meanwhile, innovation-led local firms and new entrants with differentiated metal processes are winning defense and resources contracts, keeping the competitive field open and diverse.
Investment & Growth Opportunities
Highest Growth Segments
Electron beam melting at ~20.0% CAGR, functional part manufacturing at ~19.4%, selective laser sintering at ~18.5%, digital light processing at ~17.7%, stereolithography at ~16.9% and tooling at ~16.7% are the primary investment vectors through 2034, followed by fused deposition modeling at ~15.6%, prototyping at ~15.4% and other technologies at ~14.4%.
Emerging Investment Opportunities
The most dynamic emerging opportunity is qualified metal part production and repair for defense, marine and resources customers, supported by local powder supply and deployable systems. It scales where operators face long supply lines, high downtime costs and stringent quality demands, rewarding providers with certification and rapid delivery.
Investment Themes
- Metal additive capacity and powder supply: Local atomization, alloy development and qualified printing capacity secure supply chains for defense and aerospace and support premium pricing.
- Certified production services: Quality systems, testing and traceability convert prototyping users into recurring production customers and defend margins against commodity printing.
- Deployable and distributed manufacturing: Rugged systems and digital part libraries serve remote operations, lowering inventory cost and creating recurring service revenue.
Future Market Outlook (2026-2034)
The Australia 3D printing market is projected to grow from USD 672.3 Million in 2025 to USD 787.0 Million in 2026, reaching USD 2,773.3 Million by 2034, registering a CAGR of 17.05% during 2026-2034. The market's anchor value of USD 1,477.3 Million in 2030 reflects the shift toward qualified production and sovereign supply, with Australia Capital Territory & New South Wales and Victoria & Tasmania sustaining leadership as research, defense and manufacturing clusters deepen. Three structural forces define market growth through 2034 expanding qualification of printed parts for regulated industries; policy-backed localization of defense and advanced manufacturing; and rising use of on-demand production to shorten supply lines for remote operations.
Research Methodology
Primary Research
Primary research included discussions with printer manufacturers, resellers, service bureau operators, materials suppliers and industrial users across Australia, covering technology adoption, qualification barriers, pricing behavior and demand across prototyping, tooling and production uses.
Secondary Research
Secondary research drew on company disclosures, industry association publications, government programs, academic research and trade data, triangulated to establish technology and application splits and the regional distribution of additive manufacturing activity in Australia.
Forecasting Models
Forecasting combined installed base modeling, application-level demand analysis and technology adoption curves for Australia, producing year-wise values from 2026 to 2034 with segment growth paths reconciled to the overall market CAGR.
Australia 3D Printing Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Technologies Covered | Stereolithography, Fused Deposition Modeling, Selective Laser Sintering, Electron Beam Melting, Digital Light Processing, Others |
| Processes Covered | Binder Jetting, Directed Energy Deposition, Material Extrusion, Material Jetting, Powder Bed Fusion, Sheet Lamination, Vat Photopolymerization |
| Materials Covered | Photopolymers, Plastics, Metals and Ceramides, Others |
| Offerings Covered | Printer, Material, Software, Service |
| Applications Covered | Prototyping, Tooling, Functional Part Manufacturing |
| End-Users Covered | Consumer Products, Machinery, Healthcare, Aerospace, Automobile, Others |
| Regions Covered | Australia Capital Territory & New South Wales, Victoria & Tasmania, Queensland, Northern Territory & Southern Australia, Western Australia |
| Companies Covered | AML3D Limited, SPEE3D, Aurora Labs, 3D Systems, Inc., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Australia 3D printing market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Australia 3D printing market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Australia 3D printing industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Australia 3D Printing Market Report
The market reached USD 672.3 Million in 2025 and an estimated USD 787.0 Million in 2026, supported by industrial adoption, defense localization, remote spare part needs and falling machine costs.
The market is expected to register a CAGR of 17.05% during 2026-2034, rising from USD 787.0 Million in 2026 to reach USD 2,773.3 Million by 2034 on production- and qualification-led demand.
Fused deposition modeling leads the technology segment with a 28.6% share in 2025, reflecting low machine cost, simple operation and broad thermoplastic material choice across schools, workshops and factories.
Prototyping leads the application segment with a 46.2% share in 2025, driven by rapid design iteration needs across consumer, engineering, medical and industrial product development teams.
Australia Capital Territory & New South Wales lead with a 36.5% regional share in 2025, supported by research institutes, defense agencies, hospitals and advanced manufacturers concentrated in the region.
Leading companies include AML3D Limited, SPEE3D, Aurora Labs, and 3D Systems, Inc., among others.
The market is projected to reach USD 1,477.3 Million by 2030, driven by qualified metal part production, defense localization and growing functional part manufacturing across regulated industries.
Electron beam melting at ~20.0% CAGR, functional part manufacturing at ~19.4% CAGR and selective laser sintering at ~18.5% CAGR are the fastest-growing segments, alongside metal powder supply and deployable production systems.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade