
Australia Foreign Exchange Market Size, Share, Trends and Forecast by Counterparty, Type and Region, 2026-2034
Australia Foreign Exchange Market Size, Share, Trends & Forecast (2026-2034)
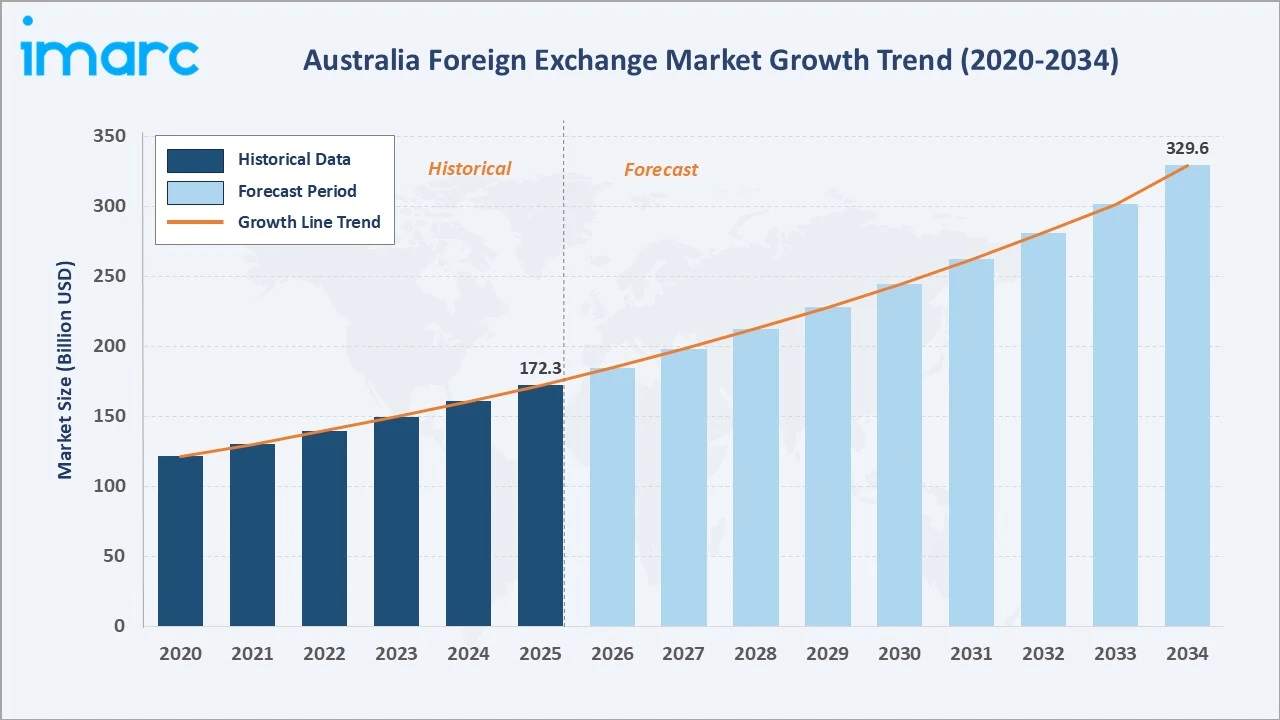
The Australia foreign exchange market grew from USD 172.3 Billion in 2025 to USD 184.8 Billion in 2026 and is projected to reach USD 329.6 Billion by 2034, exhibiting a CAGR of 7.25% during 2026-2034. Robust trading volumes driven by Australia’s commodity export linkages, deep integration with Asian financial markets, and highly developed electronic trading infrastructure are the primary forces shaping market growth.
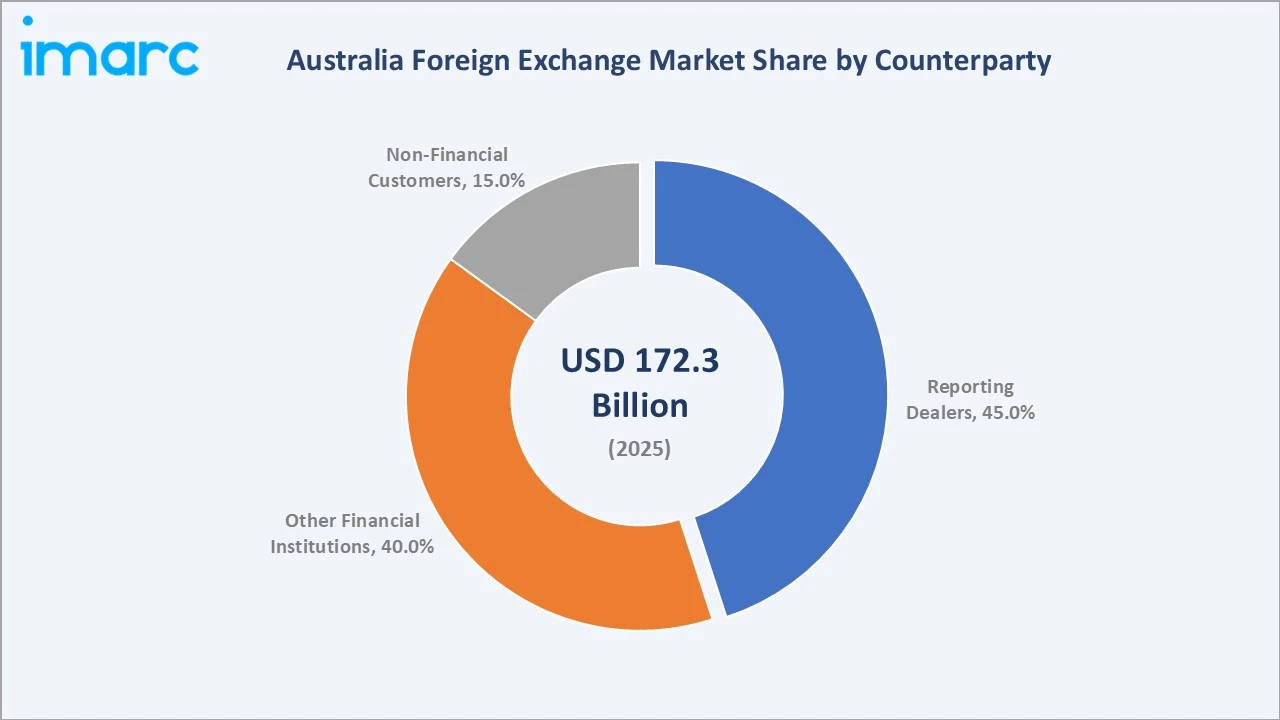
Reporting dealers lead the counterparty segment at 45.0%, outright forward and FX swaps dominate the type segment at 55.0%, and Australia Capital Territory & New South Wales commands 45.0% of regional share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 172.3 Billion |
|
Market Size (2026) |
USD 184.8 Billion |
|
Forecast Market Size (2034) |
USD 329.6 Billion |
|
CAGR (2026-2034) |
7.25% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
| Largest Region |
Australia Capital Territory & New South Wales (45.0%, 2025) |
| Second Largest Region |
Victoria & Tasmania (25.0%, 2025) |
| Leading Counterparty |
Reporting Dealers (45.0%, 2025) |
| Leading Type |
Outright Forward and FX Swaps (55.0%, 2025) |
The Australia foreign exchange market size increased from USD 121.4 Billion in 2020 to USD 172.3 Billion in 2025 and is estimated to reach USD 184.8 Billion in 2026. The market is further expected to grow to USD 244.5 Billion by 2030 and USD 329.6 Billion by 2034. The market is commercially distinctive among global foreign exchange markets, underpinned by the Australian dollar’s status as one of the most-traded currencies worldwide, deep institutional participation, and sustained commodity-driven cross-border trade flows.
To get more information on this market, Request Sample
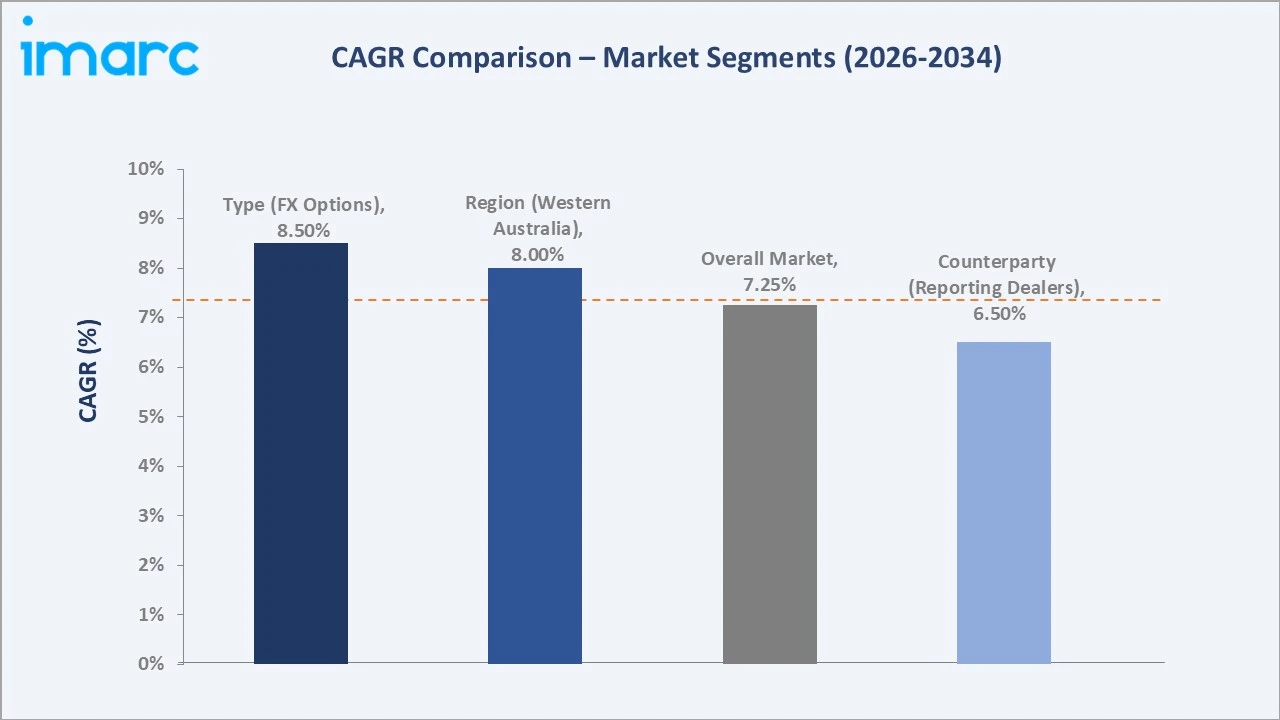
CAGR trajectories across counterparty, type, and regional sub-segments show non-financial customers and Northern Territory & Southern Australia expanding faster than the overall 7.25% market CAGR, driven by broadening retail FX participation, commodity sector hedging demand, and increasing cross-border investment activity.
Executive Summary
The Australia foreign exchange market expanded from USD 172.3 Billion in 2025 to an estimated USD 184.8 Billion in 2026, positioning it among Asia-Pacific’s most active currency trading centers. The market reflects deep trade linkages, AUD’s status as a major reserve currency, and institutional-grade electronic trading infrastructure.
Reporting dealers command 45.0% of counterparty share, reflecting the concentration of professional market-making among authorized deposit-taking institutions. Outright forward and FX swaps represent 55.0% of type share, driven by corporate hedging demand and institutional liquidity management. Australia Capital Territory & New South Wales leads regional share at 45.0%, anchored by Sydney’s role as Australia’s principal financial hub.
Key Market Insights
|
Insight |
Data |
| Leading Counterparty | Reporting Dealers – 45.0% share (2025) |
| Second Largest Counterparty | Other Financial Institutions – 40.0% share (2025) |
| Leading Type | Outright Forward and FX Swaps – 55.0% share (2025) |
| Second Largest Type |
Currency Swap – 30.0% share (2025) |
| Leading Region |
Australia Capital Territory & New South Wales – 45.0% share (2025) |
| Second Largest Region |
Victoria & Tasmania – 25.0% share (2025) |
| Top Companies | Commonwealth Bank of Australia, ANZ Group Holdings Limited, Westpac Banking Corporation, Macquarie Group Limited |
Key Analytical Observations Expanding On the Data Above:
- Reporting dealers dominance at 45.0% reflects the concentration of professional FX market-making activity among major authorized deposit-taking institutions and wholesale bank participants active across spot and derivative markets.
- Other financial institutions at 40.0% represent a growing cohort of asset managers, insurance companies, superannuation funds, and non-bank financial intermediaries deepening FX activity as cross-border investment mandates expand.
- Outright forward and FX swaps leadership at 55.0% reflects their dominant role in institutional liquidity management, short-term funding, and corporate hedging of known future currency obligations across trade and investment flows.
- Currency swap at 30.0% is supported by demand from financial institutions and corporates managing longer-term cross-currency funding obligations and interest rate exposure across multiple currency pairs.
- Australia Capital Territory & New South Wales at 45.0% leads regional share due to Sydney’s concentration of major bank headquarters, interbank dealing operations, and international financial institution offices driving the majority of domestic FX transaction volume.
Australia Foreign Exchange Market Overview
The Australia foreign exchange market encompasses the trading of AUD and other currency pairs through spot, forward, swap, and options instruments. Participants include authorized deposit-taking institutions, licensed dealers, asset managers, superannuation funds, and corporate treasury operations conducting currency transactions for hedging, investment, and trade settlement purposes.
The Australian ecosystem integrates reporting dealers, other financial institutions, corporate end-users, and regulatory bodies. Electronic platform providers, prime brokerage services, and government policy bodies form the supporting infrastructure layer, enabling a compliant, liquid, and scalable currency trading ecosystem across all AUD and cross-currency pairs.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
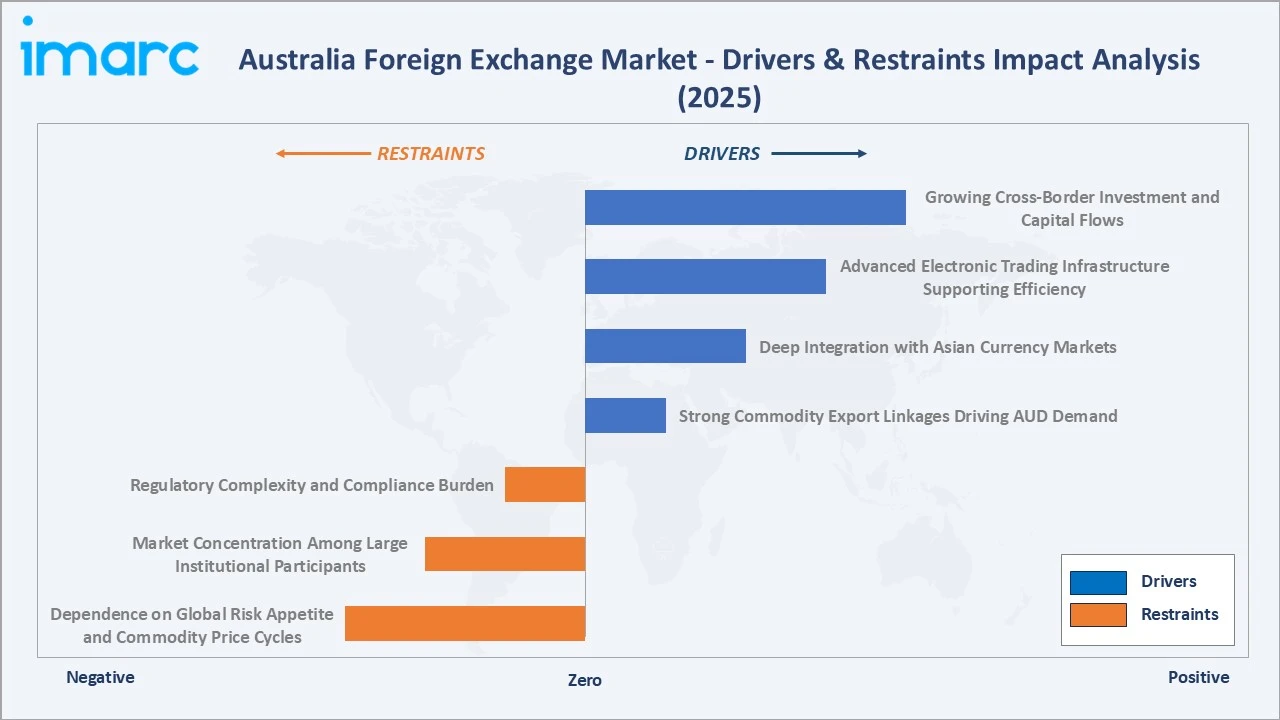
- Strong Commodity Export Linkages Driving AUD Demand: Australia’s position as one of the world’s largest exporters of iron ore, coal, and LNG generates sustained FX flows as commodity revenues are converted from USD and CNY into AUD, directly enlarging the addressable FX trading opportunity across all counterparty segments.
- Deep Integration with Asian Currency Markets: Australia’s proximity to Asia’s high-growth economies and the AUD’s role in regional trade settlement drive significant cross-currency FX flows between AUD and JPY, CNY, KRW, and SGD, expanding the counterparty and instrument mix within the domestic market.
- Advanced Electronic Trading Infrastructure Supporting Efficiency: Sophisticated electronic execution platforms, algorithmic trading systems, and automated price distribution infrastructure have increased market efficiency, reduced transaction costs, and expanded participation across institutional and non-bank segments of the FX market.
- Growing Cross-Border Investment and Capital Flows: Australia’s open capital account, investment-grade sovereign rating, and growing superannuation fund asset base drive increasing cross-border capital flows, generating sustained FX hedging and execution demand from institutional investors managing currency risk on international portfolios. According to Knight Frank’s 20th edition of The Wealth Report, Australia was allocated the fifth largest amount globally for cross-border commercial real estate (CRE) investment in 2025, with Sydney ranking as the fourth most favored city. Cross-border investment in Australia reached $US12.8 Billion in 2025.
Market Restraints
- Regulatory Complexity and Compliance Burden: The Australia foreign exchange market operates under stringent regulatory oversight, requiring market participants to comply with licensing, reporting, anti-money laundering, and financial conduct requirements. These regulatory obligations increase operational costs, administrative complexity, and compliance requirements, particularly for smaller brokers and non-bank financial institutions, potentially limiting market entry and expansion.
- Market Concentration Among Large Institutional Participants: A high proportion of total FX volume is concentrated among a small number of major authorized deposit-taking institutions, limiting competitive diversity and creating dependency on the credit intermediation capacity of dominant counterparties.
- Dependence on Global Risk Appetite and Commodity Price Cycles: The AUD functions as a risk-sensitive currency closely correlated with global commodity prices and risk appetite, exposing the market to abrupt liquidity reductions and spread widening during periods of global financial stress.
Market Opportunities
- Expansion of Electronic FX Platforms for Non-Bank Participants: Growing demand from superannuation funds, asset managers, and non-bank financial institutions for direct electronic FX access creates opportunities for platform providers and prime brokers to expand service offerings beyond the traditional interbank structure.
- Rising Demand for AUD-Denominated Hedging Products from Asian Investors: Increasing Asian institutional investment into Australian equities and real assets generates demand for AUD currency hedging products, creating new revenue opportunities for FX service providers across forward and options markets.
Market Challenges
- AUD Volatility During Global Risk-Off Episodes: The AUD’s sensitivity to global commodity prices and risk sentiment exposes market participants to abrupt AUD/USD swings during global financial stress, creating mark-to-market losses for unhedged positions and complicating liquidity management for corporate treasuries.
- Technology Investment Requirements for Electronic Execution: Maintaining competitive electronic trading infrastructure, managing latency, and meeting evolving regulatory technology requirements place significant ongoing capital and operational demands on FX service providers across all market tiers.
Emerging Market Trends
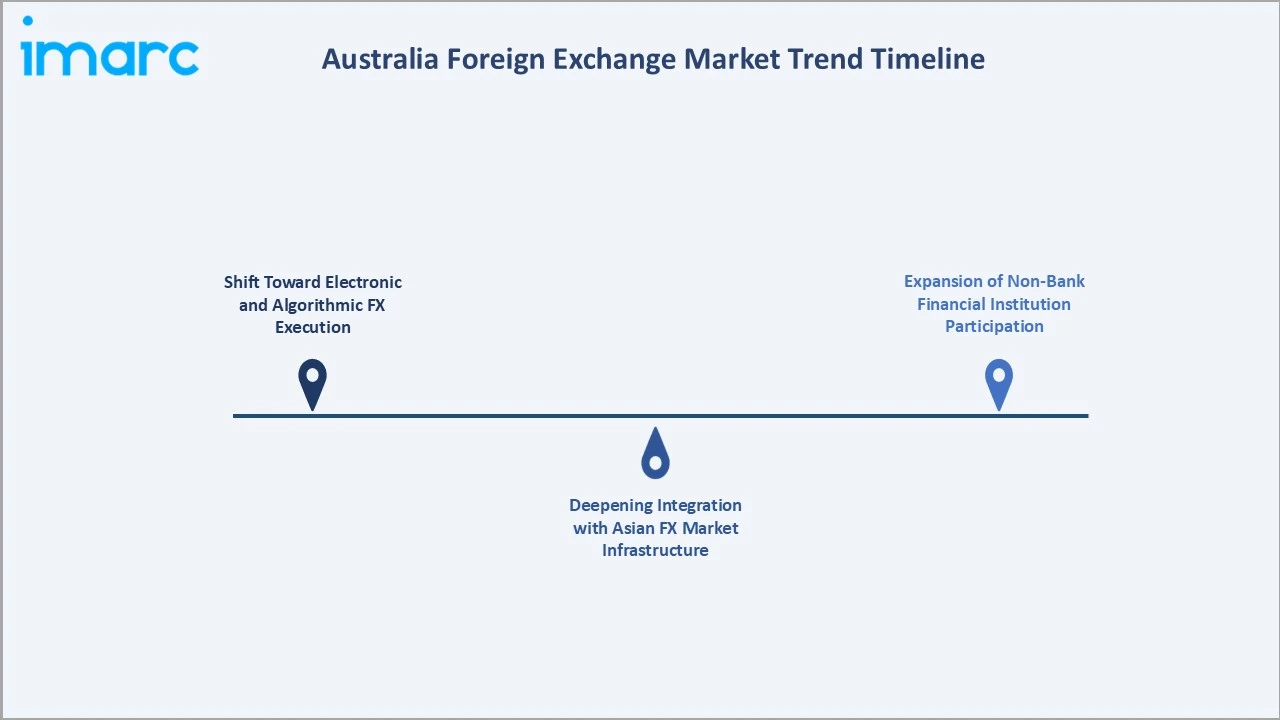
1. Shift Toward Electronic and Algorithmic FX Execution
Electronic trading platforms have displaced voice and relationship-based execution as the dominant mode for FX transactions among institutional participants in Australia. Algorithmic execution systems improve price discovery, enable finer spread management, and support higher transaction frequency across spot, forward, and swap markets. This shift is expanding access for non-bank financial institutions seeking efficient execution at institutional-grade pricing.
2. Deepening Integration with Asian FX Market Infrastructure
The Australia foreign exchange market is increasingly linked with Asian trading centers, with Sydney serving as a key pricing hub for AUD/Asia currency pairs during Asian trading hours. Cross-border renminbi transactions involving AUD are growing, reflecting China’s increasing share of Australian trade and investment flows. Electronic connectivity between Sydney, Singapore, Tokyo, and Hong Kong is tightening bid-ask spreads and improving liquidity transmission across the region.
3. Expansion of Non-Bank Financial Institution Participation
Superannuation funds, asset managers, and insurance companies are expanding their direct FX market participation, partly displacing traditional bank intermediation for routine currency hedging. The shift is driven by cost pressures, improving electronic access, and growing in-house FX capability within large institutional investors. This structural change is broadening the other financial institutions counterparty segment.
Industry Value Chain Analysis
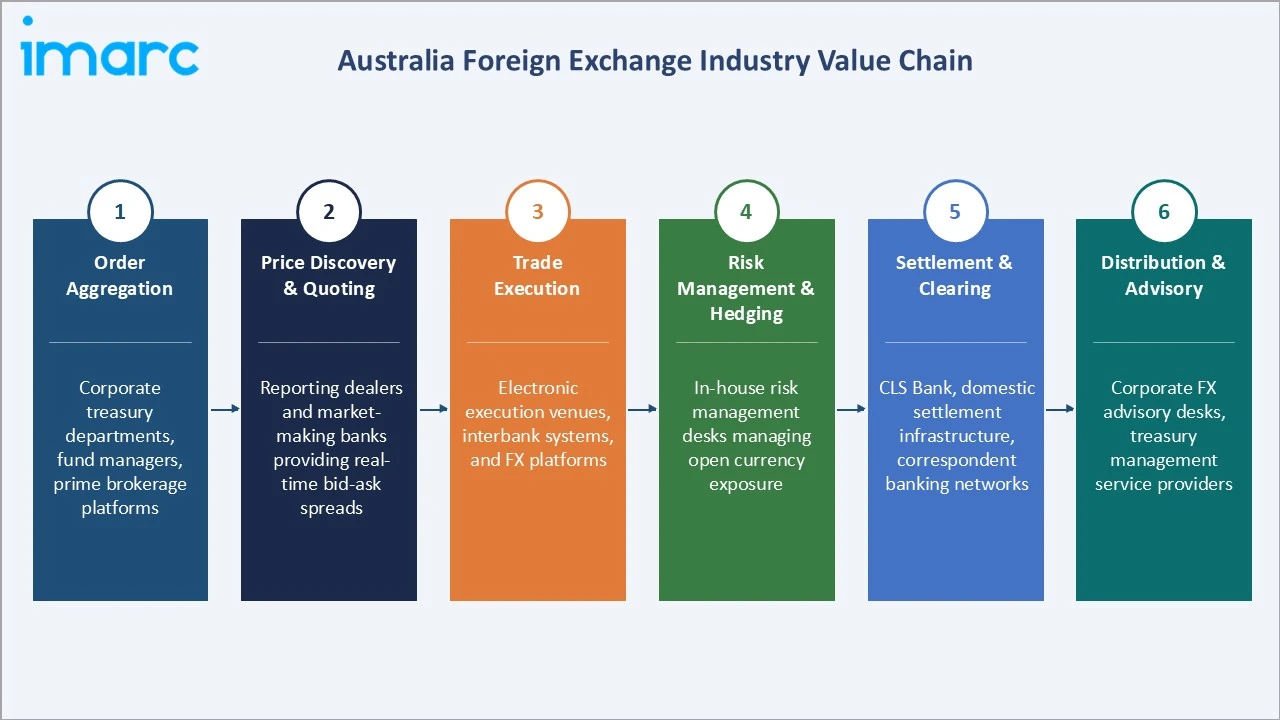
The Australia foreign exchange market value chain spans six stages, from order aggregation through distribution and advisory services. Price discovery, trade execution, and risk management stages capture the highest value-add, while regulatory compliance and settlement infrastructure are increasingly determining competitive positioning in the market.
|
Stage |
Key Participants |
| Order Aggregation | Corporate treasury departments, fund managers, and prime brokerage platforms aggregating client FX order flow |
| Price Discovery & Quoting | Reporting dealers and market-making banks providing real-time bid-ask spreads across spot, forward, and swap instruments |
| Trade Execution | Electronic execution venues, interbank systems, and FX platforms routing and matching orders across counterparties |
| Risk Management & Hedging | In-house risk management desks within banks and financial institutions managing open currency exposure across portfolios |
| Settlement & Clearing | CLS Bank, domestic settlement infrastructure, and correspondent banking networks processing FX transaction settlement |
| Distribution & Advisory | Corporate FX advisory desks, treasury management service providers, and hedging strategy consultants serving end-users |
Vertically integrated institutions controlling market-making, risk management, and distribution are positioned to capture greater revenue than single-function participants dependent on external counterparties for price discovery or settlement infrastructure.
Technology Landscape in the Australia Foreign Exchange Industry
Electronic Trading Platforms
Multi-dealer and single-dealer electronic platforms constitute the primary mode of FX execution for institutional and corporate participants in Australia. These platforms provide real-time pricing, order management, and straight-through processing across spot, forward, and swap transactions, reducing settlement risk and improving execution transparency.
Algorithmic and High-Frequency Trading
Algorithmic execution engines and high-frequency trading systems are increasingly active in AUD-denominated currency pairs, improving price discovery and narrowing spreads. Reporting dealers deploy liquidity management algorithms to optimize quoting, internalization, and position management across electronic venues.
Risk Management and Analytics Technology
Real-time risk aggregation systems, portfolio-level currency exposure monitoring, and scenario analysis platforms enable more precise currency risk management across institutional participants. Analytics tools providing AUD correlation analysis and commodity-linked FX scenario modeling are gaining adoption among superannuation funds.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
| Counterparty | Reporting Dealers |
45.0% |
2025 |
| Type | Outright Forward and FX Swaps |
55.0% |
2025 |
|
Region |
Australia Capital Territory & New South Wales |
45.0% |
2025 |

By Counterparty
Reporting dealers command a 45.0% majority share in 2025, reflecting the dominant role of major authorized deposit-taking institutions and licensed dealers in providing FX liquidity and market-making services across the Australian interbank market. The segment benefits from established credit relationships, proprietary pricing infrastructure, and direct access to global FX liquidity pools.
To access detailed market analysis, Request Sample
Other financial institutions at 40.0% represent the second-largest counterparty segment, driven by growing FX activity from superannuation funds, insurance companies, and non-bank financial intermediaries. Ongoing improvements in electronic access and expanding cross-border investment mandates are further increasing this segment’s participation.
By Type
Outright forward and FX swaps represent 55.0% of the type segment in 2025, directly reflecting their role as the primary instruments for institutional FX liquidity management, short-term funding, and corporate hedging of known future trade and investment currency obligations.
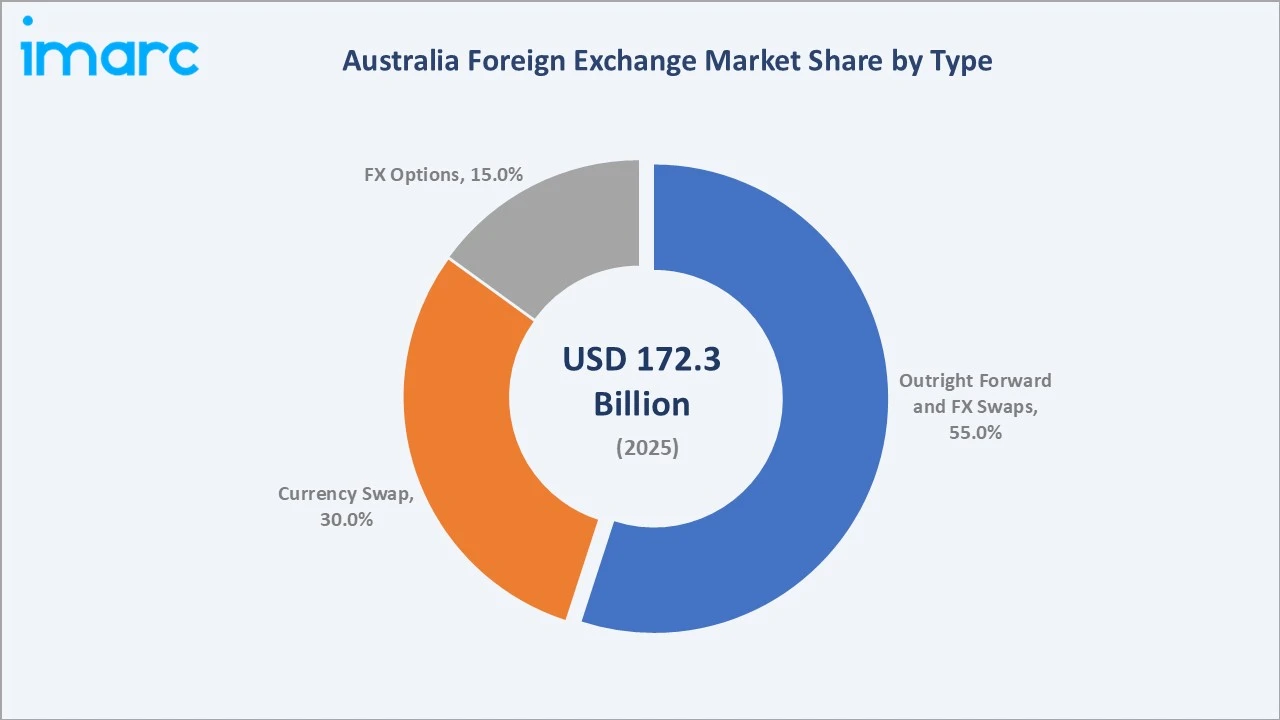
Currency swap at 30.0% is the second-largest type segment, supported by demand for cross-currency funding between AUD and major trading partner currencies.
Regional Market Insights
|
Region |
Share (2025) |
Key Growth Drivers |
| Australia Capital Territory & New South Wales | 45.0% | Sydney’s status as Australia’s primary financial center, concentration of major bank headquarters, deep interbank FX market, and high institutional trading volumes |
| Victoria & Tasmania |
25.0% |
Melbourne’s role as Australia’s second financial center, state government treasury operations, growing asset management sector, and expanding corporate FX demand |
| Queensland |
15.0% |
Resources sector FX demand from coal and LNG exports, growing trade-related currency flows, and expanding corporate and SME participation in FX markets |
| Western Australia |
10.0% |
Mining and iron ore export proceeds generating sustained AUD demand, resource sector corporate hedging activity, and growing regional financial services participation |
| Northern Territory & Southern Australia |
5.0% |
Agricultural export proceeds, emerging corporate FX activity in pastoral and mining sectors, and growing small business cross-border transaction volumes |
Australia Capital Territory & New South Wales at 45.0% in 2025 leads the regional landscape, anchored by Sydney’s concentration of major bank dealing rooms and international financial institution offices.
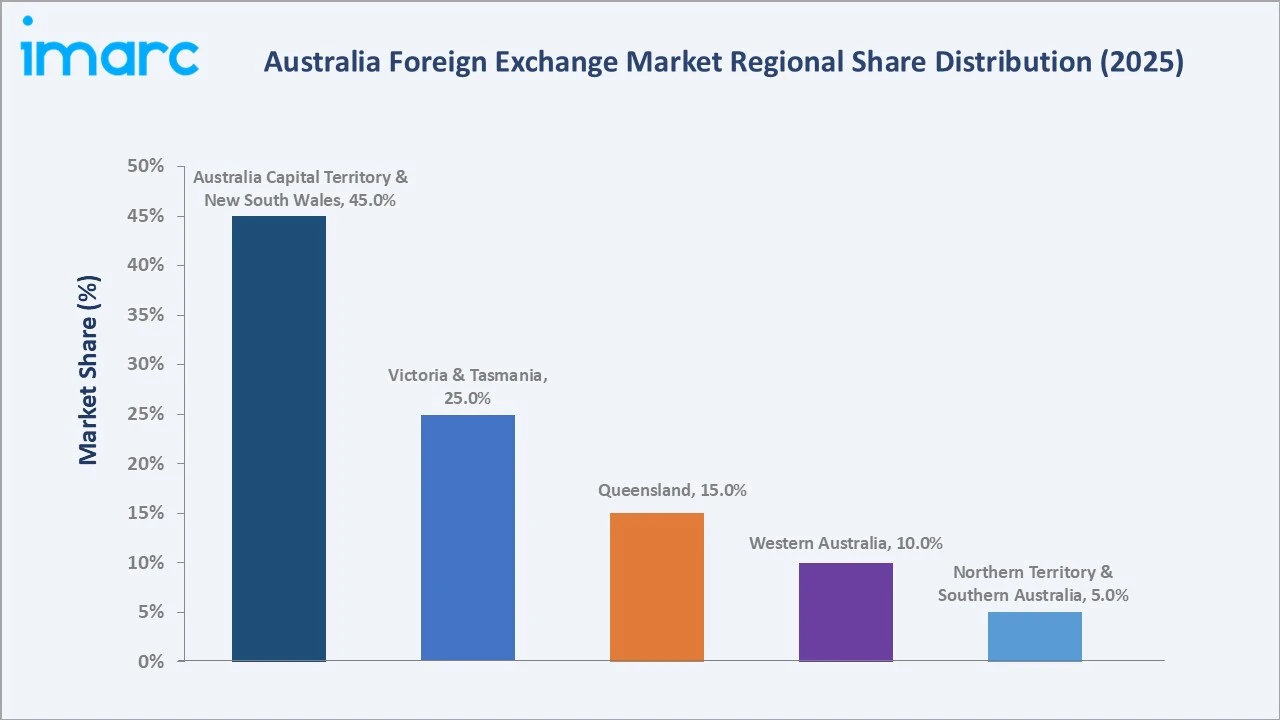
Northern Territory & Southern Australia, while currently the smallest regional contributor at 5.0%, is expanding as commodity-sector FX activity grows and financial services infrastructure develops across regional centers.
Competitive Landscape
The Australia foreign exchange market is concentrated, with major authorized deposit-taking institutions and international banks commanding the majority of market-making and institutional FX volumes. Scale, electronic trading infrastructure, credit intermediation capacity, and correspondent banking relationships form the key competitive differentiators across the industry.
|
Company |
Key Brands |
Market Position |
Core Strength |
| Commonwealth Bank of Australia | CBA Global Markets |
Market Leader |
Expanding institutional FX and currency management capabilities through electronic platform investment and client coverage |
| ANZ Group Holdings Limited | ANZ Markets | Leader | Growing FX market-making capabilities and strengthening correspondent banking relationships across Asia-Pacific |
| Westpac Banking Corporation | Westpac Institutional Bank |
Leader |
Developing electronic FX execution platforms and expanding institutional client coverage across key currency pairs |
| Macquarie Group Limited | Commodities and Global Markets (CGM) | Challenger | Expanding FX and rates trading capabilities through electronic platform investment and institutional market partnerships |
Key players include Commonwealth Bank of Australia, ANZ Group Holdings Limited, Westpac Banking Corporation, and Macquarie Group Limited, among others.
Key Company Profiles
Commonwealth Bank of Australia
Commonwealth Bank of Australia is an Australian multinational banking corporation headquartered in Sydney, New South Wales. The bank operates an institutional markets division delivering FX, rates, and structured product solutions to corporate, government, and institutional clients domestically and across Asia-Pacific.
- Product Portfolio: Institutional FX execution, spot and forward currency trading, FX hedging solutions for corporate clients, interest rate and cross-currency swap products, and treasury management services.
- Recent Developments: The bank continues to advance its digital FX execution platforms and expand its institutional client coverage across commodity, government, and superannuation fund segments.
- Strategic Focus: Expanding electronic FX execution capabilities and deepening institutional client relationships across corporate treasury and investment management segments.
ANZ Group Holdings Limited
ANZ Group Holdings Limited is an Australian multinational banking corporation headquartered in Melbourne, Victoria. The group operates a substantial institutional markets business with a strong presence across Asia-Pacific FX and fixed income markets.
- Product Portfolio: FX trading and hedging, rates products, structured currency solutions, trade finance and cross-border payment services, and commodity-linked FX management products for resource-sector clients.
- Recent Developments: ANZ Group Holdings Limited continues to strengthen its FX footprint and deepen electronic trading capabilities, reflecting growing institutional demand for efficient cross-border currency execution.
- Strategic Focus: Growing FX market-making capability and strengthening correspondent banking relationships across Asian trading centers and the domestic institutional market.
Westpac Banking Corporation
Westpac Banking Corporation is one of Australia’s major banks, headquartered in Sydney. Its institutional bank division provides FX, rates, and structured products to corporate, government, and financial institution clients across Australia and New Zealand.
- Product Portfolio: Spot, forward, and swap FX execution, cross-currency interest rate swaps, FX options for corporate hedging, commodity-linked currency products, and institutional treasury management solutions.
- Recent Developments: Westpac Banking Corporation continues to invest in electronic FX execution infrastructure and expand institutional client service capabilities across corporate, government, and financial institution segments.
- Strategic Focus: Developing advanced electronic FX execution platforms and expanding institutional client coverage across key AUD and cross-currency pairs.
Market Concentration Analysis
The Australia foreign exchange market is concentrated, with the top tier of operators comprising the four major domestic banks and a small number of significant international institutions accounting for the majority of interbank and institutional FX volumes. This concentration reflects structural advantages in credit intermediation, electronic infrastructure, and relationship networks that are difficult to replicate.
Barriers to meaningful market-making participation include substantial capital requirements for credit intermediation, ASIC licensing obligations for dealing in FX derivatives, significant technology investment for competitive electronic execution, and the need for deep correspondent banking relationships. These factors favor incumbent authorized deposit-taking institutions over potential new entrants.
Consolidation is reinforced by the high cost of maintaining competitive trading infrastructure, evolving regulatory requirements, and the advantages of established institutional relationships. This limits opportunities for smaller market participants to gain market share and strengthens the dominance of major domestic banks and international financial institutions in the Australia foreign exchange market.
Investment & Growth Opportunities
Fastest-Growing Segments
FX options are expanding fastest among type sub-segments, driven by growing adoption of structured hedging strategies among commodity exporters and institutional investors managing complex multi-asset currency exposures. Non-financial customers are expected to grow at an above-average rate, as SME FX platform access improves and as more businesses manage trade-related currency risk directly through digital FX services.
Emerging Markets
Northern Territory & Southern Australia is the fastest-growing regional market, supported by expanding agricultural and mining export volumes, growing regional business participation in cross-border trade, and improving FX service availability from digital banking platforms. The region represents a meaningful growth opportunity for FX service providers building early-mover digital distribution ahead of rising SME demand.
Venture & Investment Trends
Investment activity is concentrated in electronic FX execution platform development, algorithmic trading infrastructure, and regulatory technology for derivative reporting compliance. Capital is also flowing into FX fintech platforms providing SME and retail cross-border payment services, and into data analytics tools supporting portfolio-level currency risk management for institutional investors.
Future Market Outlook (2026-2034)
The Australia foreign exchange market is projected to grow from USD 172.3 Billion in 2025 to USD 184.8 Billion in 2026, reaching USD 329.6 Billion by 2034, registering a CAGR of 7.25% during 2026-2034. Four forces will shape the market through 2034 deepening electronic and algorithmic FX execution across all counterparty segments; expanding non-bank financial institution participation as direct electronic access reduces traditional bank intermediation; growing AUD-Asia currency pair volumes driven by deepening economic integration with China, Japan, and Southeast Asian economies; and continued regulatory evolution shaping OTC FX derivative reporting and margining requirements.
By 2034, the Australia foreign exchange market is expected to be characterized by a mix of electronically-enabled major bank market-makers, technology-driven non-bank participants, and FX fintech platforms delivering tailored services to SME and retail segments. Continued trade growth and superannuation fund expansion will sustain strong FX hedging and execution demand through the forecast period.
Research Methodology
Primary Research
Primary research included structured discussions with FX market practitioners, institutional treasury managers, regulatory specialists, and electronic platform operators, validating market sizing, segment mix, and regional demand patterns across the Australia foreign exchange market ecosystem.
Secondary Research
Secondary sources included Reserve Bank of Australia FX turnover survey data, BIS Triennial Central Bank Survey, ASIC derivative market reports, and public disclosures from listed banking institutions, FX platform operators, and financial market infrastructure providers operating in Australia.
Forecasting Models
Market forecasts used top-down and bottom-up models combining RBA FX turnover data, economic growth projections, trade flow forecasts, and financial institution participation trends. Scenario analysis addressed electronic adoption rates, regulatory framework evolution, and cross-border investment growth trajectories.
Australia Foreign Exchange Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Counterparties Covered | Reporting Dealers, Non-financial Customers, Other Financial Institutions |
| Types Covered | Currency Swap, Outright Forward and FX Swaps, FX Options |
| Regions Covered | Australia Capital Territory & New South Wales, Victoria & Tasmania, Queensland, Northern Territory & Southern Australia, Western Australia |
| Companies Covered | Commonwealth Bank of Australia, ANZ Group Holdings Limited, Westpac Banking Corporation, Macquarie Group Limited, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Australia foreign exchange market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the Australia foreign exchange market.
- Porter's Five Forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Australia foreign exchange industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Australia Foreign Exchange Market Report
The Australia foreign exchange market size is estimated at USD 184.8 Billion in 2026, driven by commodity export linkages, institutional FX demand, and AUD’s role as a major globally traded currency.
The market is projected to grow at a CAGR of 7.25% from 2026-2034, reaching USD 329.6 Billion, supported by electronic trading adoption and expanding institutional participation.
Reporting dealers dominate the market at 45.0% counterparty share in 2025, reflecting the concentration of professional FX market-making among major authorized deposit-taking institutions.
Outright forward and FX swaps represent 55.0% of the type segment in 2025, driven by their dominant role in institutional liquidity management and corporate hedging of trade and investment currency obligations.
Australia Capital Territory & New South Wales commands 45.0% share in 2025, led by Sydney’s concentration of major bank dealing operations and international financial institution offices.
Northern Territory & Southern Australia is the fastest-growing region, driven by expanding agricultural and mining exports, growing SME FX participation, and improving digital FX service access.
Key players include Commonwealth Bank of Australia, ANZ Group Holdings Limited, Westpac Banking Corporation, and Macquarie Group Limited, among others.
Key drivers include commodity export linkages, deepening Asian market integration, electronic trading infrastructure growth, and expanding cross-border investment and superannuation fund FX demand.
Key trends include the shift to algorithmic execution, deepening AUD-Asia currency integration, growth of FX options for commodity hedging, and expanding non-bank financial institution participation.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade