Australia Lubricants Market Size, Share, Trends and Forecast by Product Type, Base Oil, End Use Industry, and Region, 2026-2034
Australia Lubricants Market Size, Share, Trends & Forecast (2026-2034)
The Australia lubricants market reached USD 2.96 Billion in 2025 and is projected to reach USD 4.33 Billion by 2034, exhibiting a robust CAGR of 4.32% during 2026-2034. Australia lubricants industry growth is underpinned by the country’s resource-intensive economy, where world-class mining operations, a large heavy-vehicle fleet, expanding renewable energy infrastructure, and a substantial automotive parc collectively drive sustained demand across engine oil, industrial lubricants, and specialty fluids. Australia aims to increase the share of renewable electricity to 82% by 2030, alongside a new Critical Minerals Strategy and gas market reforms to strengthen energy security. These initiatives are increasing demand for industrial lubricants, greases, hydraulic fluids, and equipment oils. Engine oil leads product type at 26.0%, mineral oil dominates base oil at 48.0%, and Australia Capital Territory & New South Wales command the largest regional share at 27.0%.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 2.96 Billion |
|
Forecast Market Size (2034) |
USD 4.33 Billion |
|
CAGR (2026-2034) |
4.32% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Product Type |
Engine Oil – 26.0% (2025) |
|
Dominant Base Oil |
Mineral Oil – 48.0% (2025) |
|
Leading Region |
Australia Capital Territory & New South Wales – 27.0% (2025) |
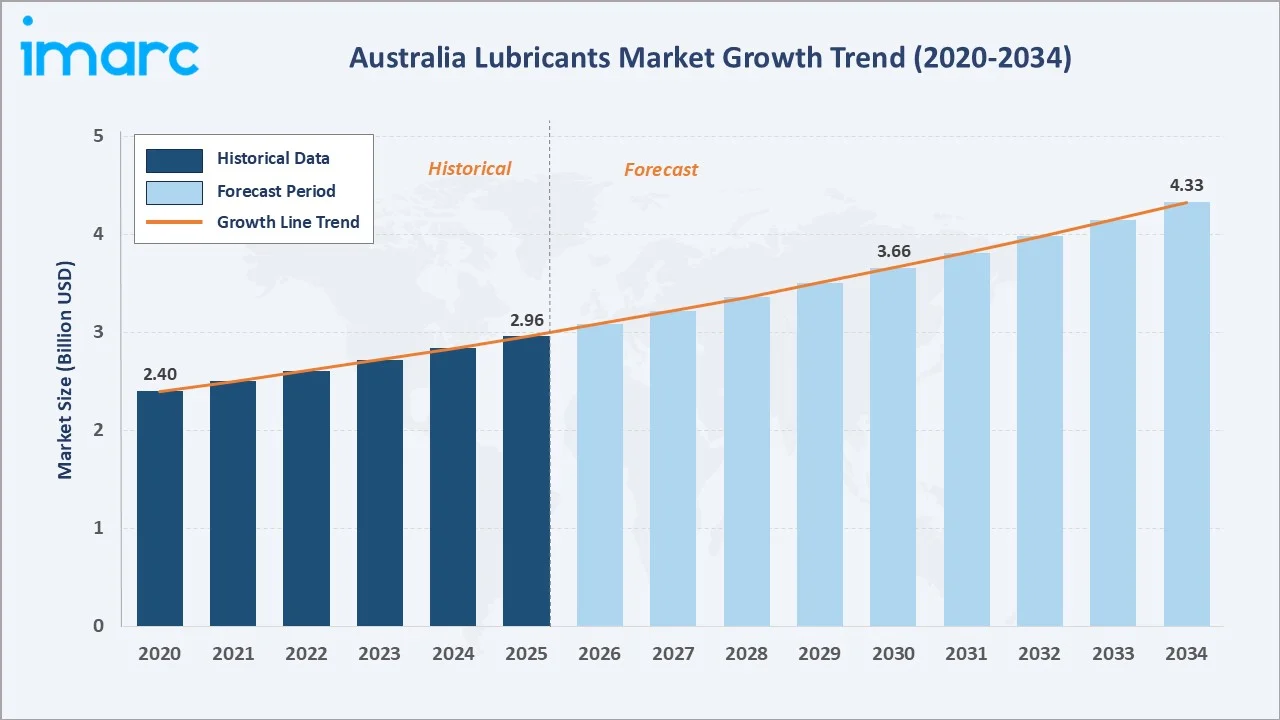
The Australia lubricants market grew from USD 2.40 Billion in 2020 to USD 2.96 Billion in 2025, driven by the post-COVID mining sector recovery, the record-high capital expenditure in Australian infrastructure projects under the National Infrastructure Pipeline, and the progressive adoption of synthetic and high-performance lubricants across the automotive and industrial sectors. The market is projected to reach USD 3.66 Billion by 2030 and USD 4.33 Billion by 2034.
To get more information on this market, Request Sample
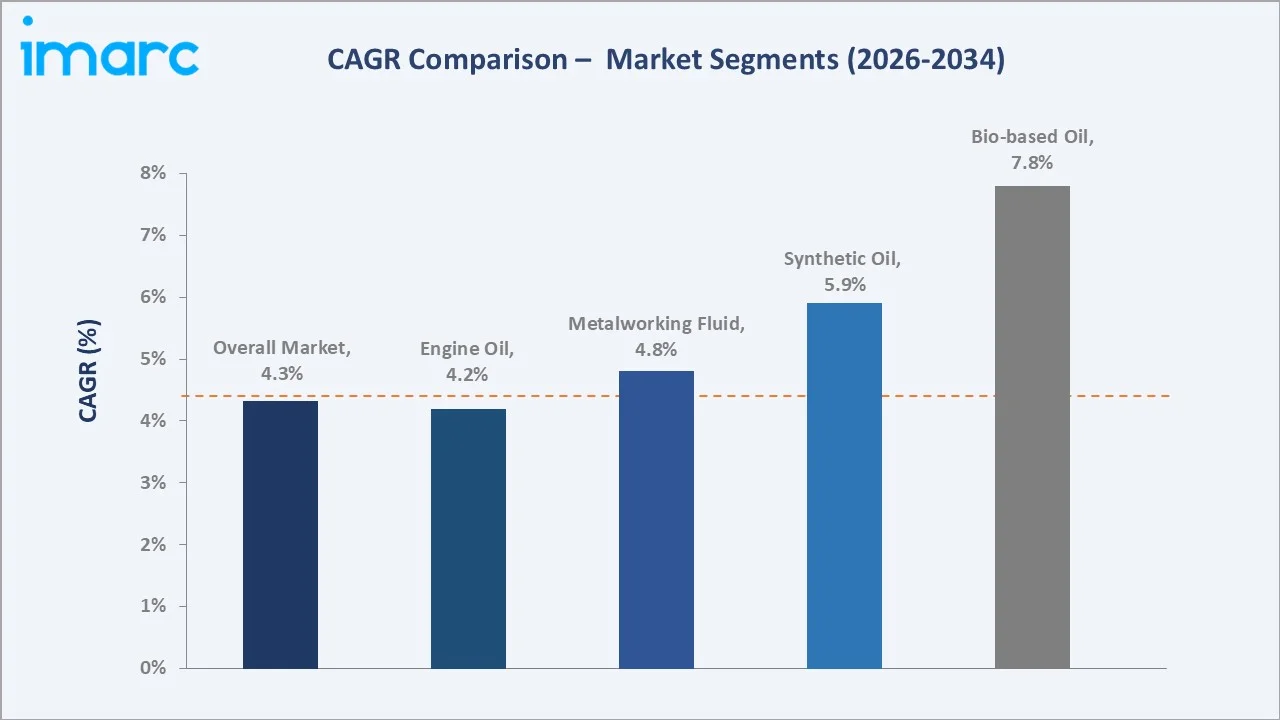
Bio-based oil grows fastest at ~7.80% CAGR through sustainability mandates and green industrial specifications. Synthetic oil grows at ~5.90% CAGR through extended drain interval demand and premium automotive adoption. Metalworking fluid grows at ~4.80% CAGR through manufacturing sector expansion. Engine oil grows at ~4.20% CAGR through fleet expansion and high-performance engine requirements.
Executive Summary
Australia lubricants market is structurally anchored by three industrial pillars that collectively create diversified, resilient demand independent of any single economic sector’s performance: the leading mining and resources sector, which drives heavy-duty engine oil, transmission fluid, and hydraulic oil demand at volumes exceeding any other comparable economy relative to GDP; a large and growing automotive vehicle parc that sustains engine oil as the market’s dominant product type; and an expanding renewable energy infrastructure base requiring specialty turbine, gear, and hydraulic oils that represent the market’s fastest-growing industrial application.
Engine oil’s 26.0% product type dominance reflects Australia’s large automotive fleet and the universal lubrication requirement of internal combustion engines across passenger vehicles, light commercial vehicles, and the extensive trucking fleet. Mineral oil’s 48.0% base oil majority reflects the continued commercial dominance of Group I and Group II mineral base oils in general industrial applications, despite the accelerating shift toward synthetics in automotive and premium industrial segments. Australia Capital Territory & New South Wales’s 27.0% regional leadership reflects the combined weight of Sydney’s massive automotive and commercial vehicle fleet, New South Wales’ large manufacturing and construction sector, and the region’s strategic position as Australia’s largest port and logistics hub.
Key Market Insights
|
Insight |
Data |
|
Dominant Product Type |
Engine Oil – 26.0% share (2025) |
|
Dominant Base Oil |
Mineral Oil – 48.0% share (2025) |
|
Leading Region |
Australia Capital Territory & New South Wales – 27.0% share (2025) |
|
Market Opportunity |
EV-specific thermal management and e-fluid demand; bio-based lubricant specifications for mining environmental compliance; food-grade lubricants for expanding food processing sector; wind turbine biodegradable gear oil for offshore wind development |
Key Analytical Observations:
- Engine Oil at 26.0% (2025): Engine oil’s commanding share reflects the convergence of Australia’s large vehicle parc, a predominantly Internal Combustion Engine (ICE) fleet, and the heavy-duty engine oil requirements of Australia’s uniquely large mining truck and haul fleet.
- Mineral Oil at 48.0% (2025): Mineral oil’s majority reflects the continued commercial dominance of petroleum-derived Group I and Group II base oils across Australia’s general industrial, marine, mining process, and mainstream automotive applications where cost is the primary procurement criterion and high-performance synthetic properties are not mandated by OEM specification.
- Australia Capital Territory & New South Wales at 27.0% (2025): Australia Capital Territory & New South Wales lead the market due to their large vehicle fleet, strong construction activity, industrial base, and extensive transport infrastructure. Demand is further supported by mining services, manufacturing, logistics, and infrastructure maintenance across New South Wales.
Australia Lubricants Market Overview
The Australia lubricants market encompasses automotive oils, industrial oils, greases, hydraulic fluids, transmission fluids, and specialty lubricants used across transportation, mining, construction, manufacturing, power generation, and marine applications. Demand is supported by a large vehicle base, extensive mining activity, infrastructure development, and industrial equipment maintenance. The market also includes conventional mineral-based products as well as synthetic and bio-based lubricants designed for higher efficiency and longer service life. Macroeconomic factors supporting the Australia industrial lubricants industry include mining investment, infrastructure development, manufacturing activity, and expansion in transport and energy assets. These trends are also strengthening the Australia lubrication systems market, while broader Australia lubrication industry insights point to rising demand for high-performance, synthetic, and equipment-specific lubricants.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
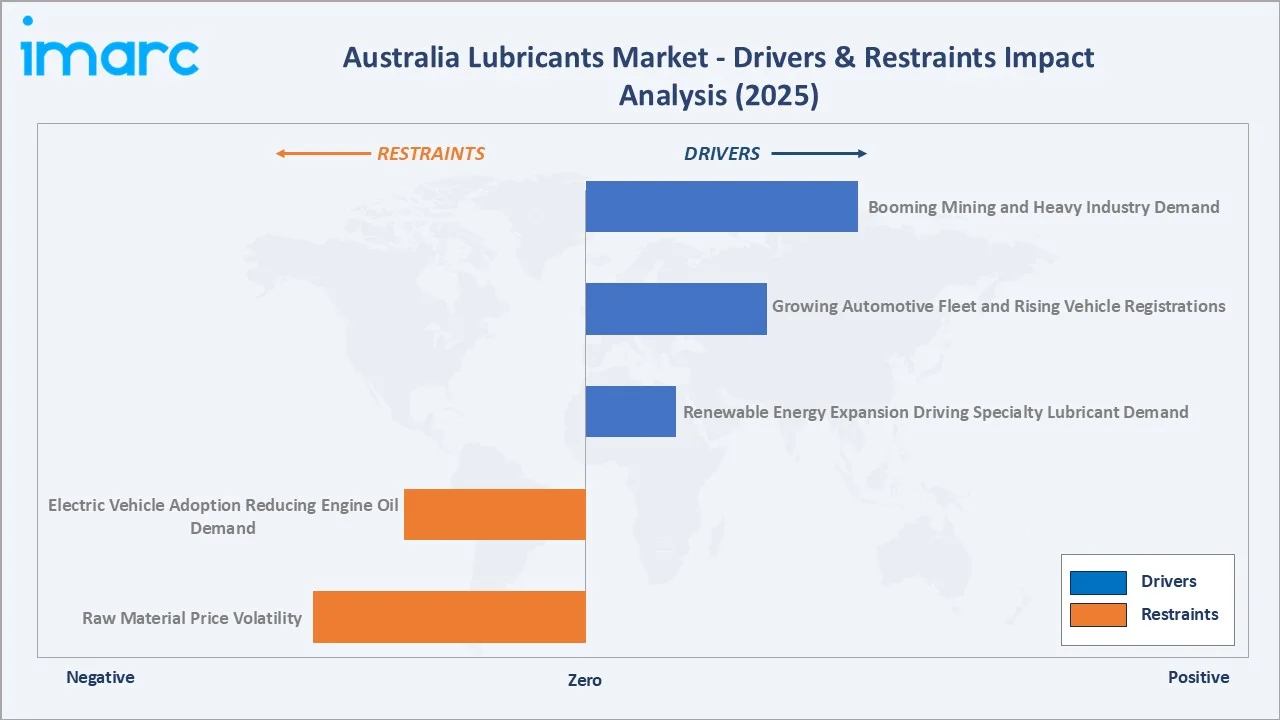
- Booming Mining and Heavy Industry Demand: Australia’s large mining and heavy-industry base is a major driver of lubricant consumption, particularly for hydraulic oils, gear oils, greases, engine oils, and transmission fluids. Continuous operation of mining trucks, excavators, crushers, conveyors, and processing equipment creates recurring maintenance requirements. Expansion of critical-mineral projects and supporting infrastructure is further increasing machinery utilization. This is strengthening demand for high-performance lubricants that reduce wear, improve equipment reliability, and extend service intervals.
- Growing Automotive Fleet and Rising Vehicle Registrations: Australia’s new vehicle market recorded 1,209,808 sales in 2025, with 98,744 units sold in December, up 3% year over year. Plug-in hybrid vehicle sales surged 130.9% to 53,484 units, while conventional hybrids rose 15.3% to 199,133 units. Battery electric vehicles reached 103,269 units, representing 8.3% of total annual sales, sustained by population growth, urbanization driving private vehicle dependence, and the expanding commercial vehicle fleet supporting Australia’s economy’s freight requirements. New vehicle sales create a diverse engine oil specification landscape. The heavy vehicle fleet’s growth creates disproportionate lubricant demand relative to its registration share, as single heavy vehicles consume 30-100x the engine oil volume of a passenger vehicle annually.
- Renewable Energy Expansion Driving Specialty Lubricant Demand: Australia’s renewable energy buildout targeting 82% renewable electricity by 2030 creates a rapidly growing and premium-priced specialty lubricant market for wind turbine gear oil, solar tracker hydraulic fluid, and large-scale battery energy storage (BESS) thermal management fluids. The development of Australia’s offshore wind industry will create additional premium lubricant demand for marine-grade, biodegradable gear and hydraulic fluids for offshore turbine drivetrain maintenance from 2028-2034.
Market Restraints
- Electric Vehicle Adoption Reducing Engine Oil Demand: Rising adoption of battery electric vehicles (BEVs) is gradually reducing demand for conventional engine oils, as BEVs do not require internal combustion engine lubrication. As the electric vehicle fleet expands, lubricant consumption associated with routine oil changes may decline. This shift could pressure the Australia lubricants market, particularly the automotive engine oil segment, while increasing the need for specialized EV fluids and thermal management solutions.
- Raw Material Price Volatility: Fluctuations in the prices of base oils, crude oil derivatives, and lubricant additives can significantly increase production costs for lubricant manufacturers. Australia’s reliance on imported refined petroleum products and specialty additives can further expose suppliers to global price and currency movements. Rising input costs may squeeze margins or lead to higher product prices, thereby restraining growth in the Australia lubricants market.
Market Opportunities
- EV-Specific Fluids and Thermal Management: Australians purchased 72,758 battery electric and plug-in hybrid vehicles during the first half of 2025, representing a 24.4% increase compared with the same period in 2024. Australia’s progressive EV fleet growth creates a new lubricant demand category: EV-specific e-fluids for electric motor cooling and lubrication, e-axle transmission fluids for electric drive units, and battery thermal management fluids (water-glycol, dielectric fluids), which is growing from near-zero in 2020 to a commercially meaningful volume by 2030 as the EV fleet scales.
- Food-Grade Lubricant Market Growth: Expansion of Australia’s food and beverage processing industry is creating opportunities for food-grade lubricants used in conveyors, mixers, packaging equipment, compressors, and other machinery. Rising emphasis on hygiene, contamination control, and food-safety compliance is encouraging processors to adopt specialized lubricants suitable for incidental food contact. Growth in automated processing and packaging facilities is further increasing lubricant requirements. This creates opportunities for suppliers offering high-performance synthetic and food-grade lubricant formulations.
Market Challenges
- Stringent Environmental and Sustainability Requirements: Growing environmental scrutiny is increasing pressure on lubricant manufacturers to reduce emissions, waste, and environmental impacts across product life cycles. Compliance with chemical handling and disposal requirements can increase operating costs. Producers also face pressure to develop lower-carbon and biodegradable lubricant formulations.
- Managing Used Lubricants and Waste Oils: Proper collection, recycling, and disposal of used lubricants remains an important operational challenge. Industrial, mining, and automotive users generate substantial quantities of waste oils requiring responsible management. Strengthening recovery and re-refining practices can increase compliance requirements while creating additional costs across the lubricant value chain.
Emerging Market Trends
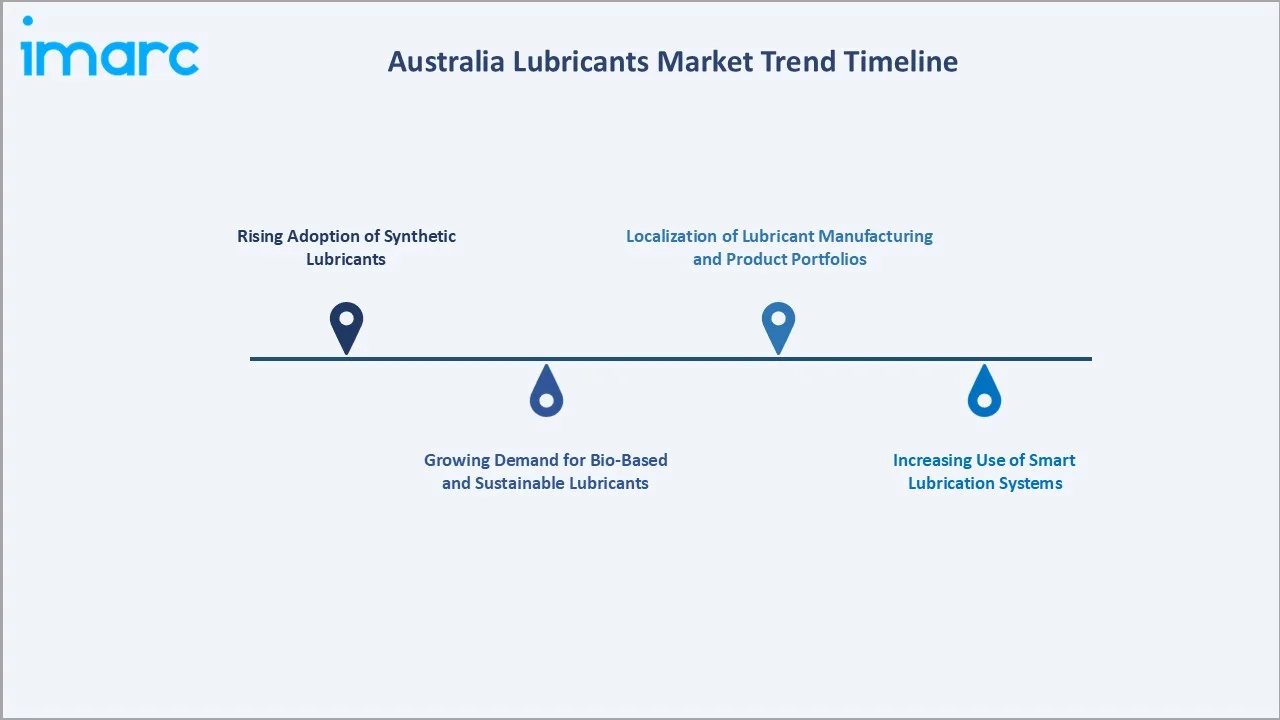
1. Rising Adoption of Synthetic Lubricants
Australian industries are increasingly adopting synthetic and semi-synthetic lubricants for improved equipment protection and longer service intervals. These products provide better performance under extreme temperatures and heavy operating conditions. Mining, transportation, and manufacturing applications are supporting this transition. Reduced maintenance downtime is also encouraging premium lubricant adoption. This trend is strengthening demand for higher-value lubricant formulations.
2. Localization of Lubricant Manufacturing and Product Portfolios
In December 2024, LIQUI MOLY introduced a new range of general-purpose motor oils for the Australian market, expanding its portfolio of lubricants, additives, and car care products. The Special Tec T oils are manufactured at the company’s new facility in Thailand, enabling LIQUI MOLY to deliver German-engineered quality at more competitive prices tailored to Australian market requirements. This launch highlights a growing trend toward regionalized lubricant production and market-specific product development for Australia. Manufacturing closer to the market can improve cost competitiveness, supply reliability, and responsiveness while allowing brands to tailor formulations and pricing to local automotive requirements.
3. Growing Demand for Bio-Based and Sustainable Lubricants
Environmental considerations are encouraging greater interest in biodegradable and lower-impact lubricants across Australia. Mining, marine, agriculture, and environmentally sensitive operations represent important potential applications. Manufacturers are increasingly exploring renewable base stocks and formulations with improved environmental profiles. Corporate sustainability targets are further influencing lubricant procurement decisions. This trend is gradually expanding the market for environmentally acceptable lubricants.
4. Increasing Use of Smart Lubrication Systems
Industrial operators are increasingly integrating automatic lubrication systems, sensors, and condition-monitoring technologies into machinery maintenance programs. These solutions optimize lubricant delivery and reduce the risks associated with over- or under-lubrication. Mining and heavy industrial operations can particularly benefit from automated systems for remotely located equipment. Predictive maintenance platforms also enable operators to monitor lubricant conditions. This trend is supporting more efficient lubricant consumption and equipment management.
Industry Value Chain Analysis
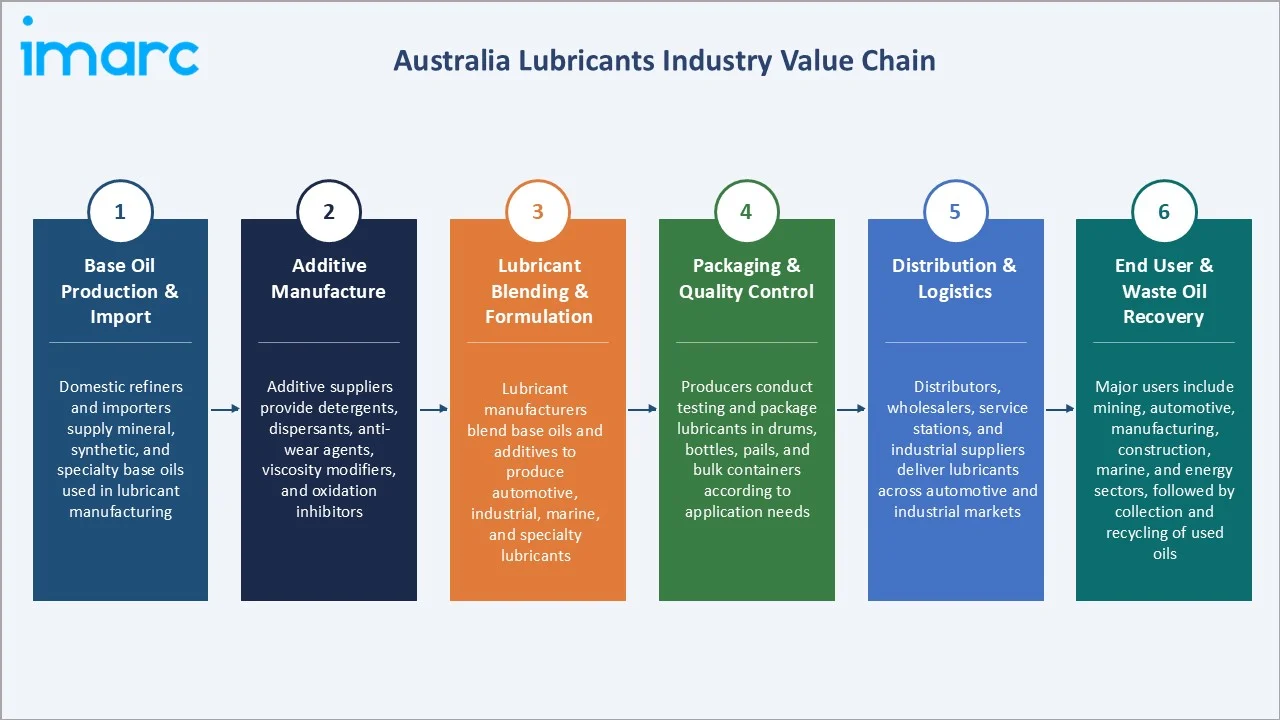
Australia lubricants value chain spans base oil production and importation, additive manufacturing and supply, domestic lubricant blending and formulation, packaging and quality certification, multi-channel distribution, and used oil collection and re-refining through the product stewardship scheme.
|
Stage |
Key Participants |
|
Base Oil Production & Import |
Domestic refiners and importers supply mineral, synthetic, and specialty base oils used in lubricant manufacturing. |
|
Additive Manufacture |
Additive suppliers provide detergents, dispersants, anti-wear agents, viscosity modifiers, and oxidation inhibitors. |
|
Lubricant Blending & Formulation |
Lubricant manufacturers blend base oils and additives to produce automotive, industrial, marine, and specialty lubricants. |
|
Packaging & Quality Control |
Producers conduct testing and package lubricants in drums, bottles, pails, and bulk containers according to application needs. |
|
Distribution & Logistics |
Distributors, wholesalers, service stations, and industrial suppliers deliver lubricants across automotive and industrial markets. |
|
End User & Waste Oil Recovery |
Major users include mining, automotive, manufacturing, construction, marine, and energy sectors, followed by collection and recycling of used oils. |
Lubricant blending & formulation is the most value-added stage in the Australia lubricants market, as it determines product performance, durability, and application-specific characteristics. Advanced formulations for mining, automotive, industrial, marine, and EV applications enable manufacturers to differentiate products and achieve higher margins.
Technology Landscape in the Australia Lubricants Industry
IoT-Enabled Smart Lubrication Technology
Smart lubrication systems integrate IoT sensors, connectivity, and data analytics to monitor lubricant delivery and equipment conditions. Operators can track lubrication performance and identify abnormal conditions before they cause equipment failures. Connected systems also help optimize lubricant consumption and maintenance schedules. The technology is particularly relevant for remote mining and industrial operations. Growing Industry 4.0 adoption is accelerating the transition toward digitally managed lubrication.
Biodegradable and Bio-Based Lubricant Technology
Bio-based and biodegradable formulations are being developed to reduce environmental impacts associated with lubricant leakage and disposal. These products are particularly relevant for marine, forestry, agriculture, construction, and environmentally sensitive operations. Advances in formulation are improving their performance compared with earlier generations. Renewable base stocks and environmentally acceptable additives are becoming more important in product development. Sustainability requirements are supporting further technological innovation in this segment.
Electric Vehicle Fluid and Thermal Management Technology
Increasing electrification is driving the development of specialized EV transmission fluids, dielectric fluids, coolants, and thermal management solutions. These fluids must provide effective heat transfer while maintaining compatibility with electrical components and advanced vehicle materials. Direct cooling technologies are becoming increasingly relevant for batteries and electric drivetrains. Lubricant manufacturers are therefore adapting formulations beyond conventional engine lubrication. This technology represents an important emerging area as Australia's EV fleet expands.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Product Type |
Engine Oil |
26.0% |
2025 |
|
Base Oil |
Mineral Oil |
48.0% |
2025 |
|
End Use Industry |
Automotive and Other Transportation |
30.0% |
2025 |
|
Region |
Australia Capital Territory & New South Wales |
27.0% |
2025 |

By Product Type
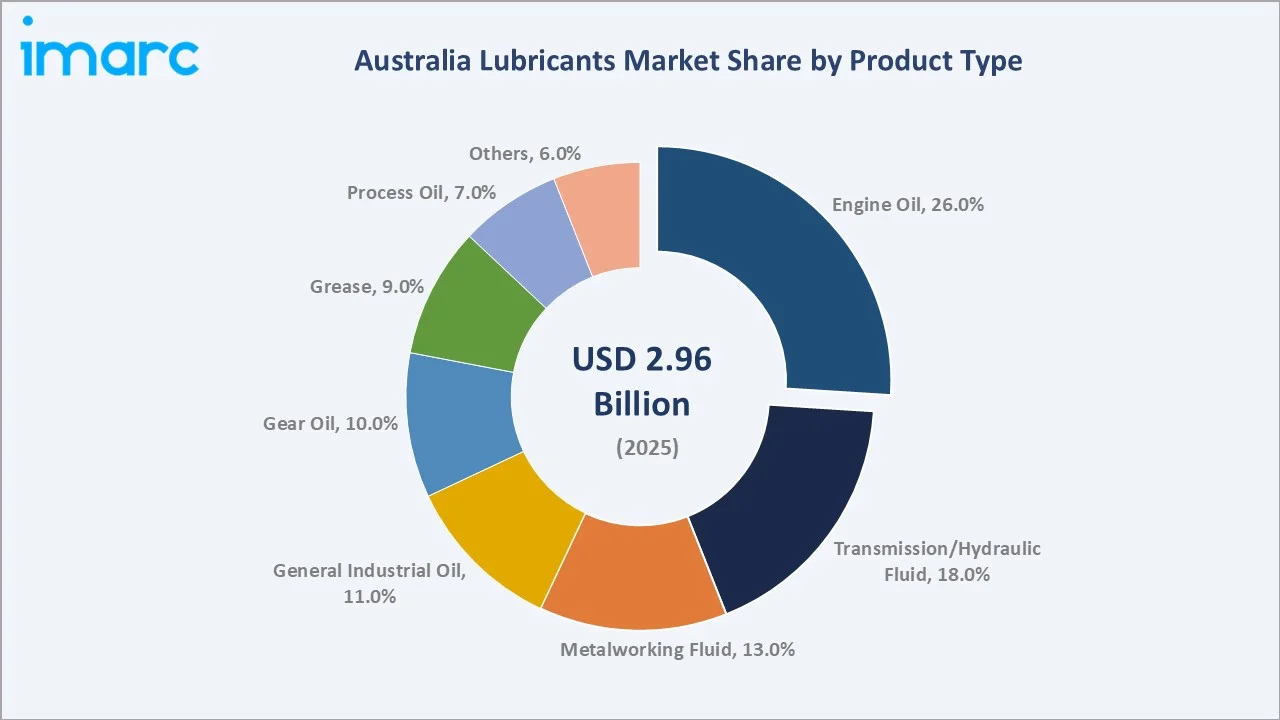
Engine oil leads at 26.0% (2025) through the automotive fleet and mining heavy equipment’s dominant lubrication requirement. Transmission/hydraulic fluid at 18.0% serves Australia’s massive mining equipment hydraulic systems and automotive transmissions.
To access detailed market analysis, Request Sample
Metalworking fluid at 13.0%, growing at ~4.80% CAGR, through advanced manufacturing and defense sector expansion. General industrial oil at 11.0%, gear oil at 10.0%, grease at 9.0%, process oil at 7.0%, and others at 6.0% complete the product spectrum.
By Base Oil
Mineral oil leads at 48.0% (2025) through cost-competitive general industrial and mainstream automotive applications.
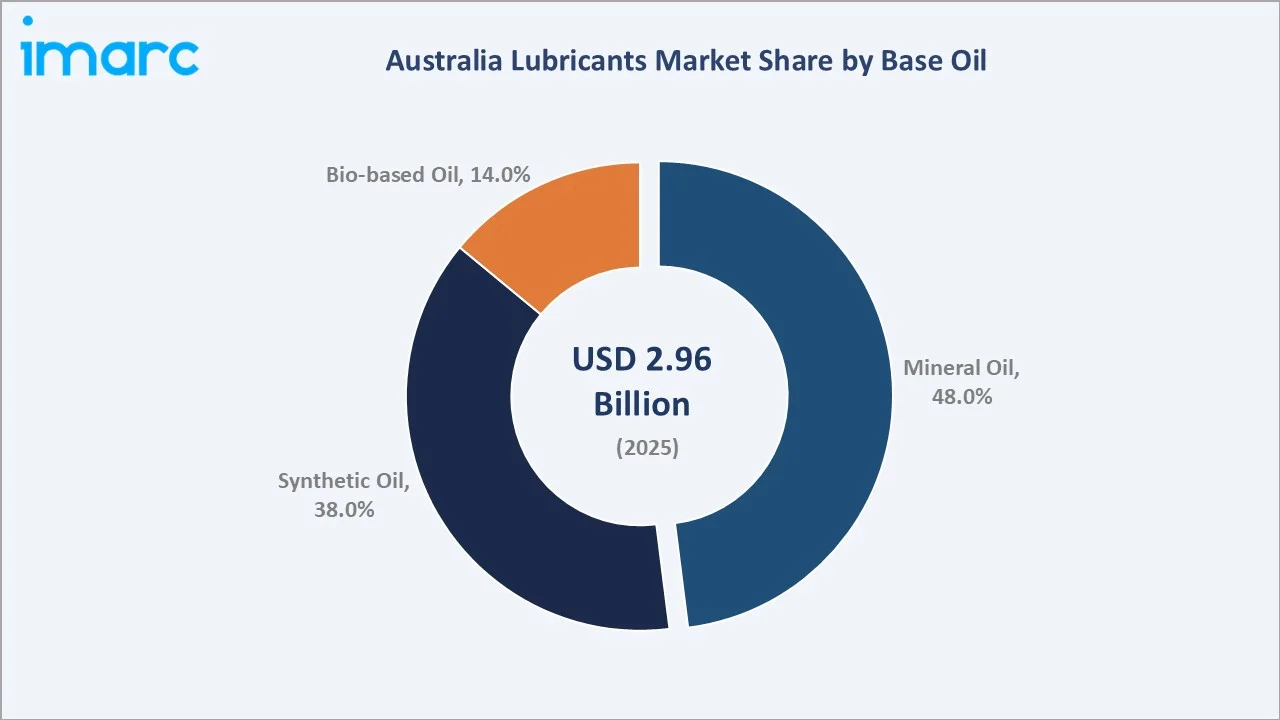
Synthetic oil at 38.0%, growing at ~5.90% CAGR, through premium automotive, mining, and power generation adoption. Bio-based oil at 14.0%, growing fastest at ~7.80% CAGR, through environmental compliance in sensitive industrial and renewable energy applications.
Regional Market Insights
|
Region |
Share (2025) |
Key Lubricants Market Drivers & Characteristics |
|
Australia Capital Territory & New South Wales |
27.0% |
Leads due to high vehicle density, diversified industrial activity, infrastructure development, and strong commercial transportation demand. |
|
Victoria & Tasmania |
23.0% |
Supported by manufacturing, automotive servicing, logistics, agriculture, and industrial equipment maintenance. |
|
Queensland |
21.0% |
Strong mining, agriculture, construction, and freight activities generate demand for heavy-duty and industrial lubricants. |
|
Western Australia |
17.0% |
Mining, iron ore, LNG, and heavy machinery operations support substantial demand for high-performance lubricants and greases. |
|
Northern Territory & Southern Australia |
12.0% |
Demand is supported by mining, agriculture, transportation, energy, and selected manufacturing and infrastructure activities. |
The Australia Capital Territory & New South Wales region leads with a 27.0% share in 2025, supported by high vehicle presence, diversified industrial activity, logistics, and commercial operations. Victoria & Tasmania account for 23.0%, benefiting from manufacturing, transportation, and automotive servicing activities. Queensland holds 21.0%, with lubricant demand supported by mining, agriculture, construction, and heavy equipment operations.
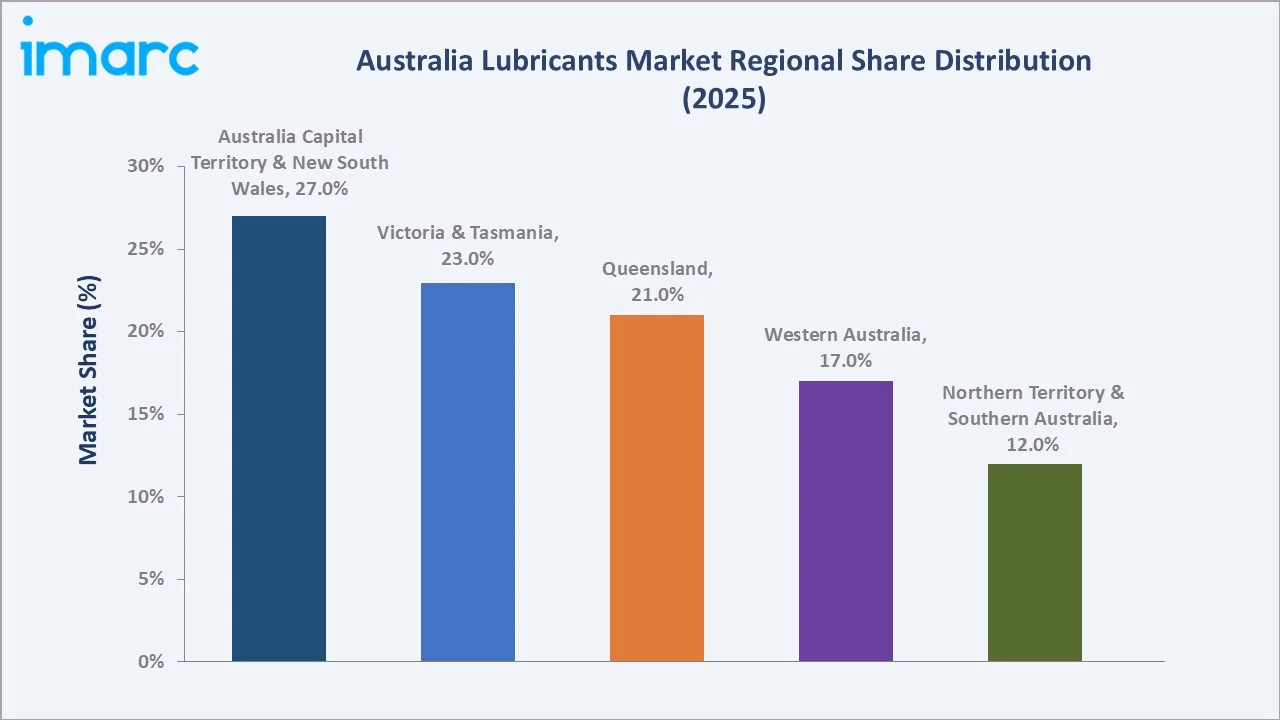
Western Australia represents 17.0%, driven primarily by extensive iron ore mining, LNG operations, and heavy-duty machinery usage. Northern Territory & Southern Australia account for the remaining 12.0%, supported by mining, agriculture, transportation, energy, and infrastructure activities.
Competitive Landscape
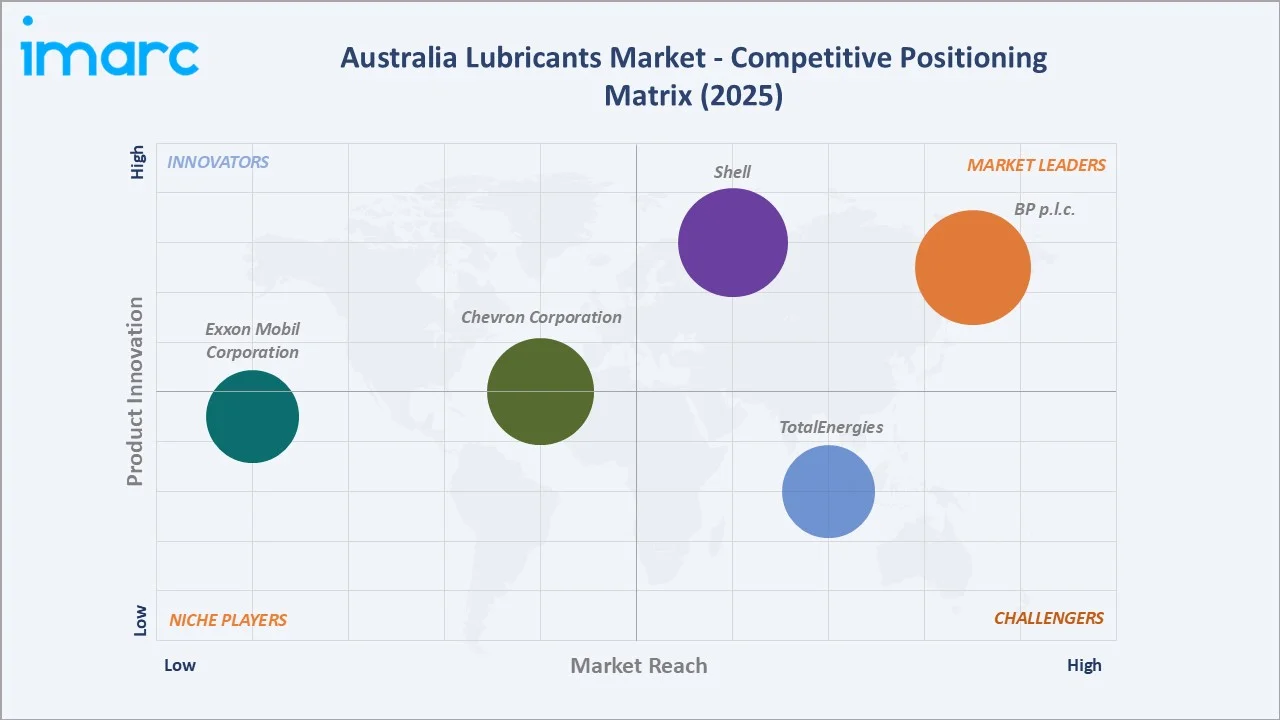
The Australia lubricants market is moderately consolidated, featuring established multinational oil companies, specialized lubricant manufacturers, and domestic suppliers. Competition centers on product performance, brand reputation, distribution reach, technical services, pricing, and innovation in synthetic and specialty lubricants.
|
Company |
Key Products |
Market Position |
Core Strength |
|
Shell |
Shell Helix Ultra engine oil, Shell Rimula Truck & Light Duty Oils, Shell Rimula Truck & Heavy-duty Engine Oils |
Market Leader |
Shell is the leading supplier of lubricants in Australia, providing essential oils, greases, and fluids to keep the nation’s heavy industries, transport, and consumer vehicles moving. |
|
BP p.l.c. |
Castrol EDGE engine oils, Castrol GTX engine oils, Castrol MAGNATEC engine oils, Castrol SPHEEROL, Castrol VECTON |
Market Leader |
The company operates in this sector primarily through its flagship lubricants brand, Castrol, supplying high-performance oils, greases, and detergents to the mining, transport, agriculture, and retail sectors. |
|
Exxon Mobil Corporation |
SpectraSyn Elite mPAO, SpectraSyn Hi Vis PAO, SpectraSyn low-viscosity PAO, SpectraSyn Plus PAO |
Established Player |
Key provider of Mobil-branded oils and greases, supplying premium automotive, commercial, and industrial lubricants. |
|
Chevron Corporation |
Black Pearl Grease EP 1, 2, Black Pearl Grease SRI 2, Starplex HD 1, 2 Greases, HDAX 3100 Ashless Gas Engine Oils, HDAX 9200 Low Ash Gas Engine Oil, GST Advantage EP |
Established Player |
Chevron Corporation manufactures and supplies premium motor oils, greases, and industrial lubricants |
|
TotalEnergies |
A GREASE COMPLEX HV 2, A-GREASE CLASSIC, A-GREASE FIL EP 2, AERO 100, AERO 120 |
Challenger |
TotalEnergies plays a major role in the Australian lubricants market by supplying high-performance engine oils, greases, and specialty fluids. |
Australia lubricants competitive landscape is defined by the tension between multinational brand technical authority commanding premium pricing through OEM approvals, technical service, and motorsport marketing; domestic independent brands competing on price, local relevance, and service agility; and specialty operators carving defensible positions in service or specification niches that generalist competitors cannot match.
Key Company Profiles
Shell
Shell is an energy and petrochemical company with a long-standing presence in Australia. Its Australian activities span gas and LNG, power, renewable energy, fuels, and lubricants. Within the Australia lubricants market, Shell offers a broad portfolio covering passenger vehicles, heavy-duty transport, mining, manufacturing, and other industrial applications, including brands such as Shell Helix and Rimula. Shell-branded fuels and lubricants are supplied across Australia under an exclusive brand-license arrangement.
- Key Products: Shell Helix Ultra engine oil, Shell Rimula Truck & Light Duty Oils, Shell Rimula Truck & Heavy-duty Engine Oils.
- Strategic Focus: Focuses on premium and high-performance lubricant solutions for automotive, mining, transport, manufacturing, marine, and other industrial applications. Its strategy is supported by product innovation, synthetic lubricant technologies, technical services, and a broad distribution network.
BP p.l.c.
BP p.l.c. is an energy company with a significant presence in Australia across fuels, energy infrastructure, and lubricants. In the Australia lubricants market, BP participates primarily through Castrol Australia, its lubricants business, serving automotive, industrial, mining, marine, and energy applications. Its Castrol portfolio includes engine oils, transmission fluids, coolants, greases, metalworking fluids, and industrial lubricants, with an emphasis on equipment protection, efficiency, reliability, and performance. This broad product and technical-service portfolio supports BP’s position across both automotive and industrial lubricant applications in Australia.
- Key Products: Castrol EDGE engine oils, Castrol GTX engine oils, Castrol MAGNATEC engine oils, Castrol SPHEEROL, Castrol VECTON.
- Strategic Focus: Through Castrol, focuses on premium automotive and industrial lubricants, technological innovation, and application-specific solutions. Castrol is expanding into EV fluids, industrial lubrication, digital maintenance services, and sustainable solutions, while emphasizing equipment efficiency, reliability, and lower total operating costs for Australian customers.
Market Concentration Analysis
The Australia lubricants market is moderately consolidated, with major multinational suppliers competing alongside established domestic lubricant manufacturers. Competition is driven by brand reputation, product performance, distribution coverage, pricing, and technical support. Large players benefit from extensive supply networks and broad automotive and industrial portfolios. Meanwhile, domestic and specialty manufacturers compete through localized production and application-specific formulations. Increasing demand for synthetic, EV-specific, and specialty lubricants is further encouraging product differentiation and innovation.
Investment & Growth Opportunities
Highest Growth Segments
Bio-based oil (~7.80% CAGR) and synthetic oil (~5.90% CAGR) represent Australia’s lubricants market’s highest-growth investment opportunities through 2034, driven by regulatory environmental compliance mandates and OEM specification tightening, respectively.
Investment Themes
- Wind Turbine Specialty Lubricants: Investment in high-performance gear oils, bearing greases, and hydraulic fluids offers opportunities as Australia expands wind power capacity. These specialized lubricants help reduce wear, extend maintenance intervals, and improve turbine reliability, particularly at remote wind farms.
- EV-Specific Fluid Platform: Growing EV adoption creates investment opportunities in integrated platforms for e-transmission fluids, dielectric coolants, thermal management fluids, and specialized greases. Developing EV-specific formulations can help lubricant suppliers offset declining conventional engine-oil demand while capturing higher-value mobility applications.
Future Market Outlook (2026-2034)
The Australia lubricants market is projected to grow from USD 2.96 Billion in 2025 to USD 4.33 Billion by 2034, delivering a robust 4.32% CAGR that reflects Australia’s unique position as a developed economy with both the consumption characteristics of a mature, high-income market (quality-driven automotive lubricant demand) and the industrial lubricant intensity of a resource superpower (mining and energy sector lubricant consumption). The midpoint anchor of USD 3.66 Billion in 2030 confirms the structural consistency of Australia’s lubricant market growth across commodity price cycles, COVID disruptions, and energy transition pressures.
First, Australia’s mining sector’s sustained capital intensity and its progressive expansion into critical minerals for the global energy transition create a lubricant demand growth engine that is unique among developed economies in scale and growth velocity. Second, Australia’s renewable energy infrastructure buildout creates a rapidly expanding specialty lubricant demand stream and will constitute an increasingly meaningful share of total market value by 2034. Third, Australia’s lubricant market’s value growth is structurally supported by the progressive premiumization of both automotive and industrial lubricant specifications that drives average selling price above inflation even as volume growth remains moderate.
Research Methodology
Primary Research
Primary research comprised in-depth interviews with lubricant supply managers, technical directors, fleet managers, food and beverage manufacturing maintenance managers, renewable energy O&M managers, independent lubricant distributors, and automotive workshop owners.
Secondary Research
Secondary research encompassed government publications, industry reports, trade databases, company annual reports, regulatory sources, and industry associations. The research also assessed automotive and industrial lubricant demand, mining activity, product trends, competitive developments, distribution networks, and technological advancements across Australia.
Forecasting Models
Forecasting models were developed using historical Australia lubricants market data (2020-2025), vehicle registration growth trajectory, Australian mining sector capex investment pipeline, critical minerals project development timeline, wind turbine installation rate, EV penetration rate scenario modeling, base oil price modeling, and per-vehicle lubricant consumption shift from mineral to synthetic grade.
Australia Lubricants Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report | Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Product Types Covered | Engine Oil, Transmission/Hydraulic Fluid, Metalworking Fluid, General Industrial Oil, Gear Oil, Grease, Process Oil, Others |
| Base Oils Covered | Mineral Oil, Synthetic Oil, Bio-based Oil |
| End Use Industries Covered | Power Generation, Automotive and Other Transportation, Heavy Equipment, Food and Beverage, Metallurgy and Metalworking, Others |
| Regions Covered | Australia Capital Territory & New South Wales, Victoria & Tasmania, Queensland, Northern territory & Southern Australia, Western Australia |
| Companies Covered | Shell, BP p.l.c., Exxon Mobil Corporation, Chevron Corporation, TotalEnergies, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Frequently Asked Questions About the Australia Lubricants Market Report
The Australia lubricants market reached USD 2.96 Billion in 2025, driven by strong demand from mining, automotive, construction, manufacturing, and transportation activities. Growing adoption of synthetic lubricants, advanced industrial fluids, and specialized products for heavy-duty equipment further supported market expansion.
The market grows at a 4.32% CAGR, reaching USD 4.33 Billion by 2034, supported by sustained demand from mining, transportation, manufacturing, and construction, alongside rising adoption of synthetic, specialty, and EV-focused lubricants.
Engine oil leads at 26.0% (2025) through Australia’s registered vehicle fleet and the heavy-duty mining haul truck fleet’s intensive engine oil consumption.
Mineral oil leads at 48.0% (2025) through cost-competitive dominance in general industrial, agricultural, mainstream automotive, and marine applications where Group I and II base oils meet specification requirements at significantly lower cost than synthetic alternatives.
Australia Capital Territory & New South Wales lead at 27.0% through NSW’s population, Hunter Valley coal mining, Port Botany marine lubricant demand, and Sydney’s role as Australia’s primary lubricant import and distribution hub.
Leading companies include Shell, BP p.l.c., Exxon Mobil Corporation, Chevron Corporation, and TotalEnergies, among others.
The market is projected to reach USD 3.66 Billion by 2030, driven by sustained demand from mining, automotive, transportation, construction, and manufacturing activities. Rising adoption of synthetic lubricants, specialty industrial fluids, and EV-specific solutions is also expected to support market growth.
Top investment opportunities include wind turbine specialty biodegradable gear oil, EV-specific Australian climate-calibrated fluids, critical minerals mining supply agreements, Australian-manufactured bio-based lubricant from agricultural feedstock, and used oil re-refinery expansion.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade