
Australia Modular Construction Market Size, Share, Trends and Forecast by Type, Module Type, Material, End Use, and Region, 2026-2034
Australia Modular Construction Market Size, Share, Trends & Forecast (2026-2034)
The Australia modular construction market grew from USD 11.80 Billion in 2025 to USD 12.45 Billion in 2026 and is projected to reach USD 17.10 Billion by 2034, exhibiting a CAGR of 4.05% during 2026-20344. Increasing adoption of off-site manufacturing technology, sustained government infrastructure programs, and persistent housing supply pressures across major urban centers are the primary forces shaping market growth.
Permanent leads the type segment at 54.0%, while commercial commands the largest end use share at 32.0%. Australia Capital Territory & New South Wales holds regional leadership at 36.0%.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 11.80 Billion |
|
Market Size (2026) |
USD 12.45 Billion |
|
Forecast Market Size (2034) |
USD 17.10 Billion |
|
CAGR (2026-2034) |
4.05% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
| Largest Region |
Australia Capital Territory & New South Wales (36.0%, 2025) |
| Second Largest Region |
Victoria & Tasmania (24.1%, 2025) |
| Leading Type |
Permanent (54.0%, 2025) |
| Leading End Use | Commercial (32.0%, 2025) |
The Australia modular construction market size increased from USD 9.68 Billion in 2020 to USD 11.80 Billion in 2025 and is estimated to reach USD 12.45 Billion in 2026. The market is further expected to grow to USD 14.40 Billion by 2030 and USD 17.10 Billion by 2034. The market occupies a distinctive position within the broader Australian construction sector, underpinned by one of the Asia-Pacific region's fastest-growing off-site manufacturing ecosystems and a growing pipeline of commercial and residential projects requiring faster, more cost-certain delivery methods.
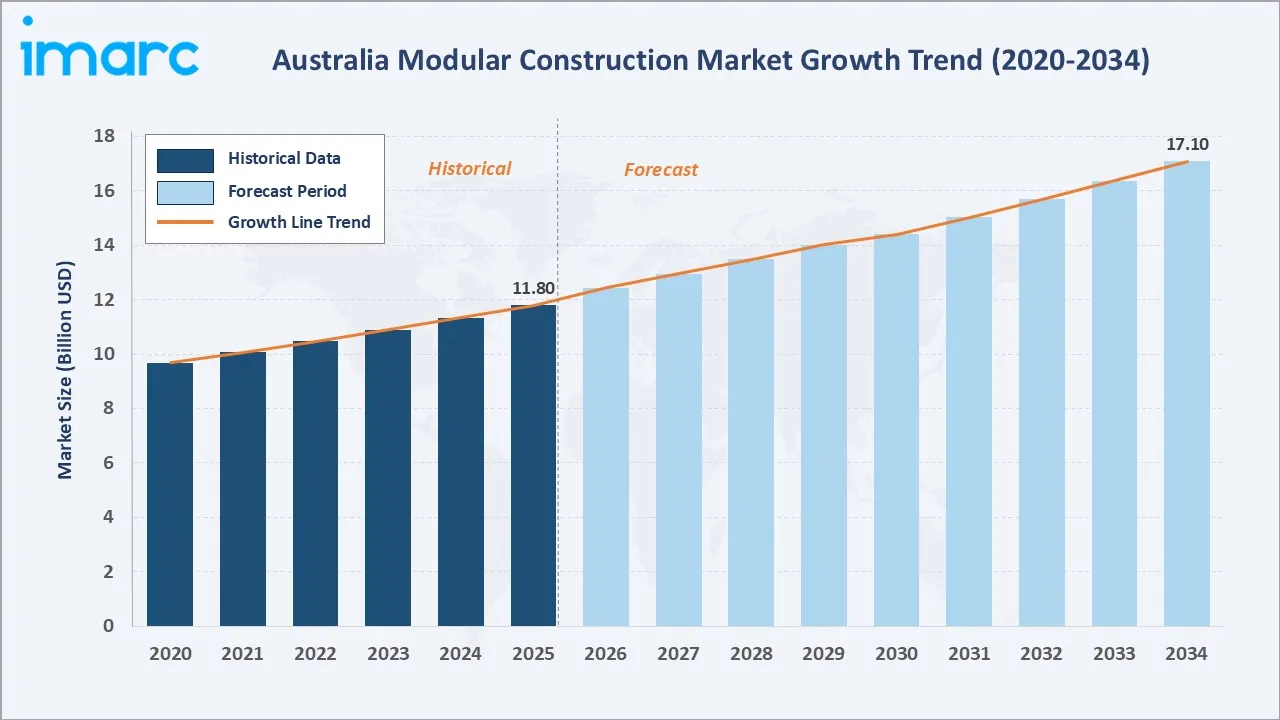
To get more information on this market, Request Sample
CAGR trajectories across type, end use, and regional sub-segments show relocatable, healthcare, and Northern Territory & Southern Australia expanding faster than the overall 4.05% market CAGR, driven by resource sector workforce accommodations, healthcare infrastructure investment, and remote community development programs respectively.
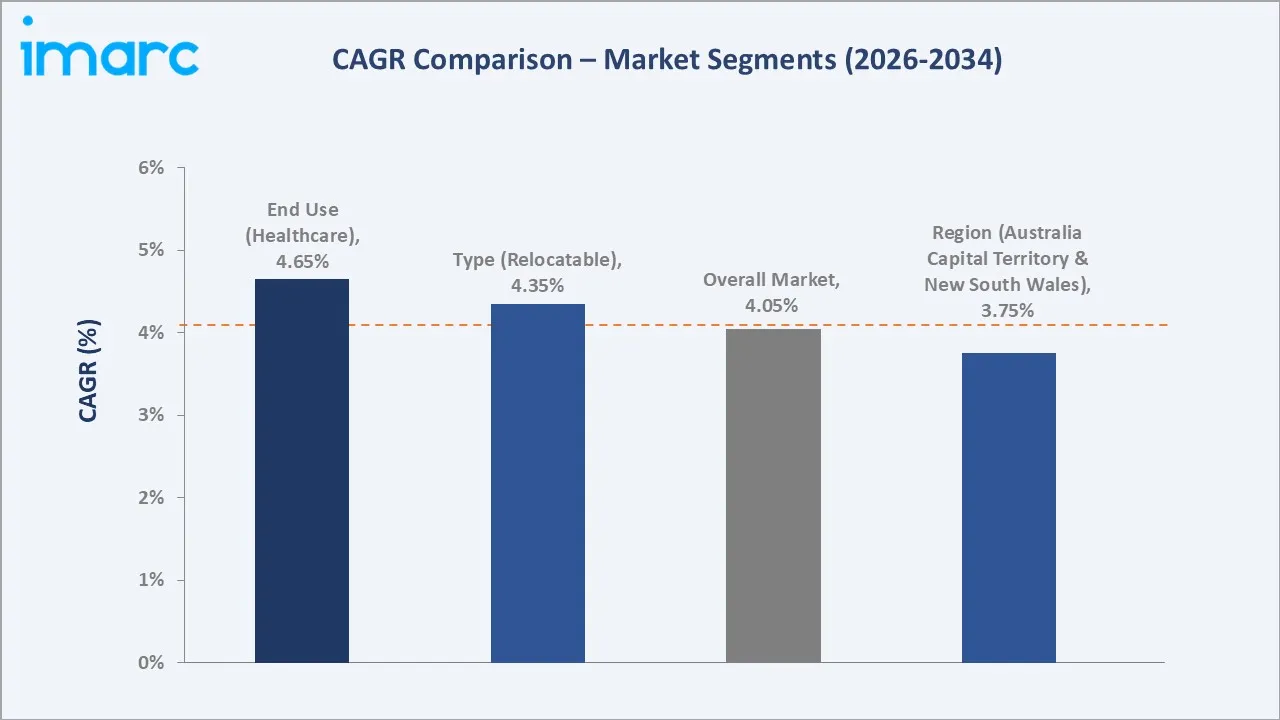
Executive Summary
The Australia modular construction market expanded from USD 11.80 Billion in 2025 to an estimated USD 12.45 Billion in 2026, positioning it among the stronger-growing construction delivery segments in the Asia-Pacific region. The market's scale is underpinned by sustained government housing and infrastructure investment, growing adoption of off-site manufacturing methods, and expanding commercial and healthcare sector demand for faster project delivery.
Permanent commands 54.0% of the type segment, reflecting developer and institutional preference for multi-decade operational buildings in commercial, healthcare, and education applications. Within the end use segment, commercial leads at 32.0%, driven by sustained office, retail, and mixed-use development activity across Sydney, Melbourne, and Brisbane. Australia Capital Territory & New South Wales holds the leading regional share at 36.0%, anchored by the concentration of major urban centers and sustained demand for residential and commercial construction projects.
Key Market Insights
|
Insight |
Data |
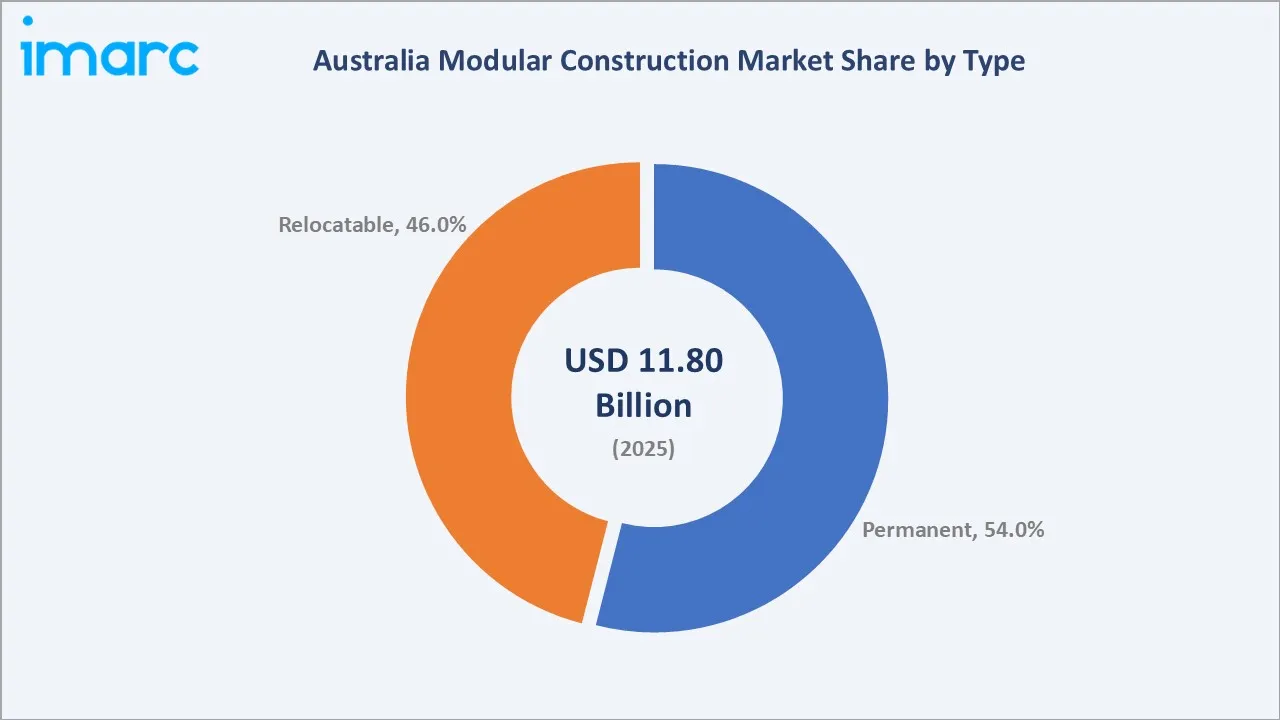
| Leading Type | Permanent – 54.0% share (2025) |
| Second Largest Type | Relocatable – 46.0% share (2025) |
| Leading End Use |
Commercial – 32.0% share (2025) |
| Second Largest End Use | Residential – 21.5% share (2025) |
| Leading Region |
Australia Capital Territory & New South Wales – 36.0% share (2025) |
| Second Largest Region |
Victoria & Tasmania – 24.1% share (2025) |
| Top Companies | Lendlease Group, Fleetwood Limited, ATCO Ltd. |
Key Analytical Observations Expanding On the Data Above:
- Permanent dominance at 54.0% reflects developer and institutional confidence in modular construction for long-lifecycle commercial, healthcare, and education buildings, where structural performance and design adaptability have improved significantly.
- Relocatable share at 46.0% remains strong due to Australia's large resource and infrastructure project pipeline, which sustains demand for high-quality, deployable workforce accommodations and site facilities across Western Australia and Queensland.
- Commercial leadership at 32.0% is driven by growing developer adoption of modular methods for cost-certain, schedule-reliable delivery of office, mixed-use, and retail facilities in constrained urban construction environments.
- Residential at 21.5% is gaining momentum as government affordable housing programs, build-to-rent sector growth, and the persistent housing supply deficit in Sydney, Melbourne, and Brisbane accelerate uptake.
- Australia Capital Territory & New South Wales at 36.0% leads regionally, driven by concentration of commercial activity, government infrastructure projects, and high housing demand across the greater Sydney and Canberra markets.
Australia Modular Construction Market Overview
Modular construction involves the off-site manufacturing of standardized building units, known as modules, within controlled factory environments, followed by their on-site assembly and installation. The methodology applies to both permanent and relocatable structures across commercial, residential, healthcare, education, and hospitality sectors.
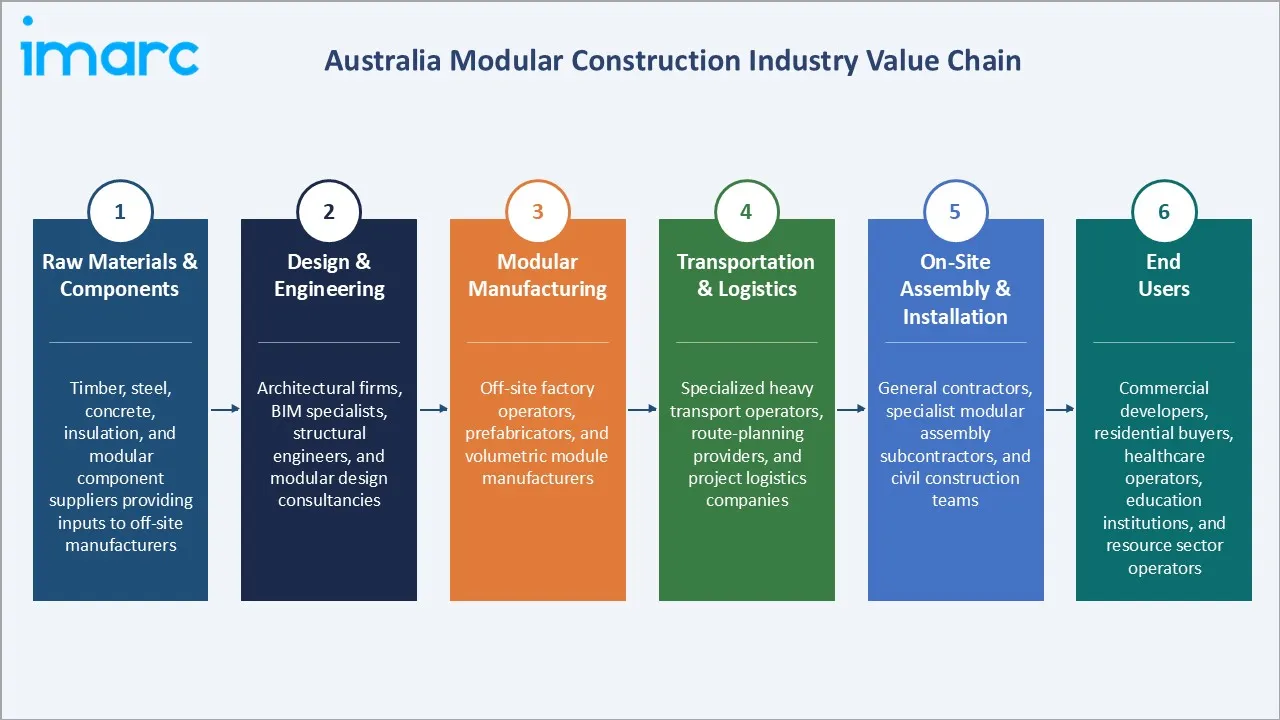
The Australia modular construction ecosystem integrates raw material suppliers, component manufacturers, design and engineering firms, off-site fabricators, transportation operators, on-site assembly contractors, and end use clients. Government agencies, standards bodies, environmental certification organizations, and technology providers form the supporting regulatory and operational layer, enabling an increasingly sophisticated construction delivery system across Australia's residential and non-residential sectors.
Market Dynamics
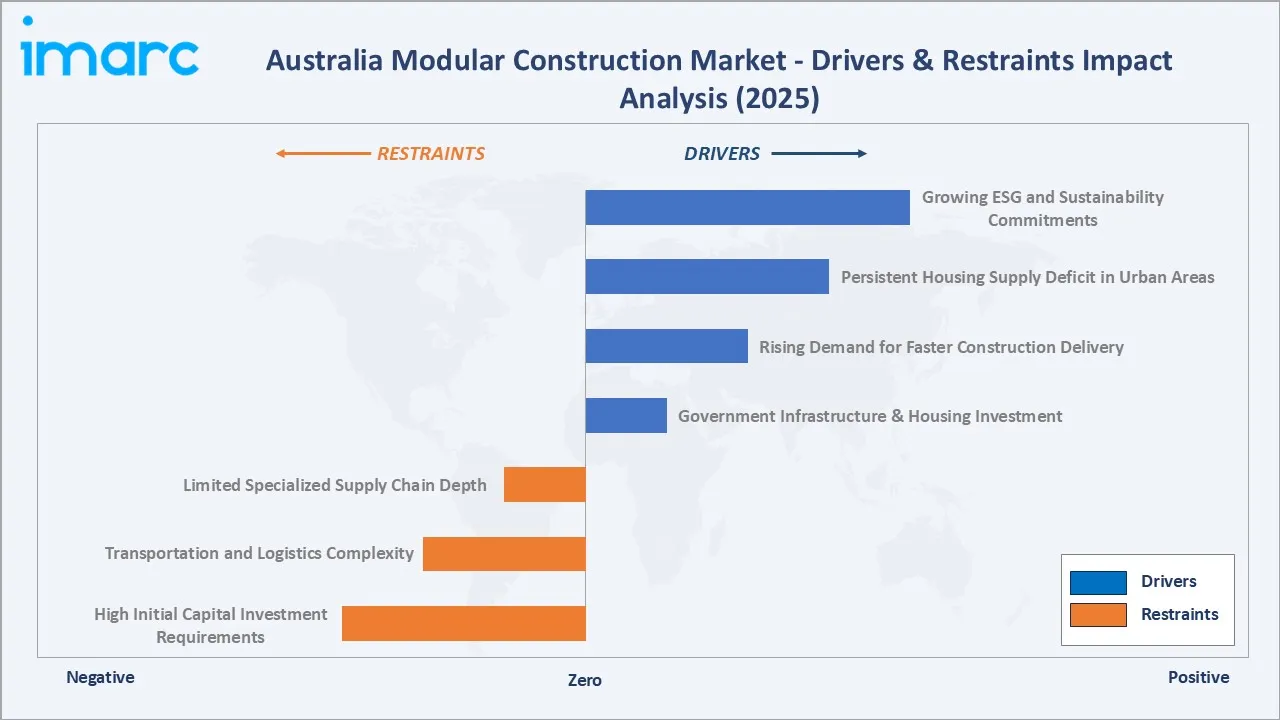
To evaluate market opportunities, Request Sample
Market Drivers
- Government Infrastructure & Housing Investment: Australia's National Housing Accord targets 1.2 Million new homes over five years from 2024, directly increasing the addressable volume for modular construction methods that can deliver residential units faster and at lower cost than conventional construction approaches.
- Rising Demand for Faster Construction Delivery: Commercial developers and institutional clients increasingly select modular construction for its ability to compress project timelines, reduce on-site labor dependency, and deliver more predictable build costs compared to traditional methods, driving steady adoption across office, retail, and mixed-use project pipelines.
- Persistent Housing Supply Deficit in Urban Areas: The persistent housing supply deficit across Sydney, Melbourne, and Brisbane is accelerating government and developer interest in modular methods as a scalable solution for delivering affordable and social housing within compressed timeframes and tighter budgets.
- Growing ESG and Sustainability Commitments: Growing ESG commitments among Australian institutional developers and listed property trusts are increasing demand for construction methods that reduce site waste, lower embodied carbon, and support green building certification, areas where modular construction has measurable advantages over conventional delivery.
Market Restraints
- High Initial Capital Investment Requirements: Establishing off-site manufacturing facilities requires substantial upfront capital in specialized equipment, factory space, and skilled workforce development, creating significant barriers for smaller construction companies seeking market entry.
- Transportation and Logistics Complexity: The movement of large pre-manufactured modules from factory facilities to construction sites requires specialized heavy transport vehicles, route planning, and permits, adding logistical complexity and cost to project delivery across diverse geographies.
- Limited Specialized Supply Chain Depth: The domestic supply chain for specialized modular construction components remains less developed than traditional construction supply networks, limiting sourcing flexibility and creating dependencies on a narrow supplier base for critical manufactured components.
Market Opportunities
- Healthcare and Education Sector Expansion: Growing demand for rapid facility construction in healthcare and education sectors creates strong addressable opportunity for modular solutions that can deliver certified clinical and academic buildings within compressed timeframes, meeting urgent capacity requirements.
- Resource Sector Workforce Accommodation Demand: Expanding resource sector projects across Western Australia and Queensland continue to generate sustained demand for high-quality, rapidly deployable workforce accommodations, a core modular construction application that underpins a significant portion of the relocatable segment.
Market Challenges
- Perception Gaps Among Traditional Developers: A segment of the development community continues to associate modular construction with lower quality compared to conventional methods, limiting adoption among established developers who default to traditional delivery approaches without evaluating updated performance standards.
- Regulatory and Planning Approval Complexity: Variations in building codes, approval procedures, and compliance requirements across Australian states and territories can create administrative challenges for modular construction projects. These complexities may extend project approval timelines, increase compliance costs, and affect the pace of market adoption.
Emerging Market Trends
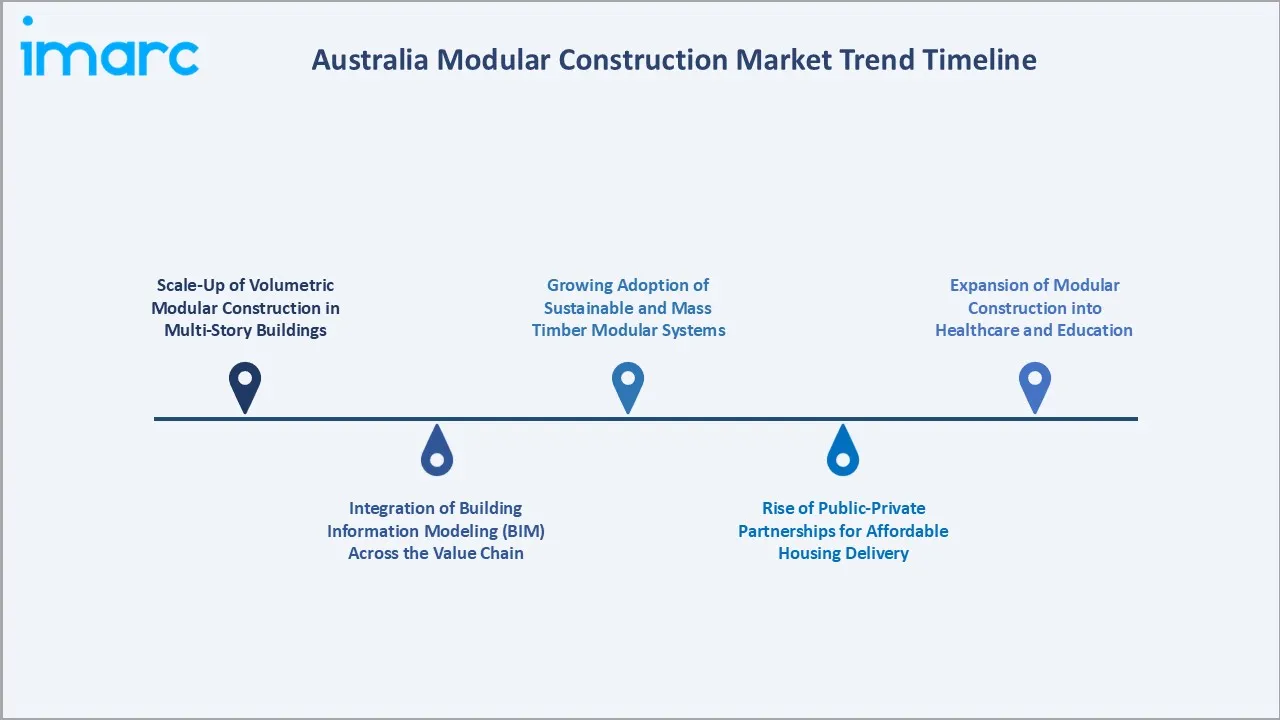
1. Scale-Up of Volumetric Modular Construction in Multi-Story Buildings
Volumetric modular construction is gaining adoption in multi-story residential, hotel, and commercial buildings across Sydney and Melbourne, moving beyond its traditional application in low-rise structures. Developers are using factory-built modules to build high-density residential towers with significantly reduced on-site construction time, improving schedule certainty and reducing community disruption.
2. Integration of Building Information Modeling (BIM) Across the Value Chain
BIM is being adopted end-to-end across the modular construction value chain, from design and engineering through manufacturing and on-site assembly. BIM-enabled digital coordination reduces design clashes, improves manufacturing precision, and accelerates approval timelines.
3. Growing Adoption of Sustainable and Mass Timber Modular Systems
Engineered mass timber, including cross-laminated timber and glued-laminated timber, is increasingly used in modular building systems, driven by its low embodied carbon, structural strength, and design versatility. Australian modular builders are incorporating timber-based modules in residential, education, and commercial buildings to meet green star and sustainability certification requirements.
4. Rise of Public-Private Partnerships for Affordable Housing Delivery
State governments across New South Wales, Victoria, and Queensland are partnering with private modular construction operators to accelerate social and affordable housing delivery. These partnerships leverage the speed and cost advantages of modular methods to increase housing supply without commensurate increases in construction program or public capital expenditure.
5. Expansion of Modular Construction into Healthcare and Education
Demand from healthcare and education sectors is broadening the modular construction addressable market beyond commercial and residential applications. State government school building programs and hospital expansion projects are increasingly specifying modular methods to deliver certified facilities within tight operational constraints, with minimal disruption to surrounding campus activities.
Industry Value Chain Analysis
The Australia modular construction value chain spans six stages, from raw material and component supply through design, manufacturing, logistics, on-site assembly, and delivery to end users. Manufacturing and design stages capture the highest value-add, while transportation and on-site assembly expertise are increasingly critical competitive differentiators in a market where project speed and scheduling certainty define contractor selection.
|
Stage |
Key Players / Examples |
| Raw Materials & Components | Timber, steel, concrete, insulation, and modular component suppliers providing inputs to off-site manufacturers |
| Design & Engineering | Architectural firms, BIM specialists, structural engineers, and modular design consultancies |
| Modular Manufacturing | Off-site factory operators, prefabricators, and volumetric module manufacturers |
| Transportation & Logistics | Specialized heavy transport operators, route-planning providers, and project logistics companies |
| On-Site Assembly & Installation | General contractors, specialist modular assembly subcontractors, and civil construction teams |
| End Users | Commercial developers, residential buyers, healthcare operators, education institutions, and resource sector operators |
Vertically integrated operators controlling design, manufacturing, and on-site assembly are positioned to capture greater margin and deliver superior schedule certainty than single-stage participants dependent on third-party manufacturers or independent installers.
Technology Landscape in the Australia Modular Construction Industry
BIM & Digital Twin Technology
BIM and digital twin platforms are transforming the modular construction design and delivery process by enabling full 3D coordination between design, manufacturing, and assembly teams. Digital twins of manufactured modules allow quality verification before dispatch, reducing on-site rework and improving installation precision.
Advanced Off-Site Manufacturing & Robotics
Robotic welding, automated cutting systems, and CNC-driven fabrication equipment are being integrated into Australian modular manufacturing facilities to improve output consistency, reduce labor intensity, and increase manufacturing throughput. Automation supports quality standardization and reduces dependency on skilled trade labor.
Sustainable Materials & Green Building Innovation
Engineered mass timber, recycled steel, and low-embodied-carbon concrete are being incorporated into modular building systems to meet green star certification requirements and institutional sustainability mandates. Material innovation is enabling modular buildings to achieve equivalent or superior environmental performance to conventionally built structures.
Smart Building Integration & IoT
Smart building sensors, IoT-enabled mechanical systems, and energy management platforms are being factory-fitted into modular buildings before dispatch, reducing on-site integration complexity. Pre-fitted smart systems support building performance monitoring, energy optimization, and preventive maintenance from day one of occupancy.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Type |
Permanent |
54.0% |
2025 |
| Module Type | Four Sided |
29.0% |
2025 |
| Material | Steel | 42.0% | 2025 |
| End Use | Commercial | 32.0% | 2025 |
|
Region |
Australia Capital Territory & New South Wales |
36.0% |
2025 |

By Type
Permanent accounts for 54.0% of the market, driven by strong demand from commercial, healthcare, and education sectors that require buildings with multi-decade operational lifespans. The segment benefits from improving structural performance standards, growing developer confidence in long-term durability, and expanding use of permanent modular solutions for multi-story commercial and residential projects.
To access detailed market analysis, Request Sample
Relocatable accounts for 46.0% of the type segment in 2025, supported by continued demand from resource sector workforce accommodations, temporary commercial premises, construction site offices, and educational and healthcare overflow capacity.
By End Use
Commercial leads the market at 32.0%, driven by strong developer adoption of modular delivery for office buildings, retail facilities, and mixed-use developments that prioritize cost certainty and schedule reliability. The segment benefits from growing recognition that modular construction can deliver high-quality buildings with reduced program risk compared to traditional methods.
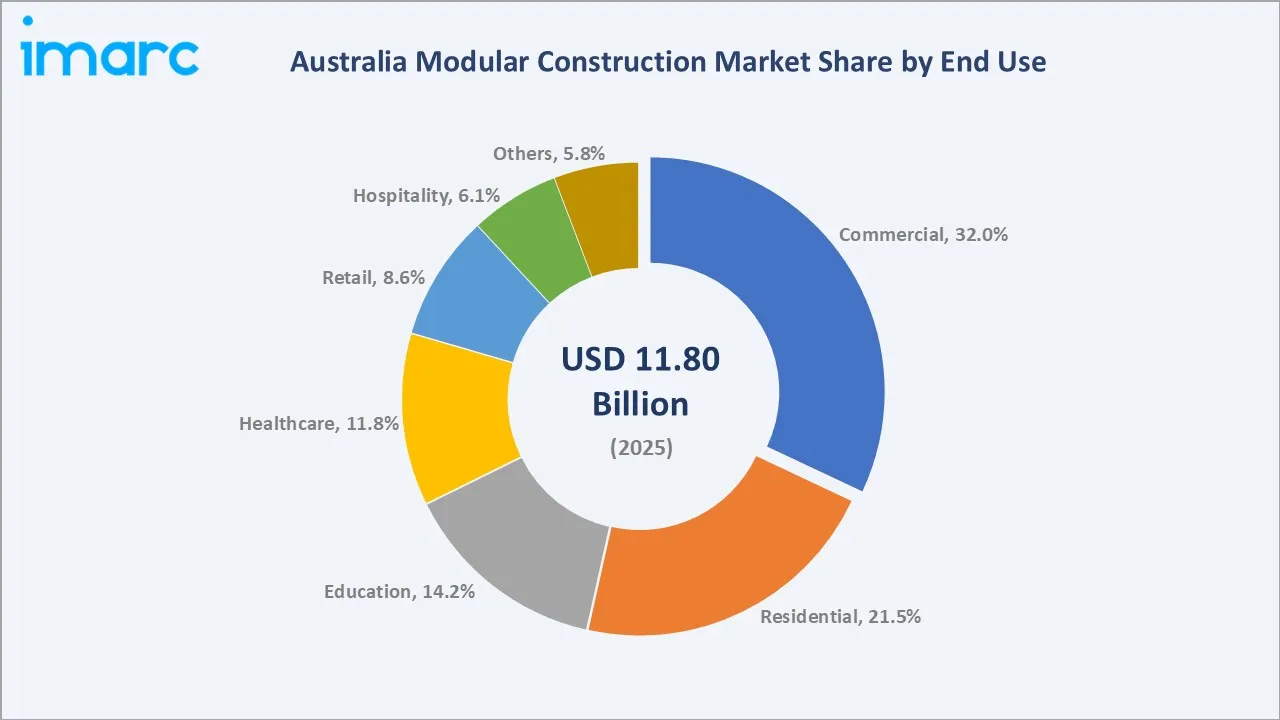
Residential accounts for 21.5% of the market, supported by government affordable housing initiatives, build-to-rent sector growth, and the persistent housing supply deficit across Sydney, Melbourne, and Brisbane.
Regional Market Insights
|
Region |
Share (2025) |
Key Growth Drivers |
| Australia Capital Territory & New South Wales | 36.0% | Concentrated commercial development, government infrastructure programs, National Housing Accord commitments, and high residential demand |
| Victoria & Tasmania | 24.1% | Expanding urban construction activity, growing healthcare and education sectors, and state government modular housing initiatives |
| Queensland |
17.3% |
Infrastructure growth, tourism-related hospitality construction, resource sector workforce accommodation demand, and urban densification |
| Western Australia |
13.4% |
Resource sector expansion, remote workforce accommodation demand, and growing regional infrastructure investment in Pilbara and Goldfields |
| Northern Territory & Southern Australia |
9.2% |
Remote community housing programs, government infrastructure projects, resource sector workforce housing, and defense facility development |
Australia Capital Territory & New South Wales at 36.0% in 2025 leads the regional landscape, anchored by concentrated commercial construction activity, government-backed affordable housing programs, and the national capital's sustained public infrastructure investment.
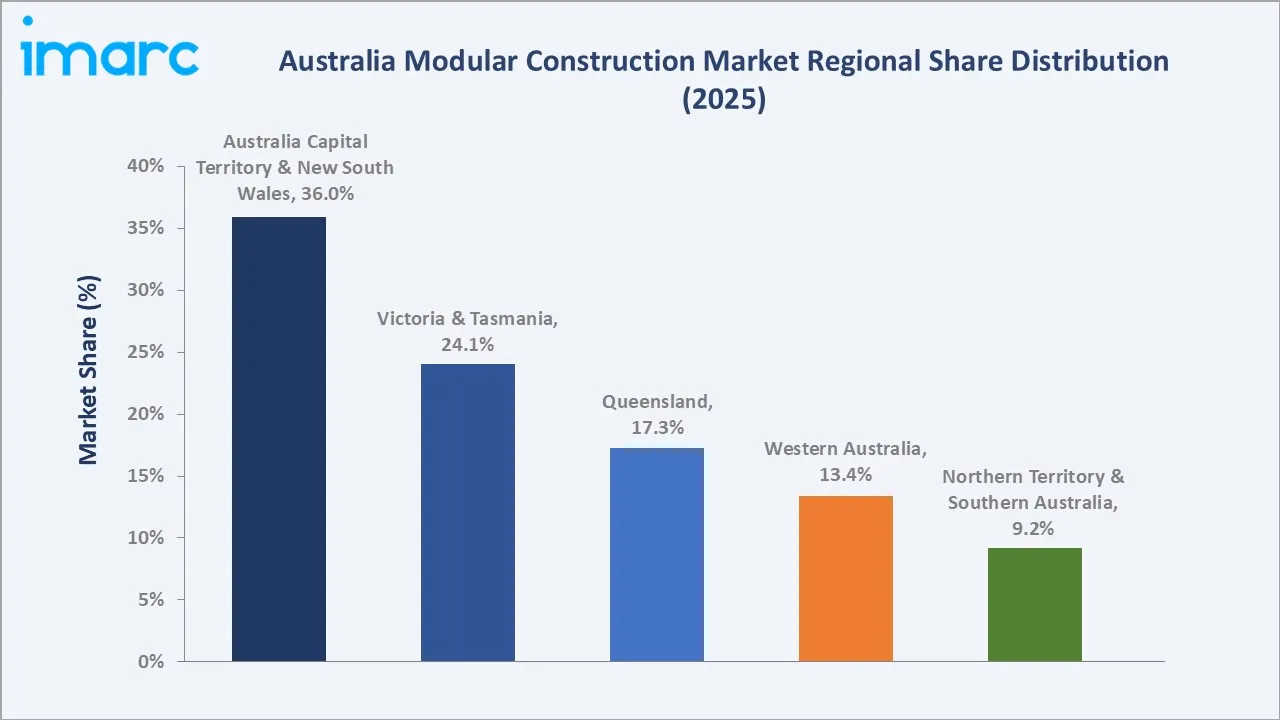
Northern Territory & Southern Australia, while currently the smallest regional contributor at 9.2%, represents the highest growth potential sub-segment, driven by expanding remote community housing programs, defense infrastructure development, and resource sector workforce accommodation demand across the region.
Competitive Landscape
The Australia modular construction market is moderately fragmented, with a mix of large integrated construction groups, specialist modular manufacturers, and international portable building companies competing on manufacturing capability, design quality, project delivery speed, and regulatory compliance credentials. Scale, certified manufacturing capacity, and proximity to major construction activity centers are the key competitive differentiators.
|
Company |
Key Brands |
Market Position |
Core Strength |
| Lendlease Group | Lendlease | Leader | Expanding prefabricated and modular construction capabilities across residential and mixed-use developments |
| Fleetwood Limited | Fleetwood Australia |
Leader |
Growing permanent and relocatable modular building solutions across education, healthcare, and resource clients |
| ATCO Ltd. | ATCO Structures |
Challenger |
Strengthening modular accommodation and industrial building solutions for resource and infrastructure clients |
Key players include Lendlease Group, Fleetwood Limited, and ATCO Ltd., among others.
Key Company Profiles
Lendlease Group
Lendlease Group is an Australian multinational construction, real estate, and infrastructure company headquartered in Sydney, New South Wales. The group operates integrated development, construction, and investment management divisions, with a growing focus on domestic Australian operations following a strategic simplification of its international business.
- Product Portfolio: Integrated property development and construction services spanning commercial, residential, and mixed-use projects; prefabricated and modular building delivery across residential apartment, social infrastructure, defense, transport, and data center segments.
- Recent Developments: The company continues to advance its Australian construction pipeline, having secured significant new project work across social infrastructure and commercial segments, while progressing its modular and prefabricated building delivery capabilities.
- Strategic Focus: Expanding prefabricated and modular construction capabilities across residential and mixed-use developments in Australia, targeting improved cost certainty, schedule reliability, and sustainability performance.
Fleetwood Limited
Fleetwood Limited is an Australian manufacturer of modular buildings and relocatable structures. The company operates manufacturing facilities across multiple states and delivers modular building solutions.
- Product Portfolio: Permanent and relocatable modular buildings for education, healthcare, housing, commercial, and resource sectors; customized modular structures and prefabricated building systems; modular accommodation and village solutions for workforce and community housing.
- Recent Developments: The company continues to expand its manufacturing capacity and strengthen modular building delivery capabilities, with a growing order book and tender pipeline supporting activity in housing, education, and resource sector segments.
- Strategic Focus: Growing permanent and relocatable modular building solutions across education, healthcare, and resource clients in Australia, with emphasis on scalable manufacturing capacity and certified delivery quality.
ATCO Ltd.
ATCO Ltd. is a Canadian diversified corporation with operations spanning modular structures, utilities, and energy infrastructure across multiple countries. In Australia, the company delivers modular and portable building solutions through its Structures division, operating manufacturing facilities and sales branches across the country.
- Product Portfolio: Modular workforce accommodations, portable and permanent structures, industrial facilities, construction site offices, emergency response buildings, and modular solutions for mining, resources, defense, healthcare, and community sectors.
- Recent Developments: The company continues to expand its Australian modular manufacturing footprint, with new facility openings strengthening production capacity and delivery capability for resource sector and government infrastructure clients.
- Strategic Focus: Strengthening modular accommodation and industrial building solutions for resource, infrastructure, and government clients across Australia, leveraging global manufacturing expertise and local operational presence.
Market Concentration Analysis
The Australia modular construction market is moderately fragmented, with the leading tier of operators, including large integrated construction groups and specialist modular manufacturers, accounting for a significant but not dominant share of total construction value.
Barriers to entry include capital requirements for factory-based manufacturing facilities, engineering expertise in modular structural systems, compliance with the National Construction Code, and the logistics capability required to transport and assemble large modules efficiently. These factors favor established operators and companies with existing manufacturing infrastructure over greenfield entrants in both permanent and relocatable segments.
Consolidation activity is at an early stage, with larger operators expanding manufacturing capacity and broadening sector coverage through organic growth. Strategic partnerships between construction groups and specialist modular manufacturers are emerging as a key growth mechanism, enabling established contractors to access modular capability without full vertical integration.
Investment & Growth Opportunities
Fastest-Growing Segments
Relocatable is expanding at above-average rates within the type segment, supported by resource sector project pipelines in Western Australia and Queensland. Among end use categories, healthcare represents the fastest-growing application, driven by hospital expansion programs.
Emerging Markets
Northern Territory & Southern Australia is the fastest-growing regional market, supported by remote community housing programs, defense infrastructure development, and resource sector workforce accommodation demand. The region represents significant untapped opportunity for operators able to establish reliable modular supply and logistics capabilities.
Investment Trends
Investment activity is concentrated in modular manufacturing facility expansion, digital design and BIM platform adoption, sustainable materials integration, and development of prefabricated systems for multi-story residential and commercial buildings. Capital is also flowing into public-private partnership structures for affordable housing delivery using modular construction.
Future Market Outlook (2026-2034)
The Australia modular construction market is projected to grow from USD 11.80 Billion in 2025 to USD 12.45 Billion in 2026, reaching USD 17.10 Billion by 2034, registering a CAGR of 4.05% during 2026-2034.
Four forces will shape the market through 2034 expanding government housing programs driving residential modular adoption; growing commercial developer acceptance of permanent modular construction for multi-story buildings; continued resource sector investment sustaining relocatable accommodation demand; and improving digital design and manufacturing technology reducing cost premiums associated with modular delivery.
By 2034, the Australia modular construction market is expected to be characterized by a mature permanent structures segment, a stable and technology-improved relocatable structures market, and significantly greater penetration of modular methods in healthcare, education, and high-density residential applications. Continued infrastructure investment will sustain strong market volume growth across the forecast period.
Research Methodology
Primary Research
Primary research included structured discussions with modular construction operators, commercial developers, healthcare and education facility managers, and regulatory officials, validating market sizing, segment mix, and regional demand patterns across the Australia modular construction ecosystem.
Secondary Research
Secondary sources included Department of Industry, Science and Resources publications, Australian Bureau of Statistics construction data, state government infrastructure program disclosures, and public reporting from listed construction and property companies operating in the Australian market.
Forecasting Models
Market forecasts used top-down and bottom-up models combining building activity projections, modular construction penetration rate assumptions, segment growth driver analysis, and scenario testing across regulatory, technology adoption, and infrastructure investment variables.
Australia Modular Construction Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report | Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Permanent, Relocatable |
| Module Types Covered | Four Sided, Open Sided, Partially Open Sided, Mixed Modules and Floor Cassettes, Modules Supported by a Primary Structure, Others |
| Materials Covered | Steel, Concrete, Wood, Plastic, Others |
| End Uses Covered | Residential, Commercial, Education, Retail, Hospitality, Healthcare, Others |
| Regions Covered | Australia Capital Territory & New South Wales, Victoria & Tasmania, Queensland, Northern Territory & Southern Australia, Western Australia |
| Companies Covered | Lendlease Group, Fleetwood Limited, ATCO Ltd., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Australia modular construction market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Australia modular construction market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Australia modular construction industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Australia Modular Construction Market Report
The Australia modular construction market size is estimated at USD 12.45 Billion in 2026, driven by sustained government infrastructure investment, growing commercial and residential sector adoption, and expanding off-site manufacturing capability.
The market is projected to grow at a CAGR of 4.05% from 2026-2034, reaching USD 17.10 Billion by 2034, supported by government housing programs and expanding sector applications.
Permanent dominates the market at 54.0% type share in 2025, driven by demand from commercial, healthcare, and education sectors requiring multi-decade operational buildings.
Commercial dominates the market at 32.0% share in 2025, driven by developer adoption of modular methods for cost-certain, schedule-reliable delivery of office, retail, and mixed-use projects.
Australia Capital Territory & New South Wales commands 36.0% share in 2025, led by concentrated commercial activity, government infrastructure investment, and strong residential demand.
Northern Territory & Southern Australia is the fastest-growing region, supported by remote community housing programs, defense infrastructure development, and resource sector workforce accommodation demand.
Key players include Lendlease Group, Fleetwood Limited, and ATCO Ltd., among others.
Key drivers include government housing targets, rising commercial developer adoption of off-site manufacturing, persistent housing supply pressure, and growing ESG and sustainability commitments.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade