
Blood Culture Test Market Size, Share, Trends and Forecast by Testing Method, Product, Technology, Application, End User, and Region, 2026-2034
Blood Culture Test Market Size, Share, Trends & Forecast (2026-2034)
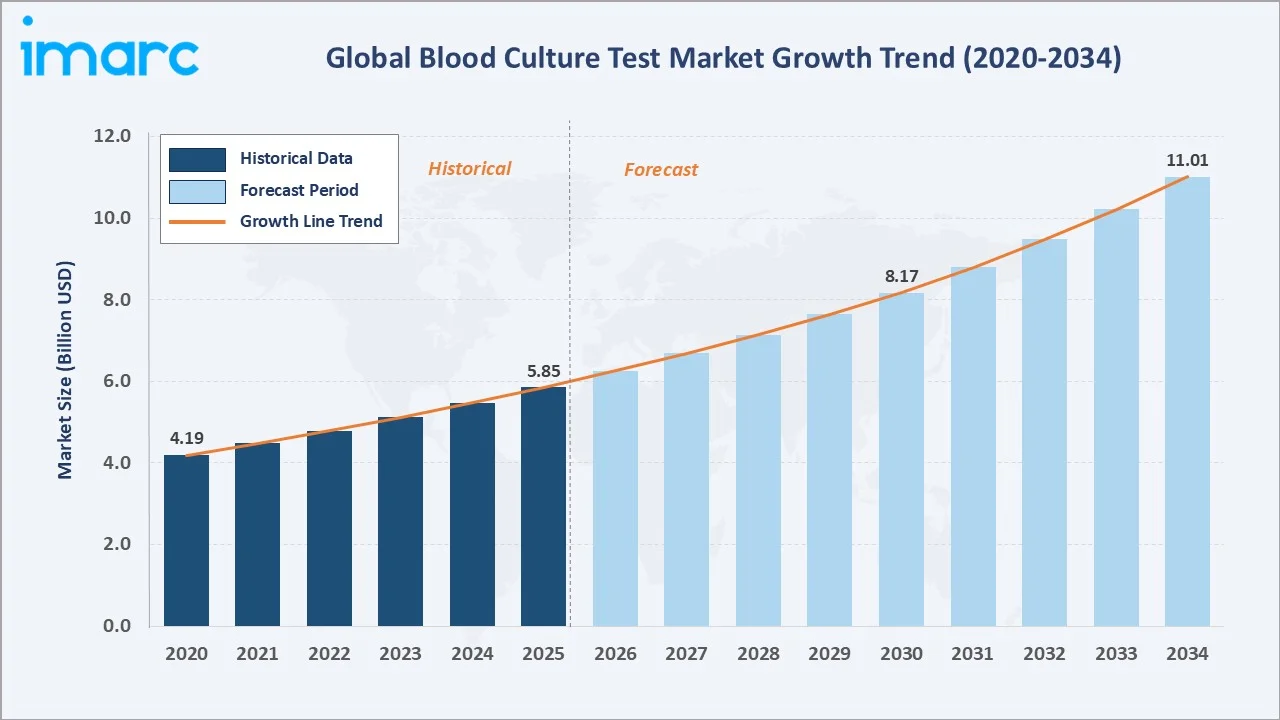
The global blood culture test market size reached USD 5.85 Billion in 2025 and is projected to reach USD 11.01 Billion by 2034, growing at a CAGR of 6.91% during 2026-2034. Growth is driven by the rising incidence of bloodstream infections and sepsis, expanding hospital-acquired infection burden, and continued advancements in automated and rapid diagnostic technologies. Consumables lead the product landscape at 60.4%, bacterial infections dominate application demand at 70.2%, and North America commands the largest regional share at 39.6%, supported by well-established healthcare infrastructure and diagnostic reimbursement systems.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 5.85 Billion |
|
Forecast Market Size (2034) |
USD 11.01 Billion |
|
CAGR (2026-2034) |
6.91% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Product |
Consumables (60.4%, 2025) |
|
Dominant Application |
Bacterial Infections (70.2%, 2025) |
|
Leading Region |
North America (39.6%, 2025) |
The market expanded steadily from USD 4.19 Billion in 2020 to USD 5.85 Billion in 2025, and is anchored at USD 8.17 Billion in 2030 en route to USD 11.01 Billion by 2034, reflecting consistent clinical demand for bloodstream infection diagnostics across hospital and reference laboratory networks worldwide.
To get more information on this market, Request Sample
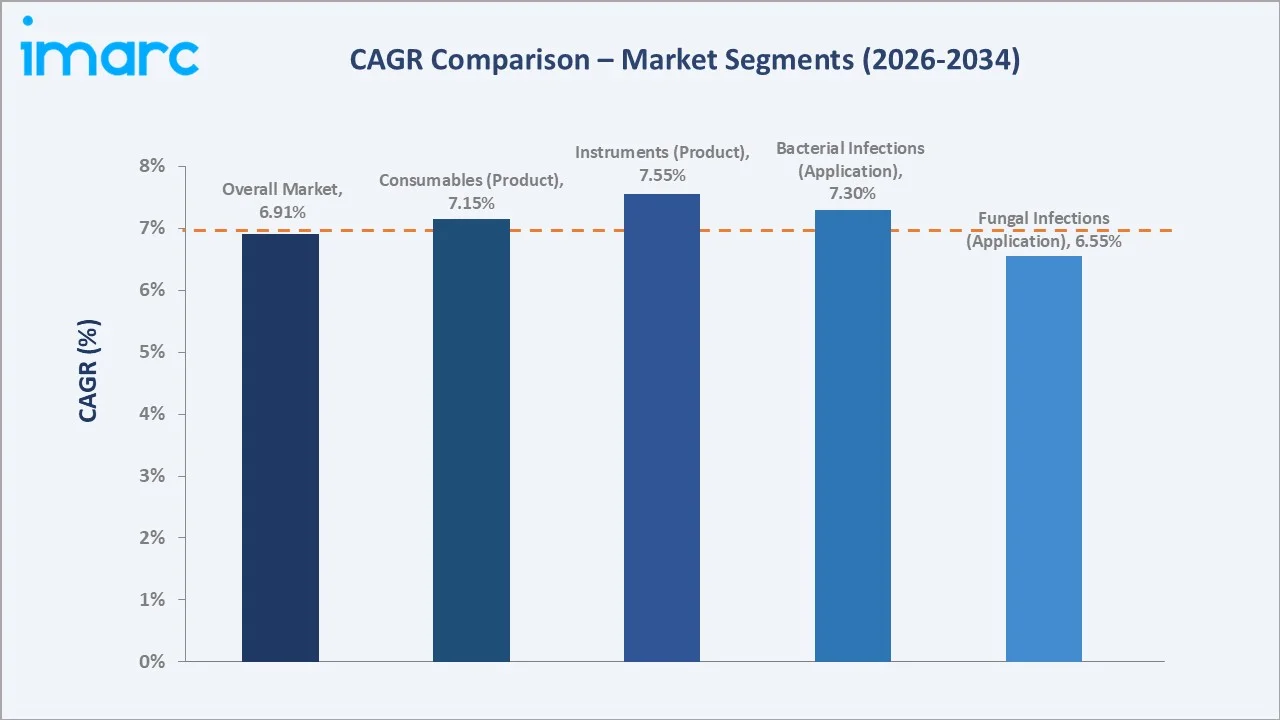
Consumables grow marginally above the overall market at approximately 7.15% CAGR, reflecting recurring, high-volume purchases of blood culture media and reagents, while bacterial infection applications grow at approximately 7.30% CAGR, sustained by rising sepsis caseloads and antimicrobial-resistance-driven testing volumes.
Executive Summary
The global blood culture test market reached USD 5.85 Billion in 2025, underscoring the diagnostic sector's growing focus on rapid, accurate identification of bloodstream pathogens. Blood culture testing remains the clinical benchmark for detecting bacteremia, fungaemia, and mycobacterial bloodstream infections, guiding targeted antimicrobial and antifungal therapy. The market is projected to reach USD 11.01 Billion by 2034.
Consumables at 60.4% dominate through repeated, high-frequency purchases of culture media, assay kits, and accessories across every testing cycle. Bacterial infections at 70.2% lead application demand due to the sheer clinical volume of suspected sepsis and bloodstream infection cases. North America accounts for the largest blood culture test market share at 39.6%, supported by its expansive hospital and laboratory network, strong insurance coverage, and rapid adoption of automated culture systems.
Key Market Insights
|
Insight |
Data |
|
Dominant Product |
Consumables - 60.4% share (2025) |
|
Dominant Application |
Bacterial Infections - 70.2% market share (2025) |
|
Leading Region |
North America - 39.6% market share (2025) |
|
Market Opportunity |
AI-enabled pathogen detection; point-of-care sepsis panels; molecular-culture integration; hospital lab automation upgrades |
Key Analytical Observations Supporting the Above Data:
- Consumables at 60.4%: Consumables dominate as blood culture media, assay kits, and reagents are consumed at every testing cycle, generating stable, repeat-purchase revenue that scales directly with rising test volumes across hospital and reference laboratories worldwide.
- Bacterial Infections at 70.2%: Bacterial infections lead application demand as sepsis and bacteremia remain the most common suspected bloodstream conditions, requiring prompt blood culture confirmation to guide antibiotic therapy and reduce mortality risk in critically ill patients.
- North America at 39.6%: North America leads through its extensive hospital and laboratory infrastructure, high insurance penetration, and early adoption of automated blood culture platforms, supported by stringent CLIA-regulated laboratory quality standards.
Blood Culture Test Market Overview
The global blood culture test market encompasses the consumables, instruments, and software/service solutions used to detect and identify bacterial, fungal, and mycobacterial pathogens in patient blood samples. The industry integrates culture media manufacturers, automated instrument developers, molecular diagnostics innovators, hospital and reference laboratories, and regulatory bodies overseeing clinical laboratory quality standards.
The ecosystem is shaped by rising bloodstream infection incidence, hospital-acquired infection surveillance mandates, and the expanding role of automation and AI in accelerating time-to-detection for critically ill patients. Continued consolidation between reagent suppliers and automated-instrument developers is streamlining procurement, while regulatory bodies increasingly emphasize standardized turnaround-time benchmarks across accredited laboratories. This blood culture test market analysis highlights the key blood culture test market trends shaping industry growth and competitive dynamics through 2034.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
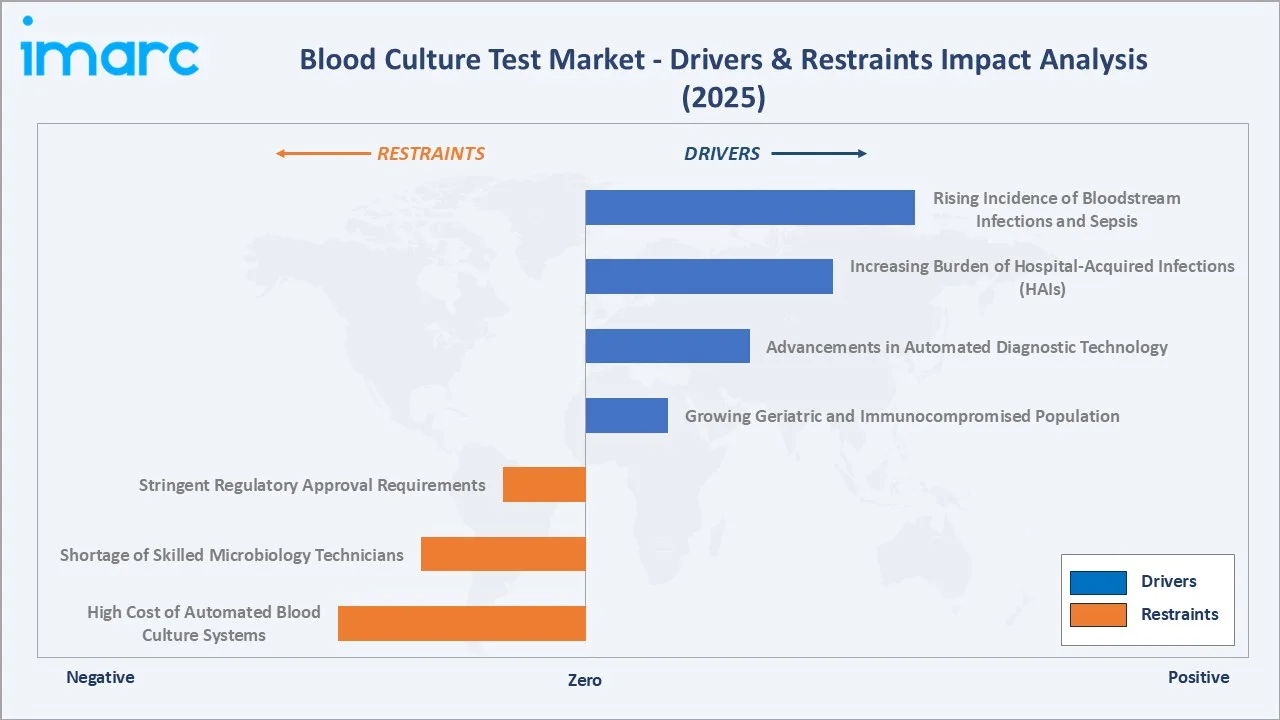
- Rising Incidence of Bloodstream Infections and Sepsis: Sepsis remains a leading cause of morbidity and mortality worldwide, and timely blood culture confirmation is essential to initiate targeted antimicrobial therapy, directly driving sustained clinical demand for blood culture testing across hospital settings. The World Health Organization estimates that sepsis affects tens of millions of patients annually, with a disproportionate share occurring in critical care and neonatal units where rapid pathogen identification directly influences survival outcomes. As antimicrobial resistance complicates empirical treatment choices, clinicians increasingly rely on culture-confirmed diagnosis to select effective, narrow-spectrum therapy rather than broad-spectrum antibiotics administered on suspicion alone.
- Increasing Burden of Hospital-Acquired Infections (HAIs): Growing hospitalization volumes and invasive procedures are increasing rates of hospital-acquired infections, prompting infection-control programs to mandate routine blood culture surveillance, thereby expanding testing volumes across surgical and intensive care units. Surgical site infections and catheter-associated bloodstream infections remain among the most common HAIs, requiring laboratories to process growing volumes of blood culture samples as part of standard post-operative monitoring protocols. National infection-surveillance agencies are tightening reporting requirements for HAI rates, indirectly reinforcing hospital investment in faster and more sensitive blood culture testing infrastructure.
- Advancements in Automated Diagnostic Technology: Automated blood culture systems using advanced sensors and software algorithms are reducing time-to-detection and improving diagnostic accuracy versus manual methods, encouraging hospital laboratories to upgrade legacy testing infrastructure. Continuous-monitoring instruments can flag positive cultures within hours rather than days, allowing clinicians to narrow antimicrobial therapy earlier and reduce average hospital length of stay for bloodstream infection patients. Vendors are increasingly bundling automated detection hardware with cloud-based data management software, creating recurring service revenue streams alongside traditional consumables sales.
- Growing Geriatric and Immunocompromised Population: An aging global population with rising rates of diabetes, cancer, and other chronic conditions faces elevated infection risk, increasing the pool of patients requiring bloodstream infection diagnostics as part of routine clinical care. Elderly and immunocompromised patients undergoing chemotherapy, dialysis, or transplant care require frequent bloodstream infection monitoring, generating recurring testing demand across oncology and nephrology departments. Demographic projections indicate a continued rise in the share of the population aged 65 and above through 2034, reinforcing structurally higher baseline demand for blood culture diagnostics.
Market Restraints
- High Cost of Automated Blood Culture Systems: Automated blood culture platforms and molecular diagnostic add-ons require significant upfront capital investment, limiting adoption among smaller hospitals and laboratories in cost-constrained healthcare systems. Instrument acquisition costs are often compounded by ongoing service contracts, proprietary consumables, and staff training requirements, further raising the total cost of ownership for smaller facilities. Public healthcare systems in price-sensitive markets frequently continue relying on manual culture methods, delaying the transition to automated platforms despite their diagnostic speed advantages.
- Shortage of Skilled Microbiology Technicians: A global shortage of trained clinical microbiologists and laboratory technicians constrains testing throughput and delays result turnaround, particularly in emerging markets with limited laboratory workforce development. Laboratory workforce attrition following recent healthcare staffing pressures has left many microbiology departments operating below optimal staffing levels, extending sample processing queues. Training pipelines for specialized clinical microbiology roles remain limited relative to overall healthcare workforce expansion, creating a persistent skills gap in several regional markets.
- Stringent Regulatory Approval Requirements: Blood culture instruments and molecular assays face rigorous regulatory review across major markets, extending product approval timelines and increasing compliance costs for manufacturers seeking global market access. Divergent regulatory frameworks between regions, such as the FDA's 510(k) pathway and the EU's In Vitro Diagnostic Regulation, require manufacturers to manage parallel submission processes for global launches. Post-market surveillance obligations add ongoing compliance costs, particularly for software-enabled diagnostic platforms that require periodic algorithm validation and documentation updates.
Market Opportunities
- AI-Enabled Pathogen Detection Platforms: Integration of artificial intelligence and machine learning into blood culture analysis enables faster interpretation of growth curves and predictive flagging of clinically significant pathogens, creating differentiation opportunities for technology-forward diagnostic vendors. Machine learning models trained on historical growth-curve data can help laboratories triage positive cultures by clinical urgency, prioritizing samples most likely to represent true bloodstream infections. Vendors that successfully embed AI-based decision support into existing instrument workflows can command premium software subscription pricing alongside core hardware and consumables sales.
- Molecular-Culture Workflow Integration: Combining rapid molecular identification with traditional culture-based confirmation shortens time-to-targeted-therapy, opening opportunities for vendors offering integrated culture-molecular diagnostic workflows in high-acuity hospital settings. Hybrid platforms that automatically trigger molecular identification upon detecting culture positivity can compress total diagnostic turnaround from days to hours, a compelling value proposition for emergency and intensive care settings. Reference laboratories are increasingly seeking single-vendor solutions that combine culture, molecular, and proteomic identification, creating cross-selling opportunities for diversified diagnostics companies.
Market Challenges
- Competitive Pressure from Regional Manufacturers: Growing competition from lower-cost regional manufacturers in Asia Pacific is pressuring pricing and margins for established global diagnostic companies, particularly in price-sensitive public healthcare procurement markets. Domestic Chinese and Indian manufacturers are scaling production of culture media and basic instrumentation at lower price points, gaining share in public tender-driven procurement processes. Global vendors are responding by localizing manufacturing and tailoring product tiers to different price segments, adding operational complexity to established commercial models.
- Sample Contamination Affecting Diagnostic Accuracy: Blood culture contamination from improper sample collection continues to generate false-positive results, requiring ongoing clinician training and advanced collection devices to preserve diagnostic accuracy and clinical trust. Contaminated cultures can trigger unnecessary antibiotic courses and extended hospital stays, creating both clinical and economic costs that undermine confidence in testing accuracy. Specialty blood-collection devices designed to divert and discard the initial sample volume are gaining adoption as a practical mitigation, though implementation requires additional staff training and workflow changes.
Emerging Market Trends
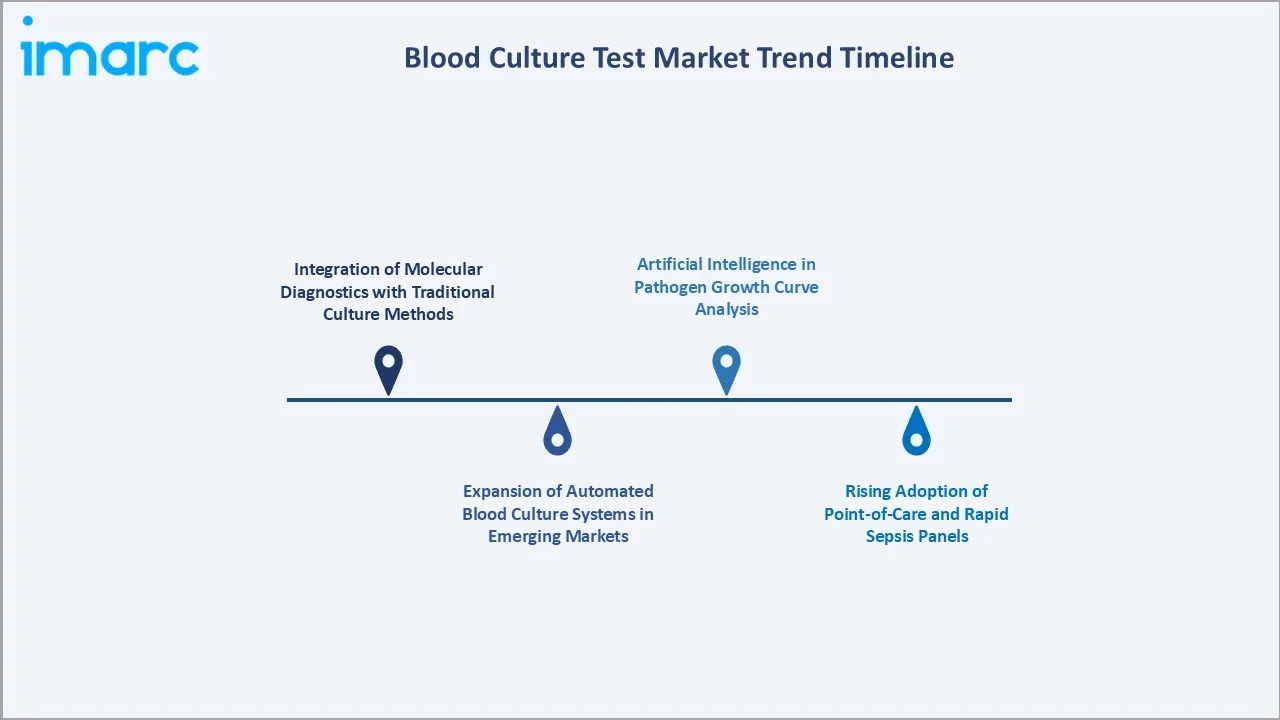
1. Integration of Molecular Diagnostics with Traditional Culture Methods
Laboratories are increasingly pairing molecular technologies such as PCR and PNA-FISH with conventional culture confirmation to shorten time-to-pathogen-identification while retaining the clinical reliability of culture-based susceptibility testing, improving early-stage antimicrobial decision-making.
2. Expansion of Automated Blood Culture Systems in Emerging Markets
Hospitals across Asia Pacific and Latin America are scaling automated blood culture systems to handle rising infection caseloads, supported by government healthcare infrastructure investment and growing awareness of early sepsis detection benefits.
3. Artificial Intelligence in Pathogen Growth Curve Analysis
AI-powered software is being deployed to interpret growth curve data in real time, flagging clinically significant positive cultures faster than manual review and helping laboratories prioritize critical results for immediate clinician action.
4. Rising Adoption of Point-of-Care and Rapid Sepsis Panels
Demand is growing for rapid, near-patient diagnostic panels that shorten the diagnostic window for suspected bloodstream infections, particularly in emergency departments and intensive care units managing time-critical sepsis cases.
Industry Value Chain Analysis
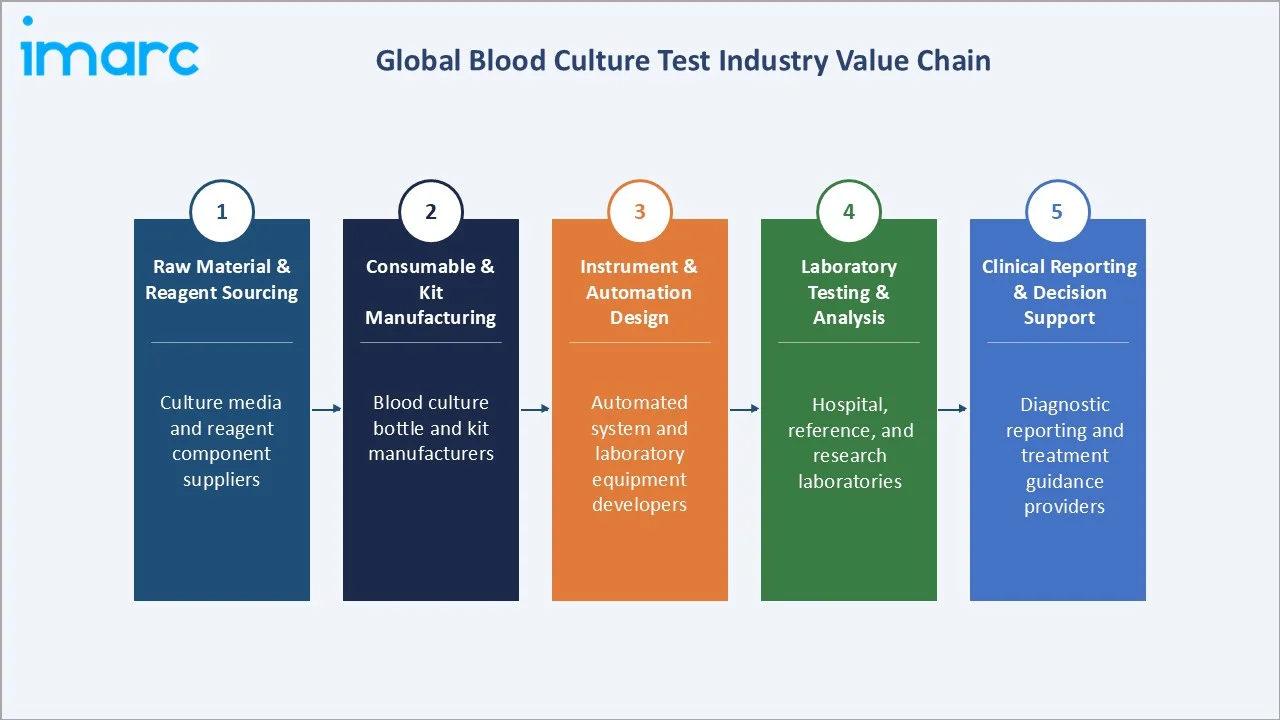
The blood culture test value chain spans raw material and reagent sourcing, culture media and diagnostic kit manufacturing, automated instrument design, laboratory testing and interpretation, and clinical reporting that informs treatment decisions.
|
Stage |
Key Participants |
|
Raw Material & Reagent Sourcing |
Culture media and reagent component suppliers |
|
Consumable & Kit Manufacturing |
Blood culture bottle and kit manufacturers |
|
Instrument & Automation Design |
Automated system and laboratory equipment developers |
|
Laboratory Testing & Analysis |
Hospital, reference, and research laboratories |
|
Clinical Reporting & Decision Support |
Diagnostic reporting and treatment guidance providers |
Technology Landscape in the Blood Culture Test Industry
Culture-Based Technology
Culture-based technology remains the clinical benchmark for detecting and identifying bacterial and fungal pathogens in blood samples, offering high sensitivity and the ability to generate viable isolates for downstream antimicrobial susceptibility testing.
Automated Blood Culture Systems
Automated systems employ continuous-monitoring sensors and software algorithms to detect microbial growth faster and more precisely than manual methods, significantly reducing time-to-detection for critically ill patients requiring urgent therapy decisions.
Molecular and Proteomic Technology
Molecular platforms, including PCR and PNA-FISH, alongside proteomic identification methods, are increasingly used alongside culture-based confirmation to accelerate pathogen identification and support faster, more targeted antimicrobial treatment decisions.
Market Segmentation Analysis
The blood culture test market share is segmented by product and application, with consumables and bacterial infections leading their respective categories in 2025.
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Testing Method |
Conventional |
65.4% |
2025 |
|
Product |
Consumables |
60.4% |
2025 |
|
Technology |
Culture-based Technology |
66.5% |
2025 |
|
Application |
Bacterial Infections |
70.2% |
2025 |
|
End-User |
Hospital Laboratories |
53.8% |
2025 |
|
Region |
North America |
39.6% |
2025 |

By Product
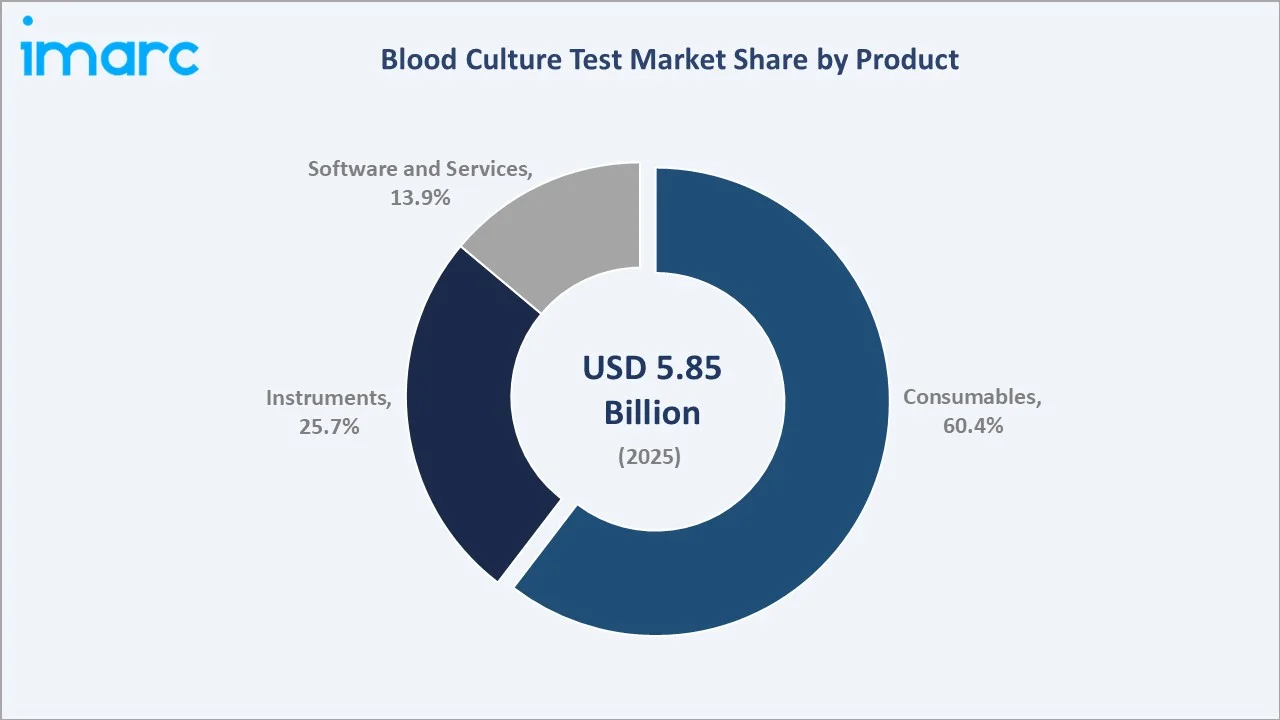
Consumables lead the market at 60.4% in 2025, encompassing blood culture media, assay kits and reagents, and accessories consumed at every testing cycle, making this the most commercially resilient and highest-revenue-generating product category.
To access detailed market analysis, Request Sample
Instruments at 25.7% capture automated blood culture systems and supporting laboratory equipment, while software and services at 13.9% represent the fastest-scaling category as laboratories adopt data-management and AI-enabled interpretation tools.
By Application
Bacterial infections lead application demand at 70.2% in 2025, reflecting the high clinical volume of suspected sepsis and bacteremia cases requiring prompt diagnostic confirmation to guide targeted antibiotic therapy across hospital and emergency care settings.
Fungal infections at 18.7% reflect rising fungaemia incidence among immunocompromised patients, while mycobacterial infections at 11.1% represent a smaller but clinically critical segment tied to tuberculosis and related bloodstream infection surveillance.
Regional Market Insights
|
Region |
Share (2025) |
Key Market Drivers & Characteristics |
|
North America |
39.6% |
Strong healthcare infrastructure and insurance coverage support broad diagnostic access |
|
Europe |
25.8% |
Antimicrobial resistance concerns and infection-control priorities drive testing demand |
|
Asia Pacific |
20.7% |
Rising infection incidence and expanding healthcare investment fuel market growth |
|
Latin America |
8.1% |
Improving healthcare infrastructure supports gradual diagnostics adoption |
|
Middle East and Africa |
5.8% |
Emerging healthcare infrastructure development drives early-stage market growth |
North America, at 39.6%, leads through its expansive network of hospitals, clinics, and diagnostic laboratories, complemented by a well-established insurance system and stringent CLIA-driven laboratory quality standards. Europe, at 25.8%, reflects rising antimicrobial resistance concerns and sustained investment in infection-control diagnostics.
Asia Pacific, at 20.7%, is expanding rapidly on rising sepsis caseloads in China and India alongside government healthcare investment. Latin America, at 8.1%, and the Middle East and Africa, at 5.8%, remain earlier-stage but steadily growing markets driven by improving diagnostic infrastructure and infectious disease surveillance programs.
Competitive Landscape
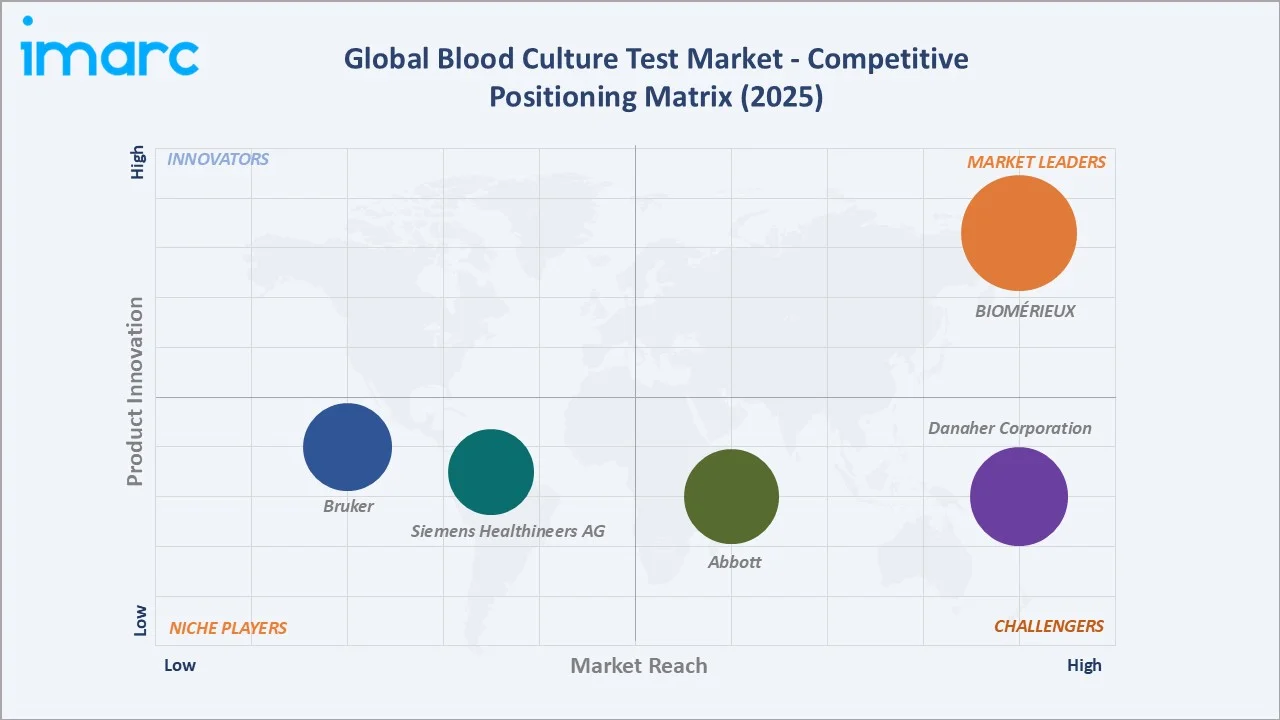
The global blood culture test market is moderately consolidated, led by diversified diagnostics majors alongside specialty microbiology and molecular technology companies competing on automation speed, assay breadth, and integrated laboratory workflow solutions.
|
Company Name |
Key Products |
Market Position |
Core Strength |
|
BIOMÉRIEUX |
BacT/ALERT Blood Culture Systems |
Market Leader |
Deep specialization in clinical microbiology and rapid pathogen identification |
|
Abbott |
Diagnostic Testing Platforms and Reagents |
Strong Challenger |
Extensive global diagnostics distribution and rapid-testing innovation pipeline |
|
Danaher Corporation |
Clinical Microbiology and Molecular Diagnostics Solutions |
Strong Challenger |
Diversified life sciences and diagnostics portfolio with strong R&D scale |
|
Bruker |
MALDI-TOF Mass Spectrometry Identification Systems |
Niche Specialist |
Advanced proteomic pathogen identification technology leadership |
|
Siemens Healthineers AG |
Laboratory Diagnostics and Automation Systems |
Niche Specialist |
Strong laboratory automation and diagnostics integration expertise |
Key players include BIOMÉRIEUX, Abbott, Danaher Corporation, Bruker, Siemens Healthineers AG, and others.
Key Company Profiles
BIOMÉRIEUX
BIOMÉRIEUX is a France-based in-vitro diagnostics specialist with a strong global presence in the blood culture test market through its BacT/ALERT automated blood culture systems and clinical microbiology identification platforms.
- Key Products: BacT/ALERT Blood Culture Systems, VITEK Microbial Identification Platforms.
- Strategic Focus: Expanding integrated culture-to-identification workflow solutions that combine automated detection with rapid molecular and proteomic pathogen confirmation. The company is prioritizing research and development investment toward shortening total time-to-result across the culture-to-identification workflow, aiming to compress diagnostic turnaround for sepsis patients. bioMerieux is also expanding regional manufacturing and distribution capacity across Asia Pacific to meet rising demand for automated microbiology platforms in fast-growing hospital markets.
Abbott
Abbott is a US-based global healthcare company with a significant presence in the blood culture test market through its diagnostic testing platforms and rapid-result reagent solutions used across hospital laboratories and emergency care settings.
- Key Products: Diagnostic Testing Platforms and Rapid Assay Reagents.
- Strategic Focus: Expanding rapid diagnostic testing capabilities and broadening laboratory automation compatibility to support faster clinical decision-making in infectious disease management. Abbott continues to broaden its point-of-care and central-laboratory diagnostic portfolio, aiming to offer a connected testing ecosystem that spans emergency, inpatient, and outpatient care settings. The company is also pursuing strategic collaborations with hospital networks to pilot next-generation rapid diagnostic technologies ahead of broader commercial rollout.
Market Concentration Analysis
The blood culture test market is moderately concentrated at the automated-systems level, with the key players collectively commanding a leading share of global automated blood culture platform installations, given their long-standing clinical microbiology relationships with hospital laboratories. The key players hold strong challenger positions through diversified diagnostics and consumables portfolios, while various other players in the market compete as specialists in proteomic identification and laboratory automation. Market concentration is expected to moderate gradually as regional manufacturers expand cost-competitive consumables offerings across emerging markets.
Investment & Growth Opportunities
Highest Growth Segments
Instruments (~7.55% CAGR), bacterial infection applications (~7.30% CAGR), and software and services (fastest-scaling category from a smaller base) represent the highest-growth investment vectors within the blood culture test market through 2034.
Emerging Investment Opportunities
AI-enabled data interpretation software represents the market's highest-value emerging opportunity, as laboratories increasingly seek to combine automated detection hardware with predictive analytics that shorten time-to-actionable-result for critically ill patients.
Investment Themes
- AI-Enabled Diagnostic Software Investment: Deploying AI-driven growth-curve interpretation software as a differentiator for automated blood culture platforms represents a scalable, high-margin investment opportunity as hospitals prioritize faster sepsis diagnosis and treatment initiation. Software-as-a-service pricing models for diagnostic interpretation tools offer recurring revenue potential that complements traditional hardware and consumables sales cycles. Early movers integrating validated AI algorithms into regulatory-cleared instruments are positioned to capture premium pricing as hospitals standardize on connected diagnostic ecosystems.
- Regional Consumables Manufacturing Expansion: Building consumables manufacturing scale in Asia Pacific and Latin America captures rising testing volumes in fast-growing healthcare systems while offering a structural cost advantage over globally centralized production models. Localized production reduces logistics costs and supply-chain lead times, an increasingly important consideration following recent global supply-chain disruptions affecting laboratory consumables. Regional manufacturing partnerships also help global vendors meet local-content requirements tied to public healthcare procurement programs in several emerging markets.
Future Market Outlook (2026-2034)
The global blood culture test market is projected to grow from USD 5.85 Billion in 2025 to USD 11.01 Billion by 2034, delivering a 6.91% CAGR over the forecast period. The market's anchor value of USD 8.17 Billion in 2030 reflects an industry at a pivotal automation and molecular-integration inflection point, with AI-enabled interpretation tools expected to become a standard feature of automated blood culture platforms.
Three structural forces define market growth through 2034: sustained global sepsis and bloodstream infection incidence, deepening hospital automation investment, and the progressive convergence of culture-based and molecular diagnostic workflows into unified, faster clinical decision-support systems.
Research Methodology
This blood culture test market analysis is based on a combination of primary and secondary research methodologies to ensure accuracy and reliability of the data presented.
Primary Research
Primary research comprised structured interviews with clinical microbiologists, hospital laboratory directors, infection-control specialists, and diagnostic instrument product managers across major regional markets.
Secondary Research
Secondary research encompassed company annual reports, WHO and CDC infection surveillance data, clinical microbiology journal publications, and regional healthcare infrastructure and regulatory databases.
Forecasting Models
Market revenue forecasts were developed using a bottom-up model incorporating hospital and laboratory testing volume by region, average revenue per test by product category, and technology-adoption-adjusted pricing for automated and molecular platforms.
Blood Culture Test Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Testing Methods Covered | Conventional, Automated |
| Products Covered |
|
| Technologies Covered |
|
| Applications Covered | Bacterial Infections, Fungal Infections, Mycobacterial Infections |
| End Users Covered | Hospital Laboratories, Reference Laboratories, Research Laboratories, Others |
| Regions Covered | Asia Pacific, Europe, North America, Latin America, Middle East and Africa |
| Countries Covered | United States, Canada, Germany, France, United Kingdom, Italy, Spain, Russia, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Mexico |
| Companies Covered | BIOMÉRIEUX, Abbott, Danaher Corporation, Bruker, Siemens Healthineers AG, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the blood culture test market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the global blood culture test market.
- The study maps the leading, as well as the fastest-growing, regional markets. It further enables stakeholders to identify the key country-level markets within each region.
- Porter's Five Forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the blood culture test industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Blood Culture Test Market Report
The global blood culture test market reached USD 5.85 Billion in 2025, driven by consumables dominant at 60.4%, bacterial infection applications leading at 70.2%, and North America commanding 39.6% of the global market share.
The blood culture test market grows at 6.91% CAGR during 2026-2034, reaching USD 11.01 Billion by 2034, reflecting sustained sepsis incidence and expanding hospital automation investment.
Consumables lead at 60.4%, capturing recurring purchases of blood culture media, assay kits, and reagents consumed at every testing cycle across hospital and reference laboratories.
Bacterial infections lead at 70.2%, reflecting the high clinical volume of suspected sepsis and bacteremia cases requiring prompt diagnostic confirmation.
North America leads at 39.6%, supported by extensive hospital and laboratory infrastructure, strong insurance coverage, and early adoption of automated blood culture systems.
Leading companies include BIOMÉRIEUX, Abbott, Danaher Corporation, Bruker, Siemens Healthineers AG, and others.
The blood culture test market is projected to reach USD 8.17 Billion by 2030, with AI-enabled interpretation tools gaining broader adoption across automated platforms.
Priority opportunities include AI-enabled diagnostic software, regional consumables manufacturing expansion, and integrated molecular-culture diagnostic workflow solutions.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade