
Brazil Cashew Market Size, Share, Trends and Forecast by Form, Distribution Channel, Application and Region, 2026-2034
Brazil Cashew Market Size, Share, Trends & Forecast (2026-2034)
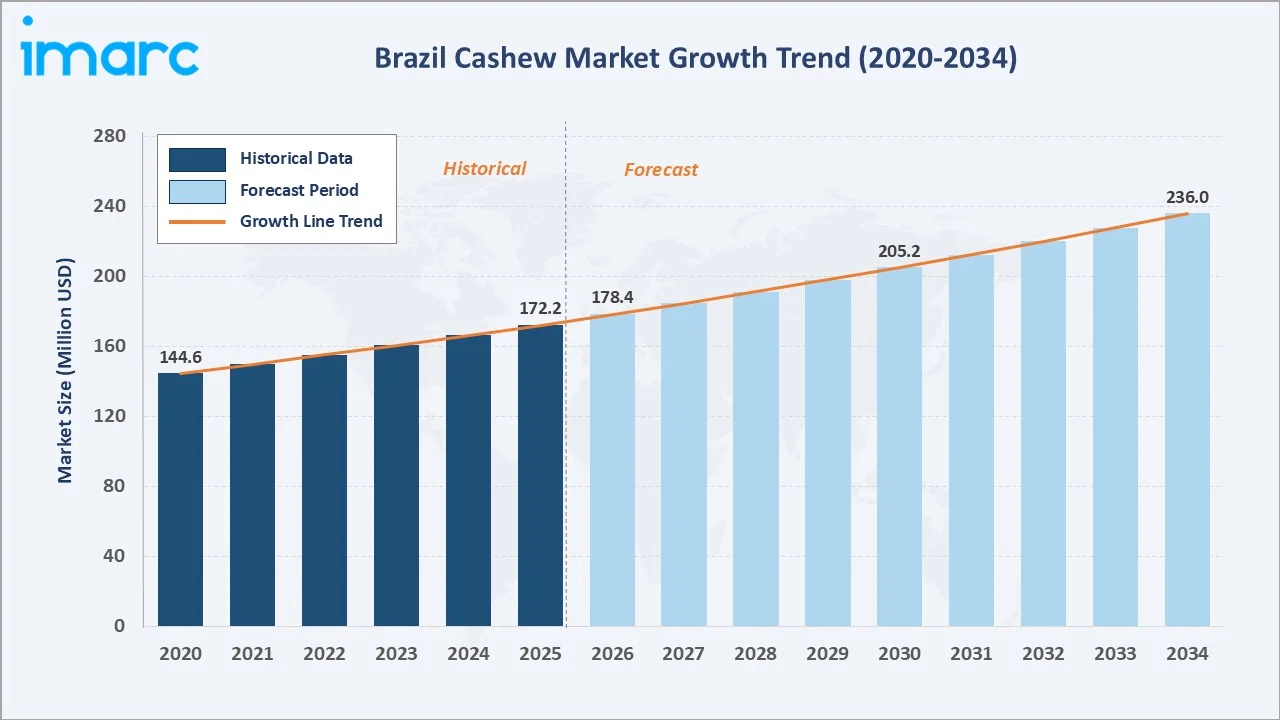
The Brazil cashew market size was valued at USD 172.2 Million in 2025 and is estimated to reach USD 178.4 Million in 2026. It is further projected to reach USD 236.0 Million by 2034, growing at a CAGR of 3.56% during 2026-2034. The market is driven by rising consumer demand for healthy snack options, expanding export opportunities, government agricultural support, and growing adoption of value-added cashew products across food and cosmetics sectors.
Whole cashews lead the form segment at 39.4%. Supermarkets command 41.8% of distribution channels. Southeast Brazil holds 42.6% of the regional market share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 172.2 Million |
|
Market Size (2026) |
USD 178.4 Million |
|
Forecast Market Size (2034) |
USD 236.0 Million |
|
CAGR (2026-2034) |
3.56% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Form |
Whole (39.4%, 2025) |
|
Leading Distribution Channel |
Supermarkets (41.8%, 2025) |
|
Leading Region |
Southeast (42.6%, 2025) |
The Brazil cashew market size increased from USD 144.6 Million in 2020 to USD 172.2 Million in 2025 and is estimated to reach USD 178.4 Million in 2026. The market is further expected to grow to USD 205.2 Million by 2030 and USD 236.0 Million by 2034. Brazil, as one of the world original cashew-producing nations, continues to leverage its agricultural legacy, favourable climatic conditions in the Northeast, and growing domestic health-food consumption trends to sustain market expansion.
To get more information on this market, Request Sample
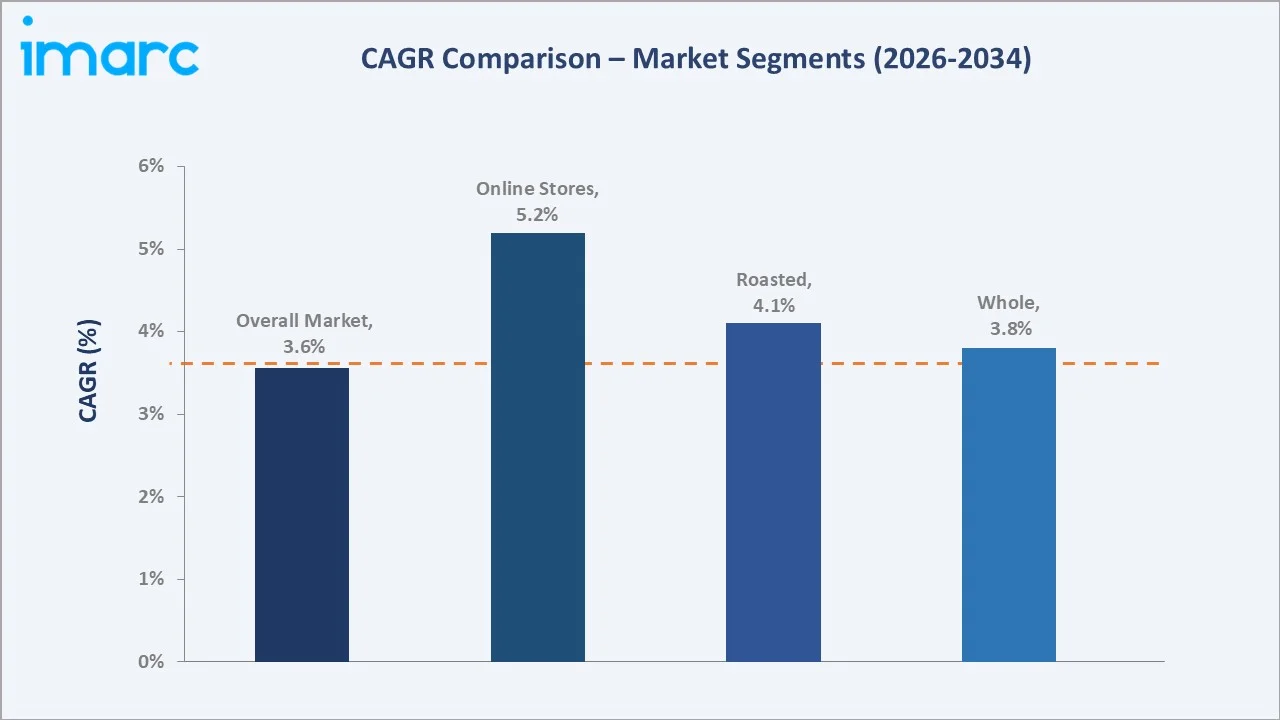
Online stores segment is the fastest-growing distribution channel, expanding at approximately 5.2% CAGR, driven by increasing e-commerce penetration in Brazilian urban centres. Whole cashews sustain dominance through broad consumer acceptance and versatile application across snacking, cooking, and food manufacturing segments.
Executive Summary
The Brazil cashew market expanded from USD 172.2 Million in 2025 to an estimated USD 178.4 Million in 2026, underpinned by rising health consciousness, growing export volumes, and expanding supermarket distribution reach. The market is projected to reach USD 236.0 Million by 2034. Whole cashews lead form at 39.4%. Supermarkets dominate distribution at 41.8%. Southeast leads regionally at 42.6%.
Key Market Insights
|
Insight |
Data |
|
Dominant Form |
Whole - 39.4% share (2025) |
|
Leading Distribution Channel |
Supermarkets - 41.8% market share (2025) |
|
Leading Region |
Southeast - 42.6% share (2025) |
|
Market Opportunity |
Rising health-conscious consumption; growing export demand; increasing value-added cashew product adoption across food and cosmetics sectors |
Key Analytical Observations Supporting the Above Data:
- Whole at 39.4%: Whole cashews dominate due to their versatility across snacking, cooking, and food ingredient applications. Consumer preference for minimally processed, natural nuts sustains strong retail demand through supermarkets and specialist retailers. Their wide application in confectionery, dairy products, and culinary uses further reinforces market leadership across all Brazilian regions.
- Supermarkets at 41.8%: Supermarkets lead distribution through broad geographic reach, competitive pricing, and consumer trust in established retail chains. Major Brazilian supermarket groups including GPA, Carrefour, and Assai have expanded their nut and dried fruit categories, providing significant shelf space and promotional support for cashew products across premium and economy segments.
- Southeast at 42.6%: Southeast Brazil leads consumption through its concentrated urban population, higher per-capita income, and dense modern retail infrastructure in Sao Paulo, Rio de Janeiro, and Minas Gerais. The region strong foodservice sector and growing health-food retail presence further support premium cashew product consumption above other Brazilian regions.
Brazil Cashew Market Overview
The Brazil cashew market represents a unique convergence of production heritage and growing domestic consumption, with Brazil serving simultaneously as one of the world major cashew producers and an increasingly significant domestic consumer. The market structure integrates smallholder farming cooperatives with large industrial processors and commercial exporters.
The market ecosystem spans cashew cultivation in the Northeast, industrial processing across multiple states, and retail distribution concentrated in the Southeast. Rising urbanisation, growing middle-class health consciousness, and expanding e-commerce are reshaping consumer access and product diversity across the cashew value chain.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
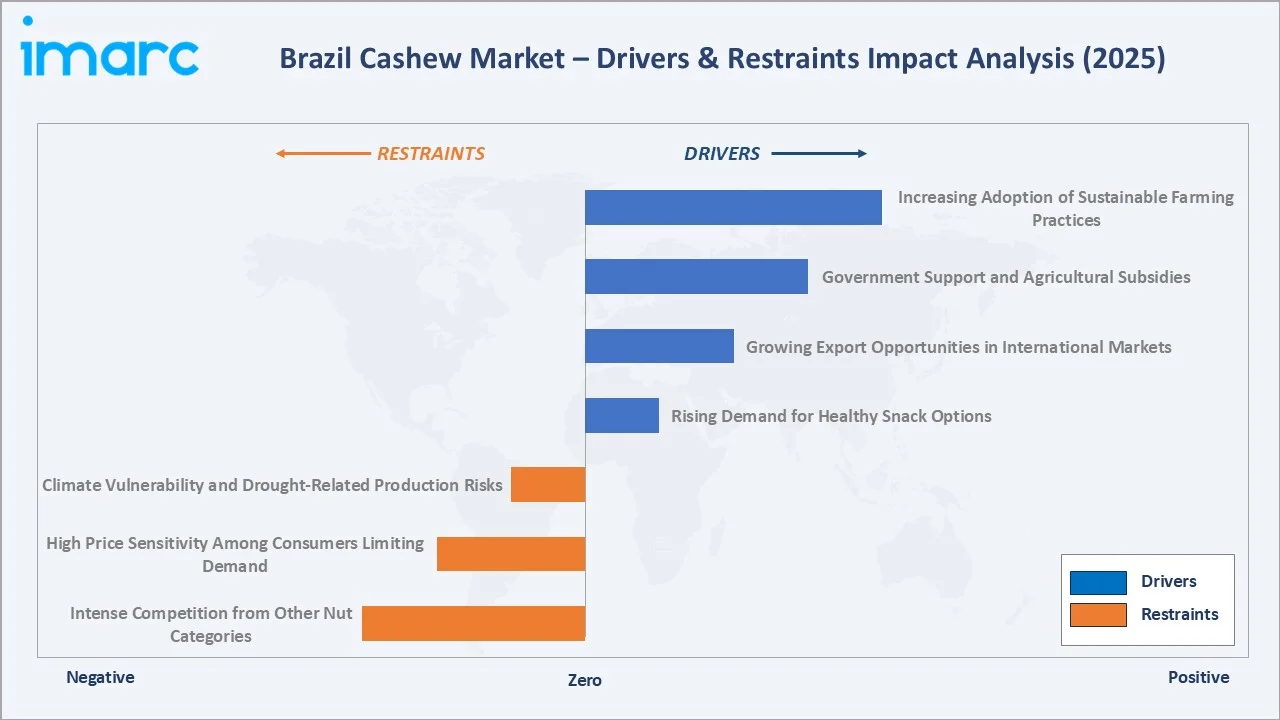
- Rising Demand for Healthy Snack Options: Growing health and wellness awareness among Brazilian consumers is driving sustained demand for cashews as a nutrient-rich, plant-based protein snack. The increasing adoption of vegetarian and vegan diets, combined with rising awareness of cashews cardiovascular benefits, antioxidant content, and essential mineral composition, is expanding the consumer base. Health-focused millennials and urban professionals are driving premium cashew product adoption across supermarkets and online retail channels nationally.
- Growing Export Opportunities in International Markets: Brazil established position as a globally recognised cashew origin is generating significant export demand from North America, Europe, and emerging markets. The United States remains Brazil largest cashew export destination, with growing demand from the Netherlands, Canada, Argentina, and Germany providing additional revenue streams. International buyers increasing preference for traceable, certified, and sustainably produced cashews is creating premium pricing opportunities for Brazilian processors.
- Government Support and Agricultural Subsidies: The Brazilian government active support for cashew farming through BNDES financing programmes, MAPA agricultural development initiatives, and APEX-Brasil export promotion has materially strengthened production capacity and market competitiveness. The Normative Instruction No. 37/2023, mandating environmentally responsible agricultural methods, has encouraged investment in modern farming practices that improve both productivity and market positioning in premium export segments globally.
- Increasing Adoption of Sustainable Farming Practices: Growing consumer and buyer demand for sustainably produced cashews is incentivising Brazilian farmers and processors to adopt precision farming, reduced pesticide programmes, and traceability systems. Sustainability certification is becoming a key market access requirement for export channels, particularly to European markets, creating structural demand for certified Brazilian cashews that command premium prices above conventional market grades.
Market Restraints
- Climate Vulnerability and Drought-Related Production Risks: Brazil cashew production is heavily concentrated in the semi-arid Northeast, making it acutely vulnerable to drought conditions, irregular rainfall patterns, and climate variability. Drought events can sharply reduce yields, creating supply disruptions that drive price volatility and dampen market growth. The structural dependence on a single climate-sensitive production zone creates recurring market risk affecting both domestic supply availability and export volume consistency.
- High Price Sensitivity Among Consumers Limiting Demand: Cashew nuts command premium pricing relative to other snack foods in the Brazilian market, making demand highly elastic and sensitive to price movements. During periods of supply-driven price increases or macroeconomic pressure on household incomes, consumers readily substitute cashews with more affordable nut alternatives or snack products. This price sensitivity constrains market penetration in lower-income segments and limits overall volume growth.
- Intense Competition from Other Nut Categories: The Brazilian snack nut market features strong competition from peanuts, Brazil nuts, almonds, and macadamia nuts, each commanding established consumer loyalty and distribution presence. Peanuts in particular benefit from significantly lower price points and widespread domestic production, providing a readily accessible substitute. Imported almonds and macadamia nuts are growing their premium market share, creating competitive pressure on cashew positioning in the health-food and premium snacking segments.
Market Opportunities
- Value-Added Cashew Product Development: The growing food industry demand for cashew butter, cashew milk, cashew flour, and cashew-based dairy alternatives presents significant value-creation opportunities beyond raw kernel sales. Food manufacturers are increasingly formulating cashew-based plant-protein products targeting the growing vegan and flexitarian consumer base, providing higher-margin revenue streams for Brazilian cashew processors investing in downstream product development.
- Digital Retail and Direct-to-Consumer Channel Expansion: The rapid expansion of Brazilian e-commerce platforms including Mercado Livre, Amazon Brazil, and specialised health-food online retailers is creating new direct consumer access pathways. Online cashew sales allow producers to capture higher margins while reaching health-conscious urban consumers in secondary cities underserved by specialist retail infrastructure.
Market Challenges
- Post-Harvest Losses and Processing Infrastructure Gaps: Inadequate post-harvest storage, processing facility limitations, and supply chain inefficiencies in the Northeast production zone result in significant quality deterioration and volume losses between farm and market. Improving cold-chain infrastructure and expanding certified processing capacity remains a priority investment challenge constraining the market ability to fully capture the value of Brazil underlying cashew production potential.
- Regulatory Compliance and Certification Costs: Meeting increasingly stringent domestic (MAPA) and international food safety, sustainability, and traceability certification requirements imposes material compliance costs on producers and processors. Smallholder farmers and smaller cooperatives face disproportionate burdens in meeting these requirements, limiting their ability to access premium-priced market segments and creating consolidation pressure within the industry.
Emerging Market Trends
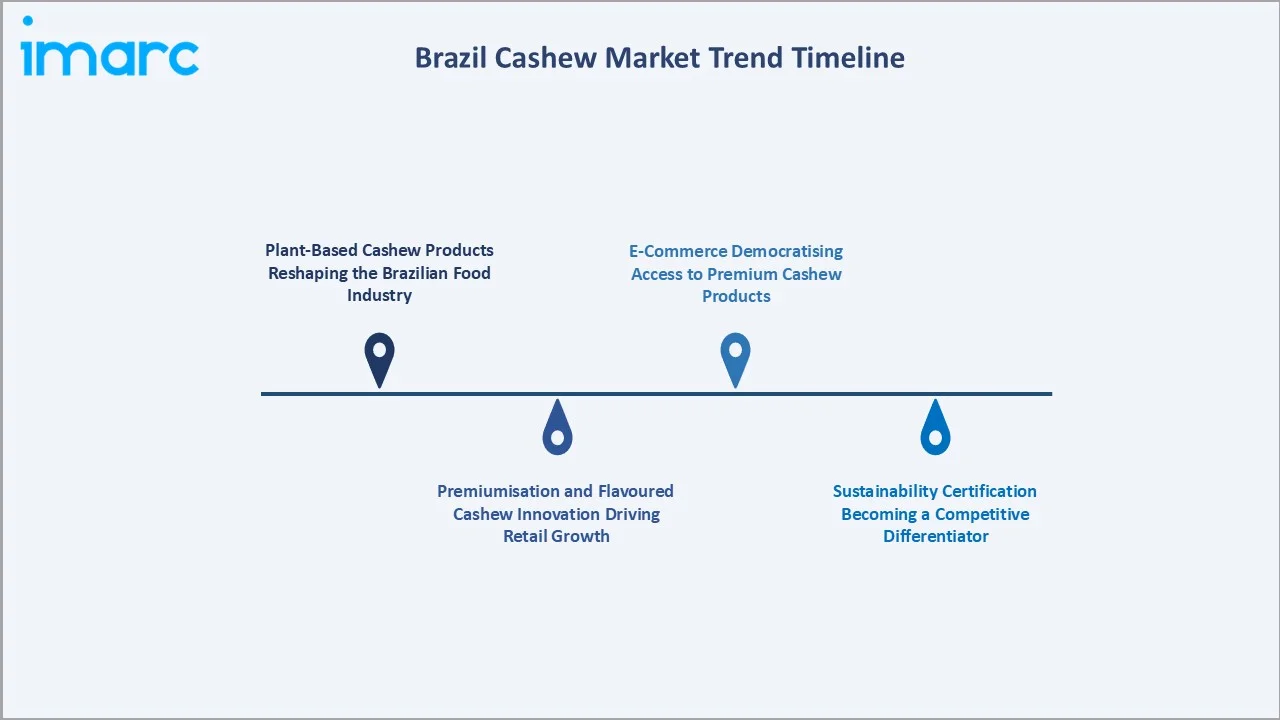
1. Plant-Based Cashew Products Reshaping the Brazilian Food Industry
Cashew-based milk, butter, cream, and cheese alternatives are gaining significant traction in Brazil rapidly growing plant-based food sector. Food manufacturers are leveraging cashews naturally creamy texture and nutritional profile to create premium vegan dairy alternatives targeting the expanding flexitarian consumer base.
2. Premiumisation and Flavoured Cashew Innovation Driving Retail Growth
Brazilian retailers are increasingly stocking premium flavoured cashew variants including chilli-lime, honey-roasted, spiced, and infused options that command higher margins. This premiumisation trend is expanding the cashew snack category beyond traditional plain roasted and salted offerings into a diversified premium snack segment.
3. E-Commerce Democratising Access to Premium Cashew Products
Online grocery and health-food platforms are enabling premium cashew brands to reach health-conscious consumers in Brazilian cities beyond the Southeast major metropolitan centres. This digital distribution expansion is driving volume growth in previously underserved secondary markets while improving producer margin capture.
4. Sustainability Certification Becoming a Competitive Differentiator
Brazilian cashew producers investing in organic certification, fair-trade accreditation, and environmental sustainability documentation are achieving premium pricing in export markets. This sustainability premium is increasingly influencing domestic retail buyers seeking certified products for premium store brands and health-food sections.
Industry Value Chain Analysis
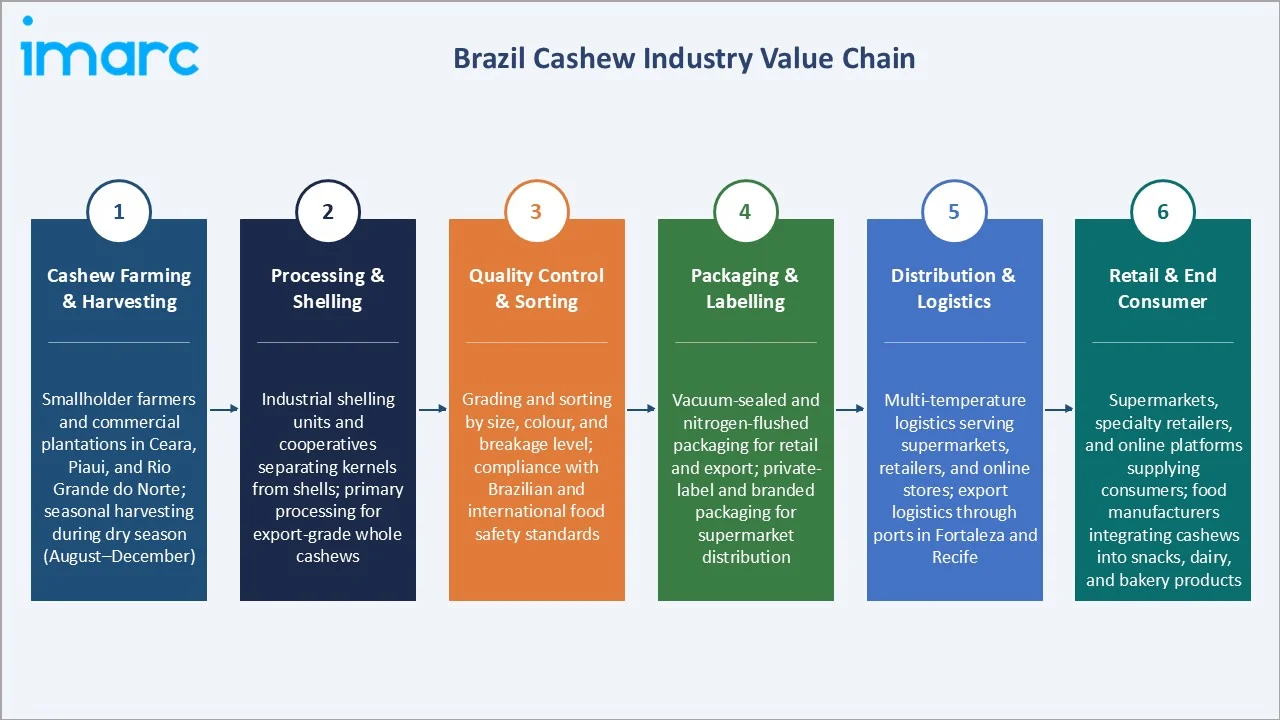
The Brazil cashew industry value chain spans from farm-level cultivation in the Northeast through industrial processing, quality grading, packaging, and multi-channel distribution to end consumers across Brazil and international markets. Each stage contributes distinct value addition and presents specific investment and improvement opportunities.
|
Stage |
Key Activities & Participants |
|
Cashew Farming & Harvesting |
Smallholder farmers and commercial plantations in Ceara, Piaui, and Rio Grande do Norte; seasonal harvesting during dry season. |
|
Processing & Shelling |
Industrial shelling units and cooperatives separating kernels from shells; primary processing for export-grade whole cashews. |
|
Quality Control & Sorting |
Grading and sorting by size, colour, and breakage level; compliance with Brazilian and international food safety standards. |
|
Packaging & Labelling |
Vacuum-sealed and nitrogen-flushed packaging for retail and export; private-label and branded packaging for supermarket distribution. |
|
Distribution & Logistics |
Multi-temperature logistics serving supermarkets, retailers, and online stores; export logistics through ports in Fortaleza and Recife. |
|
Retail & End Consumer |
Supermarkets, specialty retailers, and online platforms supplying consumers; food manufacturers integrating cashews into snacks, dairy, and bakery products. |
The processing and shelling stage is the industry most commercially significant value-creation point, where raw cashews are transformed into marketable kernels with distinct grade classifications that determine pricing tiers. The distribution stage has emerged as a rapidly evolving competitive battleground as online channels challenge the traditional supermarket dominance in cashew retail.
Technology Landscape in the Brazil Cashew Industry
Precision Agriculture and Yield Optimisation Technology
Brazilian cashew farms in Ceara and Piaui are increasingly adopting precision agriculture tools including drone-based monitoring, soil moisture sensors, and GPS-guided irrigation systems. These technologies are improving yield per hectare and reducing water consumption, critical improvements in the drought-prone Northeast production zone.
Industrial Processing and Automation
Modern cashew processing facilities in Brazil are investing in automated shelling, electronic sorting, and infrared quality inspection systems that improve throughput, reduce breakage, and ensure consistent grade quality. Automated processing lines are reducing labour costs while improving food safety compliance and export certification outcomes.
E-Commerce and Digital Marketing Technology
Cashew brands are leveraging social media marketing, influencer-driven health content, and performance digital advertising to reach Brazil growing online food consumer base. Direct-to-consumer e-commerce platforms supported by digital fulfilment capabilities are enabling premium cashew brands to build margin-accretive direct relationships with health-conscious urban consumers.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Form |
Whole |
39.4% |
2025 |
|
Distribution Channel |
Supermarkets |
41.8% |
2025 |
|
Application |
🔒 |
🔒 |
2025 |
|
Region |
Southeast |
42.6% |
2025 |

By Form
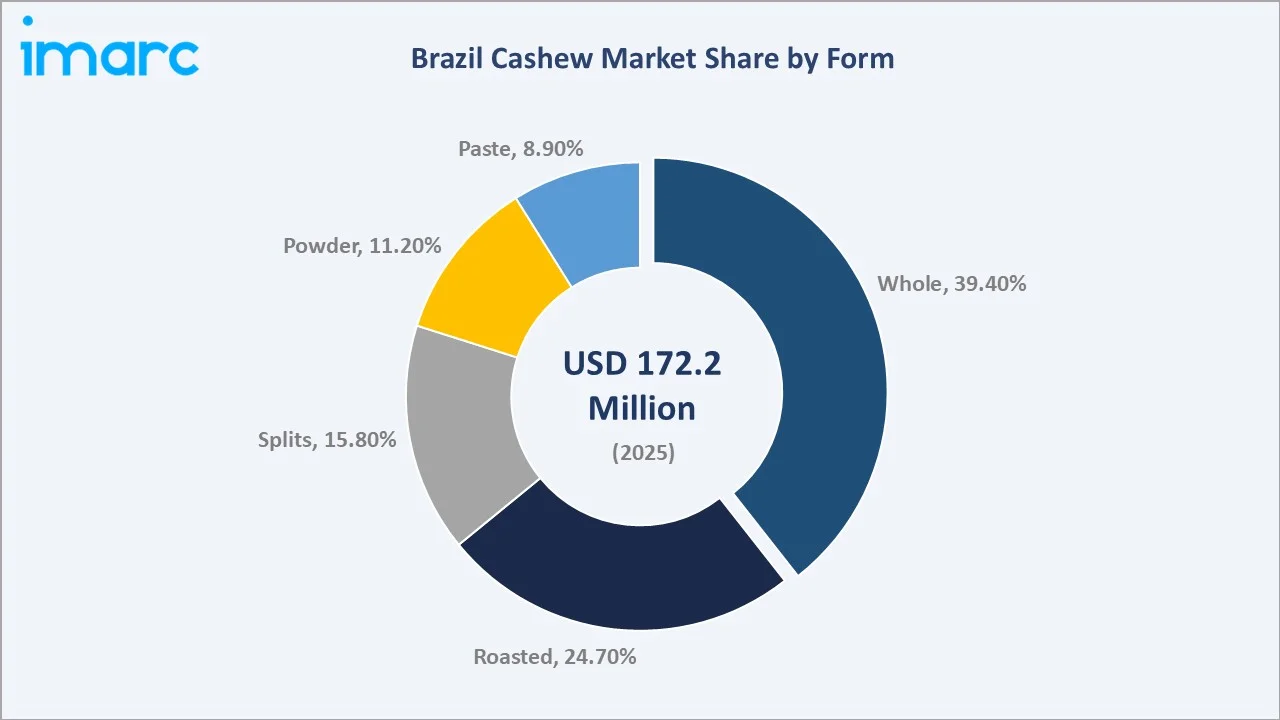
Whole cashews lead at 39.4% (2025). Whole cashews represent the market dominant form through their broad consumer acceptance, versatile application across direct snacking and food ingredient uses, and established retail presence across all distribution channels. Their premium positioning and natural minimally-processed appeal resonate strongly with health-conscious Brazilian consumers.
To access detailed market analysis, Request Sample
Roasted cashews at 24.7% represent the largest value-added category, commanding premium pricing through flavour enhancement and extended shelf life. Splits at 15.8% serve food manufacturing applications at accessible price points. Powder at 11.2% and Paste at 8.9% serve the growing plant-based food and food ingredient manufacturing markets.
By Distribution Channel
Supermarkets lead at 41.8% (2025). Supermarkets command the largest distribution share through their geographic reach, competitive pricing, high consumer footfall, and growing nut and dried fruit category investment. Major Brazilian supermarket chains are expanding premium cashew sections to capture health-food consumer spending.
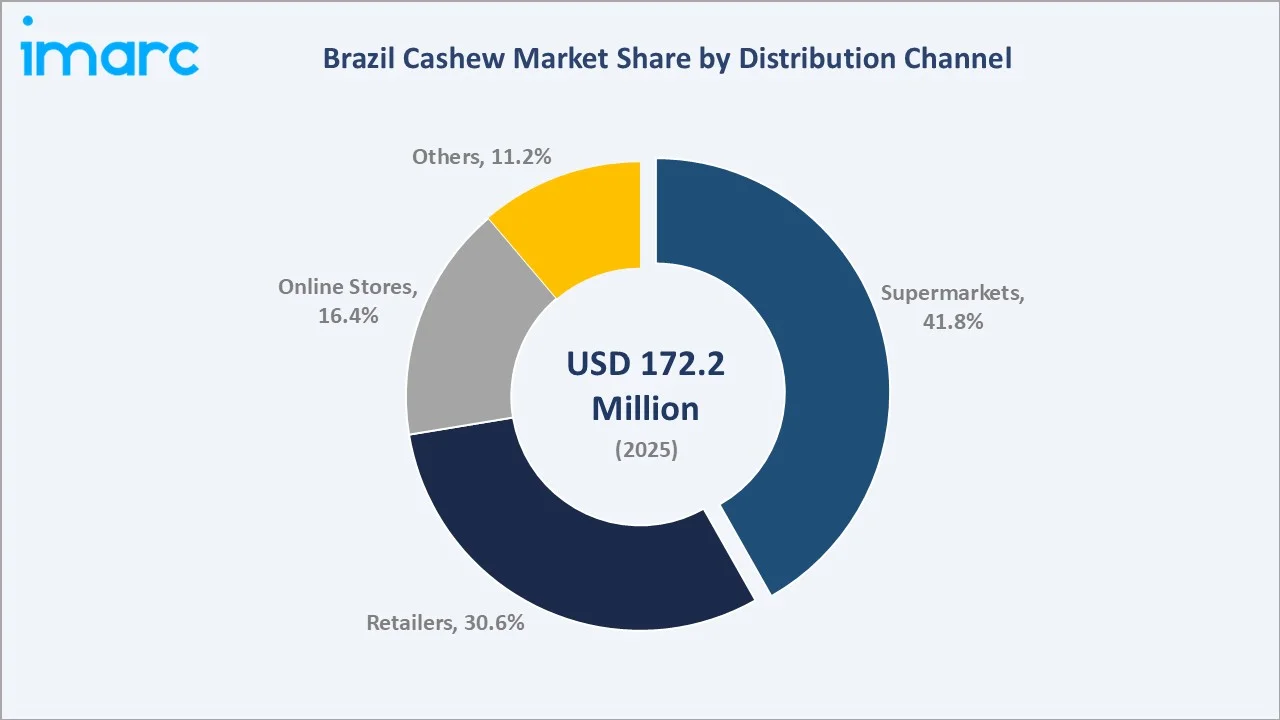
Retailers at 30.6% include independent food stores and specialist nut retailers serving local communities. Online Stores at 16.4% is the fastest-growing channel, expanding through e-commerce penetration and health-food digital retail. Others at 11.2% includes foodservice, B2B food industry supply, and direct farm-gate sales.
Regional Market Insights
|
Region |
Share (2025) |
Key Drivers & Characteristics |
|
Southeast |
42.6% |
Largest consumption hub driven by Sao Paulo and Rio de Janeiro high-income population, dense retail infrastructure, and strong demand for premium and packaged cashew products. |
|
Northeast |
23.8% |
Primary production region accounting for over 95% of Brazil cashew cultivation; states of Ceara, Piaui, and Rio Grande do Norte dominate supply-side activity. |
|
South |
17.4% |
Strong health-conscious consumer base and well-developed supermarket networks supporting steady cashew retail demand across Parana, Santa Catarina, and Rio Grande do Sul. |
|
Central-West |
9.1% |
Growing urban population and expanding modern retail in Mato Grosso and Goias supporting rising cashew consumption in this agricultural-focused region. |
|
North |
7.1% |
Emerging market with low per-capita cashew consumption; growth supported by rising disposable incomes and improving distribution networks in Para and Amazonas. |
Southeast Brazil 42.6% market leadership reflects Sao Paulo role as Brazil largest consumer market, combined with Rio de Janeiro and Minas Gerais growing premium food retail presence. The Northeast 23.8% share reflects its dual role as both major producer and significant domestic consumer, with local market access advantages for Northeast-based processors.
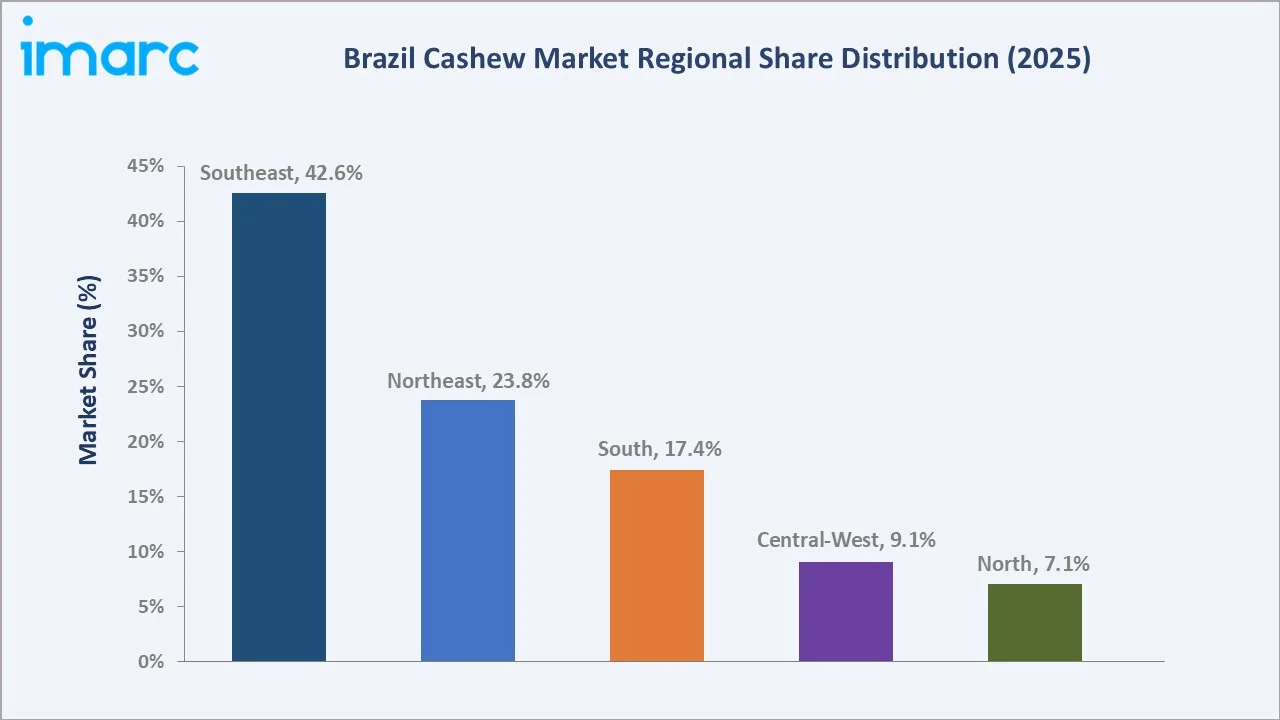
The South region 17.4% is supported by Parana and Rio Grande do Sul health-conscious consumer base and strong modern retail penetration. Central-West at 9.1% is experiencing above-average growth driven by expanding urbanisation, while North at 7.1% remains the least penetrated region with growing consumption opportunity as income levels rise.
Competitive Landscape
The Brazil cashew market features moderate concentration, with leading processors competing alongside regional cooperatives and international commodity traders. Competition is driven by product quality, processing efficiency, certification status, distribution network reach, and ability to meet both domestic retail and international export specifications.
|
Company |
Key Products |
Market Position |
Core Strength |
|
Olam Group |
Export-grade whole cashews, processed cashew kernels |
Strong Challenger |
Global agri-commodity major with significant Brazil cashew sourcing, processing, and export capabilities. |
|
Noble Enterprise |
Roasted cashews, flavoured cashews, cashew splits |
Innovator |
Niche premium roasted and flavoured cashew specialist with strong independent retailer distribution. |
|
Valency International Pte Ltd |
Raw Cashew Nut, Cashew Kernel |
Strong Challenger |
Singapore-headquartered integrated agri-trading and processing company with a leading position in global cashew supply chains, owning processing factories in Vietnam, India, and Nigeria. |
Key players include Olam Group, Noble Enterprise, Valency International Pte Ltd, and others.
Key Company Profiles
Noble Enterprise
Noble Enterprise is a leading company of nuts and dry fruits, with cashews representing a key product within its extensive dry fruit and nut portfolio. The company has built strong supply chain credentials over more than four decades, operating a processing house with a capacity of 750 MT per month and serving both domestic retailers and wholesale buyers, with overseas supply capabilities across global markets.
- Key Products: Roasted cashews, flavoured cashews, cashew splits, whole cashew nuts, and mixed dry fruit assortments sourced from high-quality international growers and supplied through retail, wholesale, and overseas distribution channels.
- Strategic Focus: Noble Enterprise's strategic focus is on strengthening its position as a quality-driven, nutrition-oriented dry fruit and nut supplier by deepening domestic retail and wholesale distribution while expanding its overseas buyer base. The company is investing in processing capacity upgrades, premium international sourcing relationships, and quality certification maintenance to sustain its competitive advantage and grow its share of the organised nut and dry fruit retail segment across domestic and export markets.
Olam Group
Olam Group represents a significant presence in the country's cashew sourcing and processing ecosystem. As one of the world's largest agri-commodity traders, Olam leverages its global supply chain infrastructure to source, process, and export Brazilian cashews to international food manufacturers and retail customers.
- Key Products: Export-grade whole cashew kernels, graded processed cashew nuts, and value-added cashew ingredients for international food manufacturing applications across snacking, confectionery, and food ingredient segments.
- Strategic Focus: Olam Group’s strategic focus is on expanding its certified sustainable cashew sourcing volume, deepening processing capabilities to deliver value-added cashew ingredients to global food manufacturers, and strengthening traceability documentation to capture premium pricing in sustainability-conscious export markets globally.
Market Concentration Analysis
The Brazil cashew market exhibits moderate concentration in processing and export, with a small number of integrated industrial processors and international traders accounting for a significant share of formal market volume. The domestic retail market is more fragmented, with numerous regional brands and private-label products competing alongside established national brands.
Market concentration is increasing as international commodity traders expand their Brazil cashew sourcing operations and domestic processors invest in scale expansion and quality certification. Smaller regional processors and cooperatives face consolidation pressure but retain competitive advantages through local farmer relationships and traceability documentation.
Investment & Growth Opportunities
Highest Growth Segments
Online Stores channel (~5.2% CAGR through e-commerce expansion), Roasted cashews (~4.1% CAGR through premiumisation), Southeast region (~4.3% CAGR through premium retail growth), and cashew-based value-added food products represent the highest-growth investment opportunities in the Brazil cashew market through 2034.
Emerging Investment Opportunities
The plant-based cashew ingredient segment - including cashew milk, cashew butter, and cashew-based dairy alternatives - represents the most significant emerging value-creation opportunity as Brazil plant-based food market expands with growing consumer demand for high-quality, locally sourced vegan food ingredients.
Investment Themes
- Processing facility modernisation and capacity expansion in the Northeast to improve quality consistency, reduce post-harvest losses, and meet growing international certification requirements for export market access.
- Digital retail and direct-to-consumer channel investment enabling premium cashew brands to capture higher margins and build direct consumer relationships in Brazil rapidly growing e-commerce food market.
Future Market Outlook (2026-2034)
The Brazil cashew market is projected to grow from USD 172.2 Million in 2025 to USD 178.4 Million in 2026, reaching USD 236.0 Million by 2034, registering a CAGR of 3.56% during 2026-2034. The market anchor value of USD 205.2 Million in 2030 reflects continued structural growth supported by domestic health food adoption, export market expansion, and growing value-added product development.
Three structural forces define Brazil cashew market growth through 2034: the sustained expansion of health-conscious consumption driving premium cashew product adoption; the digital transformation of Brazilian food retail creating new direct-consumer distribution channels; and the global growth in plant-based food demand creating significant export market opportunity for Brazilian cashew ingredient producers.
Research Methodology
Primary Research
Primary research comprised structured interviews with Brazil cashew industry stakeholders including cashew processors, export companies, supermarket category managers, cooperative representatives, and agricultural development officials in Ceara, Sao Paulo, and Rio de Janeiro.
Secondary Research
Secondary research encompassed IBGE agricultural production data, MAPA regulatory documentation, BNDES investment reports, Brazilian trade data, company financial disclosures, food industry publications, and supermarket retail data. Over 50 secondary sources were reviewed.
Forecasting Models
Market revenue forecasts were developed using a bottom-up demand model: domestic cashew consumption by form and channel multiplied by average retail pricing, aggregated by region, with export revenue modelled separately using trade data and price trend analysis.
Brazil Cashew Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Forms Covered | Whole, Roasted, Powder, Paste, and Splits |
| Distribution Channels Covered | Supermarkets, Retailers, Online Stores, and Others |
| Applications Covered | Dairy Products, Bakery Products, Snacks and Bars, Confectionaries, Cereals, Desserts, Beverages, Cosmetic Products, and Others |
| Regions Covered | Southeast, South, Northeast, North and Central-West |
| Companies Covered | Olam Group, Noble Enterprise, Valency International Pte Ltd, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Brazil cashew market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Brazil cashew market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Brazil cashew industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Brazil Cashew Market Report
The Brazil cashew market size was valued at USD 178.4 Million in 2026, driven by rising health-conscious consumption, growing export demand, and expanding modern retail distribution across supermarkets and online channels throughout Brazil.
The Brazil cashew market grows at a CAGR of 3.56% during 2026-2034, reaching USD 236.0 Million by 2034. Growth is sustained by premiumisation, export expansion, e-commerce adoption, and growing demand for value-added cashew products in food manufacturing and plant-based food segments.
Whole cashews lead at 39.4% through versatile application across snacking, cooking, and food ingredient uses, supported by strong consumer preference for minimally processed natural nuts across all Brazilian retail channels.
Supermarkets lead at 41.8% through broad geographic reach, competitive pricing, and category investment by major Brazilian retail chains. Online Stores at 16.4% is the fastest-growing channel, expanding through e-commerce penetration and health-food digital retail adoption.
Southeast Brazil leads at 42.6% through its concentrated urban population, higher per-capita income, and dense modern retail infrastructure in Sao Paulo, Rio de Janeiro, and Minas Gerais supporting strong premium cashew product consumption.
Leading companies include Olam Group, Noble Enterprise, Valency International Pte Ltd, and others.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade