Brazil Convenience Stores Market Size, Share, Trends and Forecast by Product Types, Store Types, and Region, 2026-2034
Brazil Convenience Stores Market Size, Share, Trends & Forecast (2026-2034)
The Brazil convenience stores market grew from USD 35.4 Billion in 2025 to USD 36.5 Billion in 2026 and is projected to reach USD 46.3 Billion by 2034, growing at a CAGR of 3.04% during 2026-2034. The market is driven by rapid urbanization, increasingly busy lifestyles, and growing consumer demand for quick and accessible shopping solutions. Expanding store networks, extended operating hours, and rising demand for ready-to-eat foods, beverages, and everyday essentials are further supporting market growth. Staple products lead at 46.8% by product type, traditional convenience stores command 31.6% by store type, and the Southeast region holds the largest share at 45.2%.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 35.4 Billion |
|
Market Size (2026) |
USD 36.5 Billion |
|
Forecast Market Size (2034) |
USD 46.3 Billion |
|
CAGR (2026-2034) |
3.04% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Product Types |
Staple Products (46.8%, 2025) |
|
Dominant Store Types |
Traditional Convenience Stores (31.6%, 2025) |
|
Leading Region |
Southeast (45.2%, 2025) |
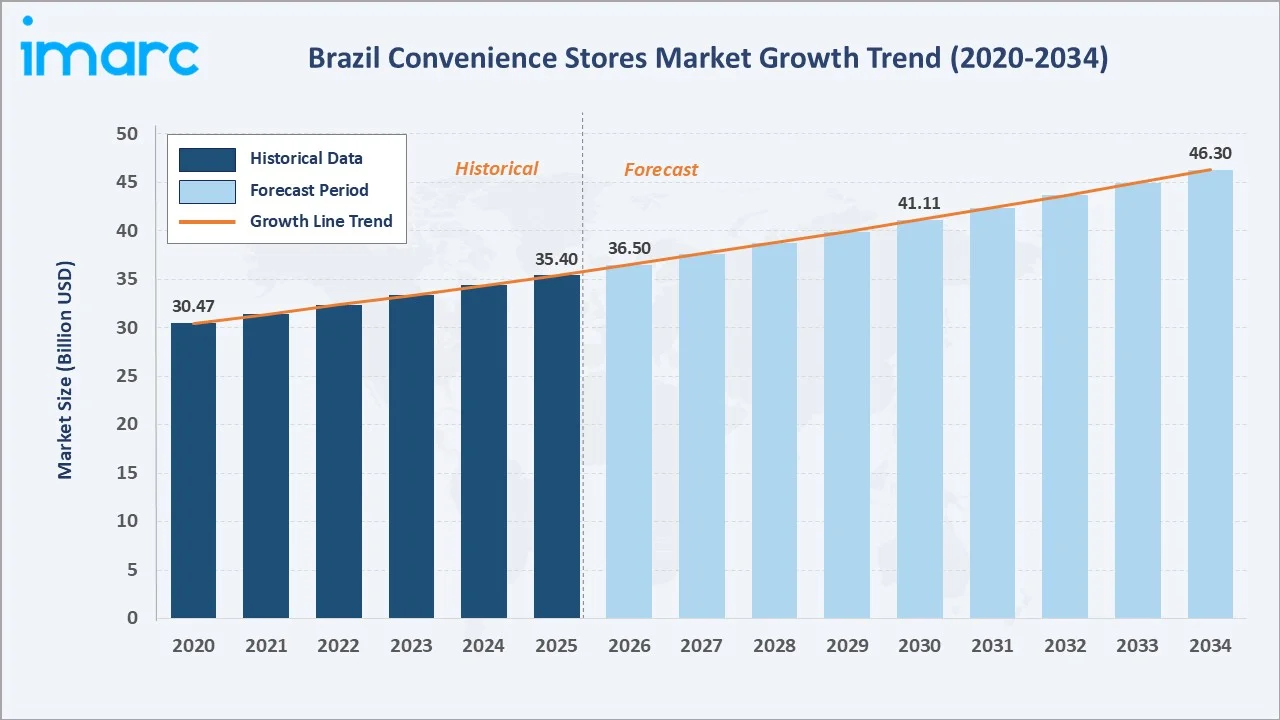
The Brazil convenience stores market grew from USD 30.47 Billion in 2020 to USD 35.4 Billion by 2025 and is estimated to reach USD 36.5 Billion in 2026. The market is projected to reach USD 41.11 Billion by 2030 and USD 46.3 Billion by 2034.
To get more information on this market, Request Sample
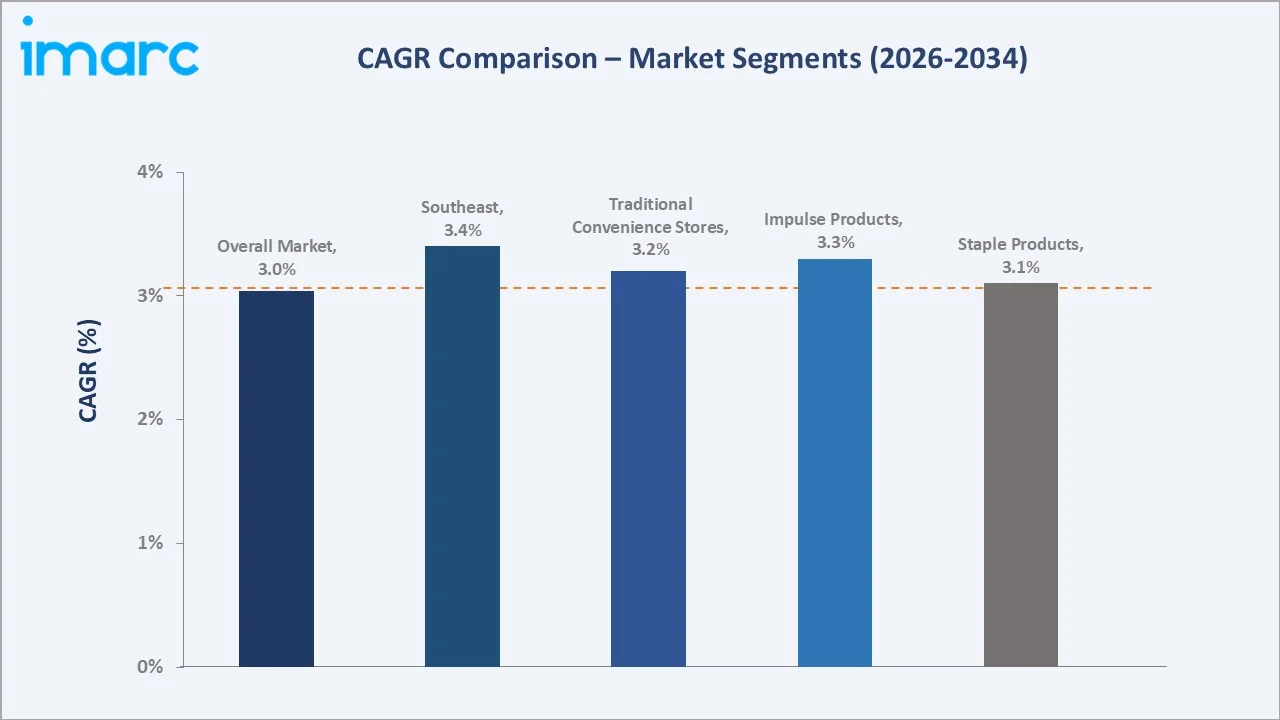
Staple products grow at ~3.1% CAGR driven by everyday grocery and food demand. Impulse products expand fastest at ~3.3% CAGR through food-to-go and snack category growth. Southeast region leads at ~3.4% CAGR through urban chain expansion and fuel station c-store network densification.
Executive Summary
The Brazil convenience stores market is experiencing sustained growth anchored by rapid urbanization, the expansion of organized fuel station convenience store networks, and rising consumer preference for quick and accessible shopping formats. Staple products dominate at 46.8%, reflecting the essential grocery and household supply role of Brazilian convenience stores. Traditional convenience stores lead at 31.6% through the dominance of fuel station-attached formats. The Southeast holds 45.2% market share through urban density and consumer spending concentration.
Key Market Insights
|
Insight |
Data |
|
Dominant Product Types |
Staple Products - 46.8% share (2025) |
|
Dominant Store Types |
Traditional Convenience Stores - 31.6% share (2025) |
|
Leading Region |
Southeast - 45.2% (2025) |
|
Key Market Opportunity |
Brazil's fuel station network represents an underpenetrated c-store expansion opportunity for incremental annual revenue by 2030 as attached convenience store penetration rises. |
Key Analytical Observations Supporting the Above Data:
- Staple Products at 46.8%: Staple product dominance reflects the role of Brazilian convenience stores as essential grocery access points for urban consumers seeking quick top-up shopping between major supermarket visits. Beverages (water, soft drinks, juices), packaged snacks, tobacco products, basic personal care items, and dairy products represent the backbone of convenience store revenue.
- Traditional Convenience Stores at 31.6%: The traditional convenience store format, defined by floor space, comprehensive product selection across all categories, 24-hour operations, and fuel station attachment, commands the largest format share.
- Southeast at 45.2%: The Southeast region leads due to its high population density, strong urbanization, higher consumer purchasing power, and concentration of major metropolitan areas. The region’s extensive retail infrastructure and strong demand for quick, on-the-go purchases further reinforce its market leadership.
Brazil Convenience Stores Market Overview
The Brazil convenience stores market encompasses organized retail stores operated on a small-format, extended-hours model selling fast-moving consumer goods, food-to-go, beverages, tobacco, emergency health products, and automotive supplies through locations attached to fuel stations or in standalone urban and transit positions. The market is served by organized national chains, organized regional players, independent operators, and the large Brazilian informal retail sector partially captured within market estimates.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
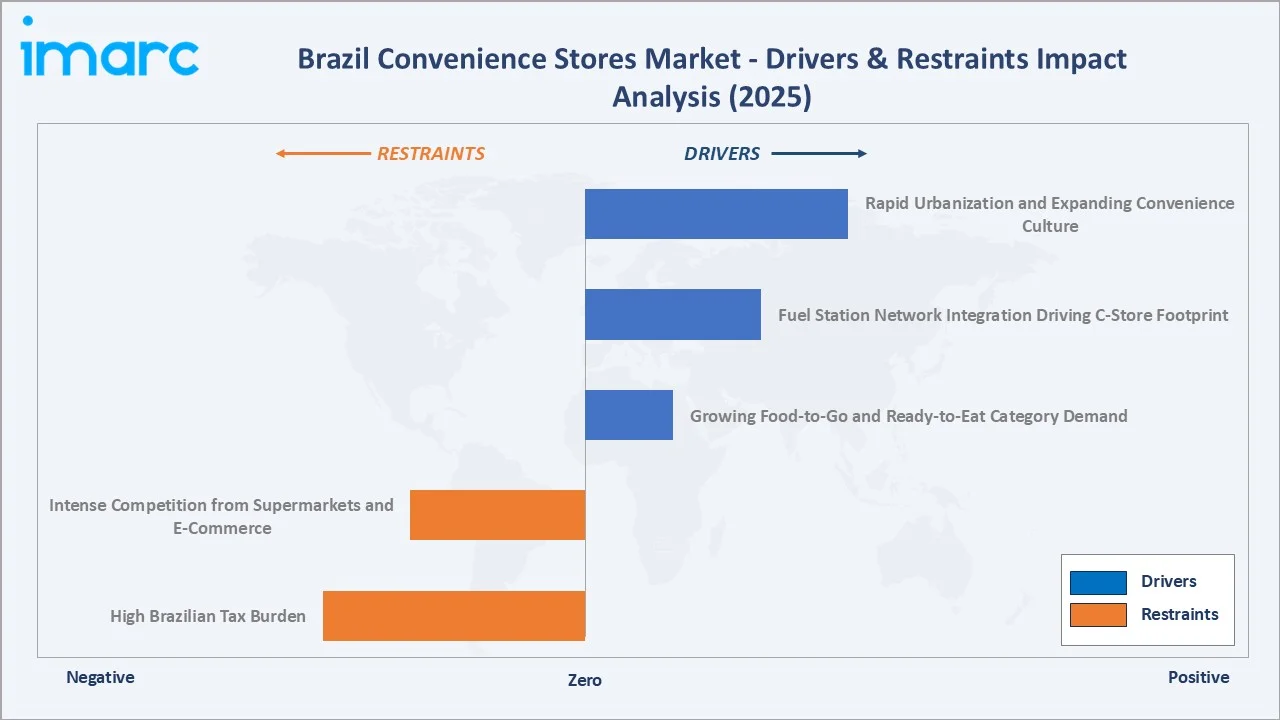
- Rapid Urbanization and Expanding Convenience Culture: Brazil's 87% urban population, one of the world's most urbanized large nations, creates the dense consumer geography that convenience stores require for profitability. São Paulo's metropolitan area alone sustains thousands of convenience store locations through high foot traffic corridors, transit hubs, and densely residential neighborhoods. Urban lifestyle changes, including longer working hours, longer commutes, and single-person household growth, are increasing the frequency of convenience store shopping occasions.
- Fuel Station Network Integration Driving C-Store Footprint: The vast Brazilian fuel station network, with 44,000 fuel stations, provides pre-existing, high-traffic real estate for convenience store attachment at minimal incremental location acquisition cost. Fuel networks create natural vehicle-traffic captive audiences amenable to convenience impulse purchasing, making fuel station attachment the most capital-efficient convenience store expansion model in the Brazilian market.
- Growing Food-to-Go and Ready-to-Eat Category Demand: The Brazilian consumer's expanding appetite for convenient prepared food, driven by urban time poverty, food delivery culture normalization, and COVID-era home meal preparation habit reversal, is transforming convenience stores from ambient product dispensaries to food service destinations. Coffee programs, fresh sandwiches, pastels, and hot lunch offerings are driving basket size increases and repeat visits frequently at organized chain locations.
Market Restraints
- Intense Competition from Supermarkets and E-Commerce: Brazilian supermarket chains are expanding neighborhood compact formats and 24-hour operations that directly compete with convenience stores on product range and pricing. Simultaneously, rapid grocery e-commerce delivery is providing sub-2-hour grocery delivery that challenges the convenience store value proposition for home consumption occasions.
- High Brazilian Tax Burden: Brazil's complex multi-layered tax system creates a significant operating cost burden for convenience store operators. Effective tax rates on convenience store revenues leave limited margin for investment in store modernization, food service capability development, and technology upgrades compared to convenience operators in lower-tax jurisdictions.
Market Opportunities
- Private Label Development for Margin Improvement: Organized convenience chains are developing private label product ranges in beverages, snacks, and personal care items that generate higher gross margins versus national brand equivalents. Premium beer private label and coffee blend private offerings demonstrate the Brazilian c-store market's private label development opportunity, particularly in beverages where consumer brand loyalty is lower than in food categories.
- EV Charging Hub Integration at Fuel Station C-Stores: As Brazil's EV market accelerates, driven by ethanol-hybrid vehicle adoption and federal EV incentives, fuel station convenience stores are positioned to benefit from longer consumer dwell time during EV charging sessions versus traditional fuel fill-up. EV charging programs and electromobility initiatives are transforming fuel stations into energy-plus-convenience hubs where charging dwell time dramatically increases per-visit convenience store spending.
Market Challenges
- Security and Shrinkage Management in Urban Markets: Brazilian urban convenience stores face significant security challenges from robbery, organized retail theft, and inventory shrinkage rates averaging 3-5% of sales in unprotected locations. High security investment requirements, armored cashier positions, CCTV, and security personnel add 2-4% of revenue in operating costs for urban c-store locations, compressing the already thin margins available in Brazil's high-tax operating environment.
- Supply Chain Complexity and Product Freshness Management: Managing fresh food, prepared food, and perishable product supply chains in Brazil's geographically vast market, with cold chain gaps in North and Northeast distribution networks, creates significant product waste and freshness compliance challenges. The regulatory requirements of food safety standards for prepared food require investment in store-level food safety training and cold storage equipment that raises operating costs at smaller convenience store locations.
Emerging Market Trends
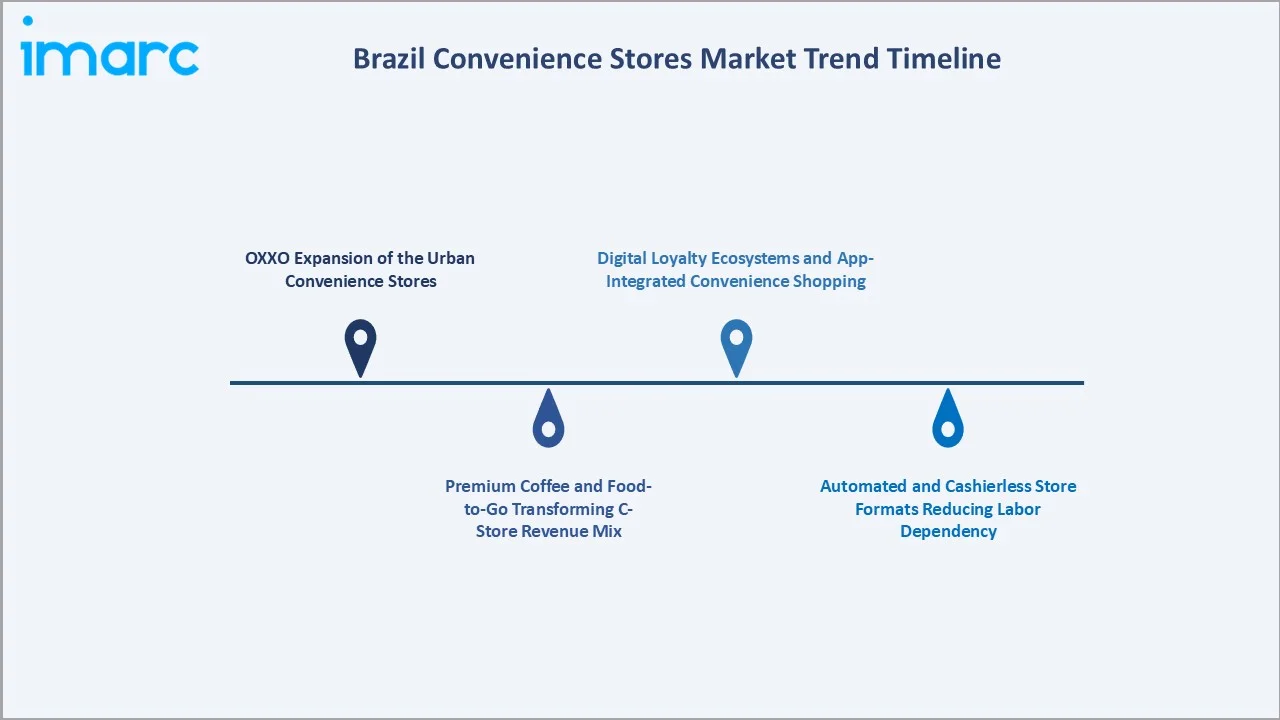
1. OXXO Expansion of the Urban Convenience Stores
FEMSA's OXXO is fundamentally reshaping the Brazilian convenience store market by introducing the standalone urban c-store concept, operating independently of fuel stations and targeting high-traffic pedestrian locations in metro systems, urban commercial corridors, and residential neighborhoods. In December 2024, FEMSA’s OXXO convenience store chain reached 600 outlets in Brazil within four years of entering the market, with operations spanning 24 cities across São Paulo State and a workforce exceeding 4,000 employees. The company plans to maintain Brazil as a key market for organic expansion over the next five years, with a particular focus on strengthening its presence across São Paulo.
2. Premium Coffee and Food-to-Go Transforming C-Store Revenue Mix
Brazilian convenience stores are rapidly evolving from ambient product dispensaries to food service destinations, with premium coffee programs driving significant per-transaction value uplift. Barista-style coffee offerings, am/pm's coffee and hot food menu, and coffee programs are generating high revenue from fresh food and beverage categories. The Brazilian consumer's deep coffee culture makes premium convenience coffee a high-frequency repeat purchase driver that builds store visit habits beyond the traditional fuel stop occasion.
3. Digital Loyalty Ecosystems and App-Integrated Convenience Shopping
Convenience store operators are investing heavily in mobile app loyalty programs that integrate purchase history, personalized offers, digital payment, and food pre-ordering. Fintech ecosystems and apps create digital touchpoints that extend customer relationships beyond point-of-sale transactions. These digital ecosystems generate first-party consumer data enabling personalized promotion targeting, predictive inventory replenishment, and cross-selling between fuel and c-store purchase occasions.
4. Automated and Cashierless Store Formats Reducing Labor Dependency
Labor cost escalation is driving investment in automation, self-checkout technology, and cashierless store format pilots. Automated micro-store formats and self-checkout kiosk pilots demonstrate that small-format c-stores can operate with fewer checkout staff while maintaining or improving consumer throughput speed. Cashierless technology using computer vision and weight-sensor shelf systems is being piloted in metro-adjacent high-traffic locations where labor shortage and turnover challenges are most acute.
Industry Value Chain Analysis
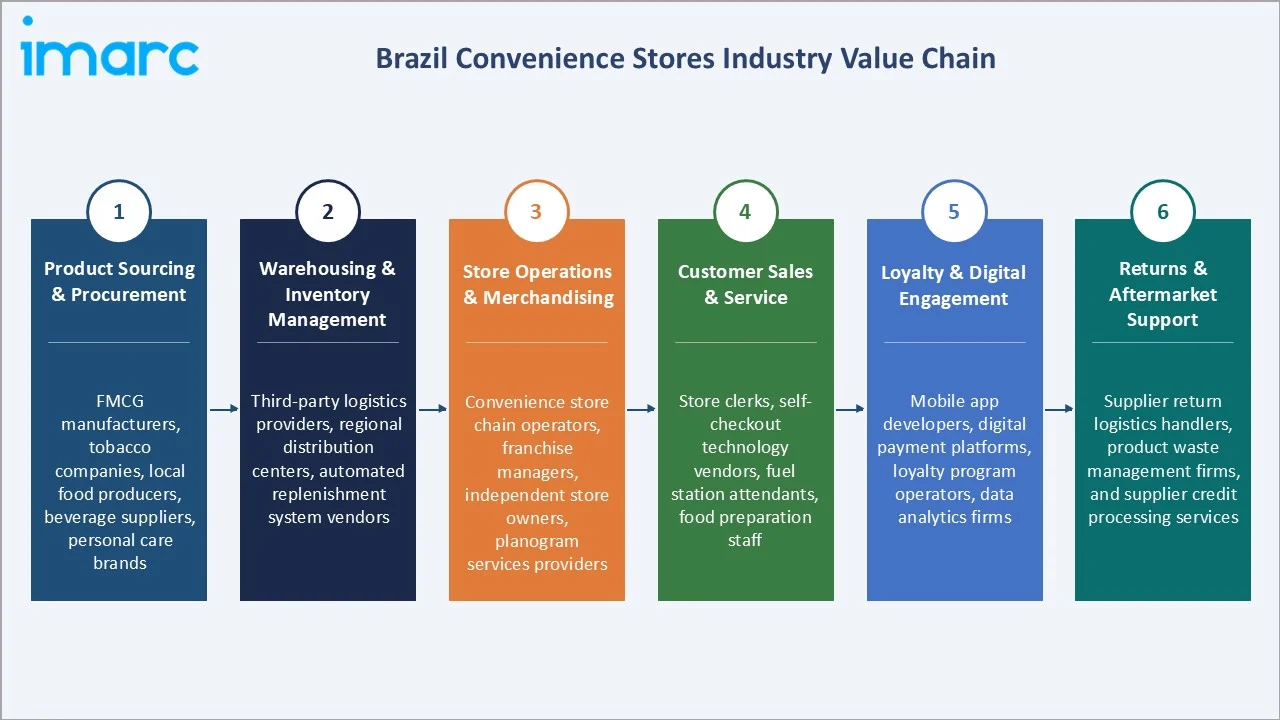
The Brazil convenience stores value chain encompasses product sourcing and procurement, warehousing and inventory management, store operations and merchandising, customer sales and service, digital loyalty and engagement, and aftermarket returns and support.
|
Stage |
Key Players |
|
Product Sourcing & Procurement |
FMCG manufacturers, tobacco companies, local food producers, beverage suppliers, personal care brands. |
|
Warehousing & Inventory Management |
Third-party logistics providers, regional distribution centers, automated replenishment system vendors. |
|
Store Operations & Merchandising |
Convenience store chain operators, franchise managers, independent store owners, planogram services providers. |
|
Customer Sales & Service |
Store clerks, self-checkout technology vendors, fuel station attendants, food preparation staff. |
|
Loyalty & Digital Engagement |
Mobile app developers, digital payment platforms, loyalty program operators, data analytics firms. |
|
Returns & Aftermarket Support |
Supplier return logistics handlers, product waste management firms, and supplier credit processing services. |
Store operations and merchandising represent the primary competitive value creation stage, where inventory availability, product freshness, store cleanliness, and service speed directly determine consumer satisfaction and repeat purchase frequency. Organized chain operators with advanced planogram compliance systems, automated inventory replenishment through connected POS-to-distribution center data flows, and trained store operations teams demonstrate the largest gap versus independent operators and informal retail competitors.
Technology Landscape in the Brazil Convenience Stores Industry
Point-of-Sale and Inventory Management Systems
Point-of-sale (POS) and inventory management systems are increasingly being adopted by convenience stores to streamline billing, monitor stock levels, and manage daily operations efficiently. These systems provide real-time visibility into sales and inventory, helping retailers reduce stockouts and excess inventory. Integration with data analytics and automated replenishment also enables better demand forecasting, pricing decisions, and overall store productivity.
Loyalty Program Technology and First-Party Data Analytics
Convenience store loyalty program technology has evolved from simple stamp cards to sophisticated mobile app ecosystems generating rich first-party consumer behavior data. Digital wallets, which integrate bill payment, transfers, and insurance alongside convenience purchase rewards, create a financial services-anchored loyalty relationship that dramatically increases consumer switching costs versus pure product loyalty programs. Integrating fuel purchase rewards with am/pm convenience spending demonstrates the multi-category loyalty data advantage available to fuel station-anchored c-store operators.
Food Safety and Cold Chain Technology
Food safety compliance requirements for fresh and prepared food are driving investment in temperature monitoring technology, food preparation workflow automation, and supplier traceability systems. IoT-enabled refrigeration unit temperature logging, digital compliance checklists replacing paper-based systems, and supplier certificate management platforms are becoming standard technology investments for organized convenience chains operating food service programs. These technology investments simultaneously improve food safety compliance, reduce product waste from temperature excursions, and provide audit trail documentation for inspection readiness.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Product Types |
Staple Products |
46.8% |
2025 |
|
Store Types |
Traditional Convenience Stores |
31.6% |
2025 |
|
Region |
Southeast |
45.2% |
2025 |

By Product Types
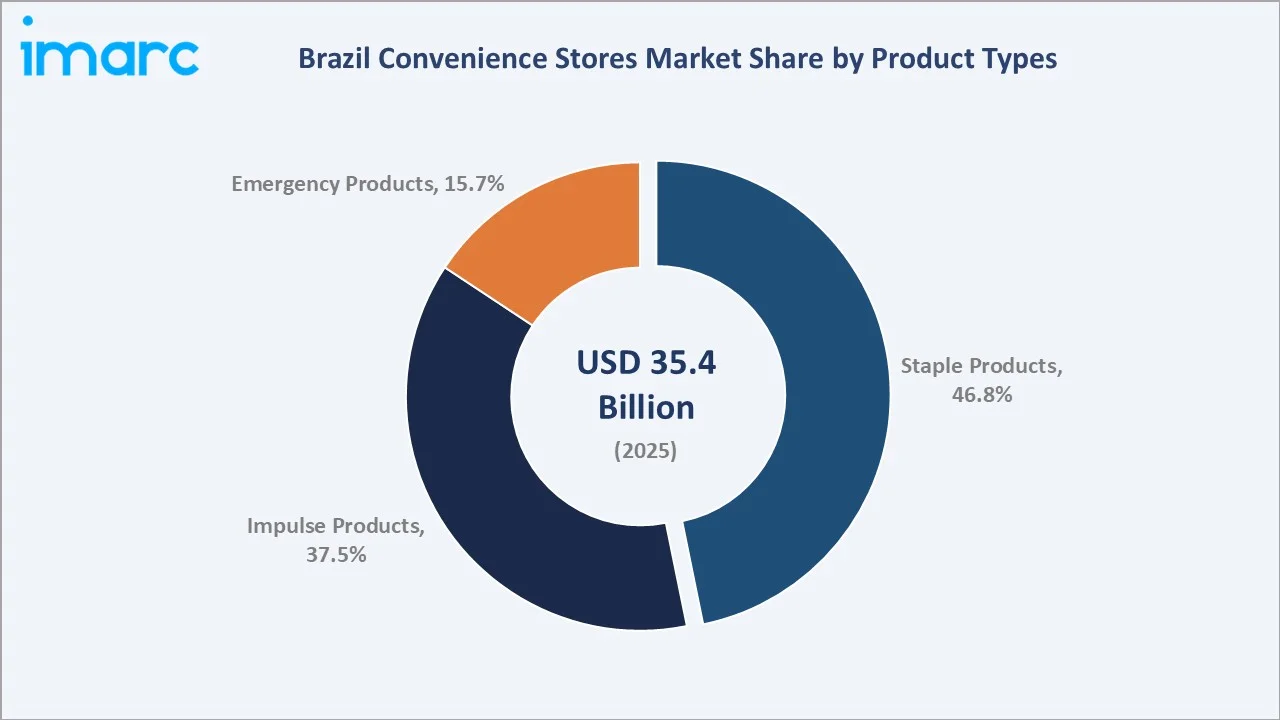
Staple products command 46.8% in 2025, encompassing the essential daily consumption categories that drive consistent store visits: beverages (water, soft drinks, energy drinks, beer), packaged snacks, tobacco products, basic dairy (milk, yogurt, cheese), bread and bakery, and household basics. The staple product category benefits from Brazil's high shopping frequency culture, creating predictable high-velocity category performance across all formats and regions.
To access detailed market analysis, Request Sample
Impulse products at 37.5% represent the fastest-growing and highest-margin category, led by hot beverages (coffee, cappuccino), fresh food (sandwiches, hot dogs, pastels, coxinhas), confectionery, and seasonal gift items. Emergency products at 15.7% serve high-margin, low-frequency purchases across pharmaceutical OTC products, phone chargers and accessories, automotive supplies, and stationery.
By Store Types
Traditional convenience stores command 31.6% in 2025, representing the standard fuel station-attached or urban standalone c-store format with comprehensive product selection, extended or 24-hour operations, and organized chain management.
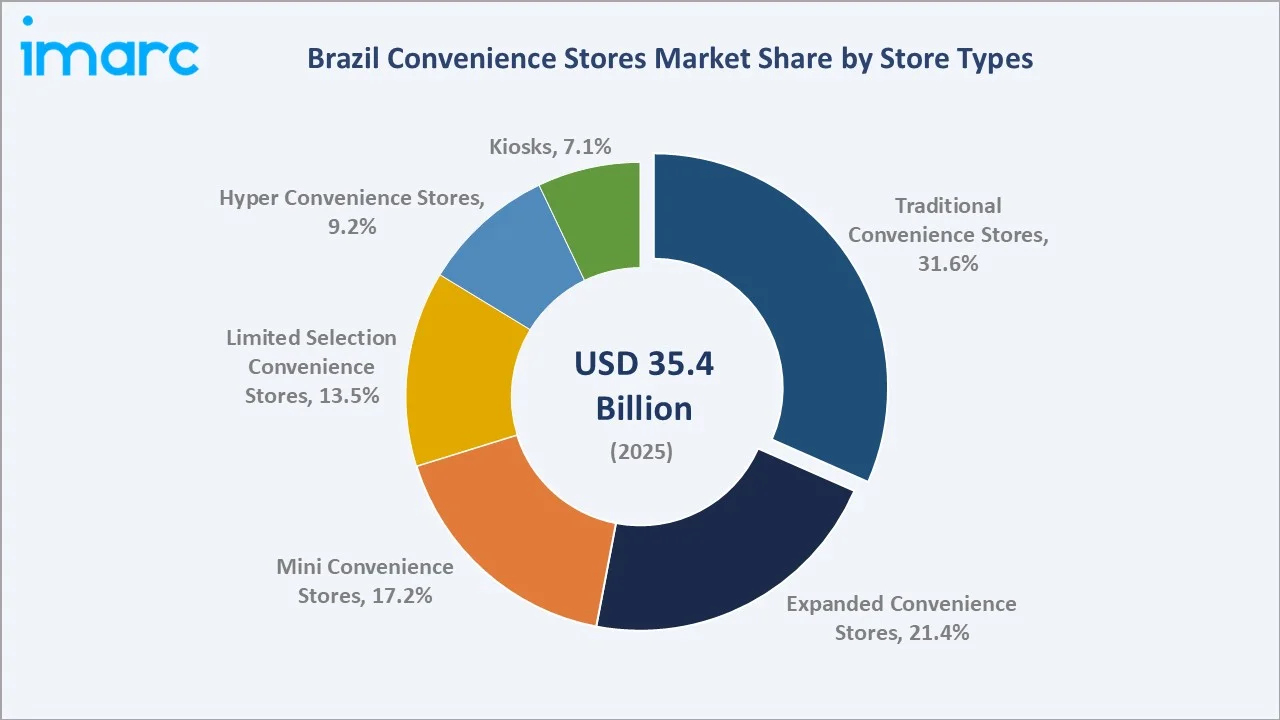
Expanded convenience stores at 21.4% represent the next-generation format with food service areas, seating, wider product selection, and enhanced service offerings including ATMs and lottery terminals. Mini convenience stores at 17.2% serve high-traffic locations with space constraints, metro stations, office building lobbies, and university campuses, with limited SKU selections. Limited selection convenience stores at 13.5% serve rural and semi-urban locations with basic assortments. Hyper convenience stores at 9.2% and kiosks at 7.1% address specialized location and consumer service requirements.
Regional Market Insights
|
Region |
Share (2025) |
Key Brazil Convenience Stores Market Drivers & Characteristics |
|
Southeast |
45.2% |
Reflecting dense urban populations, highest consumer spending power, largest fuel station and attached c-store network concentration, and strong presence of organized chains. |
|
South |
22.7% |
Reflecting high income levels, strong cultural tradition of organized food retail, well-developed highway and fuel station convenience store network, and growing organized chain penetration. |
|
Northeast |
15.6% |
Reflecting growing urban middle-class consumer base, increasing fuel station c-store attachment rates, and rapid OXXO expansion targeting the Northeast's large and underpenetrated consumer population with accessible convenience formats. |
|
Central-West |
9.1% |
Reflecting high per-capita income and urban concentration, a growing agribusiness economy, and strong highway corridor convenience store demand from long-distance trucking and agricultural commodity transportation networks. |
|
North |
7.4% |
Reflecting lower formal retail penetration, logistics challenges increasing convenience store operating costs, and a predominantly informal retail landscape. |
Southeast's 45.2% reflects its status as both the economic and convenience retail capital of Brazil. South Brazil's 22.7% reflects the region's high formalized retail penetration and strong consumer spending, built on well-developed highway networks and organized fuel station c-store culture.
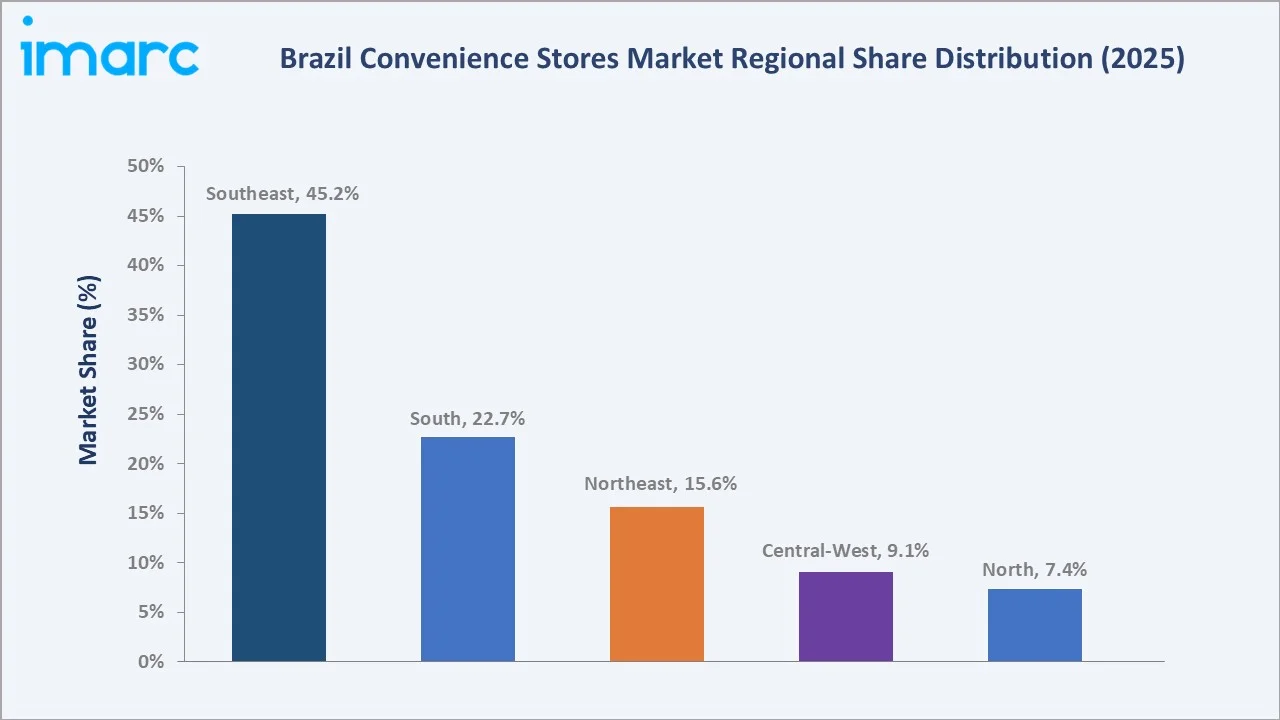
Northeast's 15.6% is the market's highest-growth potential region as urban expansion targeting the region's large, underpenetrated population. Central-West at 9.1% benefits from high per-capita income and growing agribusiness corridor highway c-store demand. The North at 7.4% remains logistics-challenged, but urban growth in some states is creating organized chain expansion opportunities.
Competitive Landscape
The Brazil convenience stores market features a competitive landscape anchored by integrated fuel distribution and retail groups, specialized convenience chain operators, food retailers expanding into convenience formats, and pharmacy and general retail chains competing in the 24-hour small-format space. Market leadership is contested through location network scale, food service quality, digital payment and loyalty ecosystem integration, and supplier relationship management.
|
Company |
Key Stores |
Market Position |
Core Strength |
|
FEMSA |
OXXO |
Market Leader |
FEMSA drives the growth of neighborhood convenience retail in Brazil through full ownership and expansion of the OXXO store chain. |
|
Petrobras |
BR Mania |
Established Player |
Petrobras created and grew BR Mania, one of Brazil's largest convenience store chains located at its service stations. |
|
Pereira Group |
Comper |
Innovator |
Operates as one of the largest retail and wholesale food groups in Brazil rather than a traditional chain of standalone convenience stores. |
Competitive dynamics are shifting as OXXO standalone urban expansion introduces direct competition for high-traffic locations previously dominated by fuel station-anchored formats. Digital payment integration through proprietary fintech wallets is becoming a key differentiator, while food service capability, particularly premium coffee and fresh food, is increasingly the primary driver of consumer format preference among urban Brazilian convenience shoppers.
Key Company Profiles
FEMSA
FEMSA is a multinational company with a growing presence in Brazil’s convenience stores market through its OXXO retail network. The company operates neighborhood-focused stores offering beverages, snacks, ready-to-eat foods, groceries, and other everyday essentials. Its operations are supported by established retail expertise, supply chain capabilities, and a focus on providing convenient and accessible shopping experiences.
- Key Stores: OXXO.
- Strategic Focus: Expanding its OXXO store network across high-density urban locations in Brazil while strengthening accessibility and customer convenience. Its strategy emphasizes organic store expansion, localized product assortments, operational efficiency, and digital retail capabilities to reinforce its position in the convenience stores market.
Petrobras
Petrobras is a major Brazilian energy company with a longstanding presence in the country’s fuel retail ecosystem, which includes convenience-store formats associated with service stations. Within the convenience retail segment, its branded network supports the sale of snacks, beverages, ready-to-eat products, and other everyday essentials. Its extensive service-station footprint and strong brand recognition support convenient access for motorists and local consumers.
- Key Offerings: BR Mania.
- Strategic Focus: Strengthening convenience retail offerings associated with fuel stations by enhancing customer experience, product accessibility, and service integration. Its strategic approach emphasizes modernization, digital solutions, operational efficiency, and diversified non-fuel offerings to capture additional consumer spending at service locations.
Market Concentration Analysis
The Brazil convenience stores market is moderately concentrated in the organized sector, collectively commanding an estimated 40-50% of organized convenience store revenue through their combined fuel station-attached locations. Market consolidation is likely through the forecast period as OXXO's aggressive expansion accelerates competitive response from established players, particularly in high-traffic urban locations, and as digital payment and loyalty platform investment requirements raise barriers for smaller operators unable to match organized chain technology investment. The informal retail sector's gradual formalization through tax regularization programs and payment digitization may bring additional independent convenience operators into formal market accounting over time.
Investment & Growth Opportunities
Highest Growth Segments
Impulse product food service (~3.3% CAGR), Southeast region urban expansion (~3.4% CAGR), standalone urban OXXO-format c-stores, EV charging hub convenience integration, digital payment and fintech-enabled c-store revenue, and Northeast region underpenetrated market development represent the highest-return investment vectors in the Brazil convenience stores market through 2034.
Investment Themes
- Fuel Station C-Store Attachment Program: Independent fuel station operators representing most of Brazil's stations without organized c-store attachments represent a capital-efficient expansion opportunity through franchise program development, plug-and-play store format packages, and shared inventory procurement systems.
- Fintech and Digital Wallet Integration: Brazilian c-store operators with physical network scale can layer financial services, bill payment, money transfer, micro-credit, and mobile top-up onto existing store infrastructure to generate revenue from Brazil's underbanked or informally banked adult consumers who use physical retail touchpoints for financial transactions.
Future Market Outlook (2026-2034)
The Brazil convenience stores market is projected to grow from USD 35.4 Billion in 2025 to USD 36.5 Billion in 2026, reaching USD 46.3 Billion by 2034, exhibiting a CAGR of 3.04% during 2026-2034. The market is projected to reach an anchor value of USD 41.11 Billion by 2030, representing the mid-period milestone at which fuel station c-store attachment and food service category revenues grow.
Three structural forces will define the Brazil convenience stores market through 2034. First, Brazil's continuing urbanization trajectory creates persistent demand for accessible, extended-hours neighborhood retail that convenience stores are uniquely positioned to serve, as the density and time-poverty of urban living increases the frequency and necessity of convenience channel shopping versus weekly supermarket-only procurement behavior. Second, the format transformation of fuel stations from fuel-only into integrated convenience, food service, and mobility hubs will expand the revenue per customer visit and total addressable revenue at the fuel station footprint that remains the backbone of organized Brazilian convenience retail. Third, the digital ecosystem competition will drive investment in consumer data capability and personalized promotion that increases basket size, visit frequency, and brand loyalty.
Research Methodology
Primary Research
Primary research comprised in-depth interviews with convenience store chain executives, fuel station operators, FMCG supplier account managers, retail technology providers, Brazilian retail industry association representatives, and consumer research professionals. These discussions validated market size estimates, product type and store type demand dynamics, regional penetration patterns, and technology adoption trajectory for the 2026-2034 forecast period.
Secondary Research
Secondary research encompassed fuel station licensing data, retail trade statistics, Brazilian supermarkets association sector reports, retail data, IMARC Group proprietary retail and consumer goods databases, annual reports of key market participants, and industry publications covering Brazil's convenience retail and foodservice market developments through 2025.
Forecasting Models
Forecasting models incorporated historical convenience store revenue correlations with Brazilian GDP growth, urbanization rates, and fuel station expansion data, organized chain store opening and closure data; consumer spending index trajectories by region; digital payment adoption curves and their impact on average transaction values; and macroeconomic indicators including inflation, interest rates, and consumer confidence. Both bottom-up store count and revenue per store modeling and top-down GDP-linked consumer spending approaches were cross-validated for forecast consistency.
Brazil Convenience Stores Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Product Types Covered | Staple Products, Impulse Products, Emergency Products |
| Store Types Covered | Kiosks, Mini Convenience Stores, Limited Selection Convenience Stores, Traditional Convenience Stores, Expanded Convenience Stores, Hyper Convenience Stores |
| Regions Covered | Southeast, South, Northeast, North, Central-West |
| Companies Covered | FEMSA, Petrobras, Pereira Group, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Brazil convenience stores market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Brazil convenience stores market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Brazil convenience stores industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Brazil Convenience Stores Market Report
The Brazil convenience stores market size is estimated at USD 36.5 Billion in 2026, driven by fuel station c-store network expansion, OXXO Brasil urban rollout, digital payment adoption, food-to-go category growth, and urbanization-driven consumer frequency increases across organized convenience formats.
The Brazil convenience stores market is projected to grow at a CAGR of 3.04% during 2026-2034, driven by continued urbanization, increased fuel station c-store penetration, food service revenue expansion, digital loyalty ecosystem investment, and Northeast region underpenetrated market development.
The market is projected to reach USD 41.11 Billion by 2030, representing the mid-period milestone when fuel station c-store attachment approaches 50%, and food service reaches most of the organized chain convenience revenue nationally.
Staple products lead with a 46.8% share in 2025, driven by daily consumer top-up shopping for beverages, packaged snacks, tobacco, dairy, and household basics across the convenience store network serving Brazil's highly urbanized and high-frequency shopping consumer base.
Traditional convenience stores lead with a 31.6% share in 2025, anchored by fuel station-attached am/pm and expanding OXXO standalone urban stores, defining the organized convenience standard in Brazil.
The Southeast leads with a 45.2% share in 2025, anchored by São Paulo's metropolitan population, all major organized chain headquarters, highest per-capita convenience store revenue, and the most developed fuel station c-store network density in Brazil.
Key players include FEMSA, Petrobras, and Pereira Group, among others.
The Brazil convenience stores market is projected to reach USD 46.3 Billion by 2034, driven by OXXO national network maturity, EV charging hub c-store integration, food service category premiumization, digital fintech and loyalty ecosystem revenue, and Northeast and Central-West region underpenetrated market development.
Key opportunities include fuel station c-store attachment program development for independent stations, premium coffee and fresh food service investment doubling per-visit food and beverage revenue, fintech wallet integration generating financial service revenue from underbanked consumers, EV charging hub convenience spending capture, and Northeast region franchise expansion targeting the underpenetrated large urban consumer base.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade