
Brazil Shrimp Market Size, Share, Trends and Forecast by Environment, Species, Shrimp Size, Distribution Channel, and Region, 2026-2034
Brazil Shrimp Market Size, Share, Trends & Forecast (2026-2034)
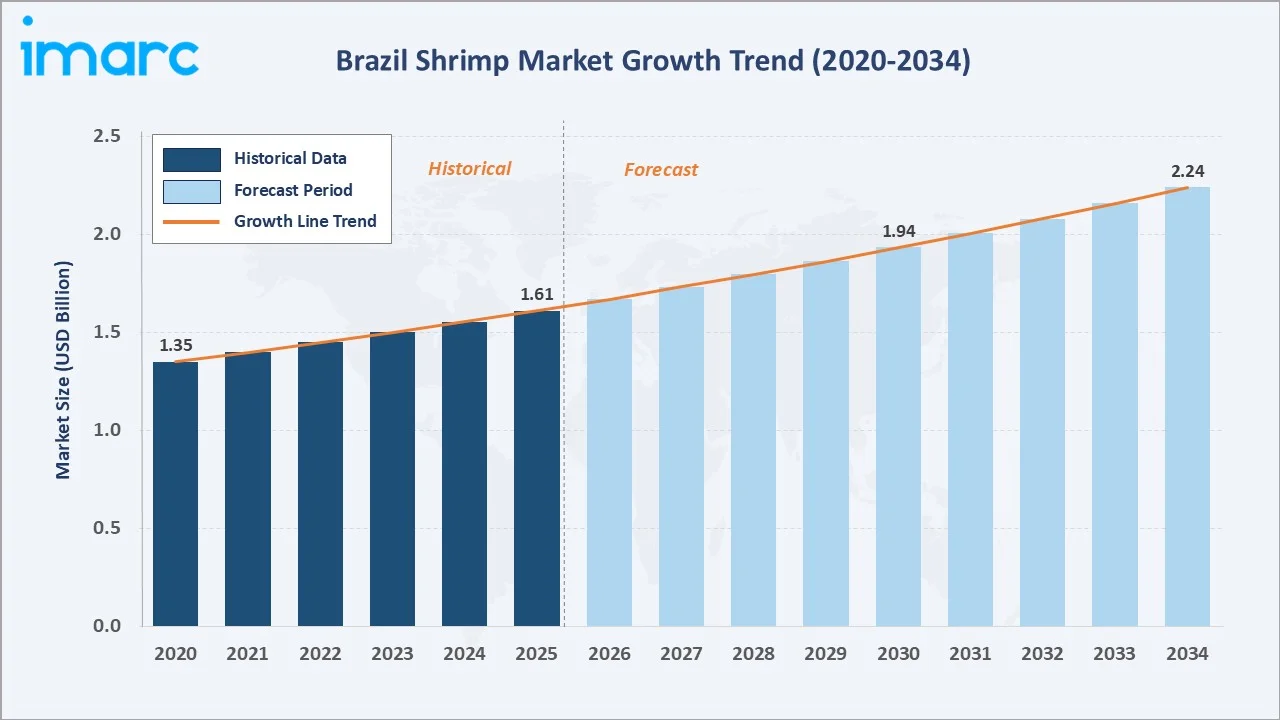
The Brazil shrimp market size increased from USD 1.61 Billion in 2025 to USD 1.67 Billion in 2026 and is projected to reach USD 2.24 Billion by 2034, registering a CAGR of 3.72% during the forecast period 2026-2034. Farmed shrimp dominates the supply landscape, commanding a 71.6% share in 2025, driven by rapid aquaculture expansion across the Northeast and Southeast regions.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 1.61 Billion |
| Market Size (2026) | USD 1.67 Billion |
|
Forecast Market Size (2034) |
USD 2.24 Billion |
|
CAGR (2026-2034) |
3.72% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Largest Region |
Southeast – 44.2% |
|
Largest Environment |
Farmed Shrimp – 71.6% |
|
Leading Distribution Channel |
Hotels and Restaurants – 34.5% |
The chart below illustrates the full market growth trajectory from 2020 to 2034, distinguishing historical performance from the forward-looking forecast period.
To get more information on this market, Request Sample
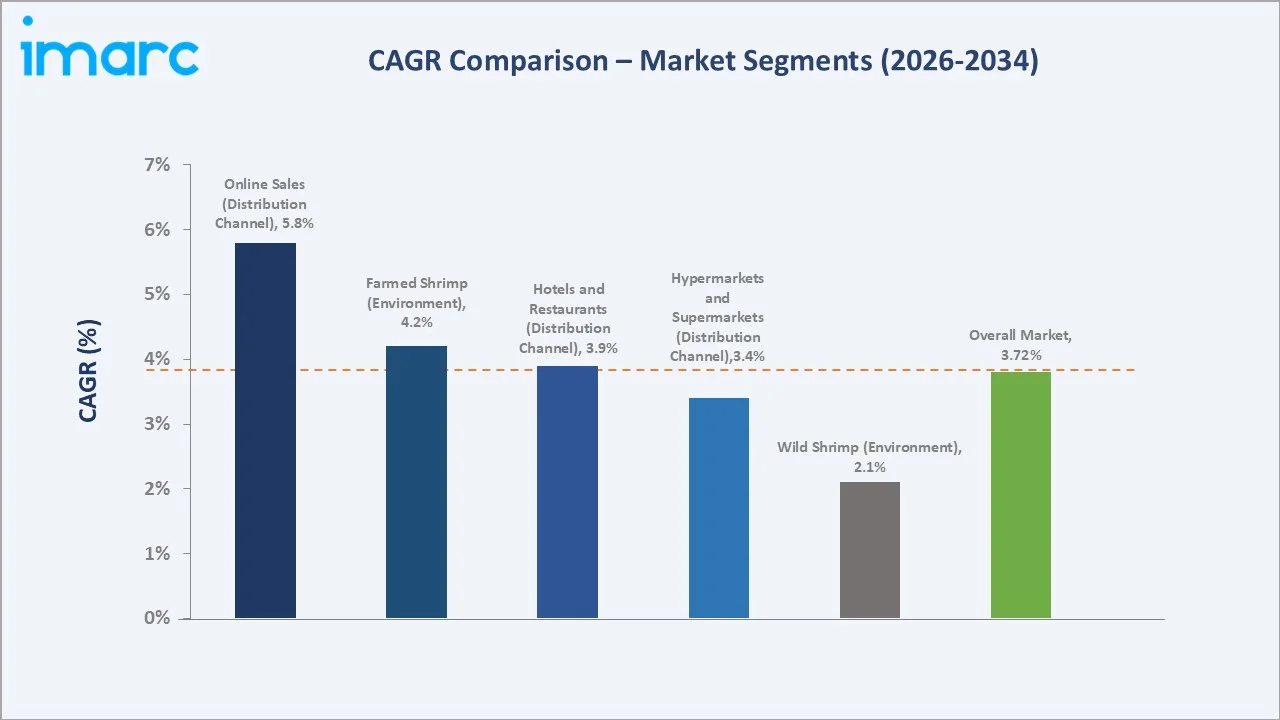
The CAGR comparison chart highlights differential growth rates across key market segments, enabling targeted investment prioritization.
Executive Summary
The Brazil shrimp market has demonstrated consistent upward momentum, rising from USD 1.35 Billion in 2020 to USD 1.61 Billion in 2025 and an estimated USD 1.67 Billion in 2026. This trajectory reflects the combined effect of rising domestic seafood consumption, significant investments in modern aquaculture infrastructure, and growing interest from international buyers in certified Brazilian produce. The market is projected to reach USD 1.94 Billion by 2030 and USD 2.24 Billion by 2034, driven by a sustained CAGR of 3.72%.

Aquaculture dominates supply, with farmed shrimp accounting for 71.6% of the 2025 market. The Penaeus vannamei species remains the workhorse of Brazilian shrimp farms, valued for its fast growth cycles, disease tolerance, and feed efficiency. The Northeast region is the primary production hub, while the Southeast contributes the largest share of consumption at 44.2%. Hotels and restaurants are the leading distribution channel at 34.5%, reflecting the deeply embedded role of shrimp in Brazilian cuisine and gastronomy.
Looking ahead, the Brazil shrimp market outlook is shaped by multiple growth levers: expanding biofloc and recirculating aquaculture system (RAS) adoption, growth in online seafood sales (currently 12.3% of distribution), cold chain modernization, and certification-driven export potential. Key challenges include disease risk management, price volatility of fishmeal inputs, and the need for sustained investment in logistics infrastructure outside major urban centers.
Key Market Insights
|
Insight |
Detail |
|
Market Size (2025) |
USD 1.61 Billion |
|
Market Size (2034) |
USD 2.24 Billion |
|
Growth Rate (CAGR) |
3.72% (2026-2034) |
|
Dominant Environment |
Farmed Shrimp – 71.6% (2025) |
|
Leading Distribution Channel |
Hotels and Restaurants – 34.5% (2025) |
|
Largest Region |
Southeast – 44.2% (2025) |
|
Fastest Growing Channel |
Online Sales – CAGR ~5.8% (2026-2034) |
|
Top Companies |
MBRF, JBS, Camanor Produtos Marinhos Ltda., Carapitanga, Potipora |
|
Key Market Opportunity |
Export certification & premium seafood positioning |
Key Observations From the Data Above:
- Farmed shrimp at 71.6% of total supply reflects a structural shift from wild fishing toward controlled aquaculture – a trend that reduces supply volatility and enables consistent quality standards for export markets.
- Hotels and restaurants capture 34.5% of distribution, underscoring shrimp's central role in Brazilian food service – from casual seafood eateries to premium coastal restaurants.
- The Southeast region's 44.2% share is driven by São Paulo and Rio de Janeiro's urban consumer bases and superior cold chain connectivity, while the Northeast provides 21.6% and serves as the dominant production heartland.
- Online sales at 12.3% represent the fastest-growing channel, with a projected CAGR of ~5.8% through 2034 as e-commerce penetration in perishable food categories accelerates post-pandemic.
- The market opportunity in premium export positioning is significant: buyers in Europe and North America increasingly seek traceable, sustainably farmed shrimp, and Brazil's coastal geography offers ideal conditions to meet this demand at competitive price points.
Brazil Shrimp Market Overview
Brazil shrimp market industry encompasses the full spectrum of shrimp production, processing, and distribution activities within the country – from artisanal coastal fishing to large-scale aquaculture operations and modern processing facilities. Brazil is one of South America's leading shrimp producers, with the sector deeply integrated into the national food economy. Shrimp contributes significantly to both domestic food security and export revenues, particularly from the Northeast coastal states of Rio Grande do Norte, Ceará, and Pernambuco.
Macroeconomic factors influencing the market include rising per capita income (Brazil's GDP per capita was approximately USD 10280.31 in 2024), improved cold chain infrastructure investment under federal programs, and shifting dietary preferences among urban consumers. Brazil's BRL/USD exchange rate also plays a key role in export competitiveness, with currency movements in 2023–2025 providing favorable windows for exporters. Industry associations such as ABCC (Brazilian Association of Shrimp Farmers) and MAPA (Ministry of Agriculture) regulatory frameworks govern production standards, disease protocols, and certification requirements.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
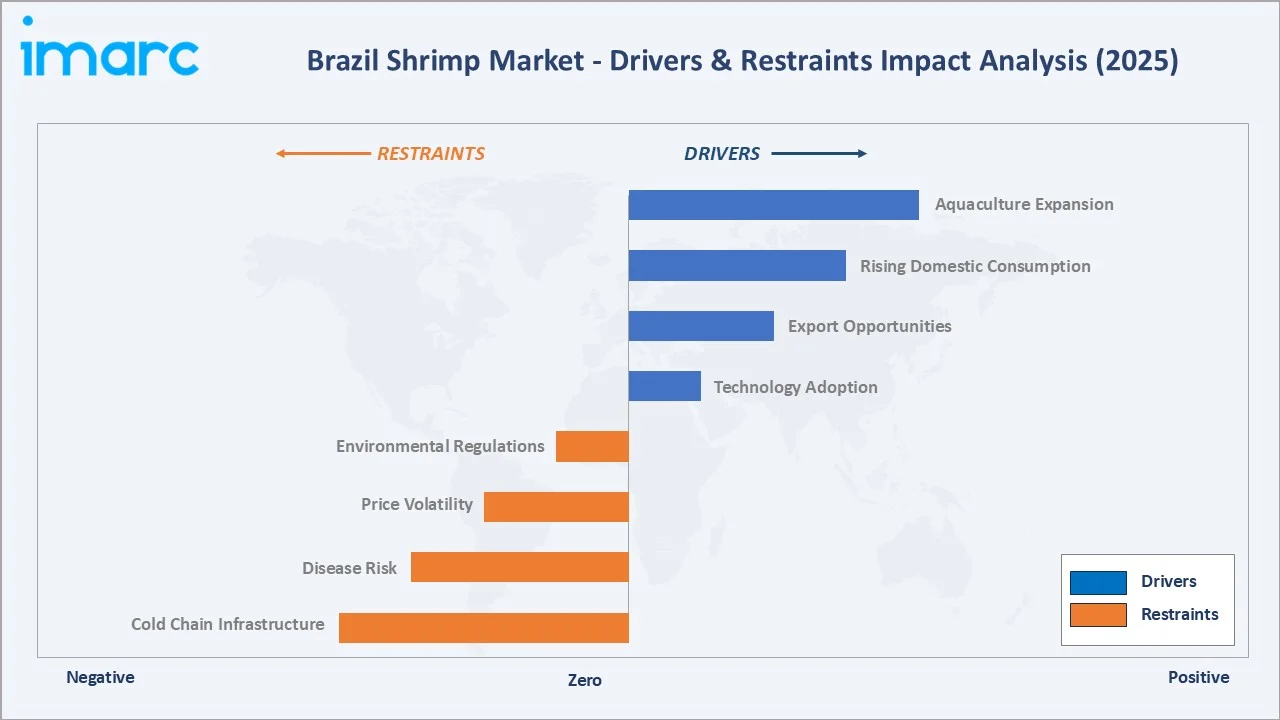
- Aquaculture Expansion – Brazil's aquaculture capacity has expanded significantly, particularly in shrimp farming across the Northeast. Government financing through development banks and rural credit programs has supported pond development, hatchery modernization, and the strengthening of feed supply chains, enabling the sector to scale production and improve operational efficiency.
- Rising Domestic Consumption – Per capita shrimp consumption in Brazil has grown steadily, supported by rising middle-class incomes and greater availability of affordable farmed shrimp in mainstream supermarket chains. Urban populations in major cities like São Paulo and Rio de Janeiro account for a significant share of national seafood demand.
- Export Opportunities – International demand for certified Brazilian shrimp is rising, particularly in European and US markets seeking diversified supply sources beyond Southeast Asia. Brazilian shrimp exports are increasing, with further growth potential dependent on the expansion of certification and compliance standards.
- Technology Adoption – Biofloc technology and semi-intensive farming techniques have improved yield rates on farms adopting these methods, reducing mortality and enhancing feed conversion efficiency across Northeast operations.
Market Restraints
- Cold Chain Infrastructure Gaps – Outside major metropolitan areas and coastal production zones, cold chain infrastructure remains underdeveloped. Post-harvest losses in inland distribution corridors continue to weigh on market efficiency and reduce producer margins across the supply chain.
- Disease Risk in Aquaculture – Viral diseases such as White Spot Syndrome Virus (WSSV) and Early Mortality Syndrome (EMS) periodically affect farm yields. While Brazilian farms have implemented biosecurity protocols, disease-related losses remain a material risk factor.
- Raw Material Price Volatility – Fishmeal, a key input for shrimp feed, experienced price volatility due to global supply disruptions, compressing farm-level margins and discouraging expansion among smaller producers.
- Environmental Regulatory Compliance – Increasing regulatory scrutiny on water use, effluent management, and coastal land use creates compliance costs for aquaculture operators, particularly for new farm licensing in ecologically sensitive coastal zones.
Market Opportunities
- Export Certification Scale-Up – A relatively small share of Brazilian shrimp farms currently holds internationally recognized certifications such as ASC and BAP. Expanding certification across the Northeast’s production base could unlock access to premium retail channels in Europe, enabling price premiums and accelerating export revenue growth.
- Online Sales Channel Development – With online seafood sales still representing a relatively small share of overall distribution, there is substantial room for growth. E-commerce platforms and direct-to-consumer models are gaining traction in São Paulo, supported by the rapid development of last-mile cold chain delivery infrastructure.
- Value-Added Product Innovation – Consumer interest in ready-to-cook and marinated shrimp products is rising. Value-added formats command higher price premiums over commodity frozen shrimp, offering processors and retailers a strong opportunity to enhance margins.
Market Challenges
- Skilled Labor Availability – Modern aquaculture and processing operations require trained technicians in biosecurity, water quality management, and food safety. Skilled labor shortages in rural Northeast Brazil limit the pace at which farms can adopt advanced production practices.
- Infrastructure in Production Regions – Road quality, electricity reliability, and logistics connectivity in key shrimp-producing municipalities of Ceará, RN, and Pernambuco remain constraints for efficient product movement to consumption centers.
- Competition from Asian Imports – Brazilian domestic processors face price competition from lower-cost frozen shrimp imports from Ecuador and India, particularly in price-sensitive modern trade channels where shelf pricing is a primary purchase driver.
Emerging Brazil Shrimp Market Trends
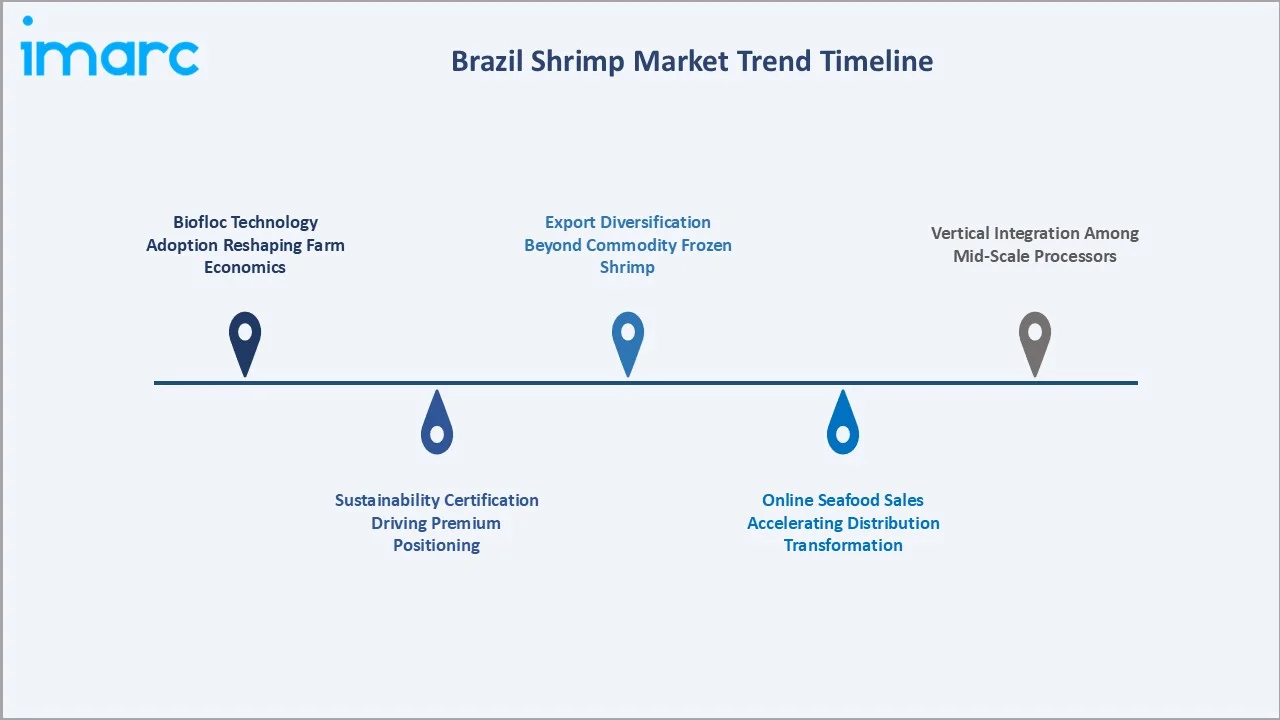
Trend 1: Biofloc Technology Adoption Reshaping Farm Economics
Biofloc technology (BFT) is gaining rapid traction across commercial shrimp farms in Brazil, offering a pathway to high-density production with minimal water exchange. Farms adopting BFT have reported significant productivity improvements compared to traditional semi-intensive systems, while also reducing disease risks through better microbial management. Adoption is steadily increasing, particularly across key Northeast farming regions.
Trend 2: Sustainability Certification Driving Premium Positioning
Sustainability certification programs are increasingly influencing buyer purchasing decisions in both domestic and export markets. Certified producers in Brazil command price premiums in international markets, and industry stakeholders expect certified farm area to expand significantly, driven by retailer mandates for traceable and responsibly sourced seafood.
Trend 3: Online Seafood Sales Accelerating Distribution Transformation
Online sales are the fastest-growing channel, with projected CAGR of approximately 5.8% through 2034. Major e-commerce platforms and dedicated seafood delivery services are expanding cold chain last-mile capabilities in São Paulo, Rio de Janeiro, and Belo Horizonte. This shift is drawing younger urban consumers who prioritize convenience and supply transparency over traditional retail formats.
Trend 4: Export Diversification Beyond Commodity Frozen Shrimp
Brazilian shrimp exporters are moving up the value chain, increasingly supplying headless, shell-on (HLSO) and individually quick frozen (IQF) peeled products instead of commodity whole frozen shrimp. Value-added exports generate higher revenue per kilogram and are better positioned for premium retail placement in European supermarkets. Improvements in export logistics have also reduced transit times, supporting this shift toward higher-value products.
Trend 5: Vertical Integration Among Mid-Scale Processors
Mid-sized shrimp processors are increasingly pursuing vertical integration by establishing or acquiring hatcheries, feed production capabilities, and direct distribution channels. This approach helps reduce input cost volatility and enhances quality control. The consolidation trend is expected to accelerate, with a handful of mid-scale producers likely emerging as regional leaders with significant control over national processing capacity.
Industry Value Chain Analysis
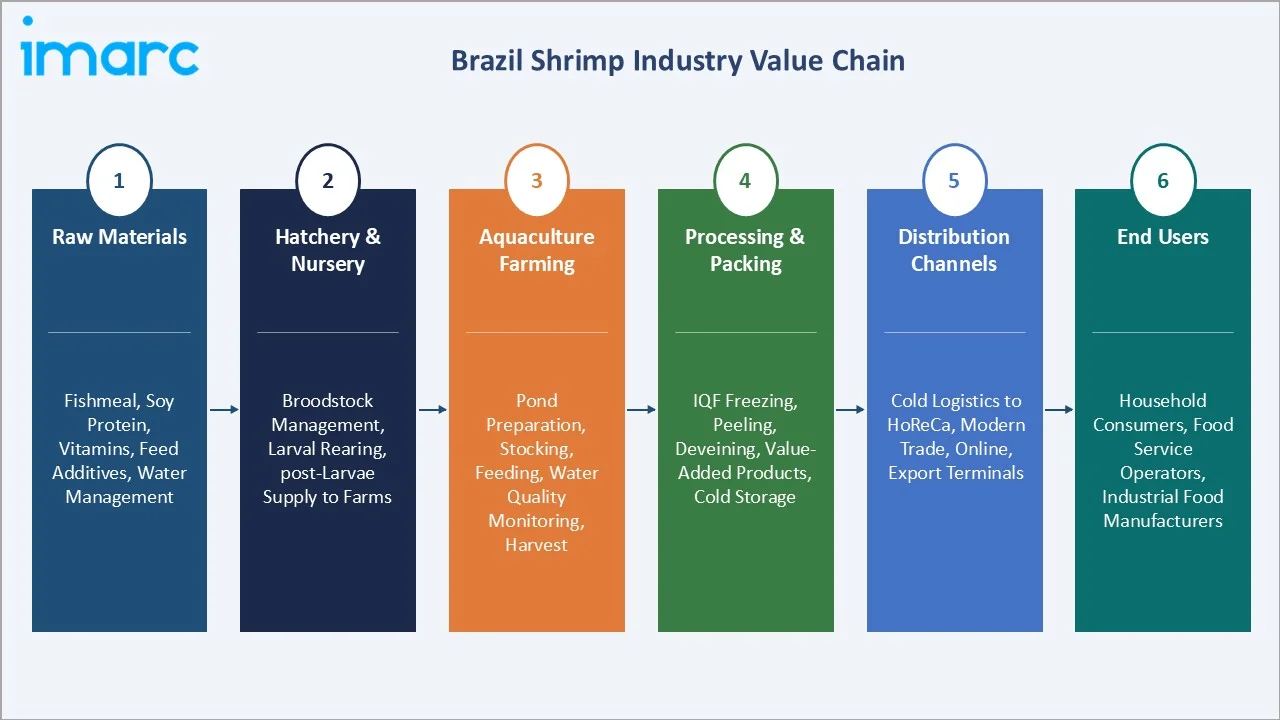
The Brazil shrimp industry value chain spans six interconnected stages – from raw material sourcing to end-user consumption – with multiple opportunities for value creation and efficiency improvement at each node.
|
Stage |
Key Activities |
|
Raw Materials |
Fishmeal, soy protein, vitamins, feed additives, water management |
|
Hatchery & Nursery |
Broodstock management, larval rearing, post-larvae supply to grow-out farms |
|
Aquaculture Farming |
Pond preparation, stocking, feeding, water quality monitoring, harvest |
|
Processing & Packaging |
IQF freezing, peeling, deveining, value-added product creation, cold storage |
|
Distribution Channels |
Cold logistics to HoReCa, modern trade, online, and export terminals |
|
End Users |
Household consumers, food service operators, industrial food manufacturers, export buyers |
The diagram below illustrates the linear flow of the Brazil shrimp industry value chain, from raw inputs through to end consumption.
Technology Landscape in the Brazil Shrimp Industry
Aquaculture Technology Innovations
Brazilian shrimp farming is transitioning from conventional extensive and semi-intensive systems to technology-enhanced production models. Biofloc technology (BFT) enables stocking densities of 150–300 shrimp per square meter – three to five times higher than conventional ponds – while maintaining water quality through controlled microbial communities. Recirculating aquaculture systems (RAS) are being piloted for indoor, year-round production near urban consumption centers in the South and Southeast, reducing transport costs and enabling premium freshness positioning.
Feed Technology and Nutrition Science
Feed costs represent a significant share of total shrimp production expenses in Brazil. Advances in functional feed formulations—incorporating immunostimulants, probiotics, and organic acids—are helping reduce antibiotic dependence and improve survival rates. At the same time, the introduction of low-fishmeal and alternative protein feeds, including insect-based inputs, is addressing raw material cost volatility while aligning with sustainability standards required by international certification bodies.
Digital Monitoring and Smart Farm Management
IoT-enabled sensor arrays for real-time water quality monitoring (dissolved oxygen, pH, salinity, temperature) are gaining commercial adoption on mid-scale farms. Remote monitoring platforms help reduce labor costs and enable faster response to environmental stress events that can lead to mortality. In parallel, larger operators are integrating machine learning–based predictive feeding systems, improving feed conversion efficiency compared to manual feeding practices.
Brazil Shrimp Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Environment | Farmed Shrimp | 71.6% | 2025 |
| Species | 🔒 | 🔒 | 2025 |
| Shrimp Size | 🔒 | 🔒 | 2025 |
| Distribution Channel | Hotels and Restaurants | 34.5% | 2025 |
| Region | Southeast | 44.2% | 2025 |

By Distribution Channel
To access detailed market analysis, Request Sample
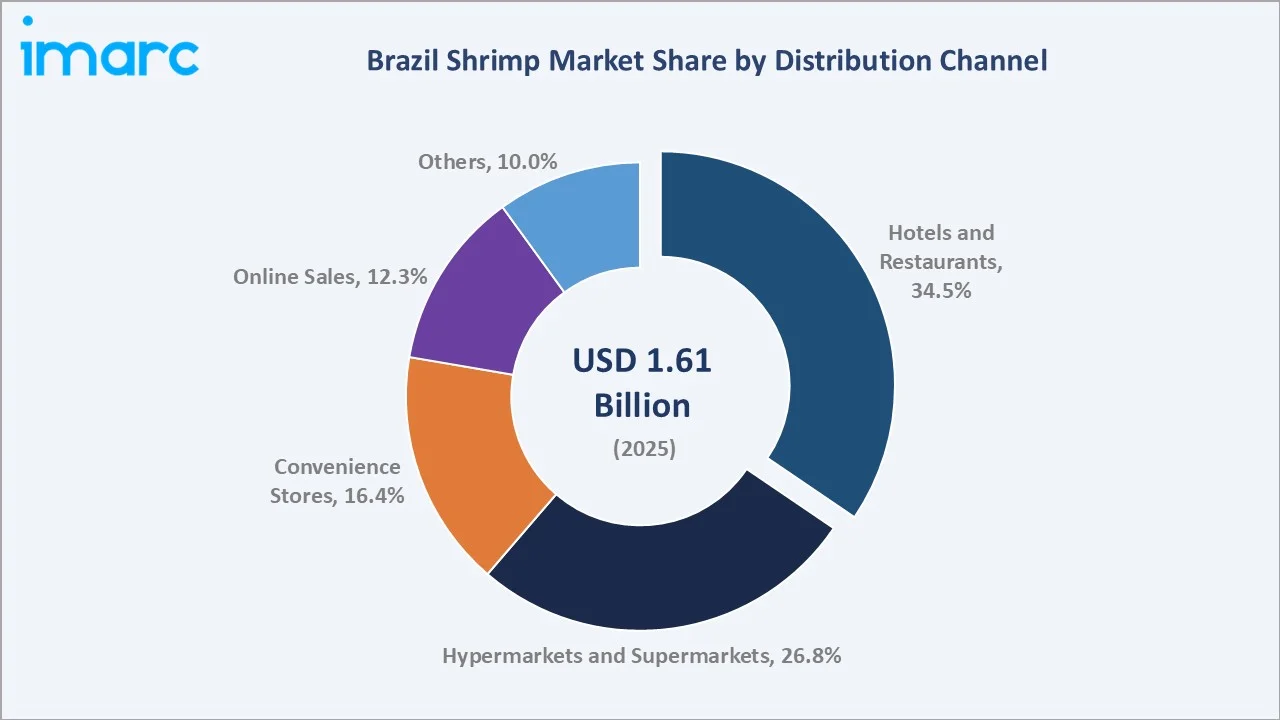
Hotels and Restaurants lead at 34.5%, reflecting the strategic importance of food service in shrimp demand. Brazilian coastal cuisine – particularly in the Northeast and Southeast – positions shrimp as a premium ingredient in botequins, churrascarias, and fine dining establishments.
By Environment
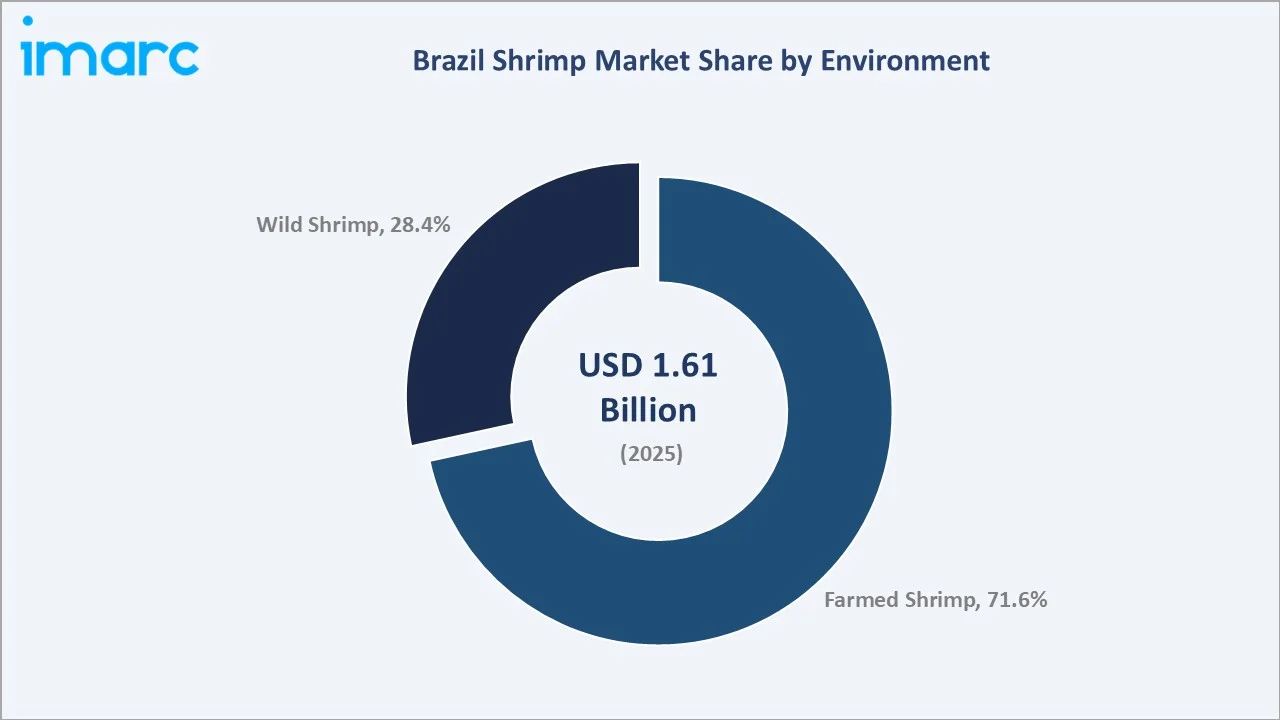
Farmed shrimp's 71.6% dominance reflects decades of aquaculture investment in Brazil's Northeast coast. Wild shrimp retains a premium positioning in specialty markets and traditional fishing communities, particularly in Amazonian River systems where Macrobrachium species are harvested.
Regional Market Insights
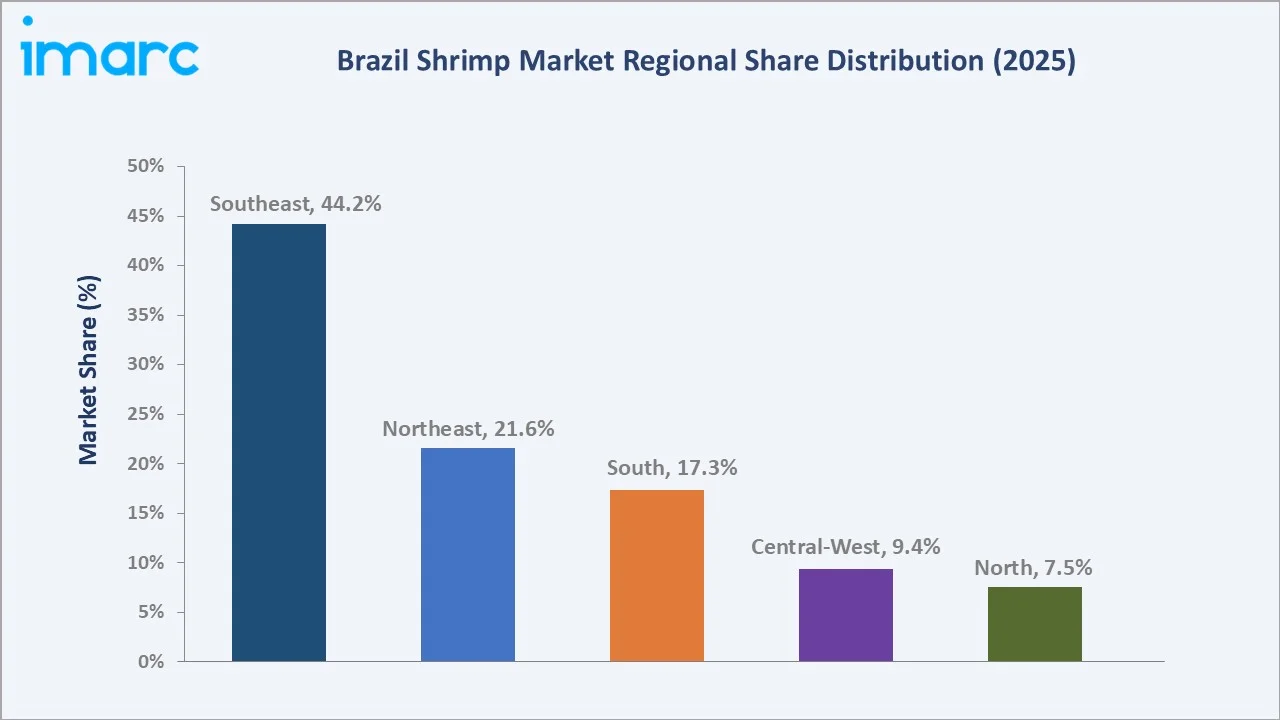
Brazil's shrimp market is characterized by a pronounced regional divide between production-dominant Northeast states and consumption-driven Southeast urban markets. The five administrative regions represent distinct market profiles:
|
Region |
Share (2025) |
Key Growth Drivers |
Regulatory Impact |
|
Southeast |
44.2% |
São Paulo & Rio de Janeiro urban consumption; modern trade expansion; cold chain maturity |
MAPA food safety standards; retail labeling compliance |
|
Northeast |
21.6% |
Primary production hub; aquaculture expansion; export logistics via Fortaleza/Natal ports |
IBAMA fishing regulations; ABCC biosecurity protocols |
|
South |
17.3% |
High per capita income; premium seafood demand; restaurant culture in Florianopolis/Curitiba |
State environmental permits; cold storage licensing |
|
Central-West |
9.4% |
Urbanization of Brasilia/Goiania; growing modern trade; emerging middle class demand |
Federal procurement standards |
|
North |
7.5% |
Amazonian wild shrimp; Macrobrachium rosenbergii harvest; traditional communities |
Fishing quotas; IBAMA biodiversity regulations |
The Southeast's 44.2% share is underpinned by population concentration combined with high disposable income levels and a well-developed cold chain network.
Competitive Landscape
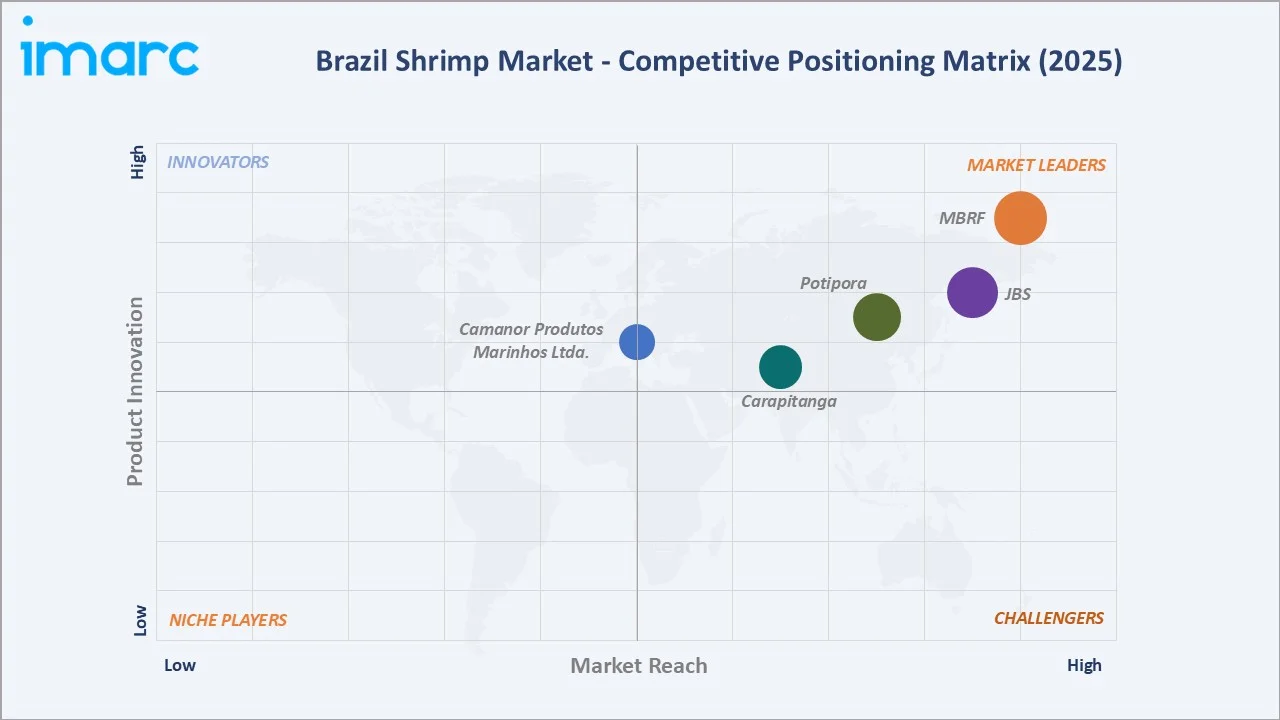
The Brazil shrimp market competitive landscape is characterized by a mix of large-scale integrated food companies, mid-sized regional processors, and artisanal producer cooperatives.
|
Company |
Brand / Business Unit |
Market Position |
Competitive Strength |
|
MBRF |
Sadia, Perdigão |
Leader |
National distribution, brand equity, integrated cold chain |
|
JBS |
Seara |
Leader |
JBS group scale, retail penetration, R&D investment |
|
Camanor Produtos Marinhos Ltda. |
Camanor |
Leader |
Proprietary AquaScience closed-system technology; 40% strategic stake held by Charoen Pokphand Foods (Thailand), providing access to global genetics and feed R&D |
|
Carapitanga |
Carapitanga |
Leader |
Large-scale Northeast farm operations, domestic retail channel expansion |
|
Potipora |
Potipora |
Challenger |
Full chain vertical integration (post-larvae to shelf), in-house feed production |
The competitive positioning matrix below maps key players based on market presence (geographic reach) and product innovation capability, identifying Leaders, Challengers, Established, and Niche quadrant positions.
Key Company Profiles
MBRF
MBRF Global Foods Company is a leading Brazilian multinational food company formed through the merger of two major players including BRF and Marfrig. The merger was completed in 2025, creating one of the world’s largest multi-protein food platforms.
- Product Portfolio: Frozen shrimp, peeled & deveined formats, marinated shrimp skewers, ready-to-cook shrimp products. National distribution via an extensive cold chain spanning all five Brazilian regions.
- Recent Developments: In 2025, BRF and Marfrig officially merged on September 22, 2025, forming MBRF Global Foods, with shares trading under ticker MBRF3 from September 23. With its vast cold-chain and multi-protein distribution network, MBRF is well-positioned to strengthen its shrimp sourcing and seafood portfolio across global markets.
- Strategic Focus: Multi-protein platform diversification; synergy capture from the BRF–Marfrig merger; brand-driven premium positioning under Sadia and Perdigão; deepening export footprint across MENA, Asia, and GCC markets.
JBS
JBS is the world's largest animal protein company and one of the largest food companies globally. The company employs more than 280,000 people , with products reaching consumers daily through brands including Friboi, Seara, Pilgrim's Pride, and Others.
- Product Portfolio: Through the Seara brand, JBS offers a frozen seafood range in the Brazilian market comprising four shrimp SKUs, tilapia fillets, salmon steaks, salmon chunks, squid rings, mussels, and a paella kit. JBS leveraged Seara's full national logistics and sales structure to distribute certified seafood products across Brazil, combining quality, innovation, and sustainability under the Seara brand identity.
- Recent Developments: In 2023, JBS inaugurated two new automated plants at its industrial complex in Rolândia, Paraná, as part of its value-added food expansion strategy. The facilities will support Seara’s growth. The site is among the company’s most modern in Brazil and supports its broader USD 1.6 billion investment plan aimed at expanding production capacity, improving automation, and increasing focus on higher-value processed food products.
- Strategic Focus: Multi-protein and multi-geography diversification as a structural buffer against single-category volatility; accelerating growth in higher-value processed and prepared food segments under Seara domestically.
Camanor Produtos Marinhos Ltda
Camanor Produtos Marinhos Ltda. is a Brazilian aquaculture company specializing in sustainable shrimp farming, processing, and commercialization, with a strong focus on the species Litopenaeus vannamei.
- Product Portfolio: Fresh and frozen whole shrimp, headless shrimp, and peeled and deveined shrimp across multiple sizing grades.
- Recent Developments: In 2025, Camanor Produtos Marinhos Ltda is recognized for its integrated and technology-driven aquaculture model. The company operates using its proprietary AquaScience system, a closed and controlled production approach that enables high-density shrimp farming with minimal chemical and antibiotic use, improving both productivity and sustainability.
- Strategic Focus: Vertical integration; certification-driven premium positioning; Northeast production leadership.
Market Concentration Analysis
The Brazil shrimp market exhibits moderate concentration at the processing and distribution level, with more significant fragmentation at the farming stage. The top five companies – MBRF, JBS, Camanor Produtos Marinhos Ltda., Carapitanga, Potipora– collectively account for an estimated 35–40% of national processed shrimp volume in 2025.
At the aquaculture farming level, fragmentation is significant. Brazil’s Northeast hosts thousands of shrimp farms, with most operating at small scales. These producers generally rely on cooperatives or regional processors for sales rather than directly accessing modern retail or export markets.
Consolidation trends are accelerating. Larger processors are acquiring mid-scale farms to secure supply, while well-capitalized exporters are building processing capabilities to capture more value before shipment. This vertical integration trend is expected to gradually increase market concentration over the coming years. However, the farming segment is likely to remain fragmented, supported by government credit programs that continue to favor small and medium-scale producers.
Investment & Growth Opportunities
Fastest-Growing Segments
- Online Sales Channel – CAGR of ~5.8% (2026–2034); investment in B2C cold chain e-commerce infrastructure in Southeast Brazil presents a compelling opportunity for digital-first seafood retailers and logistics providers.
- Farmed Premium Shrimp – Certified aquaculture operations targeting European and North American export markets offer 30–50% higher revenue per kilogram than commodity frozen product, making certification investment highly accretive.
- Value-Added Processing – Ready-to-cook, marinated, and IQF peeled shrimp formats command higher price realization than commodity whole frozen shrimp, offering processors significant margin improvement potential.
Emerging Markets & Geographies
- Central-West Brazil (9.4% share in 2025) – Urbanization in Brasilia, Goiania, and Campo Grande is creating new middle-class seafood demand centers. Cold chain investment targeting these inland cities represents a logistics-driven growth opportunity.
- Export to MENA and Asian Markets – Beyond established European and US export lanes, Brazil's certified shrimp is beginning to attract buyers from Saudi Arabia, UAE, Japan, and South Korea who seek reliable, halal-certified or quality-certified alternatives to dominant Southeast Asian sources.
Venture Investment Trends
- Aquaculture Technology Startups – IoT-based water monitoring, AI-driven feeding systems, and biofloc management platforms are gaining strong traction within Brazil’s agritech ecosystem. These technologies are attracting venture capital interest, with farm management startups securing early-stage funding to scale digital solutions for aquaculture efficiency, productivity, and sustainability.
- Vertical RAS Facilities – Recirculating aquaculture system projects near urban consumption centers (São Paulo, Rio de Janeiro) are attracting investor attention, offering year-round production, superior product freshness, and reduced transport costs versus Northeast-produced frozen shrimp.
Future Market Outlook (2026-2034)
The Brazil shrimp market forecast projects steady and sustainable growth, with total market value expanding from USD 1.61 Billion in 2025 to USD 1.67 Billion in 2026, reaching USD 2.24 Billion by 2034, registering a CAGR of 3.72% during 2026–2034. The market is expected to cross the USD 1.94 Billion mark by 2030, representing a critical inflection point as export revenues contribute more meaningfully to total market value.
Technological disruption will reshape competitive dynamics across the forecast horizon. Biofloc and RAS adoption will accelerate yield improvements at leading farms, while AI-driven farm management platforms reduce operational costs. Digital transformation in distribution – particularly the scaling of cold chain e-commerce, fundamentally altering channel economics for processors and retailers.
Industry transformation will be further driven by sustainability imperatives. Mandatory sustainability reporting for listed food companies, growing retailer sustainability mandates, and rising consumer preference for certified traceable seafood will raise the bar for market participation. Companies that invest early in certification, technology, and export market relationships are best positioned to capture premium market share and drive margin expansion through the 2026–2034 period.
Research Methodology
Primary Research
IMARC Group conducts in-depth primary research through structured interviews with industry stakeholders including shrimp farm operators, processing plant managers, aquaculture technology providers, export traders, retail category managers, and government officials from MAPA and ABCC. These interviews capture qualitative market intelligence on pricing trends, supply chain dynamics, technology adoption, and strategic priorities not captured in secondary sources.
Secondary Research
Secondary research encompasses a comprehensive review of authoritative data sources including: Brazilian government statistical agencies (IBGE, MAPA, MDIC), ABCC industry association reports, FAO Fisheries and Aquaculture data, trade publications (Seafood International, Undercurrent News), company annual reports and financial filings, academic and institutional research from Embrapa Pesca and LABOMAR (UFC), and patent databases for aquaculture technology innovation tracking.
Forecasting Models
Market sizing and forecasting employs a combination of bottom-up and top-down methodologies. The bottom-up approach aggregates production data by region, species, and farm type, calibrated against processing capacity utilization and cold chain throughput data. The top-down model aligns national market estimates with macroeconomic variables including GDP growth, consumer price indices for food, household income trends, and export trade flow data from MDIC (Ministry of Development, Industry, Commerce and Services). Final forecasts are validated through triangulation with primary research inputs and cross-referenced against comparable market forecasts from FAO and peer research institutions.
Brazil Shrimp Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Environments Covered | Farmed Shrimp, Wild Shrimp |
| Species Covered | Penaeus Vannamei, Penaeus Monodon, Macrobrachium Rosenbergii, Others |
| Shrimp Sizes Covered | <21, 21-25, 26-30, 31-40, 41-50, 51-60, 61-70, >70 |
| Distribution Channels Covered | Hypermarkets and Supermarkets, Convenience Stores, Hotels and Restaurants, Online Sales, Others |
| Regions Covered | Southeast, South, Northeast, North, Central-West |
| Companies Covered | MBRF, JBS, Camanor Produtos Marinhos Ltda., Carapitanga, Potipora, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Brazil shrimp market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Brazil shrimp market.
- Porter's Five Forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Brazil shrimp industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Brazil Shrimp Market Report
The Brazil shrimp market size is estimated at USD 1.67 Billion in 2026, growing at a CAGR of 3.72%.
The market is projected to grow at a CAGR of 3.72% during the forecast period of 2026 to 2034.
The Southeast region holds the largest share at 44.2% in 2025, driven by urban consumption centers in Sao Paulo and Rio de Janeiro with mature cold chain infrastructure.
Farmed shrimp dominates with 71.6% of the market in 2025, primarily Penaeus vannamei species farmed across Northeast Brazilian coastal states.
Hotels and Restaurants lead at 34.5% in 2025, followed by Hypermarkets and Supermarkets at 26.8%, reflecting shrimp's strong role in Brazilian food service.
Key drivers include aquaculture expansion, rising domestic consumption, growing export opportunities in Europe and North America, and adoption of biofloc and advanced farming technologies.
Leading companies include MBRF, JBS, Camanor Produtos Marinhos Ltda., Carapitanga, and Potipora.
Key challenges include cold chain gaps in inland regions, disease risk in aquaculture operations, raw material price volatility for shrimp feed, and competition from lower-cost Asian imports.
Online sales at 12.3% in 2025 represent the fastest-growing channel, projected to reach a CAGR of approximately 5.8% through 2034 as cold chain e-commerce expands.
Farmed shrimp commands 71.6% of the USD 1.61 Billion Brazil shrimp market in 2025, representing approximately USD 1.15 Billion in farmed production value.
Brazil is an emerging shrimp exporter. Export growth is driven by sustainable aquaculture certifications and competitive currency exchange rates.
The Brazil shrimp market is projected to reach USD 1.94 Billion by 2030, serving as a midpoint milestone in the 2026 to 2034 growth trajectory.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade