Electric Vehicle Aftermarket Size, Share, Trends and Forecast by Replacement Part, Propulsion Type, Vehicle Type, Certification, Distribution Channel, and Region, 2026-2034
Electric Vehicle Aftermarket Size, Share, Trends & Forecast (2026-2034)
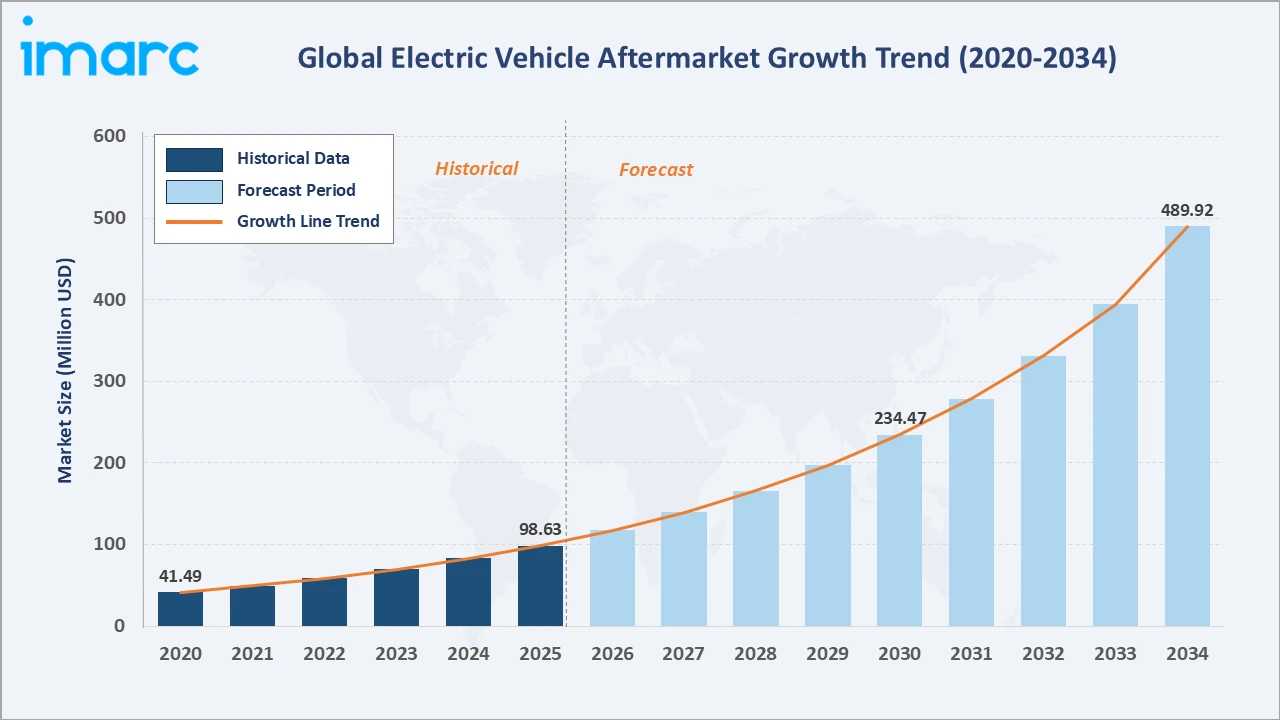
The electric vehicle aftermarket grew from USD 98.63 Million in 2025 to USD 117.28 Million in 2026 and is projected to reach USD 489.92 Million by 2034, exhibiting a CAGR of 18.91% during 2026-2034. Rapid expansion of the global electric vehicle fleet, increasing average vehicle age, and rising consumer preference for cost-effective third-party maintenance solutions are the primary forces shaping market growth.
Tire leads the replacement part segment at 28.7%, passenger cars dominate the vehicle type segment at 78.9%, and North America commands 35.2% of regional share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 98.63 Million |
|
Market Size (2026) |
USD 117.28 Million |
|
Forecast Market Size (2034) |
USD 489.92 Million |
|
CAGR (2026-2034) |
18.91% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Largest Region |
North America (35.2%, 2025) |
|
Second Largest Region |
Asia-Pacific (29.4%, 2025) |
|
Leading Replacement Part |
Tire (28.7%, 2025) |
|
Leading Vehicle Type |
Passenger Cars (78.9%, 2025) |
The electric vehicle aftermarket size increased from USD 41.49 Million in 2020 to USD 98.63 Million in 2025 and is estimated to reach USD 117.28 Million in 2026. The market is further expected to grow to USD 234.47 Million by 2030 and USD 489.92 Million by 2034. The market is commercially distinctive among global automotive aftermarket segments, underpinned by one of the fastest-growing electric vehicle fleets worldwide and a rapidly expanding organized aftermarket service sector.
To get more information on this market, Request Sample
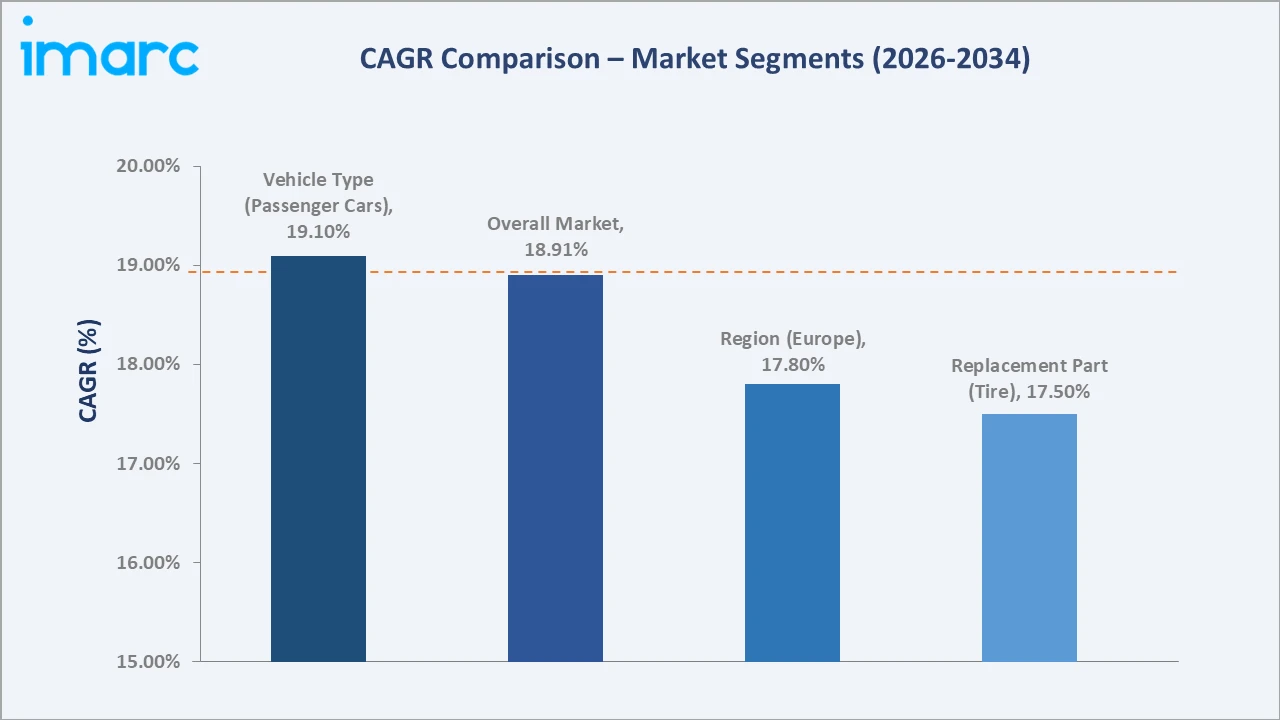
CAGR trajectories across replacement part, vehicle type, and regional sub-segments show battery and Asia-Pacific expanding faster than the overall 18.91% market CAGR, driven by the accelerating transition to electric mobility, expanding EV charging infrastructure, and increasing consumer investment in vehicle maintenance.
Executive Summary
The electric vehicle aftermarket expanded from USD 98.63 Million in 2025 to an estimated USD 117.28 Million in 2026, positioning it among the fastest-growing vehicle aftermarket segments globally. The market's scale is underpinned by the rapidly expanding global electric vehicle fleet, increasing consumer demand for affordable maintenance solutions, and rising investment in specialized EV service infrastructure.
Tire commands 28.7% replacement part share, reflecting its high wear rate and frequent replacement cycle in electric vehicles. Passenger cars represent 78.9% of the vehicle type segment, driven by the widespread consumer adoption of electric passenger vehicles and the expanding fleet requiring regular aftermarket services. North America leads regional share at 35.2%, anchored by the United States' strong EV adoption rates and well-developed automotive aftermarket ecosystem.
Key Market Insights
|
Insight |
Data |
|
Leading Replacement Part |
Tire – 28.7% share (2025) |
|
Second Largest Replacement Part |
Battery – 18.6% share (2025) |
|
Leading Vehicle Type |
Passenger Cars – 78.9% share (2025) |
|
Second Largest Vehicle Type |
Commercial Vehicles – 21.1% share (2025) |
|
Leading Region |
North America – 35.2% share (2025) |
|
Second Largest Region |
Asia-Pacific – 29.4% share (2025) |
|
Top Companies |
Robert Bosch GmbH, LKQ Corporation, AUMOVIO SE, Denso Corporation |
Key Analytical Observations Expanding On the Data Above:
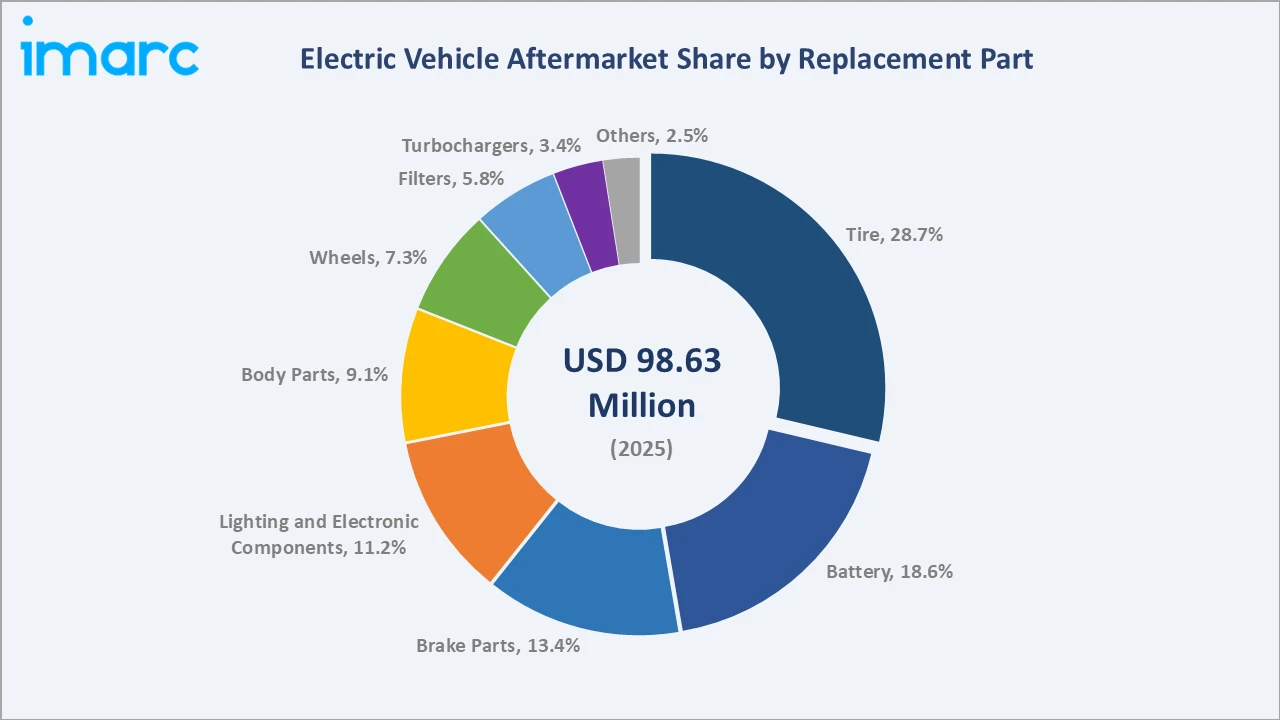
- Tire dominance at 28.7% reflects its lower capital requirement and operational readiness at current market scale, making it the preferred aftermarket category across global EV owner segments.
- Battery share at 18.6% is growing as the installed base of aging electric vehicles expands, driving demand for battery pack replacements and performance restoration services across consumer and fleet segments.
- Passenger cars leadership at 78.9% is driven by widespread consumer adoption of electric passenger vehicles globally, generating substantial demand for replacement parts, maintenance services, and performance upgrades.
- Commercial vehicles share at 21.1% is expanding as fleet operators increasingly adopt electric commercial vehicles, creating demand for specialized aftermarket services, battery maintenance, and component replacements.
- North America at 35.2% leads regional share due to the United States' advanced EV adoption infrastructure, strong consumer spending on vehicle maintenance, and well-established automotive aftermarket distribution networks.
Electric Vehicle Aftermarket Overview
The electric vehicle aftermarket encompasses the supply, distribution, and installation of replacement parts, accessories, and services for electric vehicles beyond the OEM's warranty period.
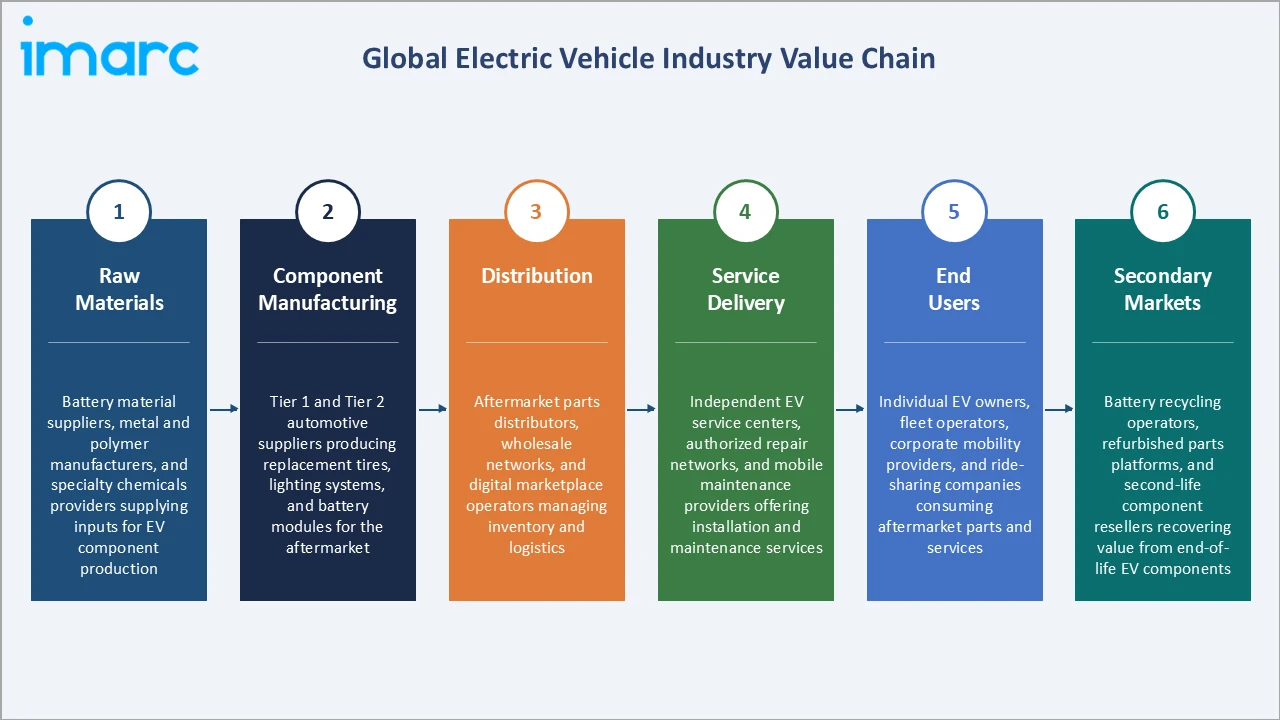
The global ecosystem integrates raw material suppliers, component manufacturers, third-party parts distributors, specialized EV service providers, digital marketplace operators, and end users. Government policies promoting EV adoption, expanding public charging infrastructure, and the increasing availability of affordable aftermarket components are collectively shaping a rapidly evolving market landscape that is attracting investment from both traditional automotive aftermarket companies and new EV-focused entrants.
Market Dynamics
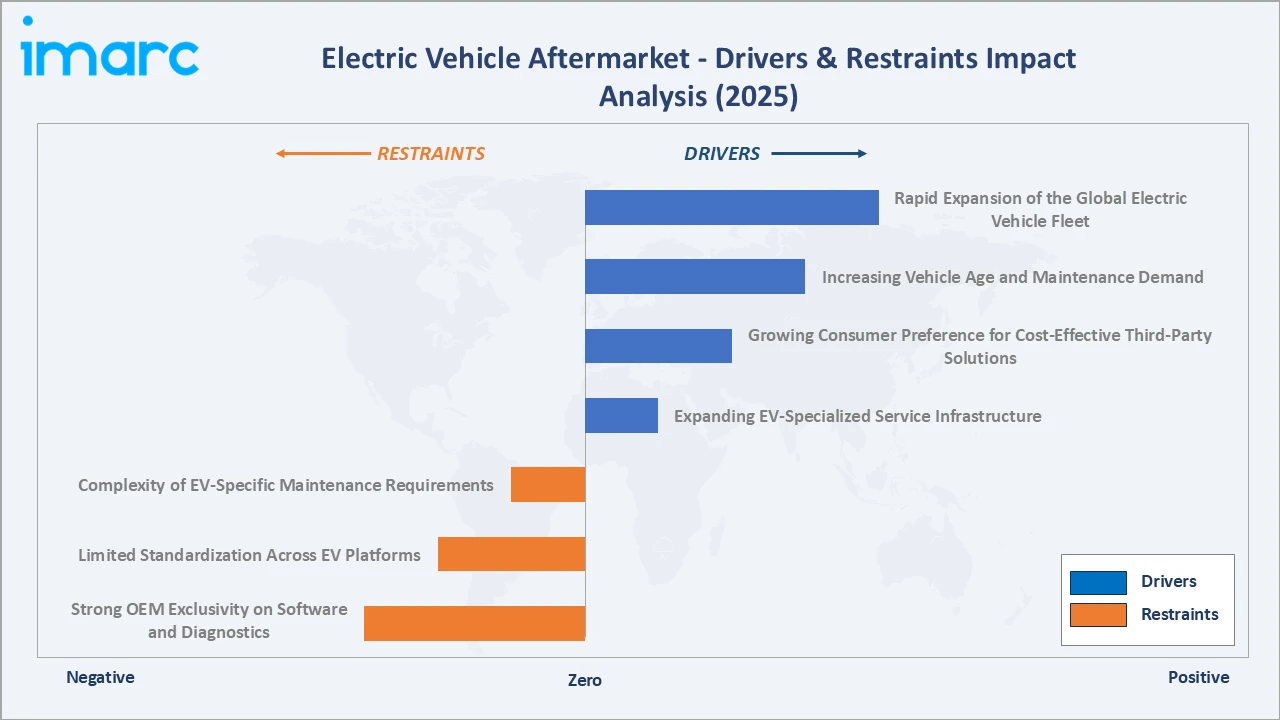
To evaluate market opportunities, Request Sample
Market Drivers
- Rapid Expansion of the Global Electric Vehicle Fleet: As per IMARC Group, the global electric vehicle market size was valued at USD 917.3 Billion in 2025. The electric vehicle fleet is growing substantially, driven by supportive government policies, declining battery costs, and increasing consumer awareness of environmental benefits. This expanding fleet directly enlarges the electric vehicle aftermarket market opportunity across all replacement part and service segments, as more vehicles require maintenance, component replacements, and performance upgrades.
- Increasing Vehicle Age and Maintenance Demand: As early-adopter electric vehicles age beyond their warranty periods, demand for third-party aftermarket components, battery replacements, and specialized maintenance services is accelerating. Aging fleets create substantial pull for replacement parts including tires, brake components, and lighting systems, benefiting aftermarket suppliers and service providers.
- Growing Consumer Preference for Cost-Effective Third-Party Solutions: Consumers are increasingly turning to independent aftermarket providers for vehicle maintenance and repair, seeking more affordable alternatives to authorized dealer service networks.
- Expanding EV-Specialized Service Infrastructure: The rapid build-out of specialized EV service centers, diagnostic tool providers, and certified technician training programs is removing key barriers to aftermarket adoption. Growing service infrastructure is improving accessibility of quality aftermarket maintenance across urban and suburban markets globally.
Market Restraints
- Complexity of EV-Specific Maintenance Requirements: Electric vehicles require specialized diagnostic tools, high-voltage safety training, and complex battery management expertise that differs substantially from conventional vehicle maintenance. This technical complexity raises the barrier for traditional aftermarket service providers, limiting competitive supply and sustaining above-market service costs for EV owners.
- Limited Standardization Across EV Platforms: The absence of standardized battery formats, connector interfaces, and component specifications across electric vehicle manufacturers complicates the production and distribution of universal aftermarket parts. Fragmented platform architecture increases inventory costs for distributors and limits economies of scale for parts manufacturers, constraining overall market competitiveness.
- Strong OEM Exclusivity on Software and Diagnostics: Leading EV manufacturers maintain proprietary control over vehicle software, diagnostic systems, and battery management protocols, restricting independent service providers from conducting certain maintenance and calibration tasks. This limits the addressable opportunity for independent aftermarket operators in high-value service categories.
Market Opportunities
- Battery Reconditioning and Second-Life Services: Growing volumes of electric vehicles approaching battery end-of-life are creating a substantial opportunity for battery reconditioning, cell balancing, and second-life EV aftermarket solutions. Aftermarket operators capable of extending battery life at lower cost than new replacement packs can capture significant value as the fleet ages.
- Expansion in Emerging EV Markets: Rapidly growing EV adoption in Asia-Pacific, Latin America, and Middle East and Africa is creating greenfield aftermarket opportunities in regions with underdeveloped EV service ecosystems. Aftermarket companies establishing distribution networks ahead of fleet maturation can build durable market positions in these high-growth geographies.
Market Challenges
- Over-the-Air Software Updates Reducing Service Frequency: Increasing use of over-the-air software updates by EV manufacturers enables remote performance optimization and issue resolution without physical intervention, reducing the frequency of certain service visits and limiting aftermarket service touch points for independent operators.
- Supply Chain Disruptions for Specialized EV Components: Aftermarket supply chains for critical EV-specific components, including high-voltage battery cells, power electronics, and specialized semiconductors, remain vulnerable to supply disruptions. Geopolitical tensions, raw material constraints, and concentrated manufacturing expose aftermarket operators to parts availability risk.
Emerging Market Trends
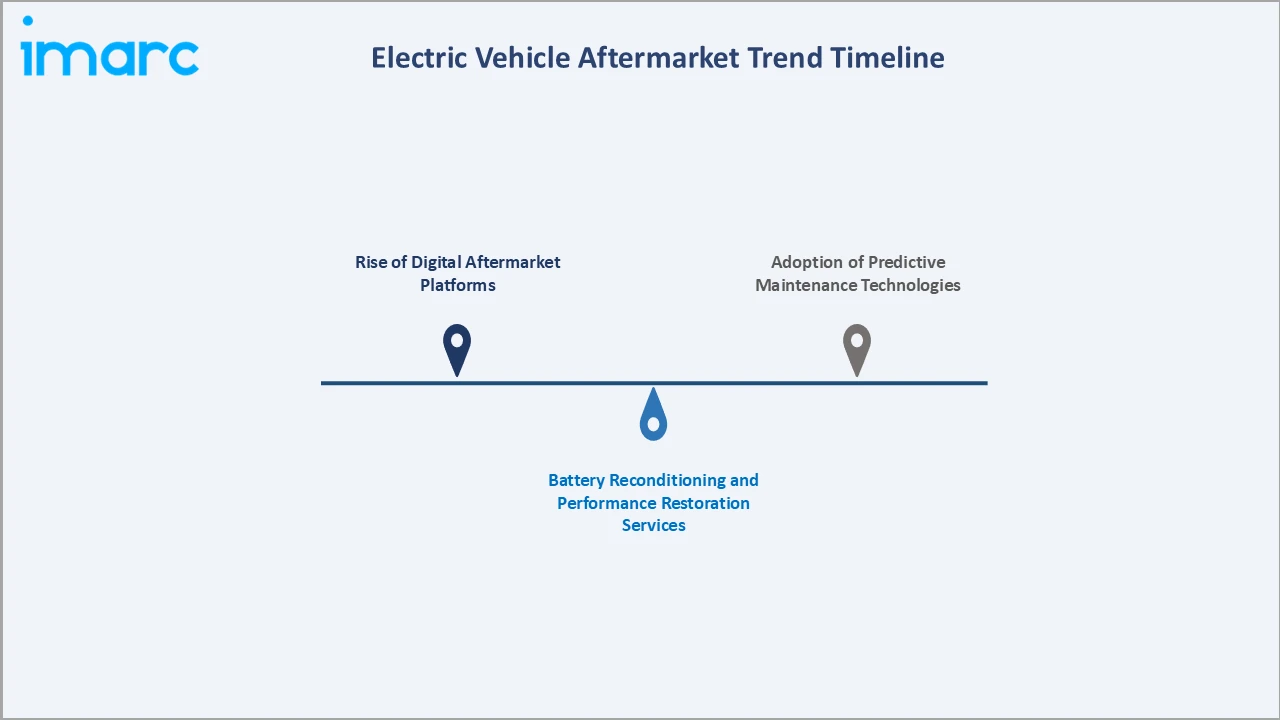
1. Rise of Digital Aftermarket Platforms
Digital platforms connecting consumers, parts suppliers, and certified EV service providers are transforming the distribution and accessibility of services across the electric vehicle aftermarket industry. These platforms enable real-time inventory visibility, competitive pricing, and certified technician matching.
2. Battery Reconditioning and Performance Restoration Services
The growing volume of electric vehicles exceeding their warranty-period battery capacity thresholds is driving demand for professional battery reconditioning, cell replacement, and performance restoration services. Specialized service providers are deploying advanced battery diagnostic and cell-level balancing technologies to extend battery usable life at a fraction of new pack replacement costs, creating a distinct and rapidly expanding service category within the aftermarket ecosystem.
3. Adoption of Predictive Maintenance Technologies
Telematics integration and connected vehicle data platforms are enabling predictive maintenance models that identify component wear and potential failure before service disruption occurs. Aftermarket operators leveraging predictive analytics can schedule proactive replacement of high-wear items including tires, brake components, and thermal management systems, improving customer satisfaction and building recurring service relationships.
Industry Value Chain Analysis
The electric vehicle aftermarket value chain spans six stages, from raw materials and component manufacturing through distribution, service delivery, and end-user consumption. Parts manufacturing and service delivery stages capture the highest value-add, while digital platforms and distribution networks are increasingly determining competitive position across the rapidly evolving aftermarket ecosystem.
| Stage | Key Players / Examples |
|---|---|
| Raw Materials | Battery material suppliers, metal and polymer manufacturers, and specialty chemicals providers supplying inputs for EV component production |
| Component Manufacturing | Tier 1 and Tier 2 automotive suppliers producing replacement tires, brake components, lighting systems, and battery modules for the aftermarket |
| Distribution | Aftermarket parts distributors, wholesale networks, and digital marketplace operators managing inventory and logistics across regional and national markets |
| Service Delivery | Independent EV service centers, authorized repair networks, and mobile maintenance providers offering installation, diagnostics, and maintenance services |
| End Users | Individual EV owners, fleet operators, corporate mobility providers, and ride-sharing companies consuming aftermarket parts and services |
| Secondary Markets | Battery recycling operators, refurbished parts platforms, and second-life component resellers recovering value from end-of-life EV components |
Vertically integrated operators controlling parts distribution, service delivery, and secondary market recovery are positioned to capture greater margin than single-stage operators dependent on spot parts supply and commodity buyers.
Technology Landscape in the Electric Vehicle Aftermarket Industry
Battery Technology
Advancements in lithium-ion battery chemistry, cell replacement techniques, and battery management system calibration are enabling aftermarket operators to extend battery life, restore performance, and reduce total cost of ownership for EV consumers beyond the warranty period.
Materials Innovation
EV-specific tire compounds designed to handle the high torque and vehicle weight characteristics of electric vehicles are entering the aftermarket, while advanced composite materials are improving brake component longevity in regenerative braking systems.
Smart Connectivity
Telematics integration and electric vehicle aftermarket software platforms are enabling remote diagnostics, predictive maintenance scheduling, and over-the-air service monitoring. Aftermarket service providers leveraging real-time component data can offer proactive maintenance, improving customer outcomes and service efficiency.
Automation
Automated diagnostic tools and robotic disassembly systems are being adopted in high-volume aftermarket service operations for battery swap, tire service, and predictive inspection processes. Automation improves throughput consistency, reduces labor costs, and enhances technician safety in high-voltage EV maintenance environments.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Replacement Part | Tire | 28.7% | 2025 |
| Propulsion Type | 🔒 | 🔒 | 2025 |
| Vehicle Type | Passenger Cars | 78.9% | 2025 |
| Certification | Genuine Parts | 46.2% | 2025 |
| Distribution Channel | Authorized Service Centers (OEMs) | 37.1% | 2025 |
| Region | North America | 35.2% | 2025 |

By Replacement Part
Tire commands a 28.7% majority share in 2025, driven by the high torque and vehicle weight characteristics of electric vehicles that accelerate tire wear relative to conventional vehicles. Tire replacement remains one of the most frequent aftermarket service needs for EV owners, generating recurring demand across consumer and fleet segments globally.
To access detailed market analysis, Request Sample
Battery at 18.6% is the second-largest replacement part segment, supported by the growing volume of electric vehicles exceeding warranty-period battery performance thresholds. As fleet age increases, demand for battery pack replacements and cell-level reconditioning services is expanding, positioning battery as the fastest-growing segment within the replacement part category.
By Vehicle Type
Passenger cars represent 78.9% of the vehicle type segment in 2025, directly reflecting the consumer-driven expansion of the global electric passenger vehicle fleet. Widespread adoption of electric cars across major markets including the United States, China, and Europe is generating substantial and growing demand for aftermarket replacement parts, maintenance services, and performance accessories.
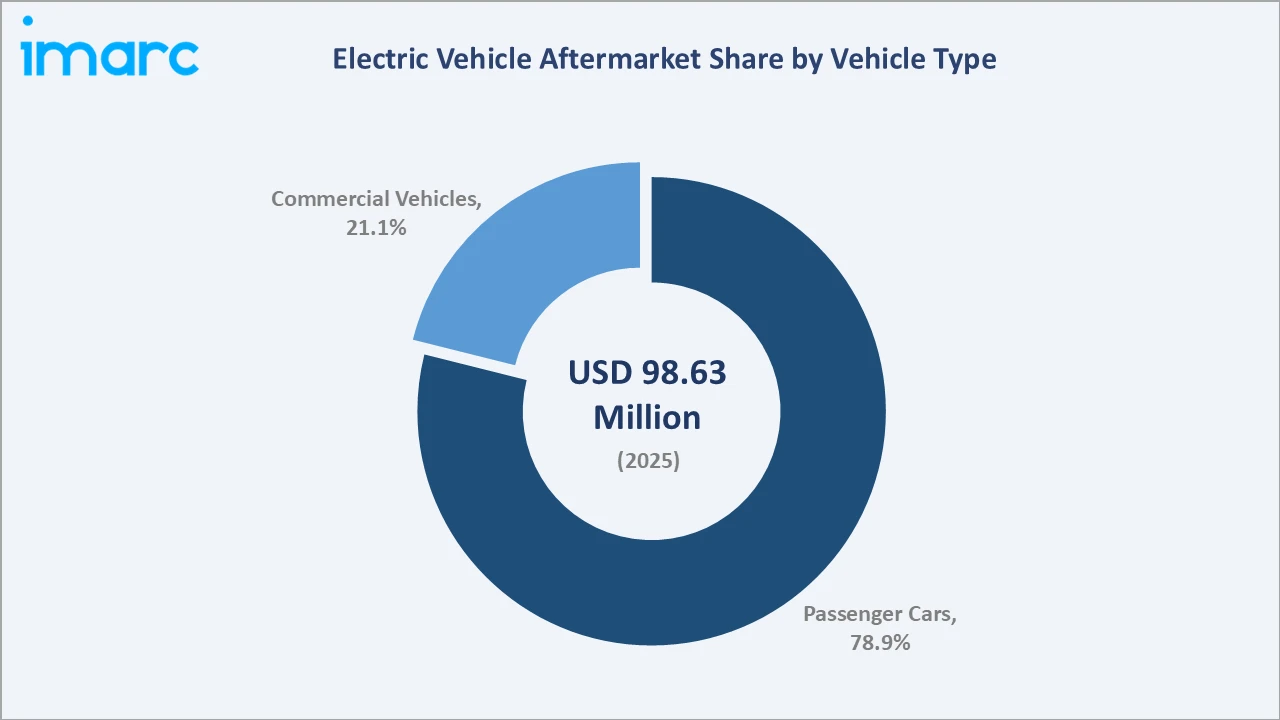
Commercial vehicles at 21.1% represent a smaller but strategically important segment, supported by fleet operators' increasing adoption of electric vans, trucks, and buses and the specialized maintenance requirements of commercial EV fleets.
Regional Market Insights
| Region | Share (2025) | Key Growth Drivers |
|---|---|---|
| North America | 35.2% | Advanced EV adoption infrastructure, strong consumer spending on vehicle maintenance, well-established automotive aftermarket distribution networks, and supportive government policies for electric vehicle ownership |
| Asia-Pacific | 29.4% | World's largest electric vehicle manufacturing and adoption base, rapidly expanding EV fleet in China and South Korea, growing specialized aftermarket service infrastructure, and increasing consumer awareness of EV maintenance needs |
| Europe | 23.1% | Strong regulatory support for EV adoption, growing vehicle fleet maturity, established automotive aftermarket ecosystem, and expanding network of certified EV service providers |
| Latin America | 7.1% | Increasing EV adoption driven by government incentives, growing urban mobility electrification, expanding distribution networks for aftermarket parts, and rising consumer awareness |
| Middle East and Africa | 5.2% | Early-stage EV fleet development supported by government sustainability initiatives, growing EV charging infrastructure investment, and increasing premium vehicle electrification in urban centers |
North America at 35.2% in 2025 leads the regional landscape, anchored by the United States' well-developed automotive aftermarket distribution ecosystem and high consumer spending on vehicle maintenance services.
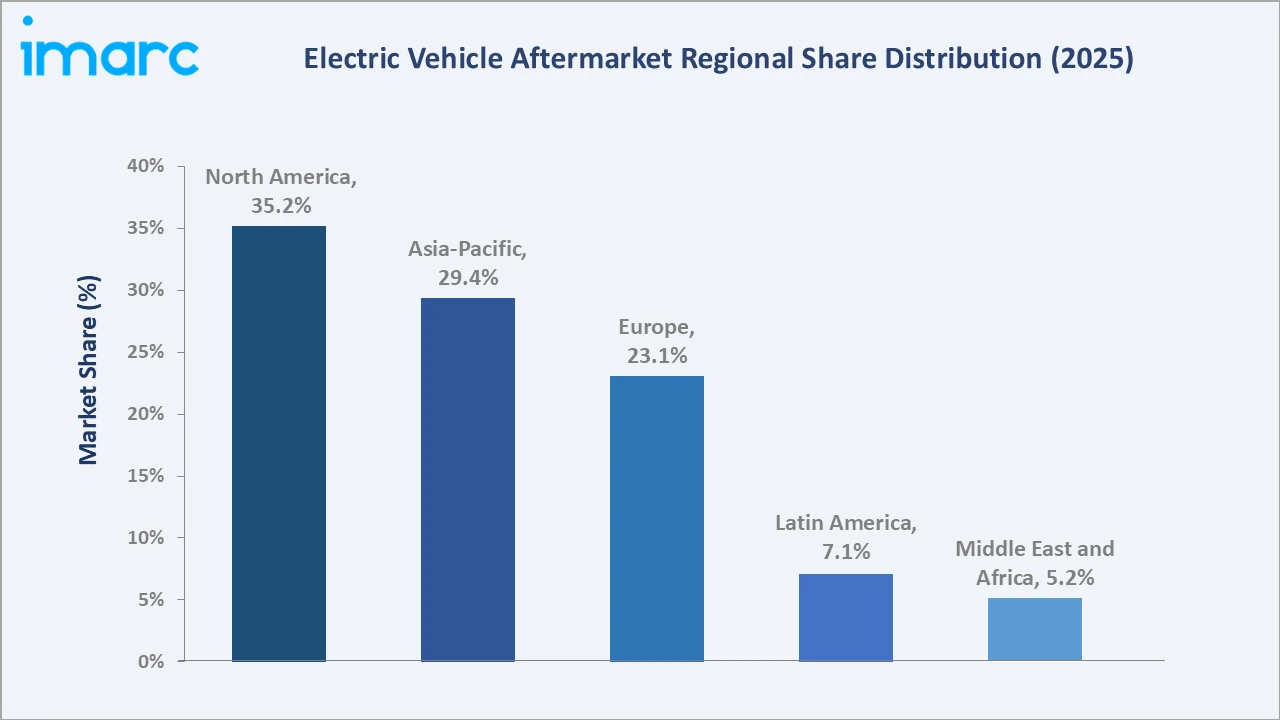
Asia-Pacific, while the second-largest contributor at 29.4%, is expanding at an above-average rate as China's massive and rapidly maturing electric vehicle fleet generates growing volumes of aftermarket service demand and component replacement requirements.
Competitive Landscape
The electric vehicle aftermarket is fragmented, with a mix of global automotive suppliers, established aftermarket parts distributors, and specialist EV service providers competing on parts quality, distribution reach, and service capability. Scale, certified component supply, and proximity to major EV adoption markets form the key competitive differentiators.
| Company Name | Brand / Key Product | Position | Strategic Focus |
|---|---|---|---|
| Robert Bosch GmbH | Bosch Mobility Aftermarket | Leader | Expanding EV-specific aftermarket parts and diagnostic solutions through global distribution networks and strategic investment in electric drivetrain service capabilities |
| LKQ Corporation | LKQ | Leader | Scaling aftermarket parts distribution for electric vehicles through acquisitions, expanding certified EV parts inventory, and growing specialist service network coverage |
| AUMOVIO SE | ATE / VDO / REDI-Sensor | Challenger | Building EV-compatible replacement parts portfolio and expanding service center partnerships to strengthen competitive position in the growing electric vehicle aftermarket |
| Denso Corporation | Denso | Challenger | Leveraging electronics and thermal management expertise to develop certified EV aftermarket components targeting high-value technical segments |
Key players include Robert Bosch GmbH, LKQ Corporation, AUMOVIO SE, and Denso Corporation, among others.
Key Company Profiles
Robert Bosch GmbH
Robert Bosch GmbH is a German multinational engineering and technology company headquartered in Gerlingen, Germany. The company operates one of the world's largest automotive aftermarket businesses through its Bosch Mobility Aftermarket division, supplying diagnostic tools, replacement parts, and service solutions for conventional and electric vehicles.
- Product Portfolio: EV-specific diagnostic tools, battery management components, brake systems, sensors, and a comprehensive range of automotive replacement parts supplied through global distribution networks.
- Recent Developments: The company continues to expand its EV aftermarket product range and invest in diagnostic technology platforms designed to support the growing fleet of electric vehicles requiring aftermarket service.
- Strategic Focus: Strengthening EV-specific aftermarket capabilities across diagnostics, electrification components, and service training to capture growing demand from the expanding electric vehicle service ecosystem.
LKQ Corporation
LKQ Corporation is a United States-based distributor of aftermarket, recycled, and remanufactured vehicle parts headquartered in Nashville, Tennessee. The company operates an extensive distribution network across North America and Europe, supplying a broad range of parts for conventional and electric vehicles.
- Product Portfolio: New aftermarket, recycled OEM, and remanufactured replacement parts for electric and conventional vehicles, supplied through national distribution centers and company-operated service branches.
- Recent Developments: The company continues to expand its EV-compatible parts inventory, develop certified recycled EV battery modules, and extend its distribution network to serve growing electric vehicle maintenance demand.
- Strategic Focus: Building a comprehensive EV aftermarket parts supply chain through organic inventory expansion and strategic acquisitions, targeting aftermarket leadership across North America and European markets.
AUMOVIO SE
AUMOVIO SE is an independent automotive technology company, headquartered in Germany. The company supplies replacement parts, diagnostic tools, and service solutions for conventional and electric vehicles through its established aftermarket brands, including ATE, VDO, and REDI-Sensor.
- Product Portfolio: Brake systems, chassis components, sensors, electronic components, and EV-specific thermal management solutions distributed through global aftermarket channels under the ATE, VDO, and REDI-Sensor brand names.
- Recent Developments: The company continues to advance operational and product development priorities aligned with its strategic focus on the electric vehicle aftermarket.
- Strategic Focus: Developing certified EV-compatible parts offerings under its established aftermarket brands and deepening independent service center collaborations to grow its presence in the evolving electric vehicle aftermarket.
Market Concentration Analysis
The electric vehicle aftermarket is fragmented at the current stage, with leading operators including global automotive suppliers and major parts distributors accounting for a moderate share of overall market volume. The market's rapid growth and evolving technology landscape limit concentration, with significant opportunity for both established players and specialist entrants.
Barriers to entry vary by segment. Parts manufacturing requires substantial capital investment in EV-specific tooling and certification processes. Distribution requires scale, geographic coverage, and established supplier relationships. Service delivery requires specialized EV maintenance training, high-voltage safety certification, and diagnostic tool investment. These factors favor established automotive aftermarket companies with existing infrastructure over greenfield entrants.
Consolidation is underway, with leading parts distributors and service networks acquiring EV-specialist operators to accelerate capability build-out. Strategic partnerships between OEM suppliers and independent aftermarket companies are emerging as a key structure for scaling certified EV parts supply and service network coverage across major markets.
Investment & Growth Opportunities
Fastest-Growing Segments
Battery is expanding fastest among replacement part sub-segments, driven by the growing volume of electric vehicles exceeding warranty-period battery performance thresholds. This trend is further supported by rising demand for battery diagnostics, replacement services, and compatible aftermarket battery solutions as electric vehicle adoption increases.
Emerging Markets
Asia-Pacific is the fastest-growing regional market, supported by China's massive electric vehicle adoption base and rapidly maturing fleet generating growing aftermarket demand. Latin America and Middle East and Africa represent significant untapped opportunity for aftermarket companies establishing distribution and service presence ahead of fleet maturation.
Venture & Investment Trends
Investment activity is concentrated in EV-specialized digital aftermarket platforms, battery reconditioning service facilities, and predictive maintenance technology providers. Capital is also flowing into certified parts manufacturing for EV-specific components, particularly battery modules, power electronics, and thermal management systems increasingly required as the global EV fleet ages.
Future Market Outlook (2026-2034)
The electric vehicle aftermarket is projected to grow from USD 98.63 Million in 2025 to USD 117.28 Million in 2026, reaching USD 489.92 Million by 2034, registering a CAGR of 18.91% during 2026-2034.
Four forces will shape the market through 2034: rapid expansion of the global electric vehicle fleet increasing aftermarket part and service demand; increasing vehicle age driving battery replacement and component reconditioning needs; digital platform growth improving parts accessibility and service booking for EV owners; and advancing battery and drivetrain technology enabling more cost-effective aftermarket servicing beyond the warranty period.
By 2034, the electric vehicle aftermarket is expected to be characterized by a mix of specialized EV aftermarket operators, manufacturer-certified parts programs, and digital marketplace platforms linking consumers with certified service providers. Continued EV fleet growth will sustain strong demand across all replacement part and service categories through the forecast period.
Research Methodology
Primary Research
Primary research included structured discussions with automotive aftermarket distributors, EV service center operators, fleet managers, and technology providers, validating market sizing, segment mix, and regional demand patterns across the electric vehicle aftermarket ecosystem.
Secondary Research
Secondary sources included industry association publications, government EV policy and fleet reports, public disclosures from listed aftermarket parts companies and electric vehicle manufacturers, and data from automotive industry bodies including the International Energy Agency and Society of Automotive Engineers.
Forecasting Models
Market forecasts used top-down and bottom-up models combining global EV fleet size projections, vehicle age distribution assumptions, aftermarket penetration rate estimates, and regional adoption trajectory analysis. Scenario analysis addressed EV adoption pace, technology standardization, and regulatory developments affecting aftermarket access.
Electric Vehicle Aftermarket Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Predictive Market Assessment:
|
| Replacement Parts Covered | Tire, Battery, Brake Parts, Filters, Body Parts, Lighting and Electronic Components, Wheels, Turbochargers, Others |
| Propulsion Types Covered | Battery Electric Vehicles, Hybrid Electric Vehicles, Fuel Cell Electric Vehicles, Plug-In Hybrid Electric Vehicles |
| Vehicle Types Covered | Passenger Cars, Commercial Vehicles |
| Certifications Covered | Genuine Parts, Certified Parts, Uncertified Parts |
| Distribution Channels Covered | Authorized Service Centers (OEMs), Premium Multi-Brand Service Centers, Digital Aggregators, Others |
| Regions Covered | Asia Pacific, Europe, North America, Latin America, Middle East and Africa |
| Countries Covered | United States, Canada, Germany, France, United Kingdom, Italy, Spain, Russia, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Mexico |
| Companies Covered | Robert Bosch GmbH, LKQ Corporation, AUMOVIO SE, Denso Corporation, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the electric vehicle aftermarket from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the global electric vehicle aftermarket.
- The study maps the leading, as well as the fastest-growing, regional markets. It further enables stakeholders to identify the key country-level markets within each region.
- Porter's Five Forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the electric vehicle aftermarket industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Electric Vehicle Aftermarket Report
The electric vehicle aftermarket size is estimated at USD 117.28 Million in 2026, driven by the rapidly expanding global EV fleet, increasing vehicle age, and growing consumer demand for cost-effective aftermarket maintenance services.
The market is projected to grow at a CAGR of 18.91% from 2026-2034, reaching USD 489.92 Million, supported by fleet expansion and maturing vehicle age driving aftermarket demand.
Tire dominates the replacement part segment at 28.7% share in 2025, driven by high wear rates from EV torque characteristics and frequent replacement cycles.
Passenger cars dominate the vehicle type segment at 78.9% share in 2025, driven by widespread consumer adoption of electric passenger vehicles across major global markets.
North America commands 35.2% share in 2025, led by the United States' advanced EV adoption infrastructure and well-established automotive aftermarket distribution ecosystem.
Asia-Pacific is the fastest-growing region, supported by China's massive EV fleet and rapidly maturing vehicle base generating increasing aftermarket service demand.
Key players include Robert Bosch GmbH, LKQ Corporation, AUMOVIO SE, and Denso Corporation, among others.
Key drivers include rapid EV fleet expansion, increasing vehicle age driving replacement demand, growing consumer preference for affordable aftermarket services, and expanding EV service infrastructure.
Key challenges include the complexity of EV-specific maintenance, limited component standardization across platforms, and strong OEM software exclusivity restricting independent service access.
Major opportunities include battery reconditioning services for aging fleets, digital aftermarket platform development, and expansion in emerging EV markets across Asia-Pacific and Latin America.
Digital diagnostics, battery reconditioning technologies, predictive maintenance platforms, and automated service tools are improving aftermarket service quality and expanding accessible service categories for EV owners.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade