
Europe Electric Toothbrush Market Size, Share, Trends and Forecast by Technology, Bristle Type, Distribution Channel, End User, and Country, 2026-2034
Europe Electric Toothbrush Market Size, Share, Trends & Forecast (2026-2034)
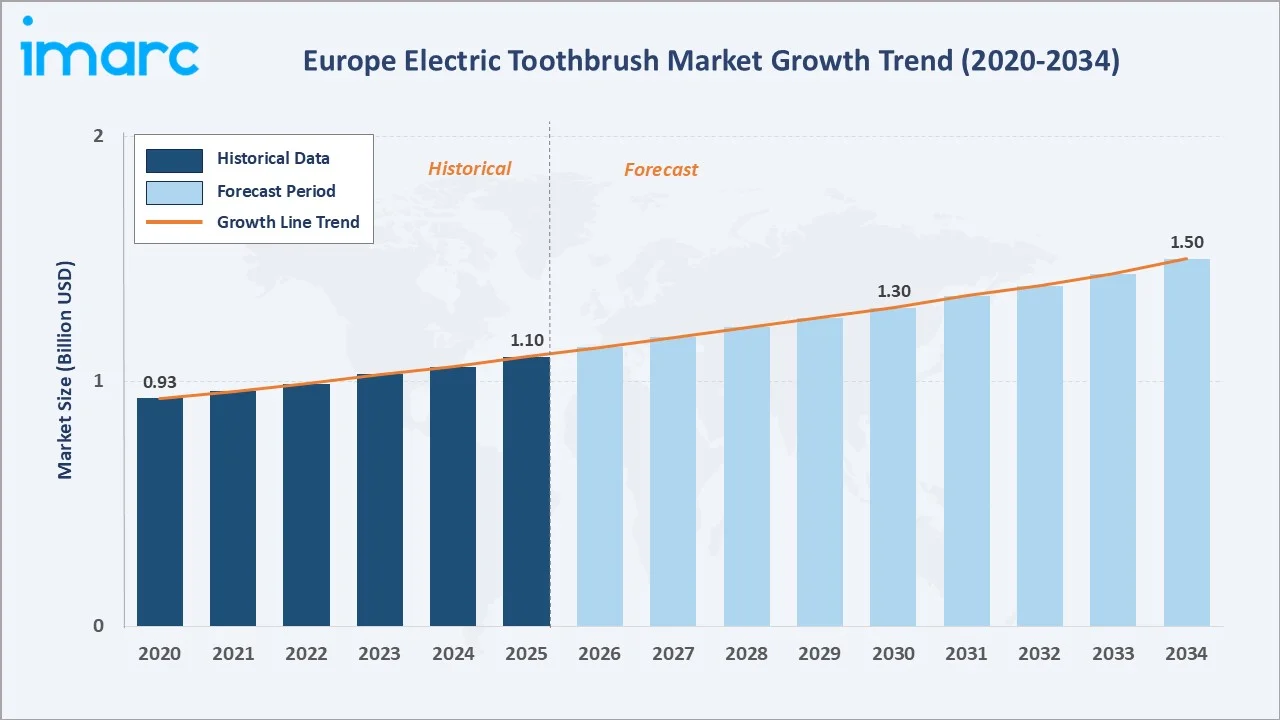
The Europe electric toothbrush market grew from USD 1.10 Billion in 2025 to USD 1.14 Billion in 2026 and is projected to reach USD 1.50 Billion by 2034, growing at a CAGR of 3.42% during 2026-2034. Rising oral health awareness, an aging geriatric population, and increasing adoption of smart oral hygiene devices across Europe drive the market. Rotational technology dominates at 58.6%. Offline distribution leads at 73.7%. Germany commands 30.1% of the European market share.
Expanding e-commerce channels, premiumization of personal care products, and dental tourism are further supporting market growth. Technological innovation in brush heads, pressure sensors, and app-connected devices is accelerating consumer upgrades from manual to electric toothbrushes across Europe.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 1.10 Billion |
|
Market Size (2026) |
USD 1.14 Billion |
|
Forecast Market Size (2034) |
USD 1.50 Billion |
|
CAGR (2026-2034) |
3.42% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Technology |
Rotational (58.6%, 2025) |
|
Dominant Distribution Channel |
Offline (73.7%, 2025) |
|
Leading Country |
Germany (30.1%, 2025) |
The Europe electric toothbrush market size increased from USD 0.93 Billion in 2020 to USD 1.10 Billion in 2025 and is estimated to reach USD 1.14 Billion in 2026. The market is further expected to grow to USD 1.30 Billion by 2030 and USD 1.50 Billion by 2034.
To get more information on this market, Request Sample
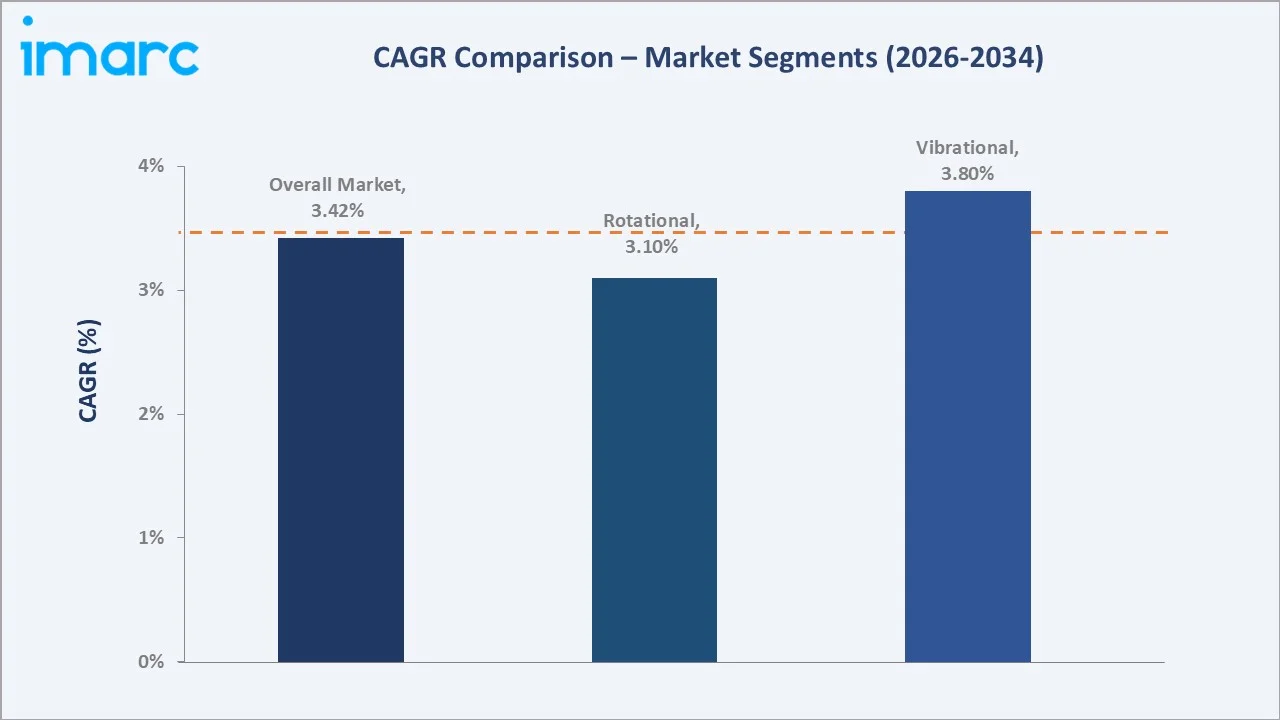
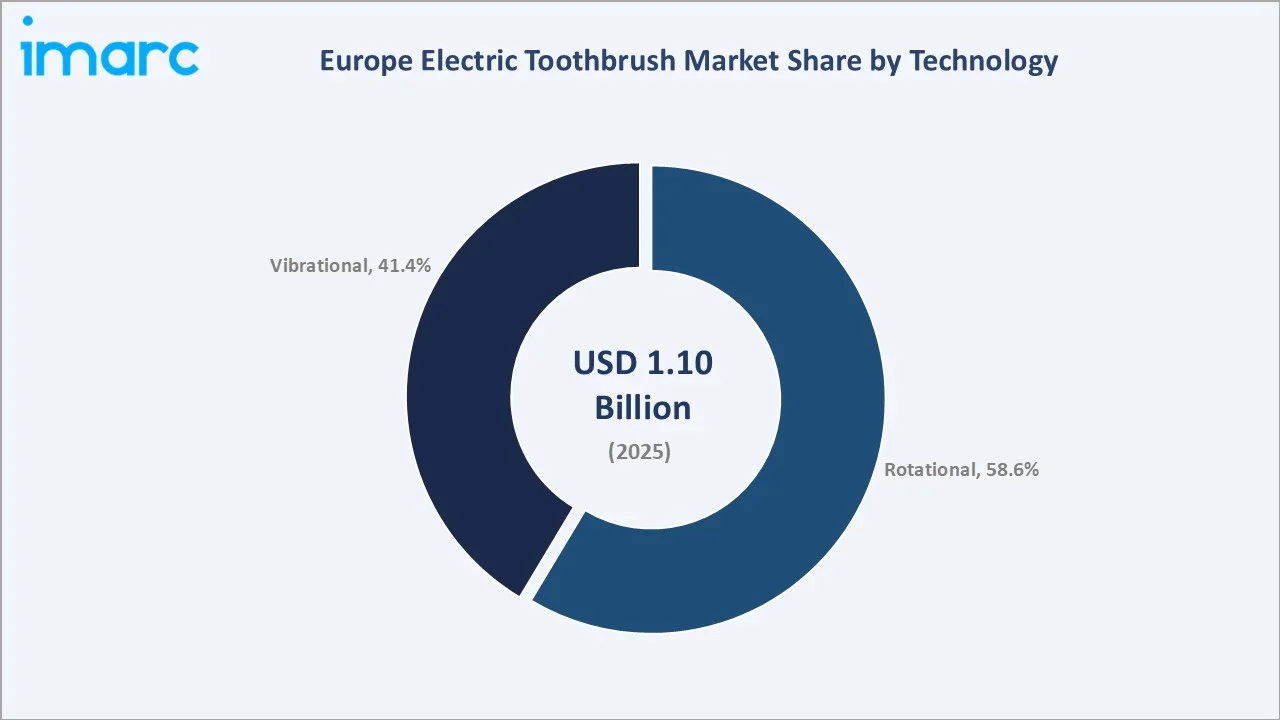
Rotational technology grows at approximately 3.1% CAGR through its dominance among dentist-recommended products and established premium brands. Vibrational technology grows at ~3.8% CAGR, driven by softer brushing motion preferences, sonic innovation, and Philips Sonicare's strong European brand presence.
Executive Summary
The Europe electric toothbrush market expanded from USD 1.10 Billion in 2025 to an estimated USD 1.14 Billion in 2026, positioning it among the continent's most commercially significant personal care segments. Germany leads at 30.1%, underscoring Western Europe's mature consumer base and strong dental hygiene culture.
The market's scale is driven by Europe's aging population, high oral health consciousness, and strong dentist-endorsed product culture. Rising adoption of connected smart toothbrushes and subscription-based replacement head models is creating recurring revenue structures for leading players. The market is projected to reach USD 1.50 Billion by 2034.
Offline retail leads at 73.7%, reflecting the importance of in-store dental product advice and pharmacy distribution. However, online channels are growing at a faster pace as consumers shift to D2C subscriptions, reaching 26.3% in 2025. Rotational at 58.6% leads through established brand trust and clinical endorsement.
Key Market Insights
|
Insight |
Data |
|
Dominant Technology |
Rotational – 58.6% share (2025) |
|
Leading Distribution Channel |
Offline – 73.7% share (2025) |
|
Leading Country |
Germany – 30.1% share (2025) |
|
Market Opportunity |
Smart toothbrush connectivity; eco-friendly refillable brush heads; subscription replacement models; dental clinic partnerships across Europe |
Key Analytical Observations Supporting the Above Data:
- Rotational at 58.6%: The rotational segment dominates due to strong endorsement by dental professionals and established consumer familiarity with oscillating technology. Leading brands such as Oral-B have built significant loyalty in this segment across all European markets. Clinical studies consistently support rotational brushes for superior plaque removal, reinforcing dentist recommendations and driving consumer preference.
- Offline at 73.7%: Pharmacies, supermarkets, and specialized dental retailers remain the primary purchase points, as consumers prefer in-person product consultation for personal oral hygiene tools. Pharmacist recommendations play a key role in brand selection for electric toothbrushes, particularly for first-time buyers and elderly consumers seeking guidance on oral care suitability.
- Germany at 30.1%: Germany leads regionally owing to high consumer awareness of dental hygiene, a well-established pharmacy retail infrastructure, and the strong brand presence of Oral-B and Philips Sonicare across major retail chains and pharmacies nationwide. German consumers exhibit above-average willingness to invest in premium personal care products.
Europe Electric Toothbrush Market Overview
The Europe electric toothbrush market is commercially positioned at a unique intersection: a mature consumer base with high oral health awareness, a rapidly growing premium segment driven by smart dental devices, and a strong professional endorsement culture that differentiates product categories across all major European economies.
The market's structure integrates domestic manufacturing, cross-border imports, authorized retail chains, pharmacy distribution, and a growing direct-to-consumer e-commerce base. Macroeconomic factors include aging demographics, rising disposable incomes, and increasing consumer spending on preventive health and wellness products.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
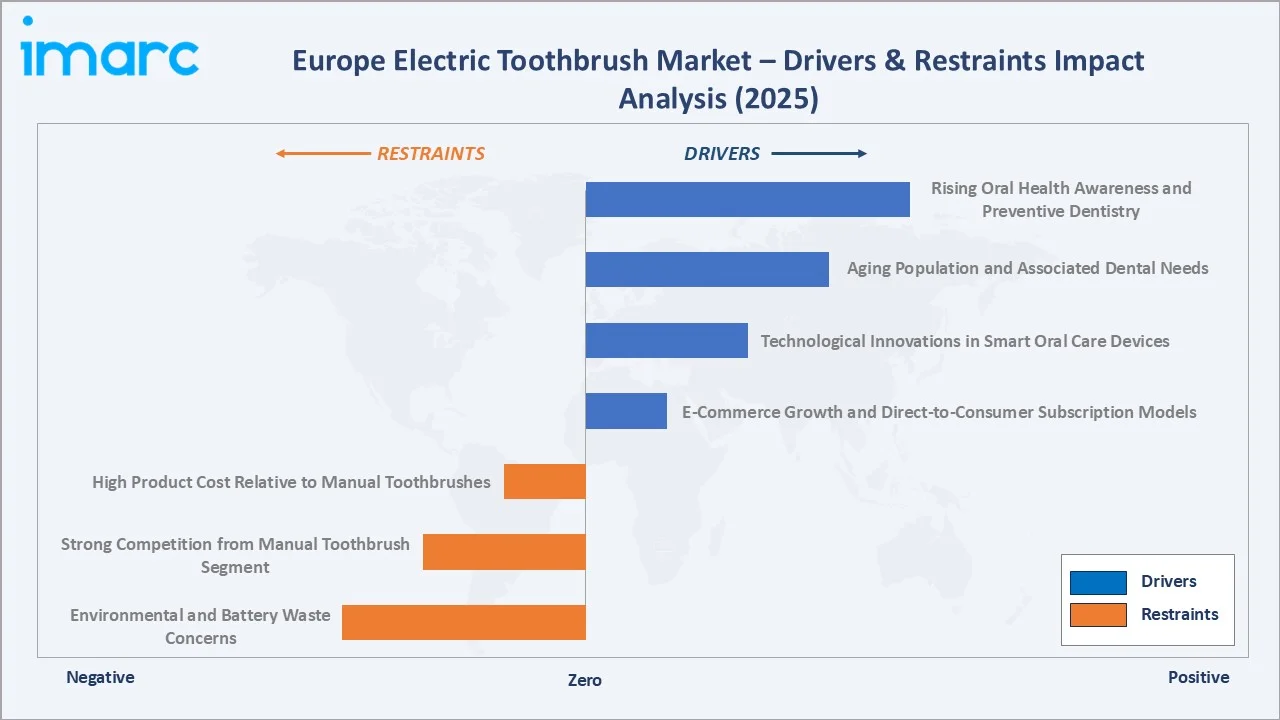
- Rising Oral Health Awareness and Preventive Dentistry: Growing awareness of dental hygiene benefits is driving adoption of electric toothbrushes across Europe. Consumers are increasingly investing in premium oral care products following dentist recommendations, fueling consistent demand across all income segments. European dental associations and national health bodies actively promote electric toothbrush use as a superior preventive dentistry tool, further accelerating market penetration across all age groups and geographies.
- Aging Population and Associated Dental Needs: Europe's growing geriatric population represents a key structural driver, as elderly individuals face higher incidences of gum disease and require effective, easy-to-use plaque removal tools. Electric toothbrushes offer superior cleaning with minimal physical effort, making them the preferred choice for older consumers. Healthcare systems across Germany, France, and the UK increasingly recommend electric toothbrushes as part of geriatric oral health management programs.
- Technological Innovations in Smart Oral Care Devices: Continuous innovation in brush head design, pressure sensors, Bluetooth connectivity, and AI-based brushing feedback is attracting tech-savvy consumers across Europe. Brands are launching app-connected models providing real-time coaching, improving consumer engagement and product premiumization. Recent launches such as Oral-B iO Series with AI brushing recognition and Philips Sonicare's SenseIQ technology have set new benchmarks for the smart toothbrush category in European markets.
- E-Commerce Growth and Direct-to-Consumer Subscription Models: The expansion of online retail platforms and subscription-based replacement brush head models is supporting market growth significantly. D2C channels enable brands to offer personalized bundles, while consumers benefit from convenience and cost savings. Platform-specific promotions and dentist-endorsed subscription plans on brand websites and third-party marketplaces are driving digital adoption, particularly among younger professional demographics.
Market Restraints
- High Product Cost Relative to Manual Toothbrushes: The significantly higher price point of electric toothbrushes versus manual alternatives limits penetration in price-sensitive consumer segments across Europe. While premium products continue to grow, cost remains a barrier for first-time adopters, especially in Eastern European markets. The upfront investment in a quality electric toothbrush, combined with ongoing costs for replacement heads, can deter budget-conscious consumers accustomed to low-cost manual toothbrush options.
- Strong Competition from Manual Toothbrush Segment: Manual toothbrushes remain widely available, affordable, and deeply embedded in consumer habits across several European markets. Overcoming behavioral inertia requires significant marketing investment, particularly in markets with lower average disposable incomes. The manual toothbrush's simplicity, portability, and near-zero recurring cost make it a persistent competitive threat, particularly in Eastern European and rural markets where electric toothbrush brand awareness remains limited.
- Environmental and Battery Waste Concerns: Consumer concerns about the environmental impact of non-recyclable brush heads, plastic components, and battery disposal are growing across Europe. Increasing regulatory scrutiny under the EU Green Deal and Extended Producer Responsibility frameworks is prompting manufacturers to invest in sustainable alternatives, adding development costs. Negative consumer perception around the environmental footprint of electronic personal care products could slow adoption among eco-conscious European consumer demographics.
Market Opportunities
- Eco-Friendly and Sustainable Product Development: Rising environmental consciousness among European consumers is creating a significant opportunity for brands offering recyclable brush heads, biodegradable handles, and rechargeable battery systems. Sustainability-led product lines attract premium-paying eco-conscious consumers and align with EU regulatory requirements. First movers in certified sustainable electric toothbrush product lines can establish strong brand differentiation and tap into Europe's rapidly expanding ethical consumer market.
- Expansion in Eastern European Markets: Countries such as Poland, Czech Republic, and Romania represent underpenetrated markets with growing middle-class populations and improving dental health awareness. As disposable incomes rise and organized retail infrastructure develops, these markets present significant growth opportunities. Early market entry and brand awareness investment in Eastern Europe can secure long-term consumer loyalty ahead of increased competitive intensity.
Market Challenges
- Fragmented Retail Distribution Across Geographies: Europe's diverse retail landscape, with significant variation in pharmacy chains, hypermarket presence, and e-commerce penetration across countries, makes it challenging for brands to maintain consistent distribution coverage and pricing strategies. Adapting go-to-market models for each country's retail preferences while maintaining pan-European brand consistency requires substantial investment in regional distribution partnerships and category management capabilities.
- Intense Price Competition from Private Label and Asian Brands: The entry of low-cost electric toothbrushes from Asian manufacturers and private label offerings from European pharmacy and retail chains is intensifying price competition. Established premium brands must continuously innovate to justify higher price points and defend market share against value alternatives. The rapid improvement in quality of budget electric toothbrushes has narrowed the performance gap, challenging premium brands' ability to communicate differentiated value to price-sensitive European consumers.
Emerging Market Trends
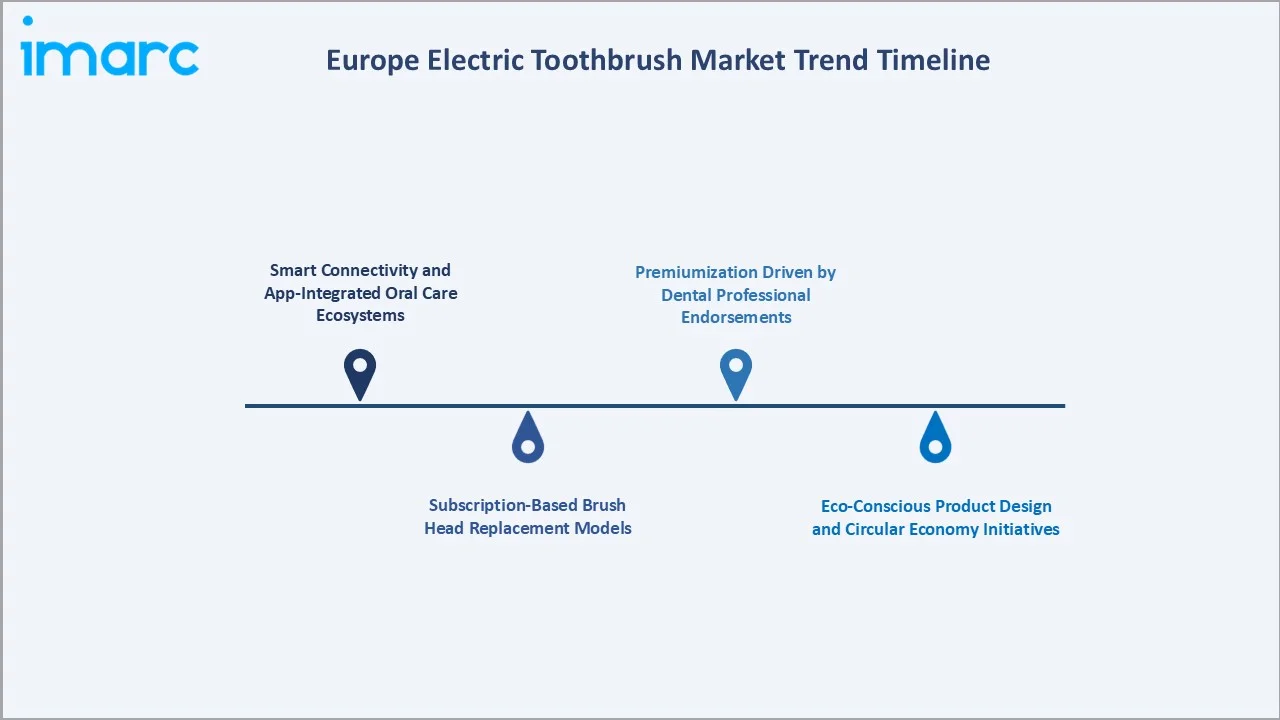
1. Smart Connectivity and App-Integrated Oral Care Ecosystems
Smart toothbrushes with Bluetooth and AI-driven coaching are reshaping consumer expectations across Europe. Leading brands are integrating real-time brushing data with dental health apps, enabling personalized recommendations and brushing habit tracking. This trend drives premiumization and creates ongoing consumer engagement beyond the point of purchase, establishing long-term brand loyalty through digital health ecosystem integration.
2. Subscription-Based Brush Head Replacement Models
Subscription models for replacement brush heads are gaining traction across European markets. Brands like Oral-B and Philips Sonicare are leveraging D2C channels to deliver timely brush head replacements, improving hygiene outcomes while generating predictable recurring revenue. This model enhances consumer retention and average revenue per user while addressing the clinical recommendation that brush heads be replaced every three months.
3. Eco-Conscious Product Design and Circular Economy Initiatives
Consumer demand for sustainable oral care is growing across all European markets. Brands are launching biodegradable brush heads, recyclable packaging, and plant-based bristles to align with European Green Deal commitments. Companies offering take-back schemes for used brush heads are gaining favor among environmentally aware consumers and aligning with EU Extended Producer Responsibility regulations.
4. Premiumization Driven by Dental Professional Endorsements
Dental clinic partnerships and dentist-endorsed product positioning continue to drive premium segment growth across Europe. European consumers place significant trust in professional recommendations, creating a loyal customer base for clinically validated electric toothbrush models with advanced cleaning technology. Brands investing in clinical study partnerships and dental professional education programs are achieving above-market growth in the premium segment.
Industry Value Chain Analysis
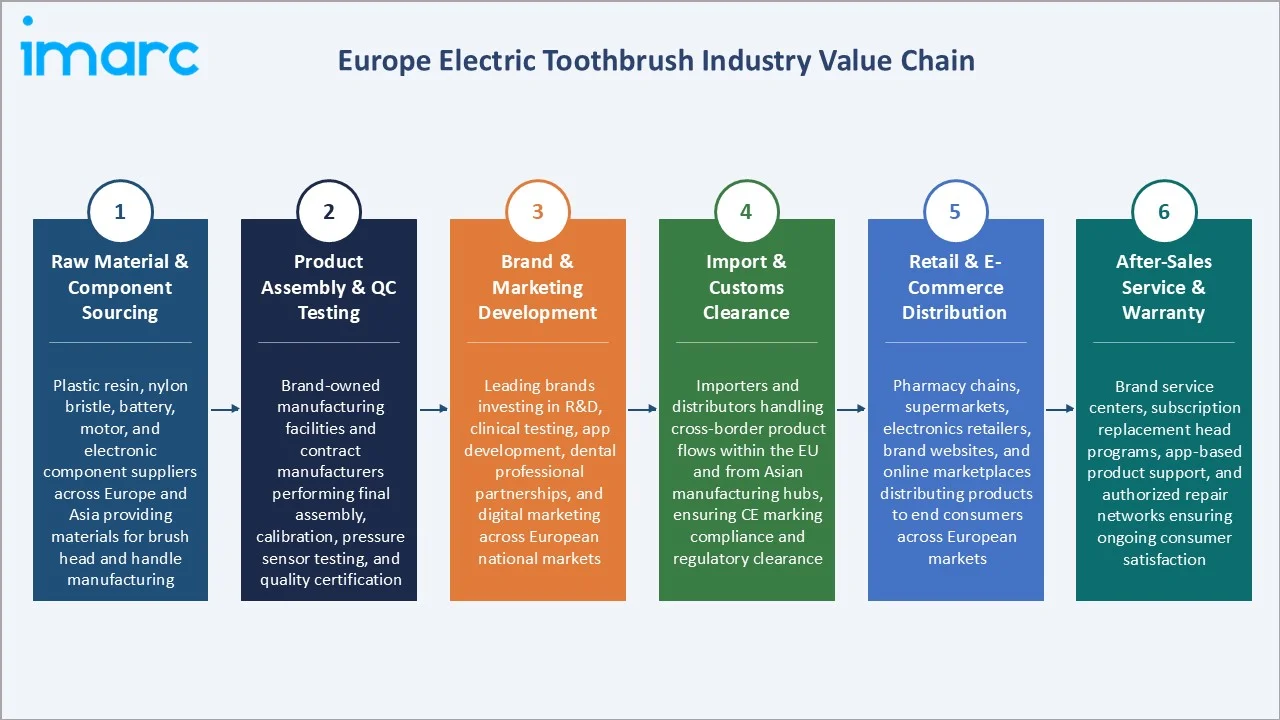
The Europe electric toothbrush value chain is vertically integrated for leading players and distributed across specialized suppliers for smaller brands. The chain's structure creates differentiation opportunity at every stage, from bristle technology to retail experience and after-sales service.
|
Stage |
Key Participants |
|
Raw Material & Component Sourcing |
Plastic resin, nylon bristle, battery, motor, and electronic component suppliers across Europe and Asia providing materials for brush head and handle manufacturing |
|
Product Assembly & QC Testing |
Brand-owned manufacturing facilities and contract manufacturers performing final assembly, calibration, pressure sensor testing, and quality certification |
|
Brand & Marketing Development |
Leading brands investing in R&D, clinical testing, app development, dental professional partnerships, and digital marketing across European national markets |
|
Import & Customs Clearance |
Importers and distributors handling cross-border product flows within the EU and from Asian manufacturing hubs, ensuring CE marking compliance and regulatory clearance |
|
Retail & E-Commerce Distribution |
Pharmacy chains, supermarkets, electronics retailers, brand websites, and online marketplaces distributing products to end consumers across European markets |
|
After-Sales Service & Warranty |
Brand service centers, subscription replacement head programs, app-based product support, and authorized repair networks ensuring ongoing consumer satisfaction |
The retail and e-commerce distribution stage is Europe's most commercially dynamic value chain segment, where brand investment in pharmacy partnerships, digital shelf optimization, and subscription acquisition determines market share outcomes more than manufacturing efficiency.
Technology Landscape in the Europe Electric Toothbrush Industry
Rotational (Oscillating) Technology
Rotational electric toothbrushes use oscillating-rotating movements to remove plaque effectively. This technology is backed by decades of clinical research and strong dentist endorsement. Oral-B has built a dominant market position through rotational brush head innovation, driving the segment's 58.6% share in 2025. The technology's proven plaque removal efficacy and wide price range from entry to premium positions it as the default choice for European consumers seeking their first electric toothbrush.
Vibrational (Sonic) Technology
Sonic electric toothbrushes generate high-frequency vibrations disrupting plaque beyond the direct reach of bristles. Philips Sonicare has been the primary innovator in Europe. Growing preference for gentle yet effective brushing, particularly among sensitive gum patients, is driving vibrational technology's 41.4% share. The segment grows at ~3.8% CAGR as premium positioning and app integration elevate sonic toothbrushes into the connected health ecosystem.
Smart and Connected Toothbrush Technology
Bluetooth-enabled toothbrushes paired with AI-driven mobile apps represent the fastest-growing technology subsegment in Europe. Real-time brushing guidance, coverage mapping, and gamified dental hygiene are particularly impactful among younger consumers and parents managing children's brushing habits. As smartphone penetration and health app usage continue to rise across Europe, smart toothbrush adoption is expected to accelerate significantly through 2034.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Technology |
Rotational |
58.6% |
2025 |
|
Bristle Type |
Soft Bristles |
🔒 |
2025 |
|
Distribution Channel |
Offline |
73.7% |
2025 |
|
End User |
Adults |
78.8% |
2025 |
|
Country |
Germany |
30.1% |
2025 |

By Technology
Rotational leads at 58.6% (2025). This segment dominates through strong clinical endorsement, established brand loyalty, and broad availability across all price points from entry-level to premium models. Oral-B's iO Series and Pro range command strong shelf presence across European pharmacy chains.
To access detailed market analysis, Request Sample
Vibrational at 41.4% is growing at ~3.8% CAGR through premium positioning, sonic technology advantages for sensitive teeth, and Philips Sonicare's strong European brand equity. The segment benefits from growing consumer awareness of sonic technology's effectiveness for gum care and whitening outcomes.
By Distribution Channel
Offline leads at 73.7% (2025). Pharmacies, supermarkets, and specialty dental retailers remain dominant purchase channels, benefiting from in-store dental professional recommendations and consumer preference for hands-on product evaluation before purchase across all major European markets.
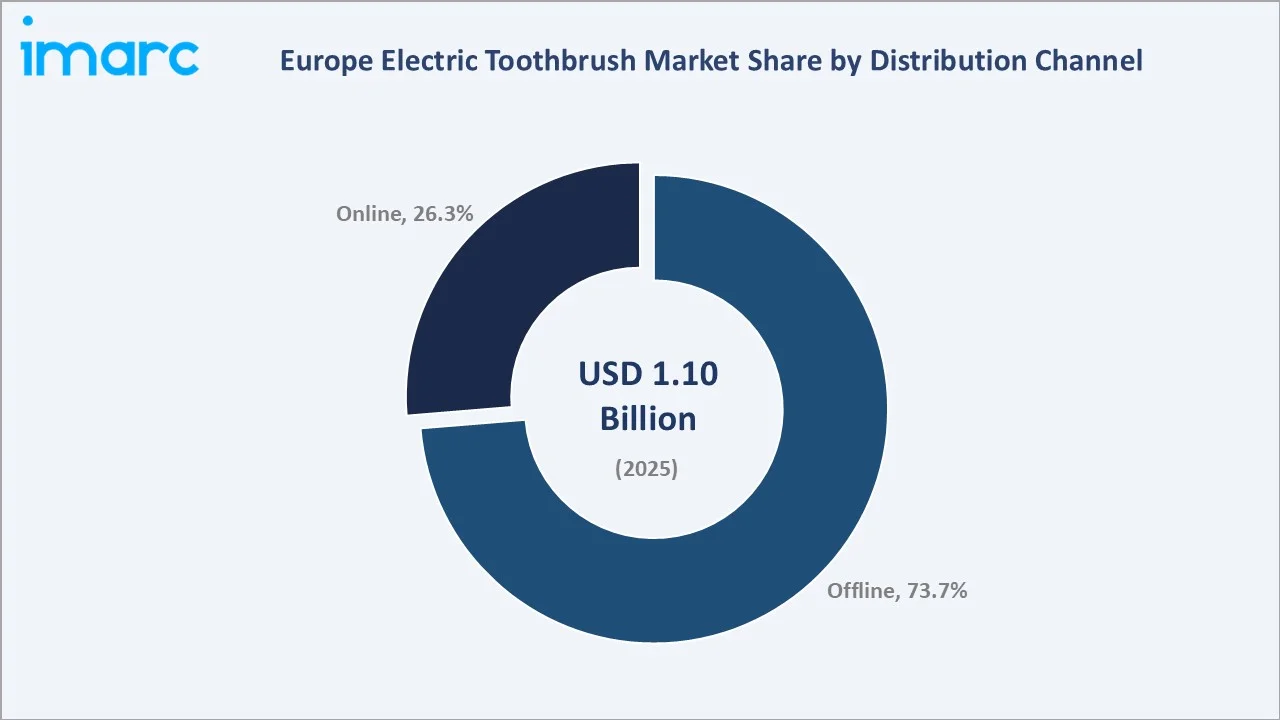
Online at 26.3% is the fastest-growing channel, expanding at ~4.6% CAGR. D2C subscription models, e-commerce platforms, and online pharmacy channels drive digital growth.
Regional Market Insights
|
Country |
Share (2025) |
Key Europe Electric Toothbrush Market Drivers & Characteristics |
|
Germany |
30.1% |
Driven by high oral health awareness, strong pharmacy retail infrastructure, and leading brand presence of Oral-B and Philips Sonicare across mass and premium segments. |
|
United Kingdom |
20.4% |
Supported by widespread e-commerce adoption, NHS dental hygiene promotion campaigns, and strong consumer uptake of premium oral care products across all demographics. |
|
France |
18.2% |
Reflects growing preventive dentistry culture, rising demand for premium dental care, and expanding pharmacy and parapharmacy distribution networks throughout metropolitan and regional markets. |
|
Italy |
12.6% |
Growing awareness of advanced oral hygiene, dentist recommendations driving adoption, and increasing uptake of electric toothbrushes in urban metropolitan centers and northern Italy. |
|
Spain |
8.9% |
Rising disposable incomes and growing health consciousness support gradual adoption, particularly among younger urban demographics and through growing e-commerce penetration. |
|
Others |
9.8% |
Includes Eastern European markets with significant growth potential as dental awareness improves, organized retail infrastructure expands, and middle-class purchasing power rises. |
Germany's 30.1% market leadership reflects its strong pharmacy retail density, above-average consumer spending on health products, and reputation as Europe's leading market for premium personal care brands including both domestic and international electric toothbrush manufacturers.
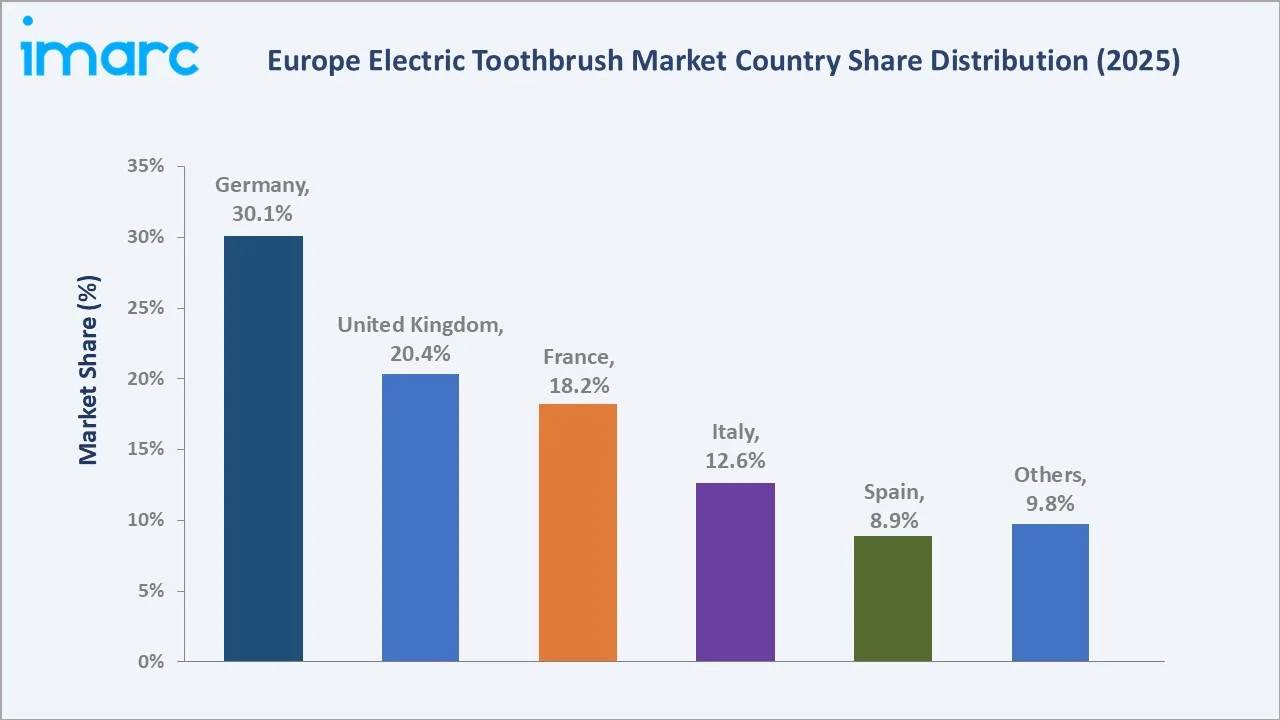
The United Kingdom's 20.4% share reflects robust e-commerce infrastructure and growing consumer awareness. France at 18.2% benefits from a well-developed parapharmacy network. Italy and Spain represent steady growth markets while Others (9.8%) highlights Eastern Europe's emerging commercial potential driven by rising dental awareness and disposable incomes.
Competitive Landscape
The Europe electric toothbrush competitive landscape is dominated by a small number of global players with strong brand equity and extensive distribution networks, while facing growing competition from Asian manufacturers offering price-competitive alternatives at increasingly high quality levels.
|
Company |
Key Brands |
Market Position |
Core Strength |
|
Koninklijke Philips N.V. |
Philips Sonicare Series |
Market Leader |
Philips leads through its Sonicare range with advanced sonic technology, strong dentist partnerships, and a comprehensive product portfolio from entry-level to premium connected smart toothbrushes across Europe. |
|
Procter & Gamble |
Oral-B iO3 Electric Toothbrush, Oral-B iO5 Electric Toothbrush, Oral-B iO6 Electric Toothbrush, Oral-B iO9 Electric Toothbrush |
Market Leader |
Oral-B dominates the rotational segment with clinically proven oscillating-rotating technology and strong dental professional endorsement, supported by P&G's extensive European retail distribution network. |
|
Colgate-Palmolive Company |
Colgate Electric Toothbrush |
Strong Challenger |
Colgate leverages its strong brand trust and pharmacy distribution network to offer a competitive range of electric toothbrushes, particularly targeting the affordable premium segment across European markets. |
|
Panasonic Corporation |
Sonic toothbrush |
Innovator |
Panasonic focuses on compact design and innovative ultrasonic cleaning technology, appealing to tech-oriented European consumers seeking advanced performance in a sleek, travel-friendly format. |
|
Xiaomi |
Mijia Smart Servo-oscillation Electric Toothbrush Pro, Xiaomi Oscillation Electric Toothbrush, Xiaomi Smart Electric Toothbrush T501, Xiaomi Electric Toothbrush T302, Xiaomi Electric Toothbrush T700 |
Value Player |
Xiaomi disrupts the market with affordable electric toothbrushes combining basic performance with smart features, expanding electric toothbrush adoption among price-sensitive European demographics. |
Key players include Koninklijke Philips N.V., Procter & Gamble, Colgate-Palmolive Company, Panasonic Corporation, Xiaomi, and others.
Key Company Profiles
Koninklijke Philips N.V.
Koninklijke Philips N.V. is a leading global health technology company with a dominant presence in the Europe electric toothbrush market through its Philips Sonicare brand, the world's leading sonic toothbrush range with clinically validated plaque removal efficacy.
- Key Brands: Philips Sonicare DiamondClean, ProtectiveClean, ExpertClean, and app-connected smart series across entry-level to ultra-premium price tiers.
- Recent Developments: In July 2026, Philips Sonicare introduced the Next-Generation DiamondClean 9900 Prestige, its first electric toothbrush featuring on-device AI and real-time spatial guidance. The device uses a 12-segment on-device Mouth Map and light-ring feedback to show brushing coverage, while smart pressure sensors adjust intensity when excessive force is detected.
- Strategic Focus: Maintaining leadership through premium connected smart toothbrush innovation, dental professional partnerships across major European markets, and direct-to-consumer digital subscription models for replacement brush heads. Philips is actively expanding its clinical research partnerships with European dental institutions to strengthen its dentist-endorsed positioning across Germany, France, and the UK, securing long-term brand trust and recommendation-driven market share.
Procter & Gamble
Procter & Gamble is one of the world's leading consumer goods companies, with Oral-B representing its flagship electric toothbrush brand in Europe and among the most clinically endorsed dental hygiene products globally with over 60 years of professional endorsement heritage.
- Key Brands: Oral-B iO Series, Smart Series, Genius, Pro, and Vitality ranges covering entry-level to ultra-premium price segments across European markets.
- Strategic Focus: Defending market leadership through continuous technology innovation in its iO Series, dental professional endorsement programs across European dental associations, and expansion of its subscription-based brush head replacement service. P&G is investing in clinical research demonstrating iO Series superiority in gum health improvement outcomes, supporting premium pricing and dentist recommendation rates across Germany, UK, and France where professional endorsement most strongly influences consumer purchase decisions.
Market Concentration Analysis
The Europe electric toothbrush market is highly concentrated at the premium end, with the key players commanding an estimated combined 55-65% of the European branded electric toothbrush market by value, creating a commercially dominant two-player premium structure.
Market concentration is evolving through two opposing forces: consolidation by leading brands through smart toothbrush innovation and subscription models maintaining or expanding their premium share, while Asian competitors and private label pharmacy offerings are fragmenting the mid and entry-level price segments.
Investment & Growth Opportunities
Highest Growth Segments
Smart connected toothbrush segment (~4.8% CAGR through AI and app integration), online D2C subscription channel (~4.6% CAGR), eco-friendly sustainable product lines (~5.2% CAGR from ESG consumer demand), vibrational sonic technology (~3.8% CAGR), and Eastern European market expansion (~5.5% CAGR from low penetration base) represent the highest-growth investment vectors through 2034.
Emerging Investment Opportunities
Europe's growing dental wellness tourism and preventive dentistry culture represent structural demand drivers. The certified sustainable oral care segment, with recyclable components and carbon-neutral manufacturing credentials, attracts ESG-focused investors and premium-brand consumers simultaneously, creating dual commercial value.
Investment Themes
- Smart toothbrush AI platform investment for Europe's digitally connected health consumer: AI-driven brushing coaching platforms and IoT-enabled dental devices create recurring revenue streams and consumer lock-in above one-time hardware purchase models, offering superior lifetime customer value metrics.
- Eastern European market entry for Europe's most commercially underpenetrated electric toothbrush geography: Poland, Romania, and Czech Republic offer significant first-mover advantage as dental awareness rises and organized retail infrastructure develops, with growing middle-class populations increasingly receptive to electric toothbrush adoption.
Future Market Outlook (2026-2034)
The Europe electric toothbrush market is projected to grow from USD 1.10 Billion in 2025 to USD 1.14 Billion in 2026, reaching USD 1.50 Billion by 2034, registering a CAGR of 3.42% during 2026-2034.
Three structural forces define Europe electric toothbrush market growth through 2034: Europe's aging population creating sustained demand for easy-to-use advanced dental care tools; digital commerce maturation enabling geographic market democratization; and innovation-led premiumization through smart toothbrush technology creating category value uplift above volume growth.
Research Methodology
Primary Research
Primary research comprised structured interviews with Europe electric toothbrush industry stakeholders including retail category managers, dental professionals, brand representatives, e-commerce platform managers, and consumer survey data from electric toothbrush users across Germany, the UK, France, Italy, Spain, and other European markets.
Secondary Research
Secondary research encompassed European oral care market import-export data, company annual reports, dental association publications, EU regulatory filings, investor presentations, and industry association reports covering personal care and oral hygiene market dynamics. Over 50 secondary sources reviewed.
Forecasting Models
Market revenue forecasts were developed using a consumer penetration model: European adult population by income and country segment multiplied by electric toothbrush adoption rate and average selling price, creating total market revenue by segment aggregation across the historical and forecast periods.
Europe Electric Toothbrush Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report | Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Technologies Covered | Rotational, Vibrational |
| Bristle Types Covered | Soft Bristles, Nanometer Bristles |
| Distribution Channels Covered | Online, Offline |
| End Users Covered | Adults, Children |
| Countries Covered | Germany, France, United Kingdom, Italy, Spain, Others |
| Companies Covered | Koninklijke Philips N.V., Procter & Gamble, Colgate-Palmolive Company, Panasonic Corporation, Xiaomi, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Frequently Asked Questions About the Europe Electric Toothbrush Market Report
The Europe electric toothbrush market size is estimated at USD 1.14 Billion in 2026, driven by rising oral health awareness and adoption of advanced dental hygiene devices across all major European markets.
The Europe electric toothbrush market grows at 3.42% CAGR during 2026-2034, reaching USD 1.50 Billion by 2034. Growth is sustained by smart toothbrush adoption, aging demographics, expanding e-commerce penetration, and increasing dentist endorsement of electric brushes as the standard of oral care.
Rotational technology leads at 58.6% through strong dental professional endorsements, established brand leadership of Oral-B, and clinically proven plaque removal efficacy accepted by European consumers, dental bodies, and national health authorities across the continent.
Offline leads at 73.7% through Europe's strong pharmacy and specialist dental retailer network. Pharmacies remain the primary point of purchase as consumers seek in-store guidance for oral care product selection from pharmacists and dental hygiene specialists.
Germany leads at 30.1% through high dental health awareness, well-developed pharmacy retail infrastructure, and the strong brand presence of leading global electric toothbrush manufacturers including Oral-B and Philips Sonicare in major retail chains.
Leading companies include Koninklijke Philips N.V., Procter & Gamble, Colgate-Palmolive Company, Panasonic Corporation, Xiaomi, and others.
The Europe electric toothbrush market is projected to reach approximately USD 1.30 Billion by 2030, with smart toothbrush adoption growing as AI brushing coaches and connected dental health ecosystems become mainstream consumer expectations across Western and Central Europe.
Three priority investment opportunities: smart toothbrush AI platform development enabling recurring consumer engagement and dentist-integrated health monitoring; eco-sustainable certified product line creation addressing European Green Deal consumer preferences; and Eastern European market expansion capturing the continent's highest-growth underpenetrated dental care geography.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade