
Europe Health Insurance Market Size, Share, Trends, and Forecast by Provider, Type, Plan Type, Demographics, Provider Type, and Region, 2026-2034
Europe Health Insurance Market Size, Share, Trends & Forecast (2026-2034)
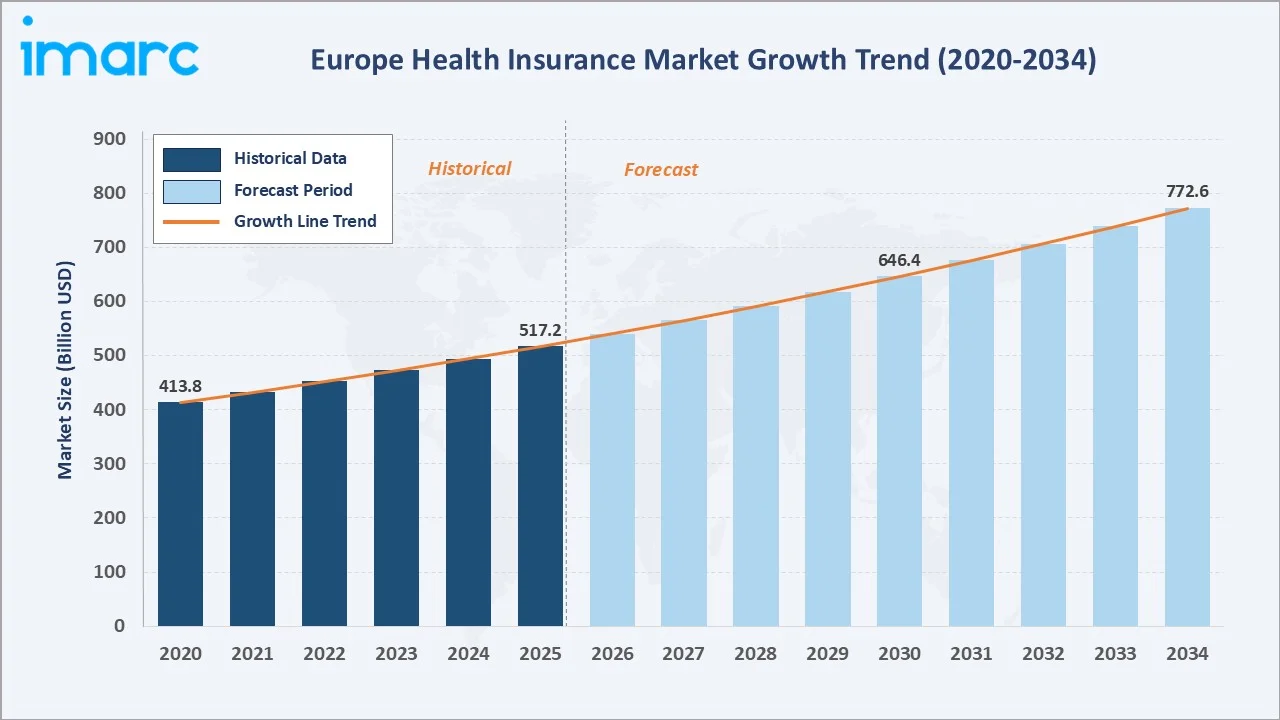
The Europe health insurance market grew from USD 517.2 Billion in 2025 to USD 540.8 Billion in 2026 and is projected to reach USD 772.6 Billion by 2034, growing at a CAGR of 4.6% during 2026-2034. Market growth is driven by an aging population, rising chronic disease burden, growing awareness of Europe personal accident health insurance, and increasing adoption of private supplemental coverage alongside public health systems. The aging population across the WHO European Region is expanding significantly, with the number of people aged 60 years and above projected to increase from 215 million in 2021 to 247 million by 2030 and exceed 300 million by 2050. This demographic shift is driving the market by increasing demand for healthcare services, chronic disease management, hospitalization, long-term care, and specialized elderly care. Private providers lead at 58.7%. Life-time coverage leads the type at 63.8%. Germany leads regionally at 24.8%.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 517.2 Billion |
| Market Size (2026) | USD 540.8 Billion |
|
Forecast Market Size (2034) |
USD 772.6 Billion |
|
CAGR (2026-2034) |
4.6% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Leading Provider |
Private Providers (58.7%, 2025) |
|
Leading Type |
Life-Time Coverage (63.8%, 2025) |
|
Leading Country |
Germany (24.8%, 2025) |
The Europe health insurance market has grown steadily from USD 413.8 Billion in 2020 to USD 517.2 Billion in 2025 and an estimated USD 540.8 Billion in 2026, reflecting a 4.6% CAGR driven by demographic aging, post-COVID health awareness, rising out-of-pocket healthcare costs, and growing demand for private coverage supplementing public health systems. The market is projected to reach USD 646.4 Billion by 2030 and USD 772.6 Billion by 2034.
To get more information on this market, Request Sample
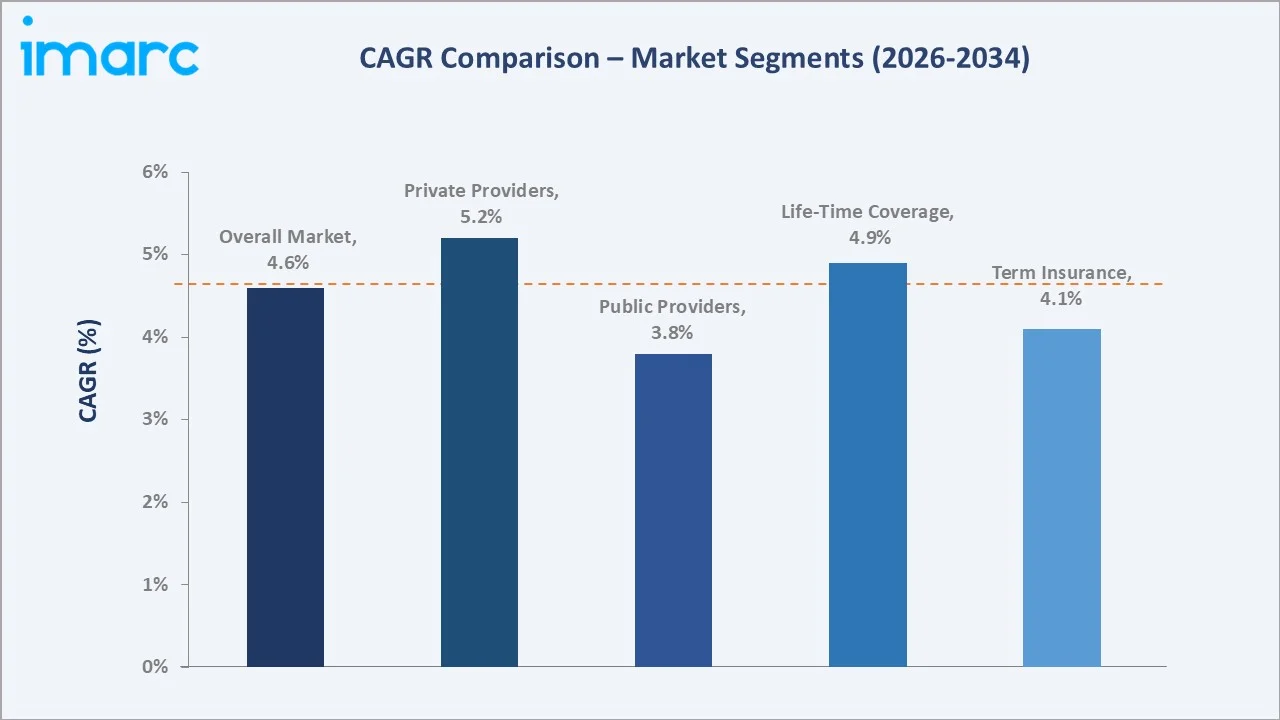
Private providers grow at ~5.2% CAGR through expanding supplemental and international health plan adoption. Life-time coverage grows at ~4.9% CAGR through policyholder preference for comprehensive long-term plans. Public providers grow at ~3.8% CAGR through statutory contribution adjustments. The overall 4.6% CAGR reflects steady, broad-based demand expansion across Europe's diverse insurance market landscapes.
Executive Summary
The Europe health insurance market is experiencing sustained structural growth driven by deep demographic, economic, and policy dynamics. Europe's rapidly aging population is creating unprecedented demand for comprehensive health coverage spanning hospital care, specialist consultations, chronic disease management, and long-term care. Rising healthcare service costs across all European economies are increasing the financial protection value proposition of both statutory and private health insurance.
Private providers at 58.7% lead market share, benefiting from growing consumer demand for faster specialist access, elective procedure coverage, and international health plans beyond what national health systems provide. Life-time coverage at 63.8% dominates insurance type, reflecting consumer preference for long-term health financial security. Germany leads regionally at 24.8%, driven by its mature dual statutory-private insurance architecture.
Key Market Insights
|
Insight |
Data |
|
Leading Provider |
Private Providers - 58.7% share (2025) |
|
Leading Type |
Life-Time Coverage - 63.8% share (2025) |
|
Leading Country |
Germany - 24.8% share (2025) |
|
Market Opportunity |
Digital health integration; senior care expansion; corporate group plans; wellness-linked products |
Key Analytical Observations Supporting the Above Data:
- Private Providers at 58.7%: Private health insurers dominate revenue share as they serve the critical supplemental, replacement, and international health insurance needs that complement statutory public systems. Growing demand for faster specialist access, reduced waiting times, and premium care facilities is driving private plan uptake across the UK, Germany, France, and Spain.
- Life-Time Coverage at 63.8%: Life-time coverage plans command the dominant share as European consumers prioritize long-term health financial security, particularly as aging populations face increasing chronic disease management requirements that necessitate continuous, comprehensive insurance rather than short-duration term plans.
- Germany at 24.8%: The Germany health & medical insurance market leads through its mature dual insurance architecture, high national healthcare expenditure as a GDP percentage, strong private insurance culture among higher-income professionals, and comprehensive employer health benefit programs.
Europe Health Insurance Market Overview
The Europe health insurance market encompasses statutory public health insurance systems (social health insurance funded through payroll contributions), private health insurance plans (supplemental, replacement, and international coverage), and hybrid models combining public and private participation. Products span medical insurance, critical illness, family floater health insurance, and others. Coverage types include life-time coverage (comprehensive continuous plans) and term insurance (fixed-duration coverage). The market serves individual policyholders, families, corporate groups, and governmental bodies across Germany, France, the United Kingdom, Italy, Spain, and other European nations. The Europe home healthcare market expansion and growing Europe personal accident health insurance awareness are creating adjacent product development opportunities. The Europe liability insurance market linkages also influence corporate health benefit plan structure and scope across European employer markets.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
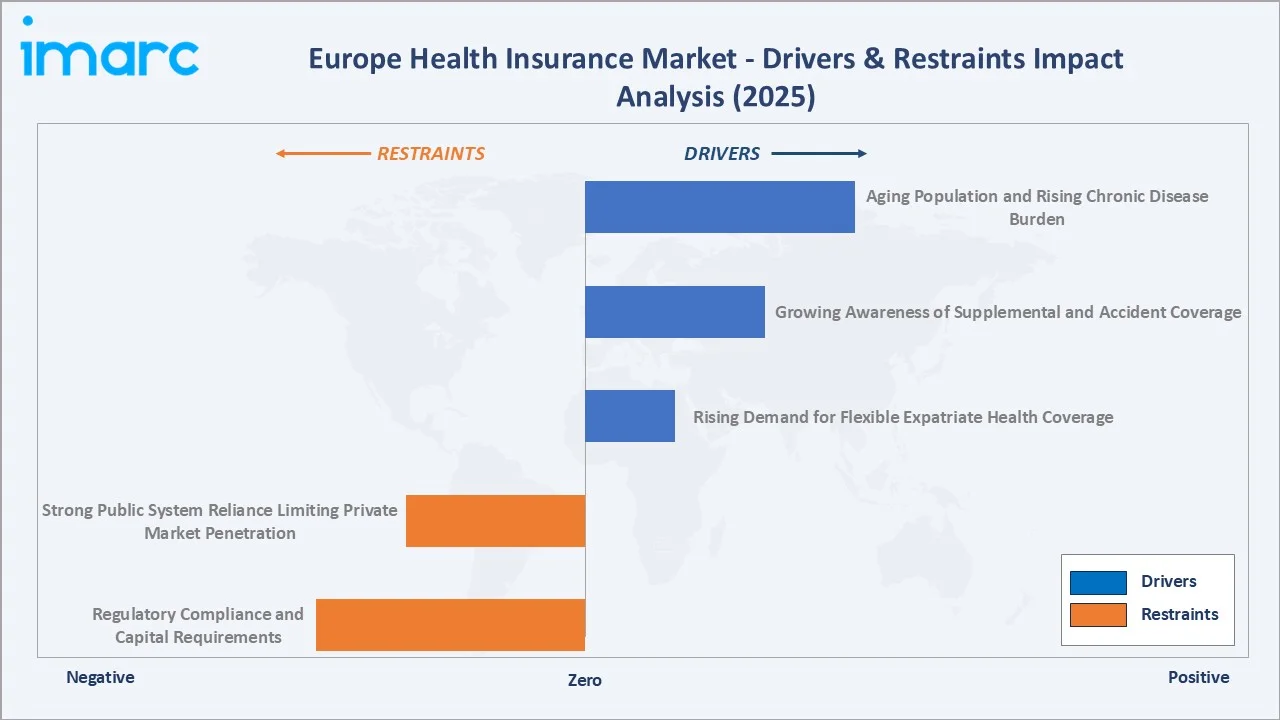
- Aging Population and Rising Chronic Disease Burden: EU population aged 65 years and above increased from 16% in 2000 to 21% in 2023 and is projected to reach approximately 29% by 2050; the demand for comprehensive health coverage is structurally expanding. Chronic conditions including cardiovascular disease, diabetes, cancer, and dementia require sustained multi-year healthcare expenditure, driving consumer demand for life-time coverage plans and specialist access through private providers across all European markets.
- Growing Awareness of Supplemental and Accident Coverage: Increasing consumer awareness of Europe personal accident health insurance, critical illness plans, and income protection products is expanding the addressable insurance market beyond conventional medical expense coverage. Post-COVID health consciousness has accelerated policyholder interest in comprehensive, multi-risk health financial protection.
- Rising Demand for Flexible Expatriate Health Coverage: Growing cross-border mobility across Europe is increasing demand for health insurance products tailored to expatriates and internationally mobile individuals. In March 2026, APRIL International introduced MyHealth International, a new health insurance solution developed specifically for European expatriates and individuals with international mobility needs. The offering combines flexible healthcare coverage, round-the-clock assistance, and digital services, including a virtual payment card that enables policyholders to access healthcare services without making upfront payments. Insurers are responding with flexible coverage, 24/7 assistance, and digital payment solutions that improve convenience and reduce upfront healthcare expenses.
Market Restraints
- Regulatory Compliance and Capital Requirements: Stringent solvency, reporting, consumer protection, and data privacy regulations increase compliance costs for health insurers across Europe. High capital reserve requirements can also limit the entry of smaller players and constrain investment in product innovation and market expansion.
- Strong Public System Reliance Limiting Private Market Penetration: In markets with comprehensive public health systems, particularly France, Italy, and Spain, private insurance penetration remains constrained by consumer satisfaction with public provision. The cultural expectation of healthcare as a public entitlement reduces the urgency of private insurance procurement, particularly among lower-income demographic segments.
Market Opportunities
- Expansion of Cross-Border Health Insurance Services: In June 2026, ExpatInsure opened a new office in Larnaca, Cyprus, establishing an operational base within the European Union to support the expansion of its international health insurance services across Europe. The move represents an important step in the company’s European growth strategy, extending its specialist international insurance model beyond its existing operations in the United States and the United Kingdom. The launch highlights growing opportunities for insurers to expand international health coverage across Europe as expatriate and mobile populations increase.
- Senior Care and Long-Term Care Insurance Expansion: The growing Europe home healthcare market, combined with aging demographics, is creating substantial demand for long-term care and senior health insurance products that cover in-home nursing, rehabilitation services, and chronic condition management beyond conventional hospital-centric coverage. Insurers developing specialized senior health product portfolios are positioned to capture this rapidly expanding demographic segment across Germany, France, Italy, and other aging European economies.
Market Challenges
- Claims Cost Inflation and Loss Ratio Pressures: Healthcare cost inflation exceeding general CPI across European markets is creating loss ratio pressure for health insurers, requiring continuous premium adjustments that risk policyholder attrition. Pharmaceutical price increases, advanced diagnostic technology costs, and specialist consultation fee escalation are structural claims cost drivers that challenge profitability maintenance across all European private health insurance segments.
- Health Data Privacy and Regulatory Complexity: GDPR compliance requirements and evolving health data governance frameworks impose strict limitations on how health insurers collect, process, and use policyholder health data for underwriting personalization, wellness program design, and risk management. Navigating these requirements while delivering the personalized, data-driven health insurance products that attract modern consumers represents a complex and costly operational challenge across all European markets.
Emerging Market Trends
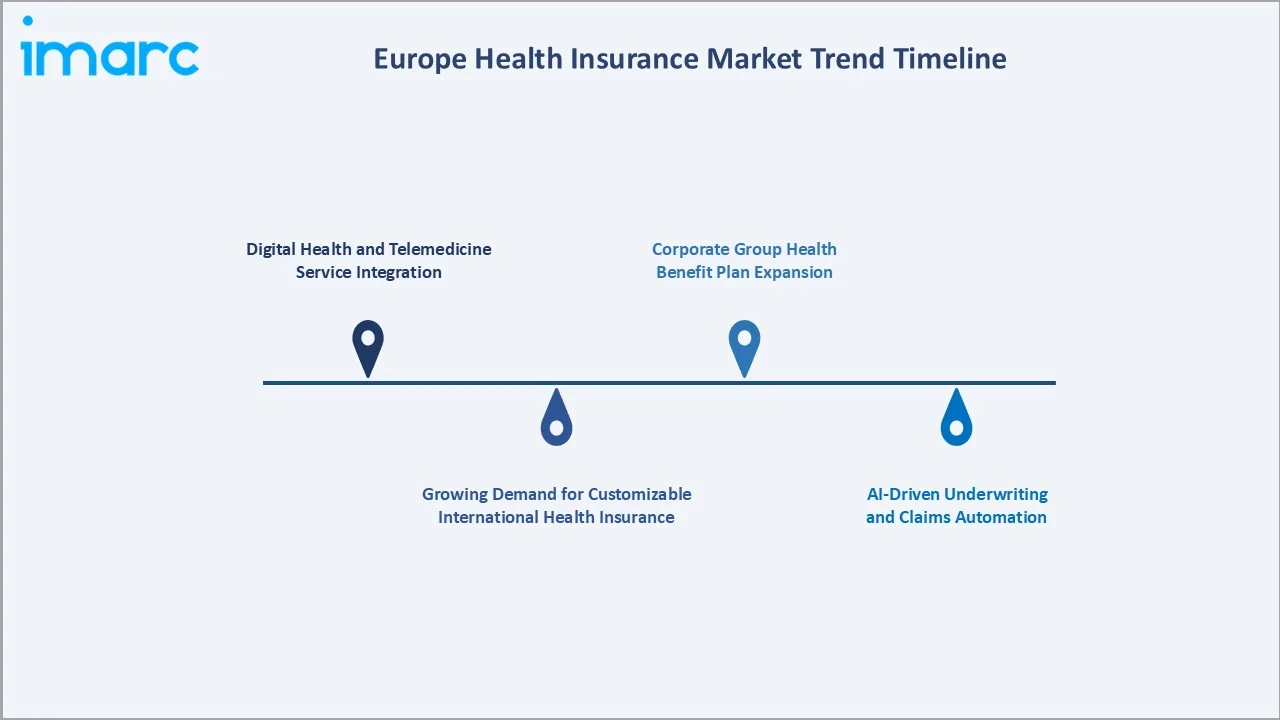
1. Digital Health and Telemedicine Service Integration
European health insurers are systematically integrating telemedicine platforms, digital GP consultations, mental health apps, and AI-powered symptom checkers into their plan offerings as standard value-added services. Telemedicine reduces claims costs by diverting low-acuity consultations from high-cost emergency and specialist settings, while increasing policyholder engagement and perceived plan value.
2. Growing Demand for Customizable International Health Insurance
In November 2025, Allianz Partners, through its Allianz Care brand, introduced an updated portfolio of international health insurance plans for individual expatriates and their families across the UK and Europe. Designed for people living abroad for 12 months or longer, including expatriates, students, digital nomads, professionals, and families, the new range includes three core plans, Base, Enhanced, and Signature, all covering inpatient care. Customers can also personalize their policies with optional benefits such as outpatient treatment and dental coverage. Insurers are increasingly offering tiered coverage and optional benefits to better match diverse healthcare needs and budgets.
3. Corporate Group Health Benefit Plan Expansion
Employers across European markets are expanding health benefit programs as talent retention and workforce wellness investment strategies. Growing employer demand for comprehensive group medical, critical illness, dental, and mental health benefit packages is creating significant volume opportunities for insurers with established corporate benefit platforms. The Europe liability insurance market dynamics further reinforce employer interest in comprehensive health coverage that reduces workplace health liability exposure.
4. AI-Driven Underwriting and Claims Automation
Artificial intelligence and machine learning are transforming health insurance underwriting accuracy, fraud detection, and claims processing efficiency across European markets. Major insurer internal AI programs are enabling more sophisticated risk stratification, predictive health analytics, and automated claims adjudication. These capabilities are reducing underwriting costs, improving loss ratio management, and enabling more personalized premium structures aligned with individual health risk profiles.
Industry Value Chain Analysis
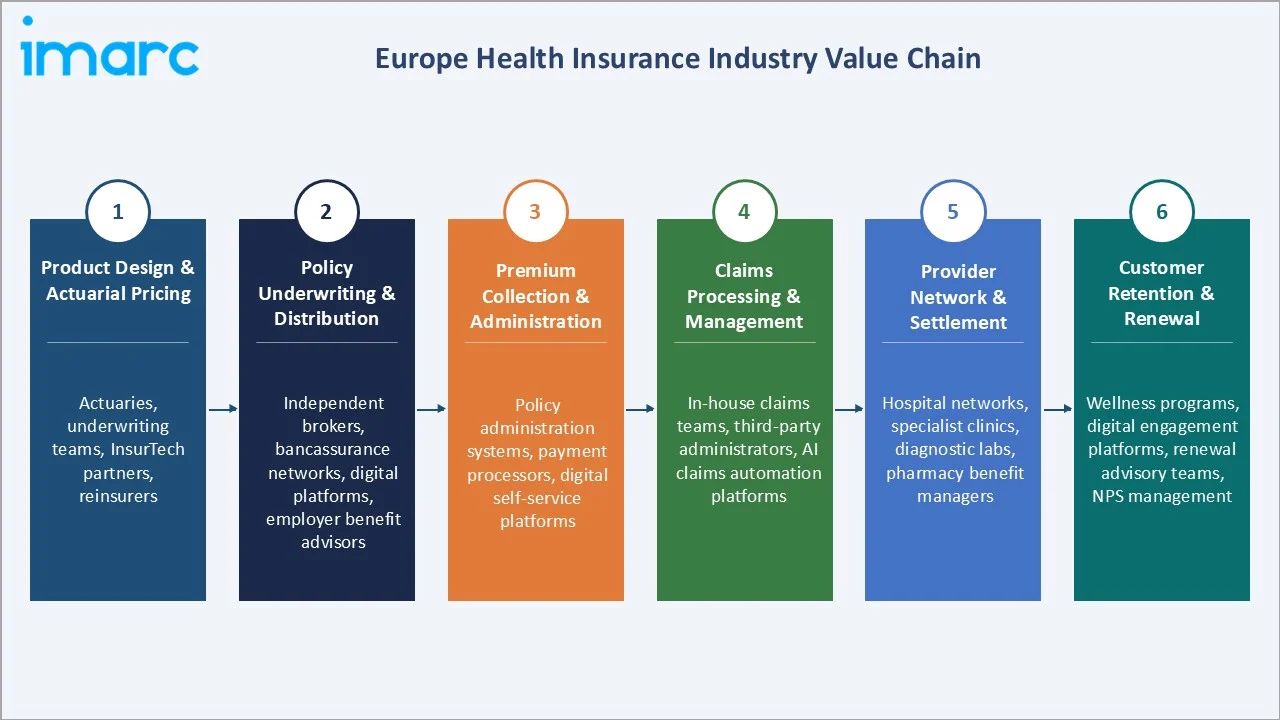
The Europe health insurance market value chain spans product design and actuarial pricing, policy underwriting and distribution, premium collection and administration, claims processing and management, provider network and settlement, and customer retention and renewal.
|
Stage |
Key Participants |
|
Product Design & Actuarial Pricing |
Actuaries, underwriting teams, InsurTech partners, reinsurers. |
|
Policy Underwriting & Distribution |
Independent brokers, bancassurance networks, digital platforms, employer benefit advisors. |
|
Premium Collection & Administration |
Policy administration systems, payment processors, digital self-service platforms. |
|
Claims Processing & Management |
In-house claims teams, third-party administrators, AI claims automation platforms. |
|
Provider Network & Settlement |
Hospital networks, specialist clinics, diagnostic labs, pharmacy benefit managers. |
|
Customer Retention & Renewal |
Wellness programs, digital engagement platforms, renewal advisory teams, NPS management. |
Claims processing and management is the most value-intensive and cost-sensitive stage, directly determining loss ratios and profitability for European health insurers. Product design and actuarial pricing are strategically critical for maintaining underwriting discipline and competitive pricing across demographically diverse European markets.
Technology Landscape in the Europe Health Insurance Industry
Telemedicine and Digital Health Service Platforms
Telemedicine integration is now standard across premium European health insurance plans, with platforms enabling same-day GP consultations, specialist referrals, prescription management, and mental health counseling via video and app interfaces. These services reduce plan churn by increasing perceived value and divert low-acuity consultations from expensive emergency settings, directly improving loss ratios.
Wearables, IoT Health Monitoring, and Wellness Platforms
Wearable device integration, through Apple Watch, Fitbit, and medical-grade IoT sensors, enables European health insurers to offer behavior-linked premium structures and preventive health interventions. Vitality's model of rewarding active policyholders with premium reductions and retail rewards through its health tracking ecosystem has been adopted across multiple European markets, demonstrating measurable claims reduction and policyholder engagement improvement. This technology creates a fundamentally different insurer-policyholder relationship based on shared health outcomes.
Digital Distribution and InsurTech Platforms
Digital-first health insurance distribution platforms are disrupting traditional broker and bancassurance channels, enabling consumers to compare, purchase, and manage health insurance policies entirely online. InsurTech entrants are challenging incumbent distribution models across the UK, Germany, and France, while established insurers are investing in direct-to-consumer digital platforms. These investments reduce distribution costs, improve policyholder data collection, and enable faster product iteration in response to evolving consumer health coverage preferences.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Provider |
Private Providers |
58.7% |
2025 |
|
Type |
Life-Time Coverage |
63.8% |
2025 |
|
Plan Type |
🔒 |
🔒 |
2025 |
|
Demographics |
🔒 |
🔒 |
2025 |
|
Provider Type |
🔒 |
🔒 |
2025 |
|
Country |
Germany |
24.8% |
2025 |

By Provider
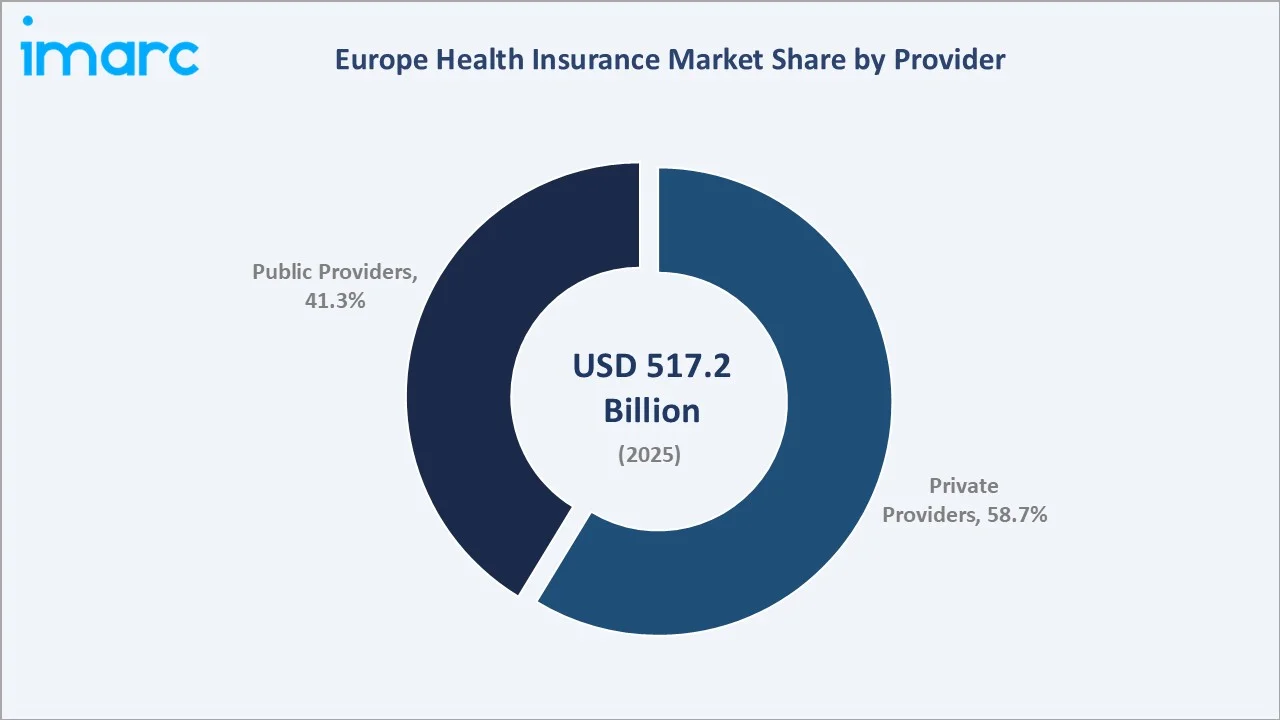
Private providers lead at 58.7% (2025), serving supplemental, replacement, and international health coverage needs beyond statutory public systems. Private providers grow at ~5.2% CAGR through 2034, driven by demand for faster specialist access, elective procedure coverage, and comprehensive international health plans.
To access detailed market analysis, Request Sample
Public providers retain a 41.3% share, reflecting the significant statutory health insurance systems across Germany, France, Italy, and Spain. Public provider contributions grow at ~3.8% CAGR through 2034, driven by regulatory statutory contribution adjustments and expanding public health service coverage commitments, particularly for aging demographics and long-term care.
By Type
Life-time coverage dominates at 63.8% (2025), reflecting European consumer preference for continuous, long-term health financial protection. This coverage type is particularly valued by aging policyholders managing chronic conditions requiring ongoing specialist and hospital care. Life-time coverage grows at ~4.9% CAGR through 2034, supported by growing awareness of Europe personal accident health insurance complementing long-term medical plans and increasing advisor recommendations for comprehensive life-stage coverage.
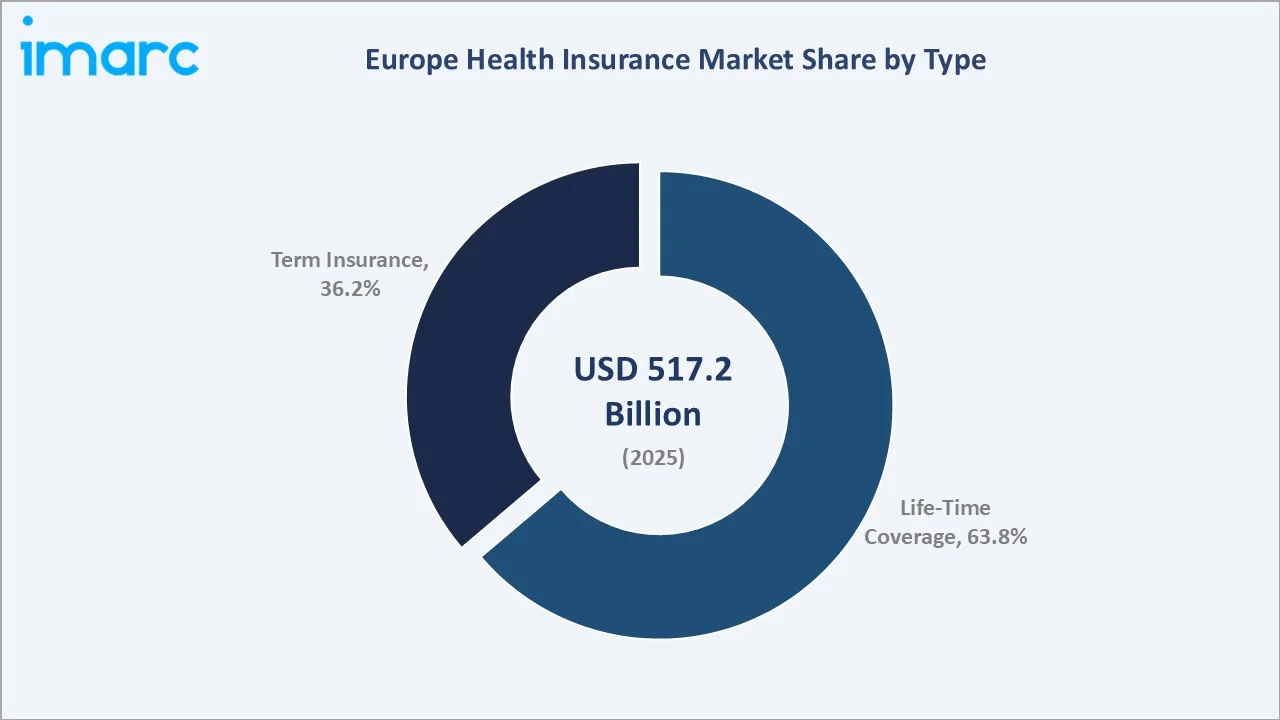
Term insurance holds 36.2% market share, catering to consumers with specific short-duration health coverage needs, including expatriates, short-term workers, travelers, and younger consumers seeking cost-effective entry-level health protection. Term insurance grows at ~4.1% CAGR, supported by growing demand for flexible, renewable short-duration plans from mobile European workforces and digital-first insurance platforms offering term-based micro-insurance products.
Regional Market Insights
|
Country |
Share (2025) |
Key Europe Health Insurance Market Drivers & Characteristics |
|
Germany |
24.8% |
Reflecting the mature dual GKV/PKV insurance architecture, Germany's health & medical insurance market leadership is driven by PKV policyholders. |
|
United Kingdom |
21.7% |
Reflecting growing private medical insurance adoption driven by NHS waiting list pressures, strong employer group plan market. |
|
France |
19.6% |
Reflecting the supplemental insurance model, growing critical illness and long-term care plan adoption. |
|
Italy |
14.8% |
Reflecting supplemental private insurance over the SSN universal system, growing employer health fund adoption. |
|
Spain |
9.7% |
Reflecting growing private health insurance adoption among urban middle-class professionals and growing Europe personal accident health insurance awareness. |
|
Others |
9.4% |
Reflecting diverse health insurance market development across the Netherlands, Belgium, Poland, Switzerland, Scandinavia, and other European nations with varied public-private insurance balance models. |
Germany's 24.8% share reflects its position as Europe's largest national health insurance market, underpinned by Europe's most sophisticated statutory-private dual insurance system. The UK's 21.7% reflects the structural pressure on NHS capacity that is driving private PMI adoption at historically high rates, with employer-funded group plans comprising the majority of new policy uptake. France's 19.6% reflects near-universal supplemental insurance coverage that makes it one of Europe's most saturated private supplemental insurance markets.
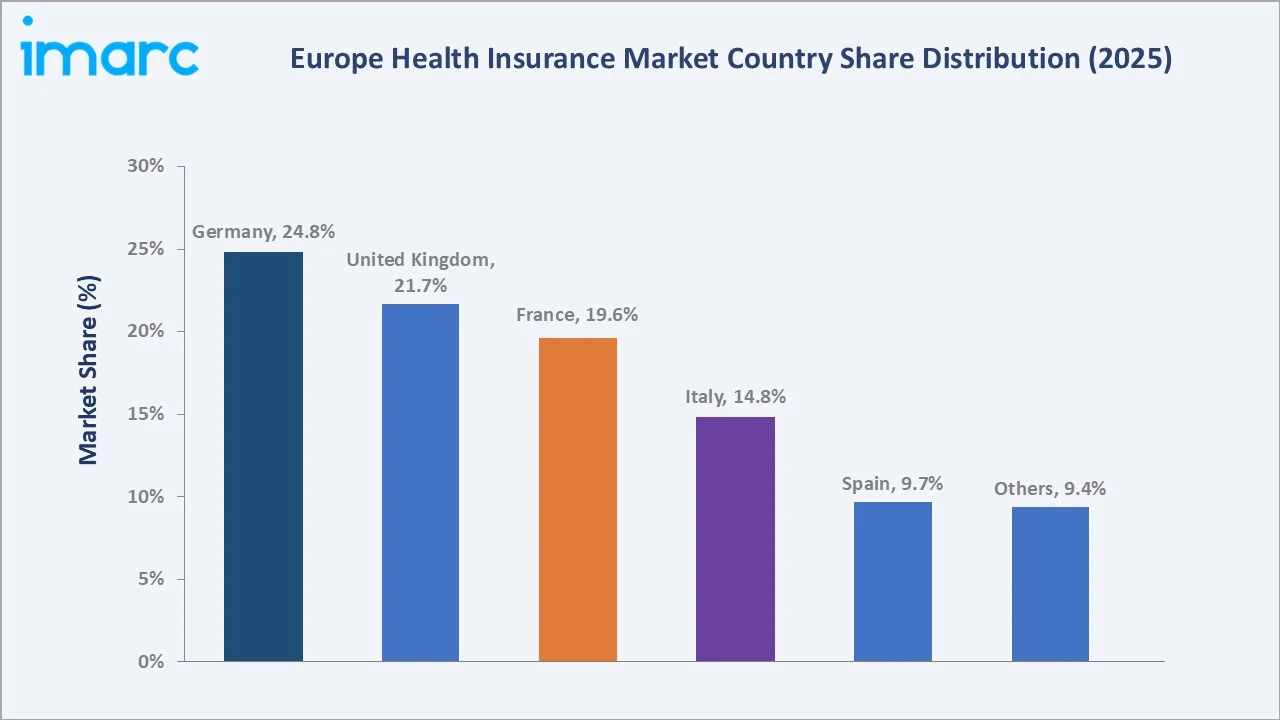
Italy's 14.8% reflects accelerating employer health fund adoption and growing private coverage interest in Northern Italy's affluent economic centers. Spain's 9.7% reflects a growing private insurance market, particularly among urban professionals in major centers, where private insurance covers faster specialist access beyond the SNS system. The others at 9.4% represent collective growth opportunity across Netherlands, Belgium, Scandinavia, and emerging Central and Eastern European markets expanding regulated private health insurance frameworks.
Competitive Landscape
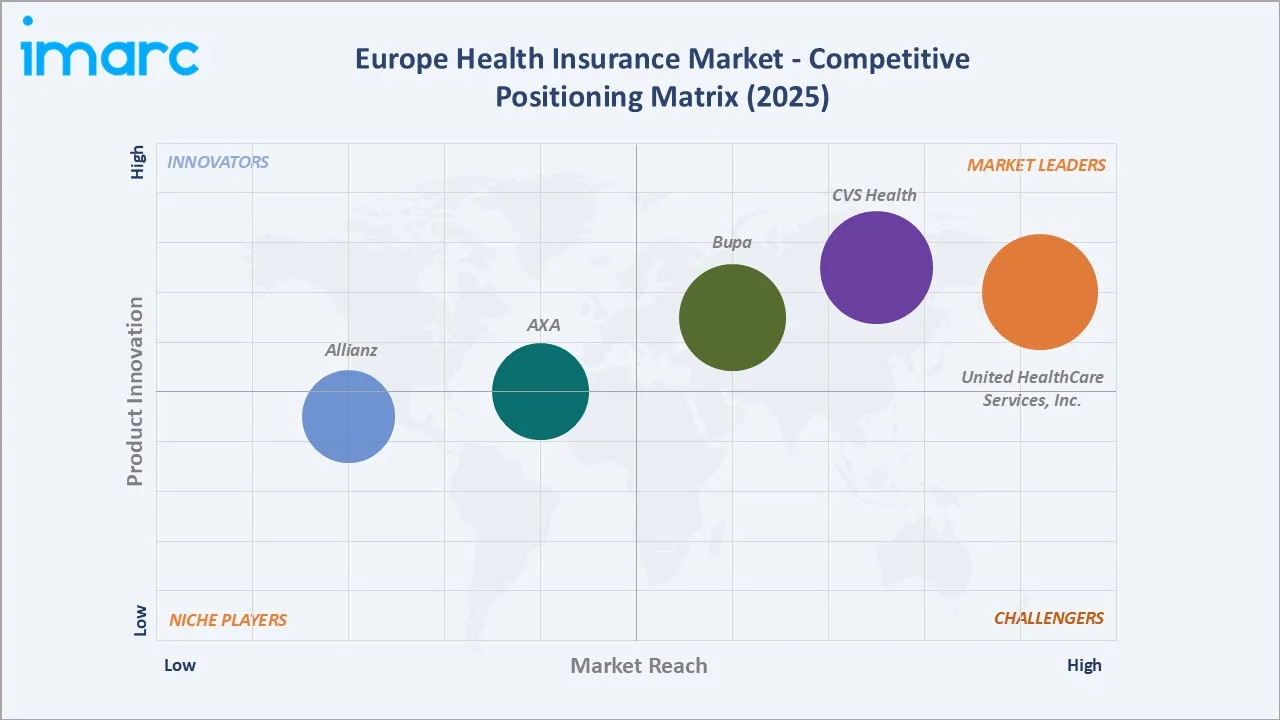
The Europe health insurance market is moderately concentrated, with global insurance giants holding significant market shares alongside national specialists. Competition centers on product breadth, digital health integration, network quality, regulatory compliance expertise, and corporate benefit platform capability. Growing demand for wellness-linked products and digital health services is reshaping the competitive differentiation framework across European markets.
|
Company |
Key Offerings |
Market Position |
Core Strength |
|
CVS Health |
Aetna Health Insurance |
Market Leader |
CVS Health provides health insurance through its subsidiary, Aetna, which offers medical, dental, and behavioral health coverage. |
|
United HealthCare Services, Inc. |
UnitedHealthcare short term plans, UnitedHealthcare Individual and Family ACA plans |
Market Leader |
UnitedHealthcare provides international private medical insurance and health-related assistance for expatriates, business travelers, and globally mobile workforces across Europe. |
|
AXA |
AXA International health insurance plans |
Established Player |
AXA operates as a major health insurance provider and medical cover orchestrator across Europe, offering localized private plans and expat coverage. |
|
Bupa |
Bupa Health Insurance |
Market Leader |
UK's leading private medical insurer; Bupa Global international health plans; growing digital health platform; strong corporate group plan market in UK, Spain, and Ireland |
|
Allianz |
International Health Insurance, Short-Term Health Plans |
Established Player |
Allianz plays a major role in European health insurance by providing specialized international coverage, expatriate protection, and employee benefit solutions through its Allianz Care brand. |
The competitive landscape is evolving toward digital health service differentiation, behavior-linked premium models, and corporate benefit platform capability as primary competitive differentiators. Global multi-line insurers leverage European distribution networks and brand trust, while specialized health insurers compete on product depth and service quality.
Key Company Profiles
CVS Health
CVS Health, operating through Aetna, is one of the leading diversified health care benefits companies. In Europe, Aetna International provides comprehensive individual and group health insurance plans for globally mobile professionals and expatriates across all major European markets. The company's strength lies in its integrated health services ecosystem combining insurance benefits with CVS Health's pharmacy, clinical, and digital health capabilities, enabling a holistic health management proposition that extends beyond traditional indemnity insurance.
- Key Offerings: Aetna Health Insurance.
- Strategic Focus: Expanding European international health plan market share, deepening CVS Health ecosystem integration, advancing AI-driven health management capabilities, growing digital health engagement among European policyholders.
United HealthCare Services, Inc.
United HealthCare Services, Inc. is one of the largest health insurers by revenue, operating through its UnitedHealthcare insurance business. In Europe, the company operates through international health plan divisions serving corporate clients and globally mobile individuals. The company's health analytics and health services platform brings sophisticated data-driven health management capability to European corporate benefit programs, differentiating its offering from conventional indemnity health insurance providers through integrated care management and predictive health interventions.
- Key Offerings: UnitedHealthcare short term plans, UnitedHealthcare Individual and Family ACA plans.
- Strategic Focus: Growing European corporate group health plan market, advancing health analytics and care management in European markets, expanding mental health and behavioral health benefit offerings, deploying AI-driven claims and utilization management capabilities.
Market Concentration Analysis
The Europe health insurance market is moderately concentrated at the European level, with the top five operators CVS Health, United HealthCare Services, Inc., AXA, Bupa, and Allianz, collectively accounting for an estimated 35-45% of total European private health insurance in 2025. However, market concentration varies significantly by country: the Germany health & medical insurance market features approximately GKV funds alongside around PKV private insurers. The Europe personal accident health insurance market and Europe home healthcare insurance segments are more fragmented, with national specialists and InsurTech entrants competing alongside global insurers. Consolidation is expected to continue through 2034, driven by capital efficiency pressures, digital transformation investment requirements, and the competitive advantages of scale in claims management and provider network negotiation.
Investment & Growth Opportunities
Highest Growth Segments
Private provider plans (~5.2% CAGR est.), life-time coverage products (~4.9% CAGR est.), senior and long-term care insurance development, digital health-integrated wellness plans, and corporate group health benefit expansion represent Europe's highest-priority health insurance investment vectors through 2034.
Investment Themes
- Digital Health and AI-Enabled Health Insurance Platform Development: Investments in AI-powered underwriting, telemedicine integration, wearable-linked wellness programs, and digital claims processing create durable competitive advantages and loss ratio improvements. Platforms enabling personalized health insurance through behavior-linked premium structures represent the most strategically differentiated investment opportunity in the Europe health insurance market.
- Senior Care and Long-Term Care Insurance Product Expansion: Europe's rapidly aging demographics and growing Europe home healthcare market create compelling product development investment opportunities. Insurers investing in dedicated senior health product portfolios covering home nursing, rehabilitation, and long-term care supplements are positioned to capture disproportionate growth from the most rapidly expanding European health insurance demographic segment through 2034.
Future Market Outlook (2026-2034)
The Europe health insurance market is projected to grow from USD 517.2 Billion in 2025 to USD 540.8 Billion in 2026 and is forecast to reach USD 772.6 Billion by 2034, delivering a 4.6% CAGR over the forecast period through private provider expansion, life-time coverage growth, digital health integration, and senior care product development. The market's anchor value of USD 646.4 Billion in 2030 represents the point at which digital health-integrated insurance plans achieve mainstream European adoption, and the private insurance market captures meaningful share from constrained public healthcare systems.
Three structural forces are expected to define the Europe health insurance market through 2034. First, Europe's demographic aging megatrend will continuously expand the addressable health insurance market across all five principal coverage segments. Second, public healthcare system capacity constraints will continue to drive private insurance adoption across the UK, Italy, Spain, and emerging Central and Eastern European markets. Third, digital health transformation will fundamentally reshape competitive dynamics in the European health insurance market. Insurers deploying AI underwriting, wearable-integrated wellness programs, and telemedicine-embedded health plans will achieve superior loss ratios, policyholder retention, and product innovation velocity compared to technology-laggard competitors.
Research Methodology
Primary Research
Primary research comprised in-depth interviews with senior executives from health insurance companies, national health regulatory authorities, broker networks, employee benefit advisors, healthcare service providers, and industry consultants across Germany, France, the United Kingdom, Italy, Spain, and other European markets. Discussions validated market size estimates, assessed provider and type segment growth dynamics, evaluated competitive positioning, and gathered qualitative insights on regulatory developments, digital health integration trends, and demographic market drivers.
Secondary Research
Secondary research encompassed company annual reports, regulatory filings, national insurance supervisory authority publications, demographic and healthcare expenditure data, health system statistics, industry databases, press releases, and reputed market intelligence publications. These resources were used to analyze market trends, competitive positioning, regulatory developments, and country-level market characteristics across the European health insurance sector.
Forecasting Models
Forecasting models were developed using historical data (2020-2025), demographic aging projections, healthcare expenditure growth trends, regulatory evolution timelines, private insurance penetration rate analysis, and macroeconomic GDP and disposable income indicators. The analysis incorporated both top-down and bottom-up approaches validated through primary research, generating reliable market forecasts through 2034.
Europe Health Insurance Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Providers Covered | Private Providers, Public Providers |
| Types Covered | Life – Time Coverage, Term Insurance |
| Plan Types Covered | Medical Insurance, Critical Illness Insurance, Family Floater Health Insurance, Others |
| Demographics Covered | Minor, Adults, Senior Citizen |
| Provider Types Covered | Preferred Provider Organizations (PPOs), Point of Service (POS), Health Maintenance Organizations (HMOs), Exclusive Provider Organizations (EPOs) |
| Countries Covered | Germany, France, United Kingdom, Italy, Spain, Others |
| Companies Covered | CVS Health, United HealthCare Services, Inc., AXA, Bupa, Allianz, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Europe health insurance market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the Europe health insurance market.
- Porter's Five Forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Europe health insurance industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Europe Health Insurance Market Report
The Europe health insurance market size is estimated at USD 540.8 Billion in 2026, driven by aging demographics, rising healthcare costs, growing Europe personal accident health insurance awareness, and increasing private coverage adoption supplementing public health systems.
The market is projected to grow at a CAGR of 4.6% during 2026-2034, reaching USD 772.6 Billion by 2034, driven by private provider expansion, Life-time coverage growth, digital health integration, and senior care product development.
Private providers lead at 58.7% (2025), serving supplemental, replacement, and international health coverage needs beyond statutory public systems.
Life-time coverage leads at 63.8% (2025), reflecting European consumer preference for continuous long-term health financial protection across aging demographics managing chronic conditions requiring sustained medical care and specialist access.
Germany leads at 24.8% (2025) through its mature dual GKV/PKV insurance architecture, high national healthcare expenditure, and comprehensive employer health benefit culture.
Leading companies include CVS Health, United HealthCare Services, Inc., AXA, Bupa, and Allianz, among others.
The market is projected to reach approximately USD 646.4 Billion by 2030, reflecting steady private provider expansion, growing life-time coverage adoption, digital health integration, and contributions from emerging Central and Eastern European regulated private health insurance markets.
Priority investment opportunities include digital health and AI-enabled platform development, senior care and long-term care insurance product expansion for aging demographics, corporate group health benefit plan growth, behavior-linked wellness insurance product development, and emerging Central and Eastern European market entry.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade