
Europe Plant-based Seafood Market Size, Share, Trends and Forecast by Product Type, Distribution Channel, and Country, 2026-2034
Europe Plant-Based Seafood Market Size, Share, Trends & Forecast (2026-2034)
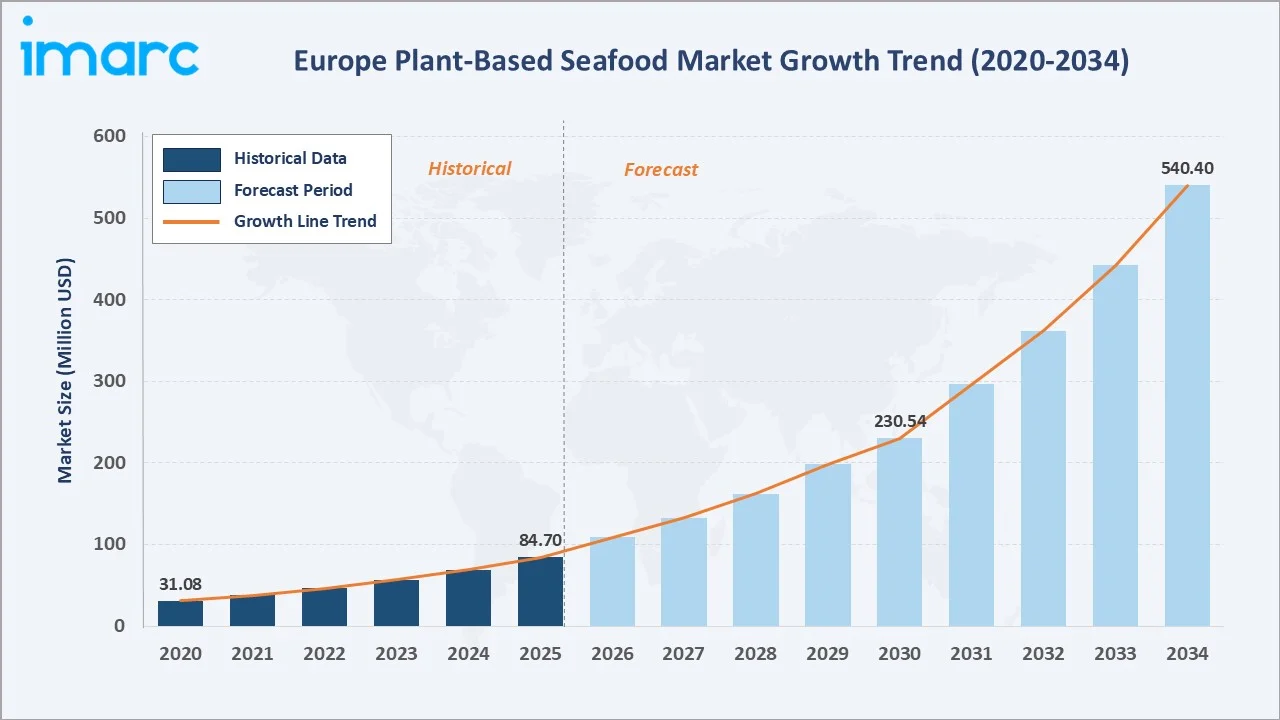
The Europe plant-based seafood market grew from USD 84.7 Million in 2025 to USD 108.8 Million in 2026 and is projected to reach USD 540.4 Million by 2034, growing at a CAGR of 22.19% during 2026-2034. The market is driven by rising consumer demand for sustainable and ethical food choices, growing vegan and flexitarian populations, and increasing regulatory support for alternative proteins across European nations.
Expanding retail distribution, product innovation in taste and texture, and strong investment in food-tech are further supporting market growth. Fish Products dominate at 48.6%. Supermarkets and Hypermarkets lead distribution at 45.8%. Germany commands 26.8% of the European market share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 84.7 Million |
|
Market Size (2026) |
USD 108.8 Million |
|
Forecast Market Size (2034) |
USD 540.4 Million |
|
CAGR (2026-2034) |
22.19% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Product Type |
Fish Products (48.6%, 2025) |
|
Dominant Distribution Channel |
Supermarkets and Hypermarkets (45.8%, 2025) |
|
Leading Country |
Germany (26.8%, 2025) |
The Europe plant-based seafood market size increased from USD 31.08 Million in 2020 to USD 84.7 Million in 2025 and is estimated to reach USD 108.8 Million in 2026. The market is further expected to grow to USD 230.54 Million by 2030 and USD 540.4 Million by 2034. Europe is at the forefront of the global plant-based seafood movement, driven by high consumer awareness, stringent sustainability regulations, and strong investment in food-tech innovation.
To get more information on this market, Request Sample
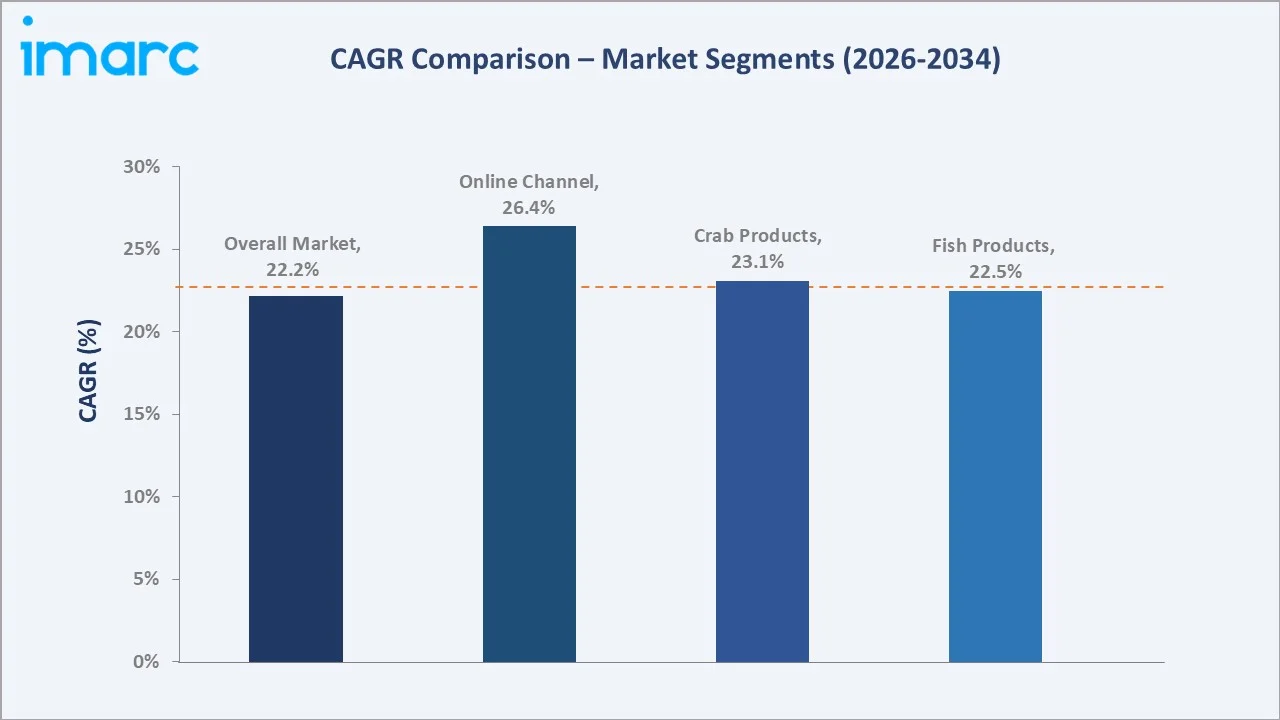
The Online Channel segment grows fastest at ~26.4% CAGR through the rapid expansion of the online channel, premium product positioning, and growing consumer willingness to pay for high-quality plant-based alternatives. Fish Products grow at ~22.5% CAGR through strong consumer familiarity and broad retail adoption.
Executive Summary
The Europe plant-based seafood market expanded from USD 84.7 Million in 2025 to an estimated USD 108.8 Million in 2026. The market is underpinned by Europe's large health-conscious consumer base, growing environmental awareness, and increasing availability of innovative plant-based seafood products across retail channels. These structural demands are supporting expansion at a rate that significantly outpaces overall food market growth. The market is projected to reach USD 540.4 Million by 2034. Fish Products at 48.6% lead through high consumer familiarity and product innovation. Supermarkets and Hypermarkets at 45.8% dominate distribution. Germany leads regionally at 26.8%.
Key Market Insights
|
Insight |
Data |
|
Dominant Product Type |
Fish Products – 48.6% share (2025) |
|
Dominant Distribution Channel |
Supermarkets and Hypermarkets – 45.8% share (2025) |
|
Leading Country |
Germany – 26.8% share (2025) |
|
Market Opportunity |
Online channel expansion, premium product innovation, Southern European market penetration, foodservice adoption |
Key Analytical Observations Supporting the Above Data:
- Fish Products at 48.6%: Fish products dominate due to high consumer familiarity with seafood flavors, extensive product availability across European retail, and strong R&D investments replicating popular species such as tuna, salmon, and cod.
- Supermarkets and Hypermarkets at 45.8%: This channel dominates through high foot traffic, mainstream shelf placement, and dedicated plant-based food sections in leading European retail chains, driving both trial and repeat purchase.
- Germany at 26.8%: Germany leads due to strong environmental policy frameworks, high consumer health awareness, robust food innovation ecosystem, and well-developed plant-based food retail infrastructure across the country.
Europe Plant-Based Seafood Market Overview
Europe plant-based seafood market is positioned at a unique intersection: a highly environmentally conscious consumer base, ambitious EU sustainability targets under the Farm-to-Fork Strategy, and a well-developed food retail infrastructure creating one of the most commercially active plant-based seafood markets globally. The market structure is characterized by rapid product innovation and expanding distribution reach.
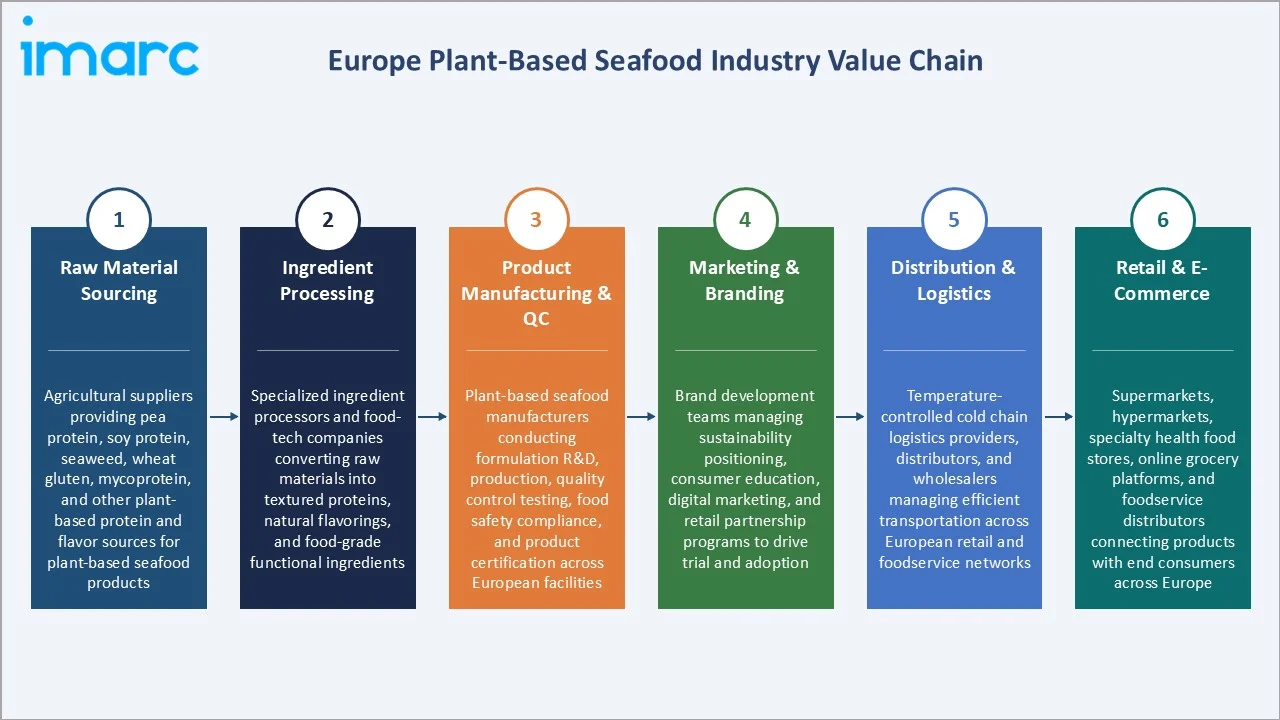
The Europe plant-based seafood ecosystem integrates raw material suppliers, specialized ingredient processors, innovative food manufacturers, quality certification bodies, and a well-organized retail and foodservice distribution network. Macroeconomic factors include EU sustainability directives, growing vegan and flexitarian population, rising health consciousness, and increasing investment in alternative protein technologies.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
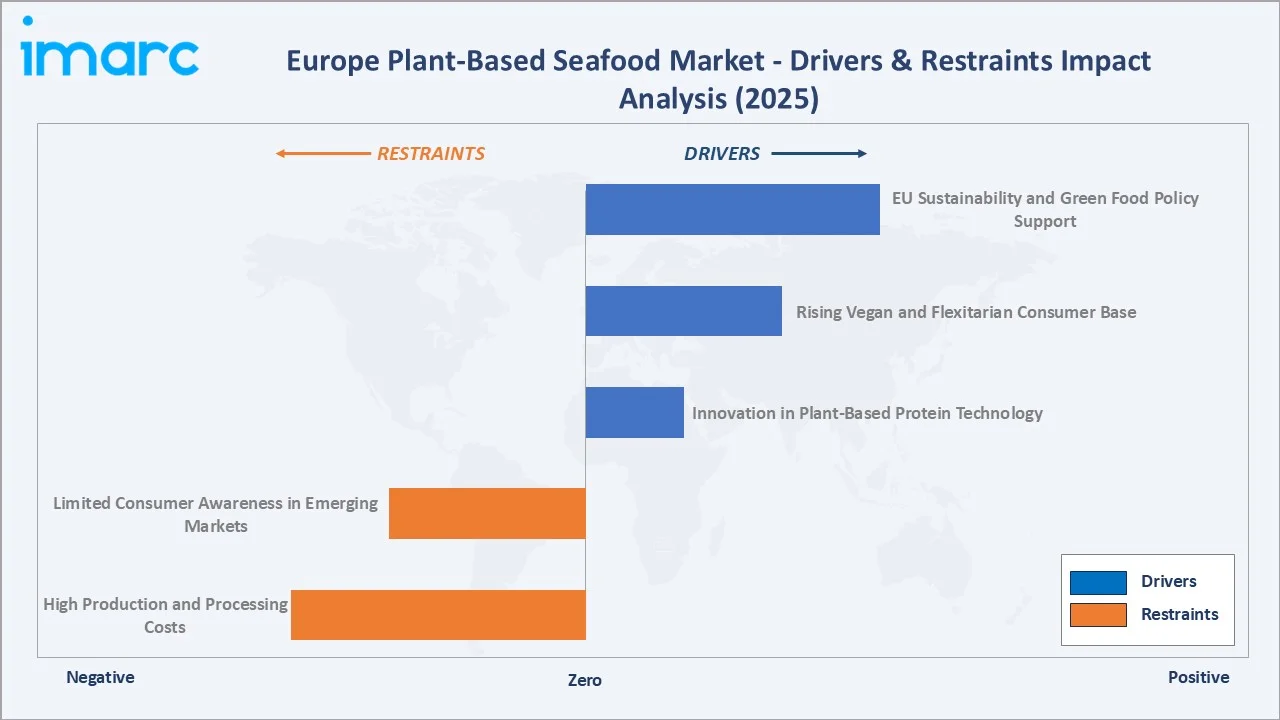
- Rising Vegan and Flexitarian Consumer Base: Growing adoption of vegan and flexitarian diets across Europe is accelerating demand for plant-based seafood alternatives. Consumers are increasingly seeking protein-rich, ethical, and sustainable food options. According to industry estimates, over 3.5 million Europeans identify as vegan, with the flexitarian population growing rapidly across Germany, UK, and France, making plant-based seafood an attractive growth segment for both new and established food brands.
- EU Sustainability and Green Food Policy Support: The EU Farm-to-Fork Strategy and European Green Deal are creating a favorable regulatory environment for alternative proteins, including plant-based seafood. Government-backed sustainability mandates are encouraging food manufacturers to develop and commercialize innovative products, with the EU targeting a 25% organic farming share and significant reduction in conventional meat and fish consumption by 2030, directly supporting plant-based seafood market expansion.
- Innovation in Plant-Based Protein Technology: Continuous advancements in food technology, including improved high-moisture extrusion, fermentation-derived proteins, and precision ingredient formulation, are enhancing the taste, texture, and nutritional profile of plant-based seafood products. These innovations are making plant-based seafood increasingly indistinguishable from conventional options and driving mainstream consumer adoption across European markets.
- Growing Health and Environmental Consciousness: Rising consumer awareness about environmental sustainability, ocean overfishing, and the health benefits of plant-based diets is driving market growth. Consumers are actively choosing plant-based seafood as a sustainable and healthier alternative, reducing carbon footprint while maintaining protein intake.
Market Restraints
- High Production and Processing Costs: The manufacturing of plant-based seafood requires specialized ingredients, advanced processing technologies, and significant R&D investments, resulting in higher production costs compared to conventional seafood. These elevated costs translate to premium retail pricing, limiting adoption among price-sensitive consumer segments and constraining mass market penetration.
- Limited Consumer Awareness in Emerging European Markets: While Western European markets show strong adoption, consumer awareness of plant-based seafood remains limited in parts of Southern and Eastern Europe. Cultural food preferences, limited product availability, and lower digital marketing penetration in these regions constrain broader market development.
- Taste and Texture Acceptability Challenges: Despite significant technological advances, plant-based seafood products still face consumer skepticism regarding taste, texture, and mouthfeel compared to conventional seafood. Overcoming consumer reluctance in the mainstream market beyond early adopters and health-conscious segments remains a critical challenge for market participants.
Market Opportunities
- Online Channel Expansion: Rapid growth in e-commerce and direct-to-consumer food platforms across Europe is creating new distribution opportunities for plant-based seafood brands. Online channels enable wider geographic reach, supporting targeted marketing to health-conscious and sustainability-oriented consumer segments, with online plant-based food sales growing at over 26% CAGR.
- Premium and Artisanal Product Launches: Growing consumer willingness to pay a premium for high-quality, sustainably sourced, and innovative plant-based seafood products is creating significant opportunities for premium product development and niche market positioning across European markets, particularly in the UK, Germany, and Scandinavia.
Market Challenges
- Supply Chain Complexity for Novel Ingredients: Sourcing sustainable, non-GMO, and high-quality plant-based proteins for seafood alternatives requires complex and often fragmented supply chains. Ensuring consistent ingredient quality, managing supply chain risks, and maintaining cold chain integrity remain key operational challenges for manufacturers.
- Regulatory Compliance and Labelling Standards: Navigating diverse European regulations on food labelling, novel food ingredients, and health claims presents significant compliance complexity. Varying national regulations across European countries add cost and operational burden for market participants seeking pan-European distribution.
Emerging Market Trends
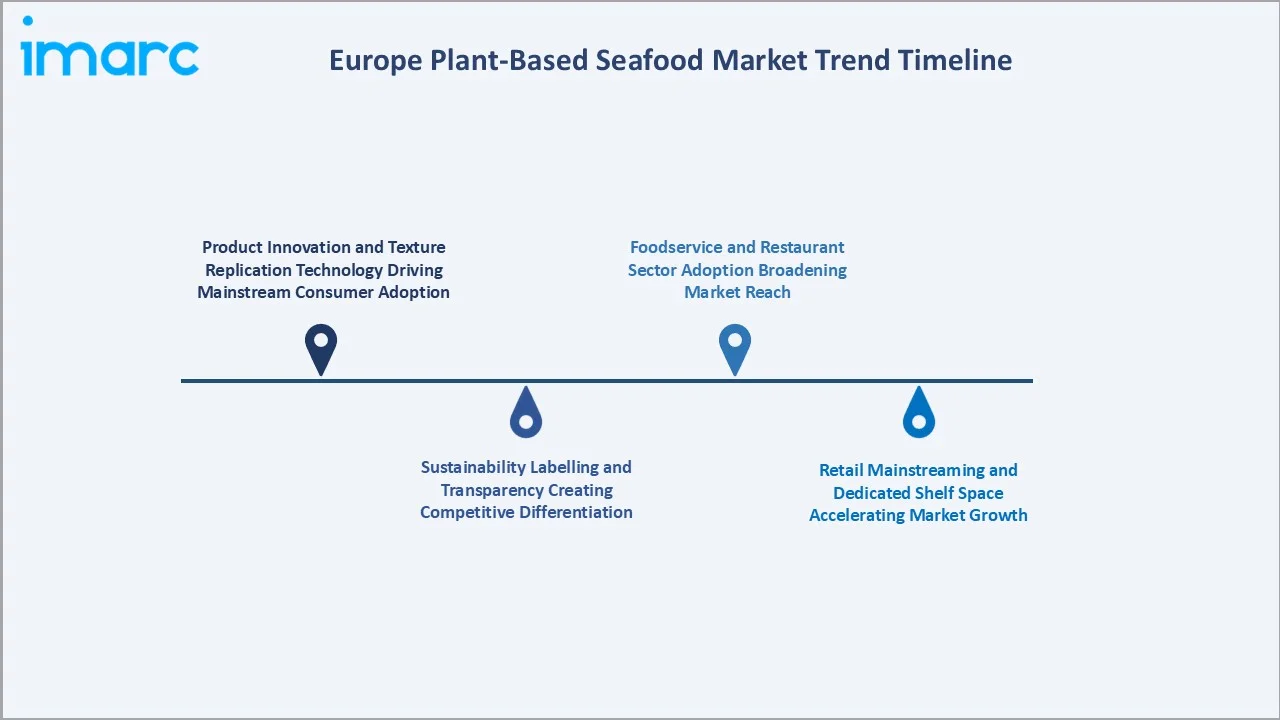
1. Product Innovation and Texture Replication Technology Driving Mainstream Consumer Adoption
Advanced food technology is enabling manufacturers to replicate the taste, texture, and mouthfeel of conventional seafood with increasing accuracy. Investment in proprietary high-moisture extrusion processes and novel ingredient blends is driving a wave of premium plant-based seafood products that are expanding consumer acceptance beyond early adopters into mainstream retail.
2. Sustainability Labelling and Transparency Creating Competitive Differentiation
Consumers across Europe are demanding transparency regarding the environmental impact, ingredient sourcing, and nutritional profile of plant-based seafood products. Brands investing in clear sustainability labelling, third-party certifications such as organic and carbon-neutral claims, and transparent supply chains are gaining significant competitive advantages in the European market.
3. Retail Mainstreaming and Dedicated Shelf Space Accelerating Market Growth
Leading European supermarket chains including Tesco, Carrefour, Lidl, and Aldi are dedicating increasing shelf space to plant-based seafood products, signaling growing mainstream acceptance. This retail-level commitment is accelerating consumer trial and adoption, moving plant-based seafood from specialty health stores to everyday grocery shopping.
4. Foodservice and Restaurant Sector Adoption Broadening Market Reach
Growing adoption of plant-based seafood in European restaurants, quick-service chains, and foodservice establishments is broadening market reach beyond retail. Celebrity chef endorsements, sustainability-focused restaurant concepts, and increasing consumer demand for plant-based menu options are driving foodservice channel growth across Europe.
Industry Value Chain Analysis
The Europe plant-based seafood value chain is a highly integrated system spanning raw material sourcing to end consumer delivery. The chain encompasses agricultural raw material suppliers, specialized ingredient processors, innovative food manufacturers, quality certification bodies, and a well-developed retail and foodservice distribution network across European countries.
|
Stage |
Key Participants |
|
Raw Material Sourcing |
Agricultural suppliers providing pea protein, soy protein, seaweed, wheat gluten, mycoprotein, and other plant-based protein and flavor sources for plant-based seafood products |
|
Ingredient Processing |
Specialized ingredient processors and food-tech companies converting raw materials into textured proteins, natural flavorings, and food-grade functional ingredients for plant-based seafood |
|
Product Manufacturing & QC |
Plant-based seafood manufacturers conducting formulation R&D, production, quality control testing, food safety compliance, and product certification across European facilities |
|
Marketing & Branding |
Brand development teams managing sustainability positioning, consumer education, digital marketing, and retail partnership programs to drive trial and adoption |
|
Distribution & Logistics |
Temperature-controlled cold chain logistics providers, distributors, and wholesalers managing efficient transportation across European retail and foodservice networks |
|
Retail & E-Commerce |
Supermarkets, hypermarkets, specialty health food stores, online grocery platforms, and foodservice distributors connecting products with end consumers across Europe |
The product manufacturing and quality control stage represents the most commercially consequential value chain stage for plant-based seafood, where significant R&D investment in texture replication and flavor development directly determines consumer acceptance and market growth rates.
Technology Landscape in the Europe Plant-Based Seafood Industry
High-Moisture Extrusion Technology
High-moisture extrusion is the primary technology enabling realistic muscle-like textures in plant-based seafood products. This advanced process aligns plant proteins to create fibrous structures mimicking the flakiness and chewiness of conventional fish and shellfish. Ongoing improvements in extrusion equipment design and process parameters are enabling manufacturers to produce increasingly sophisticated textures at commercial scale, directly supporting consumer acceptance.
Fermentation and Mycoprotein Technology
Fermentation-based technologies, including mycoprotein production, are enabling the development of highly nutritious and texturally superior plant-based seafood alternatives. These technologies offer significant advantages in protein quality, essential amino acid profile, and environmental footprint compared to other plant proteins. Fermentation-derived ingredients are increasingly being integrated into mainstream plant-based seafood product formulations across Europe.
Flavor Encapsulation and Natural Seafood Flavoring
Advanced flavor encapsulation techniques and natural seafood-derived flavor compounds are being used to enhance the authentic seafood taste profile of plant-based alternatives. The use of algae-based omega-3 fatty acids, natural seaweed extracts, and proprietary flavor encapsulation systems is improving consumer acceptance and enabling premium product positioning across European markets.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Product Type |
Fish Products |
48.6% |
2025 |
|
Distribution Channel |
Supermarkets and Hypermarkets |
45.8% |
2025 |
|
Country |
Germany |
26.8% |
2025 |

By Product Type
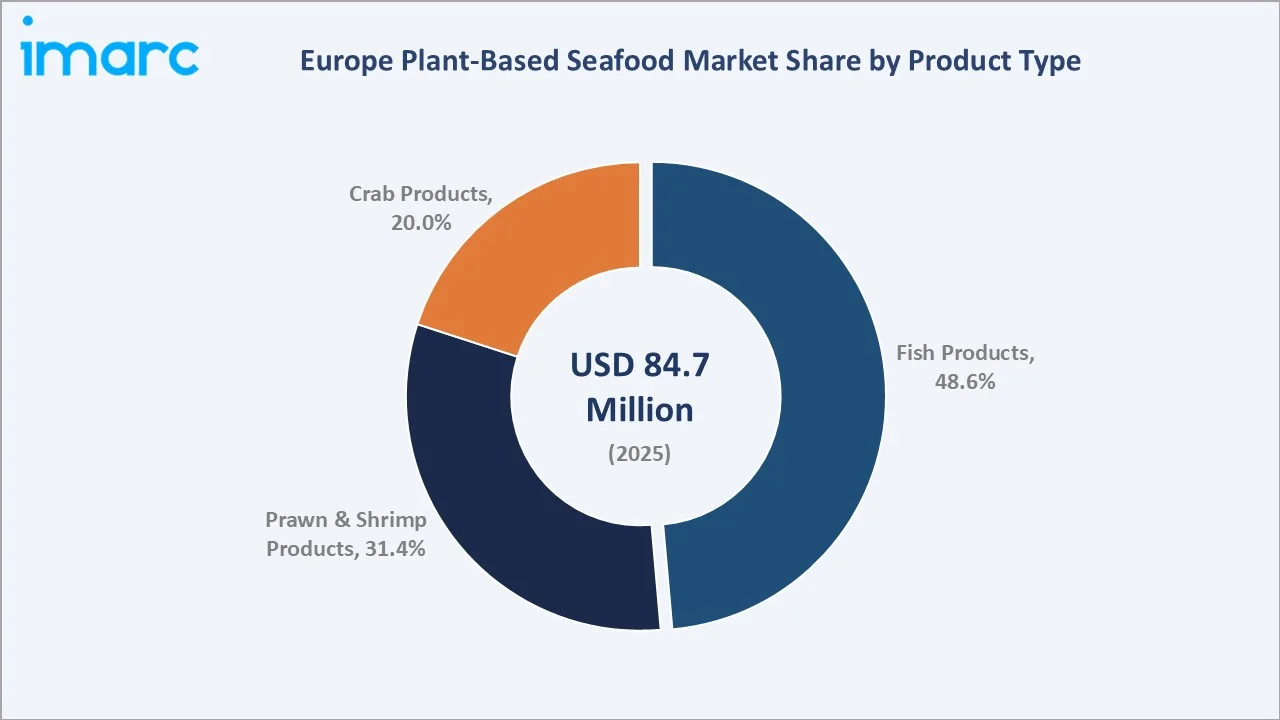
Fish Products lead at 48.6% (2025). The fish products segment dominates the Europe plant-based seafood market through high consumer familiarity with fish-based foods, extensive product availability across European retail channels, and strong investments replicating popular species such as tuna, salmon, and cod. The segment is projected to grow at a CAGR of ~22.5% during 2026-2034, driven by continued product innovation and expanding mainstream retail distribution.
To access detailed market analysis, Request Sample
Prawn & Shrimp Products at 31.4% represent the second-largest segment, growing at ~21.8% CAGR through the popularity of shrimp-based dishes across European cuisines and restaurant adoption. Crab Products at 20.0% are growing at ~23.1% CAGR through premium restaurant adoption and innovative product launches targeting sustainability-conscious fine dining consumers.
By Distribution Channel
Supermarkets and Hypermarkets lead at 45.8% (2025). This channel dominates through high retail foot traffic, mainstream product visibility, and increasing dedicated plant-based food sections in leading European retail chains. The segment is expected to grow at ~21.2% CAGR during 2026-2034, supported by major retailers actively expanding plant-based offerings and providing premium shelf placement to support consumer trial.
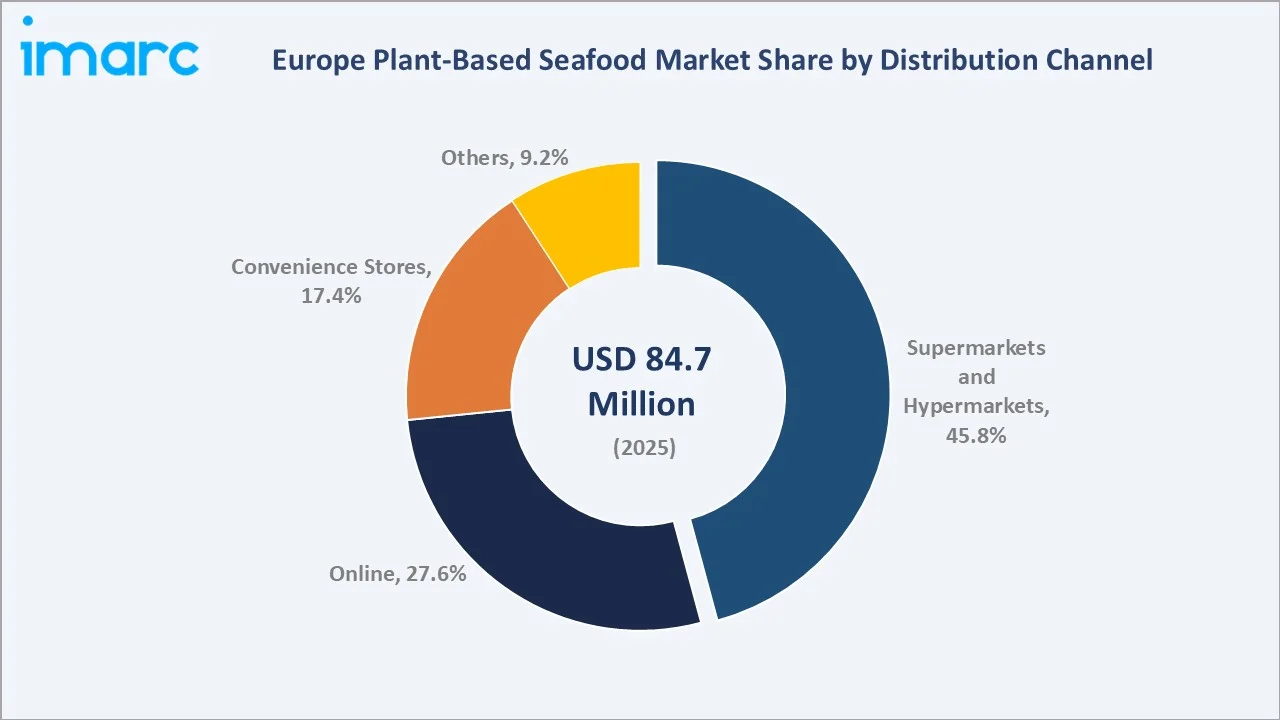
Online channels at 27.6% are the fastest-growing distribution segment at ~26.4% CAGR, benefiting from the rise of direct-to-consumer platforms, subscription food boxes, and increasing consumer comfort with online grocery shopping across Europe. Convenience Stores at 17.4% serve impulse purchase occasions, while Others at 9.2% includes foodservice establishments and specialty health food outlets.
Regional Market Insights
|
Country |
Share (2025) |
Key Europe Plant-Based Seafood Market Drivers & Characteristics |
|
Germany |
26.8% |
Driven by strong environmental policy frameworks, high consumer purchasing power, robust food innovation ecosystem, and well-developed plant-based food retail infrastructure across major cities. |
|
United Kingdom |
22.7% |
Supported by one of Europe's highest vegan and flexitarian populations, strong consumer demand for sustainable food, and active product innovation from UK-based food-tech companies and startups. |
|
France |
20.4% |
Growing health consciousness, sophisticated culinary culture increasingly embracing plant-based alternatives, and increasing mainstream retail adoption across major French supermarket chains. |
|
Italy |
12.6% |
Emerging market with growing consumer interest in sustainable food alternatives, driven by Mediterranean diet evolution, increasing foodservice adoption, and expanding urban retail availability. |
|
Spain |
10.8% |
Rising vegan consumer community, increasing product availability across Spanish retail chains, and government sustainability initiatives supporting plant-based seafood market expansion. |
|
Others |
6.7% |
Includes Benelux, Nordic countries, and Eastern Europe, with growing plant-based food awareness, increasing retail availability, and strong sustainability commitments driving demand. |
Germany's 26.8% market leadership reflects the country's strong environmental policy framework, Europe's highest per-capita organic food consumption, and a robust food innovation sector actively developing and commercializing plant-based seafood products for both domestic and export markets.
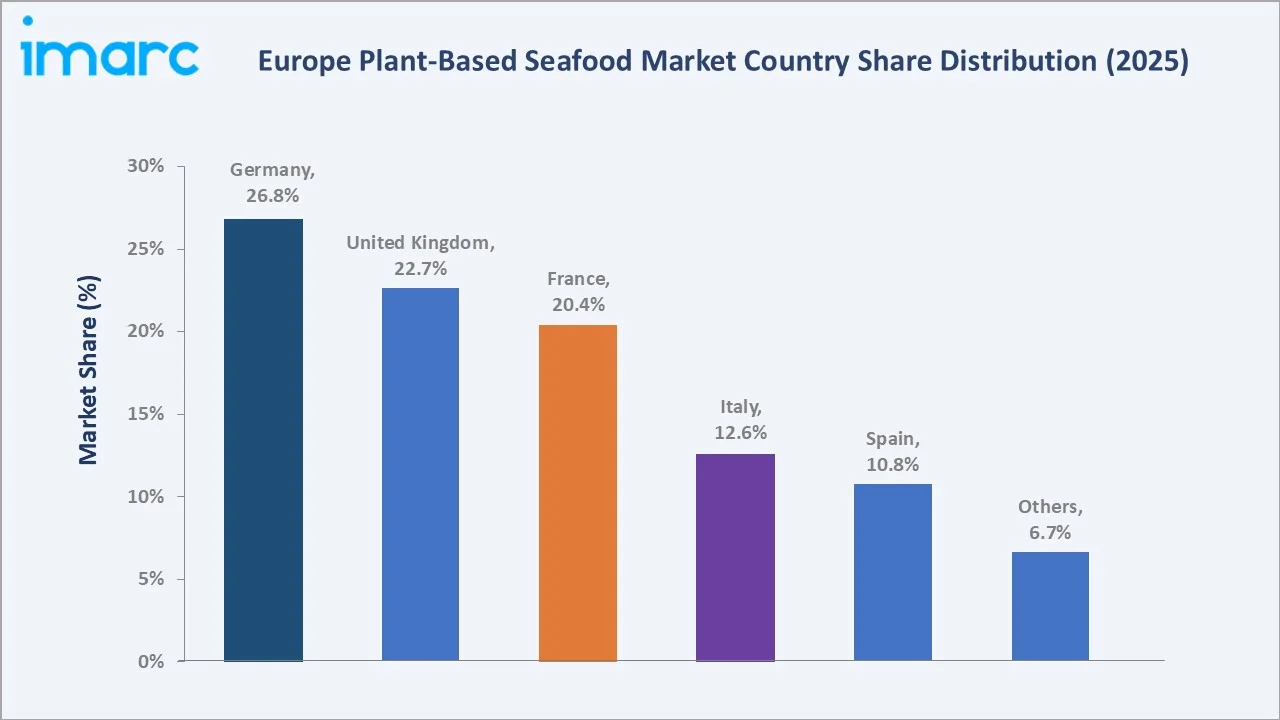
United Kingdom's 22.7% share is driven by one of Europe's highest vegan and flexitarian populations, strong retail support from major UK supermarket chains including Tesco and Sainsbury's, and a vibrant food startup ecosystem. France at 20.4% benefits from a sophisticated culinary culture increasingly embracing plant-based alternatives. Southern European markets including Italy at 12.6% and Spain at 10.8% are emerging growth frontiers with significant untapped market potential.
Competitive Landscape
The Europe plant-based seafood market competitive landscape is characterized by a dynamic mix of dedicated plant-based food companies, established food conglomerates expanding their sustainable product portfolios, and innovative food-tech startups. Competition is intensifying as consumer demand grows, attracting both local European brands and global players seeking to capitalize on the high-growth market opportunity.
|
Company |
Key Brands |
Market Position |
Core Strength |
|
Nestlé S.A. |
Garden Gourmet, Sweet Earth |
Market Leader |
Nestlé S.A. leverages its extensive global R&D capabilities, well-established retail relationships, and strong marketing resources to drive plant-based seafood adoption across European supermarkets and foodservice channels. |
|
Unilever PLC |
The Vegetarian Butcher |
Strong Challenger |
Unilever PLC leverages its massive European retail distribution network, sustainability brand commitments, and marketing expertise to accelerate mainstream consumer adoption of plant-based alternatives including plant-based seafood. |
|
Revo Foods |
The Revo Salmon, The Kraken, El Blanco, The Prime Cut |
Emerging Challenger |
Revo Foods leverages its proprietary 3D food printing and mycoprotein-based extrusion technology — the world's first commercialised at supermarket scale — to produce whole-cut plant-based seafood with industry-leading texture replication. |
The competitive landscape is evolving rapidly as food-tech innovation, EU sustainability mandates, and growing consumer demand attract new entrants and accelerate product development cycles. Key competitive differentiators include protein source innovation, texture replication quality, sustainability credentials, and retail distribution breadth.
Key Company Profiles
Nestlé S.A.
Nestlé S.A. is one of the world's leading food and beverage companies and a dominant player in the European plant-based food market, leveraging its extensive R&D capabilities, global supply chain, and strong retail relationships to drive sustainable food innovation and market growth.
- Key Brands: Garden Gourmet, Sweet Earth, and other plant-based food product lines marketed across European retail channels.
- Strategic Focus: Expanding plant-based food portfolio across European retail channels while investing in R&D for improved taste, texture, and nutritional profiles to achieve broader mainstream consumer adoption and sustainable revenue growth.
Unilever PLC
Unilever PLC is a global consumer goods company with a significant and rapidly growing presence in the European plant-based food market through its strategically developed plant-based brands, leveraging its massive retail distribution network, marketing capabilities, and sustainability brand positioning.
- Key Brands: The Vegetarian Butcher and other plant-based food brands distributed across European retail and foodservice channels.
- Strategic Focus: Leveraging extensive European retail relationships, marketing capabilities, and sustainability commitments to drive mainstream consumer adoption and achieve commercial scale for plant-based seafood and protein products.
Market Concentration Analysis
The Europe plant-based seafood market is moderately fragmented, with the top five players accounting for an estimated 45-55% of total market revenue. Large food conglomerates including Nestlé S.A. and Unilever PLC are expanding market positions through scale, retail relationships, and R&D investment, while dedicated plant-based seafood companies such as Good Catch are capturing significant share through product innovation and brand building.
Market concentration is evolving through two key forces: consolidation by large food corporations acquiring or partnering with innovative plant-based seafood startups to access proprietary technology and consumer brand loyalty, and continued growth of dedicated plant-based brands leveraging innovation and direct-to-consumer channels to build loyal consumer bases.
Investment & Growth Opportunities
Highest Growth Segments
Online distribution channel (~26.4% CAGR through e-commerce acceleration), Crab Products (~23.1% CAGR through premium restaurant adoption), premium product tier (~25% CAGR through health and sustainability trends), Southern European markets (~28% CAGR from underpenetrated base), and foodservice channel (~20% CAGR through restaurant adoption) represent Europe's highest-growth plant-based seafood investment vectors through 2034.
Emerging Investment Opportunities
Europe's plant-based seafood market offers compelling investment opportunities in food-tech innovation, particularly in texture replication and precision fermentation technologies. The foodservice channel represents a significant growth avenue, as restaurants increasingly adopt plant-based seafood to meet growing consumer demand for sustainable menu options.
Investment Themes
- Food technology investment in high-moisture extrusion and fermentation platforms for superior texture and nutritional profiles: Advanced food technology enabling realistic plant-based seafood textures represents the most commercially critical investment category, directly determining consumer acceptance and market expansion rates across European markets.
- Retail distribution expansion in Southern and Eastern European markets for above-average growth through underpenetrated geographies: Significant market expansion opportunity exists where plant-based seafood penetration remains low relative to Western European benchmarks, offering investors above-market return potential through first-mover advantage.
Future Market Outlook (2026-2034)
The Europe plant-based seafood market is projected to grow from USD 84.7 Million in 2025 to USD 108.8 Million in 2026, reaching USD 540.4 Million by 2034, registering a CAGR of 22.19% during 2026-2034. The market's anchor value of USD 230.54 Million in 2030 reflects a structural inflection as plant-based seafood transitions from specialty to mainstream consumer product across European markets.
Three structural forces define Europe plant-based seafood market growth through 2034: EU sustainability mandates creating permanent structural demand for alternative proteins across food supply chains; continuous food-tech innovation enabling higher-quality and increasingly cost-competitive plant-based seafood products; and growing retail mainstreaming accelerating consumer trial and driving sustained repeat purchase behavior.
Research Methodology
Primary Research
Primary research comprised structured interviews with Europe plant-based seafood industry stakeholders, including Product Development Directors, Sustainability Officers, Retail Category Managers, food-tech entrepreneurs, and consumer survey data from plant-based food consumers across Germany, United Kingdom, France, Italy, and Spain covering product preferences, purchase drivers, and consumption frequency.
Secondary Research
Secondary research encompassed European food industry trade publications, EU regulatory documents and Farm-to-Fork strategy documentation, company annual reports and investor presentations, food-tech innovation databases, retail scanner data, and sustainability certification body reports. Over 50 secondary sources were reviewed and cross-referenced for data validation.
Forecasting Models
Market revenue forecasts were developed using a bottom-up segmentation model combining product type, distribution channel, and regional analysis, with macroeconomic overlays including EU sustainability policy timelines, consumer income growth projections, vegan population growth rates, and food-tech innovation adoption curves calibrated to historical market data.
Europe Plant-based Seafood Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report | Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Product Types Covered | Fish Products, Prawn & Shrimp Products, Crab Products |
| Distribution Channels Covered | Supermarkets and Hypermarkets, Convenience Stores, Online, and Others |
| Countries Covered | Germany, France, United Kingdom, Italy, Spain, Others |
| Companies Covered | Nestlé S.A., Unilever PLC, Revo Foods, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Europe plant-based seafood market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the Europe plant-based seafood market.
- The study maps the leading, as well as the fastest-growing, regional markets.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Europe plant-based seafood industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Europe Plant-based Seafood Market Report
Europe plant-based seafood market size is estimated at USD 108.8 Million in 2026, driven by rising consumer demand for sustainable food alternatives, growing vegan and flexitarian populations, and strong retail distribution expansion across Germany, UK, France, and other major European markets.
Europe plant-based seafood market grows at 22.19% CAGR during 2026-2034, reaching USD 540.4 Million by 2034. Growth is sustained by EU sustainability mandates, continuous product innovation, expanding distribution networks, and increasing mainstream consumer adoption across all European markets.
Fish Products lead at 48.6% through high consumer familiarity with fish-based foods, extensive product availability across European retail channels, and strong investments in taste and texture replication technologies targeting popular species such as tuna, salmon, and cod.
Supermarkets and Hypermarkets lead at 45.8% through high retail foot traffic, mainstream product placement, and increasing dedicated plant-based food sections in major European retail chains including Tesco, Carrefour, Lidl, and other leading grocery retailers.
Germany leads at 26.8% through strong environmental policy support, high consumer health awareness, Europe's highest per-capita organic food consumption, and a robust food innovation ecosystem developing and commercializing plant-based seafood products.
Leading companies include Nestlé S.A., Unilever PLC, and Revo Foods, among other innovative food-tech companies and established food conglomerates active in the European market.
Europe plant-based seafood market is projected to reach approximately USD 230.54 Million by 2030, with mainstream retail adoption accelerating, online channel growth driving new consumer segments, and expanding foodservice adoption supporting continued double-digit growth rates across European markets.
Three priority investment opportunities: food-tech innovation in texture replication and precision fermentation technology platforms, retail distribution expansion in Southern and Eastern European markets with untapped demand, and online and direct-to-consumer channel development targeting health-conscious and sustainability-oriented European consumers.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade