
Europe Toys Market Size, Share, Trends and Forecasts by Product Type, Age group, Sales Channel, and Country, 2026-2034
Europe Toys Market Size, Share, Trends & Forecast (2026-2034)
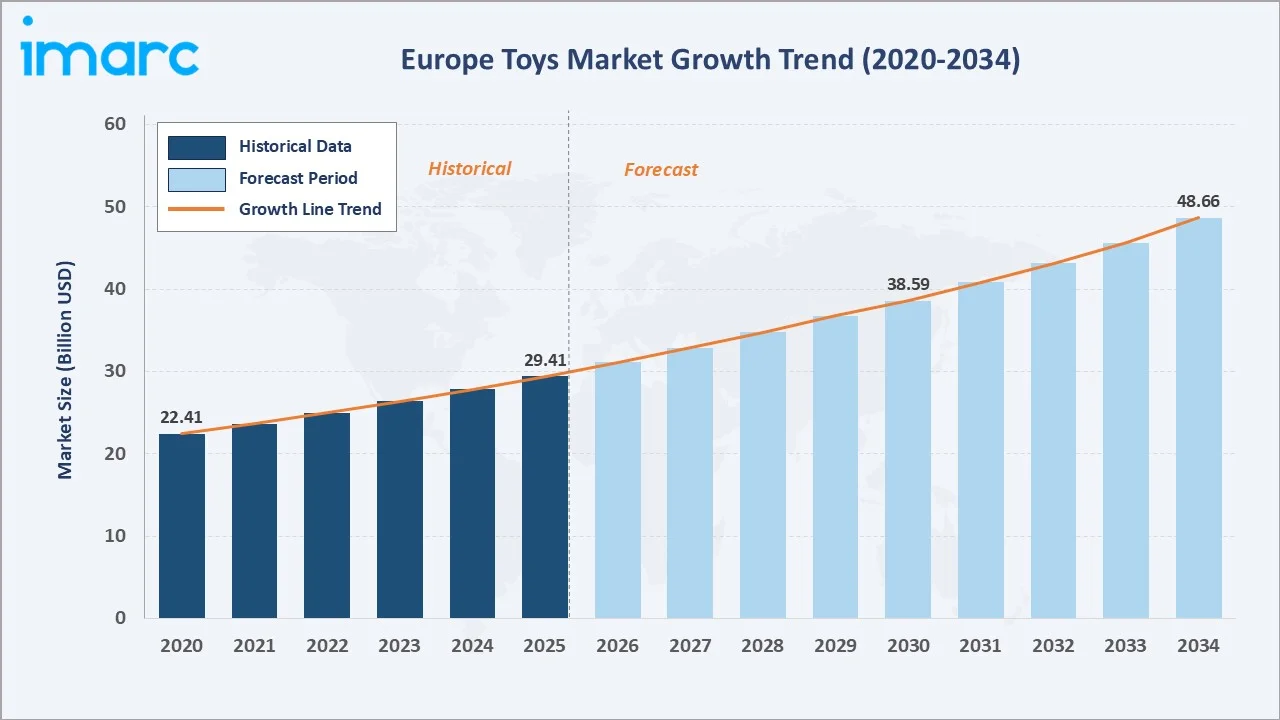
The Europe toys market size increased from USD 29.41 Billion in 2025 to USD 31.51 Billion in 2026 and is projected to reach USD 48.66 Billion by 2034, growing at a CAGR of 5.58% during 2026-2034. The market is driven by rising demand for smart toys, e-commerce expansion, growing parental spending on STEM-educational toys, and EU sustainability mandates. In 2024, approximately 3.55 million babies were born across the EU, with first-born children accounting for 46.6% of total births. This supports the Europe toys market by sustaining a steady base of young consumers and encouraging household spending on infant, preschool, educational, and developmental toys. Games and puzzles lead product type at 21.8%. The 5 to 10 years age group leads at 42.5%. Germany leads regionally at 23.5% (2025).
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 29.41 Billion |
|
Market Size (2026) |
USD 31.51 Billion |
|
Forecast Market Size (2034) |
USD 48.66 Billion |
|
CAGR (2026-2034) |
5.58% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Leading Product Type |
Games and Puzzles (21.8%, 2025) |
|
Leading Age Group |
5 to 10 Years (42.5%, 2025) |
|
Leading Country |
Germany (23.5%, 2025) |
The Europe toys market expanded from USD 22.41 Billion in 2020 to USD 29.41 Billion in 2025 and an estimated USD 31.51 Billion in 2026, driven by the post-pandemic surge in home-based play, accelerating e-commerce adoption across the continent, and rising parental investment in educational, tech-integrated toys. The market is projected to reach USD 38.59 Billion by 2030 and USD 48.66 Billion by 2034.
To get more information on this market, Request Sample
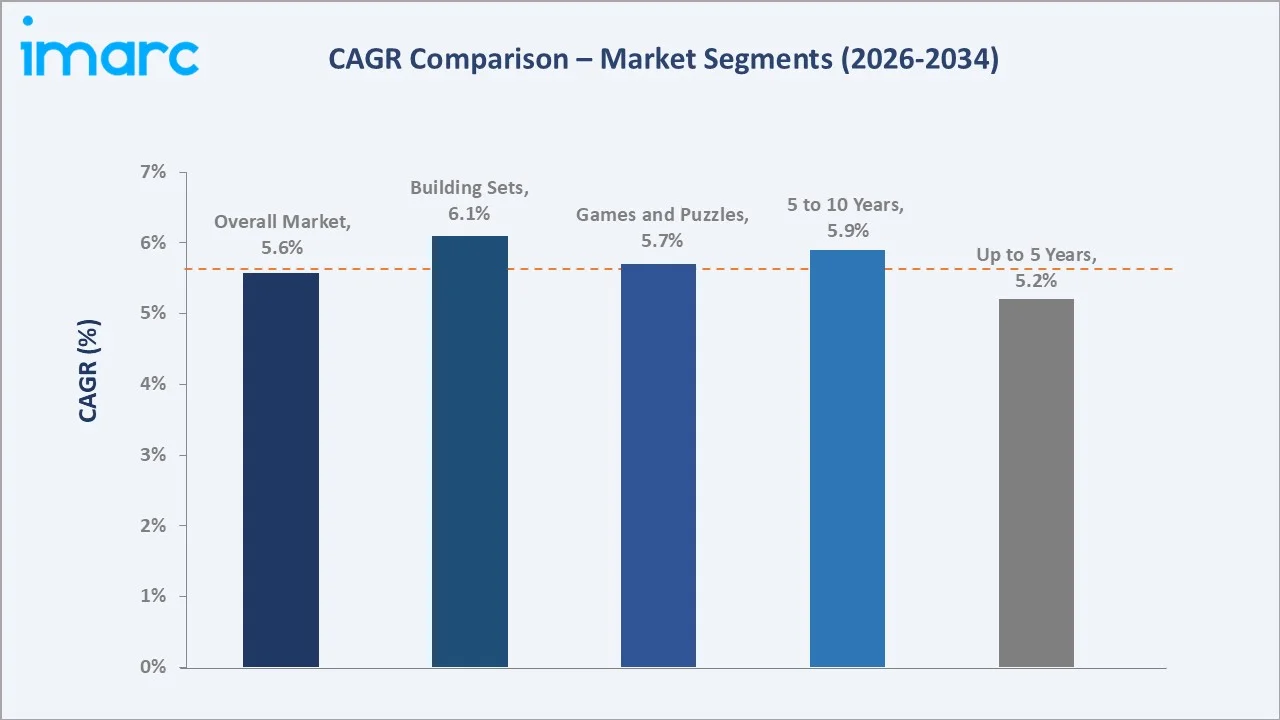
Games and puzzles grow at ~5.7% CAGR through family gaming culture and post-COVID indoor entertainment boom. Building sets grow at ~6.1% CAGR, the fastest product type segment, driven by LEGO's continued dominance and growing adult hobbyist demand. The 5-10 years age group grows at ~5.9% CAGR through franchise-linked toys and educational play adoption.
Executive Summary
The Europe toys market is experiencing sustained growth, supported by rising disposable incomes, growing consumer awareness of developmental benefits of play, and accelerating digital and smart toy integration. E-commerce platforms have fundamentally transformed distribution, giving European parents access to a wider variety of toys at competitive prices. The Europe smart toys market is particularly dynamic, with AI-enabled, sensor-equipped, and app-connected toys gaining rapid traction across Germany, France, the UK, and other major markets. Games and puzzles lead product type at 21.8%, and the 5-10 years age group leads at 42.5% of total market value.
Key Market Insights
|
Insight |
Data |
|
Leading Product Type |
Games and Puzzles - 21.8% share (2025) |
|
Leading Age Group |
5 to 10 Years - 42.5% share (2025) |
|
Leading Country |
Germany - 23.5% share (2025) |
|
Market Opportunity |
Smart toy AI integration; eco-toy expansion; STEM licensing; e-commerce scale-up |
Key Analytical Observations Supporting the Above Data:
- Games and Puzzles at 21.8%: Games and puzzles lead the market, fueled by the COVID-19-era family gaming revival, growing demand for board games across all age groups, and the rise of adult puzzle enthusiasts in markets like Germany, France, and the UK.
- 5 to 10 Years at 42.5%: The 5-10 years cohort leads the age group segment as this bracket drives the highest spend on franchise-linked toys, building sets, board games, and interactive outdoor products, all of which command premium price points in the Europe toys market.
- Germany at 23.5%: The Germany toys market dominates regionally due to the country's robust economy, strong STEM culture, high per-capita spending on quality educational toys, and Nuremberg Toy Fair's role as the global industry's leading annual trade event.
Europe Toys Market Overview
The Europe toys market encompasses a broad range of physical and digital products designed for children and adult collectors across seven core product categories: games and puzzles, building sets, dolls, action figures, sports and outdoor toys, plush, and others. Products are sold through supermarkets and hypermarkets, specialty stores, department stores, and online platforms, with e-commerce rapidly gaining share.
The market is shaped by diverse consumer preferences across Germany, the United Kingdom, France, Italy, Spain, and other European nations. The Europe baby toys market and the growing Europe smart toys market collectively drive the highest innovation and premiumization activity within the segment. Macroeconomic enablers include rising disposable incomes, EU toy safety regulation compliance standards, growing sustainability awareness, and accelerating AR and AI integration in toy product development.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
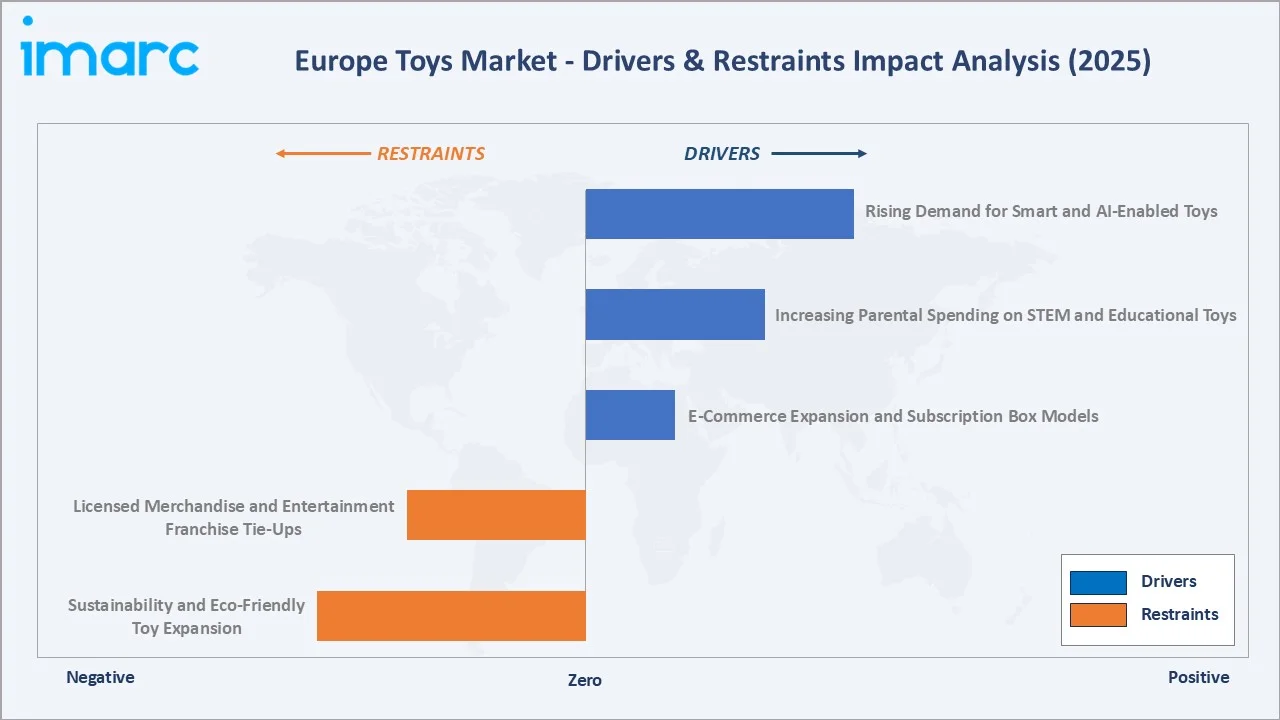
- Rising Demand for Smart and AI-Enabled Toys: The Europe smart toys market is growing rapidly as AI, sensors, and connectivity transform conventional play experiences. Smart toys that respond to voice commands, adapt to a child's learning pace, and integrate with educational apps are gaining adoption across Germany, the UK, France, and Scandinavian markets. In October 2024, Clementoni launched AIRO, an AI-enabled robot designed for children aged nine and up, reflecting the smart toy innovation acceleration.
- Increasing Parental Spending on STEM and Educational Toys: European parents are increasingly investing in toys that provide cognitive, developmental, and educational value. The Germany toys market particularly reflects high per-capita spending on premium STEM-aligned products. Building sets, coding kits, and science experiment toys are growing at above-market rates, supported by national curricula integrating STEM learning from early childhood.
- E-Commerce Expansion and Subscription Box Models: E-commerce platforms provide unprecedented access to toy variety, price comparison, and parental reviews across European markets. Curated subscription box models delivering age-appropriate toys monthly are particularly gaining traction in the UK and Germany, creating a recurring revenue channel for toy manufacturers.
Market Restraints
- Stringent EU Toy Safety Regulations and Certification: The EU toy safety standards impose rigorous compliance requirements on toy manufacturers. Meeting these standards increases product development lead times and costs, particularly for smaller manufacturers and new market entrants seeking to compete against established European and global brands.
- Rising Raw Material and Logistics Costs: Global supply chain disruptions, increased freight costs, and rising prices for plastics, metals, and electronic components have compressed profit margins for mid-tier toy manufacturers. Sustainability mandates requiring transition to eco-friendly packaging and recycled materials add further cost pressure, particularly for manufacturers with high-volume, low-margin product portfolios.
Market Opportunities
- Sustainability and Eco-Friendly Toy Expansion: European consumers' strong environmental consciousness creates a significant market opportunity for toys manufactured from sustainable materials and packaged in biodegradable or recycled alternatives.
- Licensed Merchandise and Entertainment Franchise Tie-Ups: Licensing agreements with major entertainment franchises, including film studios, gaming companies, and TV production houses, create recurring demand for branded action figures, building sets, and dolls. In March 2024, the LEGO Group introduced new LEGO DUPLO PEPPA PIG sets in collaboration with Hasbro, allowing toddlers to engage with the popular PEPPA PIG universe through colorful, age-appropriate building sets.
Market Challenges
- Competition from Digital Entertainment and Screen Time: Tablets, video games, and streaming content compete directly with traditional toys for children's attention and parental spending. Toy manufacturers must continuously innovate to integrate digital experiences into physical products, or risk substitution by purely digital entertainment alternatives, especially in the Above 10 Years age group segment.
- Seasonal Revenue Concentration: Most of the annual toy sales in Europe occur in Q4, driven by Christmas and holiday gifting. This strong seasonal concentration creates revenue volatility, inventory management challenges, and profitability pressures during off-peak quarters for retailers and manufacturers operating across European markets.
Emerging Market Trends
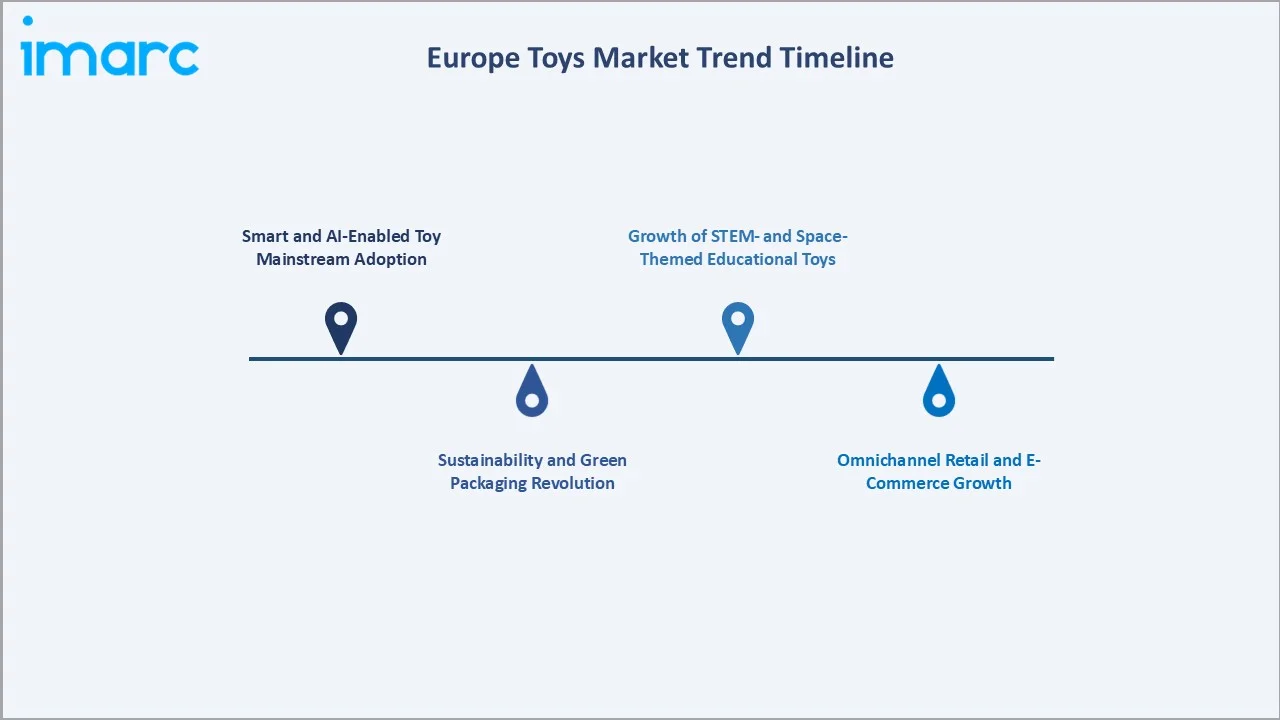
1. Smart and AI-Enabled Toy Mainstream Adoption
The Europe smart toys market has transitioned from niche novelty to a mainstream product category. AI-enabled toys capable of adapting to individual children's learning styles, AR-integrated play experiences, and IoT-connected smart toys are gaining widespread adoption across Germany, the UK, and France. In May 2026, SwitchBot expanded into home robotics with its new Kata Friends AI-powered cuddle robots. The smart companions feature app-customizable digital eyes, a built-in camera, and motorized arms and ears, combining interactive technology with pet-like engagement.
2. Sustainability and Green Packaging Revolution
European toy manufacturers are systematically transitioning to sustainable materials and eco-friendly packaging in response to consumer preferences and EU regulatory requirements. Cardboard packaging, plant-based plastics, and certified wood materials are replacing conventional plastics across product categories.
3. Growth of STEM- and Space-Themed Educational Toys
In January 2026, the European Space Agency (ESA) and Playmobil expanded their partnership with a new range of space-themed toys inspired by European Mars exploration, offering children an engaging way to explore space science and discovery through play. This collaboration highlights rising demand for toys that combine entertainment with science, technology, engineering, and space-learning concepts. Such partnerships are encouraging manufacturers to develop educational play products that promote curiosity, problem-solving, and early interest in STEM subjects.
4. Omnichannel Retail and E-Commerce Growth
European toy retailers are accelerating omnichannel strategies, integrating physical in-store experiences with digital discovery and purchasing. Online toy sales grew significantly post-pandemic and continue to gain share across all European markets. In October 2024, Ducklings Toy Shop opened a new, larger store at Five Valleys in Stroud, doubling its previous retail space. The expanded location enables the family-run business to offer a broader range of toys and games while hosting collector events, activities, and swap sessions, creating immersive, experience-focused retail environments for discerning European toy consumers.
Industry Value Chain Analysis
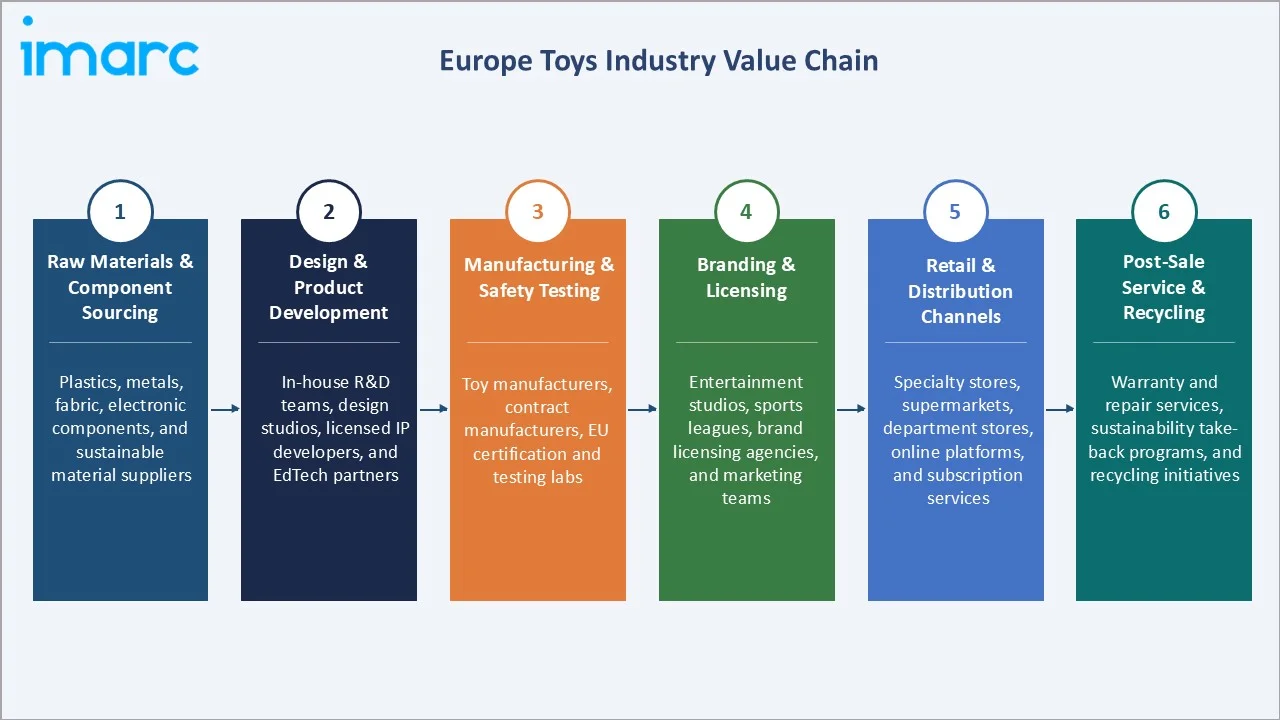
The Europe toys market value chain integrates raw material sourcing, product design and development, manufacturing and safety testing, branding and licensing, retail distribution, and post-sale service and recycling. Each stage is governed by stringent EU safety standards and increasingly shaped by sustainability requirements across the supply chain.
|
Stage |
Key Participants |
|
Raw Materials & Component Sourcing |
Plastics, metals, fabric, electronic components, and sustainable material suppliers. |
|
Design & Product Development |
In-house R&D teams, design studios, licensed IP developers, and EdTech partners. |
|
Manufacturing & Safety Testing |
Toy manufacturers, contract manufacturers, EU certification and testing labs. |
|
Branding & Licensing |
Entertainment studios, sports leagues, brand licensing agencies, and marketing teams. |
|
Retail & Distribution Channels |
Specialty stores, supermarkets, department stores, online platforms, and subscription services. |
|
Post-Sale Service & Recycling |
Warranty and repair services, sustainability take-back programs, and recycling initiatives. |
Manufacturing and safety testing represent the most compliance-intensive stages due to the EU toy safety standards. Branding and licensing are the highest value-added stages for leading manufacturers, as franchise-linked products command significant premium pricing and sustained demand cycles across European markets.
Technology Landscape in the Europe Toys Industry
Augmented Reality and Interactive Digital Integration
AR-integrated toys merge physical play with digital overlays, creating immersive experiences accessible via smartphones and tablets. AR game components encourage STEM skill development through problem-solving, critical thinking, and creativity challenges. The Spain smart toys market is experiencing growing AR toy adoption, particularly within the 5-10 Years and Above 10 Years age groups, as manufacturers tailor AR-enabled products to European language and cultural preferences.
Sustainable and Smart Material Innovation
European toy manufacturers are investing in smart material innovation, developing biodegradable plastics, FSC-certified wood components, recycled fabric plush, and water-based paint formulations that meet EU chemical safety standards. Sustainable toy lines are becoming commercially significant, particularly in Germany, the Netherlands, and Scandinavian markets where eco-consciousness is highest among European parents and gift buyers.
IoT Connectivity and App-Integrated Play Ecosystems
Connected toys integrating wireless charging, Bluetooth, Wi-Fi, and companion app ecosystems are gaining adoption across premium segments of the Europe toys market. App-connected toys provide additional educational content, progress tracking, and parental controls that enhance safety and developmental oversight. These connected ecosystems also create recurring digital revenue streams for manufacturers through in-app content and activity expansions beyond the initial toy purchase.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Product Type |
Games and Puzzles |
21.8% |
2025 |
|
Age Group |
5 to 10 Years |
42.5% |
2025 |
|
Sales Channels |
🔒 |
🔒 |
2025 |
|
Country |
Germany |
23.5% |
2025 |

By Product Type
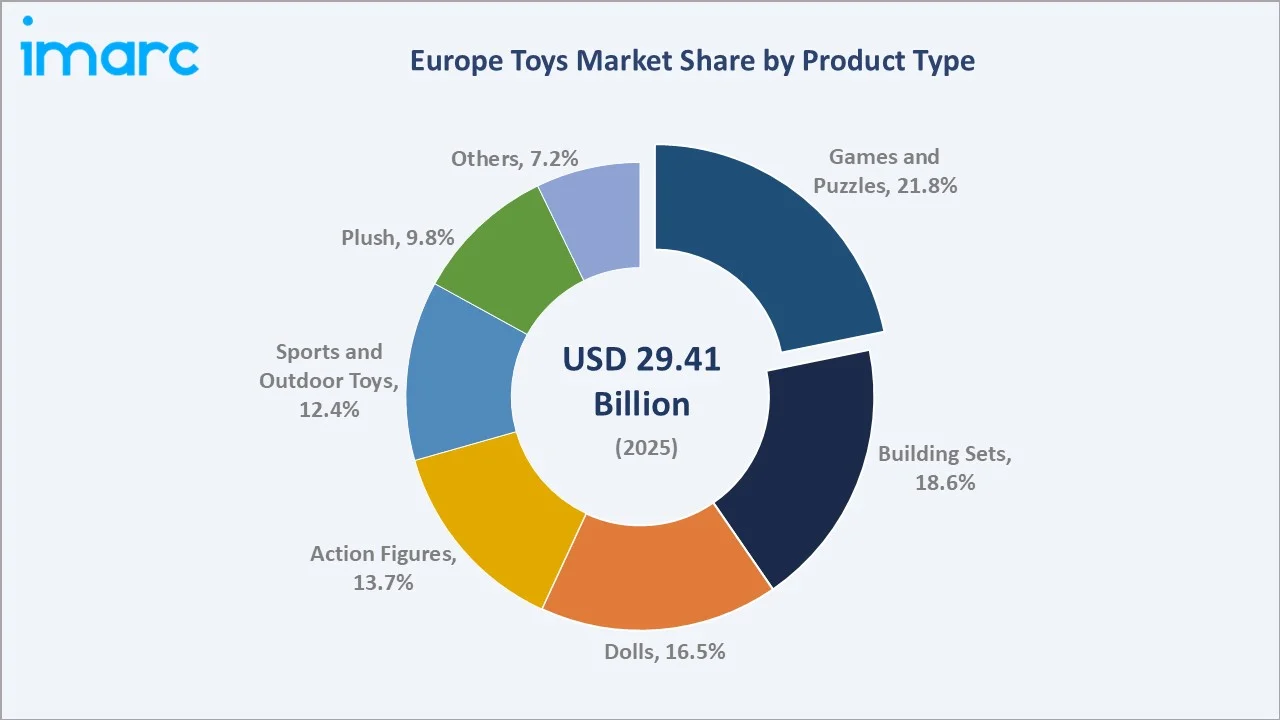
Games and puzzles lead at 21.8% (2025), driven by the enduring family bonding and social interaction appeal of board games and the post-pandemic indoor entertainment boom.
To access detailed market analysis, Request Sample
Building sets follow at 18.6%, recording the fastest product-type CAGR at ~6.1% through 2034, driven by premium franchise sets and STEM education curriculum integration. Dolls account for 16.5%, action figures for 13.7%, sports and outdoor toys for 12.4%, plush for 9.8%, and others for 7.2% of the 2025 market.
By Age Group
The 5 to 10 years age group leads at 42.5% (2025), representing the peak spend bracket where children actively engage with franchise-linked toys, building sets, board games, and interactive outdoor products that command premium price points.
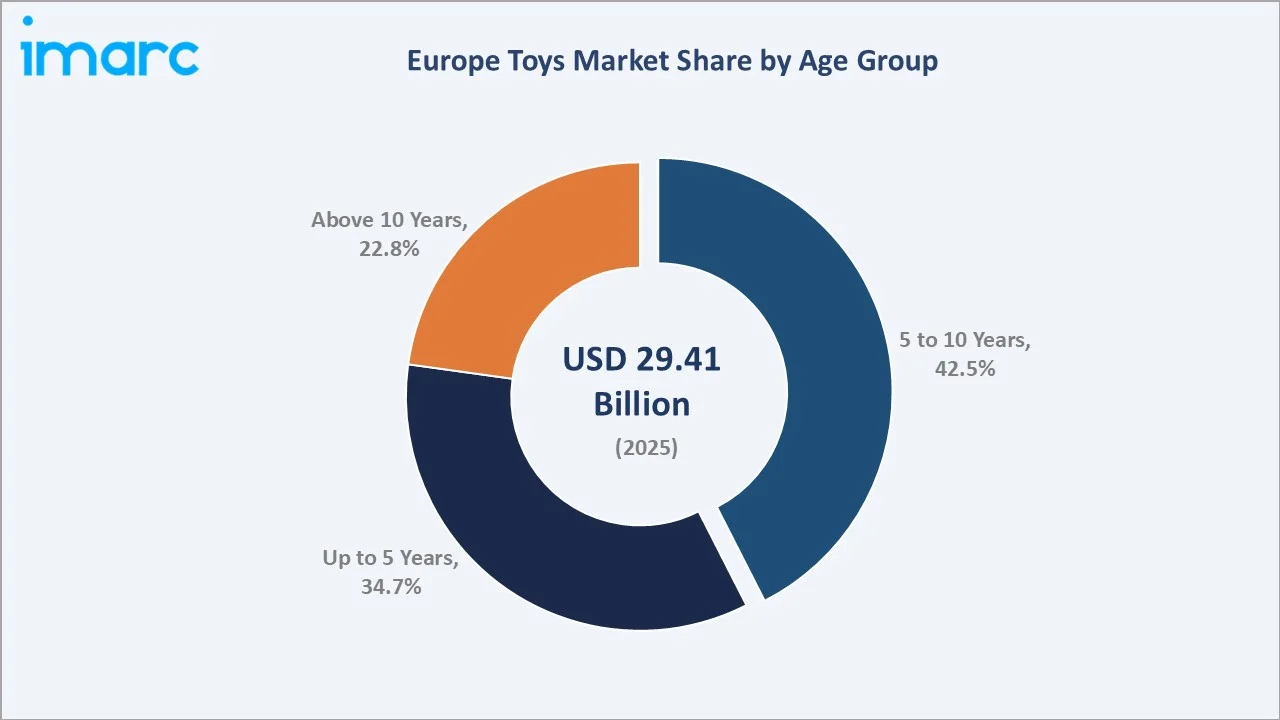
The up to 5 years segment accounts for 34.7%, driven by parental emphasis on safety-certified sensory, plush, and developmental toys for early childhood. Above 10 years accounts for 22.8%, a growing segment driven by adult collectors and complex STEM toys.
Regional Market Insights
|
Country |
Share (2025) |
Key Europe Toys Market Drivers & Characteristics |
|
Germany |
23.5% |
Reflecting strong STEM education culture, the Germany toys market benefits from high per-capita spending on premium educational and eco-friendly toys. |
|
United Kingdom |
21.8% |
Reflecting strong entertainment franchise influence, high e-commerce toy sales penetration, and demand for licensed products, board games, and building sets. |
|
France |
18.7% |
Reflecting cultural emphasis on creativity and early childhood education, the France smart toys market is growing rapidly alongside demand for art kits, educational toys, and technology-integrated products. |
|
Italy |
14.6% |
Reflecting traditional family-oriented cultural values, Italian consumers favor board games, outdoor toys, and dolls promoting social interaction. |
|
Spain |
10.5% |
Reflecting growing demand for outdoor sports toys, tech-integrated products, and affordable educational toys. |
|
Others |
10.9% |
Reflecting diverse consumption patterns across the Netherlands, Poland, Scandinavia, and other European markets, where eco-friendly toys, STEM products, and licensed merchandise are gaining share. |
Germany's 23.5% dominance reflects the Germany toys market's fundamental structural advantages: Europe's largest consumer economy, the world-famous Nuremberg Toy Fair, and a strong cultural emphasis on high-quality, educationally enriching, and sustainably produced toys. The UK's 21.8% share reflects the influence of entertainment franchise licensing, with consumers demonstrating strong affinity for franchise-linked building sets, action figures, and board games.
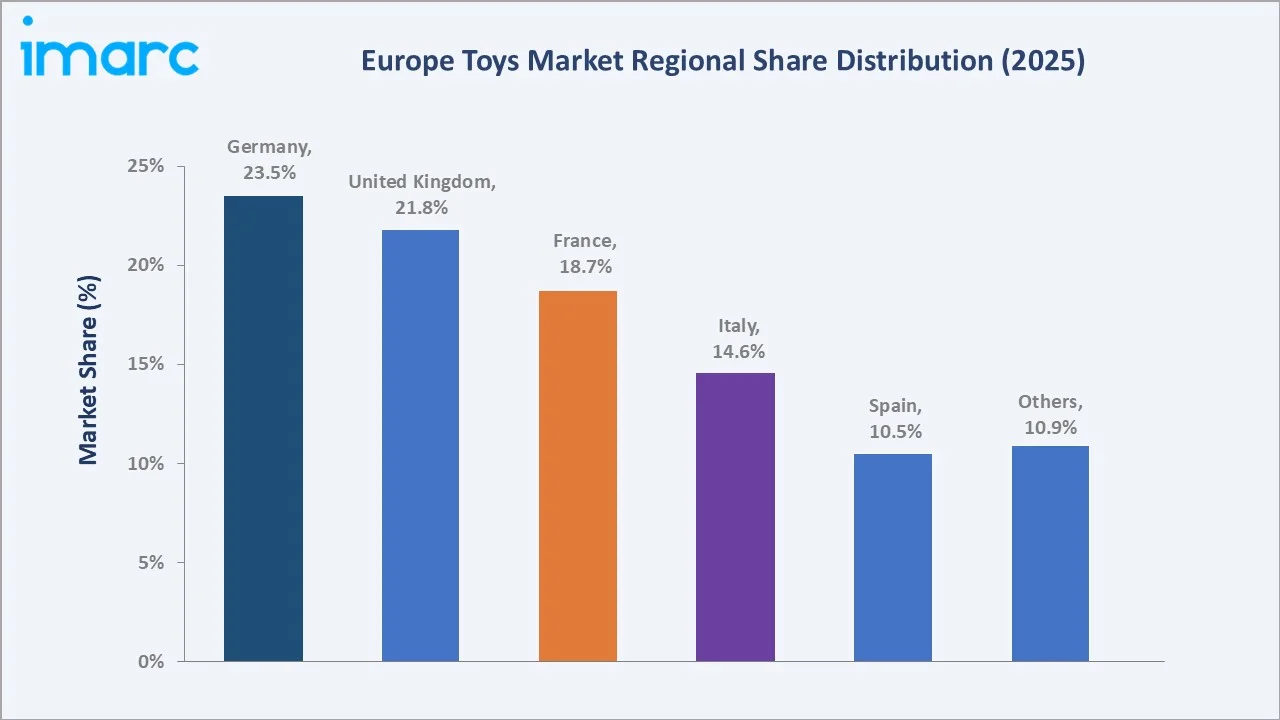
France's 18.7% share reflects its dual affinity for traditional creative toys and growing France smart toys market adoption, particularly in the 5-10 Years age group. Italy's 14.6% reflects family-centered purchase behavior and strong specialty channel influence. Spain's 10.5% share is supported by active outdoor toy culture and the emerging Spain smart toys market, driven by manufacturer investment in AR-integrated and AI-enabled product lines tailored to Spanish consumer preferences.
Competitive Landscape
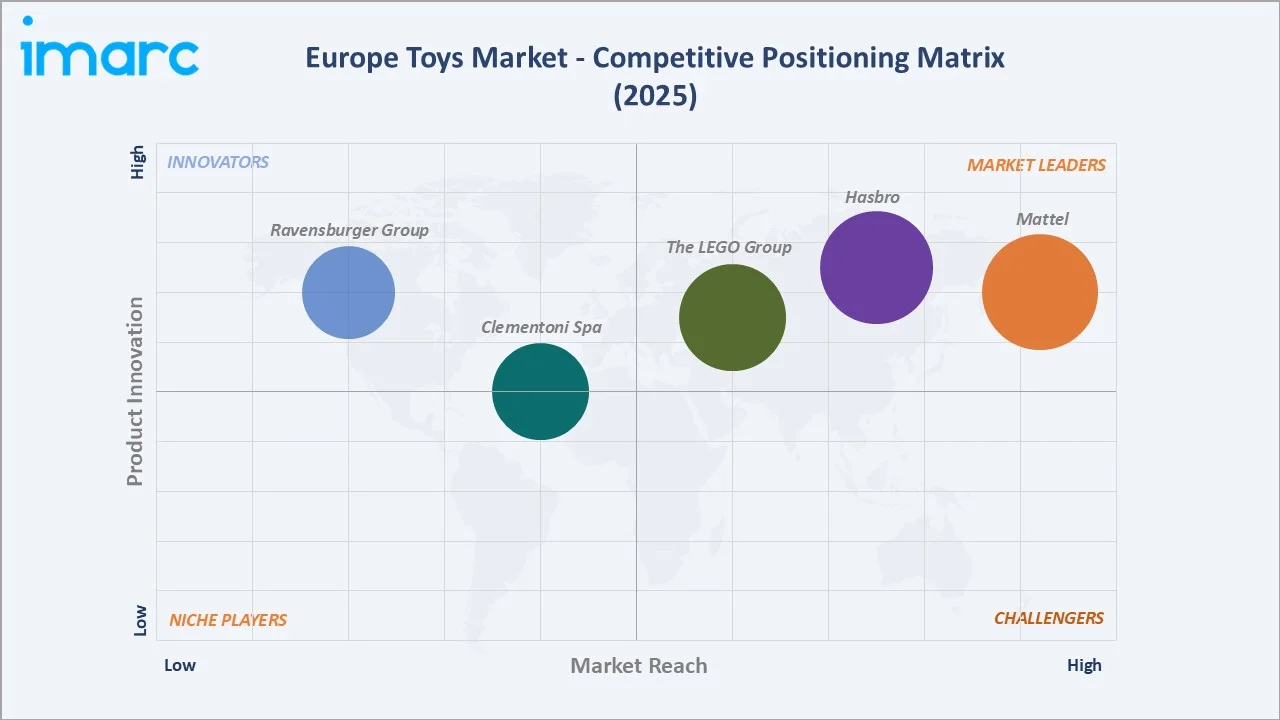
The Europe toys market features a moderately concentrated competitive structure dominated by global toy giants, alongside strong regional European players. Competition centers on franchise licensing depth, product innovation, sustainability credentials, omnichannel distribution capability, and brand heritage. Strategic moves include licensing partnerships with entertainment studios, retail expansion, and acquisition of complementary brands.
|
Company |
Key Brands |
Market Position |
Core Strength |
|
The LEGO Group |
LEGO DUPLO, Technic, BrickHeadz, LEGO Fortnite |
Market Leader |
LEGO Group is the largest toy manufacturer in the world by sales and a dominant leader in the European toy market. |
|
Hasbro |
STAR WARS, Marvel, Avalon Hill, Ghostbusters, The Legend of Zelda, Magic: The Gathering |
Market Leader |
Hasbro plays a major role in the European toy and entertainment market through localized brand licensing, regional partnerships, and major franchise distribution. |
|
Mattel |
American Girl, Barbie, DC Universe, Disney, Hot Wheels, Harry Potter, Fisher-Price, Jurassic World, Marvel, Star Wars |
Market Leader |
Mattel plays a major role in the European toy market as a leading brand manager and IP company, driven by key markets like the UK, Germany, and France. |
|
Clementoni Spa |
Baby Clementoni, Soft Clemmy, Disney Baby, Education Clementoni, Science & Play Lab, Science Museum Build |
Established Player |
Clementoni Spa is a leading Italian manufacturer and key European market player specializing in educational toys, board games, and puzzles. |
|
Ravensburger Group |
Jigsaw Puzzles, GraviTrax, Disney Lorcana |
Innovator |
The Ravensburger Group is a leading European market leader and trusted provider of jigsaw puzzles, board games, and leisure/activity products |
Competition is intensifying around Europe smart toys market leadership, sustainability credentials, and omnichannel capability. Global players are acquiring regional specialists and forging entertainment franchise partnerships to defend premium market positions, while emerging players are leveraging eco-toy and smart toy niches to establish differentiated market footprints across European consumer segments.
Key Company Profiles
The LEGO Group
The LEGO Group is the world's largest toy company by revenue and the undisputed leader in the Europe toys market's Building Sets segment. The company operates globally with particularly dominant positions in Germany, the UK, and France. The company's franchise-linked theme sets drive sustained demand across children and adult collector segments.
- Key Brands: LEGO DUPLO, Technic, BrickHeadz, LEGO Fortnite.
- Key Developments: In January 2024, The LEGO Group, Hasbro, and Merlin Entertainments collaborated to bring the popular PEPPA PIG character to life through LEGO DUPLO products, combining established entertainment and toy brands to create engaging play experiences for young children.
- Strategic Focus: Expanding DUPLO range for the Europe baby toys market, integrating digital and physical play through LEGO Horizon Adventures and app connectivity, advancing sustainability targets for sustainable materials.
Hasbro
Hasbro is a toy and entertainment company with a leading position in the Europe toys market across games and puzzles, action figures, and arts and crafts categories. Hasbro's European operations benefit from deep entertainment franchise relationships with Marvel, Peppa Pig, and others, enabling consistent licensed product launches.
- Key Brands: STAR WARS, Marvel, Avalon Hill, Ghostbusters, The Legend of Zelda, Magic: The Gathering.
- Strategic Focus: Expanding licensed franchise portfolio for European entertainment tie-ups, growing games and puzzles category through digital-physical hybrid board games, investing in sustainable packaging and eco-conscious manufacturing practices.
Market Concentration Analysis
The Europe toys market is moderately concentrated, with The LEGO Group, Hasbro, and Mattel collectively accounting for an estimated 35-45% of total European toy market revenue in 2025. Regional European specialists hold significant shares within their respective product and country segments. The remaining market is distributed among regional distributors, specialty retailers, licensed merchandise specialists, and emerging eco-toy brands.
Investment & Growth Opportunities
Highest Growth Segments
Building sets (~6.1% CAGR est.), above 10 years age group (~6.3% CAGR est.), the Europe smart toys market through AI/AR integration, sustainable eco-toy product lines, and franchise-linked collectibles for adult consumers represent the Europe toys market's highest-priority investment vectors through 2034.
Investment Themes
- Smart Toy Technology Investment: The Europe smart toys market presents a compelling investment opportunity as AI, AR, and IoT integration expand from early adopter to mainstream consumer adoption. Germany toys market dominance in STEM education spending and the France smart toys market's rapid growth both indicate strong structural demand for technology-integrated toy products commanding significant fee premiums over conventional alternatives.
- Sustainability and Eco-Toy Platform Development: European regulatory and consumer pressure for sustainable materials and packaging creates a durable competitive advantage for toy manufacturers that lead the eco-toy transition. Investment in FSC-certified material supply chains, biodegradable packaging development, and sustainable brand positioning enables premium pricing, regulatory compliance, and long-term consumer loyalty across all European markets.
Future Market Outlook (2026-2034)
The Europe toys market is projected to grow from USD 29.41 Billion in 2025 to USD 31.51 Billion in 2026 and is forecast to reach USD 48.66 Billion by 2034, delivering a 5.58% CAGR over the forecast period through smart toy technology integration, sustainable product expansion, franchise licensing growth, and emerging market penetration. The market's anchor value of USD 38.59 Billion in 2030 represents the inflection point at which the Europe smart toys market achieves mainstream scale and sustainable toy lines achieve commercial significance across all European geographies.
Three structural forces are expected to define the Europe toys market through 2034. First, the Europe smart toys market will achieve mainstream scale, as AI-enabled toys, AR-integrated play experiences, and IoT-connected educational systems transition from premium niche to mass-market category. Second, sustainability will become a mandatory rather than optional market differentiator. Third, franchise licensing will remain the primary driver of peak-demand product launches and premium pricing across the Europe toys market.
Research Methodology
Primary Research
Primary research comprised in-depth interviews with senior executives from toy manufacturers, specialty retailers, e-commerce platforms, licensed entertainment companies, regulatory affairs specialists, and consumer behavior researchers across Germany, France, the United Kingdom, Italy, Spain, and other European markets. These discussions validated market size estimates, assessed product type and age group growth dynamics, evaluated competitive positioning, and gathered qualitative insights on sustainability trends, smart toy technology adoption, and regulatory developments in the Europe toys market.
Secondary Research
Secondary research encompassed company annual reports, licensing agreement disclosures, EU regulatory publications on toy safety and chemical compliance, European retail industry databases, e-commerce market data, press releases, and reputed market intelligence publications. These resources were used to analyze market trends, competitive positioning, channel dynamics, product category performance, and regional market characteristics across the European toy industry.
Forecasting Models
Forecasting models were developed using historical market data (2020-2025), product category innovation pipelines, licensing deal announcements, sustainability investment trends, EU regulatory roadmaps, and macroeconomic household income and disposable spending projections. The analysis incorporated both top-down and bottom-up approaches, validated through primary research cross-referencing, to generate reliable market forecasts through 2034.
Europe Toys Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report | Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Product Types Covered | Action Figures, Building Sets, Dolls, Games and Puzzles, Sports, and Outdoor Toys, Plush, Others |
| Age Groups Covered | 5 Years, 5 To 10 Years, Above 10 years |
| Sales Channels Covered | Supermarkets and Hypermarkets, Specialty Stores, Department Stores, Online Stores, Others |
| Countries Covered | Germany, France, United Kingdom, Italy, Spain, Others |
| Companies Covered | The LEGO Group, Hasbro, Mattel, Clementoni Spa, Ravensburger Group, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Europe toys market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the Europe toys market.
- Porter's Five Forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Europe toys industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Europe Toys Market Report
The Europe toys market size is estimated at USD 31.51 Billion in 2026, driven by rising disposable incomes, smart toy demand growth, e-commerce expansion, sustainability trends, and strong franchise-linked toy demand across Germany, the UK, France, Italy, and Spain.
The market is projected to grow at a CAGR of 5.58% during 2026-2034, reaching USD 48.66 Billion by 2034, driven by Europe smart toys market expansion, sustainable toy adoption, franchise licensing growth, and increasing adult collector demand.
Games and puzzles lead at 21.8% (2025), driven by family gaming culture, the post-COVID indoor entertainment boom, and growing adult puzzle communities across Germany, France, and the UK.
The 5 to 10 years age group leads at 42.5% (2025), driven by peak spend on franchise toys, building sets, and board games.
Germany leads at 23.5% (2025) through its strong STEM culture, the Germany toys market's premium spending profile, Nuremberg Toy Fair influence, and robust specialty and e-commerce retail infrastructure.
Leading companies include The LEGO Group, Hasbro, Mattel, Clementoni Spa, and Ravensburger Group, among others.
The market is projected to reach approximately USD 38.59 Billion by 2030, reflecting smart toy mainstream adoption, sustainable toy line expansion, and growing franchise-linked collectible demand across all major European markets.
Key Europe smart toys market trends include AI-enabled personalized learning toys, AR-integrated play experiences, IoT-connected educational systems, app-linked toy platforms, and the growing France smart toys market and Spain smart toys market adoption.
Key drivers include rising smart toy demand, parental STEM education investment, e-commerce expansion, franchise licensing power, sustainability mandates, growing adult collector segment, and the Europe baby toys market growth supported by premium developmental product investment.
Primary challenges include stringent EU toy safety standards and compliance costs, competition from digital entertainment substitutes, rising raw material and logistics costs, and strong seasonal revenue concentration in Q4 holiday gifting periods.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade