
Feminine Hygiene Products Market Size, Share, Trends and Forecast by Product Type, Distribution Channel, and Region, 2026-2034
Feminine Hygiene Products Market Size, Share, Trends & Forecast (2026-2034)
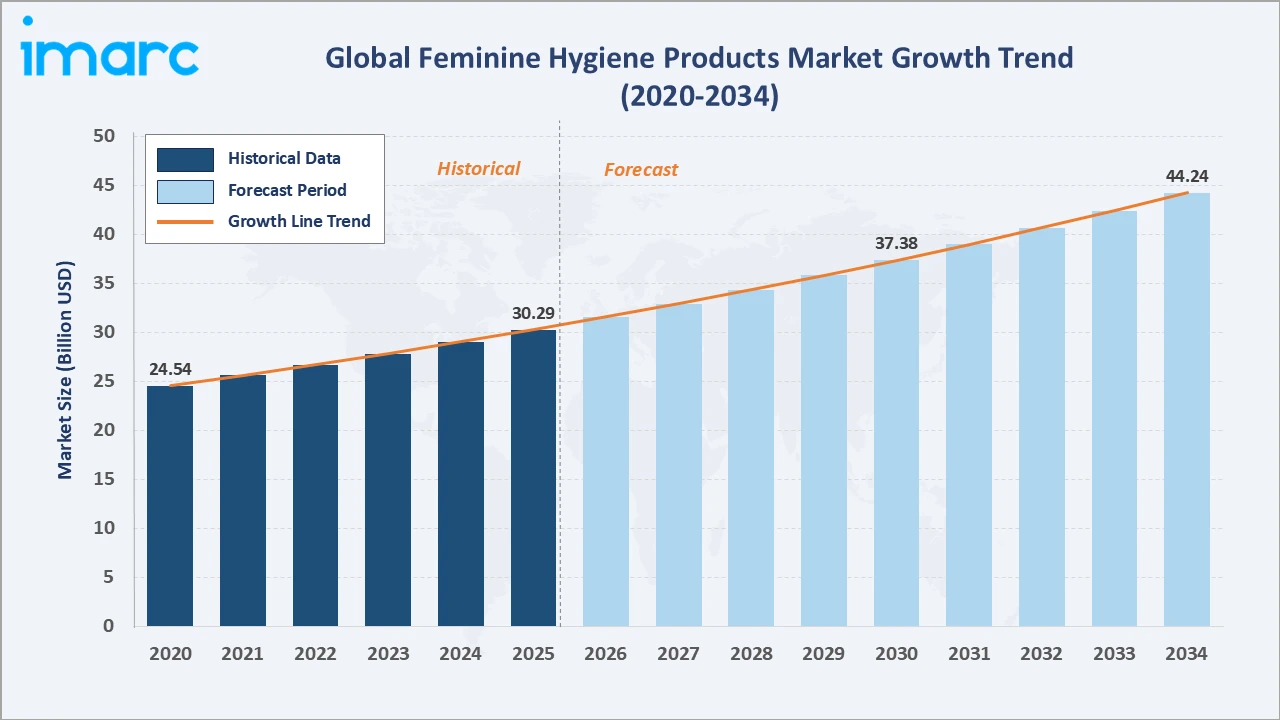
The global feminine hygiene products market grew from USD 30.29 Billion in 2025 to USD 31.59 Billion in 2026 and is projected to reach USD 44.24 Billion by 2034, growing at a CAGR of 4.30% during 2026-2034. Rising menstrual health awareness, a growing female workforce, and continuous product innovation are supporting steady growth. Kotex research found that 82% of women regularly feel frustrated by today’s period products, highlighting strong demand for better-performing solutions.
Wider retail and online availability, menstrual education programs, and growing demand for organic and comfortable products continue to expand the feminine hygiene industry. Sanitary pads dominate at 45.1%. Supermarkets and hypermarkets lead distribution channels at 45.9%. Asia Pacific commands 34.7% of global market share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 30.29 Billion |
|
Market Size (2026) |
USD 31.59 Billion |
|
Forecast Market Size (2034) |
USD 44.24 Billion |
|
CAGR (2026-2034) |
4.30% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Product Type |
Sanitary Pads (45.1%, 2025) |
|
Dominant Distribution Channel |
Supermarkets and Hypermarkets (45.9%, 2025) |
|
Leading Region |
Asia Pacific (34.7%, 2025) |
The feminine hygiene market size increased from USD 24.54 Billion in 2020 to USD 30.29 Billion in 2025 and is estimated to reach USD 31.59 Billion in 2026. The market is further expected to grow to USD 37.38 Billion by 2030 and USD 44.24 Billion by 2034. Growth is driven by rising product penetration in emerging economies and premiumization in mature markets.
To get more information on this market, Request Sample
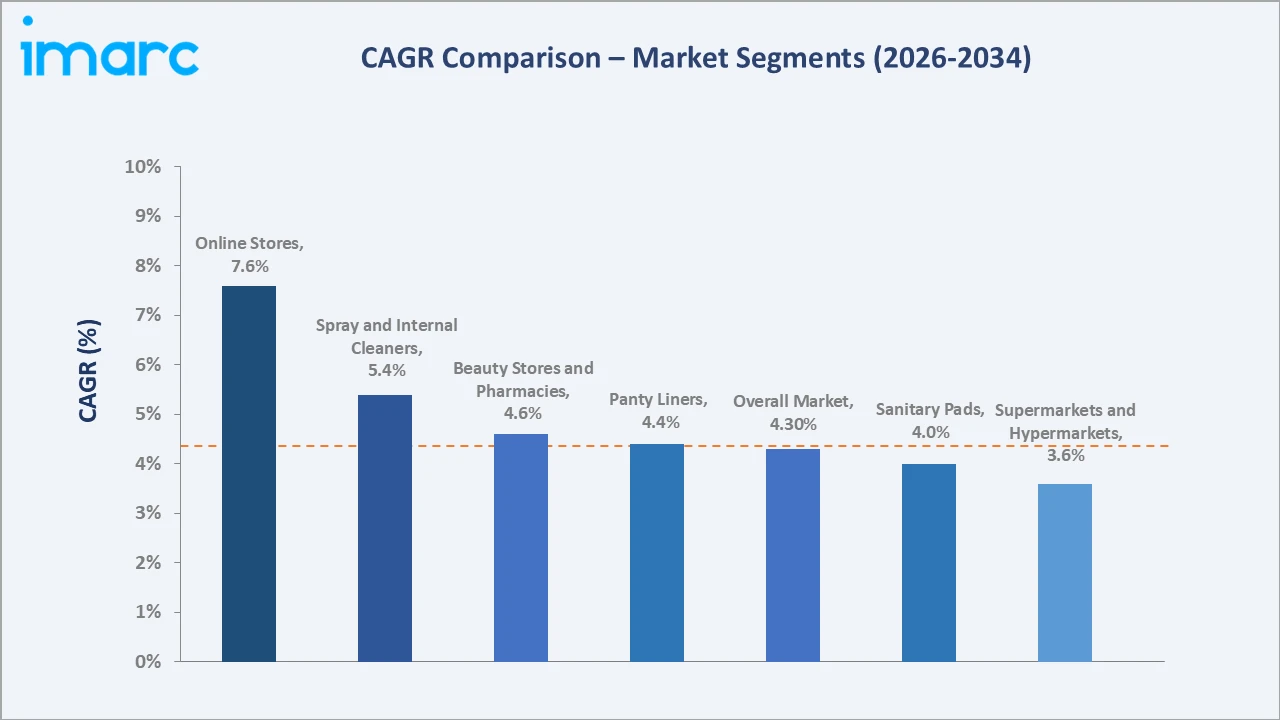
Online stores are expected to grow fastest at ~7.6% CAGR, supported by discreet purchasing, subscription services, and direct-to-consumer brands. Spray and internal cleaners follow at ~5.4% CAGR as intimate care and wellness products gain acceptance among younger consumers.
Executive Summary
The global feminine hygiene products market expanded from USD 30.29 Billion in 2025 to an estimated USD 31.59 Billion in 2026. Demand is broadening as more girls and women gain access to affordable products, while consumers in developed markets seek greater comfort, safety, and sustainability. Leading brands are investing in new materials, education programs, and local manufacturing in emerging markets. The market is projected to reach USD 44.24 Billion by 2034. Sanitary pads at 45.1% lead as the most widely used product. Supermarkets and hypermarkets at 45.9% remain the main sales channel. Asia Pacific leads regionally at 34.7%.
Key Market Insights
|
Insight |
Data |
|
Dominant Product Type |
Sanitary Pads - 45.1% share (2025) |
|
Dominant Distribution Channel |
Supermarkets and Hypermarkets - 45.9% market share (2025) |
|
Leading Region |
Asia Pacific - 34.7% share (2025) |
|
Market Opportunity |
Organic and biodegradable products; reusable period care; affordable products for emerging markets; online subscriptions; menstrual wellness products |
Key Analytical Observations Supporting the Above Data:
- Sanitary Pads at 45.1%: Sanitary pads dominate because they are easy to use, widely available, affordable, and culturally accepted across regions. They remain the first choice for most women in Asia, Africa, and Latin America and are offered in a wide range of sizes and absorbencies.
- Supermarkets and Hypermarkets at 45.9%: Supermarkets and hypermarkets lead because they offer wide brand choice, promotions, and convenient one-stop shopping, making them the main destination for regular household purchases of feminine hygiene products.
- Asia Pacific at 34.7%: Asia Pacific leads regionally due to its large female population, rising incomes, expanding retail networks, and government and nonprofit programs promoting menstrual hygiene in India, China, and Southeast Asia.
Global Feminine Hygiene Products Market Overview
Feminine hygiene products include sanitary pads, panty liners, tampons, menstrual cups, period underwear, and intimate washes and cleaners. The feminine hygiene industry also includes products for postpartum care and light incontinence that share similar materials and retail channels. These products support menstrual management, everyday freshness, and intimate health, and they are essential personal care items for women and girls worldwide.
The industry ecosystem links raw material suppliers, manufacturers, packaging and logistics providers, retailers, online platforms, regulators, and consumers. Macroeconomic factors include household income, female labor participation, urbanization, education levels, and public health policy, all of which shape product access and spending. Public health programs, school education, and nonprofit initiatives also play an important role in expanding product use in developing countries.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
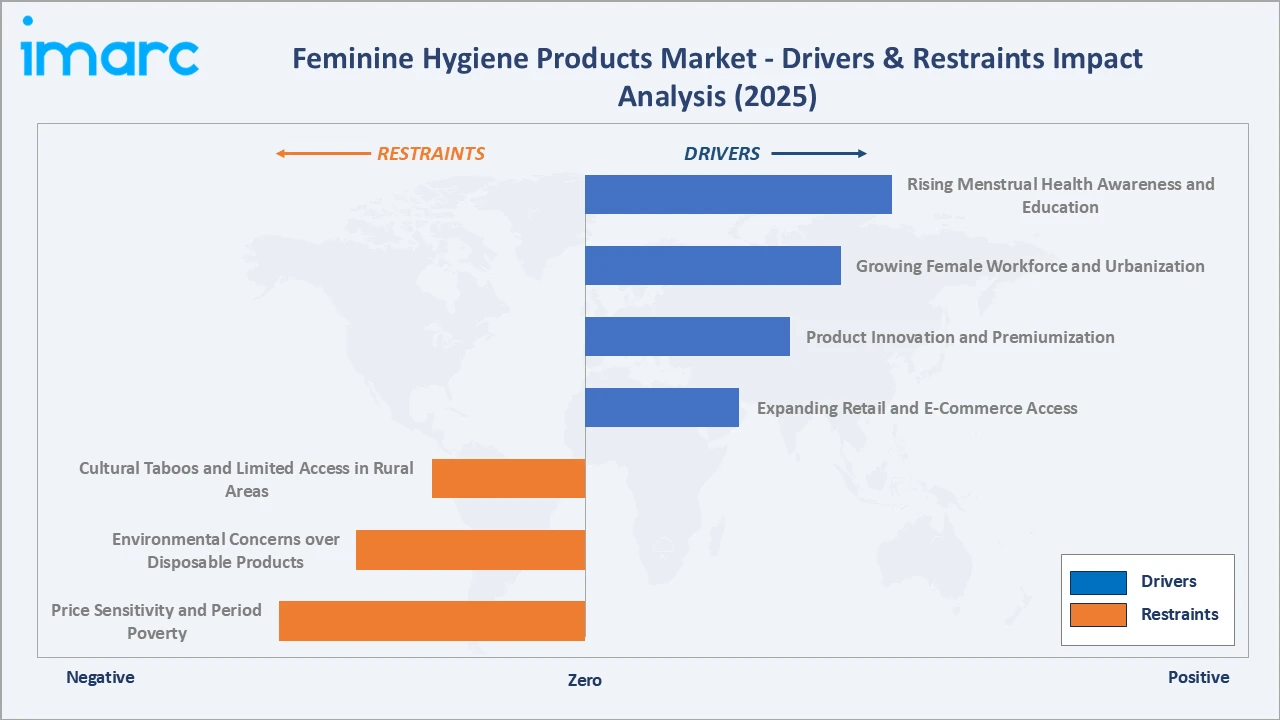
- Rising Menstrual Health Awareness and Education: Governments, nonprofits, schools, and brands are running menstrual health education programs that challenge stigma and encourage the use of safe, hygienic products. As awareness of the health risks of unhygienic practices grows, more girls and women are switching from cloth and other traditional methods to modern products, expanding the consumer base in emerging markets. School-based programs that combine education with free or subsidized product distribution are especially effective in building lifelong product habits among adolescent girls. Social media and digital campaigns are also normalizing conversations about periods, reducing embarrassment around purchasing products in stores. Health professionals and community workers are also playing a larger role in recommending safe and suitable products.
- Growing Female Workforce and Urbanization: More women are working outside the home and living in cities, increasing demand for reliable, convenient, and discreet products that support active lifestyles. Urban consumers have easier access to modern retail and online stores, and they are more willing to try premium, thinner, and longer-lasting products. Higher education levels and greater financial independence among women are also increasing spending on personal care, including feminine hygiene products that offer better comfort and protection during long working days. Travel, sports, and fitness activities also encourage the use of products designed for movement, discretion, and extended wear.
- Product Innovation and Premiumization: Brands are introducing thinner pads with better absorbency, leak-protection designs, skin-friendly materials, organic cotton options, and products for specific needs such as overnight use, teens, and sensitive skin. These innovations encourage consumers to trade up to higher-value products and strengthen brand loyalty. Research into consumer frustrations, such as leaks, discomfort, and odor, is guiding the development of new designs and features. Premium products often carry higher margins, encouraging manufacturers to invest further in research and development. Packaging redesigns inspired by beauty and skincare categories are also helping brands make period care more appealing to younger consumers.
- Expanding Retail and E-Commerce Access: Wider distribution through supermarkets, pharmacies, convenience stores, and online platforms is making feminine hygiene products easier to find and buy. E-commerce and subscription services offer discreet purchasing and home delivery, while rural distribution networks are improving access in underserved areas. Partnerships with pharmacies, community health workers, and rural retail networks are helping brands reach consumers in smaller towns and villages that were previously difficult to serve. Quick commerce platforms in large cities now deliver feminine hygiene products within minutes, adding convenience for urgent needs. Vending machines in schools, offices, and public restrooms are also improving access for women on the move.
Market Restraints
- Price Sensitivity and Period Poverty: For many low-income women and girls, regular purchase of disposable products remains unaffordable. Period poverty limits product use in developing regions and among disadvantaged groups in developed countries, slowing market penetration despite rising awareness. Taxes on menstrual products in some countries further raise prices, although several governments have removed these taxes or introduced free distribution programs in schools and public facilities to improve access. Inflation in household budgets can also lead some consumers to trade down to lower-priced or private label products.
- Environmental Concerns over Disposable Products: Disposable pads and tampons contain plastics and synthetic materials that contribute to landfill waste. Growing environmental awareness and stricter rules on single-use plastics are pushing some consumers toward reusable alternatives, which can reduce repeat purchases of disposable products. Manufacturers face growing pressure to reduce plastic content, improve recyclability, and provide clear information about the environmental impact of their products. Disposal challenges in areas without proper waste management also raise public health and environmental concerns.
- Cultural Taboos and Limited Access in Rural Areas: In many regions, cultural taboos around menstruation discourage open discussion and product purchases. Limited retail presence, poor sanitation infrastructure, and lack of disposal facilities in rural areas further restrict the adoption of modern feminine hygiene products. Limited awareness among older generations and family decision-makers can also influence product choices for younger women and girls in traditional households. Inadequate toilets and water facilities in schools and workplaces can further discourage regular product use during menstruation.
Market Opportunities
- Organic, Biodegradable, and Reusable Products: Demand is rising for organic cotton pads and tampons, biodegradable materials, menstrual cups, and period underwear. Brands that combine sustainability with strong performance can capture environmentally conscious consumers and differentiate in crowded markets. Certifications, transparent sourcing, and clear end-of-life information can help build trust and justify premium pricing for sustainable ranges.
- Affordable Products for Emerging Markets: Low-cost, locally manufactured products tailored to regional needs can expand access among first-time users in Africa, South Asia, and Latin America. Partnerships with governments, schools, and nonprofits can accelerate adoption. Smaller pack sizes and value ranges also make products accessible to consumers who purchase on a daily or weekly basis.
Market Challenges
- Raw Material Price Volatility: Prices of pulp, nonwovens, superabsorbent polymers, and cotton can change sharply, affecting production costs. Manufacturers must balance cost increases with affordability, particularly in price-sensitive markets. Long-term supply contracts, local sourcing, and material efficiency programs help manufacturers reduce exposure to price swings. Supply chain disruptions and higher freight costs can also affect product availability and pricing in some regions. Diversifying supplier bases across regions is becoming a priority for major manufacturers.
- Product Safety and Regulatory Scrutiny: Consumers and regulators are paying closer attention to ingredients, chemicals, and labeling. Meeting evolving safety standards and maintaining consumer trust require continuous testing, transparency, and investment in quality control. Clear communication about product safety, testing, and ingredients is increasingly important for maintaining brand reputation on social media. Differences in regulations across countries also add complexity for companies operating in many markets. Brands that invest early in compliance and transparent communication are better positioned to maintain consumer confidence.
Emerging Market Trends
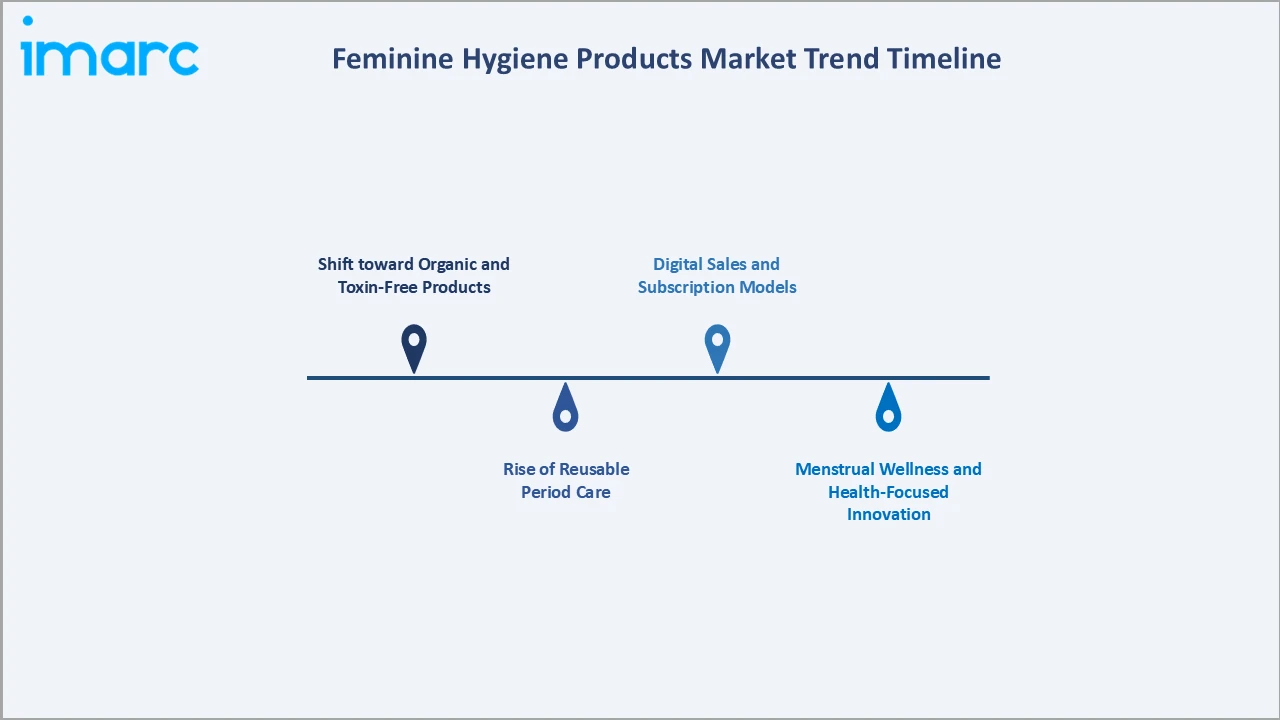
1. Shift toward Organic and Toxin-Free Products
Consumers are increasingly choosing products made with organic cotton and free from fragrances, dyes, and chlorine bleaching. Transparent ingredient labeling and dermatological testing are becoming important purchase factors. This shift is encouraging established brands to launch organic lines and creating opportunities for natural-focused challengers. Retailers are dedicating more shelf space to organic ranges, and private label brands are also introducing natural options at lower prices. Demand for transparency is also encouraging brands to publish full ingredient lists and third-party test results.
2. Rise of Reusable Period Care
Menstrual cups, reusable cloth pads, and period underwear are gaining popularity as consumers seek cost savings and lower environmental impact over time. Improved designs, education, and availability through mainstream retailers are helping these products move from niche to everyday use. Many users combine reusable and disposable products depending on situation, creating demand for hybrid solutions and complementary products. Government and nonprofit programs are also distributing reusable products in some regions to address affordability and waste concerns.
3. Digital Sales and Subscription Models
Online platforms and subscription services allow women to purchase products discreetly and receive regular deliveries. Direct-to-consumer brands use digital channels to educate consumers, personalize offers, and build communities, reshaping how products are marketed and sold. Influencer partnerships and educational content on social platforms play a major role in reaching younger consumers and building trust in new brands. Data from online sales also helps brands understand preferences and launch targeted products faster. Flexible delivery schedules and bundled offers also help online sellers increase repeat purchases.
4. Menstrual Wellness and Health-Focused Innovation
Brands are expanding into menstrual wellness, including pain relief, intimate skincare, cycle tracking, and products designed for specific needs such as heavy flow or sensitive skin. Feminine hygiene market trends increasingly connect period care with broader women’s health and self-care routines. Products for perimenopause, postpartum care, and light bladder leaks are also expanding the category beyond traditional menstrual care. This broader focus allows brands to engage women across different life stages and build longer customer relationships. Partnerships with healthcare providers and wellness platforms are helping brands deliver credible health information to consumers.
Industry Value Chain Analysis
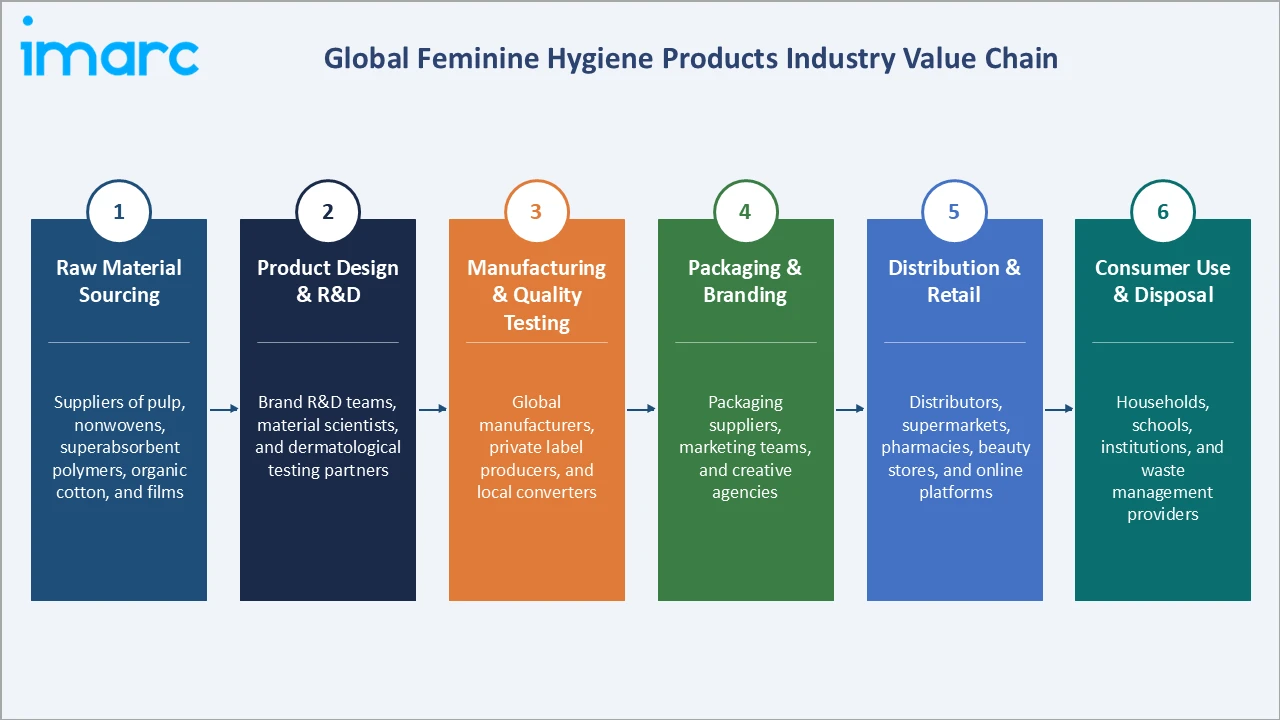
The feminine hygiene products value chain spans raw material sourcing, product design and research, manufacturing and quality testing, packaging and branding, distribution and retail, and consumer use and disposal. Value is concentrated in brand building, product innovation, and distribution reach. Raw material quality and supply reliability are also critical, as they determine product performance and production costs.
|
Stage |
Key Participants |
|
Raw Material Sourcing |
Suppliers of pulp, nonwovens, superabsorbent polymers, organic cotton, and films |
|
Product Design & R&D |
Brand R&D teams, material scientists, and dermatological testing partners |
|
Manufacturing & Quality Testing |
Global manufacturers, private label producers, and local converters |
|
Packaging & Branding |
Packaging suppliers, marketing teams, and creative agencies |
|
Distribution & Retail |
Distributors, supermarkets, pharmacies, beauty stores, and online platforms |
|
Consumer Use & Disposal |
Households, schools, institutions, and waste management providers |
Manufacturing and quality testing is the most consequential stage of the chain. Product performance, safety, and consistency depend on advanced materials and production processes, and manufacturers that combine scale with innovation can deliver high-quality products at competitive prices. Efficient distribution and strong retail relationships are equally important for ensuring products are available where consumers shop.
Technology Landscape in the Global Feminine Hygiene Products Industry
Advanced Absorbent Core Technologies
New absorbent core designs, superabsorbent polymers, and channel structures pull fluid away from the surface quickly and lock it in, improving dryness and leak protection while allowing thinner products. These technologies support ultra-thin pads and longer-lasting overnight protection. Wing designs, side guards, and raised back barriers further improve fit and reduce leaks during sleep and physical activity. Testing with diverse consumer groups ensures that new designs perform well across body types and flow levels.
Sustainable and Skin-Friendly Materials
Manufacturers are developing organic cotton covers, plant-based films, biodegradable backsheets, and bamboo-derived materials to reduce environmental impact. Breathable, hypoallergenic materials and pH-balancing features help reduce irritation and odor for sensitive users. Odor control technologies and natural fragrances are also being refined to provide freshness without irritation. Compostable wrappers and paper-based packaging are also reducing plastic use across product ranges.
Digital Tools and Smart Period Care
Period tracking apps, online education platforms, and connected wellness tools help women monitor cycles and choose suitable products. Brands are using digital data and consumer feedback to design products that better match individual needs. Online product finders and personalized recommendations help consumers select the right absorbency and format for their cycles.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Product Type | Sanitary Pads | 45.1% | 2025 |
| Distribution Channel | Supermarkets and Hypermarkets | 45.9% | 2025 |
| Region | Asia Pacific | 34.7% | 2025 |

By Product Type
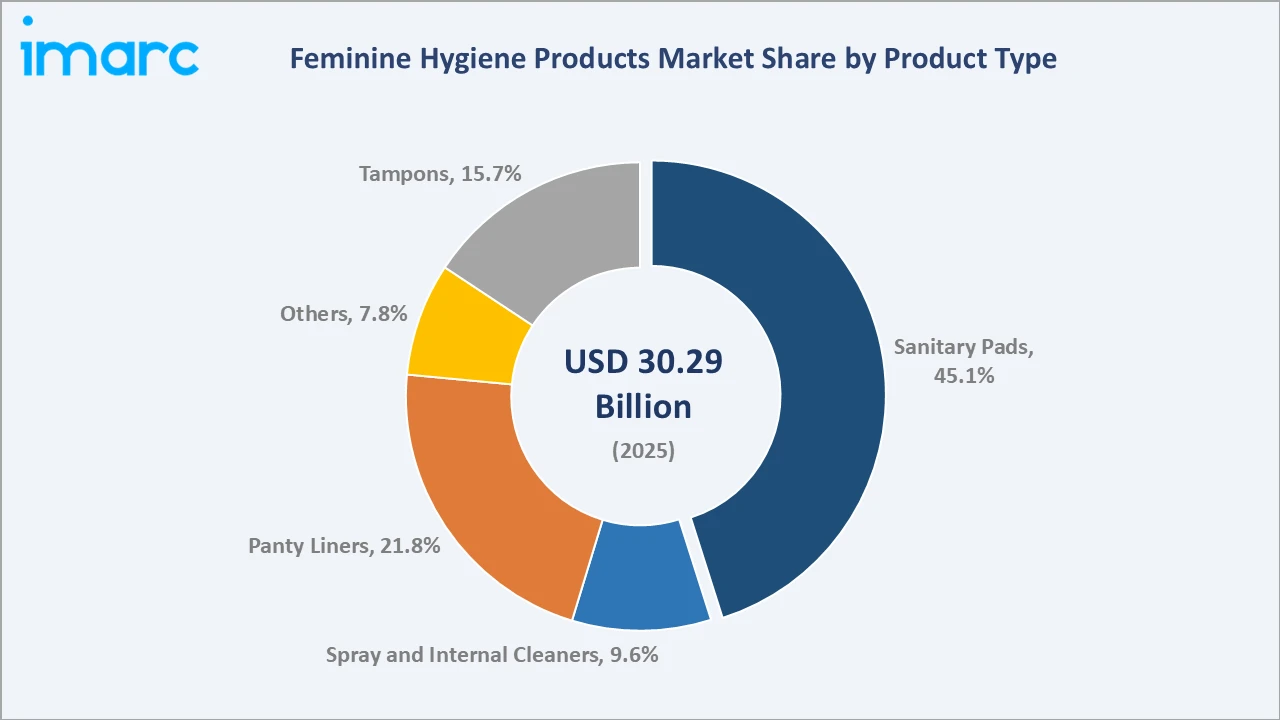
Sanitary pads lead at 45.1% (2025). Their ease of use, affordability, and wide acceptance make them the most common choice worldwide, especially in Asia, Africa, and Latin America where tampon use remains limited. Product variety across thickness, length, and absorbency allows consumers to choose options for light days, heavy flow, and overnight use.
To access detailed market analysis, Request Sample
Panty liners at 21.8% grow at ~4.4% CAGR, supported by daily freshness needs. Tampons at 15.7% grow at ~4.1%, spray and internal cleaners at 9.6% grow fastest at ~5.4%, and others at 7.8% grow at ~5.0%.
By Distribution Channel
Supermarkets and hypermarkets lead at 45.9% (2025). Wide brand selection, regular promotions, and convenient one-stop shopping make them the main channel for household purchases of feminine hygiene products. Private label ranges in these stores also offer lower-priced alternatives to leading brands.
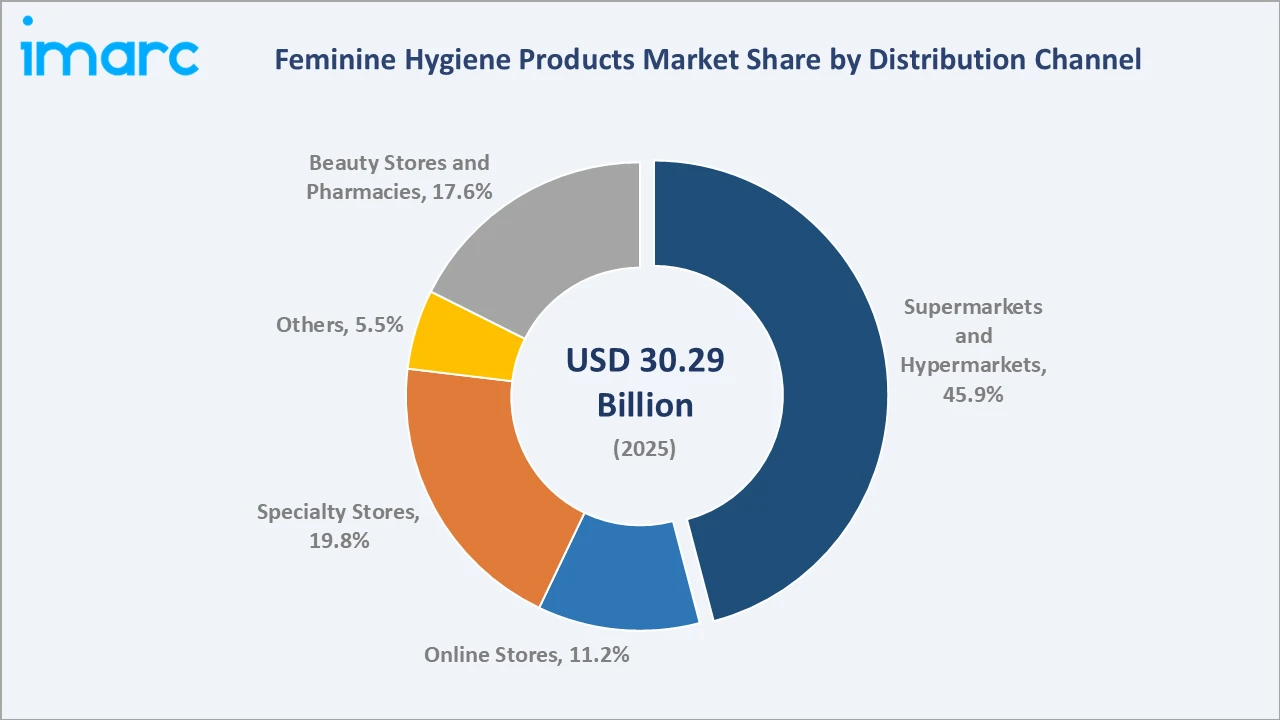
Specialty stores at 19.8% grow at ~4.0% CAGR, beauty stores and pharmacies at 17.6% at ~4.6%, online stores at 11.2% grow fastest at ~7.6%, and others at 5.5% at ~3.2%.
Regional Market Insights
|
Region |
Share (2025) |
Key Global Feminine Hygiene Products Market Drivers & Characteristics |
|
Asia Pacific |
34.7% |
Large female population, rising incomes, and menstrual hygiene programs in India, China, and Southeast Asia. |
|
North America |
27.6% |
High product penetration, premium and organic demand, and strong tampon use. |
|
Europe |
21.8% |
Strong sustainability focus, reusable product adoption, and free product programs. |
|
Middle East and Africa |
9.1% |
Rising awareness, local manufacturing, and nonprofit distribution programs. |
|
Latin America |
6.8% |
Growing urban demand and expanding retail and online channels. |
Asia Pacific's 34.7% market leadership reflects its large female population, rising incomes, and expanding access in India, China, and Southeast Asia. North America's 27.6% reflects high penetration, strong demand for premium and organic products, and wide tampon use.
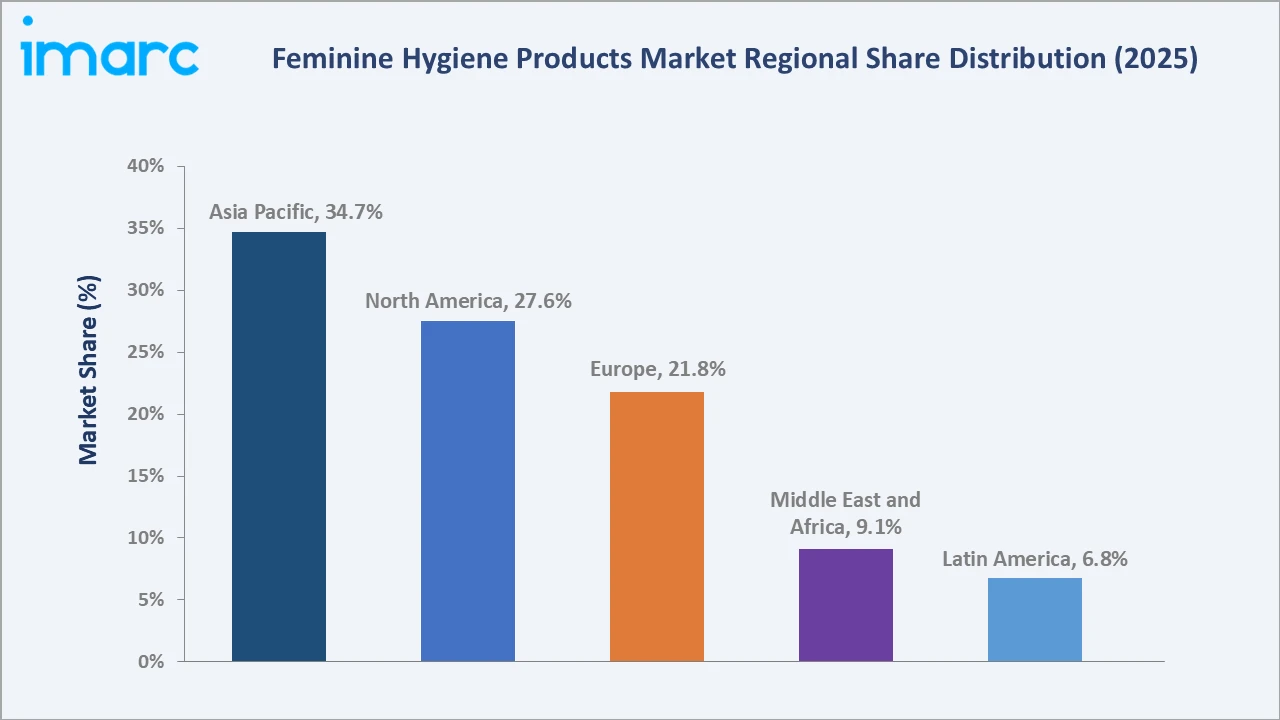
Europe's 21.8% reflects mature demand and a strong shift toward sustainable and reusable products. Middle East and Africa at 9.1% and Latin America at 6.8% are smaller, but rising awareness and local production support strong growth. Expanding retail networks and growing urban populations are expected to lift demand in these regions over the forecast period.
Competitive Landscape
The global feminine hygiene products market is led by a small group of multinational consumer goods companies, alongside regional brands, private labels, and fast-growing organic and reusable product specialists. Competition centers on product innovation, brand trust, pricing, and distribution reach.
| Company | Key Brands | Market Position | Core Strength |
|---|---|---|---|
| Procter & Gamble | Always, Tampax, Whisper, Always Discreet | Market Leader | Global leader in feminine care with strong innovation. |
| Kimberly-Clark | Kotex, U by Kotex, Camelia | Market Leader | Century-long feminine care heritage and new materials. |
| Unicharm Corporation | Sofy | Strong Challenger | Strong Asian presence and expansion in emerging markets. |
| Kao Corporation | Laurier, Merries | Innovator | Advanced materials and skin-friendly product design. |
| Edgewell Personal Care | Playtex, Carefree | Strong Challenger | Established tampon and liner brands in North America. |
The most important competitive dynamic is the balance between premium innovation and affordability. Leading players are launching organic and high-performance products in mature markets while building local manufacturing and low-cost ranges for emerging markets. Partnerships with retailers, schools, and nonprofits are also important for building brand visibility and long-term loyalty. Acquisitions of niche organic and reusable brands also allow large companies to enter fast-growing segments quickly.
Key Company Profiles
Procter & Gamble
Procter & Gamble is the global market leader in the feminine care category, with brands spanning pads, liners, tampons, and adult incontinence products.
- Key Brands: Always, Tampax, Whisper, Always Discreet.
- Recent Developments: In May 2026, Tampax launched the Tampax Starter Kit to help young girls and teens manage their first periods, with step-by-step instructions on each wrapper.
- Strategic Focus: Expanding menstrual education through initiatives such as Flow With a Glow, launched with WASH United in May 2026.
Kimberly-Clark
Kimberly-Clark Corporation is an American multinational consumer goods company headquartered in Irving, Texas, USA. The company manufactures personal care, consumer tissue, and professional hygiene products, with a portfolio of well-known brands serving consumers and businesses worldwide.
- Key Brands: Kotex, U by Kotex, Camelia.
- Recent Developments: In February 2026, Kotex unveiled a completely reimagined lineup of pads and liners featuring Gravity Core technology, BioCare and Bamboo varieties, and a new brand identity.
- Strategic Focus: Delivering performance innovation and wellness-focused design across the period care portfolio.
Unicharm Corporation
Unicharm Corporation is a Japanese consumer goods company headquartered in Tokyo, Japan, specialising in personal care, feminine hygiene, baby care, and adult incontinence products.
- Key Brands: Sofy.
- Recent Developments: In October 2026, Unicharm and Toyota Tsusho launched Sofy Unicharm East Africa in Kenya to develop, produce, and market sanitary products for East African markets.
- Strategic Focus: Expanding into new markets, including the launch of SOFY in Brazil from March 2026.
Market Concentration Analysis
The global feminine hygiene products market is moderately concentrated, with a few multinational companies holding a large share of branded sales in major markets. Regional brands and private labels remain strong in many countries, particularly in price-sensitive segments. In emerging markets, local manufacturers compete effectively on price and distribution in smaller towns.
Market concentration is evolving through two opposing forces: leading players are expanding through innovation and local manufacturing, while organic, reusable, and direct-to-consumer brands are gaining feminine hygiene market share in niche and premium segments.
Investment & Growth Opportunities
Highest Growth Segments
Online stores (~7.6% CAGR through e-commerce and subscriptions), spray and internal cleaners (~5.4% CAGR through intimate care demand), Middle East and Africa (~5.6% CAGR through rising awareness), and Asia Pacific (~5.2% CAGR through expanding access) represent the highest-growth investment areas in the global feminine hygiene products market through 2034.
Emerging Investment Opportunities
Local manufacturing of affordable products in Africa and South Asia is one of the most promising opportunities. Investments in production capacity, distribution, and education programs can unlock demand among millions of first-time users.
Investment Themes
- Sustainable period care: Organic, biodegradable, and reusable products address rising environmental concerns.
- Direct-to-consumer and subscription models: Digital brands build loyalty through convenience and education.
Future Market Outlook (2026-2034)
The global feminine hygiene products market is projected to grow from USD 30.29 Billion in 2025 to USD 31.59 Billion in 2026, reaching USD 44.24 Billion by 2034, registering a CAGR of 4.30% during 2026-2034. The anchor value of USD 37.38 Billion in 2030 marks a point at which sustainable and online-sold products should hold a larger share of sales. By then, menstrual wellness products and reusable options should also be established categories in major markets.
Three structural forces define global feminine hygiene products market growth through 2034 rising access and awareness in emerging markets; product innovation and premiumization; and the shift toward sustainable and digital purchasing. Together, these forces support steady growth across product types, channels, and regions over the forecast period.
Research Methodology
Primary Research
Primary research comprised structured interviews with industry stakeholders, including manufacturers, raw material suppliers, distributors, retailers, gynecologists, and nonprofit program managers, along with consumer survey inputs from all major regions.
Secondary Research
Secondary research covered company annual reports and press releases, government and health organization publications, trade data, and industry reports. Over 50 credible secondary sources were reviewed, compared, and cross-checked for accuracy and consistency across datasets.
Forecasting Models
Market revenue forecasts were developed using a consumption-based model: menstruating female population by region multiplied by product penetration, usage rates, and average prices for each product type and channel, with segment results aggregated to total market value. Assumptions were validated through detailed discussions with experienced industry experts, manufacturers, raw material suppliers, retailers, and distributors across all major global regions and markets.
Feminine Hygiene Products Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical and Forecast Trends, Industry Catalysts and Challenges, Segment-Wise Historical and Predictive Market Assessment:
|
| Product Types Covered | Sanitary Pads, Panty Liners, Tampons, Spray and Internal Cleaners, Others |
| Distribution Channels Covered | Supermarkets and Hypermarkets, Specialty Stores, Beauty Stores and Pharmacies, Online Stores, Others |
| Regions Covered | Asia Pacific, Europe, North America, Latin America, Middle East and Africa |
| Companies Covered | Procter & Gamble, Kimberly-Clark, Unicharm Corporation, Kao Corporation, Edgewell Personal Care, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the feminine hygiene products market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the global feminine hygiene products market.
- The study maps the leading, as well as the fastest-growing, regional markets. It further enables stakeholders to identify the key country-level markets within each region.
- Porter's Five Forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the feminine hygiene products industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Feminine Hygiene Products Market Report
The feminine hygiene market size is estimated at USD 31.59 Billion in 2026, supported by rising awareness, product innovation, and wider retail access.
The feminine hygiene products market grows at 4.30% CAGR during 2026-2034, reaching USD 44.24 Billion by 2034.
Sanitary pads lead at 45.1%, owing to their ease of use, affordability, and wide acceptance.
Supermarkets and hypermarkets lead at 45.9%, offering wide brand choice and convenient shopping.
Asia Pacific leads at 34.7%, driven by a large female population and expanding product access.
Leading companies include Procter & Gamble, Kimberly-Clark, Unicharm Corporation, Kao Corporation, and Edgewell Personal Care, among others.
Key feminine hygiene market trends include organic and toxin-free products, reusable period care, online subscriptions, and menstrual wellness innovation.
The feminine hygiene products market is projected to reach approximately USD 37.38 Billion by 2030.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade