
Fish Farming Market Size, Share, Trends and Forecast by Environment, Fish Type, and Region, 2026-2034
Fish Farming Market Size, Share, Trends & Forecast (2026-2034)
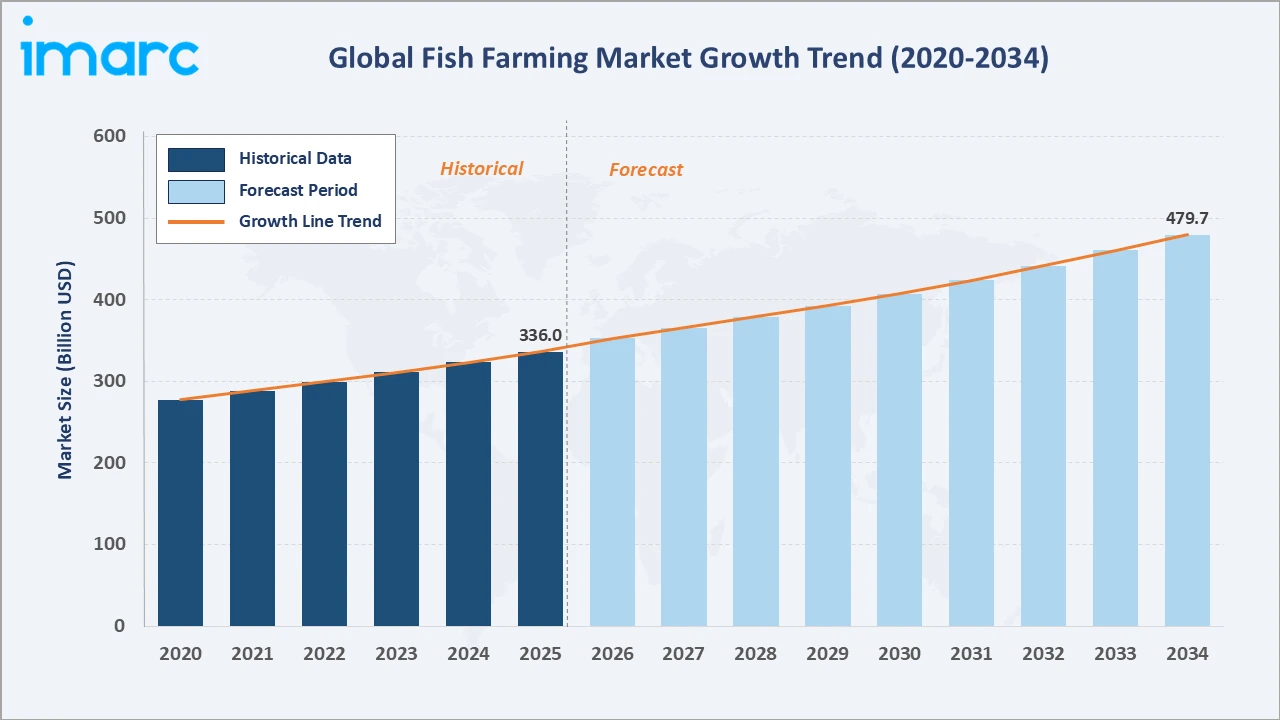
The global fish farming market grew from USD 336.0 Billion in 2025 to USD 352.8 Billion in 2026 and is projected to reach USD 479.7 Billion by 2034, at a CAGR of 3.91% during 2026-2034. Global aquaculture production of aquatic animals reached a record 103 million tonnes in 2024.
Recirculating aquaculture systems, improved feeds, and digital farm monitoring are reshaping the fish farming industry and lifting productivity. Fresh water dominates environments at 45.0%. Salmon leads fish types at 25.0%. Asia-Pacific commands 45.0% of global market share, supported by large-scale production in China, India, Indonesia, and Vietnam.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 336.0 Billion |
|
Market Size (2026) |
USD 352.8 Billion |
|
Forecast Market Size (2034) |
USD 479.7 Billion |
|
CAGR (2026-2034) |
3.91% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Environment |
Fresh Water (45.0%, 2025) |
|
Dominant Fish Type |
Salmon (25.0%, 2025) |
|
Leading Region |
Asia-Pacific (45.0%, 2025) |
The global fish farming market size increased from USD 277.3 Billion in 2020 to USD 336.0 Billion in 2025 and is estimated to reach USD 352.8 Billion in 2026. It is expected to reach USD 407.1 Billion by 2030 and USD 479.7 Billion by 2034, reflecting rising seafood consumption worldwide.
To get more information on this market, Request Sample
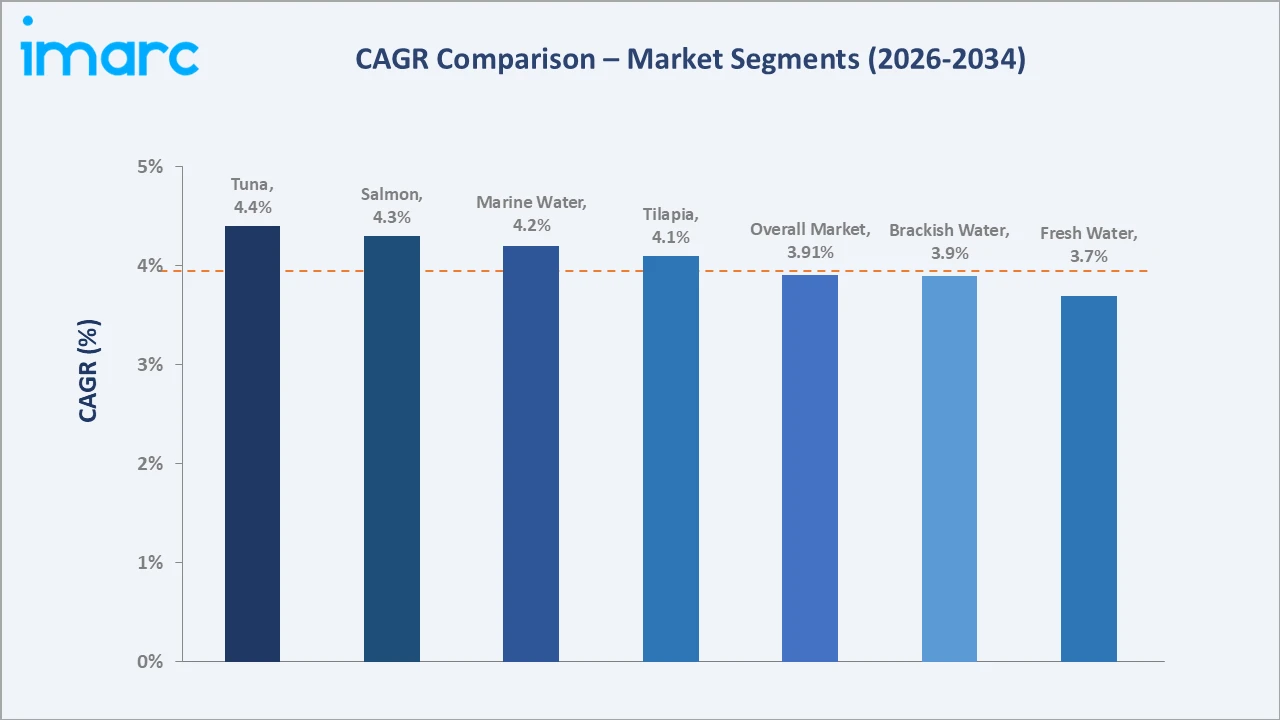
Tuna is expected to grow fastest at ~4.4% CAGR, supported by ranching and closed-cycle farming for premium sashimi markets. Salmon follows at ~4.3% CAGR as land-based and offshore systems expand, while marine water farming grows at ~4.2% on new coastal and open-ocean sites.
Executive Summary
The global fish farming market expanded from USD 336.0 Billion in 2025 to USD 352.8 Billion in 2026 and is projected to reach USD 479.7 Billion by 2034. Producers are investing in disease control, new systems, and acquisitions. Fresh water leads at 45.0%, salmon at 25.0%, and Asia-Pacific at 45.0%.
Integrated salmon producers continue to dominate high-value segments, while small and medium farmers in Asia, Africa, and Latin America drive volume growth in freshwater species. Rising investment in land-based systems, offshore farming, and alternative feeds signals a shift toward more resilient, efficient, and sustainable aquaculture production models.
Key Market Insights
|
Insight |
Data |
|
Dominant Environment |
Fresh Water - 45.0% share (2025) |
|
Dominant Fish Type |
Salmon - 25.0% market share (2025) |
|
Leading Region |
Asia-Pacific - 45.0% share (2025) |
|
Market Opportunity |
Land-based recirculating systems; offshore farming; alternative feed ingredients; value-added processed products; certified sustainable seafood |
Key Analytical Observations Supporting the Above Data:
- Fresh Water at 45.0%: Freshwater farming dominates because ponds, tanks, and inland cages are widespread across Asia, require lower capital investment, and support high-volume species such as tilapia, carp, and catfish that serve large domestic markets.
- Salmon at 25.0%: Salmon leads because of its high value per kilogram, strong global demand for fresh fillets and sushi, and large integrated producers in Norway, Chile, Scotland, and Canada that supply retailers and foodservice operators worldwide.
- Asia-Pacific at 45.0%: Asia-Pacific leads regionally due to its long aquaculture tradition, abundant inland water resources, low production costs, and very high per-capita fish consumption in China, Indonesia, Vietnam, India, and Bangladesh.
Global Fish Farming Market Overview
Fish farming involves breeding and raising fish in controlled environments such as ponds, tanks, raceways, net pens, and offshore cages for food. It supplies a growing share of global seafood, supports rural livelihoods, and reduces pressure on wild fish stocks that are increasingly overexploited in many oceans.
The fish farm industry links hatcheries, feed producers, equipment suppliers, farmers, processors, distributors, regulators, and consumers. Feed prices, disease outbreaks, water quality, trade policies, and consumer preferences shape profitability. Because farming sites require licences and suitable water, production is concentrated in regions with favorable natural conditions.
Fish farming also contributes to national food security strategies, providing affordable protein for growing populations and diversifying rural incomes. Export-oriented producers in Norway, Chile, Vietnam, and Ecuador generate significant foreign exchange, while importing countries rely on farmed seafood to meet rising domestic demand and stabilize supply throughout the year.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
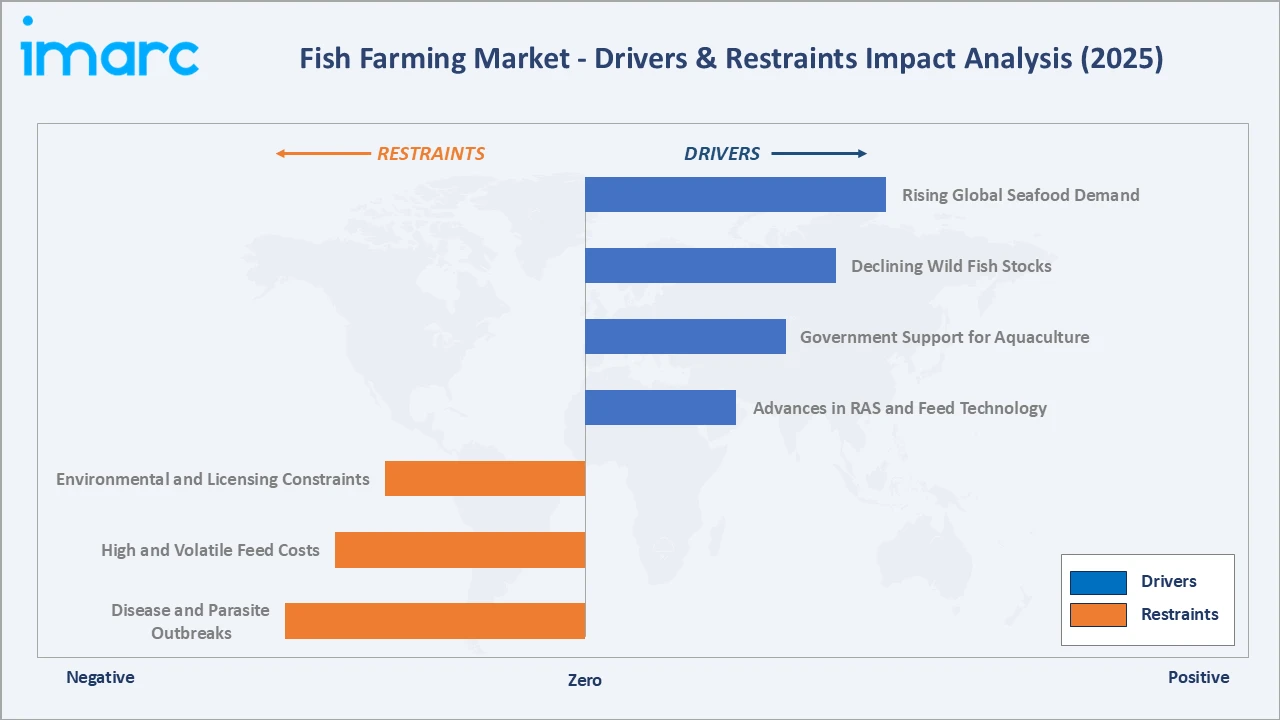
- Rising Global Seafood Demand: Population growth, urbanization, and rising incomes are increasing demand for affordable, high-protein food. Consumers increasingly view fish as a healthy source of omega-3 fatty acids, and retailers are expanding fresh and frozen seafood ranges, strengthening demand for farmed fish across all major regions.
- Expanding middle-class populations in China, India, Southeast Asia, and Africa are adding millions of new seafood consumers each year. Growth in modern retail, online grocery delivery, and ready-to-cook products is making farmed fish more convenient, encouraging repeat purchases and supporting steady volume growth for producers.
- Declining Wild Fish Stocks: Many wild fisheries are fully exploited or overfished, limiting growth in capture production. Aquaculture fills this supply gap with consistent, year-round volumes. Governments and food companies increasingly rely on farmed fish to secure stable seafood supplies and reduce dependence on volatile wild catch.
- Fisheries management rules, quota limits, and closed seasons further restrict wild catch growth in many regions. As a result, aquaculture now supplies more than half of global aquatic animal production, and processors increasingly source farmed fish to ensure consistent size, quality, and availability for their customers.
- Government Support for Aquaculture: Many countries promote aquaculture through subsidies, research funding, training programs, and dedicated farming zones. National strategies in China, India, Indonesia, and Norway target higher output and exports, while development banks finance hatcheries, feed mills, and cold chains in emerging producing regions.
- Public programs also support disease surveillance, extension services, and certification schemes that help small farmers raise productivity and access export markets. Infrastructure investment in roads, electricity, and cold storage near farming clusters lowers post-harvest losses and improves the competitiveness of farmed fish in domestic and international markets.
- Advances in RAS and Feed Technology: Recirculating aquaculture systems, improved vaccines, selective breeding, and efficient feeds are raising survival rates and growth. These technologies reduce disease losses and environmental impact, allowing farms to produce more fish per unit of feed, water, and land than earlier systems.
- Automation and data analytics are improving farm management, enabling precise feeding, early detection of health problems, and better harvest planning. As these technologies become more affordable, adoption is spreading from large salmon producers to medium-sized farms raising tilapia, sea bass, shrimp, and other species.
Market Restraints
- Disease and Parasite Outbreaks: Viral diseases, bacterial infections, and parasites such as sea lice can cause heavy fish mortality. Outbreaks raise treatment costs, reduce harvest volumes, and may trigger site closures or trade restrictions, creating significant financial risk for farmers in dense production areas.
- Biosecurity measures, vaccination programs, and fallowing periods help limit outbreaks, but they increase operating costs and require skilled staff. In some regions, repeated disease events have led to stricter regulation, lower stocking densities, and reduced production growth, affecting the profitability of farming operations.
- High and Volatile Feed Costs: Feed accounts for a large share of farm operating costs. Prices of fishmeal, fish oil, soybean meal, and other ingredients fluctuate with harvests, weather, and trade conditions, squeezing margins for farmers who cannot quickly pass higher costs on to buyers.
- Rising energy and transport costs also affect feed manufacturing and delivery, particularly for farms in remote coastal and island locations. Producers are responding with improved feed formulations, better feeding practices, and long-term supply contracts, but feed price volatility remains a persistent challenge for the industry.
- Environmental and Licensing Constraints: Concerns over water pollution, escapes, and impacts on wild fish lead to strict regulations and limited new licences. Lengthy approval processes, production caps, and resource taxes in some countries restrict expansion and raise compliance costs for established and new producers alike.
- Competition for coastal space with tourism, shipping, and fishing communities can further delay or block new farm developments. Producers increasingly engage with local stakeholders, invest in environmental monitoring, and adopt closed or offshore systems to address concerns and secure long-term operating permissions.
Market Opportunities
- Land-Based and Offshore Farming: Recirculating land-based farms near consumer markets and offshore cages in open waters allow production beyond crowded coastal sites. These systems reduce disease and environmental pressures, and investors are funding large projects in North America, Europe, the Middle East, and Asia.
- Offshore projects can access larger areas with better water exchange, while land-based farms offer full control over water quality and biosecurity. Although capital costs remain high, improving technology and growing operating experience are gradually reducing production costs and attracting long-term institutional investment.
- Alternative Feed Ingredients: Insect meal, algae oils, single-cell proteins, and processing by-products can reduce dependence on fishmeal and fish oil. Suppliers that scale these ingredients cost-effectively can lower feed costs, improve sustainability credentials, and meet rising demand from retailers seeking responsibly farmed seafood.
- Partnerships between feed companies, ingredient start-ups, and fish farmers are accelerating trials and commercial adoption. Regulatory approvals for new ingredients and growing production capacity for insect and algae products are expected to support wider use of sustainable feeds throughout the forecast period.
Market Challenges
- Climate Change and Water Quality: Rising water temperatures, algal blooms, low oxygen events, and extreme weather increase fish stress and mortality. Farmers must invest in monitoring, site relocation, and resilient species to protect production, adding costs and uncertainty to long-term planning in exposed coastal regions.
- Climate risks are prompting farmers to diversify species, develop heat-tolerant strains, and move production to deeper or cooler waters. Insurance costs are rising in vulnerable areas, and governments are funding research on climate adaptation to protect aquaculture supply and coastal livelihoods.
- Public Perception and Certification Costs: Concerns about antibiotics, feed sourcing, and environmental impacts can affect consumer acceptance of farmed fish. Meeting certification standards and traceability requirements demands investment in audits and reporting, which can be especially challenging for small-scale farmers in developing countries.
- Producers are responding with transparent reporting, third-party certification, and digital traceability tools that allow buyers to verify farming practices. Clear labeling and education campaigns are also helping improve consumer understanding of responsibly farmed fish and its role in sustainable food systems.
Emerging Market Trends
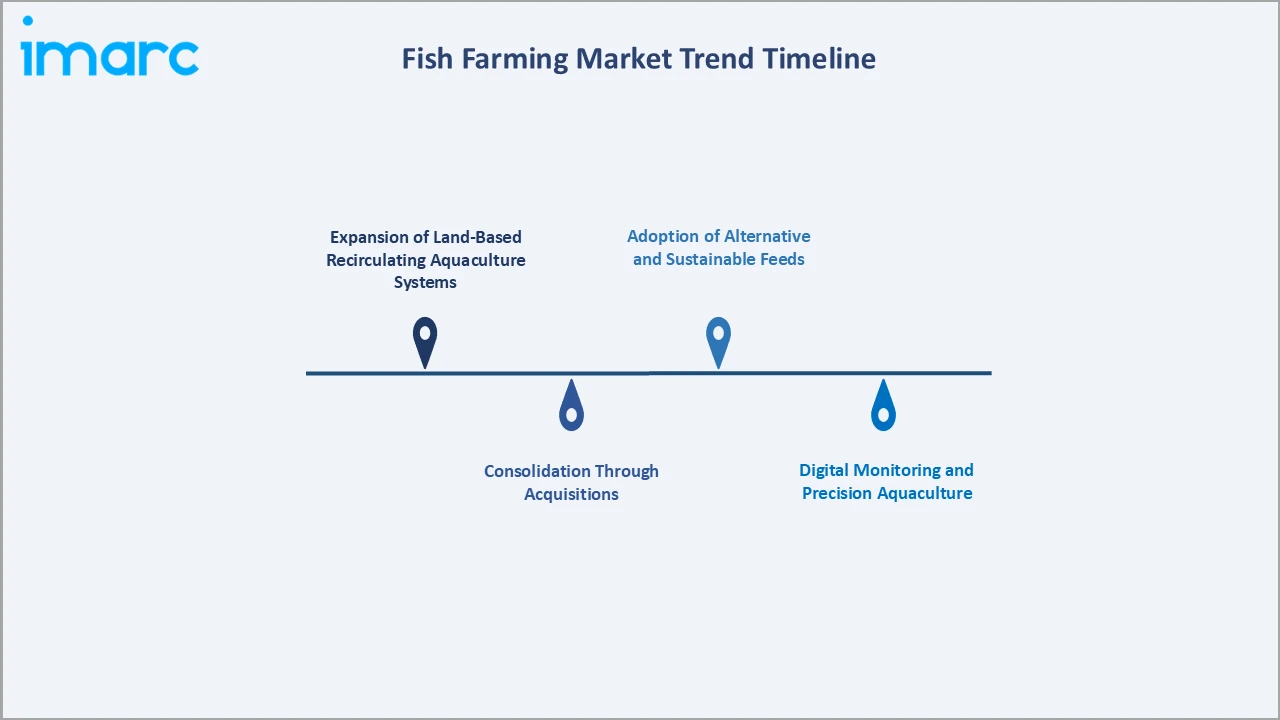
1. Expansion of Land-Based Recirculating Aquaculture Systems
Producers are investing in recirculating aquaculture systems that reuse water, control conditions, and operate close to consumer markets. Fish farming market analysis shows land-based salmon, trout, and shrimp projects advancing in North America, Europe, and the Middle East, reducing transport distances and disease exposure.
Higher capital costs remain a barrier, but successful commercial harvests are improving investor confidence and attracting new projects in several regions. Operators are also locating farms near renewable power sources to reduce energy costs and lower the carbon footprint of production.
2. Consolidation Through Acquisitions
Leading companies are acquiring farms, hatcheries, and processors to secure licences, diversify species, and strengthen market access. Transactions in 2026, including purchases in Atlantic Canada, Chile, and Greece, highlight the push for scale, integrated supply chains, and broader geographic portfolios across the industry.
Larger groups can spread disease, market, and regulatory risks across multiple regions and species, strengthening their bargaining power with retailers. Scale also supports investment in processing capacity, branding, and research that smaller independent farmers often cannot afford.
3. Adoption of Alternative and Sustainable Feeds
Feed producers are blending insect meal, algae oils, and plant proteins into diets to reduce reliance on wild fish ingredients. These feeds help farmers manage costs, improve sustainability scores, and respond to retailer and investor expectations on responsible sourcing and lower carbon footprints.
Feed producers are also improving formulations to cut feed conversion ratios and reduce nutrient discharge from farms into surrounding waters. Functional feeds that support immunity and gut health are also helping reduce mortality and treatment needs.
4. Digital Monitoring and Precision Aquaculture
Underwater cameras, sensors, artificial intelligence, and automated feeders are helping farmers track fish health, growth, and appetite in real time. Precision feeding reduces waste and costs, while data platforms support early disease detection, better harvest planning, and improved traceability for buyers and regulators.
Remote operation centers allow specialists to manage several farming sites at once, improving labor productivity and operational safety. These tools are becoming increasingly important as farms move to more exposed offshore locations with difficult access.
Industry Value Chain Analysis
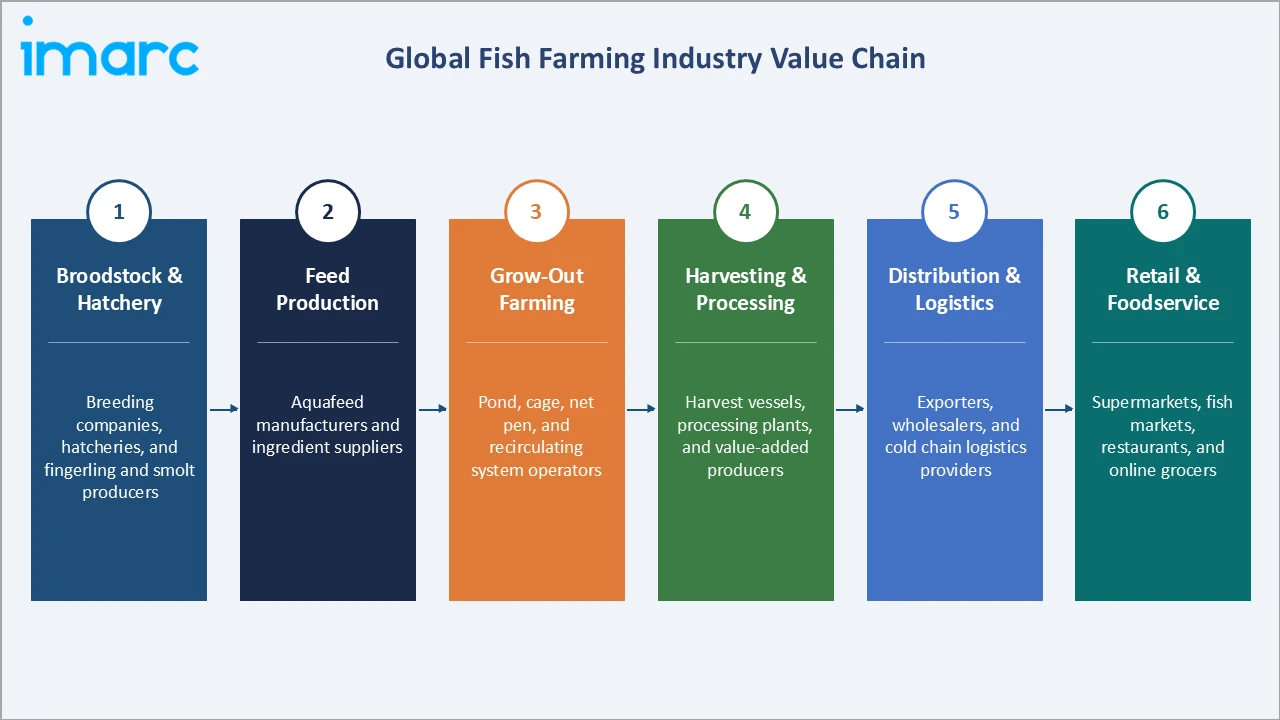
The fish farming value chain spans broodstock and hatchery, feed production, grow-out farming, harvesting and processing, distribution and logistics, and retail and foodservice. Value is concentrated in genetics, feed efficiency, and farming licences, which determine production costs, fish quality, and the ability to supply premium markets.
|
Stage |
Key Participants |
|
Broodstock & Hatchery |
Breeding companies, hatcheries, and fingerling and smolt producers |
|
Feed Production |
Aquafeed manufacturers and ingredient suppliers |
|
Grow-Out Farming |
Pond, cage, net pen, and recirculating system operators |
|
Harvesting & Processing |
Harvest vessels, processing plants, and value-added producers |
|
Distribution & Logistics |
Exporters, wholesalers, and cold chain logistics providers |
|
Retail & Foodservice |
Supermarkets, fish markets, restaurants, and online grocers |
Grow-out farming is the most consequential stage, as survival rates, feed conversion, and fish health determine profitability. Processing and cold chain logistics also matter greatly because farmed fish is perishable, and efficient handling preserves quality, reduces waste, and enables access to distant export markets.
Technology Landscape in the Global Fish Farming Industry
Recirculating Systems and Offshore Cages
Recirculating aquaculture systems filter and reuse most of their water, enabling controlled, biosecure production on land. Offshore cages and semi-submersible structures withstand rough seas, allowing farms to operate in deeper waters with stronger currents, better water exchange, and fewer conflicts with coastal communities.
Both systems require significant investment but offer greater production control and long-term expansion potential than conventional coastal net pens. Hybrid approaches, such as raising post-smolts on land before transfer to sea, are also gaining popularity.
Fish Health, Genetics, and Vaccines
Selective breeding programs improve growth rates, disease resistance, and feed efficiency across generations. Vaccines, functional feeds, and non-chemical sea lice treatments reduce antibiotic use and mortality, helping farmers meet regulatory requirements and consumer expectations for responsibly produced fish.
Genomic tools are accelerating breeding progress, while improved diagnostics allow faster identification and treatment of emerging diseases on farms. Together, these tools help producers protect animal welfare while improving survival and growth performance.
Digital Monitoring and Automated Feeding
Sensors measure oxygen, temperature, and water quality continuously, while cameras and artificial intelligence estimate fish size and detect behavioral changes. Automated feeding systems adjust rations in real time, reducing feed waste, lowering costs, and improving growth consistency across large farming operations.
Cloud platforms integrate farm data with supply chain systems, supporting traceability, regulatory reporting, and more accurate sales planning for producers. Shared data also helps insurers, lenders, and regulators assess farm performance and risks more accurately.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Environment | Fresh Water | 45.0% | 2025 |
| Fish Type | Salmon | 25.0% | 2025 |
| Region | Asia-Pacific | 45.0% | 2025 |

By Environment
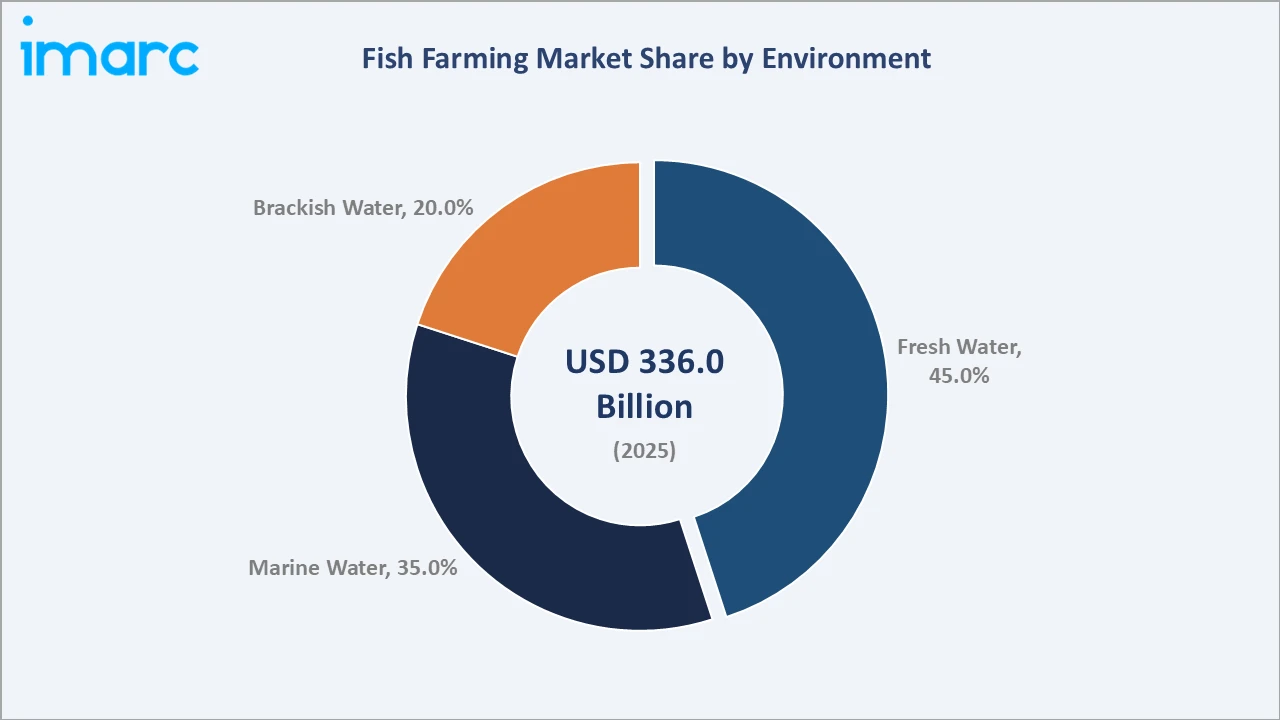
Fresh water leads at 45.0% (2025). Ponds, tanks, raceways, and inland cages support large volumes of tilapia, carp, catfish, and trout at relatively low cost. Extensive freshwater resources across Asia and growing inland farming in Africa and Latin America sustain demand across all regions.
To access detailed market analysis, Request Sample
Marine water at 35.0% grows fastest at ~4.2% CAGR, supported by salmon, sea bass, and offshore projects. Brackish water at 20.0% grows at ~3.9%, while fresh water grows at ~3.7%. Coastal ponds for milkfish and other species remain important in Southeast Asia.
By Fish Type
Salmon leads at 25.0% (2025). High market value, strong retail and sushi demand, and large integrated producers support its leadership. Tilapia follows at 22.0%, valued as an affordable, fast-growing species farmed widely in Asia, Africa, and Latin America for domestic and export markets.
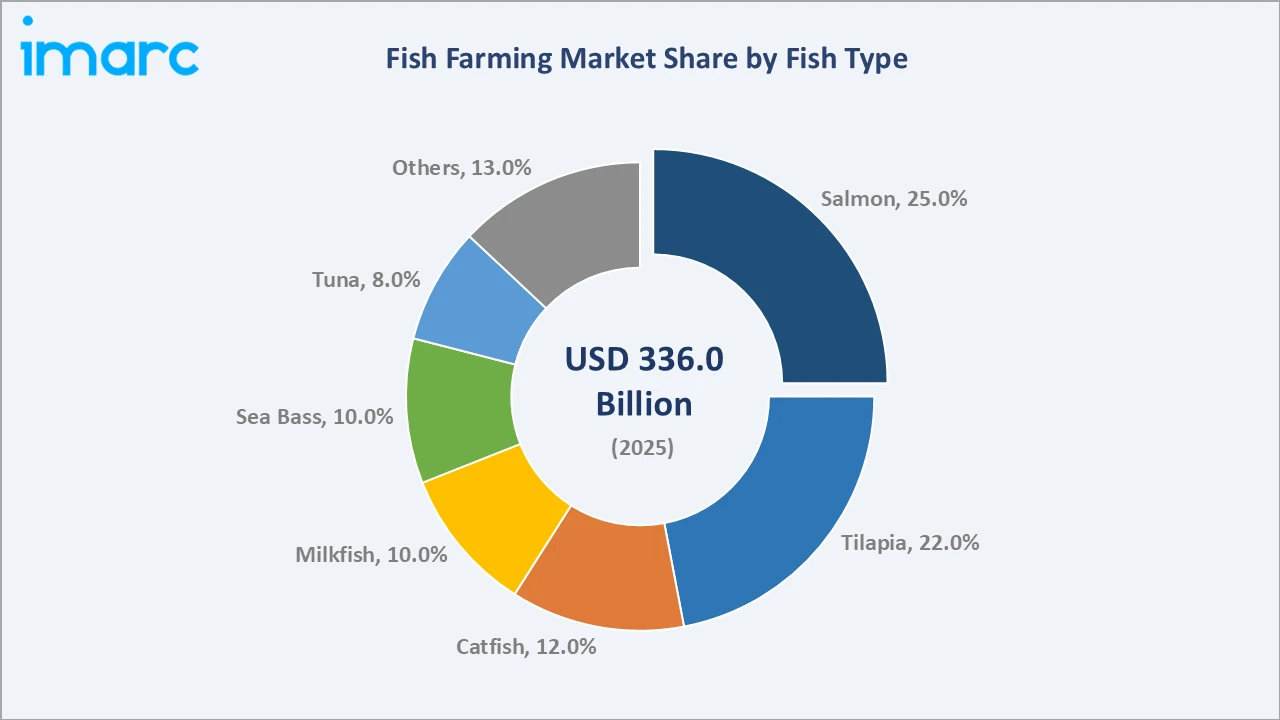
Tuna at 8.0% grows fastest at ~4.4% CAGR, followed by salmon at ~4.3% and tilapia at ~4.1%. Catfish at 12.0%, milkfish and sea bass at 10.0% each, and others at 13.0% serve diverse regional markets, supporting broad growth in fish farming market size.
Regional Market Insights
|
Region |
Share (2025) |
Key Global Fish Farming Market Drivers & Characteristics |
|
Asia-Pacific |
45.0% |
Large freshwater production, low costs, and high fish consumption in China and India. |
|
Europe |
20.0% |
Salmon farming in Norway and Scotland and Mediterranean sea bass and bream. |
|
North America |
15.0% |
Salmon in Canada, catfish in the U.S., and land-based farm investment. |
|
Latin America |
12.0% |
Chilean salmon and growing tilapia farming in Brazil and Mexico. |
|
Middle East and Africa |
8.0% |
Food security programs and expanding tilapia and marine farming. |
Asia-Pacific's 45.0% market leadership reflects extensive freshwater and coastal farming, low production costs, and very high fish consumption in China, India, Indonesia, and Vietnam. Europe's 20.0% reflects large salmon operations in Norway, Scotland, and the Faroe Islands, alongside Mediterranean sea bass and sea bream production in Greece and Turkey.
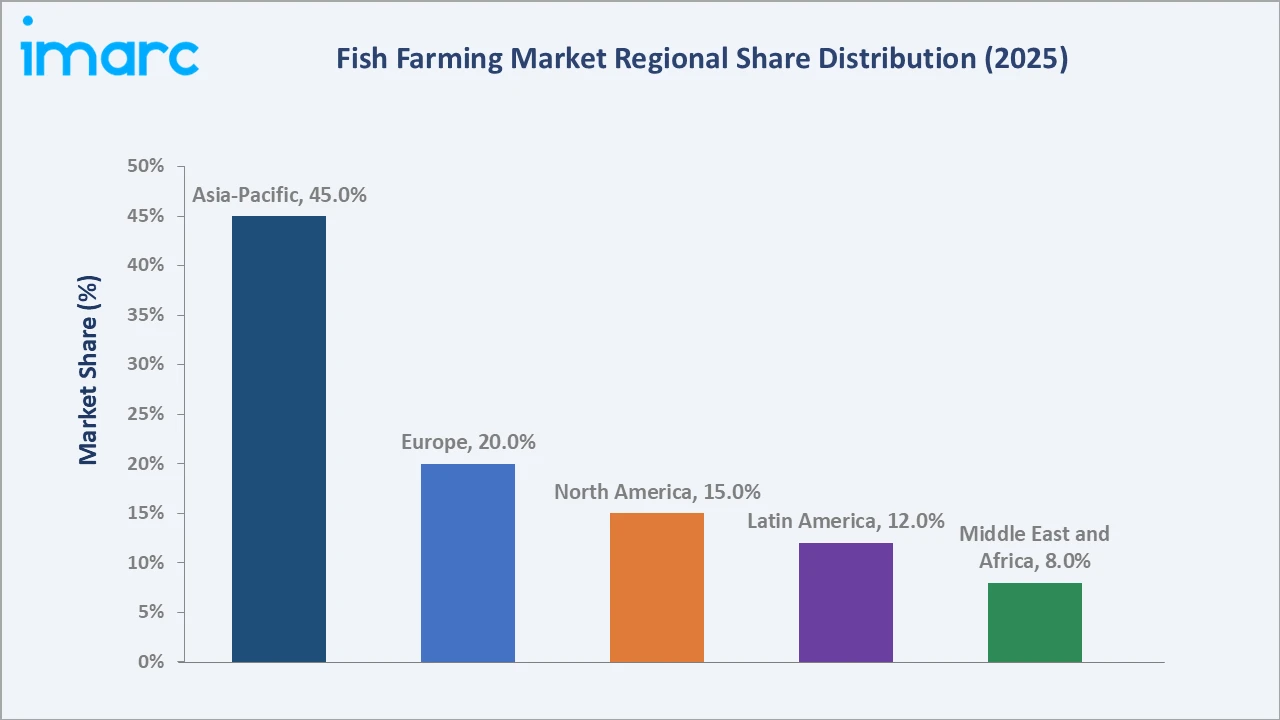
North America's 15.0% reflects salmon farming in Canada, catfish production in the United States, and investment in land-based systems. Latin America at 12.0% benefits from Chilean salmon and tilapia in Brazil, while Middle East and Africa at 8.0% grows with food security and aquaculture development programs.
Competitive Landscape
The global fish farming market includes large integrated salmon producers, diversified seafood groups, and thousands of small and medium regional farmers. Competition centers on licences, farming costs, fish health, product quality, and market access, shaping fish farming market share. Acquisitions continue to consolidate leading producers.
| Company | Key Brands | Market Position | Core Strength |
|---|---|---|---|
| Mowi | MOWI | Market Leader | World's largest farmed Atlantic salmon producer. |
| Cooke Aquaculture | True North Seafood, Cooke | Market Leader | Family-owned salmon and sea bass farming group. |
| Lerøy | Lerøy | Strong Challenger | Integrated salmon and trout farming with processing. |
| Cermaq Group AS | Cermaq | Strong Challenger | Salmon farming in Norway, Chile, and Canada. |
| Nissui | Nissui, Salmones Antarctica | Strong Challenger | Salmon, trout, and Japanese fish aquaculture. |
| Tassal Group | Tassal | Innovator | Tasmanian Atlantic salmon and prawn farming. |
| Nireus | Nireus Select, Thalassa | Innovator | Greek sea bass and sea bream farming. |
The most important competitive dynamic is consolidation, as leading producers acquire farms in Atlantic Canada, Chile, and Greece to secure scarce licences and diversify species. Investment in disease control, land-based systems, and cost efficiency is also becoming a key differentiator for maintaining margins.
Key Company Profiles
Mowi
Mowi is a leading global seafood company specialising in the farming, processing, and distribution of Atlantic salmon, with operations across multiple countries and an international workforce.
- Key Brands: MOWI.
- Recent Developments: In March 2026, Mowi unveiled new packaging for its MOWI, Ducktrap, and Marine Harvest by Mowi brands in the U.S., with rollout running through 2027.
- Strategic Focus: Concentrating on core farming geographies, with 2026 harvest guidance of about 600,000 tonnes of salmon.
Cooke Aquaculture
Cooke Aquaculture is a family-owned seafood company with salmon, sea bass, and sea bream farming and wild fishery operations across the Americas, Europe, and Australia.
- Key Brands: True North Seafood, Cooke.
- Recent Developments: In 2026, Cooke acquired Avramar Seafood and launched Cooke Hellas to operate its Greek sea bream and sea bass farms.
- Strategic Focus: Expanding salmon farming in Atlantic Canada through the agreed purchase of Mowi's Canada East operations.
Lerøy
Lerøy is a global seafood company engaged in aquaculture, wild catch, processing, and distribution, serving customers across international markets.
- Key Brands: Lerøy.
- Recent Developments: In the first quarter of 2026, Lerøy harvested 39,900 tonnes of salmon and trout, up from 38,200 tonnes a year earlier.
- Strategic Focus: Targeting the lowest relative farming cost in all operating regions and a 220,000-tonne harvest in Norway by 2030.
Market Concentration Analysis
The global fish farming market is highly fragmented, with large integrated producers leading salmon farming, while millions of small and medium farmers dominate freshwater and brackish water production across Asia, Africa, and Latin America.
Market concentration is rising in salmon and Mediterranean species through acquisitions and licence consolidation, particularly in Norway, Chile, Canada, and Greece. Competition remains highly dispersed in tilapia, catfish, and carp farming, where low entry barriers allow many local producers to serve domestic markets.
Investment & Growth Opportunities
Highest Growth Segments
Tuna (~4.4% CAGR through closed-cycle farming), salmon (~4.3% CAGR through land-based and offshore systems), marine water (~4.2% CAGR through new sites), and Asia-Pacific (~4.2% CAGR through rising consumption) represent the highest-growth investment areas in the fish farming industry through 2034.
Emerging Investment Opportunities
Land-based recirculating farms, offshore aquaculture, and alternative feed ingredients are among the most promising opportunities, supporting production growth with lower environmental impact. Investment in hatcheries, vaccines, and cold chain infrastructure in emerging markets also offers strong long-term returns for producers and investors.
Investment Themes
- Biosecure farming systems: Recirculating and offshore systems reduce disease risks and expand capacity.
- Feed innovation: Alternative ingredients lower costs and improve sustainability performance.
Future Market Outlook (2026-2034)
The global fish farming market is projected to grow from USD 336.0 Billion in 2025 to USD 352.8 Billion in 2026, reaching USD 479.7 Billion by 2034 at a CAGR of 3.91%. The 2030 value of USD 407.1 Billion marks wider adoption of land-based and offshore farming.
Three structural forces define fish farming industry growth through 2034 rising seafood demand; limits on wild catch; and technology-driven productivity gains. Together, these forces support steady growth across environments, fish types, and regions, while disease control and feed costs remain key factors shaping profitability.
Research Methodology
Primary Research
Primary research comprised structured interviews with industry stakeholders, including fish farmers, hatchery operators, feed producers, processors, distributors, equipment suppliers, and policymakers across all major producing and consuming regions. Interviews validated volumes and growth expectations.
Secondary Research
Secondary research covered company press releases, annual reports, FAO and government statistics, trade associations, and industry publications. Over 50 credible secondary sources were reviewed, compared, and cross-checked for accuracy and consistency across datasets and regions.
Forecasting Models
Market revenue forecasts were developed using a supply- and demand-based model: production volumes by environment, fish type, and region multiplied by average farm-gate prices and aggregated to total market value. Assumptions were validated through discussions with industry experts, farmers, and processors.
Fish Farming Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical and Forecast Trends, Industry Catalysts and Challenges, Segment-Wise Historical and Predictive Market Assessment:
|
| Environments Covered | Marine Water, Fresh Water, Brackish Water |
| Fish Types Covered | Salmon, Milkfish, Tuna, Tilapia, Catfish, Sea Bass, Others |
| Regions Covered | Asia Pacific, Europe, North America, Latin America, Middle East and Africa |
| Countries Covered | United States, Canada, Germany, France, United Kingdom, Italy, Spain, Russia, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Mexico |
| Companies Covered | Mowi, Cooke Aquaculture, Lerøy, Cermaq Group AS, Nissui, Tassal Group, Nireus, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the global fish farming market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the global fish farming market.
- The study maps the leading, as well as the fastest-growing, regional markets. It further enables stakeholders to identify the key country-level markets within each region.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the fish farming industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Fish Farming Market Report
The global fish farming market size is estimated at USD 352.8 Billion in 2026, supported by rising seafood demand, limits on wild catch, and expanding aquaculture production across Asia-Pacific, Europe, and the Americas.
The market grows at a 3.91% CAGR during 2026-2034, reaching USD 479.7 Billion by 2034, driven by higher consumption, technology adoption, and supportive government policies.
Fresh water leads at 45.0%, owing to widespread pond, tank, and inland cage farming of tilapia, carp, and catfish across Asia and other regions.
Salmon leads at 25.0%, supported by its high market value, strong retail and sushi demand, and large integrated producers in Norway and Chile.
Asia-Pacific leads at 45.0%, driven by large freshwater production, low farming costs, and high per-capita fish consumption in China, India, and Indonesia.
Leading companies include Mowi, Cooke Aquaculture, Lerøy, Cermaq Group AS, Nissui, Tassal Group, and Nireus, among others.
Land-based farming is growing as recirculating systems allow biosecure production of salmon
The market is projected to reach approximately USD 407.1 Billion by 2030, supported by steady growth in salmon, tilapia, and other farmed species, along with expanding production in Asia-Pacific.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade